
- Home
- »
- Advanced Interior Materials
- »
-
Flexible Pipes Market Size, Share & Growth Report, 2033GVR Report cover

Flexible Pipes Market (2026 - 2033)
Size, Share & Trends Analysis Report By Raw Material (High Density Polyethylene, Polyamides, Polyvinylidene Fluoride), By Application (Onshore, Offshore), By Region, And Segment Forecasts
Market Size, 2025
$1.4BMarket Estimate, 2026
$1.5BMarket Forecast, 2033
$1.9BCAGR, 2026–2033
4.0%Flexible Pipes Market Summary
The global flexible pipes market size was valued at USD 1.4 billion in 2025 and is projected to grow from USD 1.5 billion in 2026 to USD 1.9 billion by 2033, growing at a CAGR of 4.0% from 2026 to 2033. Asia Pacific dominated the market, accounting for a largest revenue share of 37.5% in 2025. This flexible pipes industry growth is attributed to the increasing exploration activities in offshore oil and gas locations.
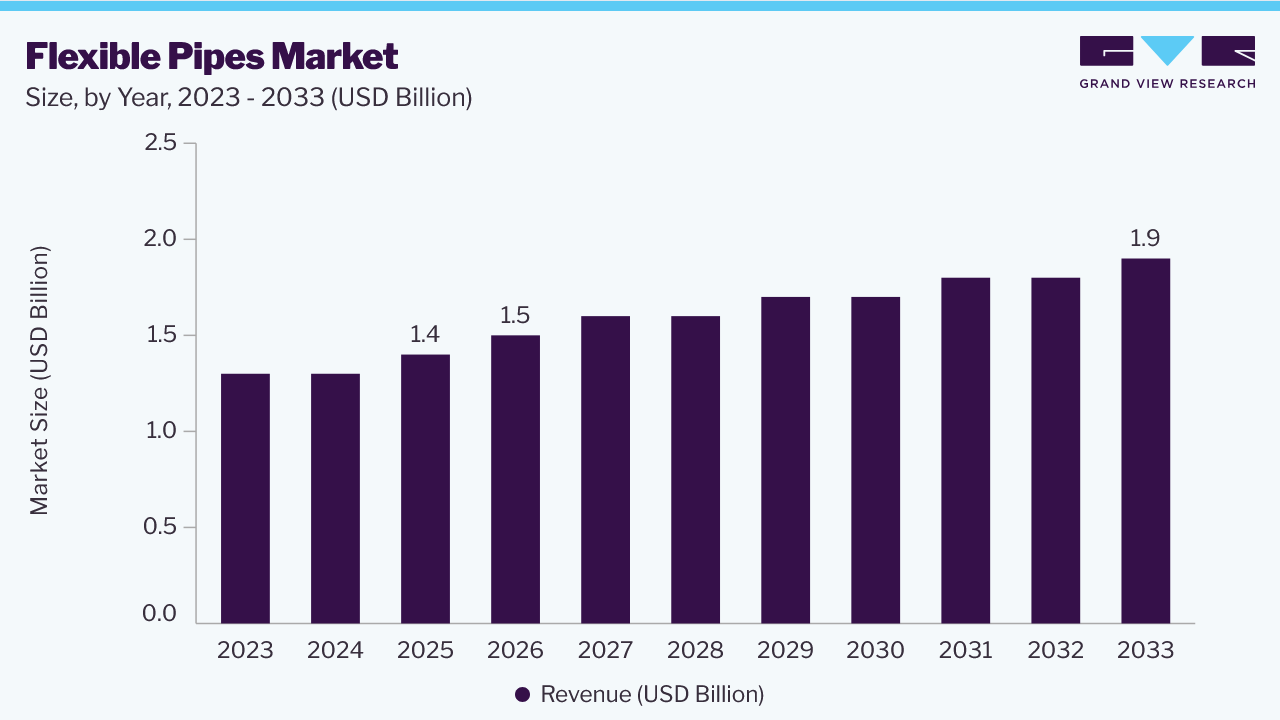 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By raw material: The high-density polyethylene segment held the largest market share of around 47.0% in 2025.
- By application: The offshore segment held the largest market share of over 72.0% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (37.5% revenue share, 2025)
- Fastest-growing regional market: North America (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 1.4 Billion
- Estimated market size in 2026: USD 1.5 Billion
- Projected market size by 2033: USD 1.9 Billion
- CAGR (2026-2033): 4.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
These flexible pipes are essential for transporting fluids in challenging environments, particularly in deep-water operations where traditional piping systems may fail. The demand for flexible pipes is further bolstered by advancements in drilling technologies, which have enhanced the efficiency and safety of oil and gas extraction processes. As conventional reserves deplete, the industry is shifting focus toward deep-water and ultra-deep-water reserves, necessitating robust and adaptable piping solutions that can withstand high pressures and harsh conditions.
Growing investments in offshore oil and gas developments across major energy-producing countries are further supporting the demand for flexible pipes. As conventional oil and gas reserves mature, exploration activities are increasingly shifting toward deepwater and ultra-deepwater fields, where flexible pipes offer superior resistance to high pressure, dynamic movement, and harsh offshore conditions. For instance, in February 2025, China National Offshore Oil Corporation (CNOOC) commenced production at the Bozhong 26-6 Oilfield Development Project (Phase I). The project includes a new central processing platform, an unmanned wellhead platform, and subsea pipelines, supporting the deployment of flexible pipe solutions for offshore oil and gas production.
Analyst Perspective
The flexible pipes industry is primarily driven by increasing investment in offshore oil and gas exploration, particularly in deepwater and ultra-deepwater developments, where flexible pipe systems offer superior pressure resistance, corrosion protection, and installation flexibility. Rising offshore production activities in regions such as Brazil, the North Sea, the Gulf of Mexico, and Asia Pacific continue to support demand for advanced flexible pipe solutions. In addition, manufacturers are focusing on improving pipe durability through advanced polymer materials and composite technologies to enhance operational reliability in harsh offshore environments. Growing investments in subsea infrastructure and floating production systems are expected to create new opportunities while continued offshore energy developments are expected to sustain long-term market demand.
Raw Material Insights
By raw material, the high-density polyethylene segment held the largest market share of around 47.0% in 2025 and is further expected to grow at a significant CAGR over the forecast period. HDPE is widely used owing to its excellent strength-to-density ratio, corrosion resistance, flexibility, and cost-effectiveness, making it suitable for demanding offshore and onshore applications. For example, in July 2024, TechnipFMC secured a substantial contract from Petrobras to design, engineer, and manufacture flexible pipes for offshore pre-salt fields in Brazil. The project includes flexible pipe systems for water injection and gas lift applications, reflecting continued investments in offshore infrastructure and supporting demand for high-performance flexible pipe materials. HDPE's durability and ease of processing continue to support its widespread adoption across the industry.
The PVDF segment is projected to grow at the fastest CAGR over the forecast period. This material is renowned for its exceptional chemical resistance and stability under extreme conditions, including high temperatures and aggressive chemicals. PVDF's unique properties make it ideal for specialized applications, such as in the chemical processing and nuclear industries, where reliability and safety are paramount. As industries increasingly prioritize performance and longevity in their materials, demand for PVDF is expected to rise, positively impacting market dynamics and fostering innovation in pipe manufacturing technologies.
Application Insights
By application, the offshore segment held the largest market share, over 72.0%, in 2025 and is expected to witness the fastest CAGR during the forecast period. The segment is driven by increasing deepwater and ultra-deepwater exploration activities, rising investments in offshore production infrastructure, and growing development of subsea oil and gas fields. Flexible pipes are widely used in offshore operations owing to their ability to withstand high pressure, dynamic loading, and harsh marine environments while enabling efficient hydrocarbon transportation. For instance, in October 2024, Baker Hughes secured a multi-year contract from Petrobras to supply 77 km of flexible pipe systems and associated services for the Búzios, Libra, Berbigão, Sururu, and Sépia pre-salt fields in Brazil's Santos Basin. The contract supports hydrocarbon production, associated gas, and water injection operations, highlighting continued investments in offshore infrastructure and the growing demand for flexible pipe systems.
The onshore segment is expected to witness significant CAGR during the forecast period, driven by increasing investments in onshore oil and gas production, chemical processing, water transportation, and industrial infrastructure. Flexible pipes are widely adopted in onshore applications owing to their ease of installation, lower maintenance requirements, and ability to transport hydrocarbons and industrial fluids across challenging terrain. Their flexibility, corrosion resistance, and long service life make them suitable for gathering lines, flowlines, and fluid transfer systems. In addition, the expansion of pipeline infrastructure and increasing industrial activities across emerging economies are expected to support demand for flexible pipes in onshore operations.
Regional Insights
The flexible pipes industry in Asia Pacific dominated the global industry at approximately 37.5% in 2025 and is further expected to grow at a significant rate over the forecast period. The region is driven by expanding offshore oil and gas developments, growing investments in pipeline infrastructure, and increasing demand for high-performance polymer materials.For instance, in June 2024, Bharat Petroleum Corporation Ltd. (BPCL) selected Univation Technologies' UNIPOL PE Process for two world-scale polyethylene production lines in India. The facilities will manufacture HDPE and LLDPE resins for pipe applications, supporting the regional supply of raw materials for flexible pipe manufacturing.
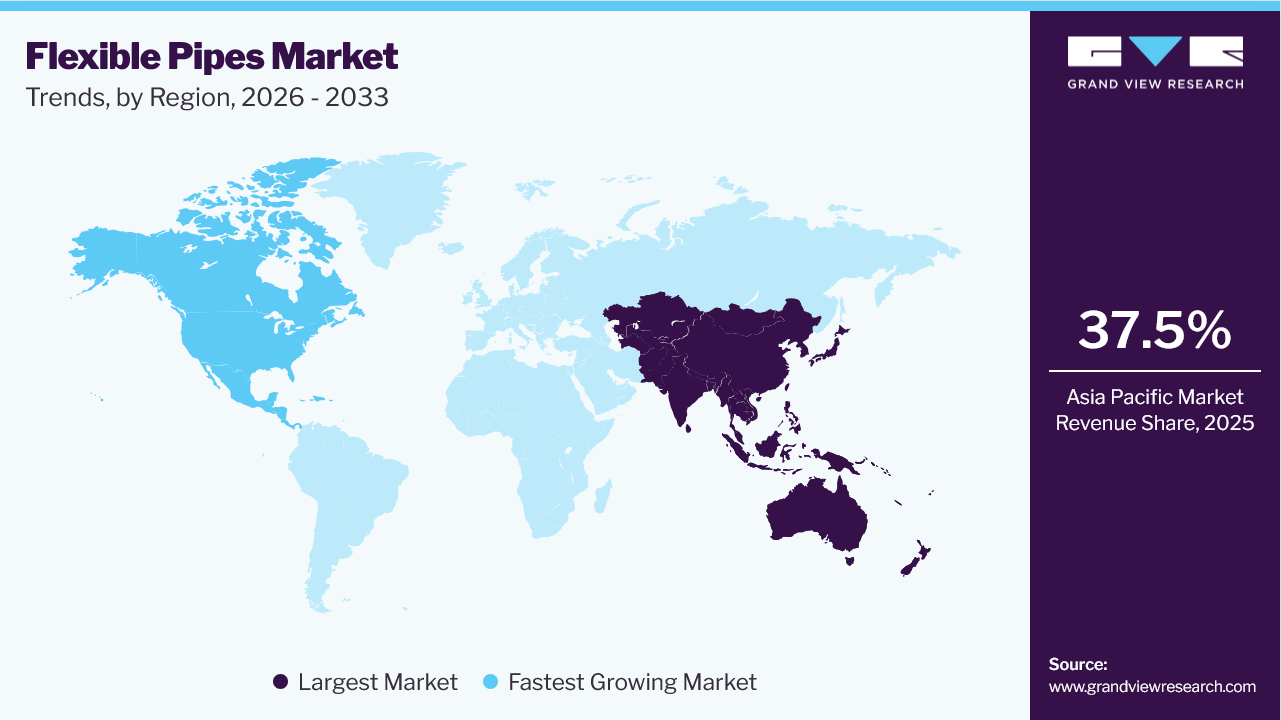 To learn more about this report, Download Free Sample Report
The China flexible pipes industry is expected to grow steadily owing to increasing investments in offshore oil and gas exploration, expansion of subsea production infrastructure, and continued development of pipeline networks. Growing demand for durable, corrosion-resistant piping systems across industrial and energy applications is expected to drive market growth.
North America Flexible Pipes Market Trends
North America flexible pipes industry is expected to witness substantial growth, supported by increasing shale gas production, offshore exploration activities in the Gulf of Mexico, and investments in pipeline infrastructure. Flexible pipes are increasingly adopted for hydrocarbon transportation owing to their corrosion resistance, installation flexibility, and long service life. For instance, in April 2024, AmeriTex Pipe & Products announced plans to construct a new High-Density Polyethylene (HDPE) and polypropylene corrugated pipe manufacturing facility in Texas. The investment expands production capacity for HDPE pipe systems to support growing infrastructure demand across water and industrial applications.
Key Flexible Pipes Company Insights
The flexible pipes industry is characterized by established global manufacturers competing through product innovation, material advancements, technological development, strategic partnerships, and offshore project collaborations. Companies continue to invest in advanced composite materials, high-performance thermoplastics, and subsea pipeline technologies to strengthen their competitive position across offshore oil and gas applications.
Key Flexible Pipes Companies
The following key companies have been profiled for this study on the flexible pipes market:
-
NOV Inc.
-
TechnipFMC plc
-
Prysmian S.p.A.
-
Baker Hughes Company
-
Shawcor Ltd. (Mattr Corp.)
-
Pipelife Nederland B.V. (SOLUFORCE)
-
Airborne B.V.
-
Magma Global Ltd.
-
ContiTech AG
-
Chevron Phillips Chemical Company LLC
-
FlexSteel Pipeline Technologies, Inc.
Recent Developments
- In May 2025, TechnipFMC signed a technology development agreement with Petrobras to accelerate the commercialization of its Hybrid Flexible Pipe (HFP) technology. The HFP combines carbon fiber composites with PEEK thermoplastic materials to provide superior resistance to CO₂-induced stress corrosion cracking, lower weight, and longer service life for ultra-deepwater flexible pipe applications.
- In March 2025, Baker Hughes entered into a pre-commercial technology agreement with Petrobras to develop a new generation of CO₂-resistant flexible pipe systems for offshore production. The flexible pipes are being engineered to achieve a 30-year service life in high-CO₂ environments, addressing stress corrosion cracking through advanced materials and design.
- In March 2024, NOV launched its actively heated flexible pipe system that electrically heats the pipe's inner carcass layer to prevent wax and hydrate formation during subsea oil and gas production. The system improves flow assurance, supports long-distance transport of viscous fluids, and reduces dependence on conventional hydrate mitigation methods.
Flexible Pipes Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.4 billion
Estimated Market size in 2026
USD 1.5 billion
Projected Market size by 2033
USD 1.9 billion
Growth rate
CAGR of 4.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Raw material, application, region
Regional Scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; China; India; Japan; South Korea; Brazil; Argentina
Key companies profiled
NOV Inc.; TechnipFMC plc; Prysmian S.p.A.; Baker Hughes Company; Shawcor Ltd. (Mattr Corp.); Pipelife Nederland B.V. (SOLUFORCE); Airborne B.V.; Magma Global Ltd.; ContiTech AG; Chevron Phillips Chemical Company LLC; FlexSteel Pipeline Technologies, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Flexible Pipes Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each sub segment from 2021 to 2033. For this study, Grand View Research has segmented global flexible pipes market report based on raw material, application, and region.
-
Raw Material Outlook (Revenue, USD Billion, 2021 - 2033)
-
High Density Polyethylene
-
Polyamides
-
Polyvinylidene Fluoride
-
Others
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Onshore
-
Offshore
-
Deepwater
-
Ultra-deep water
-
Subsea
-
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Frequently Asked Questions About This Report
The global flexible pipes market size was valued at USD 1.4 billion in 2025 and is estimated at USD 1.5 billion for 2026.
The global flexible pipes market is expected to grow at a CAGR of 4.0% from 2026 to 2033, reaching USD 1.9 billion.
The high-density polyethylene segment accounted for the largest revenue share of around 47.0% in 2025.
Key players in the market include NOV Inc., TechnipFMC plc, Prysmian S.p.A., Baker Hughes Company, Shawcor Ltd. (Mattr Corp.), Pipelife Nederland B.V. (SOLUFORCE), Airborne B.V., Magma Global Ltd., ContiTech AG, Chevron Phillips Chemical Company LLC, FlexSteel Pipeline Technologies, Inc., and others.
Asia Pacific dominated with an approximately 37.5% revenue share in 2025.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


