
- Home
- »
- Food Safety & Processing
- »
-
Food Processing Blades Market Size Report, 2026-2033GVR Report cover

Food Processing Blades Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Straight, Curved, Circular), By Application (Grinding, Cutting/Portioning, Slicing), By End-use (Proteins, Other Foods), By Region, And Segment Forecasts
Market Size, 2025
$1.1BMarket Estimate, 2026
$1.2BMarket Forecast, 2033
$2.3BCAGR, 2026–2033
9.4%Food Processing Blades Market Trends
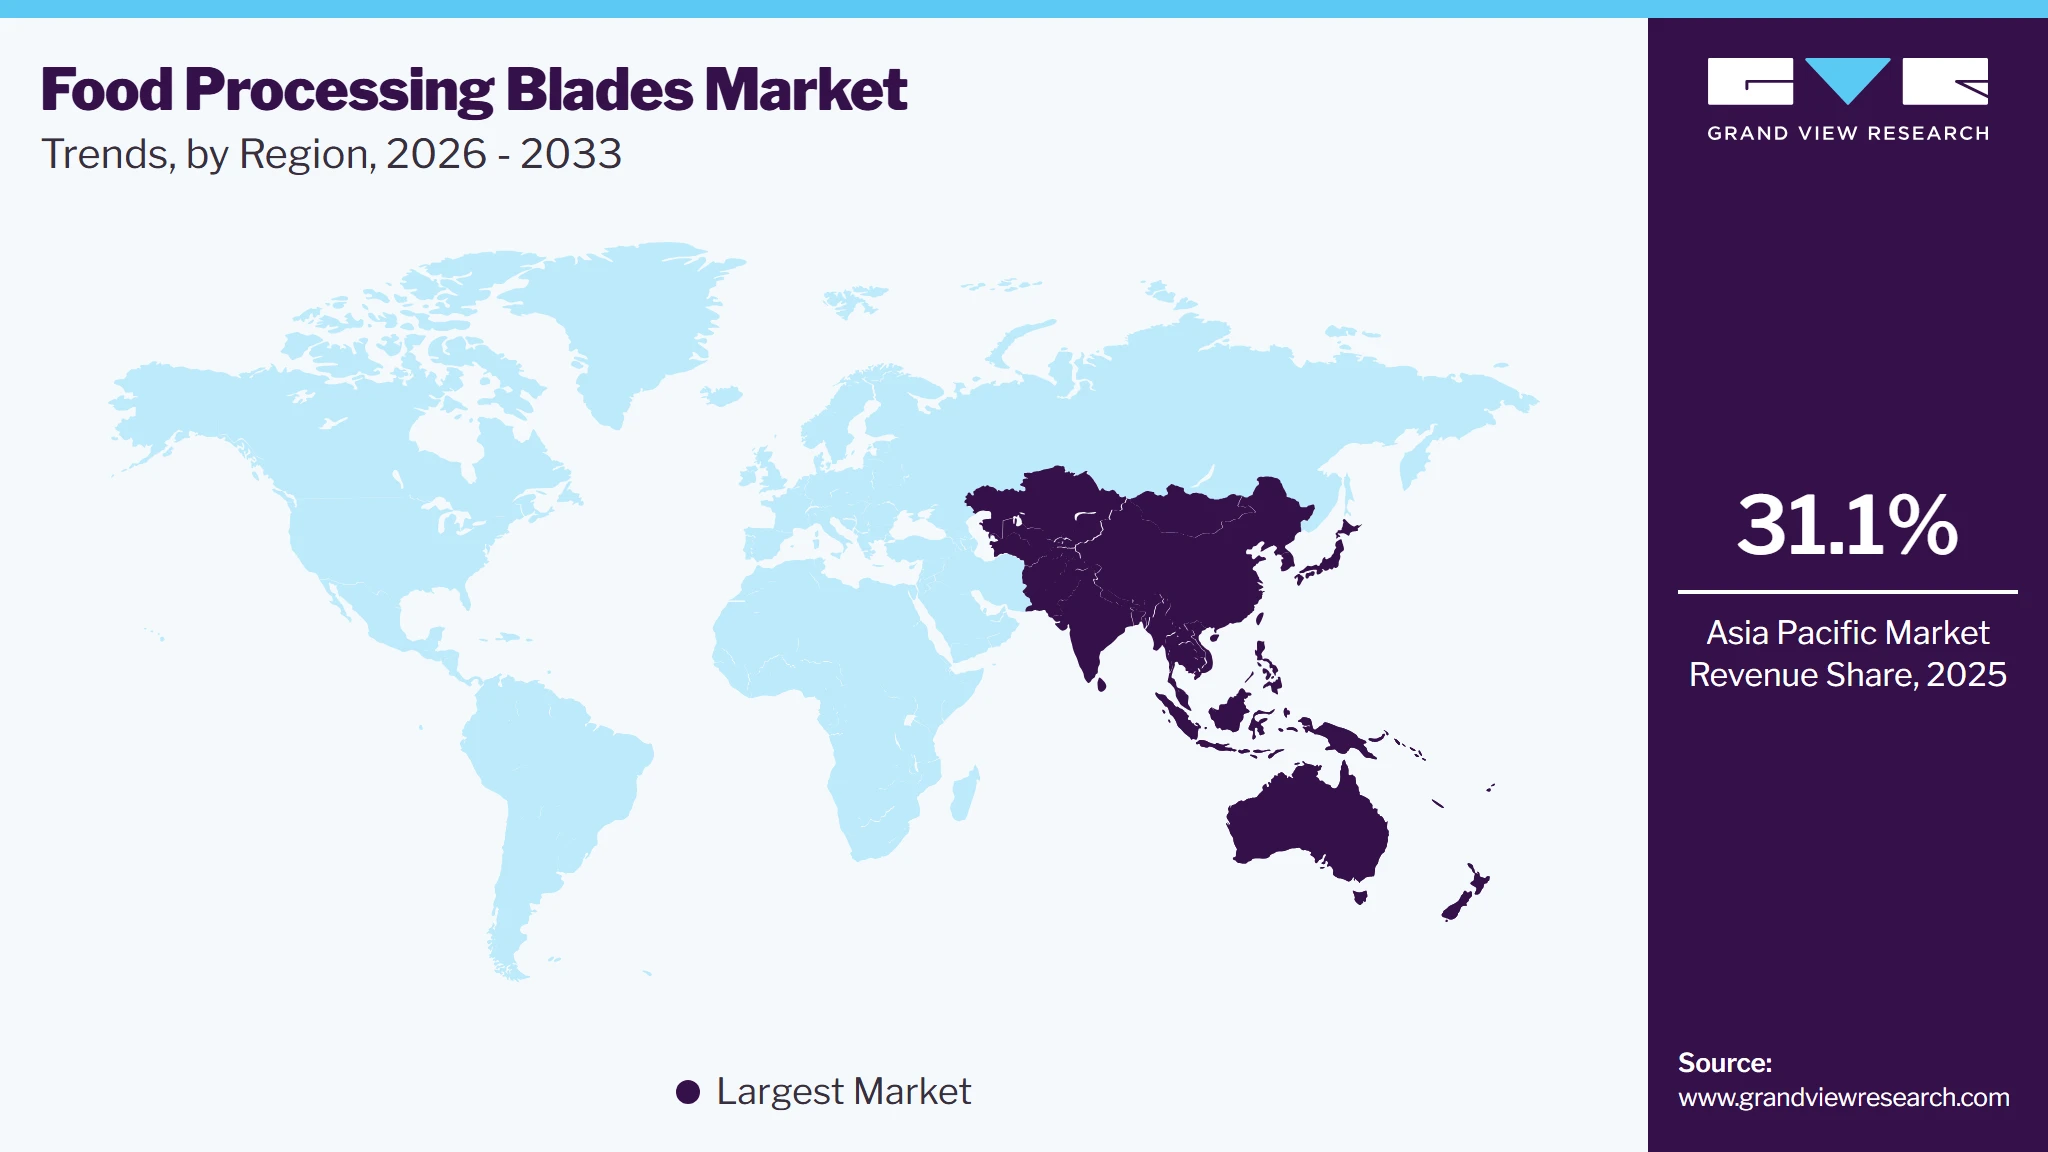
The global food processing blades market size was valued at USD 1.1 billion in 2025 and is projected to grow from USD 1.2 billion in 2026 to USD 2.3 billion by 2033, at a CAGR of 9.4% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 31.1% in 2025. This growth can be attributed to rising disposable incomes and increased spending power among the middle class, leading to higher demand for processed food products. In addition, the growing preference for convenience foods, including ready-to-eat meals, is boosting market expansion. Furthermore, advances in technology and blade manufacturing are enhancing product quality and efficiency, while adherence to food safety regulations also supports the need for high-quality food processing blades in production processes.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Circular segment led the market with the largest revenue share of 40% in 2025.
- By application: Grinding segment led the market with the largest revenue share of 23.9% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (31.1% revenue share, 2025)
- By country: The China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 1.1 Billion
- Estimated market size in 2026: USD 1.2 Billion
- Projected market size by 2033: USD 2.3 Billion
- CAGR (2026-2033): 9.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
A direct answer, usually in 1 working day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Food processing blades are essential tools employed in the food industry for various functions, including cutting, slicing, dicing, and chopping. The increasing global population and urbanization are driving a rising demand for processed foods, which are preferred for convenience, longer shelf life, and affordability. As consumer preferences shift towards ready-to-eat meals, the food processing sector is experiencing significant growth, leading to an escalating need for food processing blades.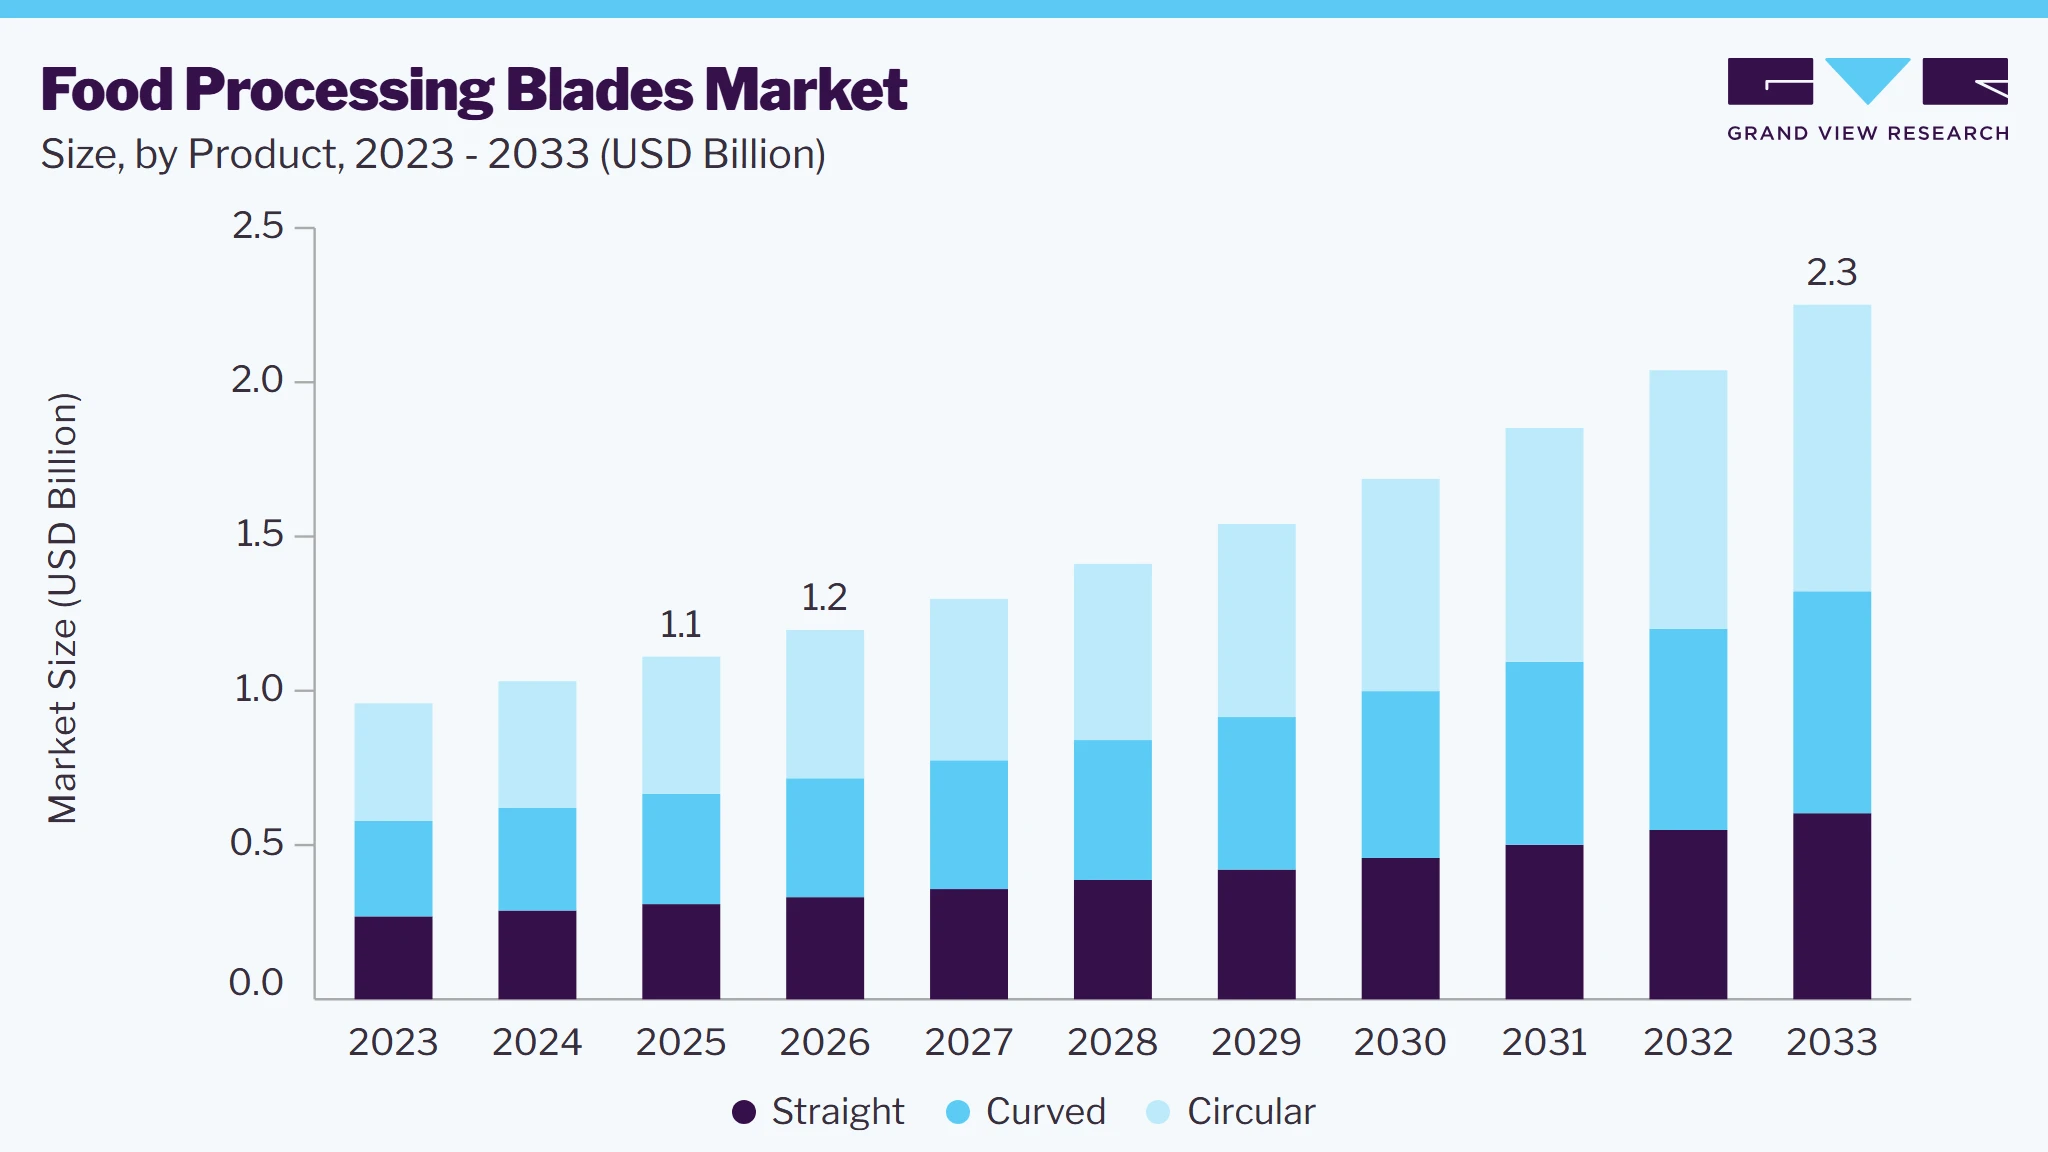 To learn more about this report, Download Free Sample Report
In addition to changing consumer habits, ongoing technological advancements are transforming the industry. Innovations such as laser cutting and precision machining are enhancing the efficiency and accuracy of food processing operations. These advancements enable manufacturers to produce blades that offer improved performance and durability, thereby creating new opportunities for their use in various applications.
Furthermore, government regulations play a crucial role in shaping the food processing blades market. Increasingly stringent regulations are being implemented to ensure the safety of food products. These regulations often mandate that food processors utilize specific types of blades that meet established safety standards, thus driving demand for compliant food processing blades.
Market Dynamics
The food processing blades market is driven by the growing production of processed, packaged, and convenience food products in industrial food manufacturing facilities. The rapid adoption of automated processing equipment is driving demand for precision-engineered blades that improve cutting accuracy, processing efficiency, and product uniformity. Stringent food safety and hygiene regulations are increasing the adoption of corrosion-resistant, food-grade blade materials that ensure regulatory compliance and minimize contamination risks. Continuous advancements in blade materials, surface coatings, and edge retention technologies are enhancing durability, wear resistance, and overall equipment performance. However, fluctuations in raw material prices and recurring blade replacement requirements continue to exert pressure on operational costs.
The food processing blades market is driven by the increasing deployment of automated and high-speed food processing equipment across industrial manufacturing facilities. Food processors are prioritizing precision-engineered blade solutions to improve cutting accuracy, maintain product uniformity, enhance processing efficiency, and reduce material wastage.
Furthermore, stringent food safety regulations and growing emphasis on operational reliability are accelerating the adoption of high-performance blades manufactured from food-grade, corrosion-resistant materials with superior wear resistance and extended service life.
Food processing blades are subject to continuous wear due to constant contact with hard, abrasive, and fibrous food materials, resulting in frequent sharpening, maintenance, or replacement. High-performance blades made from stainless steel, carbide, or specialized alloys involve significant procurement costs, particularly for industrial-scale food processors operating multiple production lines. Additionally, blade replacement often requires temporary production shutdowns, increasing maintenance expenses and reducing operational efficiency. These factors are particularly challenging for small and medium-sized food manufacturers with limited maintenance budgets, thereby restraining market growth.
The expansion of food manufacturing capacity across emerging economies, coupled with increasing investments in advanced processing infrastructure, is creating substantial growth opportunities for the market. Rising demand for application-specific processing equipment is encouraging the development of customized blade geometries, advanced metallurgical compositions, and specialized surface coatings that enhance durability and processing performance.
In addition, the growing integration of smart manufacturing practices and automated production lines is expected to generate sustained demand for high-precision blade solutions capable of supporting continuous and high-volume processing operations.
Analyst Perspective
The food processing blades market is witnessing steady growth as food manufacturers increasingly invest in automated processing equipment to improve productivity, product consistency, and food safety. Rising demand for processed, packaged, and ready-to-eat foods is driving the need for high-performance blades capable of delivering precise cutting, slicing, dicing, and portioning while minimizing material waste and downtime. In addition, stringent hygiene standards and the growing adoption of stainless steel and wear-resistant blade materials are encouraging processors to upgrade their equipment. As food processing facilities continue to modernize and automate production lines, manufacturers offering durable, precision-engineered, and application-specific food processing blades are expected to benefit from sustained long-term market growth.
Product Insights
Based on product, the circular segment led the market with the largest revenue share of 40% in 2025. This growth can be attributed to their effectiveness and versatility. Circular blades are designed for high-volume cutting, slicing, and portioning, making them ideal for food manufacturers who require consistent and precise results. In addition, their ability to maintain a sharp edge during extensive use enhances productivity while minimizing downtime for maintenance.
The curved blades are expected to grow at the fastest CAGR of 8.7% over the forecast period, owing to their effectiveness in specialized applications such as skinning and filleting. These blades offer superior maneuverability, allowing for intricate cutting tasks that require precision and control. In addition, as the food industry increasingly emphasizes quality and presentation, the demand for curved blades is rising, particularly in meat and seafood processing. Furthermore, their unique design enables processors to achieve cleaner cuts, improving the overall quality of the final product and supporting market expansion.
Application Insights
Based on application, the grinding segment led the market with the largest revenue share of 23.9% in 2025, primarily driven by its efficiency in reducing food particle size. Grinding blades are essential for processing various food materials, including meat, vegetables, and grains, into smaller, more uniform particles. Furthermore, this capability enhances the consistency and quality of food products, making them more appealing to consumers. Moreover, as the demand for high-quality processed foods rises, the importance of grinding applications in food production continues to drive market growth.
The cutting/portioning application segment is expected to grow at the fastest CAGR of 9.4% over the forecast period, as manufacturers focus on optimizing food preparation processes. Food processing blades designed for cutting and portioning ensure uniformity and precision in slicing ingredients, which is crucial for maintaining product quality and presentation. In addition, the increasing popularity of convenience foods and ready-to-eat meals further fuels the demand for efficient cutting solutions. Furthermore, as food processors strive to meet consumer expectations for consistency and quality, the cutting and portioning segment is poised for continued expansion in the market.
End-use Insights
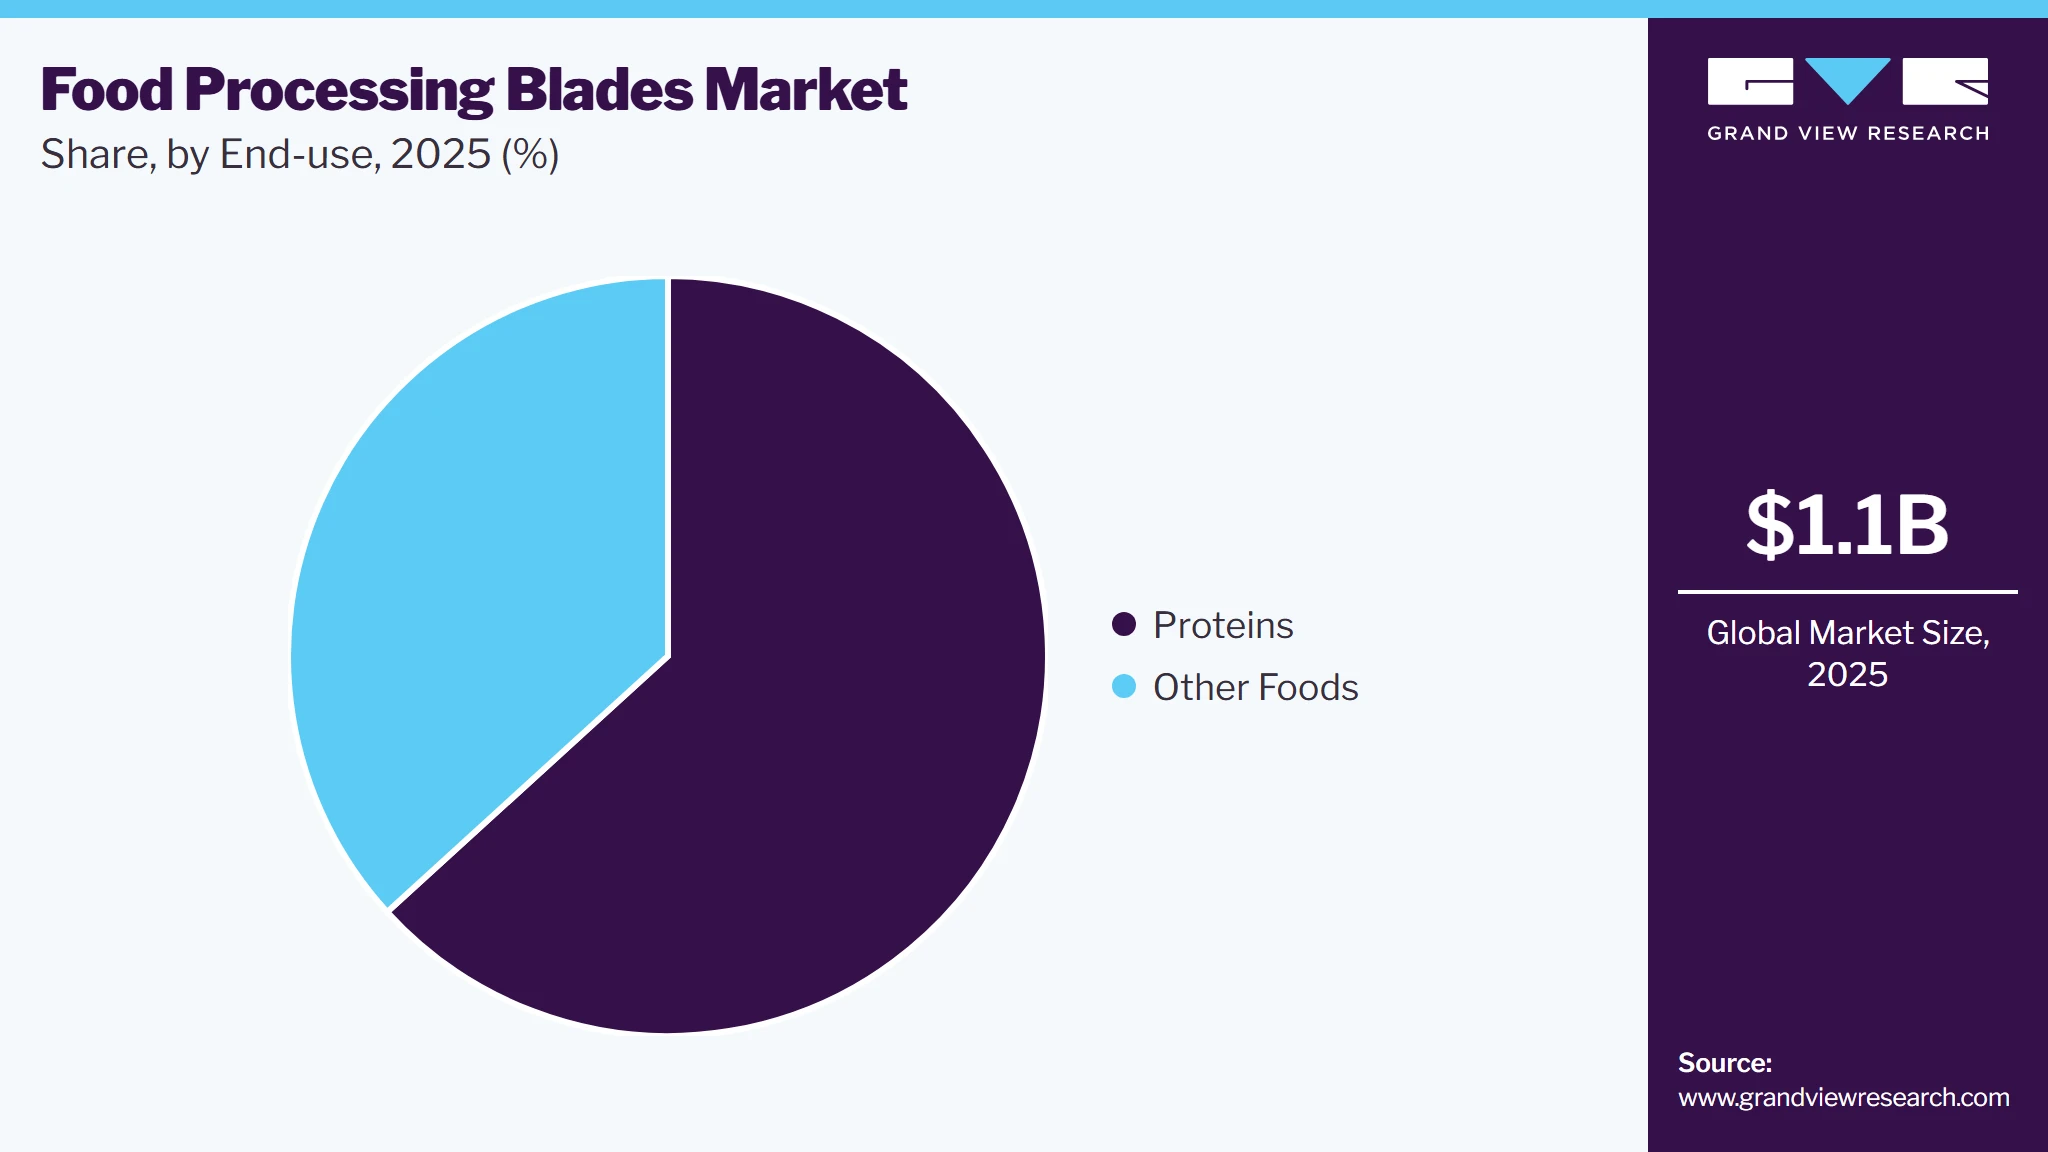
Based on end use, the proteins segment led the market with the largest revenue share of 63.2% in 2025, driven by the increasing consumption of meat and seafood products. As consumers seek high-quality protein sources, food processors are optimizing their operations to meet this demand. In addition, efficient cutting and processing techniques are essential for maintaining product quality and safety, leading to a higher demand for specialized blades. Moreover, advancements in blade technology enhance precision and durability, further supporting the growth of this segment.
 To learn more about this report, Download Free Sample Report
The other foods segment is expected to grow at a CAGR of 9.3% from 2025 to 2033, owing to the rising popularity of processed fruits, vegetables, and convenience foods. In addition, as consumer lifestyles become busier, there is a growing preference for ready-to-eat and pre-packaged food items that require efficient processing. Furthermore, food processing blades play a crucial role in ensuring uniformity and quality in these products. Moreover, innovations in blade design and materials are improving performance, making them indispensable in various food applications, thereby driving growth in this segment.
Regional Insights
Asia Pacific dominated the food processing blades market with the largest revenue share of 31.1% in 2025, primarily driven by rapid urbanization and an expanding food and beverage industry. Increasing disposable incomes and changing consumer preferences for convenient and ready-to-eat food products are further fueling demand. In addition, the region's large agricultural base necessitates efficient processing equipment, leading to heightened investments in food processing technologies. Furthermore, as consumers increasingly prioritize quality and safety in food products, the demand for advanced food processing blades continues to rise.
 To learn more about this report, Download Free Sample Report
China Food Processing Blades Market Trends
The food processing blades market in China held the largest share in the Asia Pacific region in 2025, driven by its booming food processing sector. The country's vast population and rising urbanization have led to a surge in demand for processed foods, including meat and seafood. Furthermore, technological advancements are enhancing production efficiency, prompting manufacturers to invest in high-quality processing equipment. Moreover, the government's focus on food safety regulations also drives the need for compliant food processing blades, solidifying China's position as a key player in this market.
North America Food Processing Blades Market Trends
The North America food processing blades market is expected to grow significantly over the forecast period, fueled by a strong emphasis on convenience foods and ready-to-eat meals. As lifestyles become busier, consumers increasingly turn to processed options that save time while ensuring quality. In addition, the region's established food processing industry is also adopting advanced technologies to improve efficiency and maintain high safety standards. Furthermore, innovations in blade design and materials contribute to enhanced performance, driving demand among manufacturers seeking competitive advantages.
The U.S. food processing blades market dominated the North American market and accounted for the largest revenue share in 2024. This growth can be attributed to the rising consumption of processed foods across various demographics. In addition, the growing trend towards health-conscious eating has led to increased demand for high-quality meat, poultry, and seafood products that require efficient processing solutions. Furthermore, regulatory pressures regarding food safety standards compel manufacturers to invest in advanced processing equipment, including specialized blades that ensure compliance.
Middle East & Africa Food Processing Blades Market Trends
The Middle East and Africa food processing blades market is expected to grow at a CAGR of 9.0% over the forecast period, owing to urbanization and increasing disposable incomes. The evolving food and beverage industry is adapting to changing consumer preferences, leading to a higher demand for processed and packaged foods. In addition, investments in modernizing food processing facilities are rising, enhancing productivity and product quality. Furthermore, as local manufacturers seek to meet international standards, the demand for efficient and reliable food processing blades is expected to grow significantly in this region.
Europe Food Processing Blades Market Trends
The food processing blades market in Europe is expected to experiencing growth driven by stringent food safety regulations and a strong preference for high-quality processed foods. The region's established culinary traditions and modern consumer demands for convenience foster innovation in food processing technologies. Furthermore, sustainability concerns are prompting manufacturers to adopt eco-friendly practices and materials in blade production. Moreover, as European consumers increasingly seek transparency regarding their food sources, the demand for efficient and compliant food processing blades continues to rise.
Key Food Processing Blades Company Insights
Major companies in the global food processing blades industry include Simonds International, Urschel Laboratories, Inc., Dexter Russell, and others. These players are adopting several key strategies to enhance their brand presence. Strategic collaborations and partnerships are being formed to leverage shared expertise and resources, fostering innovation in blade design and manufacturing. In addition, strategic acquisitions are also prevalent, allowing companies to expand their product portfolios and enter new markets effectively. Furthermore, a strong focus on new product development and launches is evident, as firms aim to meet evolving consumer demands and enhance operational efficiency across the food processing sector.
-
Norwood Commercial Products specializes in manufacturing a wide range of food processing blades designed for various applications within the food industry. The company focuses on producing high-quality cutting tools that cater to the needs of different sectors, including meat, poultry, and seafood processing. Operating within the food processing segment, the company provide innovative solutions that enhance efficiency and precision in food preparation and production processes.
-
Fortifi Food Processing Solutions manufactures a variety of blades used for cutting, slicing, and portioning across multiple food segments, including proteins and other processed foods. Operating primarily within the food processing segment, the company leverages innovative technologies to deliver high-performance solutions that meet the evolving needs of their customers.
Key Food Processing Blades Companies
The following key companies have been profiled for this study on the food processing blades market.
-
APV Engineered Coatings
-
Simonds International
-
Urschel Laboratories, Inc.
-
Dexter Russell
-
M.K. Morse LLC
-
Norwood Commercial Products
-
Fortifi Food Processing Solutions
-
Grote Company
-
Cardinal/AGSCO
-
Waring Commercial
-
Wilbur Curtis
-
Jarvis India
-
Hallde
-
Talsabell S.A.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., Simonds International; Urschel Laboratories, Inc.; Dexter Russell; Grote Company; Friedr. Dick GmbH & Co. KG; BAADER; Marel
- Prioritize investment in advanced blade engineering, proprietary metallurgical technologies, and precision manufacturing to strengthen product differentiation.
- Expand strategic collaborations with OEMs and food processing equipment manufacturers while reinforcing aftermarket replacement and maintenance service portfolios.
- Strengthen global market penetration through geographic expansion, application-specific product development, and compliance with evolving international food safety standards.
- Comprehensive product portfolios supported by strong technological capabilities and extensive application expertise across multiple food processing industries.
- Well-established global distribution networks, long-standing customer relationships, and high brand credibility among industrial food processors.
- Significant R&D investments enabling continuous product innovation, enhanced blade durability, cutting precision, and operational performance.
- Premium pricing structures may constrain market penetration within price-sensitive and emerging economies.
- Greater exposure to fluctuations in specialty steel and raw material costs, impacting manufacturing economics and profitability.
- Longer product development and commercialization cycles associated with stringent quality assurance and regulatory compliance requirements.
Emerging & Regional Players (e.g., Jarvis India; Hallde; Talsabell S.A.; Nemco Food Equipment)
- Emphasize specialized product offerings tailored to regional processing requirements and niche food applications.
- Expand market presence through distributor partnerships, localized sales networks, and customer-centric technical support services.
- Focus on cost-effective manufacturing, customized blade solutions, and operational responsiveness to address evolving customer requirements.
- Strong regional market knowledge enabling rapid adaptation to local processing practices and customer specifications.
- Enhanced manufacturing flexibility and customization capabilities supporting diverse food processing applications.
- Competitive cost structures and responsive customer service facilitating penetration into regional and mid-sized food processing enterprises.
- Limited international market presence and comparatively lower brand recognition than multinational competitors.
- Relatively constrained R&D capabilities and technological resources, limiting the pace of product innovation.
- Smaller manufacturing scale and distribution footprint may restrict participation in large-scale global procurement programs and multinational customer contracts.
Recent Developments
-
In April 2024, Fortifi Food Processing Systems, a global frontrunner in food processing equipment and automation, announced its acquisition of Nothum Food Processing Systems. Nothum is renowned for designing and manufacturing advanced lines for batter, tempura, breading, and frying, primarily targeting the protein processing sector. This acquisition allows Fortifi to further elevate its service excellence to customers.
-
In March 2024, Fortifi Food Processing Solutions officially launched as a comprehensive platform for leading brands in food processing equipment and automation. With operations in over 15 countries, Fortifi enhances productivity and worker safety across various sectors, including protein, dairy, and fruits and vegetables. The recent acquisition of MHM Automation strengthens their offerings with innovative systems that improve product quality.
Food Processing Blades Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 1.1 billion
Market size value in 2026
USD 1.2 billion
Revenue forecast in 2033
USD 2.3 billion
Growth rate
CAGR of 9.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, Volume in million units, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, end use, and region
Regional scope
North America; Asia Pacific; Europe; Latin America; Middle East and Africa
Country scope
U.S.; Canada; Mexico; China; India; Japan; South Korea; UK; Germany; France; Italy; Brazil; Argentina
Key companies profiled
Simonds International; Urschel Laboratories, Inc.; Dexter Russell; Grote Company; Jarvis India; Hallde; Talsabell S.A.; Friedr. Dick GmbH & Co. KG; BAADER; Marel; Nemco Food Equipment
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Food Processing Blades Market Report Segmentation
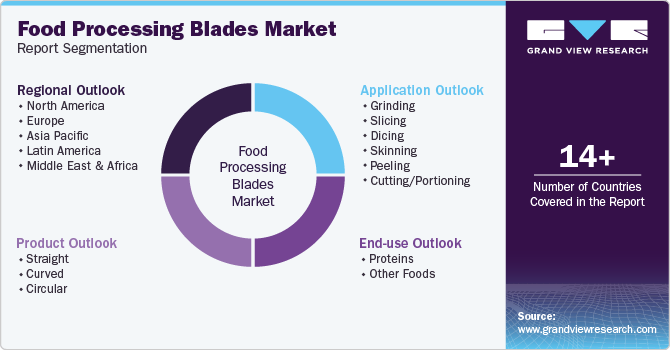
This report forecasts revenue growth at global, regional, and country levels and analyzes the latest industry trends in each sub-segment from 2021 to 2033. For this study, Grand View Research has segmented the global food processing blades market report based on product, application, end-use, and region.
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Volume, Million Units; Revenue, USD Million, 2021 - 2033)
-
Straight
-
Single Edge
-
Double Edge
-
Serrated
-
-
Curved
-
Single Edge
-
Serrated
-
-
Circular
-
Flat Edge
-
Beveled Edge
-
Scalloped Edge
-
Toothed
-
Notched
-
Semi-circular
-
Involute
-
-
-
Application Outlook (Volume, Million Units; Revenue, USD Million, 2021 - 2033)
-
Grinding
-
Slicing
-
Dicing
-
Skinning
-
Peeling
-
Cutting/Portioning
-
-
End-use Outlook (Volume, Million Units; Revenue, USD Million, 2021 - 2033)
-
Proteins
-
Fish
-
Poultry
-
Bovine
-
Pork
-
-
Other Foods
-
Fruits
-
Vegetables
-
Nuts
-
-
-
Regional Outlook (Volume, Million Units; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
Research Methodology
The food processing blades market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each food processing blades segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue Capture Definition
Straight
Revenue is generated through the sale of straight food processing blades designed for linear cutting operations, including slicing, trimming, chopping, and portioning across industrial food processing applications.
Curved
Revenue is generated from the sale of curved food processing blades engineered for contour-based cutting, skinning, trimming, and specialized processing applications requiring enhanced cutting precision.
Circular
Revenue is generated through the sale of circular food processing blades used in high-speed rotary cutting, slicing, shredding, and portioning equipment across automated processing lines.
Segment - Application
Revenue Capture Definition
Grinding
Revenue is generated from blades manufactured for grinding equipment that facilitate size reduction and comminution of food products in industrial processing operations.
Slicing
Revenue is generated through the sale of blades specifically designed for the precision slicing of food products, ensuring uniform thickness and high processing efficiency.
Dicing
Revenue is generated from blades utilized in dicing equipment to produce uniform cubes or pieces of food products for commercial processing applications.
Skinning
Revenue is generated through the sale of specialized blades used for removing skin from meat, poultry, seafood, and other food products while minimizing product loss.
Peeling
Revenue is generated from blades designed for industrial peeling equipment used in the processing of fruits, vegetables, and similar agricultural products.
Cutting/Portioning
Revenue is generated through the sale of blades used for cutting, trimming, and portioning food products into standardized sizes to improve production efficiency and product consistency.
Segment – End Use
Revenue Capture Definition
Proteins
Revenue is generated from the sale of food processing blades utilized in processing protein-based products, including meat, poultry, seafood, and other animal-derived food products.
Other Foods
Revenue is generated through the sale of food processing blades used in processing fruits, vegetables, nuts, and other non-protein food categories across industrial manufacturing facilities.
Estimation Model
Layer No.
Layer Name
Key Question
Description
01
Food Processing Demand Layer
Where are food processing blades required?
Analyze demand across meat, poultry & seafood, fruits & vegetables, bakery, dairy, confectionery, beverages, and other food processing industries.
02
Food Processing Infrastructure & Equipment Investment Layer
Where is new equipment demand being created?
Evaluate investments in food processing facilities, processing line expansions, automation upgrades, and modernization projects. Assess greenfield plants, capacity additions, and replacement of aging processing equipment that drive procurement of new food processing blades.
03
Technology Adoption Layer
What proportion of processing operations utilize advanced blade technologies?
Segment demand by blade type, material, application, and end-use industry. Apply adoption rates based on food type, cutting precision, processing speed, hygiene requirements, wear resistance, and equipment compatibility.
04
Revenue Conversion Layer
How is market revenue generated?
Estimate annual shipments of food processing blades by blade type, application, end-use industry, and region. Quantify revenues generated exclusively from the sale of new food processing blades supplied to food processors, OEMs, equipment manufacturers, and distributors.
Customization Table
Client Request
Customization Delivered
Value Adds
Competitive Benchmarking
Benchmarked key food processing blade manufacturers based on product portfolio, blade technology, manufacturing capabilities, end-use specialization, geographic footprint, and competitive positioning across global and regional markets.
Enabled comparative assessment of market participants, technology leadership, and competitive positioning to support strategic decision-making.
Regional Segmentation
Evaluated regional demand by analyzing food processing capacity, automation levels, processed food production, manufacturing investments, and regulatory landscape across key geographic markets.
Identified high-potential regional markets and investment opportunities, facilitating market prioritization and expansion planning.
Opportunity assessment
Assessed growth opportunities across automated food processing, application-specific blade solutions, advanced materials, and emerging food manufacturing investments.
Highlighted high-value growth segments and demand trends, enabling targeted investment, product development, and market expansion strategies.
Frequently Asked Questions About This Report
Some of the key players operating in the food processing blades market include Minerva Omega group s.r.l., Biro Manufacturing Company, GEA Group Aktiengesellschaft, JBT Corporation, Marel, Nemco Food Equipment, LTD, and others.
Key factors include increasing demand for processed and packaged foods, rising automation in food processing facilities, growing emphasis on food safety and hygiene, and the need for precision cutting solutions that improve productivity and reduce material waste.
The global food processing blades market size was estimated at USD 1.1 billion in 2025 and is expected to be USD 1.2 billion in 2026.
The global food processing blades market, in terms of revenue, is expected to grow at a compound annual growth rate of 9.4% from 2026 to 2033 to reach USD 2.3 billion by 2033.
Asia Pacific is anticipated to be one of the fastest-growing regional markets over the forecast period, driven by expanding food processing industries, increasing consumption of processed foods, and rising investments in automated food manufacturing facilities.
The circular segment led the market with the largest revenue share of 40.0% in 2025.
The grinding segment accounted for the largest revenue share of 23.9% in 2025.
The proteins segment led the market with the largest revenue share of 63.2% in 2025.
Asia Pacific dominated the food processing blades market with the largest revenue share of 31.1% in 2025.
About the Author(s)
Food Safety & Processing Research Team
Consumer Goods · Food Safety & ProcessingThis report was authored by the food safety & processing research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the food safety & processing segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


