
- Home
- »
- Advanced Interior Materials
- »
-
Frac Sand Market Size, Share & Trends Report, 2026-2033GVR Report cover

Frac Sand Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Coarse, Fine), By Application (Oil & Gas, Industrial), By Region (North America, Europe, Asia Pacific, Latin America, Middle East & Africa), And Segment Forecasts
Market Size, 2025
$6.1BMarket Estimate, 2026
$6.5BMarket Forecast, 2033
$9.5BCAGR, 2026–2033
5.7%Frac Sand Market Summary
The global frac sand market size was valued at USD 6.1 billion in 2025 and is projected to grow from USD 6.5 billion in 2026 to USD 9.5 billion by 2033, at a CAGR of 5.7% from 2026 to 2033. North America market dominated, with a revenue share of 72.9% in 2025. Growth is driven by the increasing demand from unconventional oil & gas exploration activities, particularly in shale formations where longer horizontal laterals and higher-intensity hydraulic fracturing techniques require significantly larger volumes of high-quality proppants.
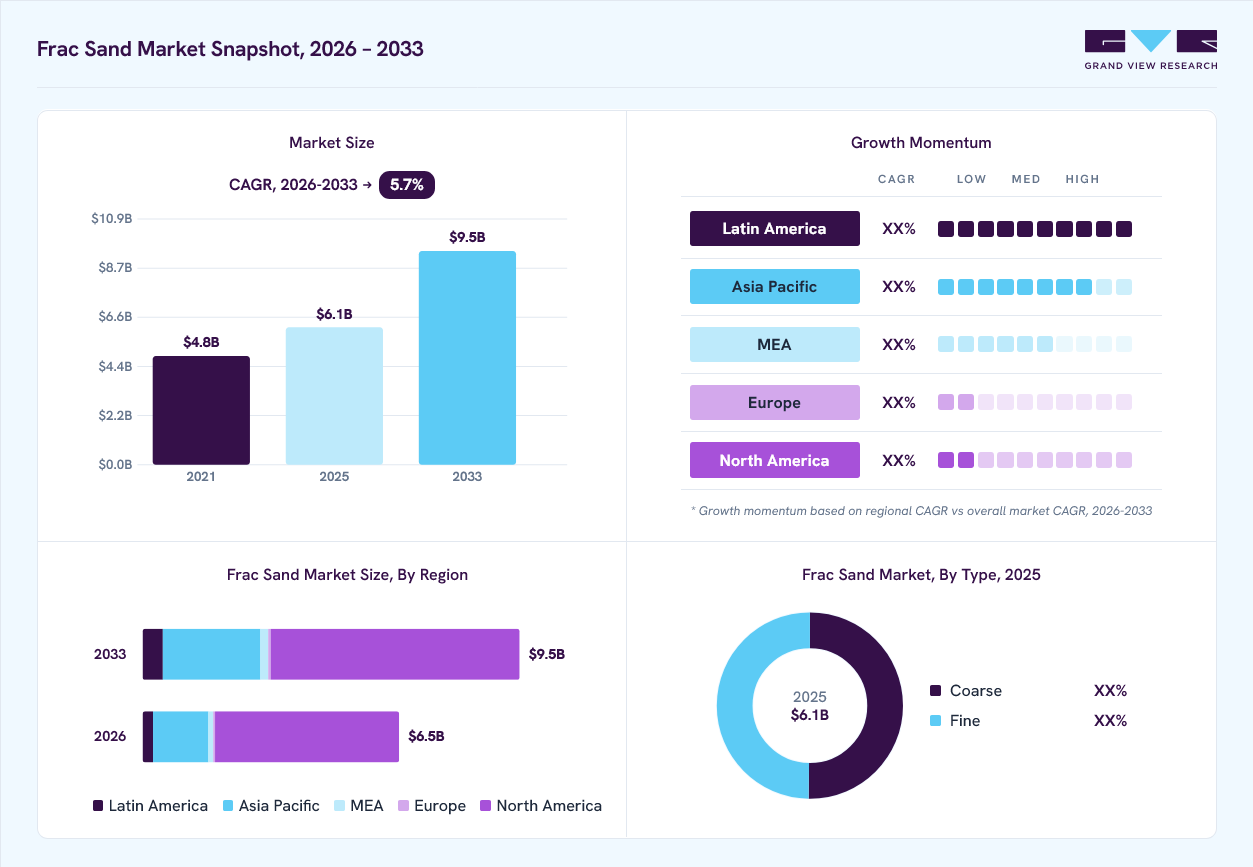 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Coarse type segment led the market with the largest revenue share of 50.2% in 2025.
- By application: Oil segment led the market with the largest revenue share of 84.6% in 2025.
Regional Highlights
- Largest regional market: North America (72.9% revenue share, 2025)
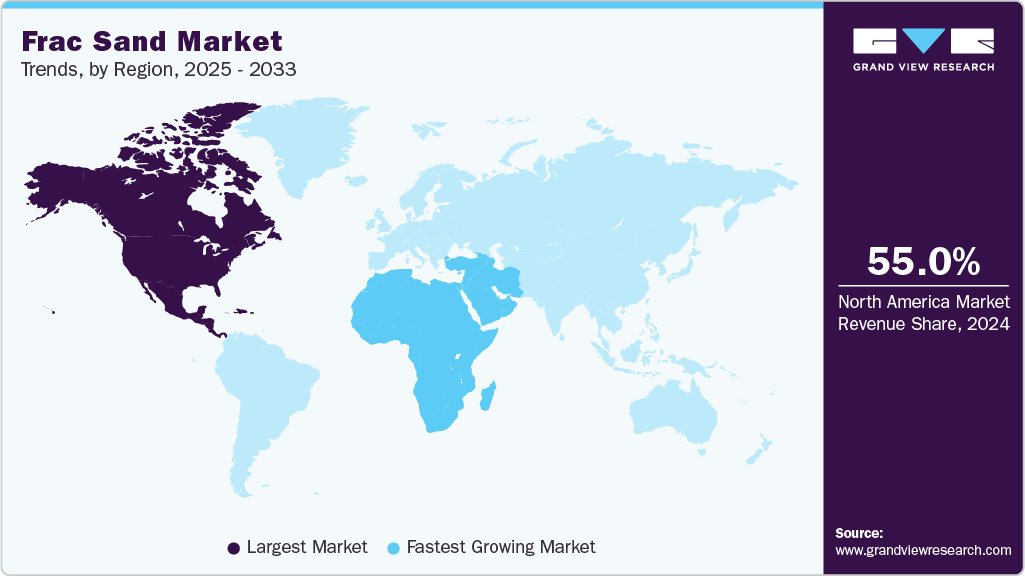
- Fastest-growing regional market: Latin America (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecasts
- Market size in 2025: USD 6.1 Billion
- Estimated market size in 2026: USD 6.5 Billion
- Projected market size by 2033: USD 9.5 Billion
- CAGR (2026-2033): 5.7%
Prism AI by Grand View Research Free to tryAsk a question about the frac sand marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
In addition, the shift toward multi-stage fracturing, rising drilling efficiencies, and the expansion of in-basin frac sand mines, which reduce transportation costs, are further supporting market expansion across key producing basins.Sustainability has become a central theme shaping the future of the market, with producers increasingly adopting environmentally responsible mining and processing practices. Regulatory pressures, community concerns, heightened scrutiny over land disturbance and dust emissions are driving companies to implement advanced reclamation programs, water recycling systems, and dust-suppression technologies at both mining and transloading sites. In addition, operators are optimizing logistics by shifting toward in-basin sand sourcing, which significantly reduces transportation-related emissions, fuel consumption, and overall environmental footprint. As ESG compliance becomes more integral to the oil and gas value chain, frac sand suppliers are prioritizing transparent reporting, responsible resource management, and the development of sustainable mining frameworks to align with operator expectations.
 To learn more about this report, Download Free Sample Report
Technological innovation is transforming frac sand production, handling, and usage, leading to increased efficiency and reduced operational costs. Producers are integrating automated washing, drying, and screening systems to enhance particle consistency and meet stringent proppant specifications. At the wellsite, innovative proppant delivery systems, real-time monitoring, and digital logistics platforms are streamlining proppant supply chains and reducing downtime. Advances in mine automation, drone-based site monitoring, and predictive maintenance are improving productivity and worker safety. Moreover, enhanced characterization technologies such as high-resolution grain analysis and crush-resistance modeling are enabling operators to optimize proppant selection for specific reservoir conditions. Collectively, these technological improvements support higher-intensity fracking operations while enhancing reliability and cost efficiency across the industry.
Market Dynamics
The growth of the frac sand market is primarily driven by the continued expansion of unconventional oil and gas exploration, particularly shale oil and shale gas production. Hydraulic fracturing operations require large quantities of high-purity silica sand to keep fractures open and improve hydrocarbon flow, making frac sand an essential proppant in well-completion activities. Rising drilling activity across major shale basins such as the Permian, Eagle Ford, and Bakken, along with sustained investments in upstream oil and gas projects, continues to strengthen demand for frac sand worldwide.
The increasing exploration and production of shale oil and shale gas are major factors driving growth in the frac sand market. Hydraulic fracturing relies on high-purity silica sand as a proppant to keep fractures open, allowing oil and natural gas to flow more efficiently from unconventional reservoirs. As energy companies expand drilling across key shale formations, demand for frac sand continues to rise.
Growing investments in unconventional resource development, supported by advancements in drilling technologies and favorable energy demand, are further accelerating frac sand consumption. Longer horizontal wells and multi-stage fracturing operations require significantly higher volumes of sand per well, strengthening the need for a reliable frac sand supply. This trend is expected to support sustained market growth as operators focus on maximizing production efficiency and improving hydrocarbon recovery.
Volatility in crude oil and natural gas prices is a significant restraint for the frac sand market, as fluctuations in energy prices directly influence upstream exploration and production investments. During periods of low oil and gas prices, operators often reduce drilling and hydraulic fracturing activities, leading to lower demand for frac sand. This uncertainty affects mining companies, processing facilities, and suppliers by creating inconsistent demand patterns and limiting long term capacity expansion investments.
The expansion of in basin frac sand mining facilities presents a significant opportunity for the frac sand market by reducing transportation costs and improving supply chain efficiency for oil and gas operators. Locally sourced sand enables faster deliveries, lower logistics expenses, and greater operational flexibility compared to sand transported over long distances. As exploration activities continue to expand across major shale basins, investments in regional mining, processing, and distribution infrastructure are expected to strengthen the availability of cost competitive frac sand and support long term market growth.
Analyst Perspective
The frac sand market is expected to witness stable long term growth, supported by continued investments in unconventional oil and gas exploration and the widespread adoption of hydraulic fracturing technologies. Frac sand remains an essential proppant for improving well productivity and hydrocarbon recovery, making it a critical component of shale oil and gas development. Increasing drilling activity, longer horizontal wells, and higher proppant loading per well are driving sustained demand, particularly across major shale basins in North America.
Type Insights
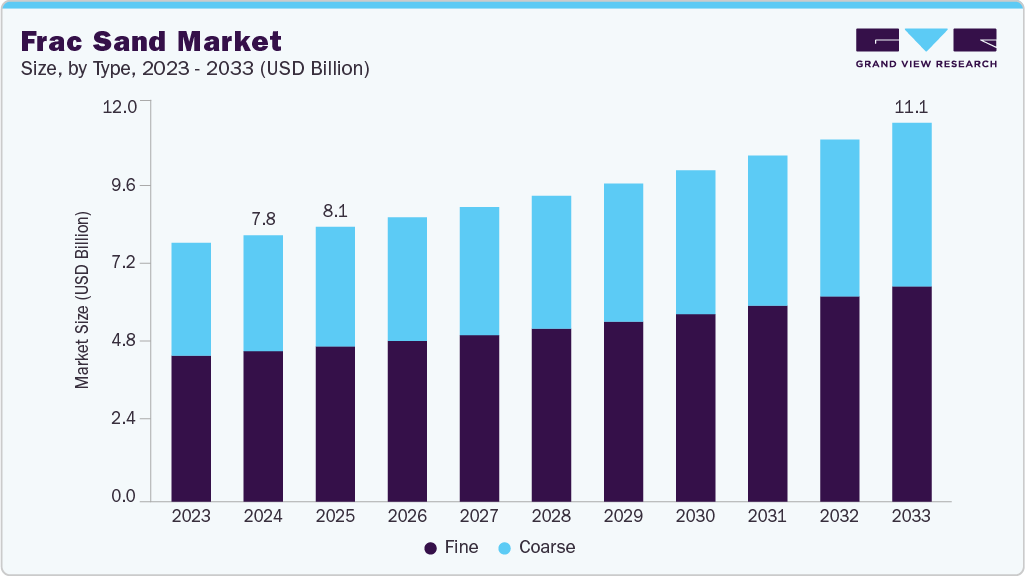
Coarse type segment led the market with the largest revenue share of 50.2% in 2025. However, its application remains secondary due to its more limited suitability for high-pressure wells and its greater sensitivity to reservoir conditions. While fine sand is cost-effective and commonly used in certain formations or as a blend to optimize proppant loads, its performance constraints restrict its usage in deeper or more demanding wells. However, operators are increasingly employing fine sand in low-pressure basins or during slickwater fracs to reduce costs, supporting steady but comparatively minor demand growth within this segment.
The coarse frac sand segment held a significant share in the market in 2024 due to its superior crush resistance, higher permeability, and widespread use in high-intensity hydraulic fracturing operations. Coarse grains are preferred in major shale plays such as the Permian and Eagle Ford, where operators continue to increase lateral lengths and fracture stages, requiring proppants that maintain conductivity under extreme downhole pressures. This segment also benefits from stable demand as exploration & production companies prioritize productivity and long-term recovery rates, making coarse sand the most commercially significant material in frac operations.
Application Insights
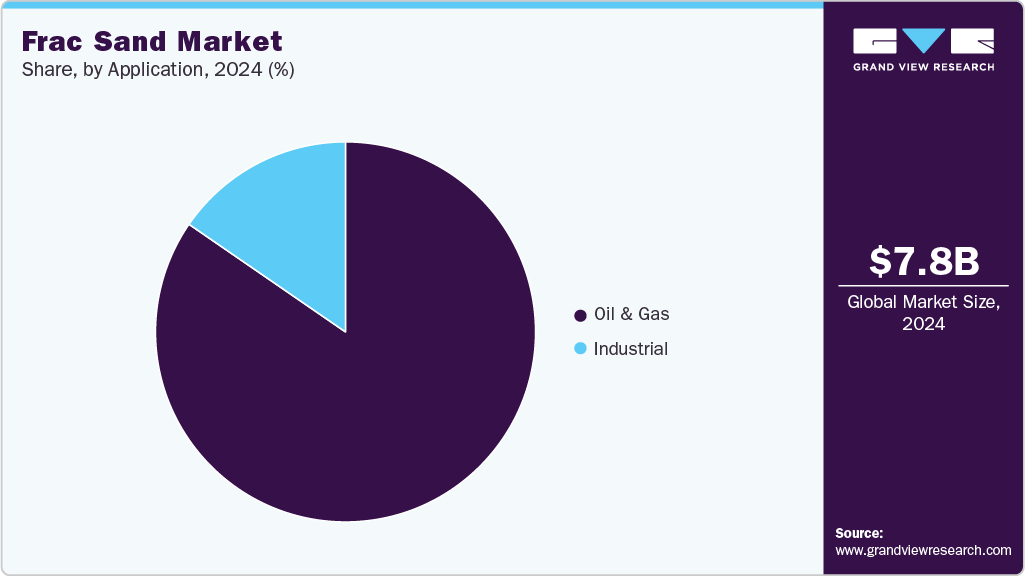
Based on application, oil segment led the market with the largest revenue share of 84.6% in 2025, driven by the continued expansion of shale gas and tight oil development. Hydraulic fracturing activities require massive volumes of proppants, with modern wells consuming thousands of tons of sand per completion. The shift toward high-intensity fracking, multi-well pads, and increased sand per lateral foot has reinforced the oil & gas sector as the primary demand center. The segment’s dominance is expected to persist, driven by drilling efficiencies, improved completion designs, and sustained upstream investment particularly in North America.
 To learn more about this report, Download Free Sample Report
The industrial segment, although significantly smaller, remains a crucial niche application for specific grades of silica sand used in glassmaking, foundries, filtration, and construction materials. Although industrial use does not match the scale or growth velocity of oil & gas applications, it provides a stable baseline of demand due to its integration into manufacturing value chains. Growth in this segment is influenced by developments in construction, automotive, and industrial production, offering steady but modest expansion compared to the high-volume requirements of hydraulic fracturing.
Regional Insights
North America dominated the frac sand market with the largest revenue share of 72.9% in 2025, driven by extensive shale development, high completion intensity, and a well-established proppant supply chain. The region continues to lead global demand due to its vast inventory of unconventional wells and the adoption of high-sand-loading completion designs, particularly in the Permian, Eagle Ford, and Haynesville basins. Strong logistics infrastructure, widespread use of in-basin sand, and continuous drilling efficiencies further reinforce North America’s dominant position, ensuring steady and resilient consumption throughout the forecast period.
 To learn more about this report, Download Free Sample Report
U.S. Frac Sand Market Trends
The frac sand market in the U.S., held the largest share in the North America region in 2025. The frac sand industry in the U.S. is the epicenter of global frac sand demand, accounting for the majority of consumption due to its unique scale of shale oil and gas operations. The nation’s prolific basins, such as the Permian and Appalachia, rely heavily on high-quality coarse sand to maximize healthy productivity and resource recovery. The rapid adoption of longer laterals, multi-well pad drilling, and high-intensity hydraulic fracturing continues to drive proppant usage per well to new highs. In addition, the U.S. hosts the world’s largest frac sand mining and processing network, which enables a reliable domestic supply and reinforces its leadership in the global market.
Asia Pacific Frac Sand Market Trends
Asia Pacific frac sand industry is an emerging growth region, supported by rising energy demand and the gradual expansion of unconventional exploration activities in China, Australia, and parts of Southeast Asia. China is increasing its investment in shale gas development, thereby boosting demand for both locally available proppants and high-quality silica sand imports. Although the region’s current consumption is lower than that of North America, improvements in drilling technologies, supportive government initiatives, and the push for energy security are expected to accelerate long-term market growth.
Europe Frac Sand Market Trends
Europe frac sand industry represents a smaller but stable market for frac sand, primarily driven by industrial applications and limited hydraulic fracturing activity. Countries such as Germany, Poland, and the UK maintain moderate demand due to their industrial manufacturing bases, which use specialized silica sand for glass, foundry, and filtration purposes. Environmental regulations and social opposition to fracking have constrained large-scale shale development, keeping oil & gas-related sand consumption relatively low. Nonetheless, incremental industrial growth and selective energy projects contribute to steady, albeit slower, market expansion across the region.
Key Frac Sand Company Insights
Some of the key players operating in the market include U.S. Silica Holdings, Hi-Crush Inc., Smart Sand Inc., and others.
-
U.S. Silica Holdings, established in 1900 and headquartered in Katy, Texas, is involved in the mining, processing, and distribution of industrial minerals, including silica sand used in oil and gas, industrial, and specialty applications. The company supplies a range of frac sand grades designed for hydraulic fracturing and proppant-related operations. U.S. Silica works on improving operational efficiency through process enhancements, product consistency initiatives, and the integration of advanced material-handling technologies.
-
Hi-Crush Inc., founded in 2010 and based in Houston, Texas, operates as a producer and supplier of proppant solutions for the oil and gas industry. The company manages mining, processing, and logistics assets that support the delivery of frac sand to major shale basins. Hi-Crush maintains a focus on improving supply chain reliability through efficient transportation systems, last-mile delivery services, and the adoption of site-level handling and storage technologies.
-
Smart Sand Inc., established in 2011 and headquartered in The Woodlands, Texas, engages in the production and supply of silica sand used primarily in hydraulic fracturing operations. The company offers various sand grades sourced from its mining and processing facilities, servicing operators and service companies across multiple drilling regions. Smart Sand focuses on operational continuity through effective resource management, logistics optimization, and the implementation of structured processes for material quality control.
Key Frac Sand Companies
The following key companies have been profiled for this study on the frac sand market.
-
Atlas Energy Solutions
-
Badger Mining Corporation
-
Black Mountain Sand
-
Covia Holdings
-
Emerge Energy Services
-
Hi-Crush Inc.
-
Pattison Company
-
Sibelco
-
Smart Sand Inc.
-
U.S. Silica Holdings
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g. Atlas Energy Solutions, Badger Mining Corporation)
- Mature participants in the frac sand market primarily focus on large scale mining operations, vertically integrated supply chains, and long term supply agreements with oilfield service companies and exploration and production operators.
- These companies operate extensive mining, washing, drying, storage, and logistics facilities to ensure a reliable supply of high quality frac sand for hydraulic fracturing activities.
- Established players possess significant competitive advantages through their ownership of high quality silica sand reserves, extensive processing infrastructure, and integrated logistics networks.
- Their ability to produce and deliver large volumes of frac sand consistently enables lower production costs, greater pricing competitiveness, and reliable supply for large hydraulic fracturing projects.
- Despite their strong market positions, mature players face challenges related to fluctuations in crude oil and natural gas prices, which directly influence hydraulic fracturing activity and frac sand demand.
- Mining and processing operations require substantial capital investments in extraction equipment, processing plants, transportation infrastructure, and environmental compliance systems.
Emerging & Regional Players (e.g., Black Mountain Sand)
- Emerging participants in the frac sand market generally focus on innovative resource recovery technologies, modular processing systems, and specialized environmental remediation services.
- Rather than competing directly with established waste management companies on project scale, these firms target niche opportunities involving critical metal recovery, construction material recycling, contaminated land remediation, and circular economy solutions.
- Emerging companies benefit from operational flexibility and the ability to establish mining and processing facilities close to major shale plays.
- Their localized operations reduce transportation distances, lower logistics costs, and enable faster delivery compared to suppliers shipping frac sand from distant mining regions.
- Emerging participants face significant challenges related to limited production capacity, restricted financial resources, and lower economies of scale.
- Competing against established producers with integrated mining operations, extensive rail networks, and large customer bases can be difficult, particularly during periods of reduced drilling activity and pricing pressure.
Recent Developments
-
U.S. Silica Holdings, in March 2025, reported the completion of upgrades at one of its Texas processing facilities to expand the production capacity of regionally sourced frac sand. The improvement aims to support the rise in offtake from oil and gas operators and strengthen supply reliability during peak drilling activity. The company noted that the updated unit incorporates process-control systems intended to maintain consistent product specifications.
-
Hi-Crush Inc., in February 2025, announced the expansion of its last-mile logistics infrastructure in the Permian Basin through the addition of new storage and handling units. The initiative aims to streamline proppant delivery operations and reduce transportation-related delays at well sites. According to the company, the added infrastructure will utilize automated loading systems to enhance operational continuity.
-
Smart Sand Inc., in January 2025, introduced an enhancement to its rail-based transloading network to increase throughput for frac sand shipments to key shale basins. The upgrade is designed to enhance material movement during peak demand periods and support long-term customer contracts. The company stated that the new configuration enables more efficient coordination between mining, transport, and distribution activities.
Frac Sand Market Report Scope
Report Attribute
Details
Market definition
Frac sand is high-purity silica sand characterized by uniform grain size, high crush resistance, and durability, primarily used as a proppant in hydraulic fracturing to enhance hydrocarbon recovery. The market size represents the total annual revenue generated from the sale of frac sand supplied across end-use applications globally.
Market size in 2025
USD 6.1 billion
Estimated market size in 2026
USD 6.5 billion
Projected market size by 2033
USD 9.5 billion
Growth rate
CAGR of 5.7% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million, volume in million tons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, volume forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, application, region.
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Russia; China; India; Japan; Australia; Brazil; Argentina
Key companies profiled
Atlas Energy Solutions; Badger Mining Corporation; Black Mountain Sand; Covia Holdings; Emerge Energy Services; Hi-Crush Inc.; Pattison Company; Sibelco; Smart Sand Inc.; U.S. Silica Holdings
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Frac Sand Market Report Segmentation
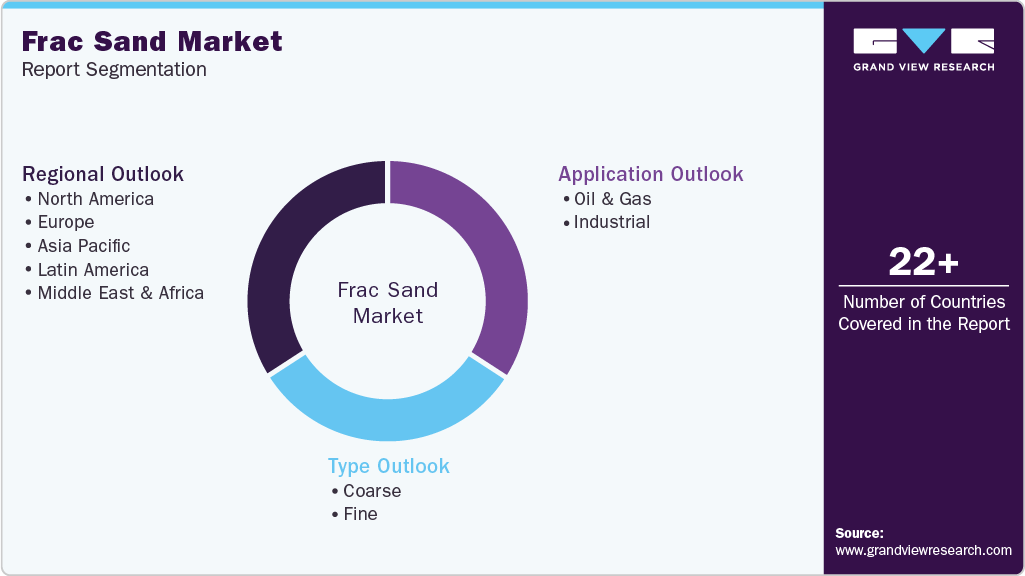
This report forecasts global, country, and regional revenue growth and analyzes the latest trends in each sub-segment from 2021 to 2033. For this study, Grand View Research has segmented the global frac sand market report by type, application, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Coarse
-
Fine
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Oil & Gas
-
Industrial
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Russia
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
South Africa
-
Iran
-
-
Research Methodology
The frac sand market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each frac sand segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Type
Revenue Capture Definition
Coarse
Includes larger mesh sizes (typically 20/40, 30/50, and similar grades) primarily utilized in hydraulic fracturing operations requiring high conductivity and crush resistance.
Fine
Includes finer mesh sizes (typically 40/70, 100 mesh, and similar grades) increasingly adopted in unconventional oil & gas wells due to improved reservoir contact and enhanced fracture distribution.
Application
Revenue Capture Definition
Oil & Gas
The oil & gas segment includes the use of frac sand as a proppant in hydraulic fracturing operations to keep fractures open and facilitate the flow of oil and natural gas from unconventional reservoirs such as shale formations, as well as in well stimulation and completion activities.
Industrial
The industrial segment includes the use of frac sand across non-oilfield applications such as glass manufacturing, foundry casting, construction materials, filtration systems, ceramics, chemical processing, and other industrial applications.
Estimation Model
Layer Name
Key Question
Description
Oil & Gas Exploration Demand Base Layer
What forms the demand base?
Identify global oil and natural gas exploration and production activities, particularly unconventional shale resources. Assess hydraulic fracturing operations, drilling rig counts, well completions, and investments in upstream oil & gas projects to establish the total addressable demand for frac sand.
Hydraulic Fracturing Penetration Layer
Where is frac sand utilized?
Estimate the penetration of frac sand across key applications including shale oil, shale gas, tight oil, and tight gas wells. Analyze the adoption of coarse and fine frac sand grades across horizontal drilling and hydraulic fracturing operations in major producing regions. Evaluate regional demand based on drilling intensity and well completion activities.
Frac Sand Consumption Intensity Layer
How much frac sand is consumed?
Analyze frac sand consumption intensity based on the number of wells completed, lateral well length, fracture stage count, proppant loading per well, and completion design. Evaluate average frac sand usage across different well types and geological formations. Consumption intensity varies according to reservoir characteristics, drilling technologies, and completion techniques.
Revenue Layer
How is market revenue generated?
Market revenue is quantified through the sale of frac sand products supplied to oilfield service providers and exploration & production companies. Revenue generation is driven by hydraulic fracturing activity, well completion volumes, and demand for high purity silica sand. Market value is influenced by oil & gas prices, drilling activity, frac sand grades, logistics costs, and regional supply demand dynamics.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Frac Sand Market Assessment
Customized analysis of frac sand demand, production capacity, shale drilling activity, and consumption trends across key regions and countries.
Supported identification of high-growth regional markets, supply-demand gaps, and strategic expansion opportunities for market participants.
Frac Sand Pricing & Supply Chain Analysis
Detailed assessment of pricing trends, transportation costs, rail and trucking logistics, procurement dynamics, and supply chain challenges influencing frac sand distribution.
Provided insights into cost optimization opportunities, pricing fluctuations, logistics efficiency, and sourcing strategies across major shale basins.
Competitive Landscape & Strategic Benchmarking
Comprehensive evaluation of major frac sand producers, regional suppliers, operational strategies, production capacities, partnerships, and expansion activities.
Enabled understanding of competitive positioning, regional market share dynamics, and strategic developments shaping the frac sand industry.
Frequently Asked Questions About This Report
The key players operating in the frac sand market are Atlas Energy Solutions; Badger Mining Corporation; Black Mountain Sand; Covia Holdings; Emerge Energy Services; Hi-Crush Inc.; Pattison Company; Sibelco; Smart Sand Inc.; U.S. Silica Holdings
North America market dominated, with a revenue share of 72.9% in 2025.
The global frac sand market is driven by rising shale oil and gas activity, which requires higher volumes of proppants for hydraulic fracturing. Increasing use of longer laterals and multi-stage fracs is boosting sand consumption per well. Steady growth in completion activity across major basins further supports demand.
Latin America is the fastest-growing region over the forecast period.
Coarse type segment led the market with the largest revenue share of 50.2% in 2025.
The frac sand market is expected to grow at a CAGR of 5.7% from 2026 to 2033, reaching USD 9.5 billion by 2033.
Oil segment led the market with the largest revenue share of 84.6% in 2025.
The frac sand market size was valued at USD 6.1 billion in 2025 and is estimated at USD 6.5 billion in 2026.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


