
- Home
- »
- Beauty & Personal Care
- »
-
Hair Accessories Market Size And Share Report, 2026-2033GVR Report cover

Hair Accessories Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Clips & Pins, Head Bands, Wigs & Extensions, Elastics & Ties), By Distribution Channel (Supermarkets & Hypermarkets, General Stores, Online), By Region, And Segment Forecasts
Market Size, 2025
$25.2BMarket Estimate, 2026
$27.2BMarket Forecast, 2033
$46.6BCAGR, 2026–2033
8.0%Hair Accessories Market Summary
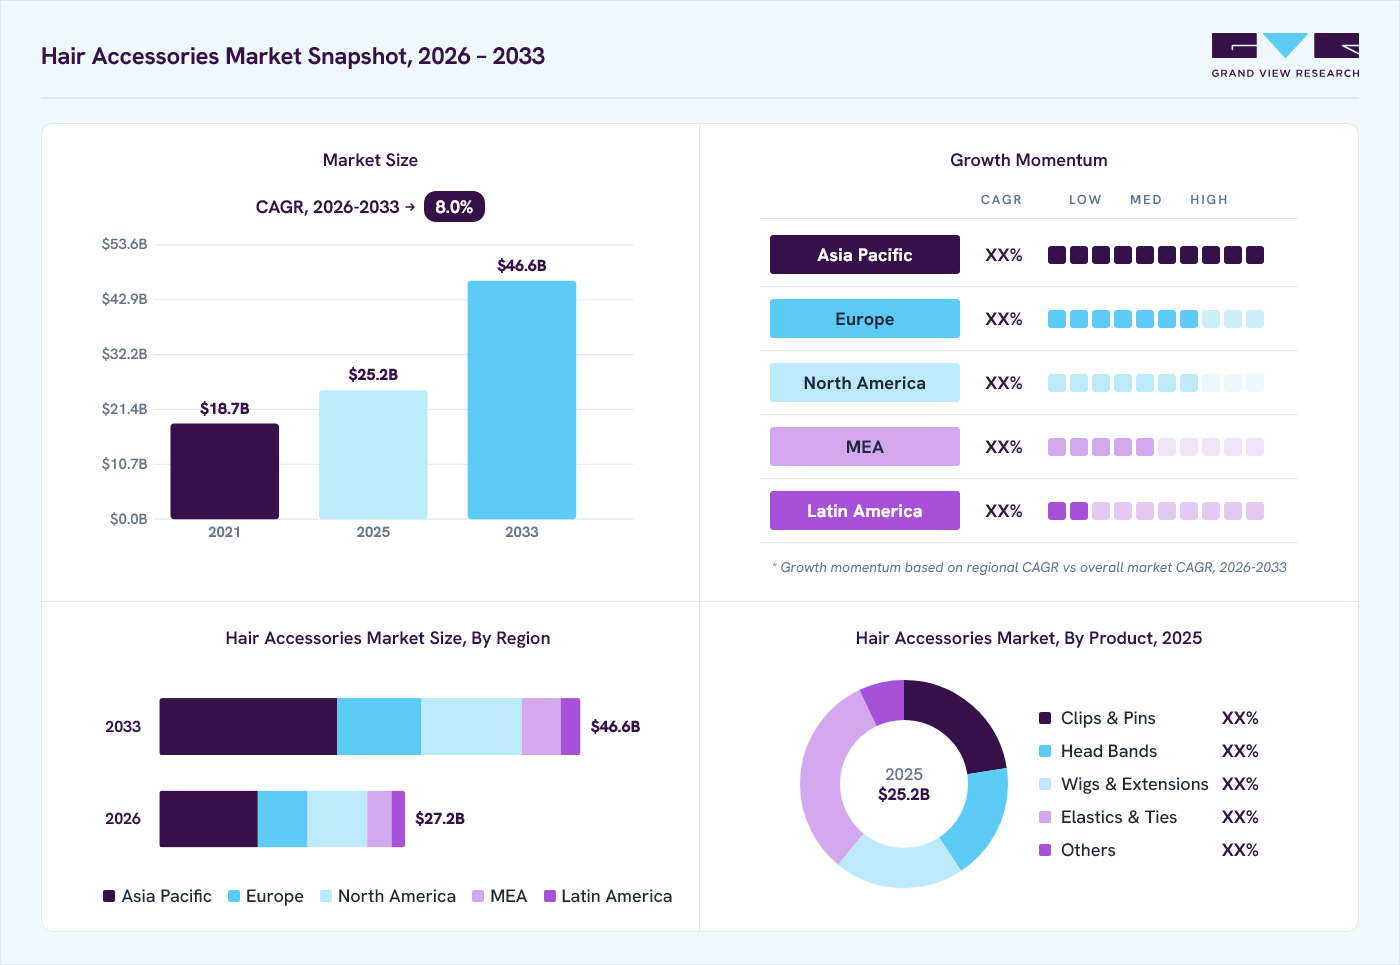
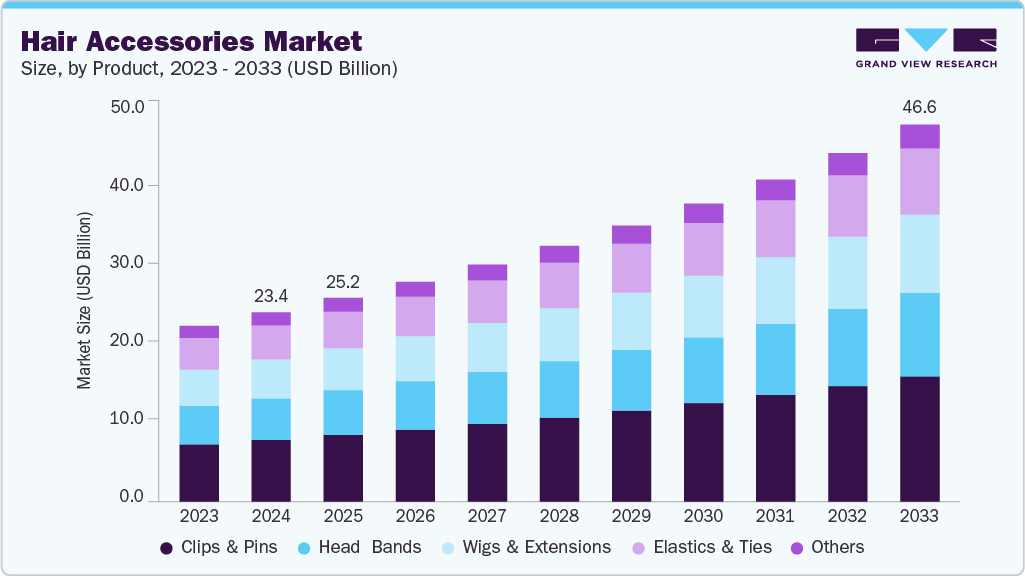
The global hair accessories market size was valued at USD 25.2 billion in 2025 and is projected to grow from USD 27.2 billion in 2026 to USD 46.6 billion by 2033, at a CAGR of 8.0% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 39.8% in 2025. The market growth is attributed to a rising preference for fashionable products that serve a utility purpose and give a trendy look to the hairdo.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Elastics & ties segment dominated the market, with a revenue share of 32.0% in 2025.
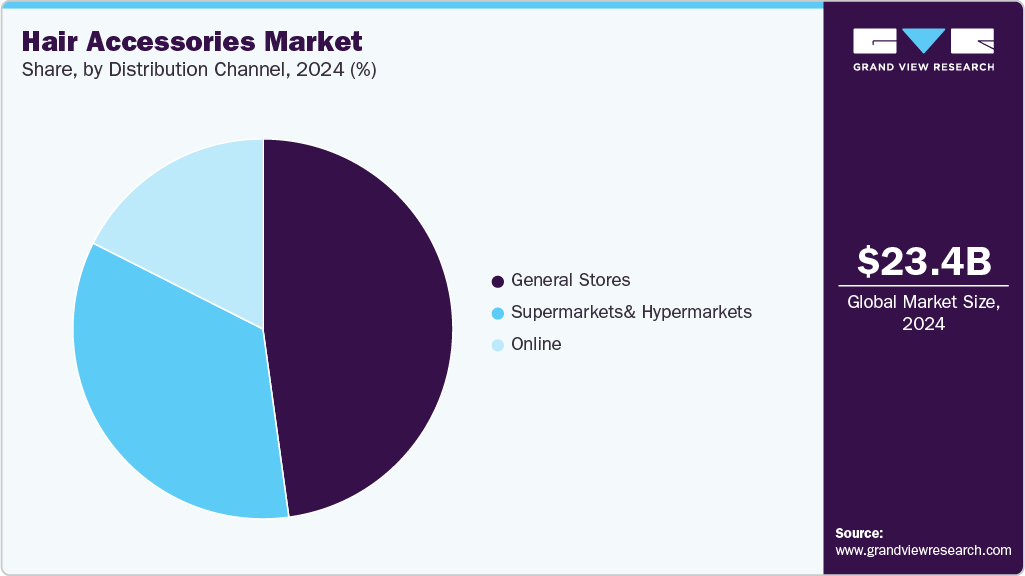
- By distribution channel: General stores segment held the largest market share of 47.6% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (39.8% revenue share, 2025)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 25.2 Billion
- Estimated market size in 2026: USD 27.2 Billion
- Projected market size by 2033: USD 46.6 Billion
- CAGR (2026-2033): 8.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Furthermore, the increasing popularity and availability of videos, tutorials, and pictures of trendy hairstyles and hair accessories have evolved the fashion tastes among consumers, which, in turn, is expected to propel the market growth.The internet has played a key role in making consumers more familiar with hair accessories through social media influencers, bloggers, and vloggers. According to a 2024 survey, approximately 69% of consumers trust influencer recommendations more than traditional advertising. Gen Z is twice as likely to purchase based on an influencer recommendation compared to millennials. This shows the growing importance of influencer marketing in reaching and engaging consumers, especially within the 18 to 34-year-old demographic.
 To learn more about this report, Download Free Sample Report
Personalized hair accessories are gaining popularity as consumers seek unique items that reflect their styles. From monogrammed clips to DIY kits, the market embraces customization, allowing consumers to express their creativity and preferences through bespoke designs. For instance, Kitsch offers customizable hair accessories including monogrammed scrunchies, clips, and headbands. Customers can choose initials, colors, and styles to create unique pieces that reflect their personality. Their DIY kits also allow for personal creativity.
Environmental consciousness is influencing consumer choices, leading to a surge in demand for hair accessories made from sustainable materials. Brands increasingly offer products crafted from biodegradable, cruelty-free, and recycled materials such as bamboo, organic cotton, and vegan leather. This shift caters to eco-aware consumers and aligns with global sustainability goals. For instance, KOOSHOO is renowned for its commitment to sustainability, offering hair accessories made from GOTS-certified organic cotton and natural rubber. Their products are dyed using low-impact, non-toxic dyes in a solar-powered facility. Additionally, KOOSHOO utilizes FSC-certified recycled paper for packaging, ensuring a plastic-free and biodegradable product lifecycle.
Rising demand for cute, themed, or character-based hair accessories for young girls contributes significantly to market volume. Colorful, cartoon-based clips and bows (e.g., Disney, Peppa Pig) are especially popular among young girls. These accessories are used for school, events, and everyday wear, driving high sales volumes and fostering early brand loyalty.
Hair accessories are integral to rituals (like weddings or festivals) in regions such as India and Africa. Due to cultural continuity, bridal hairpieces, decorative pins, and religious ornaments stay in high demand. Consumers appreciate traditional, handcrafted designs-especially within diaspora communities-sustaining demand for culturally specific accessories through global e-commerce and niche artisan marketplaces.
Market Dynamics
The global hair accessories market is driven by evolving fashion trends, increasing beauty and personal grooming expenditure, and growing consumer demand for products that combine functionality with style. Demand is increasingly influenced by social media, celebrity trends, and seasonal fashion cycles, while intense competition and product commoditization continue to shape pricing dynamics across the market.
A key driver of the market is the increasing consumer emphasis on personal appearance, hairstyling, and self-expression. Hair accessories such as clips, bands, scrunchies, pins, and headbands are increasingly used as both functional grooming products and fashion accessories, supporting demand across diverse age groups and consumer segments.
Market growth is constrained by the highly fragmented nature of the industry and the widespread availability of low-cost alternatives. Many hair accessories offer limited technological or functional differentiation, resulting in frequent price-based competition and relatively low brand loyalty among consumers.
A significant opportunity exists in the growing demand for premium, designer-inspired, and sustainable hair accessories made from high-quality fabrics, recycled materials, and eco-friendly components. As consumers increasingly seek products that align with fashion trends and sustainability preferences, premium and differentiated product offerings are expected to capture a larger share of market value growth.
Analyst Perspective
The hair accessories market is characterized by high purchase frequency, rapid fashion cycles, and a strong influence of beauty and lifestyle trends. Demand is supported by both functional hair management needs and fashion-driven purchasing behavior across diverse consumer groups. Market value is increasingly concentrated in premium, trend-led, and aesthetically differentiated products, while competition remains fragmented across mass-market retailers, fashion brands, and niche accessory specialists. Over the forecast period, product design, brand positioning, and responsiveness to evolving consumer trends are expected to remain key competitive differentiators.
Consumer Insights & Surveys
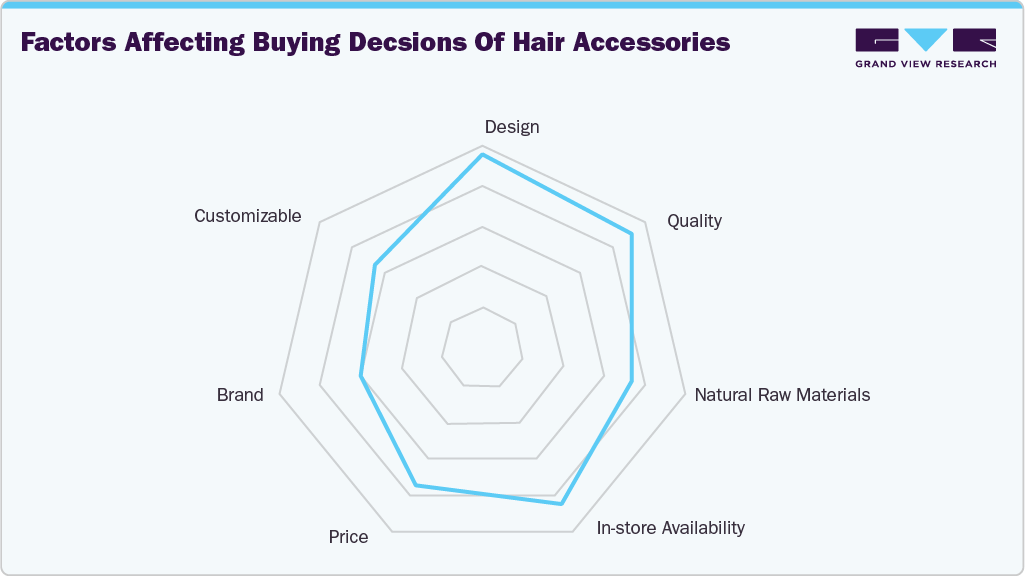
Quality, design, brand, value for money, price, in-store availability, customization, and use of natural raw materials are some of the major factors that govern consumers' buying decisions when it comes to hair accessories. Among the abovementioned factors, quality and design play key roles in product selection. Consumers generally look for designs that go well with the current trends. However, price, in-store availability, use of natural raw materials, and customization are crucial factors influencing consumers’ purchasing decisions.
 To learn more about this report, Download Free Sample Report
Growing awareness around health and environmental sustainability is motivating consumers to choose hair accessories made from natural materials and free from synthetic components. Recently, wig buyers have voiced increasing concern about product safety and long-term effects, leading to a preference for human hair wigs over synthetic ones. Human hair wigs offer greater versatility-they can be colored, curled, and straightened easily, making them more attractive to consumers.
Similarly, due to environmental concerns, there is a rising aversion to plastic hair ties. As a result, eco-friendly alternatives such as biodegradable hair ties made from organic cotton and natural rubber are gaining popularity.
Economic conditions also play a critical role in shaping consumer purchasing behavior. With relatively higher purchasing power, North American and European consumers are more inclined to invest in premium, branded, and higher-quality hair accessories.
In addition, advertising, marketing efforts, and social media significantly influence buying decisions and brand preferences, often prompting consumers to switch between brands based on perceived value or trends.
Product Insights
Based on product, elastics & ties segment led the market with the largest revenue share of 32.0% in 2025. The broad assortment of available products largely drives the expansion of the elastics and ties segment in design, shape, and material. While these items were traditionally made from leather or rubber, advancements in manufacturing technologies have enabled producers to incorporate fabrics like silk, velvet, sateen, and mesh. This has resulted in more stylish and refined options that secure hair and complement the wearer’s overall look.
Hair elastics and ties have remained a staple for women, serving as essential tools for everyday hair management. Their continued market leadership is supported by their affordability, widespread accessibility, and extensive variety. Leading brands such as Claire’s and Conair Corporation offer diverse collections, reinforcing the segment’s strong global hair accessories industry position.
Demand for wigs & extensions grow at the fastest CAGR over the forecast period, driven by increasing demand for high-quality human hair products, which are favored over synthetic options for their natural appearance and versatility. These accessories are particularly popular among consumers with curly and textured hair and those seeking solutions for hair thinning caused by sun exposure and chemical treatments. Instead of undergoing expensive and invasive hair transplant procedures, many are turning to wigs and extensions as a practical alternative. Pricing plays a crucial role in consumer choices and depends on factors such as hair type (natural or synthetic), length, texture, color, cap construction (lace front, monofilament, etc.), brand, and whether the wig is heat-friendly. This variety in features and price points has contributed to the segment's widespread appeal and expanding market presence.
Distribution Channel Insights
Based on the distribution channel, the sale of hair accessories through general stores led the market with a revenue share of 47.6% in 2025. General stores, which range from small neighborhood shops to larger outlets, commonly carry daily-use items like groceries, personal care products, snacks, drinks, newspapers, and basic beauty essentials. These stores typically provide a limited but sufficient selection of products, enabling customers to make quick and convenient purchases. Often situated in busy, high-traffic areas, general stores such as Sainsbury’s, Londis, Mast General Store, Krystals Express, Casey’s General Stores, and fuel station outlets like Buc-ee’s, Boston, and Kelly’s Market cater to a wide range of shoppers. In response to rising interest in hair accessories, many stores have started stocking items like clips, pins, headbands, and hair ties. They attract the typical convenience store clientele and working individuals, women, and families who appreciate buying these accessories individually or in smaller quantities. Consumers are drawn to general stores for their accessibility, familiar product availability, and the convenience of repeat purchases.
 To learn more about this report, Download Free Sample Report
The online sales channels are anticipated to register fastest growing CAGR over the forecast period. The rise of online distribution has greatly transformed consumer shopping behaviors by offering convenience, such as doorstep delivery, simple payment options, attractive discounts, and access to a wide variety of products on one platform. Major market players are increasingly launching e-commerce websites in key markets, driven by growing internet access and the popularity of mobile shopping. For instance, UK-based hair accessory brand Tegen Accessories sells items like banana clips, hair claws, snap clips, and chignon pins directly through its website. Additionally, many mid-sized brands expand their reach by listing products on established online retailers such as Amazon, Next, Walmart, and Target. The COVID-19 pandemic accelerated this shift toward digital shopping, making consumers more cautious about in-person purchases and inclined to shop online to minimize exposure in crowded stores.
Regional Insights
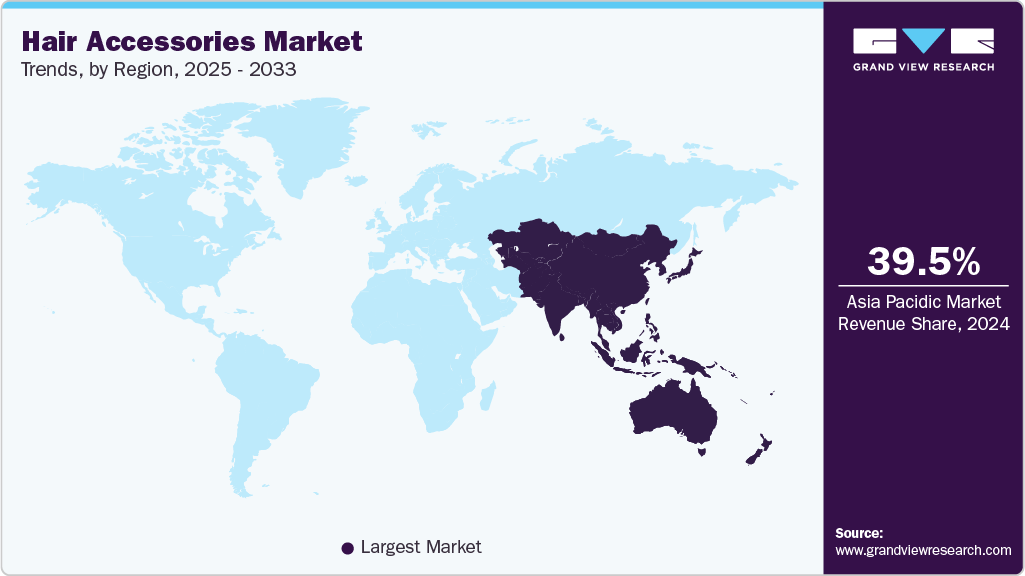
Asia Pacific dominated the hair accessories market with the largest revenue share of 39.8% in 2025. The increasing number of working women, especially in the corporate and fashion sectors, has driven the demand for hair accessories in developing countries such as India, Indonesia, and China. According to the survey in 2023, approximately 60.5% of women were employed in China, surpassing the global average of 51.16% and outperforming many developed nations. This increase in women in the workforce, coupled with the rising spending power of consumers, has driven spending on a range of grooming products, including hair accessories.
 To learn more about this report, Download Free Sample Report
China Hair Accessories Market Trends
The hair accessories market in China held the market share of 37.7 % in the Asia Pacific region in 2025, owing to a high-frequency, impulse-driven consumption model anchored in micro-trends, local manufacturing speed, and integrated social commerce. Yiwu-based supply chains produce trend-led items like Hanfu hairpins and acetate claw clips within days at ultra-low price points. Live-streamers on Douyin, Xiaohongshu, and Taobao market these accessories as daily "dopamine dressing" accents, leveraging seamless mobile checkouts to convert social media engagement into constant impulse buys.
The growing influence of Western culture and increased awareness of fashion trends and hairstyles drive the demand for hair accessories in India. Rising numbers of working women and their higher disposable incomes have further boosted spending on these products. The market is evolving from being largely unorganized and unbranded to featuring curated collections from luxury boutiques, high-street brands, and international players, with e-commerce playing a key role in expanding consumer access. Hair accessories like elastics, ties, clips, and pins are becoming everyday essentials for many Indian women, especially with the growing popularity of elaborate hairstyles.
At the same time, hair loss and thinning have become common issues affecting both men and women, leading to increased demand for wigs and extensions as affordable alternatives to costly hair treatments and surgeries. India’s position as a leading manufacturer of hair wigs globally is expected to support strong growth in this segment, contributing significantly to the overall hair accessories industry.
U.S. Hair Accessories Market Trends
In the U.S., having healthy, shiny, and well-maintained hair has become an important part of many individuals’ daily routines to enhance their overall appearance. As a result, people are increasingly caring for their hair, trying out various hairstyles, and embracing trendy and innovative hair accessories to suit their styles. As a developed nation with the largest global economy and the second-highest purchasing power parity, the U.S. market benefits from strong consumer spending. This growing interest in grooming products and high disposable income is expected to drive significant growth in the hair accessories industry over the coming years.
The Trump administration's recent tariffs have significantly impacted the U.S. hair accessories market, particularly affecting products imported from China. In April 2025, the U.S. imposed a 145% tariff on certain Chinese goods, including synthetic and human hair products essential for braids, wigs, and weaves. While this rate was later reduced to 30%, the initial increase led to substantial price hikes. For instance, synthetic braiding hair that previously cost $3-$5 per pack now ranges from $10 to $12, and human hair wigs have seen price increases of up to $100.
Small business owners in the beauty supply industry, such as those in Atlanta and Detroit, report that these tariffs have strained their operations. Many rely on Chinese imports for their inventory, and the elevated costs have forced them to either absorb the price increases or pass them on to customers, potentially reducing sales. Companies like Bellami Hair have introduced a 10% tariff surcharge on their products to mitigate the financial impact.
Key Hair Accessories Company Insights
The dominance of major companies such as Goody Products Inc., Claire’s, H&M, and Conair Corporation continues to define the upper tier of the competitive spectrum in the hair accessories industry.
-
Goody Products, Inc. is a well-known American brand focusing on hair accessories and styling tools. Founded in 1907 by Abraham and Henry Goodman, the company has become a trusted name in personal care, offering diverse products such as brushes, combs, elastics, clips, and barrettes. Based in Atlanta, Georgia, Goody mainly functions as a private-label brand, with its products available through major retailers like Walmart, Target, CVS, and Amazon.
-
Claire’s is a prominent American retailer specializing in fashion accessories, jewelry, and beauty products. It primarily targets tweens, teens, and young adults. Founded in 1961 by Rowland Schaefer as Fashion Tress Industries, the company initially focused on fashion wigs. The company is headquartered in Hoffman Estates, Illinois, and operates over 2,750 stores across 17 countries, including North America and Europe, under the Claire’s and Icing brands.
Key Hair Accessories Companies
The following key companies have been profiled for this study on the hair accessories market.
-
Goody Products Inc.
-
Claire’s Stores Inc.
-
Conair LLC
-
H&M Hennes & Mauritz Retail Private Limited
-
Forever 21
-
Annie International Inc.
-
Silke London
-
HAIRDRAMACO INDIA PRIVATE LIMITED
-
Bunzee Bands, LLC
-
Jennifer Behr, LLC
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Goody Products Inc., Claire’s Stores Inc., Conair LLC, H&M Hennes & Mauritz Retail Private Limited, Forever 21, Annie International Inc.)
- Focus on product portfolio expansion, fashion trend alignment, retail distribution growth, and mass-market accessibility across multiple price segments.
- Strong brand recognition, extensive retail presence, broad product portfolios, and established supply chain capabilities.
- Higher exposure to changing fashion trends, inventory risks, and intense competition from low-cost manufacturers and private-label brands.
Emerging Players (Silke London, HAIRDRAMACO INDIA PRIVATE LIMITED, Bunzee Bands, LLC, Jennifer Behr, LLC)
- Focus on premium hair accessories, niche styling solutions, direct-to-consumer sales, and differentiated product designs and materials.
- Greater flexibility, stronger product differentiation, and closer alignment with premium and fashion-conscious consumer segments.
- Limited distribution reach, lower brand awareness, and fewer financial and marketing resources compared to established market participants.
Recent Developments
-
In February 2025, Goody partnered with fashion brand LoveShackFancy to launch a limited-edition collection of 35 hair accessories, including brushes, clips, scrunchies, and headbands adorned with vintage floral designs. The collection features four signature LoveShackFancy prints, blending the brand's whimsical and romantic aesthetic with Goody's functional designs.
-
In February 2025, the Conair 2-in-1 Heat & Heatless Hair Curler Set. This innovative styling tool offers versatility by allowing users to choose between heat styling on dry hair and heatless styling on damp hair. The set includes a satin curling ribbon, a claw clip, two scrunchies, a USB cord for heating, and a satin pouch for storage. The smooth satin material ensures shiny curls without heat damage, and the curler can be adjusted to accommodate various hair lengths.
-
In March 2024, Claire's announced a collaboration with Walgreens to introduce its range of fashion accessories, including hair products, to over 4,400 Walgreens locations across the United States. This partnership aims to make Claire's trendy hair accessories more accessible to shoppers nationwide, featuring dedicated displays within the seasonal sections of participating Walgreens stores.
Hair Accessories Market Report Scope
Report Attribute
Details
Market size in 2025
USD 25.2 billion
Estimated market size in 2026
USD 27.2 billion
Projected market size by 2033
USD 46.6 billion
Growth rate
CAGR of 8.0 % from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; Japan; India; South Korea; Australia & New Zealand; Brazil; South Africa
Key companies profiled
Goody Products Inc.; Claire’s Stores Inc.; Conair LLC; H&M Hennes & Mauritz Retail Private Limited; Forever 21; Annie International Inc.; Silke London; HAIRDRAMACO INDIA PRIVATE LIMITED; Bunzee Bands, LLC; Jennifer Behr, LLC
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Hair Accessories Market Report Segmentation
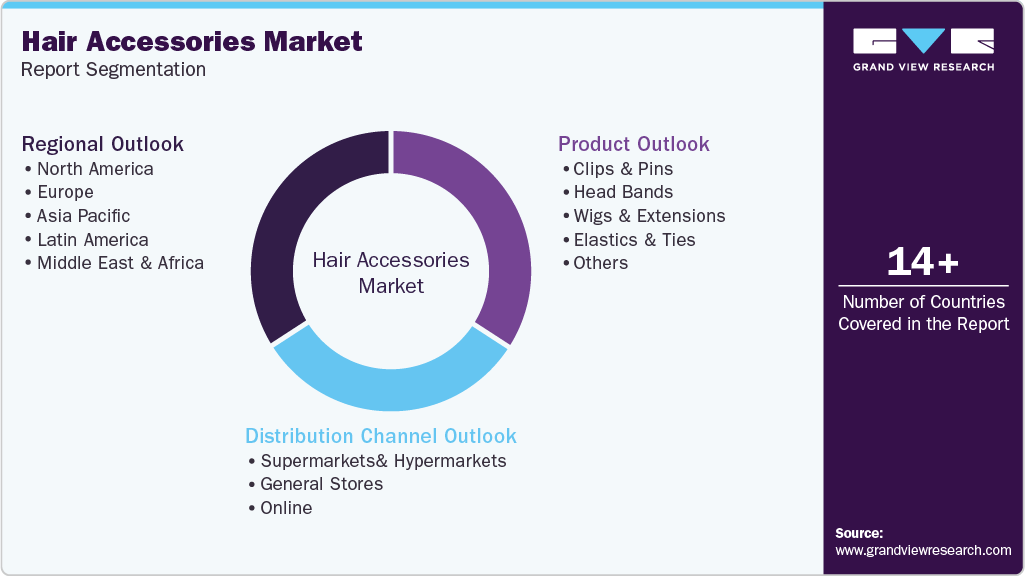
This report forecasts revenue growth at the global level and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global hair accessories market report by product, distribution channel, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Billion, 2021 - 2033)
-
Clips & Pins
-
Head Bands
-
Wigs & Extensions
-
Elastics & Ties
-
Others
-
-
Distribution Channel Outlook (Revenue, USD Billion, 2021 - 2033)
-
Supermarkets& Hypermarkets
-
General Stores
-
Online
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
-
Middle East and Africa (MEA)
-
UAE
-
-
Research Methodology
The hair accessories market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each hair accessories segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Clips & Pins
Revenue is generated from the sale of hair clips, barrettes, bobby pins, claw clips, and similar hair-styling, securing, and decorative accessories. Revenue includes purchases across mass-market, premium, and fashion accessory channels.
Head Bands
Revenue is generated from the sale of headbands for fashion, hair management, sports, and personal grooming. Revenue includes purchases across offline and online retail channels.
Wigs & Extensions
Revenue is generated through the sale of hair wigs, hairpieces, and extensions used for cosmetic enhancement, fashion, and hair volume or length augmentation purposes. Revenue includes both synthetic and natural hair products.
Elastics & Ties
Revenue is generated from the sale of hair elastics, scrunchies, ponytail holders, and hair ties used to secure and style hair. Revenue includes purchases across everyday grooming and fashion applications.
Others
Revenue is generated through the sale of other hair accessories, including hair combs, decorative hair jewelry, hair wraps, hair sticks, and specialty styling accessories. Revenue includes purchases through both offline and online distribution channels.
Estimation Model
Layer Name
Key Question
Description
Addressable Consumer Base Layer
Who forms the addressable customer base?
Individuals across different age groups utilizing hair care, grooming, styling, and fashion accessories as part of their personal care routines.
Hair Styling & Grooming Participation Layer
Who actively uses hair accessories?
Consumers regularly engaging in hair styling, hair management, fashion-focused grooming, and appearance enhancement activities.
Hair Accessories Adoption Layer
Which consumers purchase hair accessories?
Consumers purchasing clips & pins, headbands, wigs & extensions, elastics & ties, and other hair accessories for functional, fashion, and cosmetic purposes.
Monetisation Layer
How much revenue is generated?
Revenue generated through the sale of hair accessories across product categories, price points, brands, and distribution channels.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Distribution Channel Influence Assessment (Channel × Purchase Behavior)
Assessed the role of supermarkets, fashion retailers, beauty specialty stores, salons, and e-commerce platforms in product discovery, brand selection, and purchase conversion.
Reveals where revenue is captured across the sales ecosystem and supports channel investment and go-to-market strategies.
Purchase Frequency & Replacement Cycle Assessment
Evaluated purchasing frequency, replacement behavior, and accessory ownership patterns across key consumer groups and product categories.
Reveals recurring revenue drivers and highlights segments with the strongest volume-generation potential.
Fashion Trend & Premiumization Analysis (Design Preference × Price Positioning)
Assessed the influence of fashion trends, material preferences, branding, and premium styling features on consumer purchasing decisions.
Highlights high-margin growth opportunities and supports product development, pricing, and brand positioning strategies.
Frequently Asked Questions About This Report
The global hair accessories market size was valued at USD 25.2 billion in 2025 and is estimated at USD 27.2 billion for 2026.
The global hair accessories market is expected to grow at a CAGR of 8.0% from 2026 to 2033, reaching USD 46.6 billion.
Elastics & ties segment dominated the market, with a revenue share of 32.0% in 2025 while wigs and extensions segment is fastest growing segment.
Key factors driving the hair accessories market growth include rising fashion and social media trends, expanding e-commerce access, and strong influence from celebrities and influencers, along with growing demand for everyday grooming and seasonal style changes.
General stores led the market with a revenue share of 47.6% in 2025.
Asia Pacific dominated with a 39.8% revenue share in 2025.
Key players include Goody Products Inc.; Claire’s Stores Inc.; Conair LLC; H&M Hennes & Mauritz Retail Private Limited; Forever 21; Annie International Inc.; Silke London; HAIRDRAMACO INDIA PRIVATE LIMITED; Bunzee Bands, LLC; Jennifer Behr, LLC..
About the Author(s)
Beauty & Personal Care Research Team
Consumer Goods · Beauty & Personal CareThis report was authored by the beauty & personal care research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the beauty & personal care segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


