
- Home
- »
- Medical Devices
- »
-
Hand-held Surgical Instruments Market Size Report, 2033GVR Report cover

Hand-held Surgical Instruments Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Forceps, Retractors, Dilators), By Application (Orthopedic Surgery, Cardiology, Ophthalmology), By End-use, By Region, And Segment Forecasts
Market Size, 2025
$6.1BMarket Estimate, 2026
$6.5BMarket Forecast, 2033
$11.2BCAGR, 2026–2033
8.0%Hand-held Surgical Instruments Market Summary
The global hand-held surgical instruments market size was valued at USD 6.1 billion in 2025 and is projected to grow from USD 6.5 billion in 2026 to USD 11.2 billion by 2033, at a CAGR of 8.0% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 34.7% in 2025. Factors expected to drive market growth include the increasing number of surgical procedures, rising prevalence of chronic diseases, technological advancements in surgical instruments, and growing demand for minimally invasive and specialized surgical procedures.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Retractors segment led the market with the largest revenue share of 19.2% in 2025.
- By application: Orthopedic surgery segment led the market with the largest revenue share of 17.6% in 2025.
- By end use: Hospitals segment led the market with the largest revenue share of 69.3% in 2025.
Regional Highlights
- Largest regional market: North America (34.7% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 6.1 Billion
- Estimated market size in 2026: USD 6.5 Billion
- Projected market size by 2033: USD 11.2 Billion
- CAGR (2026-2033): 8.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
A direct answer, usually in 1 working day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Instruments such as forceps, scalpels, and retractors are essential across general, orthopedic, and minimally invasive surgeries. Innovations in ergonomic designs and durable materials enhance precision and reduce surgeon fatigue. Emerging markets, such as Asia-Pacific and Latin America, contribute to growth through increased healthcare investments.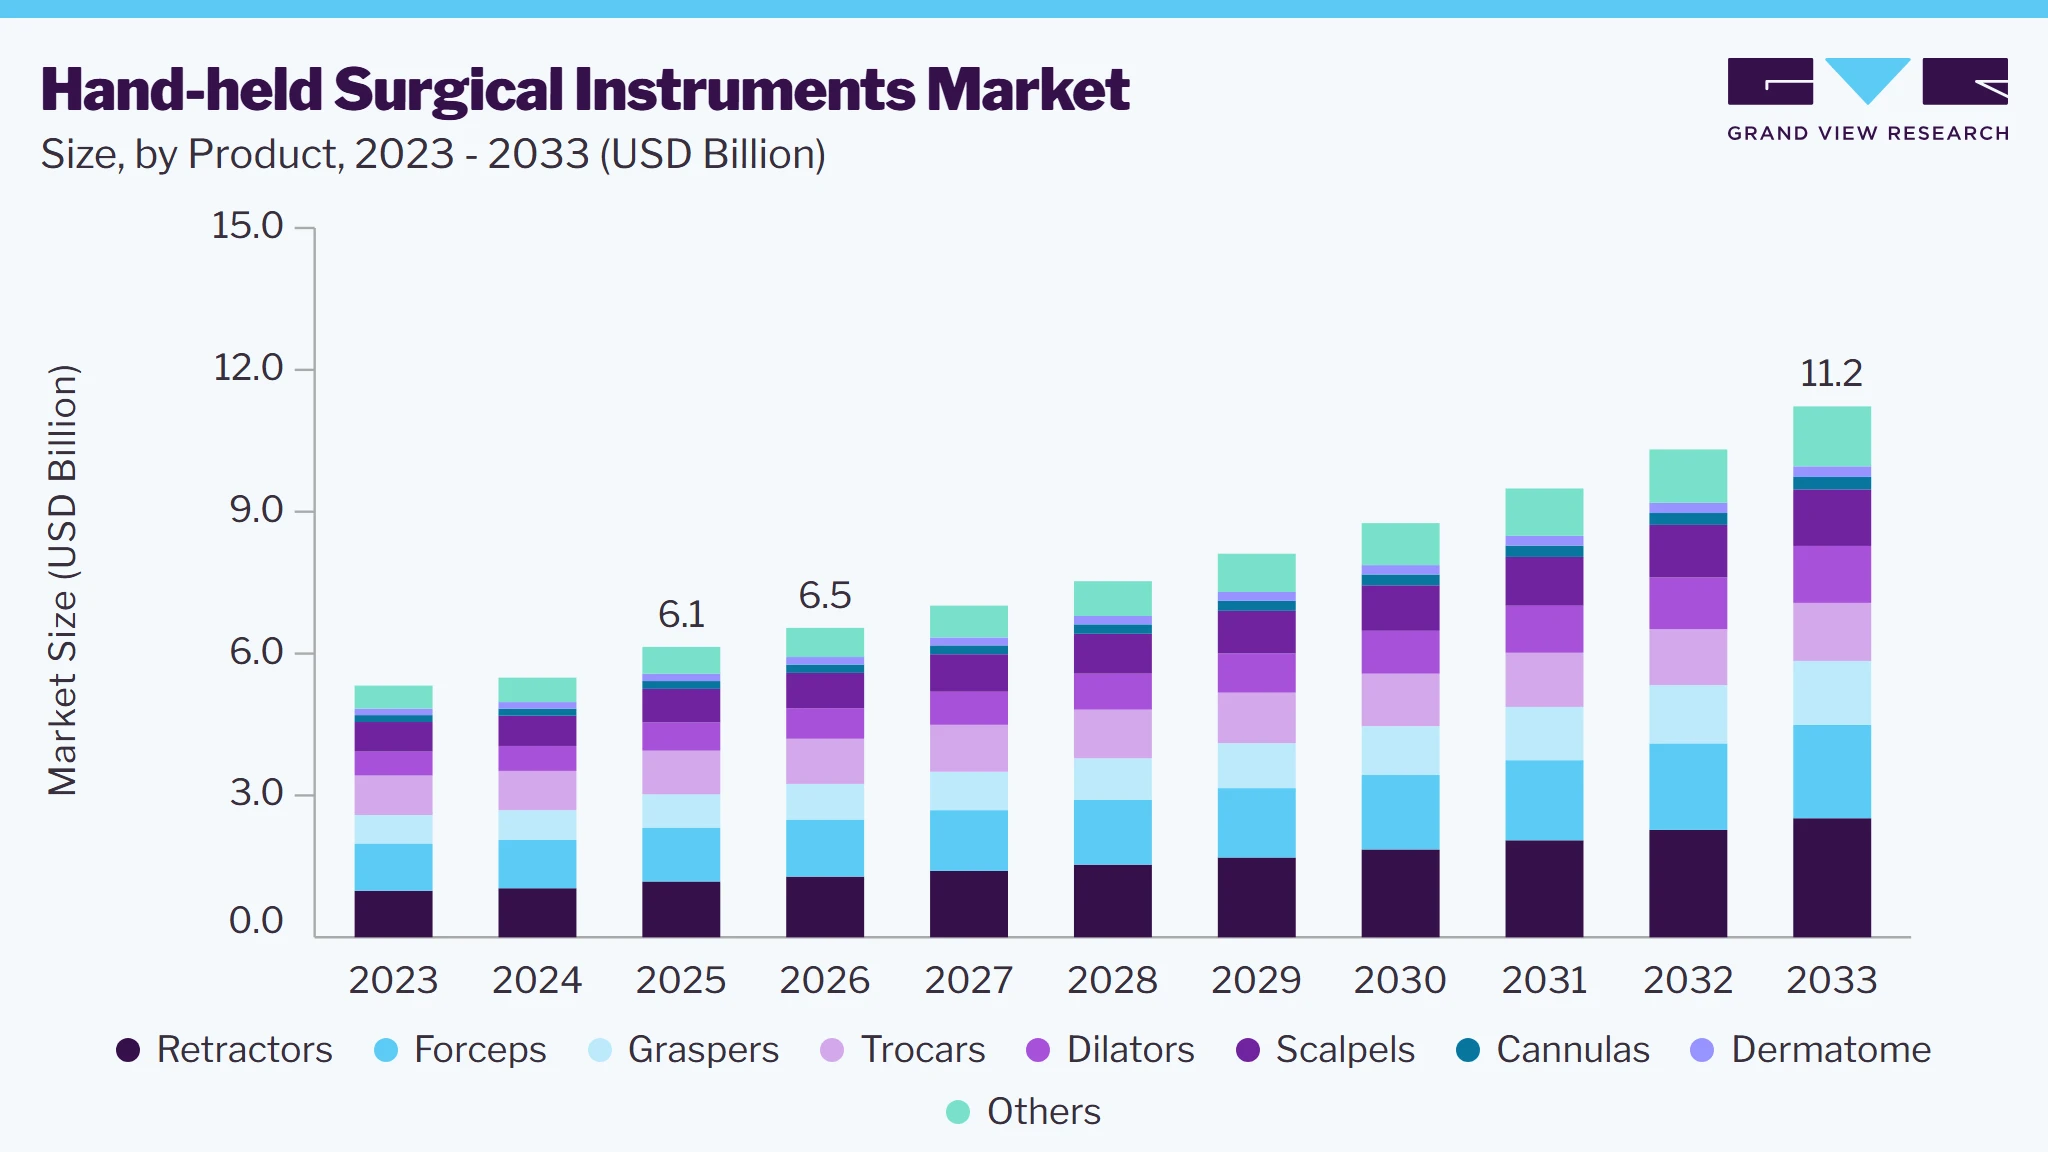 To learn more about this report, Download Free Sample Report
The growing number of surgical procedures, particularly aesthetic surgeries, is a key driver for the hand-held surgical instruments market. Popular procedures like breast surgery, eyelid surgery, liposuction, nose reshaping, and tummy tucks have seen increased demand in recent years, boosting the need for hand-held surgical instruments. Additionally, the global rise in heart diseases, driven by factors such as physical inactivity, obesity, smoking, poor nutrition, and family history, is contributing to market growth. The CDC reports that in 2020, approximately 20.1 million adults aged 20 and older had coronary artery disease. The aging population, especially those over 60, is more prone to cardiovascular, orthopedic, and neurological disorders, further driving demand for surgical tools. Moreover, the rising number of road accidents is another significant factor fueling the market for hand-held surgical instruments.
Innovations in surgical instruments and the increasing adoption of advanced devices by surgeons are expected to drive the hand-held surgical instruments market in the coming years. In 2021, bioengineering students at the University of Illinois introduced a new design for obstetric forceps, featuring silicone Shape Deposition Manufacturing (SDM) fingers to enhance safety and ease during delivery. Surgeons continue to prioritize high-quality instruments that enable efficient and precise surgeries without compromising patient health. An example of such innovation is the advanced powered screwdriver, designed for delicate surgeries, incorporating sensors and software to provide real-time intelligence to the surgeon.
The market also sees growing investments in research and development (R&D) to develop instruments tailored to specific surgical needs. For instance, hand-held instruments for robotic-assisted surgeries are becoming more prevalent, reflecting the trend toward automation and precision in medical procedures. Additionally, government initiatives to improve healthcare infrastructure in emerging economies are expected to create lucrative opportunities for market players.
Market Dynamics
Hand-held surgical instruments are witnessing increasing adoption across hospitals, ambulatory surgical centers, specialty clinics, and outpatient care settings as they enable surgeons and healthcare professionals to perform a wide range of surgical procedures with enhanced precision, control, and procedural efficiency. These instruments incorporate advanced design features such as ergonomic configurations, lightweight materials, disposable and reusable formats, enhanced grip mechanisms, minimally invasive compatibility, and high-performance stainless steel or polymer-based components to support safe and effective surgical interventions across multiple specialties. Handheld surgical instruments help healthcare providers address the growing demand for efficient and high-quality surgical care by facilitating improved surgical accuracy, reduced procedure times, enhanced patient outcomes, greater support for minimally invasive and outpatient procedures, optimized operating room workflows, and reduced healthcare costs. Their widespread application across general surgery, orthopedic surgery, cardiovascular procedures, gynecology, neurosurgery, ophthalmology, and other specialty areas continues to drive market growth, particularly amid rising surgical volumes, increasing preference for minimally invasive procedures, and expanding healthcare infrastructure globally.
Increasing prevalence of chronic diseases is emerging as a significant driver for the growth of the hand-held surgical instruments market. The rising global burden of chronic conditions such as cardiovascular diseases, cancer, orthopedic disorders, diabetes, and gastrointestinal diseases has led to a substantial increase in the number of surgical interventions performed worldwide. Patients suffering from chronic illnesses often require repeated surgical procedures, minimally invasive treatments, and long-term disease management, thereby increasing the demand for efficient, precise, and portable surgical instruments. Handheld surgical instruments are extensively utilized across various specialties owing to their ease of use, improved surgical precision, and compatibility with both conventional and minimally invasive procedures. Furthermore, the growing aging population, which is more susceptible to chronic diseases, coupled with expanding healthcare infrastructure and increasing surgical volumes in hospitals, ambulatory surgical centers, and outpatient settings, is further accelerating market growth.
The growing preference for minimally invasive and non-invasive procedures is expected to restrain the growth of the handheld surgical instruments market. Advances in technologies such as robotic-assisted surgery, catheter-based interventions, endoscopic procedures, and image-guided therapies are reducing the reliance on traditional open surgical procedures that require a wide range of handheld instruments. In addition, increasing patient demand for procedures associated with shorter hospital stays, reduced pain, faster recovery times, and lower risk of complications is encouraging healthcare providers to adopt less invasive treatment approaches. As a result, the reduced volume of conventional surgeries in certain specialties may limit the demand for traditional handheld surgical instruments, thereby restraining market growth to some extent.
Market Concentration & Characteristics
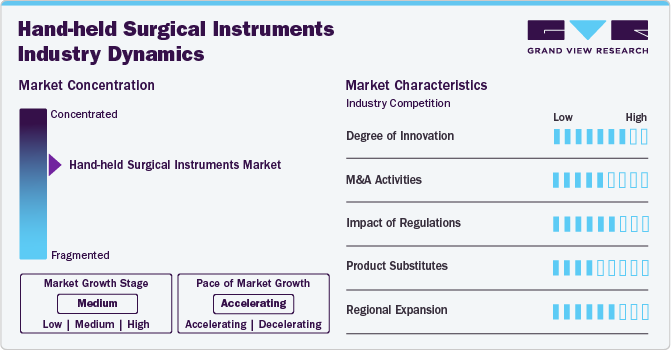
The hand-held surgical instruments industry is moderately concentrated, with a few key players dominating the market, including Medtronic, Stryker, and Johnson & Johnson. These companies lead through extensive product portfolios, global distribution networks, and robust research and development (R&D) efforts. The industry is characterized by a focus on innovation, such as ergonomic designs, durability, and precision. It is highly regulated, with stringent quality standards ensuring safety and performance. While large manufacturers hold significant market shares, smaller players also contribute by offering specialized instruments and targeting niche markets. The industry is influenced by growing healthcare demands and technological advancements.
The hand-held surgical instruments industry is highly innovative, with manufacturers continuously introducing advanced technologies to enhance precision, safety, and efficiency. Innovations such as ergonomic designs, lightweight materials, and advanced coatings improve instrument handling and reduce surgeon fatigue. The development of specialized tools, like Wexler Surgical’s VATS Viper Forceps introduced in July 2024, highlights the trend towards creating instruments tailored for specific procedures, such as Video-Assisted Thoracoscopic Surgery (VATS). These forceps offer improved maneuverability, control, and precision, optimizing outcomes for minimally invasive surgeries. Technological advancements, including integrated sensors and powered tools, are also shaping the future of surgical instruments.
 To learn more about this report, Download Free Sample Report
Regulations play a critical role in the hand-held surgical instruments industry, ensuring safety, effectiveness, and quality. Regulatory bodies such as the U.S. FDA and the European Medicines Agency (EMA) impose strict guidelines on the manufacturing, testing, and approval processes for surgical tools. These regulations include biocompatibility, sterilization standards, and performance benchmarks. Compliance with these standards is crucial for market entry and maintaining product safety. Additionally, ongoing regulatory changes, such as updates to sterilization protocols or material requirements, influence product development. Strict adherence to regulations ensures that only safe, effective, and high-quality instruments reach healthcare providers and patients.
Mergers and acquisitions (M&A) in the hand-held surgical instruments industry have been growing as companies seek to expand their technological capabilities, product portfolios, and market presence. In November 2024, StarFish Medical, a prominent North American medical device development company, has announced its acquisition of Omnica Corporation, a renowned medical device design and engineering firm based in Southern California. The acquisition includes Omnica's 25,000-square-foot facility in Irvine, CA, where the company develops various medical products such as disposables, diagnostic tools, hand-held instruments, monitoring equipment, point-of-care devices, and surgical instruments. Such strategic moves enable companies to improve operational efficiency and accelerate innovation, further driving competition and growth within the industry.
In the hand-held surgical instruments industry, product substitutes include robotic surgical systems, which offer greater precision, control, and minimally invasive options for procedures. These systems, such as the da Vinci Surgical System, reduce the reliance on traditional hand-held tools by offering enhanced automation and real-time imaging capabilities. Additionally, 3D-printed surgical instruments are emerging as potential substitutes, providing customized solutions that may reduce costs and improve functionality. Despite these advancements, traditional hand-held instruments remain essential for many procedures, especially in settings where high precision and manual control are crucial, keeping them highly relevant in the surgical field.
The hand-held surgical instruments industry is witnessing significant regional expansion, driven by rising healthcare demands and technological advancements. In North America and Europe, established healthcare infrastructures and the adoption of minimally invasive surgeries are key growth factors. Emerging markets in Asia-Pacific, particularly China and India, are expanding rapidly due to increasing healthcare investments and a growing patient population. Additionally, the demand for advanced surgical tools is rising in Latin America and the Middle East, where healthcare modernization is underway.
Analyst Perspective
The global hand-held surgical instruments market is positioned at the convergence of several long-term healthcare, surgical care, and medical device industry trends, including the increasing volume of surgical procedures worldwide, rising demand for precision-based interventions, and continuous advancements in ergonomic and specialty-specific surgical instrument technologies. Growing clinical requirements associated with complex surgical procedures, trauma management, cardiovascular interventions, orthopedic reconstructions, minimally invasive surgeries, and routine general surgical procedures are creating substantial opportunities for handheld surgical instrument manufacturers as healthcare providers increasingly seek highly reliable, precision-engineered, and cost-effective surgical tools that enhance procedural efficiency and patient outcomes. Furthermore, the increasing emphasis on surgical safety, infection prevention, and workflow optimization is accelerating the adoption of advanced handheld surgical instruments across diverse healthcare settings. In addition, the market is benefiting from the expansion of surgical services across both developed and emerging healthcare systems, supported by rising healthcare expenditure, expanding hospital infrastructure, and increasing access to surgical care.
Product Insights
Based on product, the retractors segment led the market with the largest revenue share of 19.2% in 2025 and is expected to grow at the fastest CAGR over the forecast period. Forceps are essential for grasping, holding, or manipulating tissues during surgeries, offering precision and control. The rise in usage is attributable to its advantages, such as it helps in eliminating the need for holding minute objects with hands and avoid contamination. Their versatility makes them crucial in procedures across specialties like obstetrics, cardiology, orthopedics, and neurosurgery. The growing number of surgeries, especially minimally invasive ones, further boosts the demand for forceps.
However, the graspers segment is expected to experience maximum growth with a CAGR of 9.4% over the forecast period. Graspers are essential for holding, manipulating, or removing tissue during delicate procedures, offering enhanced precision and control. The need for specialized graspers grows as the demand for MIS rises, driven by benefits like shorter recovery times and reduced complications. Technological advancements, such as robotic-assisted surgeries and ergonomic designs, are further contributing to the segment's growth.
End-use Insights
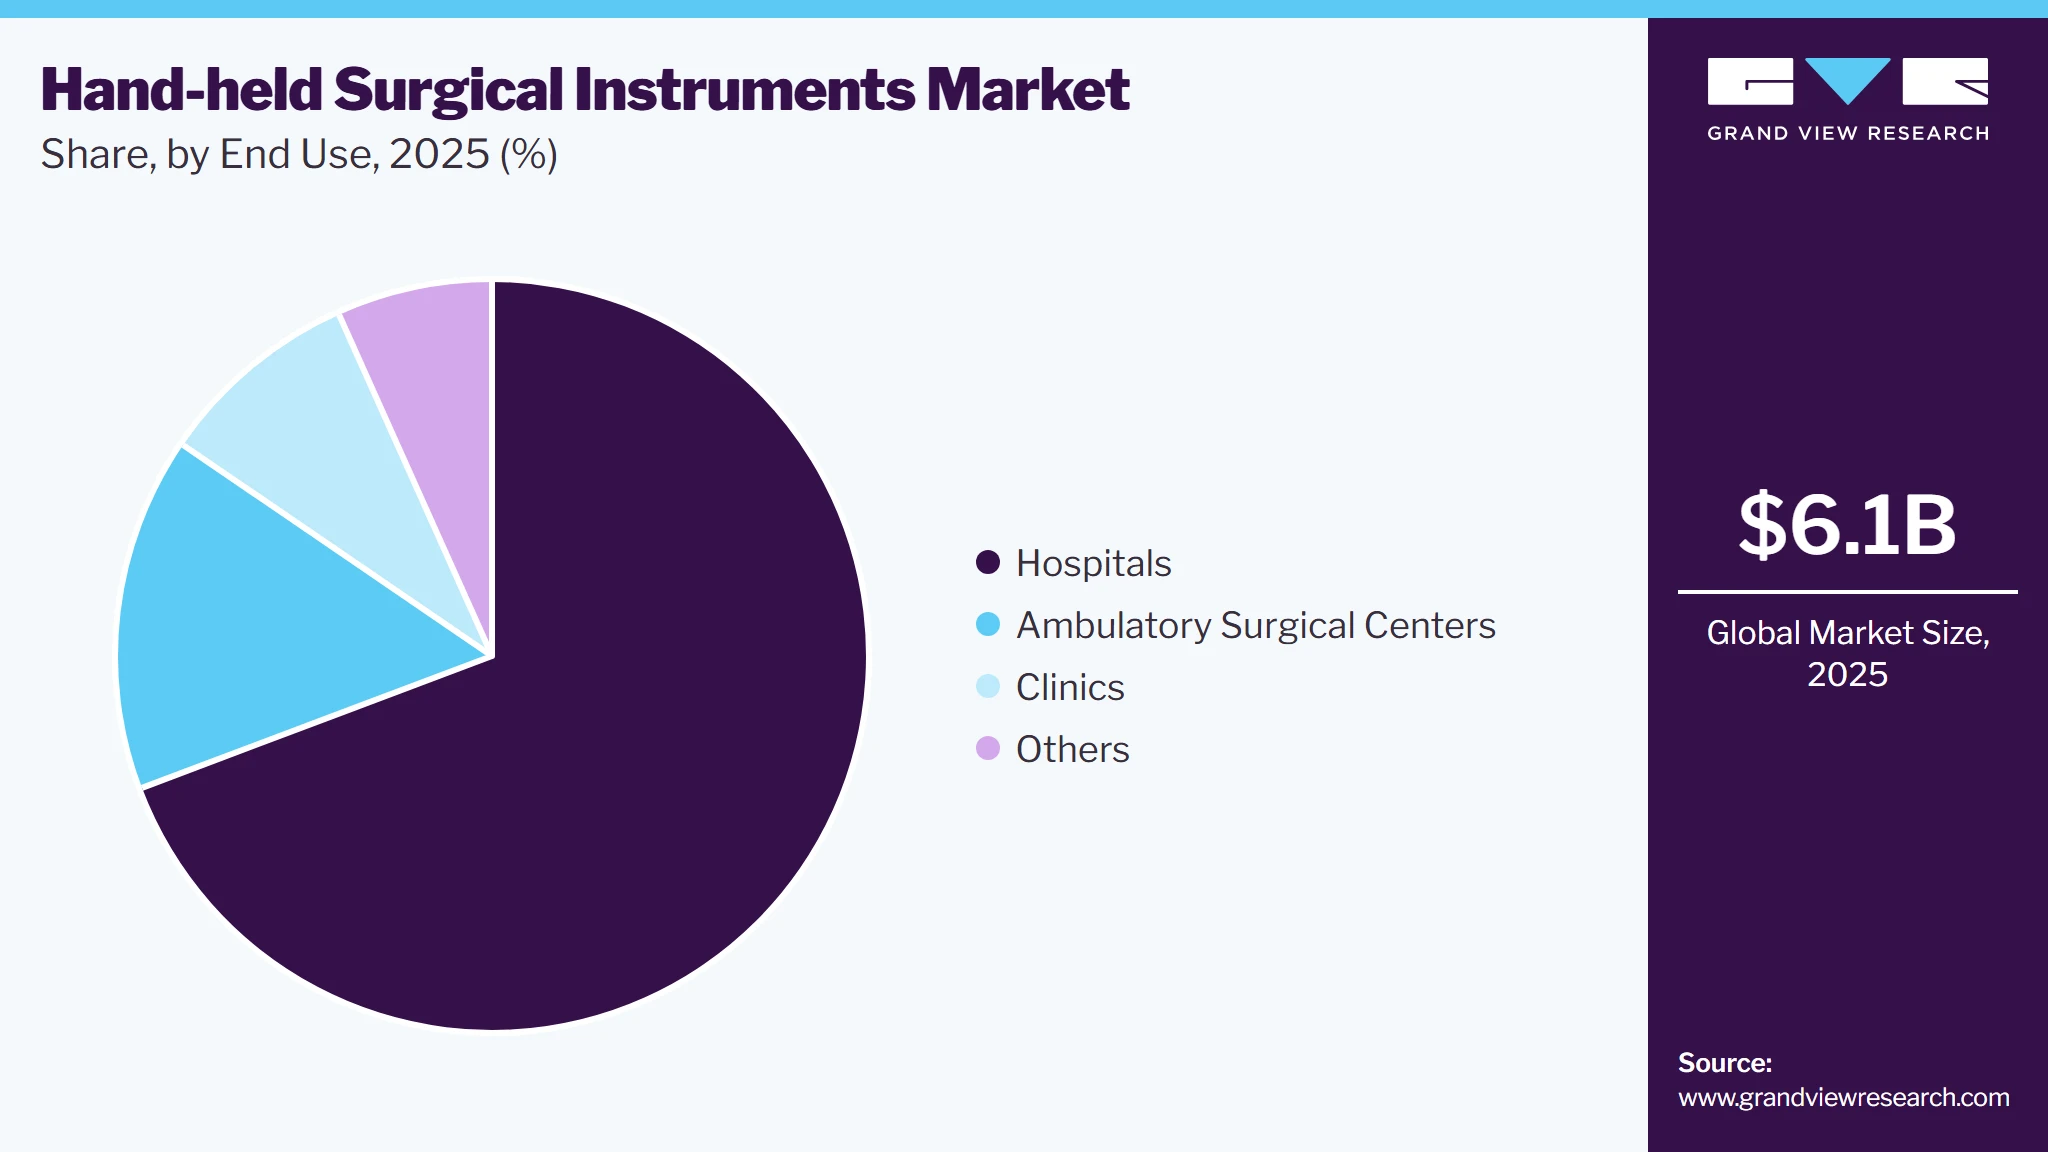
Based on end use, the hospitals segment led the market with the largest revenue share of 69.3% in 2025, owing large number of cases and preventive surgeries being performed in these settings. In addition, the availability of all the types of surgical instruments and skilled professionals is expected to fuel the segment growth. The rising number of admissions due to increasing number of chronic disorders is also expected to propel the segment growth over the forecast period. With increase in the number of procedures, such as angioplasty and kidney & liver transplants, and incidence of trauma, the demand for surgical equipment has significantly increased in hospitals.
 To learn more about this report, Download Free Sample Report
The clinics and ambulatory surgical centers segment is expected to experience rapid growth due to the increasing popularity of aesthetic and cosmetic surgeries in these centers. Ambulatory surgical centers offer advantages such as reduced costs and shorter patient stays, making them ideal for individuals who do not require extended hospital care. Additionally, the rising number of dental and orthopedic specialty clinics worldwide, along with the growing prevalence of melanoma and skin cancer, has driven more patients to dermatology clinics. Orthopedic clinics, providing specialized care for conditions like fractures, sprains, and arthritis, are also becoming more popular over general hospitals.
Application Insights
Based on application, the orthopedic surgery segment led the market with the largest revenue share of 17.6% in 2025 due to factors such as high incidence of Musculoskeletal (MSK) ailments and increasing developments in minimally invasive surgeries. According to a research article by WHO published in July 2022, approximately 1.71 billion people have MSK conditions globally. It is the leading cause of disability worldwide, which hampers an individual’s productivity.
The neurosurgery segment is expected to be the fastest-growing segment in the hand-held surgical instruments market, driven by the increasing prevalence of neurological disorders and advancements in surgical techniques. As conditions like brain tumors, spinal cord injuries, and neurodegenerative diseases rise globally, the demand for precise and effective surgical instruments for neurosurgery is escalating. The adoption of minimally invasive surgeries, which require specialized instruments, is also contributing to growth.
Regional Insights
North America dominated the hand-held surgical instruments market with the largest revenue share of 34.7% in 2025. According to the American Hospital Association Statistics 2024, the U.S. has approximately 6,120 operational hospitals, performing 40-50 million surgeries annually for conditions like cardiovascular diseases, cancer, and trauma (NCBI, 2020). Rising surgeries drive demand for surgical instruments. Additionally, 702,880 heart disease deaths in 2022 highlight growing demand for minimally invasive techniques, boosting market growth.
 To learn more about this report, Download Free Sample Report
U.S. Hand-held Surgical Instruments Market Trends
The hand-held surgical instruments market in the U.S. held the largest share in the North America region in 2025, supported by a well-developed healthcare system and advanced treatment facilities. Growth is driven by rising minimally invasive surgeries across aesthetics, dentistry, orthopedics, and more. Cosmetic surgeries grew 5% in 2023, totaling 1,575,244 procedures, fueled by self-awareness of aging and weight loss trends.
Europe Hand-held Surgical Instruments Market Trends
The European hand-held surgical instruments market, the second largest globally in 2025, is growing due to rising chronic diseases like diabetes, affecting 61 million people in Europe, projected to reach 67 million by 2030. Increased adoption of robotic-assisted surgeries and expanding outpatient clinics further drive demand for advanced handheld tools.
The UK hand-held surgical instruments market is steadily expanding, driven by factors such as high per capita income, a well-established healthcare system, a large pool of healthcare professionals, easy access to medical services, advanced device availability, and supportive reimbursement policies. These elements collectively fuel the market's growth in the region.
The France hand-held surgical instruments market is expanding, supported by substantial healthcare spending that guarantees access to quality, patient-focused services. In 2021, France allocated approximately 12.31% of its GDP to healthcare, according to World Bank data. Its robust healthcare infrastructure promotes the adoption of minimally invasive surgical instruments and devices.
Germany hand-held surgical instruments market is primarily fueled by the rising prevalence of chronic diseases. According to the International Diabetes Federation, in 2021, 10% of Germany's adult population of 62,027,700 had diabetes, amounting to 6,199,900 cases. This growing burden significantly drives the demand for advanced surgical tools.
Asia Pacific Hand-held Surgical Instruments Market Trends
The Asia Pacific hand-held surgical instruments market is growing rapidly due to rising chronic diseases like cancer, diabetes, and cardiovascular conditions, particularly in China, India, and Japan. With 1.4 million cancer diagnoses in India in 2022, demand for advanced surgical tools is surging. Additionally, the adoption of minimally invasive techniques and innovations in surgical technology, such as robotic systems, is enhancing patient outcomes. Hospitals are increasingly investing in modern instruments to improve care, driving market growth across the region.
The hand-held surgical instruments market in Japan is growing, primarily driven by the country’s aging population, with approximately 30% aged 65 and older in 2023, according to World Bank data. Growth is further fueled by the introduction of advanced surgical tools and frequent product launches. Manufacturers are heavily investing in R&D to develop innovative instruments that enhance precision, efficiency, and patient care.
The hand-held surgical instruments market in China is anticipated to grow quickly, driven by the rising prevalence of orthopedic conditions among the population. A study published by BioMed Central Ltd. in July 2023 revealed that osteoporotic fractures are prevalent in the Chinese elderly population. In addition, the study reported that the prevalence has increased significantly from 2000 - 2010 to 2012 - 2022.
The hand-held surgical instruments market in India is anticipated to grow significantly due to the increasing launch of surgical instruments. The companies operating in the country are launching advanced surgical instruments that can be used in surgeries. For instance, in August 2023, a medical technology provider, Healthium Medtech, launched India's first exclusive range of sutures, TRUMAS, to manage challenges faced during suturing in minimally invasive surgeries. Such product launches by domestic & international industry participants in India are anticipated to drive the country's market growth over the forecast period.
Latin America Hand-held Surgical Instruments Market Trends
The Latin American hand-held surgical instruments market is primarily driven by Brazil and Argentina. The geriatric population in Latin America is increasing, leading to a higher demand for healthcare services & products. For instance, according to the World Bank, the adult population aged 65 and above in the Latin America and Caribbean region was around 9% of the total population in 2023, which is anticipated to double by 2050. In addition, the large number of road & traffic accidents across the region is anticipated to boost the demand for hand-held surgical instruments in Latin America.
Middle East & Africa Hand-held Surgical Instruments Market Trends
The Middle East & Africa hand-held surgical instruments market is growing due to the rising focus of industry players, robust medical infrastructure, and increasing prevalence of chronic diseases. Government initiatives to enhance healthcare manufacturing capabilities further support market expansion. The region’s emphasis on advancing its healthcare sector and demand for advanced surgical tools attract global companies. For instance, Johnson & Johnson MedTech began direct operations in Saudi Arabia in February 2024, aiming to improve healthcare with cutting-edge medical and surgical equipment. This aligns with Saudi Arabia’s Vision 2030, which prioritizes better clinical outcomes and local workforce development.
The hand-held surgical instruments market in Saudi Arabia is anticipated to grow significantly due to the increasing geriatric population and the large number of surgical procedures being performed in the country. The geriatric population is expected to boost the demand for surgical instruments as they predominantly suffer from various health conditions. According to an article published by the Arab News in October 2023, the aging population in Saudi Arabia is predicted to increase from 1.11 million in 2022 to 3.58 million by 2035. Thus, the rising geriatric population is anticipated to increase the demand for hand-held surgical instruments in the coming years.
Key Hand-held Surgical Instruments Company Insights
The competitive scenario in the hand-held surgical instruments market is highly competitive, with key players such as Zimmer Biomet, Medtronic and others. The major companies are undertaking various organic and inorganic strategies such as new product development, collaborations, acquisitions, mergers, and regional expansion to serve the unmet needs of their customers.
Key Hand-held Surgical Instruments Companies:
The following key companies have been profiled for this study on the hand-held surgical instruments market.
-
Zimmer Biomet
-
B. Braun Melsungen AG
-
Integra LifeSciences Corporation
-
Medtronic, plc.
-
Smith & Nephew
-
Zimmer Biomet Holdings
-
Johnson & Johnson Services, Inc.
-
Becton, Dickinson and Company
-
CooperSurgical, Inc.
-
Thompson Surgical Instruments Inc.
-
Aspen Surgical
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (B. Braun Melsungen AG, Integra LifeSciences Corporation, Medtronic, Smith & Nephew, Zimmer Biomet Holdings)
- Focus on expanding comprehensive surgical instrument portfolios across general surgery, orthopedic, cardiovascular, neurosurgery, and minimally invasive procedures.
- Emphasize continuous product innovation, ergonomic instrument design, and premium-quality materials to enhance surgical precision and clinical outcomes.
- Strong brand recognition, extensive product portfolios, and long-standing relationships with healthcare providers and surgical facilities support sustained market leadership.
- Advanced manufacturing capabilities, established global supply chains, and robust regulatory expertise enable efficient large-scale operations.
- High manufacturing and R&D costs, coupled with stringent regulatory requirements, increase operational complexity and time-to-market.
- Large organizations often experience slower innovation cycles due to complex organizational structures and extensive validation processes.
Emerging Players (CooperSurgical, Inc., Thompson Surgical Instruments Inc., Aspen Surgical)
- Focus on niche surgical specialties, cost-effective handheld instruments, and customized instrument offerings tailored to specific surgical procedures.
- Prioritize innovation in ergonomic designs, lightweight materials, reusable instruments, and specialty surgical tools.
- Faster product development cycles and operational flexibility allow emerging companies to respond quickly to evolving surgeon preferences and market demands.
- Specialized product portfolios and customization capabilities strengthen differentiation in targeted surgical segments.
- Limited financial resources, narrower distribution networks, and lower brand awareness restrict large-scale market penetration.
- Regulatory approval challenges and limited clinical validation capabilities may delay commercialization and expansion efforts.
Recent Developments
-
In August 2024, CooperSurgical, Inc acquired OBP Surgical, enhancing its portfolio of medical devices. This acquisition strengthens the company's position in women's health and expands its offerings, aiming to provide innovative solutions and improve surgical outcomes.
-
In June 2024, Zimmer Biomet announced an exclusive distribution agreement with THINK Surgical for the wireless, handheld TMINI Miniature Robotic System, designed for total knee arthroplasty. The partnership integrates Zimmer Biomet's technology into a customized TMINI robotic solution.
-
In July 2023, B. Braun Melsungen AG and Chengdu-based Borns Medical formed a strategic partnership to promote standardized robotic surgery applications. This collaboration leverages B. Braun's medical expertise and Borns' robotic technology to advance minimally invasive surgeries by integrating consumables and enhancing surgical precision.
Hand-held Surgical Instruments Market Report Scope
Report Attribute
Details
Market size in 2025
USD 6.1 billion
Estimated market size in 2026
USD 6.5 billion
Projected market size by 2033
USD 11.2 billion
Growth rate
CAGR of 8.0% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait;
Key companies profiled
B. Braun Melsungen AG; Integra LifeSciences Corporation; Medtronic; Smith & Nephew; Zimmer Biomet Holdings; Johnson & Johnson Services, Inc.; Becton, Dickinson and Company; CooperSurgical, Inc.; Thompson Surgical Instruments Inc.; Aspen Surgical
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Hand-held Surgical Instruments Market Report Segmentation
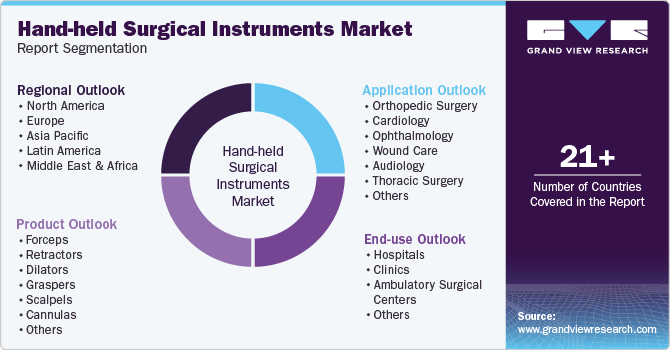
This report forecasts revenue growth at country levels and provides an analysis on the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the hand-held surgical instruments market report based on product, application, end-use and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Forceps
-
Retractors
-
Dilators
-
Graspers
-
Scalpels
-
Cannulas
-
Dermatomes
-
Trocars
-
Others
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Orthopedic Surgery
-
Cardiology
-
Ophthalmology
-
Wound Care
-
Audiology
-
Thoracic Surgery
-
Urology and Gynecology Surgery
-
Plastic Surgery
-
Neurosurgery
-
Others
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Clinics
-
Ambulatory Surgical Centers
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The hand-held surgical instruments market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each hand-held surgical instruments segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Forceps
Revenue is generated through the commercialization of specialized grasping and clamping instruments used to stabilize, manipulate, or extract biological tissues and surgical materials. Manufacturers capture high-volume, highly continuous revenue through two main pipelines: premium, medical-grade reusable stainless steel variants requiring strict reprocessing, and high-turnover, single-use sterile disposable forceps distributed in pre-packaged clinical procedural kits.
Retractors
Revenue flows from the sale of manual and self-retaining instruments engineered to hold back tissue edges or organs to maintain surgical site visibility. Market participants generate income from upfront capital purchases of complex, multi-component articulating retractor frameworks, alongside recurring revenue from specialized replacement blades, modular attachments, and light-guide fiber-optic accessories.
Dilators
Revenue is captured by distributing calibrated, graduated rods or expandable instruments designed to safely enlarge narrow anatomical ducts, vessels, or luminal openings. Income is derived via modular multi-piece sizing sets purchased by operating suites, alongside steady, high-frequency replacement orders for single-use, flexible balloon dilator accessories or protective visual sheath systems.
Graspers
Revenue is generated through the supply of fine-mechanism manual instruments utilized extensively to hold, rotate, or mobilize internal tissues during minimally invasive procedures. Device developers capture substantial high-margin revenue from advanced laparoscopic and thoracoscopic grasper lines, leveraging continuous clinical replacement cycles driven by finite jaw-hinge lifecycles or single-use end-effector tip components.
Scalpels
Revenue streams develop from the high-volume production of primary surgical cutting instruments. Volume-based revenue is split between classic reusable steel scalpel handles paired with high-frequency, single-use replacement blades, and specialized fully disposable safety scalpels equipped with retractable plastic shielding mechanisms mandated by international healthcare worker safety guidelines.
Cannulas
Revenue is derived from the commercialization of hollow surgical tubes used to aspirate fluids, deliver therapeutic gases, or act as structural entry conduits for secondary instrumentation. Manufacturers generate consistent, repeating income streams through high-volume bulk supply agreements for sterile, single-use suctions, flushing sets, and trocars-compatible cannula assemblies.
Dermatomes
Revenue flows through the sale of high-precision surgical instruments engineered to slice thin, uniform sections of skin for autologous skin grafting procedures. Medical device firms capture high-value revenue from capital mechanical or automated handpiece sales, alongside a lucrative aftermarket stream driven by single-use precision micro-blades and calibrated guard plate assemblies.
Trocars
Revenue is captured through the structural commercialization of access ports designed to puncture abdominal or thoracic walls to establish a secure, gas-tight operative pathway. Manufacturers monetize this highly profitable segment by executing bulk, recurring contract sales of sterile, single-use bladed, bladeless, and optical port kits directly consumed during daily laparoscopic interventions.
Others
Revenue encompasses alternative specialized handheld instrumentation categories, including standard surgical scissors, surgical needle holders, tissue clamps, bone rongeurs, curettes, probes, and specialized sterilization storage trays or organizing hardware blocks.
Segment - Application
Revenue capture definition
Orthopedic Surgery
Revenue is generated by supplying robust, high-torque manual tools (such as bone-cutting forceps, heavy-duty retractors, bone levers, and curettes) designed for structural joint reconstructions, internal fracture fixations, and spinal interventions. Income is driven by large-scale, high-margin specialized instrument tray sales aligned with growing global aging demographics and orthopedic trauma procedures.
Cardiology
Revenue flows from ultra-fine, corrosion-resistant microsurgical instruments optimized for open and minimally invasive cardiothoracic procedures. Manufacturers capture premium pricing margins by engineering high-tensile titanium or tungsten-carbide embedded tools required for coronary artery bypasses and valve repairs.
Ophthalmology
Revenue is captured through the commercialization of highly specialized, ultra-precise micro-instruments built to operate within delicate ocular structures. Income is characterized by premium specialized device pricing combined with rapid tool replenishment cycles across high-throughput cataract and vitreo-retinal surgical practices.
Wound Care
Revenue is derived from basic, high-volume surgical debridement and management tools utilized across outpatient clinics, emergency units, and burn care settings. Income is anchored on steady, predictable, low-cost consumable replenishment contracts with institutional facility groups.
Audiology
Revenue flows through the sale of micro-scale otological handheld tools optimized for middle-ear reconstructions and tympanoplasty lines. Value is captured via micro-instrumentation tray sales sold directly to ENT surgery departments and private otolaryngology centers.
Thoracic Surgery
Revenue is generated through elongated, specialized instruments configured to safely access the pleural cavity. Income is driven by the clinical demand for deep-cavity manual tools that provide exceptional tactical feedback and reliable tissue hold.
Urology and Gynecology Surgery
Revenue is captured by distributing targeted endo-urological and pelvic entry tools. Manufacturers monetize this segment through standard multi-instrument procedure configurations tailored to pelvic anatomy, benefiting from high-volume elective and therapeutic interventions.
Plastic Surgery
Revenue streams develop from premium, ultra-fine aesthetic and reconstructive instrumentation. Manufacturers generate high-profit margins by marketing beautifully balanced, non-glare, high-finish handpieces directly to premium private cosmetic clinics and specialized reconstructive surgery departments.
Neurosurgery
Revenue is derived from highly precise micro-neurosurgical instrument portfolios engineered to manipulate central nervous system tissue without causing collateral trauma. This segment commands the highest individual handheld instrument unit margins due to strict material purity, tolerance requirements, and micro-engineering constraints.
Others
Revenue encompasses generalized or multi-disciplinary clinical application fields, including basic emergency trauma room lanes, podiatric treatments, dental oral-maxillofacial surgeries, and low-volume veterinary surgical channels.
Segment - End Use
Revenue capture definition
Hospitals
Revenue is generated through large-scale capital budget allotments, comprehensive national healthcare tenders, and multi-year group purchasing organization (GPO) supply contracts. Manufacturers secure bulk revenue via the wholesale deployment of complete multi-disciplinary surgical tray configurations, system-wide reprocessing maintenance agreements, and massive, high-volume recurring orders for single-use disposable instruments.
Clinics
Revenue flows from localized, private specialist practices and multi-physician clinical groups. Income in this segment is driven by lower-volume, highly targeted specialty instrument sets purchased directly through regional medical device distributors or online manufacturer portals, emphasizing rapid asset delivery and ease of local maintenance.
Ambulatory Surgical Centers
Revenue is captured through high-throughput, cost-efficient commercial supply frameworks tailored to lean outpatient surgical environments. Manufacturers monetize this high-growth segment by bundling single-use sterile disposable instrument setups and modular, quick-turnaround component arrays that minimize in-house sterilization bottle-necks and maximize fast patient throughput.
Others
Revenue is derived through alternative or emerging device endpoints, including academic medical research laboratories, military/field hospital procurement lines, professional surgical tech educational institutes, and emergency mobile rescue services acquiring specialized trauma-access handheld instrument configurations.
Estimation Model
Step
Guiding Question
Process Steps
Data & Sources
Scope Definition
What is being studied?
1. Define product categories including handheld surgical instruments.
2. Segment the market by product type and application. 3. Set geographic boundaries. 4. Align criteria for base year forecast horizon (2022-2032).
Regulatory agencies (FDA, EMA, PMDA), WHO, surgical associations, company annual reports
Build the Product Base
How large is the potential demand for handheld surgical instruments?
1. Analyze the volume of surgical procedures performed globally across key specialties.
2. Estimate the installed base and replacement demand for hospitals, ASCs, and specialty surgical centers.
3. Evaluate the utilization pattern for handheld surgical instruments across different surgical procedures.
4. Establish baseline demand for handheld surgical instruments by specialty and region.
Hospital statistics, OECD databases, WHO surgical volume databases, healthcare expenditure data, company financial reports
Estimate Penetration
What is the adoption rate and utilization rate of handheld surgical instruments across surgical environments?
1. Quantify adoption rates of handheld surgical instruments across various surgical environments and settings.
2. Assess the ratio of advanced handheld instruments to conventional ones.
3. Evaluate the shift from reusable instruments to single‑use disposable instruments.
4. Estimate the impact of minimally invasive procedures on handheld instrument utilization.
Primary interviews with surgeons, procurement managers, hospital administrators, surgical societies.
Revenue Conversion
How does surgical instrument utilization translate into market revenue?
1. Calculate average selling prices (ASPs) for handheld instruments and determine the total global revenue by product category.
2. Segment revenue by region, specialty, and end‑user.
3. Validate estimates against company financial reports, distributor sales data, and market databases.
4. Cross‑check calculations with sales logs and benchmark data from industry sources.
Manufacturer price catalogs, company annual reports, distributor pricing databases,
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Application Analysis
Conducted a comprehensive application landscape assessment of the global handheld surgical instruments market across major surgical specialties and clinical settings. The study evaluated instrument utilization patterns across key applications, including general surgery, orthopedic surgery, cardiovascular surgery, neurosurgery, plastic and reconstructive surgery, gynecology, urology, ophthalmology, and minimally invasive procedures. The analysis examined procedure volumes, surgical workflow requirements, adoption trends for reusable and disposable instruments, and the impact of technological advancements such as ergonomic designs, precision-engineered instruments, and specialty-specific surgical tools. Furthermore, the study assessed healthcare infrastructure development, rising surgical procedure volumes, prevalence of chronic diseases, and increasing demand for outpatient and ambulatory surgical interventions influencing instrument demand across hospitals, ambulatory surgical centers, and specialty clinics globally.
Enables stakeholders to gain a detailed understanding of demand dynamics across various surgical applications and identify high-growth therapeutic areas within the handheld surgical instruments market. The study supports strategic decision-making by highlighting emerging surgical specialties, evolving procedural trends, and utilization patterns across healthcare settings. It also assists manufacturers in optimizing product portfolios, prioritizing R&D investments, identifying application-specific market opportunities, and strengthening commercialization strategies across hospital, ambulatory, and specialty care environments.
Porter's Analysis
Conducted a detailed Porter’s Five Forces analysis for the global handheld surgical instruments market to evaluate the competitive intensity and structural attractiveness of the industry. The assessment analyzed the bargaining power of suppliers, considering raw material availability, stainless steel and specialty alloy sourcing, and manufacturing capabilities. The study evaluated buyer bargaining power across hospitals, group purchasing organizations (GPOs), ambulatory surgical centers, and healthcare systems. Additionally, it assessed the threat of new entrants by examining regulatory barriers, capital investment requirements, product quality standards, and brand loyalty. The analysis further investigated the threat posed by substitute products, including robotic-assisted surgery systems and minimally invasive technologies, along with the degree of competitive rivalry among established market participants based on product innovation, pricing strategies, distribution networks, and geographic expansion initiatives.
Enables stakeholders to understand the competitive structure and profitability potential of the handheld surgical instruments market. The study supports informed business decisions regarding market entry, pricing strategies, partnership development, and competitive positioning. It also helps organizations identify potential market risks, evaluate supplier and buyer dynamics, benchmark competitor strategies, and develop sustainable growth initiatives to strengthen market presence and long-term profitability.
Geographic Analysis
Conducted a comprehensive geographic assessment of the global handheld surgical instruments market across key regions, including North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. The study evaluated regional differences in surgical procedure volumes, healthcare expenditure, healthcare infrastructure development, regulatory frameworks, reimbursement scenarios, and adoption of advanced surgical technologies. The analysis further examined country-level demand patterns, demographic trends, prevalence of chronic diseases, aging population dynamics, and expansion of hospital and ambulatory care facilities influencing market growth. Additionally, the study assessed regional manufacturing capabilities, import-export dynamics, pricing variations, and government initiatives supporting surgical care access and healthcare modernization across major global markets.
Enables stakeholders to identify region-specific growth opportunities, assess market attractiveness, and prioritize expansion strategies across high-potential geographies. The study supports strategic decision-making by providing insights into regional demand drivers, competitive landscapes, regulatory environments, and healthcare investment trends. It also assists companies in optimizing regional market entry strategies, strengthening distribution networks, aligning product offerings with local clinical requirements, and effectively allocating resources to maximize global market penetration.
Frequently Asked Questions About This Report
North America dominated with a 34.7% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
Retractors segment led the market with the largest revenue share of 19.2% in 2025.
Orthopedic surgery segment led the market with the largest revenue share of 17.6% in 2025.
The global hand-held surgical instruments market size was valued at USD 6.1 billion in 2025 and is estimated at USD 6.5 billion for 2026.
The global hand-held surgical instruments market is expected to grow at a CAGR of 8.0% from 2026 to 2033, reaching USD 11.2 billion by 2033.
North America dominated the hand-held surgical instruments market with a share of 34.7% in 2025. This is attributable to the increasing incidence of chronic diseases such as cardiovascular diseases, neurological diseases, cancer, diabetes, and autoimmune diseases.
Some key players operating in the hand-held surgical instruments market include Zimmer Biomet Holdings; B. Braun Melsungen AG; Becton, Dickinson and Company; Integra LifeSciences Corporation; Smith & Nephew; Medtronic; CooperSurgical Inc.; Johnson & Johnson; Thompson Surgical Instruments Inc.; and Aspen Surgical.
Key factors that are driving the market growth include increasing prevalence of chronic diseases, rise in the number of road and other accidents, and rise in the number of surgical procedures across the world.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


