
- Home
- »
- Healthcare IT
- »
-
Healthcare Claims Management Market Size Report, 2033GVR Report cover

Healthcare Claims Management Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Medical Billing, Claims Processing), By Component (Software, Services), By Solution Type (Integrated), By Deployment Mode, By End-use, By Region And Segment Forecasts
Market Size, 2025
$35.7BMarket Estimate, 2026
$42.3BMarket Forecast, 2033
$146.6BCAGR, 2026–2033
19.4%Healthcare Claims Management Market Summary
The global healthcare claims management market size was valued at USD 35.7 billion in 2025 and is projected to grow from USD 42.3 billion in 2026 to USD 146.6 billion by 2033, at a CAGR of 19.4% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 38.8% % in 2025. The market is witnessing remarkable expansion globally due to the development of variables such as an increased focus on providing high-quality healthcare services to the target population and the rising rate of adoption of technology-related services.
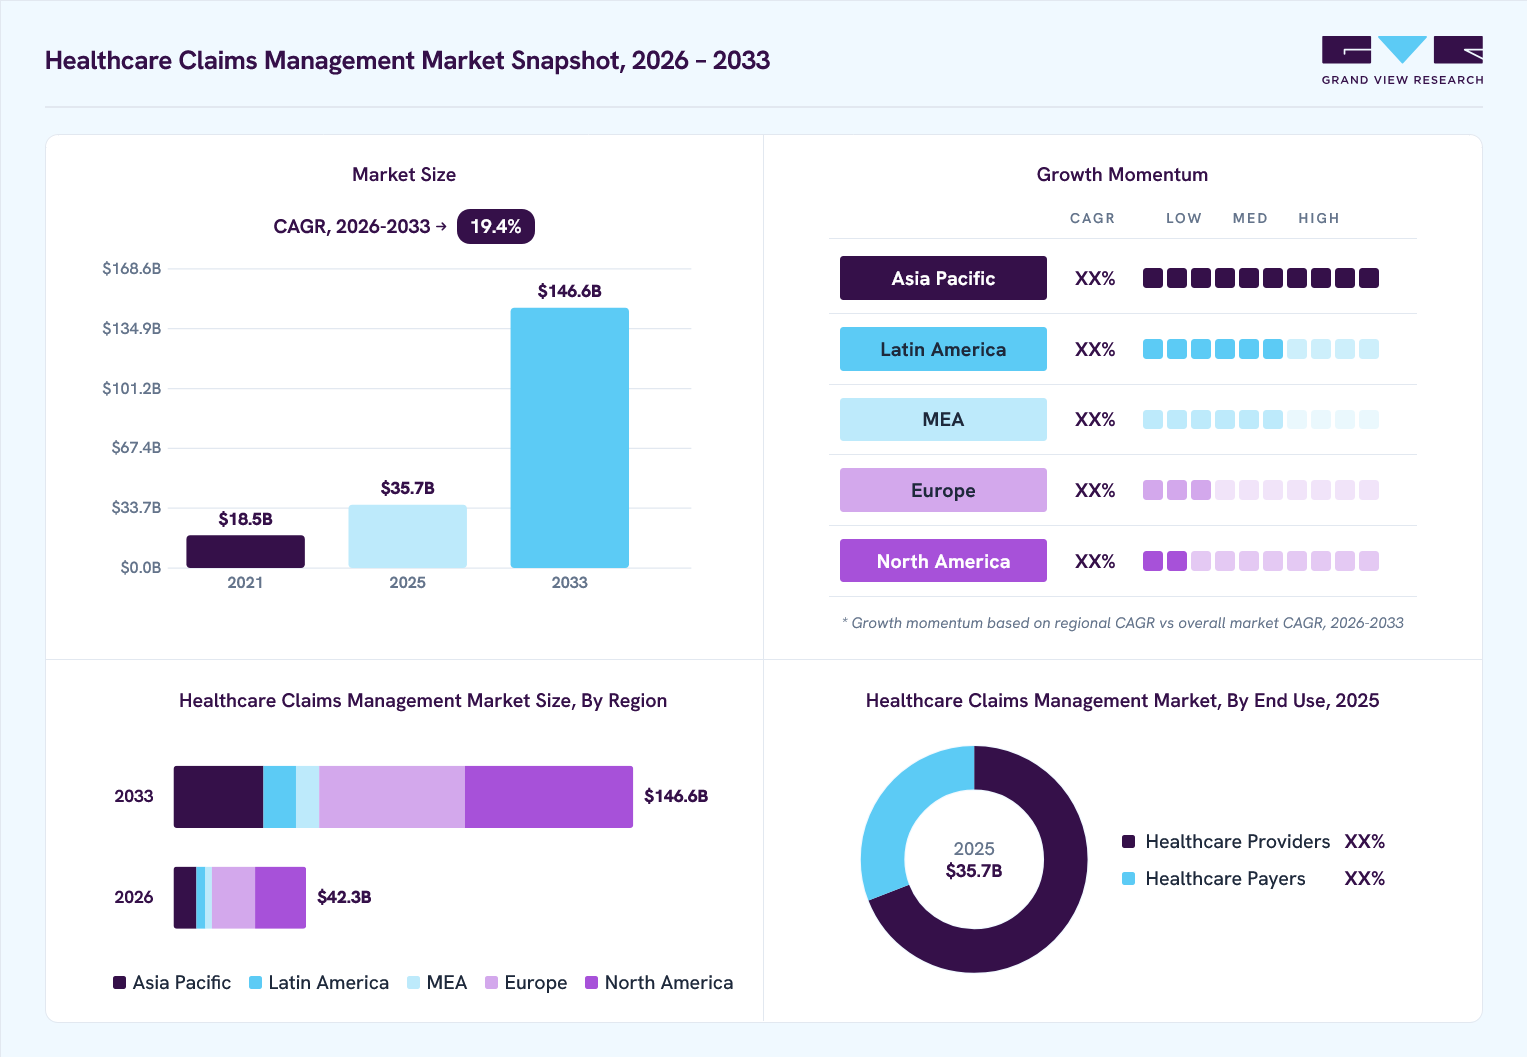 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Medical billing segment held the largest revenue share of 55.7% in 2025.
- By component: Software segment held the largest revenue share of 66.3% in 2025.
- By solution type: Integrated solutions segment held the largest revenue share of 75.1% in 2025.
- By deployment mode: Web-based segment held the largest revenue share of 46.7% in 2025.
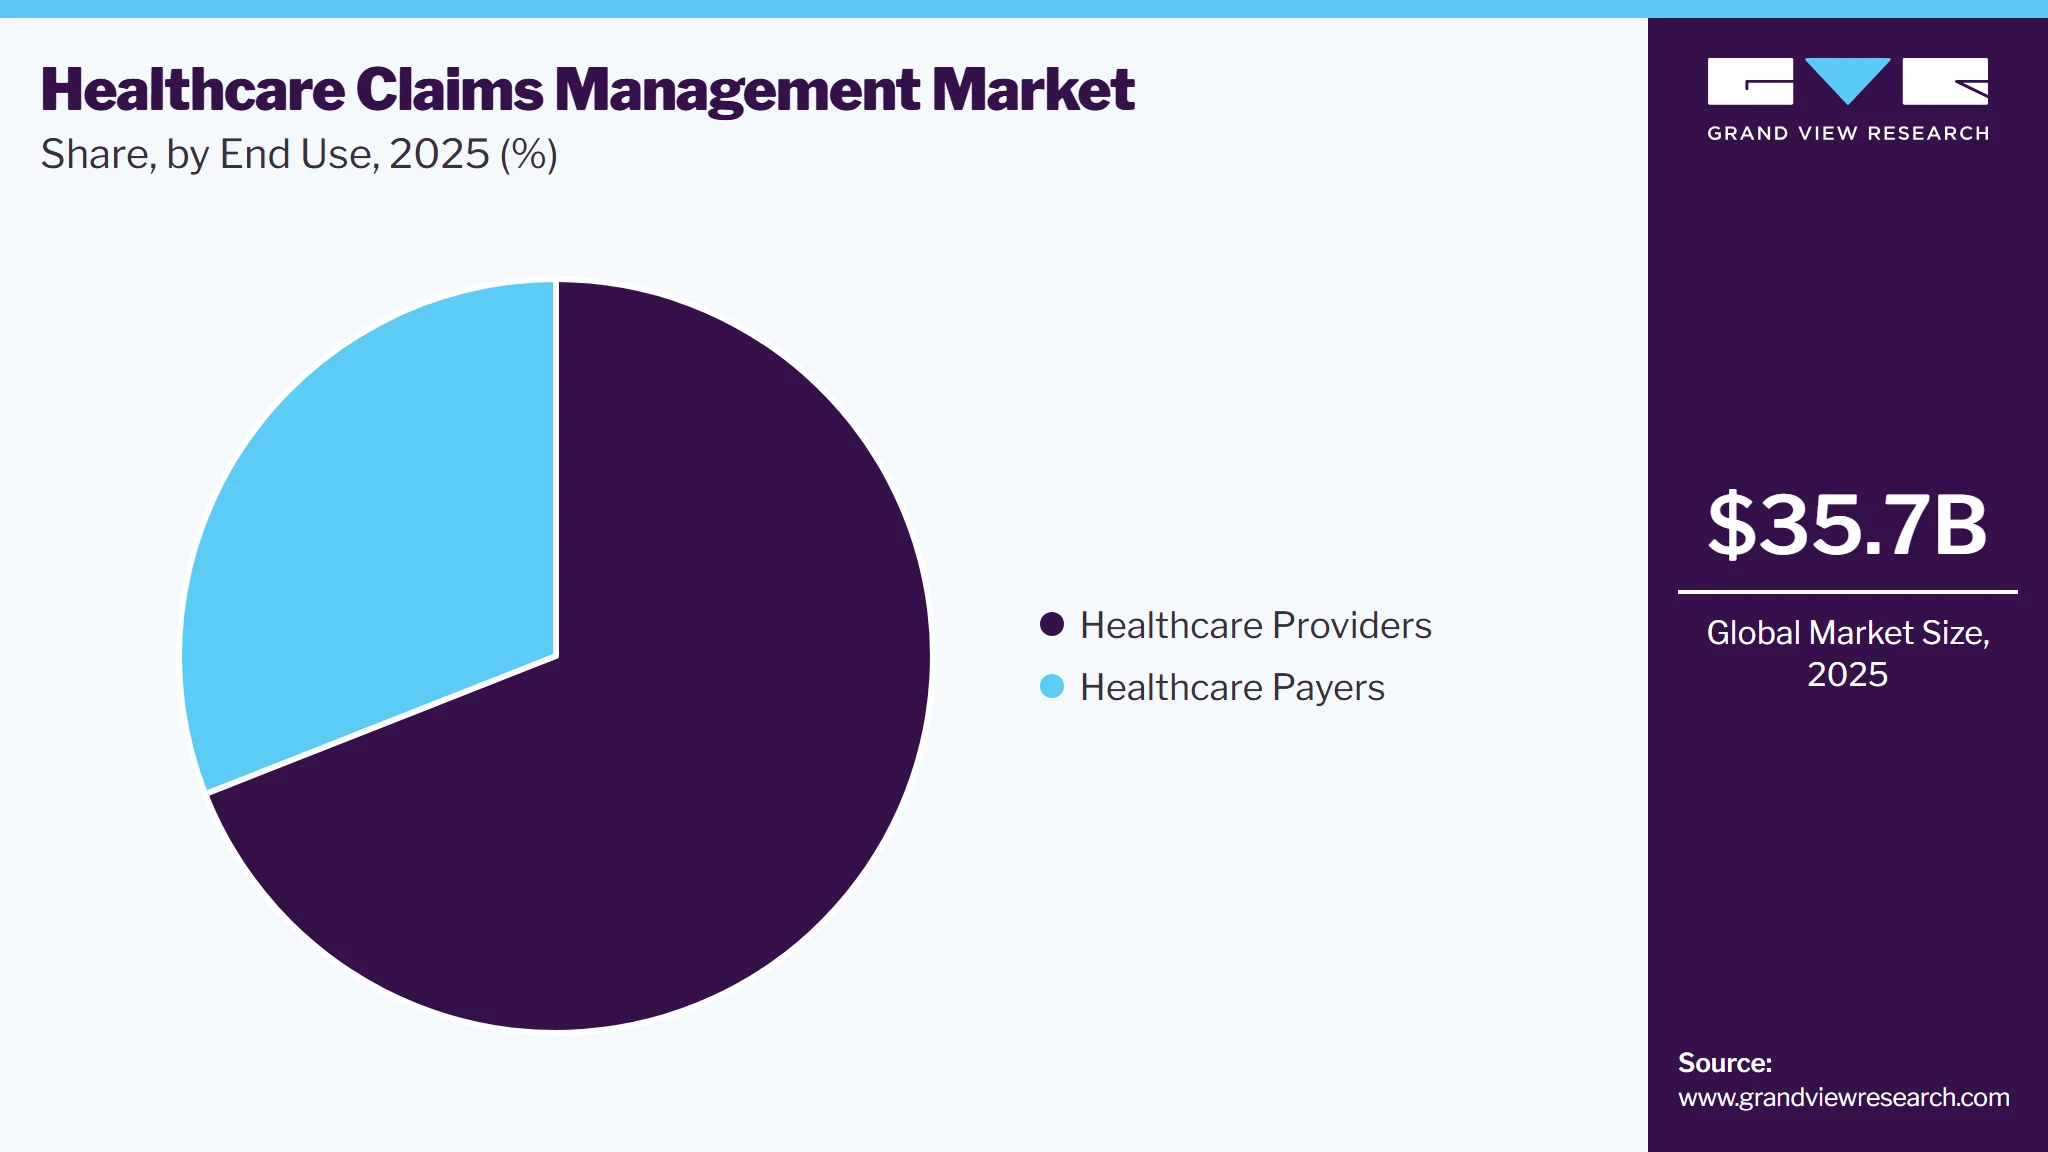
- By end use: Healthcare providers segment held the largest revenue share of 69.0% in 2025.
Regional Highlights
- Largest regional market: North America (38.8% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 35.7 Billion
- Estimated market size in 2026: USD 42.3 Billion
- Projected market size by 2033: USD 146.6 Billion
- CAGR (2026-2033): 19.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Furthermore, the growing health insurance sector and rising internet usage and digitalization are positively influencing the overall industry growth. The COVID-19 pandemic has had a positive impact on the market for healthcare claims management since its peak in March 2020, when medical offices were obliged to raise billing and payment due to new pandemic realities. Healthcare IT technologies including medical billing software, practice management software and electronic health records (EHR)/ electronic medical records (EMR) were employed to make the process feasible despite the shortage of people. Customers and competitors paid attention to this, which led to the ongoing existence, focus on improvement, and dependency on such small-scale human interference software over the period.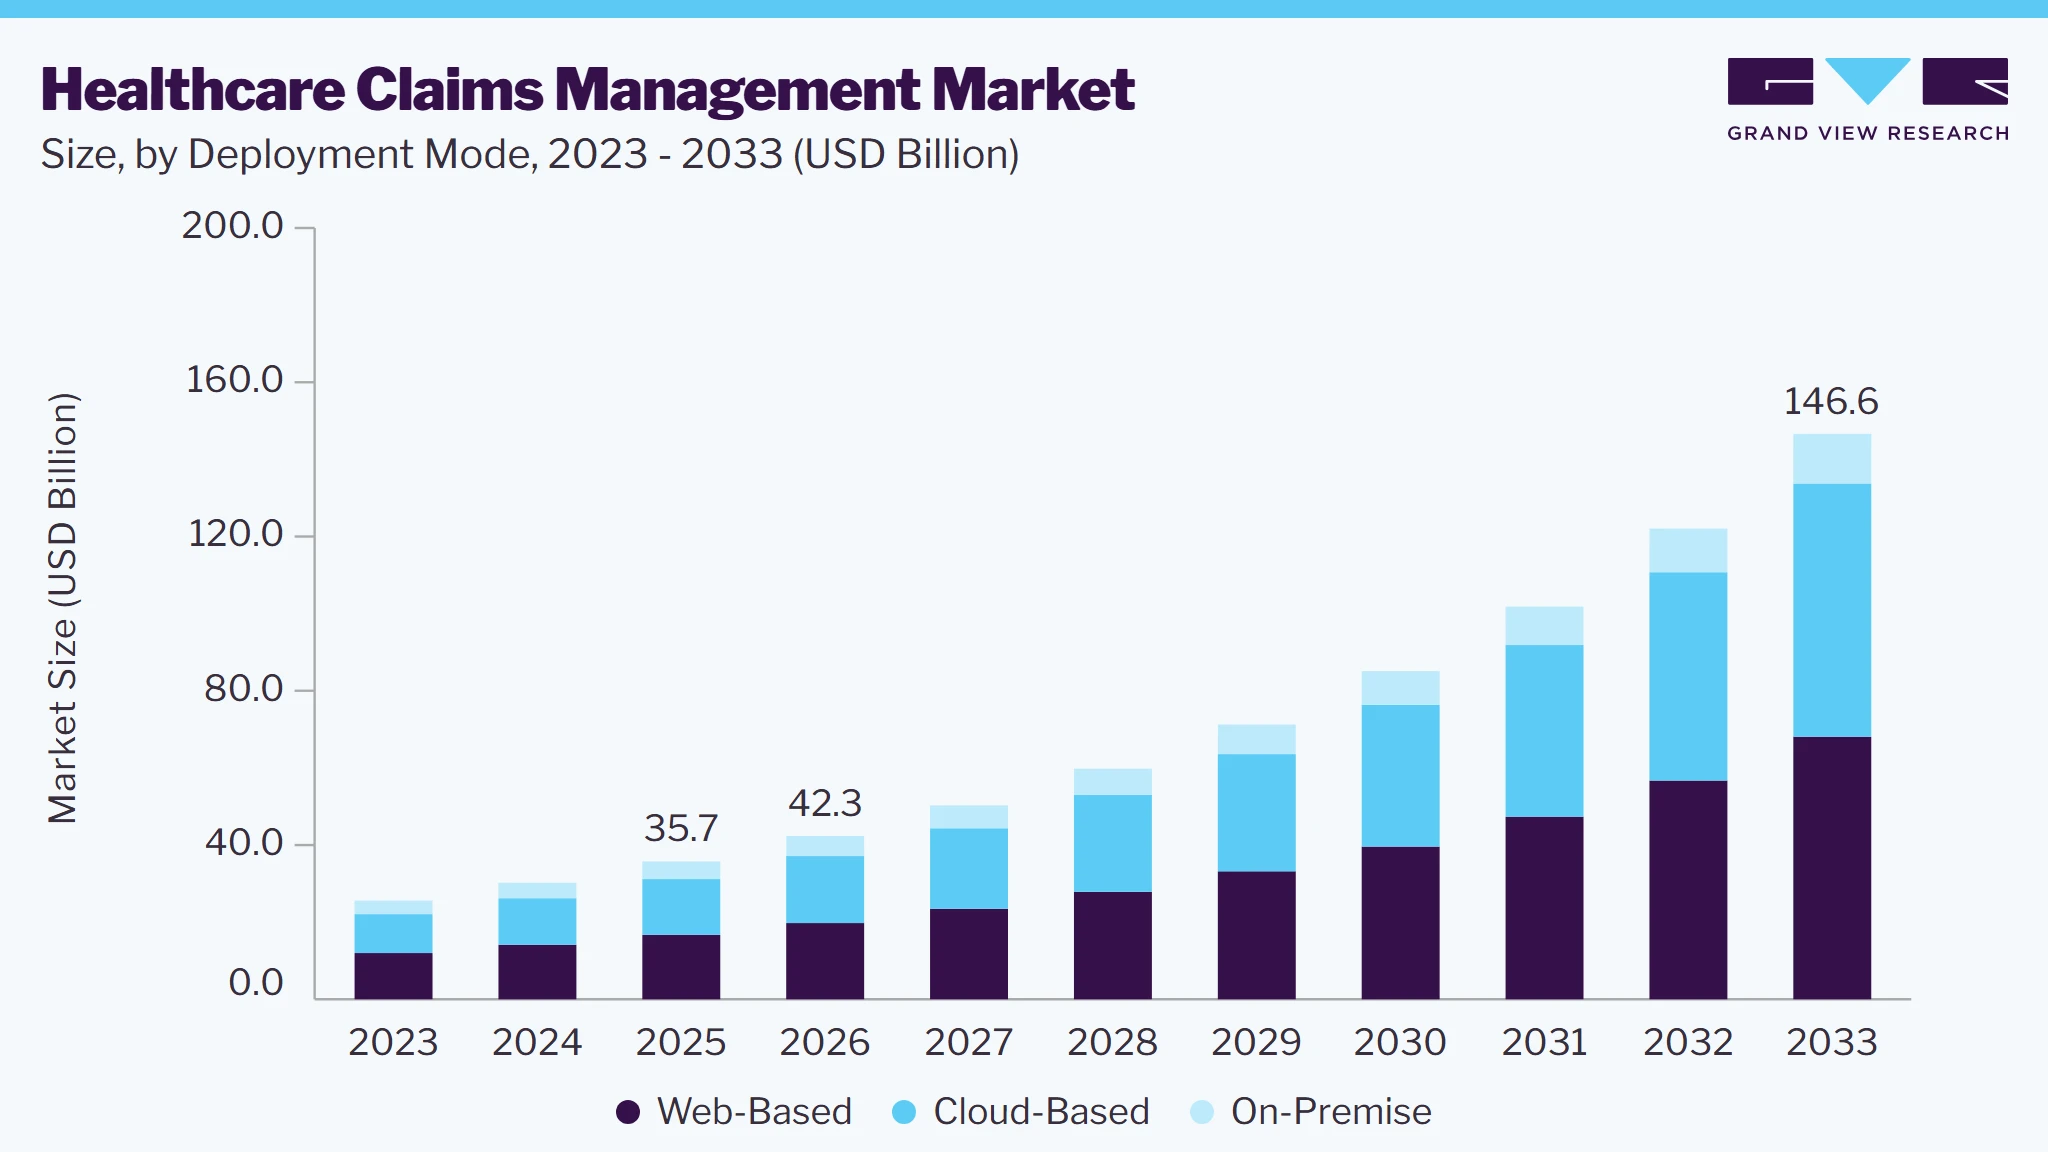 To learn more about this report, Download Free Sample Report
In addition, the World Health Organization (WHO) reported in its 'Administrative Mistakes: Technical Series on Safer Primary Care 2016' study that administrative errors account for 5-50% of medical errors in primary care, recognizing the need for digital accuracy solutions like medical billing and claims processing management, which includes services and software. Overall, the industry will witness significant growth as a result of this.
Data privacy issues are one of the primary factors that may stymie industry growth in all of the healthcare IT segments that are seeing a revolution through digitization, including the market for healthcare claims management, unless and until set regulations are in place to limit its market impact to some extent.
Market Dynamics
The healthcare claims management market is driven by increasing healthcare expenditures, rising claim volumes, and the growing adoption of digital revenue cycle management (RCM) solutions. AI-powered claims automation, cloud-based platforms, and advanced analytics are improving claims accuracy, reducing denials, and accelerating reimbursement processes. However, concerns related to data security, regulatory compliance, interoperability with legacy systems, and high implementation costs continue to challenge market growth.
The increasing volume of healthcare claims, driven by rising healthcare utilization, expanding health insurance coverage, and growing reimbursement complexity, is fueling demand for healthcare claims management solutions. Healthcare providers and payers process millions of claims annually, making manual claims processing inefficient and prone to errors. Modern claims management platforms leverage automation, AI-assisted coding, rules-based validation, and electronic claims submission to reduce claim denials, accelerate reimbursements, and improve operational efficiency.
In addition, regulatory mandates such as ICD-10, HIPAA, value-based reimbursement, and electronic health record (EHR) integration are encouraging healthcare organizations to adopt advanced claims management software and outsourced billing services. For instance, in April 2026, Waystar Holding Corp. introduced new AI-powered capabilities through its AltitudeAI platform to advance the autonomous revenue cycle. The solution leverages agentic AI to automate denial prevention, revenue recovery, documentation review, and payment workflows, helping healthcare providers reduce manual administrative tasks and improve reimbursement efficiency.
Healthcare claims management systems must comply with continuously evolving reimbursement policies, coding standards, payer-specific rules, and government regulations. Frequent updates to CPT, HCPCS, ICD coding, and payer requirements necessitate continuous software upgrades and staff training. Furthermore, implementation of enterprise-grade claims management platforms often requires integration with EHRs, practice management systems, clearinghouses, and financial systems, increasing deployment costs and extending implementation timelines, particularly for small and mid-sized healthcare providers.
Artificial intelligence, machine learning, robotic process automation (RPA), and predictive analytics are creating significant opportunities in healthcare claims management. AI-enabled solutions can automatically identify coding errors, predict claim denials before submission, recommend corrective actions, prioritize high-risk claims, automate prior authorization workflows, and optimize reimbursement cycles. Growing adoption of cloud-based revenue cycle management platforms, interoperability standards (FHIR), and payer-provider digital collaboration is expected to further accelerate market growth over the forecast period.
For instance, in September 2025, Experian Health released its 2025 State of Claims Survey Report, highlighting increasing adoption of AI-powered claims management solutions. The company reported that healthcare providers using AI experienced reduced claim denials and improved resubmission success, reinforcing the growing opportunity for AI-driven automation in healthcare claims processing.
Analyst Perspective
The market is undergoing significant transformation as healthcare providers and payers adopt digital solutions to streamline reimbursement processes, reduce administrative costs, and improve claims accuracy. Rising healthcare expenditures, growing claim volumes, and evolving reimbursement models are accelerating the adoption of automated claims management platforms that enhance operational efficiency and minimize claim denials. Artificial intelligence, machine learning, robotic process automation (RPA), and advanced analytics are emerging as key technologies, enabling intelligent claims adjudication, fraud detection, predictive denial management, and faster payment processing. As healthcare organizations continue to prioritize revenue cycle optimization, regulatory compliance, and seamless interoperability, healthcare claims management is evolving from a transactional administrative function into a strategic capability that supports financial sustainability, improved patient experiences, and value-based care delivery.
Product Insights
Based on product, medical billing segment held the largest revenue share of 55.7% in 2025. Increasing internet usage, digitization, higher healthcare spending, and demand for risk and compliance management are key factors driving the medical billing segment. Medical billing is further categorized into professional billing and institutional billing. Professional billing is the process of submitting claims for medical services or treatments performed by physicians or healthcare professionals to persons who have insurance. Furthermore, one distinguishing feature of physician billing from professional billing is that it contains medical coding, which may result in pricing variations and be a factor in determining out-of-pocket spending.
Unlike professional billing, where errors can occur for a variety of reasons, including technical errors, institutional billing services are error-free. The majority of hospitals and healthcare providers pick these services since they specialize in medical billing. Institutional billing is larger than the physician billing industry, and this trend is projected to continue as more hospitals and major clinics begin to use institutional billing services, which will ultimately influence the entire medical billing segment to expand throughout the forecast period.
The target population's need for high-quality healthcare services is being prioritized, and technology-related services are being adopted at an increasing pace. As a result, the healthcare claims processing segment is anticipated to grow throughout the forecast period. The claims processing devices are popular among a wide spectrum of customers globally, and demand for them is increasing, which will help the healthcare claims processing segment grow over the forecast period. Furthermore, the expanding health insurance sector is positively influencing the overall industry growth.
Component Insights
Based on component, software segment held the largest revenue share of 66.3% in 2025. The segment is expected to maintain its dominance throughout the forecast period. The healthcare industry has been revolutionized by overall digitization, which has improved patient treatment guidance systems and software technologies that have provided simple access to healthcare data through cost-effective automated billing and claims processing systems. Medical billing and claims processing software have several advantages, including more accurate bills, fewer administrative errors, fewer insurance claim denials, invoice tracking, and speedier payments, which boosts efficiency and accuracy even more.
Medical billing and claims processing services are used to process, fill out, and monitor health insurance claims to save time. Medical offices had to make greater billing and payment tracking modifications in 2020 due to new pandemic realities. As the number of COVID-19 patients grew, practitioners were forced to administer the therapies owing to a lack of resources around the world. This helped the medical billing and claims processing service provider get attention, which, in turn, led to higher revenue growth for the competitors in this industry.
One of the key driving causes for practitioners opting for medical billing and claims processing services is the hassle-free procedure of settling claims with features such as the availability of skilled coders familiar with the newest medical codes and claims processing. The significant risk of data breaches connected with medical billing in the U.S., on the other hand, is likely to stifle market expansion throughout the forecast period. According to Becker's Healthcare reported statistics, nearly 50 million Americans' health records have been compromised in 2021, which is almost three times more than in the previous three years.
Solution Type Insights
Based on solution type, the integrated solutions segment held the largest revenue share of over 75.1% in 2025. It is expected to maintain its dominance throughout the forecast period. Navigating convoluted insurance requirements, recognizing best practices for data gathering, and evaluating data to uncover possibilities for improvement are skills that are unrelated to patient care but equally critical for any healthcare institution that wants to stay in business. For the reasons outlined above, providers are constantly looking for methods to improve claim management and medical billing systems. Thus, implementing an integrated billing and claims processing system, which offers several benefits, is one method to do so.
Standalone solutions are primarily focused on certain features and capabilities. When compared to an integrated solution, this sort of solution can provide more features. Following the development of the criteria, a particular choice of one standalone solution that best meets those needs might be made. Furthermore, even though integrated solutions have a limitation of restricted functionality, the rising acceptance of integrated solutions may hinder the growth of the standalone segment over the forecast period.
End-use Insights
Based on end use, the healthcare providers segment held the largest revenue share of 69.0% in 2025. The healthcare providers segment is anticipated to rise moderately over the forecast period, with growth aided by the adoption of rigorous regulatory rules in various countries such as the U.S. Due to IT infrastructure limits in emerging nations, the healthcare providers segment has faced challenges. This is mostly because the price is a key impediment to the adoption of advanced technology such as claims processing software. As advanced deployment modes, such as Cloud-based solutions, gain popularity, implementation of such solutions due to high maintenance costs hinders smaller healthcare provider organizations from adopting such solutions, which might hinder market growth over the forecast period.
 To learn more about this report, Download Free Sample Report
Healthcare payers in this market are expected to expand rapidly during the forecast period, supported by the implementation of stringent regulatory requirements, an in-house lack of experienced individuals for claims processing, and growing healthcare costs and related frauds. Payers have also helped healthcare providers by providing a cloud-based and web-based portal that provides accurate and timely information about not just the pandemic but also assists them to handle medical billing and related claims.
Furthermore, increased occurrences of data breaches and loss of confidentiality, and migration from legacy systems are likely to hinder the growth of the healthcare payers in the market.
Deployment Mode Insights
Based on deployment mode, the web-based segment held the largest revenue share of 46.7% in 2025. The web-based and cloud-based segments both have a strong competitive presence in the market. Sales of cloud-based billing and claims processing services and solutions, which can be hosted on public or private clouds, make up the cloud-based billing and claims processing market. Cloud billing is a concept that refers to a hybrid of cloud computing and electronic billing. Furthermore, cloud medical billing is revolutionizing the computer system, offering increased billing flexibility and data accessibility.
With the rise of the cloud, billing has evolved from a stand-alone back-office solution to a critical component of the whole statement process. Furthermore, regardless of the industry, overall cloud billing services assist organizations in saving money while still offering excellent customer service. According to a Flexera study from 2021, 93% of organizations are using cloud-based technology, with 73% seeking to optimize their present cloud utilization for cost savings. As a result, the cloud-based billing industry's overall growth is being supported by a growing need for cheaper capital and operating costs.
A web browser is required to use web-based medical billing and claims processing systems. Web software is made by combining handwriting (user) with scripting languages like Java and Adobe Flash (server). To allow online web services to work, the web browser relies on the parts of the webserver installed on the device.
The web-based segment would see similar positive acceptance by applicants as a cloud-based system, but market growth would vary over time as cloud-based systems are still preferred since a web-based system requires internet connectivity to access the system. While needing an online internet connection is a limitation compared to a cloud-based system, it does have the advantage of allowing users to access the system from anywhere.
Since the hardware, data, and software platform are within your control and ownership, thus, it is anticipated that throughout the forecast period, on-premise billing and claims processing software and services would contribute to the segment growth. Furthermore, this growth will undoubtedly increase as the system's adoption increases; however, this growth of traditional on-premise medical billing and claims processing systems will be relatively less in comparison to cloud-based and web-based systems, which have gained popularity and acceptance in the aftermath of the pandemic.
Regional Insights
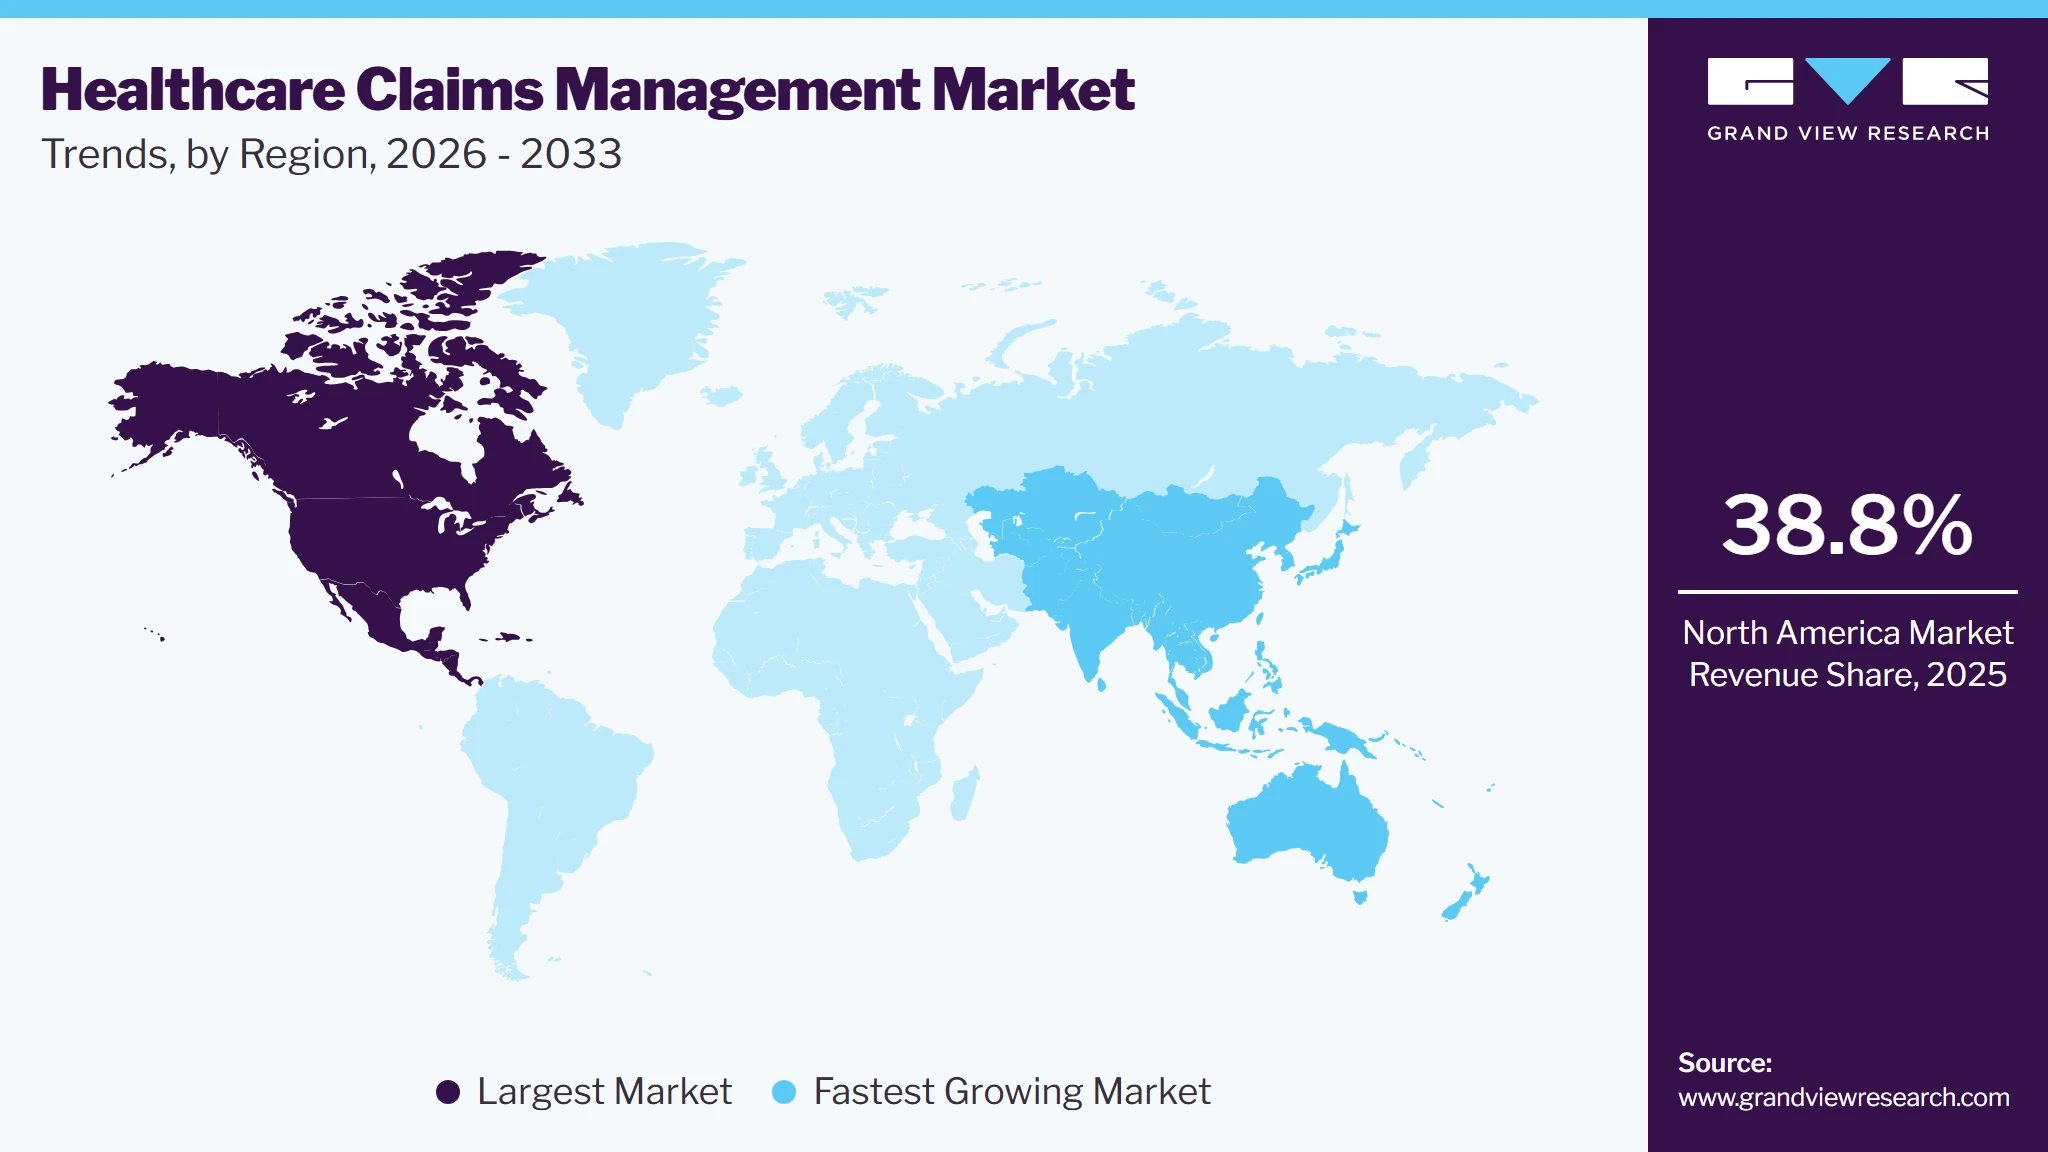
North America dominated the healthcare claims management market with the largest revenue share of 38.8% in 2025. This can be attributed to an increase in patient load and healthcare coverage, adoption of EHRs and e-prescribing services, growing government spending, and improving healthcare infrastructure.
 To learn more about this report, Download Free Sample Report
U.S. Healthcare Claims Management Market Trends
The healthcare claims management market in the U.S. held the largest share in the North America region in 2025. This dominance is driven by the country’s complex healthcare insurance and reimbursement system, which generates high demand for efficient claims-processing solutions. Increasing healthcare spending and claim volumes are encouraging providers and payers to automate claims workflows and reduce administrative costs. The adoption of AI, automation, and cloud-based platforms is improving claims adjudication, denial management, fraud detection, and payment accuracy. Rising regulatory requirements and widespread use of electronic health records further support digital claims processing.
Asia Pacific Healthcare Claims Management Market Trends
Asia Pacific (APAC) is expected to be the fastest-growing region in the forecast period. Factors such as the quick expansion of the healthcare business in India attempts to improve the quality of healthcare delivery in Japan, and the adoption of healthcare IT systems in countries with well-developed healthcare systems such as China is expected to contribute to Asia's strong growth over the forecast period.
Key Healthcare Claims Management Company Insights
The market is highly fragmented with many small and large players. This leads to high competition for the companies to sustain their position. Many software companies have given medical billing and claims processing software to this very profitable area, resulting in increased rivalry. To remain competitive, several companies have begun to provide comprehensive portal solutions via their web interfaces. According to a Kaiser Family Foundation study, insurance companies reject roughly one out of every five claims because of identical claims and a lack of transparency. As a result, companies that can bring more effective technologies to the market will have an edge over the broader market, especially if their software is backed up by solid insurance claims with no or few denials, indicating their superiority over alternatives. This will eventually lead to industry expansion.
Besides, notable players contribute to the industry growth by entering acquisitions and launching new products. For instance, in October 2021, The SSI Group developed a strategic alliance with RCxRules to provide updated automated billing solutions for healthcare organizations' population health and revenue cycle operations, resulting in revenue growth as the strategic partnership grows. Likewise, in January 2021, Optum acquired Change Healthcare, with the acquisition assisting the company in gaining software, advisory management, technology, and revenue cycle management. Some prominent players in the global healthcare claims management market include:
Key Healthcare Claims Management Companies
The following key companies have been profiled for this study on the healthcare claims management market.
-
McKesson Corporation
-
The SSI Group, Inc.
-
Quest Diagnostics
-
Kareo
-
Optum, Inc (a subsidiary of UnitedHealth Group)
-
Conifer Health Solutions
-
CareCloud
-
eClinicalWorks
-
IBM
-
Cerner Corporation
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (UnitedHealth Group, McKesson Corporation, Oracle, Experian Health)
- Offer end-to-end healthcare claims management and RCM solutions with AI, automation, cloud deployment, analytics, and payer-provider connectivity.
- Strong global presence, broad product portfolios, advanced AI capabilities, large customer base, and established payer-provider networks.
- High implementation costs, complex legacy system integration, long deployment cycles, and regulatory compliance challenges.
Emerging / Specialized Players (R1 RCM Inc., Veradigm Inc., Availity, LLC, eClinicalWorks)
- Focus on cloud-based claims management, medical billing, denial management, payer connectivity, and AI-driven workflow automation.
- Agile innovation, cost-effective SaaS solutions, strong RCM expertise, and faster deployment.
- Limited global reach, narrower product portfolios, and lower enterprise penetration compared to established players.
Recent Developments
-
In June 2026, Capline Healthcare Management announced that its AI-powered revenue cycle management (RCM) platform helps healthcare practices recover 15–20% more revenue by improving claims accuracy, denial management, eligibility verification, and accounts receivable follow-up. The company reported a 96% first-pass claim acceptance rate and highlighted AI-enabled workflows as a means to reduce revenue leakage and accelerate reimbursements for over 1,300 U.S. healthcare practices.
"Independent practices need more than basic billing help. Many of them are losing money because claims are not corrected quickly, denials are not worked with enough consistency, or aging accounts do not get the right follow-up. Our AI-RCM process helps our team find those issues earlier and move them through the right workflow."
- Abhinav Rastogi, Founder, Capline Healthcare Management
-
In May 2026, Aetna, a CVS Health company, launched its second-generation AI-powered Claims Assist Manager (CAM) to streamline healthcare claims processing and improve payment accuracy. The platform uses agentic AI to automate manual review workflows and has reduced complex claims processing time by over 20%, improving reimbursement speed and efficiency.
“Claims Assist Manager shows how we are using AI to modernize the fundamentals of healthcare operations, by reducing manual steps and accelerating decision making, we are delivering faster, more reliable outcomes for providers and members.”
- Katerina Guerraz, EVP and Chief Operating Officer at Aetna.
Healthcare Claims Management Market Report Scope
Report Attribute
Details
Market size in 2025
USD 35.7 billion
Estimated market size in 2026
USD 42.3 billion
Projected market size by 2033
USD 146.6 billion
Growth rate
CAGR of 19.4% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Solution type, deployment mode, component, product, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S., Canada, Mexico, UK, Germany, France, Italy, Spain, Norway, Denmark, Sweden, China, Japan, India, South Korea, Australia, Thailand, Brazil, Argentina, Saudi Arabia, South Africa, UAE, Kuwait
Key companies profiled
UnitedHealth Group, McKesson Corporation, Oracle, Veradigm Inc., R1 RCM Inc., Experian Health, Waystar Holding Corp., Change Healthcare, Cognizant Technology Solutions Corporation, Conifer Health Solutions, Availity, LLC, eClinicalWorks
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Healthcare Claims Management Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels, and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global healthcare claims management market report based on product, component, solution type, deployment mode, end-use, and region:
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Medical Billing
-
Professional
-
Institutional
-
-
Claims Processing
-
-
Component Outlook (Revenue, USD Million, 2021 - 2033)
-
Software
-
Services
-
-
Solution Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Integrated Solutions
-
Standalone Solutions
-
-
Deployment Mode Outlook (Revenue, USD Million, 2021 - 2033)
-
Cloud-based
-
On-premise
-
Web-based
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Healthcare Providers
-
Healthcare Payers
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
U.K.
-
Germany
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
Mexico
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
Israel
-
-
Research Methodology
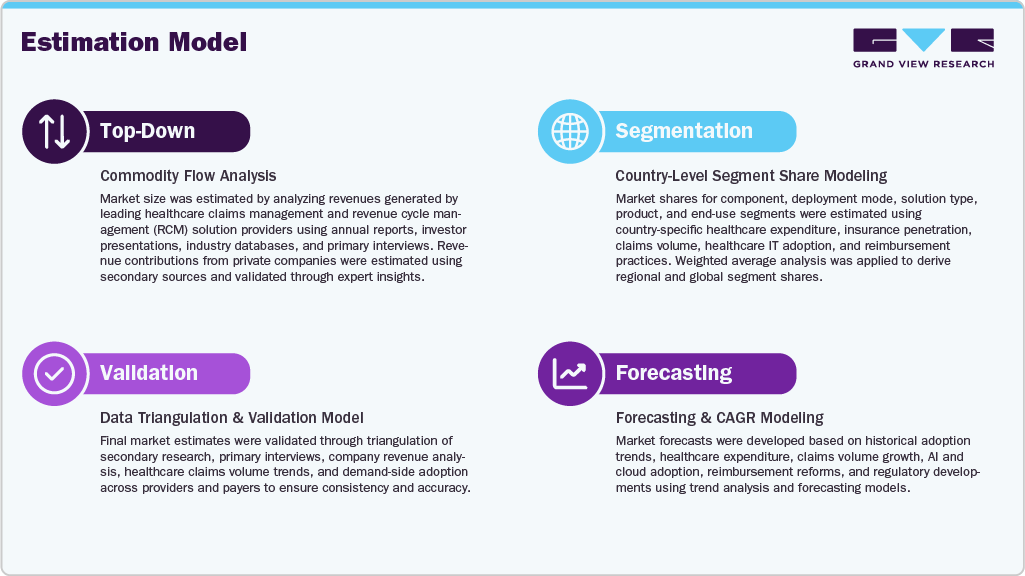
The healthcare claims management market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each healthcare claims management segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment- Product
Revenue Capture Definition
Medical Billing
Revenue generated from solutions used to create, submit, track, and reconcile medical claims for healthcare services. This includes physician and hospital billing software, charge capture systems, coding and documentation tools, payment posting, patient billing, accounts receivable management, denial management, and reimbursement optimization solutions that facilitate accurate claim generation and payment collection.
Claims Processing
Revenue generated from solutions that automate and manage the complete healthcare claims lifecycle, including claims intake, validation, adjudication support, eligibility verification, fraud detection, payment determination, remittance processing, denial management, appeals management, and claims settlement across payer and provider organizations.
Segment-Component
Revenue Capture Definition
Software
Revenue generated from software platforms used for medical billing, electronic claims submission, claims editing, denial management, payment posting, coding assistance, eligibility verification, prior authorization, reimbursement management, and revenue cycle optimization. This includes standalone claims management applications, integrated revenue cycle management (RCM) platforms, AI-enabled claims automation software, cloud-based claims processing solutions, and payer-provider claims exchange systems.
Services
Revenue generated from professional and managed services supporting healthcare claims management, including medical billing outsourcing, claims processing services, coding services, denial management, revenue cycle consulting, implementation, training, system integration, maintenance, technical support, and business process outsourcing (BPO) services related to healthcare reimbursement.
Segment-Solution Type
Revenue Capture Definition
Integrated Solutions
Revenue generated from comprehensive healthcare claims management platforms integrated with electronic health records (EHR), electronic medical records (EMR), practice management systems, hospital information systems (HIS), revenue cycle management (RCM), payment systems, and payer networks. These solutions provide end-to-end claims workflow automation, interoperability, financial reporting, and reimbursement management within a unified platform.
Standalone Solutions
Revenue generated from independent healthcare claims management applications that perform specific claims-related functions such as claims submission, claims editing, denial management, eligibility verification, payment reconciliation, or coding support without requiring full integration into enterprise healthcare management platforms.
Segment-Deployment Mode
Revenue Capture Definition
Cloud-Based
Revenue generated from healthcare claims management solutions hosted on cloud infrastructure and delivered through Software-as-a-Service (SaaS) or hosted platforms. These solutions provide remote accessibility, automated updates, scalable computing resources, data backup, security, interoperability, and subscription-based claims management capabilities.
On-Premise
Revenue generated from healthcare claims management software installed and operated on the customer's internal servers or data centers. Revenue includes perpetual software licenses, implementation, customization, maintenance, upgrades, and infrastructure-related services supporting locally deployed claims management systems.
Web-Based
Revenue generated from browser-accessible healthcare claims management applications hosted on centralized servers and accessed through internet connectivity. These solutions enable online claim submission, reimbursement tracking, eligibility verification, coding support, denial management, and payment reconciliation without requiring local software installation.
Segment- End Use
Revenue Capture Definition
Healthcare Providers
Revenue generated from healthcare claims management solutions purchased by hospitals, physician practices, ambulatory surgical centers, diagnostic laboratories, imaging centers, rehabilitation facilities, home healthcare providers, specialty clinics, and other healthcare delivery organizations for medical billing, claims submission, reimbursement management, denial management, coding, and revenue cycle optimization.
Healthcare Payers
Revenue generated from healthcare claims management solutions utilized by public and private health insurance companies, managed care organizations, third-party administrators (TPAs), government healthcare programs, and other payer organizations for claims adjudication, payment processing, fraud detection, eligibility verification, provider reimbursement, utilization management, and claims analytics.
Estimation Model
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Pricing Model Benchmarking
Analysis of key pricing models such as subscription, per-claim, enterprise licensing, and managed services used in healthcare claims management solutions.
Helps identify optimal pricing strategy, customer willingness-to-pay, and revenue optimization opportunities.
Competitive Landscape Analysis
Analysis of key players based on product portfolio, market presence, AI capabilities, RCM solutions, claims automation, interoperability, cloud adoption, and strategic initiatives.
Company market share analysisHelps understand market structure, competitive positioning, key differentiators, and growth strategies of leading vendors.
Regional Demand & Digital Transformation Analysis
Assessment of regional demand across major geographies driven by healthcare digitization, insurance expansion, and AI adoption in claims processing.
Helps identify high-growth regions and supports market expansion and investment decisions.
Frequently Asked Questions About This Report
Web-based segment held the largest revenue share of 46.7% in 2025.
The integrated solutions segment held the largest revenue share of over 75.1% in 2025.
The global healthcare claims management market size was estimated at USD 35.7 billion in 2025 and is expected to reach USD 42.3 billion in 2026
Asia Pacific is the fastest-growing region over the forecast period.
North America dominated the healthcare claims management market with a share of 38.8% in 2025.
Some key players operating in the healthcare claims management market include UnitedHealth Group, McKesson Corporation, Oracle, Veradigm Inc., R1 RCM Inc., Experian Health, Waystar Holding Corp., Change Healthcare, Cognizant Technology Solutions Corporation, Conifer Health Solutions, Availity, LLC, eClinicalWorks.
The global healthcare claims management market is expected to grow at a CAGR of 19.4% from 2026 to 2033, reaching USD 146.6 billion by 2033
Software segment held the largest revenue share of 66.3% in 2025.The segment is expected to maintain its dominance throughout the forecast period.
Key factors that are driving the healthcare claims management market growth include increasing healthcare claims volume and shift toward automated revenue cycle management, growing adoption of AI and cloud-based claims management solutions, and rising focus on reducing claim denials and improving revenue cycle efficiency.
About the Author(s)
Healthcare IT Research Team
Healthcare · Healthcare ITThis report was authored by the healthcare it research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the healthcare it segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


