
- Home
- »
- Medical Devices
- »
-
Healthcare Contract Sales Organizations Market Report, 2026-2033GVR Report cover

Healthcare Contract Sales Organizations Market (2026 - 2033)
Size, Share & Trends Analysis Report By Service (Personal Promotion, Non - Personal Promotion), By Therapeutic Area (Oncology, Cardiovascular, Neurology), By End Use, By Region, And Segment Forecasts
Market Size, 2025
$11.9BMarket Estimate, 2026
$12.9BMarket Forecast, 2033
$21.8BCAGR, 2026–2033
7.8%Healthcare Contract Sales Organizations Market Summary
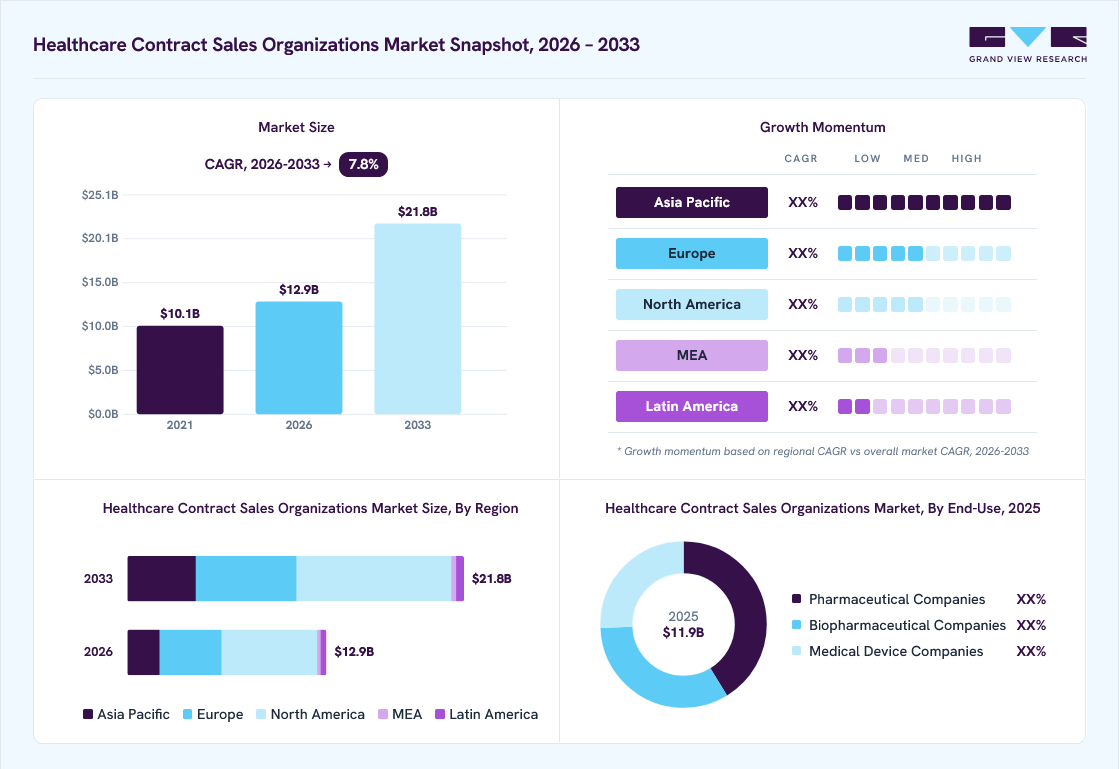
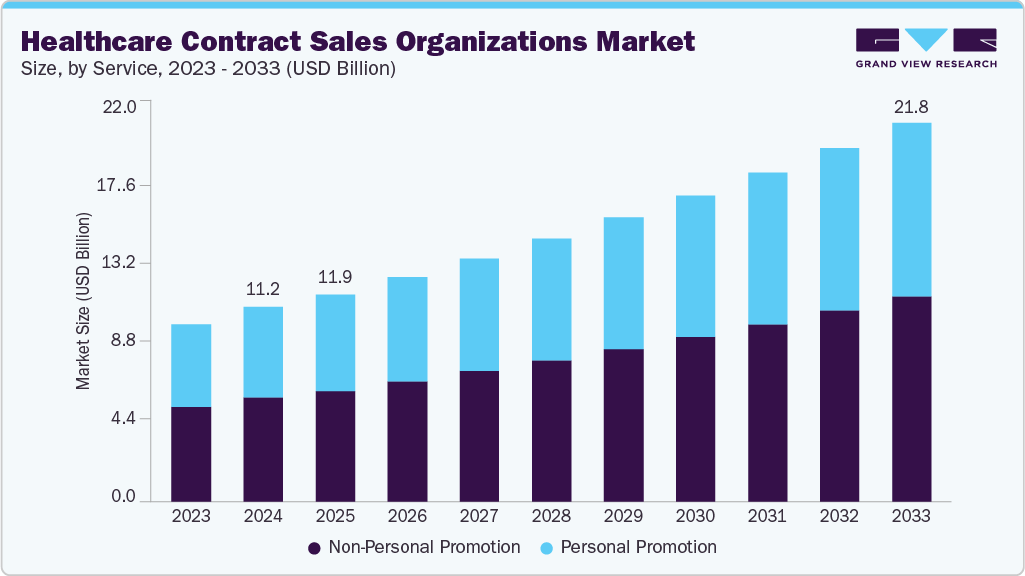
The global healthcare contract sales organizations market size was valued at USD 11.9 billion in 2025 and is projected to grow from USD 12.9 billion in 2026 to USD 21.8 billion by 2033, growing at a CAGR of 7.8% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 48.2% in 2025. The market is advancing due to several factors, including the growing demand for specialty and innovative drugs, technological advancements and digital transformation, and the increasing interest of healthcare companies in expanding product sales.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By service: Non-personal promotion segment led the market with the largest share of 53.4% in 2025.
- By therapeutic area: Oncology segment led the market with the largest share of 31.1% in 2025.
- By end-use: Pharmaceutical companies segment led the market with the largest share of 37.6% in 2025.
Regional Highlights
- Largest regional market: North America (48.2% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (fastest CAGR, 2026-2033)
- By country: The U.S. is expected to grow significantly from 2026 to 2033
Market Size & Forecast
- Market size in 2025: USD 11.9 Billion
- Estimated market size in 2026: USD 12.9 Billion
- Projected market size by 2033: USD 21.8 Billion
- CAGR (2026-2033): 7.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Increasing global shift toward personalized and specialty medicines such as biologics, oncology therapies, and rare disease treatments is one of the factors driving market growth. Meeting the demand for innovative medicines requires highly trained, niche-focused salesforces. Thus, pharmaceutical companies rely on CSOs with specialized therapeutic knowledge and advanced engagement capabilities to effectively communicate complex product information to healthcare professionals. This has led to expanded roles for CSOs in educational outreach, post-launch support, and digital engagement.Furthermore, the integration of artificial intelligence (AI), customer relationship management (CRM) tools, and digital marketing platforms is revolutionizing performance in healthcare sales and outreach. For instance, about 35% of drug manufacturers are adopting broader digital transformation initiatives to boost efficiency and innovation. CSOs adopting these technologies can deliver data-driven insights, optimize field force productivity, and enhance customer engagement through multichannel strategies. This digital transformation reduces costs and improves efficiency, making CSOs indispensable partners for modern pharmaceutical companies. Moreover, the use of virtual detailing and analytics-driven targeting has expanded the role of CSOs beyond traditional sales, strengthening their position in an increasingly tech-enabled healthcare ecosystem.
 To learn more about this report, Download Free Sample Report
Moreover, intensifying competition in the global healthcare and pharmaceutical sectors has propelled companies to seek innovative strategies to expand their product reach and maximize revenue potential. As new therapies and medical technologies enter the market, healthcare firms face increasing pressure to achieve faster adoption and wider coverage across diverse healthcare systems. This has led to a surge in partnerships with contract sales organizations that offer specialized, scalable salesforces and strong local market expertise. CSOs help companies penetrate competitive markets, improve product visibility, and maintain consistent engagement with healthcare professionals. Thus, the growing sales-driven focus of healthcare firms continues to propel the demand for contract sales services worldwide.
Opportunity Analysis
The healthcare contract sales organizations market presents significant opportunities driven by increasing outsourcing trends among pharmaceutical, biotechnology, and medical device companies. As firms focus on core competencies, such as R&D, they increasingly rely on CSOs for scalable, data-driven sales and marketing support. The growing adoption of digital health solutions, AI-based customer targeting, and omnichannel engagement enhances efficiency and reach. Expansion into emerging markets with rising healthcare expenditure further boosts potential. Moreover, evolving healthcare regulations and the demand for specialized sales forces in niche therapies open avenues for innovation and strategic partnerships across global and regional CSO networks.
Impact of U.S. Tariffs on the Global Healthcare Contract Sales Organizations Market
The imposition of new U.S. tariffs and the Trump administration’s drug pricing reforms are reshaping the global healthcare contract sales organizations industry. For instance, in October 2025, major pharmaceutical companies such as AbbVie, AstraZeneca, and Bristol-Myers Squibb opted for direct-to-consumer sales and discounts but the role of intermediaries, including CSOs, faces disruption. Initiatives such as TrumpRx.gov, launching in early 2026, aim to bypass traditional sales channels, pressuring CSOs to adapt through digital transformation and strategic diversification. The short-term impacts include reduced outsourcing demand in the U.S., but the global markets may benefit from companies reallocating CSO functions to cost-efficient regions, driving innovation and cross-border partnership opportunities.
Technological Advancements
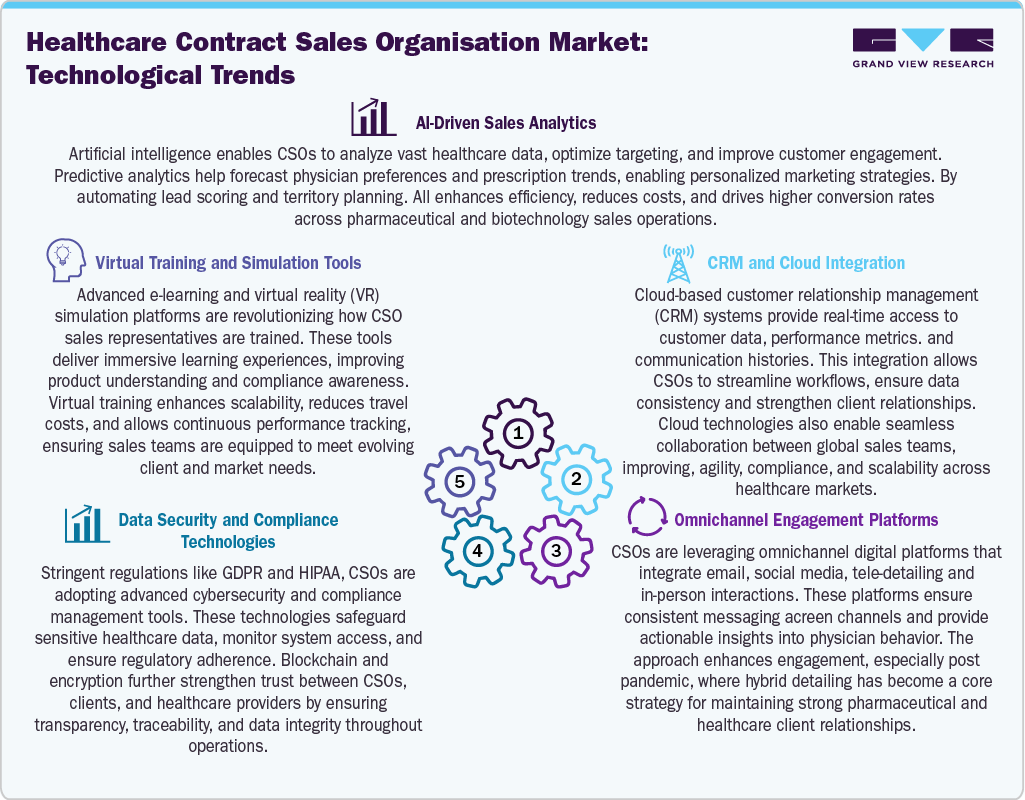
Technological advancements are transforming the Healthcare Contract Sales Organizations (CSO) market by enhancing efficiency, compliance, and engagement. AI-driven analytics optimize sales targeting and forecasting, while cloud-based CRM systems improve data access and collaboration. Omnichannel engagement platforms integrate digital and physical interactions for seamless physician communication. Advanced data security tools ensure regulatory compliance and protect sensitive healthcare information. In addition, virtual training and simulation technologies enable scalable, cost-effective, and immersive learning experiences for sales teams. In conclusion, these innovations empower CSOs to deliver personalized, data-driven strategies, strengthen client relationships, and adapt to the rapidly evolving healthcare and pharmaceutical commercialization landscape.
 To learn more about this report, Download Free Sample Report
Pricing Model Analysis
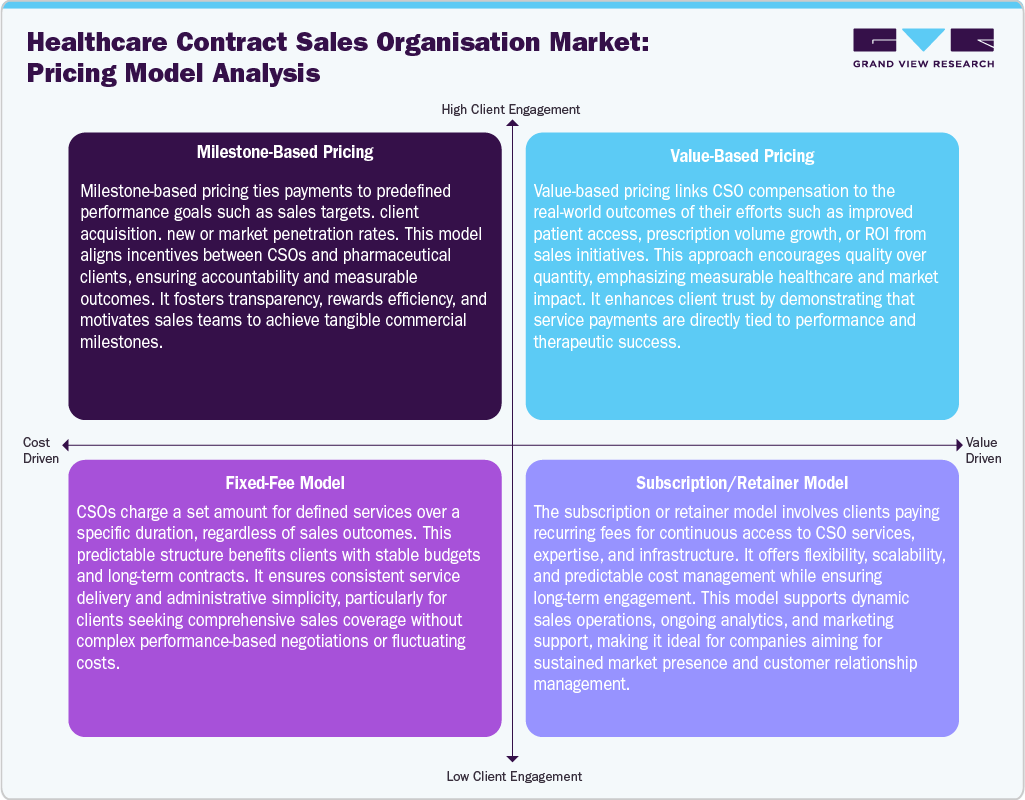
In the healthcare CSO market, four primary pricing models are employed to align services with sponsor needs. Milestone-based pricing ties payments to achieving specific sales or performance goals, ensuring accountability. Value-based pricing focuses on measurable outcomes like market impact or patient access, emphasizing quality. Fixed-fee models provide predictable costs for defined services, ensuring budget stability. Subscription or retainer models offer continuous access to CSO expertise through recurring payments, supporting sustained engagement and scalability. Thus, these models enable pharmaceutical and biotech companies to choose cost-effective, transparent, and performance-driven partnerships that align with their commercialization and market expansion strategies.
 To learn more about this report, Download Free Sample Report
Market Dynamics
The healthcare contract sales organizations market is witnessing growth as pharmaceutical, biopharmaceutical, and medical device companies increasingly opt for outsourced commercial models to enhance flexibility, speed, and market reach. Besides, the rising demand for specialty and innovative therapies is expected to drive the need for skilled sales representatives, key account managers, medical affairs support, remote medical science liaisons, and nurse educators who can effectively communicate complex product value to targeted healthcare professionals.
Moreover, the market is fueled by the growing adoption of hybrid and omnichannel engagement models, integrating field promotion with virtual detailing, digital education, CRM-based targeting, and analytics-driven performance tracking. Such strategies enable companies to enhance physician engagement, optimize territory coverage, and facilitate product launches more efficiently.
Furthermore, an increase in product launches, geographic expansion strategies, and the demand for scalable commercial infrastructure are offering significant new opportunities for Contract Sales Organization (CSO) providers. Thus, the market is anticipated to be fueled by therapy-specific sales models, specialty care commercialization, enhanced digital engagement capabilities, flexible field force deployment, and outcome-oriented outsourcing partnerships. Such factors are expected to drive the market growth.
The growing demand for specialty and innovative drugs is one of the key driver for the Healthcare Contract Sales Organizations market. Specialty medicines, including biologics, oncology therapies, immunology drugs, neurology treatments, rare disease therapies, and advanced injectable products, require highly targeted commercial engagement compared to traditional primary care drugs which drives the market growth. Besides, these therapies often involve complex clinical data, specialist prescribers, patient access challenges, reimbursement considerations, and the need for continuous scientific education. As a result, pharmaceutical and biopharmaceutical companies increasingly rely on CSOs to deploy trained sales representatives, key account managers, remote medical science liaisons, and nurse educators who can support specialized product communication.
Moreover, the trend is particularly driven by new product launches, indication expansions, and geographic market entry, where companies require rapid commercial scale-up without building permanent internal sales teams. CSOs supports clients to improve physician engagement, strengthen account coverage, and accelerate market penetration across hospitals, specialty clinics, and targeted prescriber networks. In addition, specialty drugs require coordinated support across sales, medical affairs, and patient education, creating demand for integrated CSO models. Thus, rising specialty drug commercialization is expanding the need for flexible, therapy-specific, and knowledge-intensive contract sales solutions.
Regulatory complexity acts as a key restraint for the Healthcare Contract Sales Organizations market, as CSO providers must operate within strict compliance frameworks governing pharmaceutical promotion, medical communication, data privacy, and healthcare professional engagement. Sales representatives, remote MSLs, nurse educators, and key account teams must ensure that promotional claims, product discussions, and educational interactions remain aligned with approved labeling and regional regulations. Any non-compliance can lead to reputational risk, penalties, and client loss. As regulations differ across countries, CSO providers face higher training, monitoring, documentation, and quality assurance costs, which can limit scalability and slow market expansion.
The growing shift toward omnichannel and hybrid healthcare professional engagement presents a strong opportunity for the Healthcare Contract Sales Organizations market. Pharmaceutical, biopharmaceutical, and medical device companies are increasingly moving beyond traditional field sales models and adopting a mix of in-person promotion, remote detailing, virtual medical science liaison support, digital education, nurse educator programs, webinars, and analytics-led targeting. This creates demand for CSO providers that can deliver flexible, technology-enabled commercial support across multiple channels. As healthcare providers prefer more personalized and convenient interactions, CSOs can help clients improve reach, frequency, and engagement quality without increasing fixed internal sales force costs. Hybrid models are particularly valuable for specialty therapies, product launches, mature brands, and regional market expansion, where companies need scalable support tailored to specific physician groups, accounts, and therapeutic areas. CSOs that invest in digital platforms, CRM integration, remote engagement teams, and performance analytics can capture higher-value contracts. Thus, omnichannel commercialization offers a major growth opportunity by enabling cost-efficient, measurable, and targeted healthcare engagement.
Market Concentration & Characteristics
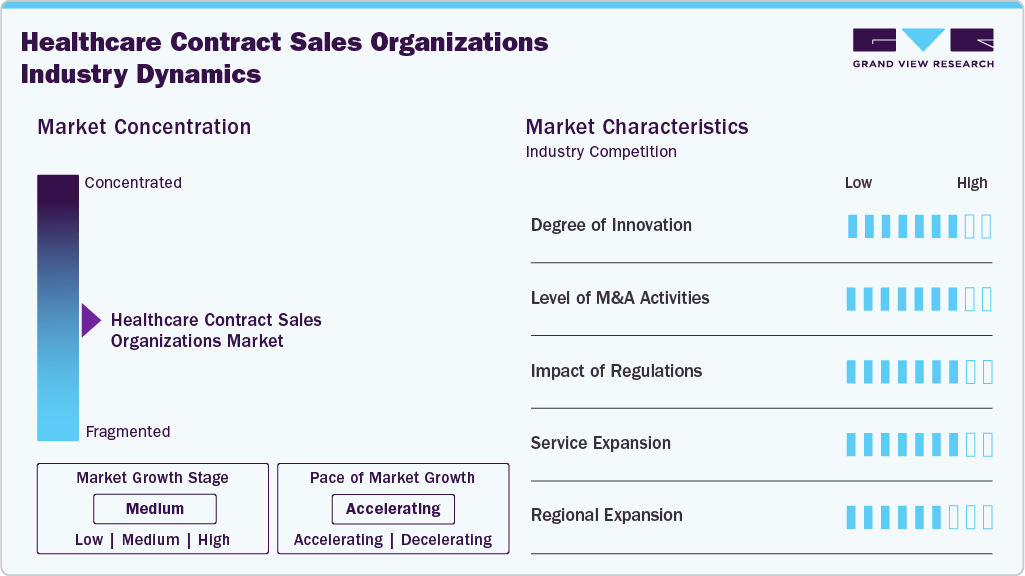
The healthcare contract sales organizations industry is witnessing moderate growth, with growth accelerating. The market is characterized by the degree of innovation, level of M&A activities, regulatory impact, service expansion, and regional expansion.
The market is witnessing a surge in innovation through AI-driven analytics, omnichannel engagement, and CRM integration. These technologies enhance field force productivity, optimize physician targeting, and improve compliance tracking, enabling pharma companies to achieve higher sales efficiency. For instance, in October 2025, Grupo Elfa and NUPCO signed an MoU to enhance Saudi Arabia’s healthcare ecosystem through AI integration, innovative supply-chain models, and collaborative sourcing, supporting Vision 2030’s goals for efficiency and resilience.
 To learn more about this report, Download Free Sample Report
Mergers and acquisitions are reshaping the healthcare CSO landscape, with large firms acquiring niche service providers to expand therapeutic expertise, digital capabilities, and geographic coverage. For instance, in August 2025, EVERSANA and Waltz Health merged to create a unified healthcare platform integrating AI-powered drug-price and payer models, enhancing pharmaceutical commercialization, patient access, and affordability across the U.S. healthcare ecosystem.
The global healthcare regulations are evolving, demanding transparency in promotional activities, data privacy, and compliance with ethical marketing standards. Stricter oversight encourages CSOs to adopt advanced compliance tools, standardized training, and audit mechanisms, enhancing trust between healthcare providers, pharmaceutical clients, and regulatory bodies.
CSOs are diversifying services to include digital detailing, patient support, data analytics, and market access consulting. This evolution enables pharmaceutical clients to streamline multichannel engagement, enhance brand visibility, and adapt to hybrid sales environments driven by technology adoption and shifting models of healthcare professional interaction.
Healthcare CSOs are actively expanding into emerging markets of the Asia Pacific, Latin America, and the Middle East, capitalizing on growing pharmaceutical demand and healthcare infrastructure development. Regional diversification enables companies to balance revenue streams, access new client bases.
Analyst Perspective
The Healthcare Contract Sales Organizations (CSOs) market is witnessing new growth opportunities as it transitions from a traditional outsourced sales model to a more integrated commercial enablement ecosystem. This change is driven by the need for flexible field force deployment, expedited product launch execution, and cost-efficient market coverage across both specialty and primary care therapies. As healthcare engagement grows more complex, CSO services are evolving towards hybrid models that include a mix of in-person promotion, remote scientific engagement, nurse education, key account support, and analytics-led targeting.
Pharmaceutical, biopharmaceutical, and medical device companies are increasingly shifting towards CSOs to manage their fluctuating sales force needs, expand into new markets, and support both mature and newly launched products without the necessity of building large fixed internal teams. Moreover, increasing therapeutic specialization, omnichannel engagement capabilities, compliance-driven execution, and quantifiable sales productivity is expected to drive the market. Thus, the market offers new opportunities for scalable, outcome-oriented commercial outsourcing models that align with the changing engagement needs of healthcare providers.
Service Insights
Based on service, the non-personal promotion segment led the market with the largest revenue share of 53.4% in 2025 and is expected to grow at the fastest CAGR over the forecast period. Medical affairs solutions, remote medical science liaisons, nurse (clinical) educators, and others are included in this segment. Digital transformation and evolving physician engagement models drive the segment growth. Pharmaceutical and biotech companies are increasingly relying on virtual communication tools, email marketing, webinars, and AI-driven content delivery to reach healthcare professionals efficiently. For instance, in October 2025, Wellgistics Health partnered with DataVault AI to develop PharmacyChain, a blockchain-enabled manufacturer-to-patient platform enhancing prescription tracking, reimbursement, and distribution, with beta testing planned for early 2026. This innovation positions Wellgistics for market expansion and competitive differentiation.
On the other hand, the personal promotion segment held the second fastest growth over the analysis timeframe. This segment comprises the promotional sales team, key account management, and vacancy management. The market is driven by its critical role in building strong relationships between healthcare professionals and pharmaceutical companies. Personalized, face-to-face interactions facilitate the effective communication of drug benefits, clinical data, and patient outcomes, ultimately leading to improved prescription uptake. CSOs increasingly employ trained medical representatives and hybrid digital engagement models to enhance reach and compliance.
Therapeutic Area Insights
Based on therapeutic area, the oncology segment led the market with the largest revenue share of 31.1% in 2025 and is expected to grow at the fastest CAGR over the forecast period, due to the growing prevalence of cancer and the increasing complexity of oncology therapies. According to the United States Cancer Statistics (USCS), in 2023, cancer was responsible for more than 613,349 deaths in the U.S. Pharmaceutical companies depend on specialized CSOs to manage physician engagement, patient support, and multichannel sales for high-cost, targeted therapies. The need for extensive education, adherence monitoring, and regulatory compliance further drives the outsourcing trend. Ongoing advancements in biologics, immunotherapies, and precision medicine have led to the need for oncology-focused CSOs, which are essential for facilitating timely market access and supporting the effective commercialization of these innovative therapies.
The cardiovascular segment is projected to witness the second-fastest growth during the forecast period, driven by increasing demand for innovative therapies and the expansion of emerging healthcare markets. Pharmaceutical companies are outsourcing specialized sales teams to CSOs to effectively promote cardiovascular drugs, including biologics and novel therapeutics, to healthcare professionals. The growth is further boosted by several other factors, including aging populations, increased adoption of cardiovascular treatments, and ongoing clinical advancements.
End Use Insights
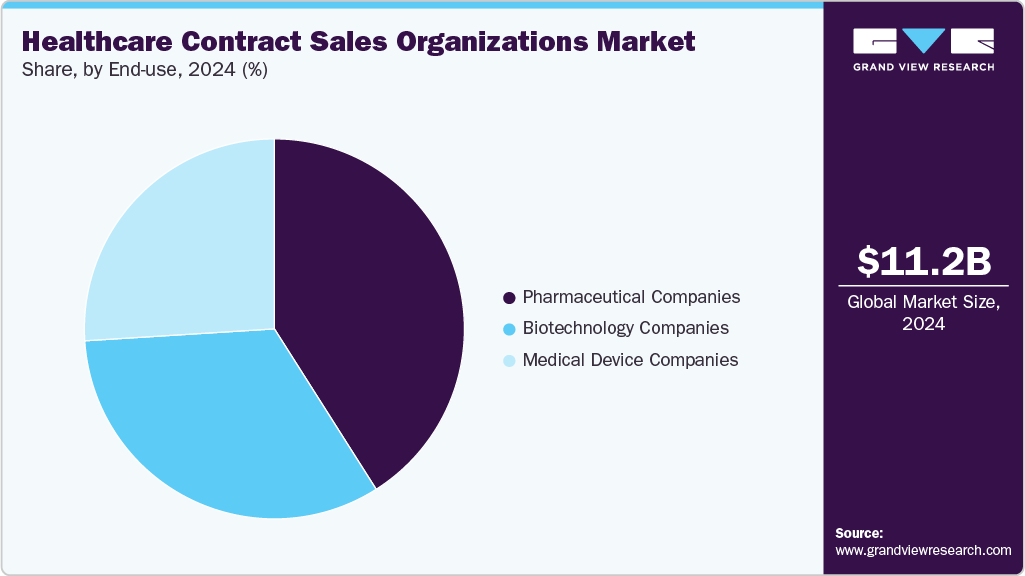
Based on end use, the pharmaceutical companies segment led the market with the largest revenue share of 37.6% in 2025. The growth of this segment is driven by high demand for outsourced sales and marketing support. Companies outsource to CSOs for managing product launches, physician detailing, and efficient multichannel engagement. With the growing complexity of drug portfolios, regulatory compliance requirements, and the need for targeted sales strategies, CSOs have become essential partners, making pharmaceutical companies the dominant segment in the market.
 To learn more about this report, Download Free Sample Report
The biopharmaceutical companies segment is estimated to witness the fastest-growing CAGR over the forecast period. The rapid development of biologics, gene therapies, and specialty drugs drives the segment growth. These complex and high-value therapies require highly skilled salesforces, targeted physician engagement, and compliance with stringent regulations. Rising investment in personalized medicine, niche therapeutics, and global clinical trials further drives demand, positioning biopharmaceutical companies as the key growth engine in the CSO market.
Regional Insights
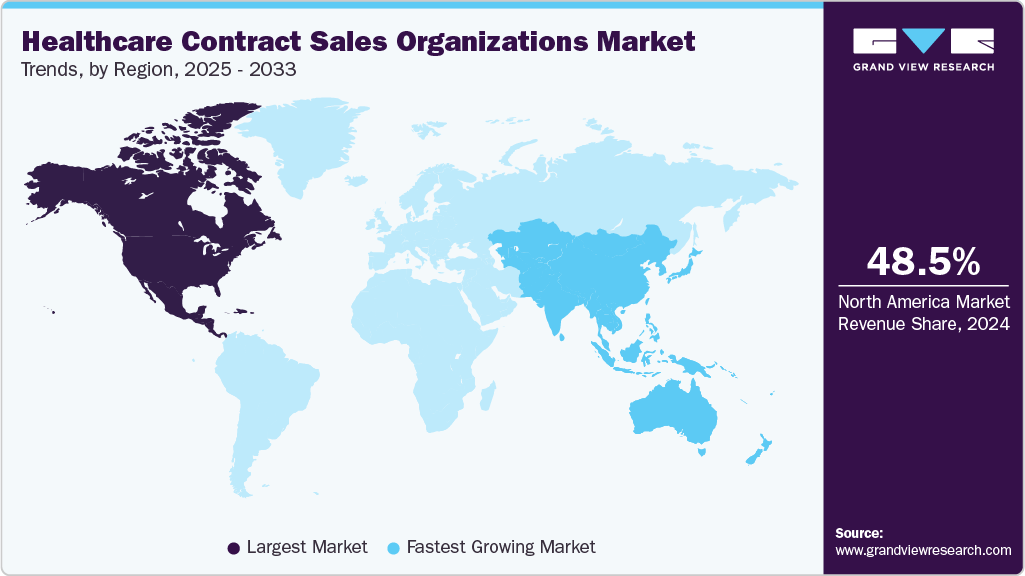
North America dominated the healthcare contract sales organizations market with the largest revenue share of 48.2% in 2025, driven by growing outsourcing of sales and marketing, cost optimization, and the increasing complexity of pharmaceutical launches. Companies such as IQVIA, Syneos Health, and MaBico are boosting market growth through strategic initiatives. The region is making advances in digital detailing, AI-driven sales analytics, and virtual engagement platforms that improve efficiency and targeting. The rising focus on specialty therapies and personalized medicine further increases CSO demand, making the region highly competitive with innovative service offerings and strategic partnerships, transforming the market.
 To learn more about this report, Download Free Sample Report
U.S. Healthcare Contract Sales Organizations Market Trends
The healthcare contract sales organizations market in the U.S. held the largest share in the North America region in 2025, driven by increasing pressure to lower drug prices, government initiatives, and growing competition among CSOs to support DTC strategies. For example, in October 2025, it was reported that pharmaceutical companies such as AbbVie, AstraZeneca, and Bristol-Myers Squibb would sell drugs directly to U.S. patients at discounts, supporting Trump’s efforts to reduce prices and bypass intermediaries.
The Canada healthcare contract sales organizations industry is expected to grow at a single-digit CAGR during the forecast period, as pharmaceutical companies seek cost-efficient, flexible sales solutions amid rising healthcare expenditures and regulatory scrutiny. CSOs are enhancing analytics, multichannel marketing, and remote detailing capabilities to support pharma clients. Strategic partnerships and consolidation among CSOs are also intensifying competition, enabling providers to offer broader geographic reach and comprehensive services across Canada.
Europe Healthcare Contract Sales Organizations Market Trends
The Europe healthcare contract sales organizations industry is projected to have a robust CAGR during the forecast period as companies focus on device commercialization and market expansion. Strategic collaborations with major hospitals, such as AP-HP and Nantes University Hospital, enhance market credibility, prompting CSOs to offer specialized sales, training, and support services to capture the evolving European healthcare landscape.
The healthcare contract sales organizations industry in Germany held the largest share in 2025, fueled by strong healthcare infrastructure, high R&D investment, and an aging population. The market is expanding as pharma companies increasingly outsource sales and marketing functions to optimize efficiency and compliance. Germany's robust healthcare infrastructure and favorable regulatory environment continue to attract investments and partnerships, fostering a conducive ecosystem for CSOs.
The UK healthcare contract sales organizations industry accounted for a notable share in Europe in 2025. Growth in this region is driven by increasing demand for sterile injectables, strict regulatory standards, and strategic partnerships. For instance, in June 2025, Romanian company Antibiotice received NHS contracts for injectable penicillins, highlighting the importance of consistent supply, quality compliance, and tender competitiveness. This initiative demonstrated success in the UK healthcare market by emphasizing the need for reliable production and adhering to stringent quality standards.
Asia Pacific Healthcare Contract Sales Organizations Market Trends
The healthcare contract sales organizations industry in the Asia Pacific is the fastest-growing segment with a significant CAGR over the forecast period. The region is constituted of a substantial number of pharmaceutical and biopharmaceutical companies actively investing in innovative therapeutics, driving higher demand for contract sales services. In addition, the relatively lower cost of delivering these services compared to other developed regions is expected to stimulate contract sales activities further and strengthen the segment’s market growth.
The healthcare contract sales organizations industry in Japan accounted for a considerable share in the Asia Pacific in 2024. The market is boosted by an increasingly outsourced sales and marketing approach to navigate complex regulatory frameworks and demands from an aging population. Some of the other drivers include rising R&D investment in innovative therapeutics, government support for healthcare modernization, and a growing emphasis on personalized medicine. CSOs are enhancing digital engagement, multichannel sales, and specialized training to meet the needs of their clients.
The India healthcare contract sales organizations industry is projected to register the fastest CAGR during the forecast period, as pharmaceutical and biotech companies increasingly outsource sales and marketing to optimize costs and reach. The market is advancing due to the growing domestic pharma sector, rising demand for specialty medicines, and an expanding hospital network. Competitive advantages hinge on cost efficiency, regulatory compliance, and expertise in managing complex sales processes, positioning India as a key hub for outsourced healthcare sales services.
The China healthcare contract sales organizations industry is expected to register substantial growth during the forecast period, driven by regulatory reforms that accelerate the approval and launch of innovative drugs. Multinational and local pharmaceutical companies, for instance, in October 2025, Gilead plans to expand partnerships with China-based contract sales organizations to enhance drug access and channel coverage, while actively collaborating with local innovators such as CytoSwant and Pregene Biopharma. These regional partnerships accelerate market reach and support the growth of innovative therapies in China.
Latin America Healthcare Contract Sales Organizations Market Trends
The healthcare contract research organizations industry in Latin America is projected to register a significant CAGR during the forecast period, as pharmaceutical companies increasingly outsource sales and marketing functions to navigate complex, fragmented healthcare systems. Drivers include rising demand for specialty and innovative drugs, cost pressures on local healthcare providers, and the need for localized expertise in regulatory compliance and market access.
The Brazil healthcare contract sales organizations industry is experiencing robust growth due to rising demand for innovative therapies, cost pressures, and a growing middle-class population with increased access to healthcare. Advancements in artificial intelligence and digital sales strategies are transforming CSO operations, enhancing customer engagement and data-driven decision-making.
Middle East & Africa Healthcare Contract Sales Organizations Market Trends
The healthcare contract sales organizations industry in the Middle East is growing steadily due to rising demand for specialty and generic medicines, growing private healthcare investment, and efforts to improve drug accessibility across the region. For instance, in January 2025, Irish MedTech companies announced regional expansions, high-value contracts, and strategic partnerships, highlighting innovative medical and digital healthcare solutions across the Middle East.
The South Africa healthcare contract sales organizations industry is expected to witness a notable CAGR during the forecast period, driven by increasing outsource of sales and marketing functions to navigate the country’s complex healthcare landscape. Drivers include rising demand for innovative therapies, cost pressures on public and private healthcare providers, and the need for specialized sales expertise. Strategic partnerships with local distributors and hospitals enhance market access and competitive positioning in this emerging African market.
The healthcare contract sales organizations industry in the UAE is increasingly competitive as major players expand regionally and globally. For instance, in October 2025, PureHealth’s acquisition of a 60% stake in Greece’s Hellenic Healthcare Group highlights strategic growth through international partnerships, enhancing service coverage and expertise. Drivers include rising demand for advanced healthcare services, government support for healthcare innovation, and the need for specialized sales and marketing capabilities.
Key Healthcare Contract Sales Organizations Company Insights
Key players in the industry include IQVIA, Syneos Health, and CMIC Holdings, among others. These companies dominate through extensive global networks, advanced technology integration, and specialized sales expertise, collectively capturing the majority of market share and driving growth across the pharmaceutical and biopharmaceutical sectors. For instance, in April 2024, IQVIA partnered with Salesforce to develop Life Sciences Cloud, a next-generation customer engagement platform designed to enhance advanced Contract Sales Organization (CSO) services and optimize pharmaceutical commercialization.
Key Healthcare Contract Sales Organizations Companies:
The following are the leading companies in the healthcare contract sales organizations market. These companies collectively hold the largest market share and dictate industry trends.
- CMIC HOLDINGS Co., LTD.
- Axxelus
- EPS Corporation.
- IQVIA, Inc.
- Publicis Group
- MaBico
- Syneos Health
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (IQVIA, Inc.; Syneos Health; Publicis Group; E)
- Established players focus on integrated commercial outsourcing models, combining field sales teams, key account management, medical affairs support, remote engagement, and analytics-led deployment. They expand through long-term pharma partnerships, therapeutic specialization, regional delivery networks, digital engagement platforms, and flexible staffing models to support product launches, mature brands, and vacancy coverage.
- Established players benefit from strong global presence, diversified healthcare client bases, large representative networks, deep therapeutic expertise, and established compliance frameworks. Their ability to deliver end-to-end CSO services, integrate digital and field engagement, manage complex launches, and provide scalable commercial infrastructure gives them a strong advantage over smaller or regional providers.
- Established players may face challenges from high operating costs, complex organizational structures, slower customization, and dependence on large pharmaceutical contracts. Their standardized service models can limit flexibility for niche clients, while pricing pressure, evolving digital engagement preferences, and competition from agile regional CSO providers may affect margins and client retention.
Emerging Players (Axxelus; MaBico)
- Emerging players focus on niche therapeutic coverage, flexible sales force deployment, cost-efficient staffing, and localized client support. They often target small and mid-sized pharmaceutical, biopharmaceutical, and medical device companies by offering customized promotional teams, vacancy support, remote engagement, and faster execution for market entry, product launches, and regional expansion.
- Emerging players offer greater flexibility, faster decision-making, competitive pricing, and tailored service delivery compared to large CSO providers. Their ability to serve niche markets, support regional commercialization, customize sales teams, and adapt quickly to client-specific needs makes them attractive for smaller healthcare companies seeking focused and scalable commercial support.
- Emerging players may have limited geographic reach, smaller sales force capacity, narrower therapeutic expertise, and lower brand recognition. They can face challenges in winning large multinational contracts, investing in advanced digital platforms, meeting complex compliance requirements, and scaling operations across multiple regions while maintaining consistent service quality and delivery standards.
Recent Developments
-
In October 2025, Grupo Elfa and NUPCO signed a two-year strategic MoU to enhance Saudi Arabia’s healthcare ecosystem. The collaboration focuses on AI integration, innovative supply-chain models, and technology-driven solutions to improve product availability and efficiency. This partnership supports Vision 2030 goals, optimizing procurement, logistics, and healthcare infrastructure in the Kingdom.
-
In March 2025, Scienture Holdings signed a Master Commercial Services Agreement with Syneos Health, utilizing their CSO expertise to enhance market reach, sales strategy, and customer engagement. This partnership strengthens Scienture’s commercialization capabilities and growth potential.
-
In September 2025, StarTrials announced expansion into key Asian markets, establishing offices and local partnerships to enhance clinical trial operations, patient recruitment, and data quality, accelerating drug development timelines and regional CRO capabilities.
Healthcare Contract Sales Organizations Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 11.9 billion
Market size value in 2026
USD 12.9 billion
Revenue forecast in 2033
USD 21.8 billion
Growth rate
CAGR of 7.8% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Service, therapeutic area, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S., Canada, Mexico, UK, Germany, France, Italy, Spain, Denmark, Sweden, Norway, Japan, China, India, Thailand, South Korea, Australia, Brazil, Argentina, South Africa, Saudi Arabia, UAE, Kuwait, Oman, Qatar
Key companies profiled
CMIC HOLDINGS Co., LTD., Axxelus, EPS Corporation, IQVIA, Inc., Publicis Group, MaBico, Syneos Health
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Healthcare Contract Sales Organizations Market Report Segmentation
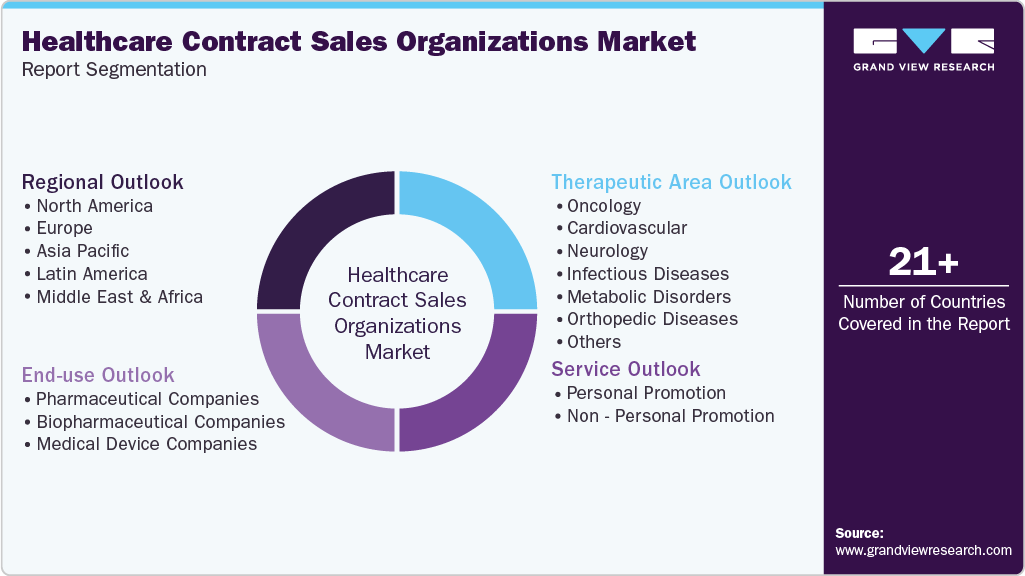
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global healthcare contract sales organizations market report based on service, therapeutic area, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Service Outlook (Revenue, USD Million, 2021 - 2033)
-
Personal Promotion
-
Promotional sales team
-
Key account management
-
Vacancy Management
-
-
Non - Personal Promotion
-
Medical Affairs Solutions
-
Remote Medical Science Liaisons
-
Nurse (Clinical) Educators
-
Others
-
-
-
Therapeutic Area Outlook (Revenue, USD Million, 2021 - 2033)
-
Oncology
-
Cardiovascular
-
Neurology
-
Infectious Diseases
-
Metabolic Disorders
-
Orthopedic Diseases
-
Others
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Pharmaceutical companies
-
Biopharmaceutical companies
-
Medical device companies
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
UAE
-
Saudi Arabia
-
Kuwait
-
Qatar
-
Oman
-
-
Research Methodology
The healthcare contract sales organizations market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each healthcare contract sales organizations segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Service
Definition
Personal Promotion
The segment captures revenue generated by providing Contract Sales Organizations services for personal promotion to end users. The segment includes field-based promotional sales teams, physician detailing, product promotion support, territory coverage, sales force deployment, key account engagement, vacancy management, and other in-person commercial engagement services.
Promotional Sales Team
The segment captures revenue generated by providing Contract Sales Organizations services for promotional sales teams to end users. The segment includes dedicated or syndicated sales representatives, field force deployment, physician office visits, product detailing, territory management, sales activity reporting, and execution of brand-specific promotional campaigns.
Key Account Management
The segment captures revenue generated by providing Contract Sales Organizations services for key account management to end users. The segment includes engagement with hospitals, health systems, group practices, payers, pharmacy networks, and strategic healthcare accounts to support product access, relationship management, account planning, and commercial growth.
Vacancy Management
The segment captures revenue generated by providing Contract Sales Organizations services for vacancy management to end users. The segment includes temporary sales representative coverage, interim territory management, backfilling vacant sales roles, maintaining physician engagement continuity, and supporting uninterrupted promotional activity during client workforce gaps.
Non - Personal Promotion
The segment captures revenue generated by providing Contract Sales Organizations services for non-personal promotion to end users. The segment includes medical affairs support, remote medical science liaison services, nurse or clinical educator programs, virtual engagement, digital education, omnichannel communication support, and other non-field-based promotional and educational services.
Medical Affairs Solutions
The segment captures revenue generated by providing Contract Sales Organizations services for medical affairs solutions to end users. The segment includes scientific communication support, medical information services, healthcare professional education, advisory board coordination, medical content dissemination, evidence communication, and support for compliant medical engagement activities.
Remote Medical Science Liaisons
The segment captures revenue generated by providing Contract Sales Organizations services for remote medical science liaisons to end users. The segment includes virtual scientific exchange, remote key opinion leader engagement, medical inquiry response, disease-state education, clinical data communication, and support for medical affairs outreach through digital channels.
Nurse (Clinical) Educators
The segment captures revenue generated by providing Contract Sales Organizations services for nurse or clinical educators to end users. The segment includes patient and provider education, therapy administration training, adherence support, disease awareness education, product-use guidance, clinical workflow support, and education programs delivered by qualified nursing or clinical professionals.
Others
The segment captures revenue generated by providing Contract Sales Organizations services for other non-personal promotion activities to end users. The segment includes tele-detailing, digital promotional campaigns, webinar support, call center-based education, virtual product information delivery, patient support communication, and other remote or technology-enabled engagement services.
Segment - Therapeutic Area
Revenue capture definition
Oncology
The segment captures revenue generated by providing Contract Sales Organizations services for oncology therapeutic areas to end users. The segment includes sales force deployment, key account engagement, medical education support, field promotion, remote engagement, and commercial support for cancer therapies, supportive oncology products, hematology-oncology treatments, and related diagnostic or treatment solutions.
Cardiovascular
The segment captures revenue generated by providing Contract Sales Organizations services for cardiovascular therapeutic areas to end users. The segment includes promotional sales teams, key account management, physician engagement, medical affairs support, and remote education for therapies addressing hypertension, heart failure, coronary artery disease, arrhythmia, thrombosis, dyslipidemia, and related cardiovascular conditions.
Neurology
The segment captures revenue generated by providing Contract Sales Organizations services for neurology therapeutic areas to end users. The segment includes commercial promotion, specialist engagement, clinical education, remote medical science liaison support, and sales force solutions for therapies targeting epilepsy, multiple sclerosis, migraine, Parkinson’s disease, Alzheimer’s disease, neuropathic pain, and other neurological disorders.
Infectious Diseases
The segment captures revenue generated by providing Contract Sales Organizations services for infectious disease therapeutic areas to end users. The segment includes sales and medical engagement support for antibiotics, antivirals, antifungals, vaccines, hospital anti-infectives, diagnostic-linked therapies, disease awareness programs, and provider education across community, hospital, and specialty care settings.
Metabolic Disorders
The segment captures revenue generated by providing Contract Sales Organizations services for metabolic disorder therapeutic areas to end users. The segment includes promotional sales support, clinical education, key account engagement, and remote outreach for diabetes, obesity, dyslipidemia, endocrine disorders, metabolic syndrome, and related chronic disease therapies requiring long-term physician and patient engagement.
Orthopedic Diseases
The segment captures revenue generated by providing Contract Sales Organizations services for orthopedic disease therapeutic areas to end users. The segment includes commercial and educational support for therapies, biologics, pain management products, musculoskeletal disorder treatments, osteoporosis solutions, joint health products, and post-surgical or rehabilitation-related orthopedic care offerings.
Others
The segment captures revenue generated by providing Contract Sales Organizations services for other therapeutic areas to end users. The segment includes sales, key account, medical affairs, nurse educator, and remote engagement services across dermatology, respiratory, gastroenterology, ophthalmology, rare diseases, women’s health, immunology, urology, and other specialty or primary care therapeutic categories.
Segment - End Use
Revenue capture definition
Pharmaceutical Companies
The segment captures revenue generated by providing Healthcare Contract Sales Organizations services to pharmaceutical companies. The segment includes outsourced sales force deployment, promotional detailing, vacancy management, key account management, medical affairs support, nurse educator programs, remote engagement, and commercial support for branded drugs, generics, specialty medicines, and mature product portfolios.
Biopharmaceutical Companies
The segment captures revenue generated by providing Healthcare Contract Sales Organizations services to biopharmaceutical companies. The segment includes field sales teams, specialist engagement, medical science liaison support, clinical education, launch support, key opinion leader engagement, and remote promotional services for biologics, biosimilars, cell and gene therapies, vaccines, and advanced therapeutic products.
Medical Device Companies
The segment captures revenue generated by providing Healthcare Contract Sales Organizations services to medical device companies. The segment includes outsourced sales representatives, hospital account management, product demonstration support, clinical educator services, surgeon and physician engagement, remote training, and commercial support for diagnostic devices, surgical instruments, implants, monitoring systems, and other healthcare technologies.
Estimation Model
Top-Down Approach
Bottom-Up Approach
Service-Based Revenue Mapping
Data Triangulation Approach
The overall healthcare commercial outsourcing market is assessed first, followed by allocation to the Healthcare Contract Sales Organizations market based on outsourcing penetration, pharmaceutical promotional spending, commercial team requirements, product launch activity, and regional adoption of outsourced sales models. This approach helps estimate market size by narrowing broader healthcare outsourcing revenues into CSO-specific services such as sales force deployment, key account management, vacancy coverage, medical affairs support, and remote engagement.
Revenues of key Healthcare Contract Sales Organization providers are analyzed and aggregated across service type, therapeutic area, end user, and geography. Company disclosures, service portfolios, contract structures, client base, field force strength, and regional presence are reviewed to estimate segment-level revenue contribution. This approach supports granular market sizing by building estimates from provider-level revenues and validating demand across pharmaceutical, biopharmaceutical, and medical device companies.
Market revenue is distributed across personal promotion and non-personal promotion services based on adoption, pricing, contract duration, and client spending patterns. Personal promotion includes promotional sales teams, key account management, and vacancy management, while non-personal promotion includes medical affairs solutions, remote MSLs, nurse educators, and digital engagement services. This model helps determine which service categories contribute most significantly to overall market revenue.
The market estimates are validated by comparing outputs from top-down, bottom-up, and service-based models. Key validation parameters include provider revenues, representative deployment cost, contract length, client spending, therapeutic area demand, product launch volumes, and outsourcing penetration. Primary inputs from industry participants and secondary indicators such as annual reports, company portfolios, promotional budgets, and commercial outsourcing trends are used to ensure consistency, reliability, and market-level accuracy.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Cross-Segmentation Opportunity Assessment
Conducted detailed cross-segmentation across CSO services, including personal promotion, promotional sales teams, key account management, vacancy management, non-personal promotion, medical affairs solutions, remote MSLs, nurse educators, and other engagement models across therapeutic areas and end users.
Enabled identification of high-growth CSO service models, therapy-specific outsourcing opportunities, end-user demand pockets, and priority segments across pharmaceutical, biopharmaceutical, and medical device commercialization needs.
Regional Expansion & Country-Level Market Assessment
Evaluated country-level opportunities across North America, Europe, Asia Pacific, Latin America, and MEA, including the U.S., Canada, Mexico, UK, Germany, France, Italy, Spain, Japan, China, India, Brazil, UAE, Saudi Arabia, and other markets.
Supported regional prioritization, market entry planning, sales force deployment strategy, outsourcing maturity assessment, and identification of countries with strong demand for flexible commercial and medical engagement support.
Market Entry & Commercial Operating Model Review
Assessed market entry strategies for CSO providers and healthcare companies based on go-to-market models, service mix, therapeutic area focus, client targeting, pricing structure, sales force outsourcing intensity, and hybrid field-remote engagement models.
Delivered strategic clarity on optimal entry routes, partner selection, commercialization approach, service portfolio positioning, launch readiness, and scalable operating models for healthcare commercial outsourcing expansion.
Competitive Dynamics, & Productivity Benchmarking
Benchmarked CSO providers based on service capabilities, regional presence, therapeutic specialization, client mix, digital engagement strength, sales force scale, remote MSL coverage, nurse educator networks, and deployed representative volume.
Enabled competitive positioning, volume forecasting, representative productivity assessment, account coverage analysis, and identification of emerging trends such as hybrid detailing, remote engagement, omnichannel promotion, and medical affairs outsourcing.
Frequently Asked Questions About This Report
Based on service, the non-personal promotion segment led the market with the largest revenue share of 53.4% in 2025 and is expected to grow at the fastest CAGR over the forecast period.
Based on therapeutic area, the oncology segment led the market with the largest revenue share of 31.1% in 2025 and is expected to grow at the fastest CAGR over the forecast period.
Based on end use, the pharmaceutical companies segment led the market with the largest revenue share of 37.6% in 2025.
Key players operating inthis market include - CMIC HOLDINGS Co., LTD., Axxelus, EPS Corporation, IQVIA, Inc., Publicis Group, MaBico, Syneos Health.
The healthcare contract sales organizations market is witnessing growth as pharmaceutical, biopharmaceutical, and medical device companies increasingly opt for outsourced commercial models to enhance flexibility, speed, and market reach.
The global healthcare contract sales organizations market size was estimated at USD 11.9 billion in 2025 and is projected to reach USD 12.9 billion in 2026.
The global healthcare contract sales organizations market is expected to grow at a CAGR of 7.8% from 2026 to 2033 to reach USD 21.8 billion by 2033.
North America dominated the healthcare contract sales organizations market with the largest revenue share of 48.2% in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


