
- Home
- »
- Medical Devices
- »
-
Healthcare Mobile Robots Market Size Report, 2026-2033GVR Report cover

Healthcare Mobile Robots Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Hospital Service & Logistics, Disinfection & Sanitation), By Application, By End Use, By Control Technology, By Region, And Segment Forecasts
Market Size, 2025
$1.0BMarket Estimate, 2026
$1.2BMarket Forecast, 2033
$4.0BCAGR, 2026–2033
18.2%Healthcare Mobile Robots Market Summary
The global healthcare mobile robots market size was valued at USD 1.0 billion in 2025 and is projected to grow from USD 1.2 billion in 2026 to USD 4.0 billion by 2033, at a CAGR of 18.2% from 2026 to 2033. North America dominated the market, accounting for the largest revenue share of 42.8% in 2025. The industry is driven by the increasing adoption of automation to address healthcare workforce shortages, enhance operational efficiency, and improve patient safety.
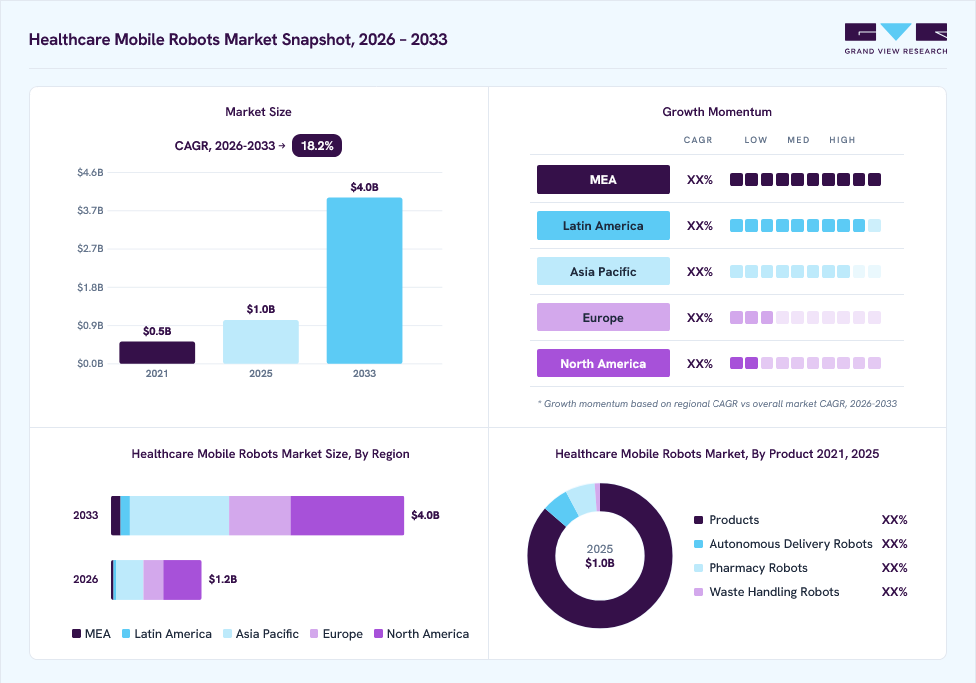 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Hospital service & logistics segment dominated the market in 2025, accounting for the largest revenue share of 36.4%.
- By application: Material transport & logistics segment held the largest revenue share of 35.7% in 2025.
- By end use: Hospitals segment held the largest revenue share of 71.7% in 2025.
- By control technology: Autonomous navigation segment accounted for the largest revenue share of 64.3% in 2025.
Regional Highlights
- Largest regional market: North America (42.8% revenue share, 2025)
- Fastest-growing regional market: Latin America (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 1.0 Billion
- Estimated market size in 2025: USD 1.2 Billion
- Projected market size by 2033: USD 4.0 billion
- CAGR (2026-2033): 18.2%
GVR research-powered AIAsk Prism AI about the healthcare mobile robots marketGet cited answers from GVR research on market growth, segments, regulations and forecasts.Start with✓ Source-linked answers ✓ Market-specific context ✓ Traceable figuresExplore Prism AI ↗
Growing investments in smart hospitals, attached with advancements in artificial intelligence (AI), autonomous navigation, and connected healthcare infrastructure, are accelerating the deployment of mobile robots for logistics, disinfection, telepresence, and patient assistance across hospitals and other healthcare settings.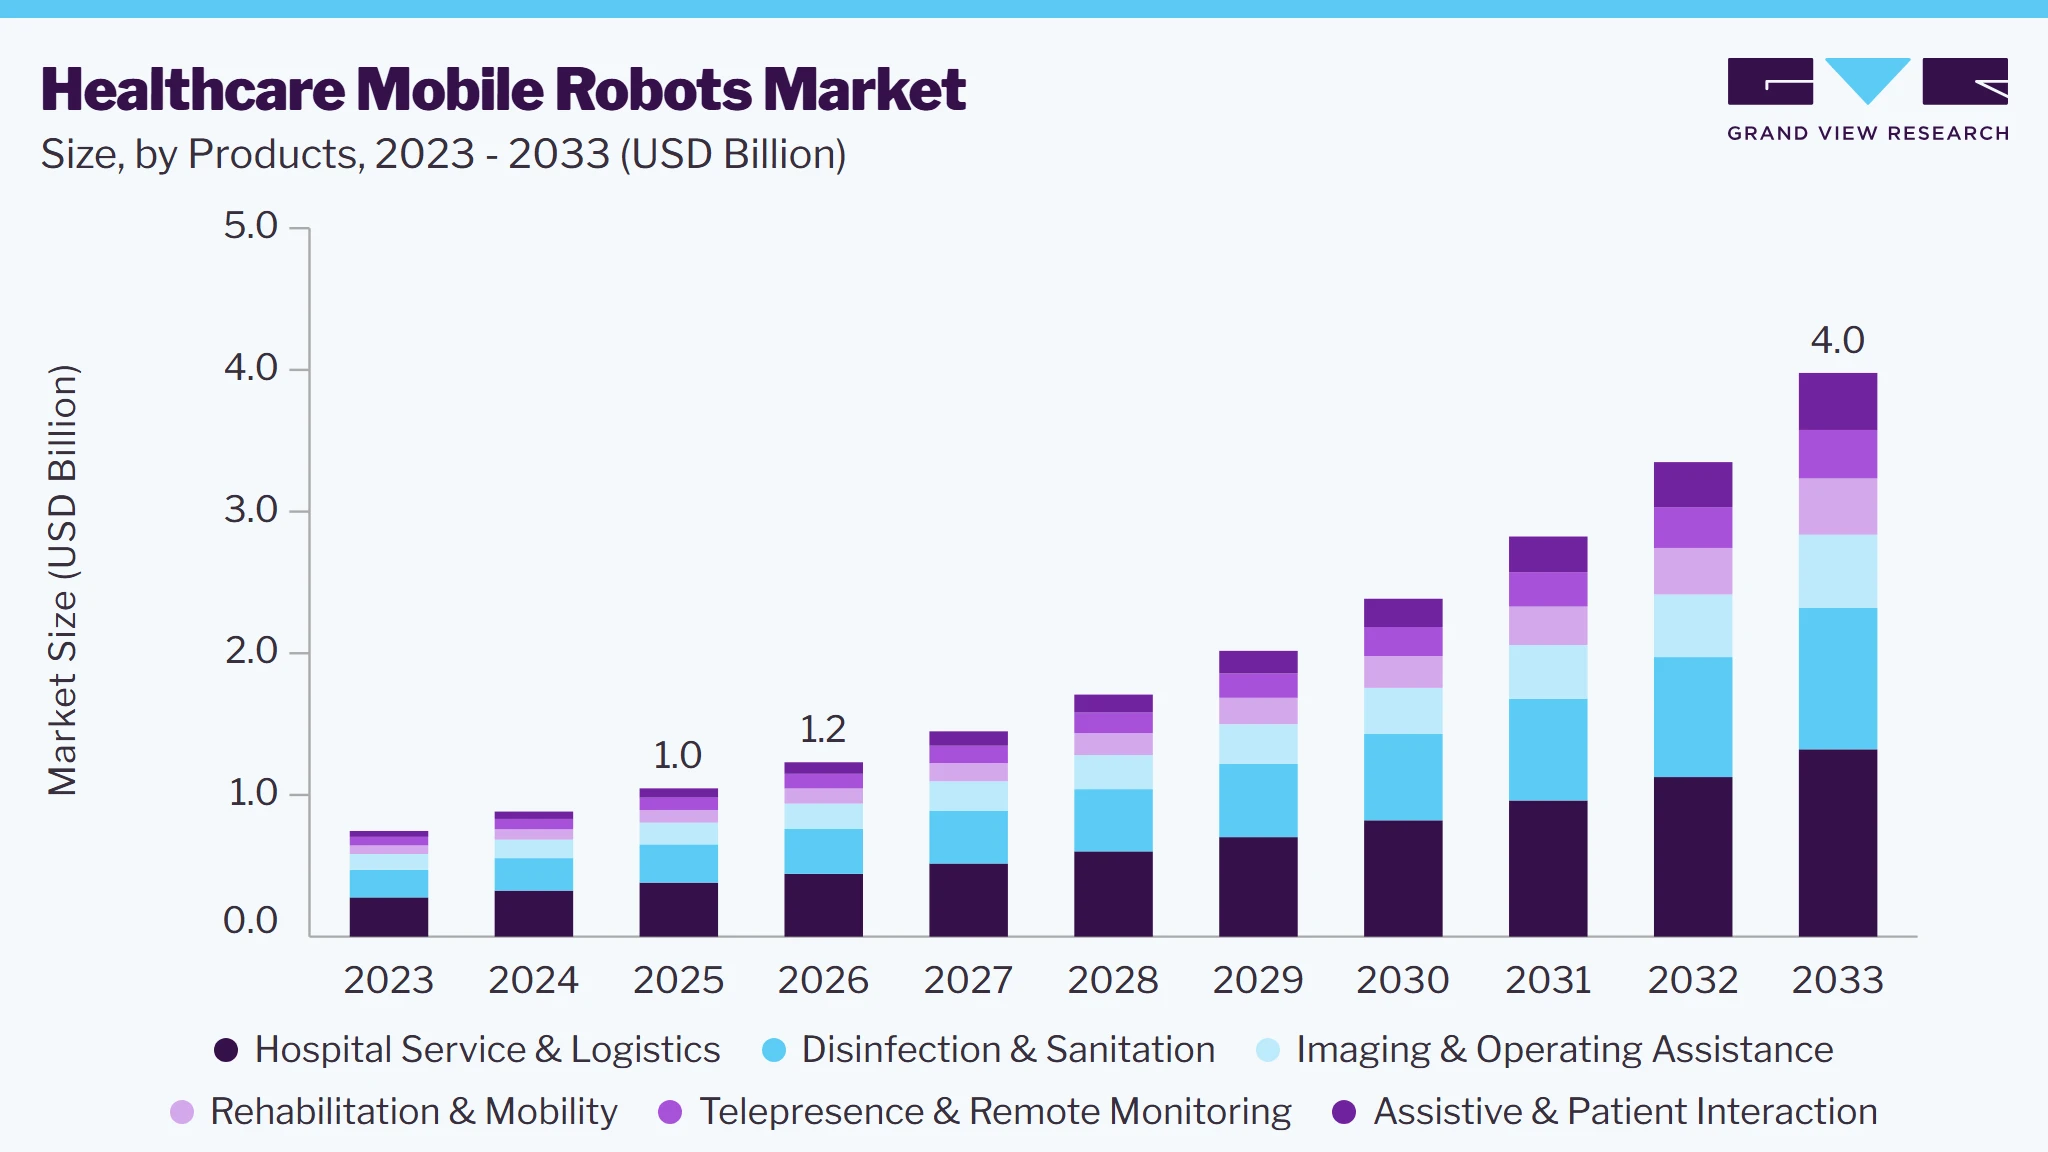 To learn more about this report, Download Free Sample Report
Market Dynamics
Healthcare mobile robot adoption is moving from isolated pilots toward workflow-based deployments. Hospitals are connecting autonomous mobile robots with pharmacy, inventory, and fleet-management systems, while surgical and rehabilitation platforms are adding planning software, imaging, and remote support functions.
Healthcare providers are increasingly using mobile robots to reduce the time spent on repetitive, non-clinical tasks. These robots are commonly used to transport medications, laboratory specimens, linen, meals, waste, and medical equipment, while also supporting rehabilitation and remote clinical consultations. According to the WHO (May 2025), the global nursing workforce reached 29.8 million in 2023; however, a shortage of 5.8 million nurses still remained. This workforce gap is increasing the demand for mobile robots that automate routine transport and administrative tasks, allowing healthcare professionals to spend more time on patient care.
In addition, the growing adoption of smart hospitals is supporting market growth by integrating mobile robots with pharmacy, inventory management, building management, and electronic workflow systems. For instance, in September 2025, Swisslog Healthcare and Diligent Robotics announced a U.S. alliance to connect Moxi mobile robots with hospital transport and pharmacy automation. The companies reported that Moxi had completed more than 1 million deliveries across over 25 U.S. hospitals, including more than 300,000 pharmacy deliveries.
Similarly, in September 2025, ST Engineering Aethon and Oracle also announced an integration between Aethon's autonomous mobile robots and Oracle Fusion Cloud Inventory Management. The solution was designed to provide real-time inventory visibility and automatically trigger delivery and pickup tasks. These developments show that demand is increasingly tied to complete hospital workflows rather than stand-alone robots.
The high cost of healthcare mobile robots is expected to limit adoption, particularly among small hospitals and healthcare facilities in developing countries. For instance, in November 2025, OhmniLabs, the manufacturer of the OhmniClean autonomous mobile UV-C disinfection robot used in hospitals and healthcare facilities, stated that robotic disinfection solutions typically cost between USD 60,000 and USD 150,000, depending on the model, vendor, and included features. The manufacturer also stated that facilities must account for additional expenditure on system installation, employee training, maintenance, and consumables such as UV-C bulbs. These costs increase the total cost of ownership beyond the initial robot purchase. Adoption is also constrained in developing countries where healthcare facilities can lack reliable wireless connectivity, compatible elevators and doors, trained technicians, spare parts, and local manufacturer service networks.
The increasing investment in automated pharmacy infrastructure is expected to drive significant growth in the industry. Hospitals and health systems are adopting robotic pharmacy solutions to improve medication-dispensing accuracy, streamline inventory management, and reduce pharmacy staff workload. This trend is driving the integration of autonomous mobile robots with pharmacy automation systems to enable efficient medication transportation and internal hospital logistics. For instance, in September 2025, BD (Becton, Dickinson and Company) partnered with Henry Ford Health to deploy the BD Rowa Vmax robotic pharmacy system across community pharmacies in Michigan, supporting automated medication storage, prescription dispensing, and 24/7 patient pickup services. Such investments in smart pharmacy infrastructure are expected to accelerate the adoption of healthcare mobile robots and create new growth opportunities for market participants over the forecast period.
Market Concentration & Characteristics
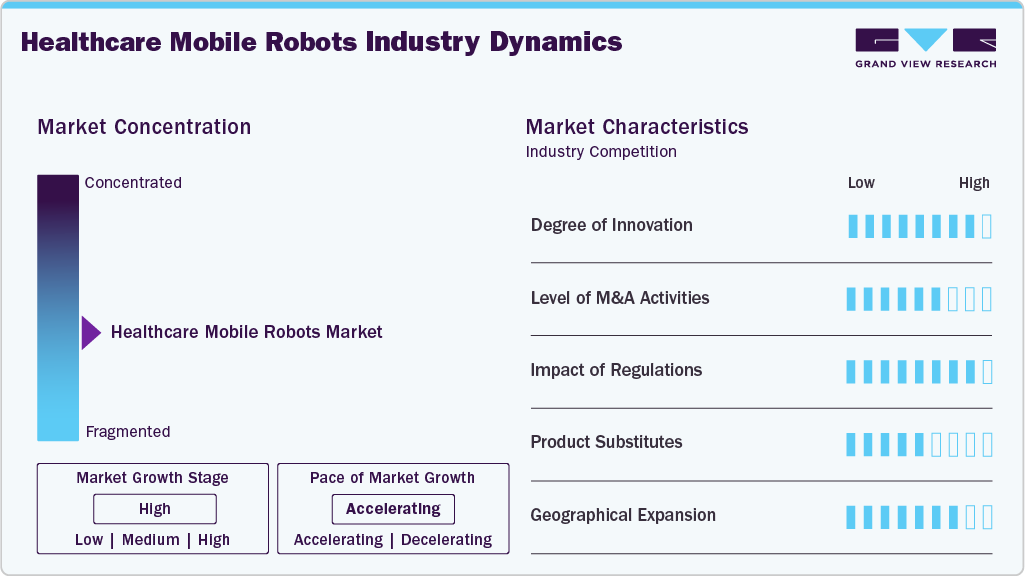
The industry has a high degree of innovation, with product development focused on safer navigation, mobile manipulation, workflow integration, and task-specific software. For instance, in October 2025, Diligent Robotics unveiled Moxi 2.0 with higher computing capacity, redesigned hardware, and an AI model informed by more than 1.25 million hospital deliveries. The company reported that Moxi operated in over 25 U.S. hospitals and that the new platform was designed to navigate dense areas around beds and wheelchairs. In October 2025, Johnson & Johnson MedTech also announced work with NVIDIA to use simulation and digital twins in the development of its MONARCH robotic platform. These examples show that innovation is moving toward systems trained and tested against real clinical workflows.
The industry is witnessing medium-to-high M&A activity, as companies acquire healthcare robotics firms to expand autonomous hospital automation capabilities and strengthen their AI-powered robotics portfolios. For instance, in January 2026, Serve Robotics announced the acquisition of Diligent Robotics, the developer of the Moxi autonomous hospital robot. The acquisition expands Serve Robotics' platform into healthcare, strengthening its presence in hospital logistics and AI-powered mobile robotics while accelerating growth in indoor healthcare automation.
 To learn more about this report, Download Free Sample Report
The industry is highly regulated, as manufacturers must comply with stringent safety, risk management, and hospital operational standards before deployment. Regulatory compliance increases development time while ensuring the safe operation of autonomous robots in healthcare facilities. For instance, in 2024, ISO approved the development of ISO 25268, the world's first international standard specifically for autonomous mobile robots (AMRs) used for pharmaceutical delivery inside hospitals. The standard provides guidelines for safe medication transport, elevator integration, emergency stop functions, and hospital logistics, highlighting the growing regulatory oversight of healthcare mobile robots.
The industry is experiencing moderate product expansion, with manufacturers enhancing their portfolios by introducing robots for specific hospital workflows, including medication delivery, pharmacy automation, and internal logistics. For instance, in May 2024, Richtech Robotics launched Medbot, an elevator-enabled autonomous mobile robot designed for hospitals. The robot automates secure medication delivery, integrates with elevators and IoT-enabled hospital infrastructure, and supports 24/7 pharmacy logistics, expanding the company's healthcare robotics portfolio.
The industry is experiencing moderate-to-high geographic expansion, as companies establish regional headquarters and service networks to support the growing adoption of hospital automation. For instance, in March 2025, Pudu Robotics expanded its operations in North America by opening a new U.S. headquarters in Santa Clara, California, and a new fulfillment center in New Jersey. The expansion strengthens local sales, deployment, and after-sales support for customers across healthcare, logistics, and other sectors.
Analyst Perspective
The industry is driven by the need to automate repetitive tasks, address healthcare workforce shortages, improve operational efficiency, and enhance patient support. Rehabilitation Therapy is expected to grow at the fastest pace as robotic systems gain adoption for gait training and mobility support. Hospitals remain the major end-use segment, although long-term care and elderly-care facilities present emerging growth opportunities. From a technology perspective, autonomous navigation leads adoption, while teleoperated and hybrid systems are gaining traction for applications requiring remote supervision. Overall, the market is moving toward AI-enabled, connected, and multifunctional mobile robots capable of supporting multiple healthcare workflows.
Product Insights
By product, the hospital service & logistics segment accounted for the largest revenue share of 36.4% in 2025. The segment is supported by increasing adoption of autonomous mobile robots for medication, laboratory samples, medical supplies, and equipment transportation within hospitals. For instance, in July 2025, Diligent Robotics reported that its Moxi robots had completed more than 300,000 pharmacy deliveries, while the fleet had surpassed 1.1 million total hospital deliveries. Moxi robots are deployed across more than 30 U.S. health systems, demonstrating the growing use of mobile robots for routine hospital logistics
The assistive & patient interaction segment is expected to register the fastest CAGR during the forecast period. Growth is attributed to the increasing adoption of socially assistive robots for patient communication, information delivery, companionship, and engagement. For instance, in January 2026, a study published in Frontiers in Digital Health evaluated a GPT-reinforced social robot for patient communication at Medisch Spectrum Twente Hospital in the Netherlands. The robot was designed to provide patients with evidence-based information and support interaction with healthcare professionals, demonstrating the potential of AI-enabled robots in patient-centered care
Application Insights
By application, the material transport & logistics segment accounted for the largest revenue share of 35.7% in 2025 and is expected to maintain its dominance over the forecast period. The segment is driven by the increasing adoption of mobile robots for transporting medicines, laboratory samples, medical supplies, meals, and other materials within healthcare facilities. For instance, in March 2026, Toyota Memorial Hospital in Japan deployed 24 Potaro autonomous transport robots, which performed an average of 170 transport trips per day within the hospital. The robots were integrated with elevators, automatic doors, and the hospital's internal infrastructure to transport medicines, specimens, and other materials, reducing the need for staff to perform repetitive transportation tasks.
The rehabilitation therapy segment is projected to register the fastest CAGR of 21.5% from 2026 to 2033. The growth is supported by increasing adoption of robotic systems for gait training, mobility assistance, and repetitive rehabilitation exercises. For instance, WakeMed Rehabilitation Hospital highlighted its use of the EksoNR robotic exoskeleton in its robotic walking program to support patients recovering from stroke, spinal cord injury, acquired brain injury, and multiple sclerosis. The system assists patients with repetitive walking movements during rehabilitation and enables therapists to adjust the level of robotic assistance according to patient needs.
Control Technology Insights
By control technology, the autonomous navigation segment accounted for the largest revenue share of 64.3% in 2025 and is expected to maintain its dominance during the forecast period. The segment is driven by the increasing use of autonomous mobile robots equipped with sensors, mapping technologies, and navigation systems to perform logistics, delivery, and cleaning tasks with limited human intervention. For instance, in May 2025, researchers published a study on a dynamic SLAM system for hospital logistics robots, integrating nonlinear optimal filtering, deep learning, and multimodal sensor data to improve positioning accuracy and navigation performance in complex hospital environments. The study demonstrated improved mapping and real-time positioning capabilities, supporting the development of more reliable autonomous navigation systems for healthcare mobile robots.
The Teleoperated / Remote-Driven segment is expected to register the fastest CAGR of 19.1% from 2026 to 2033. Growth is supported by the increasing use of remotely controlled robotic systems for telepresence, remote monitoring, and clinical procedures requiring specialist intervention from a distance. For instance, in February 2025, NTT, Hirosaki University Hospital, Medicaroid, and other partners demonstrated remote operation of the hinotori surgical robot between two hospitals in Japan. The demonstration connected Hirosaki University Hospital and Tsugaru General Hospital over approximately 30 km and achieved high-precision remote control with a one-way transmission delay of only 0.28 milliseconds. The demonstration highlights advances in remote robotic control and the potential to extend specialized medical expertise across geographically separated healthcare facilities.
End Use Insights
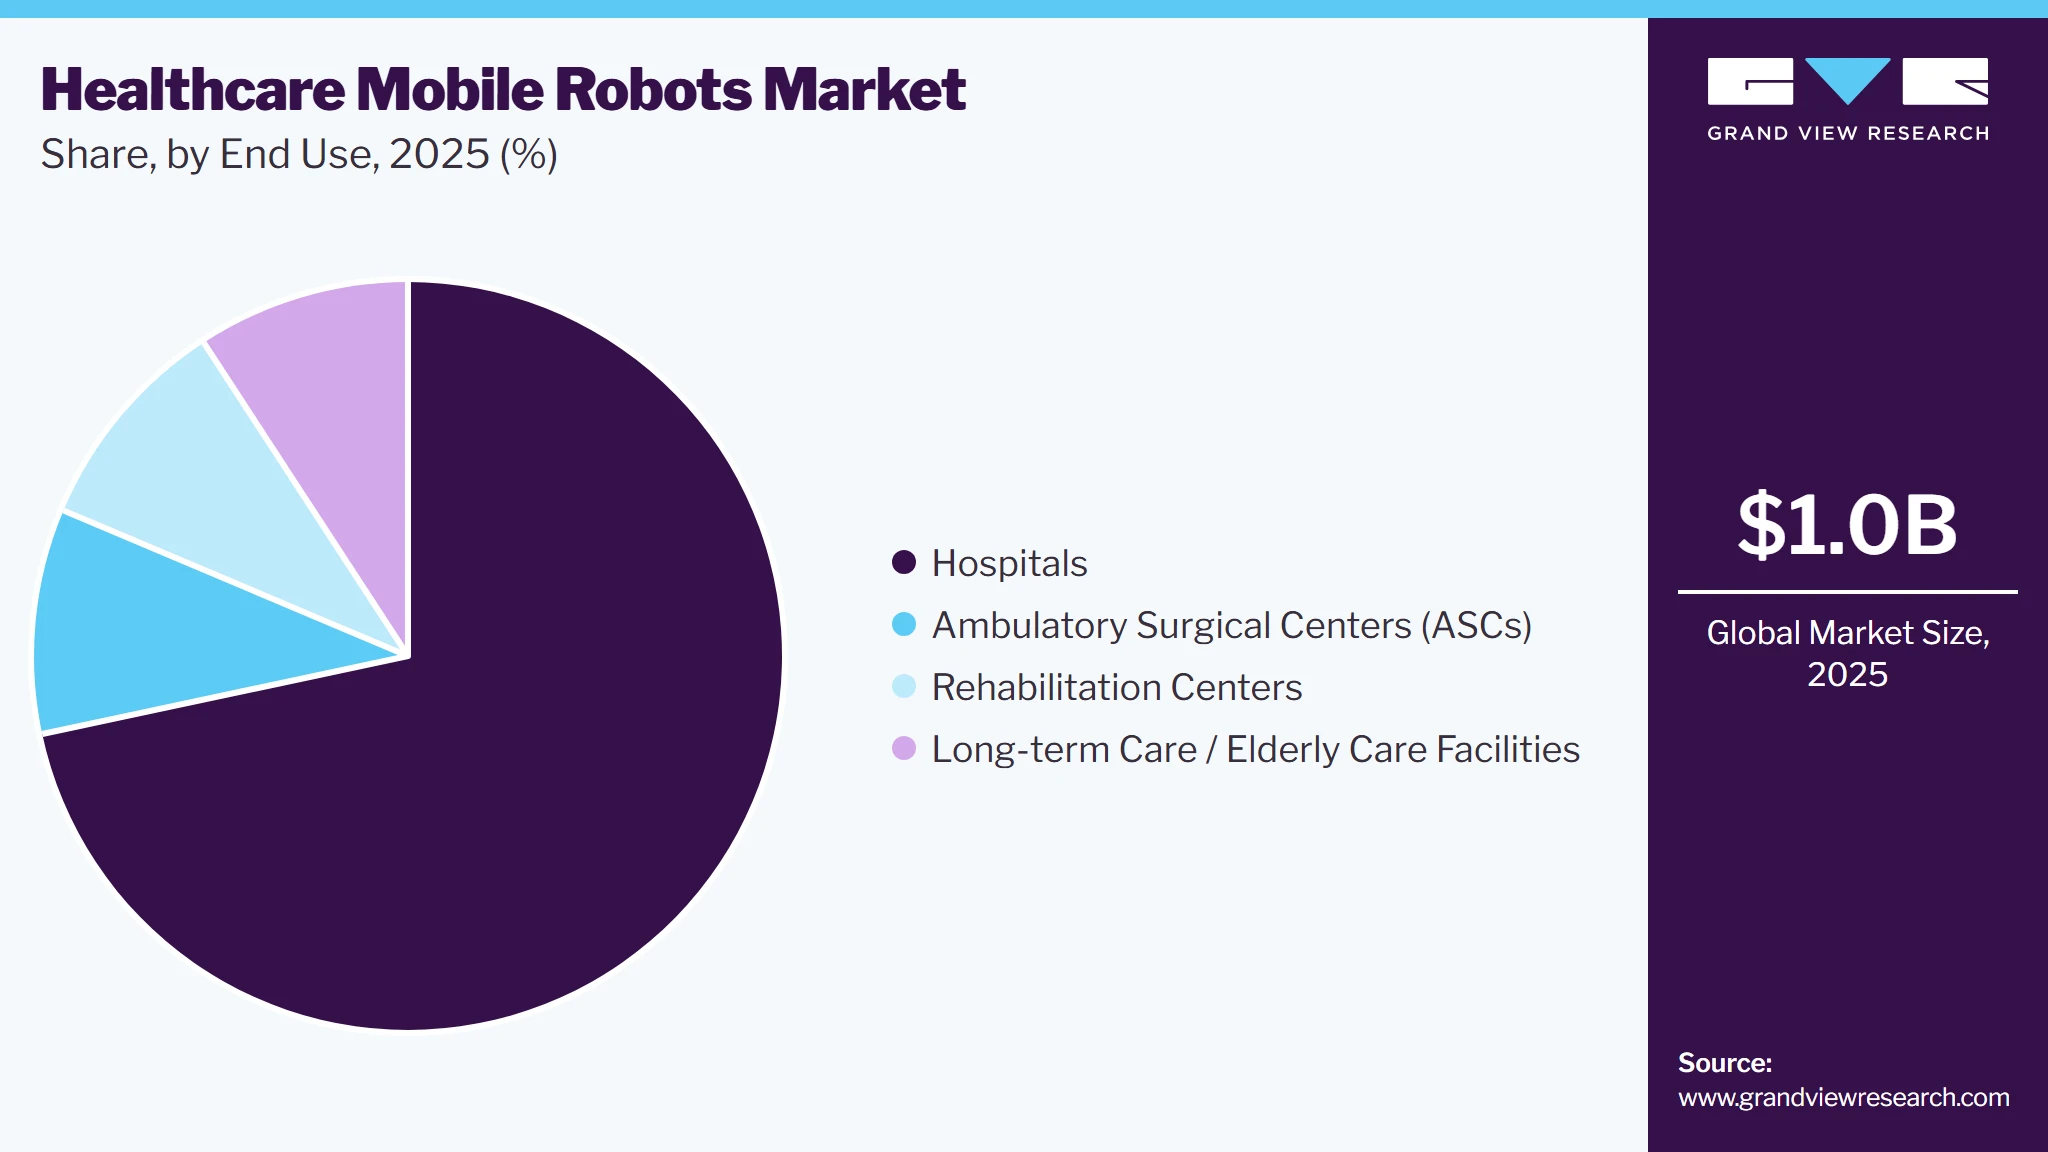
By end use, the hospitals segment accounted for the largest revenue share of 71.6% in 2025 and is expected to maintain its dominance over the forecast period. The strong adoption of mobile robots in hospitals is driven by their increasing use in material transportation, disinfection, patient monitoring, rehabilitation, and other routine healthcare activities. For instance, in May 2025, MacKay Memorial Hospital in Taiwan deployed three AI-powered robots for logistics, patient assistance, and environmental monitoring. One robot was designed to autonomously transport specimens and materials, while another supported patient registration, navigation, and companionship. The deployment demonstrates the expanding use of mobile robots across multiple hospital workflows to improve operational efficiency and support healthcare staff.
 To learn more about this report, Download Free Sample Report
The Long-term Care / Elderly Care Facilities segment is expected to register the fastest CAGR of 21.1% from 2026 to 2033. Growth is driven by increasing adoption of mobile and socially assistive robots for resident engagement, communication, companionship, and basic service support. For instance, in April 2025, Heriot-Watt University and North Star Housing Group deployed a Furhat humanoid robot named “Basil” at Aspen Gardens, an extra-care housing development in the U.K. The robot was designed to interact with residents and visitors through conversations and was also connected to a smart coffee machine to provide basic services. The deployment demonstrates the increasing use of socially assistive robotics in supported-living environments and highlights their potential to improve social connection and service delivery for older adults.
Regional Insights
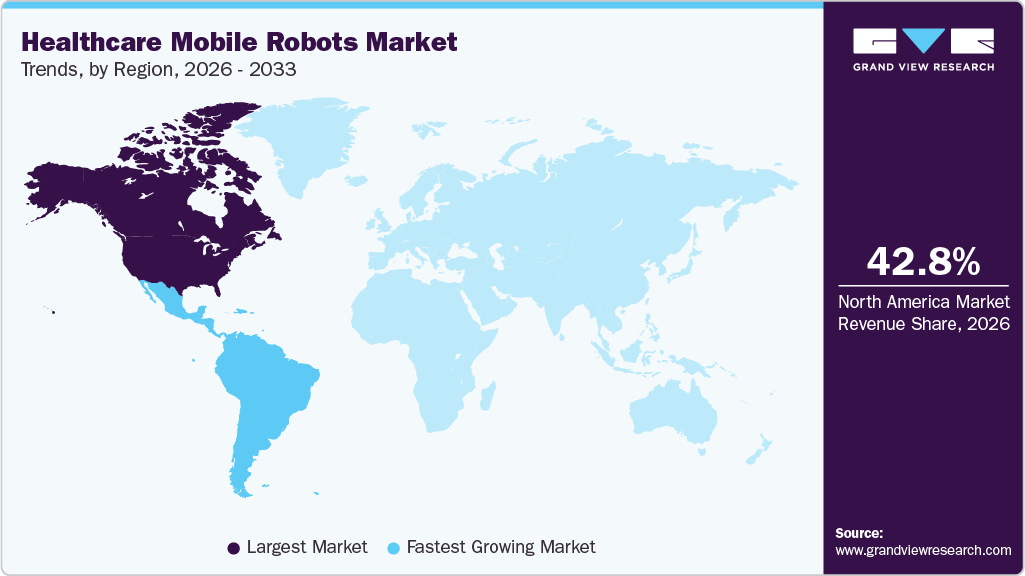
The North America healthcare mobile robots market accounted for the largest revenue share of 42.8% in 2025, driven by the increasing adoption of autonomous mobile robots (AMRs) to automate hospital logistics, address workforce shortages, and improve operational efficiency. The region also benefits from advanced healthcare infrastructure and rising investments in AI-enabled hospital automation. For instance, in June 2026, Relay Robotics expanded its partnership with BayCare Health System by deploying additional autonomous mobile robots at Winter Haven Hospital and Winter Haven Women's Hospital to automate the transport of medications and laboratory specimens
 To learn more about this report, Download Free Sample Report
U.S. Healthcare Mobile Robots Market Trends
The healthcare mobile robots market in the U.S. held the largest share in North America in 2025, driven by increasing investments in hospital automation, rising workforce shortages, and the growing adoption of AI-enabled autonomous mobile robots for logistics and material handling. The presence of leading robotics companies and continued investments in smart hospital infrastructure further support market growth. For instance, in September 2025, ST Engineering Aethon partnered with Oracle to integrate autonomous mobile robots with Oracle Fusion Cloud Inventory Management, enabling U.S. hospitals to automate inventory transport and improve supply chain visibility and operational efficiency.
Europe Healthcare Mobile Robots Market Trends
The healthcare mobile robots market in Europe is expected to witness significant growth over the forecast period due to increasing investments in hospital automation, supportive digital health initiatives, and rising adoption of autonomous mobile robots (AMRs) for hospital logistics and patient care. Growing demand for workflow optimization and healthcare workforce support is further accelerating market growth across the region.For instance, in April 2026, University Hospital Graz (Austria) deployed STILL's AXH iGo autonomous mobile robots to automate 24/7 transportation of medical supplies and materials through its hospital logistics network, improving operational efficiency at one of Europe's largest hospital campuses.
The UK healthcare mobile robots market is driven by increasing NHS investments in healthcare automation and smart hospital technologies. The adoption of robotics to improve logistics efficiency and reduce staff workload is supporting market growth. For instance, in July 2025, DHL Supply Chain announced a Euro 550 million (USD 739.74 million) investment to expand automation and robotics across its UK operations, including the development of a new DHL Health Logistics facility to support the country's growing life sciences and healthcare sector.
The healthcare mobile robots market in Germany is expected to grow substantially over the forecast period, driven by increasing investments in smart hospitals, hospital logistics automation, and AI-enabled robotic technologies. The country's strong medical technology ecosystem and focus on digital healthcare transformation are further supporting the adoption of autonomous mobile robots across healthcare facilities. For instance, in March 2025, Graz University Hospital introduced its first Autonomous Mobile Robot (AMR) in the hospital's logistics tunnel to automate the transport of medical supplies and materials, supporting more efficient hospital logistics and smart hospital operations.
Asia Pacific Healthcare Mobile Robots Market Trends
The healthcare mobile robots market in Asia Pacific is driven by expanding hospital infrastructure, a growing aging population, strong robotics manufacturing capabilities, and increasing government support for healthcare automation. For instance, in July 2025, Kawasaki Heavy Industries and Foxconn announced the joint development of Nurabot, an autonomous nursing-assistant robot, following a successful trial at Taichung Veterans General Hospital that began in April 2025.
The India healthcare mobile robots market is expected to grow rapidly due to increasing investments in healthcare automation, expanding hospital infrastructure, and rising adoption of AI-enabled robotic technologies. The growing demand to improve hospital efficiency and reduce workforce burden is encouraging healthcare providers to adopt robotic solutions. For instance, in December 2025, SS Innovations launched the SSi Mantra TeleSync Mobile Unit, a mobile robotic telesurgery platform designed to extend robotic surgical care to remote and underserved regions across India, supporting the country's digital healthcare transformation.
The healthcare mobile robots market in Japan is driven by its aging population, persistent healthcare workforce shortages, and strong expertise in robotics innovation. Hospitals are increasingly adopting autonomous mobile robots to automate logistics and improve operational efficiency. For instance, in June 2025, Kawasaki Heavy Industries and Keio University Hospital launched an automated in-hospital delivery service using the FORRO autonomous mobile robot to transport laboratory specimens, medications, and medical supplies, reducing the workload of healthcare professionals.
Latin America Healthcare Mobile Robots Market Trends
The healthcare mobile robots market in Latin America is anticipated to grow at the fastest CAGR over the forecast period, driven by increasing investments in healthcare modernization and hospital automation, as well as the adoption of AI-enabled robotic technologies. Rising demand to improve operational efficiency and expand access to advanced healthcare services is further supporting market growth across the region. For instance, in September 2025, Hospital Unimed São Domingos deployed an automated service robot developed by Robovisor to deliver diagnostic test results within the hospital, improving workflow efficiency and supporting digital transformation in healthcare operations.
Middle East and Africa Healthcare Mobile Robots Market Trends
The healthcare mobile robots market in the Middle East & Africa is expected to grow at a significant CAGR over the forecast period, driven by increasing investments in smart hospitals, AI-enabled healthcare technologies, and hospital automation across the UAE and Saudi Arabia. Government-led digital health initiatives and rising demand for operational efficiency are accelerating the adoption of robotic solutions in healthcare facilities. For instance, in April 2025, Burjeel Holdings partnered with Hippocratic AI to deploy multilingual AI healthcare agents across its hospitals in the UAE to support patient communication, clinical workflows, and operational efficiency. While this deployment focuses on AI agents rather than autonomous mobile robots, it reflects the region's broader investment in healthcare automation and intelligent hospital technologies.
Key Healthcare Mobile Robots Companies Insights
Companies in the healthcare mobile robots market are active across hospital service & logistics, disinfection & sanitation, assistive & patient interaction, telepresence & remote monitoring, rehabilitation & mobility, and imaging & operating assistance. Their product portfolios, installed bases, partnerships, regulatory progress, and healthcare-specific revenue exposure are considered when mapping the supply side of the market.
Key Healthcare Mobile Robots Companies
Some of the key players in the healthcare mobile robots market are:
-
ABB Ltd
-
Aethon
-
Omron Corporation
-
Teradyne
-
Ateago Technology
-
VGo Communications, Inc.
-
Awabot
-
Xenex Disinfection Services Inc.
-
Medtronic
-
ST Engineering Aethon
-
Diligent Robotics
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established players (ABB Ltd., Omron Corporation, Teradyne, Amazon.com, Inc., Medtronic))
Expand procedure and rehabilitation platforms through new indications, software, imaging, training, installed-base upgrades, and selected acquisitions. Use direct sales and service networks to support regulated clinical workflows.
Large installed bases, clinical evidence, regulatory experience, surgeon and hospital relationships, training programs, and global service coverage.
High system and service costs, long clinical sales cycles, complex regulation, and dependence on procedure adoption, capital budgets, and trained users.
Emerging players (Aethon, Ateago Technology, VGo Communications, Inc., Awabot, Xenex Disinfection Services Inc.)
Focus on defined healthcare tasks such as hospital delivery, compact robotic surgery, walking assistance, and disinfection. Use partnerships, service contracts, and focused clinical or workflow evidence to enter hospital networks.
Healthcare-specific product design, faster product iteration, focused customer support, and the ability to address gaps not served by broad medical technology portfolios.
Smaller sales and service networks, limited financing capacity, concentration in a few products or customers, and greater exposure to integration, reimbursement, and scale-up risk.
Recent Developments:
-
In July 2026, ABB Robotics announced a global collaboration with Roche Diagnostics to develop AI-powered robotic solutions for clinical laboratories. The partnership focuses on integrating autonomous mobile robots (AMRs) for laboratory intralogistics and pathology slide handling, improving workflow efficiency and automation in healthcare laboratories. This collaboration strengthens ABB's position in the healthcare mobile robots market by expanding its AI-enabled automation capabilities.
-
In May 2025, ABB Ltd. completed the acquisition of Sevensense, a provider of AI-based Visual SLAM navigation technology. The acquisition enhances ABB's autonomous mobile robot (AMR) portfolio by enabling more accurate and intelligent navigation in dynamic indoor environments, including hospitals and healthcare facilities. The development strengthens ABB's capabilities in healthcare mobile robotics by improving the safety, flexibility, and efficiency of autonomous hospital logistics.
-
In September 2025, Swisslog Healthcare entered a strategic partnership with Diligent Robotics to integrate the Moxi autonomous mobile robot into hospital logistics. The collaboration combines Swisslog's transport automation solutions with Moxi's autonomous last-mile delivery capabilities to automate the movement of medications, laboratory samples, and medical supplies within hospitals. The partnership aims to improve workflow efficiency, reduce the burden on healthcare staff, and accelerate the adoption of autonomous mobile robots in healthcare facilities.
-
In September 2023, the U.S. FDA granted Xenex Disinfection Services, Inc. a De Novo authorization to use a LightStrike+ UV robot to disinfect healthcare facilities.
-
In April 2023, ABB Ltd. Robotics upgraded its AMRs by incorporating Visual Simultaneous Localization and Mapping (Visual SLAM) technology. This new technology was expected to help AMRs make better navigation decisions based on environmental factors.
-
In December 2022, ABB Ltd. opened its advanced robotics factory in Shanghai, China. The facility spans an area of 67,000 square meters and is fully automated & flexible. ABB invested USD 150 million in this production and research center, which would employ digital & automation technologies to produce the next generation of robots.
Healthcare Mobile Robots Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.0 billion
Estimated market size in 2026
USD 1.2 billion
Projected market size by 2033
USD 4.0 billion
Growth rate
CAGR of 18.2% from 2026 to 2033
Actual data
2021 – 2025
Forecast period
2026 – 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Products, applications, end use, control technology, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
ABB Ltd.; Aethon; Omron Corporation; Teradyne; Ateago Technology; VGo Communications, Inc.; Awabot; Xenex Disinfection Services Inc; Medtronic; ST Engineering Aethon; Diligent Robotics
Customization scope
Free report customization (equivalent to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Healthcare Mobile Robots Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and analyzes industry trends across each sub-segment from 2021 to 2033. Grand View Research has segmented the global healthcare mobile robots market report based on product, applications, end use, control technology, and region:
-
Products Outlook (Revenue, USD Billion, 2021 - 2033)
-
Hospital Service & Logistics
-
Autonomous Delivery Robots
-
Pharmacy Robots
-
Waste Handling Robots
-
-
Disinfection & Sanitation
-
UV Disinfection Robots
-
Chemical/Spray Robots
-
-
Assistive & Patient Interaction
-
Nurse-Assist Robots
-
Social Robots
-
-
Telepresence & Remote Monitoring
-
Remote Consultation Robots
-
ICU Telepresence Robots
-
-
Rehabilitation & Mobility
-
Exoskeletons
-
Gait Training Robots
-
-
Imaging & Operating Assistance
-
Mobile Imaging Robots
-
Navigation Robots
-
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Material Transport & Logistics
-
Infection Control & Sterilization
-
Patient Monitoring & Teleconsultation
-
Rehabilitation Therapy
-
Surgical/Imaging Assistance
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Hospitals
-
Ambulatory Surgical Centers (ASCs)
-
Rehabilitation Centers
-
Long-term Care / Elderly Care Facilities
-
-
Control Technology Outlook (Revenue, USD Billion, 2021 - 2033)
-
Autonomous navigation
-
Teleoperated / remote-driven
-
Assisted / hybrid control
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
MEA
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
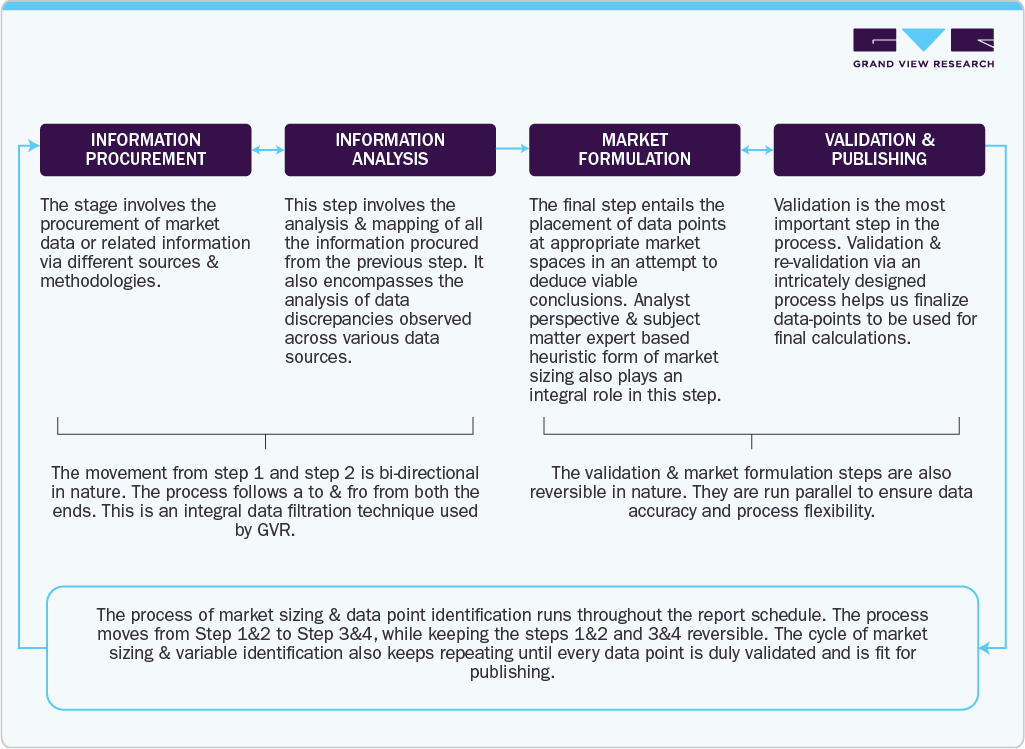
The market estimates in this report were developed by reconciling demand-side and supply-side models. The demand-side model uses country-level counts of hospitals, ambulatory surgical centers, rehabilitation centers, research institutes, and other relevant facilities from government, association, and institutional sources. Facility counts are not treated as robot adopters. Each facility base is adjusted for addressability, observed or supported adoption, installed units per adopting site, replacement and expansion demand, and product-specific average selling prices. The supply-side model uses company filings, investor presentations, regulatory records, product data, and verified business information to estimate revenue from healthcare mobile robots. The two results are compared, reviewed for scope consistency, and triangulated before publication.
Segment Definition
Segment
Segment Definition
By Products
Hospital Service & Logistics
Includes mobile robotic systems designed to support non-clinical hospital operations by transporting medicines, laboratory samples, meals, linens, medical supplies, and equipment between departments. These robots help automate repetitive internal logistics activities and reduce the workload on hospital staff.
Disinfection & Sanitation
Includes autonomous and semi-autonomous robots used for cleaning and disinfecting hospital rooms, operating areas, corridors, and other healthcare spaces. Systems using technologies such as UV-C light, spraying, or automated surface cleaning are covered under this category.
Assistive & Patient Interaction
Includes robots designed to directly interact with patients and provide assistance, communication, companionship, navigation, reminders, and other non-clinical support. The segment covers socially assistive and patient-facing robotic systems used to improve patient engagement and experience.
Telepresence & Remote Monitoring
Includes mobile robotic platforms that enable healthcare professionals, caregivers, or family members to remotely communicate with and observe patients. These systems generally combine mobile navigation with cameras, displays, microphones, and connectivity for virtual interaction and monitoring.
Rehabilitation & Mobility
Includes robotic systems that assist patients with walking, movement, balance, gait training, and physical rehabilitation. These solutions are used to support recovery and improve mobility among patients requiring structured or repetitive rehabilitation activities.
Imaging & Operating Assistance
Includes mobile robotic platforms used to support medical imaging, image-guided procedures, surgical activities, patient positioning, and operating-room workflows. The segment covers robotic systems that improve the positioning, mobility, or handling of imaging and clinical equipment.
By Application
Material Transport & Logistics
Includes the use of mobile robots for transporting medicines, laboratory specimens, medical equipment, supplies, meals, linens, and other materials within healthcare facilities. The application focuses on automating internal transportation and improving the efficiency of hospital logistics.
Infection Control & Sterilization
Includes the deployment of mobile robots for automated disinfection, sanitation, and infection-control activities. These systems are used to treat patient rooms, operating rooms, isolation areas, and other high-risk environments to support healthcare facilities in maintaining hygiene standards.
Patient Monitoring & Teleconsultation
Includes robotic applications that enable remote patient observation, communication, virtual consultations, and interaction with healthcare professionals. These systems can support routine monitoring and allow clinicians to communicate with patients without being physically present.
Rehabilitation Therapy
Includes the application of mobile robotic technologies in physical rehabilitation, gait training, mobility exercises, and recovery programs. Robots provide repetitive and controlled movements that can complement therapist-led rehabilitation and support patient recovery.
Surgical/Imaging Assistance
Includes robotic applications supporting surgical procedures, medical imaging, image-guided interventions, and operating-room activities. These systems can assist with equipment positioning, imaging, navigation, and other tasks requiring precision and controlled movement.
By End Use
Hospitals
Includes general hospitals, specialty hospitals, teaching hospitals, and academic medical centers that deploy mobile robots across logistics, sanitation, patient support, monitoring, rehabilitation, imaging, and clinical workflows. Hospitals represent the broadest end-use environment because robots can be deployed across multiple departments.
Ambulatory Surgical Centers (ASCs)
Includes outpatient surgical facilities where mobile robots are used to support surgical and imaging workflows, material transportation, infection control, and other facility operations. These centers provide a growing environment for robotic technologies because of their focus on efficient and standardized workflows.
Rehabilitation Centers
Includes specialized facilities providing physical, neurological, and mobility rehabilitation services. Mobile robots are used in these settings for gait training, mobility assistance, repetitive therapy, and other rehabilitation activities that support patient recovery.
Long-term Care / Elderly Care Facilities
Includes nursing homes, assisted-living facilities, elderly-care centers, and other residential care environments where mobile robots support monitoring, communication, social interaction, transportation, and routine assistance. Adoption is supported by the need to improve care delivery and address increasing demand for elderly-care services.
By Control Technology
Autonomous Navigation
Includes mobile robots capable of independently navigating healthcare environments and performing assigned tasks with limited human intervention. These systems use technologies such as sensors, cameras, mapping, localization, artificial intelligence, and obstacle detection to navigate dynamic indoor environments.
Teleoperated / Remote-Driven
Includes mobile robots that are controlled by a human operator from a remote location. These systems are primarily used where direct human supervision is required, including telepresence, remote monitoring, virtual consultations, and other applications involving geographically separated patients and healthcare professionals.
Assisted / Hybrid Control
Includes mobile robots that combine autonomous functions with human supervision or manual intervention. These systems can independently perform navigation or routine tasks but allow operators to intervene when required, making them suitable for complex or changing healthcare environments.
Estimation Model
 To learn more about this report, Download Free Sample Report
Market-specific Research Models:
Consensus-Based Estimates & Forecasting
Public company revenue is reviewed from annual reports, quarterly filings, investor presentations, and earnings releases. When a reported segment includes a product outside the study scope, product mix, installed base, procedure volume, placements, geographic exposure, and management commentary are used to estimate the relevant share. Private-company estimates use disclosed funding and commercial data, company announcements, deployment evidence, product coverage, and business-information databases such as S&P Global, Crunchbase, ZoomInfo, and RocketReach.
Our methodology included:
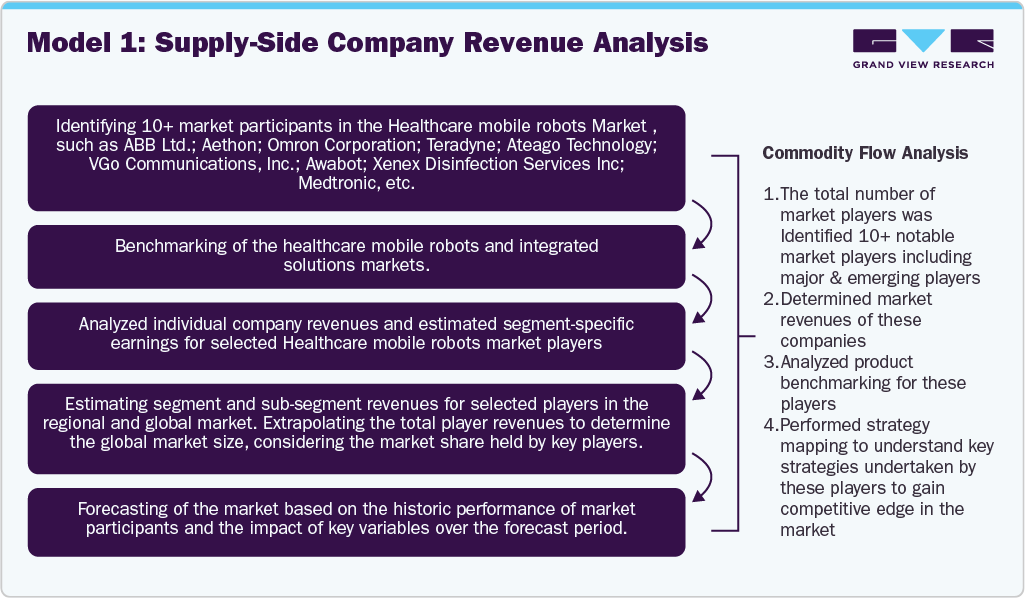
Model 1: Supply-Side Company Revenue Analysis - Public-company healthcare robotics revenue is derived from reported business or product segments and adjusted only where the disclosed segment is broader than the study scope. Private-company revenue is estimated using business information databases and checked against product penetration, deployments, workforce, funding, customer announcements, and the share of the company's portfolio attributable to healthcare mobile robots. Company estimates are summed and adjusted for uncovered participants, distributor margins, and double-counting.
Model 2: Demand-Side Volume-Price Analysis - For each country and end-use setting, the model applies an addressable share and an adoption rate to the actual facility base. Revenue is calculated from new adopters, units per adopting facility, fleet expansion, replacement cycles, and product-specific average selling prices. Surgical and rehabilitation systems are also checked against reported placements, installed bases, procedures, and reimbursement evidence where available.
Model 3: Country-Level Multivariate Analysis - Adoption assumptions are tested against healthcare expenditure, facility scale, workforce availability, regulatory access, reimbursement, hospital digital readiness, local distributor and service coverage, and verified 2025 deployments. Countries are not estimated as a fixed ratio of hospital counts when original facility data are available.
Model 4: Segment-Level Multivariate Analysis - Type and end-use shares are built from supplier product mix, placements, procedure and usage data, customer deployments, pricing, and replacement patterns. Overlap between mobile hospital robots, surgical systems, rehabilitation systems, and walking-assist devices is removed through consistent product definitions.
Model 5: CAGR and Forecast Analysis - Forecasts incorporate the 2025 installed base, product pipeline, regulatory milestones, replacement cycles, expected facility adoption, service capacity, pricing change, and country-level healthcare investment. The forecast is reviewed under base, upside, and downside adoption scenarios before the final CAGR is selected.
 To learn more about this report, Download Free Sample Report
Supply-side analysis maps revenue from manufacturers and healthcare robotics specialists to the study's product and geographic scope. Reported figures are preferred. Where healthcare mobile robot revenue is not separately disclosed, the estimate applies a documented attribution to the relevant business segment based on product range, installed base, placements, procedure volume, customer evidence, and geographic mix. The resulting company total is reconciled with the country-level volume-price model to identify gaps, double counting, or scope differences.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Healthcare Mobile Robots Market Adoption & Application Analysis
Developed a tailored analysis of the global Healthcare Mobile Robots market, focusing on Hospital Service & Logistics, Disinfection & Sanitation, Assistive & Patient Interaction, Telepresence & Remote Monitoring, Rehabilitation & Mobility, and Imaging & Operating Assistance.
The study assessed adoption trends across hospitals, ambulatory surgical centers, rehabilitation facilities, long-term care centers, and research institutions, considering factors such as healthcare workforce shortages, demand for automation, patient care optimization, and operational efficiency improvements.
Enables stakeholders to understand evolving healthcare automation requirements, identify high-growth robotic application areas, evaluate adoption potential across healthcare settings, and develop informed investment strategies aligned with digital transformation and healthcare delivery modernization.
Healthcare Robotics Technology, Integration & Competitive Assessment
Delivered a customized evaluation of healthcare mobile robot technologies, including autonomous navigation, artificial intelligence, machine learning, sensors, computer vision, robotic mobility platforms, remote monitoring, and integration with hospital information systems. The analysis covered workflow automation capabilities such as medication delivery, logistics transportation, patient assistance, rehabilitation support, and telepresence applications. Competitive benchmarking was performed across leading companies including Intuitive Surgical, Stryker, KUKA, Swisslog Healthcare, Aethon, and other robotics solution providers.
Provides actionable insights into commercially attractive robotic technologies, emerging AI-enabled healthcare automation trends, integration challenges, regulatory considerations, and competitive positioning. Supports identification of innovation opportunities, technology adoption barriers, and future growth pathways in healthcare robotics.
Healthcare Mobile Robots Digital Infrastructure & Market Landscape Assessment
Conducted a focused assessment of the healthcare mobile robotics ecosystem, including robotic hardware, software platforms, cloud connectivity, cybersecurity, interoperability frameworks, and hospital workflow integration requirements. The analysis evaluated market entry opportunities, reimbursement considerations, regulatory environment, procurement models, and competitive strategies of key participants. The study assessed technology adoption across developed and emerging markets, including North America, Europe, Asia Pacific, Latin America, and Middle East & Africa, while analyzing infrastructure readiness and healthcare automation maturity.
Supports strategic planning for healthcare robotics expansion, technology investment decisions, regulatory compliance strategies, and geographic market prioritization. Helps stakeholders identify adoption opportunities, infrastructure requirements, competitive advantages, and long-term growth opportunities across the global Healthcare Mobile Robots value chain.
Frequently Asked Questions About This Report
Latin America is the fastest-growing region over the forecast period.
Hospital service & logistics segment dominated the market in 2025, accounting for the largest revenue share of 36.4%.
Material transport & logistics segment held the largest revenue share of 35.7% in 2025.
Hospitals segment held the largest revenue share of 71.7% in 2025.
The market’s growth is driven by the increasing adoption of automation to address healthcare workforce shortages, enhance operational efficiency, and improve patient safety.
The global healthcare mobile robots market is expected to grow at a CAGR of 18.2% from 2024 to 2030, reaching USD 4.0 billion by 2033.
North America dominated with a 42.8% revenue share in 2023.
Some of the major players in the healthcare mobile robots market are: ABB Ltd.; Aethon; Omron Corporation; Teradyne; Ateago Technology; VGo Communications, Inc.; Awabot; Xenex Disinfection Services Inc; Medtronic; ST Engineering Aethon; Diligent Robotics
The global healthcare mobile robots market size was valued at USD 1.0 billion in 2023 and is estimated at USD 1.2 billion for 2026.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


