
- Home
- »
- Advanced Interior Materials
- »
-
High Purity Alumina Market Size & Share Report, 2026-2033GVR Report cover

High Purity Alumina Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (4N, 5N, 6N), By Application (LED, Li-ion Battery, Semiconductor, Phosphor), By Region (North America, Europe, Asia Pacific), And Segment Forecasts
Market Size, 2025
$5.6BMarket Estimate, 2026
$6.8BMarket Forecast, 2033
$30.8BCAGR, 2026–2033
23.7%High Purity Alumina Market Summary
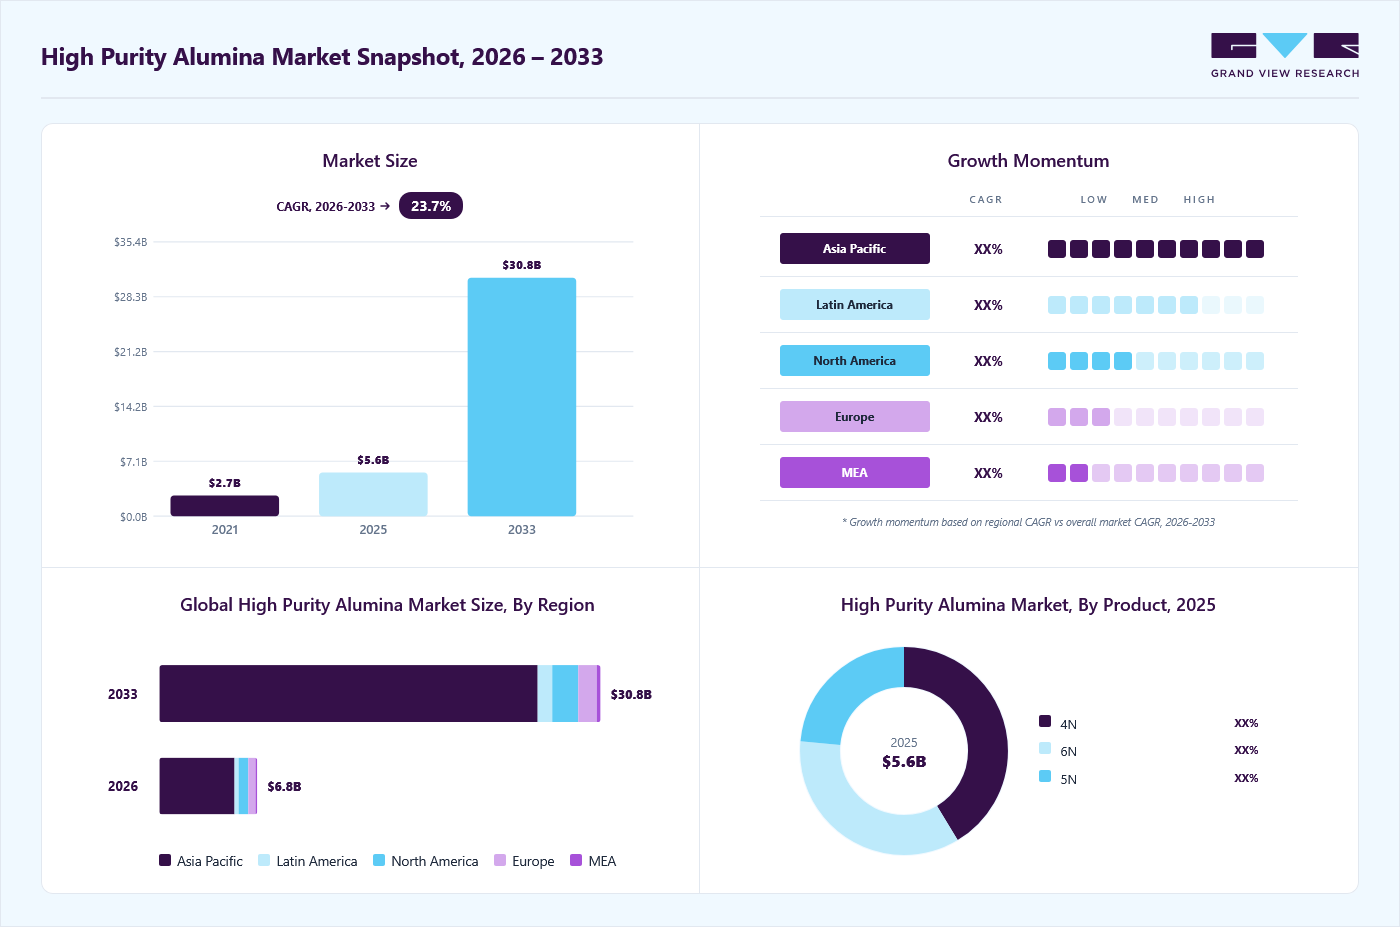
The global high-purity alumina market size was valued at USD 5.6 billion in 2025 and is projected to grow from USD 6.8 billion in 2026 to USD 30.8 billion by 2033, at a CAGR of 23.7% from 2026 to 2033. Asia Pacific dominated the global market with the largest revenue share of 75.3% in 2025. The increasing use of high-purity alumina (HPA) in electric vehicle (EV) batteries and in electronic manufacturing components is anticipated to drive industry growth during the forecast period.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: 4N segment led the market with the largest revenue share of 41.3% in 2025.
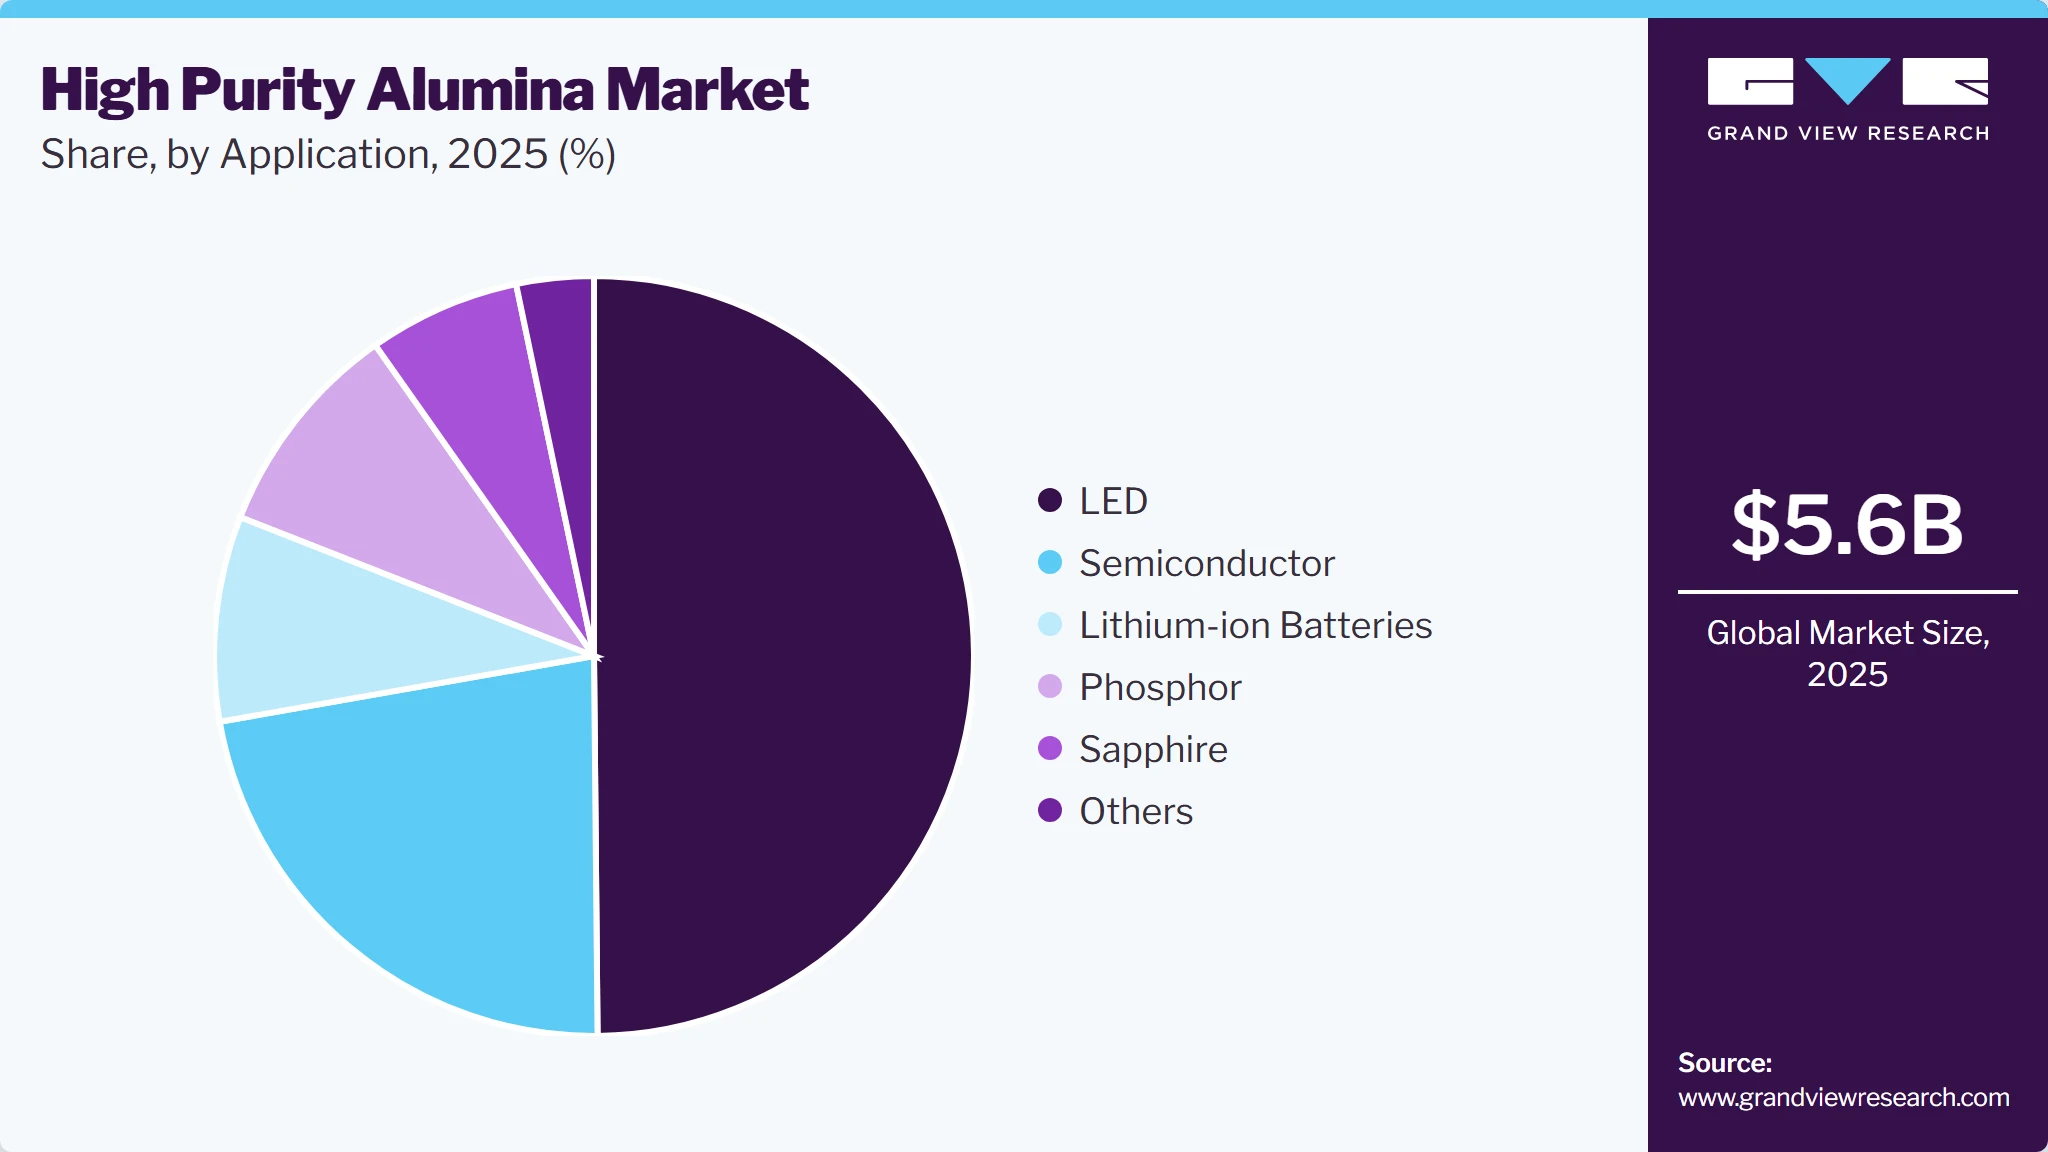
- By application: LED segment led the market with the largest revenue share of 49.9% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (75.3% revenue share, 2025)
- By country: The high purity alumina market in the China held the largest share in the Asia Pacific region in 2025.
Market Size & Forecast
- Market size in 2025: USD 5.6 Billion
- Estimated market size in 2026: USD 6.8 Billion
- Projected market size by 2033: USD 30.8 Billion
- CAGR (2026-2033): 23.7%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The lithium-ion battery consists of a thin coating on the separator sheet and a nano-thickness for alumina-coated separators to improve battery performance. This HPA enhances the durability of the battery by increasing its ability to withstand a high rate of discharge.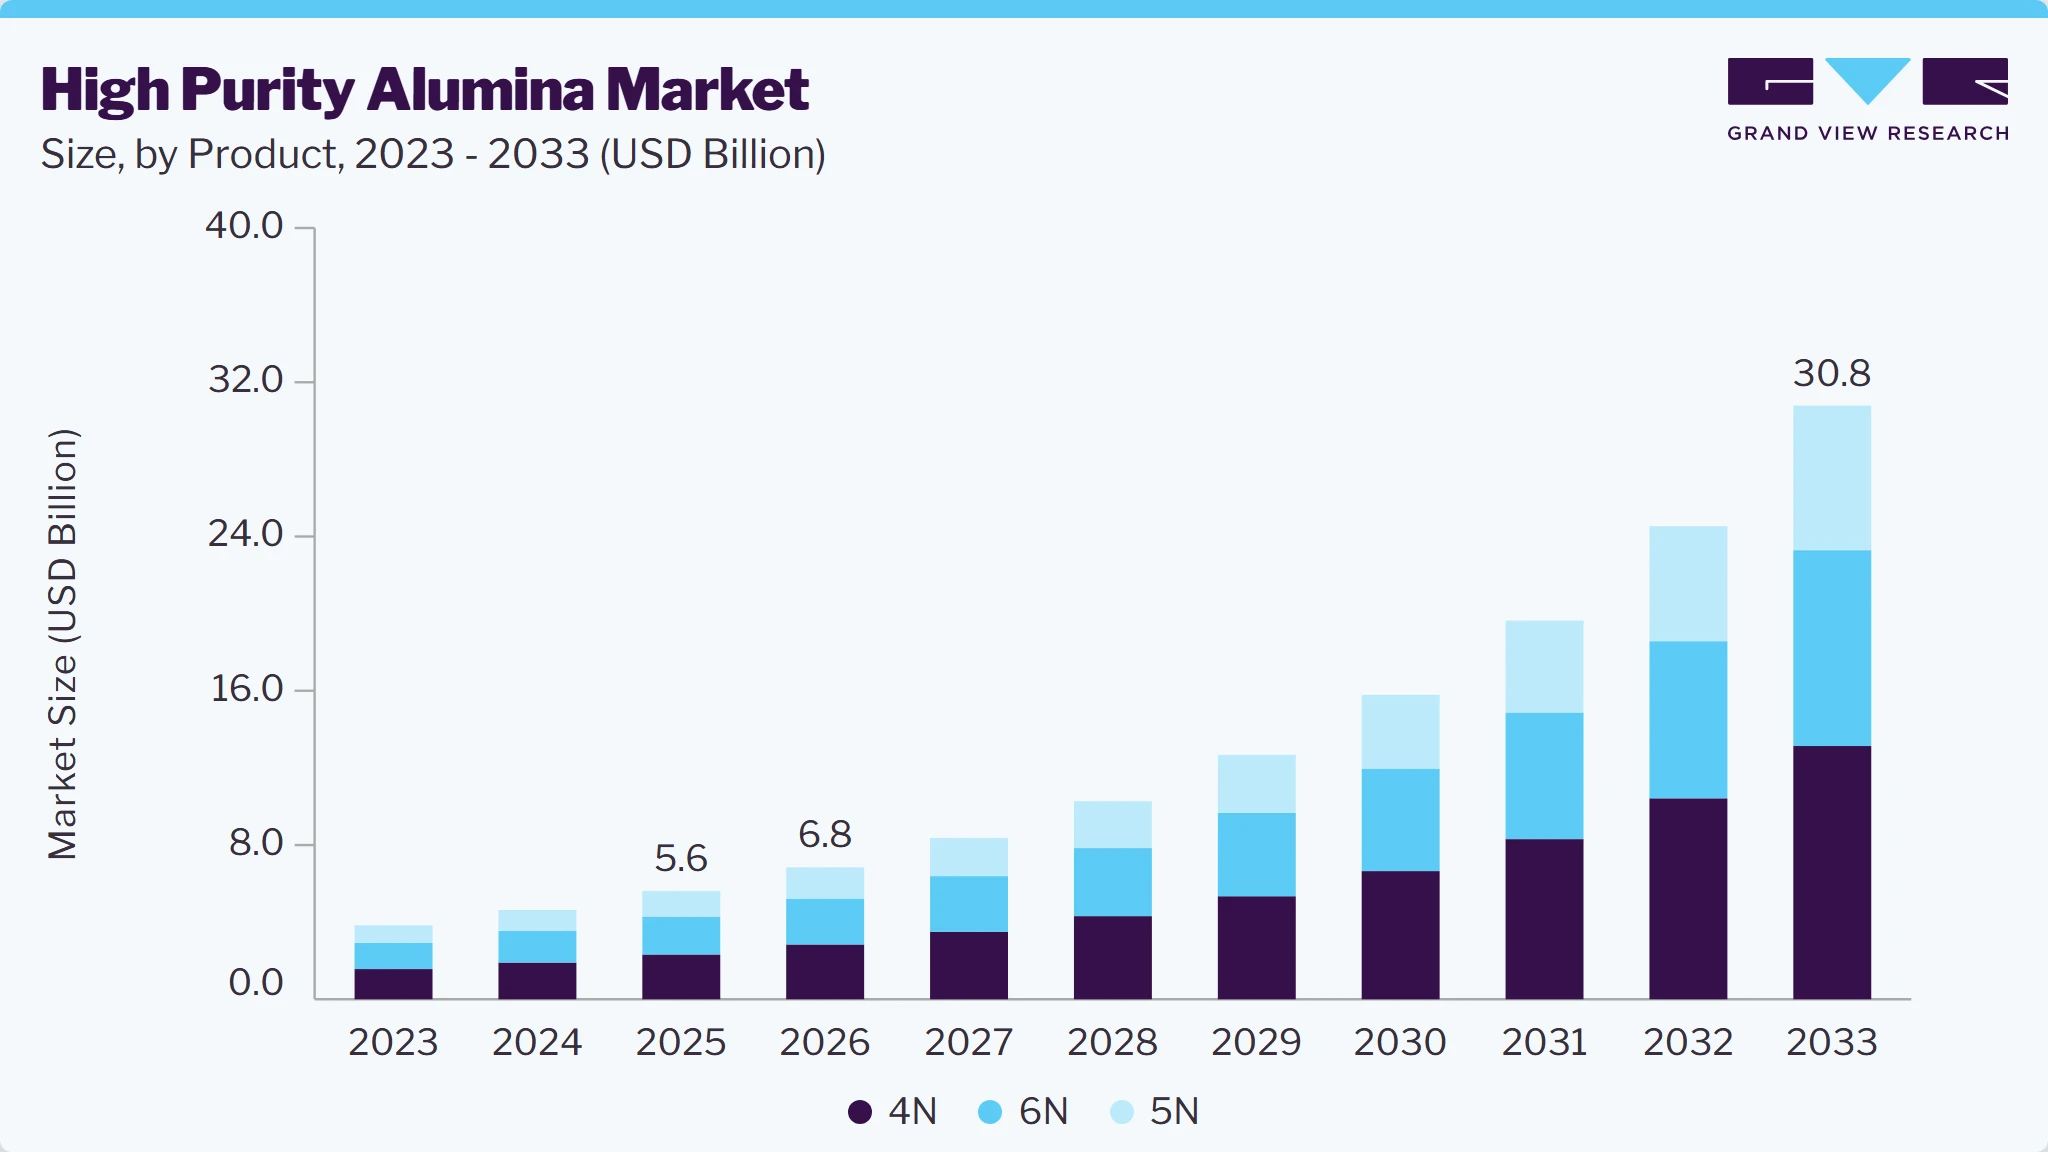 To learn more about this report, Download Free Sample Report
High Purity Alumina (HPA) is a refined form of aluminum oxide with a purity of 99.9% or greater. Its purity, classified by the number of "nines" (4N, 5N, 6N), significantly impacts its properties and applications. According to the U.S. Energy Department, the country is expected to complete most of its lighting installation projects by 2035 and is likely to adopt LED lighting technology in the residential sector, using ENERGY STAR products. ENERGY STAR-qualified products consume around 75% less energy when compared to LCD. As a result of its consumption in LED manufacturing for residential and commercial lighting, the HPA market is anticipated to grow over the forecast period.
 To learn more about this report, Download Free Sample Report
The global HPA market is experiencing substantial growth, driven by the increasing demand for electric vehicle batteries and LED manufacturing. In addition, HPA is a crucial component in lithium-ion batteries due to its conductivity and stability. The market is also seeing trends such as strategic partnerships and the development of new technologies to reduce costs.
Furthermore, the growing demand for LED lighting, electronics, and EV batteries is one of the key drivers for the industry, where the product is widely used for its properties, such as thermal stability, brightness, and superior hardness. HPA witnesses significant demand for plasma displays, as they are an energy-efficient and cost-effective alternative to conventional materials, including incandescent light bulbs. It is also an essential base material for synthetic sapphire substrates used in numerous microelectronics, especially semiconductors.
Market Dynamics
The rapid expansion of the electric vehicle industry is a major growth driver for the high-purity alumina (HPA) market. HPA is widely used as a coating material for lithium-ion battery separators, enhancing thermal stability, improving battery safety, and reducing the risk of thermal runaway. As global automakers continue to scale up EV production and governments promote vehicle electrification through subsidies and emissions regulations, demand for advanced battery materials is rising sharply. This trend is creating substantial opportunities for HPA manufacturers across North America, Europe, and the Asia Pacific.
The growing adoption of lithium-ion batteries across electric vehicles, consumer electronics, and energy storage systems is a significant driver for the HPA market. HPA is used as a coating on battery separators to enhance thermal stability, improve safety, and minimize the risk of short circuits and thermal runaway. As battery manufacturers focus on producing safer, higher-performance batteries, demand for high-purity alumina has increased considerably. The rapid expansion of electric mobility worldwide, supported by government incentives and carbon-reduction initiatives, is further accelerating the adoption of HPA in battery applications.
In addition, rising investment in battery manufacturing facilities and gigafactories is driving strong demand for advanced battery materials. Major battery producers are increasing production capacity to meet the growing demand for electric vehicles and renewable energy storage systems. High-purity alumina plays a crucial role in extending battery life, improving charging efficiency, and enhancing overall battery reliability. As global energy transition efforts continue and battery technologies evolve toward higher energy densities, demand for high-purity alumina is expected to grow sustainably throughout the forecast period.
High production and processing costs remain a significant restraint for the high-purity alumina market. The manufacturing of HPA involves complex purification processes, specialized equipment, and substantial energy consumption to achieve purity levels of 99.99% and above. These stringent production requirements lead to higher operational and capital expenditures than those for conventional alumina products. Additionally, maintaining consistent product quality and meeting the specifications required by battery, LED, and semiconductor manufacturers further increases production costs. As a result, the high cost of high-purity alumina can limit its adoption in cost-sensitive applications and pose challenges to market expansion, particularly in regions with limited access to advanced manufacturing infrastructure.
The ongoing expansion of global semiconductor manufacturing capacity presents a significant opportunity for the high-purity alumina market. Governments and private companies are investing heavily in new semiconductor fabrication facilities to strengthen domestic chip production and reduce supply chain vulnerabilities. High-purity alumina is used in various semiconductor manufacturing processes due to its excellent thermal stability, electrical insulation, and extremely low impurity levels. The growing demand for semiconductors across applications such as artificial intelligence, 5G infrastructure, automotive electronics, data centers, and consumer devices is expected to increase the consumption of high-purity materials. As chipmakers advance toward smaller, more sophisticated semiconductor nodes, the need for ultra-pure materials such as high-purity alumina is likely to grow, creating long-term opportunities for market participants.
Analyst Perspective
The HPA market is emerging as one of the fastest-growing specialty materials markets, driven by the rapid expansion of electric vehicles, lithium-ion batteries, LEDs, semiconductors, and advanced electronic components. HPA has become a critical material due to its exceptional purity, thermal stability, hardness, and insulating properties, making it indispensable for next-generation technologies. The market is particularly benefiting from the global transition toward electrification and energy-efficient solutions, with battery manufacturers increasingly utilizing HPA as a separator coating material to improve battery safety and performance.
Product Insights
Based on product, the 4N segment led the market with the largest revenue share of 41.3% in 2025. This growth can be attributed to the application of the product in LEDs. It is also used as a battery separator for lithium-ion batteries. Growth in the lighting and EV industries is anticipated to drive the market during the forecast period. Furthermore, it provides sufficient purity for improving LED brightness and durability and is favored in large-scale industrial applications where a balance of performance and cost is essential. The booming lighting and EV industries significantly contribute to its market share.
The 5N product segment is expected to grow at a CAGR of 23.6% over the forecast period, owing to the properties such as chemical stability, scratch resistance, and extreme hardness, which make it suitable for sapphire production, which is used in the production of high-quality lenses. Furthermore, it is also used in applications for high-quality industrial ceramics, such as crucibles for high-purity metals and wear-resistant parts. The rising need for efficient and durable components in industries such as chemical processing and mining is driving the demand for high-quality industrial ceramics.
Application Insights
Based on application, LED segment led the market with the largest revenue share of 49.9% in 2025, primarily driven by the increasing demand for energy-efficient lighting solutions. In addition, governments worldwide are promoting the adoption of LEDs to reduce carbon emissions, leading to a significant shift from traditional incandescent bulbs. In addition, high-purity alumina is essential in producing sapphire substrates for LEDs, enhancing their brightness and durability. Furthermore, the expanding applications of LEDs in smart city infrastructure and automotive lighting further drive the demand for high-purity alumina, ensuring continued market growth.
 To learn more about this report, Download Free Sample Report
The semiconductor segment is expected to grow at a CAGR of 24.2% over the forecast period, owing to the rising demand for advanced electronics and electric vehicles (EVs). In addition, as global investments in technology and EV production increase, the need for reliable materials such as high-purity alumina becomes paramount. Furthermore, ongoing innovations in semiconductor technology and battery applications are expected to bolster market expansion, making high-purity alumina indispensable for future advancements.
Regional Insights
The North American high-purity alumina market demonstrates strong growth potential due to the adoption of advanced technologies and robust research and development activities. The region's market is primarily driven by the U.S., Canada, and Mexico, with significant developments in electric vehicle production, semiconductor manufacturing, and LED lighting applications. Furthermore, increased investments in high-purity alumina production capabilities aim to develop domestic mineral supply chains and reduce dependence on imports, further contributing to market growth.
U.S. High Purity Alumina Market Trends
The U.S. dominated the North America high-purity alumina market with the highest revenue share in 2025, owing to its world-leading electronics sector and significant semiconductor manufacturing capabilities. In addition, the rising consumer demand further drives market growth, particularly within the semiconductor industry. Furthermore, substantial investments in new manufacturing facilities and research capabilities highlight the U.S.'s commitment to maintaining its leadership role in high-purity alumina production.
Europe High Purity Alumina Market Trends
The high-purity alumina market in Europe is expected to be driven by increasing demand for energy-efficient lighting solutions and advancements in semiconductor technology. The region's focus on sustainability and reducing carbon emissions supports the adoption of LEDs and electric vehicles. Furthermore, strong regulatory frameworks encourage investment in innovative technologies that utilize high-purity alumina. Moreover, as Europe transitions towards greener technologies, the demand for high-purity alumina is expected to grow significantly.
Asia Pacific High Purity Alumina Market Trends
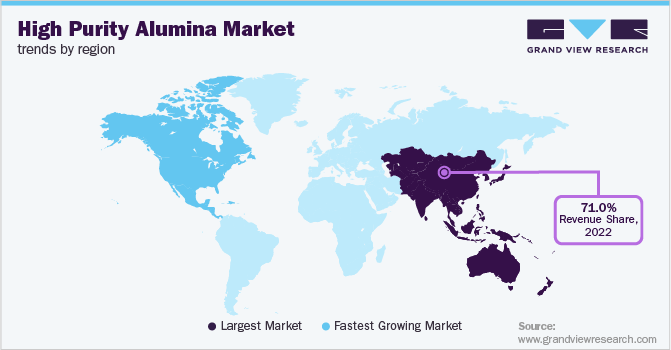
Asia Pacific dominated the high-purity alumina market, with the largest revenue share of 75.3% in 2025. This growth can be attributed to the robust manufacturing capabilities in countries such as China, Japan, South Korea, and India. In addition, this region dominates the global LED market and is witnessing increasing production of electric vehicles, particularly in China. Furthermore, the presence of major battery production facilities further strengthens the region's market position.
 To learn more about this report, Download Free Sample Report
The high-purity alumina market in China held the largest share in the Asia Pacific region in 2025, driven by the country's extensive semiconductor manufacturing base and robust LED lighting industry. In addition, China has emerged as a global leader in lighting products, supported by government initiatives and increasing domestic demand. Furthermore, the expanding electric vehicle sector spurs demand for high-purity alumina in battery applications, reinforcing China's pivotal role in the global market.
Latin America High Purity Alumina Market Trends
The Latin America high purity alumina market is expected to grow at a CAGR of 19.6% over the forecast period, driven by increasing investments in infrastructure expansion and renewable energy projects. Furthermore, countries such as Brazil are focusing on expanding their industrial capabilities, including the adoption of advanced materials such as high-purity alumina for various applications. Furthermore, rising awareness about energy efficiency and sustainability is driving demand for LEDs and electric vehicles, which will likely boost the high-purity alumina market across the region.
Key High Purity Alumina Company Insights
Major global high-purity alumina companies include Almatis, Inc., Altech Chemicals Ltd., Orbite Technologies Inc., and others. The industry is highly competitive and is anticipated to expand due to the growing penetration of HPA use in various end-use industries. Key players are expected to continue to cater to market demand in the coming years.
-
Altech Chemicals uses a specific process to produce HPA from its kaolin clay deposit. Altech is also exploring the use of HPA to manufacture epoxy molding compounds (EMCs) for the semiconductor industry to improve heat dissipation.
-
Nippon Light Metal Holdings Co., Ltd. produces high-purity alumina for various applications. Their high-purity alumina lineup is made by improving the alumina refining process for applications including mobile phone cover glass and LED boards. The company also produces aluminum hydroxide, alumina, and several chemicals used in flame retardants, ceramics, chemical products, and water purification.
Key High Purity Alumina Companies:
The following key companies have been profiled for this study on the high-purity alumina market.
-
Almatis, Inc.
-
Altech Batteries Limited.
-
Alpha HPA
-
Baikowski
-
CoorsTek Inc.
-
FYI RESOURCES
-
HONGHE CHEMICAL
-
Nippon Light Metal Holdings Co., Ltd.
-
Polar Sapphire Ltd.
-
Sumitomo Chemical Co., Ltd.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g. Almatis, Inc., Baikowski, CoorsTek Inc.)
- Mature participants in the HPA market primarily focus on large-scale production, process optimization, and long-term supply agreements with customers in the LED, semiconductor, sapphire substrate, and lithium-ion battery industries.
- These companies leverage established refining technologies and extensive operational experience to manufacture consistent 4N, 5N, and 6N purity grades.
- Established players possess significant competitive advantages through their advanced purification technologies, large-scale manufacturing infrastructure, and extensive technical expertise.
- Their ability to consistently produce ultra-high-purity alumina that meets stringent industry specifications makes them preferred suppliers for demanding applications, including semiconductor components and synthetic sapphire production.
- Despite their strong market positions, mature players face challenges associated with high production costs and energy-intensive manufacturing processes.
- Producing high-purity alumina requires multiple purification stages, strict process controls, and advanced equipment, resulting in substantial capital and operational expenditures.
Emerging & Regional Players (e.g., Altech Chemicals Ltd., Alpha HPA, FYI RESOURCES)
- Emerging participants in the high-purity alumina market generally focus on innovative production technologies, niche market opportunities, and strategic positioning within high-growth industries.
- Many newer companies are developing alternative feedstock routes and proprietary refining processes to reduce manufacturing costs and improve environmental performance.
- Emerging companies benefit from operational flexibility and the ability to adopt modern production technologies without the constraints of legacy infrastructure.
- Their facilities and processes are often designed around current market requirements, enabling improved efficiency, lower environmental impact, and enhanced scalability
- Emerging participants face significant challenges related to commercialization risks, limited production capacity, and funding requirements.
- Many newer companies are still scaling production technologies and may encounter technical difficulties when transitioning from pilot-scale operations to full commercial manufacturing.
Recent Developments
-
In May 2024, Alpha HPA announced its final investment decision to begin full-scale High Purity Alumina (HPA) production in Gladstone, Queensland. This project aimed to establish the world's largest single-site HPA refinery. Construction of the 10-hectare facility was expected to begin in mid-2024, creating 120 local jobs in addition to 300 during construction. The project is supported by substantial funding from government agencies and investors.
-
In August 2023, Sumitomo Chemical announced plans to begin mass production of its innovative ultra-fine α-alumina products (NXA series) at its Ehime Works in September. These new grades, featuring homogeneous ultra-fine particles of 150 nm or less, target emerging markets in ICT, energy-saving, and life science sectors. As a prominent player in High Purity Alumina, Sumitomo aimed to increase sales revenue in its ultrahigh purity alumina business by 30% by FY2025.
High Purity Alumina Market Report Scope
Report Attribute
Details
Market definition
The high-purity alumina market, in terms of consumption, refers to the total volume & value of high-purity alumina (4N, 5N, and 6N grades) utilized across various end-use industries worldwide.
Market size in 2025
USD 5.6 billion
Estimated market size in 2026
USD 6.8 billion
Projected market size by 2033
USD 30.8 billion
Growth rate
CAGR of 23.7% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million, volume in kilotons and CAGR from 2026 to 2033
Report coverage
Revenue forecast, volume forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, region.
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; India; China; Japan; South Korea; Brazil; Saudi Arabia; UAE
Key companies profiled
Almatis, Inc., Altech Batteries Limited, Alpha HPA, Baikowski, CoorsTek Inc., FYI Resources, Honghe Chemical, Nippon Light Metal Holdings Co., Ltd., Polar Sapphire Ltd., Sumitomo Chemical Co., Ltd.
Customization scope
Free report customization (equivalent to up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global High Purity Alumina Market Report Segmentation
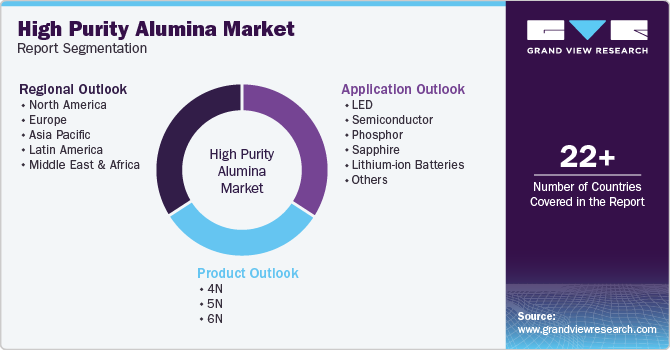
This report forecasts revenue growth at global, regional, and country levels and analyzes the latest industry trends in each sub-segment from 2021 to 2033. For this study, Grand View Research has segmented the global high purity alumina market report based on product, application, and region.
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
4N
-
5N
-
6N
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
LED
-
Semiconductor
-
Phosphor
-
Sapphire
-
Lithium-ion Batteries
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
-
Europe
-
Germany
-
UK
-
France
-
Spain
-
Italy
-
-
Asia Pacific
-
China
-
Japan
-
South Korea
-
-
Latin America
-
Brazil
-
-
Middle East and Africa
-
Research Methodology
The high purity alumina market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each high purity alumina segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Product
Revenue Capture Definition
4N
4N high-purity alumina refers to alumina with a purity of 99.99%, containing very low concentrations of metallic and non-metallic impurities. It is widely used in LED lighting, phosphors, lithium-ion battery separators, and specialty ceramic applications where high performance and purity are required.
5N
5N high-purity alumina is alumina with a purity of 99.999%, offering enhanced chemical stability, thermal resistance, and electrical insulation properties. It is commonly utilized in semiconductor substrates, sapphire wafer production, advanced optical components, and high-end electronic applications.
6N
6N high-purity alumina is ultra-high purity, with a purity of 99.9999% and extremely low trace impurities. It is primarily used in advanced semiconductor manufacturing, precision optics, aerospace electronics, and next-generation sapphire crystal applications that require exceptional material performance and reliability.
Application
Revenue Capture Definition
LED
High-purity alumina used in LED applications serves as a key raw material for sapphire substrates that support the growth of LED chips. Its high thermal conductivity, transparency, and purity help improve light output, efficiency, and device longevity.
Semiconductor
In semiconductor applications, high-purity alumina is used to manufacture sapphire wafers, insulating components, and process equipment parts. Its excellent electrical insulation and resistance to contamination make it suitable for advanced electronic fabrication processes.
Phosphor
High-purity alumina is employed in phosphor production as a host material and processing aid for lighting and display technologies. Its purity ensures consistent luminescence performance, color stability, and operational reliability.
Sapphire
High-purity alumina is the primary feedstock for synthetic sapphire crystal production, which is used in optics, electronics, and protective covers. The material's low impurity content enables the formation of high-quality sapphire with superior hardness and optical clarity.
Lithium-ion Batteries
In lithium-ion batteries, high-purity alumina is used as a ceramic coating material for battery separators to enhance thermal stability and safety. It helps improve battery performance, extend cycle life, and reduce the risk of thermal runaway.
Others
Other applications of high-purity alumina include advanced ceramics, optical lenses, biomedical devices, aerospace components, and specialty coatings. These uses benefit from its high purity, chemical resistance, mechanical strength, and thermal durability.
Estimation Model
Layer Name
Key Question
Description
Advanced Electronics & Energy Demand Base Layer
What forms the demand base?
Identify global demand from high-growth industries including LEDs, semiconductors, lithium-ion batteries, phosphors, and sapphire substrates. Assess production volumes and capacity expansions within these sectors to establish the total addressable demand for high-purity alumina.
HPA Application Penetration Layer
Where is high-purity alumina utilized?
Estimate the penetration of HPA across key applications, including LED substrates, semiconductor wafers, battery separators, phosphors, sapphire glass, and specialty optical components. Analyze adoption trends of 4N, 5N, and 6N purity grades across various end-use industries and regions.
HPA Consumption Intensity Layer
How much high-purity alumina is consumed?
Analyze HPA consumption intensity based on application specific requirements, purity levels, manufacturing technologies, and production capacities. Evaluate the amount of HPA consumed per unit of LED production, semiconductor fabrication, battery manufacturing, and sapphire substrate production. Consumption intensity is influenced by technological advancements, improvements in material efficiency, and product performance requirements.
Revenue Layer
How is market revenue generated?
Market revenue is derived from the production and sale of high-purity alumina grades, including 4N, 5N, and 6N. Revenue generation is driven by demand from LEDs, semiconductors, lithium-ion batteries, phosphors, sapphire substrates, and other specialty applications. Market value is influenced by purity grade premiums, production costs, technological complexity, supply availability, and demand from advanced manufacturing industries.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
Detailed regional analysis of the high purity alumina (HPA) market across North America, Europe, Asia Pacific, Latin America, and Middle East & Africa. Included evaluation of semiconductor manufacturing capacity, LED production, lithium-ion battery supply chains, sapphire substrate demand, government incentives for advanced materials, and regional investments in high-tech manufacturing.
Identified high growth demand centers and emerging HPA consumption hubs. Enabled strategic expansion planning based on battery manufacturing investments, semiconductor fabrication growth, and electronics production trends. Supported regional demand forecasting and market entry strategies.
Cross Segmentation
Comprehensive cross-segmentation analysis by product purity and application, including 4N HPA in phosphor and LED applications, 5N HPA in semiconductor and sapphire substrate production, and 6N HPA in advanced electronics and specialty applications. Evaluated consumption trends across lithium-ion batteries, semiconductors, LEDs, sapphire, and other end-use sectors, along with regional demand variations and technology adoption rates.
Enabled identification of the most attractive purity grade application combinations and emerging demand opportunities. Supported product portfolio optimization, investment prioritization, and customer targeting strategies.
Opportunity Assessment
Identification of high-growth opportunities across lithium-ion battery separators, semiconductor manufacturing, LED lighting, sapphire substrates, advanced optics, electric vehicles, and next-generation electronics.
Enabled prioritization of high-return growth segments and emerging regional opportunities. Supported long-term investment planning, capacity expansion decisions, and strategic business development initiatives aligned with global technology and electrification trends.
Frequently Asked Questions About This Report
The high purity alumina market is expected to grow at a compound annual growth rate of 23.7% from 2026 to 2033 to reach USD 30.8 billion by 2033.
Based on product, 4N accounted for largest revenue share of 41.3% in 2025.
The key players operating in the high-purity alumina market are Almatis, Inc., Altech Chemicals Ltd., Alpha HPA, Baikowski, CoorsTek Inc., FYI Resources, Honghe Chemical, Nippon Light Metal Holdings Co., Ltd., Polar Sapphire Ltd., and Sumitomo Chemical Co., Ltd.
The key factor that is driving the growth of the global high purity alumina market is the surging demand for high performance materials in lithium ion batteries, LEDs, and semiconductor applications, where ultra-high purity alumina is essential for enhancing efficiency, durability, and product performance.
Asia Pacific dominated the global high purity alumina market with revenue share of 75.3% in 2025.
The high purity alumina market size was estimated at USD 5.6 billion in 2025 and is expected to reach USD 6.8 billion in 2026.
Based on application, LED accounted for the largest revenue share of 49.9% in 2025, while semiconductor registered a CAGR of 24.2% over the forecast period.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


