
- Home
- »
- Healthcare IT
- »
-
Hospital-at-Home Monitoring & Care Technologies Market Report 2033GVR Report cover

Hospital-at-Home Monitoring & Care Technologies Market (2026 - 2033)
Size, Share & Trends Analysis Report By Technology (Monitoring, Respiratory Care Technologies, Digital Care Technologies), By End Use, By Region, And Segment Forecasts
Market Size, 2025
$25.2BMarket Estimate, 2026
$27.8BMarket Forecast, 2033
$59.3BCAGR, 2026–2033
11.4%Hospital-at-Home Monitoring & Care Technologies Market Summary
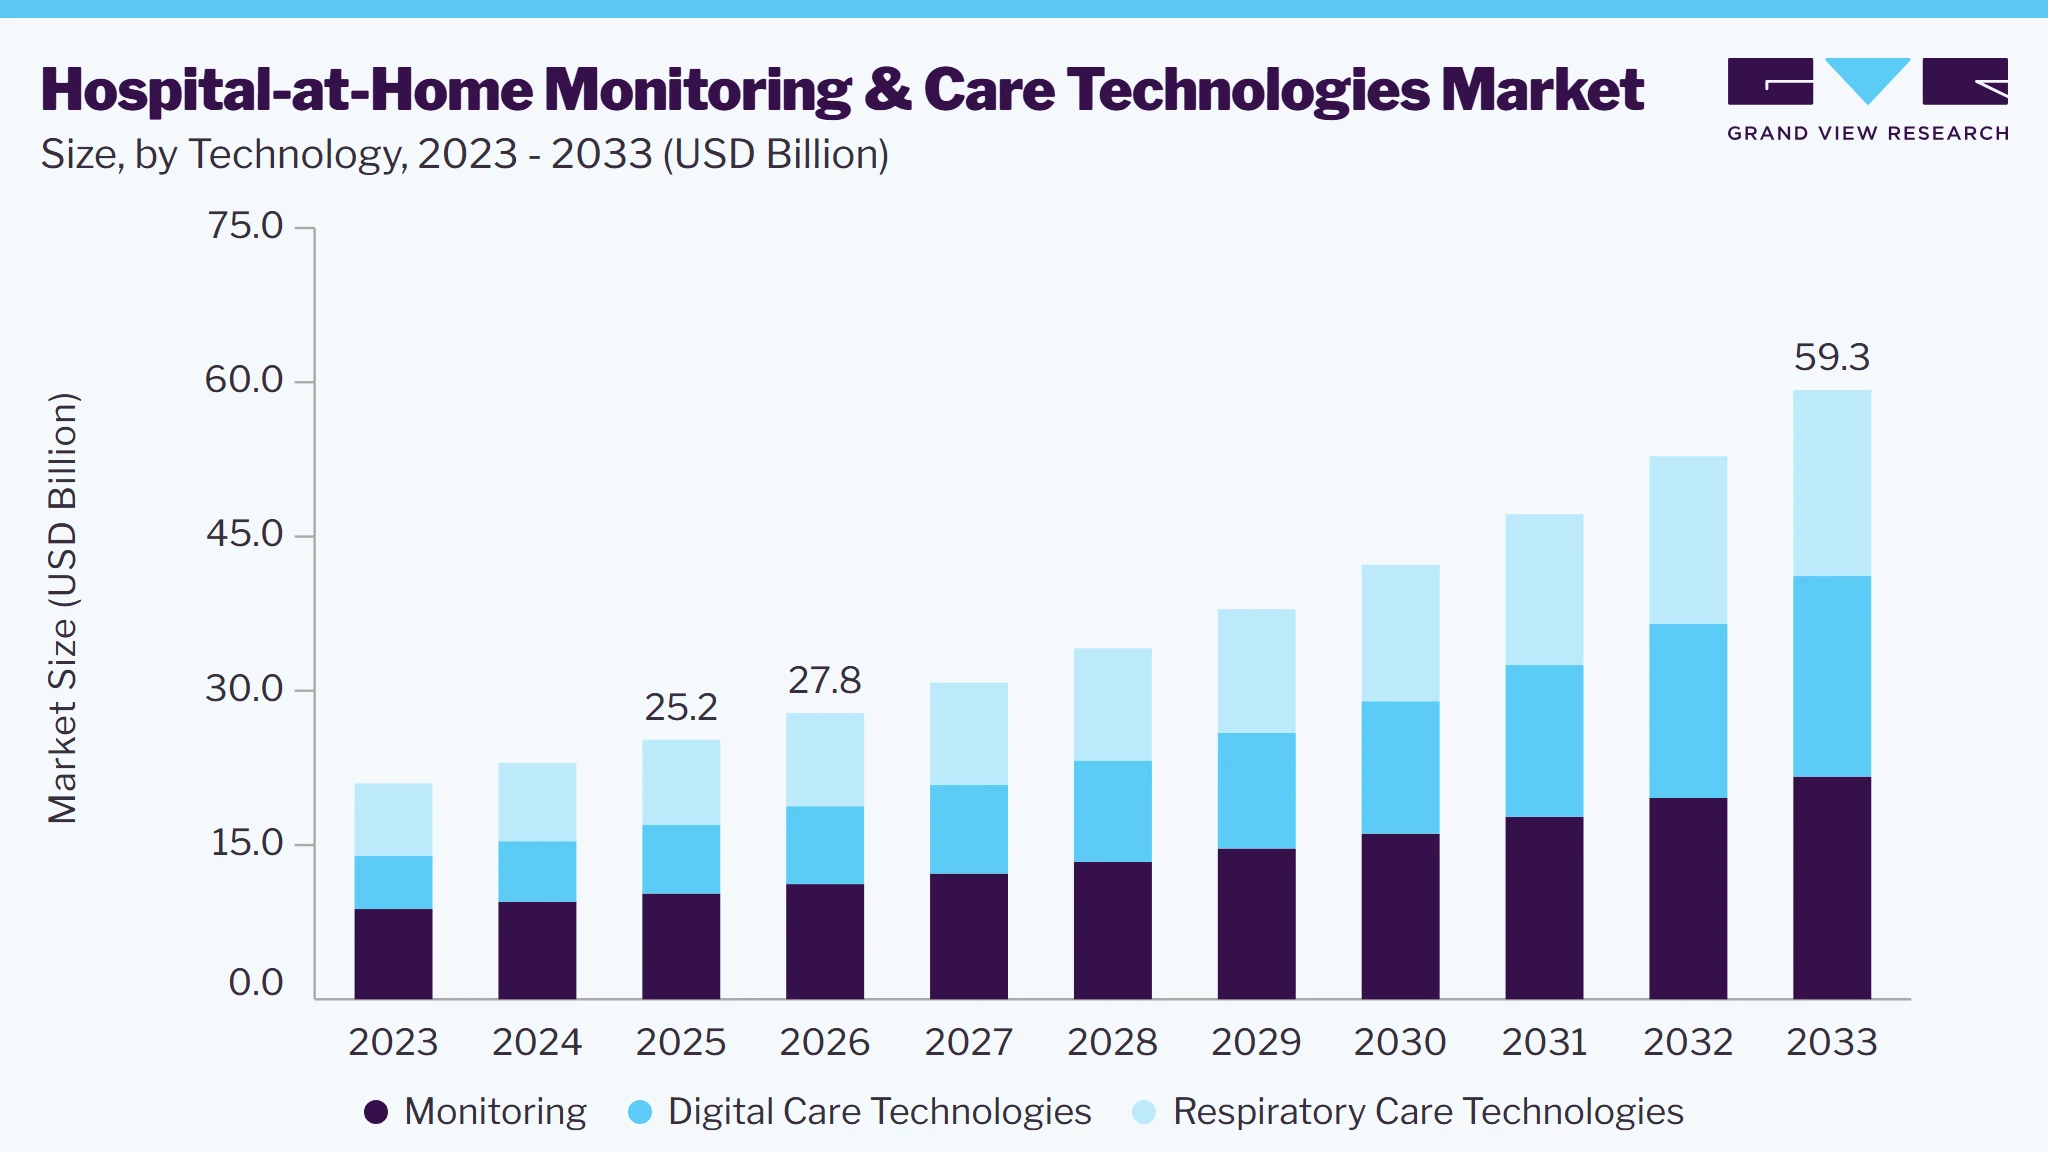
The global hospital-at-home monitoring & care technologies market size was valued at USD 25.2 billion in 2025 and is projected to grow from USD 27.8 billion in 2026 to USD 59.3 billion by 2033, at a CAGR of 11.4% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 40.4% in 2025. This growth is attributed to the growing need to reduce hospital bed pressure, rising adoption of remote monitoring and connected care technologies, and increasing demand for cost-efficient acute care delivery at home.
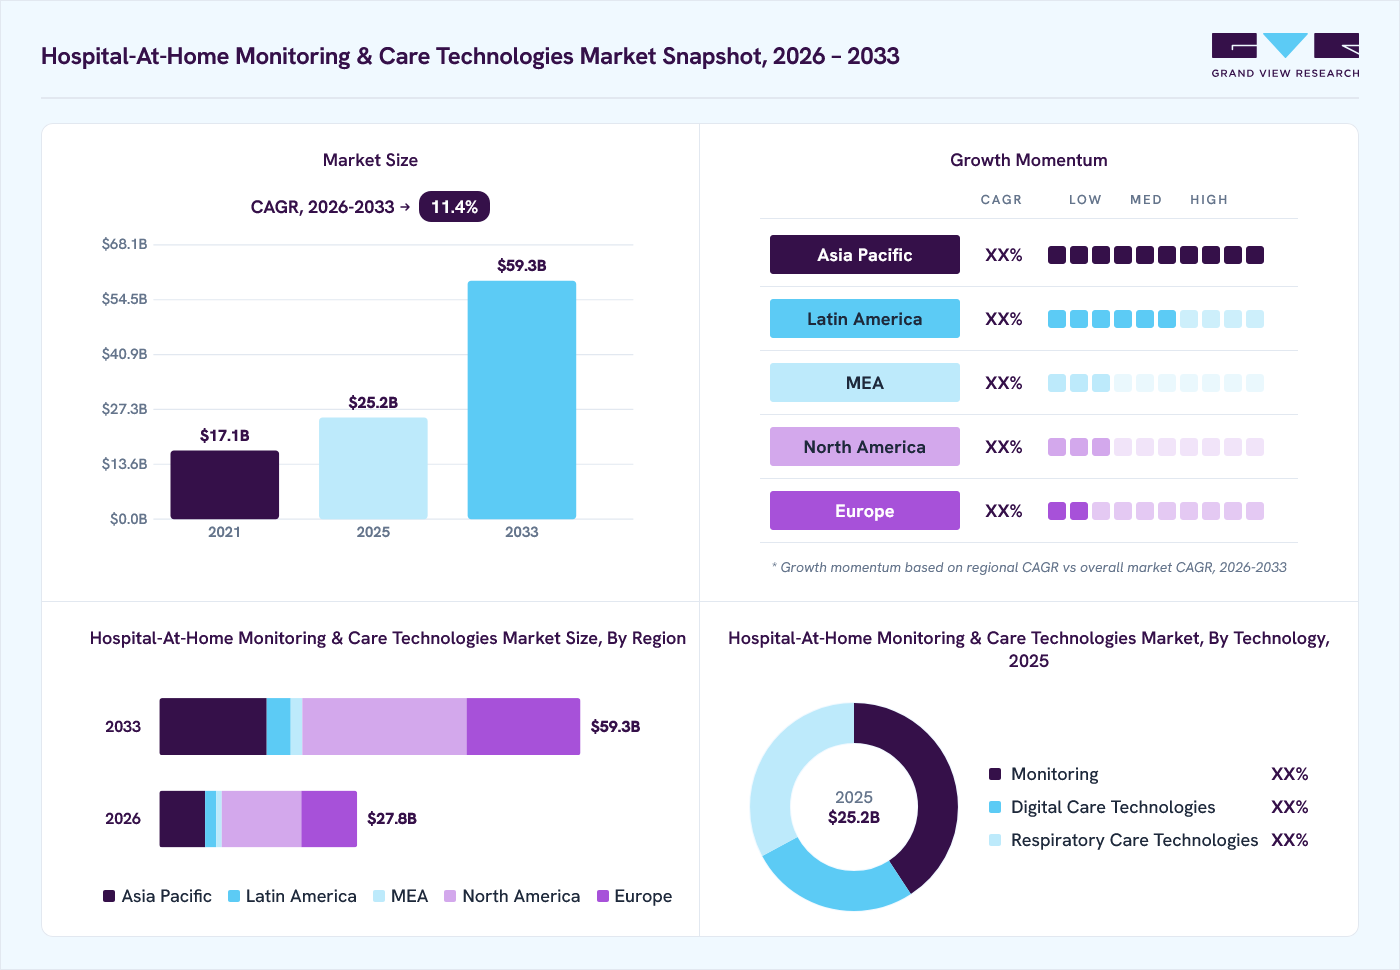 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By technology: The monitoring technologies segment held the largest market share of 40.8% in 2025.
- By end use: The hospital segment dominated the market with a revenue share of 58.0% in 2025.
Regional Highlights
- Largest regional market: North America (40.4% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 25.2 Billion
- Estimated market size in 2026: USD 27.8 Billion
- Projected market size by 2033: USD 59.3 Billion
- CAGR (2026-2033): 11.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
 To learn more about this report, Download Free Sample Report
Market Dynamic
The hospital-at-home monitoring & care technologies market is driven by hospital capacity constraints, increasing adoption of hospital-at-home and virtual ward models, rising chronic disease burden, and growing demand for continuous patient monitoring and early deterioration detection. Advancements in AI-enabled analytics, wearable sensors, wireless connectivity, and digital care platforms are further supporting adoption. However, high technology costs, data privacy and cybersecurity concerns, interoperability challenges, connectivity limitations, and regulatory requirements may restrain market growth.
The increasing adoption of wearable sensors, connected vital-sign monitors, remote patient monitoring (RPM) platforms, telehealth, and digital clinical dashboards is supporting the expansion of hospital-at-home programs. These technologies allow healthcare professionals to remotely monitor patients' physiological parameters, identify changes in condition, and intervene when required, making it more feasible to provide hospital-level care outside traditional hospital settings. For instance, in May 2026, Philips announced that a Philips-led consortium was selected by Region Stockholm to provide advanced remote monitoring for its hospital-at-home initiative. The program is designed to support hospital-level care for complex patients at home and likely to use remote-monitoring technologies and digitally connected care pathways for up to 15,000 patients annually. This highlights how connected monitoring and digital care technologies are enabling hospital-at-home expansion and driving market demand.
High Technology and Implementation Costs is a significant restraint in the market due to the substantial investment required for connected monitoring devices, respiratory equipment, digital platforms, connectivity, EHR integration, and cybersecurity infrastructure. These requirements increase the initial implementation costs for healthcare providers.
Moreover, ongoing expenses for device maintenance, software integration, technical support, and staff training can increase the total cost of ownership, which may limit adoption among smaller healthcare organizations.
Integration of AI-enabled technologies is a significant opportunity in the Hospital-at-Home Monitoring & Care Technologies Market due to the ability of AI to analyze continuous physiological data, identify early signs of patient deterioration, generate predictive insights, and support timely clinical intervention. AI can strengthen remote monitoring and enable healthcare providers to manage higher-acuity patients at home.
Leading companies are integrating AI with connected monitoring and digital care technologies to improve patient surveillance and clinical decision-making.
Company
Product / Platform
AI integration
Biofourmis
Biovitals HospitalHome / Biovitals Analytics Engine
Specifically designed for acute hospital-level care at home and combines continuous monitoring with AI-based analytics.
Koninklijke Philips N.V.
Hospital-at-Home solution + Respiree 1Bio
AI analysis of continuous cardio-respiratory data to identify physiological changes and support early detection of deterioration in patients monitored outside the hospital.
VitalConnect
VitalPatch + VistaCenter / Cardiac Monitoring
AI-based ECG analysis and detection of 21 cardiac arrhythmias, supporting continuous cardiac monitoring and clinical notification. The VitalConnect solution is also used for Hospital-at-Home monitoring.
Market Concentration & Characteristics
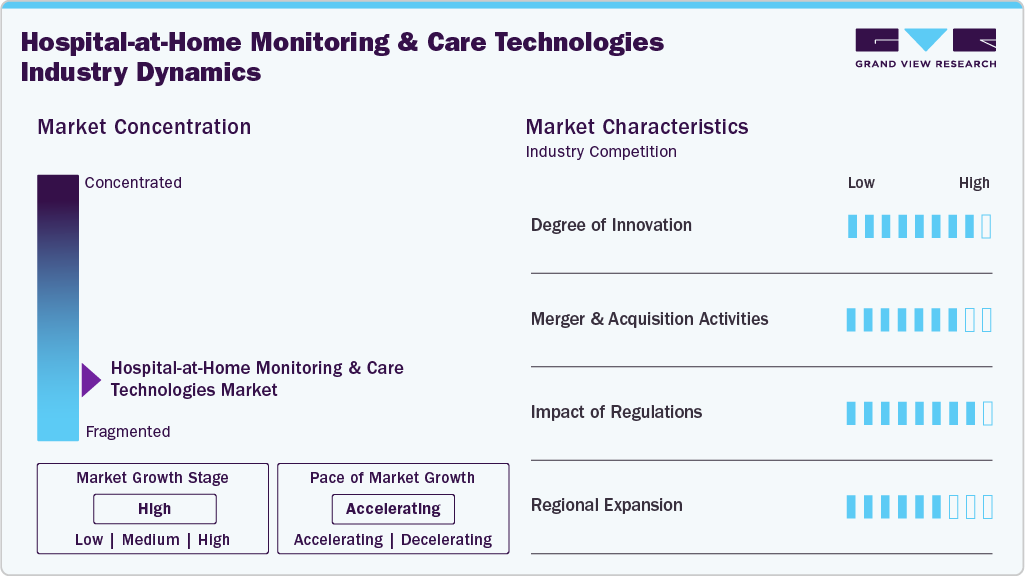
The degree of innovation in the hospital-at-home monitoring & care technologies market is high, driven by advances in multimodal wearable monitors that continuously capture multiple physiological parameters and transmit data to clinicians, enabling remote monitoring and early detection of patient deterioration. For instance, in July 2026, LifeLens Technologies received FDA 510(k) clearance for expanded indications of its Wearable Physiological Monitoring system, adding SpO₂, heart rate, respiratory rate, heart rate variability, and skin temperature to ECG monitoring. This highlights the shift toward multimodal patches for continuous monitoring in home-based care.
"Managing complex disease requires monitoring solutions that deliver the breadth of clinical, environmental, and contextual data needed to make informed treatment decisions" But breadth alone isn't enough, the data has to be trusted. This clearance, along with multiple actively enrolling clinical studies, reflects our commitment to closing that confidence gap with clinical validation and FDA regulatory review. We're building the evidence base that turns continuous physiological data into meaningful clinical insight."
Landy Toth, founder and CEO of LifeLens.
The level of merger and acquisitions activities in the market is high, as companies seek to strengthen patient-monitoring portfolios, expand technological capabilities, and access advanced sensing and AI-enabled technologies. M&A activity is also expanding capabilities across acute and home-based care. For instance, in June 2026, Danaher completed its acquisition of Masimo Corporation, a patient-monitoring company specializing in pulse oximetry, sensors, and other monitoring technologies. The acquisition added AI-enabled patient monitoring capabilities to Danaher's diagnostics portfolio and is expected to strengthen its presence in acute-care monitoring.
 To learn more about this report, Download Free Sample Report
The impact of regulations is significant in this market, as connected medical devices and digital platforms must meet requirements for safety, performance, clinical validation, cybersecurity, and data privacy. In the U.S., applicable medical devices require FDA clearance or approval, while in Europe, manufacturers must comply with the EU Medical Device Regulation (MDR) and applicable data protection requirements. In China, medical devices are regulated by the National Medical Products Administration (NMPA), with Class II and Class III devices generally requiring registration and compliance with safety, effectiveness, quality, and clinical evaluation requirements before commercialization.
The regional expansion of the hospital-at-home monitoring & care technologies market is significant, supported by growing healthcare digitization, increasing demand for home-based care, and improving healthcare infrastructure across emerging markets. Key players are expanding through regional partnerships, distribution networks, regulatory approvals, and localized product launches to increase access to connected monitoring and digital care technologies.
Analyst Perspective
The hospital-at-home monitoring & care technologies market is driven by the rising adoption of physiological monitoring wearable sensors, wireless connectivity, and AI-enabled analytics. Adoption is shifting toward multimodal, continuous, and clinically validated technologies that enable remote monitoring and earlier detection of patient deterioration. Market players such as Medtronic, GE HealthCare, Philips, ResMed, Mindray, Huma, Doccla, Biofourmis, VitalConnect, and VivaLNK are strengthening their portfolios through wearable monitoring, AI-enabled analytics, digital care platforms, product innovation, partnerships, and expansion into home-based care. Competition remains high as medical-device and digital players leverage clinical expertise, distribution networks, continuous monitoring, AI, and integrated hospital-to-home solutions.
Technology Insights
The monitoring segment dominated the market with a revenue share of 40.8% in 2025. The segment dominance is due to increasing use of wearable and connected devices to continuously measure ECG, heart rate, SpO₂, blood pressure, temperature, and respiratory rate in patients receiving care at home, providing clinicians with real-time physiological data for early intervention. Advances in multimodal sensors, wireless connectivity, miniaturized devices, and continuous monitoring technologies also drive market growth. For instance, in March 2026, Current Health partnered with Cardinal Health’s Velocare to support hospital-at-home programs through the delivery, installation, and retrieval of Current Health’s in-home clinical monitoring kits. The collaboration supports continuous monitoring, clinical outreach, and timely escalation, highlighting the growing use of connected monitoring in hospital-at-home care.
The digital care technologies segment is expected to grow at the fastest CAGR from 2026 to 2033. Growth is driven by increasing adoption of RPM platforms, virtual wards, telehealth, clinical alerting, AI-based analytics, and patient engagement solutions. These technologies integrate patient data, enable remote communication with care teams, and support digital clinical workflows. Growth is further supported by the need to scale hospital-at-home programs, with AI-enabled analytics, automated alerts, and digital care pathways helping clinicians identify deterioration earlier and coordinate patient care more efficiently.
End Use Insights
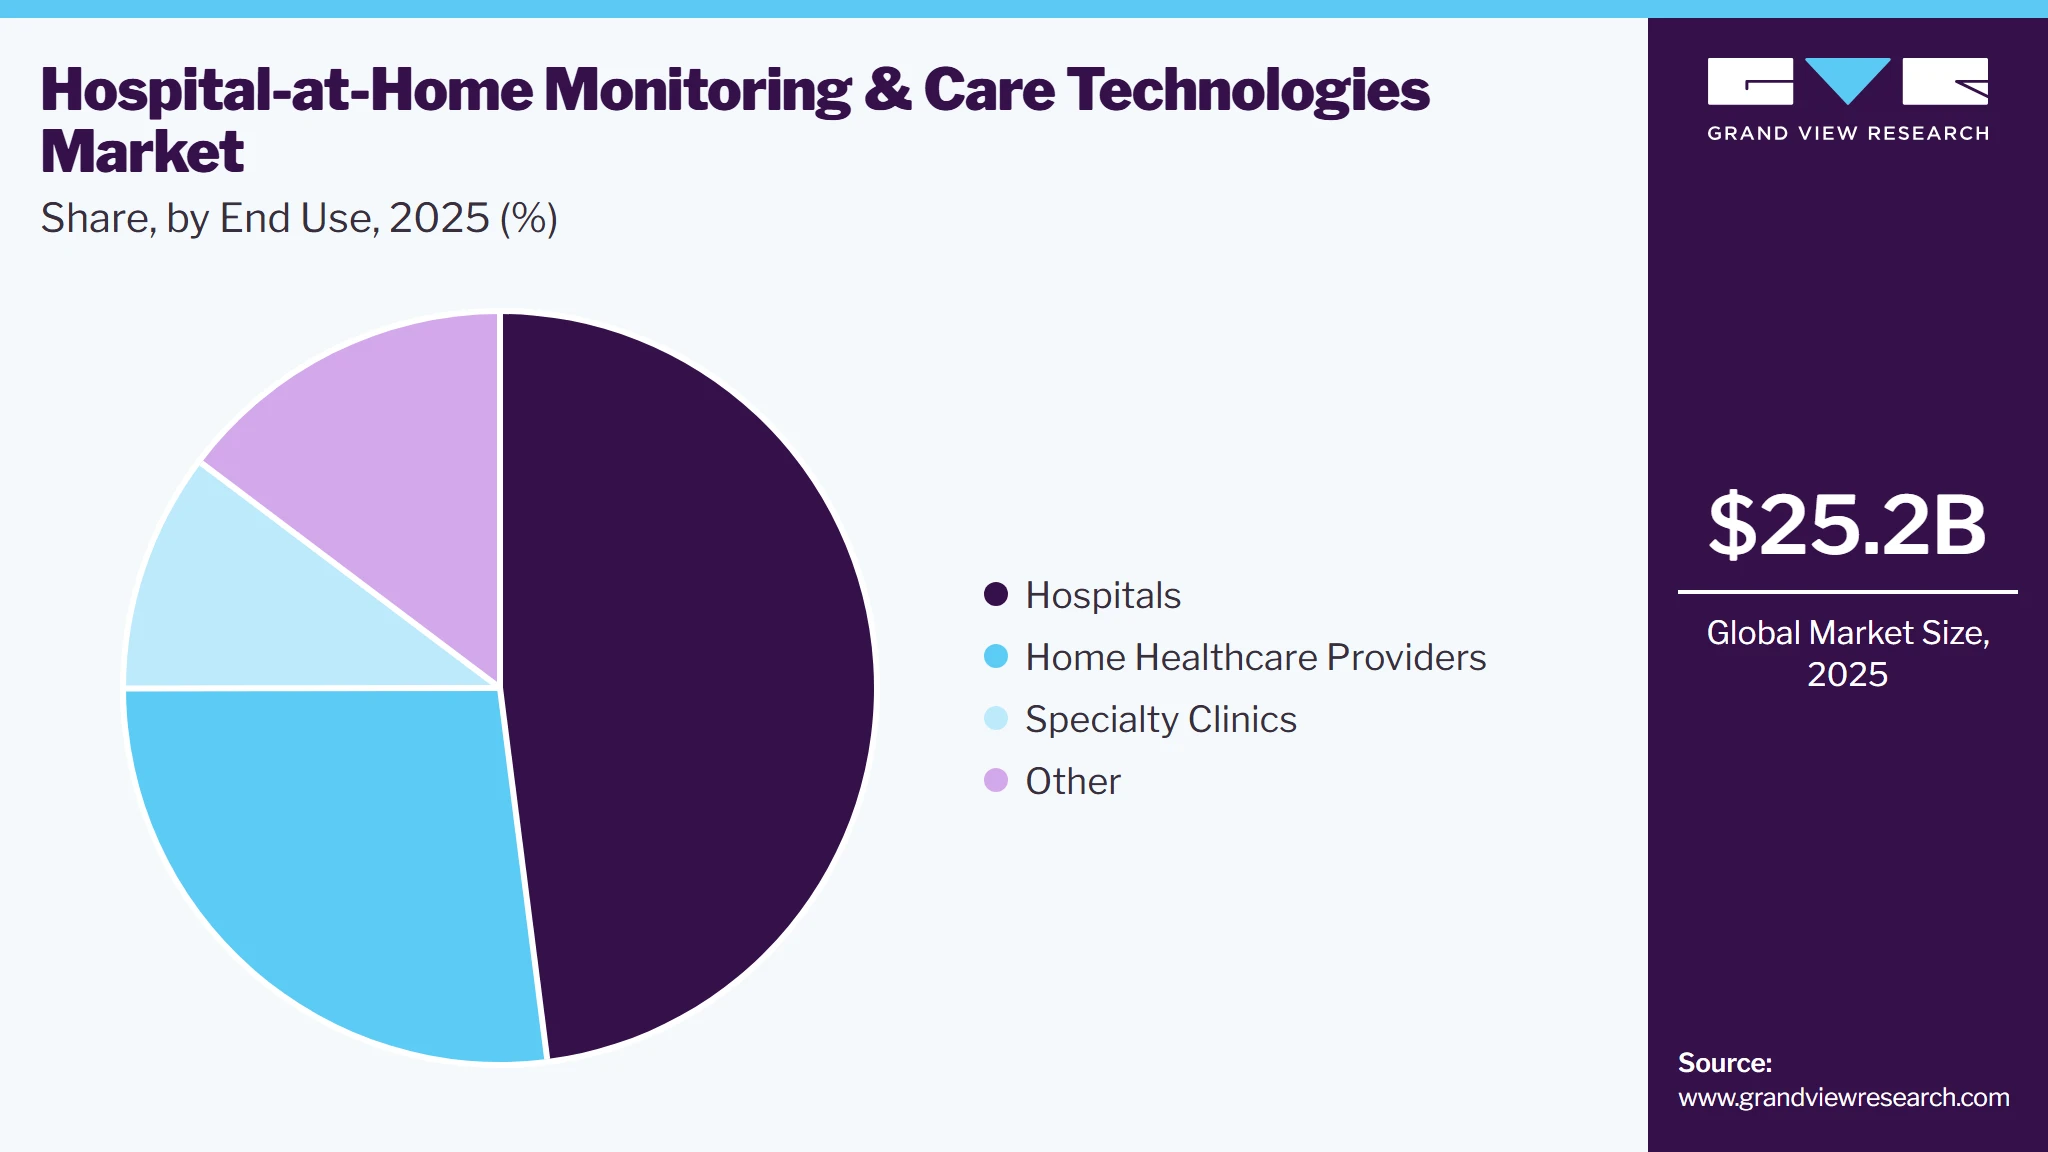
The hospitals segment held the largest revenue share of 58.0% in 2025. This dominance is driven by hospitals expanding hospital-at-home programs to extend acute and post-acute care beyond traditional inpatient settings while maintaining clinical oversight through remote monitoring and digital care technologies. The increasing use of connected monitoring devices, virtual wards, and integrated clinical platforms is strengthening hospitals' ability to monitor patients remotely and manage care transitions.
 To learn more about this report, Download Free Sample Report
The home healthcare provider segment is expected to grow at the fastest CAGR of 12.9% during the forecast period. This growth is driven by the expansion of home-based acute care, remote patient monitoring, and technology-enabled clinical services. These providers increasingly combine skilled nursing and home-care services with connected monitoring, telehealth, and digital care platforms, creating greater demand for hospital-at-home technologies.
Regional Insights
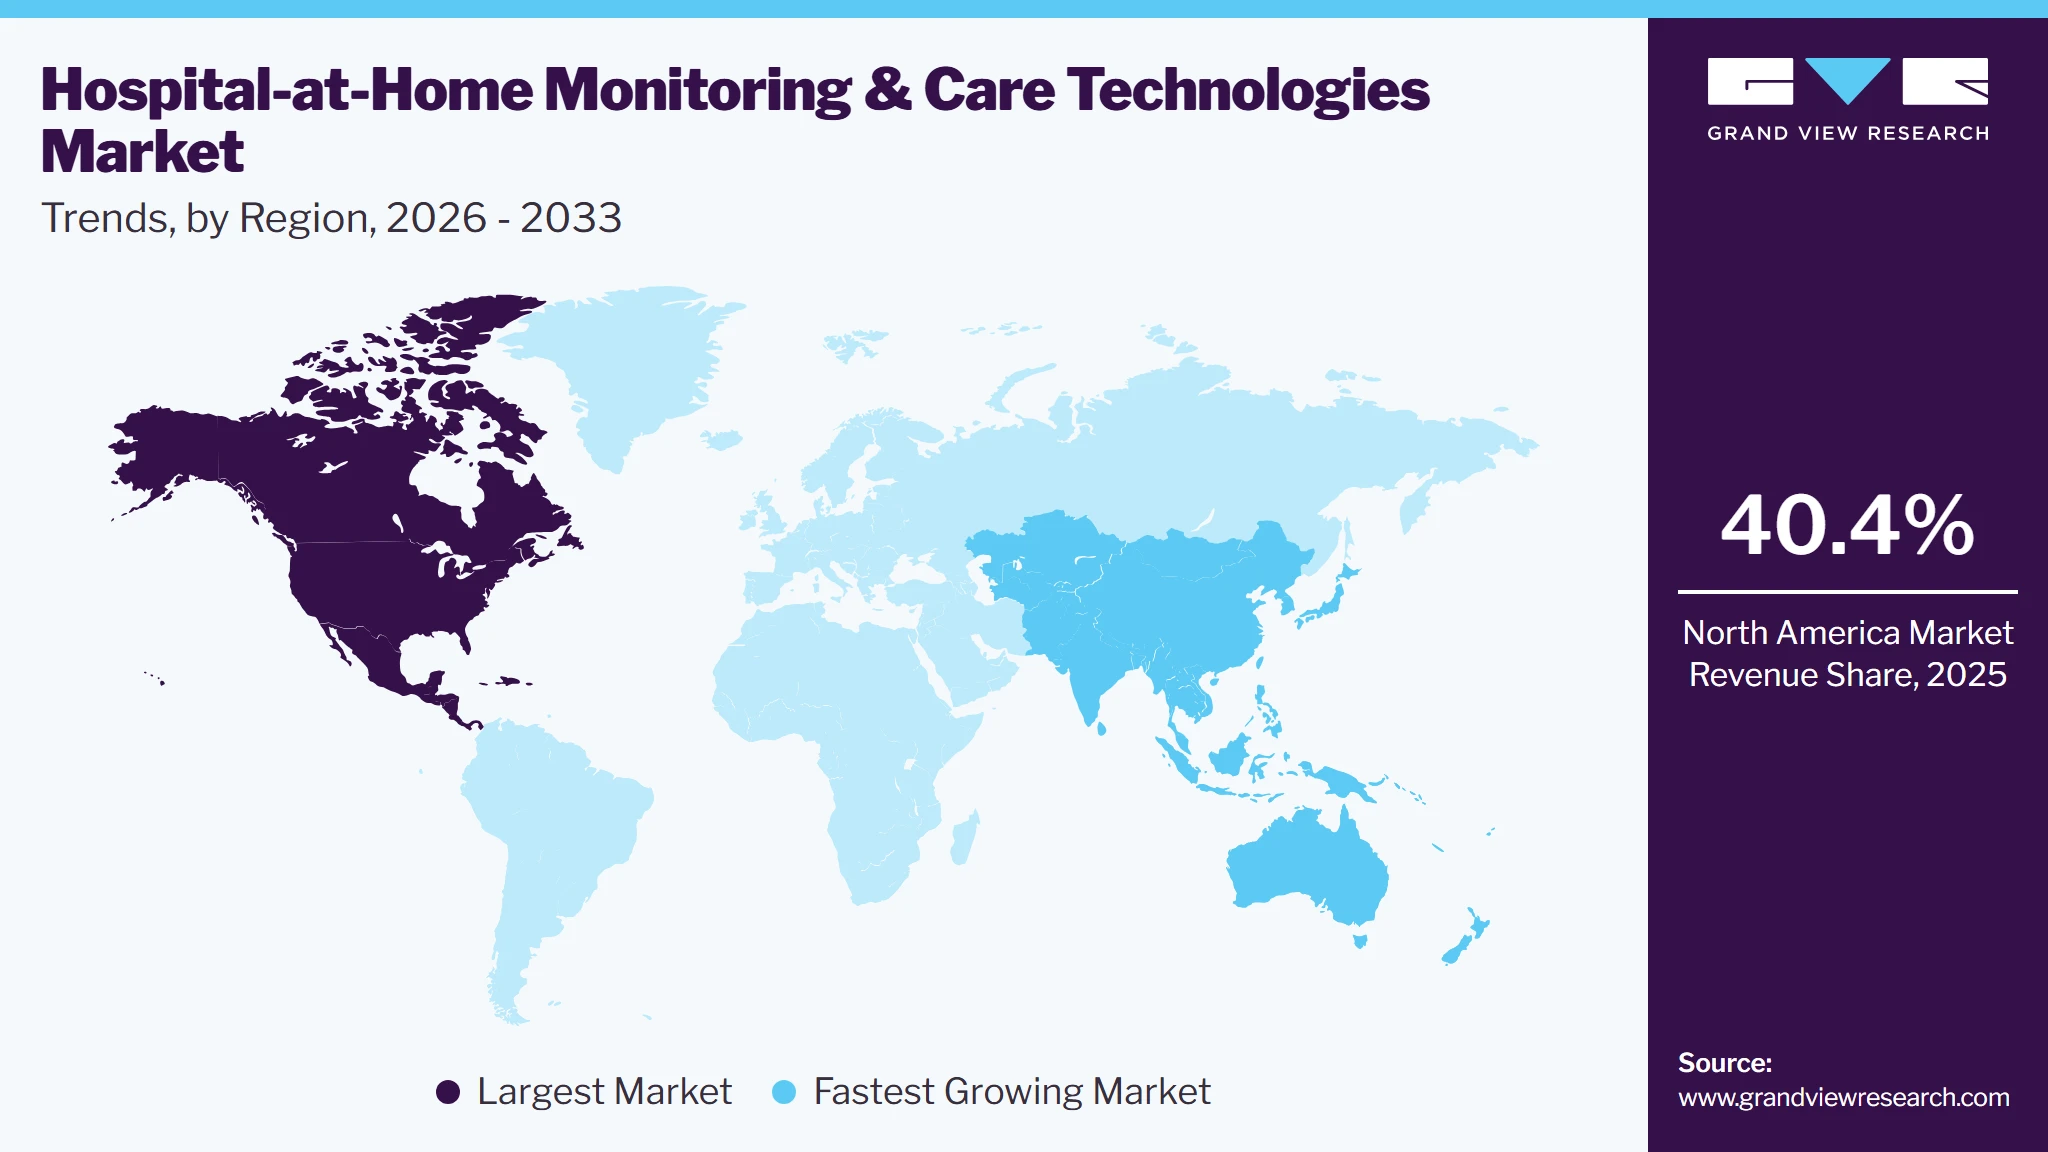
North America hospital-at-home monitoring & care technologies market dominated the global market with a revenue share of 40.4% in 2025. This dominance is due to the advanced healthcare infrastructure, established remote patient monitoring, high healthcare expenditure, and strong adoption of connected monitoring technologies. Key players include Medtronic, GE HealthCare, Philips, ResMed, Mindray, Huma, Doccla, Biofourmis, VitalConnect, and VivaLNK strengthening the market in the region. For instance, in August 2026, iRhythm announced an agreement to acquire VitalConnect for approximately USD 287.5 million, thereby expanding its cardiac monitoring portfolio across ambulatory, inpatient, and hospital-to-home care settings.
 To learn more about this report, Download Free Sample Report
U.S. Hospital-at-Home Monitoring & Care Technologies Market Trends
The U.S. dominated the North America market in 2025, supported by high healthcare expenditure, chronic disease prevalence, established remote patient monitoring practices, and advanced healthcare infrastructure. The presence of major players, including Medtronic, GE HealthCare, Philips, ResMed, Mindray, Huma, Doccla, Biofourmis, VitalConnect, and VivaLNK, further supports market development. For instance, in July 2026, Dexcom was selected as the first participant in the FDA's TEMPO Digital Health Devices Pilot Program, supporting the integration of Dexcom G7 and Stelo data with contextual health information and AI-powered insights for chronic disease management. This development highlights the growing integration of AI and connected monitoring technologies into U.S. digital healthcare.
Europe Hospital-at-Home Monitoring & Care Technologies Market Trends
Hospital-at-home monitoring & care technologies market in Europe held a significant share of the global market in 2025, supported by aging populations, chronic disease prevalence, established healthcare infrastructure, and growing adoption of remote monitoring and virtual care. For instance, in August 2026, Philips announced collaborations with Blue Spark Technologies, Caretaker Medical, Cuviva, LifeSignals, Respiree, and smartQare to expand its open patient-monitoring ecosystem, integrating wearable and out-of-hospital technologies for continuous patient monitoring from hospital to home. This development supports continuous patient monitoring during hospital-to-home transitions and recovery at home.
Hospital-at-home monitoring & care technologies market in UK supported by established healthcare infrastructure, an aging population, chronic disease burden, and the NHS's focus on virtual wards and home-based care. Increasing adoption of remote patient monitoring and connected technologies is supporting demand for continuous ECG, glucose, respiratory, and multimodal monitoring. The expansion of virtual wards and digital care pathways is expected to further support market growth.
Germany hospital-at-home monitoring & care technologies market is driven by the advanced healthcare infrastructure, an aging population, high healthcare expenditure, and a strong medical-device industry drive the market growth. Increasing demand for continuous monitoring and home-based care is supporting adoption of clinical-grade wearable technologies. Growing integration of connected monitoring devices with healthcare workflows is expected to further support market expansion.
Asia Pacific Hospital-at-Home Monitoring & Care Technologies Market Trends
Asia Pacific is expected to grow at the fastest CAGR of 12.9% from 2026 to 2033. Market growth is due to by expanding healthcare infrastructure, increasing chronic disease prevalence, and rising adoption of remote and connected patient monitoring. For instance, Vivalink provides clinically validated wearable monitoring technologies that continuously measure parameters such as ECG, heart rate, respiratory rate, SpO₂, and temperature, supporting remote patient monitoring across healthcare settings.
Hospital-at-home monitoring & care technologies market in Japan is driven by strong healthcare infrastructure, an aging population, high healthcare expenditure, and a well-established medical-device industry. The increasing need for continuous monitoring of older adults and patients with chronic conditions is supporting demand for connected and clinical-grade wearable technologies. Growing adoption of digital healthcare and remote monitoring is expected to further support market growth.
Hospital-at-home monitoring & care technologies market in China represents a significant growth opportunity, driven by its large patient population, expanding healthcare infrastructure, increasing chronic disease burden, and growing healthcare digitization. Investments in digital health and remote patient monitoring are increasing demand for continuous physiological monitoring technologies, while domestic and international medical-device manufacturers are expanding the availability of connected monitoring solutions.
Latin America Hospital-at-Home Monitoring & Care Technologies Market Trends
Hospital-at-home monitoring & care technologies market in Latin America is expected to grow significantly, driven by healthcare digitization, rising chronic disease prevalence, increasing adoption of remote patient monitoring, and improving healthcare infrastructure. Growing use of home-based care and connected healthcare technologies is supporting demand for wearable ECG, glucose, respiratory, and multimodal monitoring solutions.
Middle East & Africa Hospital-at-Home Monitoring & Care Technologies Market Trends
Hospital-at-home monitoring & care technologies market in Middle East & Africa is driven by healthcare modernization, increasing healthcare investments, digital health adoption, and growing demand for remote patient monitoring. Expanding healthcare infrastructure and home-based care are creating opportunities for connected physiological monitoring, wearable ECG, pulse oximetry, glucose, and multimodal monitoring technologies.
Key Hospital-at-Home Monitoring & Care Technologies Company Insights
Key players in the hospital-at-home monitoring & care technologies market are strengthening their positions through strategic partnerships, and geographic expansion. Major companies such as Medtronic, Koninklijke Philips N.V., GE HealthCare Technologies Inc., ResMed Inc., and Biofourmis, Inc. are expanding capabilities across hospital-to-home monitoring and remote care.
Key Hospital-at-Home Monitoring & Care Technologies Companies
The following key companies have been profiled for this study on the hospital-at-home monitoring & care technologies market.
Product Categories - Key Companies
Monitoring Technologies
Respiratory Care Technologies
Digital Care Technologies
- Medtronic
- GE HealthCare Technologies Inc.
- Koninklijke Philips N.V.
- ResMed Inc.
- Shenzhen Mindray Bio-Medical Electronics Co., Ltd.
- Masimo Corporation (Danaher)
- Fisher & Paykel Healthcare Limited
- Resmed
- Breas Medical AB
- Inogen, Inc.
- BMC Medical Co., Ltd.
- Drive|DeVilbiss Healthcare, Inc.
- Huma Therapeutics Limited
- Doccla Limited
- Biofourmis, Inc.
- VitalConnect, Inc.( iRhythm Technologies)
- VivaLNK, Inc
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Medtronic, GE HealthCare Technologies Inc., Koninklijke Philips N.V., Fisher & Paykel Healthcare Limited)
- Expand connected monitoring and respiratory-care portfolios, integrate AI and digital technologies, strengthen hospital and home-care partnerships, and expand distribution.
- Established clinical brands, broad product portfolios, strong R&D capabilities, regulatory expertise, healthcare-provider relationships, and extensive distribution networks.
- High development and regulatory costs, complex healthcare IT integration, dependence on reimbursement and clinical adoption, and competition from specialized technology providers.
Emerging Players (Huma Therapeutics Limited, Doccla Limited, Biofourmis, Inc., VitalConnect, Inc., Inogen, Inc., BMC Medical Co., Ltd., Drive DeVilbiss Healthcare, Inc.)
- Develop specialized remote monitoring, digital-care, wearable, and home respiratory technologies; expand AI-enabled analytics, target hospital-at-home applications, strengthen strategic partnerships, and enter new geographic markets.
- Specialized technologies, continuous physiological monitoring, digital-care capabilities, focused respiratory solutions, flexible product development, and targeted clinical applications.
- Smaller distribution networks, lower brand recognition, narrower portfolios in some segments, limited resources compared with major medtech companies, and dependence on regulatory approvals and strategic partnerships.
Recent Developments
-
In August 2026, Empatica received FDA 510(k) clearance for its Health Monitoring Platform for Parkinson's, which combines clinical-grade wearables, digital biomarkers, and connected monitoring to continuously assess symptoms including bradykinesia, dyskinesia, tremor, sleep, and medication compliance. This development highlights the expansion of wearable and digital monitoring technologies into remote neurological disease management.
"Wearable monitoring enhances our understanding of how Parkinson's symptoms change daily and respond to treatment, Bringing objective, real-world data into clinical care can assist clinicians in making more informed, personalized decisions and better support people living with Parkinson's."
Ritesh Ramdhani, MD, Associate Professor of Neurology and Director of the Deep Brain Stimulation Program
-
In May 2026, Johnson & Johnson highlighted the use of remote patient monitoring and AI-powered approaches to collect patient data through wearables and apps, providing healthcare providers with real-time insights to support more timely treatment decisions.
-
In March 2026, Philips partnered with Cuviva to integrate remote patient monitoring and patient-engagement technologies into its monitoring ecosystem, enabling physiological data from connected devices to be securely transmitted to clinicians through cloud-based dashboards and supporting Hospital-at-Home care.
-
In October 2024, BioIntelliSense received FDA clearance for its BioButton Multi-Patient wearable and BioDashboard system for continuous patient monitoring. The medical-grade wearable enables automated collection of vital signs for continuous monitoring across hospital units and hospital-level care at home.
Hospital-at-Home Monitoring & Care Technologies Market Report Scope
Report Attribute
Details
Market size in 2025
USD 25.2 billion
Estimated market size in 2026
USD 27.8 billion
Projected market size by 2033
USD 59.3 billion
Growth rate
CAGR of 11.4% from 2026 to 2033
Actual data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Market Value in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Technology, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait
Key companies profiled
Medtronic; GE HealthCare Technologies Inc.; Koninklijke Philips N.V.; ResMed Inc.; Shenzhen Mindray Bio-Medical Electronics Co., Ltd.; Huma Therapeutics Limited; Doccla Limited; Biofourmis, Inc.; VitalConnect, Inc.; VivaLNK, Inc.; Fisher & Paykel Healthcare Limited; Breas Medical AB; Inogen, Inc.; BMC Medical Co., Ltd.; Drive|DeVilbiss Healthcare, Inc.; Masimo Corporation (Danaher)
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Hospital-at-Home Monitoring & Care Technologies Market Report Segmentation
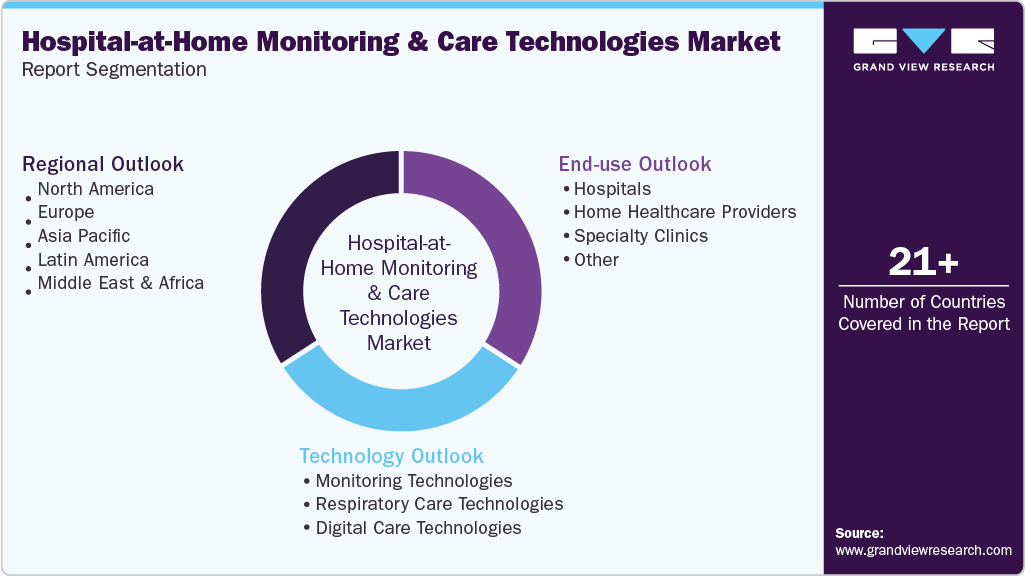
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global hospital-at-home monitoring & care technologiesmarket report based on technology, end use, and regions.
 To learn more about this report, Download Free Sample Report
-
Technology Outlook (Revenue, USD Billion, 2021 - 2033)
-
Monitoring Technologies
-
Multiparameter Patient Monitors
-
Pulse Oximeters
-
ECG Monitors
-
Blood Pressure Monitors
-
Temperature Monitors
-
Respiratory Rate Monitors
-
Wearable Patient Monitors
-
Continuous Monitoring Patches
-
-
Respiratory Care Technologies
-
Positive Airway Pressure (PAP) Devices
-
Non-Invasive Ventilation Devices
-
Invasive Ventilation Devices
-
Oxygen Concentrators
-
Nebulizers
-
-
Digital Care Technologies
-
RPM Platforms
-
Virtual Nursing Platforms
-
Telehealth & Platforms
-
Clinical Alert & Escalation Systems
-
AI-Based Deterioration Prediction
-
Patient Engagement Platforms
-
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Hospitals
-
Home Healthcare Providers
-
Specialty Clinics
-
Other
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The hospital-at-home monitoring & care technologies market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each hospital-at-home monitoring & care technologies segment quantified using the revenue-capture definitions in the table below.
Market Definition- Hospital-at-Home Monitoring & Care Technologies market includes devices, software, connectivity, and digital tools that enable healthcare professionals to remotely monitor and support patients receiving hospital-level or acute care at home. The market covers technologies for physiological monitoring, respiratory support, clinical alerting, and digital care coordination. Market revenue is captured from the sale, licensing, subscription, and deployment of these technologies.
Segment Definition
Segment- Technology
Revenue Capture Definition
Monitoring Technologies
Revenue generated from technologies used to continuously or intermittently monitor physiological parameters in hospital-at-home and home-based care settings.
- Multiparameter Patient Monitors : Revenue generated from monitors that simultaneously measure multiple physiological parameters, such as ECG, SpO₂, blood pressure, temperature, and respiratory rate, for remote patient monitoring.
- Pulse Oximeters: Revenue generated from devices used to measure blood oxygen saturation (SpO₂) and pulse rate in patients receiving home-based care.
- ECG Monitors: Revenue generated from devices used to record and monitor cardiac electrical activity and identify abnormalities or arrhythmias remotely.
- Blood Pressure Monitors: Revenue generated from devices used to measure and transmit systolic and diastolic blood pressure for remote clinical monitoring.
- Temperature Monitors: Revenue generated from devices used to continuously or intermittently measure and transmit patient body temperature.
- Respiratory Rate Monitors: Revenue generated from devices used to measure and monitor the patient's breathing rate remotely.
- Wearable Patient Monitors: Revenue generated from wearable devices that continuously or intermittently capture one or more physiological parameters for remote clinical monitoring.
- Continuous Monitoring Patches: Revenue generated from adhesive or skin-worn monitoring patches designed to continuously capture physiological parameters and transmit patient data to healthcare professionals.
Respiratory Care Technologies
Revenue generated from respiratory care devices used to support patients receiving acute or chronic care at home, including oxygen concentrators, PAP devices, non-invasive ventilation (NIV) devices, invasive ventilation devices, and nebulizers.
- Respiratory Care Technologies: Revenue generated from respiratory devices used to provide monitoring, respiratory support, and therapy to patients receiving hospital-at-home or home-based care.
- Positive Airway Pressure (PAP) Devices: Revenue generated from devices that deliver positive airway pressure to maintain airway patency during breathing, including CPAP and APAP devices.
- Non-Invasive Ventilation Devices: Revenue generated from devices that provide ventilatory support through a mask or other non-invasive interface without an invasive airway.
- Invasive Ventilation Devices: Revenue generated from mechanical ventilators that provide respiratory support through an artificial airway, such as an endotracheal or tracheostomy tube.
- Oxygen Concentrators: Revenue generated from devices that extract and concentrate oxygen from ambient air for supplemental oxygen therapy at home.
- Nebulizers: Revenue generated from devices that convert liquid medication into an aerosol for inhalation during respiratory treatment.
Digital Care Technologies
Revenue generated from software, digital platforms, and connected-care solutions that enable remote monitoring, clinical communication, care coordination, decision support, and patient engagement in hospital-at-home settings.
- RPM Platforms: Revenue generated from software platforms that collect, transmit, integrate, and display patient physiological and clinical data for remote monitoring.
- Virtual Nursing Platforms: Revenue generated from digital platforms that enable nurses to remotely assess, communicate with, educate, and support patients through virtual care workflows.
- Telehealth Platforms : Revenue generated from platforms enabling remote consultations and communication between patients and healthcare professionals through video, audio, messaging, or other digital channels.
- Clinical Alert & Escalation Systems: Revenue generated from systems that identify abnormal patient readings or clinical events and generate alerts or escalation notifications for healthcare professionals.
- AI-Based Deterioration Prediction: Revenue generated from AI and predictive analytics solutions that analyze patient data to identify patterns associated with potential clinical deterioration and support early intervention.
- Patient Engagement Platforms: Revenue generated from digital platforms that enable patients to communicate with care teams, report symptoms, receive care instructions, complete assessments, and participate in care remotely.
Segment- End-use
Revenue Capture Definition
Hospitals
Revenue generated from technologies purchased or deployed by hospitals to monitor and manage patients receiving hospital-at-home or home-based acute care.
Home Healthcare Providers
Revenue generated from technologies used by home healthcare providers to deliver remote monitoring, respiratory care, and digitally enabled care in patients' homes.
Specialty Clinics
Revenue generated from technologies used by specialty clinics to remotely monitor and manage patients requiring disease-specific or post-acute care at home.
Other
Revenue generated from technologies used by other organizations, including ambulatory care providers, long-term care facilities, and healthcare technology service providers, for hospital-at-home and remote care delivery.
Estimation Model
Commodity Flow Analysis (Top Down)
Market size was estimated by analyzing revenues generated by individual market segments including monitoring, respiratory-care, and digital-care technology providers, supported by company annual reports, investor presentations, distributor insights, and industry databases.
Country-Level Segment Share Modeling
Country-level shares for Monitoring Technologies, Respiratory Care Technologies, Digital Care Technologies, and End Use were derived using hospital-at-home adoption, healthcare infrastructure, remote monitoring penetration, chronic disease burden, reimbursement conditions, and technology availability. Weighted averages were applied to determine regional and global segment distributions.
Data Triangulation & Validation Model
Market estimates were validated by triangulating secondary research, primary interviews, company-level revenue assessments, technology deployment data, healthcare-provider adoption, and demand-side analysis to ensure consistency across technologies, end uses, and geographies.
Forecasting & CAGR Modeling
Market forecasts were developed using hospital-at-home adoption, remote patient monitoring growth, chronic disease prevalence, healthcare expenditure, technology adoption, wearable and sensor innovation, AI integration, and regulatory developments. Trend and scenario-based modeling were applied to estimate future market growth and CAGR.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Emerging Technology & AI-Integrated Product Analysis
Assessment of newly launched and emerging technologies, including AI-integrated monitoring devices, multimodal wearable sensors, continuous monitoring patches, AI-enabled digital care platforms, and connected respiratory-care technologies across key market segments.
Identifies technology innovation trends, AI adoption, emerging product opportunities, technology gaps, and areas of differentiation, supporting product development, technology investment, and competitive strategy.
Competitive Positioning & Market Share Analysis
Analysis of market share by technology segments such as monitoring technologies, respiratory care technologies, and digital care technologies. Analysis strategic initiative such as product capabilities, geographic presence, partnerships, launches, and M&A activities.
Enables comparison of established and emerging players by technology segment, identifies competitive gaps and high-potential segments, and supports market expansion, portfolio optimization, and strategic positioning.
Regional Opportunity Analysis
Assessment of regional opportunities based on hospital-at-home adoption, remote patient monitoring penetration, healthcare expenditure, chronic disease burden, digital-health infrastructure, reimbursement environment, regulatory framework, and connected-device adoption across key countries and regions.
Helps identify high-growth markets, prioritize geographic expansion, optimize resource allocation, and identify opportunities across hospital, home healthcare, ambulatory, and long-term care settings.
Frequently Asked Questions About This Report
The global hospital-at-home monitoring & care technologies market size was estimated at USD 25.2 billion in 2025 and is expected to reach USD 27.8 billion in 2026.
North America dominated the market and accounted for a 40.4% share in 2025.
Key factors that are driving the market growth include the growing need to reduce hospital bed pressure, rising adoption of remote monitoring and connected care technologies, and increasing demand for cost-efficient acute care delivery at home
Some key players operating in the hospital-at-home monitoring & care technologies market include Medtronic, GE HealthCare Technologies Inc., Koninklijke Philips N.V., ResMed Inc., Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Huma Therapeutics Limited, Doccla Limited, Biofourmis, Inc., VitalConnect, Inc., VivaLNK, Inc., Fisher & Paykel Healthcare Limited, Breas Medical AB, Inogen, Inc., BMC Medical Co., Ltd., Drive|DeVilbiss Healthcare, Inc. Masimo Corporation (Danaher)
Asia Pacific is the fastest-growing region over the forecast period.
The global hospital-at-home monitoring & care technologies market is expected to grow at a compound annual growth rate of 11.4% from 2026 to 2033, reaching USD 59.3 billion by 2033.
The monitoring technologies segment held the largest market share of 40.8% in 2025 while digital care technologies segment is second fastest growing market.
The hospital segment dominated the market with a revenue share of 58.0% in 2025.This dominance is driven by hospitals expanding hospital-at-home programs to extend acute and post-acute care beyond traditional inpatient settings while maintaining clinical oversight through remote monitoring and digital care technologies.
About the Author(s)
Healthcare IT Research Team
Healthcare · Healthcare ITThis report was authored by the healthcare it research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the healthcare it segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


