
- Home
- »
- Medical Devices
- »
-
Hospital Furniture Market Size & Share Report, 2026-2033GVR Report cover

Hospital Furniture Market (2026 - 2033)
Size, Share & Trends Analysis Report By Application (Patient's Furniture, Staff's Furniture), By Product (Patient Lifts, Beds), By Material (Metal, Wood), By End Use, By Sales Channel, By Region, And Segment Forecasts
Market Size, 2025
$11.8BMarket Estimate, 2026
$12.6BMarket Forecast, 2033
$20.0BCAGR, 2026–2033
6.8%Hospital Furniture Market Summary
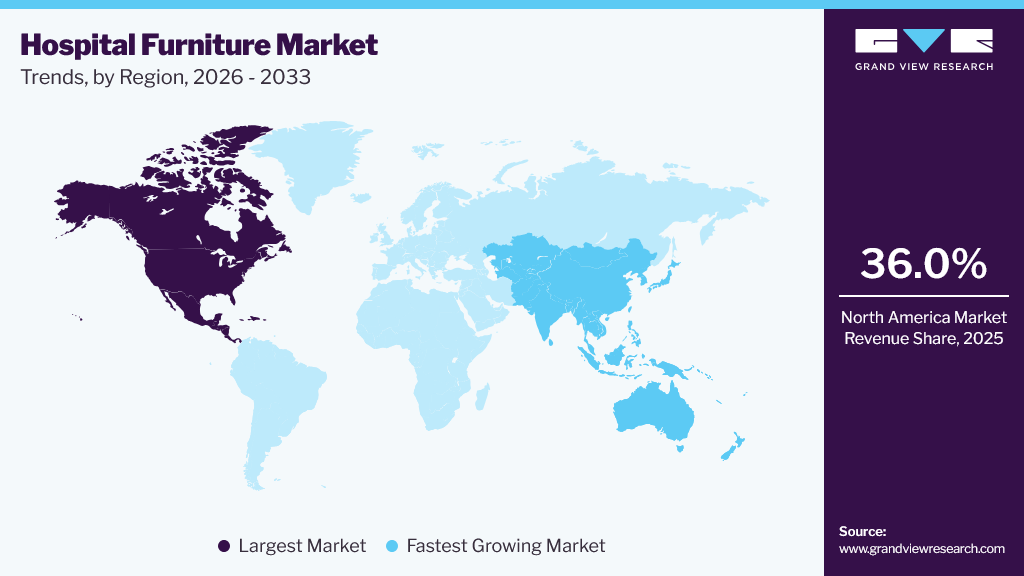
The global hospital furniture market size was valued at USD 11.8 billion in 2025 and is projected to grow from USD 12.6 billion in 2026 to USD 20.0 billion in 2033, at a CAGR of 6.8% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 36.0% in 2025. The market growth is attributed to the rising number of hospital admissions globally, a favorable insurance & reimbursement environment, and government support for developing hospital infrastructure in the healthcare sector.
Key Market Trends & Insights
- By application: Patient’s furniture segment dominated in 2025 and accounted for the largest share of around 46.0%.
- By material: Metal segment dominated in 2025 and accounted for the largest share of more than 40.0%.
- By end use: Ambulatory Surgery Centers (ASCs) segment is anticipated to exhibit the highest CAGR of more than 7.0% during the forecast period.
- By product: Beds segment accounted for the largest revenue share of around 25.0% in 2025.
- By sales channel: Offline sales channel dominated the industry in 2025, accounting for more than 60.0% of overall revenue.
Regional Highlights
- Largest regional market: North America (36.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market Size in 2025: USD 11.8 Billion
- Estimated Market Size in 2026: USD 12.6 Billion
- Projected Market Size by 2033: USD 20.0 Billion
- CAGR (2026-2033): 6.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The primary driver of market expansion is the growing network of hospitals and clinics worldwide. To prevent sudden, adverse circumstances such as pandemics, public organizations are working to build new healthcare infrastructure. The demand for more modern hospitals and clinics is the primary growth driver in the market over the forecast period. The public sector’s initiatives to modernize current hospital infrastructure also play a significant role in driving the industry. The hospital furniture market is witnessing a consistent surge in contract production adoption. With greater focus on product quality and a high-end finish, the idea of personalized furniture has become increasingly popular.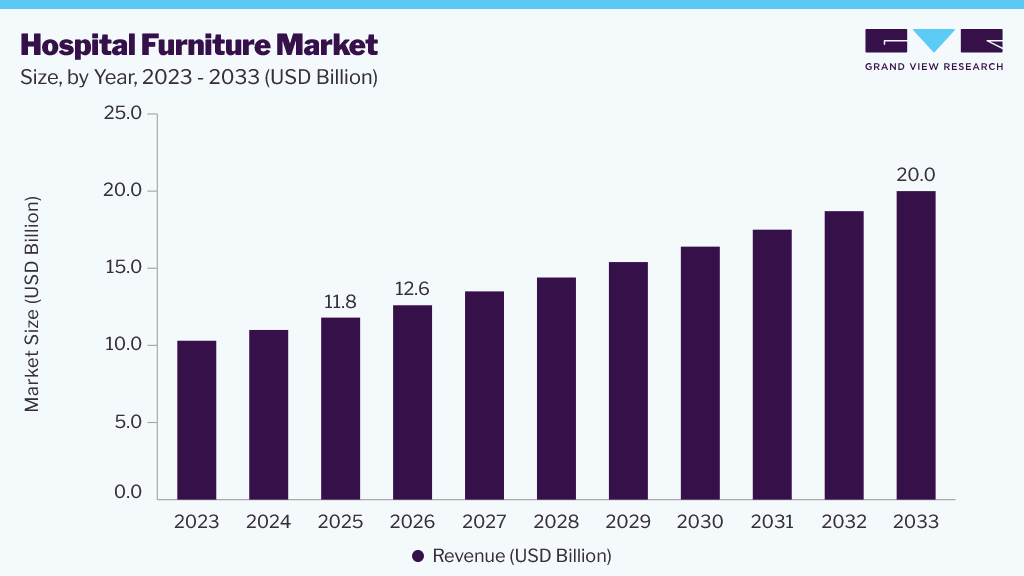 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Manufacturers are developing ergonomic designs that emphasize aesthetics, comfort, and patient hospitality. Conventional hospital furniture has several drawbacks, including the development of skin ulcers and bed sores in obese patients due to extra pressure from the furniture on already thin skin. As a result, companies are working to enhance the usability and appearance of healthcare furnishings for overweight people. This is encouraging for medical facilities that are spending money on furniture capable of supporting several hundred pounds of patient weight. According to the World Obesity Federation's World Obesity Atlas Report 2025, the number of adults living with obesity is expected to increase by more than 115% between 2010 and 2030, rising from 524 million to approximately 1.13 billion globally. In addition, to deal with Healthcare-Associated Illnesses or Infections (HAIs), prevention is currently the main focus in furniture design. Infection control is becoming more crucial as hospital cleanliness standards improve.
A key challenge in hospital furniture design and production is limited research and development in many countries. While some nations have advanced hospital infrastructure and furnishings, others lack essential sector advancements.
Market Dynamics
The hospital furniture market is influenced by evolving healthcare delivery models and ongoing investments in healthcare infrastructure worldwide. The expansion of hospitals and critical care facilities is driving demand for advanced furniture solutions, while the high cost of technologically advanced products remains a challenge to wider adoption. At the same time, the growing shift toward home healthcare and long-term care services is creating new opportunities for manufacturers to expand product offerings and address patient needs.
Growing healthcare infrastructure and increased capital expenditure in hospital construction are among the factors driving growth in the hospital furniture market. Both governments and private healthcare organizations in developing and developed countries are inclined to build new hospitals, upgrade existing healthcare facilities, and expand intensive care units. This has increased demand for hospital furniture items, including beds, ICU beds, examination tables, trolleys, and storage systems, which help hospitals run their day-to-day operations. The rising prevalence of chronic diseases and an aging population have increased the need for additional hospital beds.
In addition, hospital modernization is driving demand for advanced, ergonomic furniture solutions, including electrically adjustable beds and modular ICU setups that improve workflow and patient experience. For instance, in 2024, the Government of India inaugurated and expanded multiple AIIMS hospitals and launched several healthcare infrastructure projects worth approximately USD 1,410 million, significantly increasing tertiary care capacity across states. Similarly, countries such as the U.S., Canada, and the UK are investing considerable capital in programs to build new hospitals and improve existing ones, in a bid to increase access to health care services. These healthcare growth programs will contribute to increased global demand for hospital furniture.
The high cost of advanced hospital furniture is a key restraint on the hospital furniture market. Electric ICU beds, motorized operating tables, multifunctional patient recliners, and critical care systems, among other pieces of modern hospital furniture, require the use of expensive materials, precise manufacturing processes, and dedicatedly designed electronic components. Consequently, the final product becomes expensive, restricting access for small and medium-sized hospitals with tight budgets, particularly in developing countries. The public sector in healthcare faces budgetary restraints and thus prioritizes more pressing issues, such as buying essential equipment rather than furniture. This price sensitivity in healthcare organizations will slow the adoption of advanced hospital furniture, thereby creating a significant barrier to market growth.
The growing demand for home healthcare services and long-term care facilities is poised to become a major opportunity for the hospital furniture industry. Chronic illness rates, the elderly population, and requirements for post-hospital care following discharge from a healthcare facility have increased the need for medical furniture away from hospitals. These include adjustable hospital beds, recliner chairs for patients, mobility hospital furniture, and space-saving patient care units used at home and in nursing facilities. As health institutions look to adopt a decentralized approach to healthcare delivery to ease hospital strain and increase patient convenience, this trend is being bolstered. In addition, the growing number of geriatric homes and rehabilitation centers is generating a constant demand for high-quality, comfortable hospital furniture that is easy for patients to operate. Manufacturers are increasingly focusing on portable, lightweight hospital furniture for home care. Shifting trends toward home and long-term healthcare will generate new business opportunities for hospital furniture companies in the years to come.
Analyst Perspective
The global hospital furniture market is expanding rapidly, driven by increased healthcare infrastructure, an aging population, and a shift toward integrated, patient-focused care. Growth is further supported by the adoption of Internet of Medical Things (IoMT) and smart furniture technologies, transforming basic equipment into advanced systems such as automated ICU beds, ergonomic chairs, and modular layouts that improve clinical efficiency. While extensive public and private investments in developing regions fuel demand, manufacturers face challenges from regulatory requirements and fluctuating raw material costs. Moving deeper into the forecast period, the use of eco-friendly biopolymers, automated telemetry, and the growth of ambulatory surgical centers are expected to shape sourcing strategies and market demand.
Product Insights
The beds segment accounted for the largest revenue share of around 25.0% in 2025. The hospital beds segment has been classified into sub-segments, including ICU beds, fowler beds, general hospital beds, pediatric beds, maternity beds, and others. The growing demand for ICU beds due to the higher prevalence of chronic disorders that need critical care services is expected to drive the segment during the forecast period. In addition, electrical or powered beds are preferred over plain beds from private hospitals due to the rising number of bariatric surgeries and the growing geriatric population. These beds offer enhanced patient comfort, safety, and mobility. For example, in January 2024, Joerns Healthcare launched new models of its EasyCare and UltraCare long-term care beds, which are designed to improve both patient comfort and caregiver efficiency. This development reflects the increasing demand for advanced long-term care and electrically operated hospital bed solutions. Such product innovations are expected to further drive growth in the global hospital beds segment.
The chairs segment is expected to grow significantly over the forecast period. The chairs include examination, birthing, dialysis, ophthalmic, ENT, dental, pediatric, bariatric, and geriatric chairs. The growing demand for rehabilitation chairs, including pediatric, bariatric, and geriatric models used for patient bathing, positioning, and mobility, is expected to drive the segment. The growing geriatric population and rising cases of paralysis & spinal injuries are also anticipated to drive the segment.
Application Insights
The patient’s furniture segment dominated the global industry in 2025, accounting for approximately 45.0% of overall revenue. The segment is estimated to expand further at the fastest growth rate, retaining its dominant position in the industry throughout the forecast period. Demand for patient furniture, such as examination couches, examination lights, drawers, benches, bedside tables, over-bed tables, and chairs, is high. Easier product maintenance is the major driving factor for the market.
Furthermore, the physician’s furniture segment is expected to grow at the highest CAGR during the forecast period. The physician’s furniture segment is further classified into examination tables, surgical chairs, and others. The rising patient footfall in larger hospitals, growing concerns regarding patient safety & mobility, and the need for good support during medical examinations are expected to boost segment growth during the forecast period.
Sales Channel Insights
The offline sales channel dominated the industry in 2025, accounting for more than 60.0% of overall revenue. The real-time experience, high purchase confidence, lower rejection rates, availability of customization options, immediate delivery, sales personnel assistance, comprehensive installation support, and simple returns are among the factors driving the growth of the offline sales channel segment.
The online sales channel segment is estimated to register the fastest growth rate during the forecast period, owing to several factors, such as the ease of comparison, availability of a variety of product options and product reviews from other customers, and great offers & discounts on product prices. However, factors such as delayed deliveries and uncertain quality may limit the penetration of the online sales channel in industry practice.
Material Insights
The metal segment dominated the industry in 2025, accounting for more than 40.0% of global revenue. Increasing adoption, coupled with rising demand for metal furniture owing to its excellent durability and comfort, will drive segment growth during the forecast period. In addition, stainless steel contains anti-microbial properties for healthcare equipment and the operating room. Thus, the widespread use of metal-based furniture equipment is also expected to propel segment growth.
The wood segment is expected to grow at the fastest CAGR during the forecast period, driven by the widespread use of wooden furniture. Wooden furniture is preferred for its inherent warmth and appeal; its organic qualities can provide thermal benefits and help balance internal moisture and humidity. Wood feels warmer to the touch than other structural materials, such as steel, because it has relatively low thermal conductivity. However, using harsh cleaning agents could damage the surface. After being used for a while, moisture can cause the wood to swell, potentially promoting bacterial growth. Wooden furniture is porous by nature and prone to nicks and scratches. Innovations and developments in wood technology to make wooden furniture more durable and long-lasting are driving segment growth.
End-use Insights
The ambulatory surgery centers (ASCs) segment is anticipated to exhibit the highest CAGR of around 7.0% during the forecast period. The demand for hospital furniture in ASCs is primarily driven by increased preference for same-day surgeries, which offer significant cost savings & waiting time reductions, and by the growing number of patients requiring surgical procedures. It is also projected that the availability of reimbursement policies for ASCs will aid in the development of this market.
The hospitals & specialty clinics segment accounted for the largest revenue share in 2025. The segment's growth is mainly driven by the increasing number of hospitals. Strong competition has increased demand for various types of furniture, leading to technological improvements in hospital furniture-attached devices. In addition, government expansions are triggering large furniture procurement contracts. For instance, in March 2026, under the Ministry of Health and Family Welfare's PM-ABHIM infrastructure push running through 2026, funds are being actively deployed to construct new critical care blocks and tier-II/III hospitals. This has generated immediate public tenders for thousands of ICU beds, fowler beds, transport trolleys, crash carts, and bedside lockers, contributing to the segment growth.
Regional Insights
The North America region held the largest share, exceeding 35.0% in 2025. This is attributed to the high prevalence of chronic health conditions such as obesity, diabetes, and cardiovascular diseases, which significantly increase hospitalization rates and drive demand for advanced healthcare infrastructure and hospital-based care. The region also faces a substantial burden of emergency medical cases, underscoring the need for well-equipped hospitals and critical care facilities. In addition, bariatric surgery and related procedures remain among the most effective long-term weight management solutions, with their adoption increasing significantly over the past decade. The rising number of such surgical interventions has further strengthened the demand for advanced hospital furniture, including operating tables, ICU beds, and patient handling systems. Collectively, these factors contribute to North America's dominance in the global hospital furniture market.
 To learn more about this report, Download Free Sample Report
Asia Pacific Hospital Furniture Market Trends
Asia Pacific is expected to grow at the highest CAGR during the forecast period. Favorable government policies, such as reimbursements for hospital furnishings and other equipment, are credited with the region’s growth. Due to rising cases of communicable diseases and public awareness of hospital-acquired infections, China has had the fastest growth in Asia Pacific. Japan has a robust healthcare system in terms of infrastructure, hospital beds, supplies, and equipment, among other things, which has helped the total market maintain a substantial industry share. In addition, substantial private sector investments are contributing significantly to regional growth. For instance, in June 2025, Aster DM Healthcare announced a capital expenditure plan of approximately USD 221.9 million in India to expand its hospital network, reflecting ongoing large-scale investments in healthcare capacity expansion. This move is expected to increase demand for hospital infrastructure, including beds, ICU installations, and hospital furniture, and driving growth in the Asia Pacific hospital furniture market.
Key Hospital Furniture Company Insights
The market is highly fragmented and highly competitive globally, with several key players. These players focus on growth strategies, such as new product launches, collaborations, partnerships, operational expansions, mergers & acquisitions, and patient awareness campaigns.
Key Hospital Furniture Companies
The following key companies have been profiled for this study on the hospital furniture market.
-
Stryker
-
Invacare Corp.
-
ARJO AB
-
Steris Plc.
-
Medline Industries, Inc.
-
Baxter International Inc.
-
Drive DeVilbiss Healthcare
-
GF Health Products, Inc.
-
NAUSICAA Medical
-
Sunrise Medical (US) LLC
-
Herman Miller Inc.
-
Kovonox
-
Getinge AB.
Recent Developments
-
In May 2026, EIR Healthcare partnered with MillerKnoll to deliver factory-integrated healthcare interior solutions combining construction and hospital furniture systems. The collaboration aims to speed up the delivery of fully equipped clinical environments through modular, scalable design.
-
In March 2026, Stryker Corporation launched its SmartHospital Platform, a digital ecosystem designed to connect devices, data, workflows, and care teams across healthcare facilities to improve operational efficiency and patient outcomes.
-
In May 2025, Aster DM Healthcare announced the development of its fourth hospital in Bengaluru as part of its ongoing expansion strategy in India. The new multi-specialty facility is expected to increase healthcare capacity and generate demand for hospital beds, patient room furniture, and other healthcare infrastructure, supporting growth in the hospital furniture market.
-
In March 2024, JSI officially entered the healthcare market, emphasizing human-centered design focused on caregiving, recovery, and patient comfort. The company launched four healthcare-focused product lines, including recliners, sleep sofas, seating systems, and modular casework designed for clinical and caregiver environments.
Hospital Furniture Market Report Scope
Report Attribute
Details
Market size in 2025
USD 11.8 billion
Estimated market size in 2026
USD 12.6 billion
Projected market size by 2033
USD 20.0 billion
Growth rate
CAGR of 6.8% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, sales channel, material, end use, and region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; Japan; China; India; Australia; South Korea; Thailand; Brazil; Mexico; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Stryker; Invacare Corporation; ARJO AB; Steris Plc.; Medline Industries, Inc.; Baxter International Inc.; Drive DeVilbiss Healthcare; GF Health Products, Inc.; NAUSICAA Medical; Sunrise Medical (US) LLC; Herman Miller Inc.; Kovonox; Getinge AB
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Hospital Furniture Market Segmentation
This report forecasts revenue growth at the regional and country levels and provides an analysis on the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global hospital furniture market report on the basis of product, application, sales channel, material, end use, and region:
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Beds
-
ICU Beds
-
Fowler Beds
-
Plain Hospital Beds
-
Pediatric Beds
-
Maternity Beds
-
Others
-
-
Patient Lift
-
Manual Lifts
-
Power Lifts
-
Stand up Lifts
-
Heavy duty Lifts
-
Overhead Track Lifts
-
Others
-
-
Tables
-
Examination Tables
-
Obstetric Tables
-
Surgical Tables
-
Others
-
-
Chairs
-
Medical Carts
-
Stretchers
-
Others
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Physician’s Furniture
-
Patient’s Furniture
-
Staff’s Furniture
-
-
Sales Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Offline
-
Online
-
-
Material Outlook (Revenue, USD Million, 2021 - 2033)
-
Wood
-
Metal
-
Plastic
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals & Specialty Clinics
-
Ambulatory Surgical Centers
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
U.K.
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Mexico
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Frequently Asked Questions About This Report
Offline sales channel dominated the hospital furniture market with a share of 60.0% in 2025.
Key players include Stryker; Invacare Corporation; ARJO AB; Steris Plc.; Medline Industries, Inc.; Baxter International Inc.; Drive DeVilbiss Healthcare; GF Health Products, Inc.; NAUSICAA Medical; Sunrise Medical (US) LLC; Herman Miller Inc.; Kovonox; Getinge AB
The global hospital furniture market size was valued at USD 11.8 billion in 2025 and is estimated at USD 12.6 billion for 2026.
The global hospital furniture market is expected to grow at a CAGR of 6.8% from 2026 to 2033, reaching USD 20.0 billion.
North America dominated with a 36.0% revenue share in 2025.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


