
- Home
- »
- Advanced Interior Materials
- »
-
Industrial Air Filtration Market Size & Share Report 2026-2033GVR Report cover

Industrial Air Filtration Market (2026 - 2033) Size, Share & Trends Analysis Report By Product (Fume Collection, HEPA), By Distribution Channel (OEM, Aftermarket), By End-use, By MERV Rating, By Region, And Segment Forecasts
Market Size, 2025
$6.8BMarket Estimate, 2026
$7.1BMarket Forecast, 2033
$10.8BCAGR, 2026–2033
6.0%Industrial Air Filtration Market Summary
The global industrial air filtration market size was valued at USD 6.8 billion in 2025 and is projected to grow from USD 7.1 billion in 2026 to USD 10.8 billion by 2033, at a CAGR of 6.0% from 2026 to 2033. The North America held the largest share of 41.9% of the global market in 2025. Rising industrialization and stricter workplace air quality regulations are key factors driving the market.
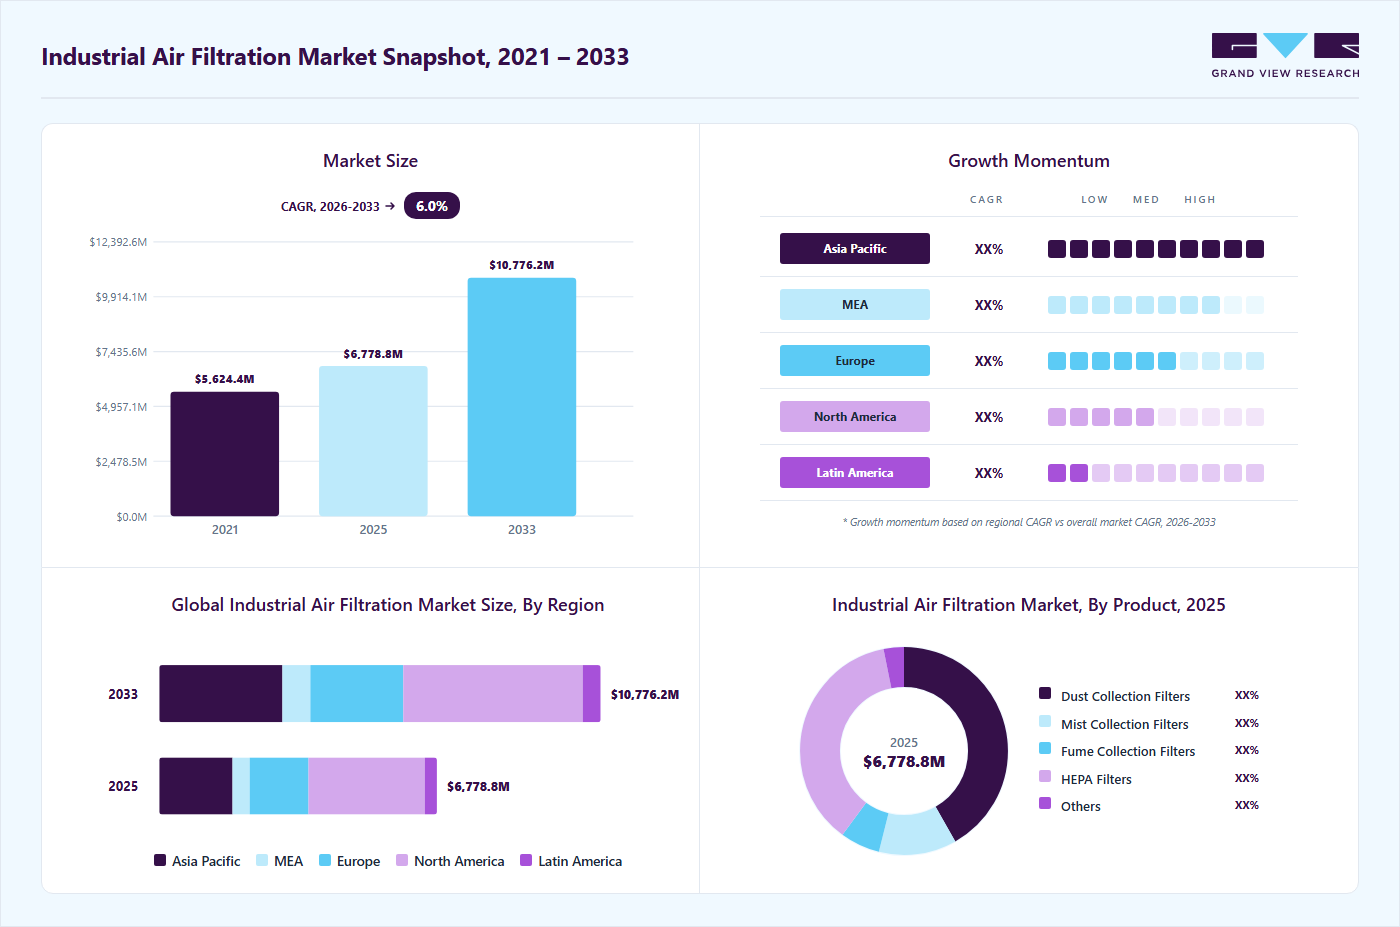 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Dust collection filters segment held the largest market share of 41.7% in 2025.
- By distribution channel: Aftermarket segment accounted for the largest share of 78.8% in 2025.
- By MERV rating: Above 17 MERV segment accounted for the largest share of 36.7% in 2025.
- By end use: Food & beverage segment accounted for the largest share of 21.5% in 2025.
Regional Highlights
- Largest regional market: North America (41.9% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: China industrial air filtration market dominated the Asia Pacific in 2025.
Market Size & Forecast
- Market size in 2025: USD 6.8 Billion
- Estimated market size in 2026: USD 7.1 Billion
- Projected market size by 2033: USD 10.8 Billion
- CAGR (2026-2033): 6.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Governments and safety bodies are enforcing tighter limits on particulate emissions to protect worker health and the environment. This is pushing industries to install advanced filtration systems across manufacturing and processing facilities.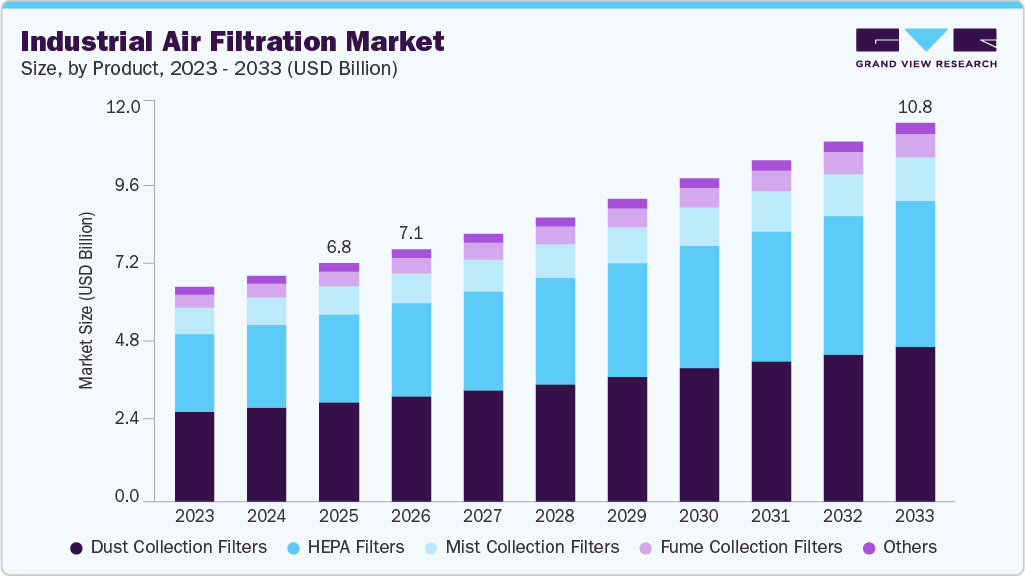 To learn more about this report, Download Free Sample Report
Growing awareness of equipment protection and operational efficiency is further accelerating market growth. Effective air filtration reduces dust buildup, corrosion, and unplanned downtime in industrial machinery. Industries are increasingly investing in reliable filtration to improve productivity and extend equipment life. The shift toward preventive maintenance and cleaner production environments is strengthening long-term demand.
Market Dynamics
The growing emphasis on cleaner industrial operations and healthier work environments is one of the key factors driving the industrial air filtration market. Industries such as manufacturing, chemicals, mining, cement, pharmaceuticals, food processing, and metal fabrication generate large amounts of dust, smoke, fumes, and airborne particles during daily operations. As environmental regulations become stricter across the globe, companies are increasingly investing in advanced air filtration systems to reduce emissions and comply with workplace safety standards.
Governments and environmental agencies across major economies are also tightening emission standards and workplace safety regulations, further accelerating the adoption of industrial air filtration technologies. Regulatory bodies such as OSHA (Occupational Safety and Health Administration), EPA (Environmental Protection Agency), and various European environmental agencies continue to enforce stricter guidelines related to particulate emissions, hazardous air pollutants, and industrial ventilation systems.
One of the key restraints affecting the growth of the industrial air filtration market is the high installation and maintenance cost associated with advanced filtration systems. Industrial facilities often require large-scale air filtration equipment capable of handling dust, fumes, smoke, and hazardous airborne particles, which involves significant upfront investment in equipment, ducting, monitoring systems, and installation services. In addition, these systems require regular maintenance, filter replacement, and energy consumption to ensure efficient performance and regulatory compliance. For small and medium-sized industries, particularly in cost-sensitive and developing markets, the ongoing operational expenses can become a major challenge, limiting the adoption of advanced air filtration technologies despite increasing environmental and workplace safety concerns.
Market Concentration & Characteristics
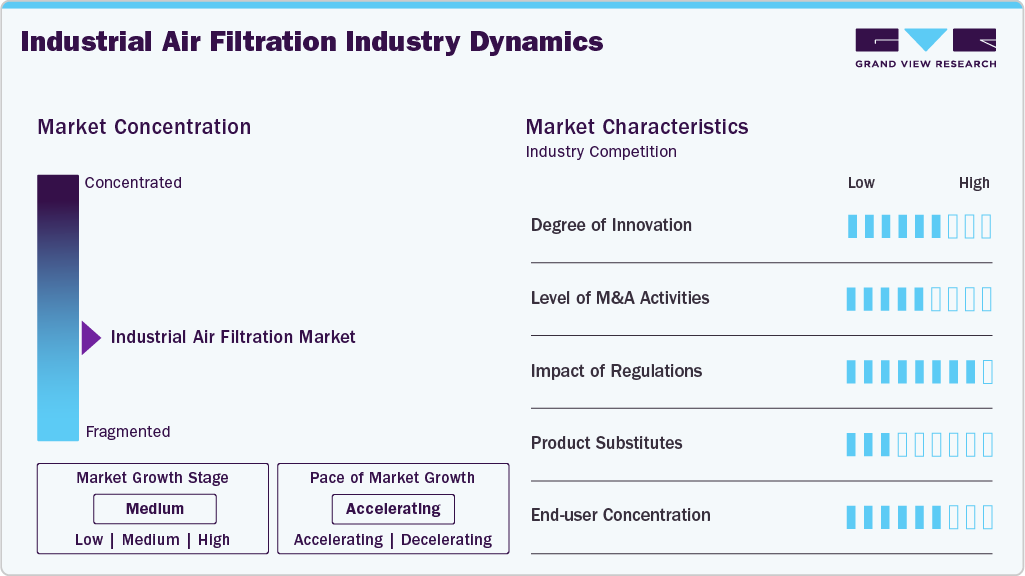
The industrial air filtration industry is moderately fragmented, with the presence of several global players alongside a large number of regional and niche manufacturers. Leading companies compete on technology, filtration efficiency, and compliance with evolving emission standards, while smaller players focus on cost-effective and application-specific solutions. Continuous product upgrades and customization needs limit complete market consolidation.
The industrial air filtration industry shows a high degree of innovation driven by rising efficiency expectations and sustainability goals. Manufacturers are focusing on advanced filter media, longer service life, and energy-efficient system designs. Digital features such as real-time monitoring and predictive maintenance are gaining traction. Continuous innovation is essential to meet diverse industrial applications and evolving performance standards.
 To learn more about this report, Download Free Sample Report
Regulatory impact on the market is strong, as industries must comply with strict air quality, emission, and worker safety norms. Environmental agencies are tightening limits on particulate matter and hazardous fumes across industrial operations. Non-compliance can lead to penalties and operational shutdowns, increasing the adoption of certified filtration systems. Regulations also encourage upgrades from conventional to high-efficiency filtration technologies.
End user concentration is moderate, with demand spread across multiple industries such as cement, metals, chemicals, and pharmaceuticals. Large industrial facilities account for higher-value installations, while small and mid-sized plants contribute steady aftermarket demand. No single end-use sector dominates overall consumption. This diversified demand base reduces dependency on any one industry and supports stable market growth.
Product Insights
Dust collection filters dominated the market and accounted for a 41.7% share in 2025, due to their extensive use across cement, metal, power, and wood processing industries. These filters effectively captured large volumes of particulate matter generated during heavy industrial operations. Their proven reliability, scalability, and suitability for large production facilities supported widespread adoption. Expansion of dust-intensive industries further strengthened their leading market position.
The HEPA Filters segment is expected to grow at a fastest CAGR of 6.6% from 2026 to 2033 in terms of revenue, driven by increasing demand for ultra-clean air in pharmaceutical, food, and electronics manufacturing. Stricter contamination control and hygiene standards accelerated their adoption. These filters offered high removal efficiency for fine particles and microorganisms. Rising investments in cleanroom and controlled manufacturing environments supported rapid segment growth.
Distribution Channel Insights
The aftermarket segment dominated the market in 2025 and accounted for 78.8% share, due to the continuous need for filter replacement and system maintenance. Industrial facilities relied heavily on regular servicing to maintain filtration efficiency and comply with air quality norms. Aging installed filtration systems increased demand for spare filters and upgrades. The recurring nature of replacement cycles supported a strong aftermarket revenue share.
The OEM segment is expected to grow at a significant CAGR of 5.3% from 2026 to 2033 in terms of revenue, due to the rising installation of new industrial plants and process expansion projects. Equipment manufacturers are increasingly integrating filtration systems into new machinery and production lines. Stricter emission standards encouraged end users to adopt compliant filtration solutions at the installation stage. Growth in industrial automation and greenfield projects further supported OEM channel expansion.
MERV Rating Insights
Above 17 MERV filters dominated the market and accounted for a 36.7% share in 2025, due to their high efficiency in capturing fine and ultra-fine particles. These filters were widely adopted in pharmaceutical, chemical, and clean manufacturing environments with strict air quality requirements. Their ability to meet stringent regulatory and safety standards supported strong demand. Increasing focus on contamination control further reinforced their market leadership.
The 9 to 12 MERV segment is expected to grow at a significant CAGR of 6.4% from 2026 to 2033 in terms of revenue, due to its balance between filtration efficiency and cost-effectiveness. These filters were increasingly used in general manufacturing and food processing facilities. Rising awareness of workplace air quality encouraged upgrades from lower MERV ratings. Their suitability for mid-range industrial applications supported steady growth.
End-use Insights
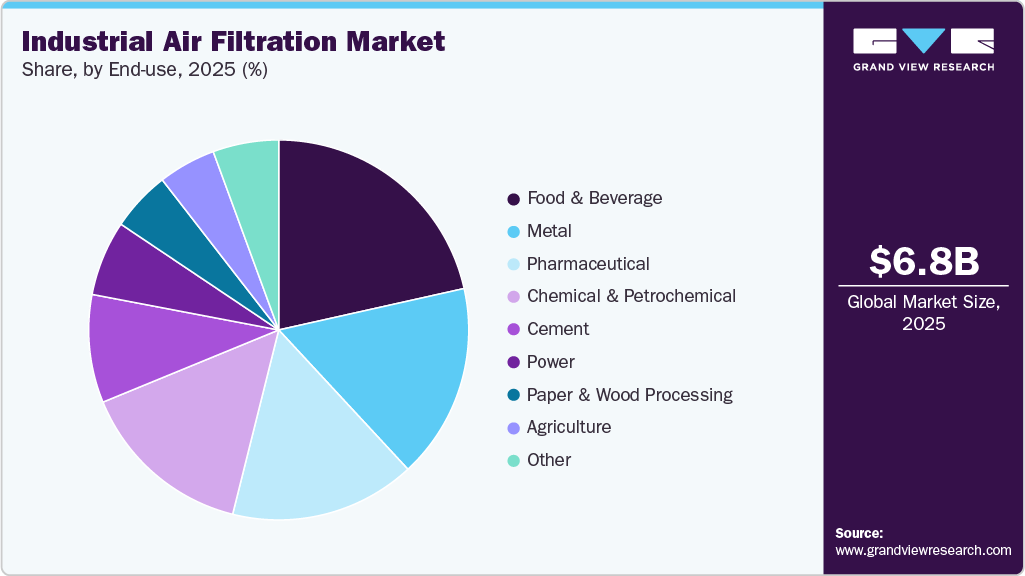
The food & beverage segment dominated the market and accounted for a 21.5% share in 2025, due to strict hygiene and contamination control requirements. Processing plants relied on effective air filtration to maintain product quality and comply with food safety regulations. High usage of dust, mist, and odor control systems supported consistent demand. Expansion of packaged and processed food production further strengthened segment dominance.
 To learn more about this report, Download Free Sample Report
The Pharmaceutical segment is expected to grow at the fastest CAGR of 6.7% from 2025 to 2033 in terms of revenue, due to rising drug manufacturing and stringent cleanroom standards. Air filtration played a critical role in controlling airborne contaminants during production and packaging. Increasing regulatory scrutiny accelerated the adoption of high-efficiency filtration systems. Growth in biopharmaceuticals and contract manufacturing supported rapid segment expansion.
Regional Insights
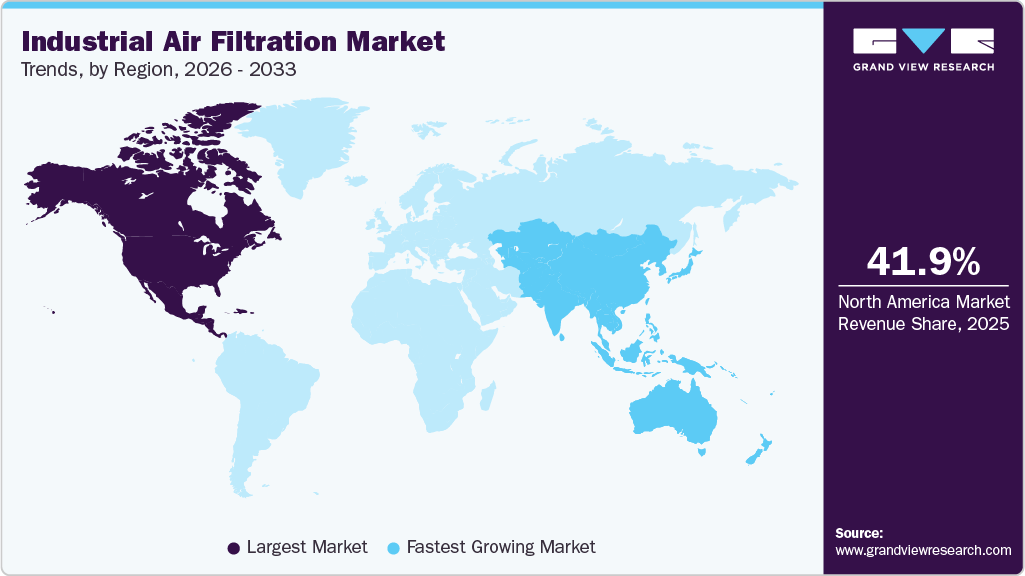
North America dominated the industrial air filtration market and accounted for a 41.9% share in 2025, due to strict environmental regulations and high compliance enforcement. The region had a large installed base of manufacturing and processing facilities requiring advanced filtration systems. Strong awareness of worker safety and air quality standards supported consistent adoption. Continuous upgrades and replacement demand reinforced regional market leadership.
 To learn more about this report, Download Free Sample Report
U.S. Industrial Air Filtration Market Trends
The industrial air filtration market in the U.S. dominated North America due to its strong industrial base and strict environmental regulations. Manufacturing, food processing, pharmaceutical, and power sectors widely adopted advanced filtration systems. High awareness of workplace safety and air quality standards supported sustained demand. Continuous upgrades and aftermarket replacements reinforced market dominance.
Canada industrial air filtration marketshowed steady growth driven by expanding food processing, chemicals, and energy industries. Increasing focus on worker health and environmental compliance encouraged the adoption of efficient air filtration systems. Investments in industrial modernization supported replacement and retrofit demand. Government initiatives on emission control further supported market growth.
Europe Industrial Air Filtration Market Trends
The industrial air filtration market in Europe showed steady growth due to stringent emission control regulations and a strong focus on environmental sustainability. Industrial facilities increasingly adopted high-efficiency filtration to meet regional air quality standards. The modernization of aging industrial infrastructure supported replacement demand. Focus on energy-efficient and eco-friendly solutions drove gradual market growth.
Germany industrial air filtration marketdominated Europe due to its strong manufacturing and automotive base. Strict emission control norms and workplace safety regulations drove widespread adoption of advanced filtration systems. Industries invested heavily in dust and fume control to meet environmental standards. Continuous technological upgrades supported Germany’s leading market position.
The industrial air filtration market in the UKshowed steady growth driven by rising demand from food processing, pharmaceuticals, and chemical industries. Increasing regulatory focus on air quality and worker safety encouraged filtration system upgrades. Modernization of aging industrial facilities supported aftermarket demand. Growth in clean manufacturing practices further supported market expansion.
Asia Pacific Industrial Air Filtration Market Trends
The industrial air filtration market in the Asia Pacific was the fastest-growing region at a CAGR of 6.7% over the forecast period, driven by rapid industrialization and expanding manufacturing activities. Rising investments in food processing, pharmaceuticals, and chemicals increased demand for air filtration systems. Governments strengthened emission norms to address pollution concerns. Growth of new industrial plants and infrastructure supported accelerated market expansion.
China industrial air filtration marketdominated the Asia Pacific market due to its vast manufacturing base and high industrial output. Stringent government policies on emission control and workplace safety increased the adoption of filtration systems. Heavy industries such as cement, metal, and chemicals generated strong demand. Continuous investments in pollution control infrastructure supported market leadership.
India showed strong growth driven by rapid industrialization and expanding food processing and pharmaceutical sectors. Increasing enforcement of air quality and occupational safety regulations encouraged filtration adoption. Growth in new manufacturing plants and infrastructure projects supported demand. Rising awareness of cleaner production practices further accelerated market expansion.
Middle East & Africa Industrial Air Filtration Market Trends
The industrial air filtration market in the Middle East and Africa region grew due to rising industrial activity in oil & gas, power, and manufacturing sectors. Governments have increased focus on occupational health and emission control in industrial zones. Demand for dust and fume filtration systems rose in harsh operating environments. Infrastructure development and industrial diversification supported regional growth.
Saudi Arabia industrial air filtration marketshowed steady growth due to expanding industrial and energy-related activities. Investments in petrochemicals, power generation, and manufacturing increased demand for dust and fume filtration systems. Growing focus on worker safety and emission control supported the adoption of advanced filtration solutions. Industrial diversification initiatives further strengthened market growth.
Central & South America Industrial Air Filtration Market Trends
The industrial air filtration market in the CSA experienced growth supported by expanding cement, mining, and food processing industries. Increasing regulatory attention to industrial emissions encouraged the adoption of filtration systems. Investments in industrial modernization improved demand for upgraded air quality solutions. Economic recovery in key countries supported gradual market expansion.
Brazil industrial air filtration market showed steady growth due to expansion in food processing, cement, and metal industries. Increasing regulatory focus on industrial emissions encouraged the adoption of effective filtration systems. The modernization of manufacturing facilities supported replacement and upgrade demand. Rising awareness of workplace air quality further contributed to market growth.
Key Industrial Air Filtration Company Insights
Some of the key players operating in the market include Donaldson Company Inc., Honeywell International Inc., and Daikin Industries, Ltd.
-
Donaldson Company Inc. focused strongly on industrial dust, fume, and mist collection solutions across heavy manufacturing sectors. The company emphasized high-efficiency filter media to handle harsh operating conditions and high particulate loads. Its portfolio addressed cement, metalworking, and power generation applications. Continuous investment in cartridge and baghouse technologies improved filtration performance and service life. A strong aftermarket presence supported recurring revenue through replacement filters and system upgrades.
-
Honeywell International Inc. strengthened its position through advanced air filtration systems designed for regulated industrial environments. The company leveraged high-performance particulate and gas-phase filtration to support compliance-driven industries. Its solutions are aligned closely with pharmaceutical, chemical, and food processing applications. Focus on integrated building and process safety systems differentiates its offerings. Ongoing innovation supported the adoption of higher MERV and HEPA-grade filtration products.
Key Industrial Air Filtration Companies:
The following key companies have been profiled for this study on the industrial air filtration market.
- MANN+HUMMEL
- Donaldson Company Inc.
- Honeywell International Inc.
- Daikin Industries, Ltd.
- Danaher
- SPX FLOW, Inc.
- Lydall, Inc.
- American Air Filter Company, Inc.
- Industrial Air Filtration, Inc.
- PARKER HANNIFIN CORP
- Camfil
- K&N Engineering
- Freudenberg SE
- Testori Spa
- Eaton
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature players: Parker Hannifin Corporation; Honeywell International, Inc.; MANN+HUMMEL; Daikin Industries, Ltd.; Danaher Corporation; Donaldson Company, Inc.; Freudenberg & Co. Kg.
- The companies continuously adopt new strategies, actively launch industrial air filtration, and collaborate with multiple partners and suppliers to provide enhanced customer experience.
- For instance, in January 2022, Danaher Corporation launched the Supralon lube oil filter and hydraulic filter range. These products contributed to the preservation and extension of equipment life in hydraulic and lubricating oil applications.
- Such companies have a worldwide presence with multiple manufacturing locations
- For instance, Honeywell International, Inc., MANN+HUMMEL, Daikin Industries, Ltd. have a vast geographic presence
- Companies invest heavily in their R&D departments
- As some of the companies operate on a regional level, they are often exposed to political, economic, regulatory, and currency risks that may affect their business operations.
- Established structures and processes of companies, such as Honeywell International, Inc., MANN+HUMMEL, Daikin Industries, Ltd., are expected to hinder, making it challenging to respond swiftly to evolving customer needs or regulatory changes.
Emerging players: Filtration Group; Testori SpA; Lydall Inc.; Industrial Air Filtration, Inc.
- Collaboration with local and niche players in the market.
- For instance, in October 2021, Filtration Group formed a partnership with Columbus Industries to offer a wide range of high-performance air filters. This collaboration broadens Filtration Group's extensive array of top-tier indoor air filtration solutions, aiming to deliver safe and purified air to its clientele.
- Can provide higher cost-effectiveness.
- Customized product based on the specific requirement.
- Provide superior customer service.
- Company has a limited product portfolio.
- Intense competition faced from the key players such as such as Honeywell International, Inc., MANN+HUMMEL, Daikin Industries, Ltd., with established brand reputations.
- Lower cash reserves may restraint the company's growth.
Recent Developments
-
In December 2025, Daikin announced an investment of USD 28.6 million to expand its manufacturing operations in Australia to strengthen local production capacity. The expansion supported the growing demand for air handling and ventilation equipment. It also improved supply efficiency for industrial and commercial customers. The move aligned with Daikin’s long-term focus on regional manufacturing and sustainability.
-
In September 2024, Donaldson launched filtration services across selected EMEA countries to support industrial manufacturers with system performance and compliance. The services focused on compressed air and process filtration testing, monitoring, and maintenance. This helped end users improve filtration reliability and meet quality standards.
Industrial Air Filtration Market Report Scope
Report Attribute
Details
Market size in 2025
USD 6.8 billion
Estimated market size in 2026
USD 7.1 billion
Projected market size by 2033
USD 10.8 billion
Growth rate
CAGR of 6.0% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, distribution channel, MERV rating, application, region
Regional scope
North America, Europe, Asia Pacific, CSA, MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; China; Japan; India; Australia; Brazil; Argentina; Saudi Arabia; South Africa
Key companies profiled
MANN+HUMMEL; Donaldson Company Inc.; Honeywell International Inc.; Daikin Industries, Ltd.; Danaher; SPX FLOW, Inc.; Lydall, Inc.; American Air Filter Company, Inc.; Industrial Air Filtration, Inc.; PARKER HANNIFIN CORP; Camfil; K&N Engineering; Freudenberg SE; Testori Spa; Eaton
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Industrial Air Filtration Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global industrial air filtration market report based on product, distribution channel, MERV rating, application, and region:
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Dust Collection Filters
-
Cartridge Collectors & Filters
-
Baghouse Filters
-
Other Filters
-
-
Mist Collection Filters
-
Fume Collection Filters
-
HEPA Filters
-
Others
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
OEM
-
Aftermarket
-
-
MERV Rating Outlook (Revenue, USD Million, 2021 - 2033)
-
1 to 4 MERV
-
5 to 8 MERV
-
9 to 12 MERV
-
13 to 16 MERV
-
Above 17 MERV
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Cement
-
Food & Beverage
-
Metal
-
Power
-
Pharmaceutical
-
Chemical & Petrochemical
-
Paper & Wood Processing
-
Agriculture
-
Other
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
Italy
-
UK
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
Saudi Arabia
-
South Africa
-
-
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
Detailed assessment of the industrial air filtration market across North America, Europe, Asia Pacific, Latin America, and Middle East & Africa, including country-level analysis for the U.S., Germany, China, India, Japan, and Brazil. Evaluation includes industrial emission regulations, manufacturing activity, air quality standards, infrastructure investments, and adoption trends across major end-use industries.
Identify high-growth regional markets and country-level demand hotspots. Enable prioritization of markets based on industrial activity, regulatory environment, and environmental compliance requirements.
Product-Level Segmentation Expansion
Expanded analysis across Dust Collection Filters, Mist Collection Filters, Fume Collection Filters, HEPA Filters, Cartridge Collectors, Baghouse Filters, Activated Carbon Filters, Electrostatic Filters, and other industrial filtration technologies.
Identify the fastest-growing and highest-margin filtration technologies. Support product portfolio optimization and technology investment decisions. Enable benchmarking across premium and standard filtration systems.
MERV Rating-Based Segmentation
Detailed market analysis based on MERV ratings including 1–4, 5–8, 9–12, 13–16, and Above 17 MERV filtration systems. Assessment includes adoption trends by industry, contamination sensitivity, cleanroom requirements, energy efficiency considerations, and regulatory compliance standards.
Understand industry-wise demand for low-, medium-, and high-efficiency filtration systems. Support premium product positioning and regulatory compliance planning. Identify industries transitioning toward higher-efficiency filtration technologies.
Company Market Share & Positioning Benchmarking
Detailed benchmarking of key players based on estimated market share, regional dominance, filtration specialization, distribution strength, aftermarket capabilities, and end-use penetration. Includes categorization of premium global players, regional manufacturers, and cost-focused suppliers.
Understand market concentration and competitive positioning across the industrial air filtration ecosystem. Support competitive differentiation and strategic planning. Identify underserved customer segments and regional expansion opportunities.
Frequently Asked Questions About This Report
The global industrial air filtration market size was valued at USD 6.8 billion in 2025 and is estimated at USD 7.1 billion for 2026.
The global industrial air filtration market is expected to grow at a CAGR of 6.0% from 2026 to 2033, reaching USD 10.8 billion by 2033.
Asia Pacific is the fastest-growing region over the forecast period.
Some of the key players operating in the global industrial air filtration market include MANN+HUMMEL; Donaldson Company Inc.; Honeywell International Inc.; Daikin Industries, Ltd.; Danaher; SPX FLOW, Inc.; Lydall, Inc.; American Air Filter Company, Inc.; Industrial Air Filtration, Inc.; PARKER HANNIFIN CORP; Camfil; K&N Engineering; Freudenberg SE; Testori Spa; Eaton
The global industrial air filtration market was driven by stricter emission and workplace safety regulations across industries. Growing industrialization and rising awareness of worker health and equipment protection further supported market growth
The dust collection filters segment led with a 41.7% market share in 2025, while the HEPA filters segment is expected to grow at the fastest CAGR.
The aftermarket segment held the largest market share of 78.8% in 2025.
The above 17 MERV segment led with a 36.7% market share in 2025.
The food & beverage segment held the largest market share of 21.5% in 2025, while the pharmaceutical segment is expected to grow at the fastest CAGR.
North America dominated with a 41.9% revenue share in 2025.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


