
- Home
- »
- Next Generation Technologies
- »
-
Industrial Computed Tomography Market Size Report, 2033GVR Report cover

Industrial Computed Tomography Market (2026 - 2033)
Size, Share & Trends Analysis Report By Offering (Equipment, Services), By Type, By Scanning Technique, By Application, By Vertical, By Region, And Segment Forecasts
Market Size, 2025
$812.1MMarket Estimate, 2026
$873.2MMarket Forecast, 2033
$1,450.1MCAGR, 2026–2033
7.6%Industrial Computed Tomography Market Summary
The global industrial computed tomography market size was valued at USD 812.1 million in 2025 and is projected to grow from USD 873.2 million in 2026 to USD 1,450.1 million in 2033, at a CAGR of 7.6% from 2026 to 2033. Asia Pacific dominated with a revenue share of over 33.5% in 2025. The increasing use of additive manufacturing techniques in production processes across industries such as automotive, aerospace, defense, and electronics has contributed to market growth. Additive manufacturing, also known as 3D printing, involves the production of complex designs and structures that are expensive and difficult to produce using traditional manufacturing methods.
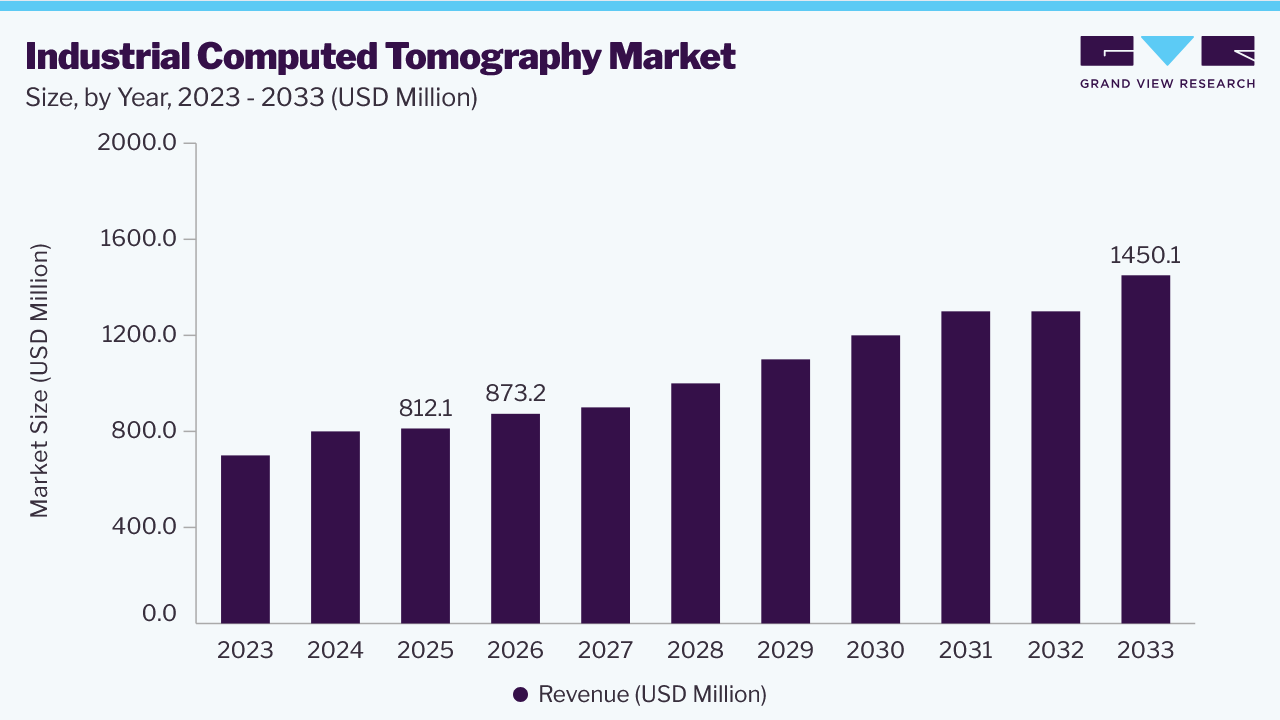 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By offering: The equipment segment held the largest market share of approximately 52.0% in 2025.
- By type: The high-voltage CT segment held the largest market share of over 42.5% in 2025.
- By scanning technique: The fan-beam CT segment held the largest market share of over 44.0% in 2025.
- By application: The flaw detection and inspection segment held the largest market share of over 25.0% in 2025.
- By vertical: The automotive segment held the largest market share of over 26.5% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (33.5% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 812.1 Million
- Estimated market size in 2026: USD 873.2 Million
- Projected market size by 2033: USD 1,450.1 Million
- CAGR (2026-2033): 7.6%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
These structures are made by depositing material layer upon layer, creating a single-piece structure. Hence, industrial CT scanners test the strength and capabilities of the structures/designs formed using the additive manufacturing process. These scanners help the manufacturers to test & evaluate the capabilities/characteristics of the complex structures without damaging the product.
The benefits of industrial computed tomography, including the precise scanning of micro and large parts of the structure, enable the manufacturer to reduce the product development cost. Also, various types of inspection capabilities offered by this scanning technology, such as failure analysis, flaw detection, assembly analysis, and others, help improve the overall product quality, thereby reducing the product recall risk. Therefore, the pre-and post-production benefits computed tomography offers for the industrial sector are anticipated to bolster market growth in the coming years.
The increasing demand for high precision and reliability requirements for evaluating complex parts at high temperatures has pushed the aerospace computed tomography business forward. Computed tomography can also be used to inspect tiny and moderate components such as welded tubes, aluminum castings, turbine blades, and others. Furthermore, the industrial computed tomography market is being driven by the high adoption of techniques in the aerospace sector.
Analyst Perspective
The industrial computed tomography market is experiencing strong growth, driven by increasing demand for advanced non-destructive testing solutions, rising focus on quality inspection, and growing adoption of precision imaging technologies across industrial sectors. Increasingly, manufacturers are turning to industrial computed tomography equipment to detect internal defects and analyze intricate components without damaging products or assemblies. The growth in aerospace, automotive, electronics, and additive manufacturing industries is also driving market growth in terms of demand for measurement and quality control solutions. In addition, developments in imaging resolution, automation, and artificial intelligence-based inspection technologies are increasing capabilities and efficiencies. Companies that provide fast inspections and innovative tech solutions will create massive value due to the rising global demand for product quality and manufacturing accuracy.
Offering Insights
In terms of offering, the market is classified into services and equipment. The equipment segment held the largest market share of approximately 52.0% in 2025. Market players offer various types of industrial computed tomography equipment integrated with advanced software solutions for image reconstruction, visualization, and automated defect analysis. Growing innovation in industrial CT software, such as AI, machine learning, and automated inspection, among others, will fuel the use of advanced CT solutions. For instance, in September 2025, Hexagon enhanced its VGSTUDIO MAX industrial CT analysis software with upgraded AI-supported defect analysis capabilities through its Porosity & Inclusion Analysis (PIA) tool, enabling automated identification and evaluation of internal defects in manufactured components. The integration of AI-based CT analysis software improves inspection speed, reduces manual evaluation requirements, and enhances quality control processes, which is expected to support growth of the industrial computed tomography equipment segment.
The services segment is expected to grow at the fastest CAGR over the forecast period. Services include computed tomography inspection services, support, maintenance, and consulting services. The capital-intensive nature of industrial computed tomography scanners has paved the way for the high growth of the services segment in the market. Companies are increasingly outsourcing CT services to third-party service providers due to the low cost, which helps them significantly reduce their capital investment. Consequently, this shift toward external expertise allows manufacturers to leverage advanced inspection capabilities without the burden of heavy upfront technology costs.
Type Insights
In terms of type, the market is classified into high-voltage CT, micro CT, and others. The high-voltage CT segment held the largest market share of over 42.5% in 2025. High-voltage CT scanners are used to scan dense and large objects such as car engines. High-voltage CT scanners provide higher penetration capability and are suitable for analyzing complex structures where conventional lower-energy systems cannot achieve sufficient imaging depth. For instance, in July 2025, RX Solutions launched the EasyTom L 450 industrial CT system, featuring a powerful 450 kV high-energy X-ray source. This system allows for the non-destructive inspection of large, dense components typically found in the aerospace, automotive, and manufacturing sectors.. The system combines high-energy scanning capability with high-resolution imaging, supporting defect detection and quality control of complex industrial parts.
The micro CT segment is expected to grow at the fastest CAGR over the forecast period. Micro CT scanners offer high-resolution, non-destructive imaging capabilities and are widely used for inspecting small to medium-sized components made from plastics, ceramics, composites, and lightweight metals. Standard micro CT systems typically operate with X-ray source voltages ranging from 60 kV to 225 kV, enabling detailed visualization of internal structures and defects. Compared with high-voltage CT systems, micro CT scanners are generally more affordable and accessible for research institutions and industrial laboratories. In addition, increasing adoption of micro CT technology in additive manufacturing, electronics, battery inspection, medical devices, and advanced materials research is expected to drive segment growth during the forecast period.
Scanning Technique Insights
In terms of scanning technique, the market is classified into fan-beam CT, cone-beam CT, and others. The fan-beam CT function segment held the largest market share of over 44.0% in 2025. The fan-beam CT scanning technique is generally used to scan dense and large components, requiring high-energy X-ray voltages over 450 kV. Fan-beam CT scanning produces higher-quality images, and the scan is focused on a single area of interest. The ability to scan large objects and high image quality are likely to contribute to segment growth. Consequently, these technical advantages ensure that fan-beam systems remain the preferred choice for heavy-industrial inspection and quality control.
The cone-beam CT segment is expected to grow at the fastest CAGR over the forecast period. The cone-beam CT scanning technique is suitable for scanning electronic components and medium-sized cast elements. Cone-beam CT requires lower scan times, recording a typical data set within a quarter of an hour. The cone-beam CT scanning method is increasingly being used in the inspection of electronic components, additive manufacturing components, and medium-sized industrial components since the method allows one to acquire 3D high-resolution images in less time than traditional CT scanning methods. The technique enables manufacturers to perform rapid non-destructive testing and defect analysis, supporting applications where speed and accuracy are critical.
Application Insights
In terms of application, the market is classified into failure analysis, assembly analysis, flaw detection and inspection, dimensioning and tolerancing analysis, and others. The flaw detection and inspection segment held the largest market share of over 25.0% in 2025, and the segment is expected to grow at the fastest CAGR over the forecast period.
The increasing need for product inspection to detect any flaws, cracks, damage, or variations from the designed product has been the key driver of this segment's high share. Using industrial CT systems for product inspections helps the manufacturer considerably reduce production/manufacturing costs. In addition, industrial CT scanners can quickly test and analyze minor defects that are not efficiently and effectively traceable using traditional inspection methods.
The assembly analysis segment is anticipated to grow at a significant CAGR throughout the forecast period. Assembly analysis is increasingly being used in industries such as automotive, aerospace, and electronics, which require the inspection and analysis of the assembled products to gain insights into the placement and condition of smaller/minor internal components without disassembling or destroying the product. Computed tomography can help in detecting incorrectly assembled or missing components. In addition, industrial CT enables manufacturers to verify internal assembly quality, identify dimensional deviations, and evaluate the integrity of complex multi-material assemblies with high accuracy. The technology supports non-destructive inspection throughout the product development and production lifecycle, helping reduce manufacturing defects, minimize product recalls, and improve overall quality assurance.
Vertical Insights
In terms of vertical, the industrial computer tomography market is classified into oil & gas, aerospace and defense, automotive, electronics, and others. The automotive segment held the largest market share of over 26.5% in 2025.
Industrial CT systems are used in the automotive industry across the manufacturing cycle, including pre-production evaluation, in-line assembly inspection, component sorting, and detailed failure analysis. The scanners generate precise metrology data that enables the user to validate the conformity of the parts with the original CAD designs, which, in turn, helps improve the overall product quality. For instance, in July 2025, ZEISS Industrial Quality Solutions introduced OMNIA GC 220-180, an automated inspection solution for large automotive castings such as battery trays and structural components. The system includes automated defect recognition and advanced image processing capabilities. The machine features automated defect detection and advanced image processing technologies.
The electronics segment is expected to grow at the fastest CAGR over the forecast period. CT scanning, as a non-destructive testing method for inspection, is increasingly used in the electronics industry to investigate internal parts & assemblies, molded circuits, and verify the optimal functioning of the electronic components. In addition, the increasing demand for electronic devices and the resultant rise in their manufacturing, coupled with the growing focus on quality control, are anticipated to drive the segment’s growth during the forecasted period. Furthermore, as modern electronic components continue to shrink in size while growing in complexity, the need for high-resolution internal inspection becomes absolute.
Regional Insights
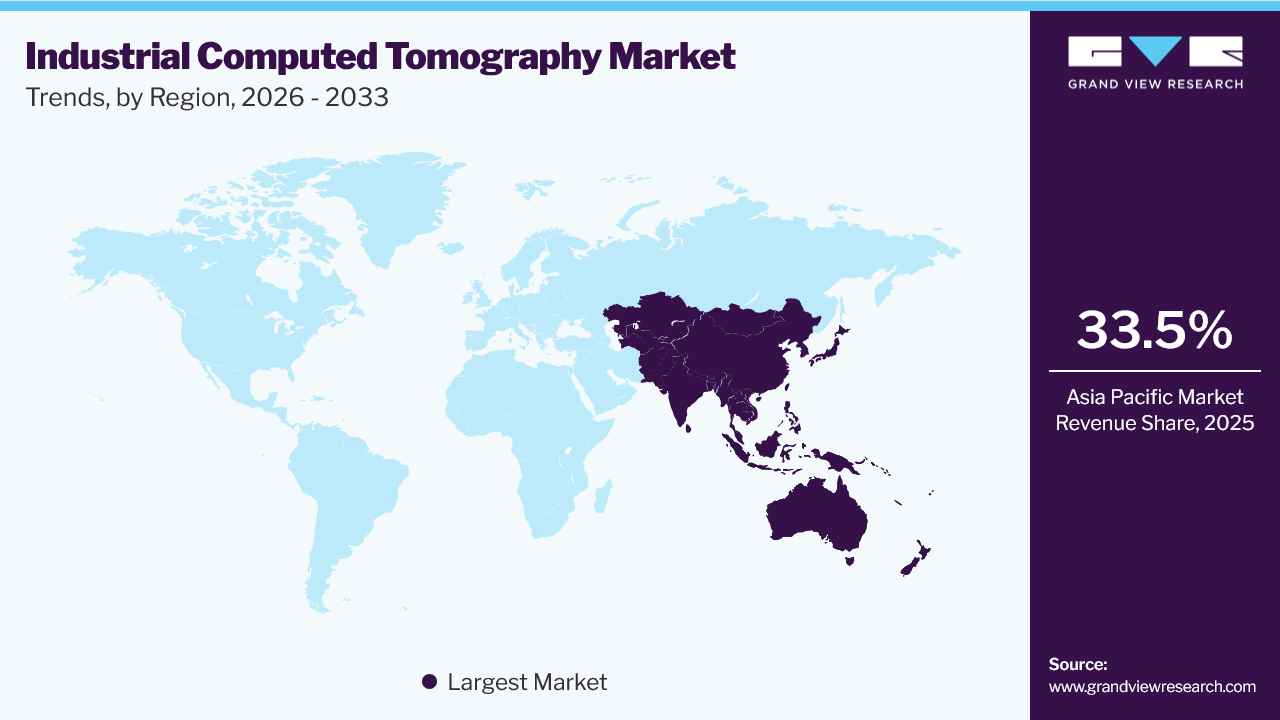
Asia Pacific dominated the Industrial Computed Tomography market, accounting for over 33.5% of revenue in 2025. It is expected to grow at the fastest CAGR throughout the forecast period. Asia Pacific has prominent market players such as Japan-based Nikon Corporation, OMRON Corporation, and Shimadzu Corporation. High manufacturing activities, especially in countries such as China, Japan, and India, are driving market growth in the region. A key driver of this growth in the market includes fast expansion in clean energy manufacturing and EV battery manufacturing infrastructure, owing to numerous initiatives taken up. This has increased demand for industrial CT systems, as they are becoming essential for inspecting and detecting defects in batteries. This has enabled the companies to avoid destructive tests and carry out high-throughput production through real-time sampling and inline scanning. This automated approach ensures high-throughput production while maintaining the rigorous safety standards required for next-generation energy storage.
 To learn more about this report, Download Free Sample Report
North America Industrial Computed Tomography Market Trends
The North America market is expected to grow at a considerable CAGR over the forecast period. North America has a developed technology infrastructure and presence of industrial CT market players such as the U.S.-based Baker Hughes Company and North Star Imaging Inc. (Illinois Tool Works Inc.). The increasing number of investments in the adoption of new & advanced technologies by key industry players is expected to drive the regional market growth. Moreover, North America has a presence of several industrial CT inspection services providers, such as Canada-based Jesse Garant Metrology Center and U.S.-based Exact Metrology. In addition, there has been a growing trend among regional laboratories to use AI and machine learning to enable automation of defect recognition. It is now possible to achieve high-speed 3D inspection within just a few minutes through the use of software, while earlier it was taking days. As factories push for fully automated quality control, access to these smart CT scanning services provides an indispensable competitive edge.
Key Industrial Computed Tomography Insights
The market is moderately consolidated and is likely to witness high competition in the market due to the presence of several industrial CT equipment and service providers. Some of the key players in the market are using innovation and product development as strategies to gain a competitive advantage. Some companies have been developing technologies, automation, and improved imaging performance to meet the changing needs of industrial applications. In addition, strategic collaborations and expansion initiatives are being pursued to strengthen market presence and enhance service capabilities across different regions.
Key Industrial Computed Tomography Companies
The following key companies have been profiled for this study on the industrial computed tomography market:
-
Nikon Corporation
-
OMRON Corporation
-
Baker Hughes Company
-
Comet Group
-
ZEISS Group
-
Shimadzu Corporation
-
North Star Imaging Inc. (Illinois Tool Works Inc.)
-
Werth Messtechnik GmbH
-
Rigaku Holdings Corporation and its Global Subsidiaries
-
VJ Technologies Inc.
Recent Developments
- In June 2025, Nikon Corporation introduced Limited Angle CT technology for its VOXLS and XT H 225 industrial X-ray inspection systems. The technology enables high-resolution CT imaging of large and complex components without requiring full 360-degree rotation of the sample.
- In May 2025, ZEISS Group introduced the ZEISS METROTOM 800 320 kV, an industrial CT system designed for high-density and complex components. The system uses a higher-energy X-ray source to improve scanning speed and measurement capability.
- In April 2025, Nikon launched the VOXLS 20 C 225, a new industrial X-ray CT system designed for non-destructive testing and metrology applications. The system provides high-quality CT data with a compact footprint for integration into laboratories and production environments.
- In September 2024, OMRON launched the VT-X950 automated X-ray inspection system, a CT-type inspection solution designed for semiconductor and advanced electronics manufacturing.
- In April 2024, OMRON Corporation introduced the VT-X850 3D CT X-ray inspection system, designed for EV-related electronics and SMT manufacturing lines. The system uses 3D CT imaging and automated inspection algorithms to detect defects in critical electronic assemblies.
Industrial Computed Tomography Market Report Scope
Report Attribute
Details
Market size in 2025
USD 812.1 million
Estimated market size in 2026
USD 873.2 million
Projected market size by 2033
USD 1,450.1 million
Growth rate
CAGR of 7.6% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD million, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Offering, type, scanning technique, application, vertical, and region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; UK; Germany; France; China; India; Japan; South Korea; Brazil; Mexico
Key companies profiled
Nikon Corporation; OMRON Corporation; Baker Hughes Company; Comet Group; ZEISS Group; Shimadzu Corporation; North Star Imaging Inc. (Illinois Tool Works Inc.); Werth Messtechnik GmbH; Rigaku Holdings Corporation and its Global Subsidiaries; VJ Technologies Inc.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Industrial Computed Tomography Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global industrial computed tomography market report by offering, type, scanning technique, application, vertical, and region:
-
Offering Outlook (Revenue, USD Million, 2021 - 2033)
-
Equipment
-
Services
-
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
High-voltage CT
-
Micro CT
-
Others
-
-
Scanning Technique Outlook (Revenue, USD Million, 2021 - 2033)
-
Fan-beam CT
-
Cone-beam CT
-
Others
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Flaw Detection and Inspection
-
Failure Analysis
-
Assembly Analysis
-
Dimensioning and Tolerancing Analysis
-
Others
-
-
Vertical Outlook (Revenue, USD Million, 2021 - 2033)
-
Oil & Gas
-
Aerospace and Defense
-
Automotive
-
Electronics
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
UK
-
Germany
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
-
Latin America
-
Brazil
-
Mexico
-
-
Middle East & Africa
-
Frequently Asked Questions About This Report
The global industrial computed tomography market size was valued at USD 812.1 million in 2025 and is estimated at USD 873.2 million for 2026.
The global industrial computed tomography market is expected to grow at a CAGR of 7.6% from 2026 to 2033, reaching USD 1,450.1 million.
Asia Pacific dominated with an over 33.5% revenue share in 2025.
The equipment segment accounted for the largest revenue share of approximately 52.0% in 2025.
Key players in the market include Nikon Corporation, OMRON Corporation, Baker Hughes Company, Comet Group, ZEISS Group, Shimadzu Corporation, North Star Imaging Inc. (Illinois Tool Works Inc.), Werth Messtechnik GmbH, Rigaku Holdings Corporation and its Global Subsidiaries, VJ Technologies Inc., and others.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


