
- Home
- »
- Pharmaceuticals
- »
-
Insomnia Therapeutics Market Size & Share Report, 2033GVR Report cover

Insomnia Therapeutics Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Benzodiazepines, Nonbenzodiazepines, Antidepressants, Orexin Antagonists, Melatonin Antagonists), By Sales Channel, By Region, And Segment Forecasts
Market Size, 2025
$3.0BMarket Estimate, 2026
$3.1BMarket Forecast, 2033
$4.4BCAGR, 2026–2033
4.9%Insomnia Therapeutics Market Summary
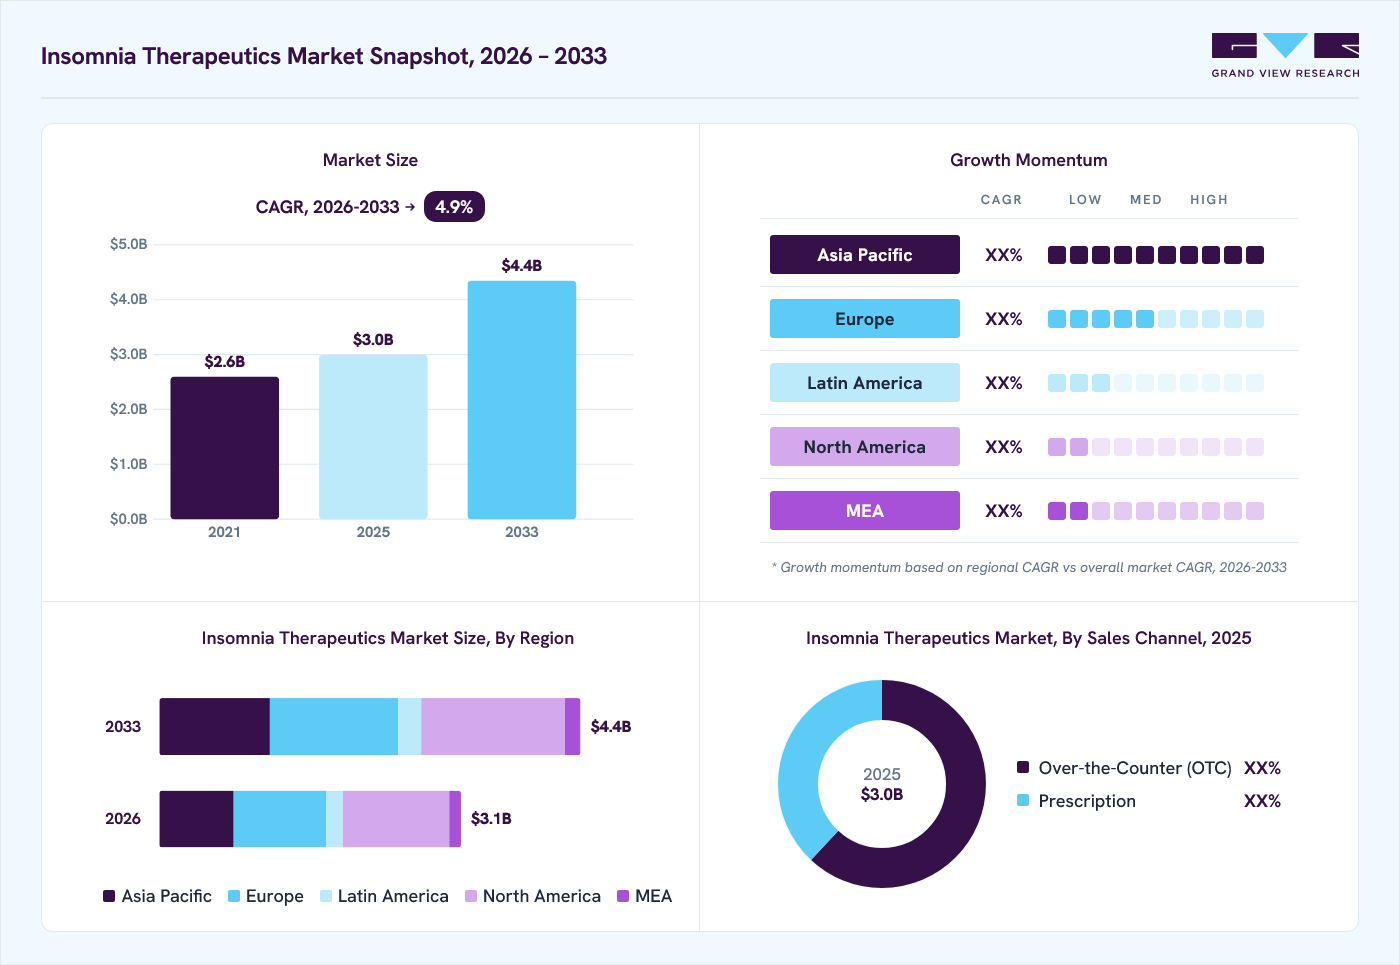
The global insomnia therapeutics market size was valued at USD 3.0 billion in 2025 and is projected to grow from USD 3.1 billion in 2026 to USD 4.4 billion by 2033, at a CAGR of 4.9% from 2026 to 2033. The market in North America dominated with a revenue share of 35.4% in 2025. Factors including increasing stress levels, lifestyle changes, and a growing geriatric population are contributing to a higher prevalence of insomnia.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Benzodiazepines segment held the largest market share of 29.3% in 2025.
- By sales channel: Over-the-counter (OTC) segment held the largest market share of 61.9% in 2025.
Regional Highlights
- Largest regional market: North America (35.4% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 3.0 Billion
- Estimated market size in 2026: USD 3.1 Billion
- Projected market size by 2033: USD 4.4 Billion
- CAGR (2026-2033): 4.9%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
According to the National Library of Medicine, about 30% of adult’s exhibit symptoms of insomnia, highlighting an urgent need for effective treatment options. This rising demand has prompted pharmaceutical companies and healthcare providers to innovate and expand their therapeutic offerings, leading to a surge in the market size. As individuals age, they often face a range of health challenges that can disrupt sleep patterns. This demographic shift necessitates tailored therapeutic interventions to address insomnia in older adults, further fueling market demand. The increasing awareness of sleep health, coupled with the availability of various treatment options-both pharmacological and non-pharmacological-has encouraged patients and healthcare providers to seek solutions for sleep disorders, thereby expanding the market landscape.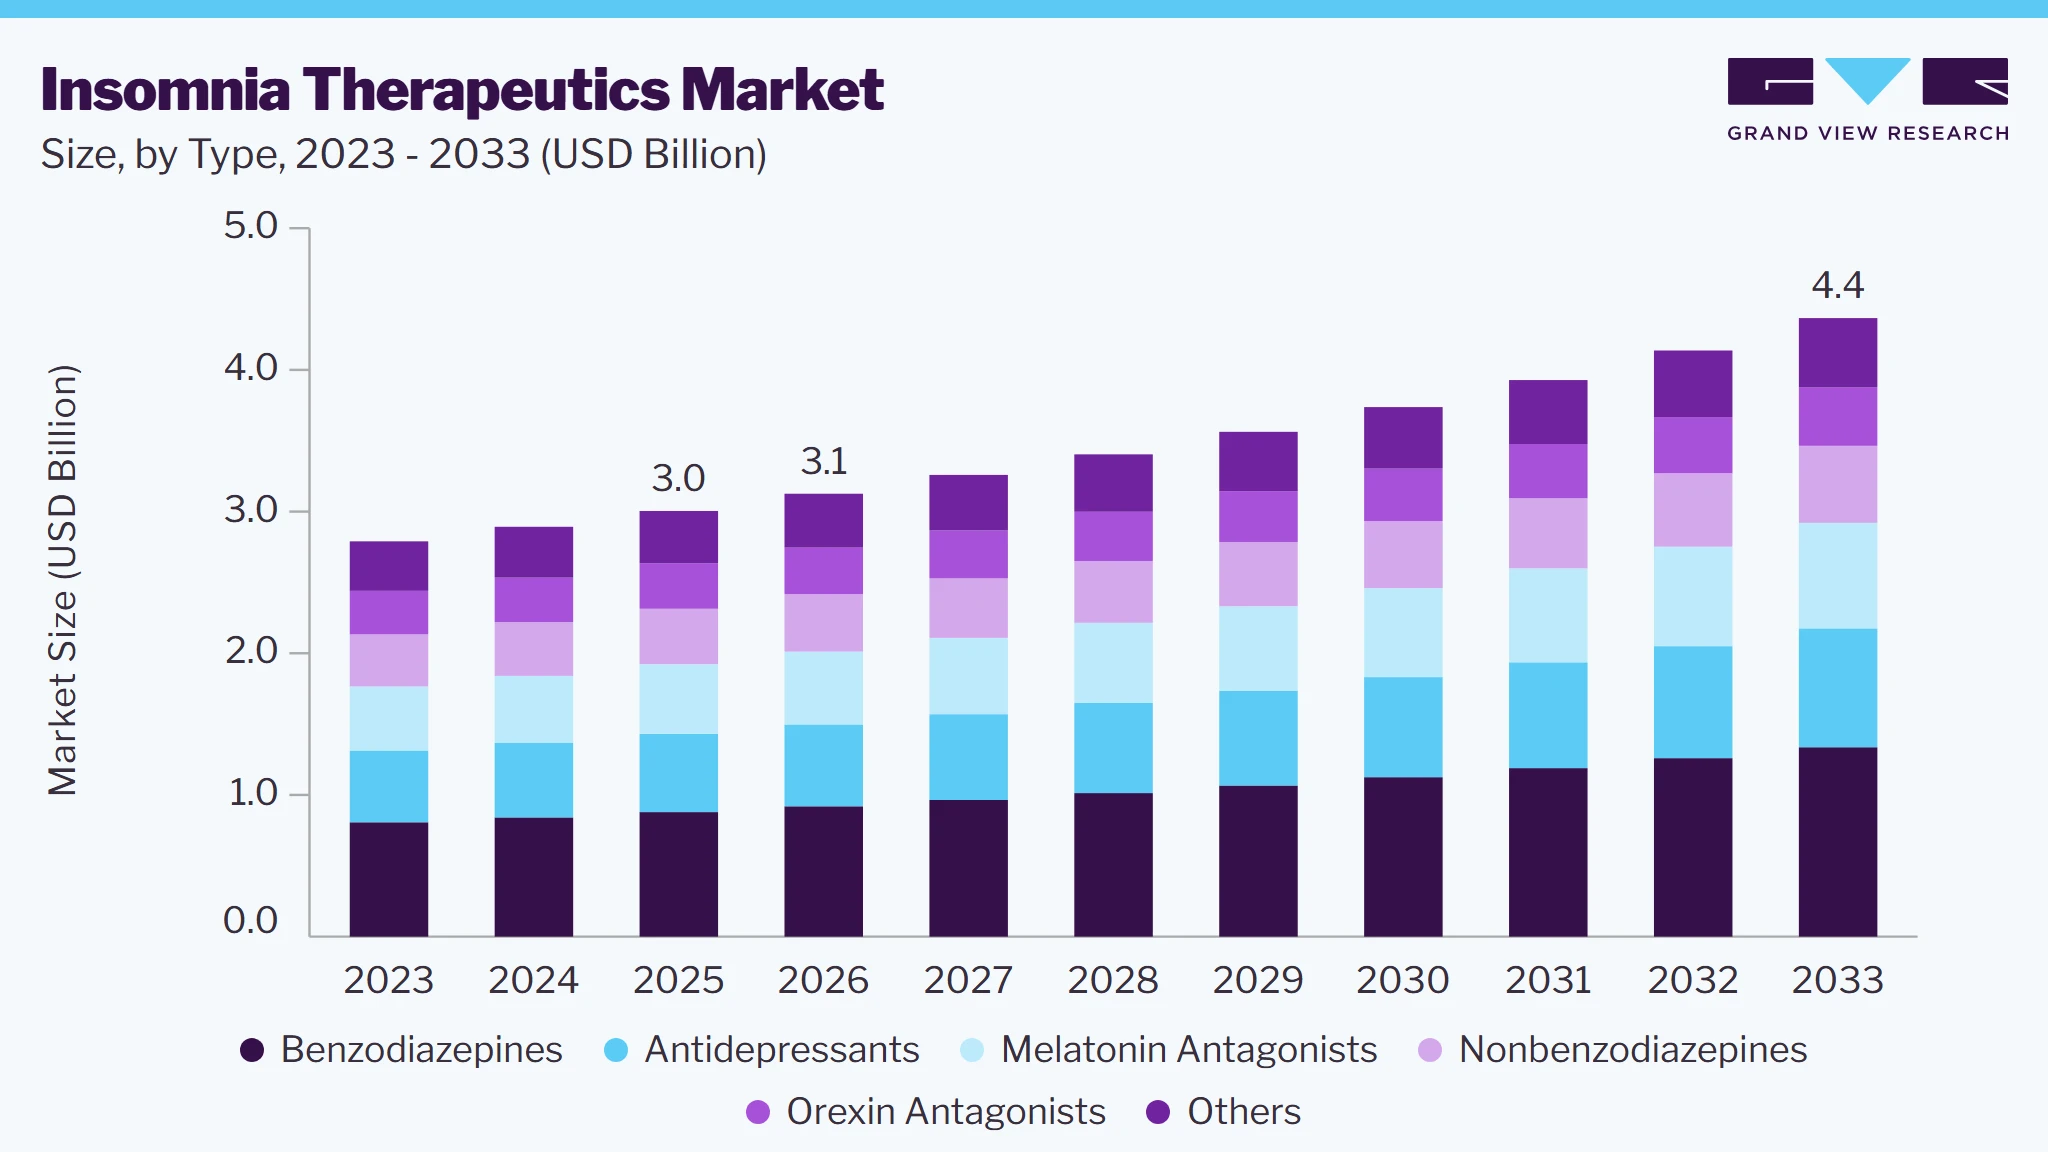 To learn more about this report, Download Free Sample Report
The introduction of innovative products, such as novel pharmacotherapeutics and digital therapies such as the FDA-approved Somryst app, has transformed the treatment paradigm for insomnia. Moreover, advancements in artificial intelligence and telemedicine offer promising avenues for improving sleep disorder management. The ability to monitor patients remotely and provide timely interventions enhances the therapeutic experience, aligning with the growing preference for personalized and accessible healthcare solutions.
Supportive reimbursement frameworks enhance the affordability of treatment options, making them more accessible to various patient populations. As telehealth services gain traction, particularly in the Asia-Pacific region, there is a heightened opportunity for broader reach and utilization of insomnia therapies. Collectively, these drivers indicate a robust trajectory for the insomnia therapeutics market, positioned for sustained expansion in the forecast period.
Market Dynamics
The global insomnia therapeutics market is driven by the growing prevalence of chronic and acute sleep disorders, increasing awareness about the health effects of poor sleep, and expanding access to diagnosis and treatment. Rising levels of stress, anxiety, depression, aging populations, and lifestyle changes have increased the number of patients seeking medical care for insomnia. The market includes prescription medicines, over the counter sleep aids, and nonpharmacological treatment approaches, with prescription therapies continuing to account for a significant share due to their use in moderate to severe cases. Healthcare providers are placing greater emphasis on individualized treatment based on patient age, underlying health conditions, and risk of long term medicine use. Regulatory agencies continue to encourage the development of therapies with improved safety profiles and lower risk of dependence. In addition, growing adoption of digital health tools and cognitive behavioral therapy for insomnia is supporting integrated care, creating opportunities for pharmaceutical companies to develop therapies that address both symptom management and long term treatment outcomes.
The insomnia therapeutics market is driven by the growing number of people experiencing chronic sleep disorders due to stress, anxiety, depression, aging, and lifestyle related factors. Poor sleep is increasingly recognized as a condition that affects cardiovascular health, metabolic disorders, mental health, and workplace productivity, leading more patients to seek medical treatment. Healthcare providers are also placing greater emphasis on early diagnosis and long term management rather than short term symptom control. This has increased demand for prescription therapies that improve sleep onset and sleep maintenance while reducing the risk of dependence and next day residual effects. Orexin receptor antagonists and other targeted therapies are expanding treatment choices for patients who do not respond well to older sedative medicines. Growing awareness among physicians and patients, together with updated clinical recommendations, continues to support the adoption of newer therapies. For instance, in May 2025, Eisai Co., Ltd. received approval in China for DAYVIGO (lemborexant) for the treatment of adults with insomnia characterized by difficulties with sleep onset and or sleep maintenance. The company stated that the product was approved for 1 adult indication and planned its commercial launch during the second quarter of fiscal 2025, supporting broader access to orexin based treatment.
The insomnia therapeutics market continues to face challenges related to the long term use of sleep medicines. Several commonly prescribed therapies are associated with risks such as dependence, tolerance, withdrawal symptoms, cognitive impairment, and daytime drowsiness, particularly among older adults. These concerns encourage physicians to prescribe medicines for shorter durations or recommend nonpharmacological approaches before initiating drug therapy. Clinical guidelines in many countries also advise careful patient selection and routine monitoring during treatment, limiting widespread long term use of prescription medicines. In addition, reimbursement limitations for newer branded therapies and higher treatment costs can reduce patient access, especially in developing healthcare systems. Many patients discontinue treatment because of adverse effects or inadequate symptom improvement, creating challenges for sustained therapy adoption. Regulatory agencies continue to require extensive clinical evidence demonstrating long term safety and effectiveness before expanding product indications. At the same time, cognitive behavioral therapy for insomnia is increasingly recommended as a first line treatment for chronic insomnia, which may reduce the number of patients receiving prescription medicines. These factors continue to limit broader market expansion despite ongoing advances in drug development and increasing awareness of sleep disorders.
The insomnia therapeutics market presents opportunities through the development of therapies that target the biological mechanisms regulating the sleep and wake cycle. Pharmaceutical companies are increasing investment in orexin pathway research to improve treatment outcomes while addressing safety concerns associated with older sedative medicines. Improved understanding of sleep physiology and the growing use of combination approaches involving medicines and behavioral therapy are creating opportunities for product differentiation. Companies are also expanding their neuroscience portfolios through acquisitions and licensing agreements to strengthen their presence in sleep medicine. In addition, the increasing number of clinical programs focused on sleep related disorders is supporting the development of therapies that may expand future treatment options for insomnia. For instance, in June 2026, Eli Lilly and Company completed the acquisition of Centessa Pharmaceuticals to strengthen its portfolio in sleep wake disorders. The acquisition added Centessa Pharmaceuticals' clinical stage orexin receptor 2 agonist programs, including candidates for narcolepsy and other sleep related disorders, expanding Eli Lilly and Company's neuroscience pipeline through one acquisition focused on orexin based therapies.
Analyst Perspective
The insomnia therapeutics market is shifting from the use of traditional sedative medicines toward therapies that offer targeted treatment with improved safety and effectiveness. The market is becoming more focused on approved insomnia therapies, continued research in sleep disorders, and the development of medicines with novel mechanisms of action. Increasing regulatory approvals and product launches are expanding the availability of newer treatment options across major healthcare markets. At the same time, ongoing clinical research is improving the understanding of sleep disorders and supporting the development of therapies that address both sleep onset and sleep maintenance. Companies are also investing in neuroscience research and expanding their sleep medicine portfolios through product development and strategic collaborations. These activities are increasing treatment options for patients, supporting broader access to insomnia therapies, and contributing to the steady development of the insomnia therapeutics market.
Type Insights
Based on type, the benzodiazepines segment led the market with the largest revenue share of 29.3% in 2025. Benzodiazepines are useful for insomnia associated with acute stress. It increases sleep duration by 30-90 minutes, decreases sleep latency, and suppresses slow-wave sleep. The higher acceptability of drugs among physicians due to their quick results and easy availability are driving segmental growth. For instance, according to a report published in the National Center for Biotechnology Information (NCBI) in 2024, the U.S. FDA has approved a few of the BZDs such as alprazolam, clobazam, chlordiazepoxide, and others for the effective treatment of insomnia.
Antidepressants are expected to grow lucratively over the forecast period. Drugs such as nefazodone, trazodone, and mirtazapine may also improve subjective sleep ratings compared to placebo or other antidepressants in patients with depression and suffering from insomnia. For instance, the European Medicines Agency (EMA) and Food and Drug Administration (FDA) approved daridorexant has demonstrated sustained efficacy, improving nocturnal sleep parameters, with a favorable safety and tolerability profile. Thus, this segment has been positively increasing with growing awareness among people and acceptance of such antidepressants in treating insomnia.
Sales Channel Insights
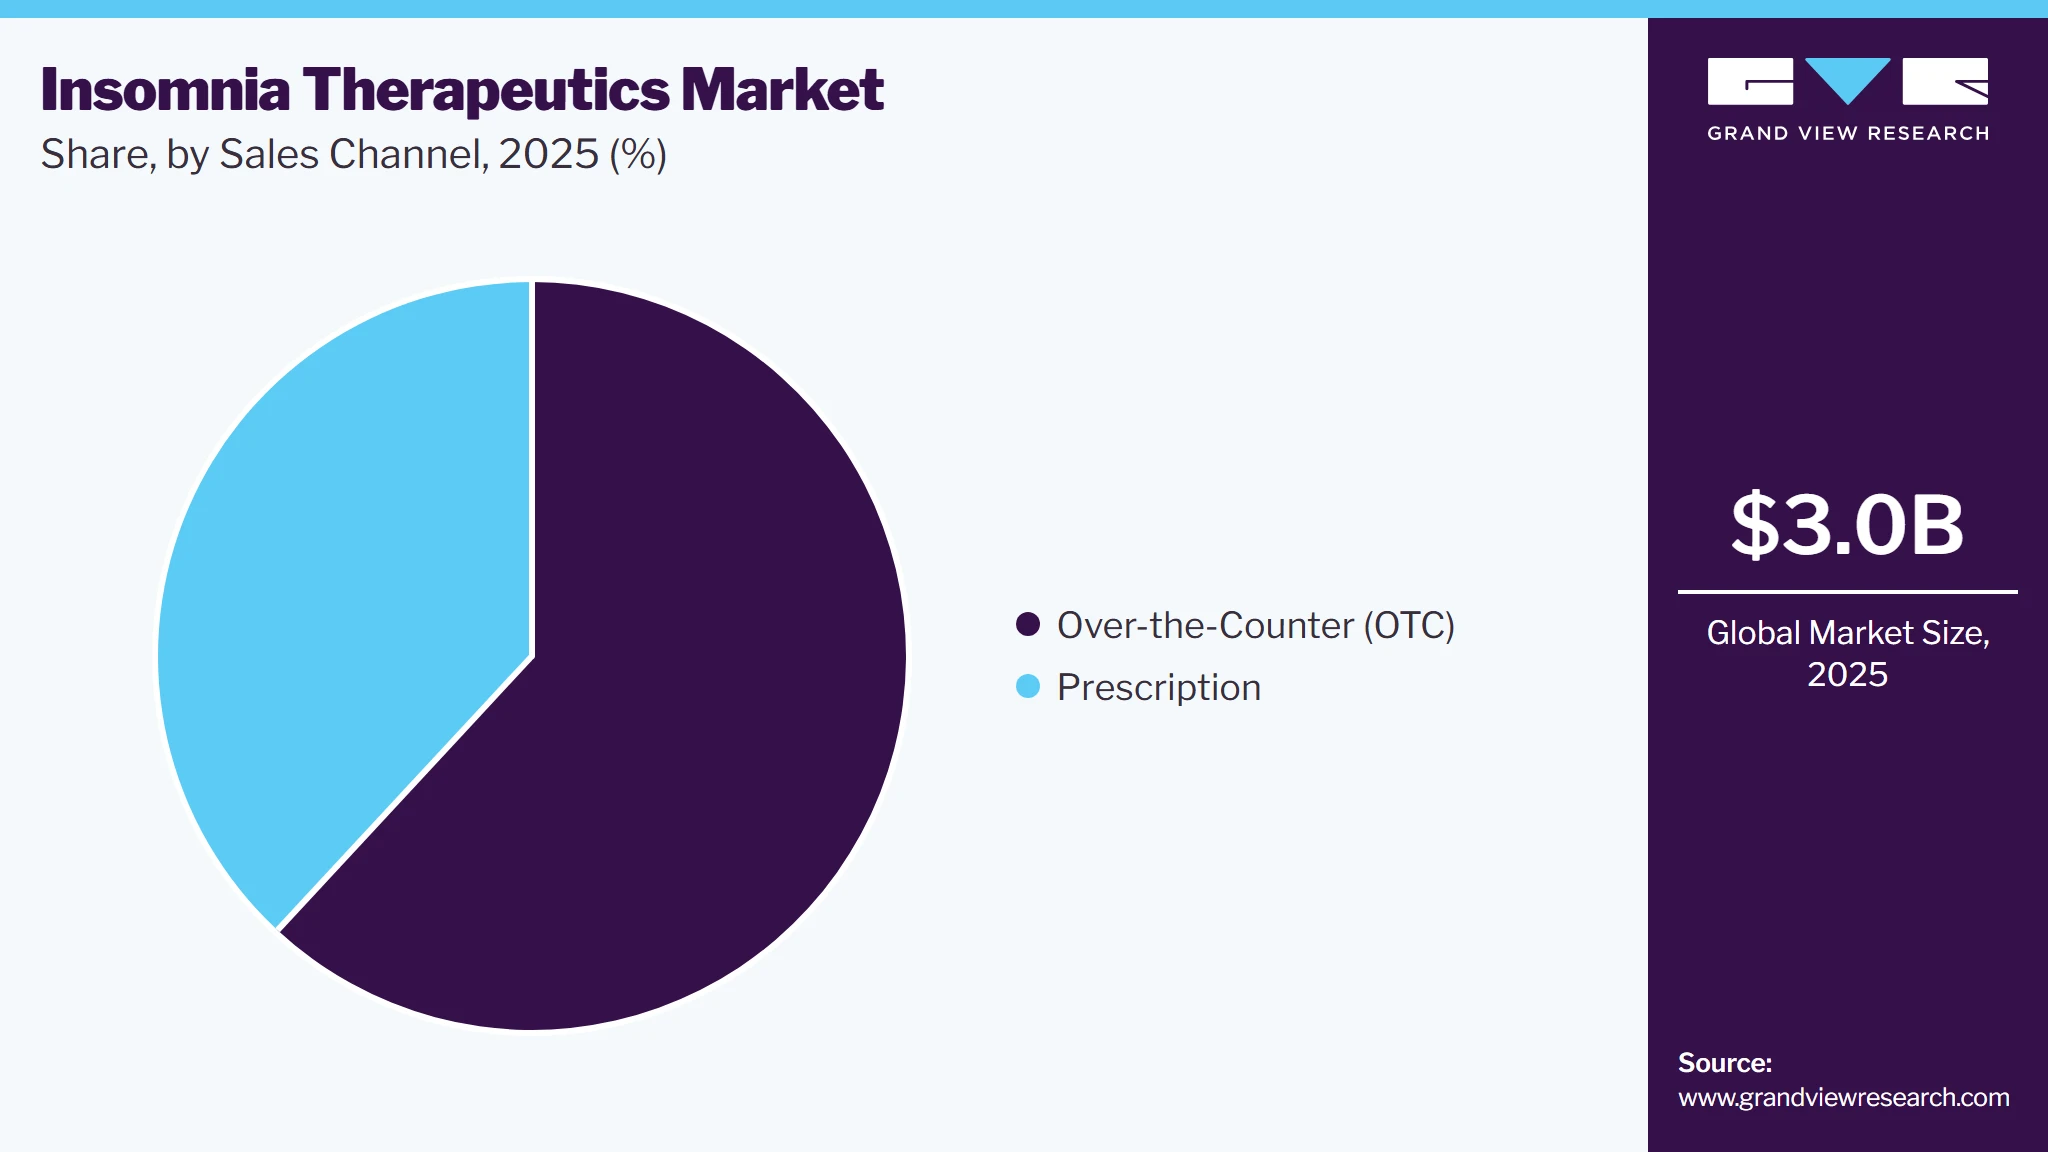
Based on sales channel, the over-the-counter (OTC) segment led the market with the largest revenue share of 61.9% in 2025, owing to the increasing number of patients with insomnia. OTC drugs do not require a prescription and are easily available to patients suffering from acute insomnia. For instance, in October 2024, Neurovalens launched Modius Sleep, an FDA-cleared medical device in the U.S., designed to treat chronic insomnia in adults through targeted neurostimulation for improved sleep quality. The emergence of combination therapies that pair OTC medications with prescription drugs or non-pharmacological interventions helps in providing more effective and personalized treatment options for patients with insomnia.
 To learn more about this report, Download Free Sample Report
Prescription therapeutics are projected to grow rapidly over the forecast period, fueled by the increasing awareness regarding drugs and their consumption amongst people. Physicians prescribe the prescription drugs after evaluating sleep disturbance patterns and a patient’s history; thereby, its reliance level is higher, and the chances of adverse effects are also less. These factors are likely to help in fostering the market growth of this segment over the forecast period.
Regional Insights
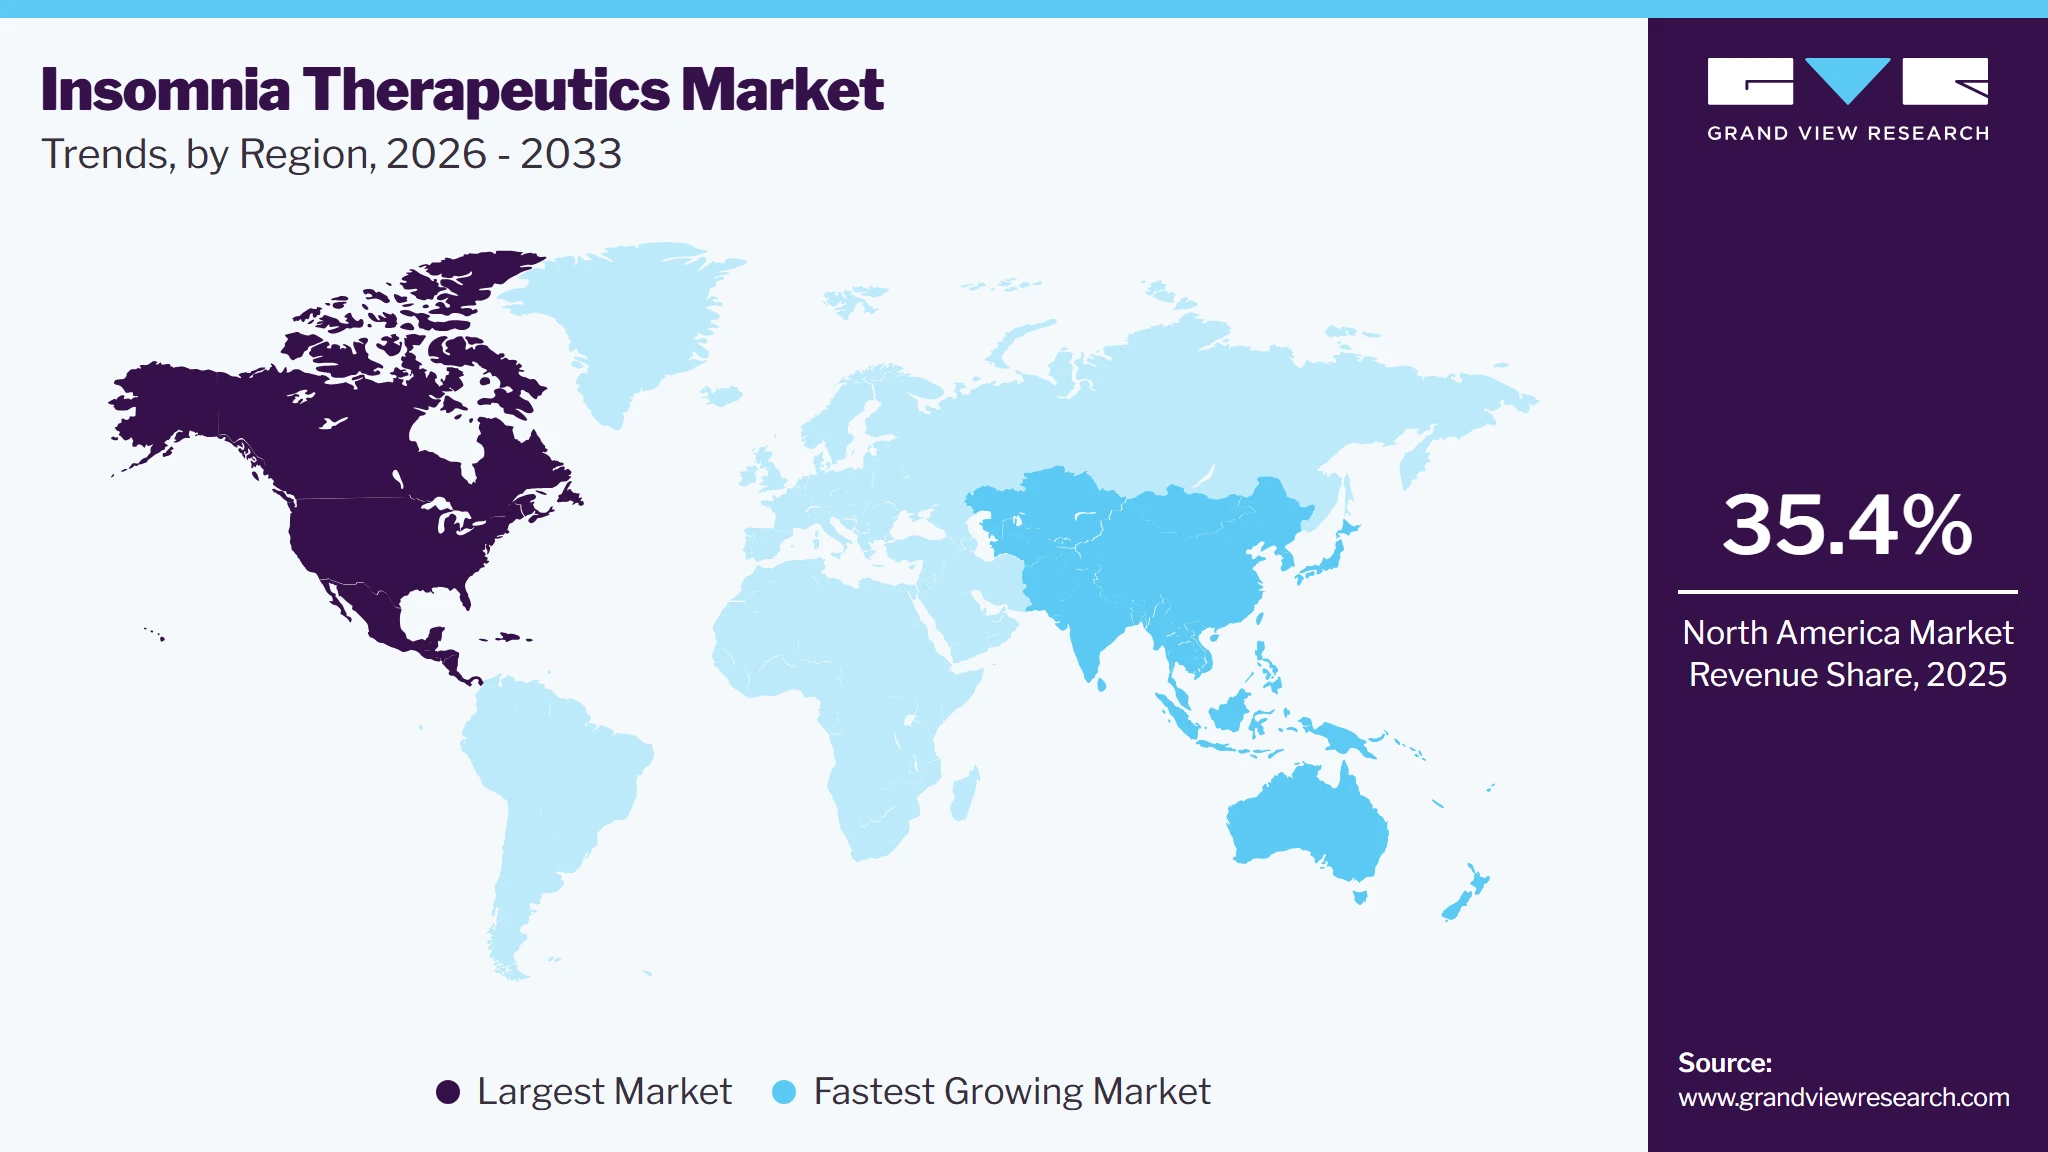
North America dominated the insomnia therapeutics market with the largest revenue share of 35.4% in 2025. Market growth in the region is due to the rising incidence of insomnia disorders, the increase in awareness levels, and high healthcare spending in this region. The American Academy of Sleep Medicine’s (AASM) Sleep Prioritization Survey 2024 highlighted concerns about adults’ sleep quality, revealing that 12% U.S. adults were diagnosed with chronic insomnia, driving insomnia therapeutics and research further. The governments in North America have been involved in creating awareness about the importance of treating insomnia and the available treatment options.
 To learn more about this report, Download Free Sample Report
U.S. Insomnia Therapeutics Market Trends
The insomnia therapeutics market in the U.S. held the largest share in the North America region in 2025, owing to the rising awareness programs and R&D facilities for new drug development. For instance, in the U.S., men (13%) were slightly more likely than women (11%) to have been diagnosed with chronic insomnia, as reported by the AASM. Meanwhile, millennials reported the highest rate of chronic insomnia diagnosis (15%). In addition, favorable reimbursement policies, rising stress levels, and a strong clinical pipeline are expected to drive the market growth over the forecast period.
Europe Insomnia Therapeutics Market Trends
Europe insomnia therapeutics market held substantial market share in 2025. Growing awareness of insomnia and the need for effective treatment has prompted educational institutions and healthcare providers to inform the public about sleep disorders. Meanwhile, advancements in drug discovery, including the development of Quviviq by Idorsia, which received FDA approval in 2022, have contributed to market growth. Lifestyle changes and work-related stress have increased the number of individuals seeking remedies for sleep issues. Despite CBT for Insomnia (CBT-I) being the recommended first-line treatment, its adoption varies across Europe, where limited availability and a dominance of hypnotic medications persist. A lack of training among CBT professionals hinders access. To combat this, experts proposed establishing a European CBT-I Academy for standardized training. Effective CBT-I incorporates behavioral and cognitive interventions, and digital treatment options have been advocated for their wide-reaching efficacy.
The insomnia therapeutics market in Germany is expected to grow in the forecast period. Current data indicates that approximately 50% of individuals with insomnia face comorbidities, such as chronic insomnia and depression. Notably, chronic insomnia was not represented in ICD-10, a gap addressed in ICD-11, effective since January 1, 2022, where it is categorized under sleep-wake disorders (code 7A00). Studies show that in Germany, the health status and quality of life of those with sleep disorders are significantly lower than that of the general population.
Asia Pacific Insomnia Therapeutics Market Trends
Asia Pacific insomnia therapeutics market is expected to register the fastest CAGR of 5.8% in the forecast period. Asia Pacific insomnia therapeutics market is anticipated to witness significant growth in the insomnia therapeutics market. Increased stress levels and shift-work sleep disorders are expected to expand the patient base in Asia Pacific. It also contributes to the growing demand for drugs in these economies. Constantly improving healthcare reimbursement policies and FDA approvals have also impacted the market growth in this region. For instance, in July 2024, Simcere Pharmaceutical announced the acceptance of the new drug application for Quviviq in China, an innovative anti-insomnia drug developed with Idorsia, successfully improving daytime functioning.
Japan insomnia therapeutics market is projected to grow at the fastest rate of 7.0% over the forecast period.Increasing awareness of mental health, urbanization, and demanding lifestyles drove demand for insomnia treatments. Factors such as traditional medicine, advancing healthcare infrastructure, and improving policies also contributed. Japan’s aging population, strong economy, and technological innovation further supported market growth, with its advanced economy and high patent registrations facilitating sleep technology development. SUSMED Med CBT-I App developed by SUSMED, Inc. received regulatory approval from the Ministry of Health, Labour and Welfare for treating insomnia patients in Japan.
Key Insomnia Therapeutics Company Insights
Some of the key companies operating in the insomnia therapeutics include Takeda Pharmaceutical Company Limited; VANDA PHARMACEUTICALS; Merck & Co., Inc. These companies are growing their market presence by launching new products, collaborations, and adopting various other strategies.
-
Takeda Pharmaceutical Company Ltd. is a Japan-based company that works for the development of insomnia therapeutics products. It also announced a co-promotion agreement with Meiji Seika Pharma Co., Ltd. for their insomnia treatment drug “ROZEREM” in Japan. Thus, using such strategies, it has been able to expand its market revenue share and its presence not only in Japan but also in other countries.
-
Merck & Co., Inc. is a U.S.-based company which works for the development of insomnia therapeutics products. It launched its insomnia treatment drug Belsomra (suvorexant), which was the first in a new class of medications called orexin receptor antagonists. This is expected to help it in expanding its portfolio of insomnia treatments and contributing to the growth of the overall insomnia therapeutics market.
Key Insomnia Therapeutics Companies
The following key companies have been profiled for this study on the insomnia therapeutics market.
- Takeda Pharmaceutical Company Limited
- VANDA PHARMACEUTICALS
- Merck & Co., Inc.
- Pfizer Inc.
- Teva Pharmaceutical Industries Ltd.
- Mylan N.V. (Viatris Inc.)
- Sumitomo Pharma Co., Ltd.
- Sanofi
- Paratek Pharmaceuticals, Inc.
- Ebb Therapeutics (Kryo)
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Takeda Pharmaceutical Company Limited, Merck & Co., Inc., Pfizer Inc., Sanofi, Teva Pharmaceutical Industries Ltd., Mylan N.V. (Viatris Inc.))
- Focus on maintaining prescription insomnia portfolios through lifecycle management, geographic expansion, and regulatory approvals. Strengthen neuroscience and central nervous system businesses through research collaborations, licensing agreements, and broad commercial distribution across hospital and retail pharmacy channels.
- Established global brands with broad commercial reach and relationships with healthcare providers. Strong manufacturing capabilities, regulatory experience, and financial resources support product availability across major markets. Diverse pharmaceutical portfolios reduce dependence on a single therapeutic area.
- Generic competition and patent expiry reduce sales of mature insomnia products. Large organizational structures may slow portfolio realignment toward newer mechanisms of action compared with focused neuroscience companies.
Emerging Players (VANDA PHARMACEUTICALS, Sumitomo Pharma Co., Ltd., Paratek Pharmaceuticals, Inc., Ebb Therapeutics (Kryo))
- Focus on expanding presence through targeted therapies, differentiated mechanisms of action, and clinical development programs for sleep disorders. Invest in product innovation, digital therapeutic approaches, and strategic partnerships to strengthen market access and broaden clinical adoption.
- Specialized focus on sleep medicine and neuroscience supports development of differentiated treatment options. Agile product development and focused research strategies enable quicker response to clinical needs and opportunities in specific patient populations.
- Limited commercial presence and smaller distribution networks compared with multinational pharmaceutical companies. Dependence on a limited number of products or pipeline assets increases business and regulatory risk, particularly during clinical development and commercialization.
Recent Developments
-
In December 2024, Shionogi and Nxera Pharma launched QUVIVIQ (daridorexant) in Japan, targeting adults with insomnia as a new treatment option in the quality of life disease area.
-
In August 2024, Big Health received FDA clearance for SleepioRx in the U.S., a digital therapeutic designed to treat chronic insomnia using Cognitive Behavioral Therapy for Insomnia (CBT-I).
-
In July 2024, the European Medicines Agency’s CHMP recommended extending Slenyto’s use to treat insomnia in children with neurogenetic disorders, addressing significant unmet needs in this patient population.
-
In February 2024, Vanda Pharmaceuticals received FDA notification regarding deficiencies in its supplemental NDA for HETLIOZ to treat insomnia, impacting further discussions on labeling and postmarketing requirements.
Insomnia Therapeutics Market Report Scope
Report Attribute
Details
Market size in 2025
USD 3.0 billion
Estimated market size in 2026
USD 3.1 billion
Projected market size by 2033
USD 4.4 billion
Growth rate
CAGR of 4.9% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, sales channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Norway; Sweden; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait.
Key companies profiled
Takeda Pharmaceutical Company Limited; VANDA PHARMACEUTICALS; Merck & Co., Inc.; Pfizer Inc.; Teva Pharmaceutical Industries Ltd.; Mylan N.V. (Viatris Inc.); Sumitomo Pharma Co., Ltd.; Sanofi; Paratek Pharmaceuticals, Inc.; Ebb Therapeutics (Kryo)
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Insomnia Therapeutics Market Report Segmentation
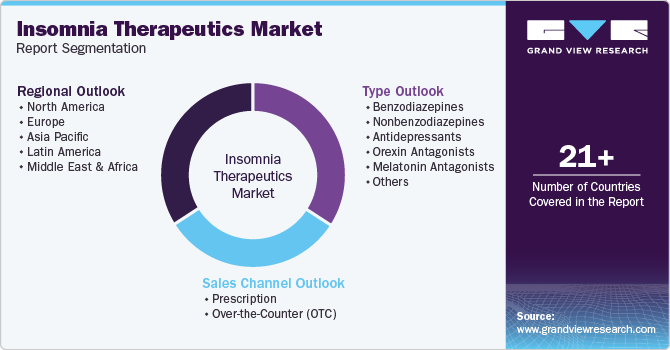
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global insomnia therapeutics market report based on type, sales channel, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Benzodiazepines
-
Nonbenzodiazepines
-
Antidepressants
-
Orexin Antagonists
-
Melatonin Antagonists
-
Others
-
-
Sales Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Prescription
-
Over-the Counter (OTC)
-
-
Regional Outlook (Revenue, USD Million; 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
APAC
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
MEA
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The insomnia therapeutics reagents market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each insomnia therapeutics reagents segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
Benzodiazepines
This segment includes prescription benzodiazepine medicines indicated for the treatment of insomnia by enhancing gamma aminobutyric acid mediated inhibitory activity in the central nervous system. It includes products prescribed for sleep initiation or maintenance and excludes nonbenzodiazepine hypnotics, antidepressants, orexin antagonists, melatonin receptor agonists, and combination products classified under other therapeutic categories.
Nonbenzodiazepines
This segment comprises prescription nonbenzodiazepine hypnotic medicines, commonly referred to as Z drugs, approved for the treatment of insomnia. These therapies selectively bind to benzodiazepine receptor sites on the gamma aminobutyric acid receptor complex to improve sleep onset or maintenance. The segment excludes benzodiazepines, antidepressants, orexin antagonists, melatonin receptor agonists, and other therapies with different mechanisms of action.
Antidepressants
This segment includes antidepressant medicines prescribed specifically for the management of insomnia because of their sedative properties, irrespective of whether insomnia is the primary or secondary indication. It covers prescription antidepressants used clinically for sleep improvement and excludes products primarily classified as benzodiazepines, nonbenzodiazepines, orexin antagonists, melatonin receptor agonists, or other insomnia therapies.
Orexin Antagonists
This segment consists of prescription dual orexin receptor antagonists approved for the treatment of insomnia by blocking orexin mediated wakefulness signaling. It includes therapies indicated for difficulties with sleep onset, sleep maintenance, or both. The segment excludes therapies acting through gamma aminobutyric acid receptors, melatonin receptors, antidepressant pathways, or any other pharmacological mechanisms.
Melatonin Agonists
This segment includes prescription melatonin receptor agonists indicated for the treatment of insomnia through activation of melatonin receptors involved in regulating the sleep and wake cycle. It excludes dietary melatonin supplements, orexin antagonists, benzodiazepines, nonbenzodiazepines, antidepressants, and all other pharmacological classes used for insomnia treatment.
Others
This segment includes all pharmacological therapies used for the treatment of insomnia that do not fall under benzodiazepines, nonbenzodiazepines, antidepressants, orexin antagonists, or melatonin agonists. It covers antihistamines, antipsychotics prescribed for insomnia, combination therapies, and other prescription or approved drug classes with distinct
Segment - Sales Channel
Revenue capture definition
Prescription
This segment includes insomnia therapeutics that require a valid prescription from a licensed healthcare professional before dispensing. It covers all prescription drug classes used for insomnia treatment irrespective of therapeutic mechanism and excludes nonprescription sleep aids available directly to consumers.
Over the Counter (OTC)
This segment includes nonprescription insomnia therapeutics that can be purchased without a physician's prescription through retail pharmacies, hospital pharmacies where applicable, online pharmacies, and other authorized sales channels. It covers approved over the counter sleep aids and excludes all prescription only insomnia medicines.
Estimation Model
 To learn more about this report, Download Free Sample Report
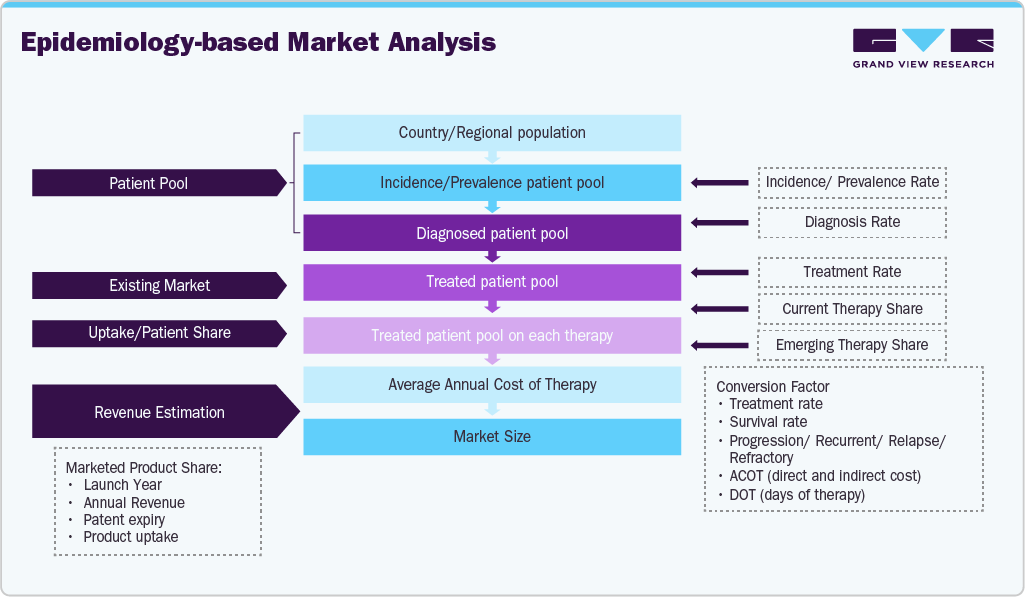
The study adopted an epidemiology-based market analysis approach to estimate the size of the global insomnia therapeutics market. Country level adult population data were evaluated to estimate the prevalence of acute and chronic insomnia using published epidemiological studies and government health databases. The diagnosed patient population was derived using diagnosis rates obtained from clinical literature and healthcare statistics. The treated patient pool was estimated by assessing prescription rates, treatment seeking behavior, and physician prescribing patterns across major markets. Patients were further segmented by therapeutic class, including benzodiazepines, nonbenzodiazepines, antidepressants, orexin receptor antagonists, melatonin receptor agonists, and other therapies. Average annual treatment cost was determined using product pricing, treatment duration, and dosing information obtained from company annual reports, regulatory documents, product labels, and healthcare databases. The market estimates were validated through primary interviews with sleep medicine specialists and industry participants.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Insomnia Therapeutics Competitive Landscape & Pipeline Assessment
Conducted a targeted assessment of the global insomnia therapeutics market, evaluating approved products, late-stage pipeline candidates, mechanisms of action, clinical development activities, regulatory progress, and competitive positioning. The study analyzed key companies including Eisai, Idorsia, Merck & Co., Inc., Takeda Pharmaceutical Company Limited, Vanda Pharmaceuticals, Sumitomo Pharma Co., Ltd., Pfizer Inc., Sanofi, Teva Pharmaceutical Industries Ltd., and other participants involved in insomnia treatment and sleep disorder research.
Helped the client identify treatment gaps, evaluate competitive products, benchmark pipeline assets, and prioritize licensing, acquisition, and partnership opportunities within the insomnia therapeutics market.
Insomnia Therapeutics Product & Clinical Benchmarking Study
Delivered a benchmarking assessment of approved insomnia therapies and pipeline products, focusing on mechanisms of action, clinical efficacy, safety profiles, treatment duration, regulatory status, and prescribing patterns. The assessment compared marketed products with pipeline candidates, evaluated clinical differentiation, intellectual property position, and product development strategies across leading companies in the insomnia therapeutics market.
Enabled the client to assess product competitiveness, identify development opportunities, compare clinical positioning across therapeutic classes, and support product development and portfolio planning decisions.
Insomnia Therapeutics Commercial Strategy & Market Access Assessment
Conducted an assessment of the commercial environment for insomnia therapeutics, evaluating product availability, distribution channels, regulatory requirements, reimbursement environment, prescribing practices, and regional market access. The study also analyzed commercialization strategies, product life cycle management, and opportunities for expanding product availability across established and developing healthcare markets.
Supported commercial planning by identifying market entry opportunities, evaluating regional expansion strategies, assessing distribution and access challenges, and strengthening product positioning across the global insomnia therapeutics market.
Frequently Asked Questions About This Report
The global insomnia therapeutics market size was valued at USD 3.0 billion in 2025 and is estimated at USD 3.1 billion for 2026.
North America dominated the insomnia therapeutics market with a 35.4% revenue share in 2025.
Asia Pacific is expected to be the fastest-growing regional market during the forecast period, driven by increasing healthcare expenditure, improving diagnosis rates, and expanding access to insomnia treatments.
The U.S. held the largest share of the North America insomnia therapeutics market in 2025, supported by high diagnosis rates, strong healthcare infrastructure, and broad availability of prescription and OTC insomnia therapies.
Key players include Takeda Pharmaceutical Company Limited, VANDA PHARMACEUTICALS, Merck & Co., Inc., Pfizer Inc., Teva Pharmaceutical Industries Ltd., Mylan N.V. (Viatris Inc.), Sumitomo Pharma Co., Ltd., Sanofi, Paratek Pharmaceuticals, Inc., and Ebb Therapeutics (Kryo).
Key factors include the rising prevalence of chronic and acute insomnia, increasing awareness of sleep health, growing stress and anxiety levels, an expanding aging population, demand for safer insomnia therapies, and continued innovation in orexin receptor antagonists and digital sleep health solutions.
The global insomnia therapeutics market is expected to grow at a CAGR of 4.9% from 2026 to 2033, reaching USD 4.4 billion by 2033.
The over-the-counter (OTC) segment dominated the market with a 61.9% revenue share in 2025.
The benzodiazepines segment accounted for the largest market share, representing 29.3% of the global revenue in 2025.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


