
- Home
- »
- Medical Devices
- »
-
Laparoscopic Gynecological Procedures Market Report 2033GVR Report cover

Laparoscopic Gynecological Procedures Market (2026 - 2033)
Size, Share & Trends Analysis Report By Procedure (Laparoscopic Hysterectomy, Laparoscopic Myomectomy), By End-use (Clinics, Ambulatory Surgery Centers, Hospitals), By Region, And Segment Forecasts
Market Size, 2025
$20.5BMarket Estimate, 2026
$21.2BMarket Forecast, 2033
$26.1BCAGR, 2026–2033
3.1%Laparoscopic Gynecological Procedures Market Summary
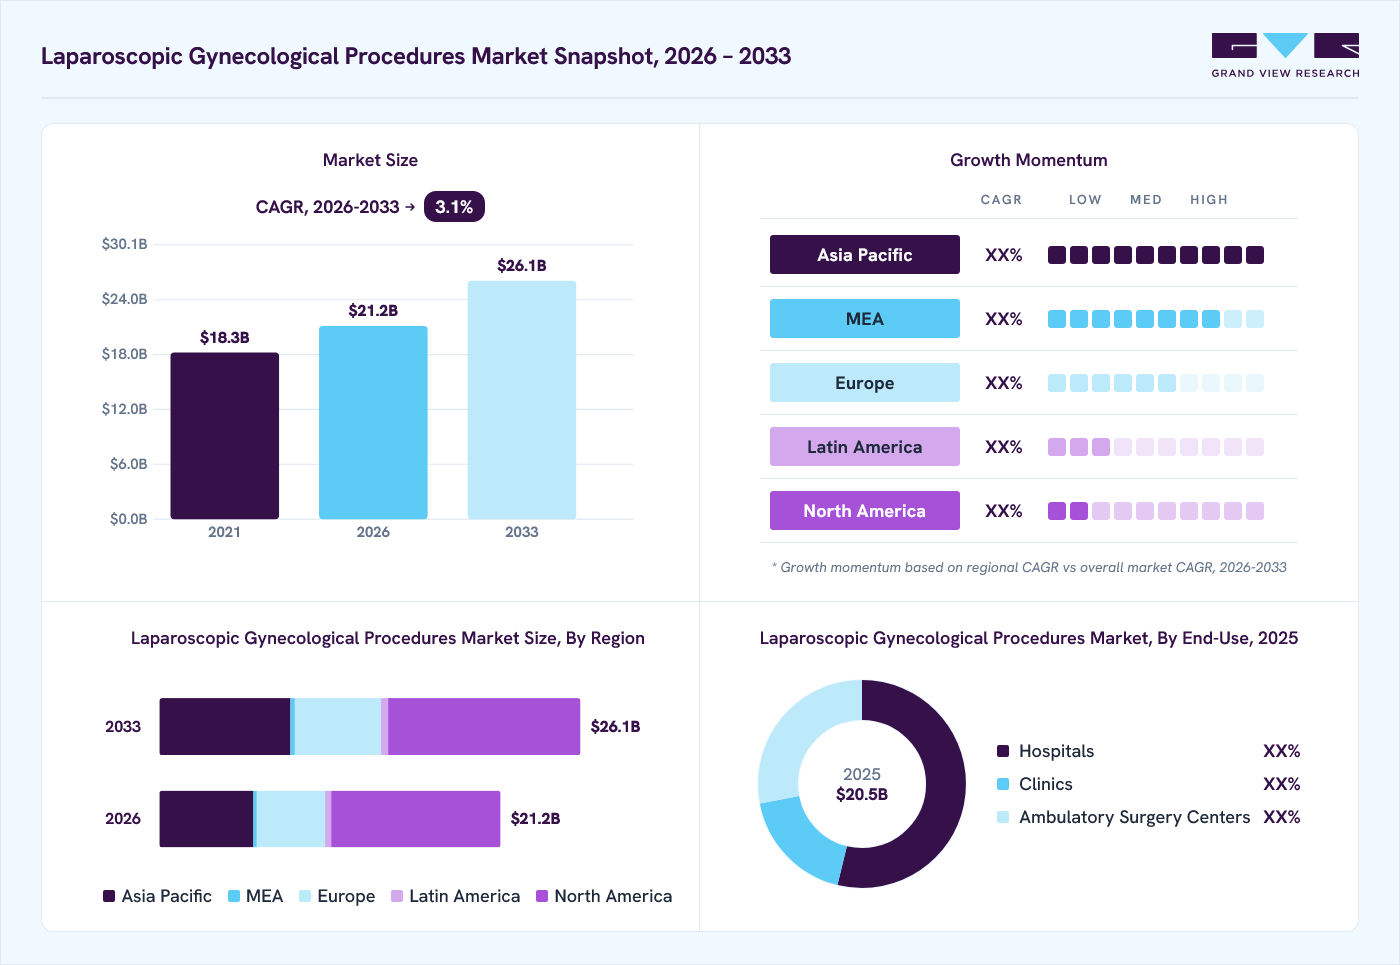
The global laparoscopic gynecological procedures market size was valued at USD 20.5 billion in 2025 and is projected to grow from USD 21.2 billion in 2026 to USD 26.1 billion by 2033, at a CAGR of 3.1% from 2026 to 2033. North America dominated the market, accounting for the largest share of 50.2% in 2025.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By procedure: Laparoscopic hysterectomy held the largest market share of 36.6% in 2025.
- By end-use: Hospitals held the largest market share of 53.7% in 2025.
Regional Highlights
- Largest regional market: North America (50.2% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market Size in 2025: USD 20.5 Billion
- Estimated Market Size in 2026: USD 21.2 Billion
- Projected Market Size by 2033: USD 26.1 Billion
- CAGR (2026-2033): 3.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Laparoscopic gynecological procedures are experiencing growth due to the increasing adoption of minimally invasive surgeries, driven by patient preference for shorter recovery times and reduced scarring; the rising prevalence of gynecological disorders, such as uterine fibroids and endometriosis; and technological advancements, including robotic-assisted surgery.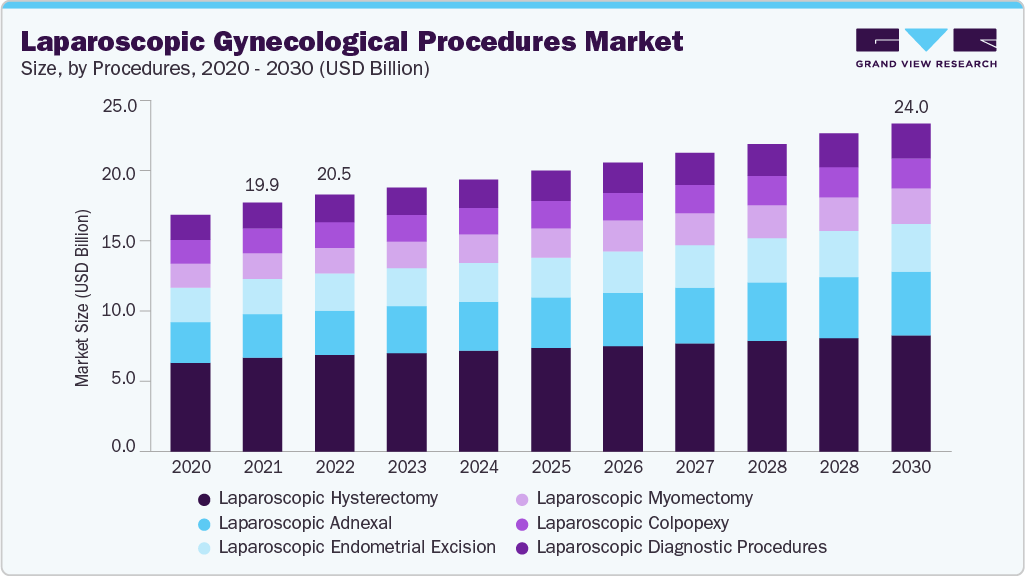 To learn more about this report, Download Free Sample Report
The growing preference for minimally invasive surgeries (MIS) is a primary driver for the rising adoption of laparoscopic gynecological procedures, particularly in the treatment of conditions such as endometriosis, fibroids, ovarian cysts, and ectopic pregnancies. Laparoscopic gynecology offers shorter recovery times, reduced hospital stays, lower postoperative complications, and minimal scarring, aligning with patient-centric trends in modern healthcare. Similarly, for healthcare providers, the increased efficiency in operating room (OR) turnover and reduced postoperative care demand are driving procedural volumes in ambulatory surgical centers (ASCs) and outpatient gynecology clinics, which is increasing their preference towards laparoscopic procedures.
“Laparoscopic procedures typically carry a reduced risk of infection, blood loss, and complications. This is especially beneficial for patients with pre-existing health conditions, as their bodies are better able to handle the minimally invasive approach. Moreover, most of the patients who have laparoscopic surgery can often go home within 24 hours and typically return to their regular activities in just a few days This is a significant advantage for patients with hectic schedules who wish to get back to their normal routines as soon as they can.”
– A Laparoscopic & General Surgeon
Moreover, surgical robots are driving innovation in the laparoscopic gynecological procedures industry by enabling enhanced precision, reproducibility, and access in complex pelvic surgeries. Advanced systems such as the da Vinci and Senhance platforms are equipped with wristed instruments, high-definition 3D visualization, and motion scaling, which enable gynecologic surgeons to perform intricate procedures, including endometriosis excision and myomectomy, with enhanced control and minimal invasiveness. For instance, the new study published by Intuitive Surgical in April 2025 highlights that robotic-assisted surgery (RAS) increases access to minimally invasive care, especially in underserved "medical deserts," by overcoming barriers such as limited surgeon training and hospital infrastructure. Hospitals adopting RAS saw higher rates of minimally invasive surgery and expanded access across diverse patient groups, improving patient outcomes. These platforms also accelerate innovation through the integration of digital capabilities, such as real-time analytics, AI-assisted image guidance, and feedback, which collectively improve surgical planning and intraoperative decision-making. Furthermore, the ability of robotic platforms to standardize techniques across varying skill levels is also transforming training and credentialing models, making complex laparoscopic procedures more widely accessible.
The demand for minimally invasive laparoscopic techniques in gynecology is further accelerated by physician training trends and technology integration. Gynecologists are increasingly opting for laparoscopic fellowships and simulation-based training platforms to improve laparoscopic skills, especially for procedures such as total laparoscopic hysterectomy (TLH), laparoscopic supracervical hysterectomy (LSH), and laparoscopic ovarian cystectomy. Market players are responding to this demand with advanced education programs. For instance, in November 2023, Ethicon, a Johnson & Johnson MedTech company, launched an AI-powered laparoscopic skills training platform at the American Association of Gynecological Laparoscopists (AAGL) Global Congress. This platform aims to enhance surgical training by providing surgeons with real-time feedback and objective performance metrics. The AI analyzes surgical techniques, offering personalized guidance to improve skills and accelerate learning. The platform's features include objective assessment of surgical performance, personalized feedback, and opportunities for repeated practice in a simulated environment, ultimately aimed at improving surgical outcomes. This innovation represents a significant advancement in surgical education and training, leveraging AI to optimize the learning process for surgeons. Such initiatives are further enhancing the laparoscopic procedure, offering capabilities of healthcare providers, further increasing the preference towards minimally invasive procedures over traditional open procedures.
The increasing prevalence of gynecological disorders such as endometriosis and uterine fibroids is significantly fueling the demand for laparoscopic interventions. Laparoscopy is increasingly preferred for the diagnosis and treatment of these conditions due to its ability to offer targeted, minimally invasive management with lower postoperative complications and faster recovery compared to open surgery. According to the World Health Organization (WHO), around 10% or approximately 190 million reproductive-age individuals globally are affected by endometriosis. Similarly, a study published in Springer Nature in May 2023 analyzed global trends in uterine fibroids from 1990 to 2019, revealing a 67% increase in incidence, 79% in prevalence, and 77% in years lived with disability. Age-period-cohort modeling indicated rising burdens, especially in low- and middle-Socio-demographic Index regions, with peak incidence at ages 35–44. This rise in gynecological procedures significantly contributes to the rise in demand for advanced laparoscopic procedures.
Moreover, the trend toward early-stage detection of gynecological conditions, driven by increased awareness and access to gynecological care, has expanded the pool of eligible patients for laparoscopic gynecological procedures. This shift is pushing healthcare facilities to invest in laparoscopic systems and training. Manufacturers of laparoscopic instruments and energy devices are capitalizing on this surge by offering disease-specific toolkits, such as fibroid morcellators and endometriosis resection kits, which are increasing procedural efficiency.
Market Dynamics
The laparoscopic gynecological procedures market is growing steadily owing to the rising inclination toward minimally invasive surgeries, high prevalence of gynecological diseases, and advances in laparoscopic surgical instruments and visualization technology. In laparoscopic gynecological procedures, specific endoscopic tools, high-quality imaging systems, and energy-based surgical equipment are used to identify and treat various gynecological ailments by reducing the need for surgical cuts, minimizing the number of days spent in the hospital, and speeding up recovery. The market includes laparoscopic hysterectomy, laparoscopic myomectomy, laparoscopic colpopexy, laparoscopic diagnostic procedures, laparoscopic endometrial excision, and laparoscopic adnexal procedures that are conducted in hospitals, specialist clinics, and ASCs. High prevalence of uterine fibroids, endometriosis, pelvic organ prolapses, ovarian cysts, gynecological cancers, along with growing awareness about minimally invasive surgery and advances in robotic-assisted laparoscopy, three-dimensional visualization systems, energy devices, and fluorescence imaging systems, are fueling the market growth.
The rising prevalence of benign and malignant conditions in the field of gynecology, as well as the growing need for minimally invasive surgical procedures, constitute some of the key drivers of the laparoscopic gynecological procedures market. The use of laparoscopic methods has been gaining more and more popularity among health care practitioners because these procedures help decrease postoperative pain, decrease blood loss, shorten the duration of stay at the hospital, and increase the cosmetic effect of the procedure. Another key driver of the market is the constant improvement of various laparoscopic visualization and energy tools.
Despite significant technological advancements, the broader adoption of laparoscopic gynecological procedures remains constrained by the high capital investment required for laparoscopic equipment, robotic surgical platforms, and advanced visualization systems. Successful execution of complex laparoscopic procedures requires specialized surgeon training, dedicated operating room infrastructure, and experienced surgical teams. Additionally, reimbursement variability, longer learning curves for advanced procedures, and limited access to minimally invasive gynecologic surgery in resource-constrained healthcare settings may restrict wider market penetration.
Market Concentration & Characteristics
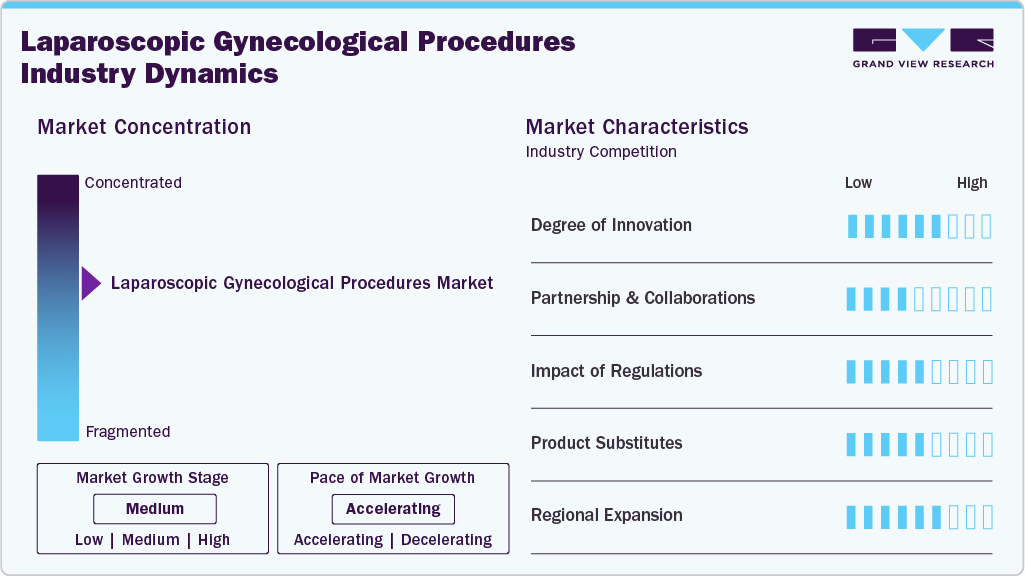
The laparoscopic gynecological procedures industry is moderately concentrated, with a mix of global Medtech leaders and specialized device makers driving innovation. Key players focus on advanced minimally invasive technologies, energy-based instruments, and robotic-assisted platforms to enhance precision and recovery times. Rising prevalence of gynecological conditions, patient preference for minimally invasive surgery, and hospital investments in laparoscopic infrastructure fuel market growth. The industry is characterized by rapid technological advancements, strategic collaborations, and continuous surgeon training initiatives. Regulatory compliance and cost efficiency remain essential competitive factors, while emerging markets offer strong expansion opportunities for both established and mid-sized device companies.
The market is experiencing significant innovation, driven by advanced technologies that enhance precision and efficiency. In June 2025, the Orlando VA Healthcare System became the first VA facility to trial the Maestro robotic assistant, a compact device allowing surgeons to operate without a bedside assistant, a notable benefit in gynecologic surgeries typically requiring two assistants. AI-driven features such as real-time camera tracking and 3D visualization tools are being integrated to improve surgical accuracy, minimize tissue trauma, and accelerate recovery. These advancements are redefining minimally invasive gynecology, expanding access to care, and positioning hospitals as innovation leaders in the market.
 To learn more about this report, Download Free Sample Report
The laparoscopic gynecological procedures market is experiencing a strong wave of mergers and acquisitions as companies expand their product portfolios and global footprint. In August 2024, KARL STORZ SE & Co. KG completed the acquisition of Asensus Surgical, making it a subsidiary. This strategic deal strengthens KARL STORZ’s position in the robotic and digital surgery segment by integrating Asensus’s advanced technologies, including the Senhance Surgical System and the in-development LUNA System. Such consolidation highlights the industry’s focus on innovation, technological leadership, and competitive expansion in minimally invasive gynecologic surgery.
Regulations play a crucial role in shaping the laparoscopic gynecological procedures industry by ensuring patient safety, device quality, and procedural standards. Strict approval pathways from regulatory bodies drive manufacturers to maintain high-quality design, clinical validation, and post-market surveillance. Compliance with standards such as sterilization, biocompatibility, and surgical precision fosters innovation while minimizing complications. Hospitals must meet accreditation and safety protocols to adopt advanced laparoscopic technologies. Additionally, evolving regulations on minimally invasive surgery promote standardized training and credentialing for surgeons. Overall, these regulations enhance clinical outcomes, build patient trust, and support the industry’s sustainable growth in advanced gynecological care.
Manufacturers are actively introducing advanced products to meet evolving clinical demands and leverage technological innovation. For example, in January 2024, Olympus Corporation launched the ESG-410 Surgical Energy Platform, an electrosurgical generator that integrates monopolar, bipolar, advanced bipolar, ultrasonic, hybrid, and PLASMA+ energy modes. This multifunctional system improves procedural efficiency and precision across multiple specialties, including gynecology, urology, and general surgery. Such product launches reflect the industry’s focus on versatility, surgical safety, and improved clinical outcomes, while strengthening manufacturers’ competitive positions in the growing minimally invasive surgery market.
The industry is experiencing strong regional expansion as companies strengthen their global presence through strategic initiatives. In January 2025, KARL STORZ SE & Co. KG, a leading provider of endoscopic and gynecological devices, acquired Swiss distributor ANKLIN to establish direct sales operations in Switzerland. This acquisition enhances customer engagement, improves service delivery, and increases operational efficiency. It also reinforces the company’s presence in gynecology, where its advanced hysteroscopic and laparoscopic solutions are widely adopted. Such regional expansions highlight the industry’s focus on localized market access and stronger customer relationships to drive sustainable growth.
Analyst Perspective
The laparoscopic gynecological procedures market continues to evolve alongside advances in minimally invasive surgery, digital operating rooms, and robotic-assisted surgical technologies. The increasing frequency of uterine fibroids, endometriosis, pelvic organ prolapse, ovarian disorders, as well as the growing tendency of patients to undergo minimally invasive surgeries, is boosting the uptake of procedures worldwide. The vendors are still investing in the development of high-resolution imaging systems, three-dimensional visualization, advanced bipolar and ultrasonic energy systems, fluorescence-guided surgery, robotic surgical systems, and ergonomically designed laparoscopic tools to facilitate surgical procedures and optimize workflow. With the continuing expansion of minimally invasive surgical programs and gynecological outpatient care in the healthcare facilities, the demand for laparoscopic surgical devices will keep growing.
Procedure Insights
The laparoscopic hysterectomy segment led the market with the largest revenue share of 36.6% in 2025, fueled by growing preference for minimally invasive techniques over open surgery. Surgeons favor this method for its shorter recovery time, lower pain, and reduced complication risks. Its broad clinical use, including for fibroids, endometriosis, adenomyosis, and early cancers, supports strong adoption. Technological advancements such as robotic-assisted surgery further enhance procedural precision and expand applications. A milestone was achieved in November 2024 when Chinese researchers performed a 1,200 km remote robotic hysterectomy using the Edge MP1000 system and 5G technology. AI integration, exemplified by Shanghai General Hospital’s AI-assisted procedures, is enhancing surgical accuracy and access globally, despite slower U.S. growth.
The laparoscopic adnexal procedures segment is projected to grow at the fastest CAGR during the forecast period. Growth is driven by the rising prevalence of ovarian and tubal conditions, including cysts, endometriosis, and ectopic pregnancies, which require precise, minimally invasive interventions. Surgeons increasingly prefer laparoscopic approaches due to reduced recovery time, lower postoperative pain, and decreased complication rates compared with open surgery. Technological innovations, such as advanced energy devices, high-definition imaging, and robotic-assisted platforms, are enhancing procedural accuracy and safety. Expanding access to skilled surgeons and rising awareness of minimally invasive options further support the rapid adoption of laparoscopic adnexal procedures worldwide.
End-use Insights
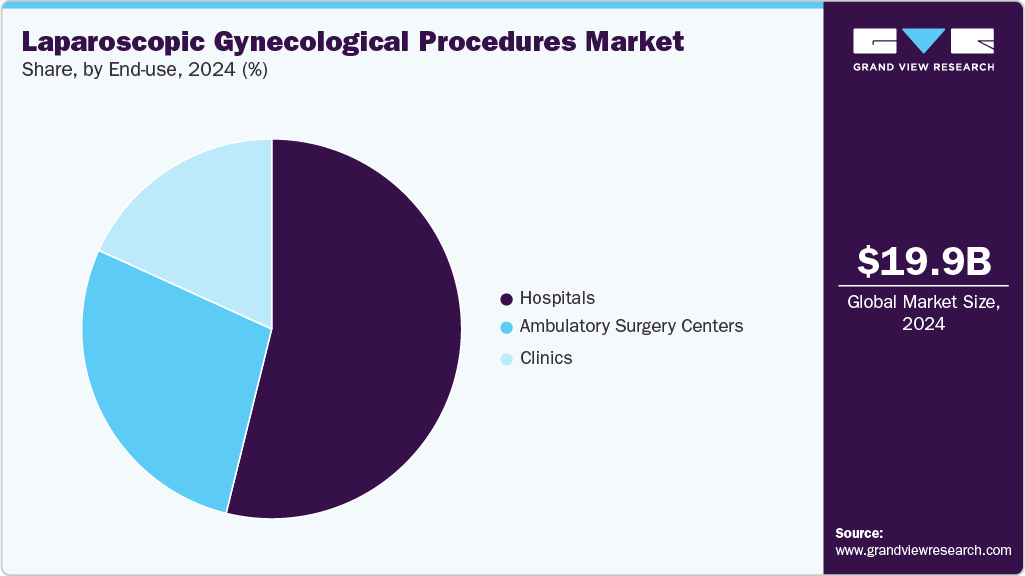
The hospitals segment led the laparoscopic gynecological procedures market with the largest revenue share of 53.7% in 2025. Hospitals dominate due to their advanced infrastructure, availability of specialized surgical teams, and access to high-end laparoscopic and robotic-assisted technologies. They are equipped to handle complex gynecological cases, including hysterectomies, adnexal surgeries, and endometriosis treatment, which require multidisciplinary support and postoperative care. Additionally, hospitals invest heavily in training, equipment maintenance, and the adoption of innovative surgical platforms, ensuring higher procedural efficiency and patient safety. Their capacity to serve both routine and high-risk cases positions them as the primary end users driving market demand and growth.
 To learn more about this report, Download Free Sample Report
The ambulatory surgery centers (ASCs) segment is expected to grow at the fastest CAGR over the forecast period. Growth is driven by increasing patient preference for outpatient care due to lower costs, shorter hospital stays, and faster recovery compared with traditional hospital settings. ASCs are adopting minimally invasive and robotic-assisted laparoscopic technologies to efficiently perform procedures such as hysterectomies, adnexal surgeries, and diagnostic laparoscopy. Rising investment in modern surgical infrastructure, coupled with supportive healthcare policies and growing awareness of outpatient surgical options, is fueling the expansion of ASCs, making them a key growth driver in the laparoscopic gynecology market.
Regional Insights
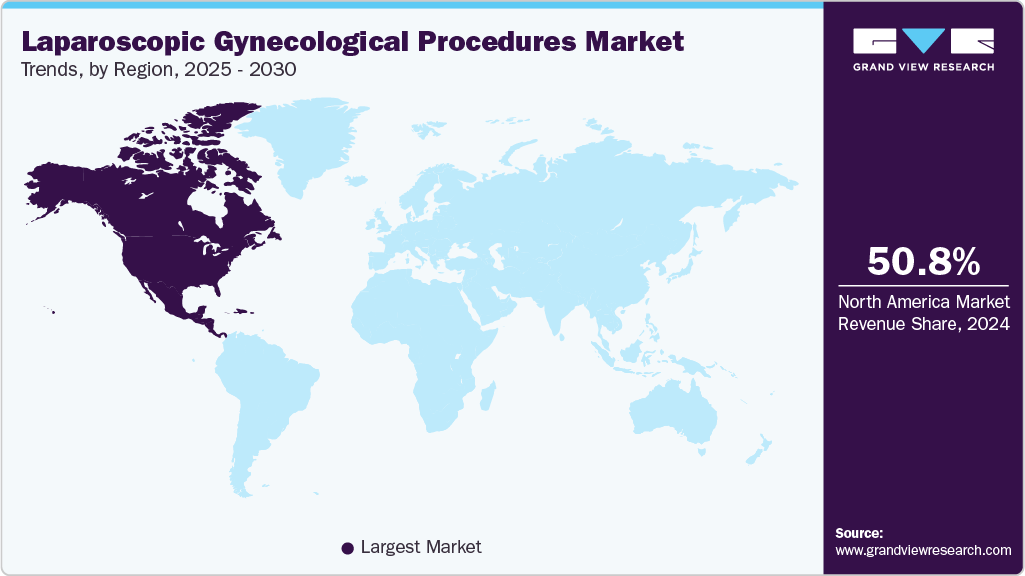
The North America laparoscopic gynecological procedures marketheld the largest share of 50.2% in 2025. The growth is driven by the increasing prevalence of gynecological conditions such as endometriosis, uterine fibroids, and ovarian cysts, which often necessitate minimally invasive surgical interventions. Technological advancements in laparoscopic equipment, leading to improved precision, reduced invasiveness, and faster recovery times, are also driving market expansion. Furthermore, the rising patient preference for minimally invasive procedures over traditional open surgeries, coupled with increasing healthcare expenditure and the presence of a well-established healthcare infrastructure in North America, contributes to market growth.
 To learn more about this report, Download Free Sample Report
U.S. Laparoscopic Gynecological Procedures Market Trends
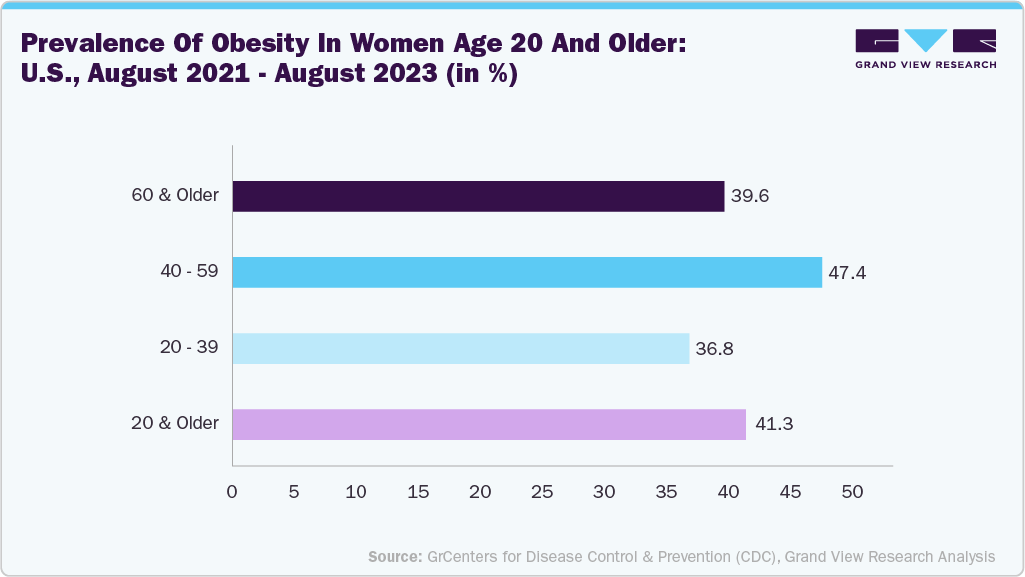
The U.S. laparoscopic gynecological procedures industry led North America in 2025, driven by the rising incidence of gynecological conditions that require surgical intervention, such as uterine fibroids, endometriosis, and ovarian cysts. According to the Society for Women’s Health Research, uterine fibroids affect around 26 million women in the U.S. aged between 15 and 50. Moreover, the prevalence of symptomatic uterine fibroids among women has significantly increased, partly due to delayed childbearing, obesity, and lifestyle-related hormonal imbalances. The demand for surgical management of these conditions is further supported by the growing number of women seeking fertility-preserving procedures, particularly among women in their late 30s and early 40s. Thus, the growing disease burden, coupled with early diagnosis and a surgical preference for laparoscopy, is directly contributing to growth in procedure volume.
 To learn more about this report, Download Free Sample Report
Europe Laparoscopic Gynecological Procedures Market Trends
The Europe laparoscopic gynecological procedures industry held a significant revenue share in 2025, driven by a shift in surgical practices, as clinicians across the region increasingly prioritize minimally invasive techniques over conventional open surgeries. This shift is driven largely by the clinical advantages of laparoscopy, including reduced patient trauma, shorter hospital stays, and faster postoperative recovery. Hospital procurement policies are also evolving to support this transition, with a number of health care centers favoring investments in advanced laparoscopic instruments and imaging systems.
The UK laparoscopic gynecological procedures market is experiencing steady growth. One of the primary drivers is the growing clinical confidence in laparoscopy due to its minimally invasive nature, which leads to shorter hospital stays and faster patient recovery. In the UK, NHS hospitals and private healthcare institutions are increasingly adopting laparoscopic technologies to optimize bed turnover rates. The increasing prevalence of various gynecological conditions in the UK is further increasing the volume of gynecological procedures performed in the country. For instance, according to Endometriosis UK, endometriosis affects around 1 in 10 women and individuals assigned female at birth within their reproductive years, making it the second most prevalent gynecological condition in the country.
The laparoscopic gynecological procedures market in Germany is experiencing steady growth, driven by demographic and clinical factors. An aging female population and rising incidence of gynecological conditions, such as endometriosis and fibroids, increase demand for surgical interventions. Delayed childbirth has led to more reproductive health complications requiring procedures like laparoscopic myomectomy and endometriosis ablation. Preference for minimally invasive techniques among both patients and gynecologists supports adoption, as these approaches reduce hospital stays and enhance recovery. Germany’s advanced hospital infrastructure further facilitates widespread implementation of laparoscopic procedures, expanding the patient pool and reinforcing market growth in the country.
The laparoscopic gynecological procedures market in France is growing steadily, fueled by the rising adoption of minimally invasive techniques. The increasing prevalence of conditions such as endometriosis, uterine fibroids, and ovarian cysts drives demand for laparoscopic interventions. Greater public awareness, supported by government initiatives, further encourages utilization. For example, in January 2022, France launched a national strategy to address endometriosis, affecting 1 in 10 women globally. The program focuses on education, early diagnosis, specialized treatment centers, and research into the disease’s causes. These measures are expected to expand the patient pool and promote wider adoption of laparoscopic gynecological procedures.
Asia Pacific Laparoscopic Gynecological Procedures Market Trends
The Asia-Pacific laparoscopic gynecological procedures industry is rapidly growing due to the rising prevalence of gynecological conditions, expanding healthcare infrastructure, and increasing adoption of minimally invasive techniques. Women increasingly prefer laparoscopic procedures for benefits like reduced pain, shorter hospital stays, and faster recovery. Growth is supported by medical tourism, with patients seeking high-quality, cost-effective care in countries such as India and Thailand. Expansion of private hospitals and specialized clinics, investment in advanced surgical equipment, and training for skilled surgeons enhance access to procedures. Additionally, government initiatives promoting women’s health and healthcare development create a favorable environment for sustained market growth.
The laparoscopic gynecological procedures market in Japan is witnessing robust growth, driven by increasing adoption of minimally invasive techniques, which offer faster recovery, reduced pain, and lower complication rates compared with open surgery. With approximately 32% of Japanese women aged 65 or older in 2023 (World Bank), demand for efficient, safe procedures is rising. Awareness among patients and providers, supported by educational initiatives and professional societies, is enhancing adoption. Technological advancements, such as sophisticated instruments, 3D imaging, and robotic systems like the da Vinci SP, approved in September 2022, are expanding the range of treatable conditions and improving precision, safety, and procedural outcomes.
The China laparoscopic gynecological procedures market is steadily expanding, driven by the rising prevalence of conditions such as uterine fibroids, endometriosis, and ovarian cysts. With 16% of Chinese women aged 65 and above in 2023 (up from 10% in 2013, World Bank), the patient pool for minimally invasive treatments is growing. Increasing awareness among patients and healthcare providers, coupled with government investments in healthcare infrastructure and professional training, supports adoption. Technological advancements, including Shanghai-based MicroPort MedBot’s Toumai four-arm laparoscopic surgical robot approved in March 2024, enhance precision, safety, and accessibility, lowering costs and broadening procedural applications, fueling market growth.
Latin America Laparoscopic Gynecological Procedures Market Trends
The laparoscopic gynecological procedures industry in Latin America is gradually expanding, fueled by the rising prevalence of conditions like endometriosis and uterine fibroids linked to changing lifestyles. Demand for minimally invasive surgeries is increasing due to faster recovery, reduced scarring, and improved patient outcomes. Technological advancements, the availability of trained professionals, and government initiatives to enhance healthcare infrastructure and promote medical tourism in countries such as Brazil and Mexico further support growth. Greater awareness among patients and providers regarding the benefits of laparoscopic procedures also drives adoption. These factors collectively strengthen the region’s market for advanced gynecological minimally invasive surgeries.
MEA Laparoscopic Gynecological Procedures Market Trends
The laparoscopic gynecological procedures industry in the Middle East and Africa (MEA) is experiencing steady growth, driven by the rising prevalence of conditions like endometriosis, uterine fibroids, and ectopic pregnancies. Increasing awareness among patients and healthcare professionals, supported by educational campaigns and technological advancements, is boosting adoption. Expanding healthcare expenditure, government initiatives, and private hospital investments in advanced surgical infrastructure further support growth. For example, in May 2023, Burjeel Medical City in Abu Dhabi launched an Advanced Gynecology Institute with laparoscopic and robotic surgical suites. These developments enhance access to minimally invasive treatments, improving patient outcomes and quality of life.
The laparoscopic gynecological procedures market in Saudi Arabia is growing rapidly, driven by government initiatives under Vision 2030 to modernize healthcare infrastructure and invest in advanced surgical technologies. Minimally invasive techniques such as laparoscopy are increasingly adopted for their shorter recovery times and lower surgical risks. High prevalence of gynecological conditions, including endometriosis affecting approximately 10% of women of reproductive age, uterine fibroids, and chronic health issues such as obesity, further drives demand. Integration of robotic-assisted systems and high-definition imaging enhances procedural precision and efficiency, supporting Saudi Arabia’s goal to become a leading healthcare hub in the Middle East.
Key Laparoscopic Gynecological Procedures Company Insights
Market players are involved in implementing strategic initiatives to hold a prominent share in the market. One key area of focus is continuous innovation through product launches and upgrades. Companies regularly introduce new laparoscopic gynecological procedures, systems, and technologies that offer enhanced capabilities in sensitivity and data analysis.
Key Laparoscopic Gynecological Procedures Companies:
The following key companies have been profiled for this study of the laparoscopic gynecological procedures market.
-
Medtronic
-
Stryker
-
Karl Storz SE & CO. Kg
-
Johnson and Johnson
-
Olympus Corporation
-
CONMED Corporation
-
B. Braun SE
-
CooperCompanies
-
Richard Wolf GmbH
-
Microline Surgical
-
Welfare Medical Ltd.
-
Intuitive Surgical
-
Shenzhen Mindray Bio Medical Electronics Co., Ltd.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Medtronic; Stryker; KARL STORZ SE & Co. KG; Johnson & Johnson; Olympus Corporation; CONMED Corporation; B. Braun SE; Cooper Companies; Intuitive Surgical; Shenzhen Mindray Bio-Medical Electronics Co., Ltd.)
Established companies focus on comprehensive minimally invasive surgical portfolios by integrating laparoscopic visualization systems, high-definition and 3D imaging platforms, energy devices, insufflation systems, robotic-assisted technologies, advanced surgical instruments, and digital operating room solutions. They emphasize continuous product innovation, surgeon training programs, regulatory approvals, strategic hospital partnerships, and global distribution expansion to strengthen market leadership.
Strong global distribution networks, diversified minimally invasive surgery portfolios, advanced R&D capabilities, extensive installed base, established clinical evidence, integrated operating room solutions, and long-standing relationships with hospitals provide sustainable competitive advantages.
Dependence on hospital capital expenditure, premium equipment pricing, lengthy procurement cycles, and increasing competition from regional manufacturers and emerging robotic surgery providers may impact market growth.
Emerging Players (Richard Wolf GmbH; Microline Surgical; Welfare Medical Ltd.)
Emerging companies prioritize development of cost-effective laparoscopic instruments, disposable surgical devices, specialized gynecological instruments, compact visualization platforms, and application-specific technologies. They focus on innovation, regional expansion, strategic distribution partnerships, and product differentiation to strengthen commercialization across developing healthcare markets.
Competitive pricing, specialized laparoscopic expertise, manufacturing flexibility, innovative disposable products, and responsiveness to evolving clinical requirements support adoption among hospitals and ambulatory surgery centers.
Limited global commercial infrastructure, smaller installed customer base, lower brand recognition, dependence on distributor partnerships, and relatively limited product portfolios may restrict international market expansion compared with established multinational companies.
Recent Developments
-
In May 2025, B. Braun Thailand partnered with the Thai-German Multidisciplinary Endoscopic Training (TG-MET) Center to advance laparoscopic gynecology training for resident physicians. The collaboration focuses on improving surgical proficiency and patient outcomes through education, global knowledge exchange, and hands-on experience, enhancing B. Braun’s commitment to enhancing minimally invasive gynecologic care in Thailand.
-
In April 2024, Medtronic introduced 14 new AI algorithms to enhance its digital capabilities in post-operative analysis for laparoscopic and robotic-assisted surgery. These algorithms, integrated within the Touch Surgery ecosystem, provide surgical insights across various procedures, including cholecystectomy, sleeve gastrectomy, and hysterectomy.
“We continue to advance our digital ecosystem with a focus on seamless connectivity. We’re excited to now be connecting surgeons during operations and connecting them with richer insights - all in a solution designed for them. Medtronic has been putting technology into surgeons' hands for more than 60 years and we're continuing this innovation with software and computing. We not only amplify surgical performance but also nurture a new generation of world-class surgical educators.”
- Vice president and general manager, Digital Technologies within the Surgical business, which is part of the Medical Surgical Portfolio at Medtronic
Laparoscopic Gynecological Procedures Market Report Scope
Report Attribute
Details
Market size in 2025
USD 20.5 billion
Estimated market size in 2026
USD 21.2 billion
Projected market size by 2033
USD 26.1 billion
Growth rate
CAGR of 3.1% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD Million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Procedure, end-use, region
Regional scope
North America, Europe, Asia Pacific, Latin America, MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; Japan; China; India; Australia; Thailand; South Korea; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Medtronic; Stryker; Karl Storz SE & CO. Kg; Johnson and Johnson; Olympus Corporation; CONMED Corporation; B. Braun SE; CooperCompanies; Richard Wolf GmbH; Microline Surgical; Welfare Medical Ltd.; Intuitive Surgical; Shenzhen Mindray Bio Medical Electronics Co., Ltd.
Customization scope
Free report customization (equivalent to 8 analyst’s working days) with purchase. Addition or alteration to country, regional & segment scope
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Laparoscopic Gynecological Procedures Market Report Segmentation
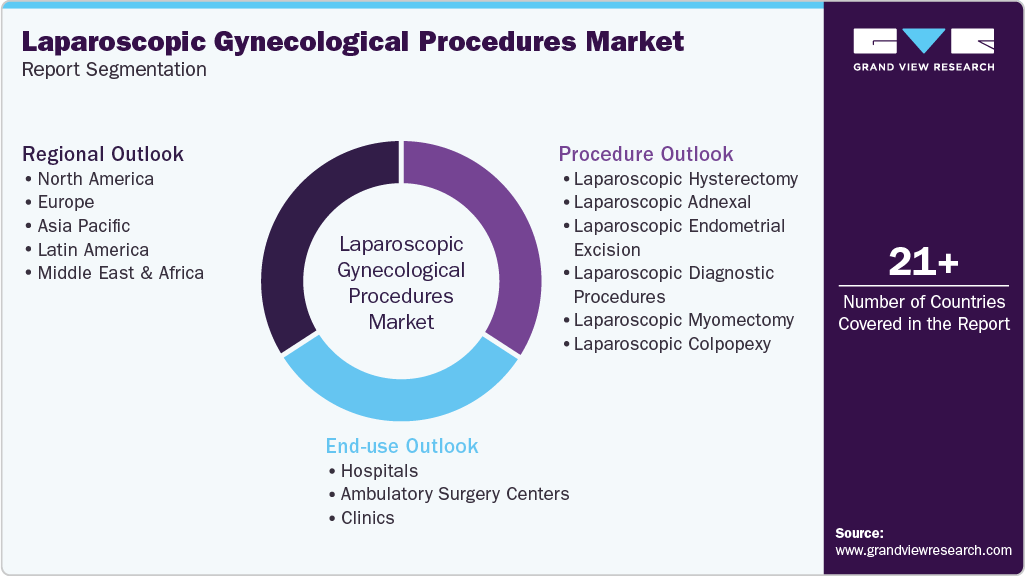
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global laparoscopic gynecological procedures market report based on procedure, end-use, and region:
 To learn more about this report, Download Free Sample Report
-
Procedure Outlook (Revenue, USD Million, 2021 - 2033)
-
Laparoscopic Hysterectomy
-
Laparoscopic Adnexal
-
Laparoscopic Endometrial Excision
-
Laparoscopic Diagnostic Procedures
-
Laparoscopic Myomectomy
-
Laparoscopic Colpopexy
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Ambulatory Surgery Centers
-
Clinics
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The laparoscopic gynecological procedures market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each laparoscopic gynecological procedures segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment –Procedure
Revenue capture definition
Laparoscopic Hysterectomy
Revenue is generated through laparoscopic systems, visualization platforms, energy devices, trocars, insufflation systems, disposable instruments, and surgical accessories utilized during minimally invasive uterine removal procedures. Manufacturers capture revenue through capital equipment sales, disposable consumables, maintenance agreements, and service contracts.
Laparoscopic Myomectomy
Revenue is derived from laparoscopic instruments, tissue extraction devices, advanced suturing systems, energy platforms, and imaging technologies supporting minimally invasive removal of uterine fibroids. Increasing preference for fertility-preserving procedures continues to support demand within this segment.
Laparoscopic Colpopexy
Revenue is generated through laparoscopic surgical devices, mesh fixation systems, advanced visualization equipment, suturing instruments, and energy devices utilized for pelvic organ prolapse repair. Manufacturers benefit from recurring sales of disposable accessories and specialized surgical instruments.
Laparoscopic Diagnostic Procedures
Revenue is derived from laparoscopic visualization systems, endoscopes, insufflation equipment, trocars, imaging systems, and disposable instruments utilized for diagnostic evaluation of pelvic pain, infertility, endometriosis, and other gynecological conditions. Growing diagnostic laparoscopy volumes continue to support equipment utilization.
Laparoscopic Endometrial Excision
Revenue is generated through laparoscopic energy devices, dissection instruments, advanced visualization systems, and specialized surgical tools supporting minimally invasive treatment of endometriosis. Increasing awareness of early intervention continues to drive procedural volumes.
Laparoscopic Adnexal
Revenue is derived from laparoscopic systems utilized during ovarian cystectomy, salpingectomy, oophorectomy, and other adnexal surgeries. Manufacturers generate revenue through laparoscopic instruments, energy devices, imaging systems, disposable consumables, and service agreements.
Segment – End use
Revenue capture definition
Hospitals
Revenue is generated through procurement and utilization of laparoscopic towers, visualization systems, energy devices, surgical instruments, and disposable accessories by tertiary hospitals, academic medical centers, and multispecialty healthcare institutions performing advanced gynecological surgeries. Manufacturers benefit from capital equipment sales, long-term service agreements, and recurring consumable purchases.
Clinics
Revenue is derived from specialty gynecology clinics adopting compact laparoscopic systems and minimally invasive surgical technologies for elective gynecological procedures. Increasing outpatient surgical volumes continue to support equipment utilization and consumable demand.
Ambulatory Surgery Centers
Revenue is generated through adoption of minimally invasive laparoscopic platforms by ambulatory surgery centers performing same-day gynecological procedures. Growing preference for outpatient surgery, reduced hospitalization, and cost-effective treatment continues to support expansion within this segment.
Estimation Model
Title
Key Question
Process Steps
Data Sources
Scope Definition
What is being sized?
1. Define Laparoscopic Gynecological Procedures Market Scope
2. Scope Procedure, and End-Use Segments
3. Establish Geographic Coverage (Global/Regional)
4. Align on base year and forecast horizon (2026–2033)
FDA, CE MDR, ACOG Guidelines, ESGE Guidelines
Estimate Fusion Biopsy Procedure Volume
How large is total addressable market?
1. Estimate Annual Gynecological Procedure Volumes
2. Segment Procedures by its Procedure Types (minimally invasive vs open surgeries)
3. Assess Adoption Rates Of Minimally Invasive Gynecological Surgery
4. Forecast Procedure Growth
Hospital Procedure Databases, National Surgical Registries
Estimate Technology Utilization
What portion of procedures utilize advanced laparoscopic technologies?
1. Evaluate Utilization of Laparoscopic Towers, Energy Devices, and Surgical Instruments
2. Evaluate Utilization Across Healthcare Settings
3. Analyze Equipment Utilization, Disposable Consumption, and Surgeon Adoption
4. Validate Through Industry Interviews
Primary interviews, clinical surveys, industry experts
Revenue Conversion
How does volume become revenue?
1. Determine Procedure Cost By Region
2. Estimate Hospital Fees and Physician Cost
3. Apply Regional Pricing Variations
4. Cross-validate with Company Revenues and Public Findings
Company Annual Reports, Distributor pricing sheets, procurement data, expert interviews
Customization Table
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
Competitive Landscape Analysis
Conducted a comprehensive assessment of leading manufacturers of laparoscopic gynecological surgical technologies by evaluating laparoscopic imaging systems, energy devices, trocars, insufflation systems, surgical instruments, robotic-assisted platforms, visualization technologies, regulatory approvals, product portfolios, pricing strategies, geographic presence, strategic partnerships, mergers and acquisitions, manufacturing capabilities, and research & development initiatives. The assessment benchmarked established and emerging participants to identify technology leadership, product differentiation, and commercialization strategies across the minimally invasive gynecological surgery market.
Enables stakeholders to benchmark technology leadership, identify innovation trends in minimally invasive gynecological surgery, evaluate competitive positioning, compare product portfolios, assess partnership opportunities, and formulate commercialization, procurement, investment, and product development strategies within the laparoscopic surgery market.
Segment by Application Analysis
Conducted a detailed assessment of laparoscopic technology adoption across hysterectomy, myomectomy, colpopexy, diagnostic laparoscopy, endometrial excision, and adnexal procedures performed in hospitals, specialty clinics, and ambulatory surgery centers. The study evaluated annual procedure volumes, technology utilization, equipment procurement trends, disposable instrument consumption, workflow efficiency, surgeon adoption, and minimally invasive surgery penetration to estimate demand across each market segment.
Enables stakeholders to identify high-growth procedural segments, optimize commercialization strategies, prioritize product development, understand procurement and utilization trends, forecast equipment and consumable demand, and support strategic planning across hospitals, specialty clinics, and ambulatory surgical centers.
Macroeconomic Analysis
Conducted an in-depth assessment of gynecological disease prevalence, female population demographics, healthcare expenditure, surgical infrastructure development, reimbursement policies, minimally invasive surgery adoption, regulatory developments, hospital investments, and technological advancements influencing demand for laparoscopic gynecological procedures. The study also evaluated trends in outpatient surgery, robotic-assisted surgery adoption, government healthcare initiatives, and women's health programs shaping long-term market growth across developed and emerging healthcare markets.
Enables stakeholders to understand demographic, epidemiological, economic, regulatory, and healthcare system factors influencing demand within the laparoscopic gynecological procedures market. The study supports long-term forecasting, manufacturing capacity planning, pricing strategy development, regional market expansion decisions, investment prioritization, and evaluation of future growth opportunities driven by advances in minimally invasive surgery and women's healthcare.
Frequently Asked Questions About This Report
Key factors that are driving the laparoscopic gynecological procedures market growth include the Increasing adoption of minimally invasive surgeries over traditional methods, the increasing prevalence of colorectal cancer, and other surgery-related technological advancements.
Laparoscopic hysterectomy held the largest market share of 36.6% in 2025, while laparoscopic adnexal procedures segment is fastest growing procedure.
hospitals segment led with a 53.7% revenue share in 2025, while ambulatory surgery centers segment is fastest growing segment.
Asia Pacific is the fastest-growing region over the forecast period.
The global laparoscopic gynecological procedures market size was valued at USD 20.5 billion in 2025 and is estimated at USD 21.2 billion for 2026.
The global laparoscopic gynecological procedures market is expected to grow at a CAGR of 3.1% from 2025 to 2030, reaching USD 26.1 billion by 2033.
North America dominated the laparoscopic gynecological procedures market with a share of 50.2% in 2025.
Some of the key players operating in the laparoscopic gynecological procedures market include Medtronic; Stryker; Karl Storz SE & CO. Kg; Johnson and Johnson; Olympus Corporation; CONMED Corporation; B. Braun SE; CooperCompanies; Richard Wolf GmbH; Microline Surgical; Welfare Medical Ltd.; Intuitive Surgical; Shenzhen Mindray Bio Medical Electronics Co., Ltd.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


