
- Home
- »
- Pharmaceuticals
- »
-
Liver Cancer Drug Market Size, Share Report, 2026-2033GVR Report cover

Liver Cancer Drug Market (2026 - 2033)
Size, Share & Trends Analysis Report By Therapy (Targeted Therapy, Immunotherapy, Chemotherapy), By Type (Hepatocellular Carcinoma), By Distribution Channel (Hospital Pharmacies, Retail Pharmacies), By Region, And Segment Forecasts
Market Size, 2025
$4.3BMarket Estimate, 2026
$5.0BMarket Forecast, 2033
$14.3BCAGR, 2026–2033
16.3%Liver Cancer Drug Market Summary
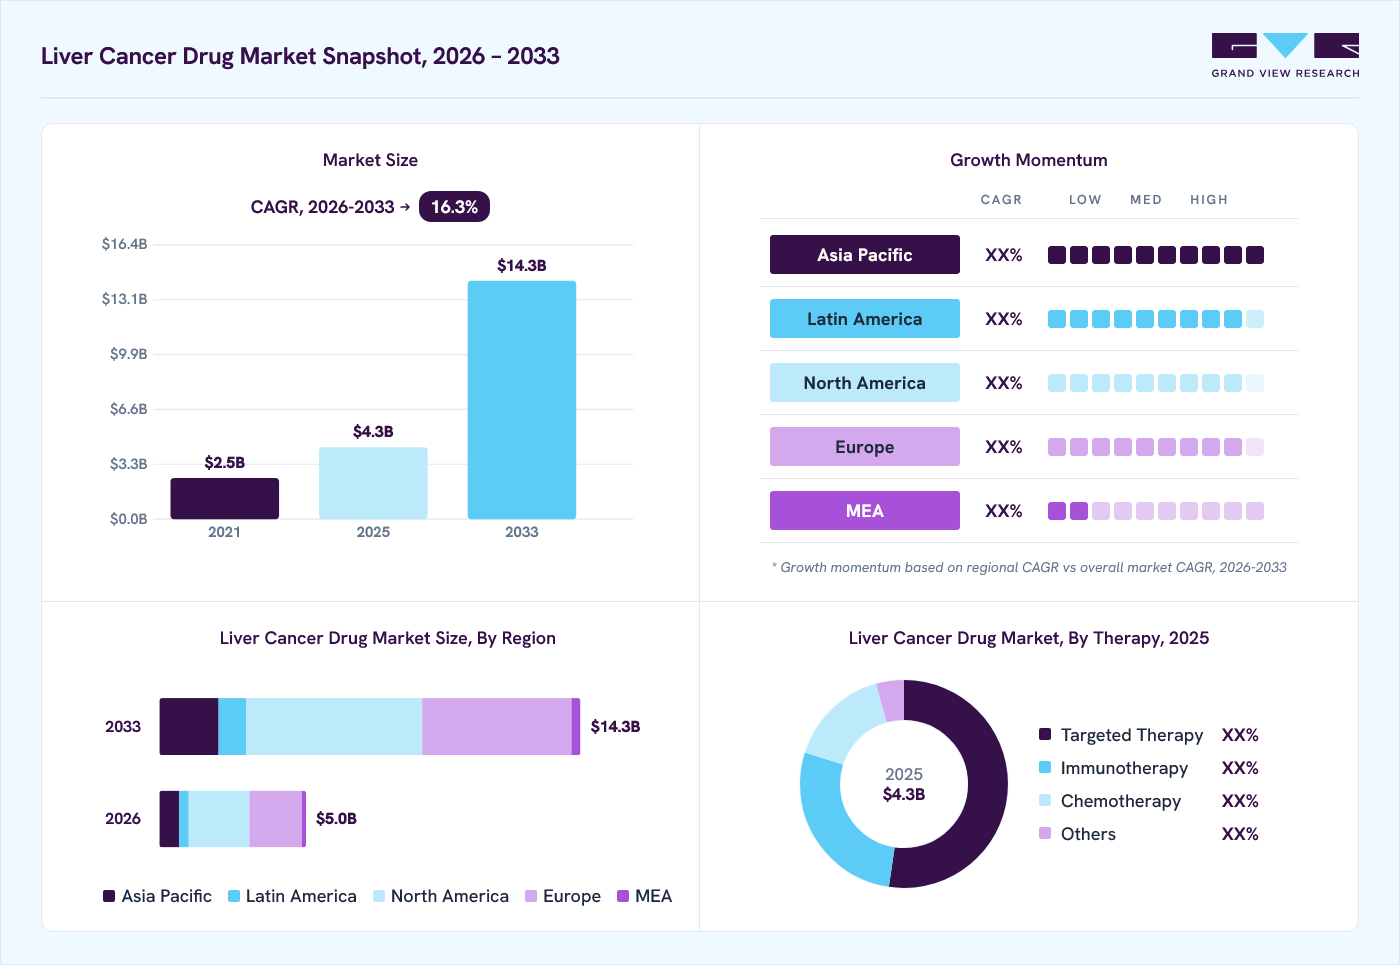
The global liver cancer drug market size was valued at USD 4.3 billion in 2025 and is projected to grow from USD 5.0 billion in 2026 to USD 14.3 billion by 2033, at a CAGR of 16.3% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 41.2% in 2025. The rising prevalence of liver cancer, advancement in treatment options, growing awareness and early diagnosis, rising healthcare expenditure, technological advancement, rising investment in research and development (R&D), government initiatives to increase access to care and promoting research in oncology are some the key drivers propelling the market growth.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By therapy: Targeted therapy segment led the market with the largest revenue share of 52.3% in 2025.
- By type: Hepatocellular carcinoma segment led the market with the largest revenue share of 38.2% in 2025.
- By distribution channel: Hospital pharmacies segment led the market with the largest revenue share of 45.6% in 2025.
Regional Highlights
- Largest regional market: North America (41.2% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 4.3 Billion
- Estimated market size in 2026: USD 5.0 Billion
- Projected market size by 2033: USD 14.3 Billion
- CAGR (2026-2033): 16.3%
Prism AI by Grand View Research Free to tryAsk a question about the liver cancer drug marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
A liver cancer drug is a medication used to treat liver cancer by targeting specific cancer cells or pathways. These drugs include chemotherapy agents such as gemcitabine and oxaliplatin, targeted therapies such as sorafenib and lenvatinib, and immunotherapies including atezolizumab. They work by inhibiting cancer growth, inducing cell death, or enhancing the immune response against cancer cells.According to the American Cancer Society, more than 800,000 people are diagnosed with liver cancer each year, accounting for more than 700,000 deaths each year worldwide. Factors such as alcohol consumption, hepatitis B & C infections, obesity, and fatty liver disease are expected to contribute to a growing incidence rate of liver cancer. The development of novel therapies and treatment options for liver cancer, including targeted therapies, immunotherapies, chemotherapy, and combination therapies, has fuelled the market growth. These advancements have improved survival rates and quality of life for patients. Increased awareness about the importance of early detection and diagnosis of liver cancer has led more patients to seek treatment at an early stage.
 To learn more about this report, Download Free Sample Report
The increasing healthcare expenditure globally and government initiatives to improve access to healthcare services have contributed to the market growth. Technological advancements in healthcare are improving the diagnosis process. The rise of precision medicine allows for tailored treatment plans based on a patient’s needs.
Market Dynamics
The liver cancer drug market is witnessing steady growth due to the rising incidence of hepatocellular carcinoma and intrahepatic cholangiocarcinoma, increasing awareness of early diagnosis, and broader access to advanced treatment options. The market is shifting from conventional chemotherapy toward targeted therapies and immunotherapies that provide improved clinical outcomes for eligible patients. Growing use of biomarker-based treatment selection and combination regimens is expanding therapeutic options for advanced liver cancer. Continued investment in clinical research is supporting the development of novel drug candidates, additional indications, and earlier-line treatment strategies. Furthermore, increasing healthcare expenditure, improving cancer care infrastructure in emerging countries, and expanding regulatory support for innovative oncology therapies are contributing to market growth. The presence of multiple approved targeted agents and immune checkpoint inhibitors, along with a strong pipeline of investigational therapies, is expected to strengthen treatment availability and support the continued growth of the liver cancer drug market during the forecast period.
The increasing use of immunotherapy and targeted therapies is a major driver of the liver cancer drug market. Hepatocellular carcinoma is frequently diagnosed at advanced stages where systemic treatment is required, leading to greater demand for therapies that improve survival and disease control. Immune checkpoint inhibitors, tyrosine kinase inhibitors, and combination regimens have become part of treatment guidelines for eligible patients, expanding the range of available treatment options. Ongoing clinical studies evaluating first-line and subsequent-line therapies continue to support broader use of these drug classes. In addition, improved molecular understanding of liver cancer has encouraged the development of therapies directed at specific biological pathways. The availability of multiple treatment options allows physicians to select therapies based on disease stage, liver function, and patient characteristics. For instance, in April 2025, Bristol Myers Squibb received U.S. FDA approval for Opdivo (nivolumab) in combination with Yervoy (ipilimumab) as a first-line treatment for adult patients with unresectable or metastatic hepatocellular carcinoma. The approval was supported by the Phase III CheckMate-9DW trial involving 668 patients, in which the combination demonstrated a statistically significant improvement in overall survival compared with lenvatinib or sorafenib. This approval expanded first-line treatment options and supported the adoption of immunotherapy for liver cancer.
The high cost of liver cancer therapies remains a significant restraint for market growth, particularly in low and middle-income countries. Most recently approved therapies are biologics or targeted agents that require prolonged treatment, increasing the overall financial burden on healthcare systems and patients. In several countries, reimbursement policies remain limited, restricting access to newer therapies. In addition, many patients with liver cancer have impaired liver function, advanced cirrhosis, or multiple comorbidities, reducing the number of patients eligible for systemic treatment. Safety concerns, immune-related adverse events, and the need for regular monitoring also limit treatment use in some patient populations. Variations in healthcare infrastructure and delayed diagnosis further reduce access to advanced therapies. Although research continues to expand treatment options, affordability and patient selection remain important challenges that can slow adoption across different regions. The need for cost-effective treatment strategies and broader reimbursement coverage continues to be an important factor affecting the overall growth of the liver cancer drug market.
The increasing development of combination therapies and expansion of regulatory approvals across multiple countries present a significant opportunity for the liver cancer drug market. Pharmaceutical companies are investing in combinations of immune checkpoint inhibitors, targeted therapies, and locoregional treatments to improve clinical outcomes across different stages of liver cancer. These approaches are increasing the number of treatment options available for patients and supporting wider adoption in clinical practice. In addition, regulatory approvals in major healthcare markets enable companies to expand product availability and strengthen their oncology portfolios. Growing participation in global clinical trials and increasing focus on earlier treatment settings are also creating opportunities for future product launches. For instance, in June 2025, Ono Pharmaceutical Co., Ltd. and Bristol-Myers Squibb K.K. received supplemental approval in Japan for Opdivo (nivolumab) and Yervoy (ipilimumab) combination therapy for unresectable hepatocellular carcinoma. The approval was based on the Phase III CheckMate-9DW study, in which the median overall survival was 23.7 months with the combination therapy compared with 20.6 months for lenvatinib or sorafenib. This approval expanded patient access to combination immunotherapy in Japan and supported further market growth.
Analyst Perspective
The liver cancer drug market is shifting from conventional chemotherapy toward targeted therapies and immunotherapies, supported by continued progress in molecular research, biomarker-guided treatment, and combination therapy development. The market is becoming more focused on companies with established oncology portfolios, strong clinical development programs, and experience in liver cancer treatment. Bristol-Myers Squibb Company and Bayer AG continue to maintain a strong position through their approved therapies and ongoing clinical studies in hepatocellular carcinoma. Eisai Co., Ltd. and Exelixis, Inc. are expanding the use of targeted therapies through clinical research and combination treatment strategies. Similarly, F. Hoffmann-La Roche Ltd., Pfizer Inc., Novartis AG, and Eli Lilly and Company are strengthening their oncology portfolios by advancing new therapeutic approaches, expanding clinical programs, and supporting the development of precision medicine for liver cancer treatment.
Therapy Insights
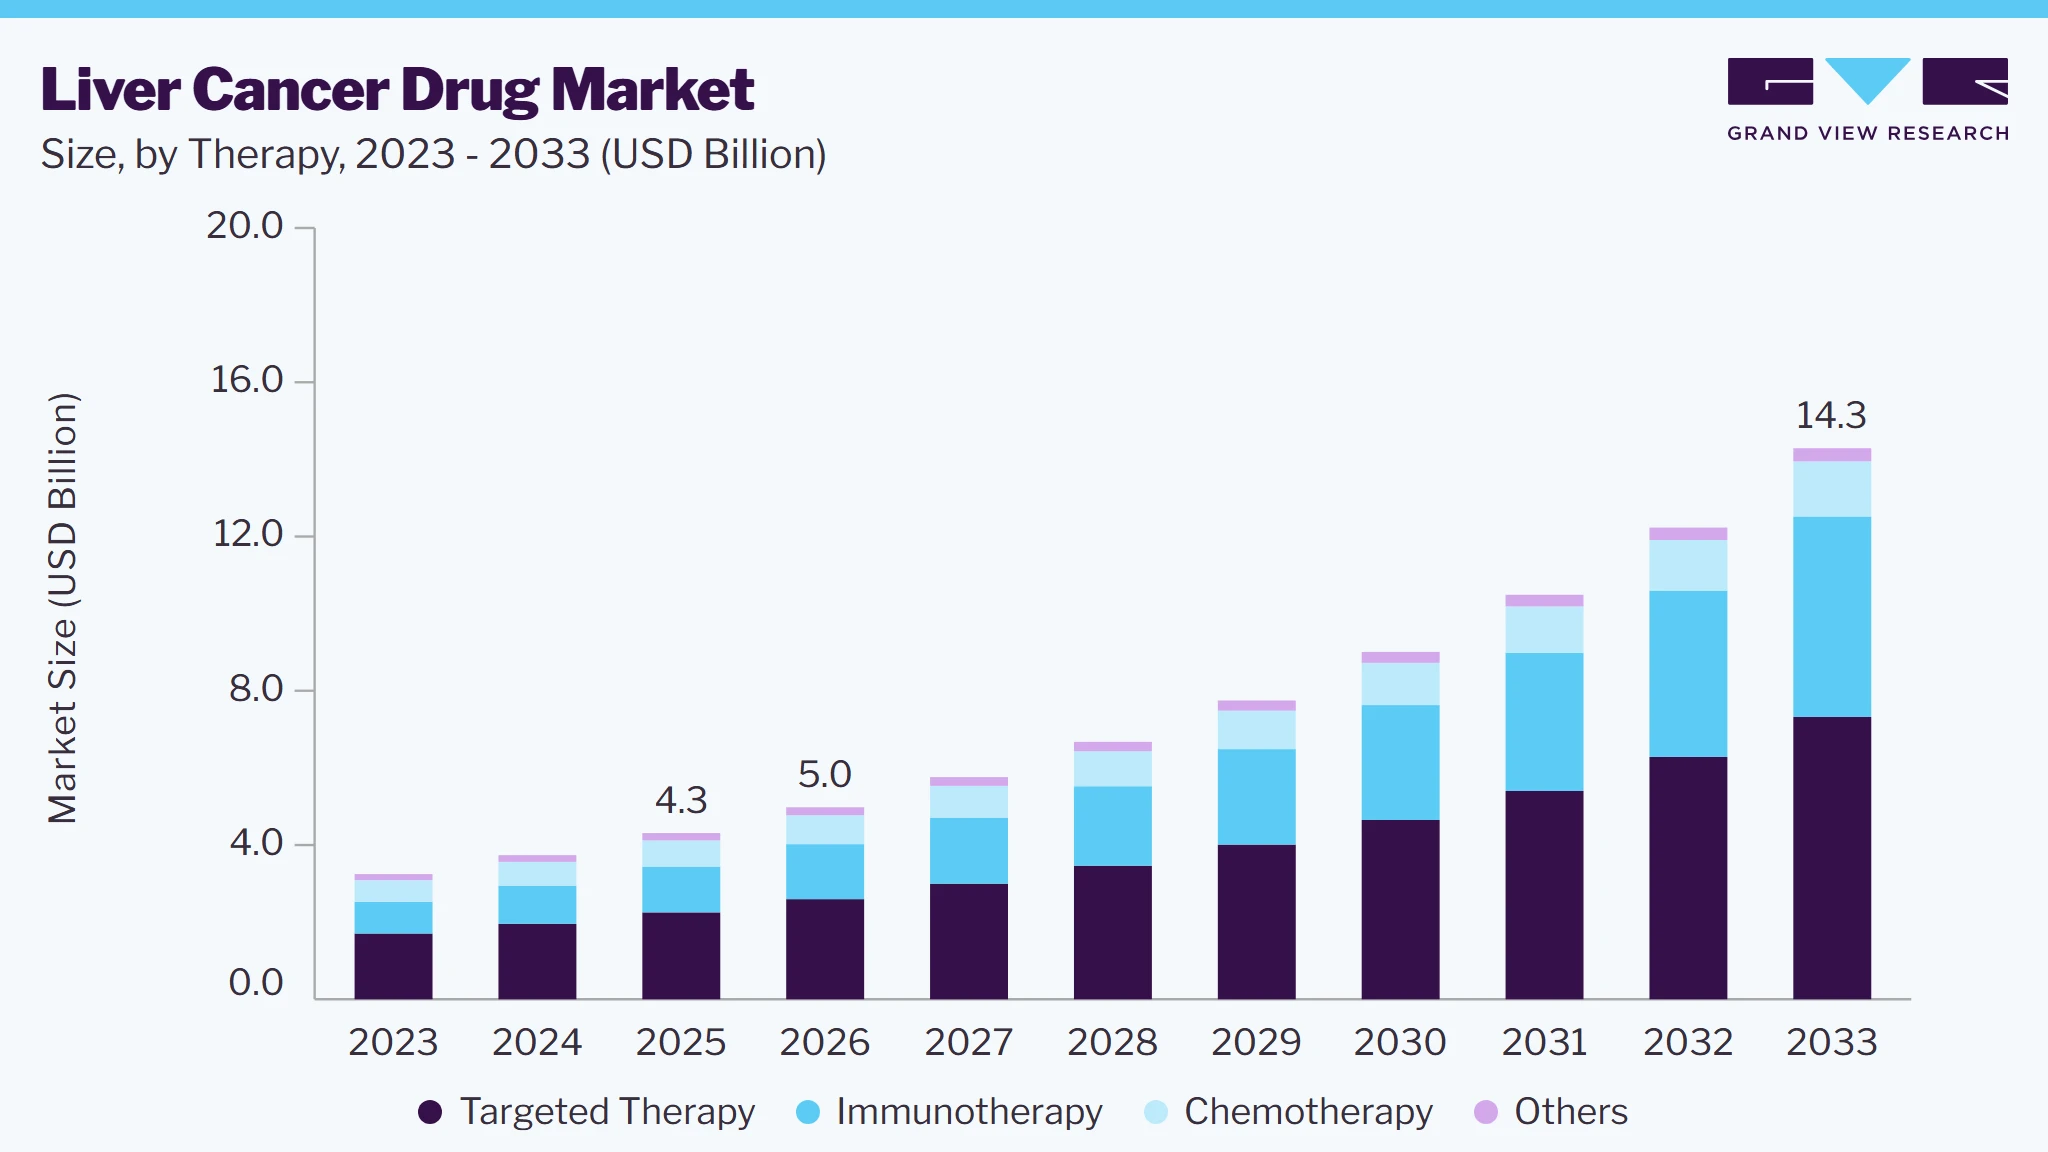
Based on therapy, the targeted therapy segment led the market with the largest revenue share of 52.3% in 2025, owing to its precision in targeting specific molecules or pathways involved in the growth and spread of cancer cells. In addition, targeted therapy aims to minimize damage to normal cells, thus reducing side effects and improving patient outcomes. Furthermore, in the case of liver cancer, targeted therapy has been identified as having promising results in inhibiting tumor growth and improving survival rates.
The immunotherapy segment is expected to grow at the fastest CAGR of 23.5% over the forecast period. Immunotherapy has shown promising results in treating liver cancer by harnessing the immune system to target and destroy cancer cells. This approach has demonstrated significant efficacy, increasing adoption and investment in immunotherapy for liver cancer treatment.
Type Insights
Based on type, the hepatocellular carcinoma segment led the market with the largest revenue share of 38.2% in 2025. HCC Is the most common type of primary liver cancer. The high prevalence and mortality rate due to HCC is leading to research and development to find effective drugs and therapies. HCC has been challenging to treat and has limited treatment options, which leads companies to invest in new and effective drugs and therapies. Furthermore, growing awareness and early detection of liver cancer allows timely intervention and treatment, driving the demand for the drug.
The cholangio carcinoma segment is expected to grow at the fastest CAGR of 7.9% over the forecast period, primarily driven by the increasing incidence rates and rising awareness. Furthermore, cholangiocarcinoma's aggressive nature and limited treatment options necessitate more effective therapies, leading to increased research and development. Moreover, collaborations between pharmaceutical companies and healthcare organizations are propelling clinical trials and novel treatments, further boosting market expansion.
Distribution Channel Insights
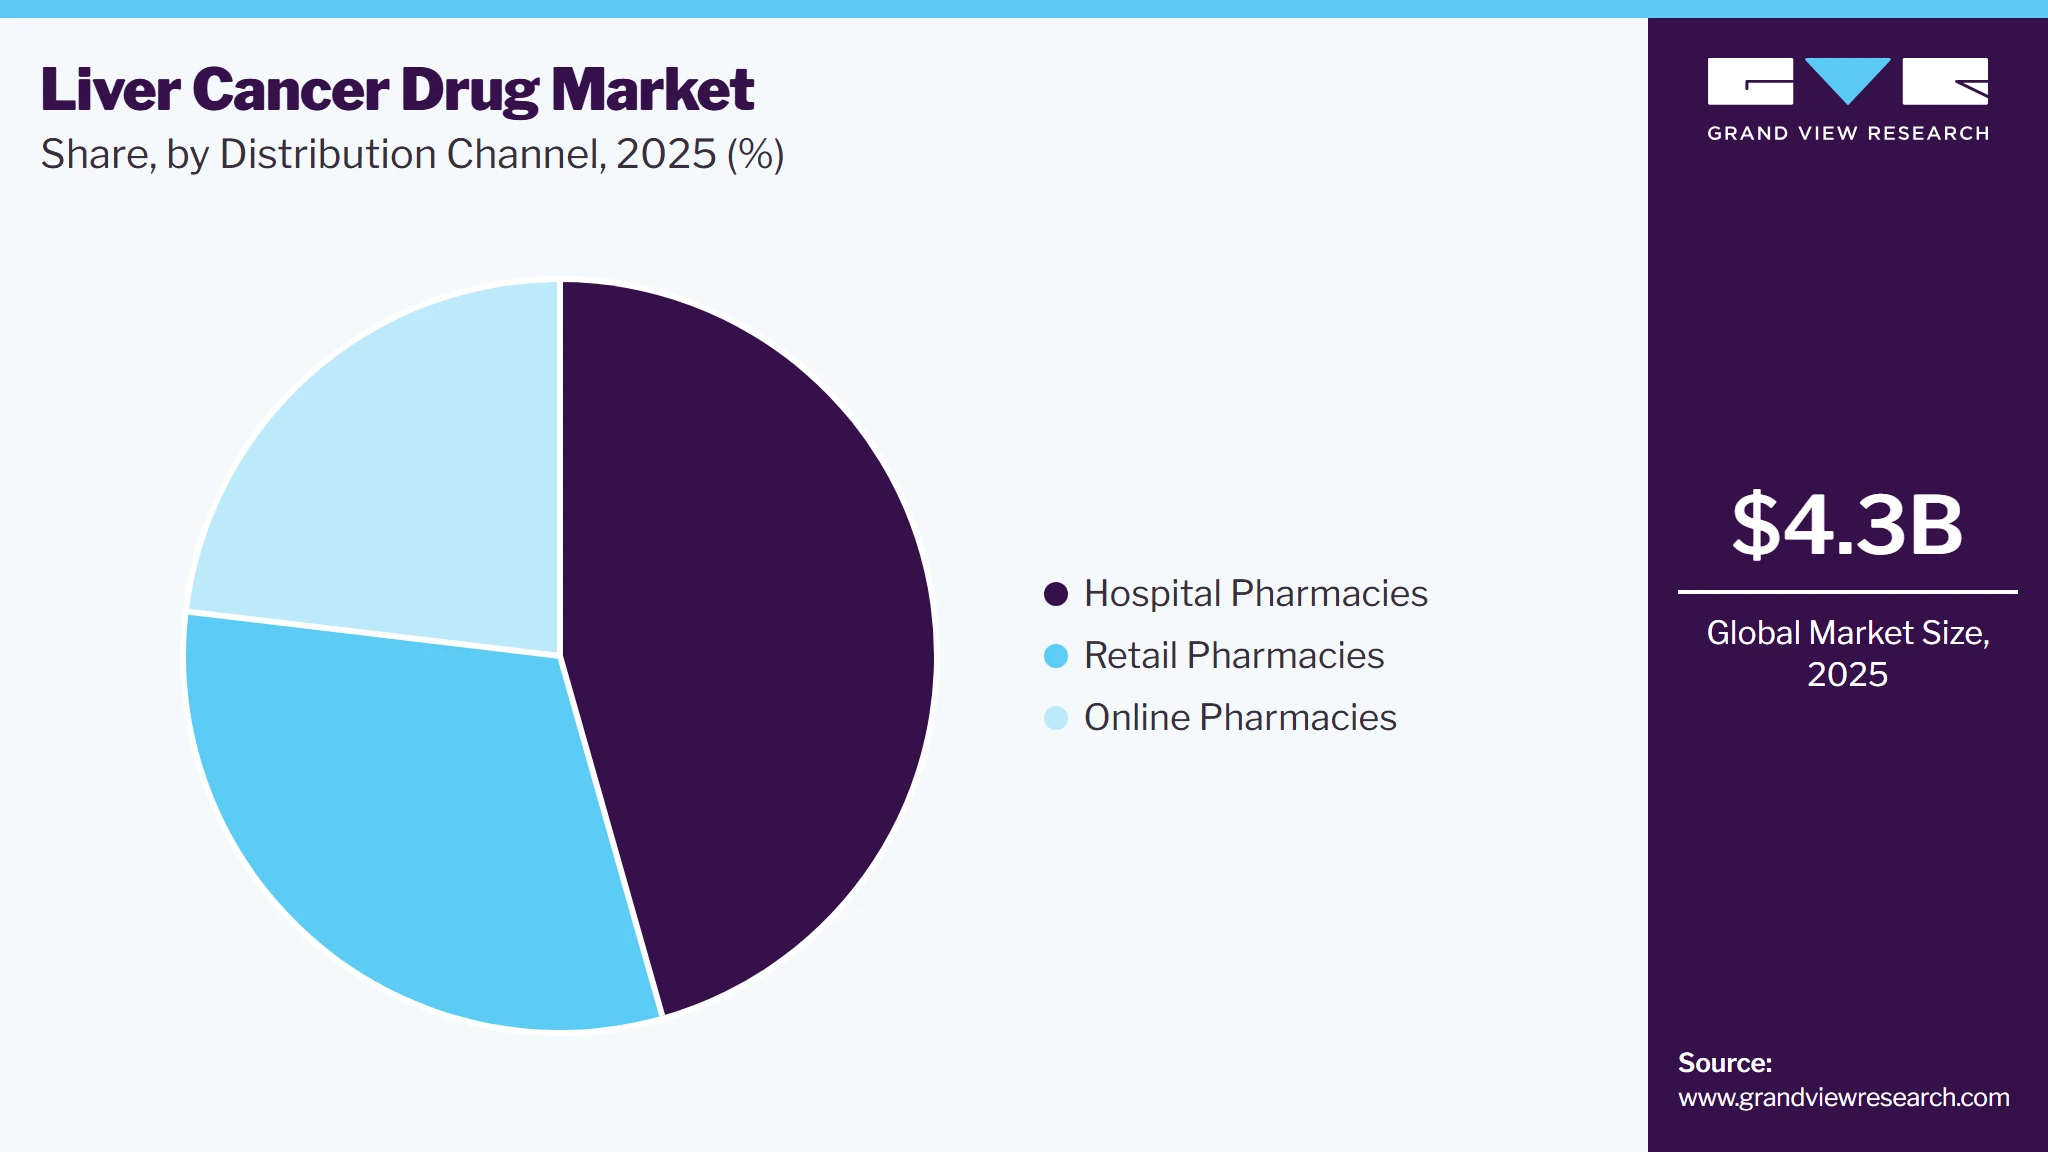
Based on distribution channel, the hospital pharmacies segment led the market with the largest revenue share of 45.6% in 2025. This growth can be attributed to the increasing prevalence of cancer, and treatments & technologies available in hospital facilities are driving the hospital pharmacy market growth. Hospitals serve as primary diagnosis and treatment centers, offering access to newly approved drugs. Furthermore, this centralized care model enhances patient outcomes and supports the adoption of innovative therapies, making hospital pharmacies a key distribution channel.
 To learn more about this report, Download Free Sample Report
Online pharmacies are expected to grow at a CAGR of 20.5% over the forecast period, attributed to convenience and accessibility. Their role in the liver cancer drug market is limited due to the specialized nature of these medications. Online platforms are expanding by offering services such as home delivery and telemedicine, which can improve patient compliance and access to care, though regulatory challenges remain a barrier.
Regional Insights
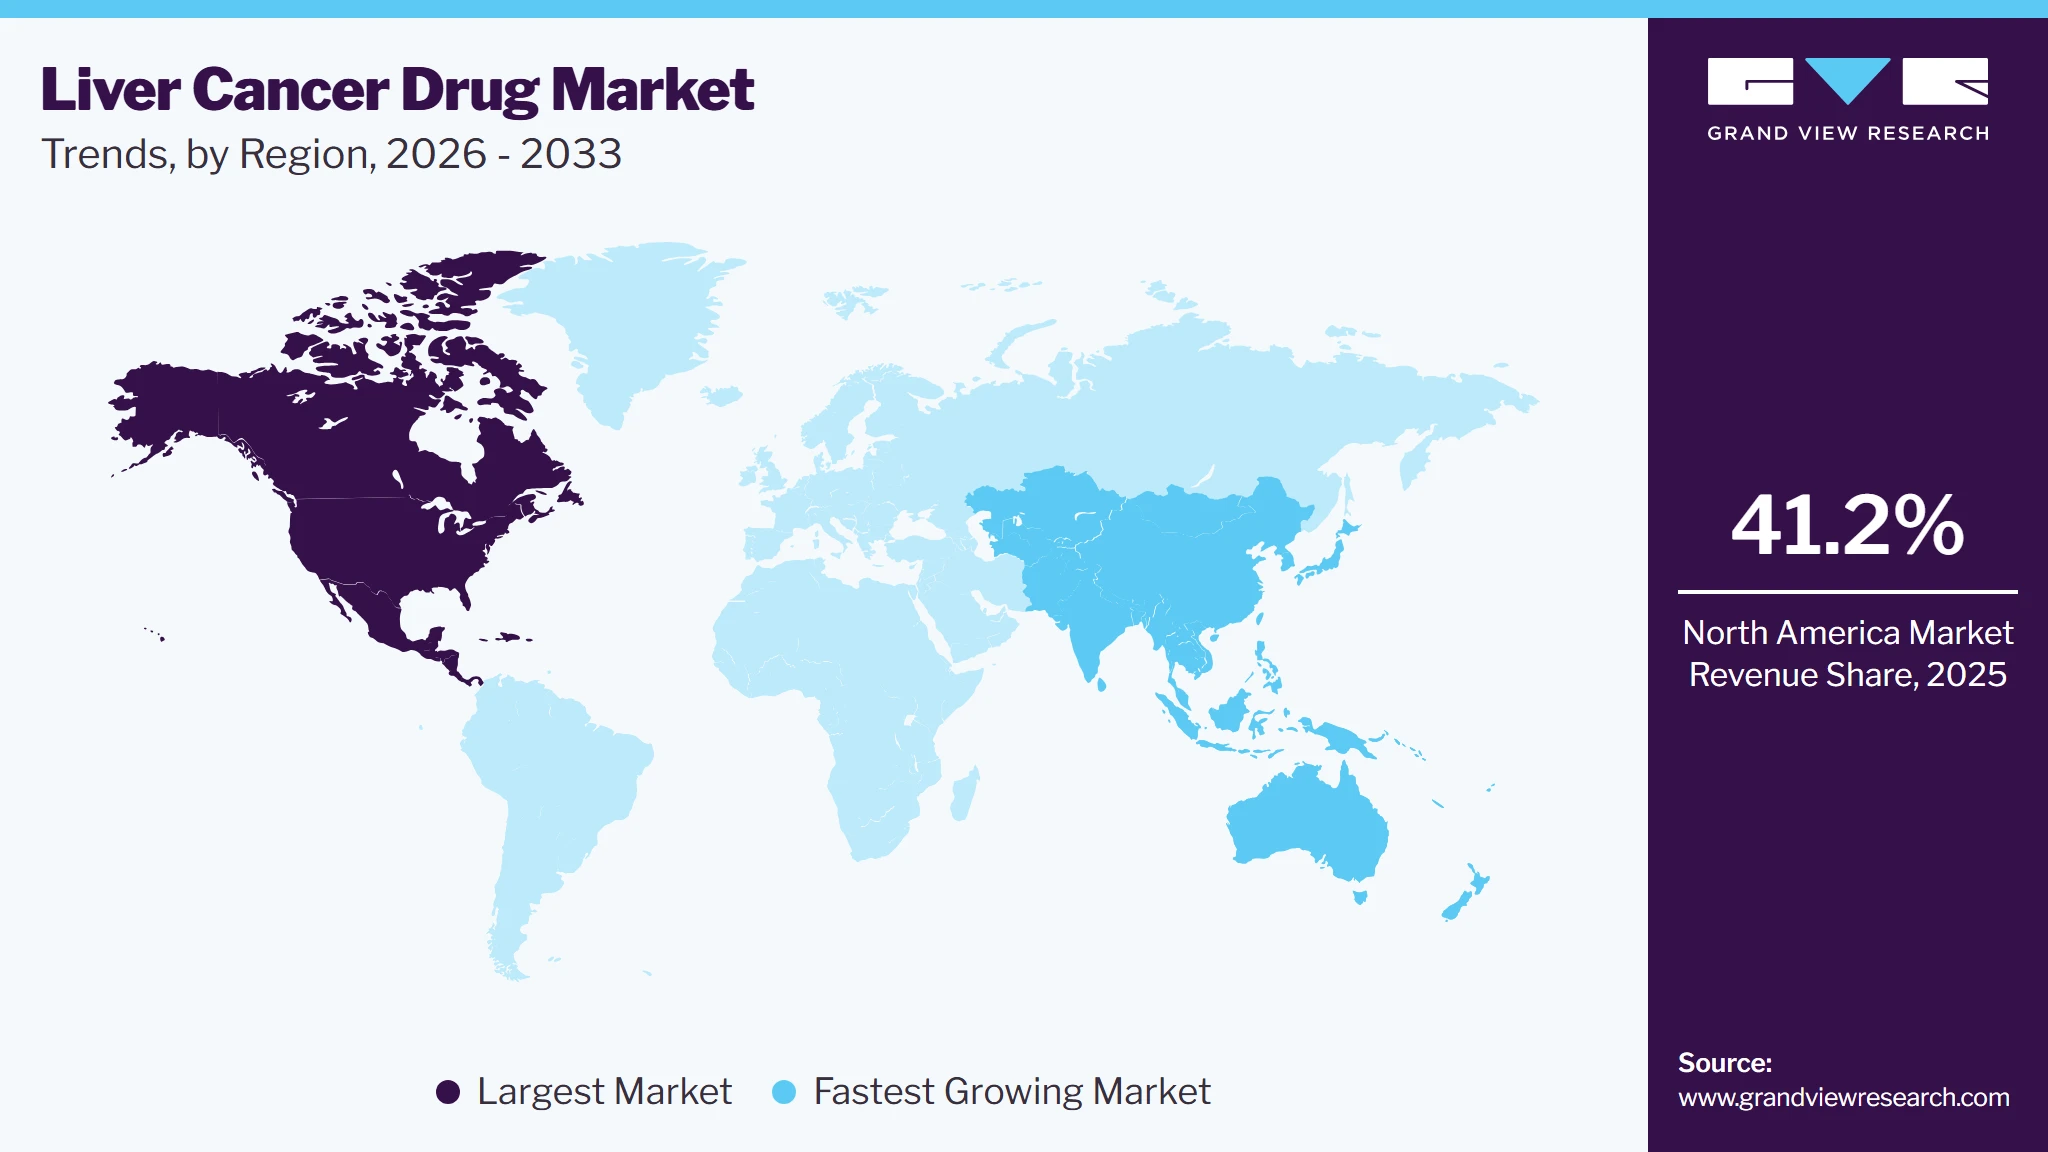
North America dominated the liver cancer drug market with the largest revenue share of 41.2% in 2025. It can be attributed to increasing awareness, advanced healthcare infrastructure and advanced medical technologies in the region. In addition, the strong regulatory framework ensures safe drugs, boosting patient trust. Key market players and ongoing R&D activities enhance the market. The advanced infrastructure supports the development of innovative treatments, further driving market expansion and improving patient outcomes.
 To learn more about this report, Download Free Sample Report
U.S. Liver Cancer Drug Market Trends
The liver cancer drug market in the U.S. held the largest share in the North America region in 2025., driven by the increasing investment in pharmaceuticals. The regulatory framework in the U.S. ensures only safe and effective drugs reach the market which increases trust of patients and healthcare providers in the drugs. Furthermore, major players and novel treatment launches contribute to its dominance. Regulatory approvals for innovative drugs support market expansion, making the U.S. a leader in liver cancer treatments. This environment fosters continuous innovation and growth.
Asia Pacific Liver Cancer Drug Market Trends
Asia Pacific liver cancer drug market is expected to grow at the fastest CAGR of 19.6% from 2025 to 2030. This growth is due to the significantly increasing investments in liver cancer drug technologies across the region. In addition, enhanced clinical research and a large target audience create opportunities. Furthermore, countries such as China offer significant potential due to unsatisfied medical needs, making it an attractive market for pharmaceutical companies. This region's diverse healthcare systems also support market expansion.
The liver cancer drug market in China dominated the Asia Pacific market and accounted for the highest share in 2024, primarily driven by its large population and increasing demand for liver cancer treatments. Furthermore, expanding healthcare infrastructure and clinical research activities create favorable conditions for pharmaceutical investments. Moreover, innovative therapies are increasingly sought after to address the rising incidence of liver cancer. Government support for healthcare development further boosts market growth.
Europe Liver Cancer Drug Market Trends
Europe liver cancer drug marketis expected to grow significantly over the forecast period. The market is primarily driven by factors such as the growing elderly population, increasing incidence of liver cancer, advancements in treatment and diagnosis procedures, and the rise in demand for minimally invasive cancer treatment techniques. In addition, increased funding for medicinal products and demand for targeted therapies contribute to growth. Furthermore, the region's strong healthcare systems support the adoption of new treatments, enhancing patient care and outcomes.
The liver cancer drug market in Germany led the European market and held the largest revenue share in 2024, driven by increased funding for cancer research and the adoption of advanced medical technologies. In addition, demand for minimally invasive treatments and targeted therapies supports expansion. Furthermore, the country's strong healthcare system and innovative research environment make it a liver cancer drug development hub. Collaborations between academia and industry further enhance market potential.
Key Liver Cancer Drug Company Insights
Key companies in the liver cancer drug industry include Exelixis, Inc., Merck KGaA, Eisai Co., Ltd., and others. These players implement strategies such as investing in R&D, launching novel drugs, forming strategic partnerships, and expanding distribution networks to enhance their portfolios and expand their market presence. Furthermore, they also focus on regulatory compliance and improving patient access to treatments.
Exelixis operates in the oncology segment, manufacturing drugs such as CABOMETYX (cabozantinib), used for treating liver cancer. The company focuses on developing targeted therapies for various cancers, including liver cancer. Its products are designed to improve patient outcomes by targeting specific pathways involved in cancer growth.
Merck KGaA operates in the pharmaceutical segment, offering a range of oncology treatments. The company collaborates with other firms to develop innovative cancer therapies, including those for liver cancer. Its products and partnerships focus on enhancing cancer care through advanced treatments and technologies.
Key Liver Cancer Drug Companies
The following key companies have been profiled for this study on the liver cancer drug market.
-
Exelixis, Inc.
-
Merck KGaA
-
Eisai Co., Ltd.
-
Bristol-Myers Squibb Company
-
Thermo Fisher Scientific Inc.
-
Pfizer Inc.
-
Eli Lilly and Company
-
F. Hoffmann-La Roche Ltd
-
Novartis AG
-
Bayer AG
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Bristol-Myers Squibb Company, Bayer AG, Eisai Co., Ltd., Exelixis, Inc., F. Hoffmann-La Roche Ltd., Novartis AG, Pfizer Inc., Eli Lilly and Company)
- Focus on expanding liver cancer treatment portfolios through the development of targeted therapies, immunotherapies, and combination regimens.
- Invest in clinical trials to support new indications and earlier-line treatment use.
- Strengthen market presence through regulatory approvals, strategic collaborations, licensing agreements, and broad commercial networks across major oncology markets.
- Broad oncology product portfolios with established therapies for liver cancer and related cancers.
- Strong clinical development capabilities, regulatory expertise, established relationships with oncology centers, and extensive global manufacturing and distribution networks support market presence.
- High research and development costs and long clinical development timelines.
- Dependence on regulatory approvals and clinical trial outcomes may delay product launches.
- Increasing competition from biosimilars, generic products, and new treatment approaches may affect product adoption.
Emerging Players (Merck KGaA, Thermo Fisher Scientific Inc.)
- Focus on expanding precision oncology capabilities through biomarker research, companion diagnostics, and strategic collaborations supporting liver cancer drug development.
- Invest in research partnerships, diagnostic technologies, and specialized oncology solutions to strengthen their position in the liver cancer treatment ecosystem.
- Strong expertise in precision medicine, molecular diagnostics, and oncology research supports the development of personalized treatment approaches.
- Flexibility to establish partnerships with pharmaceutical companies and research institutions enables expansion into emerging areas of liver cancer management.
- Limited presence in the commercial liver cancer drug portfolio compared with established pharmaceutical companies.
- Dependence on partnerships and external development programs may limit direct participation in the therapeutic market.
- Smaller marketed liver cancer drug portfolios reduce competitive positioning against companies with established oncology products.
Recent Developments
-
In January 2025, Bristol Myers Squibb received a positive CHMP opinion for Opdivo (nivolumab) plus Yervoy (ipilimumab) as a first-line treatment for non-resectable or advanced hepatocellular carcinoma, a form of liver cancer. This combination, a potential live cancer drug, demonstrated improved complete survival compared to existing treatments. The approval offers new hope for patients with this challenging condition, providing an innovative approach to liver cancer treatment.
-
In March 2024, Bayer AG and Thermo Fisher Scientific Inc. joined forces to enhance patient access to precision cancer medicines, including a potential live cancer drug. The collaboration focused on developing advanced next-generation sequencing companion diagnostics (CDx) to pinpoint individuals who could benefit from Bayer's expanding range of targeted cancer treatments.
Liver Cancer Drug Market Report Scope
Report Attribute
Details
Market size in 2025
USD 4.3 billion
Estimated market size in 2026
USD 5.0 billion
Projected market size by 2033
USD 14.3 billion
Growth rate
CAGR of 16.3% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Therapy, type, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Norway; Sweden; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait.
Key companies profiled
Exelixis, Inc.; Merck KGaA; Eisai Co., Ltd.; Bristol-Myers Squibb Company; Thermo Fisher Scientific Inc.; Pfizer Inc.; Eli Lilly and Company; F. Hoffmann-La Roche Ltd; Novartis AG; Bayer AG.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Liver Cancer Drug Market Report Segmentation
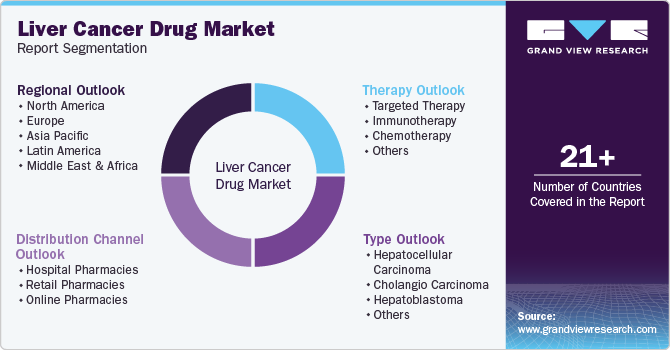
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global liver cancer drug market report based on therapy, type, distribution channel and region:
 To learn more about this report, Download Free Sample Report
-
Therapy Outlook (Revenue, USD Million, 2021 - 2033)
-
Targeted Therapy
-
Immunotherapy
-
Chemotherapy
-
Others
-
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Hepatocellular Carcinoma
-
Cholangio Carcinoma
-
Hepatoblastoma
-
Others
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospital Pharmacies
-
Retail Pharmacies
-
Online Pharmacies
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The liver cancer drug market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each liver cancer drug segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
Targeted Therapy
Includes drugs that target specific proteins or pathways involved in liver cancer growth. This segment includes multikinase inhibitors (sorafenib, lenvatinib, regorafenib, cabozantinib), VEGF-targeted therapies (bevacizumab), FGFR inhibitors (pemigatinib, futibatinib), IDH1 inhibitors (ivosidenib), and other targeted drugs used to treat liver cancer. It excludes immunotherapy drugs, chemotherapy drugs, supportive care medicines, and non-drug treatments such as surgery, radiation therapy, ablation, and transarterial chemoembolization (TACE).
Immunotherapy
Includes drugs that help the immune system recognize and destroy liver cancer cells. This segment includes PD-1 inhibitors (nivolumab, pembrolizumab, tislelizumab), PD-L1 inhibitors (atezolizumab, durvalumab), CTLA-4 inhibitors (ipilimumab, tremelimumab), and other approved immune checkpoint inhibitors. It excludes targeted therapy drugs, chemotherapy drugs, supportive care medicines, cancer vaccines, cell therapies, and non-drug treatments such as surgery, radiation therapy, ablation, and TACE.
Chemotherapy
Includes cytotoxic drugs that destroy or slow the growth of cancer cells. This segment includes fluorouracil, capecitabine, gemcitabine, cisplatin, oxaliplatin, carboplatin, doxorubicin, and chemotherapy combinations such as GEMCIS, FOLFOX, and CAPOX. It excludes targeted therapy drugs, immunotherapy drugs, supportive care medicines, and non-drug treatments such as surgery, radiation therapy, ablation, and TACE.
Others
Includes approved drug therapies for liver cancer that are not classified as targeted therapy, immunotherapy, or chemotherapy. This segment includes oncolytic viral therapies and other pharmacological treatments reported separately. It excludes targeted therapy drugs, immunotherapy drugs, chemotherapy drugs, supportive care medicines, nutritional supplements, and non-drug treatments such as surgery, liver transplantation, radiation therapy, ablation, and TACE.
Segment - Type
Revenue capture definition
Hepatocellular Carcinoma (HCC)
Includes drugs used to treat hepatocellular carcinoma, the most common type of primary liver cancer. This segment includes all approved targeted therapies, immunotherapies, chemotherapy drugs, and other systemic drugs indicated for HCC. It excludes drugs used only for cholangiocarcinoma, hepatoblastoma, metastatic liver cancer, and supportive care medicines.
Cholangiocarcinoma
Includes drugs used to treat intrahepatic cholangiocarcinoma. This segment includes chemotherapy, FGFR inhibitors, IDH1 inhibitors, immunotherapy drugs, and other systemic therapies indicated for this cancer type. It excludes drugs used only for hepatocellular carcinoma, hepatoblastoma, metastatic liver cancer, and supportive care medicines.
Hepatoblastoma
Includes drugs used to treat hepatoblastoma, a rare liver cancer that mainly affects children. This segment includes cisplatin, carboplatin, doxorubicin, fluorouracil, vincristine, and other systemic drugs used for hepatoblastoma. It excludes drugs used only for adult liver cancers, metastatic liver cancer, and supportive care medicines.
Others
Includes drugs used to treat rare primary liver cancers such as fibrolamellar carcinoma, hepatic angiosarcoma, epithelioid hemangioendothelioma, and undifferentiated embryonal sarcoma of the liver. It excludes hepatocellular carcinoma, cholangiocarcinoma, hepatoblastoma, metastatic liver cancer, and supportive care medicines.
Segment - Distribution Channel
Revenue capture definition
Hospital Pharmacies
Includes liver cancer drugs dispensed through hospital pharmacies for inpatient and outpatient treatment. This channel mainly supplies injectable immunotherapies, intravenous chemotherapy, biologics, and oral oncology drugs prescribed within hospitals. It excludes drugs dispensed through retail pharmacies, online pharmacies, clinical trial supply, and manufacturer direct distribution.
Retail Pharmacies
Includes liver cancer drugs dispensed through licensed community and chain pharmacies. This segment mainly includes oral targeted therapies and oral chemotherapy medicines prescribed for outpatient use. It excludes drugs dispensed through hospital pharmacies, online pharmacies, infusion centers, clinical trial supply, and manufacturer direct distribution.
Online Pharmacies
Includes liver cancer drugs dispensed through licensed online or mail-order pharmacies with home delivery. This segment mainly includes oral targeted therapies and oral chemotherapy medicines. It excludes drugs supplied through hospital pharmacies, retail pharmacies, infusion centers, clinical trial supply, and manufacturer direct distribution.
Estimation Model
 To learn more about this report, Download Free Sample Report
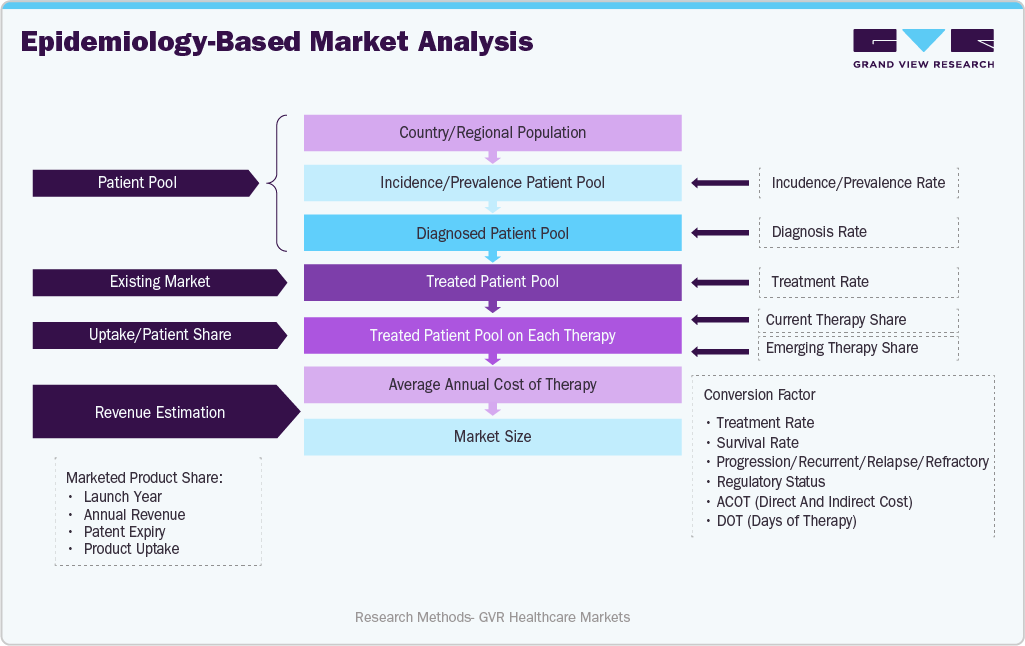
The study incorporated a combination of primary and secondary research methodologies to evaluate the global liver cancer drug market. Secondary research involved the review of company annual reports, investor presentations, regulatory filings, clinical trial registries, treatment guidelines, scientific publications, cancer registries, government health databases, industry journals, and publicly available information from pharmaceutical companies, regulatory authorities, and oncology organizations. Epidemiology data, treatment guidelines, drug approvals, and pricing information were analyzed to estimate the diagnosed and treated patient population across major regions. Primary research included interviews and discussions with pharmaceutical manufacturers, oncologists, hepatologists, hospital pharmacists, researchers, business development executives, and key opinion leaders to validate disease prevalence, treatment patterns, drug adoption, pricing trends, competitive developments, and market assumptions. The findings from both research approaches were triangulated to estimate the market size, validate segment-level estimates, and ensure the accuracy of regional and global market forecasts.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Liver Cancer Drug Competitive Landscape & Portfolio Assessment
Conducted a detailed assessment of the global liver cancer drug market by evaluating approved products, late-stage pipeline assets, clinical trial activity, therapy classes, regulatory approvals, and treatment indications. The study analyzed key companies including Exelixis, Inc., Merck KGaA, Eisai Co., Ltd., Bristol-Myers Squibb Company, Thermo Fisher Scientific Inc., Pfizer Inc., Eli Lilly and Company, F. Hoffmann-La Roche Ltd., Novartis AG, and Bayer AG, along with product development activities across hepatocellular carcinoma, cholangiocarcinoma, and other liver cancer indications.
Helped the client identify portfolio gaps, compare competitor strategies, assess pipeline positioning, evaluate licensing and partnership opportunities, and understand product development trends across the liver cancer drug market.
Liver Cancer Therapy Benchmarking Study
Delivered a benchmarking study of liver cancer therapies, including targeted therapies, immunotherapies, chemotherapy, and combination treatment regimens. The assessment compared product portfolios, mechanisms of action, approved indications, clinical development stages, treatment positioning, and regulatory status to understand the competitive positioning of available liver cancer therapies.
Enabled the client to compare available therapies, identify treatment gaps, assess clinical development strategies, evaluate competitive positioning, and support product development and portfolio planning decisions.
Liver Cancer Drug Development & Commercial Assessment
Conducted an assessment of the liver cancer drug development ecosystem by evaluating clinical development programs, regulatory pathways, manufacturing capabilities, strategic collaborations, licensing activities, and commercial distribution. The study also reviewed supply chain considerations for active pharmaceutical ingredients, biologics manufacturing, formulation development, packaging, and commercial supply across major markets.
Supported commercial planning by identifying development partners, evaluating manufacturing and supply chain risks, assessing commercialization opportunities, and improving launch planning across regional and global liver cancer drug markets.
Frequently Asked Questions About This Report
Based on type, the hepatocellular carcinoma segment led the market with the largest revenue share of 38.2% in 2025.
Based on distribution channel, the hospital pharmacies segment led the market with the largest revenue share of 45.6% in 2025.
North America dominated the liver cancer drug market with the largest revenue share of 41.2% in 2025.
The global liver cancer drug market size was estimated at USD 4.3 billion in 2025 and is projected to grow to USD 5.0 billion in 2026.
The global liver cancer drug market is expected to grow at a compound annual growth rate of 16.3% from 2026 to 2033 to reach USD 14.3 billion by 2033
Based on therapy, the targeted therapy segment led the market with the largest revenue share of 52.3% in 2025.
Some key players operating in the liver cancer drug market include Exelixis, Inc.; Merck KGaA; Eisai Co., Ltd.; Bristol-Myers Squibb Company; Thermo Fisher Scientific Inc.; Pfizer Inc.; Eli Lilly and Company; F. Hoffmann-La Roche Ltd; Novartis AG; Bayer AG.
Key factors that are driving the market growth include increasing medicare reimbursement for telehealth services, reducing emergency room visits and hospitalization rate, and technological innovation in communication technology across the world.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


