
- Home
- »
- Pharmaceuticals
- »
-
Liver Disease Therapeutic Market Size Report, 2026-2033GVR Report cover

Liver Disease Therapeutics Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Antiviral Drugs, Vaccines, Chemotherapy), By Disease (Hepatitis, Autoimmune Diseases), By Region, And Segment Forecasts
Market Size, 2025
$21.9BMarket Estimate, 2026
$23.6BMarket Forecast, 2033
$40.3BCAGR, 2026–2033
8.0%Liver Disease Therapeutics Market Summary
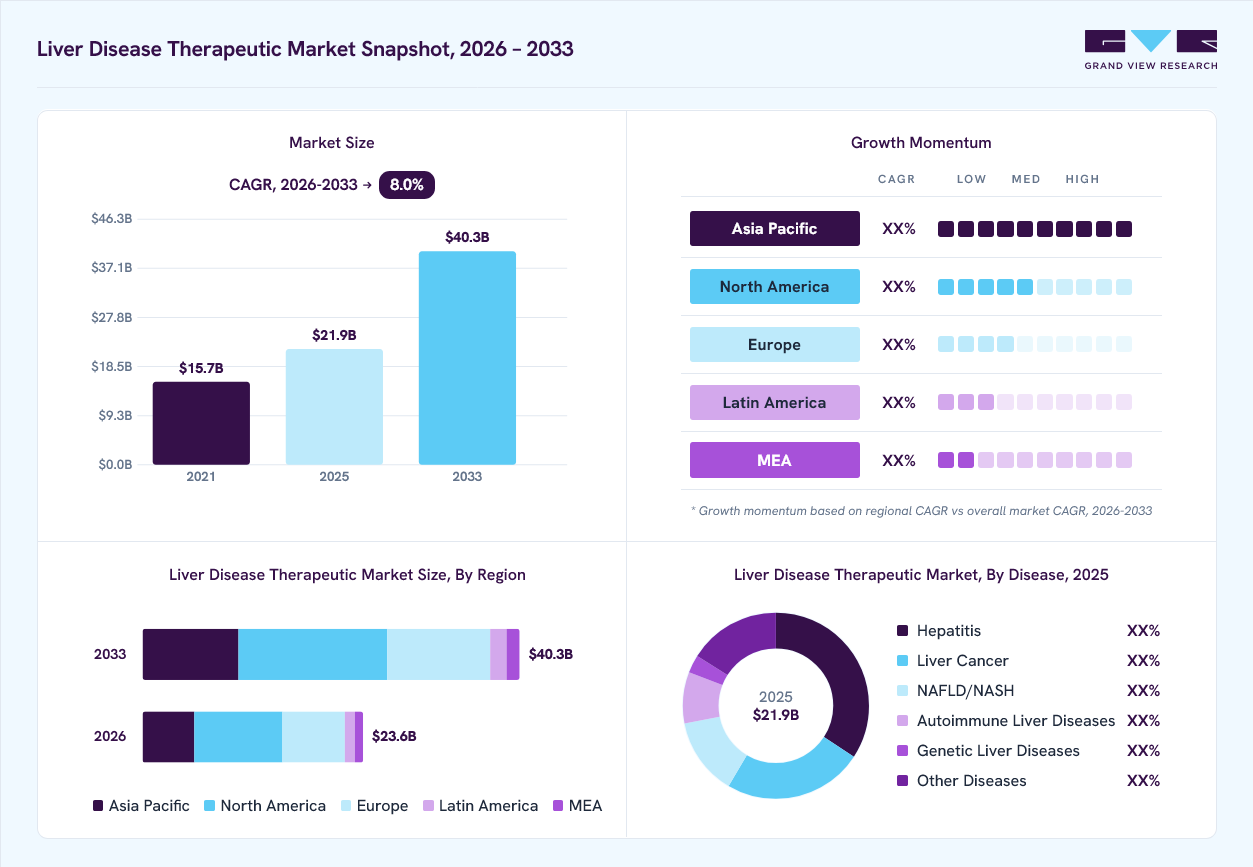
The global liver disease therapeutic market size was valued at USD 21.9 billion in 2025 and is projected to grow from USD 23.6 billion in 2026 to USD 40.3 billion by 2033, at a CAGR of 8.0% from 2026 to 2033. North America dominated the liver disease therapeutic market with the largest revenue share of 40.0% in 2025. Rising cases of NAFLD, hepatitis, and alcohol-related liver conditions, advancements in drug development, and increasing obesity and diabetes prevalence drive this growth.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Antiviral drugs segment held the largest market share of 37.8% in 2025.
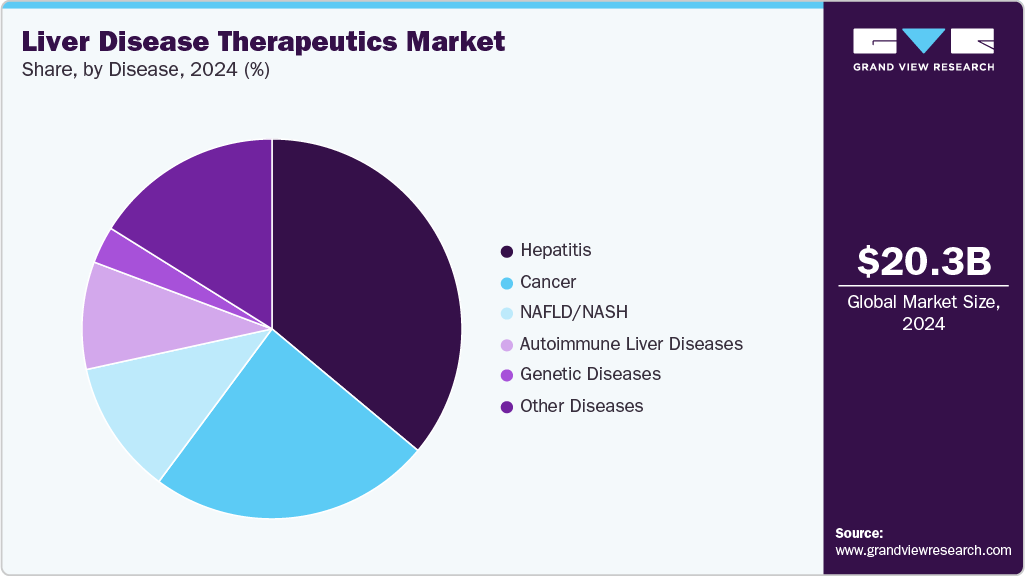
- By disease: Hepatitis segment held the largest market share of 34.2% in 2025.
Regional Highlights
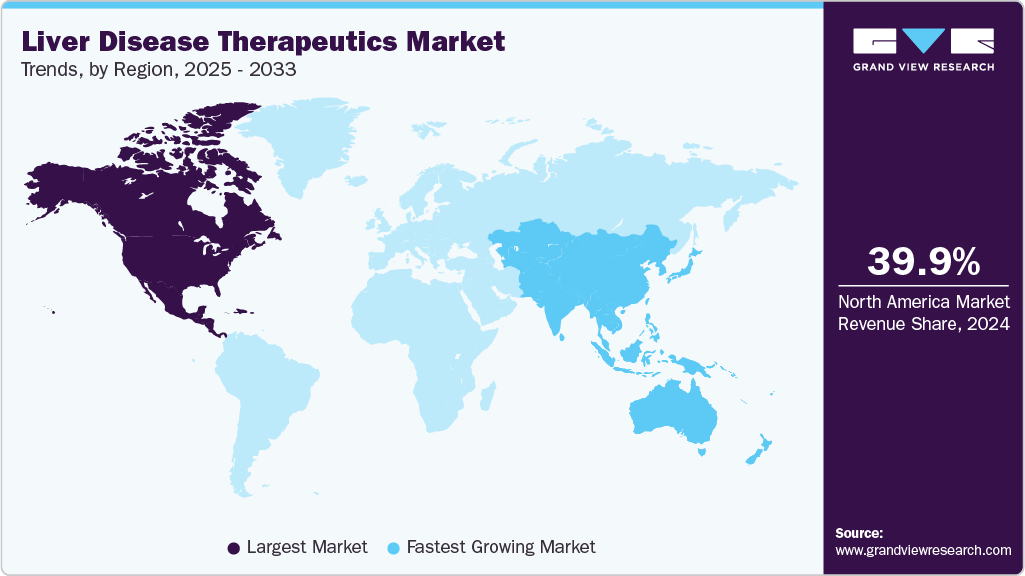
- Largest regional market: North America (40.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 21.9 Billion
- Estimated market size in 2026: USD 23.6 Billion
- Projected market size by 2033: USD 40.3 Billion
- CAGR (2026-2033): 8.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The rising prevalence of liver diseases globally is a primary driver fueling market growth. Recent epidemiological trends underscore a sustained and alarming increase in both chronic and acute liver conditions, including viral hepatitis (HBV, HCV), non-alcoholic fatty liver disease (NAFLD), alcohol-related liver disease (ALD), and hepatocellular carcinoma (HCC). This trend translates into heightened clinical demand for therapeutics across all stages of liver pathology-from early-stage antiviral management to advanced cancer-targeted therapies.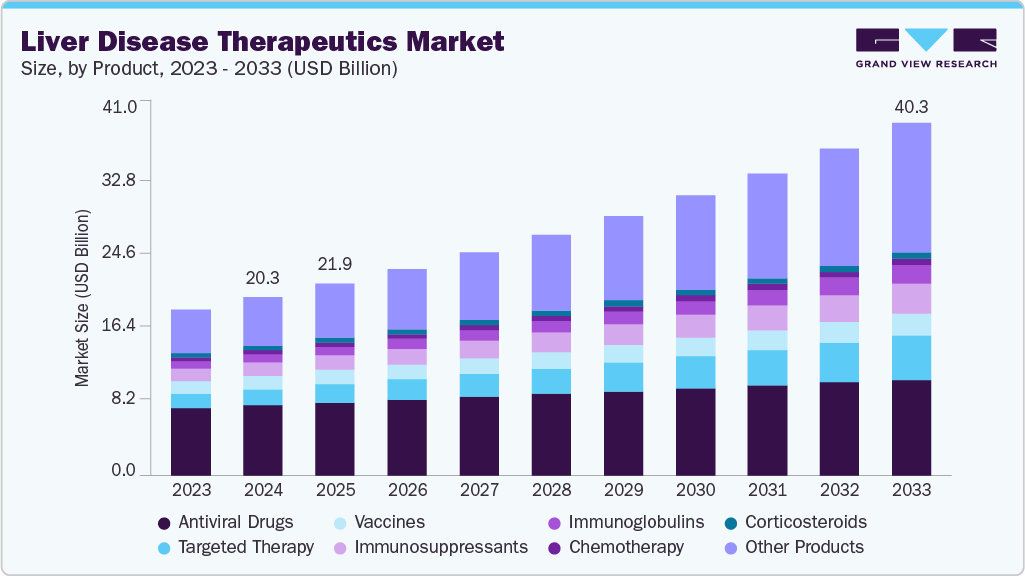 To learn more about this report, Download Free Sample Report
According to the World Health Organization (WHO, 2024), an estimated 296 million people worldwide are living with chronic hepatitis B, while 58 million are infected with chronic hepatitis C, with many unaware of their infection status until advanced liver complications develop. These chronic viral infections contribute to more than 1.1 million deaths annually, primarily due to cirrhosis and liver cancer, highlighting a substantial public health burden and an unmet need for therapeutic intervention.
Table 1 Global Burden of Key Liver Diseases
Disease Area
Estimated Global Prevalence
Key Insights
Hepatitis B (HBV)
296 million
Often asymptomatic; major cause of cirrhosis and HCC; linked to vertical transmission.
Hepatitis C (HCV)
58 million
High-risk in injectable drug users; chronic infection can lead to end-stage liver disease.
Non-Alcoholic Fatty Liver Disease (NAFLD)
~25% of global population
Closely linked with obesity and diabetes, driving a rise in NASH-related liver failure.
Alcohol-Related Liver Disease (ALD)
Rising globally (no unified estimate)
Post-pandemic spike observed; increasing hospitalizations and liver transplants.
Hepatocellular Carcinoma (HCC)
4th most common cause of cancer death globally
Often, a downstream result of chronic HBV/HCV or NASH is an increasing focus on targeted therapies.
Sources: WHO, 2024; Journal of Hepatology, 2023; PMC10026948, 2023
In addition, advancements in therapeutic innovations are a significant market driver, propelled by breakthroughs in mRNA-based platforms, antiviral development, and immune-modulating strategies. These innovations aim to overcome the limitations of conventional protein drugs and DNA therapies, thereby expanding treatment options for complex and chronic liver diseases.
According to a study published in MDPI 2022, mRNA-based approaches are gaining attention due to their ability to produce sustained therapeutic protein expression without integrating into the host genome, reducing the risk of insertional mutagenesis. mRNA's cytoplasmic activity avoids the need for nuclear entry, allowing efficient translation into proteins in hepatocytes, which are ideal targets for metabolic and viral liver disorders.
Moreover, non-viral etiologies are emerging as major contributors to the disease burden. In a 2023 study published in the Journal of Hepatology, it was noted that non-alcoholic fatty liver disease (NAFLD) affects approximately 25% of the global population. Its more severe form, non-alcoholic steatohepatitis (NASH), is rapidly progressing to become the leading cause of liver transplantation in Western countries (Younossi et al., 2023). This demographic shift is particularly driven by rising obesity, insulin resistance, and sedentary lifestyles, contributing to the systemic metabolic dysfunction observed in NAFLD/NASH populations.
Innovations in liver disease therapeutics
Focus Area
Technology
Clinical Development
Source
CMV-induced liver inflammation
mRNA-1647 vaccine
Phase 3 (NCT05085366)
Cureus (2023)
Chronic Hepatitis B
mRNA immunotherapy
Preclinical; aims to induce cellular immunity
Cells 2022, 11, 3328
Liver cancer
mRNA cancer vaccines
No approved vaccine yet; preclinical development ongoing
Cells 2022, 11, 3328
Pediatric liver disorders
mRNA for enzyme replacement
Multiple preclinical programs
Cells 2022, 11, 3328
Market Dynamics
The liver disease therapeutic market is driven by the increasing prevalence of chronic liver disorders, including metabolic dysfunction-associated steatotic liver disease (MASLD), viral hepatitis, liver fibrosis, cirrhosis, and hepatocellular carcinoma. Rising rates of obesity, diabetes, alcohol consumption, and viral infections continue to increase the number of patients requiring long-term disease management. Pharmaceutical companies are expanding their liver disease portfolios through the development of therapies targeting fibrosis, inflammation, and metabolic pathways, while regulatory approvals for novel treatments are broadening available treatment options. Growing awareness of early diagnosis, improved screening programs, and updated clinical guidelines are supporting timely treatment initiation. Healthcare systems are also increasing investments in the management of chronic liver diseases to reduce disease progression and liver-related complications. In addition, collaborations between biotechnology companies and large pharmaceutical manufacturers are supporting clinical development and expanding therapeutic pipelines. These factors continue to support demand for pharmacological interventions across different stages of liver disease.
The increasing prevalence of metabolic and chronic liver diseases is supporting demand for liver disease therapeutics. Rising incidences of obesity, type 2 diabetes, metabolic syndrome, excessive alcohol consumption, and chronic viral hepatitis have contributed to a growing patient population requiring medical treatment. Metabolic dysfunction-associated steatotic liver disease (MASLD) has become one of the most common chronic liver conditions globally, creating sustained demand for therapies that can slow disease progression and reduce complications such as fibrosis and cirrhosis. Healthcare providers are also placing greater emphasis on early diagnosis and continuous disease monitoring, supporting timely treatment initiation. Pharmaceutical companies continue to invest in therapies targeting fibrosis, inflammation, lipid metabolism, and immune pathways to address different stages of liver disease. Increasing clinical evidence supporting combination therapies and targeted treatments is expanding available treatment options. Furthermore, updated clinical guidelines and improved access to diagnostic technologies are contributing to higher treatment rates across developed and developing healthcare markets. For instance, in March 2025, Madrigal Pharmaceuticals received approval from the European Commission for Rezdiffra (resmetirom) for the treatment of adults with non-cirrhotic metabolic dysfunction-associated steatohepatitis (MASH) with moderate to advanced liver fibrosis, expanding treatment availability for chronic liver disease patients.
High treatment costs and delayed diagnosis remain key challenges for the liver disease therapeutic market. Many chronic liver disorders progress gradually and remain asymptomatic during their early stages, resulting in delayed diagnosis and treatment initiation. In several countries, routine screening for metabolic liver diseases is not widely implemented, leading to a significant proportion of patients being diagnosed only after the disease has advanced to fibrosis or cirrhosis. In addition, novel therapies developed for liver diseases often involve higher treatment costs compared to conventional treatment approaches, creating affordability challenges for healthcare systems and patients. Limited reimbursement for recently approved therapies in some markets may also restrict patient access. The management of chronic liver diseases frequently requires long-term monitoring, laboratory testing, imaging procedures, and specialist care, increasing the overall cost of treatment. Differences in healthcare infrastructure, treatment guidelines, and specialist availability across countries also contribute to uneven access to liver disease therapies, particularly in low- and middle-income regions.
The expansion of targeted therapies and clinical pipeline development offers opportunities for the liver disease therapeutic market. Pharmaceutical and biotechnology companies are focusing on therapies that address multiple disease mechanisms, including inflammation, fibrosis, lipid metabolism, and immune regulation. Increasing investment in clinical research has resulted in a broad pipeline of drug candidates for metabolic dysfunction-associated steatohepatitis (MASH), autoimmune liver diseases, viral hepatitis, and rare liver disorders. Combination therapies are also being evaluated to improve treatment outcomes across different stages of disease progression. Advances in biomarker development and non-invasive diagnostic technologies are supporting patient identification and treatment selection, enabling more personalized therapeutic approaches. Strategic collaborations, licensing agreements, and acquisitions are strengthening research capabilities and supporting product development. As regulatory agencies continue to approve new therapies, treatment options for patients with chronic liver diseases are expanding, creating opportunities for companies to strengthen their product portfolios and address unmet clinical needs. For instance, in January 2025, GSK plc entered into an agreement to acquire efimosfermin alfa, a Phase III investigational therapy for steatotic liver disease, through the acquisition of Boston Pharmaceuticals' liver disease program, strengthening its liver disease therapeutic pipeline.
Market Concentration & Characteristics
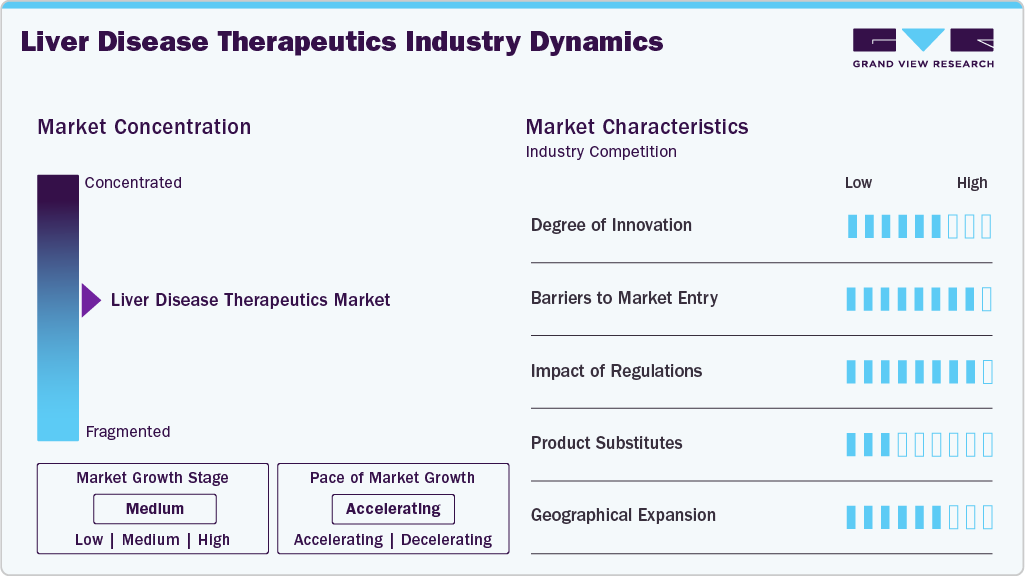
The liver disease therapeutics industry is marked by a moderate to high degree of innovation, with major players like Gilead, AbbVie, and Roche investing in novel antiviral agents and targeted therapies. Unmet clinical needs in NAFLD, autoimmune liver conditions, and liver cancer largely drive innovation. Advancements in biologics, gene editing, and RNA-based technologies are shaping next-generation treatments. However, R&D's high cost and time requirements for R&D limit participation to well-funded companies. Strategic collaborations and licensing deals further accelerate innovation cycles.
Barriers to entry in this market are high due to complex regulatory pathways, substantial capital investment, and the need for extensive clinical validation. The dominance of established players like Pfizer and Merck makes market penetration difficult for smaller firms. Intellectual property protection and strong brand loyalty to existing therapeutics add to these challenges. In addition, the necessity for long-term safety data and pharmacovigilance programs increases entry costs. New entrants often rely on niche indications or partnerships to gain a foothold.
 To learn more about this report, Download Free Sample Report
Regulatory frameworks have a significant impact, especially concerning drug approvals for hepatitis treatments and biologics. Stringent protocols from agencies like the FDA and EMA ensure safety and efficacy, but often extend time to market. Post-approval surveillance and pricing regulations also influence product launch strategies. However, accelerated approval programs and orphan drug incentives benefit developers targeting rare liver conditions. Regional disparities in reimbursement policies can affect commercial success across different markets.
While therapeutic substitutes exist, such as liver transplantation and supportive care, pharmacological alternatives remain limited for many liver diseases. Vaccines and antivirals dominate hepatitis treatment, but conditions like NAFLD lack widely accepted drug therapies, reducing substitution risks. Herbal remedies and nutritional supplements pose minimal threat due to limited clinical validation. However, lifestyle interventions and early detection strategies are increasingly integrated alongside pharmaceutical regimens. Continued innovation reduces reliance on non-pharmacological substitutes.
Geographical expansion is a key strategy for major companies aiming to tap emerging markets in Asia Pacific, Latin America, and the Middle East. The rising prevalence of liver diseases and improving healthcare access in countries like China, India, and Brazil are opening new commercial opportunities. Multinational firms leverage regional partnerships, local manufacturing, and market-specific regulatory strategies. Nonetheless, infrastructure disparities and pricing sensitivities can hinder smooth expansion. Tailored drug portfolios for local epidemiology are increasingly important for success.
Analyst Perspective
The liver disease therapeutic market is transitioning from a treatment area primarily focused on viral hepatitis to a broader market addressing metabolic liver diseases, autoimmune liver disorders, liver cancer, and rare genetic conditions. The market is supported by continued investment in targeted therapies, antifibrotic agents, and therapies addressing metabolic dysfunction-associated steatohepatitis (MASH). It is increasingly centered around companies with established capabilities in liver disease research, clinical development, regulatory approvals, and global commercialization. Gilead Sciences and AbbVie continue to maintain strong positions through their established hepatitis portfolios, while Madrigal Pharmaceuticals has expanded treatment options with the introduction of therapies for MASH. Similarly, Merck & Co., Takeda Pharmaceutical Company, F. Hoffmann-La Roche, Novartis, Pfizer, Sanofi, GSK, and Johnson & Johnson are strengthening their liver disease portfolios through pipeline development, strategic collaborations, and targeted investments across multiple liver disease indications.
Product Insights
Based on product, the antiviral drugs segment led the market with the largest revenue share of 37.8% in 2025. due to the high global prevalence of chronic viral hepatitis, long treatment durations for HBV, and premium pricing for HCV DAAs.Antiviral drugs have become central to liver disease management. These therapies, including tenofovir, entecavir, and direct-acting antivirals like sofosbuvir and glecaprevir, effectively suppress HBV and cure HCV. Their broad application across patient groups, high efficacy rates, and oral administration have made them widely adopted globally. WHO's 2030 elimination target is accelerating access to generics and diagnostics, while new therapies such as siRNA and immune-based treatments show promise for a functional HBV cure. The antiviral drug segment is expected to grow strongly, supported by policy momentum, clinical innovation, and expanding treatment infrastructure across regions.
The targeted therapy segment is projected to grow at the fastest CAGR of 11.87% over the forecast period, fueled by rising demand for personalized and mechanism-specific interventions.Targeted therapies transform liver disease treatment across indications like HCC, HBV, HDV, MASH/NASH, and PBC. In HCC, multikinase inhibitors such as sorafenib and lenvatinib and combinations like atezolizumab plus bevacizumab have significantly extended survival outcomes. For HBV and HDV, new agents, including RNAi therapies (JNJ-3989, AB-729) and entry inhibitors (bulevirtide), are moving treatment closer to a functional cure. In MASH/NASH, advanced candidates like efruxifermin and resmetirom show promise in reducing liver fat and fibrosis, with resmetirom progressing into Phase III. GLP-1 receptor agonists and fibrosis-specific agents such as seladelpar and elafibranor are expanding the precision treatment landscape, reshaping standards of care, and driving clinical innovation.
Disease Insights
Based on disease, the hepatitis segment led the market with the largest revenue share of 34.2% in 2025, attributed to the widespread burden of chronic hepatitis and the clinical success of antiviral treatments, the hepatitis segment remains a major market driver. Over 300 million people globally live with chronic hepatitis, approximately 254 million with HBV and 50 million with HCV, making it a significant public health concern. Long-term HBV therapies like tenofovir and entecavir, alongside curative HCV DAAs such as sofosbuvir and glecaprevir, have improved clinical outcomes. Vaccines for hepatitis A and B, along with new approvals like bulevirtide for HDV, are expanding preventive and therapeutic options. Regulatory support, policy efforts toward elimination, and improved diagnostics continue to enhance access, although early diagnosis and affordability challenges persist, particularly in underserved populations.
 To learn more about this report, Download Free Sample Report
The NAFLD/NASH segment is projected to grow at the fastest CAGR of 20.19% over the forecast period due to the growing prevalence of NAFLD and limited early detection.The disease poses a significant global health challenge, with only 10-20% of cases diagnosed in the early stages. NAFLD affects millions and can progress to NASH, fibrosis, cirrhosis, or HCC. The 2024 FDA approval of Rezdiffra (resmetirom)-a thyroid hormone receptor-β agonist-marked a major milestone, showing NASH resolution and fibrosis improvement in up to 30% of patients. In late-stage trials, other agents like obeticholic acid and elafibranor have demonstrated 20-30% fibrosis reduction. However, patient adherence to lifestyle interventions remains low, with 30-40% dropout rates. As pipeline drugs mature and diagnostic tools expand, the segment is expected to grow rapidly through 2026, transforming NASH management into a targeted therapeutic domain.
Regional Insights
North America dominated the liver disease therapeutic market with the largest revenue share of 40.0% in 2025, accounting for 39.87% of global revenue, driven by the rising prevalence of liver disease, aging populations, and breakthrough therapies. Over 4.5 million U.S. adults are affected, with similar trends in Canada and Mexico, driven by hepatitis B and C, NAFLD, ALD, and liver cancer. FDA-approved DAAs cure hepatitis C in at least eight weeks with over 95% success rates. Recent advances in NASH treatment, including GLP-1 agonists and FXR modulators, are nearing approval. Regulatory agencies such as the FDA, Health Canada, and COFEPRIS have accelerated review timelines, enhancing access to critical drugs. While reimbursement systems differ across the region, robust R&D, industry innovation, and regulatory flexibility continue to fuel sustained regional market growth.
 To learn more about this report, Download Free Sample Report
U.S. Liver Disease Therapeutics Market Trends
The liver disease therapeutic market in the U.S. held the largest share in the North America region in 2025, holding a significant revenue share due to its large patient population, advanced healthcare infrastructure, and rapid adoption of innovative therapies. The country faces a high prevalence of hepatitis B, hepatitis C, NAFLD, and liver cancer, with over 4.5 million adults affected by liver disease. A pivotal advancement occurred on March 14, 2024, when the FDA approved Rezdiffra (resmetirom) as the first treatment for noncirrhotic NASH with moderate to advanced fibrosis, addressing a major unmet need for the estimated 6-8 million Americans affected. Based on 12-month biopsy data from a 54-month trial, this milestone has fueled R&D momentum and heightened investor interest. Major pharmaceutical players and dual reimbursement systems further solidify the U.S. as the regional market leader.
Europe Liver Disease Therapeutics Market Trends
The liver disease therapeutics market in Europe held a substantial share in 2024, driven by the rising burden of hepatitis, NAFLD, and liver cancer, coupled with widespread alcohol consumption and aging populations. The region has seen increased early diagnosis rates due to national screening initiatives and greater public health awareness. Access to advanced treatments, including DAAs and novel targeted therapies, is improving through centralized healthcare systems and expanded reimbursement coverage. The EMA's support for fast-track drug approvals, as seen with bulevirtide for hepatitis D and elafibranor (Iqirvo) for PBC, reflects regulatory momentum. Ongoing clinical trials across Germany, France, and the UK are accelerating innovation, while growing adoption of non-invasive diagnostics such as FibroScan supports earlier interventions and better treatment outcomes.
The UK liver disease therapeutics marketcontributed significantly to the European market in 2024, driven by a rising prevalence of NAFLD, alcohol-related liver disease, and hepatitis infections. The NHS has implemented expanded screening and early detection programs, particularly for high-risk populations, which have improved diagnosis rates. NICE recommendations and national reimbursement schemes support access to innovative therapies, including DAAs for HCV and Rezdiffra for NASH. Research institutions across London, Cambridge, and Oxford are actively involved in liver disease clinical trials, advancing therapeutic options. Public health initiatives focusing on alcohol consumption and obesity management are also positively impacting disease outcomes, while increased investments in precision medicine and digital health tools are further transforming liver care across the UK.
The liver disease therapeutics market in Germany held a strong position in 2024, supported by its comprehensive healthcare infrastructure, robust diagnostic networks, and early adoption of advanced treatments. The country reported high rates of chronic hepatitis B and C, NAFLD, and alcohol-induced liver conditions, which have driven demand for antiviral drugs, targeted therapies, and supportive care. Germany’s statutory health insurance system ensures broad patient access to innovative drugs, including DAAs, GLP-1 agonists, and the recently approved Rezdiffra for NASH. Leading academic hospitals in cities such as Berlin, Munich, and Heidelberg are central to clinical trial activity and translational research.
France liver disease therapeutics market maintained a notable share in 2024, driven by a high burden of liver-related conditions, widespread screening programs, and access to innovative therapies. Rising cases of chronic hepatitis B and C, NAFLD, and alcoholic liver disease contributed to increased demand for antiviral drugs and emerging NASH treatments. The French healthcare system provides universal coverage, ensuring patient access to advanced drugs such as DAAs, FXR agonists, and GLP-1 receptor agonists. France is also actively involved in liver disease research, with institutions like INSERM and AP-HP leading clinical trials and biomarker studies.
Asia Pacific Liver Disease Therapeutics Market Trends
The liver disease therapeutics market in Asia Pacific is projected to grow at the fastest CAGR over the forecast period, fueled by the high prevalence of hepatitis B and C, rising NAFLD cases, and improving healthcare infrastructure. Countries such as China, India, and Japan are witnessing a growing disease burden due to aging populations, sedentary lifestyles, and urban dietary habits. Government-led screening initiatives and vaccination programs, particularly for hepatitis B, are expanding early diagnosis and treatment access. Increased pharmaceutical investments, local clinical trials, and accelerated regulatory pathways are boosting the availability of novel therapeutics, including DAAs, siRNA therapies, and GLP-1 receptor agonists.
Japan liver disease therapeutics market is expanding rapidly, driven by an aging population, high prevalence of hepatitis C, and increasing NAFLD/NASH cases. The country’s universal health insurance system ensures broad patient access. The government’s proactive screening for viral hepatitis and NASH in older adults has improved early diagnosis rates. Local biopharma and academic institutions in Tokyo, Osaka, and Kyoto actively participate in pivotal clinical trials for DAAs, siRNA agents, and fibrosis-targeting therapies. The 2024 inclusion of novel treatments like Resmetirom under public reimbursement reflects strong regulatory support.
The liver disease therapeutics market in China is growing steadily, fueled by its exceptionally high prevalence of hepatitis B, an estimated 70 million chronic carriers, alongside rising cases of NAFLD and alcohol-related liver conditions. The government’s national hepatitis B vaccination and screening programs have enhanced early detection and treatment access. China’s robust pharmaceutical sector, bolstered by increasing local clinical trial activity and accelerated regulatory approvals through the NMPA, facilitates faster market entry for innovative therapies such as DAAs, NASH agents, and siRNA treatments.
Latin America Liver Disease Therapeutics Market Trends
The liver disease therapeutics market in Latin America is developing steadily, driven by the growing burden of hepatitis B and C, non-alcoholic fatty liver disease (NAFLD), and alcohol-related liver conditions. Rising obesity rates and increased alcohol consumption have intensified the prevalence of liver disorders across countries like Brazil, Mexico, and Argentina. Public health initiatives, such as expanded hepatitis vaccination campaigns and awareness programs, enhance early diagnosis and treatment. Access to direct-acting antivirals (DAAs) and generic formulations has improved affordability, particularly through regional partnerships and government-subsidized programs.
Brazil liver disease therapeutics market holds a significant share of the Latin American market, driven by a high prevalence of hepatitis B, hepatitis C, non-alcoholic fatty liver disease (NAFLD), and alcohol-related liver conditions. The growing incidence of lifestyle-related disorders and liver complications has increased the demand for effective therapeutic options. Brazil's public health system plays a key role by ensuring access to essential medicines and running national programs for hepatitis prevention, early diagnosis, and treatment. Regulatory support from ANVISA accelerates drug approvals and facilitates reimbursement for advanced therapies.
Middle East & Africa Liver Disease Therapeutics Market Trends
The liver disease therapeutics market in the Middle East & Africa is growing steadily, driven by rising cases of hepatitis, NAFLD, and liver cancer linked to obesity, diabetes, and alcohol use. Increased awareness, vaccination efforts, and improved diagnostic initiatives promote early detection and treatment. Access to newer therapies such as direct-acting antivirals and anti-fibrotic drugs is expanding, especially in more developed Gulf nations. Governments are investing in specialized liver care and clinical research.
Saudi Arabia liver disease therapeutics market is expanding, fueled by the increasing prevalence of non-alcoholic fatty liver disease (NAFLD) and its progressive form, non-alcoholic steatohepatitis (NASH), largely due to rising obesity and diabetes rates. The country has seen a shift in liver disease burden from viral hepatitis to metabolic-related liver disorders. Public health initiatives focused on lifestyle modification, early screening, and vaccination programs contribute to improved disease detection and management. The government’s investment in healthcare infrastructure and access to advanced treatments enhances patient outcomes.
Key Liver Disease Therapeutics Company Insights
The market is led by major pharmaceutical companies such as Gilead Sciences, Inc., AbbVie Inc., and Bristol-Myers Squibb Company, which maintain a strong presence through innovative antiviral and immunomodulatory therapies. These companies benefit from extensive clinical research pipelines, established regulatory approvals, and robust global commercialization strategies. Other key players, including F. Hoffmann-La Roche Ltd, Takeda Pharmaceutical Company Limited, and Johnson & Johnson Services, Inc., are expanding their liver disease portfolios through acquisitions, partnerships, and targeted drug development. Merck & Co., Inc., Novartis AG, and Pfizer Inc. also contribute to market competitiveness by advancing combination therapies and leveraging precision medicine approaches.
Key Liver Disease Therapeutics Companies
The following key companies have been profiled for this study on the liver disease Ttherapeutics market.
-
Gilead Sciences, Inc.
-
AbbVie Inc.
-
Bristol-Myers Squibb Company
-
F. Hoffmann-La Roche Ltd
-
Takeda Pharmaceutical Company Limited.
-
Johnson & Johnson Services, Inc.
-
Merck & Co., Inc.
-
Novartis AG
-
Pfizer Inc.
-
Sanofi
-
GSK plc
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Gilead Sciences, Inc.; AbbVie Inc.; Bristol-Myers Squibb Company; F. Hoffmann-La Roche Ltd.; Takeda Pharmaceutical Company Limited; Johnson & Johnson Services, Inc.; Merck & Co., Inc.; Novartis AG; Pfizer Inc.; Sanofi; GSK plc)
- Focus on strengthening liver disease portfolios through product lifecycle management, label expansions, strategic acquisitions, licensing agreements, and continued investment in therapies for viral hepatitis, metabolic liver diseases, liver cancer, and rare liver disorders. Expand global presence through collaborations with healthcare providers, academic institutions, and regulatory agencies while supporting clinical development of next-generation therapeutics.
- Established commercial portfolios with strong capabilities in research, clinical development, regulatory approvals, manufacturing, and global distribution. Broad geographic presence, diversified therapeutic portfolios, and long-standing relationships with healthcare providers support product adoption across multiple liver disease indications.
- High research and development costs associated with long clinical timelines and evolving regulatory requirements. Dependence on patent-protected products exposes companies to revenue pressure from generic competition and biosimilars. Large organizational structures may extend decision-making and product development timelines.
Emerging Players (Madrigal Pharmaceuticals, Inc.; 89bio, Inc.; Akero Therapeutics, Inc.; Viking Therapeutics, Inc.; Sagimet Biosciences Inc.; Terns Pharmaceuticals, Inc.; Altimmune, Inc.)
- Focus on developing targeted therapies for metabolic dysfunction-associated steatohepatitis (MASH), liver fibrosis, and other chronic liver diseases through innovative mechanisms of action and strategic partnerships with larger pharmaceutical companies. Prioritize late-stage clinical development and regulatory advancement to strengthen product pipelines.
- Specialized development programs targeting unmet needs in chronic liver diseases, with flexibility to advance novel therapeutic approaches and combination therapies. Focused research strategies enable rapid clinical progression in selected disease indications.
- Limited commercial infrastructure and financial resources compared with established pharmaceutical companies. Heavy reliance on successful clinical trial outcomes, regulatory approvals, and strategic collaborations may affect product commercialization and global market expansion.
Recent Developments
-
In April 2025, Gilead Sciences, Inc. announced it would present over 40 abstracts at the AASLD Liver Meeting, highlighting advancements in viral hepatitis and primary biliary cholangitis (PBC). Key data included results from the RESPONSE and ASSURE studies on seladelpar, and the MYR301 study on bulevirtide for HDV. Additional presentations covered Epclusa’s safety in pregnancy, real-world SVR10K HCV data, and new HBV combination therapies.
-
In March 2025, Takeda Pharmaceutical Company Limited received approval from Japan's Ministry of Health, Labour and Welfare for Livmarli (maralixibat) Oral Solution. The drug is indicated for treating Alagille syndrome and progressive familial intrahepatic cholestasis (PFIC). This approval supports Takeda’s focus on addressing rare pediatric liver diseases with high unmet needs.
-
In August 2024, the U.S. FDA approved Gilead’s liver disease drug seladelpar (Pivlaz) for treating primary biliary cholangitis. The approval followed positive Phase 3 ENHANCE trial results showing significant efficacy. Gilead gained the drug through its USD 4.3 billion acquisition of CymaBay Therapeutics earlier in the year.
Liver Disease Therapeutics Market Report Scope
Report Attribute
Details
Market size in 2025
USD 21.9 billion
Estimated market size in 2026
USD 23.6 billion
Projected market size by 2033
USD 40.3 billion
Growth rate
CAGR of 8.0% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, disease, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Norway; Sweden; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait.
Key companies profiled
Gilead Sciences, Inc.; AbbVie Inc.; Bristol-Myers Squibb Company; F. Hoffmann-La Roche Ltd; Takeda Pharmaceutical Company Limited; Johnson & Johnson Services, Inc.; Merck & Co., Inc.; Novartis AG; Pfizer Inc.; Sanofi; GSK plc..
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Liver Disease Therapeutics Market Report Segmentation
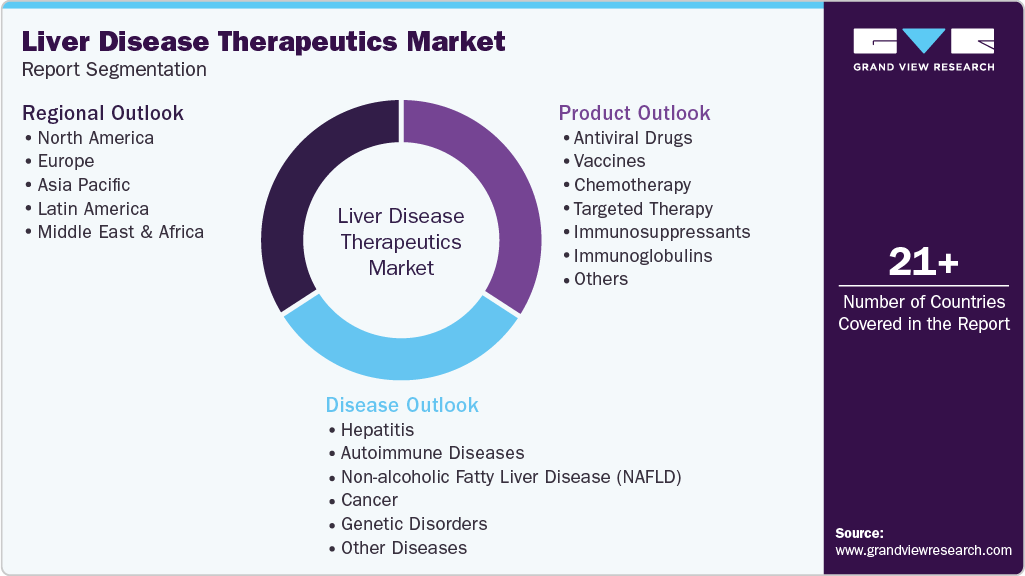
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global liver disease therapeutics market report based on product, disease, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Antiviral Drugs
-
Vaccines
-
Chemotherapy
-
Targeted Therapy
-
Immunosuppressants
-
Immunoglobulins
-
Corticosteroids
-
Other Products
-
-
Disease Outlook (Revenue, USD Million, 2021 - 2033)
-
Hepatitis
-
Autoimmune Diseases
-
Non-alcoholic Fatty Liver Disease (NAFLD)
-
Cancer
-
Genetic Disorders
-
Other Diseases
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The liver disease therapeutic market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each liver disease therapeutic segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Antiviral Drugs
Includes prescription antiviral medications indicated for the treatment and management of viral liver infections, primarily hepatitis B and hepatitis C. This segment covers direct-acting antivirals, nucleoside and nucleotide analogs, interferon-based antivirals, and other antiviral therapies intended to suppress viral replication or achieve viral clearance.
Vaccines
Includes prophylactic vaccines administered to prevent liver diseases caused by viral infections, primarily hepatitis A and hepatitis B. This segment covers monovalent and combination vaccines used in routine immunization programs, occupational protection, and high-risk populations, excluding therapeutic vaccines under clinical investigation.
Chemotherapy
Includes cytotoxic drugs administered for the treatment of primary liver cancers and selected metastatic liver malignancies. This segment covers systemic chemotherapy agents delivered alone or in combination regimens intended to inhibit tumor growth in patients with malignant liver diseases.
Targeted Therapy
Includes molecularly targeted drugs developed to inhibit specific signaling pathways involved in liver diseases, particularly hepatocellular carcinoma and metabolic liver disorders. The segment covers kinase inhibitors, monoclonal antibodies, and other targeted agents designed to improve clinical outcomes through pathway-specific mechanisms.
Immunosuppressants
Includes prescription therapies used to suppress immune system activity in autoimmune liver diseases and following liver transplantation. This segment comprises calcineurin inhibitors, antimetabolites, mTOR inhibitors, and other immunosuppressive agents indicated to prevent immune-mediated liver damage or organ rejection.
Immunoglobulins
Includes therapeutic immunoglobulin products used for passive immunization against hepatitis viruses or as supportive treatment in liver transplant recipients. This segment covers hepatitis B immunoglobulin and other immunoglobulin preparations indicated to prevent infection recurrence or provide temporary immune protection.
Corticosteroids
Includes corticosteroid therapies prescribed for immune-mediated liver disorders, particularly autoimmune hepatitis. The segment covers systemic corticosteroids used to reduce hepatic inflammation, control disease activity, and maintain remission either as monotherapy or in combination with other immunosuppressive agents.
Others
Includes liver disease therapies not classified under the preceding product categories. This segment covers bile acid therapies, antifibrotic agents, supportive medications, metabolic disease treatments, enzyme replacement therapies, investigational products with approved indications, and other pharmacological interventions used in liver disease management.
Segment - Disease
Revenue capture definition
Hepatitis
Includes therapeutic products indicated for the prevention and treatment of viral hepatitis, primarily hepatitis A, B, C, D, and E where applicable. This segment covers antiviral therapies, immunoglobulins, vaccines, and supportive pharmacological treatments prescribed for viral liver infections.
Autoimmune Diseases
Includes therapies indicated for autoimmune liver disorders resulting from immune-mediated liver injury. This segment primarily covers autoimmune hepatitis, primary biliary cholangitis, and primary sclerosing cholangitis managed through immunosuppressive agents, corticosteroids, biologics, and supportive pharmacological therapies.
Non-alcoholic Fatty Liver Disease (NAFLD)
Includes pharmacological therapies indicated for non-alcoholic fatty liver disease and metabolic dysfunction-associated steatotic liver disease, including non-alcoholic steatohepatitis (NASH/MASH). The segment covers treatments targeting hepatic fat accumulation, inflammation, fibrosis, and metabolic dysfunction associated with disease progression.
Cancer
Includes therapeutic products indicated for primary liver malignancies, predominantly hepatocellular carcinoma and intrahepatic cholangiocarcinoma. This segment covers chemotherapy, targeted therapies, immunotherapies, and combination drug regimens prescribed for malignant liver tumors, excluding surgical and interventional treatment procedures.
Genetic Disorders
Includes therapies indicated for inherited liver disorders caused by genetic abnormalities affecting liver function. This segment covers treatments for conditions such as Wilson disease, alpha-1 antitrypsin deficiency, hereditary hemochromatosis, and other rare inherited hepatic disorders requiring disease-specific pharmacological management.
Others
Includes pharmacological therapies indicated for liver diseases not categorized under hepatitis, autoimmune diseases, NAFLD, cancer, or genetic disorders. This segment covers alcoholic liver disease, drug-induced liver injury, cholestatic disorders, acute liver failure, cirrhosis, fibrosis, and other less common hepatic conditions.
Estimation Model
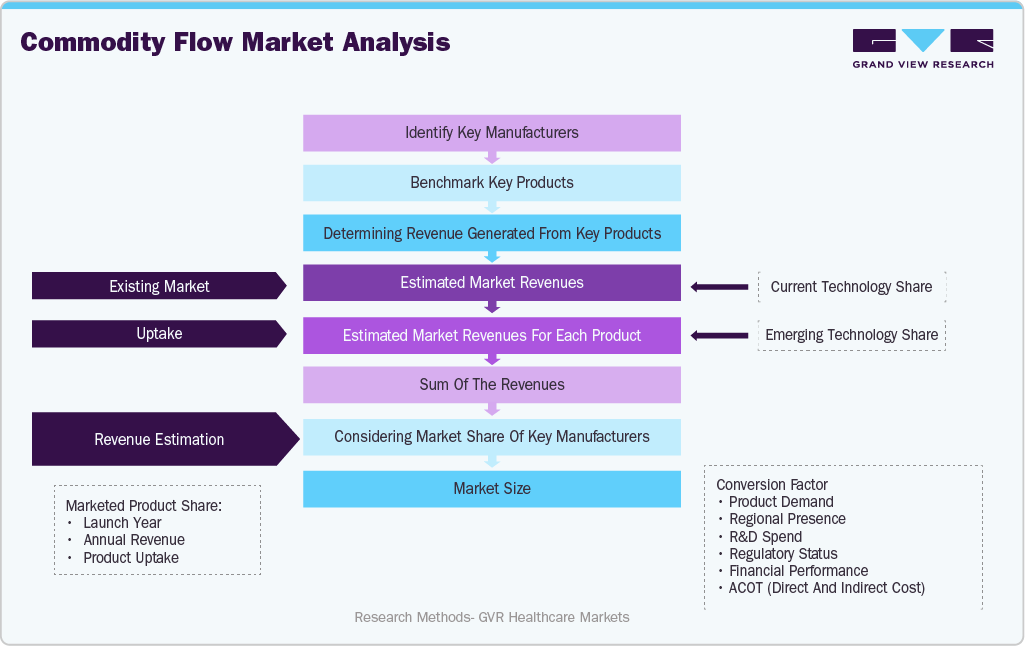
The liver disease therapeutic market was estimated using a commodity flow market analysis approach. Key manufacturers and marketed therapies across antiviral drugs, targeted therapies, immunosuppressants, corticosteroids, chemotherapy, immunoglobulins, vaccines, and other liver disease treatments were identified. Products were benchmarked based on annual revenues, launch year, product uptake, pricing, approved indications, and regional presence using company annual reports, investor presentations, regulatory filings, healthcare databases, and industry publications. Revenue generated from leading products was analyzed to estimate the existing market, followed by assessment of therapy-wise adoption across hepatitis, metabolic dysfunction-associated steatotic liver disease (MASLD/MASH), autoimmune liver diseases, liver cancer, genetic disorders, and other liver conditions. Market estimates were validated by considering manufacturer market share, treatment guidelines, product demand, regulatory approvals, geographic availability, and average annual treatment costs. Data triangulation and primary interviews with industry experts were used to finalize regional and global market estimates.
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Liver Disease Therapeutic Competitive Landscape & Pipeline Assessment
Conducted a targeted assessment of the global liver disease therapeutic market, evaluating approved products, late-stage pipeline assets, mechanism of action, disease indications, clinical development progress, and competitive positioning. The study analyzed companies including Gilead Sciences, AbbVie, Bristol Myers Squibb, Hoffmann-La Roche, Takeda Pharmaceutical Company, Johnson & Johnson, Merck & Co., Novartis, Pfizer, Sanofi, and others with emerging pipeline programs targeting chronic liver diseases, dysfunction-associated steatohepatitis (MASH), viral hepatitis, liver cancer, autoimmune liver diseases, and rare disorders.
Helped the client identify therapeutic opportunities, evaluate competitive gaps, benchmark clinical pipelines, and prioritize licensing, acquisition, and partnership opportunities across established and emerging liver disease therapeutic segments.
Liver Disease Therapeutic Portfolio & Technology Benchmarking Study
Delivered a comprehensive benchmarking analysis of liver disease therapeutic platforms, focusing on mechanism of action, product portfolios, clinical performance, regulatory status, adoption trends, and market access considerations. The assessment evaluated technologies targeting metabolic dysfunction-associated steatohepatitis, viral hepatitis, fibrosis, and hepatocellular carcinoma, while analyzing intellectual property positioning, scalability, and development strategies across leading pharmaceutical and biotechnology companies.
Enabled the client to assess portfolio competitiveness, identify pipeline gaps, benchmark therapeutic differentiation, and support investment decisions related to product development, licensing opportunities, and portfolio expansion within the liver disease therapeutic market.
Liver Disease Therapeutic Manufacturing & Supply Chain Assessment
Conducted a strategic assessment of the liver disease therapeutic manufacturing ecosystem, evaluating pharmaceutical manufacturing capabilities, active pharmaceutical ingredient (API) supply, biologics production, contract development and manufacturing organizations (CDMOs), regulatory compliance requirements, distribution networks, and global manufacturing capacity supporting commercial-scale production of liver disease therapies.
Supported manufacturing and supply chain planning by identifying optimized manufacturing partners, evaluating sourcing strategies, assessing production capabilities, and strengthening economic value chains while improving operational efficiency for regional and global markets.
Frequently Asked Questions About This Report
The global liver disease therapeutics market size was valued at USD 21.9 billion in 2025 and is estimated at USD 23.6 billion in 2026.
The global liver disease therapeutics market is expected to grow at a CAGR of 8.0% from 2026 to 2033, reaching USD 40.3 billion by 2033.
The antiviral drugs segment led the market with a 37.8% revenue share in 2025, while the targeted therapy segment is expected to witness the fastest growth during the forecast period.
Key players include Gilead Sciences, Inc., AbbVie Inc., Bristol Myers Squibb, F. Hoffmann-La Roche Ltd., Takeda Pharmaceutical Company Limited, Johnson & Johnson Services, Inc., Merck & Co., Inc., Novartis AG, Pfizer Inc., Sanofi, and GSK plc.
North America dominated the liver disease therapeutics market with a 40.0% revenue share in 2025.
Asia Pacific is expected to be the fastest-growing regional market during the forecast period, supported by increasing healthcare expenditure, a large patient population, and improving access to advanced liver disease therapies.
The hepatitis segment accounted for the largest revenue share of 34.2% in 2025, driven by the widespread prevalence of chronic hepatitis B and C infections and continued demand for antiviral therapies.
Targeted therapies, particularly those developed for MASH, liver fibrosis, and hepatocellular carcinoma, are expected to register the fastest growth owing to increasing regulatory approvals, expanding clinical pipelines, and advancements in precision medicine.
Key factors include the rising prevalence of chronic liver diseases such as MASLD/MASH, hepatitis, cirrhosis, and liver cancer, increasing obesity and diabetes rates, growing investment in targeted therapies, expanding clinical pipelines, improved diagnostic capabilities, and favorable regulatory approvals for novel liver disease treatments.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


