
- Home
- »
- Clothing, Footwear & Accessories
- »
-
Luxury Jewelry Market Size And Share Report, 2026-2033GVR Report cover

Luxury Jewelry Market (2026 - 2033)
Size, Share & Trend Analysis Report By Product (Necklace, Ring, Bracelet, Earring), By Raw Material (Gold, Platinum, Diamond, Gemstone, Precious Pearl), By Distribution Channel (Online, Offline), By Application, By Region, And Segment Forecasts
Market Size, 2025
$54.2BMarket Estimate, 2026
$59.0BMarket Forecast, 2033
$99.9BCAGR, 2026–2033
7.8%Luxury Jewelry Market Summary
The global luxury jewelry market size was valued at USD 54.2 billion in 2025 and is projected to grow from USD 59.0 billion in 2026 to USD 99.9 billion by 2033, at a CAGR of 7.8% from 2026 to 2033. The market in Asia Pacific dominated with a revenue share of 66.9% in 2025. The global market is primarily driven by rising disposable incomes, evolving fashion sensibilities, and growing consumer appetite for premium accessories that combine personal meaning with status appeal.
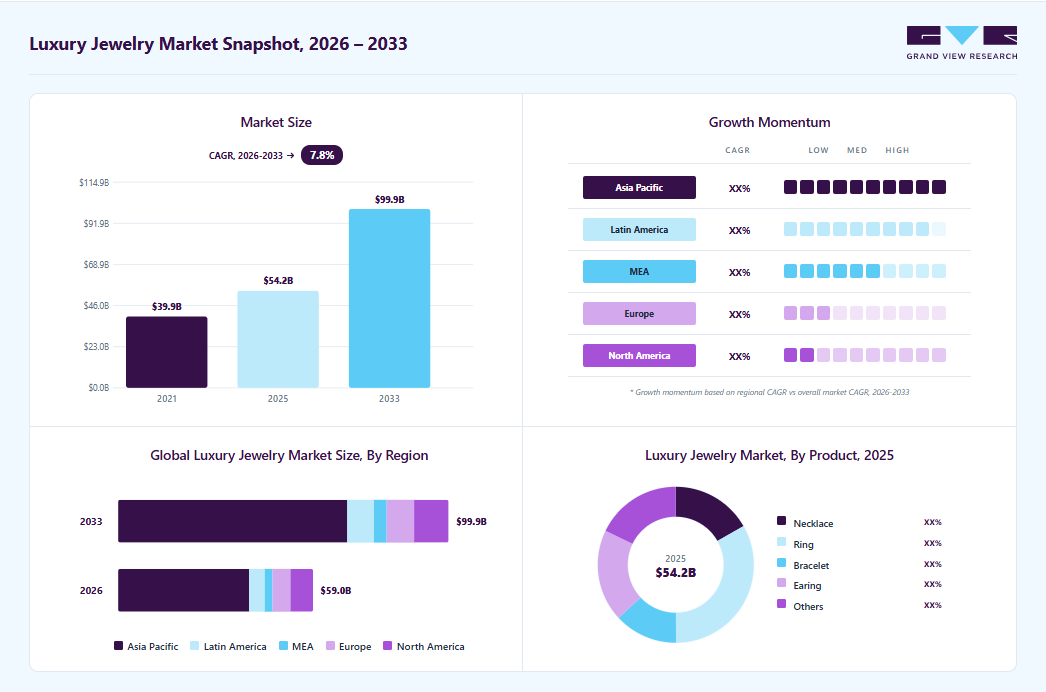 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By distribution channel: Offline segment held the largest market share of 74.4% in 2025.
- By application: Female segment held the largest market share of 67.1% in 2025.
- By product: Ring segment held the largest market share of 33.2% in 2025.
- By raw material: Gold segment held the largest market share of 33.1% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (66.9% revenue share, 2025)
- By country: China held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 54.2 Billion
- Estimated market size in 2026: USD 59.0 Billion
- Projected market size by 2033: USD 99.9 Billion
- CAGR (2026-2033): 7.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
As affluent and upper-middle-income populations continue to grow globally, spending on premium jewelry is increasing steadily across both mature and emerging markets. The U.S. luxury fine jewelry market continues to benefit from strong demand for diamond engagement rings, personalized fine jewelry, and investment-oriented gold and platinum pieces, particularly among younger affluent consumers seeking products that combine emotional value with long-term worth. At the same time, the Asia Pacific luxury jewelry market is witnessing rapid expansion driven by rising disposable incomes, aspirational luxury spending, and increasing consumer preference for branded jewelry collections.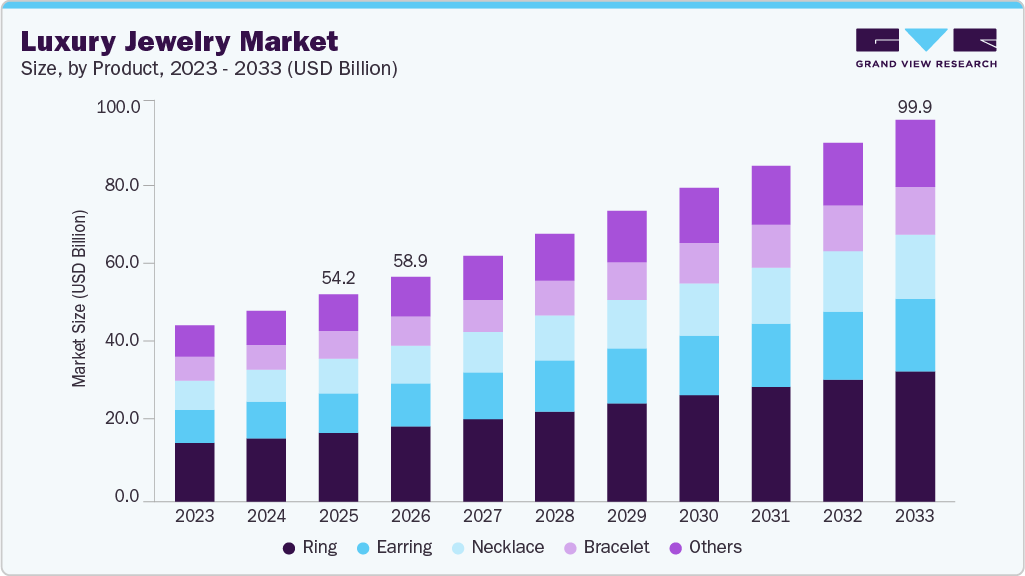 To learn more about this report, Download Free Sample Report
In the UK luxury jewelry market, buyers are increasingly drawn toward heritage-inspired craftsmanship, timeless designs, and rare gemstone collections that reflect exclusivity and sophistication. Alongside branded luxury collections, the handmade jewelry market is also gaining significant traction as consumers increasingly value artisanal detailing, limited-edition creations, and personalized jewelry that reflects individuality and self-expression.
Competitive dynamics within the luxury jewelry industry continue to be shaped by heritage branding, craftsmanship, exclusivity, and evolving consumer expectations. Leading maisons such as Cartier, Tiffany & Co., Bulgari, and Van Cleef & Arpels remain highly influential across the U.S. luxury fine jewelry market and the UK luxury jewelry market, where consumers place strong emphasis on certified gemstones, premium materials, and brand legacy. Across the Asia Pacific luxury jewelry market, luxury brands are increasingly introducing region-specific collections, high-jewelry showcases, and exclusive client experiences to strengthen engagement with affluent buyers. Meanwhile, the growing popularity of the handmade jewelry market is encouraging independent designers and luxury brands alike to focus more heavily on customization, handcrafted production methods, and one-of-a-kind designs. Ethical sourcing is also becoming increasingly important, particularly in the U.S. luxury fine jewelry market, where consumers are increasingly preferring traceable diamonds, responsibly sourced gold, and sustainability-focused luxury products.
Manufacturing innovation is further transforming the luxury jewelry industry as brands combine traditional craftsmanship with advanced technologies such as digital prototyping, precision stone-setting, and AI-enabled customization tools. These developments are helping both established luxury houses and participants in the handmade jewelry market deliver faster personalization and bespoke design services without compromising craftsmanship quality. The UK luxury jewelry market is also seeing rising demand for modern handcrafted collections that blend artisanal techniques with contemporary aesthetics, while the Asia Pacific luxury jewelry market continues to benefit from increasing investments in premium retail experiences and digitally enabled luxury shopping platforms. In addition, the U.S. luxury fine jewelry market is witnessing growing demand for gender-neutral jewelry, collectible fine jewelry, and personalized statement pieces, reflecting broader shifts toward self-expression and modern luxury consumption patterns.
Brand Market Share Insights
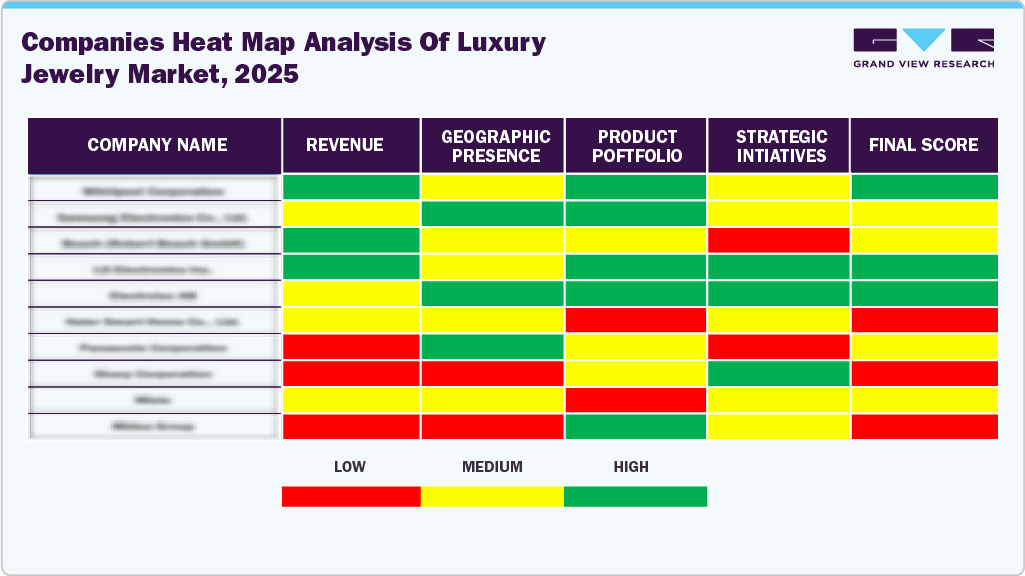
In the global luxury jewelry market, brands are increasingly optimizing their portfolios to capture growth across ultra-luxury, accessible luxury, and emerging men’s jewelry segments, reflecting a broader and more diversified international consumer base. Leading luxury houses are intensifying their focus on exceptional craftsmanship, high-jewelry exclusivity, and bespoke services designed for affluent consumers who prioritize rarity, heritage, and long-term value. Certified diamonds, traceable gemstones, artisanal production, and personalized client experiences remain key differentiators in a competitive environment shaped by strong brand prestige and high discretionary spending. These players are leveraging digital storytelling, influencer partnerships, and global omnichannel reach to stay aligned with evolving aesthetics and consumer discovery habits. In addition, men’s luxury jewelry is gaining momentum worldwide, with brands introducing contemporary rings, chains, and gender-neutral designs that reflect shifting norms around self-expression.
 To learn more about this report, Download Free Sample Report
Consumer Insights for Luxury Jewelry
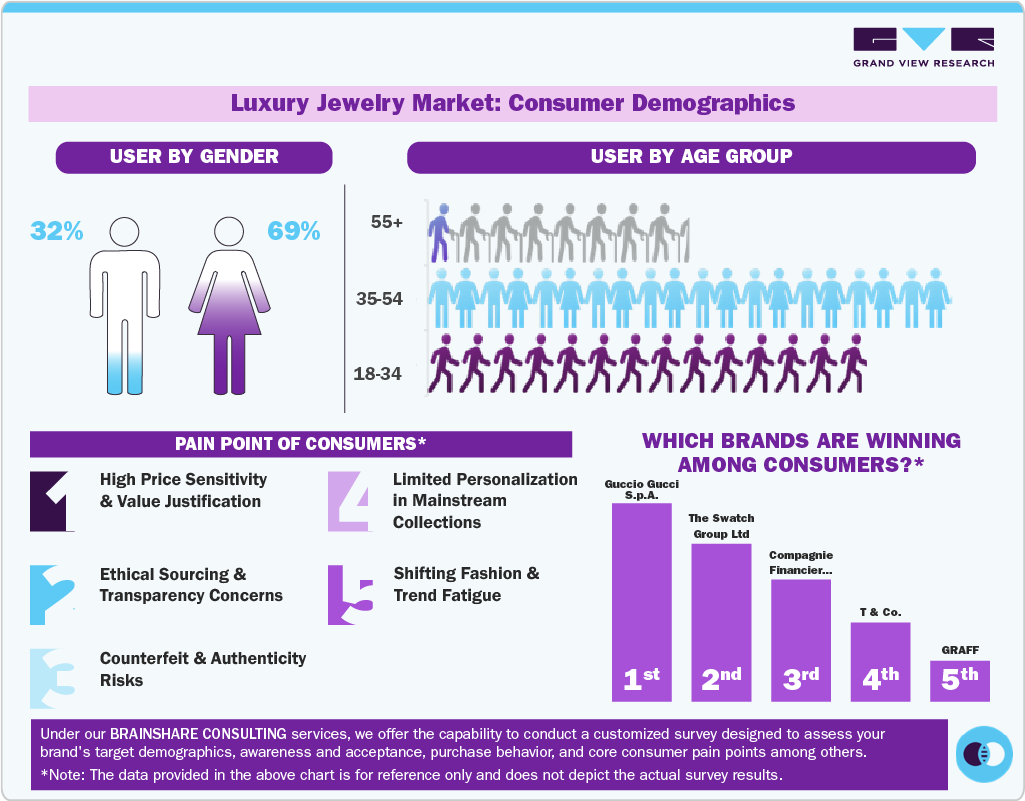
Affluent consumers are showing rising interest in jewelry that feels timeless yet adaptable, such as diamond stud earrings, delicate tennis bracelets, minimalist gold necklaces, and sleek stacking rings that can be worn across multiple settings. Luxury jewelry is becoming more integrated into daily wardrobes, driven by a growing culture of self-purchase and self-reward, particularly among high-income millennials and younger professionals who view fine pieces as symbols of success, emotional memory, and lasting craftsmanship rather than occasional indulgences.
At the same time, the luxury jewelry buying process is becoming more discerning and quality-led, with consumers placing heightened importance on authenticity, provenance, and the artistry behind each piece. Certified diamonds, traceable gemstones, and responsibly sourced precious metals are increasingly treated as baseline expectations in the premium segment, reflecting stronger consumer attention to ethical transparency and long-term trust. Established maisons continue to reinforce their leadership through signature design languages, meticulous stone-setting standards, and rarity-driven collections that emphasize exclusivity. Limited-edition releases, high jewelry showcases, and bespoke client services remain central to luxury differentiation, as ultra-premium buyers prioritize uniqueness and heritage positioning over mass accessibility.
 To learn more about this report, Download Free Sample Report
Spending patterns in the global luxury jewelry market vary sharply across consumer tiers: aspirational luxury shoppers enter through accessible fine jewelry lines and branded everyday collections, while high-net-worth individuals continue to concentrate demand on exceptional gemstones, one-of-a-kind creations, and investment-grade pieces. Additionally, demand is expanding beyond traditional women’s categories, with men’s luxury jewelry gaining visibility through modern chains, rings, and gender-neutral styling that reflects shifting cultural norms around self-expression. Digital engagement is also influencing luxury jewelry consumption, as consumers increasingly interact with brands through immersive storytelling, online personalization tools, virtual consultations, and curated omnichannel experiences that complement heritage retail environments.
Product Insights
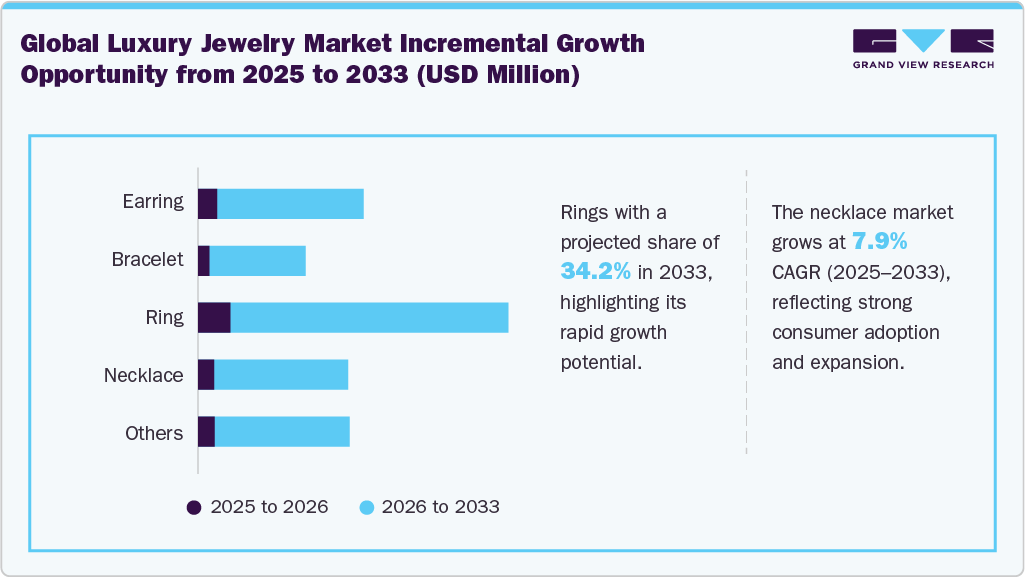
The rings accounted for the largest share of 33.2% of the global revenue in 2025. In the luxury jewelry segment, rings carry exceptional emotional and symbolic value, making them the most preferred category for engagements, weddings, anniversaries, and milestone gifting. Luxury consumers continue to prioritize diamond solitaires, eternity bands, and statement cocktail rings as enduring markers of commitment, status, and craftsmanship. Rising global wealth levels and higher discretionary spending among affluent buyers are further supporting demand for premium ring designs featuring certified gemstones, high-purity gold, and platinum settings.
The luxury ring category is also being shaped by strong momentum in customization and exclusivity. High-net-worth individuals increasingly seek bespoke creations, rare stone selections, and made-to-order designs that reflect individuality and investment value. Leading maisons such as Cartier, Tiffany & Co., Bulgari, and Van Cleef & Arpels continue to strengthen the segment through iconic bridal collections, limited-edition high jewelry pieces, and heritage-driven craftsmanship positioning.
 To learn more about this report, Download Free Sample Report
The necklace segment is projected to grow at the CAGR of 7.9% from 2026 to 2033. Luxury necklaces offer a broad spectrum of designs, ranging from high-jewelry diamond and gemstone statement pieces to refined minimalist pendants and delicate gold chains, allowing consumers to select pieces that align with personal identity and lifestyle preferences. Their ability to elevate both casual and formal looks makes necklaces a highly favored category for self-purchase, gifting, and milestone celebrations. In addition, consumers are increasingly combining multiple fine necklaces, such as pendants, chokers, and diamond station chains, to create distinctive, customized styling combinations. Luxury brands are responding by launching modular designs, adjustable lengths, and bespoke pendant options that encourage repeat purchases and collection-building.
Raw Material Insights
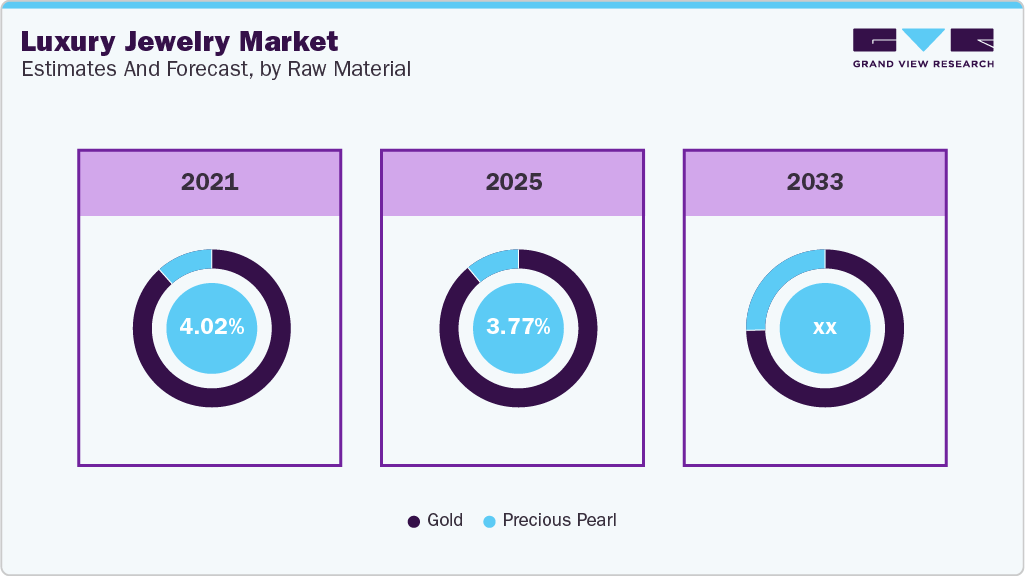
The gold jewelry market accounted for the largest share of 33.1% of the revenue in 2025. Gold’s cultural significance, timeless appeal, and status as a symbol of wealth and prosperity make it a preferred choice for many consumers. Gold's versatility in jewelry design also plays a role, as it can be crafted into a wide range of styles and combined with various gemstones to create exquisite pieces. Gold's intrinsic value and stability as an investment asset also solidify its position in the market. Gold prices have surged by more than 25% over the past year, making the precious metal an increasingly valuable asset and a reliable form of collateral. As gold prices hit record highs, demand for gold in India increased by 5%, reaching 802.8 tons in 2024. In terms of value, gold demand rose by 21%, reaching USD 59.7 billion in 2024, according to the World Gold Council.
 To learn more about this report, Download Free Sample Report
The platinum jewelry market is projected to grow at the fastest CAGR of 8.5% from 2026 to 2033. Platinum’s density and strength make it the preferred setting metal for high-value diamonds and rare colored stones, ensuring superior security and longevity in couture-level designs. Leading maisons such as Cartier and Tiffany & Co. continue to prominently feature platinum in their bridal and high jewelry collections, reflecting its role as a benchmark material in the luxury segment. In addition, ultra-high-net-worth buyers are increasingly seeking bespoke platinum pieces and limited-edition releases that emphasize exclusivity, certified sourcing, and artisanal finishing.
Distribution Channel Insights
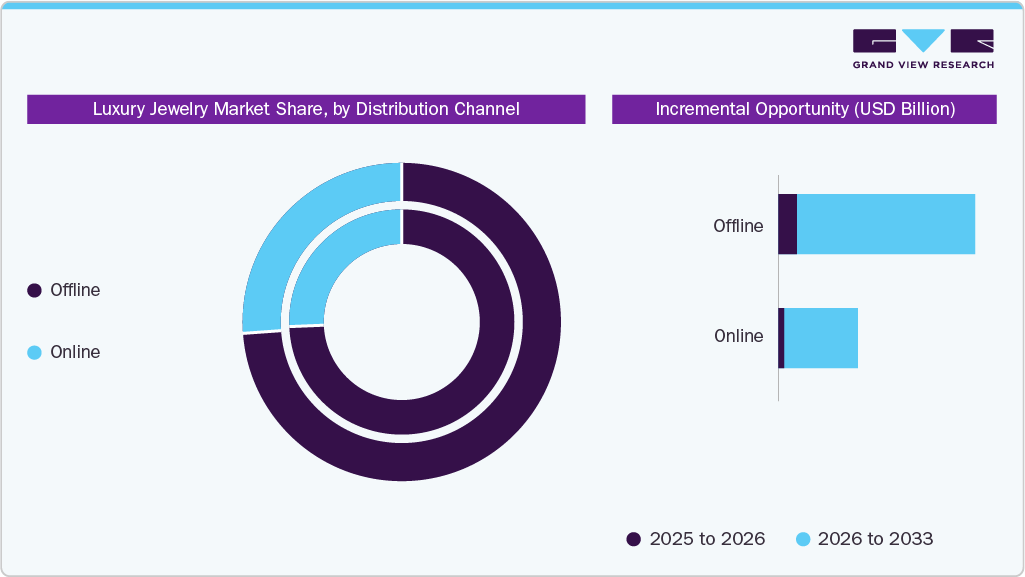
Luxury jewelry sales through offline channels accounted for the largest share of around 74.4% of the global revenue in 2025. Consumers consistently prefer in-store buying for categories such as diamond rings, platinum bridal pieces, and high-jewelry collections, where direct evaluation of craftsmanship, gemstone brilliance, metal purity, weight, and finishing precision is essential. The tactile experience of viewing pieces under professional lighting and comparing design intricacies remains a critical advantage of offline luxury channels, particularly for emotionally significant and investment-oriented purchases.
In addition, offline luxury jewelry boutiques and flagship stores provide elevated service experiences that are difficult to replicate online. Personalized client consultations, private appointments, bespoke customization, certification guidance, and heritage storytelling play a central role in influencing purchase decisions. After-sales services such as resizing, repairs, cleaning, and warranty support further strengthen trust and long-term brand relationships.
 To learn more about this report, Download Free Sample Report
Luxury jewelry sales through the online channels are projected to grow at the fastest CAGR of 8.3% from 2026 to 2033. Features such as ultra-high-definition product imagery, 360-degree viewing, virtual try-ons, certification transparency, and bespoke customization interfaces are reducing purchase hesitation and enhancing trust. Global maisons such as Cartier, Tiffany & Co., and Bulgari are integrating private virtual appointments, digital clienteling, and omnichannel services to maintain luxury-level exclusivity in online environments. In addition, insured delivery, premium packaging, flexible financing, and streamlined return policies are strengthening consumer confidence, positioning online channels as a key growth engine for luxury jewelry sales worldwide.
Application Insights
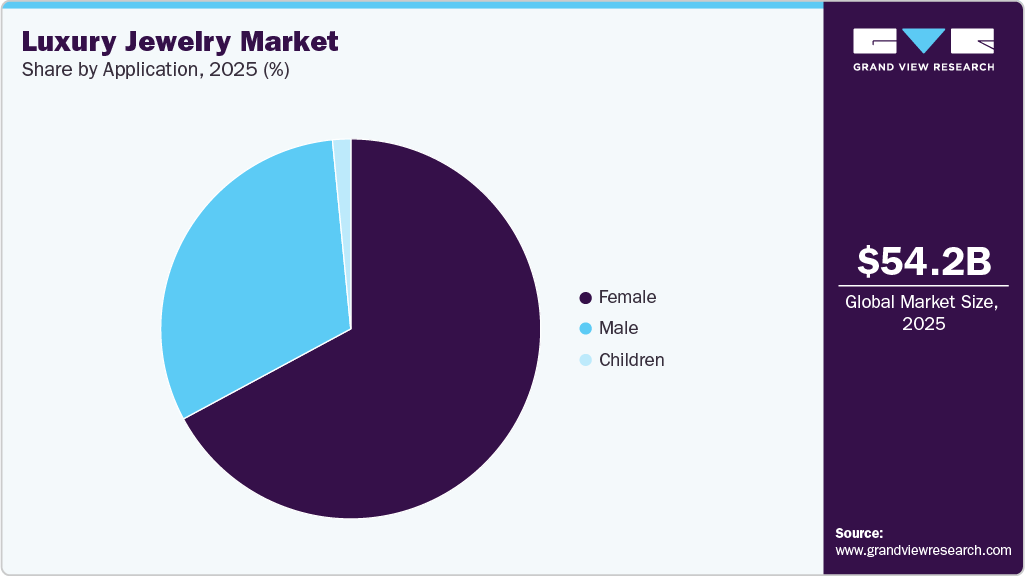
Female’s luxury jewelry accounted for the largest share of around 67.1% of the revenue in 2025. Female buyers drive sustained demand for high-value categories such as bridal diamond rings, gold and platinum wedding sets, designer earrings, and everyday fine jewelry collections. Luxury jewelry purchases among women are increasingly linked not only to traditional gifting and ceremonial milestones, but also to self-purchase motivations, including personal achievement, lifestyle enhancement, and long-term value ownership. This shift has strengthened year-round demand beyond seasonal occasions, positioning women as the most influential consumer group within the luxury segment.
 To learn more about this report, Download Free Sample Report
The demand for luxury jewelry among the male end user segment is projected to grow at the fastest CAGR of 8.2% from 2026 to 2033. Men are increasingly adopting fine jewelry not only for ceremonial occasions but also for everyday personal styling and self-expression. Demand is rising for premium rings, chains, bracelets, signet pieces, and understated diamond-accented designs that align with contemporary masculine aesthetics. Luxury jewelry is also gaining traction among male consumers as a symbol of status, individuality, and long-term value, supporting greater spending beyond traditional watch-led luxury categories.
Regional Insights
The North America luxury jewelry market accounted for the market share of 11.88% in 2025. Consumers are increasingly prioritizing certified gemstones, ethically sourced precious metals, and transparent supply chains, encouraging brands to expand sustainable luxury offerings. E-commerce and omnichannel strategies are also accelerating growth, with virtual consultations, AR try-ons, and premium delivery services making luxury jewelry more accessible beyond flagship boutiques. Social media influence, celebrity-driven trends, and seasonal promotional cycles continue to shape consumer preferences, positioning North America as a key hub of innovation and demand in the global luxury jewelry market.
U.S. Luxury Jewelry Market Trends
The U.S. led the North American luxury jewelry market in 2025, holding the largest market share with 53.72% of the region’s total revenue. Luxury jewelry demand in the country is supported by high discretionary spending, a deeply rooted gifting culture, and the growing role of fine jewelry as a symbol of personal identity and lifestyle aspiration. American consumers are increasingly purchasing luxury pieces not only for engagements, weddings, and anniversaries, but also for self-reward and everyday elegance, reinforcing year-round demand across diamonds, gold, and premium designer collections. Personalization, heritage storytelling, and exclusivity remain key differentiators shaping purchase decisions among affluent buyers.
The Canada luxury jewelry market is expected to grow steadily at a CAGR of 6.2% from 2026 to 2033, driven by rising demand for premium branded jewelry, ethically sourced gemstones, and investment-oriented purchases. Consumers are increasingly favoring sustainable and traceable luxury jewelry, while growing omnichannel retail strategies and strict hallmarking standards continue to strengthen consumer confidence and market expansion.
The Mexico luxury jewelry market is projected to witness a CAGR of 6.5% during the forecast period, supported by increasing affluent consumer spending, tourism-driven luxury purchases, and rising demand for artisanal fine jewelry. The market is benefiting from Mexico’s strong silver jewelry heritage, expanding premium retail infrastructure, and growing preference for culturally inspired luxury designs.
Europe Luxury Jewelry Market Trends
The luxury jewelry market in Europe is projected to grow at the fastest CAGR of 6.4% from 2026 to 2033, supported by the region’s deep heritage in fine craftsmanship, high fashion influence, and continued demand for premium accessories across both established and emerging luxury segments. European consumers place strong value on design excellence, artisanal production, and brand legacy, making countries such as France, Italy, and Switzerland central hubs for high-jewelry maisons and luxury innovation. Demand remains closely tied to milestone occasions, including engagements, weddings, anniversaries, and festive gifting, while a growing culture of self-purchase is expanding luxury jewelry consumption beyond traditional celebratory use.
The luxury jewelry market in the UK is projected to grow at the fastest CAGR of 5.7% from 2026 to 2033. Demand is driven by milestone-led purchases such as engagements, weddings, anniversaries, and heritage gifting, alongside a rising culture of self-purchase among affluent professionals. UK consumers continue to value craftsmanship, provenance, and timeless design, making heritage maisons and established luxury retailers highly influential. At the same time, growing interest in sustainable luxury is encouraging buyers to prioritize ethically sourced diamonds, recycled precious metals, and transparent certification, reshaping expectations across the premium segment.
Asia Pacific Luxury Jewelry Market Trends
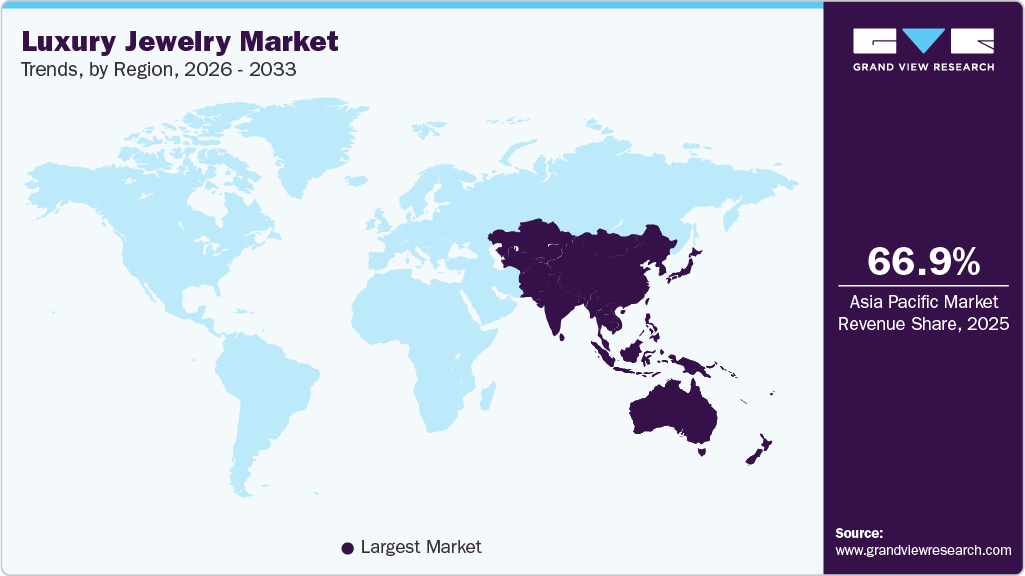
The Asia Pacific market dominated the global market, with the largest revenue share of 66.87% in 2025, driven by rapid economic expansion, rising disposable incomes, and increasing aspiration toward premium lifestyle consumption. The region benefits from a growing affluent and upper-middle-class population, accelerating urbanization, and strong demand for high-end accessories as symbols of wealth, status, and personal achievement. Cultural traditions across countries such as India, China, and Southeast Asian markets continue to reinforce consistent luxury jewelry spending, particularly in gold, diamonds, and precious gemstone pieces purchased for weddings, festivals, and family milestone celebrations.
 To learn more about this report, Download Free Sample Report
The China luxury jewelry market is anticipated to expand at a robust CAGR of 7.5% between 2026 and 2033, fueled by rising luxury consumption among millennials and Gen Z consumers, growing demand for branded fine jewelry, and increasing digital luxury retail adoption. Consumers are increasingly viewing luxury jewelry as both a status symbol and a long-term investment asset, supporting continued market growth.
The India luxury jewelry market is forecast to register a strong CAGR of 7.8% from 2026 to 2033, driven by rising disposable incomes, growing branded jewelry penetration, and the cultural significance of gold and diamond jewelry. Increasing consumer preference for certified products, contemporary lightweight designs, and organized retail formats is further accelerating market development.
The Japan luxury jewelry market is expected to witness notable growth at a CAGR of 8.3% over the forecast period, supported by strong demand for minimalist luxury designs, premium craftsmanship, and investment-grade jewelry. The rising popularity of heritage collections, gender-neutral jewelry, and authenticated pre-owned luxury jewelry is also contributing to market expansion.
Central & South America Luxury Jewelry Market Trends
The luxury jewelry market in Central & South America is projected to grow at a CAGR of 8.0% from 2026 to 2033. Expanding luxury consumption among upper-income households, especially in Brazil, Mexico, Chile, and Argentina, is driving higher spending on designer collections and investment-oriented jewelry. At the same time, the regional luxury jewelry landscape is evolving as consumers increasingly seek modern design sophistication alongside traditional craftsmanship. Local jewelers are gaining visibility through distinctive gemstone sourcing and artisanal techniques, while global maisons are strengthening their footprint through selective boutique expansion and premium partnerships.
Middle East & Africa Luxury Jewelry Market Trends
The Middle East & Africa luxury jewelry market is anticipated to register a healthy CAGR of 7.3% during the 2026 to 2033 period, supported by rising luxury spending among high-net-worth individuals, strong cultural affinity toward gold and gemstone jewelry, and increasing investments in premium retail infrastructure across key regional economies. The Gulf Cooperation Council (GCC) countries, particularly the UAE and Saudi Arabia, continue to dominate regional demand due to high disposable incomes, expanding tourism sectors, and strong consumer preference for high-carat gold jewelry and exclusive luxury collections. Luxury jewelry purchases in the region are closely linked to weddings, gifting traditions, and wealth preservation, driving sustained demand across both traditional and contemporary jewelry formats.
In Africa, demand for luxury jewelry is gradually expanding amid rising urban affluence, greater exposure to global luxury brands, and the development of premium retail channels in major cities. International luxury maisons are increasingly strengthening their regional presence through flagship boutiques, high-jewelry exhibitions, and private client experiences tailored to ultra-high-net-worth consumers. Additionally, government regulations related to gold trading, gemstone certification, anti-counterfeit measures, and luxury imports are evolving across the region, contributing to improved market formalization and greater consumer confidence in branded luxury jewelry products.
Key Luxury Jewelry Companies:
The following key companies have been profiled for this study on the luxury jewelry market.
- Guccio Gucci S.p.A.
- The Swatch Group Ltd
- Compagnie Financière Richemont SA
- T&CO.
- GRAFF
- LOUIS VUITTON
- Signet Jewelers.
- Chopard
- MIKIMOTO
- Pandora
Recent Developments
-
In May 2026, Tiffany & Co. unveiled its “Hidden Garden” high jewelry collection, inspired by floral and nature-based themes including butterflies, birds, and botanical elements. The collection featured rare diamonds, emeralds, and colored gemstones crafted into intricate platinum and gold designs, highlighting growing consumer demand for artistic storytelling, collectible luxury jewelry, and investment-grade high jewelry pieces.
-
In April 2026, Cartier introduced a new range of high-jewelry-inspired luxury watches and gemstone creations during Watches and Wonders 2026. The launch showcased sculptural timepieces featuring precious stones, intricate craftsmanship, and heritage-inspired designs, reflecting the increasing convergence of haute horology and fine jewelry within the global luxury market.
-
In March 2026, Bulgari launched its “Eclectica” high jewelry collection in Milan, presenting bold statement necklaces, transformable luxury pieces, and gemstone-focused creations featuring rare sapphires, emeralds, and colored diamonds. The launch reinforced rising demand for ultra-premium craftsmanship and exclusive collectible jewelry among high-net-worth consumers.
-
In October 2025, Tiffany & Co. introduced its reimagined “Bird on a Rock” high and fine jewelry collection inspired by Jean Schlumberger’s iconic archival motif. The collection incorporated diamond-centered wing-inspired designs and contemporary interpretations of heritage luxury jewelry, targeting affluent consumers seeking timeless yet modern statement pieces.
-
In October 2025, Tiffany & Co. expanded its Blue Book 2025 “Sea of Wonder” collection with nearly 40 new marine-inspired high jewelry creations featuring rare gemstones, shell-inspired motifs, and transformable luxury jewelry concepts. The launch highlighted growing market interest in narrative-led high jewelry and artistic gemstone compositions.
-
In February 2025, Aesop, known for its unconventional fragrances, collaborated with jeweler Patcharavipa Bodiratnangkura to create a limited-edition rhodium-plated ear cuff, inspired by the brand's floral fragrance "Aurner." The cuff’s organic leaf design reflects Aesop's deep connection to the arts.
-
In February 2025, Tanishq debuted at New York Fashion Week, collaborating with fashion designer Bibhu Mohapatra. The collaboration featured over 40 creations that complemented Bibhu's 2025 Fall collection, inspired by Indian heritage. Tanishq’s designs, known for their global appeal, highlighted the essence of India’s craftsmanship, enhancing the collection's bold elements.
Luxury Jewelry Market Report Scope
Report Attribute
Details
Market size in 2025
USD 54.2 billion
Estimated market size in 2026
USD 59.0 billion
Projected market size by 2033
USD 99.9 billion
Growth rate
CAGR of 7.8% from 2026 to 2033
Actual data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD Million, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, Raw Material, Distribution Channel, Application, and Region
Regional Scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; India; Japan; Australia & New Zealand; South Korea; Brazil; Argentina; South Africa; UAE
Key companies profiled
Guccio Gucci S.p.A.; The Swatch Group Ltd; Compagnie Financière Richemont SA; T&CO.; GRAFF; LOUIS VUITTON; Signet Jewelers.; Chopard; MIKIMOTO; Pandora
Customization scope
Free report customization (equivalent up to 8 analysts’ working days) with purchase. Addition or alteration to country, regional & segment scope. Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options Global Luxury Jewelry Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global luxury jewelry market report on the basis of product, raw material, distribution channel, application, and region.
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Necklace
-
Ring
-
Earring
-
Bracelet
-
Others
-
-
Raw Material Outlook (Revenue, USD Million, 2021 - 2033)
-
Gold
-
Platinum
-
Diamond
-
Gemstone
-
Precious Pearl
-
Others
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Offline
-
Online
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Men
-
Women
-
Children
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia & New Zealand
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
UAE
-
-
Frequently Asked Questions About This Report
Key players include Guccio Gucci S.p.A.; The Swatch Group Ltd; Compagnie Financière Richemont SA; T&CO.; GRAFF; LOUIS VUITTON; Signet Jewelers.; Chopard; MIKIMOTO; Pandora.
Key factors that are driving the luxury jewelry market growth include increasing consumer preference for branded jewelry and a rising standard of living among the urban class population worldwide.
The ring segment led with a 33.2% revenue share in 2025.
The gold segment led with a 33.1% revenue share in 2025, while platinum is the fastest-growing material.
The offline segment led with a 74.4% revenue share in 2025, while online is the fastest-growing channel.
Female segment held the largest share (over 67.0%) in 2025, while male is the fastest-growing application.
The global luxury jewelry market size was valued at USD 54.2 billion in 2025 and is estimated at USD 59.0 billion for 2026.
The global luxury jewelry market is expected to grow at a CAGR of 7.8% from 2026 to 2033, reaching USD 99.9 billion by 2033.
Asia Pacific market dominated the global market, with the largest revenue share of 66.9% in 2025, driven by rapid economic expansion, rising disposable incomes, and increasing aspiration toward premium lifestyle consumption.
About the Author(s)
Clothing, Footwear & Accessories Research Team
Consumer Goods · Clothing, Footwear & AccessoriesThis report was authored by the clothing, footwear & accessories research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the clothing, footwear & accessories segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


