
- Home
- »
- Pharmaceuticals
- »
-
Myeloproliferative Disorders Drugs Market Size Report, 2033GVR Report cover

Myeloproliferative Disorders Drugs Market (2026 - 2033)
Size, Share & Trends Analysis Report By Indication (Ph+ Chronic myelogenous leukemia (CML), Ph- Myeloproliferative Neoplasms (MPNs)), By Treatment Type, By End Use, By Region, And Segment Forecasts
Market Size, 2025
$11.9BMarket Estimate, 2026
$12.5BMarket Forecast, 2033
$19.7BCAGR, 2026–2033
6.7%Myeloproliferative Disorders Drugs Market Summary
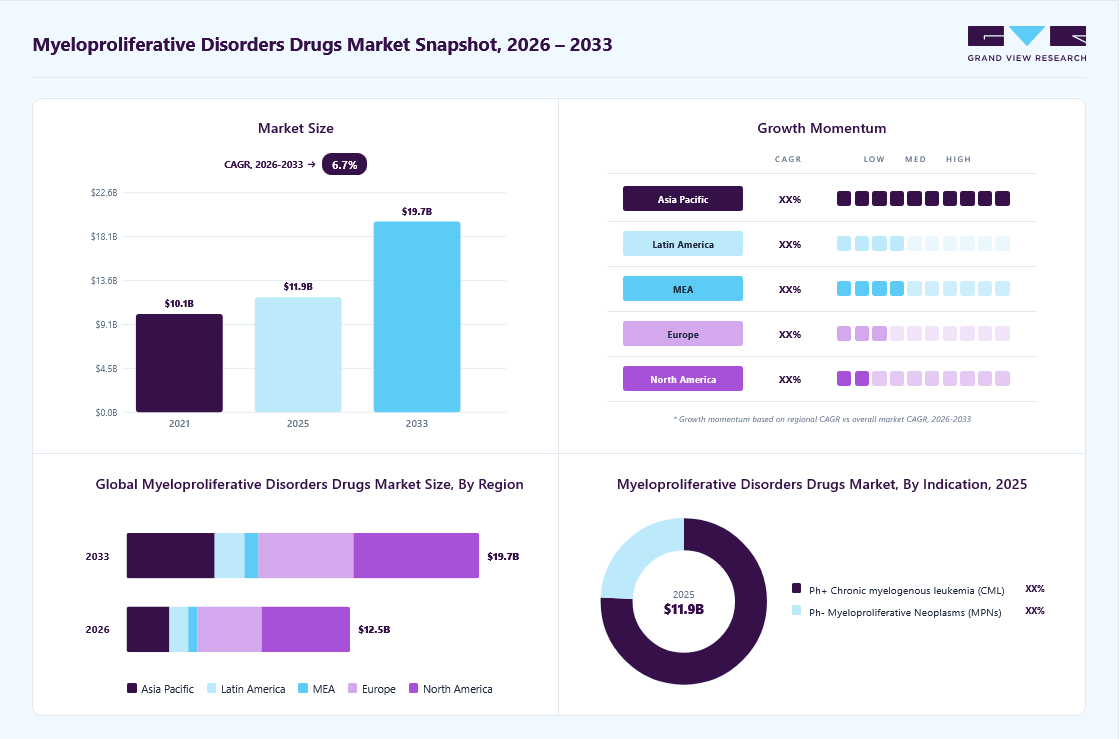
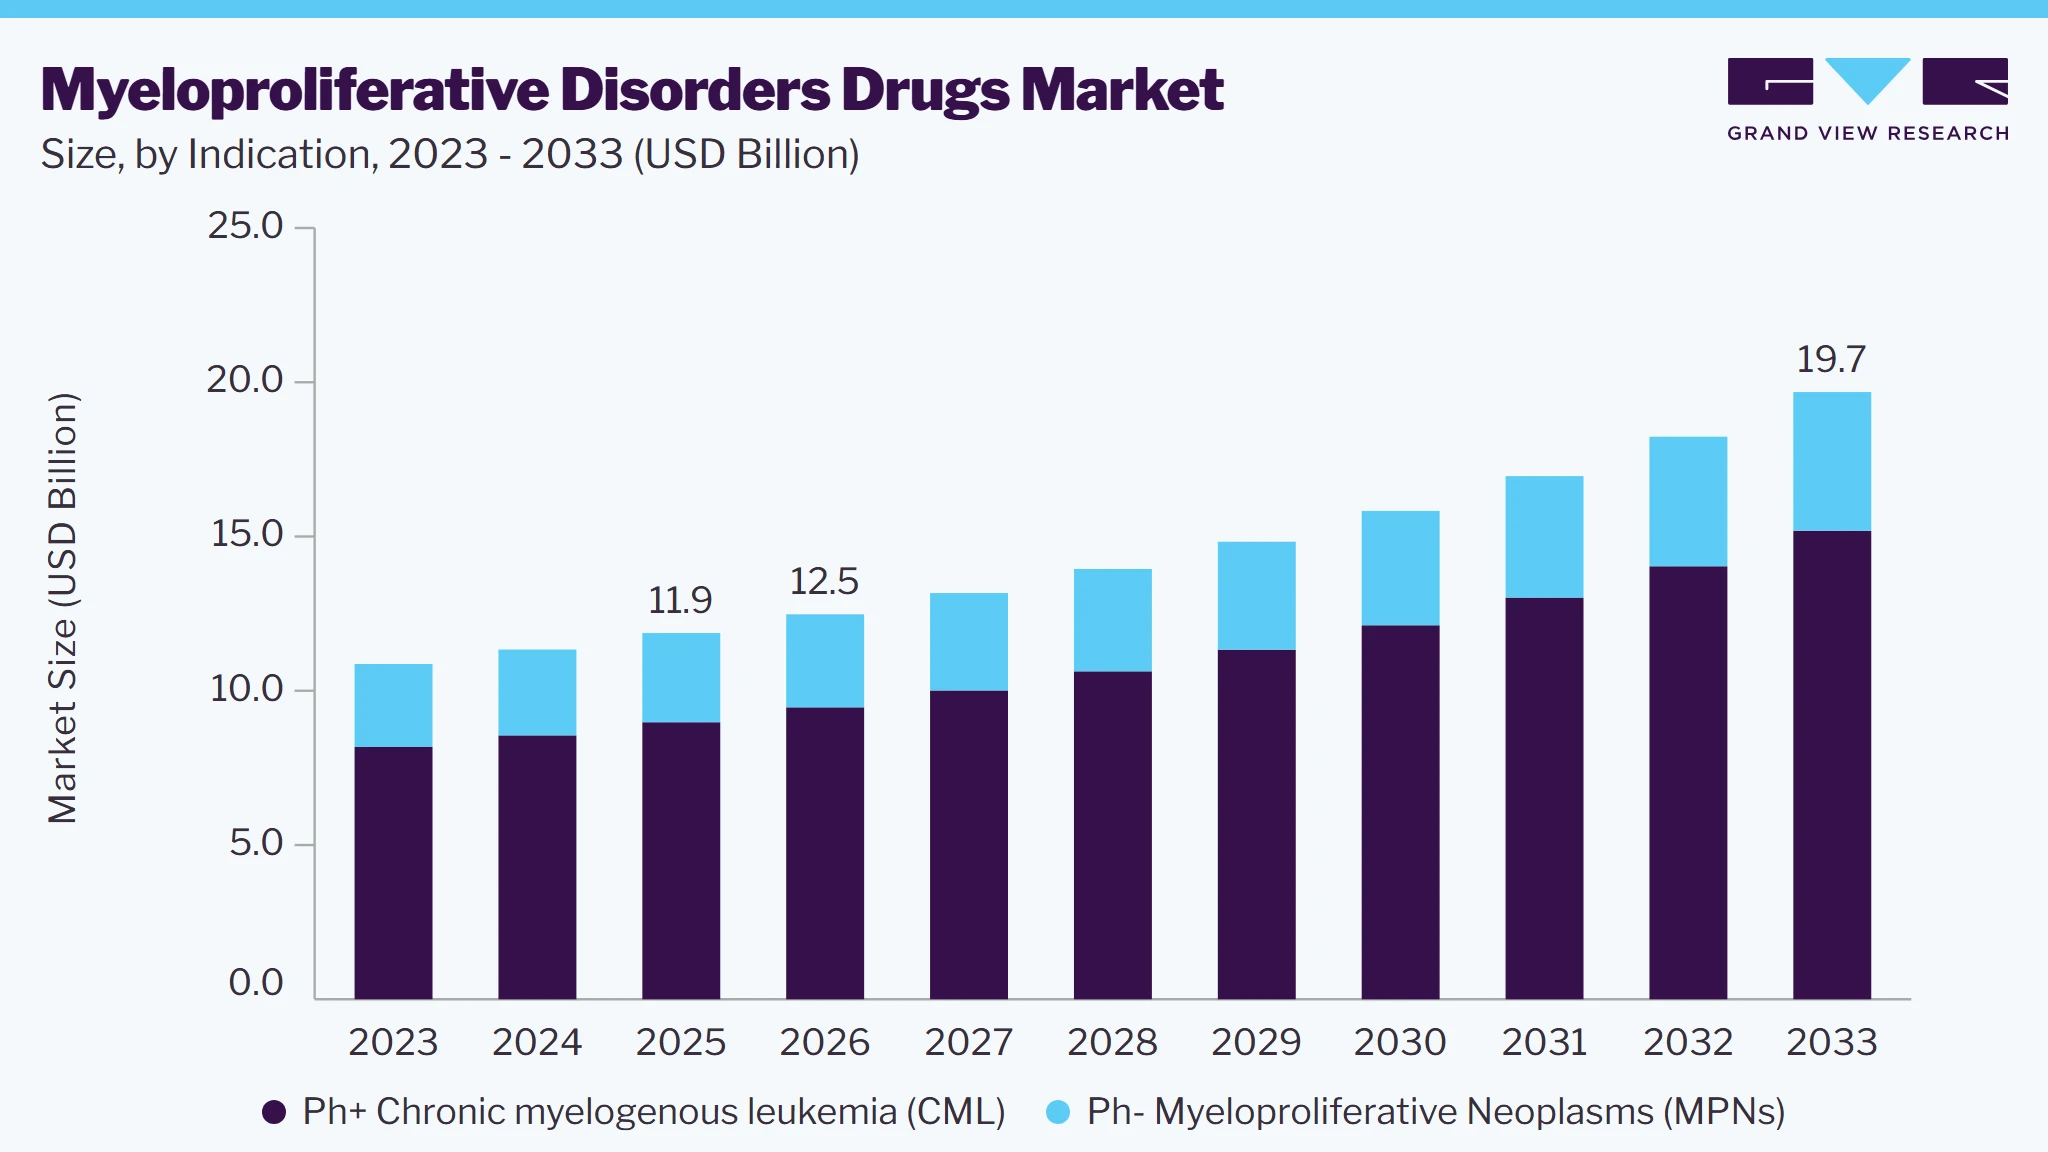
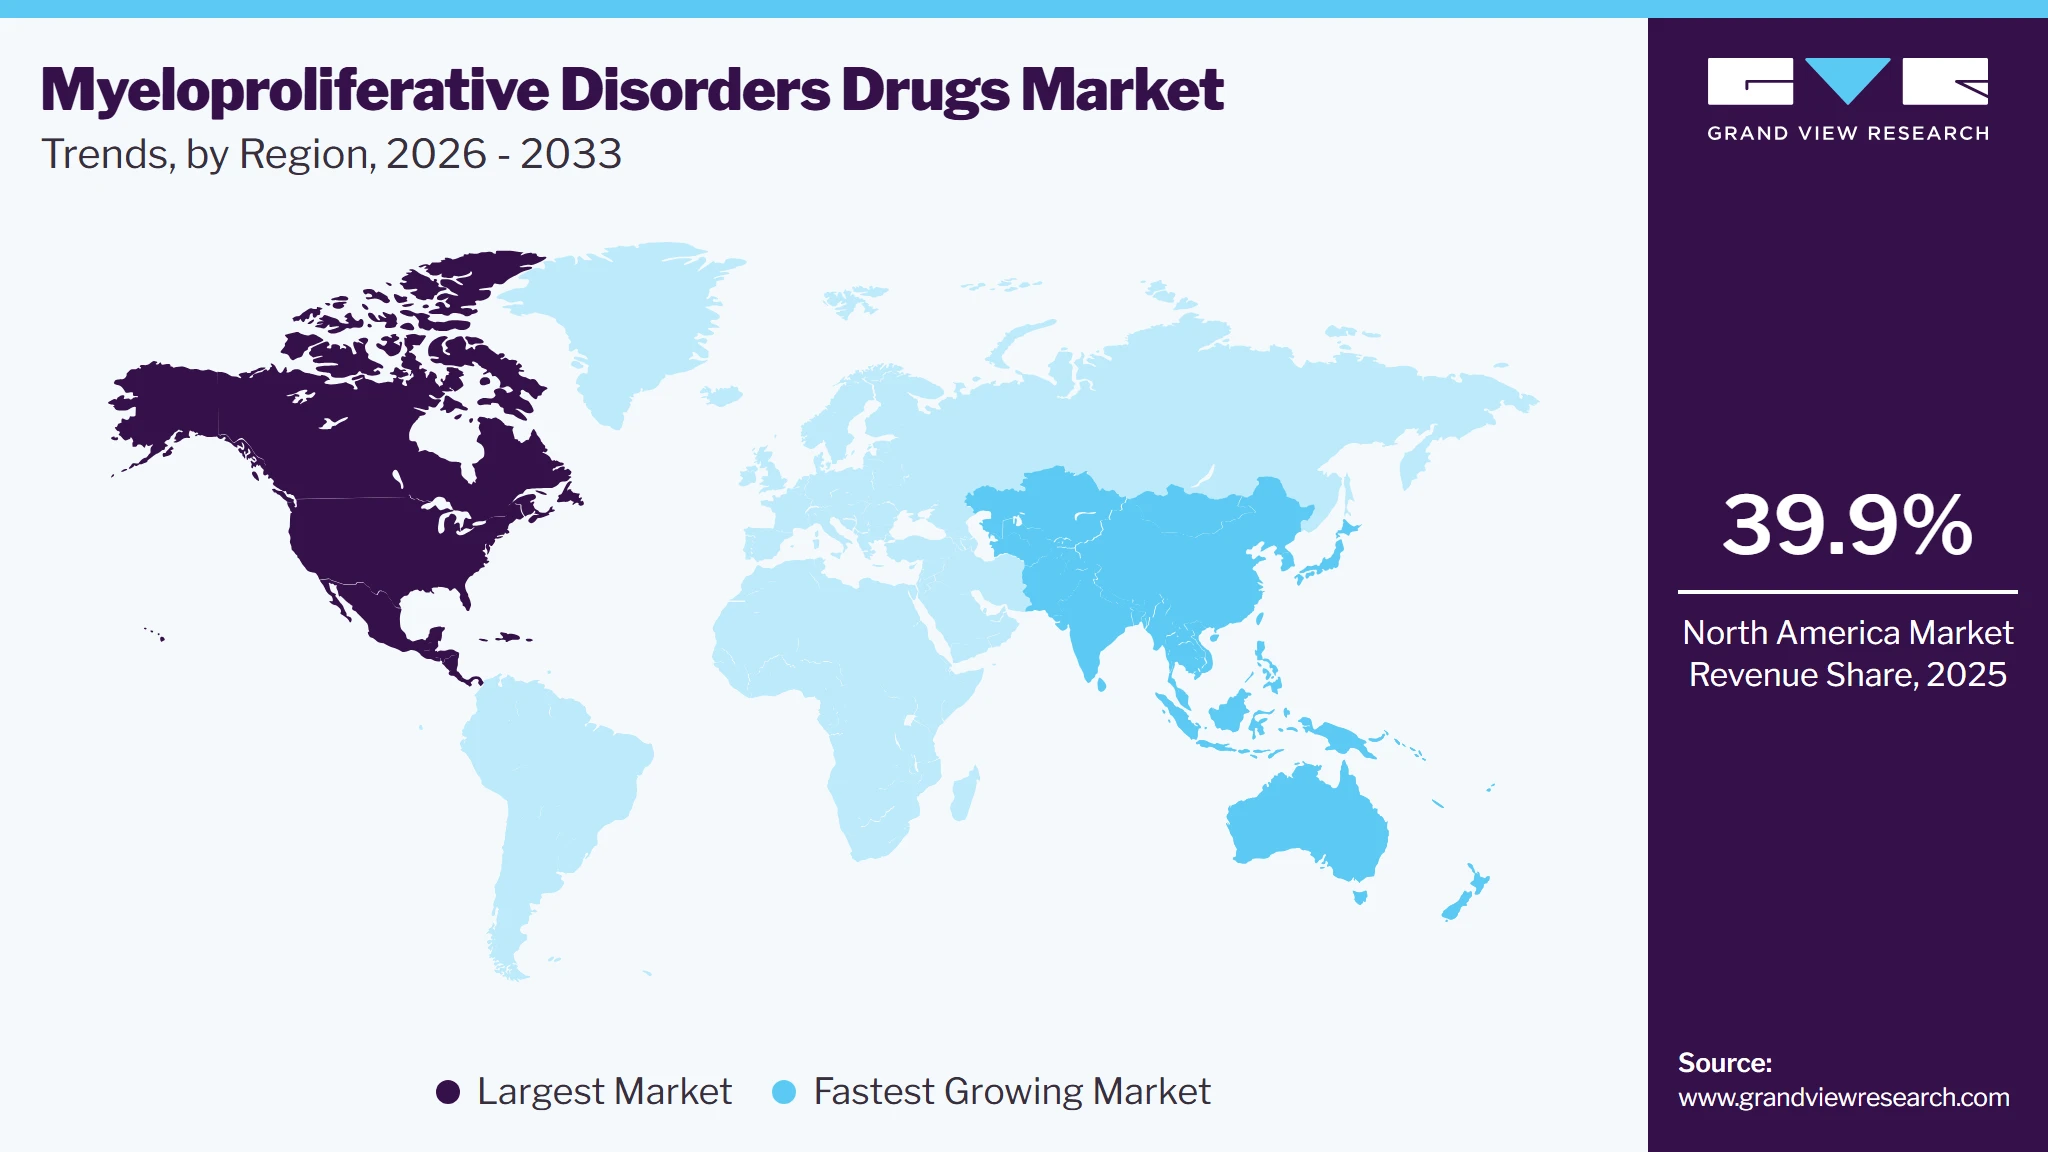
The global myeloproliferative disorders drugs market size was valued at USD 11.9 billion in 2025 and is projected to reach USD 12.5 billion in 2026 to USD 19.7 billion by 2033, at a CAGR of 6.7% from 2026 to 2033. North America myeloproliferative disorders drugs market held the largest share of 39.9% of the global market in 2025.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By indication: Ph+ Chronic Myelogenous Leukemia (CML) segment held the largest market share of 75.6% in 2025.
- By treatment type: Targeted therapy segment held the largest market share of 44.4% in 2025.
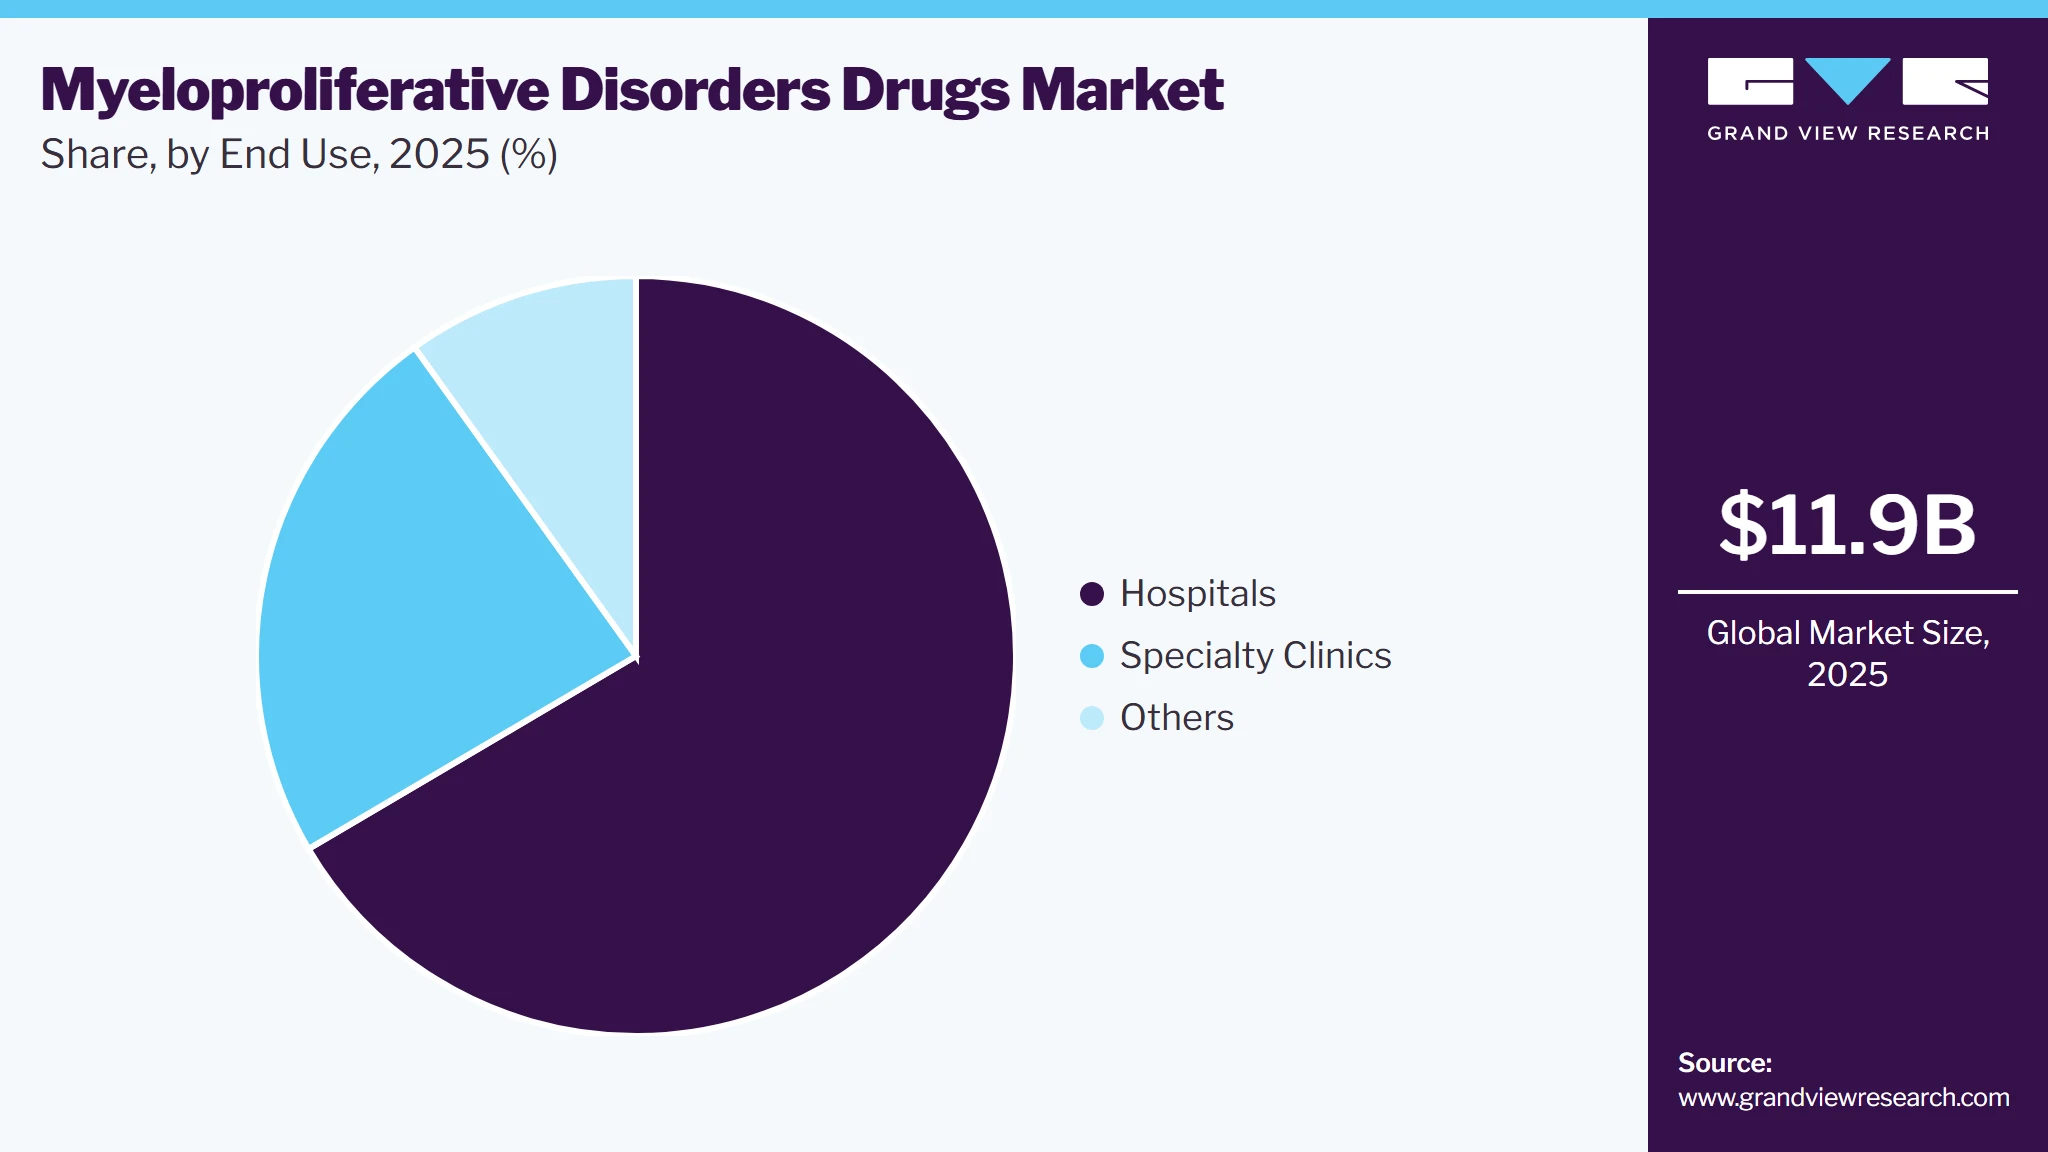
- By end use: Hospitals segment held the largest market share of 66.5% in 2025.
Regional Highlights
- Largest regional market: North America (39.9% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 11.9 Billion
- Estimated market size in 2026: USD 12.5 Billion
- Projected market size by 2033: USD 19.7 Billion
- CAGR (2026-2033): 6.7%
Prism AI by Grand View Research Free to tryAsk a question about the myeloproliferative disorders drugs marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →These conditions include polycythemia vera, essential thrombocythemia, myelofibrosis, and chronic myeloid leukemia. Treatment requirements differ based on disease indication, patient symptoms, genetic changes, and the risk of complications. Drug therapy focuses on controlling blood cell production, reducing the risk of blood clots, managing spleen enlargement, and relieving symptoms such as fatigue and itching. Treatment options include Janus kinase (JAK) inhibitors, tyrosine kinase inhibitors, interferons, cytoreductive agents, and supportive medicines. The choice of therapy depends on disease progression, treatment response, patient age, and tolerance to adverse effects. Long-term disease management remains important because several myeloproliferative disorders require regular blood tests, clinical assessment, and treatment type adjustments based on patient response and changes in disease status.
 To learn more about this report, Download Free Sample Report
Demand for myeloproliferative disorders drugs is supported by the need for long-term disease management and the availability of therapies that address specific disease mechanisms. Tyrosine kinase inhibitors remain central to chronic myeloid leukemia treatment type, while JAK inhibitors are used for selected patients with myelofibrosis and polycythemia vera. Interferon-based therapies and cytoreductive medicines provide additional treatment options for eligible patients. Treatment selection depends on disease subindication, genetic profile, symptoms, age, risk of thrombosis, and response to previous therapies. Advances in molecular testing also support disease classification and treatment selection by helping physicians identify relevant genetic abnormalities. However, treatment requirements vary across patient groups, and not all individuals with these disorders require the same drug regimen. Clinical guidelines, physician assessment, and regular monitoring remain important in determining treatment type duration, managing adverse effects, and evaluating the need for changes in therapy.
The market is shaped by pharmaceutical research, regulatory approvals, clinical treatment guidelines, and access to specialist healthcare services. Drug developers are investigating therapies that target disease-related mutations, improve symptom control, and address resistance to existing treatment types. Clinical research also focuses on improving treatment type outcomes for patients with myelofibrosis and other disorders that can progress over time. However, adverse effects, incomplete treatment responses, and disease progression remain challenges in clinical management. Access to newer medicines also differs across countries because of variations in drug pricing, reimbursement policies, regulatory requirements, and healthcare infrastructure. Generic competition in established drug classes affects treatment type costs and prescribing choices, while newer targeted therapies expand options for specific patient groups. Continued research into disease biology and treatment type combinations supports product development, although adoption depends on clinical evidence, safety findings, regulatory authorization, and the ability of healthcare systems to provide ongoing treatment type and monitoring.
Market Dynamics
Targeted therapies support growth in the myeloproliferative disorders drugs market by addressing specific mechanisms involved in abnormal blood cell production and disease progression. Tyrosine kinase inhibitors are used to treat chronic myeloid leukemia, while Janus kinase (JAK) inhibitors help manage symptoms and spleen enlargement in selected patients with myelofibrosis and polycythemia vera. Molecular testing helps physicians identify genetic changes and select suitable therapies based on disease indication, clinical risk, and previous treatment response. Patients who do not respond adequately to initial treatment require alternative drug classes or treatment combinations, supporting demand for additional therapeutic options. Long-term disease management also requires regular monitoring and continued treatment to control symptoms and disease progression.
Adverse effects and treatment resistance restrict the use of medicines in the myeloproliferative disorders drugs market. Patients receiving long-term therapy require regular monitoring to assess blood counts, organ function, treatment type response, and safety concerns. Tyrosine kinase inhibitors and JAK inhibitors can cause adverse effects that require dose adjustments, treatment type interruptions, or changes in therapy. These issues affect treatment type continuity and increase the need for clinical supervision. In chronic myeloid leukemia, resistance to tyrosine kinase inhibitors can require mutation testing and a change in treatment type. In myelofibrosis and other myeloproliferative disorders, disease progression and persistent symptoms can limit treatment type benefits. Treatment selection also depends on patient age, existing health conditions, disease risk, and tolerance to medicines. These factors complicate prescribing decisions and can increase the overall cost of care. Access to specialist hematology services and regular diagnostic testing also differs across healthcare systems, creating barriers to sustained treatment type. Together, these clinical and access-related challenges affect treatment type outcomes and limit the use of certain medicines across patient groups.
The development of medicines with different mechanisms of action creates opportunities in the myeloproliferative disorders drugs market. Some patients experience treatment type resistance, adverse effects, or inadequate responses to existing therapies, supporting research into medicines that target specific proteins and genetic changes involved in abnormal blood cell production. Chronic myeloid leukemia remains an important area for drug development, particularly for patients who require alternatives to established tyrosine kinase inhibitors. New treatment type options can help physicians select therapies based on disease stage, previous treatment type history, and patient tolerance. Regulatory approvals for additional treatment type lines can expand the number of eligible patients and provide more choices for disease management. Wider access to targeted medicines also supports demand for drug therapy, depending on reimbursement policies, clinical evidence, and healthcare availability.
Market Concentration & Characteristics
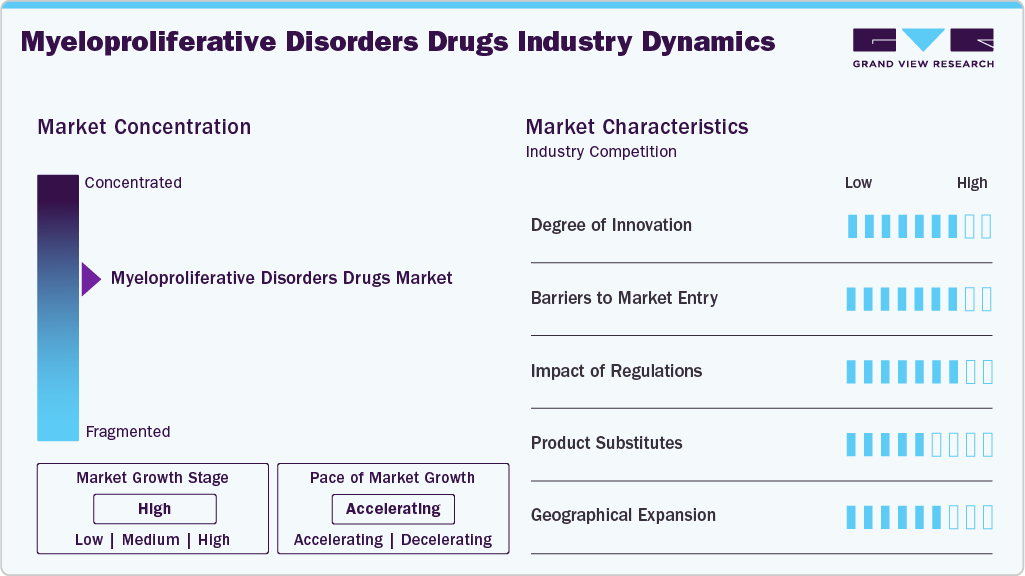
The degree of innovation in the myeloproliferative disorders drugs market is high because research focuses on disease-related mutations, targeted treatment type, and improved disease management. Pharmaceutical companies develop medicines that act on specific proteins involved in abnormal blood cell production. Tyrosine kinase inhibitors have changed chronic myeloid leukemia treatment type, while JAK inhibitors provide options for selected patients with myelofibrosis and polycythemia vera. Research also addresses treatment type resistance, persistent symptoms, and disease progression. Clinical studies evaluate new drug combinations, alternative treatment type lines, and medicines for patients who do not respond adequately to existing therapies. Molecular testing supports treatment selection by identifying relevant genetic changes. However, innovation requires clinical trials, safety assessments, and regulatory approval before new medicines become available. The need for long-term treatment type and improved disease control continues to support pharmaceutical research across different myeloproliferative disorders.
Barriers to market entry in the myeloproliferative disorders drugs market are high because pharmaceutical developers must demonstrate the safety and efficacy of new medicines through clinical trials. Development programs require investment in research, manufacturing, regulatory submissions, and post-approval safety monitoring. Since these disorders often require long-term treatment type, clinical studies must assess treatment type response, adverse effects, and disease progression. Regulatory authorities also require evidence supporting the proposed indication and patient population. Established companies benefit from approved products, clinical expertise, manufacturing capabilities, and relationships with hematologists and healthcare institutions. New entrants must also compete with existing medicines that have established roles in clinical treatment guidelines. In addition, developing therapies for relatively specific patient groups can create challenges in patient recruitment and clinical evaluation. These requirements increase development costs and extend the time needed to introduce new products.
 To learn more about this report, Download Free Sample Report
The impact of regulations on the myeloproliferative disorders drugs market is high because medicines require regulatory approval before they can be marketed for specific indications. Authorities such as the U.S. Food and Drug Administration and the European Medicines Agency evaluate clinical evidence, product quality, and safety data. Pharmaceutical companies must demonstrate that a medicine provides an acceptable benefit-risk profile for the intended patient population. Regulatory requirements also cover manufacturing quality, prescribing information, and monitoring of adverse effects after approval. Additional clinical evidence may be required when companies apply for new indications or changes in treatment type use. These requirements influence product development timelines, launch planning, and access to medicines. Differences in national approval procedures can affect the timing of product availability across countries. Regulatory decisions therefore influence competition, treatment type options, and the ability of pharmaceutical companies to expand product use.
The availability of product substitutes in the myeloproliferative disorders drugs market is moderate because several drug classes can be used to manage specific conditions, although their clinical roles differ. Treatment options include tyrosine kinase inhibitors, JAK inhibitors, interferons, and cytoreductive agents. In chronic myeloid leukemia, alternative tyrosine kinase inhibitors are available for patients who experience resistance or intolerance to a particular medicine. In polycythemia vera and essential thrombocythemia, treatment selection depends on thrombotic risk, blood cell counts, symptoms, and patient characteristics. Patients with myelofibrosis may receive JAK inhibitors or other therapies based on disease status and treatment type eligibility. However, these medicines are not interchangeable across all disorders. Genetic findings, previous treatment type response, adverse effects, and clinical guidelines determine whether an alternative is suitable. These factors limit direct substitution between drug classes.
Geographical expansion in the myeloproliferative disorders drugs market is moderate to high because pharmaceutical companies can extend product availability through regulatory approvals, distribution agreements, and access programs. Expansion depends on the prevalence of diagnosed disease, availability of hematology specialists, access to molecular testing, and healthcare funding. Countries with established diagnostic services and reimbursement systems generally provide greater access to targeted medicines. In other regions, treatment type availability may be limited by medicine costs, regulatory requirements, and gaps in specialist care. Pharmaceutical companies can expand their presence by obtaining approval for existing products in additional countries and introducing new indications where clinical evidence supports their use. However, reimbursement decisions and local treatment type guidelines influence prescribing. Differences in healthcare infrastructure also affect patient access to long-term drug therapy and monitoring. These factors determine the extent to which companies can expand the use of their medicines across geographic regions.
Analyst Perspective
The myeloproliferative disorders drugs market is shaped by demand for long-term disease management, advances in targeted therapies, and ongoing research into new treatment options. Tyrosine kinase inhibitors and JAK inhibitors remain important for selected patient groups. Market growth depends on diagnosis rates, treatment access, drug pricing, and clinical outcomes. Pharmaceutical companies are focusing on therapies that address treatment resistance and disease progression, while regulatory approvals and clinical evidence will continue to guide product adoption and competition.
Indication Insights
The Ph+ Chronic Myelogenous Leukemia (CML) segment dominated the market with the largest market share of 75.6% in 2025, supported by the established use of tyrosine kinase inhibitors, routine BCR::ABL1 molecular testing, and the need for long-term disease control. Other contributing factors include the availability of multiple treatment type options, regular molecular monitoring, treatment type switching among patients with resistance or intolerance, and continued research into targeted medicines. The chronic nature of the disease also supports sustained demand for drug therapy and follow-up care. Treatment selection depends on genetic findings, patient risk, previous therapy, and treatment type response. The availability of different tyrosine kinase inhibitors also allows physicians to modify treatment type when patients experience inadequate responses or adverse effects, supporting continued demand for medicines used to manage Ph-positive chronic myeloid leukemia.
The Ph− Myeloproliferative Neoplasms (MPNs) segment is growing significantly with a CAGR of 5.9% during the forecast period, supported by treatment type needs across polycythemia vera, essential thrombocythemia, and myelofibrosis. Growth is driven by research into disease-specific therapies, demand for better symptom control, the need to manage thrombosis risk, and treatment type options for patients who do not respond adequately to existing medicines. Greater understanding of disease-related mutations also supports the development of targeted treatment types. The need to manage complications, control blood cell counts, and address disease progression further supports demand for treatment type options. In addition, research into new therapeutic targets and medicines for patients with inadequate treatment type responses supports product development across Ph-negative disorders. These factors support the segment's growth during the forecast period.
Treatment Type Insights
The targeted therapy segment dominated the myeloproliferative disorders drugs market with the largest market share of 44.4% in 2025, supported by its ability to act on specific molecular targets involved in disease progression. The established use of tyrosine kinase inhibitors in chronic myeloid leukemia and the availability of Janus kinase inhibitors for selected patients with myelofibrosis and polycythemia vera support segment demand. Other contributing factors include long-term drug therapy requirements, the availability of multiple targeted medicines, treatment type switching due to resistance or intolerance, and research into new therapeutic targets. Advances in molecular testing also help physicians select treatment types based on genetic findings and previous treatment type response. In addition, targeted therapies provide treatment type options for patients who require alternatives to established medicines, supporting continued research and product development across different myeloproliferative disorders.
The targeted therapy segment is growing significantly with a CAGR of 6.9% during the forecast period, driven by the growing use of medicines that act on specific molecular targets involved in disease progression. Tyrosine kinase inhibitors remain important in chronic myeloid leukemia treatment, while Janus kinase (JAK) inhibitors are used to manage selected cases of myelofibrosis and polycythemia vera. Increasing awareness of disease-related genetic mutations and wider use of molecular testing support treatment selection based on patient profiles. Demand is also supported by the need for alternative therapies among patients who develop resistance or experience adverse effects with existing medicines. Pharmaceutical companies continue to investigate targeted treatments that improve disease control, manage symptoms, and address unmet treatment needs. In addition, long-term therapy requirements and regular monitoring support continued medicine use. Clinical research, new product approvals, and expanded treatment indications are expected to support segment growth during the forecast period.
End Use Insights
The hospitals segment dominated the myeloproliferative disorders drugs market with the largest market share of 66.5% in 2025, supported by the availability of hematology specialists, diagnostic laboratories, and facilities for long-term disease monitoring. Hospitals manage patients requiring treatment type initiation, dose adjustments, and evaluation of adverse effects. Other contributing factors include access to molecular testing, management of disease-related complications, coordination of multidisciplinary care, and the availability of specialized treatment type services. Hospitals also treat patients with advanced disease or inadequate responses to previous medicines, supporting demand for targeted therapies and supportive drugs. In addition, hospital-based physicians monitor blood counts and treatment type response to guide therapy selection. The need for regular clinical assessment and access to diagnostic services supports the role of hospitals in managing chronic myeloproliferative disorders.
 To learn more about this report, Download Free Sample Report
The specialty clinics segment growing significantly with a CAGR of 5.8% during the forecast period, supported by the growing role of hematology-focused services in long-term disease management. These clinics provide follow-up consultations, blood count monitoring, treatment type response assessment, and management of adverse effects for patients receiving ongoing therapy. Growth is also supported by greater use of molecular testing, increased focus on outpatient care, and the need for regular specialist reviews when treatment type changes are required. Specialist clinics can support continuity of care for patients who do not require hospital admission, helping reduce the need for hospital-based consultations. The availability of targeted medicines also increases the need for physicians experienced in selecting and monitoring disease-specific treatment types.
Regional Insights
North America dominated the myeloproliferative disorders drugs market with a market share of 39.9% in 2025, supported by access to targeted therapies and specialized hematology services. The region benefits from established diagnostic facilities that support early disease identification and treatment selection. The use of molecular testing helps physicians identify genetic abnormalities and monitor responses to tyrosine kinase inhibitors. Research activity and clinical trials support the development of medicines for chronic myeloid leukemia, myelofibrosis, and polycythemia vera. Access to specialist care and regular disease monitoring also supports long-term drug therapy demand.
 To learn more about this report, Download Free Sample Report
U.S. Myeloproliferative Disorders Drugs Market Trends
The United States drives regional demand through the availability of approved targeted medicines and established hematology care. Molecular testing supports treatment selection for patients with chronic myeloid leukemia and other myeloproliferative disorders. The presence of pharmaceutical developers and clinical research centers supports the development of new treatment type options. Access to JAK inhibitors and tyrosine kinase inhibitors supports disease management across eligible patient groups. Specialist consultations and routine blood testing also support continued use of prescription therapies.
Europe Myeloproliferative Disorders Drugs Market Trends
Europe represents a key regional market due to access to established treatment types and specialist hematology services. The use of molecular diagnostics supports disease classification and the selection of targeted medicines. Clinical research across chronic myeloid leukemia, myelofibrosis, and polycythemia vera contributes to treatment type development. National reimbursement systems and clinical guidelines influence access to approved medicines across countries. Long-term disease monitoring and the need to manage treatment type resistance also support demand for different drug classes.
The United Kingdom market is supported by specialist hematology services and access to targeted medicines for blood disorders. Molecular testing helps identify BCR::ABL1 abnormalities and guides treatment selection for chronic myeloid leukemia. Clinical expertise supports the management of patients with myelofibrosis and polycythemia vera. Research into treatment type resistance supports the evaluation of alternative medicines. Access to long-term monitoring helps physicians assess treatment type response and manage adverse effects. Demand also depends on medicine availability and access to specialist consultations.
Germany's market is supported by established hematology services, diagnostic laboratories, and access to prescription medicines. Molecular diagnostics help physicians identify disease-related mutations and select appropriate treatment type options. The use of tyrosine kinase inhibitors supports treatment type demand among patients with chronic myeloid leukemia. JAK inhibitors provide additional options for eligible patients with myelofibrosis and polycythemia vera. Clinical research supports the evaluation of new medicines and treatment type combinations. Regular blood testing and follow-up consultations contribute to long-term disease management.
France's market is supported by specialist care for chronic blood disorders and access to targeted drug therapies. Diagnostic testing helps physicians classify myeloproliferative disorders and determine suitable treatment type options. The use of tyrosine kinase inhibitors supports chronic myeloid leukemia treatment type. JAK inhibitors and other medicines address symptoms and disease complications in selected patients with Philadelphia chromosome-negative disorders. Clinical research supports the assessment of new treatment types and changes in prescribing practices. Continued monitoring of blood counts and treatment type response also supports demand for long-term drug therapy.
Asia-Pacific Myeloproliferative Disorders Drugs Market Trends
Asia Pacific is projected to register the fastest CAGR of 10.8% in the myeloproliferative disorders drugs market, supported by improving access to diagnostic services and specialist care. Greater use of molecular testing helps identify patients who require disease-specific treatment type. Expanding access to targeted medicines supports treatment type demand across chronic myeloid leukemia and Philadelphia chromosome-negative disorders. Pharmaceutical research and clinical trial activity contribute to the development of additional treatment type options. Improvements in hematology services support disease monitoring and treatment type management. Differences in healthcare access and medicine affordability across countries will continue to influence regional growth.
Japan's market is supported by access to targeted medicines, specialist hematology services, and molecular diagnostic testing. Genetic testing helps physicians select appropriate therapies for patients with chronic myeloid leukemia. The use of JAK inhibitors supports treatment type for eligible patients with myelofibrosis and polycythemia vera. An aging population contributes to the need for continued diagnosis and management of chronic blood disorders. Clinical research supports the assessment of new treatment type options and changes in treatment type practice. Regular monitoring also supports long-term medicine use and the management of treatment-related adverse effects.
China's market is supported by expanding diagnostic capabilities and increasing access to specialist hematology services. Greater use of molecular testing supports the identification and classification of myeloproliferative disorders. Access to targeted medicines supports treatment type for chronic myeloid leukemia and selected Philadelphia chromosome-negative disorders. Domestic pharmaceutical research contributes to the development of therapies for patients with different treatment type needs. Wider availability of diagnostic services supports treatment selection and follow-up care. Medicine affordability, regional differences in specialist access, and product availability continue to influence market development.
Latin America Myeloproliferative Disorders Drugs Market Trends
The Latin American market is supported by demand for medicines used to manage chronic blood disorders and their complications. Access to hematology specialists helps patients receive appropriate diagnosis and treatment type. Molecular testing supports the selection of targeted therapies for chronic myeloid leukemia. Availability of JAK inhibitors and other drug classes supports treatment type options for selected patients with myelofibrosis and polycythemia vera. Improvements in diagnostic capacity support the identification of patients who require long-term therapy. However, differences in medicine affordability, reimbursement, and specialist access affect treatment type availability across countries.
Brazil's market is supported by demand for long-term drug therapy of chronic myeloid leukemia and other myeloproliferative disorders. Hematology services and diagnostic laboratories support disease identification and treatment type monitoring. Molecular testing helps physicians evaluate treatment type response and identify resistance in chronic myeloid leukemia. Access to targeted medicines and alternative drug classes supports care for eligible patients. Research activity and improvements in diagnostic services support the management of different disease indications. Differences in access to specialist care and the affordability of newer medicines influence treatment type use across the country.
Middle East & Africa Myeloproliferative Disorders Drugs Market Trends
The Middle East and Africa market is supported by demand for medicines used to manage chronic blood disorders. Access to hematology specialists and diagnostic laboratories influences the identification of patients requiring treatment type. Molecular testing supports treatment selection for chronic myeloid leukemia where these services are available. Targeted therapies provide options for patients with eligible disease indications and clinical profiles. Improvements in diagnostic access and specialist services support long-term disease management in selected countries. However, differences in healthcare infrastructure, medicine availability, and affordability affect regional treatment type access.
Saudi Arabia's market is supported by access to specialist hospitals, hematology services, and diagnostic testing. Molecular diagnostics help physicians classify myeloproliferative disorders and guide treatment selection. The availability of targeted medicines supports the management of chronic myeloid leukemia and selected Philadelphia chromosome-negative disorders. Specialist care supports regular monitoring of blood counts, treatment type response, and adverse effects. Clinical expertise also helps physicians adjust therapies for patients who experience resistance or intolerance. Continued access to approved medicines and specialized diagnostic services will influence demand for myeloproliferative disorder treatment types across the country.
Key Myeloproliferative Disorders Drugs Company Insights
The myeloproliferative disorders drugs market is characterized by competition among pharmaceutical companies offering targeted therapies and other medicines for chronic blood disorders. Novartis AG, Bristol Myers Squibb Company, and Pfizer Inc. participate in the chronic myeloid leukemia segment through tyrosine kinase inhibitor therapies. Incyte holds a key position in the treatment type of myelofibrosis and polycythemia vera through its JAK inhibitor portfolio, while Takeda Pharmaceutical Company Limited focuses on treatment types for polycythemia vera. Teva Pharmaceutical Industries Ltd., AbbVie Inc., Eli Lilly and Company, GSK plc, and GL Pharma contribute through selected hematology products, research activities, or related drug portfolios. Competitive positioning varies by disease indication, product approvals, and treatment type use.
Key Myeloproliferative Disorders Drugs Companies
The following key companies have been profiled for this study on the myeloproliferative disorders drugs market.
-
Novartis AG
-
Bristol-Myers Squibb Company
-
Pfizer Inc.
-
Takeda Pharmaceutical Company Limited.
-
Incyte.
-
Teva Pharmaceutical Industries Ltd.
-
AbbVie Inc.
-
Eli Lilly and Company.
-
GSK plc.
-
GL Pharma
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature players
- AbbVie Inc.
- Player 2
- Player 3
- Player 4
- Player 5
- Mature companies focus on strengthening their neurology portfolios through approved botulinum toxin therapies, muscle relaxants, and lifecycle management of existing products.
- Their strategies include expanding product indications, increasing clinical evidence, improving manufacturing capacity, obtaining regulatory approvals in new countries, and strengthening partnerships with hospitals and rehabilitation centers.
- They also invest in physician education, medical affairs, and geographic expansion to maintain their presence in developed and emerging markets.
- These companies benefit from established brands, broad global distribution networks, large manufacturing capabilities, and long experience in neurology.
- Their extensive regulatory expertise, strong relationships with healthcare providers, and diversified product portfolios support continued market presence.
- Ongoing clinical research and broad commercial infrastructure help them maintain steady demand across multiple regions.
- Mature companies face pricing pressure from generic manufacturers and increasing competition in established treatment categories.
- Maintaining global manufacturing operations, regulatory compliance, and post-marketing surveillance increases operating costs.
- Product lifecycle maturity may limit rapid revenue expansion, while dependence on a limited number of leading products may increase competitive pressure as alternative therapies become available.
Emerging players
- Eisai Co., Ltd.
- Player 2
- Player 3
- Player 4
- Player 5
- Emerging players focus on expanding their presence through generic muscle relaxants, regional product launches, manufacturing expansion, and portfolio diversification.
- They emphasize cost-efficient production, licensing agreements, product registrations in additional countries, and strategic partnerships to improve commercial reach.
- Many companies also strengthen their neurology portfolios through incremental product development and broader distribution channels.
- These companies compete through cost-effective manufacturing, flexible supply chains, and growing presence in regional pharmaceutical markets.
- Their ability to supply affordable treatment options and respond to local market demand supports business expansion.
- Strong expertise in generic pharmaceuticals also allows them to compete across hospital and retail pharmacy channels.
- Emerging companies have lower brand recognition in specialized spasticity therapies compared with established botulinum toxin manufacturers.
- Their product portfolios are largely concentrated in generic medicines, which creates pricing competition.
- Limited presence in advanced biologic therapies, smaller international commercial networks, and lower investment in large-scale neurological clinical research may restrict expansion in highly specialized treatment segments.
Recent Developments
-
In May 2026, Incyte announced that the U.S. Food and Drug Administration had approved an extended-release formulation of ruxolitinib for adults with intermediate- or high-risk myelofibrosis and adults with polycythemia vera who had an inadequate response to or were intolerant of hydroxyurea.
-
In December 2025, Incyte announced that the FDA had granted Breakthrough Therapy designation to a mutant calreticulin-targeted antibody for selected patients with essential thrombocythemia, supporting further development of specialist-led treatment type options.=
-
In December 2025, Novartis AG reported that the European Commission had approved an expanded indication for asciminib for adults with Philadelphia chromosome-positive chronic myeloid leukemia in the chronic phase across all lines of treatment type. The approval expanded the medicine's use across treatment type lines in the European Union and provided an additional option for eligible patients.
Myeloproliferative Disorders Drugs Market Report Scope
Report Attribute
Details
Market size in 2025
USD 11.9 Billion
Estimated market size in 2026
USD 12.5 Billion
Projected market size by 2033
USD 19.7 Billion
Growth rate
CAGR of 6.7% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, trends
Segments covered
Indication, treatment type, end use and region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S., Canada, Mexico, UK, Germany, France, Italy, Spain, Denmark, Sweden, Norway, China, Japan, India, Australia, South Korea, Thailand, Brazil, Argentina, South Africa, Saudi Arabia, UAE, Kuwait
Key company profiled
Novartis AG; Bristol-Myers Squibb Company; Pfizer Inc.; Takeda Pharmaceutical Company Limited; Incyte; Teva Pharmaceutical Industries Ltd.; AbbVie Inc.; Eli Lilly and Company; GSK plc; GL Pharma
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Myeloproliferative Disorders Drugs Market Report Segmentation
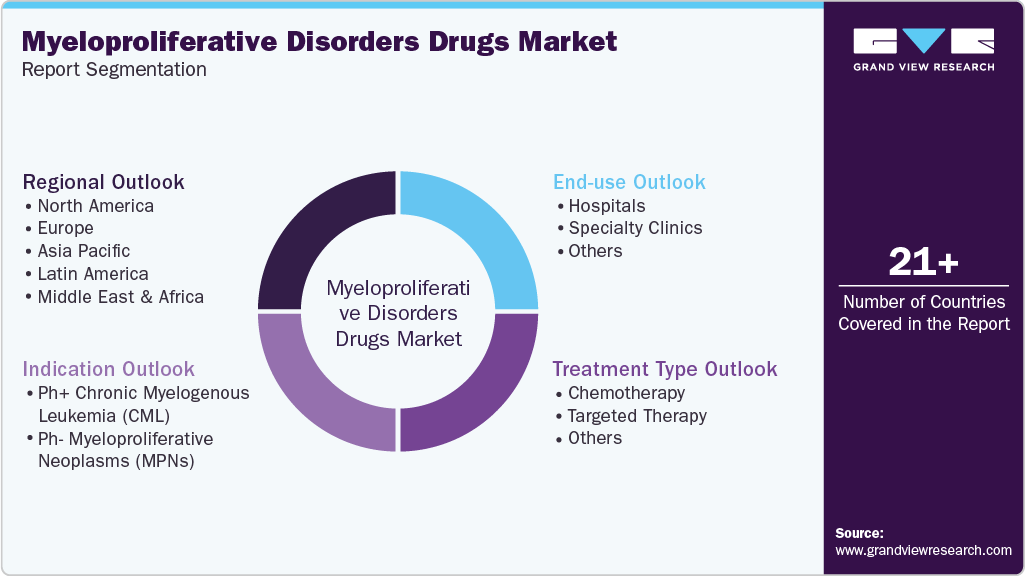
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global myeloproliferative disorders drugs market report based on indication, treatment type, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Indication Outlook (Revenue, USD Million, 2021 - 2033)
-
Ph+ Chronic Myelogenous Leukemia (CML)
-
Ph- Myeloproliferative Neoplasms (MPNs)
-
Myelofibrosis (MF)
-
Polycythemia Vera (PV)
-
Essential Thrombocythemia (ET)
-
-
-
Treatment Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Chemotherapy
-
Targeted Therapy
-
Others
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Specialty Clinics
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
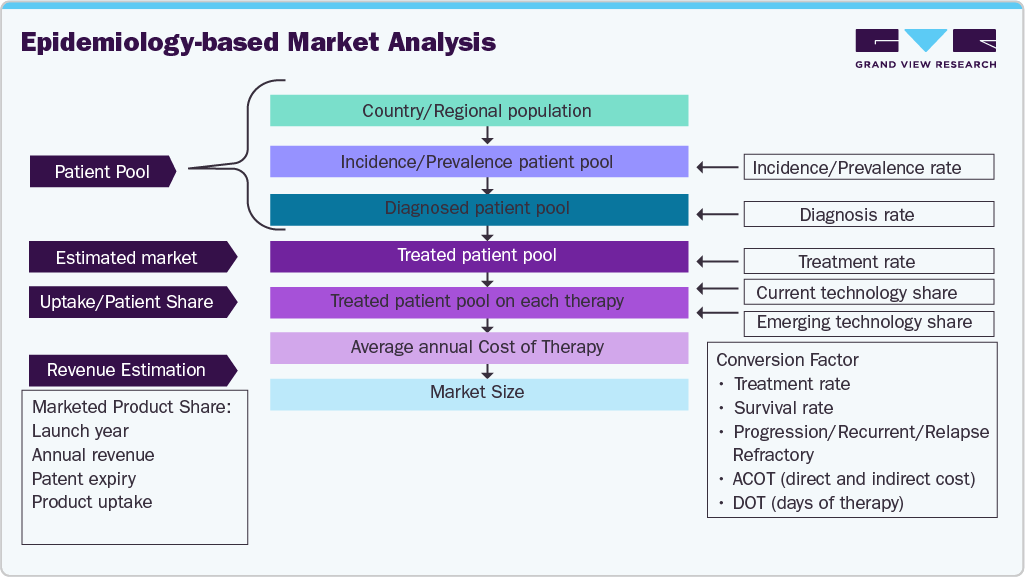
The myeloproliferative disorders drugs market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each myeloproliferative disorders drugs segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Indication
Revenue capture definition
Ph+ Chronic Myelogenous Leukemia (CML)
Includes medicines used to treat Philadelphia chromosome-positive chronic myeloid leukemia, characterized by the BCR::ABL1 fusion gene. Covered treatment types include tyrosine kinase inhibitors and other drugs used to control disease progression, manage treatment type resistance, and maintain disease control.
Ph− Myeloproliferative Neoplasms (MPNs)
Includes medicines used to treat Philadelphia chromosome-negative myeloproliferative neoplasms, including polycythemia vera, essential thrombocythemia, and myelofibrosis. Covered treatment types include JAK inhibitors, interferons, and cytoreductive agents used to control blood cell production, manage symptoms, and reduce disease-related complications.
Segment - Treatment Type
Revenue capture definition
Chemotherapy
Includes cytotoxic and cytoreductive medicines used to control abnormal blood cell production in patients with myeloproliferative disorders. Covered drugs include hydroxyurea and other chemotherapy agents used to reduce blood cell counts and manage disease-related complications.
Targeted Therapy
Includes medicines designed to act on specific molecular targets or signaling mechanisms involved in myeloproliferative disorders. Covered drugs include tyrosine kinase inhibitors used for chronic myeloid leukemia, JAK inhibitors used for selected Philadelphia chromosome-negative disorders, and other targeted medicines approved for these conditions.
Others
Includes interferons, immunomodulatory medicines, and other pharmacological treatment types used to manage myeloproliferative disorders that are not classified as chemotherapy or targeted therapy. Covered treatment types include interferon-based therapies and supportive medicines used to control blood cell production, manage symptoms, and reduce disease-related complications.
Segment - End-use
Revenue capture definition
Hospitals
Includes medicines dispensed or administered through hospital pharmacies and hospital-based treatment type services for inpatient and outpatient care. Covered uses include treatment type initiation, management of disease-related complications, dose adjustments, and ongoing care delivered through hospital facilities.
Specialty Clinics
Includes medicines dispensed or administered through independent hematology clinics and specialized outpatient centers operating separately from hospitals. Covered uses include specialist consultations, routine disease monitoring, treatment type adjustments, and ongoing drug therapy for patients managed through these facilities.
Others
Includes medicines dispensed through retail pharmacies, mail-order pharmacies, and other outpatient pharmacy channels outside hospital pharmacies and independent specialty clinics. Covered treatment types include oral prescription medicines and other drugs supplied for home use and continuing disease management.
Estimation Model
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Global Myeloproliferative Disorders Drugs Market Assessment
Conducted a detailed assessment of the myeloproliferative disorders drugs market across key countries, covering chronic myeloid leukemia, polycythemia vera, essential thrombocythemia, and myelofibrosis. The study evaluated disease prevalence, diagnosis rates, treated patient populations, treatment patterns, drug availability, pricing, and reimbursement conditions.
Helped the client identify key treatment segments, assess patient-based demand, and evaluate opportunities across targeted therapies and other drug classes. The analysis also supported market entry planning, geographic prioritization, and assessment of factors affecting access to myeloproliferative disorder treatments.
Myeloproliferative Disorders Drugs Pipeline and Competitive Benchmarking
Delivered a competitive assessment of pharmaceutical companies involved in the treatment of myeloproliferative disorders. The study examined approved drug portfolios, clinical development programs, product indications, regulatory approvals, clinical trial progress, partnerships, and product expansion activities across chronic myeloid leukemia, polycythemia vera, essential thrombocythemia, and myelofibrosis.
Enabled the client to assess competitor portfolios, identify potential product development opportunities, and evaluate changes in treatment options. The analysis supported competitive benchmarking, partnership assessment, and strategic planning across targeted therapies, JAK inhibitors, tyrosine kinase inhibitors, and other relevant drug classes.
Country-Level Treatment Access and Market Opportunity Assessment
Conducted a country-level assessment of treatment access and commercial opportunities across key markets, including the U.S., Germany, the U.K., Japan, and China. The study examined patient diagnosis, access to hematology specialists, availability of targeted medicines, treatment costs, reimbursement policies, regulatory requirements, and healthcare infrastructure.
Supported geographic prioritization by identifying differences in treatment access, medicine availability, and patient management across countries. The findings helped the client assess regional expansion opportunities, evaluate access barriers, and identify factors affecting the use of approved therapies and the introduction of new treatments.
Frequently Asked Questions About This Report
The global myeloproliferative disorders drugs market size was valued at USD 11.3 billion in 2024 and is estimated at USD 12.5 billion for 2026.
The global myeloproliferative disorders drugs market is expected to grow at a CAGR of 5.9% from 2025 to 2030, reaching USD 15.8 billion by 2030.
Ph+ Chronic myelogenous leukemia (CML) dominated the myeloproliferative disorders drugs market with a share of 80.7% in 2019. This is attributable to high prevalence of Ph+ CML in key regions.
Some key players operating in the myeloproliferative disorders drugs market include Novartis AG; Bristol-Myers Squibb Company; Pfizer Inc.; Takeda Pharmaceutical Company Limited; Incyte Corporation; and Teva Pharmaceutical Industries Ltd.
Key factors that are driving the market growth include introduction of novel drugs, presence of a strong pipeline, and increasing incidence of myeloproliferative disorders.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


