
- Home
- »
- Plastics, Polymers & Resins
- »
-
Next-gen Paper-based And Fiber-based Packaging Market Report 2033GVR Report cover

Next-gen Paper-based And Fiber-based Packaging Market (2026 - 2033)
Size, Share & Trends Analysis Report By Material Source (Recycled Fiber, Virgin Fiber), By Application (Food & Beverages, Retail & E-commerce, Healthcare & Pharmaceuticals), By Region, And Segment Forecasts
Market Size, 2025
$378.8BMarket Estimate, 2026
$391.7BMarket Forecast, 2033
$489.9BCAGR, 2026–2033
4.6%Next-gen Paper-based And Fiber-based Packaging Market Summary
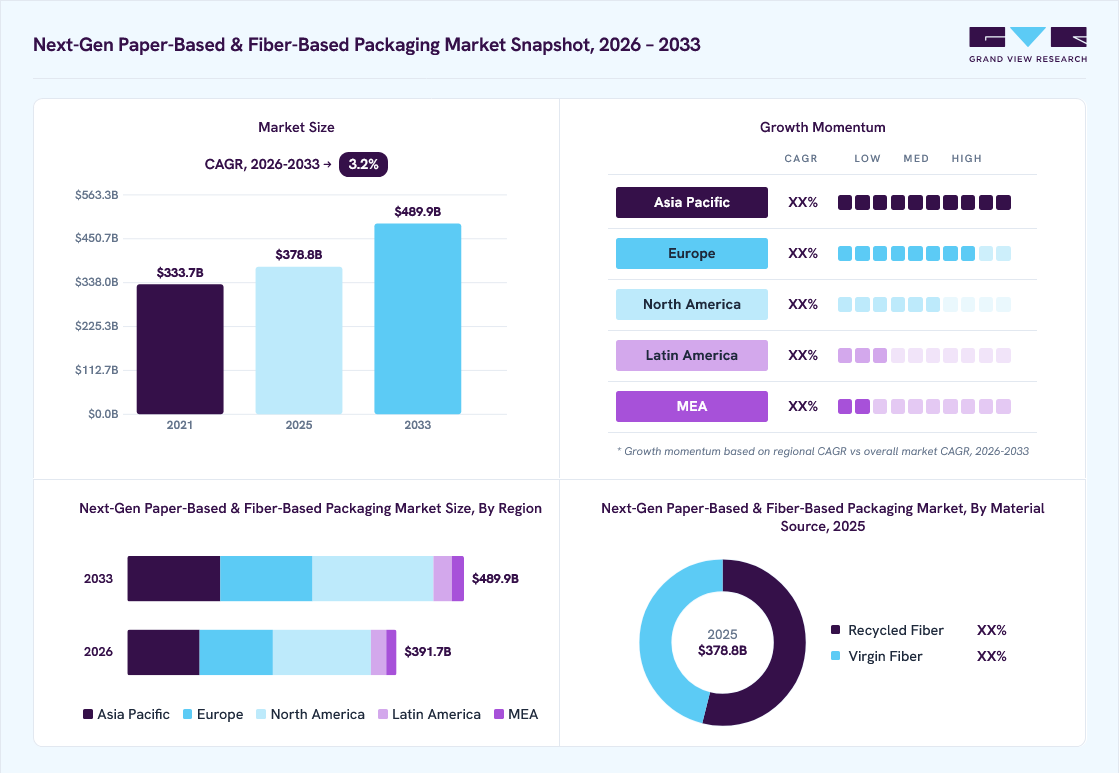
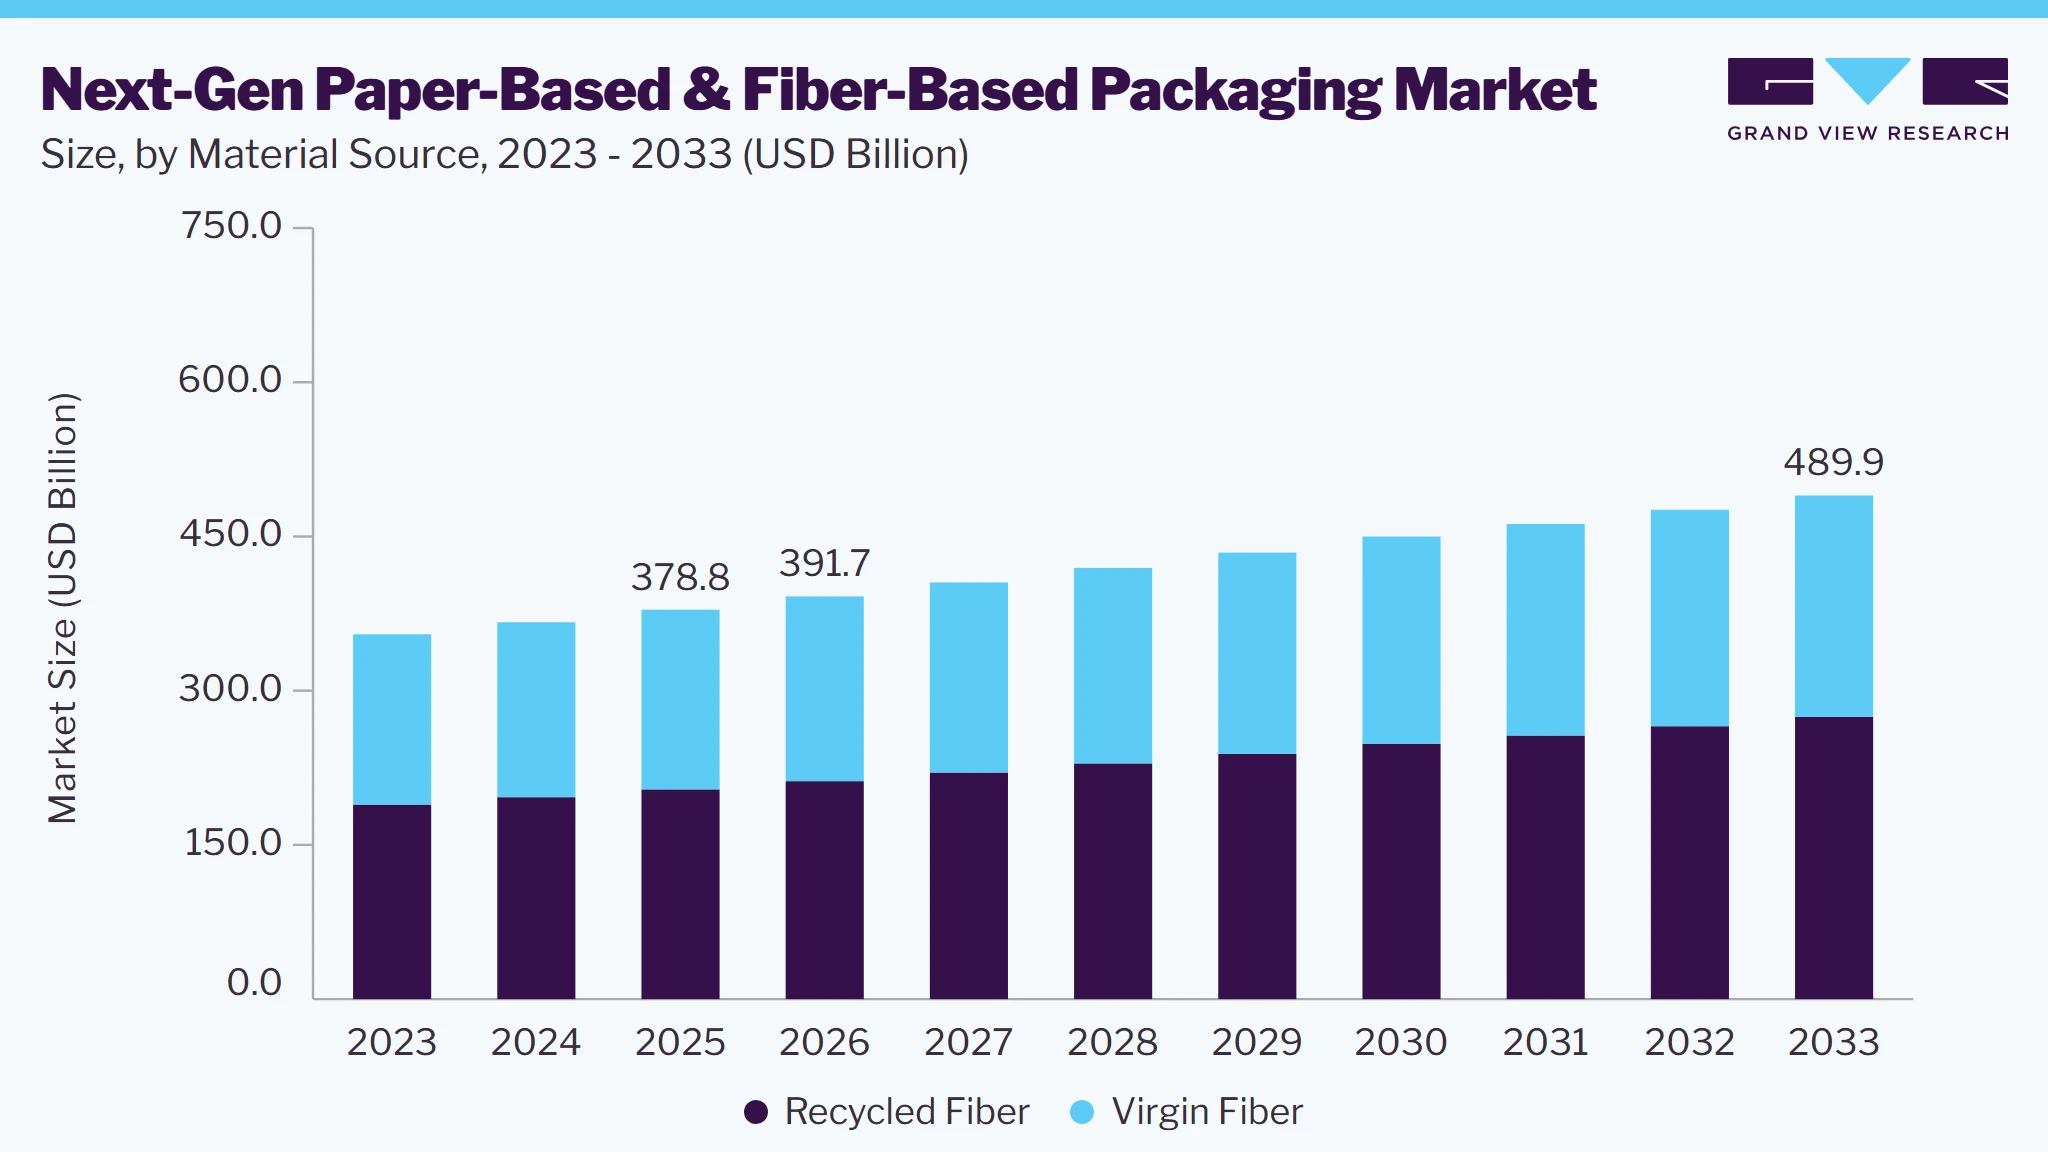
The global next-gen paper-based and fiber-based packaging market size was valued at USD 378.8 billion in 2025 and is projected to grow from USD 391.7 billion in 2026 to USD 489.9 billion by 2033, at a CAGR of 4.6% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 36.5% in 2025. The next-gen paper-based and fiber-based packaging market is driven by increasing consumer demand for sustainable packaging solutions and stringent regulations promoting eco-friendly alternatives to plastics
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By material source: Recycled fiber segment led the market with the largest revenue share of 53.8% in 2025.
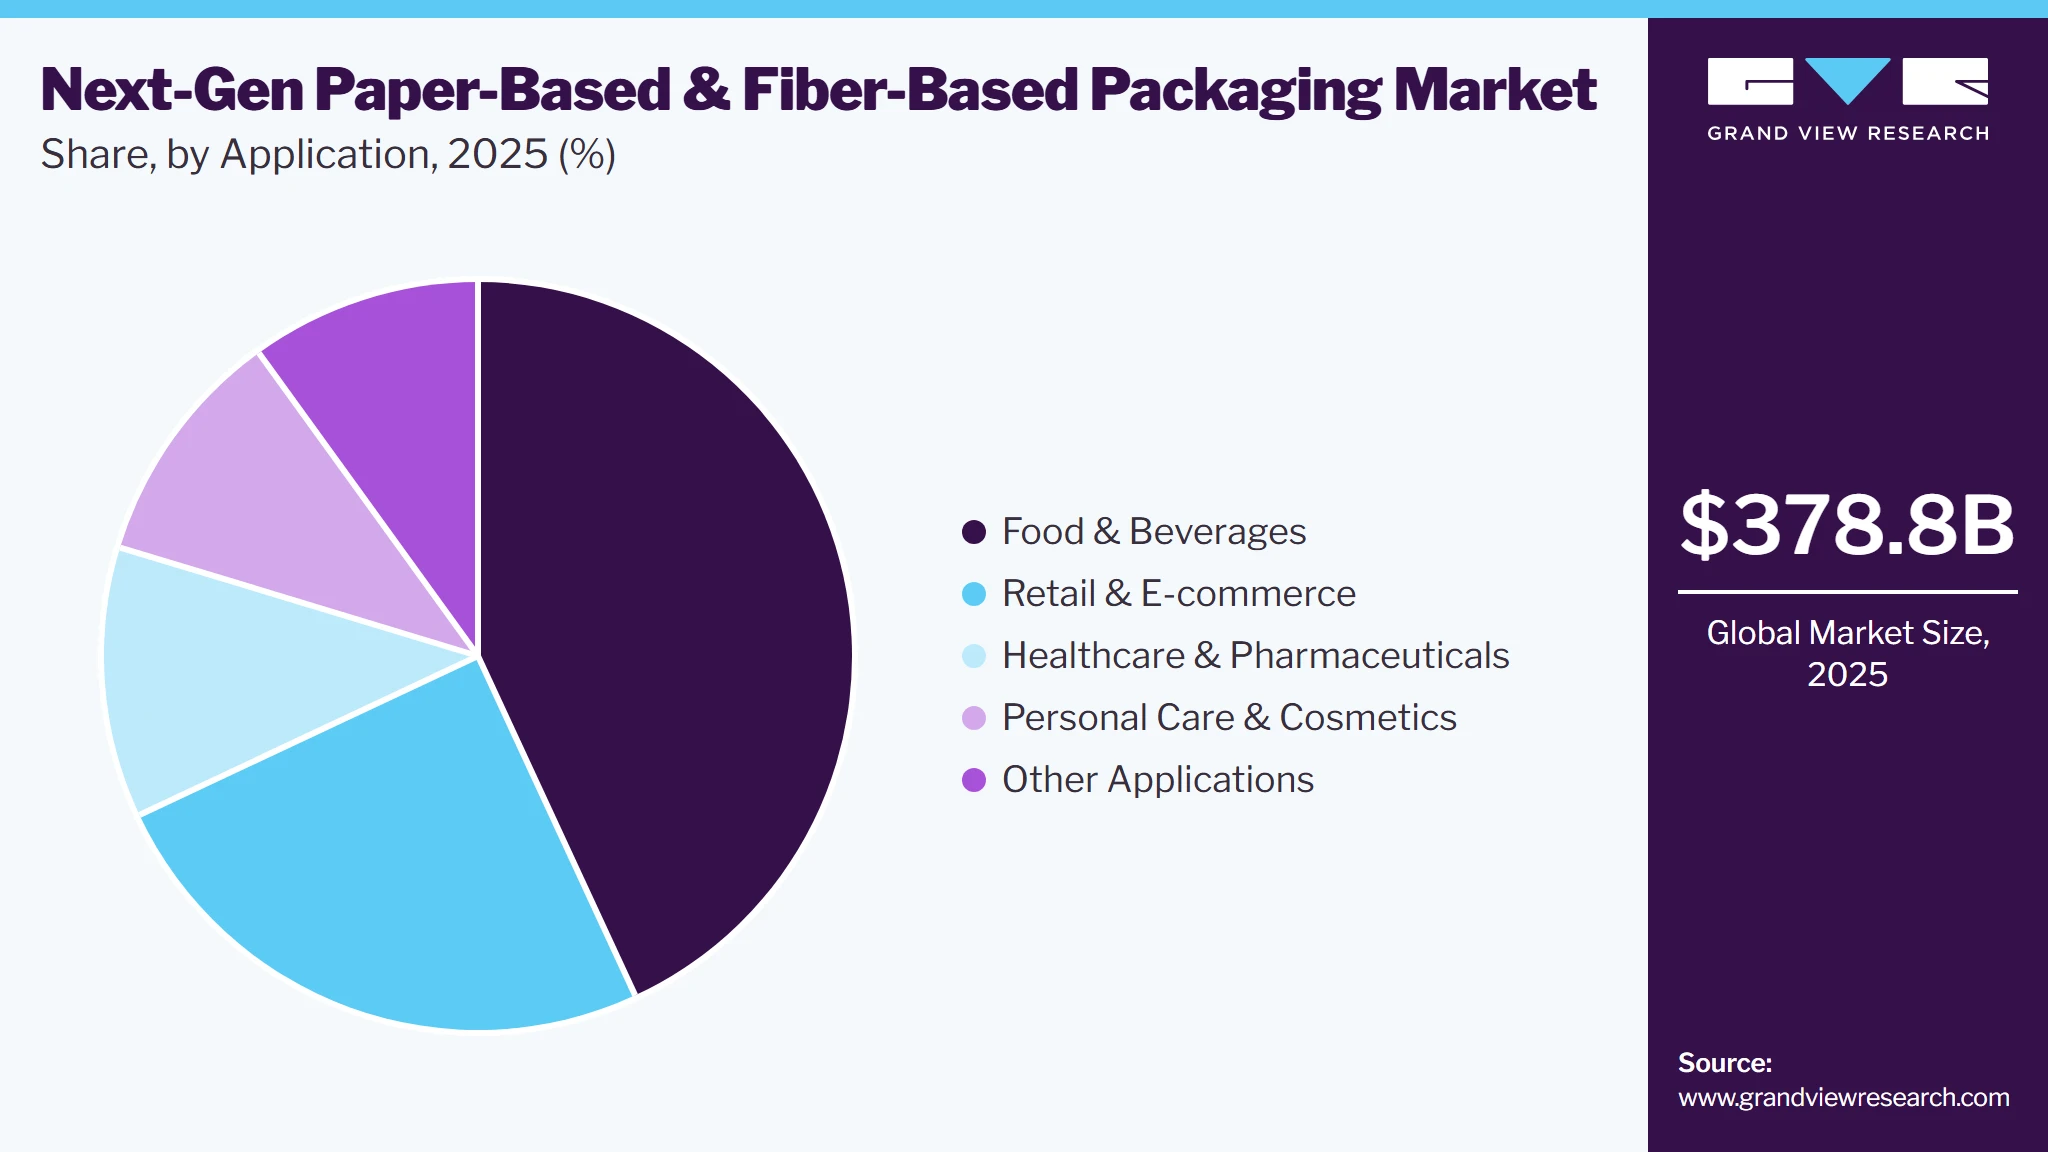
- By application: Food & beverages segment led the market with the largest revenue share of 43.1% in 2025.
Regional Highlights
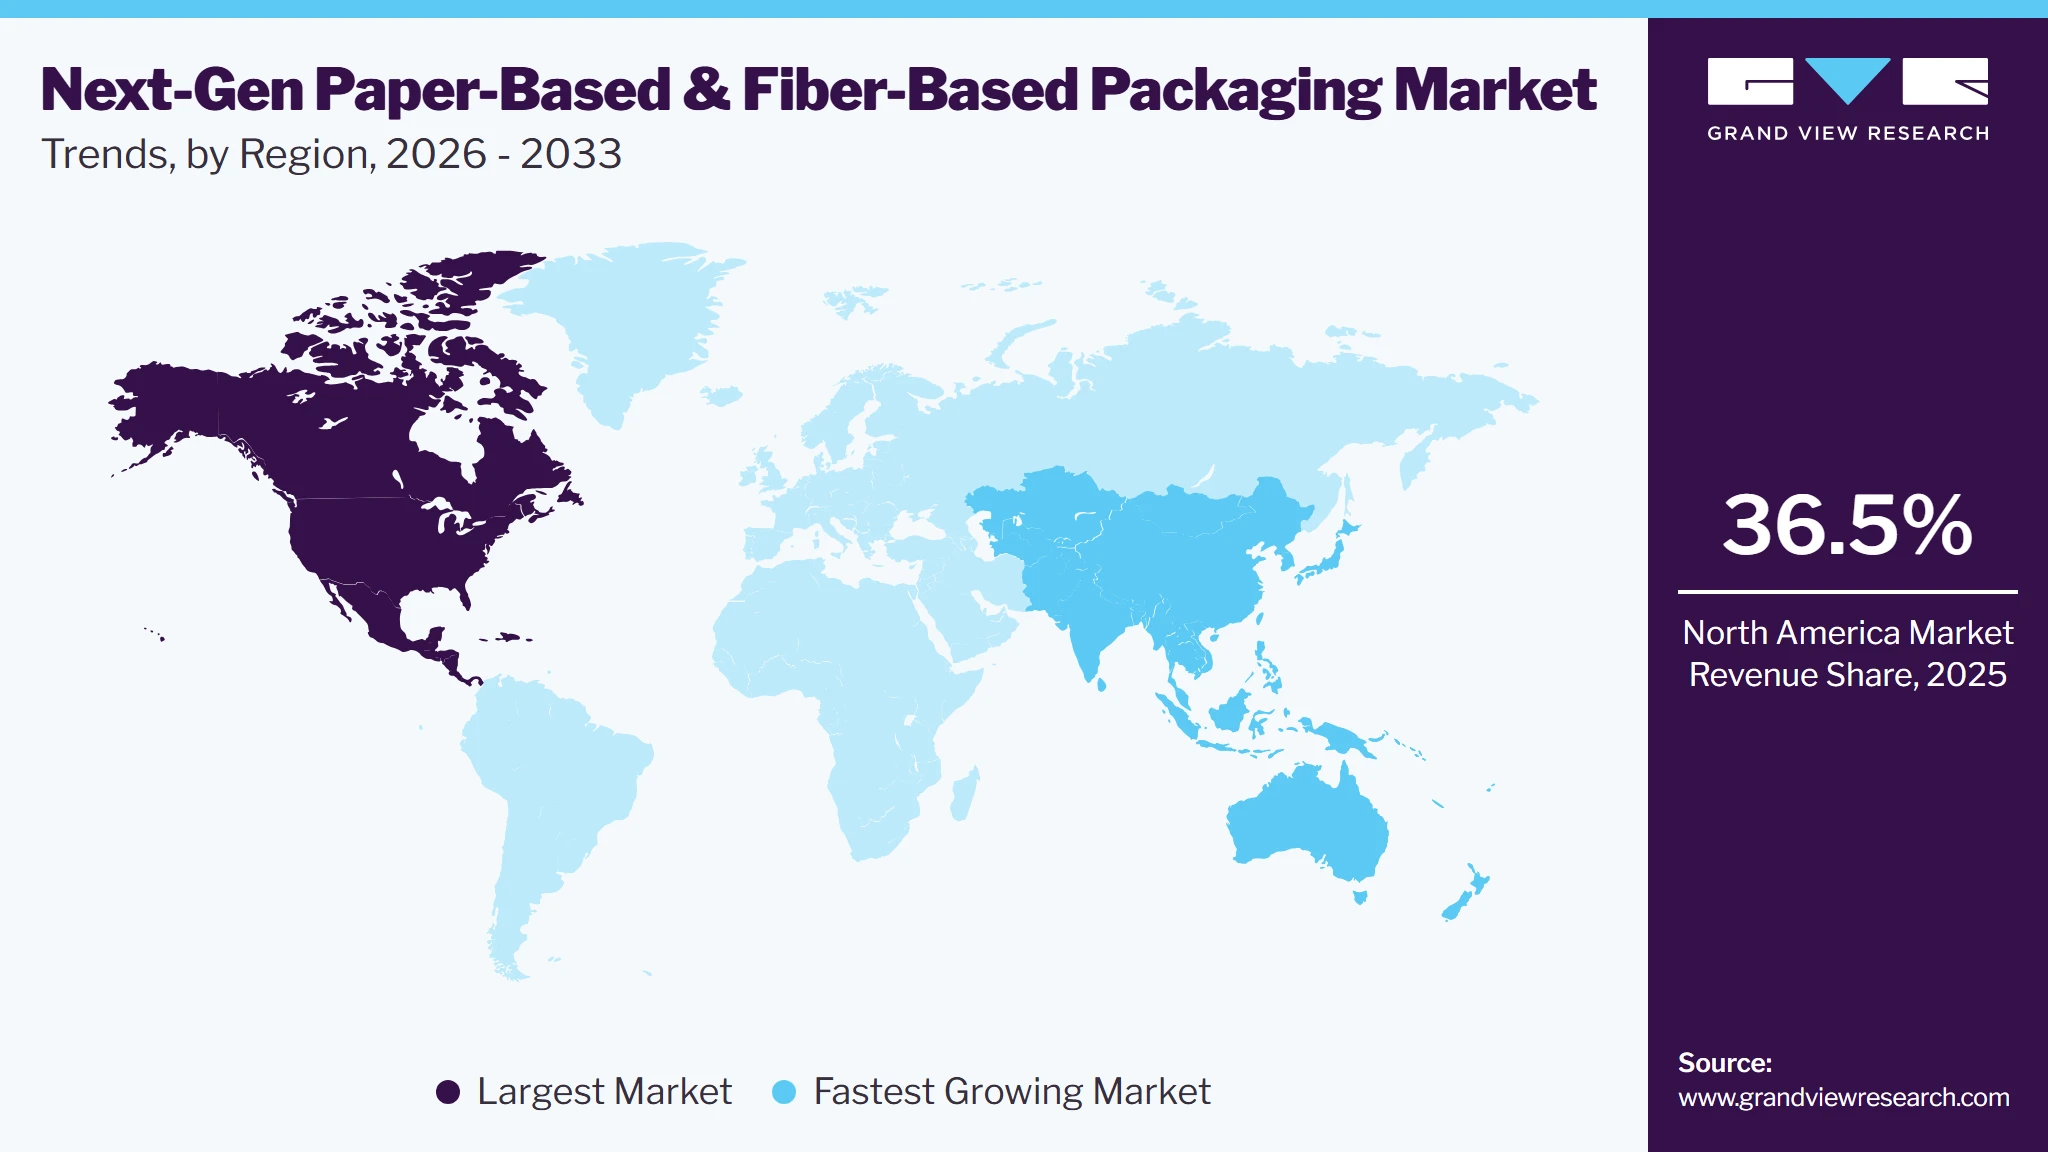
- Largest regional market: North America (36.5% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026–2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 378.8 billion
- Estimated market size in 2026: USD 391.7 billion
- Projected market size by 2033: USD 489.9 billion
- CAGR (2026-2033): 4.6%
GVR research-powered AIAsk Prism AI about the next-gen paper-based and fiber-based packaging marketGet cited answers from GVR research on market growth, segments, regulations and forecasts.Start with✓ Source-linked answers ✓ Market-specific context ✓ Traceable figuresExplore Prism AI ↗Additionally, advancements in biodegradable and recyclable material technologies are fueling market growth. Consumer awareness about environmental sustainability is driving a significant shift toward paper-based and fiber-based packaging solutions. With increasing concerns about plastic pollution and its harmful impact on ecosystems, consumers are actively seeking eco-friendly alternatives. Brands are responding by adopting sustainable packaging to align with consumer preferences and enhance brand loyalty.
For example, companies such as Nestlé and Unilever have committed to transitioning their product packaging toward paper and fiber-based solutions. Nestlé’s transition to recyclable paper wrapping for its Smarties products reflects this trend, catering to environmentally conscious consumers while also meeting stringent sustainability targets.
 To learn more about this report, Download Free Sample Report
Governments worldwide are implementing stricter regulations to reduce single-use plastics and promote sustainable packaging. The European Union’s Single-Use Plastics Directive, which aims to phase out non-recyclable plastics, has forced manufacturers to explore alternatives such as paper and fiber-based packaging. Similarly, Canada has introduced regulations to ban harmful single-use plastics by 2025, further accelerating the shift toward biodegradable and recyclable materials. Corporate sustainability goals also play a critical role in driving this market. Many companies, including Coca-Cola and PepsiCo, have announced ambitious targets to achieve 100% recyclable, reusable, or compostable packaging by 2025, which encourages the adoption of next-gen paper-based solutions.
The rapid growth of e-commerce has created a surge in demand for sustainable and durable shipping solutions. Consumers expect environmentally friendly packaging when ordering products online, driving brands and e-retailers to adopt paper and fiber-based solutions. Companies such as Amazon are leading the way by introducing sustainable alternatives, such as curbside-recyclable paper mailers and fiber-based padding for product protection. Additionally, innovations in molded fiber packaging and corrugated board technologies are helping meet the increasing demand for protective and lightweight shipping solutions that reduce waste and carbon emissions. This trend is expected to continue as e-commerce growth fuels the need for sustainable packaging practices.
Market Dynamics
The next-gen paper-based & fiber-based packaging market is experiencing steady growth, driven by rising demand for sustainable packaging, stringent regulations on single-use plastics, and increasing consumer preference for recyclable and biodegradable materials. Growing adoption across food & beverage, e-commerce, personal care, and healthcare sectors, along with advancements in barrier coatings and molded fiber technologies, is expanding market applications. However, higher production costs, raw material price fluctuations, and performance limitations in moisture-sensitive applications may hinder growth. Despite these challenges, ongoing innovation and investments in circular packaging solutions are expected to support long-term market expansion.
The market is primarily driven by the growing demand for sustainable and plastic-free packaging across industries. Increasing environmental awareness, stringent regulations on single-use plastics, and rising consumer preference for recyclable and biodegradable materials are encouraging manufacturers and brand owners to shift from conventional plastic packaging to advanced paper- and fiber-based alternatives. This trend is accelerating adoption in food & beverage, personal care, healthcare, and e-commerce applications.
The market is also benefiting from corporate sustainability initiatives aimed at reducing carbon footprints and improving packaging recyclability. Continuous innovations in barrier coatings, molded fiber technologies, and lightweight packaging designs are enhancing product performance, enabling paper- and fiber-based solutions to replace plastics in a broader range of applications while supporting circular economy goals.
The market faces a significant restraint due to the performance limitations of paper- and fiber-based materials compared to conventional plastics. Although technological advancements have improved barrier properties and durability, these materials may still offer limited resistance to moisture, grease, oxygen, and heavy loads in certain applications. Consequently, industries requiring high-performance packaging, such as food, beverages, pharmaceuticals, and industrial goods, may continue to rely on plastic-based solutions, slowing the widespread adoption of next-generation paper- and fiber-based packaging.
The market presents significant opportunities through the advancement of fiber-based packaging technologies and material innovations. Developments in high-performance barrier coatings, molded fiber products, and recyclable paper composites are enabling paper- and fiber-based packaging to serve applications that have traditionally relied on plastics. As companies invest in sustainable product development and governments continue to promote circular economy initiatives, the adoption of innovative paper- and fiber-based packaging solutions is expected to expand across food & beverage, e-commerce, healthcare, and consumer goods industries.
Analyst Perspective
The market is expected to grow steadily, driven by rising demand for sustainable packaging, stricter regulations on single-use plastics, and increasing adoption across food & beverages, retail & e-commerce, healthcare, and personal care industries. Advancements in barrier coatings, molded fiber technologies, and recyclable materials are enhancing product performance, while continued investments in innovation and circular packaging solutions are expected to strengthen market growth.
Material Source Insights
Based on material source, the recycled fiber segment led the market with the largest revenue share of 53.8% in 2025. Recycled fiber is derived from post-consumer and post-industrial waste materials, including used paper products such as newspapers, cardboard boxes, and office paper. The recycling process involves collecting, pulping, and reprocessing these materials into new fiber-based packaging products. Recycled fiber is widely used in the production of corrugated boxes, folding cartons, and molded pulp packaging, making it an eco-friendly alternative to virgin fiber. The growing emphasis on sustainability and the circular economy is a major driver for recycled fiber in next-gen packaging market.
Virgin fiber is sourced directly from freshly harvested wood pulp, which provides stronger and more durable packaging materials. Virgin fiber-based packaging is preferred for food contact materials due to its purity and compliance with stringent food safety standards. Additionally, the growing preference for premium and luxury packaging in industries such as cosmetics, pharmaceuticals, and beverages is contributing to the sustained demand for virgin fiber.
Application Insights
Based on application, the food & beverages segment led the market with the largest revenue share of 43.1% in 2025. This positive outlook is due to the rising demand for sustainable and eco-friendly packaging solutions in food & beverage industry. This segment includes products such as takeaway containers, paper straws, biodegradable trays, and recyclable cartons that cater to the growing need for food safety, convenience, and sustainability. Increasing regulations on single-use plastics and the shift toward renewable packaging materials have led companies in the food industry to adopt fiber-based solutions that ensure product freshness and extend shelf life.
 To learn more about this report, Download Free Sample Report
The personal care & cosmetics segment is projected to grow at the fastest CAGR of 4.0% during the forecast period. This segment is adopting next-gen paper-based and fiber-based packaging for items such as lotions, shampoos, and other beauty products. Brands are focusing on sustainable alternatives such as paper-based tubes, molded fiber packaging, and compostable containers to align with consumer preferences for eco-conscious products while maintaining product integrity and brand aesthetics.
The retail & e-commerce segment is also witnessing significant growth, driven by the surge in online shopping and the increasing need for secure, lightweight, and recyclable packaging solutions. E-commerce companies are focusing on reducing their environmental footprint by using fiber-based packaging solutions such as corrugated boxes, paper fillers, and molded fiber inserts to ensure the safe delivery of goods while meeting customer expectations for sustainable packaging.
Region Insights
North America dominated the next-gen paper-based & fiber-based packaging market with the largest revenue share of 36.5% in 2025. The region's robust consumer awareness around sustainability, coupled with stringent environmental regulations, has created strong market demand for eco-friendly packaging alternatives. Major retailers and consumer brands headquartered in the US and Canada have made ambitious commitments to reduce plastic packaging, creating a ripple effect throughout supply chains that favors paper and fiber-based solutions.
 To learn more about this report, Download Free Sample Report
The next-gen paper-based & fiber-based packaging market in U.S. held the largest share in the North America region in 2025. U.S. next-gen paper-based and fiber-based packaging market is experiencing robust growth primarily due to stringent regulations on single-use plastics and increased consumer preference for sustainable packaging. Besides, the country’s abundant forestry resources and established pulp and paper industry is strengthening its position in global market. Companies are leveraging these advantages while implementing sustainable forestry practices and circular economy principles.
Asia Pacific Next-gen Paper-based And Fiber-based Packaging Market Trends
The Asia Pacific region is anticipated to grow at the fastest CAGR of 6.9% over the forecast period. This positive outlook is due to its rapid industrialization and urbanization, particularly in countries such as China, India, and Southeast Asian nations. These demographic shifts have created a surge in consumption of packaged goods across food, beverage, and consumer products, while simultaneously increasing environmental awareness. Governments across the region have implemented strict regulations on single-use plastics, with countries such as China banning non-biodegradable bags and India prohibiting certain single-use plastic items, creating substantial market opportunities for sustainable paper and fiber-based alternatives.
The China next-gen paper-based and fiber-based packaging market is experiencing robust growth primarily due to its massive manufacturing capacity, governmental sustainability initiatives, and strong domestic market demand. As the world's largest paper and paperboard producer, China has leveraged its industrial infrastructure to rapidly adopt and scale innovative fiber-based packaging technologies. This transition is further accelerated by China's strict plastic reduction policies, including the 2020 nationwide ban on non-biodegradable single-use plastics, which has created urgent market demand for sustainable alternatives.
Europe Next-gen Paper-based And Fiber-based Packaging Market Trends
Europe’s growth in the global next-gen paper-based & fiber-based packaging market is due to its stringent environmental regulations and sustainability commitments. The European Green Deal and Single-Use Plastics Directive have accelerated the transition away from conventional plastics toward fiber-based alternatives. Major retailers and brands across the continent have responded by implementing ambitious packaging reduction targets, with companies such as Carrefour, Tesco, and Unilever leading initiatives to eliminate plastic packaging in certain product categories.
The next-gen paper-based and fiber-based packaging market in Germany is primarily driven by its combination of environmental policies, innovative industrial base, and consumer demand. The country has implemented some of the strictest packaging regulations in the world through its Packaging Act (VerpackG), which emphasizes extended producer responsibility and creates significant incentives for companies to adopt sustainable packaging solutions. This regulatory framework has effectively stimulated rapid innovation and adoption of next-generation fiber-based alternatives to traditional plastic packaging.
Key Next-gen Paper-based And Fiber-based Packaging Company Insights
Major players dominate the market, leveraging innovation in biodegradable, recyclable, and compostable materials to gain a competitive edge. They hold a notable market share due to their strong focus on sustainable packaging solutions and global supply chain networks. Meanwhile, emerging players and niche companies are focusing on technological advancements in barrier coatings and lightweight materials to enhance product performance. The market is highly competitive, with companies emphasizing R&D, strategic partnerships, and mergers to expand their product portfolios and strengthen their market position.
-
In January 2025, International Paper completed its acquisition of DS Smith, a British multinational packaging company, in a deal valued at approximately USD 7.2 billion. The acquisition positions International Paper as a leading sustainable packaging company, leveraging the strengths of both entities to accelerate growth and improve profitability.
-
In December 2024, Nexgen Packaging and Seaman Paper announced a strategic partnership to create a comprehensive portfolio of plastic-free, paper-based packaging solutions for the retail, apparel, and footwear industries. This collaboration aims to address the growing demand for sustainable alternatives to single-use plastics, such as polybags, which are used extensively in these sectors but have low recycling rates.
-
In May 2024, Iceland Foods partnered with PAPTIC to introduce an innovative next-generation carrier bag made from wood fibers, rolling out across all Iceland and Food Warehouse stores in the UK. The bag is crafted using PAPTIC material, which is designed to be strong, lightweight, reusable, and moisture resistant. It uses 40% less raw materials compared to conventional paper alternatives and is sourced from sustainably managed forests. At the end of its lifecycle, the bag can be recycled alongside paper or cardboard.
Key Next-gen Paper-based And Fiber-based Packaging Companies:
The following are the leading companies in the next-gen paper-based and fiber-based packaging market.
- Ranpak
- PAPTIC
- Nexgen Packaging, LLC
- The Paper Bottle Company
- UPM Specialty Papers
- PulPac
- Graphic Packaging International, LLC
- Mondi
- Stora Enso
- Smurfit Kappa
- WestRock
- DS Smith
- International Paper
- Koehler Paper
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (International Paper, Mondi, Stora Enso, Smurfit Kappa, WestRock, DS Smith, Graphic Packaging International, LLC, UPM Specialty Papers, Koehler Paper, and Ranpak)
- Expand recyclable paper-based and fiber-based packaging portfolios through continuous product innovation and investments in large-scale manufacturing.
- Strengthen global market presence through strategic acquisitions, partnerships with FMCG and e-commerce companies, and integrated supply chain capabilities.
- Strong global production networks, established customer relationships, and significant financial resources enable rapid commercialization and large-volume supply.
- Extensive R&D capabilities and diversified sustainable packaging portfolios support compliance with evolving environmental regulations and customer requirements.
- Large manufacturing infrastructures and legacy production systems can slow the adoption of disruptive packaging technologies.
- Higher operational complexity and capital-intensive investments may reduce flexibility in responding to rapidly changing sustainability trends.
Emerging Players (PulPac, PAPTIC, The Paper Bottle Company, and Nexgen Packaging, LLC)
- Focus on commercializing breakthrough technologies such as dry molded fiber, advanced barrier coatings, and paper-based alternatives to plastics.
- Accelerate market penetration through technology licensing, pilot projects, and collaborations with packaging converters and brand owners.
- High innovation agility enables rapid development of next-generation sustainable packaging solutions tailored to emerging market needs.
- Proprietary technologies and specialized expertise in fiber-based materials provide differentiation in high-growth sustainable packaging segments.
- Limited production capacity, financial resources, and global distribution networks restrict large-scale commercialization.
- Greater dependence on external funding, strategic partnerships, and customer validation can delay market expansion and profitability.
Next-gen Paper-based And Fiber-based Packaging Market Report Scope
Report Attribute
Details
Market size in 2025
USD 378.8 billion
Estimated market size in 2026
USD 391.7 billion
Projected market size by 2033
USD 489.9 billion
Growth rate
CAGR of 4.6% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Material source, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; Japan; India; South Korea; Australia; Brazil; Argentina; Saudi Arabia; South Africa; UAE
Key companies profiled
Ranpak; PAPTIC; Nexgen Packaging, LLC; The Paper Bottle Company; UPM Specialty Papers; PulPac; Graphic Packaging International, LLC; Mondi; Stora Enso; Smurfit Kappa; WestRock; DS Smith; International Paper; Koehler Paper
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Next-gen Paper-based And Fiber-based Packaging Market Report Segmentation
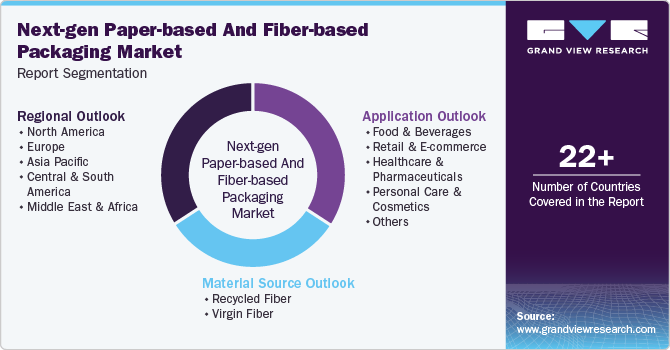
This report forecasts revenue growth at a global level and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented global next-gen paper-based and fiber-based packaging market report based on material source, application, and region:
 To learn more about this report, Download Free Sample Report
-
Material Source Outlook (Revenue, USD Million; 2021 - 2033)
-
Recycled Fiber
-
Virgin Fiber
-
-
Application Outlook (Revenue, USD Million; 2021 - 2033)
-
Food & Beverages
-
Retail & E-commerce
-
Healthcare & Pharmaceuticals
-
Personal Care & Cosmetics
-
Others
-
-
Region Outlook (Revenue, USD Million; 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
UK
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
-
Research Methodology
The next-gen paper-based and fiber-based packaging market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each next-gen paper-based and fiber-based packaging segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Material Source
Revenue capture definition
Virgin Fiber
Revenue generated from the sale of next-generation paper-based and fiber-based packaging manufactured using virgin wood pulp or other primary fiber sources. This segment includes high-strength, food-grade, and premium packaging solutions used across food & beverages, healthcare, personal care, retail, and industrial applications where superior performance and product safety are required.
Recycled Fiber
Revenue generated from the sale of next-generation paper-based and fiber-based packaging produced using recycled paper and recovered fiber materials. This segment includes recyclable and circular packaging solutions designed for retail, e-commerce, food service, consumer goods, and other applications where sustainability and resource efficiency are prioritized.
Segment - Application
Revenue capture definition
Food & Beverages
Revenue generated from the sale of next-generation paper-based and fiber-based packaging used for food and beverage products, including cartons, trays, containers, wraps, cups, and molded fiber packaging that provide product protection while supporting sustainability objectives.
Retail & E-commerce
Revenue generated from the sale of next-generation paper-based and fiber-based packaging used for retail display, shipping, and e-commerce fulfillment. This segment includes mailers, corrugated packaging, protective inserts, cushioning materials, and other fiber-based solutions designed for safe product transportation and reduced environmental impact.
Healthcare & Pharmaceuticals
Revenue generated from the sale of next-generation paper-based and fiber-based packaging used for pharmaceuticals, medical devices, healthcare products, and diagnostic equipment. This segment includes sterile-compatible cartons, inserts, molded fiber trays, and other protective packaging solutions that meet regulatory and product safety requirements.
Personal Care & Cosmetics
Revenue generated from the sale of next-generation paper-based and fiber-based packaging used for cosmetics, skincare, haircare, fragrances, and personal care products. This segment includes cartons, molded fiber packaging, paper tubes, and premium sustainable packaging designed to enhance brand appeal while reducing plastic usage.
Other Applications
Revenue generated from the sale of next-generation paper-based and fiber-based packaging used across consumer goods, electronics, industrial products, homecare, and other end-use industries requiring sustainable, recyclable, and protective packaging solutions.
Estimation Model
Layer Name
Key Question
Description
End-Use Demand Layer
What forms the demand base?
Identify global demand for next-gen paper-based & fiber-based packaging across major end-use industries, including food & beverages, retail & e-commerce, healthcare & pharmaceuticals, personal care & cosmetics, and other consumer and industrial applications. This layer establishes the total addressable demand driven by sustainability initiatives, regulatory compliance, and the transition from plastic to fiber-based packaging.
Material Adoption Layer
Where are next-gen paper-based & fiber-based packaging solutions utilized?
Estimate the penetration of virgin fiber and recycled fiber packaging across key application sectors and geographic regions. Assess adoption rates based on sustainability targets, performance requirements, recyclability, product protection needs, and evolving packaging regulations in developed and emerging markets.
Production & Supply Chain Layer
How much packaging is manufactured and supplied?
Analyze production volumes, raw material availability, converting capacity, recycling infrastructure, supply chain efficiency, and distribution networks for next-gen paper-based & fiber-based packaging. Supply intensity is influenced by pulp and recovered fiber availability, manufacturing investments, technological advancements, and regional demand patterns.
Revenue Layer
How is market revenue generated?
Market revenue is quantified through the sale of next-gen paper-based & fiber-based packaging products, including cartons, molded fiber packaging, paper mailers, protective packaging, trays, containers, wraps, and other sustainable packaging solutions. Revenue is generated from recurring demand across food & beverage, retail & e-commerce, healthcare, personal care, consumer goods, and industrial end-use industries, supported by ongoing innovation and sustainability-driven packaging adoption.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation Analysis
Delivered a detailed regional assessment of the Next-Gen Paper-Based & Fiber-Based Packaging Market across North America, Europe, Asia Pacific, Central & South America, and Middle East & Africa, highlighting market size, growth trends, sustainability regulations, manufacturing capabilities, raw material availability, and application-specific demand.
Enabled identification of high-growth regional markets, investment hotspots, regulatory influences, and region-specific expansion strategies.
Cross-Segmentation Analysis
Provided cross-segmentation analysis by Material Source (Virgin Fiber and Recycled Fiber) and Application (Food & Beverages, Retail & E-commerce, Healthcare & Pharmaceuticals, Personal Care & Cosmetics, and Other Applications) across major regions to identify high-growth market combinations and demand trends.
Supported product portfolio optimization, demand forecasting, customer targeting, and strategic resource allocation across material sources and application areas.
Competitive Benchmarking
Conducted benchmarking of leading manufacturers based on material portfolio, sustainable packaging capabilities, manufacturing footprint, geographic presence, innovation pipeline, strategic partnerships, and competitive positioning within the next-generation paper-based and fiber-based packaging market.
Helped stakeholders evaluate competitive strengths, identify market gaps, benchmark industry best practices, and formulate differentiation strategies.
Frequently Asked Questions About This Report
The food & beverages segment led the market with the largest revenue share of 43.1% in 2025.
Key factors driving the next-gen paper-based & fiber-based packaging market include rising demand for sustainable packaging, stringent plastic regulations, growing use of recyclable materials, and advancements in fiber-based packaging technologies.
Key players in the next-gen paper-based & fiber-based packaging market include Ranpak; PAPTIC; Nexgen Packaging, LLC; The Paper Bottle Company; UPM Specialty Papers; PulPac; Graphic Packaging International, LLC; Mondi; Stora Enso; Smurfit Kappa; WestRock; DS Smith; International Paper; Koehler Paper.
Asia Pacific is the fastest-growing region over the forecast period.
The recycled fiber segment led the market with the largest revenue share of 53.8% in 2025.
The global next-gen paper-based and fiber-based packaging market is expected to grow at a CAGR of 4.6% from 2026 to 2033, reaching USD 489.9 billion by 2033.
North America dominated the market, accounting for a revenue share of 36.5% in 2025.
The global next-gen paper-based and fiber-based packaging market size was valued at USD 378.8 billion in 2025 and is estimated at USD 391.7 billion for 2026.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


