
- Home
- »
- Pharmaceuticals
- »
-
Non-opioid Pain Patches Market Size & Share Report, 2033GVR Report cover

Non-opioid Pain Patches Market (2026 - 2033)
Size, Share & Trends Analysis Report By Patch Type (Lidocaine, Diclofenac, Methyl Salicylate, Capsaicin, Ketoprofen), By Distribution Channel (Retail, Hospital, Online), By Region (North America, Europe, APAC), And Segment Forecasts
Market Size, 2025
$1.0BMarket Estimate, 2026
$1.1BMarket Forecast, 2033
$1.6BCAGR, 2026–2033
4.7%Non-opioid Pain Patches Market Trends
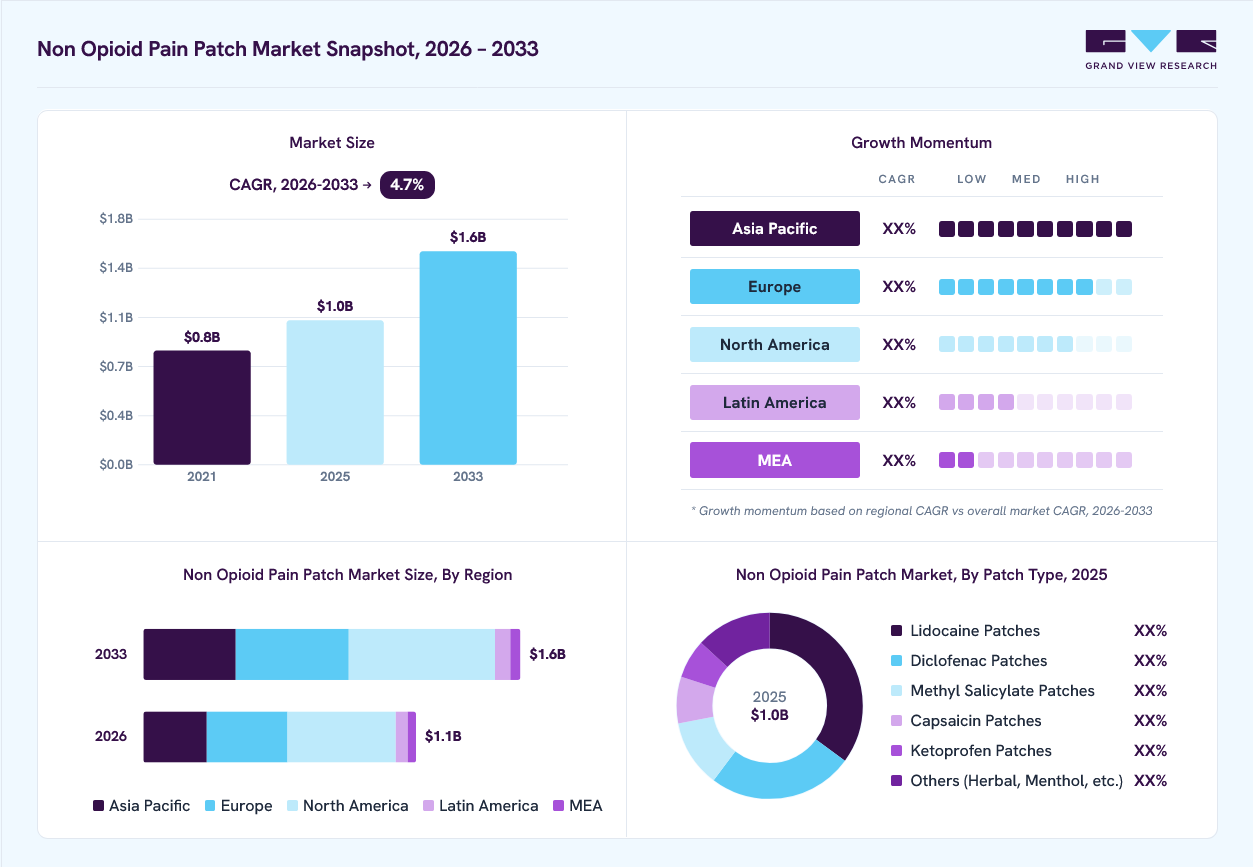
The global non-opioid pain patches market size was valued at USD 1.0 billion in 2025 and is projected to grow from USD 1.1 billion in 2026 to USD 1.6 billion by 2033, growing at a CAGR of 4.7% from 2026 to 2033. North America dominated the market, accounting for the largest global share of 39.8% in 2025. The alarming increase in opioid prescriptions and related overdose deaths has prompted healthcare providers and patients to seek effective non-opioid solutions.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By patch type: Lidocaine patches segment led the market with the largest revenue share of 35.0% in 2025.
- By distribution channel: Retail pharmacies segment held the largest revenue share of 44.3% in 2025.
Regional Highlights
- Largest regional market: North America (39.8% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026–2033)
- By country: The U.S. held the largest share of North America in 2025.
Market Size & Forecast
- Market size in 2025: USD 1.0 Billion
- Estimated market size in 2026: USD 1.1 Billion
- Projected market size by 2033: USD 1.6 Billion
- CAGR (2026-2033): 4.7%
Prism AI by Grand View Research Free to tryAsk a question about the non-opioid pain patches marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Non-opioid pain patches offer localized relief without the addictive potential associated with opioids, making them highly preferred among stakeholders in the healthcare system. As the call for safer alternatives becomes more pronounced, the market for these patches is positioned for robust expansion. The growing prevalence of chronic pain is another critical driver for the non-opioid pain patches market. Approximately 50 million Americans suffer from chronic pain, highlighting the urgent need for effective pain management options. Non-opioid pain patches address various types of pain, including chronic, neuropathic, and musculoskeletal pain, thereby tackling a significant healthcare challenge. According to the European Pain Federation, in Europe, an estimated 100 million individuals experience chronic pain, representing approximately 20% of the adult population. This condition is a major contributor to disability, accounting for over 50% of sickness absences, which adversely impacts social and work life across multiple European countries.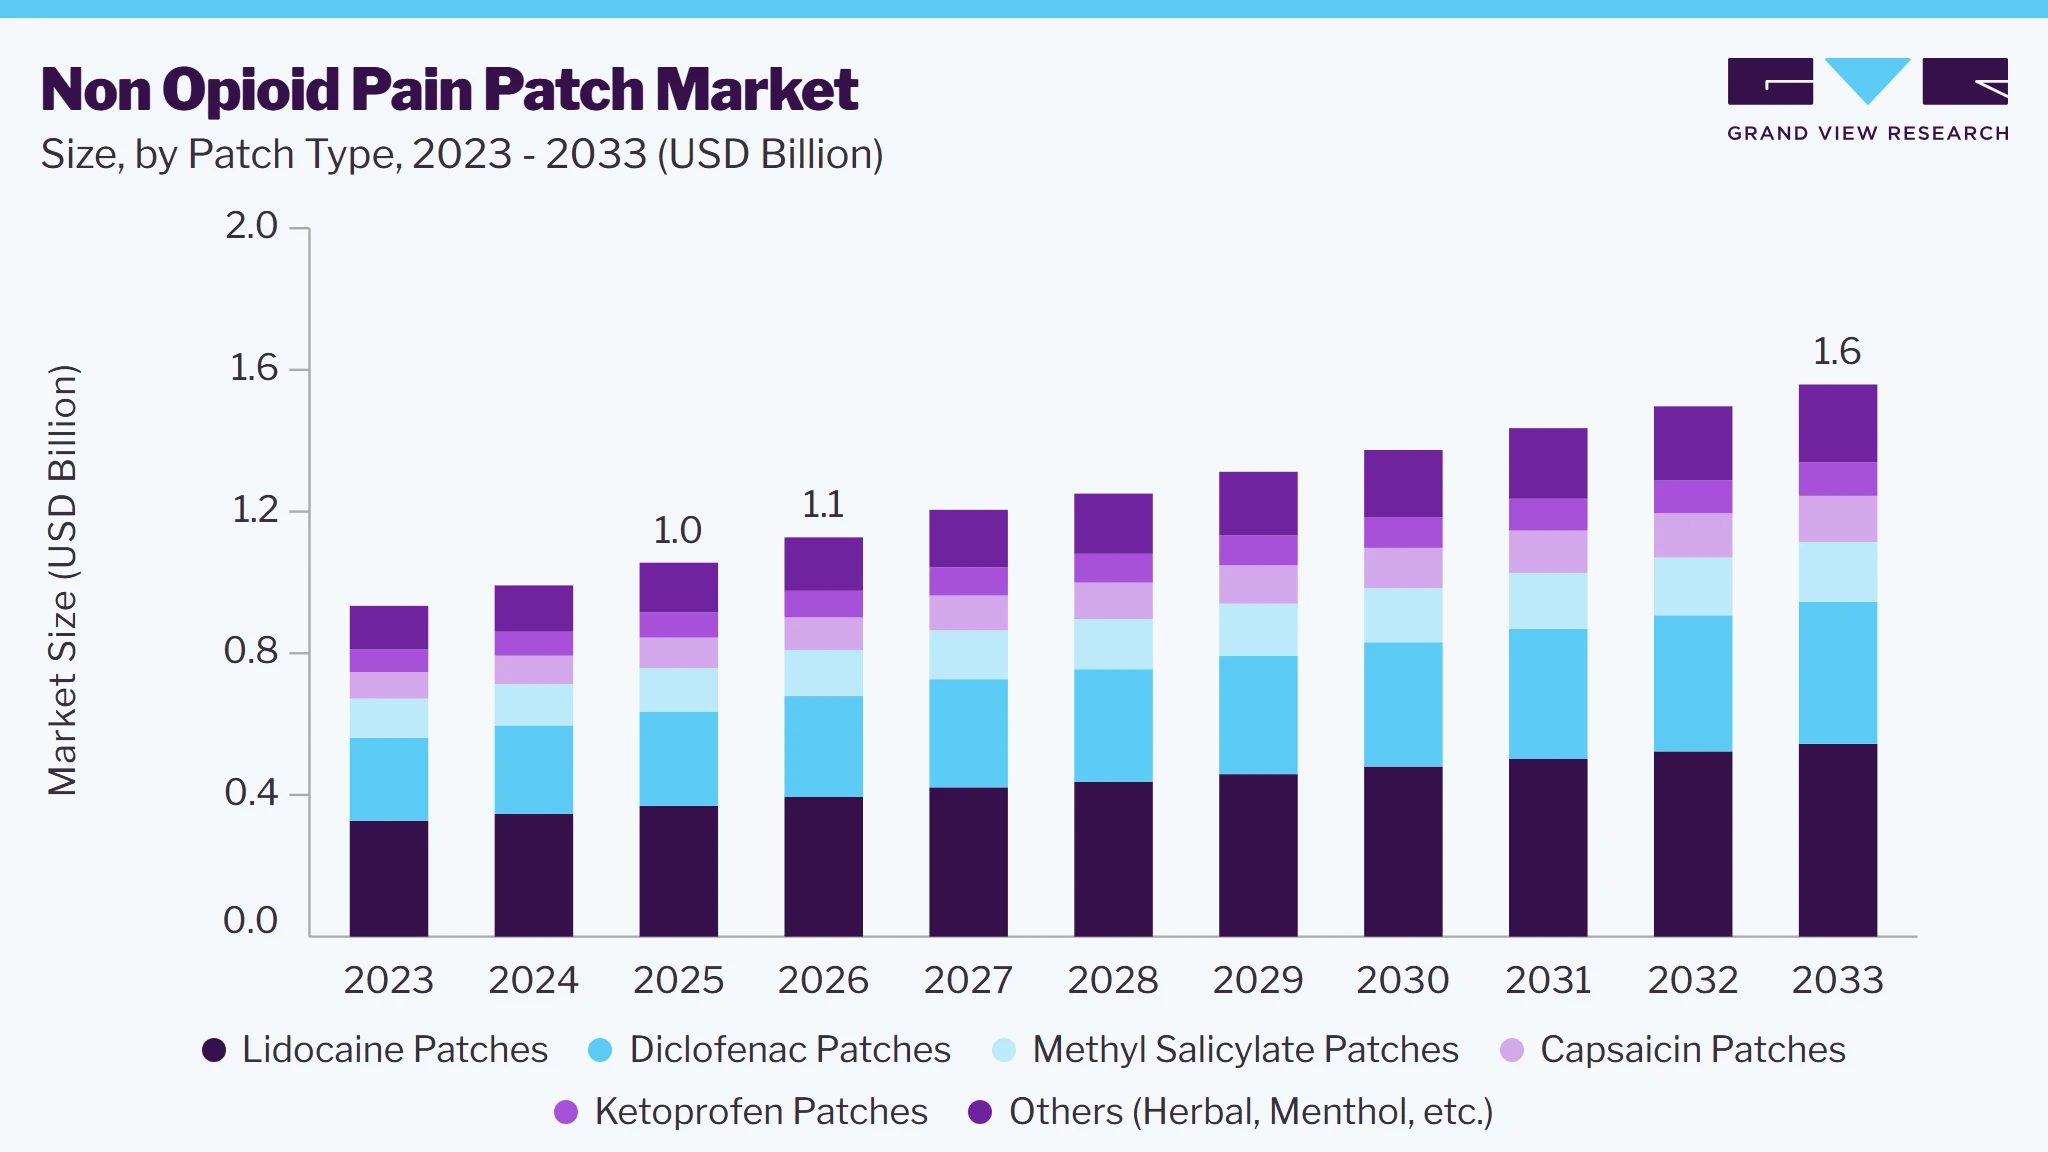 To learn more about this report, Download Free Sample Report
In Amsterdam, recent surveys indicate that around 30% of adults report experiencing chronic pain, reflecting the broader trends observed in urban areas across Europe, where women are more frequently affected than men. As chronic pain issues continue to escalate, there is an increasing demand for effective management solutions, propelling the adoption of non-opioid pain patches. Moreover, technological advancements are poised to further accelerate market growth. Continuous research and development in transdermal delivery systems have led to the creation of more effective non-opioid pain patches.
Innovations in drug formulation and patch design have significantly enhanced both efficacy and user experience. In tandem with this, increased awareness among patients and healthcare providers regarding the benefits of non-opioid therapies fosters greater acceptance and utilization. Educational initiatives and guidelines promoting non-opioid treatments are facilitating a shift away from traditional opioid prescriptions, thus creating an environment conducive to the market’s expansion. The rise of online pharmacies and retail outlets has made non-opioid pain patches more accessible to consumers, ensuring easier purchasing options and a more robust market presence.
Market Dynamics
The non opioid pain patches market is supported by the increasing focus on safer pain management options and the growing use of topical therapies for both acute and chronic pain conditions. Healthcare providers are adopting non opioid patches to reduce systemic side effects and lower the risks associated with opioid use while maintaining effective pain relief. Demand is also supported by the aging population and the rising prevalence of musculoskeletal disorders, arthritis, and sports injuries. The market is also benefiting from advances in patch technology that improve drug delivery, adhesion, and patient comfort. In addition, increasing consumer preference for self administered pain management products and continued investment in topical analgesic research are supporting steady market growth across both prescription and over the counter segments.
The non opioid pain patches market is driven by the increasing preference for safer pain management options that reduce the risk of dependence and systemic adverse effects associated with opioid therapies. Healthcare providers are incorporating topical analgesic patches into treatment plans for musculoskeletal disorders, neuropathic pain, arthritis, and minor injuries because they provide localized pain relief with improved patient convenience. Growing awareness of opioid related risks has also encouraged healthcare providers and patients to consider non opioid alternatives for appropriate pain conditions. Advances in transdermal drug delivery technologies have improved drug release, skin adhesion, and patient comfort, supporting wider adoption across healthcare facilities and home care. In addition, the increasing availability of over the counter pain patches has expanded patient access to non-invasive pain management solutions. For instance, in January 2025, Vertex Pharmaceuticals Incorporated received U.S. FDA approval for JOURNAVX (suzetrigine) 50 mg tablets for the treatment of moderate to severe acute pain in adults. The approval was supported by two Phase 3 clinical trials involving more than 870 participants and established JOURNAVX as the first non-opioid analgesic approved in a new class of pain medicines in more than 20 years. This approval reinforced industry interest in expanding non opioid pain treatment options.
The non opioid pain patches market faces challenges related to the limited number of drug molecules that can be effectively delivered through transdermal systems. Only compounds with suitable molecular characteristics can achieve therapeutic concentrations through the skin, which restricts product development opportunities. Many currently available patches contain well established active ingredients such as lidocaine, diclofenac, and capsaicin, resulting in limited product differentiation. Manufacturers must also address challenges related to skin irritation, patch adhesion, and consistent drug release across different patient populations. Regulatory requirements for demonstrating bioequivalence, product quality, and long term safety increase development timelines and costs. In addition, oral formulations, topical creams, gels, and injectable therapies continue to provide strong competition, particularly for patients requiring rapid pain relief or treatment for severe pain conditions. These factors limit the introduction of new products and slow the expansion of the non-opioid pain patches market despite increasing demand for safer pain management alternatives.
The non opioid pain patches market presents opportunities through continued innovation in transdermal drug delivery systems that improve treatment effectiveness and patient experience. Manufacturers are developing patches with improved adhesive materials, controlled drug release mechanisms, and enhanced skin permeability to improve therapeutic performance. The expansion of topical therapies for chronic pain, postoperative pain, and neuropathic pain creates additional opportunities for product development. Increasing research on novel non opioid compounds that can be delivered through transdermal systems may broaden the range of available treatment options. Rising demand for home based care and self-administered therapies is also supporting the adoption of convenient pain management products that reduce the need for frequent dosing. In addition, healthcare systems continue to encourage strategies that reduce opioid exposure while maintaining effective pain control, creating favorable conditions for non-opioid topical therapies. Companies investing in formulation technologies and clinical development are likely to benefit as healthcare providers continue to expand the use of localized pain management approaches.
Analyst Perspective
The non-opioid pain patches market is shifting from a segment primarily focused on topical pain relief to a broader pain management category, supported by improvements in transdermal drug delivery technologies and increasing demand for non-opioid therapies. The market is characterized by the presence of companies with established expertise in transdermal drug delivery, broad pain management portfolios, and strong manufacturing capabilities. Hisamitsu Pharmaceutical Co., Inc. continues to maintain a strong position through its established portfolio of topical pain patches and ongoing product development. Similarly, Teikoku Pharma, Teva Pharmaceutical Industries Ltd., Endo, Inc., and GSK plc are expanding their pain management portfolios, improving patch technologies, and increasing the availability of non-opioid treatment options across prescription and over the counter markets.
Patch Type Insights
Based on patch type, the lidocaine patches segment led the market with the largest revenue share of 35.0% in 2025, owing to their established efficacy in alleviating various pain types, including neuropathic and musculoskeletal pain. Offering localized relief with minimal systemic side effects, these patches are a preferred choice for patients and healthcare providers, further supported by their availability in both over-the-counter and prescription formulations.
Capsaicin patches are expected to grow rapidly, witnessing a CAGR of 6.7% over the forecast period. Capsaicin patches effectively manage pain from conditions such as osteoarthritis, neuropathy, and muscle injuries by depleting substance P, a neurotransmitter involved in pain signaling. With rising concerns over opioid risks, these non-invasive patches provide targeted relief with minimal side effects, enhancing patient compliance and driving their growing popularity in pain management.
Distribution Channel Insights
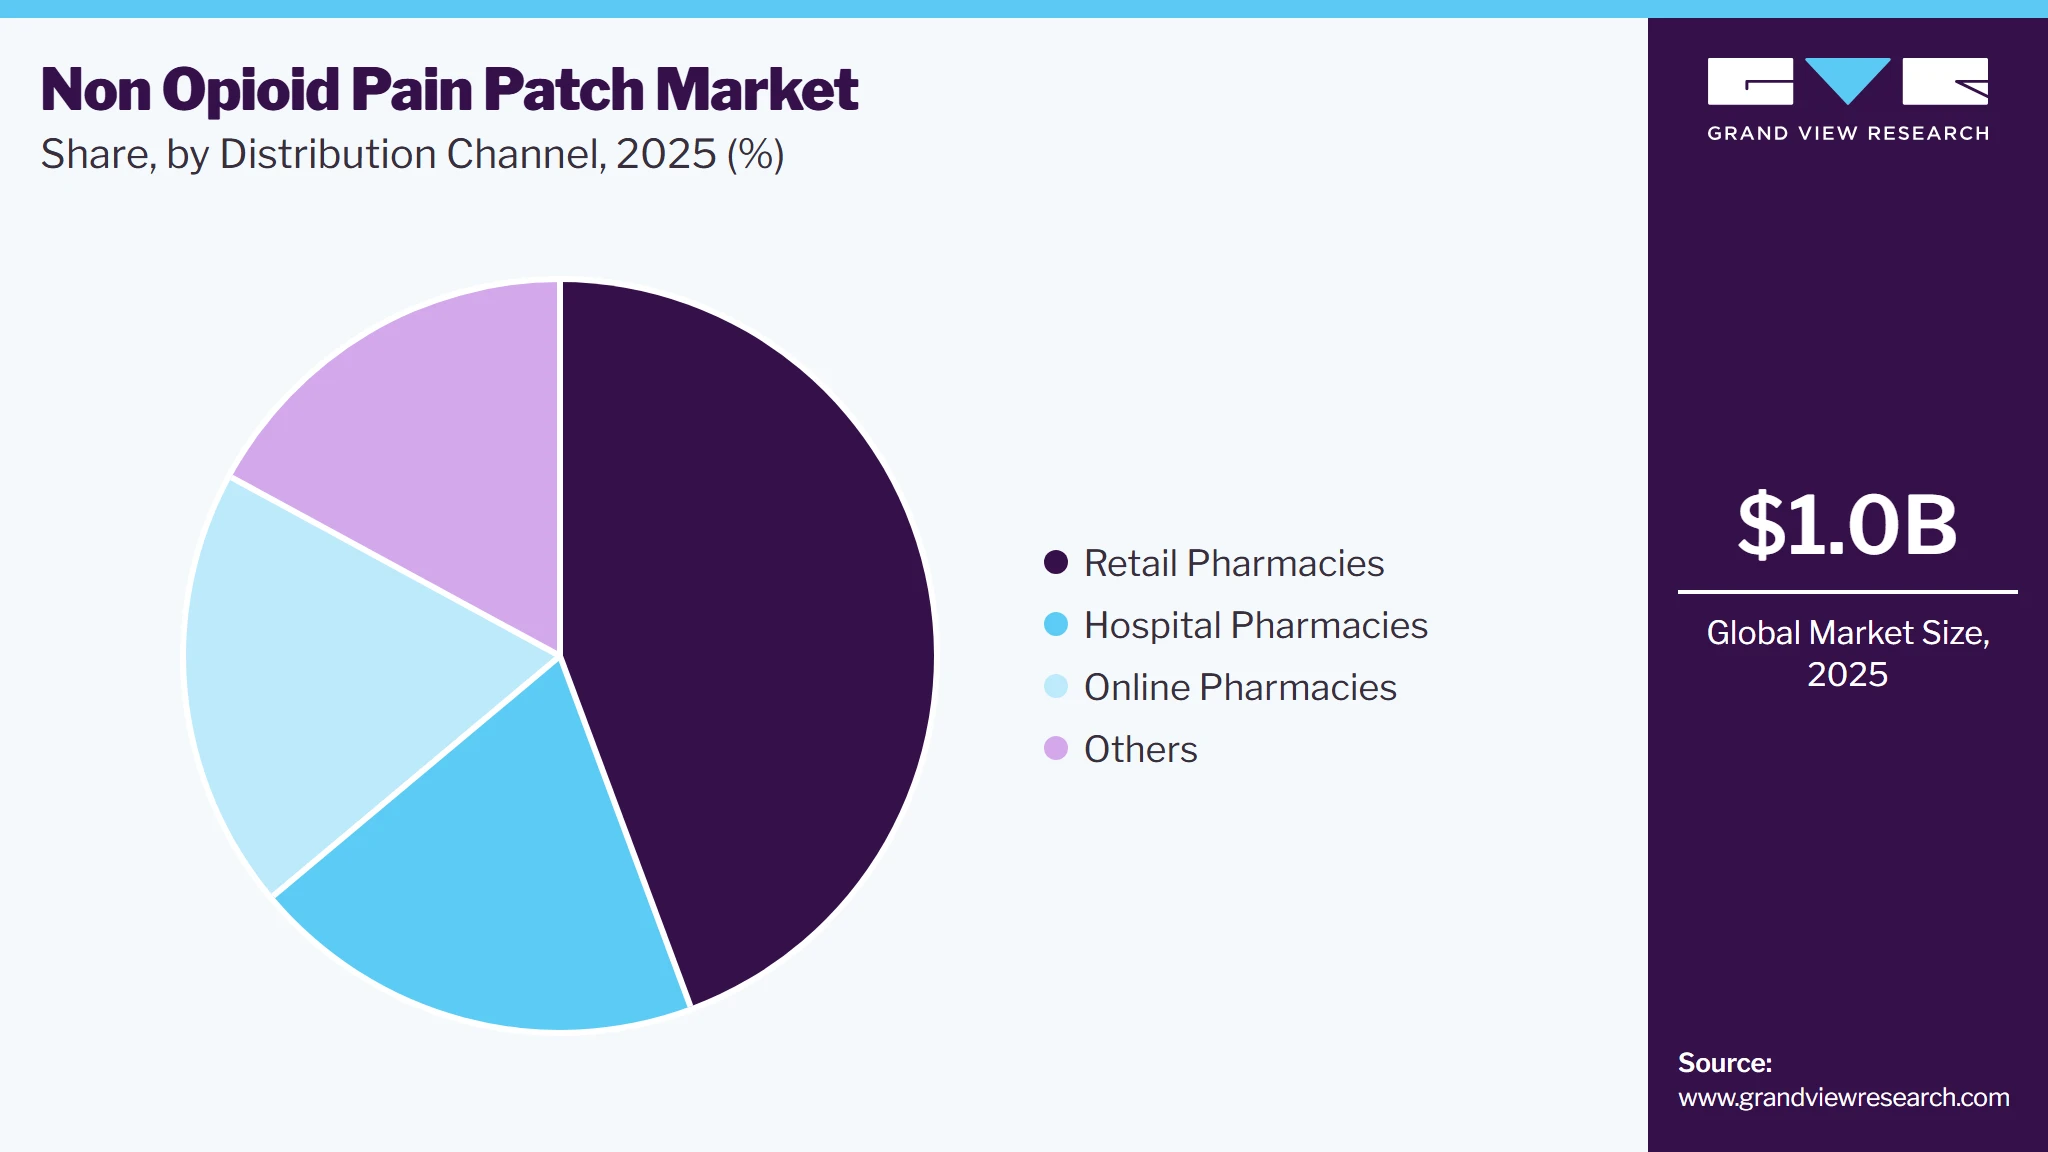
Based on distribution channel, the retail pharmacies segment led the market with the largest revenue share of 44.3% in 2025. A variety of non-opioid pain patches are available over-the-counter, enabling customers to purchase them without prescriptions. Retail pharmacies offer an extensive range of pain management products, catering to chronic pain sufferers and responding to heightened demand for safer alternatives amid the ongoing opioid crisis, thereby enhancing sales.
 To learn more about this report, Download Free Sample Report
Online pharmacies are projected to grow at the fastest CAGR of 8.1% over the forecast period. The digitization of healthcare enables patients to conveniently order non-opioid pain patches online, ensuring prompt delivery without the need for in-store visits. This benefits individuals with mobility challenges and offers a broader product selection and competitive pricing, promoting safer alternatives amid rising concerns about opioid addiction.
Regional Insights
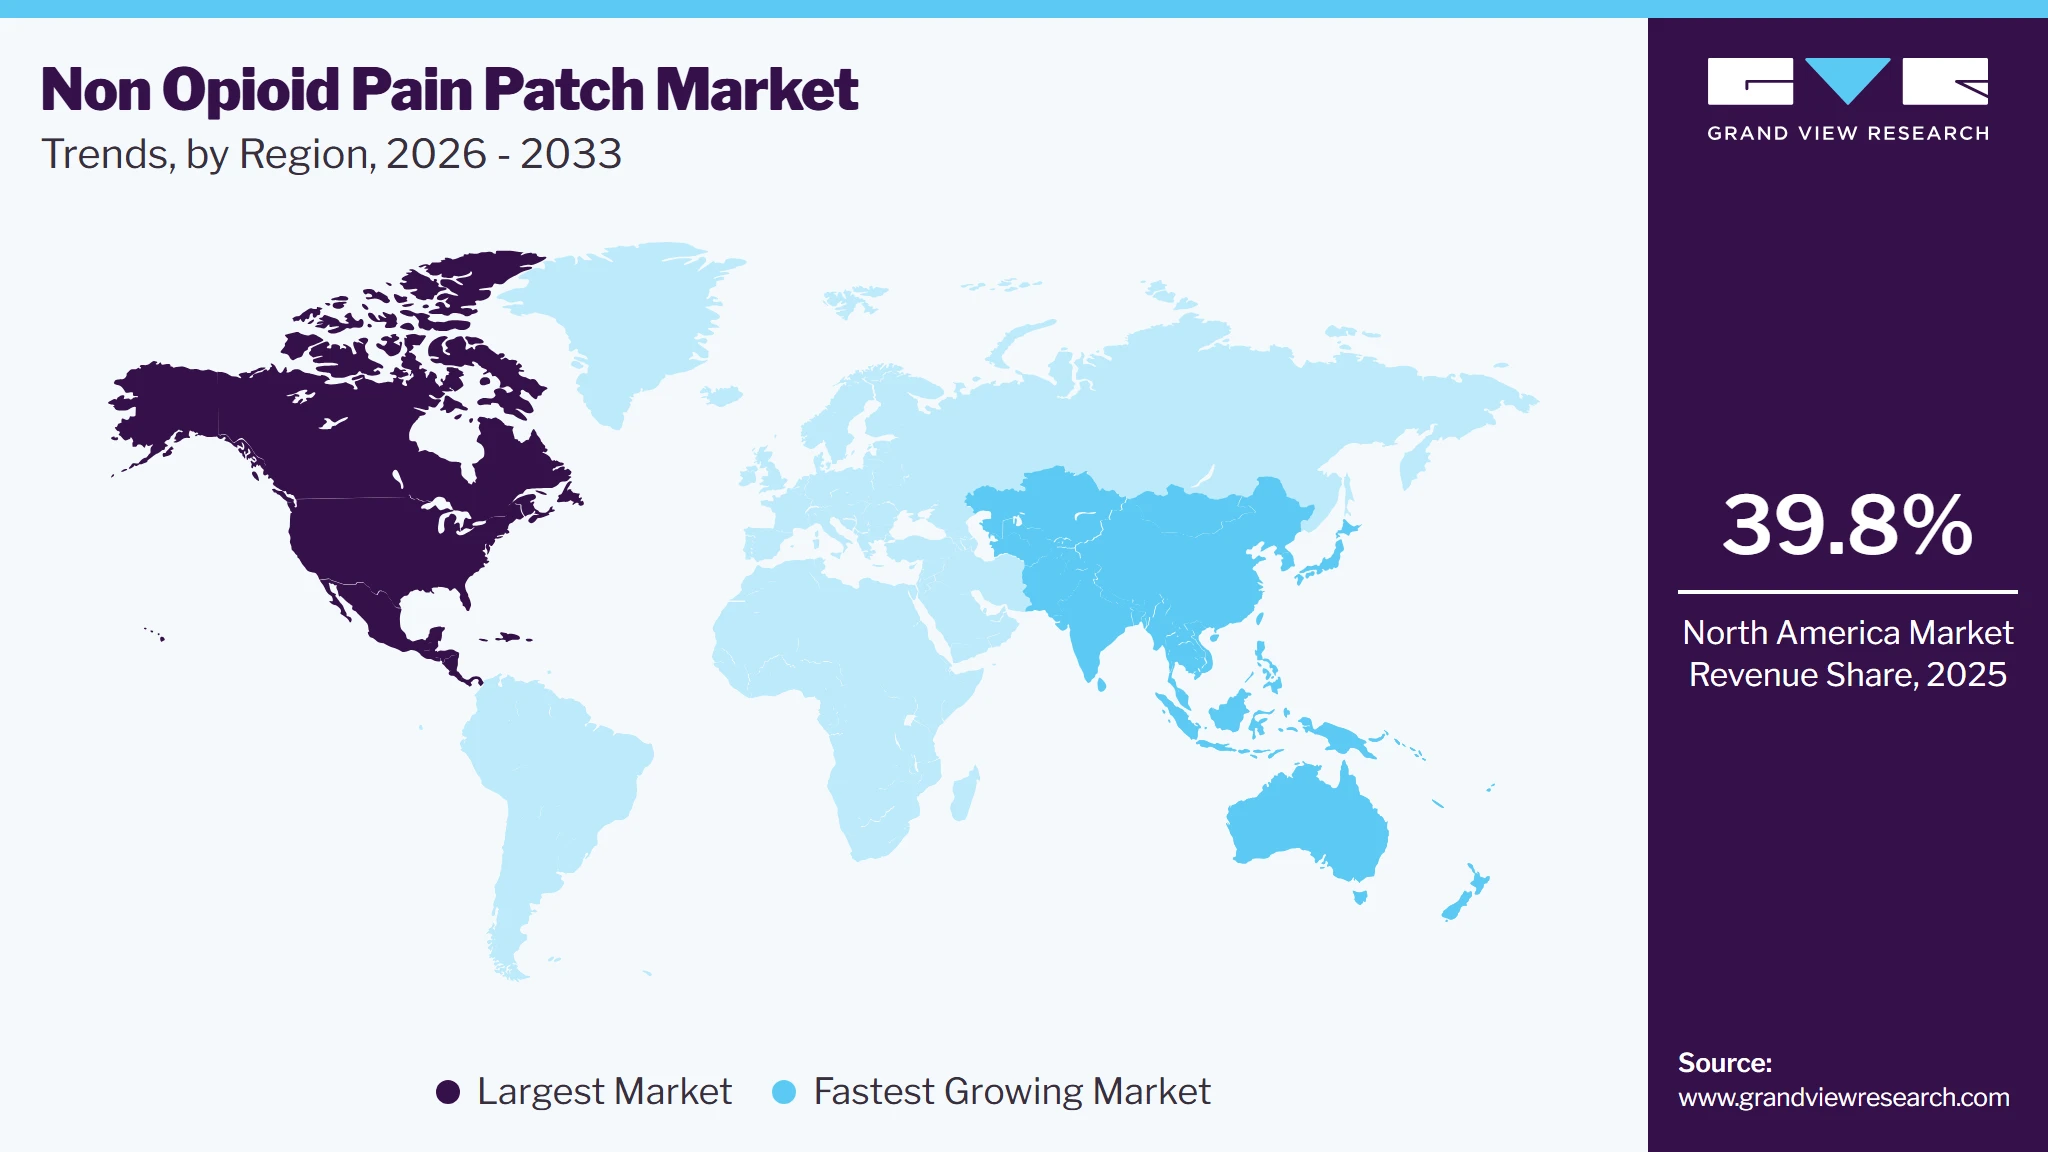
North America dominated the non-opioid pain patches market with the largest revenue share of 39.8% in 2025. North America is increasingly aware of the opioid crisis, highlighting the necessity for safer pain management alternatives. The prevalence of chronic pain conditions drives demand, while advancements in transdermal delivery technologies enhance efficacy, positioning non-opioid patches as a favored choice, supported by clinical guidelines advocating for their adoption.
 To learn more about this report, Download Free Sample Report
U.S. Non-opioid Pain Patches Market Trends
The non-opioid pain patches market in the U.S. held the largest share in the North America region in 2025. The alarming rise in opioid-related overdose statistics in the U.S. has driven healthcare providers to explore safer pain relief alternatives. Innovations such as lidocaine and diclofenac patches provide effective localized pain management, while increased accessibility through retail and online pharmacies supports consumer adoption amidst governmental initiatives to reduce opioid prescriptions.
Europe Non-opioid Pain Patches Market Trends
Europe non-opioid pain patches market held substantial market share in 2024. The rising awareness of opioid-related risks has spurred demand for non-opioid alternatives. Regulatory backing for innovative pain management, along with a focus on patient-centered care, fuels market expansion. Advancements in patch technology enhance efficacy for neuropathic and musculoskeletal pain, appealing to healthcare providers and patients.
The non-opioid pain patches market in Germany is expected to grow in the forecast period, driven by a strong healthcare system and a rising prevalence of chronic pain. The focus on innovative medical technologies fosters the adoption of advanced non-opioid patches, as healthcare professionals increasingly seek safer alternatives to opioid prescriptions.
Asia Pacific Non-opioid Pain Patches Market Trends
Asia Pacific non-opioid pain patches market is expected to register the fastest CAGR of 7.0% in the forecast period. Increasing urbanization and lifestyle changes are contributing to a rise in chronic pain conditions. Escalating healthcare expenditures and enhanced access to medical services are prompting patients to seek effective pain management solutions. The growth of e-commerce platforms facilitates access to non-opioid alternatives, driving research and development.
The non-opioid pain patches market in China is projected to grow at the fastest rate of 8.0% in the Asia Pacific market over the forecast period. The Chinese government’s initiatives to combat opioid abuse are driving a transition to safer pain management alternatives. Furthermore, advancements in pharmaceutical research have resulted in innovative non-opioid patch formulations that improve efficacy and patient compliance, while increased consumer acceptance of transdermal delivery systems fosters market growth.
Key Non-opioid Pain Patches Company Insights
Some key companies operating in the market include Acorda Therapeutics, Inc.; Teva Pharmaceutical Industries Ltd.; GSK plc; among others. The market comprises established pharmaceutical firms and emerging innovators in drug delivery systems, engaging in mergers, partnerships, and online distribution to enhance product efficacy and patient compliance.
-
Teva Pharmaceutical Industries Ltd. is a global company working in generic and specialty pharmaceuticals, producing transdermal patches that deliver medications such as lidocaine and diclofenac for localized pain relief, emphasizing innovation and accessibility in non-opioid pain management solutions for chronic conditions.
-
Endo, Inc. is focused on branded and generic pharmaceuticals, including non-opioid pain patches, utilizing transdermal delivery systems to manage neuropathic and musculoskeletal pain while prioritizing research and development to expand its safer, effective pain relief portfolio amidst rising opioid addiction concerns.
Key Non-opioid Pain Patches Companies
The following key companies have been profiled for this study on the non-opioid pain patches market.
-
Acorda Therapeutics, Inc.
-
Teva Pharmaceutical Industries Ltd.
-
GSK plc
-
Endo, Inc.
-
Hisamitsu Pharmaceutical Co., Inc.
-
IBSA Institut Biochimique SA
-
Alkermes
-
Teikoku Pharma
-
Mylan N.V.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Hisamitsu Pharmaceutical Co., Inc., Teva Pharmaceutical Industries Ltd., GSK plc, Endo, Inc., Teikoku Pharma)
- Focus on expanding non opioid pain patch portfolios through product development, formulation improvements, and geographic expansion.
- Strengthen market presence through established distribution networks, collaborations with healthcare providers, and continued investment in transdermal drug delivery technologies.
- Broad product portfolios supported by established manufacturing capabilities and regulatory experience.
- Strong relationships with healthcare providers, pharmacies, and distribution partners enable wide product availability across prescription and over the counter markets.
- High research, manufacturing, and regulatory compliance costs associated with product development.
- Dependence on mature product portfolios and established business processes may extend product development timelines and limit flexibility in responding to changing market demand.
Emerging Players (Acorda Therapeutics, Inc., IBSA Institut Biochimique SA, Alkermes, Mylan N.V.)
- Focus on expanding their presence through targeted product development, licensing agreements, and partnerships that strengthen pain management and transdermal drug delivery capabilities.
- Emphasize differentiated formulations and expansion into selected geographic markets to increase market presence.
- Ability to focus on selected therapeutic areas and introduce specialized products that address specific patient needs.
- Flexible business strategies support faster evaluation of partnership and portfolio expansion opportunities.
- More limited product portfolios and commercial reach compared with established companies.
- Smaller distribution networks and lower brand recognition may restrict market penetration in highly competitive regions and healthcare systems.
Recent Developments
-
In October 2024, Hisamitsu Pharmaceutical announced the initiation of clinical development for HP-3150, a transdermal diclofenac sodium patch for chronic lower back pain treatment in the U.S., using its advanced drug delivery technology.
-
In May 2024, Teikoku Pharma USA announced that the NMPA approved Lidoderm for treating Post Herpetic Neuralgia in China, following an exclusive licensing agreement with Link Healthcare Group since 2018.
Non-opioid Pain Patches Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 1.0 billion
Market size value in 2026
USD 1.1 billion
Revenue forecast in 2033
USD 1.6 billion
Growth rate
CAGR of 4.7% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Patch type, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Norway; Sweden; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait.
Key companies profiled
Acorda Therapeutics, Inc.; Teva Pharmaceutical Industries Ltd.; GSK plc; Endo, Inc.; Hisamitsu Pharmaceutical Co.,Inc.; IBSA Institut Biochimique SA; Alkermes; Teikoku Pharma; Mylan N.V.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Non-opioid Pain Patches Market Report Segmentation
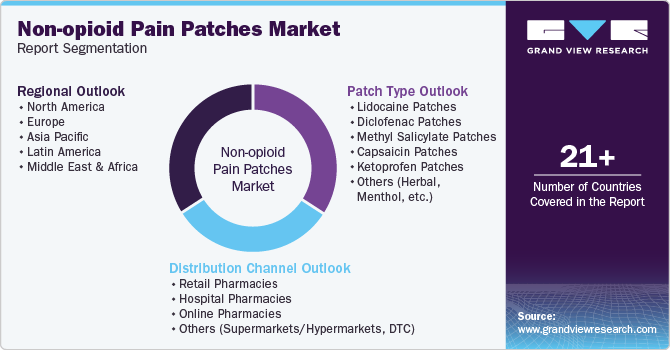
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global non-opioid pain patches market report based on patch type, distribution channel, and region:
 To learn more about this report, Download Free Sample Report
-
Patch Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Lidocaine Patches
-
Diclofenac Patches
-
Methyl Salicylate Patches
-
Capsaicin Patches
-
Ketoprofen Patches
-
Others (Herbal, Menthol, etc.)
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Retail Pharmacies
-
Hospital Pharmacies
-
Online Pharmacies
-
Others (Supermarkets/Hypermarkets, DTC)
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The non-opioid pain patches market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each non-opioid pain patches segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Patch Type
Revenue capture definition
Lidocaine Patches
Includes revenue generated from non-opioid pain patches containing lidocaine as the primary active pharmaceutical ingredient for localized pain relief through topical or transdermal administration. This segment excludes patches primarily classified under other active ingredient categories.
Diclofenac Patches
Includes revenue generated from non-opioid pain patches containing diclofenac as the primary active pharmaceutical ingredient for the treatment of localized musculoskeletal pain and inflammation. This segment excludes diclofenac products in non-patch dosage forms.
Methyl Salicylate Patches
Includes revenue generated from non-opioid pain patches containing methyl salicylate as the primary active ingredient for temporary relief of muscle and joint pain. This segment excludes products where another active ingredient is identified as the primary analgesic component.
Capsaicin Patches
Includes revenue generated from prescription and over the counter non opioid pain patches containing capsaicin as the primary active ingredient for the management of neuropathic pain and localized musculoskeletal pain. This segment excludes capsaicin products in non-patch dosage forms.
Ketoprofen Patches
Includes revenue generated from non-opioid pain patches containing ketoprofen as the primary active pharmaceutical ingredient for localized treatment of inflammatory and musculoskeletal pain. This segment excludes ketoprofen products available in oral and other topical dosage forms.
Others
Includes revenue generated from non-opioid pain patches containing active ingredients other than lidocaine, diclofenac, methyl salicylate, capsaicin, or ketoprofen. This segment includes herbal extracts, menthol, camphor, methyl nicotinate, and other analgesic ingredients marketed in patch formulations.
Segment - Distribution Channel
Revenue capture definition
Retail Pharmacies
Includes revenue generated from sales of non-opioid pain patches through chain pharmacies, independent pharmacies, and drug stores that dispense prescription and over the counter products directly to consumers.
Hospital Pharmacies
Includes revenue generated from sales of non-opioid pain patches through hospital pharmacy departments for inpatient and outpatient use under the supervision of healthcare professionals. This segment excludes products distributed through retail and online pharmacy channels.
Online Pharmacies
Includes revenue generated from sales of non-opioid pain patches through licensed online pharmacies and digital pharmacy platforms that supply prescription and over the counter products directly to consumers.
Others
Includes revenue generated from sales of non-opioid pain patches through supermarkets, hypermarkets, convenience stores, direct to consumer brand websites, and other authorized distribution channels not classified under retail pharmacies, hospital pharmacies, or online pharmacies.
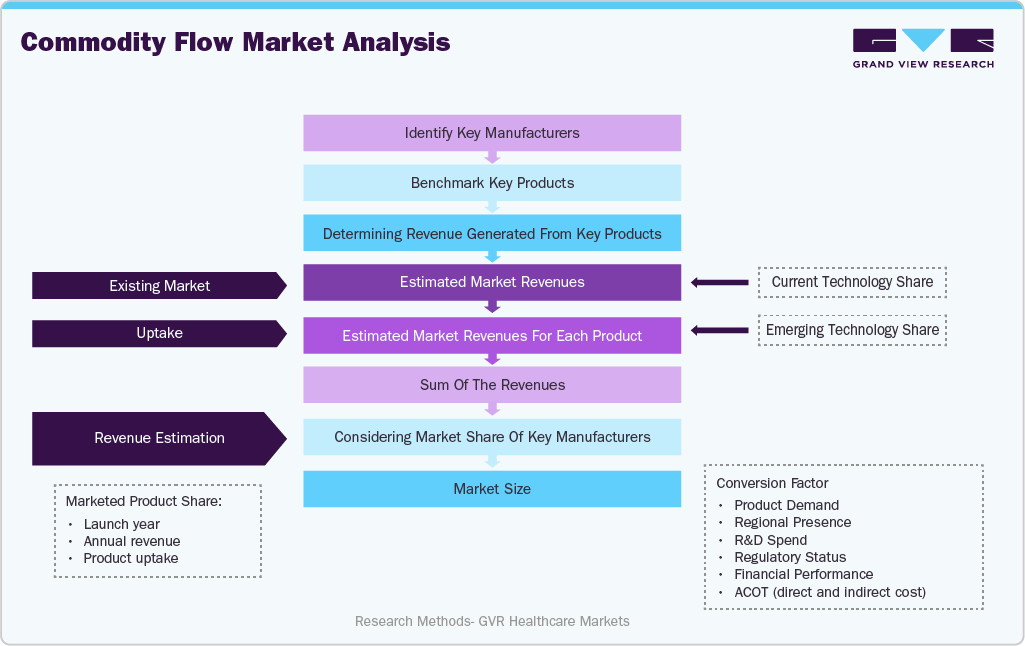
Estimation Model
 To learn more about this report, Download Free Sample Report
The global non opioid pain patches market was estimated using a commodity flow market analysis approach. Key manufacturers of non-opioid pain patches were identified, and their marketed products were benchmarked based on active ingredients, product type, pricing, distribution channels, regulatory approvals, and regional availability. Revenue generated from major prescription and over the counter pain patch products was estimated using company annual reports, investor presentations, regulatory filings, product portfolios, and industry publications. Market estimates were validated by evaluating product demand across retail pharmacies, hospital pharmacies, online pharmacies, and other distribution channels. Product availability, average selling prices, prescription trends, and over the counter sales patterns were considered to estimate regional demand. The revenues generated from key manufacturers were aggregated and adjusted by considering the market share of leading participants, product availability, geographic presence, and distribution coverage to estimate the overall market size.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Non-opioid Pain Patches Competitive Landscape & Portfolio Assessment
Conducted a detailed assessment of the global non-opioid pain patches market, evaluating marketed products, product portfolios, active pharmaceutical ingredients, patch technologies, clinical positioning, and competitive strategies. The study analyzed key participants including Hisamitsu Pharmaceutical Co., Inc., Teva Pharmaceutical Industries Ltd., Teikoku Pharma, Endo, Inc., GSK plc, IBSA Institut Biochimique SA, Acorda Therapeutics, Inc., Alkermes, and Mylan N.V., along with their product offerings and market positioning across prescription and over the counter pain patches.
Helped the client identify key competitors, evaluate product differentiation, benchmark transdermal technologies, and assess portfolio gaps to support product development, licensing, and market expansion strategies.
Non-opioid Pain Patches Technology & Product Benchmarking Study
Delivered a comprehensive benchmarking assessment of non-opioid pain patch technologies, focusing on active ingredients, patch formulations, drug delivery technologies, product performance, regulatory approvals, and manufacturing capabilities. The study compared marketed products based on formulation characteristics, application duration, treatment indications, and product positioning across major manufacturers.
Enabled the client to compare competing products, identify technology gaps, evaluate formulation strategies, and support product development decisions for new and existing non-opioid pain patch products.
Non-opioid Pain Patches Manufacturing & Supply Chain Assessment
Conducted an assessment of the manufacturing and supply chain ecosystem for non-opioid pain patches, evaluating raw material suppliers, transdermal patch manufacturing capabilities, contract development and manufacturing organizations, regulatory compliance requirements, packaging processes, and distribution networks supporting global supply. The study also assessed manufacturing capacity and supplier capabilities across key markets.
Supported manufacturing and supply chain planning by identifying qualified manufacturing partners, evaluating supplier capabilities, assessing distribution channels, and strengthening production planning to support long term business growth across global markets.
Frequently Asked Questions About This Report
The non-opioid pain patches market is driven by the increasing preference for non-opioid pain management, rising prevalence of musculoskeletal disorders and arthritis, growing adoption of topical drug delivery systems, advancements in transdermal patch technologies, expanding availability of over-the-counter pain patches, and increasing awareness of opioid-related risks.
North America dominated the global non-opioid pain patches market with a 39.8% revenue share in 2025, supported by strong adoption of topical analgesics, advanced healthcare infrastructure, and growing initiatives to reduce opioid dependence.
Asia Pacific is expected to be the fastest-growing regional market during the forecast period due to rising healthcare spending, increasing prevalence of chronic pain conditions, growing geriatric population, and improving access to advanced pain management therapies.
The retail pharmacies segment held the largest revenue share of 44.3% in 2025, driven by widespread availability of prescription and over-the-counter pain patches and strong consumer preference for pharmacy-based purchases.
Major trends include advances in transdermal drug delivery technologies, development of improved adhesive and controlled-release patch formulations, increasing demand for self-administered pain management products, expansion of over-the-counter pain patch offerings, and continued investment in non-opioid analgesic research.
The lidocaine patches segment accounted for the largest revenue share of 35.0% in 2025, driven by its widespread use in treating localized neuropathic pain, musculoskeletal pain, and post-herpetic neuralgia.
Key players in the non-opioid pain patches market include Acorda Therapeutics, Inc., Teva Pharmaceutical Industries Ltd., GSK plc, Endo, Inc., Hisamitsu Pharmaceutical Co., Inc., IBSA Institut Biochimique SA, Alkermes, Teikoku Pharma, and Mylan N.V.
The global non-opioid pain patches market size was valued at USD 1.0 billion in 2025 and is estimated at USD 1.1 billion in 2026.
The global non-opioid pain patches market is expected to grow at a CAGR of 4.7% from 2026 to 2033, reaching USD 1.6 billion by 2033.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


