
- Home
- »
- Pharmaceuticals
- »
-
Non-small Cell Lung Cancer Therapeutics Market Report 2033GVR Report cover

Non-small Cell Lung Cancer Therapeutics Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Squamous Cell Carcinoma, Large Cell Carcinoma, Adenocarcinoma), By Treatment (Chemotherapy, Immunotherapy), By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2025
$24.1BMarket Estimate, 2026
$27.1BMarket Forecast, 2033
$63.5BCAGR, 2026–2033
12.9%Non-small Cell Lung Cancer Therapeutics Market Summary
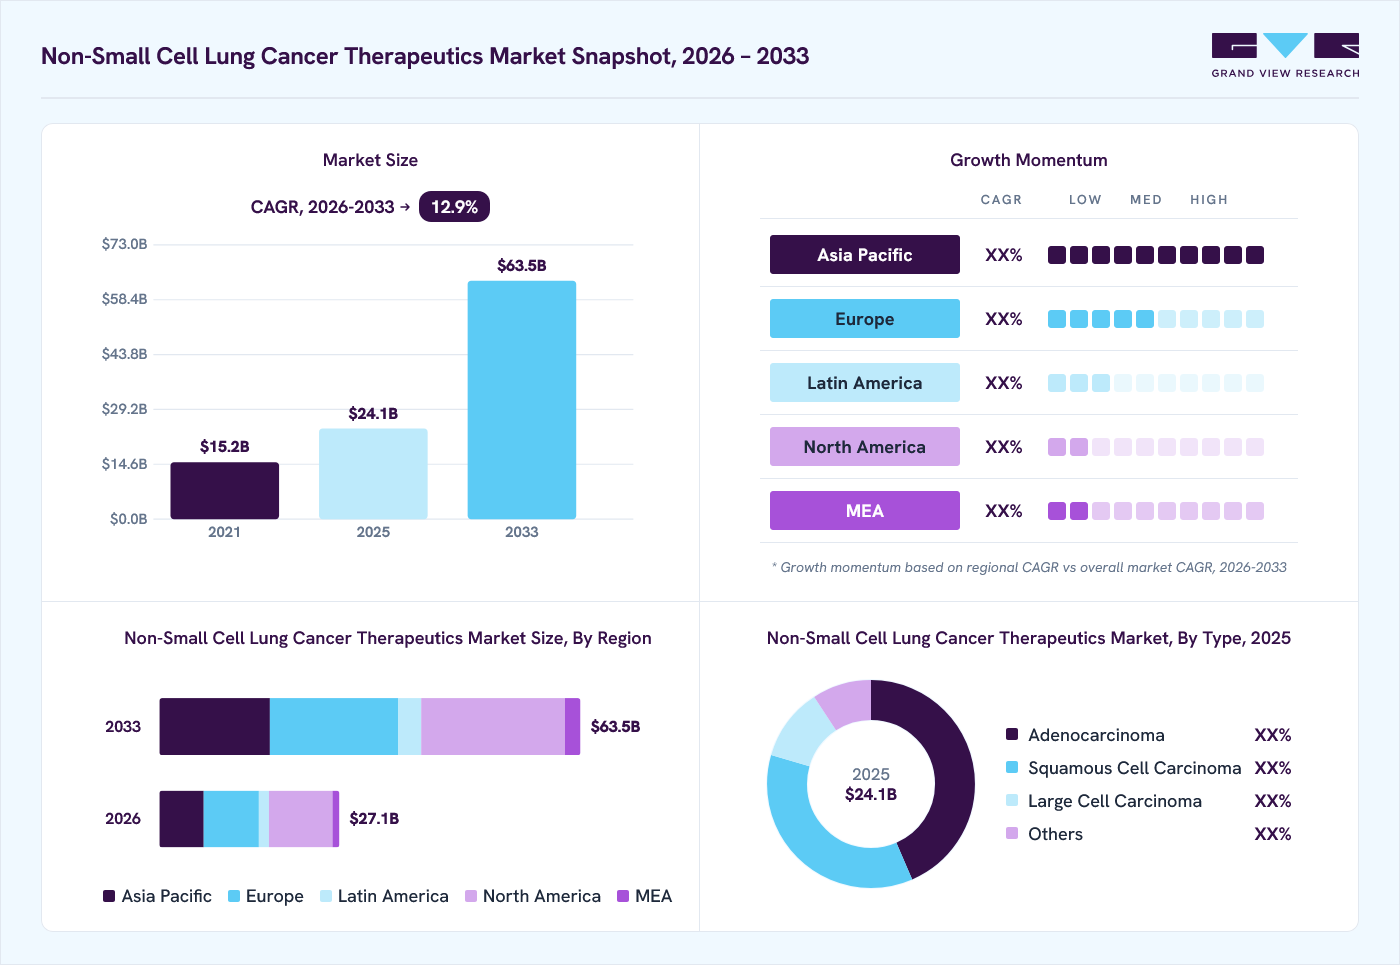
The global non-small cell lung cancer therapeutics market size was valued at USD 24.1 billion in 2025 and is projected to grow from USD 27.1 billion in 2026 to USD 63.5 billion by 2033, at a CAGR of 12.9% from 2026 to 2033. North America dominated the market, accounting for the largest revenue share of 35.4% in 2025. NSCLC remains the most common form of lung cancer, accounting for nearly 85% of all lung cancer cases worldwide.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: The adenocarcinoma segment held the highest market share of 43.5% in 2025.
- By treatment: The targeted therapy segment held the highest market share of 50.8% in 2025.
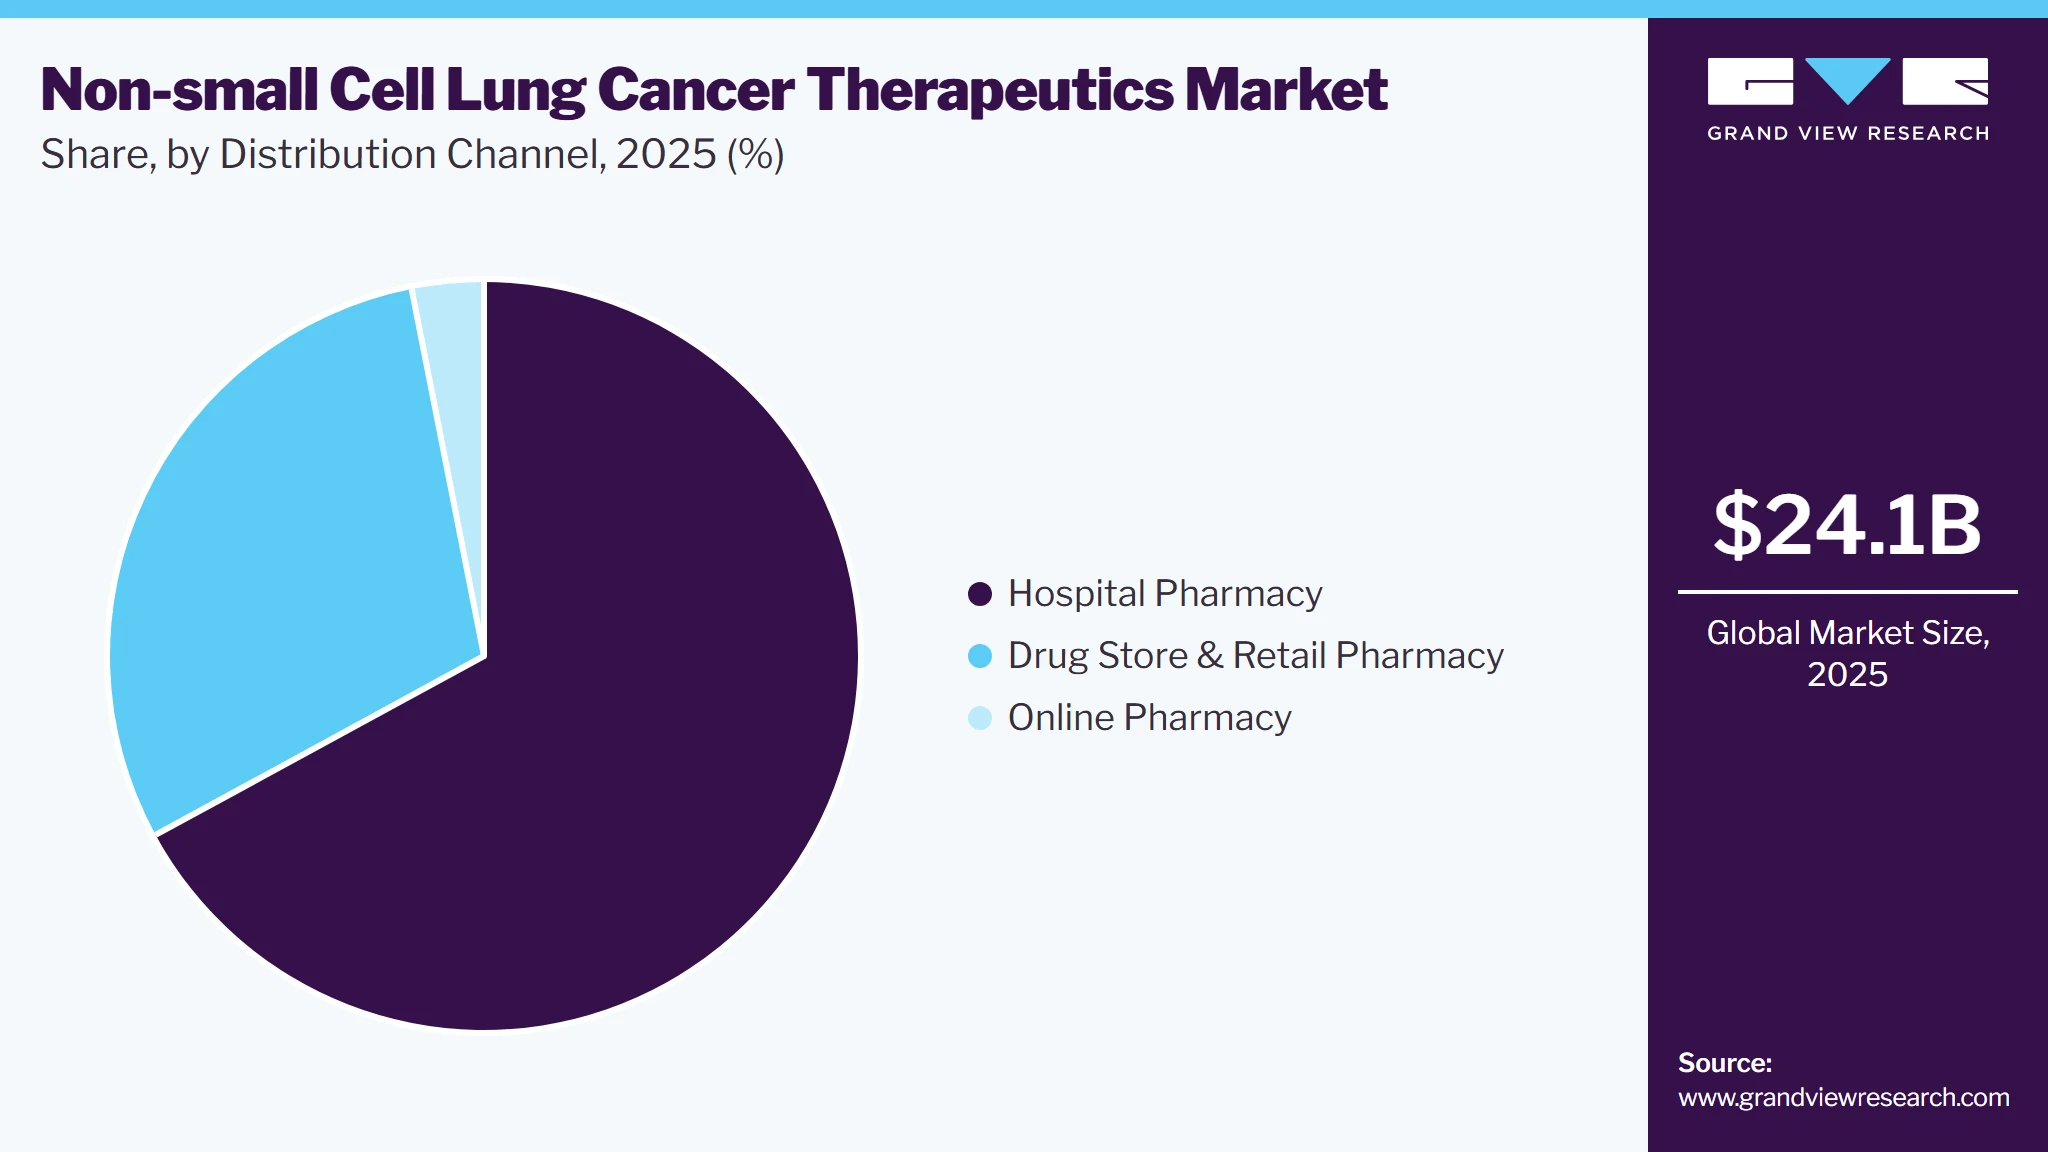
- By distribution channel: The hospital pharmacy segment held the highest market share of 67.1% in 2025.
Regional Highlights
- Largest regional market: North America (35.4% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 24.1 Billion
- Estimated market size in 2026: USD 27.1 Billion
- Projected market size in 2033: USD 63.5 Billion
- CAGR (2026-2033): 12.9%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The treatment landscape has shifted from conventional chemotherapy toward targeted therapies and immune checkpoint inhibitors, supported by updated clinical guidelines and broader molecular profiling in routine practice. Earlier diagnosis through screening programs in selected countries is also increasing the number of patients receiving treatment at earlier disease stages. However, treatment costs, unequal access to molecular diagnostics, and differences in healthcare infrastructure across regions continue to affect therapy adoption. Ongoing clinical research and regulatory approvals are expanding treatment options and supporting sustained market development.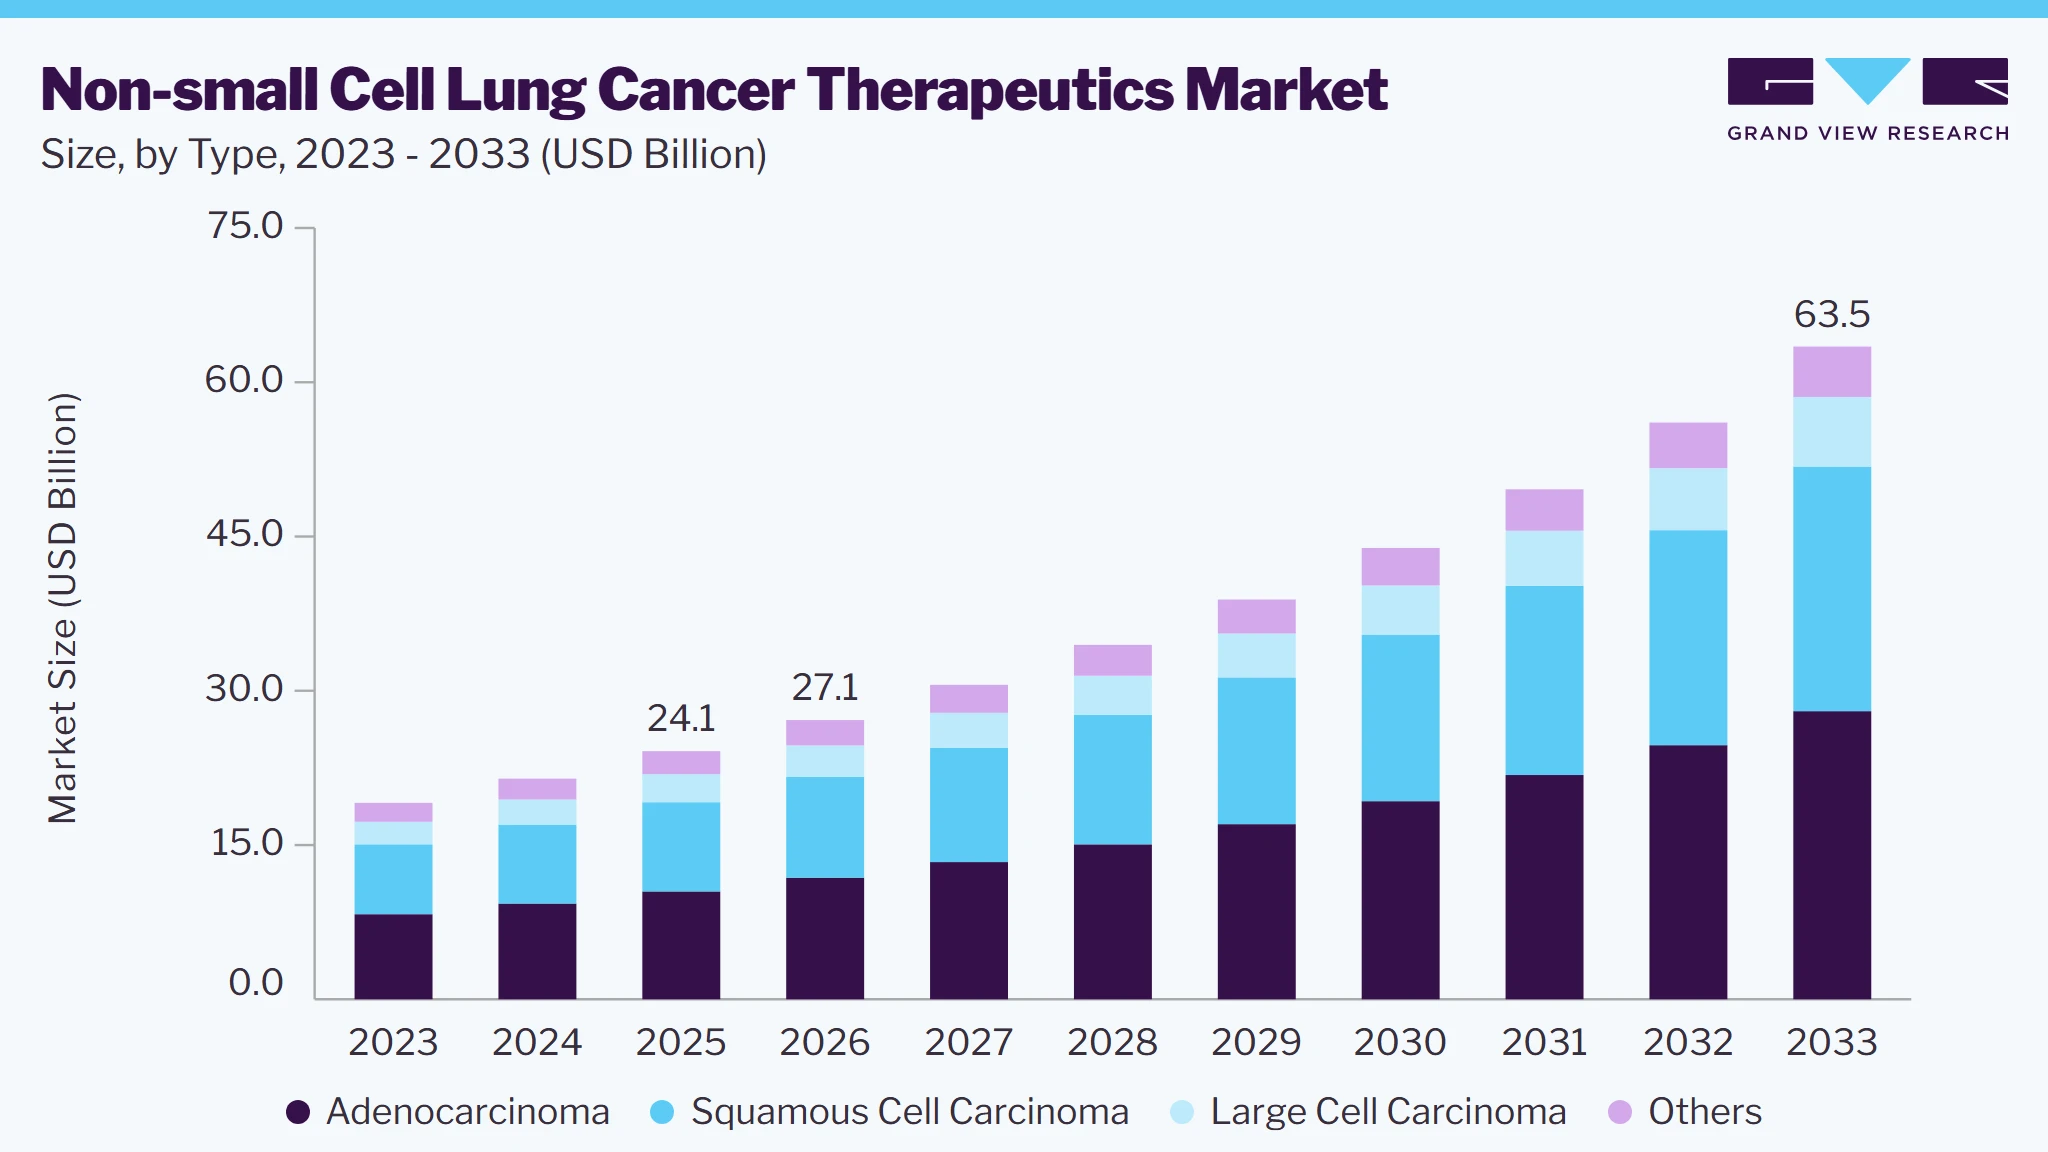 To learn more about this report, Download Free Sample Report
Market Dynamics
The industry is supported by increasing adoption of biomarker testing, which enables the selection of targeted therapies based on genetic alterations such as epidermal growth factor receptor (EGFR), anaplastic lymphoma kinase (ALK), ROS proto-oncogene 1 receptor tyrosine kinase (ROS1), B-Raf proto-oncogene, serine/threonine kinase (BRAF), mesenchymal-epithelial transition factor (MET), rearranged during transfection (RET), Kirsten rat sarcoma viral oncogene homolog (KRAS), and neurotrophic tyrosine receptor kinase (NTRK) gene fusions.
The growing number of regulatory approvals for biomarker-targeted therapies is a key factor supporting the NSCLC therapeutics industry. Advances in molecular diagnostics have enabled physicians to identify actionable genetic alterations and prescribe therapies for specific patient populations. This approach has improved treatment selection and increased the use of precision medicine across different stages of NSCLC. Pharmaceutical companies are continuing to develop therapies targeting epidermal growth factor receptor (EGFR), human epidermal growth factor receptor 2 (HER2), anaplastic lymphoma kinase (ALK), ROS proto-oncogene 1 receptor tyrosine kinase (ROS1), and other genomic alterations. In parallel, the availability of companion diagnostic tests is supporting broader biomarker testing before treatment initiation. Clinical guidelines increasingly recommend comprehensive genomic profiling for patients with advanced NSCLC, contributing to higher adoption of targeted therapies in routine clinical practice. The continuous expansion of approved indications is also providing additional treatment options for patients whose disease progresses after initial therapy, supporting sustained demand for innovative therapeutics.
The cost of treating non-small cell lung cancer remains a major challenge for healthcare systems and patients, particularly in low- and middle-income countries. Targeted therapies and immune checkpoint inhibitors require substantial healthcare expenditure, while repeated biomarker testing and disease monitoring further increase overall treatment costs. Access to next-generation sequencing and other molecular diagnostic tests is still limited in many regions because of inadequate laboratory infrastructure, a shortage of trained specialists, and uneven reimbursement policies. As a result, many patients begin treatment without complete biomarker profiling, reducing opportunities to receive mutation-specific therapies. Differences in regulatory pathways, healthcare funding, and availability of specialized oncology centers also contribute to variations in treatment access across countries. In addition, acquired resistance to targeted therapies often requires sequential treatments, increasing long-term therapy costs and placing additional pressure on healthcare budgets. These factors continue to limit the adoption of newer therapies despite ongoing progress in precision oncology, particularly in healthcare systems with constrained financial resources and limited access to advanced diagnostic technologies.
Strategic mergers, acquisitions, and licensing agreements are creating opportunities for companies to strengthen their NSCLC portfolios and accelerate global commercialization of innovative therapies. Large pharmaceutical companies are expanding access to late-stage targeted therapies by acquiring products from biotechnology firms with specialized oncology pipelines. These transactions enable companies to broaden their precision oncology portfolios, improve geographic reach, and support faster regulatory submissions across multiple regions. Licensing agreements also help developers increase manufacturing capacity, expand commercialization networks, and invest in additional clinical studies for new indications. As more therapies targeting rare genetic alterations reach late-stage development, collaborations between global pharmaceutical companies and biotechnology developers are expected to increase. These activities are supporting continued innovation while improving patient access to targeted treatments across different healthcare markets.
Market Concentration & Characteristics
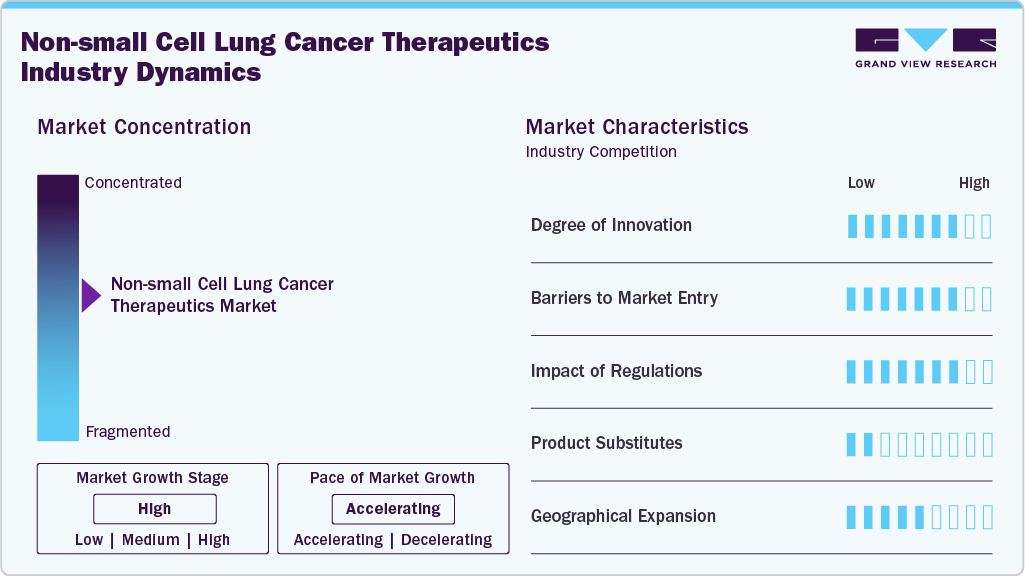
The degree of innovation remained high because the treatment approach for non-small cell lung cancer continues to shift from broad chemotherapy to precision medicine. Pharmaceutical companies are developing targeted therapies for newly identified genetic alterations and expanding the use of immune checkpoint inhibitors through combination regimens. Clinical research is also focused on antibody-drug conjugates, bispecific antibodies, and therapies designed for patients who develop resistance after earlier treatments. Advances in biomarker testing and next-generation sequencing are supporting the identification of eligible patients for these therapies. Companies are also conducting clinical studies to move targeted therapies into earlier stages of disease and evaluate their use before or after surgery. These activities continue to increase treatment options and support the development of therapies for patient populations with different molecular profiles.
The barriers to market entry remained high because developing therapies for non-small cell lung cancer requires long research timelines, multiple phases of clinical studies, and regulatory review before commercialization. Companies must also identify appropriate biomarkers, develop or partner for companion diagnostic tests, and demonstrate safety and efficacy in specific patient populations. Manufacturing targeted therapies and biologic products requires specialized facilities and quality control systems that increase development costs. In addition, competition from established pharmaceutical companies with approved products and ongoing clinical programs makes market entry more difficult for new participants. Companies entering the market also need access to oncology research networks, healthcare providers, and treatment centers to support clinical development and product adoption after regulatory approval.
 To learn more about this report, Download Free Sample Report
The impact of regulations remained high because regulatory agencies require evidence on safety, efficacy, and biomarker-based patient selection before approving new therapies for non-small cell lung cancer. Many targeted therapies are approved together with companion diagnostic tests to ensure treatment is provided to patients with the appropriate genetic alteration. Regulatory authorities also require post-marketing studies for some accelerated approvals to confirm long-term clinical benefit. Changes in clinical guidelines and regulatory requirements influence treatment adoption and product development strategies. Companies must maintain compliance with manufacturing standards, pharmacovigilance requirements, and labeling updates throughout the product lifecycle. Regulatory support for therapies addressing unmet medical needs has also encouraged continued investment in precision oncology while maintaining defined approval standards.
The availability of product substitutes remained low because treatment decisions for non-small cell lung cancer are based on disease stage, biomarker status, previous therapy, and individual patient characteristics. A therapy developed for one genetic alteration cannot generally replace a therapy designed for another mutation because each targets a different biological pathway. Although chemotherapy, immunotherapy, targeted therapy, surgery, and radiation therapy are all used in clinical practice, they serve different roles depending on the patient's diagnosis and treatment stage. Clinical guidelines and molecular testing further support the selection of therapies based on specific biomarkers rather than allowing direct substitution between products. As more mutation-specific therapies become available, treatment continues to become more personalized instead of interchangeable.
The geographical expansion remained moderate because pharmaceutical companies continue to obtain regulatory approvals and introduce therapies across North America, Europe, Asia Pacific, Latin America, and the Middle East. Expansion is supported by increasing availability of molecular diagnostic testing, growing oncology infrastructure, and rising awareness of precision medicine in many countries. However, the rate of expansion differs across regions because access to biomarker testing, reimbursement policies, healthcare spending, and availability of specialized treatment centers are not uniform. Companies often prioritize launches in countries with established regulatory pathways and advanced oncology care before expanding into developing markets. Partnerships with regional companies and healthcare providers also support product availability while helping manufacturers strengthen their presence in new geographic markets.
Analyst Perspective
The non-small cell lung cancer therapeutics market is shifting toward precision medicine with increasing use of biomarker-guided treatment and targeted therapies. Continued expansion of immunotherapy, broader molecular testing, and development of therapies for additional genetic alterations are improving treatment options. Future market growth will depend on innovation, timely diagnosis, and wider access to personalized cancer care.
Type Insights
The adenocarcinoma segment accounted for 43.5% of the market share in 2025 because adenocarcinoma is the most common histological subtype of non-small cell lung cancer and has a higher frequency of actionable genetic alterations, including epidermal growth factor receptor (EGFR), anaplastic lymphoma kinase (ALK), ROS proto-oncogene 1 receptor tyrosine kinase (ROS1), and human epidermal growth factor receptor 2 (HER2). The availability of targeted therapies and immune checkpoint inhibitors has expanded treatment options for these patients. Routine use of comprehensive biomarker testing, updated clinical guidelines recommending molecular profiling, increasing adoption of precision medicine, and continuous expansion of targeted therapy indications have further supported the segment. In addition, ongoing clinical research continues to introduce therapies for patients with resistant mutations. For instance, in August 2025, Boehringer Ingelheim received the U.S. FDA accelerated approval for zongertinib for adults with unresectable or metastatic non-squamous NSCLC with HER2 tyrosine kinase domain activating mutations after prior systemic therapy.
The Squamous Cell Carcinoma (SCC) segment is projected to register the fastest CAGR of 13.5% over the forecast period. The segment is expanding as treatment options for squamous NSCLC continue to move beyond conventional chemotherapy with the wider use of immunotherapy and combination treatment approaches. Ongoing clinical studies evaluating antibody-drug conjugates, bispecific antibodies, and novel immunotherapy combinations are creating additional treatment opportunities for this patient population. Improvements in molecular profiling and biomarker research are supporting the identification of new therapeutic targets in selected SCC patients. Growing participation in clinical trials, increasing availability of new systemic therapies, and broader adoption of personalized treatment strategies are expected to support continued growth during the forecast period.
Treatment Insights
The targeted therapy segment accounted for 50.8% of the market share in 2025 due to the targeted therapies providing treatment based on specific genetic alterations identified through molecular testing, enabling a personalized treatment approach. Increasing use of comprehensive biomarker testing, wider availability of therapies targeting epidermal growth factor receptor (EGFR), anaplastic lymphoma kinase (ALK), ROS proto-oncogene 1 receptor tyrosine kinase (ROS1), mesenchymal-epithelial transition factor (MET), rearranged during transfection (RET), and Kirsten rat sarcoma viral oncogene homolog (KRAS), expansion of approved indications, growing adoption of next-generation sequencing, and updated clinical guidelines recommending precision medicine have supported the segment. Continued development of therapies for resistant mutations has further strengthened treatment options and increased physician adoption. For instance, in June 2025, Daiichi Sankyo, Inc. received the U.S. FDA accelerated approval for datopotamab deruxtecan-dlnk for adults with locally advanced or metastatic EGFR-mutated NSCLC after prior EGFR-directed therapy and platinum-based chemotherapy.
The chemotherapy segment is expected to witness significant growth, registering a CAGR of 13.8% over the forecast period. The segment is expanding due to its continued use in combination with immunotherapies and targeted therapies across different stages of non-small cell lung cancer. Increasing adoption of platinum-based combination regimens, wider use in neoadjuvant and adjuvant treatment settings, growing diagnosis of advanced-stage disease, expanding clinical evidence supporting combination approaches, and continued inclusion in treatment guidelines are contributing to future demand. In addition, ongoing clinical studies evaluating chemotherapy with novel targeted therapies and immune checkpoint inhibitors are expected to improve treatment outcomes and expand their role across broader patient populations. These factors are expected to support the continued growth of the chemotherapy segment throughout the forecast period.
Distribution Channel Insights
The hospital pharmacy segment accounted for 67.1% of the market share in 2025 as most non-small cell lung cancer therapies, including targeted therapies, immunotherapies, and combination regimens, are initiated and monitored in hospital-based oncology centers. Hospitals provide access to oncologists, molecular diagnostic testing, infusion facilities, multidisciplinary care, and management of treatment-related adverse events. Many newly approved therapies require physician supervision, scheduled administration, and continuous patient monitoring, making hospital pharmacies the primary distribution channel. In addition, hospitals maintain direct procurement agreements with pharmaceutical manufacturers, ensure the timely availability of specialty oncology medicines, and support adherence to treatment protocols. These factors continue to strengthen the role of hospital pharmacies in delivering advanced NSCLC therapies and maintaining continuity of patient care.
 To learn more about this report, Download Free Sample Report
The drug store and retail pharmacy segment is expected to witness significant growth, registering a CAGR of 12.3% over the forecast period. The segment is expanding due to the increasing availability of oral targeted therapies, enabling patients to receive long-term treatment outside hospital settings. Growing use of specialty pharmacy services, expanding distribution networks, increasing availability of oncology medicines through organized retail pharmacies, and rising preference for home-based treatment continue to support this growth. The expansion of patient support programs, digital prescription management, and improved coordination between healthcare providers and pharmacies further enhances access to oral cancer therapies through retail channels. In addition, the increasing number of patients receiving maintenance therapy over extended periods is expected to drive prescription refills through retail pharmacies.
Regional Insights
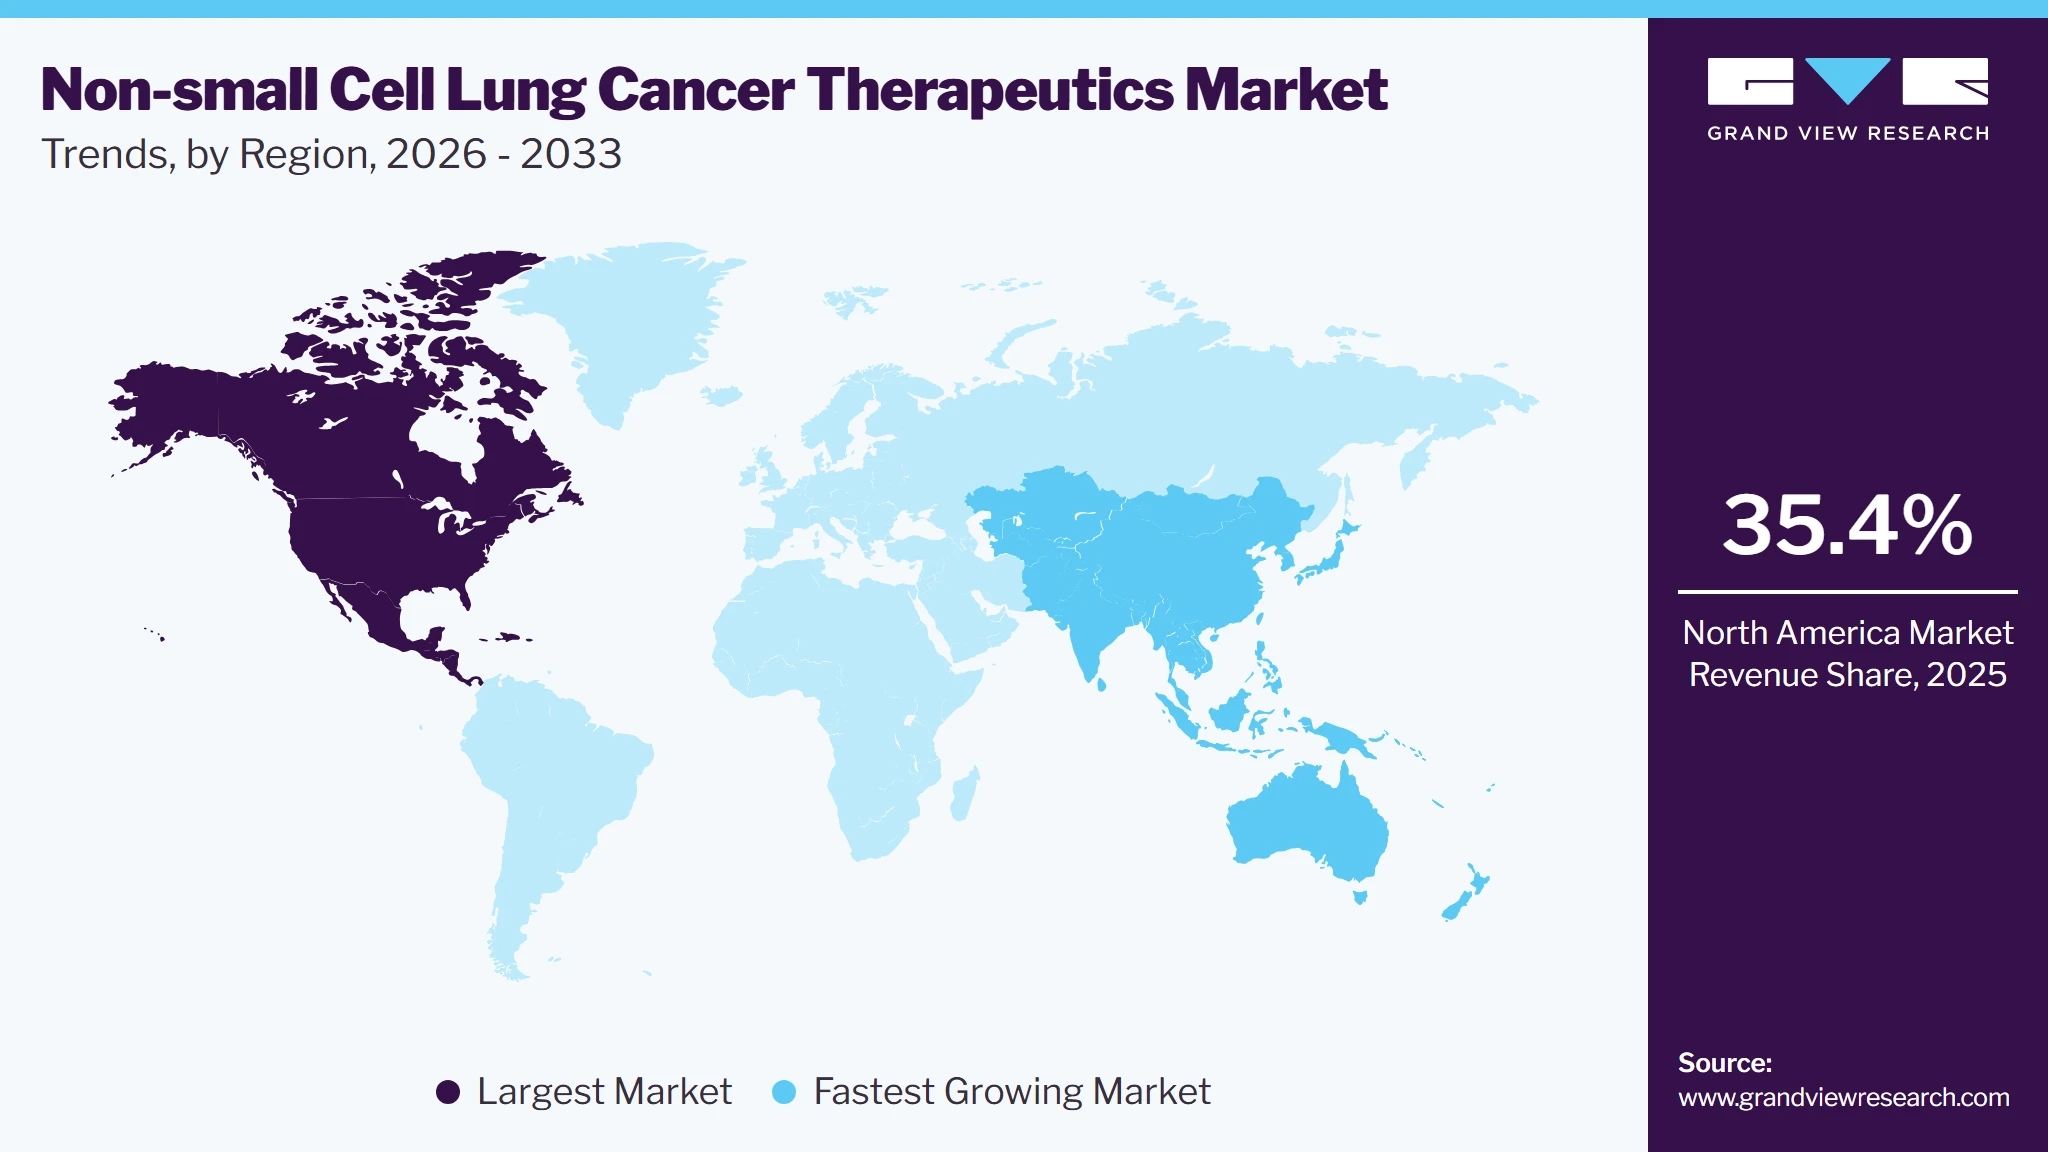
The North America non-small cell lung cancer therapeutics market dominated with a share of 35.4% in 2025. The region benefits from broad adoption of biomarker testing, increasing use of targeted therapies, and established oncology treatment networks. High utilization of molecular diagnostics supports personalized treatment selection across different stages of disease. Pharmaceutical companies continue to expand clinical development activities and introduce new treatment options through regional launches. The presence of specialized cancer centers improves access to advanced therapies and multidisciplinary care. Rising use of immunotherapy and precision medicine continues to support regional market growth.
 To learn more about this report, Download Free Sample Report
U.S. Non-small Cell Lung Cancer Therapeutics Market Trends
The non-small cell lung cancer therapeutics market in the U.S. accounted for the largest share of North America as the country has a large number of patients receiving molecular profiling before treatment initiation, supporting greater use of targeted therapies. Continuous introduction of innovative oncology medicines expands available treatment options across multiple biomarker-defined patient groups. Strong adoption of next-generation sequencing improves identification of actionable mutations. Large academic cancer centers continue to participate in clinical research for new treatment approaches. Growing use of combination therapies further supports market expansion.
Europe Non-small Cell Lung Cancer Therapeutics Market Trends
The non-small cell lung cancer therapeutics market in Europe represents a significant regional market. Increasing use of precision oncology and routine biomarker testing continues to improve treatment selection across major healthcare systems. Expanding availability of targeted therapies and immunotherapies supports adoption in clinical practice. Collaboration between pharmaceutical companies and research institutions strengthens oncology drug development. Growing awareness of molecular diagnostics contributes to earlier identification of eligible patients. Continued expansion of oncology infrastructure supports regional demand.
The UK non-small cell lung cancer therapeutics market continues to expand with increasing use of personalized medicine for non-small cell lung cancer. Wider adoption of genomic testing improves patient selection for targeted treatment. Cancer centers continue integrating molecular diagnostics into routine clinical practice. Ongoing clinical research increases access to emerging treatment approaches for eligible patients. Growing use of immunotherapy across different treatment stages contributes to demand. Expansion of specialized oncology services supports continued market development.
The non-small cell lung cancer therapeutics market in Germany remains an important market in Europe. The country has well-established oncology centers with broad access to molecular diagnostic technologies. Increasing use of targeted therapies for biomarker-positive patients supports treatment adoption. Pharmaceutical companies continue conducting clinical studies through German research institutions. High availability of specialized healthcare professionals improves treatment management. Continued integration of precision medicine into oncology practice supports market growth.
The France non-small cell lung cancer therapeutics market continues to strengthen its position through increasing adoption of precision oncology. Growing use of molecular testing supports the identification of patients eligible for targeted therapies. Oncology centers continue expanding the use of immunotherapy across different treatment settings. Clinical research activities improve access to investigational therapies for selected patients. Collaboration between hospitals and pharmaceutical companies contributes to treatment availability. Continued improvement in oncology care supports market expansion.
Asia-Pacific Non-small Cell Lung Cancer Therapeutics Market Trends
The non-small cell lung cancer therapeutics market in Asia Pacific is projected to register the fastest CAGR of 13.9% during the forecast period. Increasing diagnosis of non-small cell lung cancer, expanding access to molecular testing, and rising adoption of targeted therapies continue to support market growth. Pharmaceutical companies are expanding their commercial presence across several countries in the region. Growing investment in oncology infrastructure improves access to advanced treatment options. Clinical research activities continue to increase across major Asian markets. Rising awareness of precision medicine contributes to future market expansion.
The Japan non-small cell lung cancer therapeutics market represents an established market in Asia Pacific. The country has extensive use of molecular testing for identifying actionable genetic alterations before treatment selection. High adoption of targeted therapies supports the management of biomarker-positive patients. Pharmaceutical companies continue evaluating new therapies through clinical research programs. Cancer treatment centers maintain broad access to advanced oncology medicines. Continued use of precision medicine supports steady market growth.
The non-small cell lung cancer therapeutics market in China continues to experience steady growth. Increasing cancer diagnoses and wider availability of molecular diagnostic testing support greater treatment adoption. Domestic and multinational pharmaceutical companies continue expanding targeted therapy portfolios. Clinical trial activity has increased across major oncology centers, improving access to new therapies. Expansion of specialty hospitals strengthens the delivery of advanced cancer care. Rising use of precision medicine continues to support market development.
Latin America Non-small Cell Lung Cancer Therapeutics Market Trends
The non-small cell lung cancer therapeutics market in Latin America is expanding with the increasing availability of targeted therapies and improved cancer diagnosis. More healthcare providers are adopting molecular testing to support personalized treatment decisions. Growth in specialty oncology centers improves patient access to advanced therapies. Pharmaceutical companies continue increasing their presence through broader product availability. Clinical awareness of biomarker-driven treatment continues to improve across the region.
The Brazil non-small cell lung cancer therapeutics market accounts for a significant share of Latin America. Expanding oncology services and increasing access to molecular diagnostic testing support greater use of targeted therapies. The growing availability of immunotherapy contributes to broader treatment options for eligible patients. Cancer treatment centers continue to adopt precision medicine into routine practice. Pharmaceutical companies continue expanding oncology product availability across the country. Continued improvement in specialized cancer care supports market growth.
Middle East & Africa Non-small Cell Lung Cancer Therapeutics Market Trends
The non-small cell lung cancer therapeutics market in the Middle East & Africa continues to develop, driven by improving access to oncology services and molecular diagnostic technologies. Increasing awareness of personalized treatment supports wider adoption of targeted therapies. Expansion of specialized cancer treatment centers improves the availability of advanced medicines. Pharmaceutical companies continue strengthening their regional oncology presence. Growing clinical experience with immunotherapy contributes to treatment adoption.
The Saudi Arabia non-small cell lung cancer therapeutics market represents a developing market in the region. Expansion of specialized oncology hospitals improves access to advanced cancer treatment. Increasing use of molecular diagnostic testing supports the selection of targeted therapies for eligible patients. Adoption of precision oncology continues to increase across major healthcare institutions. Pharmaceutical companies continue introducing innovative oncology products through regional commercialization activities. Continued development of cancer care services supports future market growth.
Key Non-small Cell Lung Cancer Therapeutics Company Insights
The non-small cell lung cancer therapeutics market is moderately concentrated, with competition led by global pharmaceutical companies offering targeted therapies, immunotherapies, and antibody-drug conjugates across different biomarker-defined patient populations. AstraZeneca PLC, Merck & Co., Inc., F. Hoffmann-La Roche Ltd., Bristol Myers Squibb, Johnson & Johnson, Pfizer Inc., Novartis AG, Eli Lilly and Company, GSK plc, and Boehringer Ingelheim maintain established positions through approved products and continued expansion of clinical indications. Competition is driven by product innovation, regulatory approvals, precision medicine strategies, and the development of therapies targeting EGFR, ALK, ROS1, MET, RET, HER2, KRAS, and other molecular alterations. Companies are also strengthening their portfolios through lifecycle management, combination therapies, and pipeline expansion. The entry of new targeted therapies and increasing biomarker testing continue to intensify competition while supporting product differentiation across the NSCLC therapeutics market.
Key Non-small Cell Lung Cancer Therapeutics Companies
The following companies have been profiled for this study on the non-small cell lung cancer therapeutics market.
-
AstraZeneca PLC
-
Merck & Co., Inc.
-
F. Hoffmann-La Roche Ltd.
-
Bristol Myers Squibb
-
Johnson & Johnson
-
Pfizer Inc.
-
Novartis AG
-
Eli Lilly and Company
-
GSK plc
-
Boehringer Ingelheim
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Player: AstraZeneca PLC
- Mature players focus on expanding targeted therapy and immunotherapy portfolios through indication expansion, clinical trials, strategic collaborations, and acquisitions.
- They invest in biomarker-driven drug development, companion diagnostics, manufacturing capacity, and lifecycle management. Companies also strengthen their global commercial presence by expanding distribution networks, improving physician engagement, and supporting precision oncology programs across established healthcare markets.
- Mature players maintain a competitive edge through established NSCLC product portfolios, broad clinical evidence, global commercial operations, and experience in oncology drug development.
- Their presence across multiple treatment classes, access to molecular diagnostics, strong relationships with healthcare providers, and continuous investment in pipeline development support sustained market positioning and product adoption across major healthcare markets.
- Mature players face challenges from patent expiry, increasing competition from newly approved therapies, pricing pressure, and the need for continuous clinical development.
- Maintaining large product portfolios requires ongoing investment in research, regulatory compliance, and manufacturing. Competition from companies developing therapies for new molecular targets may reduce growth opportunities within existing treatment segments.
Emerging Player: Pfizer Inc.
- Emerging players focus on developing therapies for specific molecular targets, expanding clinical pipelines, and entering licensing or co-development agreements with larger pharmaceutical companies.
- They prioritize precision medicine, biomarker-driven research, regional commercialization, and strategic partnerships to improve product development, increase clinical evidence, and expand their presence in the NSCLC therapeutics market.
- Emerging players gain a competitive edge by developing therapies for less common genetic alterations and introducing new treatment approaches for patients with limited options.
- Flexible research models, focused product pipelines, and collaboration with biotechnology companies and research institutions support faster innovation and help establish their position in selected NSCLC treatment segments.
- Emerging players often have limited commercial infrastructure, smaller product portfolios, and lower manufacturing capacity than established pharmaceutical companies.
- They depend on successful clinical trial outcomes, regulatory approvals, and strategic partnerships to expand operations. Limited geographic presence and financial resources can delay commercialization and reduce their ability to compete across multiple global markets.
Recent Developments
-
In July 2026, AstraZeneca entered into an exclusive global licensing agreement with Dizal Pharmaceutical to acquire worldwide rights for sunvozertinib, an oral EGFR inhibitor for NSCLC with EGFR exon 20 insertion mutations, expanding its targeted lung cancer portfolio and global development capabilities.
-
In February 2026, Boehringer Ingelheim received approval from the U.S. Food and Drug Administration (FDA) for zongertinib for adults with unresectable or metastatic non-squamous non-small cell lung cancer (NSCLC) whose tumors had HER2 (ERBB2) tyrosine kinase domain activating mutations, as detected by an FDA-authorized test.
-
In January 2025, Johnson & Johnson received the European Commission approval for lazertinib in combination with amivantamab as a first-line treatment for adults with advanced non-small cell lung cancer harboring epidermal growth factor receptor (EGFR) exon 19 deletions or exon 21 L858R substitution mutations.
Global Non-small Cell Lung Cancer Therapeutics Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 24.1 billion
Estimated market size in 2026
USD 27.1 billion
Revenue forecast in 2033
USD 63.5 billion
Growth rate
CAGR of 12.9% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, trends
Segments covered
Type, treatment, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; Australia; South Korea; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key company profiled
AstraZeneca PLC; Merck & Co., Inc.; F. Hoffmann-La Roche Ltd.; Bristol Myers Squibb; Johnson & Johnson; Pfizer Inc.; Novartis AG; Eli Lilly and Company; GSK plc; Boehringer Ingelheim.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Non-small Cell Lung Cancer Therapeutics Market Report Segmentation
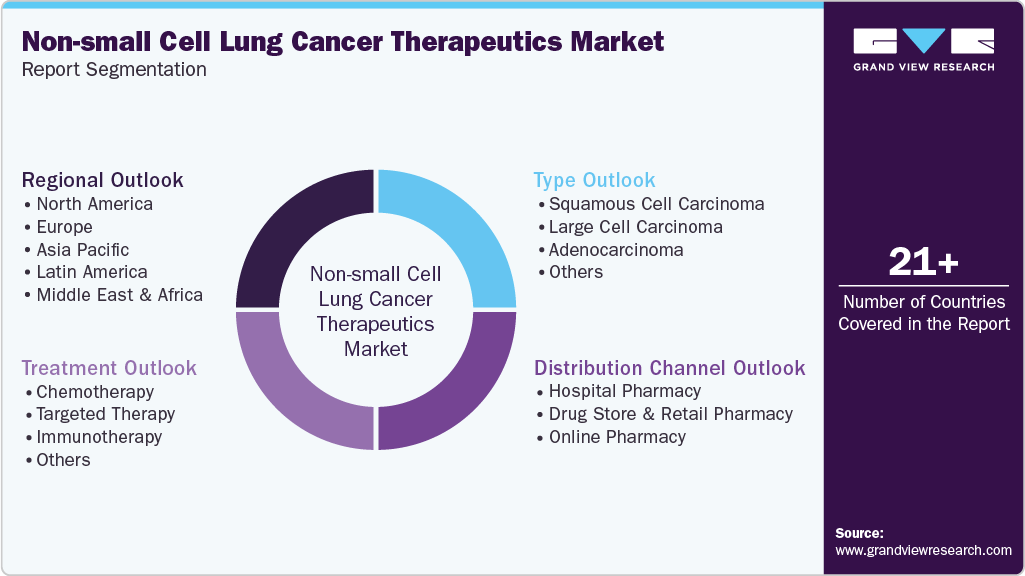
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global non-small cell lung cancer therapeutics market report based on type, treatment, distribution channel, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Squamous Cell Carcinoma
-
Large Cell Carcinoma
-
Adenocarcinoma
-
Others
-
-
Treatment Outlook (Revenue, USD Billion, 2021 - 2033)
-
Chemotherapy
-
Targeted Therapy
-
Immunotherapy
-
Others
-
-
Distribution Channel Outlook (Revenue, USD Billion, 2021 - 2033)
-
Hospital Pharmacy
-
Drug Store and Retail Pharmacy
-
Online Pharmacy
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The non-small cell lung cancer therapeutics market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each non-small cell lung cancer therapeutics segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
Squamous Cell Carcinoma
Includes therapeutics indicated for patients diagnosed with squamous cell carcinoma of the lung. This segment covers systemic therapies, including chemotherapy, immunotherapy, targeted therapy where applicable, and other approved treatments used specifically for this histological subtype.
Large Cell Carcinoma
Includes therapeutics used for the treatment of large cell carcinoma, an undifferentiated subtype of NSCLC. The segment comprises systemic treatment options selected according to disease stage, molecular profile, and clinical practice guidelines for this subtype.
Adenocarcinoma
Includes therapeutics prescribed for patients with lung adenocarcinoma, the most common subtype of NSCLC. The segment covers targeted therapies, immunotherapies, chemotherapy, and other approved treatment options used according to biomarker status and disease stage.
Others
Includes therapeutics used for less common NSCLC histological subtypes, including adenosquamous carcinoma, sarcomatoid carcinoma, and other rare NSCLC variants that are not classified under the major histological categories.
Segment - Treatment
Revenue capture definition
Chemotherapy
Includes cytotoxic drugs administered alone or in combination to destroy rapidly dividing cancer cells in NSCLC patients. The segment covers platinum-based and non-platinum chemotherapy agents used across different stages of disease.
Targeted Therapy
Includes therapies designed to inhibit specific molecular alterations associated with NSCLC, including EGFR, ALK, ROS1, BRAF, MET, RET, KRAS, HER2, and other actionable biomarkers identified through molecular testing.
Immunotherapy
Includes immune checkpoint inhibitors and other immune-based therapies that enhance the body's immune response against NSCLC cells. The segment excludes molecularly targeted therapies and conventional cytotoxic chemotherapy.
Others
Includes therapeutic approaches not classified under chemotherapy, targeted therapy, or immunotherapy, including antiangiogenic therapies, combination regimens categorized separately, and other approved systemic treatments for NSCLC.
Segment - Distribution Channel
Revenue capture definition
Hospital Pharmacy
Includes NSCLC therapeutics supplied through hospital pharmacies associated with inpatient and outpatient oncology departments, cancer centers, and specialty hospitals where treatment initiation and supervised administration commonly occur.
Drug Store and Retail Pharmacy
Includes NSCLC therapeutics dispensed through retail pharmacy chains, community pharmacies, and specialty retail pharmacies that supply prescribed oral and maintenance therapies directly to patients.
Online Pharmacy
Includes NSCLC therapeutics distributed through licensed digital pharmacy platforms that process prescriptions and deliver approved medicines directly to eligible patients while complying with local pharmaceutical regulations.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Global Non-Small Cell Lung Cancer Therapeutics Market Opportunity Assessment (U.S., Europe & Asia Pacific)
Conducted a country-level assessment of the NSCLC therapeutics market across the U.S., Germany, France, the UK, Japan, China, and India. The study evaluated NSCLC incidence, biomarker testing rates, adoption of targeted therapies and immunotherapies, treatment pathways, pricing trends, regulatory approvals, and distribution channels for marketed therapies.
Helped the client identify countries with increasing adoption of precision oncology, evaluate commercial opportunities by biomarker segment, assess pricing and market access trends, and prioritize regional expansion. The study also supported portfolio planning by identifying markets with growing use of molecular testing and targeted therapies.
NSCLC Therapeutics Competitive Benchmarking & Pipeline Assessment
Delivered a benchmarking analysis of marketed NSCLC therapies and late-stage pipeline products. The assessment covered targeted therapies, immunotherapies, antibody-drug conjugates, companion diagnostics, clinical development, licensing activities, strategic collaborations, manufacturing capabilities, intellectual property, and commercialization strategies of key market participants.
Enabled the client to compare product portfolios, identify licensing and acquisition opportunities, evaluate competitive positioning across biomarker-defined therapies, and prioritize pipeline investments. The analysis also supported product differentiation and commercialization planning within the NSCLC therapeutics market.
Emerging Market NSCLC Diagnosis & Precision Medicine Assessment
Conducted a country-level assessment of NSCLC diagnosis and treatment adoption across Brazil, Saudi Arabia, South Africa, Indonesia, Mexico, and other emerging markets. The study analyzed biomarker testing availability, molecular diagnostic capacity, adoption of targeted therapies and immunotherapies, distribution channels, regulatory pathways, and treatment patterns influencing NSCLC therapy utilization.
Supported expansion planning by identifying countries with increasing biomarker testing, growing use of targeted therapies, and improving access to precision oncology. The study also helped prioritize commercial investments, evaluate partnership opportunities, and optimize market entry strategies across emerging NSCLC therapeutics markets.
Frequently Asked Questions About This Report
North America dominated the market, accounting for the largest revenue share of 35.4% in 2025.
Some key players operating in the non-small cell lung cancer therapeutics market include AstraZeneca PLC; Merck & Co., Inc.; F. Hoffmann-La Roche Ltd.; Bristol Myers Squibb; Johnson & Johnson; Pfizer Inc.; Novartis AG; Eli Lilly and Company; GSK plc; Boehringer Ingelheim.
The adenocarcinoma segment accounted for 43.5% of the market share in 2025, while squamous cell carcinoma (SCC) segment is the fastest growing type.
The targeted therapy segment accounted for 50.8% of the market share in 2025, while chemotherapy segment is the fastest growing treatment.
The hospital pharmacy segment accounted for 67.1% of the market share in 2025, while drug store and retail pharmacy segment is distribution channel.
Asia Pacific is the fastest-growing region over the forecast period.
The global non-small cell lung cancer therapeutics market size was valued at USD 24.1 billion in 2025 and is estimated at USD 27.1 billion in 2026.
The global non-small cell lung cancer therapeutics market is expected to grow at a CAGR of 12.9% from 2026 to 2033, reaching USD 63.5 billion by 2033.
Key factors that are driving the market growth include the increasing patient population, expected entry of several drugs, and rising investment by industry players in R&D of NSCLC therapy.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


