
- Home
- »
- Medical Devices
- »
-
North America Healthcare Payer Services Market Report, 2030GVR Report cover

North America Healthcare Payer Services Market (2023 - 2030) Size, Share & Trends Analysis Report By Services (BPO Services, ITO Services, KPO Services), By Application, By End-use (Private Payers, Public Payers), And Segment Forecasts
Report Overview
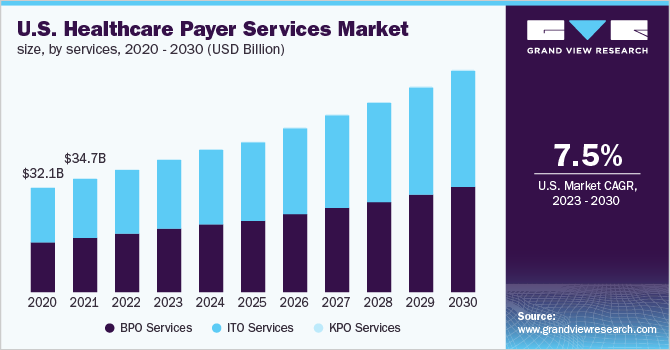
The North America healthcare payer services market size was valued at USD 47.0 billion in 2022 and is expected to expand at a CAGR of 7.3% over the forecast period. The growing demand for healthcare IT services is predicted to stimulate the healthcare supply chain business process outsourcing market growth during the forecast period. Changes in regulatory scenarios and increasing pressure on the healthcare industries to decrease service costs are likely to increase the demand for healthcare supply chain business process outsourcing. Hence, the regional market is expected to witness significant growth during the forecast period.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
The COVID-19 pandemic has had a significant impact on the healthcare payer services market in North America. The market experienced disruptions in the supply chain, changes in consumer behavior, and a shift in healthcare utilization patterns. In addition, the pandemic highlighted the importance of healthcare payer services in ensuring that people have access to the care they need, particularly in times of crisis. One of the major impacts of the pandemic on the market has been on its supply chain. The pandemic caused disruptions in the supply chain, leading to shortages of personal protective equipment and other critical medical supplies. This affected healthcare providers' ability to provide care and increased the costs for healthcare payers.
The growing disease burden in North America is boosting the healthcare payer services market in several ways. Disease burden refers to the impact of a specific disease on a population, including the number of cases, deaths, and disabilities caused by disease. According to a survey conducted by The Harris Poll and CNBC, for 4,000 U.S. adults, it showed that 44% of older millennials reported having been diagnosed with at least one chronic health condition. As the disease burden in North America continues to grow, it is driving the demand for healthcare service and fueling the healthcare payer services market.
The presence of various healthcare policies in North America is significantly impacting the growth of region’s healthcare payer services market. These policies, designed to improve access to healthcare and control costs, can affect the market in several ways. One of the major impacts of healthcare policies is on the cost of healthcare. Policies, such as the Affordable Care Act (ACA) and Medicaid, have increased the number of individuals with health insurance coverage, which can lead to greater demand for healthcare services & higher costs for payers. In addition, policies that seek to control healthcare costs, such as value-based reimbursement models, can lead to lower reimbursement rates for payers and providers, which can further increase costs.
Services Insights
ITO Services dominated the service segment with a market share of 51.3 % in 2022. The major growth factors are increasing demand for innovative and advanced technologies, a rise in investment in AI technology, information that can be easily accessed, and a rise in involvement in healthcare decisions. In addition, the rising costs, stringent regulations, and growing customer base are also likely to promote healthcare organizations to look for IT or integrated services.
KPO healthcare payer services segment is expected at a lucrative CAGR of 10.6% due to the surge in demand for highly skilled professionals and the cost advantage associated with outsourcing high-end processes to service providers from developing economies. Moreover, the growing need in emerging economies for low-cost & high-skilled professionals for domain-specific core and noncore activities of the payer vertical is one of the crucial factors anticipated to propel the sector in the forecast period.
Application Insights
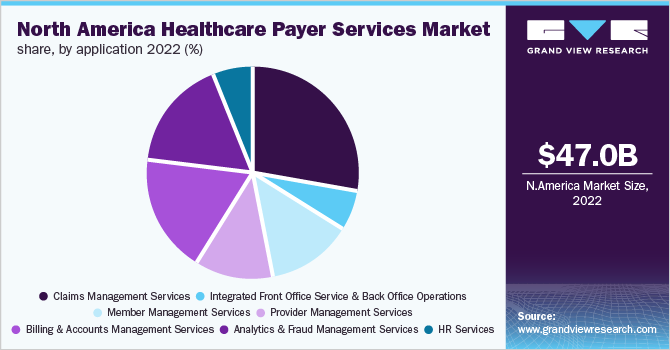
The claims management services dominated the application segment in 2022 with a market share of 28.4%. The presence of ACA and increasing overall healthcare expenditure are among some crucial factors that are driving the number of members enrolled in the Centers for Medicare and Medicaid Services. In addition, increase in patient load, improvements in healthcare coverage, and adoption of EHRs are further propelling the segment.
Provider management services are anticipated to expand at the fastest CAGR of 8.6% during the forecast period. This segment consists of provider credentialing, provider data management, contracting, and network management. Key factors contributing to segment growth include technological advancements in healthcare provider management services, increasing focus on improving quality care through payer requirements.
End-use Insights
The private payers segment accounted for the majority revenue share of 58.8% in 2022. This is attributed to the increasing private investment in the healthcare payer vertical and growing government support to promote private investment in the healthcare industry. For instance, according to Cambridge University, most Canadians hold the highest private insurance, primarily through employee benefits.
 To learn more about this report, Download Free Sample Report
The public healthcare payer segment accounted for the fastest CAGR of 7.5% over the forecast period. Public healthcare payers are federal or state governments that provide coverage to make healthcare & medical services affordable for patients. Public payers provide financial protection to patients, thereby, minimizing any out-of-pocket spending on healthcare services. The various types of public-funded insurance include Medicare, Medicaid, and Children’s Health Insurance Program (CHIP).
Key Companies & Market Share Insights
The key players in this industry are Cognizant, Flatworld Solutions, Accenture, Xerox Corporation, WIPRO Ltd., Infosys, IQVIA, Orion HealthCorp, Promantra, and Medisys Data Solutions Inc. To maintain market, share, big firms frequently engage in mergers and acquisitions, collaboration, partnership as well as new product launches. For instance, in February 2022, Accenture collaborated with League to offer a personalized digital health experience. This effort would combine Accenture’s data analytics and League’s healthcare experience platform to increase healthcare access & improve outcomes for people, payers, providers, & retail pharmacies. Some prominent players in the North America healthcare payer services market are:
-
Cognizant
-
Flatworld Solutions
-
Accenture
-
Xerox Corporation
-
WIPRO Ltd.
-
Infosys
-
IQVIA
-
Orion HealthCorp
-
Promantra
-
Medisys Data Solutions Inc.
North America Healthcare Payer Services Market Report Scope
Report Attribute
Details
Market size value in 2023
USD 50.8 billion
Revenue forecast in 2030
USD 83.0 billion
Growth rate
CAGR of 7.3% from 2023 to 2030
Base year for estimation
2022
Actual estimates/Historical data
2018 - 2021
Forecast period
2023 - 2030
Quantitative units
Revenue in USD million, CAGR from 2023 to 2030
Report coverage
Revenue forecast, company share, competitive landscape, growth factors and trends
Segments Covered
Services, application, end-use, country
Country scope
U.S., Canada
Key companies profiled
Cognizant; Flatworld Solutions; Accenture; Xerox Corporation; WIPRO Ltd.; Infosys; IQVIA; Orion HealthCorp; Promantra; Medisys Data Solutions Inc.
15% free customization scope (equivalent to 5 analyst working days)
If you need specific market information, which is not currently within the scope of the report, we will provide it to you as a part of customization
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
North America Healthcare Payer Services Market Segmentation
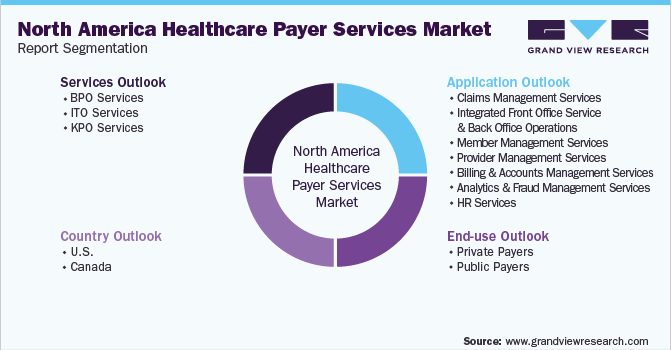
This report forecasts revenue growth at global, regional & country levels and provides an analysis of the industry trends in each of the sub-segments from 2018 to 2030. For this study, Grand View Research has segmented the North America healthcare payer services market on the basis of services, application, end-use, and country:
 To learn more about this report, Download Free Sample Report
-
Services Outlook (Revenue, USD Million, 2018 - 2030)
-
BPO Services
-
ITO Services
-
KPO Services
-
-
Application Outlook (Revenue, USD Million, 2018 - 2030)
-
Claims management services
-
Integrated front office service and back office operations
-
Member management services
-
Provider management services
-
Billing and accounts management services
-
Analytics and fraud management services
-
HR Services
-
-
End-use Outlook (Revenue, USD Million, 2018 - 2030)
-
Private Payers
-
Public Payers
-
-
Country Outlook (Revenue, USD Million, 2018 - 2030)
-
U.S.
-
Canada
-
Frequently Asked Questions About This Report
The North America healthcare payer services market size was estimated at USD 47.0 billion in 2022 and is expected to reach USD 50.8 billion in 2023.
The North America healthcare payer services market is expected to grow at a compound annual growth rate of 7.3% from 2023 to 2030 to reach USD 83.0 billion by 2030.
ITO Services dominated the service segment with a market share of 51.3 % in 2022. The major growth factors are increasing demand for innovative and advanced technologies, a rise in investment in AI technology, and a rise in involvement in healthcare decisions.
Some key players operating in the North America healthcare payer services market include Accenture, Cognizant, Xerox Corporation, IQVIA, Infosys and Wipro Ltd.
The main drivers of North America healthcare payer services market are rising demand for healthcare IT, changes in regulatory research, presence of several healthcare policies, growing disease burden, and increasing adoption of health insurance policies.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst -

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


