
- Home
- »
- Animal Health
- »
-
North America Laboratory Animal Medicine Market Report 2033GVR Report cover

North America Laboratory Animal Medicine Market (2026 - 2033) Size, Share & Trends Analysis Report By Product, By Animal Model (Rodents, Rabbits, Non-Human Primates), By Application (Rodents, Rabbits, Non-Human Primates (NHPs)), By Customer, By Country, And Segment Forecasts
North America Laboratory Animal Medicine Market Summary
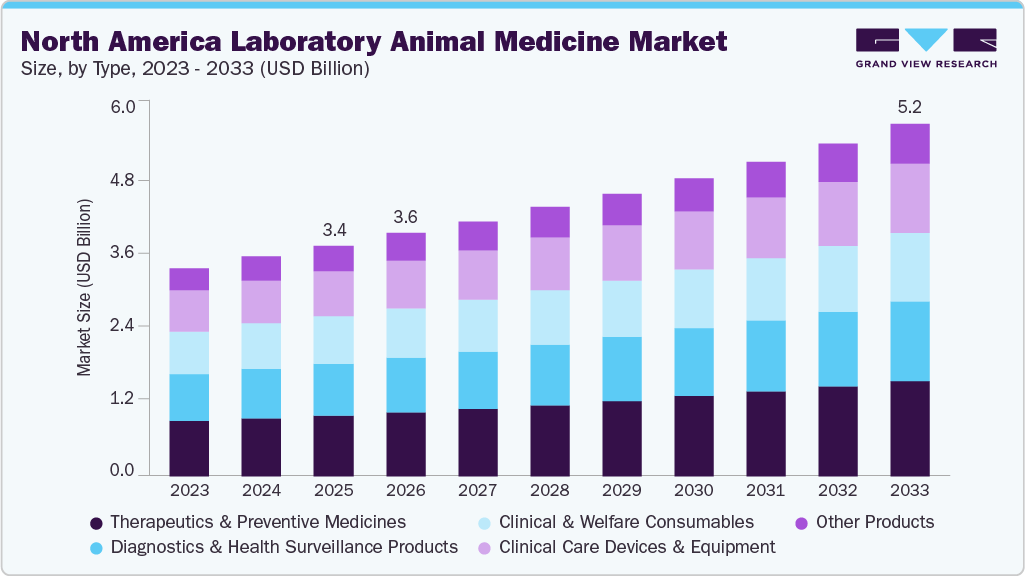
The North America laboratory animal medicine market size was estimated at USD 3.4 billion in 2025 and is projected to reach USD 5.2 billion by 2033, growing at a CAGR of 5.5% from 2026 to 2033. The market growth is driven by the expansion of public diagnostic and surveillance laboratory networks, capital investment in animal health R&D and regulated laboratory infrastructure, tightening animal care standards and oversight expectations, and growth in applied research areas that still depend on in vivo models.
Key Market Trends & Insights
- The U.S. laboratory animal medicine market held the largest revenue share, at 73.2%, in 2025.
- By product, the therapeutics & preventive medicines segment held the largest share of around 26.0% in the market in 2025
- By animal model, the rodents segment is the largest as well as the fastest in the market in 2025.
- Based on the application, the disease surveillance & colony health monitoring segment held the largest market share of 18.0% in 2025.
- By customer, the pharmaceutical & biopharmaceutical companies segment held the largest market share in 2025.
Market Size & Forecast
- 2025 Market Size: USD 3.4 Billion
- 2033 Projected Market Size: USD 5.2 Billion
- CAGR (2026-2033): 5.5%
Prism AI by Grand View Research Free to tryAsk a question about the north america laboratory animal medicine marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Capital investment in animal health R&D and regulated laboratory infrastructure is one of the crucial dynamic drivers for the sector's growth. Large, multi-year investments in biologics manufacturing and research facilities expand production capacity and upstream preclinical and validation activity. New R&D laboratories integrated within manufacturing campuses increase the volume of in vivo studies required for formulation testing, stability work, and regulatory submissions. For instance, in May 2025, Merck Animal Health announced a USD 895 million expansion of its De Soto, Kansas, biologics manufacturing facility. Such activities are bringing sustained demand for veterinary oversight, health monitoring, and compliant animal housing.The path towards highly regulated, GLP-certified laboratories is further amplifying this growth. Certification raises expectations for data integrity, traceability, and repeatability, thereby enabling tighter control over animal health variables. For instance, in July 2025, Chalk River Laboratories (CRL) became Canada's first GLP-certified lab capable of conducting radioactive work and pre-clinical radiopharmaceutical studies, following a Standards Council of Canada audit that met OECD standards for regulators such as Health Canada and the FDA. Facilities operating under GLP standards require more frequent diagnostics, standardized preventive care protocols, and documented welfare outcomes. This increases healthcare intensity per animal rather than depending on simple growth in animal numbers.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
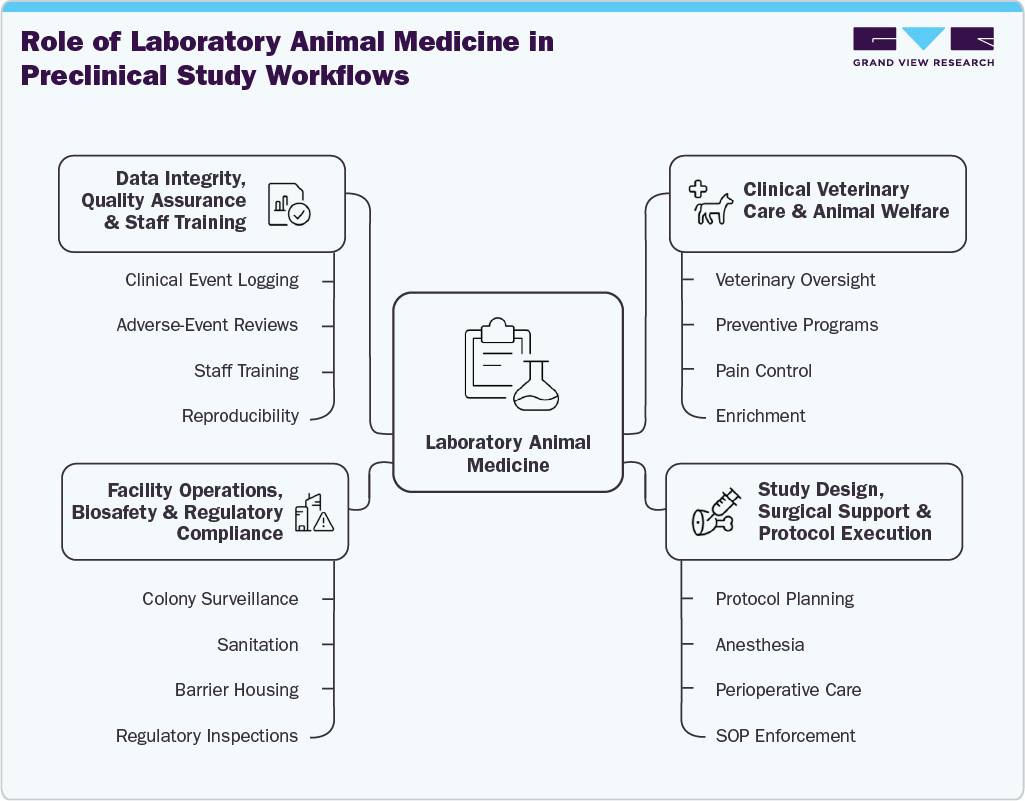
Another important driver for the market is the expansion of public diagnostic and surveillance laboratory networks. This dynamic has been increasing the scale, intensity, and regularity of laboratory animal healthcare activities. Governments are building permanent diagnostic capacity to detect animal diseases, evaluate vaccines, and conduct safety investigations. This has raised expectations for continuous health monitoring, standardized diagnostics, and documented veterinary oversight across laboratory animal populations. As laboratories become connected through formal networks, testing protocols and quality requirements are becoming more uniform. This drives higher testing frequency per animal, broader use of confirmatory diagnostics, and longer health-monitoring timelines. Animal health data is now generated on a routine basis rather than only during acute events. That change increases demand for diagnostic reagents, skilled veterinary staff, and compliant animal housing systems that support biosecure operations.
 To learn more about this report, Download Free Sample Report
Market Concentration & Characteristics
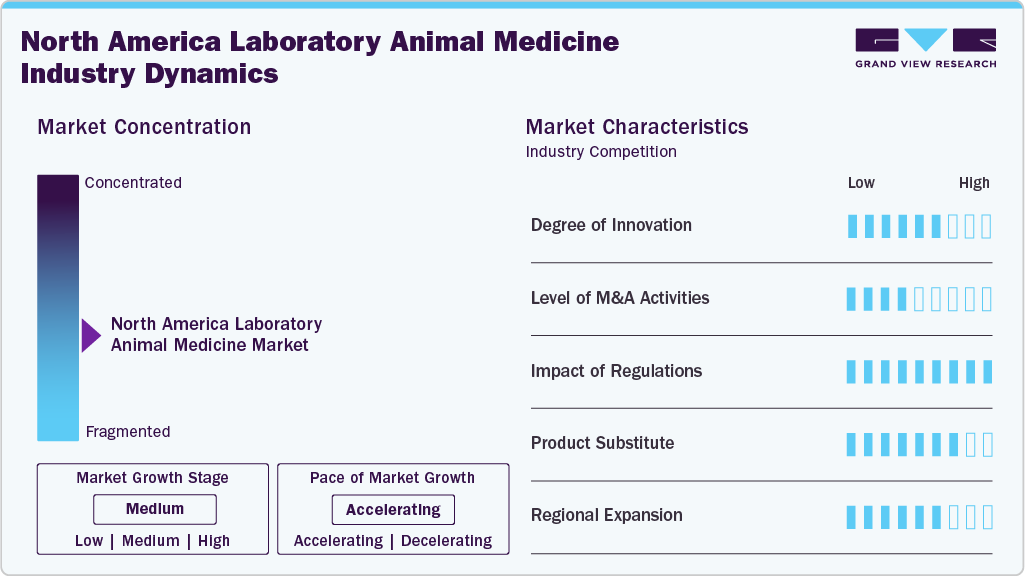
Industry concentration in the sector is driven by a few established manufacturers and a broader set of niche innovators. Large firms control core pharmaceutical and anesthesia supply channels, while specialized companies supply imaging, monitoring, and enrichment solutions. Distributors and service networks span multi-site institutions and support standardized care practices. Procurement decisions are favoring suppliers with documented quality systems, technical domain expertise, and broad channel reach. This market structure is creating high barriers to entry for smaller entrants but supporting the rapid adoption of advanced monitoring and imaging platforms across research facilities. Consolidation is forming around service excellence and validated workflows.
Innovation intensity remains elevated across North America, especially in imaging systems, physiological monitoring, anesthesia platforms, and AI-supported analytics. Vendors increasingly prioritize technologies that enhance, minimize animal stress, and promote reproducibility. Adoption of digital monitoring, automated data capture, and sensor-based welfare assessment is robust. Established manufacturers focus on incremental improvements, while emerging firms accelerate experimentation and deliver niche innovations. Product development is progressively aligned with workflow efficiency, compliance documentation, and integration with facility management software. Competitive differentiation is transitioning from hardware-centric offerings to comprehensive hardware-software ecosystems and validated, application-specific solutions.
 To learn more about this report, Download Free Sample Report
Mergers and acquisitions (M&A) activity remains steady, with larger vendors acquiring firms to expand specialized capabilities, proprietary technologies, and customer access. Consolidation is particularly evident in imaging, monitoring, and research instrumentation segments, where differentiation and validation are critical. Industry participants aim to integrate niche innovations, enhance service infrastructure, and secure recurring revenue from consumables. For smaller firms, acquisition often serves as a means of scaling manufacturing and establishing regulatory credibility. These dynamics increase competitive pressure on independent players, promote portfolio expansion strategies, and gradually concentrate market influence among vendors with comprehensive product suites and established institutional relationships.
Regulatory influence is substantial, shaping procurement decisions, product design, and supplier selection. Strict animal welfare standards, validation requirements, and documentation expectations create high compliance thresholds. Facilities prioritize audited suppliers that can provide lot traceability, certificates, and standardized reporting. Regulations also slow product switching, reducing buyer flexibility but strengthening incumbent positioning. Vendors invest heavily in quality systems, training, and technical support to meet the demands of institutional oversight. Compliance readiness often outweighs price considerations, particularly for controlled drugs, diagnostics, and species-specific systems. Overall, regulation acts as both a barrier to entry and a stabilizer of long-term supplier relationships.
Substitution pressure is rising from non-animal research methods, including in vitro models, organ-on-chip systems, and computational tools. These alternatives are gaining traction in early-stage screening and mechanistic studies, supported by ethical priorities and funding trends. Still, they do not fully replace animal models required for systemic toxicity, pharmacokinetics, and regulatory submissions. Instead of displacement, a complementary dynamic is emerging in which substitutes reduce certain study volumes while increasing demand for higher-precision animal studies. This shift sustains investment in advanced monitoring, imaging, and welfare-supportive technologies that enhance the value of remaining animal-based research workflows.
Regional expansion strategies emphasize distribution depth, service coverage, and institutional partnerships rather than simple geographic spread. Vendors strengthen multi-site support capabilities to serve CRO networks, academic clusters, and large research facilities. Growth often follows service-led models that bundle equipment, consumables, maintenance, and training. Domestic manufacturing presence and logistics reliability influence expansion success, particularly under supply chain scrutiny. Companies also target specialized research segments, such as NHP monitoring or aquatic models, to build defensible niches. Expansion within North America remains closely tied to compliance support, validated workflows, and the ability to scale technical services in tandem with product portfolios.
Product Insights
By product, the therapeutics & preventive medicines segment accounted for the highest market share of around 26.0% in 2025 and is expected to grow at the fastest rate over the forecast period. This growth is driven by the increasing emphasis on proactive colony health management across research facilities. Laboratories prioritize preventive and therapeutic medicines to maintain disease-free populations, reduce morbidity risks, and stabilize physiological conditions. Routine use of vaccines, anti-infectives, antiparasitics, and supportive therapies helps prevent outbreaks that disrupt studies and inflate operational costs. Adoption is further supported by strict welfare regulations and oversight frameworks that encourage validated treatment protocols. Advances in species-specific formulations, precise dosing, and efficient delivery methods improve safety and compliance within controlled environments. Consistent medication strategies reduce health-related variability, protect data reliability, and sustain continuous study workflows, supporting this segment’s dominant contribution to overall market share.
Diagnostics & health surveillance products is expected to be the second-largest segment due to the need for early disease detection, colony stability, and experimental reliability. Research facilities depend on routine screening, pathogen monitoring, and validated assays to prevent outbreaks that disrupt studies and compromise data quality. Stringent regulatory and accreditation frameworks across the U.S. and Canada support continuous health surveillance and documentation practices. Strong biomedical R&D activity and the rising complexity of research models further increase demand for sensitive, rapid diagnostic technologies. These factors collectively sustain high utilization of diagnostic and surveillance solutions, supporting their substantial market contribution.
Animal Model Insights
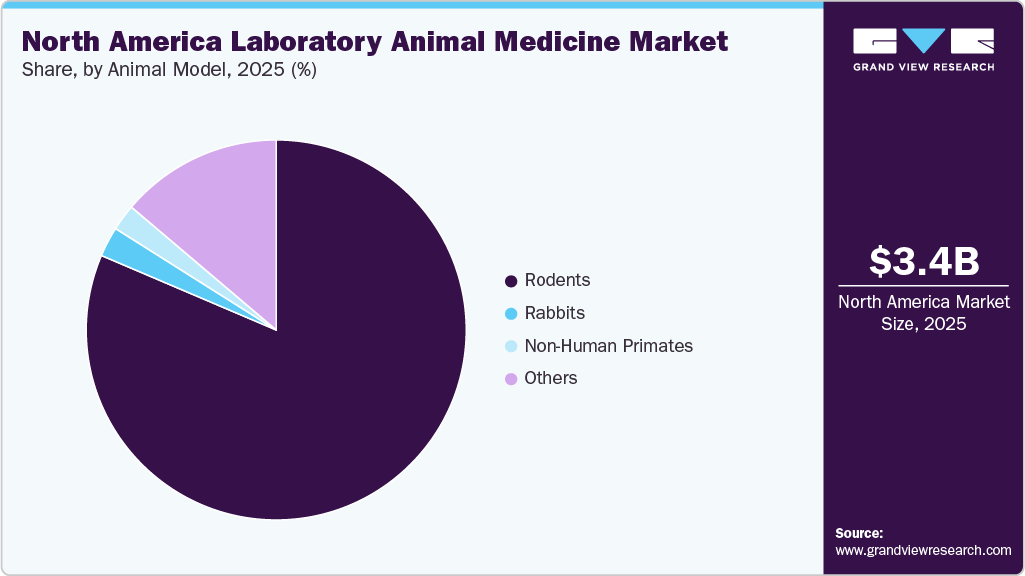
On the basis of animals, rodents held the highest market share in 2025 and are expected to maintain the fastest growth from 2026 to 2033. This dominance is driven by their dominant use in biomedical and preclinical research. High breeding volumes, short life cycles, and broad applicability across disease models sustain continuous demand. Widespread antimicrobial exposure and rising concern about resistance are driving increased investments in veterinary oversight, diagnostics, and preventive care. Facilities are expanding health surveillance, biosecurity, and standardized treatment protocols to stabilize colonies and protect data quality. Even modest increases in per-animal healthcare spending translate into substantial market expansion given the scale of rodent populations, reinforcing both their leading share and accelerated growth trajectory.
 To learn more about this report, Download Free Sample Report
The other animal segment, consisting of guinea pigs, hamsters, ferrets, pigs, dogs, sheep, and fish, etc., is expected to register the second-fastest growth rate from 2026 to 2033 due to expanding use of diverse species in specialized research applications. Increased adoption of guinea pigs, hamsters, and ferrets sustains steady demand for species-specific medicines, vaccinations, and diagnostics. Larger models such as pigs, dogs, and sheep generate higher per-animal spending since procedures often require anesthesia, analgesia, imaging, and intensive post-procedural care. Aquatic models add incremental demand for water quality testing, disease surveillance, and targeted treatments. Rising model diversification across research programs increases the need for tailored veterinary products and monitoring solutions, accelerating segment growth alongside evolving experimental requirements.
Application Insights
By application, the disease surveillance & colony health monitoring segment dominated the market with a 18.0% share in 2025, driven by the increasing need for early detection of subclinical infections and the maintenance of stable research colonies. High prevalence of undetected parasitic and microbial conditions in laboratory animals supports routine screening practices. Research facilities are expanding fecal testing, hematology, and sentinel monitoring programs to protect animal health and data reliability. Stringent welfare and compliance requirements are further strengthening recurring demand for diagnostic kits, surveillance tools, and veterinary monitoring services.
The chronic disease management & supportive care segment is anticipated to grow at the fastest CAGR of 5.9% over the coming years. This growth is driven by the persistent presence of long-term conditions such as chronic respiratory disease in rodents. These conditions often require continuous monitoring, repeated veterinary evaluations, and prolonged treatment rather than single interventions. Facilities sustain recurring use of respiratory drugs, anti-inflammatory therapies, and medications for secondary infections. Supportive care practices, including nutritional supplementation, hydration support, and environmental adjustments, further expand product utilization. The emphasis on maintaining animal stability, welfare, and study reliability increases long-term spending per animal, which accelerates demand for chronic care solutions across laboratory animal colonies.
Customer Insights
By customer the, the pharmaceutical & biopharmaceutical companies segment held the largest share of the market in 2025. Strategic engagements by leading pharmaceutical and biopharmaceutical companies, such as increased investment in advanced animal research technologies, new product launches, facility expansions, and collaborative partnerships, are driving the market growth. With technologies like the smart cages, which use AI to continuously monitor the health, activity, and behavior of multiple experimental animals, pharmaceutical and biopharmaceutical companies can obtain high-quality, real-time phenotypic data while ensuring animal welfare.
The preclinical CROs & contract laboratories segment is estimated to grow at the fastest CAGR in the forecast years. Rising demand for specialized preclinical research services is fueling the expansion of the preclinical CROs & contract laboratories. Their ability to design customized safety assessment programs, including GLP and non-GLP toxicology, safety pharmacology, and laboratory studies, ensures compliance with global regulatory standards. As more biopharmaceutical and animal health companies seek outsourced solutions for early-stage safety and efficacy testing, the need for high-quality preclinical services drives consistent demand for laboratory animals, specialized veterinary care, and associated consumables.
Country Insights
The U.S. dominated the North American laboratory animal medicine market in 2025, holding the largest revenue share at 73.2%. The market growth is attributed to rising awareness of animal welfare standards and the need for professional veterinary oversight. As institutions prioritize the health, well-being, and proper management of laboratory animals, the demand for comprehensive care services, advanced diagnostics, and structured husbandry programs continues to rise. Moreover, another major factor driving the market growth is the improved animal health monitoring and timely diagnostic solutions. Veterinary teams increasingly rely on rapid, accurate testing, including hematology, chemistry, microbiology, cytology, and histology, to detect health issues early, manage recovery, and ensure overall welfare. The demand for centralized high-throughput laboratories with fast result delivery times is encouraging investments in advanced diagnostic infrastructure that can support these needs
U.S. Laboratory Animal Medicine Market Trends
The U.S. laboratory animal medicine market is expected to grow significantly in the coming years, driven by continued demand for laboratory animals and associated diagnostics, therapeutics, preventive medicines, clinical care devices, and welfare products across pharmaceutical and biopharmaceutical research, preclinical testing, and academic research. At the same time, the market is shifting toward more human-relevant and alternative research methodologies. In April 2025, the U.S. FDA announced a roadmap to reduce animal testing in preclinical drug development by promoting approaches such as AI-based computational models, organoids, and organ-on-a-chip technologies. The NIH subsequently announced initiatives to prioritize human-based research technologies while continuing to allow animal models where scientifically appropriate. In April 2026, the FDA reported continued progress in implementing these initiatives, including expanded use of new approach methodologies (NAMs) and computational tools. These developments are expected to influence demand patterns for laboratory animal medicine products while creating opportunities for solutions focused on animal welfare, colony health monitoring, preventive care, and specialized veterinary support.
Key North America Laboratory Animal Medicine Company Insights
Key companies in the North America laboratory animal medicine market include established manufacturers and technology-focused innovators such as Kent Scientific Corporation, Plas-Labs, Harvard Apparatus, Mediso Ltd., IITCINC, TSE Systems, Dechra, Starr, and CH Technologies (USA), Inc. These firms supply anesthesia systems, imaging platforms, monitoring devices, and specialized research tools supported by extensive service networks. Market competition centers on continuous product development, integration of advanced imaging and precision monitoring technologies, and portfolio expansion. Investments targeting data accuracy, workflow efficiency, and study reproducibility are strengthening vendor positioning and sustaining technology-driven market growth across research facilities.
Key North America Laboratory Animal Medicine Companies:
- Zoetis Services LLC
- Boehringer Ingelheim International GmbH
- Merck & Co., Inc.
- Dechra
- Elanco Animal Health
- Kent Scientific Corporation
- Harvard Apparatus
- Starr
- QIAGEN
- Neogen Corporation
- Mediso Ltd.
- IITCINC
- Thermo Fisher Scientific Inc.
- Plas-Labs, Inc.
- TSE Systems
- CH Technologies (USA), Inc
Recent Developments
-
In December 2025, Mediso Ltd. installed its nanoScan 7T PET/MRI system, enabling high-precision, non-invasive animal studies. Such advancements increase demand for sophisticated translational research, supporting higher laboratory animal utilization, research funding, and technology-driven market growth.
-
In December 2025, NIH announced funding for laboratory experiments on cats despite publicly stating its efforts to phase out such research, allocating over USD 1.7 million to new and extended grants, including invasive neurological studies. Continued funding supports near-term market stability through sustained demand for animals and research services, while simultaneously intensifying scrutiny that encourages long-term adoption of alternative methods.
North America Laboratory Animal Medicine Market Report Scope
Report Attribute
Details
Market size value in 2026
USD 3.6 billion
Revenue forecast in 2033
USD 5.2 billion
Growth rate
CAGR of 5.5% from 2026 to 2033
Actual data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD Million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product; Animal Model; Application; Customer; Country
Regional scope
North America
Country scope
U.S.; Canada
Key companies profiled
Zoetis Services LLC; Boehringer Ingelheim International GmbH; Merck & Co., Inc.; Dechra; Elanco Animal Health; Kent Scientific Corporation; Harvard Apparatus; Starr; QIAGEN; Neogen Corporation; Mediso Ltd.; IITCINC; Thermo Fisher Scientific Inc.; Plas-Labs, Inc.; TSE Systems; CH Technologies (USA), Inc
Customization scope
Free report customization (equivalent to 8 analyst working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
North America Laboratory Animal Medicine Market Report Segmentation
This report forecasts revenue growth at the country level and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the NA laboratory animal medicine market report based on product, animal model, application, customer, and country:
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Diagnostics & Health Surveillance Products
-
Serology & PCR Test Kits
-
Microbiology & Parasitology Assays
-
Clinical Chemistry & Hematology Reagents / Panels
-
Others
-
-
Therapeutics & Preventive Medicines
-
Vaccines
-
Anti-infectives (Antibiotics, Antivirals, Antifungals)
-
Antiparasitics (Endo- & Ecto-parasite Control)
-
Analgesics & Sedatives
-
Anesthetics
-
Anti-inflammatory & Supportive Care Drugs
-
Others
-
-
Clinical Care Devices & Equipment
-
Animal Patient Monitoring Devices
-
Anesthesia Machines & Vaporizers
-
Ventilators & Respiratory Support Systems
-
Infusion & Syringe Pumps
-
Clinical Imaging & Diagnostic Devices
-
Others
-
-
Clinical & Welfare Consumables
-
Needles, Syringes, Catheters & Vascular Access Sets
-
Bandages, Wound Care & Surgical Consumables
-
Disinfectants, Detergents & Sanitation Products
-
Personal Protective Equipment (PPE) & Barrier Consumables
-
Others
-
-
Other Products
-
-
Animal Model Outlook (Revenue, USD Million, 2021 - 2033)
-
Rodents
-
Rabbits
-
Non-Human Primates (NHPs)
-
Others
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Disease Surveillance & Colony Health Monitoring
-
Preventive Care & Biosecurity
-
Perioperative Care (Anesthesia, Analgesia, Surgical Support)
-
Chronic Disease Management & Supportive Care
-
Welfare & Behavioral Assessment
-
End-of-Life & Euthanasia Management
-
Training, Education & Compliance Support
-
Others
-
-
Customer Outlook (Revenue, USD Million, 2021 - 2033)
-
Pharmaceutical & Biopharmaceutical Companies
-
Preclinical CROs & Contract Laboratories
-
Academic & Research Institutions
-
Others
-
-
Country Outlook (Revenue, USD Million, 2021 - 2033)
-
U.S.
-
Canada
-
Frequently Asked Questions About This Report
The North America laboratory animal medicine market size was estimated at USD 3.4 billion in 2025 and is expected to reach USD 3.6 billion in 2026.
The North America laboratory animal medicine market is expected to grow at a compound annual growth rate of 5.5% from 2026 to 2033 to reach USD 5.2 billion by 2033
By animal model, rodents held the highest market share in 2025 and are expected to continue to grow the fastest from 2026 to 2033.
Some key players operating in the North America laboratory animal medicine market include Zoetis Services LLC, Boehringer Ingelheim International GmbH, Merck & Co., Inc., Dechra, Elanco Animal Health, Kent Scientific Corporation, Harvard Apparatus, Starr, QIAGEN, Neogen Corporation, Mediso Ltd., IITCINC, Thermo Fisher Scientific Inc., Plas-Labs, Inc., TSE Systems, and CH Technologies (USA), Inc.
Key factors that are driving the market growth include expansion of public diagnostic and surveillance laboratory networks, capital investment in animal health R&D and regulated laboratory infrastructure, tightening animal care standards and oversight expectations, growth in applied research areas that still depend on in vivo models.
About the Author(s)
Animal Health Research Team
Healthcare · Animal HealthThis report was authored by the animal health research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the animal health segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


