
- Home
- »
- Plastics, Polymers & Resins
- »
-
North America Yogurt, Cheese, And Meat Form Fill And Seal Packaging Market Report, 2033GVR Report cover

North America Yogurt, Cheese, And Meat Form Fill And Seal Packaging Market (2025 - 2033) Size, Share & Trends Analysis Report By Material (PE, PP, PET), By Product, By Application, By Country, And Segment Forecasts
North America Yogurt, Cheese, And Meat Form Fill And Seal Packaging Market Summary
The North America yogurt, cheese, and meat form fill and seal packaging market size was estimated at USD 1.60 billion in 2024 and is projected to reach USD 2.21 billion by 2033, growing at a CAGR of 3.7% from 2025 to 2033. The flourishing fast food industry and growing consumption of yogurt in North America are fueling the demand for yogurt, cheese, and meat form fill, and seal packaging in North America.
Key Market Trends & Insights
- U.S. dominated the North America yogurt, cheese, and meat form fill and seal packaging market with the largest revenue share of 74.78% in 2024 and is expected to grow at a substantial CAGR of 3.8% from 2025 to 2033.
- By material, the polypropylene (PP) segment is expected to grow at the fastest CAGR of 4.1% from 2025 to 2033.
- By packaging type, the flexible FFS segment is expected to grow at the fastest CAGR of 4.0% from 2025 to 2033.
- By product, the films & wraps segment is expected to grow at the fastest CAGR of 4.2% from 2025 to 2033.
- By application, the yogurt segment is expected to grow at the fastest CAGR of 5.1% from 2025 to 2033.
Market Size & Forecast
- 2024 Market Size: USD 1.60 Billion
- 2033 Projected Market Size: USD 2.21 Billion
- CAGR (2025-2033): 3.7%
- U.S.: Largest market in 2024
Prism AI by Grand View Research Free to tryAsk a question about the north america Yogurt, Cheese, and meat form fill and seal packaging marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
The thriving fast-food industry in North America has played a key role in driving the growth of the yogurt, cheese, and meat form fill and seal (FFS) packaging market in the region. As the demand for convenient and ready-to-eat food products rises, the fast-food sector continues to expand. Consumers’ growing preference for on-the-go meals and quick-service options has heightened the need for efficient packaging solutions for dairy and meat products, thereby boosting the FFS packaging market.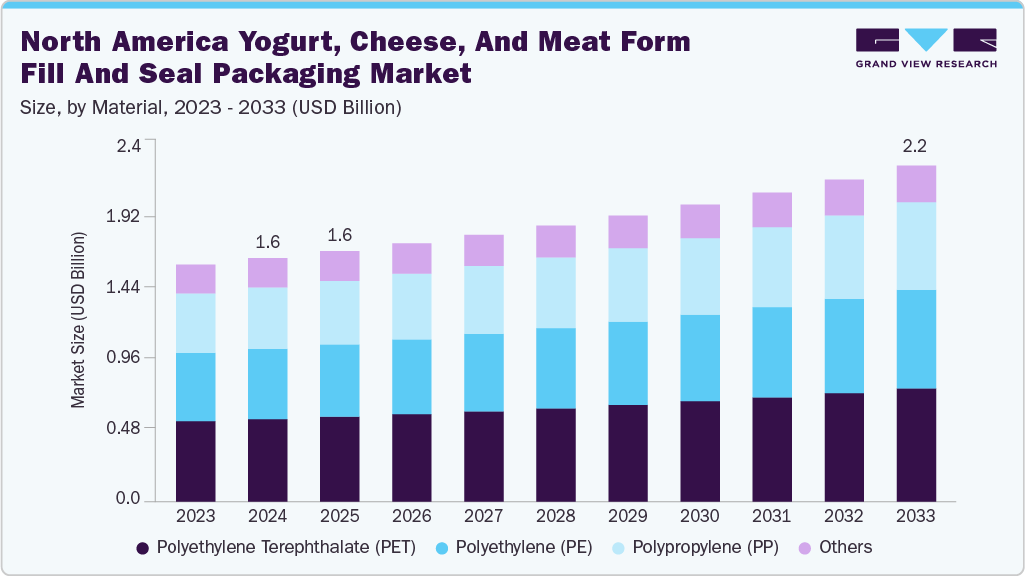 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
The fast-food industry’s dependence on form fill, and seal packaging solutions is another factor fueling market growth in North America. These solutions provide airtight sealing, which helps preserve the freshness and quality of perishable products like yogurt, cheese, and meat. The speed and efficiency of FFS machines complement the fast-paced operations of the industry, enhancing productivity and ensuring that packaged products reach consumers quickly, meeting the time-sensitive demands of fast-food operations.
Furthermore, North America is home to several major fast-food chains, including McDonald’s, Burger King, Wendy’s, Subway, Taco Bell, Pizza Hut, and Domino’s. Their menu items featuring cheese, yogurt, and meat-such as the Big Mac, Quarter Pounder with Cheese, Whopper, yogurt parfaits, Dave’s Single, Baconator, Meatball Marinara, Roasted Chicken Signature Wrap, Quesadilla, Cheesy Gordita Crunch, and Creamy Tuscan Chicken Pizza-drive the demand for FFS packaging solutions.
According to the U.S. National Agricultural Statistics Service (NASS), yogurt production in the U.S. reached 4.6 billion pounds in 2023 and is projected to increase by 6.3% to 4.9 billion pounds in 2024. Yogurt consumption in North America has been steadily rising due to its recognition as a nutritious and healthy food option, rich in protein, calcium, and probiotics that support gut health. This growing consumer preference for yogurt is expected to further boost the demand for form fill, and seal packaging solutions in the region.
Industry Characteristics
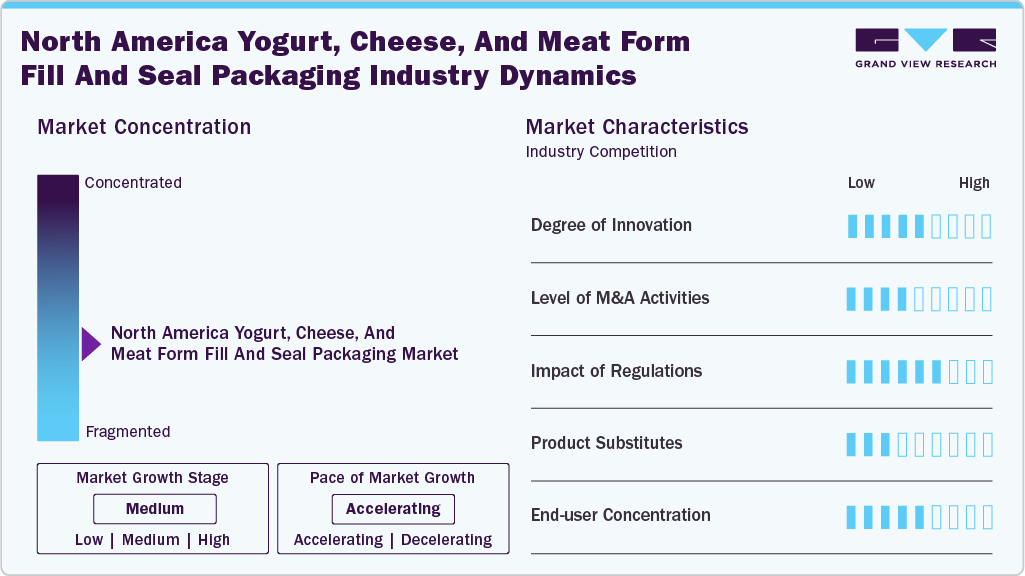
The North America yogurt, cheese, and meat form fill and seal packaging industry relies heavily on advanced machinery and automation technology. Modern FFS machines provide precise filling, high-speed sealing, and flexible packaging formats, catering to a variety of yogurt, cheese, and meat products. Continuous technological innovation, such as multi-lane filling systems, modified atmosphere packaging (MAP), and smart sensors for quality control, is a defining feature of the market.
Investment in FFS machinery is capital-intensive due to the cost of high-speed automated equipment, hygienic design requirements, and compliance with food safety regulations. Companies must invest not only in machines but also in supporting infrastructure like cold storage and automated material handling systems.
 To learn more about this report, Download Free Sample Report
The North America yogurt, cheese, and meat form fill and seal packaging industry is strongly regulated, with stringent compliance requirements for food safety and hygiene, particularly for dairy and meat products. Standards from the U.S. Food and Drug Administration (FDA), USDA, and the North American Meat Institute (NAMI) guide packaging processes, materials, and machinery maintenance. FFS packaging solutions are preferred because they minimize contamination risks by maintaining airtight and sterile sealing.
Material Insights
The PET segment led the market with the largest revenue share of 33.93% in 2024. PET is one of the most widely used materials in FFS packaging for yogurt, cheese, and meat due to its excellent transparency, strength, and barrier properties. It provides durability and resistance to impact while maintaining product freshness and shelf stability. PET’s recyclability also makes it a popular choice among dairy and meat manufacturers, aligning with North America’s growing sustainability initiatives.
Furthermore, The PP segment is expected to grow at the fastest CAGR of 4.1% during the forecast period. PP is valued in FFS packaging for its high clarity, stiffness, and resistance to high temperatures. In yogurt and cheese packaging, PP films are often used for cups, lids, and multilayer films, ensuring product safety and shelf appeal. For meat packaging, PP offers good puncture resistance and is often used in modified atmosphere packaging (MAP) formats. The growth of PP in the segment is driven by increasing demand for packaging that can withstand microwave reheating and hot filling, especially for ready-to-eat meals containing dairy and meat.
Packaging Type Insights
The flexible FFS segment led the market with the largest revenue share of 63.20% in 2024 and is expected to grow at the fastest CAGR of 4.0% during the forecast period. This dominance is due to its lightweight nature, cost-effectiveness, and adaptability in forming various pouch and bag formats. It enables excellent product visibility and branding opportunities through high-quality printing, while also offering strong barrier properties against oxygen and moisture, critical for preserving perishable dairy and meat products. The format is also easier to transport and store, reducing logistics costs for producers and retailers.
Rigid FFS packaging, typically used for products such as yogurt cups, cheese tubs, and processed meat trays, provides structural integrity and protection against external pressure during transportation and storage. Rigid FFS formats allow for effective stacking on retail shelves, which enhances product visibility and brand differentiation in supermarkets and convenience stores across North America. The dominance of supermarket and hypermarket retail channels in North America is a major factor boosting the use of rigid FFS packaging, as these formats enhance shelf appeal and convenience for consumers.
Product Insights
The films & wraps segment led the market with the largest revenue share of 42.79% in 2024 and is projected to progress at the fastest CAGR of 4.2% over the forecast period. Films and wraps are widely used in FFS packaging for yogurt, cheese, and meat due to their flexibility, cost-effectiveness, and ability to preserve product freshness. They provide barrier protection against oxygen, light, and moisture, which helps extend shelf life, particularly for perishable items like cheese slices and processed meats. Their compatibility with high-speed FFS machines makes them a preferred choice for efficient packaging operations.
Pouches are increasingly used for yogurt drinks, shredded cheese, and processed meats as they are lightweight, portable, and offer excellent branding opportunities with large printable surfaces. Stand-up and resealable pouch formats are gaining popularity in the region due to their convenience and ability to reduce packaging waste compared to rigid alternatives. The rising demand for on-the-go consumption, particularly among younger demographics and busy urban consumers, is driving pouch adoption.
Application Insights
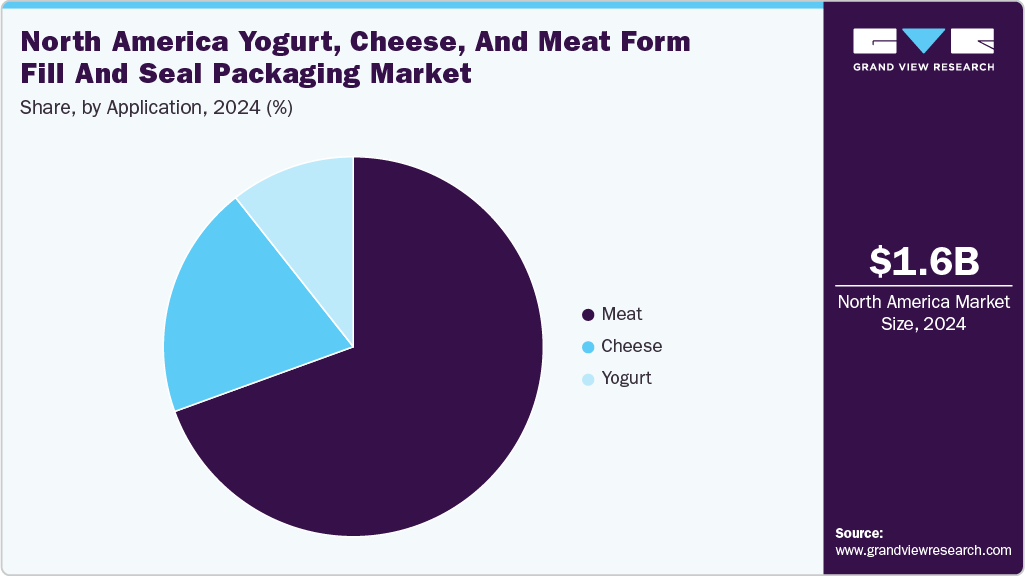
The meat segment led the market with the largest revenue share of 69.47% in 2024. The meat segment in North America utilizes form fill, and seal packaging extensively for fresh, frozen, and processed meat products. FFS packaging offers strong barrier protection against oxygen and moisture, which extends shelf life while maintaining product freshness and safety. MAP integrated with FFS solutions is increasingly used for meat to enhance preservation and appeal to consumers seeking safe, hygienic, and long-lasting products. Vacuum skin packaging formats are also gaining traction for premium meat cuts.
 To learn more about this report, Download Free Sample Report
The yogurt application segment is projected to progress at the fastest CAGR of 5.1% over the forecast period. The rising health and wellness trend in North America is fueling yogurt demand, particularly for Greek yogurt, plant-based alternatives, and functional probiotic-rich varieties. Busy lifestyles are pushing the popularity of portable single-serve packs, while multipacks cater to family consumption. In addition, product innovation in flavored and fortified yogurts, along with increasing retail promotions and online grocery sales, is driving greater adoption of FFS packaging for its cost efficiency and versatility.
Country Insights
U.S. Yogurt, Cheese, and Meat Form Fill and Seal Packaging Market Trends
Theyogurt, cheese, and meat form fill and seal packaging market in the U.S. accounted for the largest market revenue share of 74.78% in North America in 2024 and is projected to progress at the fastest CAGR of 3.8% over the forecast period. This positive outlook can be attributed to the presence of prominent producers of dairy products, such as cheese and yogurt, high meat production, and high per capita consumption of all dairy products. For instance, the United States Department of Agriculture (USDA) reported that per capita consumption of all dairy products in the U.S. reached 661 pounds per person in 2023. This positive export outlook is expected to trigger the U.S. yogurt, cheese, and meat form fill and seal packaging industry.
The Canadayogurt, cheese, and meat form fill and seal packaging market is steadily expanding, supported by strong dairy consumption, particularly in cheese and yogurt, and increasing demand for processed meat. The country’s robust food processing sector is modernizing with automated packaging solutions to reduce labor dependency and ensure higher food safety standards. Moreover, Canadian consumers show a strong preference for environmentally sustainable packaging, encouraging manufacturers to adopt recyclable and eco-friendly FFS packaging materials.
The yogurt, cheese, and meat form fill and seal packaging market in Mexico is experienced continued growth. According to the Global Agricultural Information Network (GAIN), in 2024, the growth in domestic cheese production, driven by rising demand in both the domestic and export markets. The primary driver of domestic demand in Mexico was the significant presence of the hotel, restaurant, and institutional (HRI) sector, closely followed by the food delivery sector. This surge in domestic cheese production can drive the need for efficient and high-capacity form fill and seal packaging solutions to handle larger quantities, thus benefiting the cheese form fill and seal packaging industry in the country.
Key North America Yogurt, Cheese, and Meat Form Fill and Seal Packaging Company Insights
The competitive environment of the North America yogurt, cheese, and meat FFS packaging industry is characterized by the presence of both global packaging giants and regional players. Companies are focusing on innovation in barrier films, recyclable and eco-friendly materials, and automation in machinery to meet the rising demand for extended shelf life and convenience packaging.
Strategic partnerships with dairy and meat producers, investments in advanced sealing technologies, and compliance with strict food safety regulations further intensify competition. In addition, private-label growth in retail and the rising popularity of ready-to-eat and on-the-go products push manufacturers to differentiate through customization, speed, and sustainability, making the market dynamic and moderately consolidated with continuous innovation driving competitive advantage.
Key North America Yogurt, Cheese, and Meat Form Fill and Seal Packaging Companies:
- WINPAK LTD.
- Huhtamaki
- Great American Packaging
- Amcor plc
- Transcontinental Inc.
- Econo-Pak
- ProAmpac
- Sealed Air
- Graphic Packaging International, LLC
- SIG
- Maco PKG
- Tetra Pak
Recent Developments
-
In June 2025, Amcor plc announced an investment in its Nicholasville, Kentucky, facility to expand its post-consumer recycled (PCR) packaging production capabilities. The upgraded system includes dedicated silos feeding multiple production lines to enable precise PCR blending, allowing customers to select their preferred PCR content, up to 100%. The move reflects Amcor's commitment to advancing a circular economy, helping brands meet sustainability goals, regulatory compliance, and supporting recycling markets.
-
In November 2024, WINPAK LTD. announced a long-term collaboration with NOVA Circular Solutions LLC, a unit of NOVA Chemicals, to procure post-consumer recycled polyethylene (rPE) branded as SYNDIGO. Under this agreement, WINPAK LTD. Agreed to use NOVA's high-quality rPE to manufacture and distribute sustainable flexible packaging materials designed to protect perishable food and beverage products.
North America Yogurt, Cheese, and Meat Form Fill and Seal Packaging Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 1.65 billion
Revenue forecast in 2033
USD 2.21 billion
Growth rate
CAGR of 3.7% from 2025 to 2033
Base year for estimation
2024
Historical data
2021 - 2023
Forecast period
2025 - 2033
Quantitative units
Volume in Kilotons, Revenue in USD million/billion, and CAGR from 2025 to 2033
Report coverage
Revenue forecast, competitive landscape, growth factors, and trends
Segments covered
Material, packaging type, product, application, country
Country Scope
U.S.; Canada; Mexico
Key companies profiled
WINPAK LTD.; Huhtamaki; Great American Packaging; Amcor plc; Transcontinental Inc.; Econo-Pak; ProAmpac; Sealed Air; Graphic Packaging International, LLC; SIG; Maco PKG; Tetra Pak
Customization scope
Free report customization (equivalent to up to 8 analyst’s working days) with purchase. Addition or alteration to country, regional & segment scope
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
North America Yogurt, Cheese, and Meat Form Fill and Seal Packaging Market Report Segmentation
This report forecasts revenue growth at regional and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the North America yogurt, cheese, and meat form fill and seal packaging market report based on material, packaging type, product, application, and country:
-
Material Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Polyethylene (PE)
-
Polypropylene (PP)
-
Polyethylene Terephthalate (PET)
-
Others
-
-
Packaging Type Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Flexible FFS
-
Rigid FFS
-
-
Product Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Pouches
-
Cups
-
Films & Wraps
-
Trays & Containers
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Yogurt
-
Cheese
-
Meat
-
-
Country Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
U.S.
-
Canada
-
Mexico
-
Frequently Asked Questions About This Report
The North America yogurt, cheese, and meat form fill and seal packaging market was estimated at around USD 1.60 billion in the year 2024 and is expected to reach around USD 1.65 billion in 2025.
The North America yogurt, cheese, and meat form fill and seal packaging market is expected to grow at a compound annual growth rate of 3.7% from 2025 to 2030 to reach around USD 2.21 billion by 2033.
Meat segment emerged as the dominating application segment in the North America yogurt, cheese, and meat form fill and seal packaging market due to the high demand for hygienic, portion-controlled, and extended shelf-life packaging solutions.
The key players in the North America yogurt, cheese, and meat form fill and seal packaging market include WINPAK LTD.; Huhtamaki; Great American Packaging; Amcor plc; Transcontinental Inc.; Econo-Pak; ProAmpac; Sealed Air; Graphic Packaging International, LLC; SIG; Maco PKG; and Tetra Pak.
The market is driven by rising consumer demand for convenient, ready-to-eat, and longer shelf-life food products. Additionally, advancements in packaging automation, sustainability initiatives, and strict food safety regulations are fueling market growth.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


