
- Home
- »
- Medical Devices
- »
-
U.S. Office-based Labs Market Size, Share Report, 2033GVR Report cover

U.S. Office-based Labs Market (2026 - 2033)
Size, Share & Trends Analysis Report By Modality (Single Specialty, Multi-Specialty), By Services (Cardiac, Endovascular Intervention, Venous), By Specialist, By Region, And Segment Forecasts
Market Size, 2025
$15.1BMarket Estimate, 2026
$16.6BMarket Forecast, 2033
$35.2BCAGR, 2026–2033
11.3%U.S. Office-based Labs Market Summary
The U.S. office-based labs market size was valued at USD 15.1 billion in 2025 and is projected from USD 16.6 billion in 2026 to USD 35.2 billion by 2033, at a CAGR of 11.3% from 2026 to 2033. Growing preference for office-based labs by patients in the U.S. in recent years and the increasing trend of performing surgical interventions in outpatient settings are among key factors driving the market growth. OBLs play a vital role in transforming the healthcare delivery system and are supporting the growth of medical devices, equipment, and other products.
Key Market Trends & Insights
- By services: Peripheral vascular intervention group segment held the largest revenue share of 36.5% in 2025.
- By modality: Single specialty segment held the largest revenue share of 41.3% in 2025.
- By specialist: The vascular surgeons segment dominated the U.S. office-based labs market, accounting for the largest revenue share of 40.2% in 2025.
Market Size & Forecast
- Market size in 2025: USD 15.1 Billion
- Estimated market size in 2026: USD 16.6 Billion
- Projected market size by 2033: USD 35.2 Billion
- CAGR (2026-2033): 11.3%
Prism AI by Grand View Research Free to tryAsk a question about the U.S. office-based labs marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →The rapidly transitioning healthcare delivery scenario is driving key market players to transform their business models to achieve maximum benefit from ongoing transition.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Marke Dynamics
The rising number of cardiovascular and radiological procedures in the U.S. is a significant growth driver for the office-based labs (OBLs) market. Cardiovascular disease remains the leading cause of death in the U.S. A report from the 2024 Heart Disease and Stroke Statistics indicates that nearly half of the U.S. population (48.6%) has some form of cardiovascular disease, including coronary heart disease, heart failure, stroke, and high blood pressure. This growing disease burden is translating into an increased demand for diagnostic and interventional procedures, thereby supplementing market growth.
The rising prevalence of cardiovascular and vascular diseases in the U.S. is a significant growth driver for the office-based labs (OBLs) market. According to (AHA) American Heart Association’s 2025 Stroke Statistics and Heart Disease Update, cardiovascular disease remained the leading cause of death in the U.S., accounting for 941,652 deaths in 2022, while nearly 2,500 people died from cardiovascular disease each day. The continued burden of cardiovascular disease is increasing demand for diagnostic and interventional cardiovascular services, supporting the expansion of outpatient and office-based care models.
The increasing migration of cardiovascular and vascular procedures from hospitals to physician-led outpatient facilities is a major driver of the U.S. office-based labs market. OBLs provide physicians with greater control over scheduling and procedural workflows while offering patients same-day treatment and recovery in a less complex care environment. According to a 2025 Journal of the American College of Cardiology (JACC) analysis, 65% of outpatient peripheral vascular interventions among Medicare beneficiaries were performed in OBLs in 2022, highlighting the growing role of office-based settings in cardiovascular care. The continued shift of appropriate cardiovascular interventions toward lower-cost outpatient settings is therefore increasing procedure volumes and supporting OBL expansion.
Case Study:-Increasing Use of Office-Based Labs for Chronic Limb-Threatening Ischemia Revascularization
Background:
The study evaluated the changing role of ambulatory surgical centers (ASCs) and office-based laboratories (OBLs) in the treatment of chronic limb-threatening ischemia (CLTI), a severe form of peripheral artery disease associated with high risks of amputation and mortality.
Methods:
A retrospective cohort analysis was conducted using Medicare fee-for-service claims data from 2016 to 2023, covering 925,905 beneficiaries aged 66 years and older who underwent lower-extremity peripheral vascular intervention for CLTI. The study compared procedures performed in hospital inpatient settings, hospital outpatient departments, and ASC/OBL settings.
Findings:
• The share of CLTI revascularizations performed in ASC/OBL settings increased substantially, with ASC/OBLs accounting for 46.72% of revascularizations by 2023.
• After adjustment for patient and clinical characteristics, ASC/OBL treatment was associated with a lower risk of death or major amputation compared with hospital outpatient and inpatient settings.
• ASC/OBL procedures were associated with a hazard ratio of 0.93 versus hospital outpatient settings and 0.47 versus inpatient settings for the composite outcome of death or major amputation.
• The study also found that ASC/OBL settings had higher rates of repeat revascularization, indicating the importance of appropriate patient selection for outpatient treatment.
Implications:
The findings demonstrate the expanding role of OBLs in complex peripheral vascular care and indicate that appropriately selected CLTI patients can receive revascularization in outpatient environments. The increasing migration of vascular interventions toward OBLs and other ambulatory settings supports continued investment in vascular imaging, catheterization systems, endovascular devices, monitoring equipment, and specialized OBL infrastructure.
Moreover, the study provides evidence of a broader shift in U.S. vascular care toward lower-acuity procedural settings. By 2023, ASC/OBLs had become the dominant setting for CLTI revascularization among Medicare beneficiaries, demonstrating the growing integration of office-based laboratories into the U.S. vascular care pathway.
The high capital requirements associated with establishing and operating office-based laboratories can restrain market expansion, particularly for smaller physician-owned facilities. OBLs require significant investments in advanced imaging and interventional equipment, facility infrastructure, trained personnel, compliance systems, and ongoing maintenance, while procedure volumes may take time to reach economically sustainable levels. In addition, changes in reimbursement can place further pressure on facility economics. Recent market analysis identifies reimbursement volatility, capital requirements, staffing costs, and state-level facility requirements as key operating constraints for OBLs.
The combination of high upfront investment, ongoing operating costs, and variable reimbursement can lengthen the time required for new OBLs to achieve financial sustainability, particularly in markets with lower procedure volumes or limited physician referral networks.
The increasing adoption of office-based laboratories for peripheral vascular interventions is creating opportunities for OBL operators to expand procedure volumes and broaden the range of vascular services offered. According to a 2024 Journal of Vascular Surgery study analyzing 848,526 Medicare peripheral vascular interventions found that 57.3% were performed in OBLs, while OBL utilization increased from 48.3% in 2017 to 65.5% in 2022. The study also found greater use of atherectomy and tibial interventions in OBL settings, indicating an expanding procedural scope beyond relatively simple interventions.
This shift creates opportunities for OBLs to increase procedural capacity, invest in advanced imaging and endovascular technologies, and expand specialized vascular services, particularly as more cardiovascular procedures are performed in outpatient settings. Recent JACC research also highlights the broader migration of cardiovascular procedures toward ASCs and OBLs as technological advances enable more procedures to be performed with same-day discharge.
Market Concentration & Characteristics
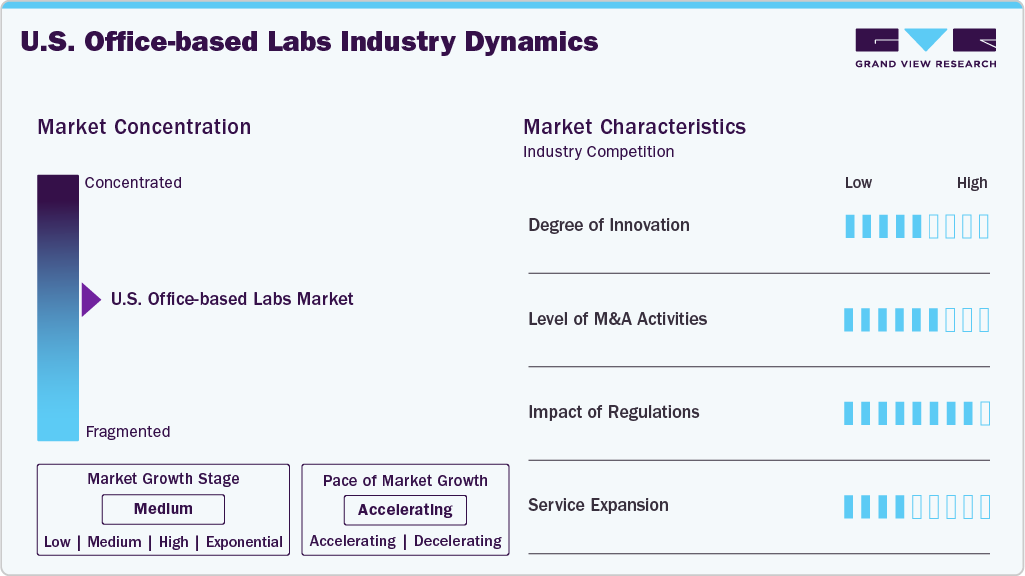
The chart below illustrates the relationship between market concentration, market characteristics, and market participants. The degree of innovation is medium, the level of partnerships & collaborations activities is medium, the impact of regulations on the market is high, the service expansion is medium, and regional expansion is medium.
Innovation in industry is medium, supported by the adoption of advanced imaging, minimally invasive technologies, digital workflow solutions, and increasingly complex endovascular procedures. OBLs are expanding their capabilities as technological advancements allow a broader range of vascular and interventional procedures to be performed in outpatient settings. For instance, a 2025 Journal of Vascular Surgery article highlighted the development of OBL-based vascular care models, including dedicated office-based vein centers, supported by advanced outpatient procedural capabilities and physician-controlled care environments.
 To learn more about this report, Download Free Sample Report
The level of partnerships & collaborations activities in the market is medium, as OBL operators increasingly collaborate with physicians, medical device companies, healthcare organizations, and management platforms to strengthen procedural capabilities and operational efficiency. In May 2026, Labcorp expanded its collaboration with Epic to make Labcorp’s full diagnostic test menu available through Epic’s Aura platform, which supports laboratory test ordering and results delivery.
"This expanded collaboration reflects how Labcorp is investing to meet the evolving needs of hospitals and health systems," "By simplifying lab integrations and delivering our full test menu directly within Epic workflows, we are expanding access and building a strong foundation for continued innovation."
- Bryan Vaughn, Executive Vice President and President of Diagnostics at Labcorp.
The impact of regulations on the sector is high, as OBL operators must comply with Medicare reimbursement policies, billing requirements, facility standards, clinical documentation, patient safety requirements, and applicable state-level regulations. Changes in reimbursement policies can directly influence the economic viability of procedures performed in OBL settings. For instance, in November 2024, the Centers for Medicare & Medicaid Services (CMS) finalized the CY 2025 Medicare Physician Fee Schedule, introducing changes to Medicare payment policies affecting physician services across office and other outpatient settings. Such payment-policy changes require OBL operators to continuously assess reimbursement levels, procedural economics, and operating models.
The level of regional expansion in the market is medium, with OBL presence varying considerably across states and geographic markets. In May 2026, ICON plc announced the opening of a 69,500-square-foot Clinical Research Unit (CRU) in San Antonio, Texas, along with two satellite outpatient clinics in Houston, Texas, and Lawrence, Kansas. The expansion is intended to increase capacity for first-in-human, healthy-volunteer, and patient-cohort studies.
"We've designed the clinic to improve the experience of study participants, while scaling our capacity and maintaining our high-quality standards. By fully integrating our clinical, laboratory, and pharmacy operations under one roof, we can largely eliminate logistical delays. This translates directly into faster dosing, real-time adaptability, and accelerated delivery of high-quality data for our sponsors. We are proud to invest in the San Antonio life sciences community and to contribute to its continued growth as a hub for innovation.”
- Dr. Ute Berger, ICON’s Chief Medical Officer and President, Development Solutions.
Analyst Perspective
The market is increasingly driven by the shift of minimally invasive procedures from hospitals to physician-owned and affiliated outpatient settings. Growth depends not only on procedure migration but also on whether office-based labs (OBLs) can maintain sufficient procedure volumes and reimbursement levels to support investments in specialized equipment, staffing, and accreditation. Facilities with strong referral networks, high-demand specialties such as interventional pain management and vascular care, and efficient patient throughput are better positioned to improve profitability. However, market expansion remains influenced by payer coverage policies, regulatory requirements, and the costs associated with establishing compliant procedural infrastructure. Importantly, procedure migration does not automatically result in market growth. A 2026 U.S. Department of Health and Human Services Office of Inspector General review found that while the share of Medicare peripheral vascular procedures performed in OBLs increased between 2019 and 2023, overall procedure volumes declined. The review also identified USD 105 million in potentially concerning payments, emphasizing the need for appropriate procedure selection, accurate documentation, and strong billing compliance practices.
Service Insights
The peripheral vascular intervention (PAD) segment held the largest revenue share of 36.5% in 2025. The increasing prevalence of PAD, growing preference for minimally invasive interventions, and advances in endovascular technologies are supporting the adoption of peripheral vascular procedures in office-based laboratories. In addition, the expansion of advanced catheter-based technologies also enables OBLs to manage a broader range of peripheral vascular conditions while maintaining efficient procedural workflows. For instance, in January 2025, a study published in the Journal of Vascular Surgery evaluated 1,408 peripheral arterial interventions performed in an office-based catheter laboratory between October 2018 and October 2023, including 27 procedures using popliteal artery access for iliofemoral occlusive disease. The study reported successful revascularization in 25 of the 27 cases, with all patients discharged approximately one hour after the procedure, demonstrating the capability of OBLs to perform specialized peripheral vascular interventions in an outpatient environment.
The cardiac segment is expected to grow at a significant CAGR over the forecast period. The increasing prevalence of cardiovascular diseases, combined with technological advancements in minimally invasive cardiac procedures, is supporting the migration of selected cardiac interventions into office-based and other outpatient settings. OBLs are increasingly incorporating cardiovascular diagnostic and interventional capabilities, including cardiac catheterization and electrophysiology-related procedures, where appropriate patient selection and procedural infrastructure support outpatient treatment. This trend is further supported by the growing emphasis on same-day discharge, lower-cost care delivery, and improved patient convenience. For instance, in July 2025, the American College of Cardiology highlighted the continued migration of cardiovascular procedures from hospital settings toward outpatient facilities, including OBLs and ASCs, as advances in technology, physician autonomy, same-day discharge, and cost considerations support the delivery of an expanding range of cardiovascular procedures outside traditional hospital environments.
Modality Insights
The single-specialty segment held the largest revenue share of 41.3% in 2025. These labs are widely used for focused procedural care, particularly in vascular and endovascular interventions, where dedicated facilities can streamline clinical workflows and improve physician and staff specialization. The concentration of procedures within a specific specialty also enables OBL operators to optimize equipment utilization, staffing, scheduling, and patient throughput while maintaining a lower-complexity outpatient environment compared with hospital-based facilities. The strong presence of vascular-focused OBLs is further supported by the increasing migration of peripheral vascular interventions toward outpatient settings. For instance, The Vascular Care Group’s Hyannis, Massachusetts facility operates as a dedicated vascular-focused office-based laboratory, providing advanced vascular and vein care to patients across Cape Cod and southeastern Massachusetts.
The hybrid segment is expected to grow at a significant CAGR over the forecast period. Hybrid OBL models combine office-based laboratory and ambulatory surgical center capabilities, allowing operators to match the site of care with the complexity of individual procedures. Lower-acuity diagnostic and interventional procedures can be performed through the OBL component, while procedures requiring deeper sedation, advanced anesthesia support, or more extensive post-procedure monitoring can be accommodated through the ASC component. This integrated model enables healthcare providers to broaden their procedural portfolio, improve facility utilization, and provide greater flexibility in managing increasingly complex outpatient interventions.
Specialist Insights
The vascular surgeons segment dominated the U.S. office-based labs market, accounting for the largest revenue share of 40.2% in 2025. Vascular surgeons remain central to the OBL market because of their strong involvement in peripheral vascular interventions, endovascular procedures, dialysis access, and other minimally invasive vascular treatments. The increasing adoption of advanced endovascular technologies and the migration of vascular procedures toward outpatient settings are further supporting demand for vascular specialists with OBL expertise. For instance, a 2026 study published in Annals of Vascular Surgery evaluated the impact of an OBL within a university vascular surgery program and found that establishment of the OBL was associated with a 57% increase in overall trainee vascular case volume and a 55% increase in endovascular case volume. The study also reported 1,892 OBL cases, with only four emergency transfers to the main hospital, highlighting the growing role of OBLs within contemporary vascular surgery practice.
 To learn more about this report, Download Free Sample Report
The interventional radiologists segment is expected to grow at a significant CAGR over the forecast period. Interventional radiologists use minimally invasive, image-guided techniques to diagnose and treat vascular and other conditions, including angiography, angioplasty, stent placement, thrombectomy, venous interventions, and image-guided ablation procedures. The expansion of OBLs provides interventional radiologists with greater opportunities to perform selected procedures in outpatient environments while improving procedural efficiency and patient convenience. For instance, a 2024 review published in Techniques in Vascular and Interventional Radiology examined business and corporate models for interventional radiologists operating in OBL and ASC settings, highlighting the increasing transition of interventional radiology toward outpatient facilities and the role of management services and private-equity-backed models in supporting OBL development.
Key U.S. Office-based Labs Company Insights
The U.S. office-based labs market players are focusing on devising innovative business growth strategies in the form of product portfolio expansions, partnerships & collaborations, mergers & acquisitions, and business footprint expansions.
Key U.S. Office-based Labs Companies:
-
Koninklijke Philips N.V.
-
GE Healthcare
-
Siemens Healthineers AG
-
Medtronic
-
Boston Scientific Corporation or its affiliates
-
Abbott
-
Envision Healthcare Corporation (Bass, Berry & Sims PLC.)
-
Surgical Care Affiliates (SCA)
-
Surgery Partners
-
Cardiovascular Coalition
-
Tenet Healthcare Corporation(TH Medical)
-
The Vascular Care Group
-
Coastal Vascular Institute(Novant Health)
-
Penn Medicine Physicians (The Trustees of the University of Pennsylvania)
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., Koninklijke Philips N.V.; GE Healthcare; Siemens Healthineers AG; Medtronic; Boston Scientific Corporation or its affiliates; Abbott;)
- Focus on expanding OBL capabilities through advanced imaging and interventional technologies, physician partnerships, facility development, acquisitions, hospital affiliations, and integration of outpatient procedural services. Medical technology companies emphasize development and deployment of imaging, navigation, catheter-based, and interventional solutions, while healthcare operators focus on expanding OBL networks, recruiting specialists, developing dedicated facilities, and integrating outpatient services with broader healthcare systems.
- Strong brand recognition, extensive medical technology portfolios, established physician and healthcare-provider relationships, significant financial resources, and broad operational capabilities. Healthcare operators benefit from existing hospital and specialty-care infrastructure, physician networks, and experience managing high-volume outpatient procedures. Their scale also supports investment in advanced imaging, interventional equipment, digital technologies, and specialized OBL infrastructure.
- Large organizational structures can result in complex decision-making and slower implementation of new operating models. Medical technology companies are also dependent on OBL operators and physicians for technology adoption, while large healthcare operators may face high capital requirements, regulatory complexity, staffing challenges, and operational costs associated with developing and maintaining OBL facilities.
Emerging Players (e.g., Cardiovascular Coalition; The Vascular Care Group; Coastal Vascular Institute (Novant Health))
- Focus on expanding specialized OBL networks through physician partnerships, specialty-focused facility development, regional expansion, strategic affiliations, and investment in minimally invasive vascular and cardiovascular procedures. These organizations emphasize dedicated outpatient environments for peripheral vascular, venous, cardiovascular, and other interventional procedures while building localized referral networks and improving procedural accessibility.
- Greater flexibility in operating models, faster decision-making, strong physician alignment, specialty-focused expertise, and the ability to develop OBL facilities around specific procedural needs and regional demand. Their focused vascular and cardiovascular capabilities enable them to optimize staffing, equipment utilization, procedural workflows, and patient throughput within dedicated outpatient environments.
- Smaller geographic footprints, comparatively lower financial resources, limited brand recognition, and greater dependence on physician recruitment and local referral networks. Emerging OBL operators can also face challenges related to high equipment and facility investment, reimbursement variability, regulatory compliance, and achieving sufficient procedure volumes to support facility economics.
Recent Developments
-
In March 2026, DeviceGuide technology received U.S. FDA 510(k) clearance for use in minimally invasive mitral valve repair. The AI-enabled system assists physicians by providing live visualization of repair-device location and movement and connects with the Azurion image-guided therapy environment.
-
In March 2026, Philips launched IntraSight Plus in the U.S. and Europe, an interventional cardiology platform combining treatment-planning tools and diagnostics for coronary interventions. The platform received FDA 510(k) clearance and is designed to streamline workflow, with Philips reporting potential system-operation time savings of up to 47%.
-
In February 2026, GE HealthCare received 510(k) clearance for Allia Moveo from U.S. FDA, a compact, cable-free C-arm designed for cardiovascular, vascular, non-vascular, interventional, and surgical procedures. The platform incorporates AI-powered guidance tools, flexible positioning, and advanced 3D imaging capabilities. Baylor St. Luke’s Medical Center in Houston became the first U.S. installation, demonstrating adoption of advanced interventional imaging technology in the U.S
-
In November 2025, CUC Inc. entered into a strategic partnership with Dr. Yuji Okuno to expand catheter-based embolotherapy for chronic pain in the U.S. through newly developed office-based laboratories. Under the agreement, CUC plans to establish 5-7 OBL locations during the first year and approximately 20 locations nationwide within three years, supported by physician and nursing training programs and advanced catheter-based treatment capabilities.
U.S. Office-based Labs Market Report Scope
Report Attribute
Details
Market size in 2025
USD 15.1 billion
Estimated market size in 2026
USD 16.6 Billion
Projected market size by 2033
USD 35.2 billion
Growth Rate
CAGR of 11.3% from 2026 to 2033
Actual Data
2021 - 2025
Forecast Data
2026 - 2033
Quantitative units
Revenue in USD billion/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Services, modality, specialist, region
Country scope
U.S.
Key companies profiled
Koninklijke Philips N.V., GE Healthcare, Siemens Healthineers AG, Medtronic, Boston Scientific Corporation or its affiliates, Abbott, Envision Healthcare Corporation (Bass, Berry & Sims PLC.), Surgical Care Affiliates (SCA), Surgery Partners, Cardiovascular Coalition, Tenet Healthcare Corporation(TH Medical), The Vascular Care Group, Coastal Vascular Institute(Novant Health), Penn Medicine Physicians (The Trustees of the University of Pennsylvania)
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
U.S. Office-based Labs Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis on industry trends in each of the segments from 2021 to 2033. For the purpose of this study, Grand View Research, Inc. has segmented the U.S. office-based labs market report on the basis of service, modality, and specialist:
-
Service Outlook (Number of Procedures, 2021 - 2033)
-
Peripheral Vascular Intervention
-
Atherectomy
-
Vascular Angioplasty
-
Stenting
-
Other PVI
-
-
Endovascular Interventions
-
Cardiac
-
Interventional radiology
-
Uterine Fibroid Embolization (UFE)
-
Prostate Artery Embolization (PAE)
-
Y90/Oncology
-
Other IR
-
-
Venous
-
RFA (Radiofrequency Ablation) and EVLT (Endovenous Laser Therapy)
-
Sclerotherapy/Glue
-
Venous Stenting
-
Other Deep Vein
-
-
Others
-
-
Modality Outlook (Revenue, USD Million, 2021 - 2033)
-
Single Specialty
-
Multi-Specialty
-
Hybrid
-
-
Specialist Outlook (Revenue, USD Million, 2021 - 2033)
-
Vascular Surgeons
-
Interventional Cardiologists
-
Interventional Radiologists
-
Others
-
-
Region Outlook (Revenue, USD Million, 2021 - 2033)
-
Northeast
-
Southeast
-
Southwest
-
Midwest
-
West
-
Research Methodology
The U.S. office-based labs market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each U.S. office-based labs segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Services
Revenue capture definition
Peripheral Vascular Intervention
Minimally invasive procedures performed in office-based laboratories to diagnose and treat diseases affecting peripheral blood vessels, particularly arteries of the lower extremities, using catheter-based intervention techniques.
Atherectomy
Peripheral vascular intervention procedures that use specialized catheter-based devices to remove, debulk, or modify atherosclerotic plaque from diseased peripheral arteries to improve blood flow.
Vascular Angioplasty
Catheter-based procedures that use balloon angioplasty to dilate narrowed or obstructed peripheral blood vessels and restore or improve blood flow without requiring open vascular surgery.
Stenting
Peripheral vascular procedures involve placement of a vascular stent within a narrowed or obstructed artery to provide structural support and maintain vessel patency following lesion treatment.
Other PVI
Other peripheral vascular intervention procedures performed in OBLs that fall outside atherectomy, angioplasty, and stenting, including selected catheter-based techniques for peripheral arterial disease.
Endovascular Interventions
Minimally invasive procedures performed through vascular access using catheters, guidewires, and other endovascular devices to diagnose or treat vascular conditions without conventional open surgery.
Cardiac
Catheter-based cardiovascular procedures performed in office-based laboratories to evaluate or treat selected cardiac and coronary conditions, including diagnostic and interventional procedures appropriate for an outpatient setting.
Interventional Radiology
Image-guided minimally invasive procedures performed by interventional radiologists to diagnose or treat vascular, oncological, and other conditions using catheters, embolization devices, and related interventional technologies.
Uterine Fibroid Embolization (UFE)
Minimally invasive interventional radiology procedures that deliver embolic agents through uterine arteries to reduce blood flow to uterine fibroids, causing them to shrink and relieve associated symptoms.
Prostate Artery Embolization (PAE)
Image-guided embolization procedures that selectively block blood flow to the prostate to reduce prostate volume and alleviate lower urinary tract symptoms associated with benign prostatic hyperplasia.
Y90/Oncology
Interventional radiology procedures using Yttrium-90 or other catheter-based technologies to deliver localized treatment to tumors, particularly through selective internal radiation therapy for appropriate liver and other oncological applications.
Other IR
Other image-guided interventional radiology procedures performed in OBLs outside UFE, PAE, and Y90/oncology applications, including selected biopsy, drainage, embolization, and vascular interventions.
Venous
Minimally invasive procedures performed in OBLs to diagnose and treat venous diseases, including superficial and deep venous disorders, using ablation, sclerotherapy, stenting, and other catheter-based techniques.
RFA and EVLT
Endovenous procedures used to treat symptomatic superficial venous insufficiency by applying radiofrequency energy or laser energy through a catheter to close the affected vein and redirect blood flow to healthier veins.
Sclerotherapy/Glue
Minimally invasive venous treatments that use injectable sclerosant agents or medical adhesive to close diseased veins and reduce abnormal venous blood flow, particularly in patients with venous insufficiency or varicose veins.
Venous Stenting
Endovascular procedures involve placement of a stent within a narrowed or obstructed vein to restore venous blood flow and maintain vessel patency, particularly in selected patients with deep venous obstruction.
Other Deep Vein
Other minimally invasive procedures targeting deep venous conditions that fall outside venous ablation, sclerotherapy/glue, and venous stenting, including selected catheter-based interventions for deep vein disease.
Others
Other procedures performed in U.S. office-based laboratories that fall outside the major peripheral vascular, endovascular, cardiac, interventional radiology, and venous procedure categories.
By Modality
Revenue capture definition
Single Specialty
Office-based laboratories focused primarily on procedures within one clinical specialty, such as vascular intervention, cardiology, or interventional radiology, with facility resources and physician expertise dedicated to that specialty.
Multi-Specialty
Office-based laboratories that provide procedures across multiple medical or interventional specialties within the same facility, allowing different specialists and procedural services to operate under a shared outpatient infrastructure.
Hybrid
Office-based laboratory models combining characteristics of single- and multi-specialty facilities, typically integrating multiple procedural capabilities or specialties within a facility while maintaining specialized service lines.
By Specialist
Revenue capture definition
Vascular Surgeons
Physicians specializing in the diagnosis and treatment of vascular diseases who perform catheter-based and minimally invasive vascular procedures in OBL settings, including peripheral angioplasty, atherectomy, stenting, and venous interventions.
Interventional Cardiologists
Cardiovascular specialists trained to perform catheter-based diagnostic and therapeutic procedures for coronary and other cardiovascular conditions, including selected interventions conducted in office-based laboratory settings.
Interventional Radiologists
Physicians specializing in image-guided minimally invasive procedures who use fluoroscopy, ultrasound, CT, and other imaging modalities to perform vascular, embolization, oncological, and other interventions in OBLs.
Others
Other physician specialists and qualified healthcare professionals involved in procedures performed at OBLs, including specialists participating in selected vascular, cardiac, venous, or image-guided outpatient interventions outside the primary specialist categories.
Estimation Model
Section
Key Summary
1.1 Research Approach
Hybrid research approach combining secondary and primary research methodologies. Market assessment is based on the number of office-based laboratories, facility capacity, procedure volumes, patient volumes, physician and specialist participation, reimbursement rates, procedure mix, payer mix, operating expenses, facility ownership structures, and geographic distribution. Insights from OBL operators, vascular and cardiovascular physician groups, hospitals and health systems, medical device companies, private equity firms, healthcare management organizations, payers, and industry experts are used to validate market estimates.
1.2 Market Estimation Framework
Market size is estimated using three approaches: (1) procedure volume and facility capacity model, (2) revenue and reimbursement model, and (3) key participant revenue validation model. These approaches are triangulated to determine the overall market size and forecast projections.
1.2.1 Demand Model
Estimates market demand based on the number of operating office-based laboratories, facility capacity, procedure volumes, patient volumes, physician participation, specialist mix, procedure complexity, geographic distribution, facility utilization, and healthcare service utilization. Demand assessment also considers the migration of appropriate cardiovascular, peripheral vascular, endovascular, interventional radiology, venous, and other minimally invasive procedures from hospital settings to outpatient office-based facilities.
1.2.2 Revenue Model
Market value is calculated based on revenues generated from procedures and services performed in office-based laboratories. The model considers procedure volumes, average reimbursement per procedure, payer mix, commercial and government reimbursement, facility fees, physician professional fees where applicable, specialty-specific revenue, ancillary services, and revenue generated across peripheral vascular, endovascular, cardiac, interventional radiology, venous, and other OBL procedures. The model also incorporates differences in reimbursement and procedure economics across facility types, specialties, and geographic regions.
1.2.3 Vendor Model
Market estimates are validated using revenues and operating activities of key OBL ecosystem participants, including physician-owned OBLs, hospital-affiliated facilities, healthcare management organizations, private-equity-backed OBL platforms, and medical technology companies supplying imaging and interventional equipment. Validation factors include OBL locations, facility openings, procedure capacity, physician and specialist participation, procedure volumes, revenue disclosures, acquisitions, partnerships, geographic expansion, new facility development, equipment investments, and financial disclosures of leading companies and healthcare organizations.
1.3 Forecast Development
Forecast projections are developed by analyzing the migration of appropriate procedures from hospitals to outpatient settings, expansion of OBL networks, growth in cardiovascular and peripheral vascular procedures, increasing adoption of minimally invasive interventions, advances in imaging and interventional technologies, physician preference for greater procedural autonomy, expansion of specialty-focused facilities, changes in reimbursement, healthcare utilization, physician recruitment, private equity investment, OBL acquisitions and partnerships, geographic expansion, and increasing demand for cost-efficient and convenient outpatient care.
1.4 Segmentation Method
Market segmentation is determined using weighted analysis of OBL facility volumes, procedure volumes, facility type, specialty mix, service mix, physician participation, facility ownership structure, patient volumes, facility utilization, reimbursement levels, payer mix, healthcare utilization, geographic distribution, procedure complexity, and expansion of OBL networks. Segmentation also considers the relative contribution of single-specialty, multi-specialty, and hybrid OBL models and the distribution of procedures across peripheral vascular, endovascular, cardiac, interventional radiology, venous, and other services
1.5 Scope & Assumptions
Market is measured in USD based on revenues generated by office-based laboratories and OBL-delivered procedural services in the U.S. Estimates incorporate the number of OBL facilities, facility capacity, procedure and patient volumes, physician and specialist participation, procedure mix, reimbursement rates, payer mix, facility utilization, practice and facility locations, ownership structure, facility operating expenses, equipment investments, specialty distribution, and regional variations in healthcare utilization and OBL adoption. The scope covers revenues associated with eligible procedures and services delivered through office-based laboratory settings, including peripheral vascular, endovascular, cardiac, interventional radiology, venous, and other minimally invasive interventions.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Procedure Volume & Specialty Mix Analysis
Assessed OBL procedures across peripheral vascular interventions, venous interventions, interventional pain management, interventional radiology, and other minimally invasive procedures. Evaluated procedure volumes, specialty concentration, complexity, and service-line mix.
Identifies high-volume service lines, opportunities to diversify procedure offerings, and potential areas for capacity expansion and investment.
Physician Participation & Referral Network Analysis
Evaluated participation by vascular surgeons, interventional radiologists, interventional cardiologists, pain management specialists, and other relevant physicians. Assessed physician ownership, referral relationships, specialist concentration, and practice affiliations.
Supports physician recruitment, referral network development, partnership planning, and identification of markets with an established specialist base.
Geographic Market Penetration & White-Space Analysis
Mapped OBL presence across U.S. states and metropolitan areas, evaluating facility density, population demographics, specialist availability, competing outpatient settings, and potential unmet procedural demand.
Helps identify underserved markets, prioritize geographic expansion, and assess competitive intensity before entering new locations.
OBL Reimbursement & Payer Mix Analysis
Evaluated Medicare, Medicare Advantage, commercial payer, and other reimbursement considerations across key OBL procedures, including coverage policies, payment differences, and relevant state-level requirements.
Enables stakeholders to assess revenue potential, identify reimbursement-sensitive procedures, evaluate payer exposure, and develop more informed financial projections.
Hospital-to-OBL Procedure Migration Analysis
Assessed the shift of eligible outpatient procedures from hospital outpatient departments and ambulatory surgery centers to OBLs, considering procedure suitability, site-of-service economics, patient convenience, and reimbursement differentials.
Helps quantify potential procedure migration opportunities and evaluate which service lines may be suitable for expansion into office-based settings.
Facility Economics & Utilization Analysis
Evaluated procedure throughput, room utilization, staffing requirements, equipment investments, operating costs, and facility capacity across different OBL models and specialty mixes.
Supports facility feasibility assessments, capital allocation, operational benchmarking, and identification of utilization levels needed to improve financial sustainability.
Technology & Equipment Investment Analysis
Examined adoption of angiography and fluoroscopy systems, vascular imaging equipment, digital documentation, procedure monitoring technologies, and other infrastructure relevant to OBL operations.
Identifies technology investment priorities, modernization opportunities, and potential capability gaps affecting procedural efficiency and service expansion
Frequently Asked Questions About This Report
The U.S. office-based labs market size was estimated at USD 15.1 billion in 2025 and is projected from USD 16.6 billion in 2026.
The U.S. office-based labs market is expected to grow at a compound annual growth rate of 11.3% from 2026 to 2033 to reach at a value of 35.2 billion in 2033.
In terms of modality, the single specialty segment held the largest revenue share of 41.3% in 2025. These labs are widely used for focused procedural care, particularly in vascular and endovascular interventions, where dedicated facilities streamline clinical workflows and improve physician and staff specialization.
Among medical imaging device manufacturers, Philips Healthcare, Siemens Healthineers, and GE Healthcare are the key providers of equipment required in setting up OBLs.Many service providers are available in the U.S., such as National Cardiovascular Partners and Envision Healthcare and Surgery Partners.
The increasing trend of surgical procedures being performed in outpatient settings and the rising incidence of various vascular diseases are among the major factors driving the OBL market in the U.S.
In terms of services, the peripheral vascular intervention group segment held the largest revenue share of 36.5% in 2025. The increasing prevalence of PAD, growing preference for minimally invasive interventions, and advances in endovascular technologies are supporting the adoption of peripheral vascular procedures in office-based laboratories.
In terms of specialist, vascular surgeons segment dominated the U.S. office-based labs market, accounting for the largest revenue share of 40.2% in 2025.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


