
- Home
- »
- Pharmaceuticals
- »
-
Ophthalmic Drugs Market Size And Share Report, 2026-2033GVR Report cover

Ophthalmic Drugs Market (2026 - 2033)
Size, Share & Trends Analysis Report By Drug Class (Steroidal drugs, Anti-VEGF Agents), By Disease, By Dosage Form, By Route of Administration, By Product, By Drug Type, By Region, And Segment Forecasts
Market Size, 2025
$41.4BMarket Estimate, 2026
$44.7BMarket Forecast, 2033
$79.4BCAGR, 2026–2033
8.5%Ophthalmic Drugs Market Summary
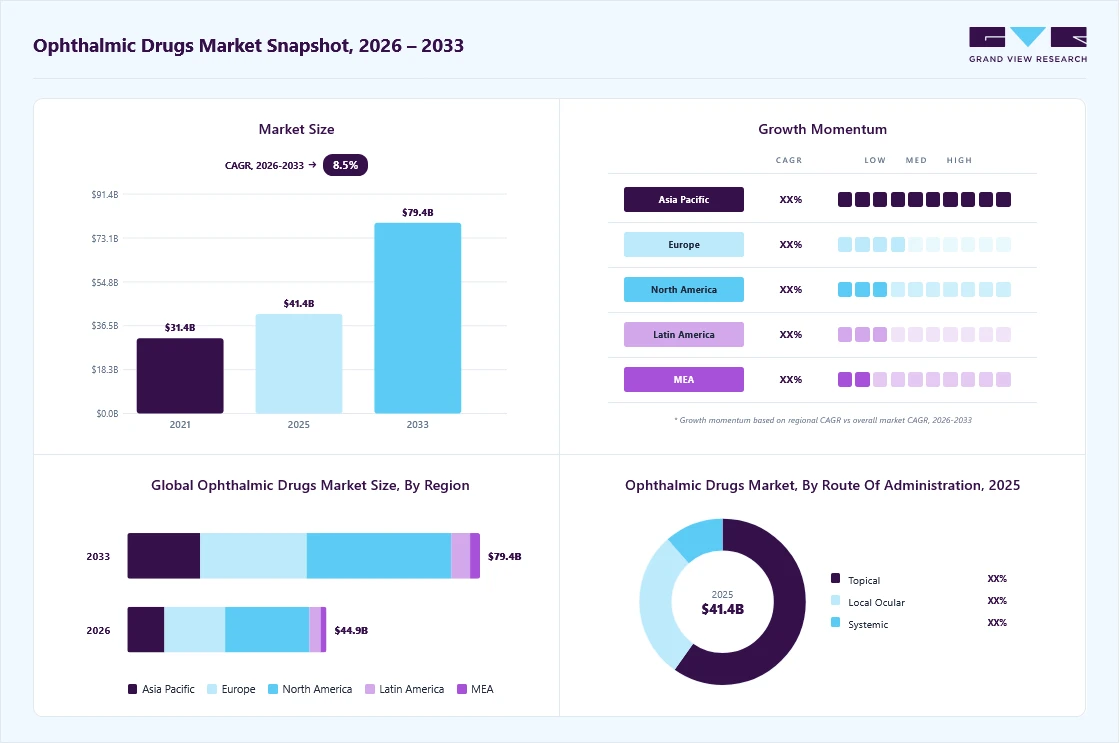
The global ophthalmic drugs market size was valued at USD 41.4 billion in 2025 and is projected to grow from USD 44.7 billion in 2026 to USD 79.4 billion by 2033, at a CAGR of 8.5% from 2026 to 2033. The market in North America dominated with a revenue share of 42.5% in 2025. The market growth is attributed to the rising prevalence of eye disease, advancements in drug delivery, and an increasing focus on research for development of novel therapeutics in the market.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By drug class: Anti-VEGF agents segment held the largest market share of 34.2% in 2025.
- By disease: Retinal disorders segment held the largest market share of 38.7% in 2025.
- By route of administration: Topical segment held the largest market share of 59.7% in 2025.
- By dosage form: Eye drops segment held the largest market share of 36.2% in 2025.
- By product: Prescription drugs segment held the largest market share of 57.7% in 2025.
Regional Highlights
- Largest regional market: North America (42.5% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 41.4 Billion
- Estimated market size in 2026: USD 44.7 Billion
- Projected market size by 2033: USD 79.4 Billion
- CAGR (2026-2033): 8.5%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Eye diseases encompass a wide spectrum of morbidities that impact various components of the visual system and function. The increase in the prevalence of eye-related disorders, such as macular degeneration, diabetic retinopathy, and presbyopia, is one of the major factors driving the growth of the overall ophthalmic drug market. The increasing prevalence of these conditions is expected to boost the market. As per WHO, in 2023, approximately 2.2 billion people were visually impaired globally. Moreover, according to a study, “Global incidence and risk factors for glaucoma,” published by the Journal of Global Health in November 2024, the worldwide incidence rate of Primary Open-Angle Glaucoma (POAG) in 2022 was 23.46 cases per 10,000 person-years for individuals aged 40 to 79. Between 1990 and 2019, there was a notable rise in this rate, increasing from 5.51 cases per 10,000 person-years in the 40 to 44 age group to 64.36 cases per 10,000 person-years in the 75 to 79 age group. This rising prevalence of eye conditions significantly increases the demand for effective ophthalmic drugs over the forecast period.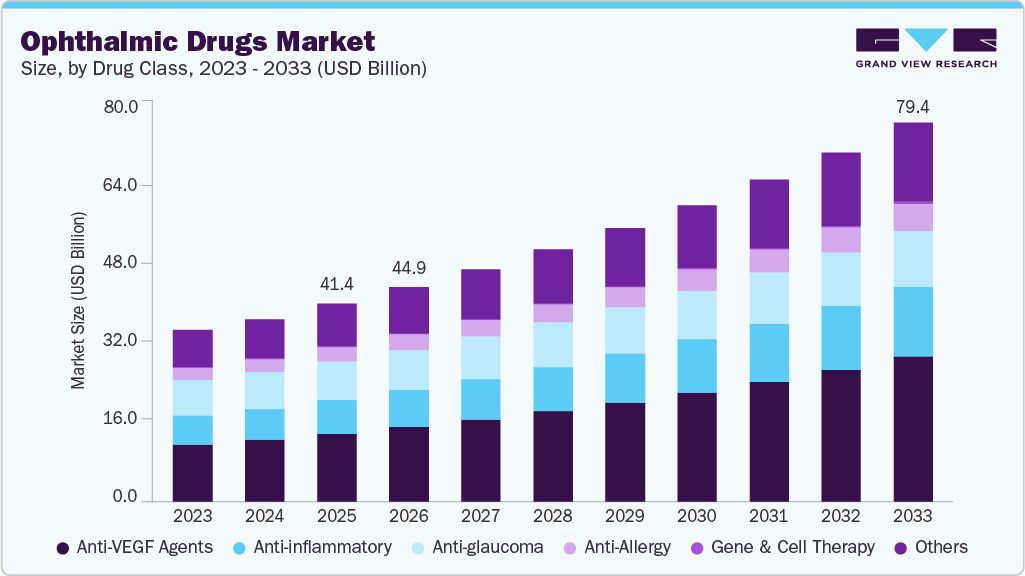 To learn more about this report, Download Free Sample Report
The growing geriatric population is anticipated to increase the number of people with eye conditions. According to the United Nations, the share of individuals aged 65 and older is growing more rapidly than that of younger populations. As a result, the percentage of the global population in this age group is anticipated to increase from 10% in 2022 to 16% by 2050. By that year, it is estimated that the number of people aged 65 and above will be twice that of children under the age of 5 and nearly equal to the number of children under 12. Presbyopia, cataracts, glaucoma, and AMD become more common as people get older. This growing adult population, coupled with the increasing prevalence of conditions such as diabetes, significantly increases the risk of various eye conditions, thereby contributing to market growth. According to the WHO, the population of individuals diagnosed with diabetes increased from 200 million in 1990 to 830 million by 2022. Some eye disorders, such as glaucoma, refractive error, and retinal degeneration, including retinitis pigmentosa, are also influenced by genetics. Another non-modifiable risk factor associated with an increased risk of acquiring some eye disorders is ethnicity.
Moreover, increasing investment by public and private organizations is further propelling the growth of the market. For instance, in July 2023, the National Eye Institute announced funding of USD 2.5 million over five years to advance glaucoma treatment research at the Missouri University of Science and Technology.
Market Concentration & Characteristics
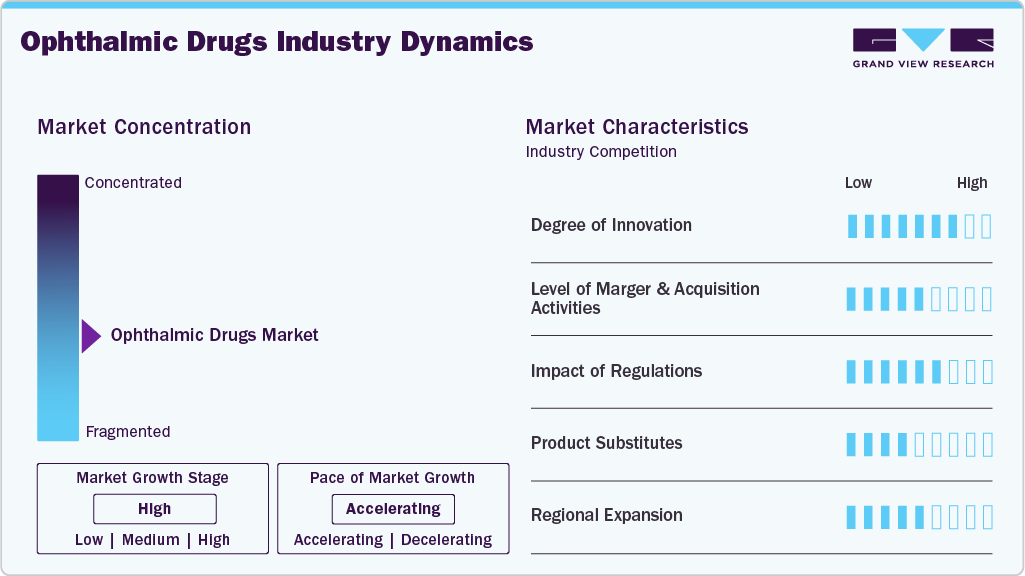
Themarket growth stage is high, and pace of the market growth is accelerating. The market is characterized by a high degree of innovation owing to the rapid advancements in drug delivery. The emergence of gene therapies as a potent drug-delivery mechanism is one of the strongest drivers of the market. For instance, EYLEA HD (aflibercept), a higher-concentration formulation approved in 2023, allows for extended dosing intervals of up to 16 weeks for AMD and DME, reducing the burden of frequent intravitreal injections.
The industry is witnessing a significant level of mergers and acquisitions, with companies adopting this strategy to expand their product portfolios and capabilities. For instance, in May 2024, Merck agreed to acquire EyeBio, an ophthalmology-focused biotech company. EyeBio’s lead candidate, Restoret, targets diabetic macular edema and neovascular age-related macular degeneration. The acquisition will significantly expand Merck’s ophthalmology portfolio and enhance its retinal disease treatment pipeline, with Restoret entering a pivotal trial in late 2024.
 To learn more about this report, Download Free Sample Report
The threat of substitutes in the ophthalmic drugs market is significantly low due to the specialized nature of these treatments and the lack of equally effective alternatives. Ophthalmic drugs, including prescription eye drops and specialized formulations, are often the primary treatment options for conditions such as glaucoma, dry eye disease, and retinal disorders. While alternatives such as surgical procedures, medical devices, or lifestyle changes exist, they are not direct substitutes but are used as complementary. Besides, the high efficacy, ease of administration, and continuous innovation in ophthalmic drugs further reduce substitution risks.
Regional expansion is driven by pharmaceutical companies seeking regulatory approvals in multiple countries to enhance market reach and revenue. For instance, in December 2024, Santen applied for approval in Japan for STN1013800 (oxymetazoline hydrochloride), an eye drop treatment for acquired blepharoptosis. The drug showed significant improvement in eyelid elevation in clinical trials, offering a non-surgical option for this condition. Oxymetazoline acts on Müller’s muscle to lift the eyelid.
Drug Class Insights
Anti-VEGF agents led the market and accounted for 34.2% of the global revenue in 2025. The segment growth is attributed to the rising prevalence of retinal disorders globally. This is anticipated to propel the sales of anti-VEGF agents, boosting segment growth. These agents are useful in ophthalmology for treating eye conditions that cause swelling or growth of new blood vessels around the retina. Moreover, increasing research activities related to anti-VEGF drugs for different ophthalmic disorders are improving the introduction of novel drugs to the market. In February 2023, Bayer AG submitted a regulatory approval application to the European Medicines Agency (EMA) for aflibercept 8 mg for neovascular (wet) age-related macular degeneration (nAMD) and diabetic macular edema (DME).
The gene and cell therapy segment is anticipated to grow at the fastest CAGR over the forecast period. Gene & cell therapy is a comparatively newer therapeutic option for treating eye diseases. The increasing adoption of these products due to high efficacy and effectiveness of drugs is expected to drive the segment growth significantly. Moreover, the increasing product approval and service providers in the market are driving segment growth. For instance, OHSU Casey Eye Institute is offering gene therapy treatment for people with inherited retinal disease due to a mutation in both copies of RPE65 gene.
Disease Insights
The retinal disorders segment dominated the market with the largest revenue share of 38.7% in 2025, mainly attributed to the growing incidence of retinal disorders around the globe and the need for effective and affordable treatment options for the same has driven the market. The U.S. CDC reports that diabetic retinopathy is likely to affect around 14.7 million Americans with diabetes by 2050. The leading drugs for treating retinal disorders are Lucentis, Eylea, and Avastin. Moreover, Platelet-Derived Growth Factor (PDGF) therapy is anticipated to be the new revolution in treating retinal disorders.
The uveitis segment is anticipated to witness strong growth over the forecast period, due to increasing awareness of the disease and its potential to cause preventable vision loss. Advancements in diagnostic imaging, such as optical coherence tomography and wide-field retinal imaging, have enabled earlier detection, which supports timely treatment uptake. The availability of improved therapeutic options, including corticosteroids, immunosuppressants, and targeted biologics, continues to broaden clinical choice and improve long-term outcomes. Sustained-release implants and novel delivery systems are also enhancing adherence, especially for chronic or recurrent cases where frequent dosing has traditionally been a challenge. Rising incidence linked to autoimmune disorders and infectious etiologies further contributes to expanding patient pools in several regions. Growing treatment guidelines, clinician training, and investment in specialty ophthalmology centers also strengthen adoption, making uveitis one of the more dynamic and innovation-driven segments in the ophthalmic drugs industry.
Route of Administration Insights
The topical segment dominated the market with the largest revenue share of 59.7% in 2025. Topical drug dosage forms generally include suspensions, solutions, and ointments. The cornea is the primary route of topical absorption that poses significant anatomical barriers. Availability of several drugs delivered via topical route of administration is estimated to be the major driver of this segment. For instance, phenylephrine, tetrahydrozoline, oxymetazoline, and naphazoline are currently available in the market as OTC ophthalmic decongestants. The topical use of oxymetazoline is generally indicated for improving symptoms such as itching, burning, and tearing associated with allergic conjunctivitis.
The local ocular route of administration segment is anticipated to grow at the fastest rate over the forecast period. Intraocular delivery route facilitates direct entry of drugs into blood retinal barrier and, therefore, the highest peak of drug concentration can be achieved. It achieves maximum intraocular bioavailability in posterior segment tissues of the eye, such as cone-containing fovea or macula. In May 2022, Alcon acquired Eysuvis pharmaceutical eye drops from Kala Pharmaceuticals for USD 60 million, paying for the rights to two commercial products based on mucus-penetrating particle drug delivery technology. Moreover, the company acquired Inveltys corticosteroid for treating postoperative inflammation and pain after ocular surgery. However, this is the most invasive route of administration, involving penetration of drugs in the eye and, thus, is not free of injection-related complications. These may include retinal hemorrhage, raised IOP, floaters, transient blurry vision, vitreous hemorrhage, retinal tears, retinal detachment, endophthalmitis, and cataracts.
Dosage Form Insights
The eye drops segment dominated the market with the largest revenue share of 36.2% in 2025. Eye drops are the most preferred form of drug delivery used for treating ocular diseases such as acute allergies, corneal ulcers, and glaucoma. The demand for enhanced ophthalmic treatments is driving companies to invest in pipeline developments. For instance, in April 2021, Bausch & Lomb and Novaliq GmbH (April 2021): Reported positive Phase 3 trial results for NOV03 (perfluorohexyloctane), a preservative-free investigational eye drop for treating dry eye disease (DED) associated with meibomian gland dysfunction. NOV03 is positioned to become the first FDA-approved prescription treatment for this condition. Such advancements are expected to fuel the segment growth.
The eye solutions & suspensions segment is anticipated to witness a significant growth rate over the forecast period. Eye solutions allow direct drug delivery, which is a distinct clinical advantage. Some of the most commonly used eye solutions include Moxeza, Ocuflox, and Neosporin. Eye solutions may also contain certain excipients to regulate viscosity, pH, and osmotic pressure. Presence of advanced technology for drug delivery in order to improve physicochemical stability & bioavailability is anticipated to boost the market growth. For instance, in January 2022, Sun Pharma launched its cyclosporine ophthalmic solution, CEQUA 0.09%, a novel treatment for DED affecting over 6 million Canadians living with the condition.
Product Insights
The prescription drugs segment dominated the market with the largest revenue share of 57.7% in 2025. Support from various private & public authorities to increase sales of prescription medicines is anticipated to boost segment growth. For instance, in May 2023, the U.S. FDA approved Bausch & Lomb and Novaliq’s Miebo for treating DED. It is the first & only prescription eye drop to receive the U.S FDA approval for DED. In addition, in March 2022, Bausch Health Companies, Inc. announced the commercial launch of XIPERE, a prescription drug used for the treatment of macular edema associated with uveitis. Moreover, increasing R&D activities for novel biologics, cell & gene therapies, and biosimilars are expected to increase the approval rate of novel prescription drugs in the coming years, propelling segment growth.
OTC drugs are anticipated to grow at the fastest CAGR over the forecast period. The growth of the segment is attributed to the increasing penetration of generics in the market, aided by the loss of patent exclusivity of major drugs. The relatively low cost of these drugs makes them affordable for a large patient base in low- and middle-income countries. Several strategic moves in the OTC market further contribute to segment growth. For instance, in July 2023, Bausch + Lomb acquired the Blink OTC eye drop line from Johnson & Johnson Vision for USD 106.5 million. The Blink portfolio, which includes products such as Blink Tears Lubricating Eye Drops and Blink Contacts Lubricating Eye Drops, addresses the rising demand for relief from dry eye and contact lens discomfort.
Drug Type Insights
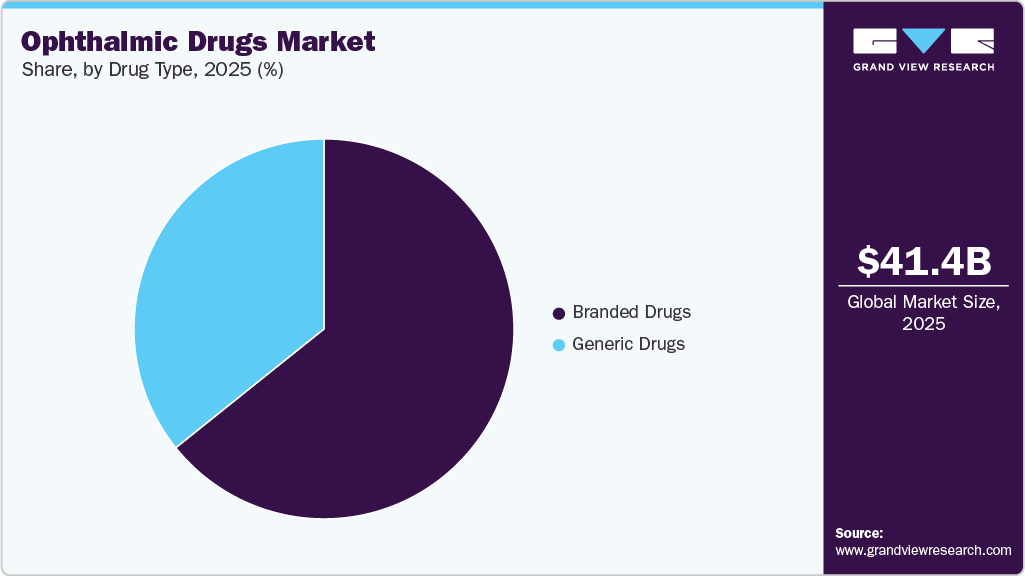
The branded drugs segment dominated the market with the largest revenue share of 64.2% in 2025. Several players are engaged in developing new treatments for various conditions, such as dry eye and glaucoma, as current treatments are known to provide temporary symptomatic relief. Hence, companies are developing long-acting, hands-free therapies to combat such challenges. In addition, ophthalmic pharmaceutical companies are entering into strategic initiatives, such as collaborations, acquisitions, and partnerships, to expand their product pipeline with new clinical-stage candidates, which is expected to boost the market.
 To learn more about this report, Download Free Sample Report
The generic drugs segment is projected to witness the fastest growth rate over the forecast period. Cost-effectiveness and patent expiry of branded drugs are some of the key factors supporting segment growth. Moreover, the generic drug is similar to an existing approved brand-name drug in terms of safety, dosage form, route of administration, quality, strength, and performance characteristics. However, the cost of generics is low, which provides an advantage to generic drugs for more prescriptions, especially in developing economies. Furthermore, government bodies are motivating drug manufacturers to increase the development of generic drugs, as they are top-selling ophthalmology drugs.
Regional Insights
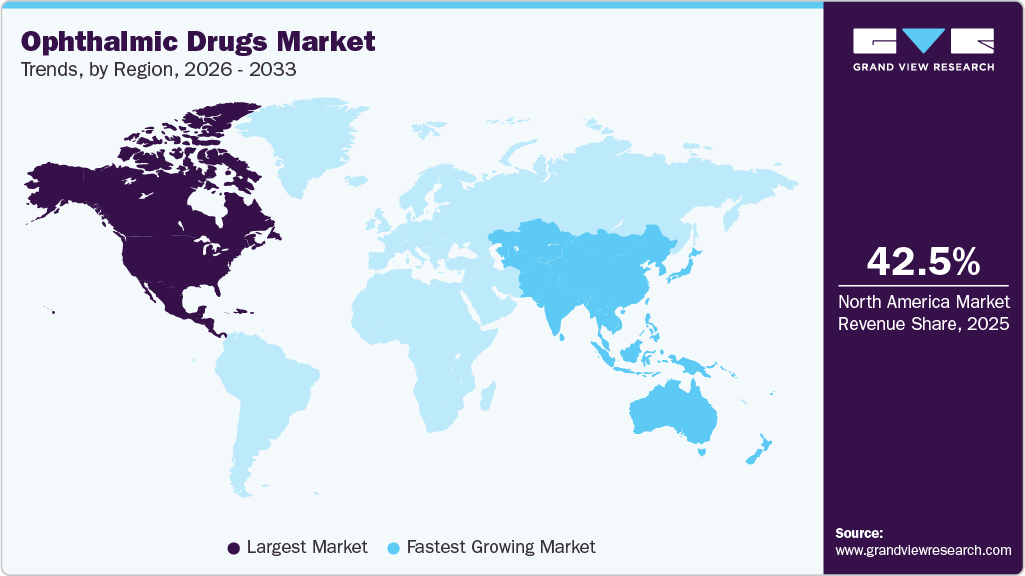
The North America ophthalmic drugs industry dominated the market and accounted for a 42.5% % share in 2025. This high share is owing to the rising prevalence of retinal diseases and favorable government initiatives in the region. North America is a developed region with high healthcare expenditure. Moreover, the high prevalence and increasing eye treatment procedures aid expansion in North America. The increasing aging population in the U.S. and Canada plays a significant role in this growing demand, as older adults are more vulnerable to eye conditions. Furthermore, the growing incidence of diabetes in the region has fueled the demand for ophthalmic drugs to manage diabetic eye diseases.
 To learn more about this report, Download Free Sample Report
U.S. Ophthalmic Drugs Market Trends
The ophthalmic drugs industry in the U.S. is expected to witness significant growth over the forecast period. The major factors driving market growth include the high prevalence of eye diseases, the aging population, technological advancements, and a supportive regulatory framework. According to the USAFacts, in 2022, nearly 1.8 million additional Americans reported having a vision disability compared to 2010, marking a 28% increase that outpaces the U.S. population growth rate of 8% during the same period. The percentage of the population experiencing vision difficulties rose from 2.1% to 2.5%. Among those with vision disabilities in 2022, individuals aged 65 and older represented 40.8%, while those aged 35 to 64 accounted for 38.4% of the total.
Europe Ophthalmic Drugs Market Trends
The ophthalmic drugs industry in Europe is driven by the increasing prevalence of diseases, advancements in diagnostic technology, and the region's aging population. The rising incidence of ophthalmic disorders in Europe is another significant factor contributing to market growth. According to the WHO, in the European region, around 90 million individuals experience some form of vision impairment or blindness, accounting for 9% of the total population. This means that 1 in every 10 people is affected by vision issues. Aging populations in countries such as Italy, Spain, and France have further led to a rise in other eye-related conditions. Governments across Europe are implementing public health initiatives aimed at early screening and management of these conditions, thus increasing the demand for therapeutic drugs.
The UK ophthalmic drugs industry is expected to grow over the forecast period due to the rising prevalence of eye diseases, the country’s aging population, and the evolving regulatory landscape. Furthermore, the increasing R&D initiatives for the development of advanced treatments for various eye conditions are further contributing to this growth. For instance, in January 2025, Glaucoma UK launched its largest-ever research grants program, offering USD 461,520 (£370,000) to support innovative projects aimed at improving the understanding, treatment, and care of glaucoma. Such initiatives are further expected to fuel the market growth in the country.
The ophthalmic drugs industry in Germany is expected to grow significantly over the forecast period. Germany's comprehensive healthcare system, better access to healthcare services, and increasing awareness about the importance of eye care are some of the major factors contributing to market growth.
Asia Pacific Ophthalmic Drugs Market Trends
The ophthalmic drugs industry in the Asia Pacific is expected to witness the fastest growth over the forecast period. The increasing burden of ophthalmic disorders and rising consumer awareness are expected to drive market growth in the region. Nearly two-thirds of the population in the Asia Pacific region is vision-impaired or blind. Moreover, the development of various novel technologies by research institutes in developing economies, such as China and India, is expected to improve healthcare facilities in the region. The presence of a well-distributed network of clinical laboratories and hospitals in India is enabling an improved market penetration of ophthalmic drugs. In addition, rapid economic development and an increase in awareness programs in this region are expected to drive market growth.
The China ophthalmic drugs industry is driven by an increasing demand for eye care solutions. This growth is fueled by a rising number of individuals suffering from eye diseases, particularly among the aging population. Age-related conditions such as cataracts, glaucoma, and macular degeneration have become more common, requiring advanced pharmaceutical treatments. Moreover, market players operating in the market are taking various initiatives to increase their market presence. For instance, in January 2025, Vyluma announced that the National Medical Products Administration of China accepted its drug application for NVK002, a treatment aimed at addressing myopia progression in children. This acceptance marks a significant step forward in the regulatory process for Vyluma's product in the Chinese market.
The ophthalmic drugs industry in Japan has witnessed the rising prevalence of eye disorders, which has increased the demand for cost-effective treatments, and the growing geriatric population has significantly contributed to market growth. According to the International Diabetes Federation, around 10.8 million adults in Japan had diabetes in 2024. Moreover, according to the Ministry of Internal Affairs and Communications, the geriatric population in Japan accounts for 29.1% of the total population.
Latin America Ophthalmic Drugs Market Trends
The ophthalmic drugs industry in Latin America has observed an increase in the incidence of dry eye disease, fueling the demand for effective care and treatment. Moreover, increasing efforts by various global organizations to increase eye care access and awareness in the region’s population further contribute to the market growth. For instance, in 2024, the International Agency for the Prevention of Blindness (IAPB’s) re-engagement in Latin America led to a tripling of membership since 2021. Key events included initiatives in Colombia and Paraguay aimed at integrating eye health services and addressing refractive errors. Such initiatives are expected to increase the demand for ophthalmic drugs in the region.
The Brazil ophthalmic drugs industry is expected to witness significant growth over the forecast period. In LATAM, Brazil has the largest population. Thus, the prevalence of target diseases in the country is high, which leads to an increased demand for therapeutics. Brazil has been witnessing positive economic growth due to the region's recent financial and political stability. The pharmaceutical industry has shown greater improvements than other industries in the country, owing to increasing government investments to enhance healthcare infrastructure.
Middle East and Africa Ophthalmic Drugs Market Trends
The ophthalmic drugs industry in the Middle East and Africa has witnessed a significant increase in the prevalence of eye diseases such as glaucoma, cataracts, and age-related macular degeneration. This rise is attributed to factors including an aging population, higher rates of diabetes leading to diabetic retinopathy, and increased exposure to environmental pollutants. Similarly, governments and healthcare organizations in the region are actively working to enhance awareness about eye health, leading to increased awareness among patients.
The Saudi Arabia ophthalmic drugs industry is witnessing significant growth, driven by demographic shifts and increasing healthcare awareness. Technological advancements in ophthalmic devices and drug delivery systems are also playing a crucial role in market growth. For instance, in October 2023, a consortium in Saudi Arabia launched "Eyenai," the first locally developed AI-powered ophthalmic solution for diabetic retinopathy screening. This innovative technology aims to enhance accessibility, affordability, and accuracy in eye care, marking a significant advancement in the nation's healthcare sector with plans for expansion across the Kingdom. The development of such solutions and advancements in the country’s healthcare sector increases the access to eye care for the wider patient population, thereby contributing to the rising demand for ophthalmic drugs.
Key Ophthalmic Drugs Company Insights
Some of the key players operating in the market include Alcon, Novartis AG, Bausch Health Companies, Inc., and Merck & Co., Inc., among others. The market is highly competitive, with a large number of manufacturers accounting for a majority of the share. New source developments, mergers and acquisitions, and collaborations are some of the major strategies adopted by these players to counter the high competition.
Key Ophthalmic Drugs Companies:
The following are the leading companies in the ophthalmic drugs market. These companies collectively hold the largest market share and dictate industry trends.
- Alcon
- Novartis AG
- Bausch Health Companies, Inc.
- Merck & Co., Inc.
- Regeneron Pharmaceuticals, Inc.
- Coherus BioSciences, Inc.
- AbbVie, Inc. (Allergan)
- Pfizer, Inc.
- Bayer AG
- Santen Pharmaceutical Co., Ltd.
- Roche (Genentech, Inc.)
- Nicox
Recent Developments
-
In December 2024, Santen announced that South Korea and Vietnam accepted for review of its New Drug Application for STN1013001 (cationic emulsion of latanoprost 50μg/mL) for treating open-angle glaucoma and ocular hypertension. This preservative-free drug improves ocular surface conditions while lowering intraocular pressure. The application is supported by positive results from a Phase III trial, demonstrating its non-inferiority to standard latanoprost and superiority in improving ocular surface disease.
-
In August 2023, Regeneron Pharmaceuticals, Inc. received approval for EYLEA HD (aflibercept), used for the treatment of wet age-related DME, macular degeneration (wAMD), and diabetic retinopathy.
Ophthalmic Drugs Market Report Scope
Report Attribute
Details
Market size in 2025
USD 41.4 billion
Estimated market size in 2026
USD 44.7 billion
Projected market size by 2033
USD 79.4 billion
Growth rate
CAGR of 8.5% from 2026 to 2033
Actual data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Drug class, disease, dosage form, route of administration, product, drug type, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East and Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Sweden; Denmark; Norway; China; Japan; India; Australia; South Korea; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait
Key companies profiled
Alcon; Novartis AG; Bausch Health Companies, Inc.; Merck & Co., Inc.; Regeneron Pharmaceuticals, Inc.; Coherus BioSciences, Inc.; AbbVie, Inc. (Allergan); Pfizer, Inc.; Bayer AG; Santen Pharmaceutical Co., Ltd.; Roche (Genentech, Inc.); Nicox
Customization scope
Free report customization (equivalent up to 8 analyst’s working days) with purchase. Addition or alteration to country, regional & segment scope
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Ophthalmic Drugs Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global ophthalmic drugs market report on the basis of drug class, disease, dosage form, route of administration, product, drug type, and region:
-
Drug Class Outlook (Revenue, USD Million, 2021 - 2033)
-
Anti-allergy
-
Anti-inflammatory
-
Non-steroidal drugs
-
Steroids
-
-
Anti-VEGF Agents
-
Anti-glaucoma
-
Others
-
-
Disease Outlook (Revenue, USD Million, 2021 - 2033)
-
Dry eye
-
Gels
-
Eye solutions & suspensions
-
Capsules & Tablets,
-
Eye drops
-
Ointments
-
-
Allergies
-
Gels
-
Eye solutions & suspensions
-
Capsules & Tablets,
-
Eye drops
-
Ointments
-
-
Glaucoma
-
Gels
-
Eye solutions & suspensions
-
Capsules & Tablets,
-
Eye drops
-
Ointments
-
-
Infection
-
Gels
-
Eye solutions & suspensions
-
Capsules & Tablets,
-
Eye drops
-
Ointments
-
-
Retinal Disorders
-
By Type
-
Macular Degeneration
-
Diabetic Retinopathy
-
Others
-
-
By Dosage Type
-
Gels
-
Eye solutions & suspensions
-
Capsules & Tablets,
-
Eye drops
-
Ointments
-
-
-
Uveitis
-
Gels
-
Eye solutions & suspensions
-
Capsules & Tablets,
-
Eye drops
-
Ointments
-
-
Others
-
Gels
-
Eye solutions & suspensions
-
Capsules & Tablets,
-
Eye drops
-
Ointments
-
-
-
Route of Administration Outlook (Revenue, USD Million, 2021 - 2033)
-
Topical
-
Local Ocular
-
Subconjunctival
-
Intravitreal
-
Retrobulbar
-
Intracameral
-
-
Systemic
-
-
Dosage Form Outlook (Revenue, USD Million, 2021 - 2033)
-
Gels
-
Eye Solutions & Suspensions
-
Capsules and Tablets
-
Eye Drops
-
Ointments
-
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Prescription Drugs
-
OTC
-
-
Drug Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Branded Drugs
-
Generic Drugs
-
-
Regional Outlook (Revenue in USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Sweden
-
Denmark
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
Saudi Arabia
-
South Africa
-
UAE
-
Kuwait
-
-
Frequently Asked Questions About This Report
The global ophthalmic drugs market size was valued at USD 41.4 billion in 2025 and is estimated at USD 44.7 billion for 2026.
The global ophthalmic drugs market is expected to grow at a CAGR of 8.5% from 2026 to 2033, reaching USD 79.4 billion.
Anti-VEGF agents segment led with a 34.2% revenue share in 2025, while gene and cell therapy is the fastest-growing segment.
Key players include Alcon, Novartis AG, Bausch Health Companies, Inc., Merck & Co., Inc., Regeneron Pharmaceuticals, Inc., Coherus BioSciences, Inc., AbbVie, Inc. (Allergan), Pfizer, Inc., Bayer AG, Santen Pharmaceutical Co., Ltd., F. Hoffmann-La Roche Ltd, and Nicox.
The ophthalmic drugs market is is driven by factors such as increasing disease prevalence, a strong developmental pipeline, advancements in drug delivery, and a promising investment scenarios.
Retinal disorders segment led with a 38.7% revenue share in 2025.
Topical segment led with a 59.7% revenue share in 2025, while local ocular route of administration is the fastest-growing area.
North America dominated with a 42.5% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


