
- Home
- »
- Medical Devices
- »
-
Ophthalmic Viscosurgical Devices Market Size Report, 2033GVR Report cover

Ophthalmic Viscosurgical Devices Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Dispersive, Cohesivem Viscoadaptive), By Source (Animal, Biological & Semi-synthetic), By Application, By Region, And Segment Forecasts
Market Size, 2021
$479.8MMarket Estimate, 2026
$521.1MMarket Forecast, 2033
$738.0MCAGR, 2022–2033
3.1%Ophthalmic Viscosurgical Devices Market Summary
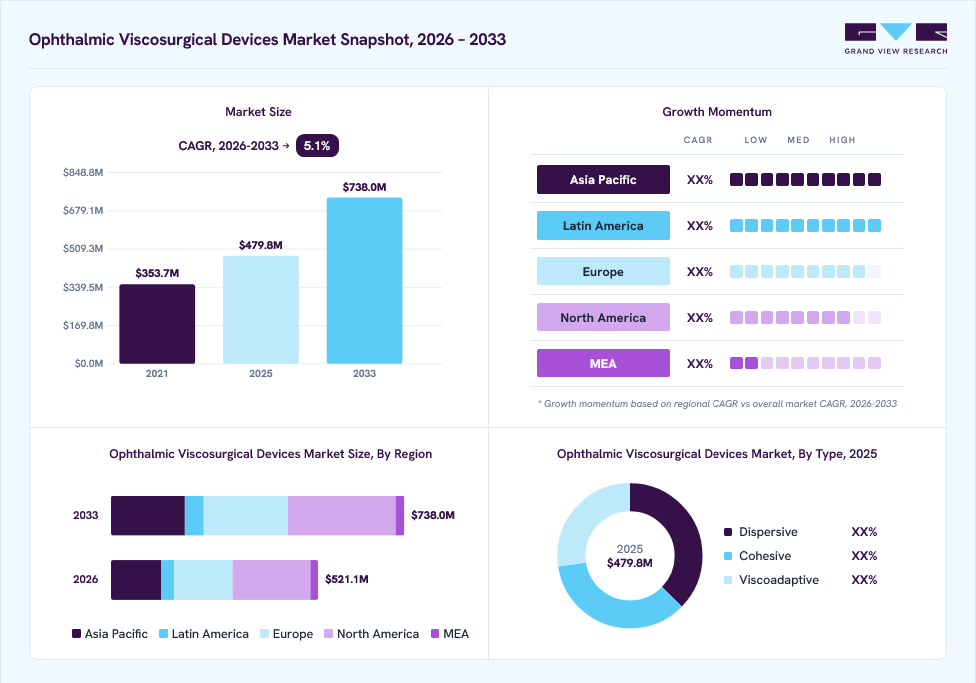
The global ophthalmic viscosurgical devices market size was valued at USD 479.8 million in 2025 and is projected to grow from USD 521.1 million in 2026 to USD 738.0 million by 2033, at a CAGR of 5.1% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 37.7% in 2025. The global population is aging, leading to a surge in age-related eye diseases such as cataracts, glaucoma, and macular degeneration.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Dispersive segment led the market with the largest revenue share of 37.2% in 2025. By source: Biological segment led the market with the largest revenue share of 39.8% in 2025. By application: Cataract surgery segment led the market with the largest revenue share of 50.9% in 2025.
Regional Highlights
- Largest regional market: North America (37.7% revenue share, 2025) Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033) By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 479.8 Million
- Estimated market size in 2026: USD 521.1 Million
- Projected market size by 2033: USD 738.0 Million
- CAGR (2026-2033): 5.1%
Prism AI by Grand View Research Free to tryAsk a question about the ophthalmic viscosurgical devices marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →According to WHO,the global population aged 60 and over will surge from 900 million in 2015 to 2 billion by 2050, representing a rapid shift from 12% to 22% of the total population. Diabetes is a significant risk factor for eye complications, increasing the demand for ophthalmic surgeries. Increased patient awareness regarding eye health and available treatments has led to higher rates of diagnosis and treatment for ocular disorders.
 To learn more about this report, Download Free Sample Report
Innovations in ophthalmic surgery techniques, including minimally invasive procedures, enhance the effectiveness and safety of surgeries. These advancements often require specialized OVDs that can improve surgical outcomes and reduce complications. Increased public awareness about eye care is encouraging early diagnosis and treatment of eye diseases. The establishment of specialized ophthalmic centers is further fueling the market growth.
Market Dynamics
The ophthalmic viscosurgical devices market is witnessing steady growth due to increased use by ophthalmic surgeons of viscoelastic substances in order to perform safe anterior segment surgeries while ensuring protection of intraocular tissues. Ophthalmic viscosurgical devices or OVDs refer to sterile viscoelastic substances, mainly based on hyaluronic acid, chondroitin sulfate, hydroxypropyl methylcellulose and other biocompatible polymers used to maintain anterior chamber depth, protect corneal endothelium, stabilize ocular tissues, and facilitate handling of intraocular tissues during surgeries. Ophthalmic viscosurgical devices consist of dispersive, cohesive and viscoadaptive products, providing an opportunity for performing various kinds of ophthalmic surgeries, such as cataract surgery, glaucoma surgery, corneal grafting, vitreoretinal surgery, etc. Increasing prevalence of cataracts, glaucoma, diabetic retinopathy and age-related ocular disorders, as well as increasing amount of surgeries and availability of ophthalmic surgeries, is stimulating market growth. In addition, advances in viscoelastic compositions, rheological properties, increased tissue protection and combination polymer technology ensure enhanced performance of surgeries and better treatment results. Investments in surgery infrastructure, increasing usage of premium intraocular lenses and increasing number of minimally invasive ophthalmic surgeries drive the demand for more advanced ophthalmic viscosurgical devices.
The growing prevalence of age-related eye diseases and increasing cataract surgery volumes are major drivers of the ophthalmic viscosurgical devices market. OVDs are of vital importance for providing protection to intraocular tissues, creating surgical spaces and helping with the placement of intraocular lenses through ophthalmic surgeries. Rise in use of premium cataract surgery techniques, minimally invasive glaucoma surgery (MIGS), corneal transplants and vitreoretinal surgeries has greatly increased the demand for customized viscoelastic agents. Moreover, constant advancements in surgical technologies and awareness regarding the benefits of early intervention also fuel the adoption of modern OVD products.
Despite widespread clinical adoption, market growth is constrained by pricing pressures, reimbursement limitations, and increasing cost sensitivity among healthcare providers. Higher costs of premium viscoadaptive and combination viscoelastic products restrict their use in health-care facilities facing financial limitations. Furthermore, surgeons might select one type of OVDs over another depending on complexity of procedure and individual choice, thus exerting pricing competition. Additional expenses incurred due to regulatory stipulations regarding sterility of ophthalmic products and difficulties in producing pure viscoelastic formulations pose extra costs to commercialization efforts.
Analyst Perspective
The ophthalmic viscosurgical devices market is positioned at the intersection of increasing global ophthalmic surgery volumes, technological advancements in intraocular procedures, and the growing demand for precision surgical outcomes. Growing aging population, higher prevalence of cataracts and glaucoma, and greater availability of advanced ophthalmic surgeries are driving the requirement of high-quality viscoelastics. Increasingly, manufacturers are paying attention to the development of new generation viscoelastics with superior rheological properties, high-end protection of the endothelial cells, stable chamber performance, and easy removal capability. Also, ongoing trend in premium intraocular lenses implantations, femtosecond laser cataract surgery, and minimally invasive glaucoma surgery will further provide scope for innovations in the market.
Type Insights
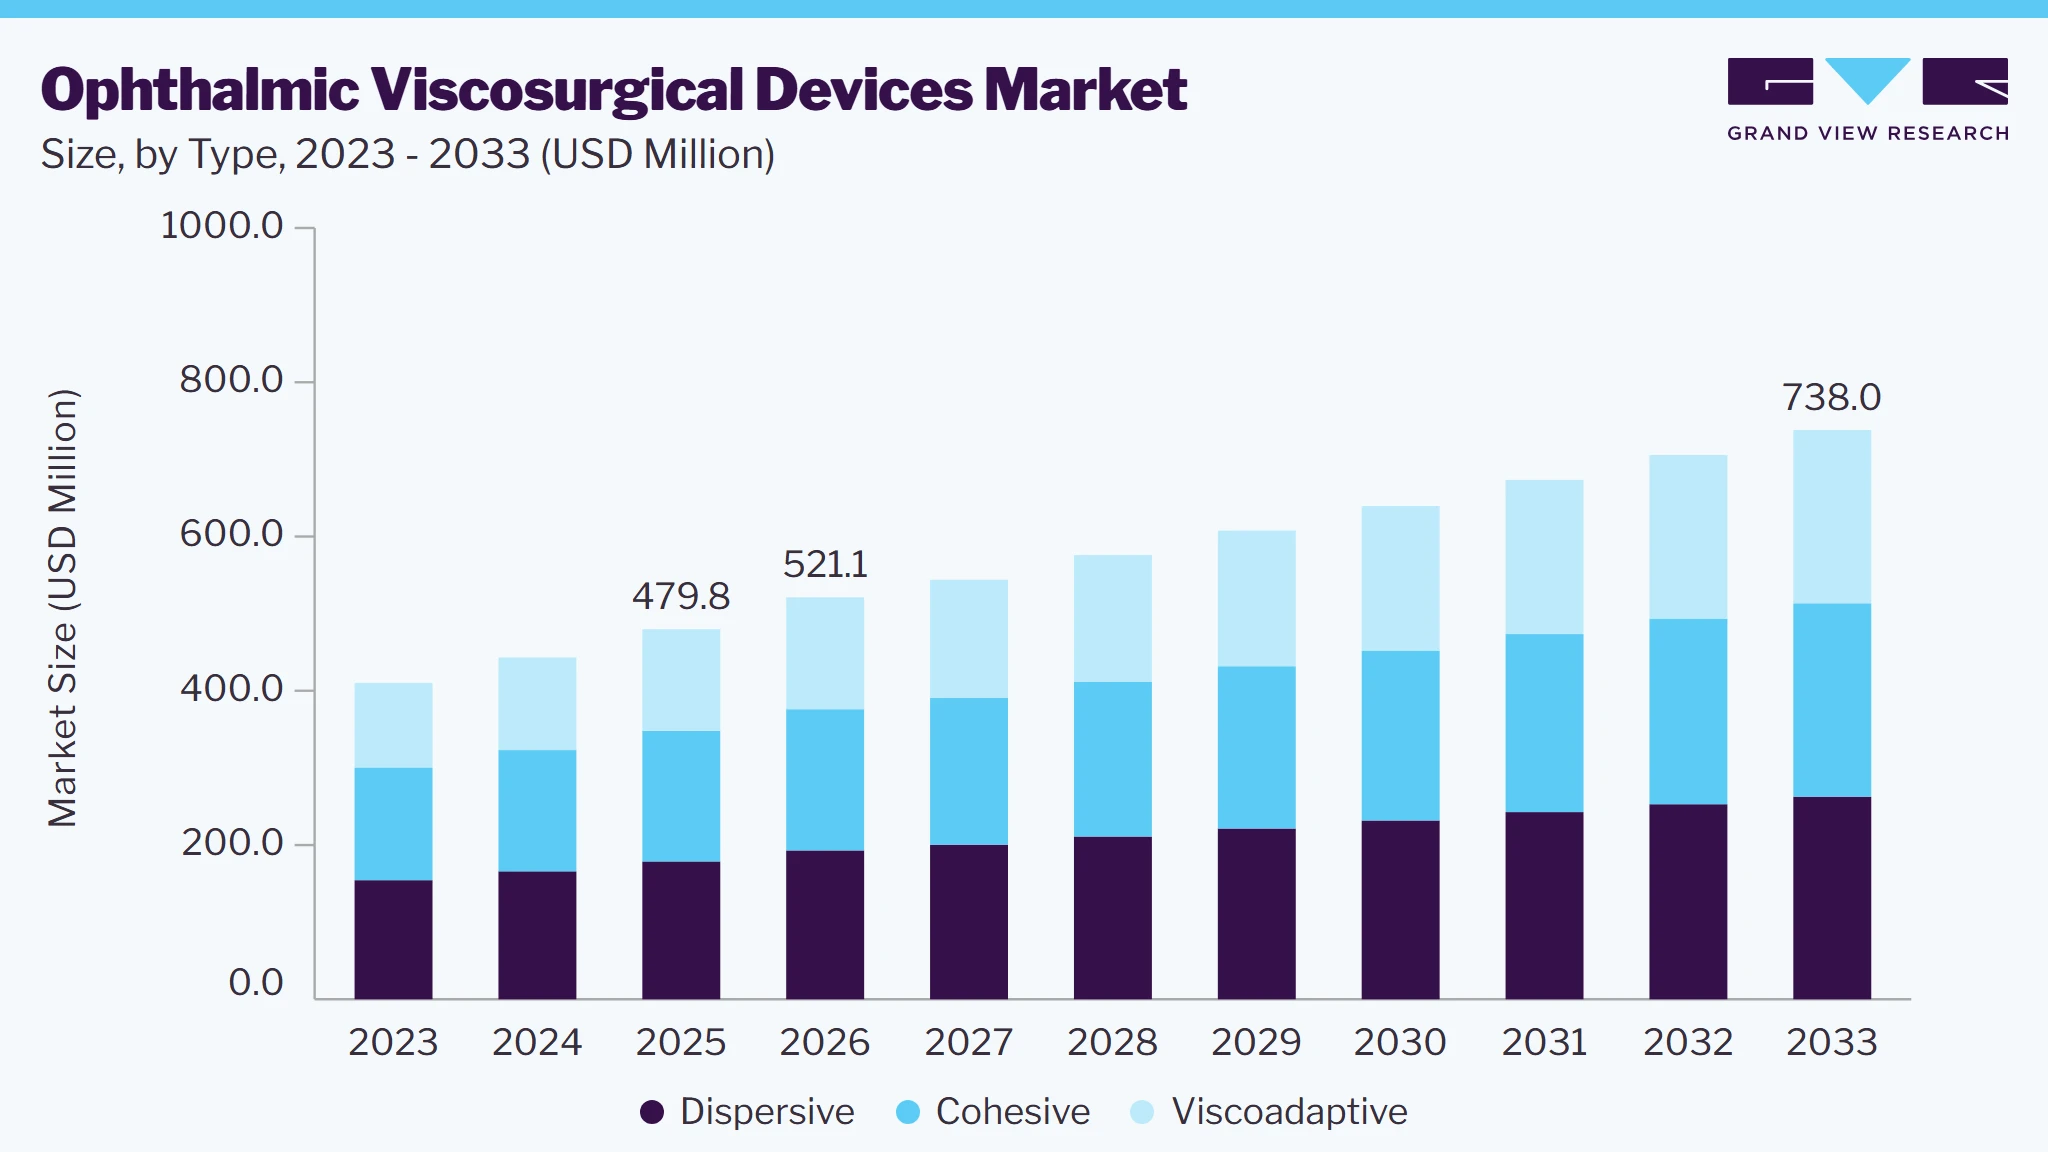
Based on type, the dispersive segment led the market with the largest revenue share of 37.2% in 2025. This is due to their ability to provide effective protection to corneal endothelial cells during cataract surgery. These devices create a stable viscoelastic environment that helps maintain intraocular pressure and prevents damage to delicate tissues. The growing incidence of cataracts, particularly among the aging population, has led to a higher demand for surgical interventions where dispersive OVDs play a crucial role.
The viscoadaptive segment is anticipated to witness the fastest CAGR of 7.7% over the forecast period. This growth is attributed to their unique ability to adapt their viscosity based on shear stress during surgical manipulation. This adaptability allows for enhanced control during procedures such as phacoemulsification and intraocular lens implantation. As surgeons increasingly seek tools that offer precision and ease of use, viscoadaptive OVDs have become a preferred choice.
Source Insights
Based on source, the biological segment led the market with the largest revenue share of 39.8% in 2025. This is due to their biocompatibility and enhanced performance during ocular surgeries. Derived from natural sources, these OVDs offer enhanced tissue protection and healing properties, making them increasingly preferred for delicate eye surgeries. Moreover, the growing emphasis on natural and minimally invasive procedures is driving the demand for biological OVDs.
The semi-synthetic segment is anticipated to witness the fastest CAGR of 7.3% over the forecast period. This is due to their customizable properties and versatility in application. These OVDs offer a balance of biocompatibility and viscoelastic properties, making them suitable for a wide range of ophthalmic procedures. The increasing number of cataract surgeries, coupled with the preference for reliable and affordable OVDs, is fueling the demand for semi-synthetic options.
Application Insights
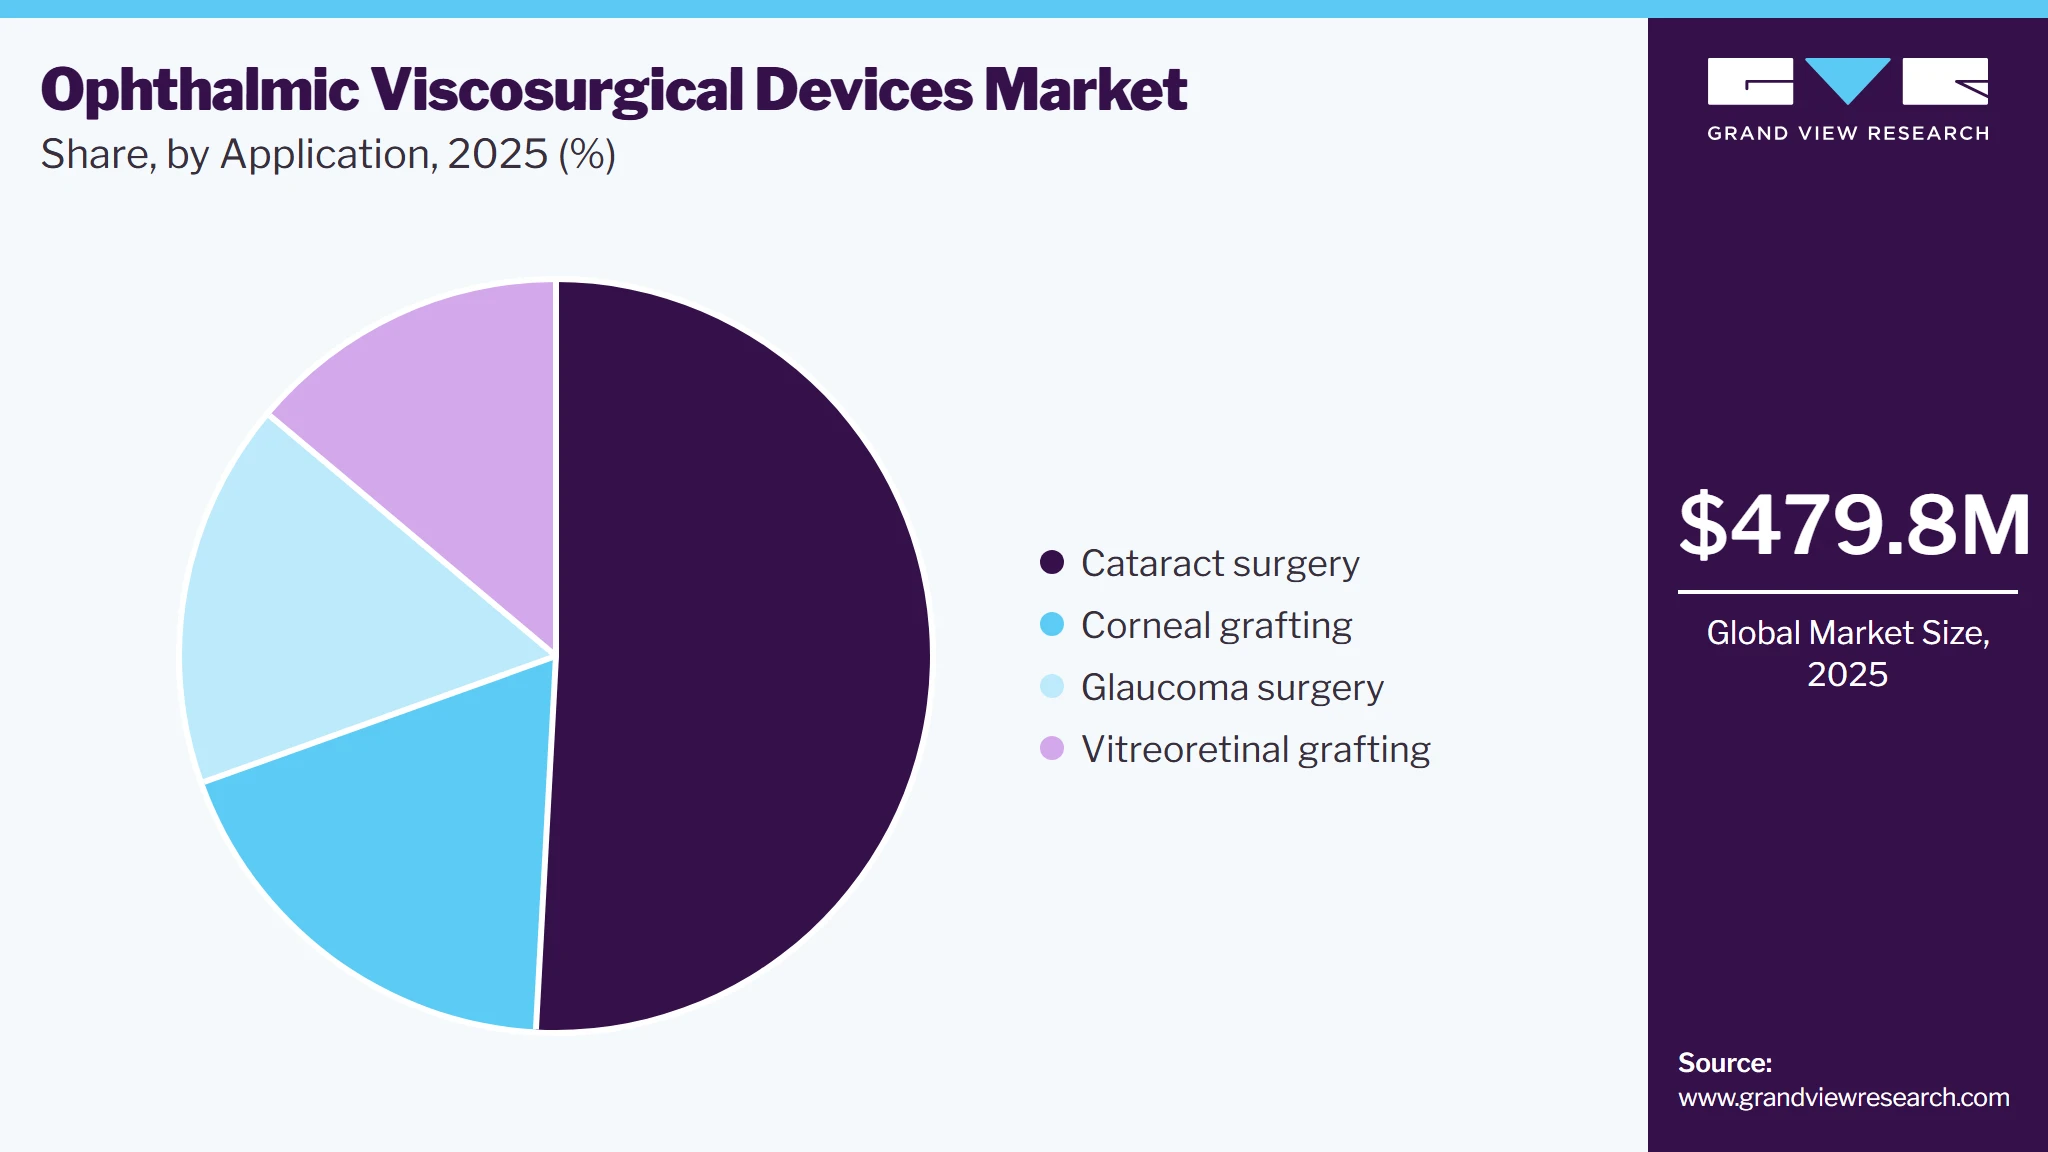
Based on application, the cataract surgery segment led the market with the largest revenue share of 50.9% in 2025. The increasing prevalence of cataracts, driven by an aging population and rising rates of diabetes, has significantly boosted the demand for OVDs in cataract surgery. Cataract is among leading cause of vision impairment and blindness at global level, affecting approximately 65.2 million people. According to American Academy of Ophthalmology,over 10 million cataract operations are performed each year worldwide. The use of OVDs in cataract surgery is crucial for maintaining anterior chamber stability, protecting delicate ocular tissues, and enhancing surgical visibility, thereby contributing to improved outcomes.
 To learn more about this report, Download Free Sample Report
Vitreoretinal grafting is projected to grow the fastest CAGR of 6.7% over the forecast period. Vitreoretinal surgery is witnessing growing OVD usage due to the rising incidence of retinal disorders such as diabetic retinopathy and macular degeneration. According to Glaucoma Research Foundation, in US, diabetic retinopathy affects nearly 7.7 million people of age 40 and older.
Regional Insights
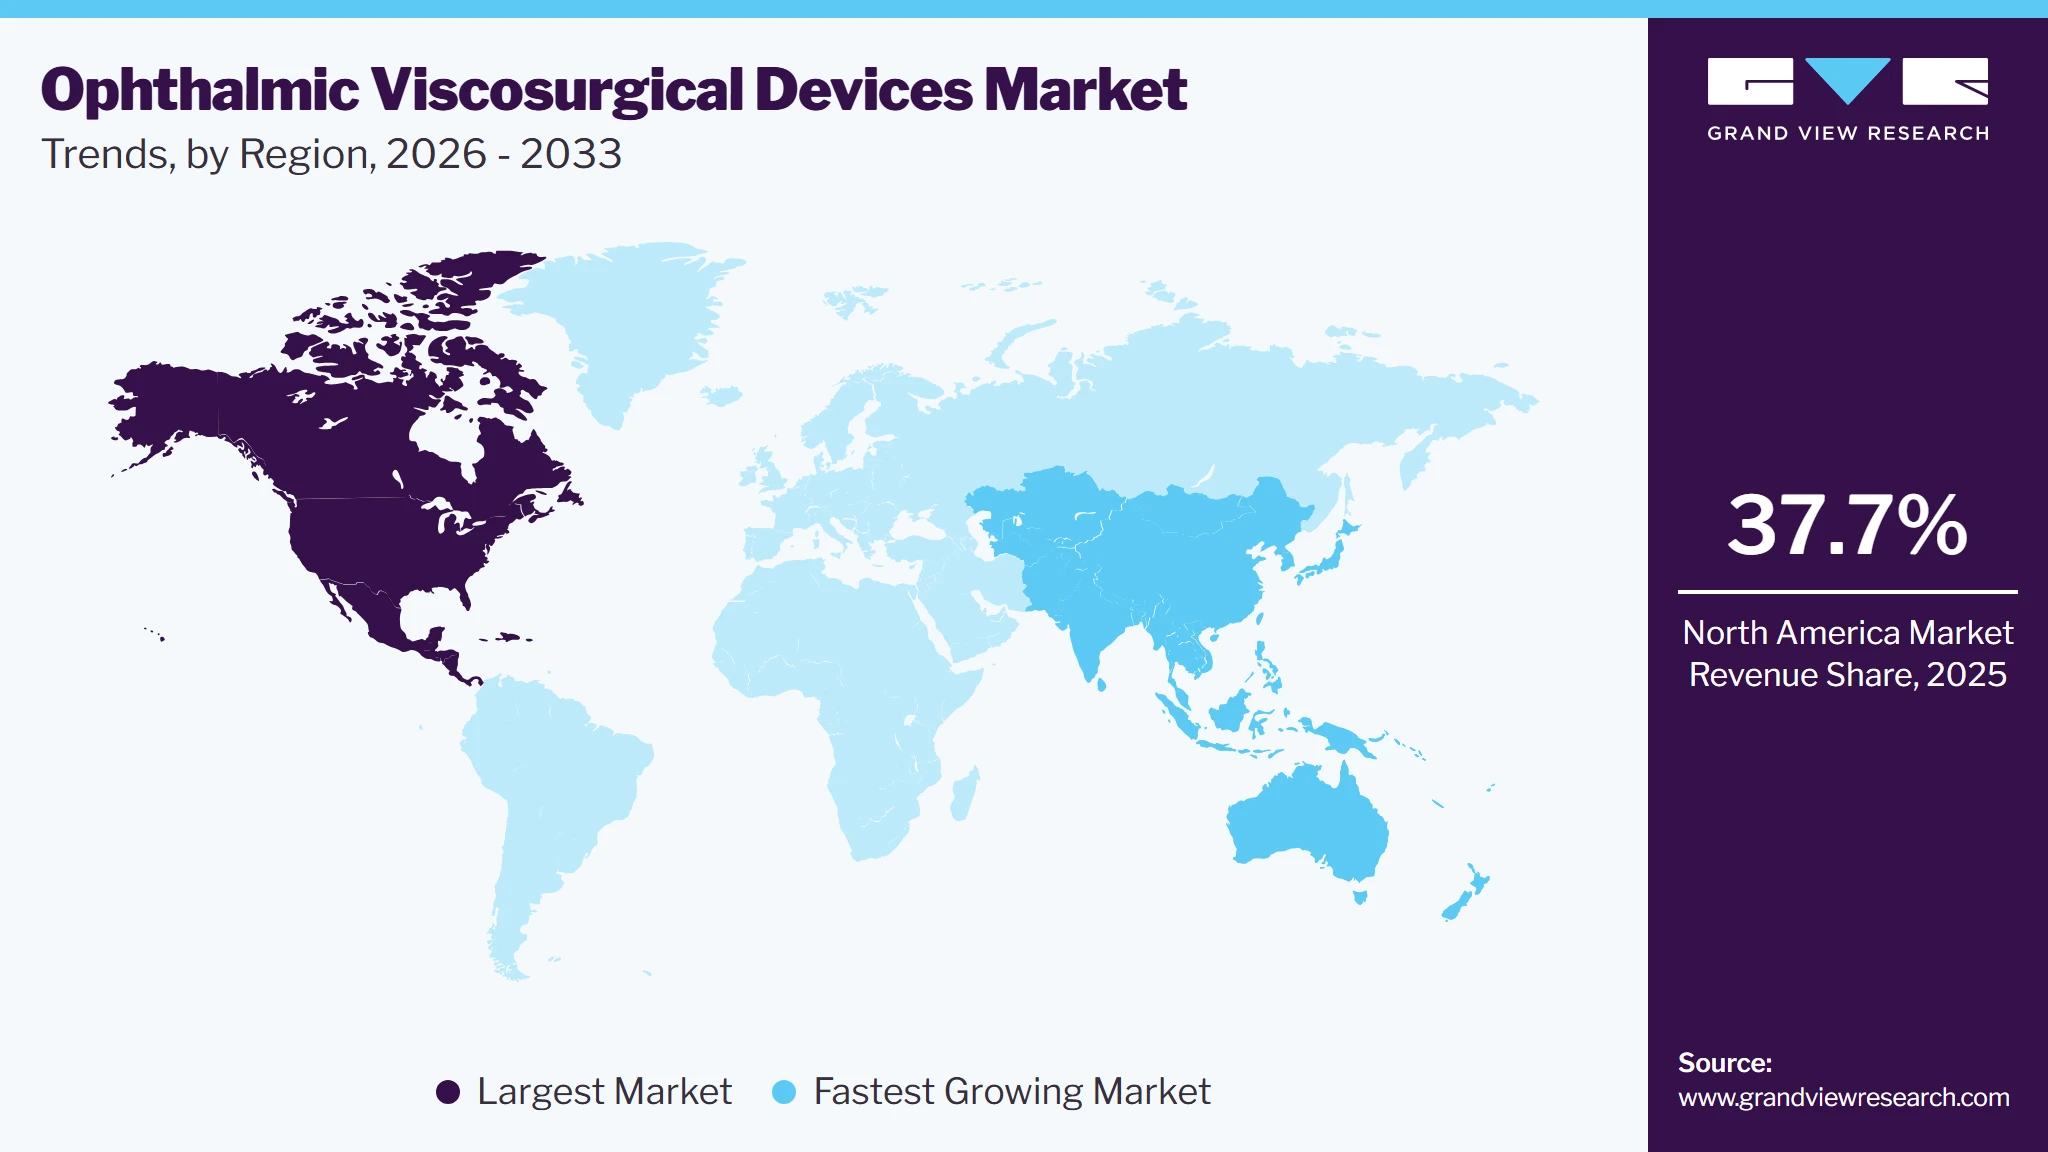
North America dominated the ophthalmic viscosurgical devices market with the largest revenue share of 37.7% in 2025. North America has a significant population with ophthalmic disorders such as cataracts and glaucoma, which necessitate surgical interventions. The presence of a robust healthcare infrastructure and increasing investment in research and development by key players in the market also contribute to this trend.
 To learn more about this report, Download Free Sample Report
U.S. Ophthalmic Viscosurgical Devices Market Trends
The ophthalmic viscosurgical devices market in the U.S. held the largest share in the North America region in 2025. U.S. ophthalmic viscosurgical devices market dominated the North America market in 2025 due to its large geriatric population, high prevalence of chronic diseases, and extensive healthcare coverage. According to Population Reference Bureau, the number of Americans aged 65 and older projected to increase by 47% and account for 23% of the total population by 2050.
Europe Ophthalmic Viscosurgical Devices Market Trends
The Europe ophthalmic viscosurgical devices market was identified as a lucrative region in this industry due to rising geriatric population, increasing prevalence of diabetic retinopathy, and advancements in ophthalmic surgical techniques. According to European Commission, more than one fifth of European population is aged 65 years and over.
The Germany ophthalmic viscosurgical devices (OVD) market is expected to grow rapidly in the coming years due to advanced research facilities and a strong focus on innovation in medical technology. Furthermore, Germany’s demographic trends show an increasing elderly population that requires more frequent eye surgeries, thereby propelling market growth. According to National Institute of Health, about 700,000 people in Germany have cataract surgery each year.
Asia Pacific Ophthalmic Viscosurgical Devices Market Trends
Asia Pacific market is anticipated to witness fastest CAGR in the coming years. This growth is due to the burgeoning population, increasing prevalence of diabetic retinopathy, and rising disposable incomes.
The ophthalmic viscosurgical devices (OVD) market in India held a substantial share in 2023 due to its large population, rising incidence of cataracts and other eye diseases, and increasing affordability of healthcare services.
Key Ophthalmic Viscosurgical Devices Company Insights
Some of the key companies in the ophthalmic viscosurgical devices market are Bausch + Lomb, Carl Zeiss Meditec AG, Bohus BioTech AB, BVI, Nordic Pharma, Inc., Truviz Ophthalmic and others. Companies in the market are focusing on launching new products to gain a competitive edge in the industry.
-
Bausch + Lomb is an American-Canadian company specializing in eye health products. It is one of the largest suppliers of intraocular lenses, lens care products, contact lenses, pharmaceuticals, and products related to eye care.
Key Ophthalmic Viscosurgical Devices Companies:
The following key companies have been profiled for this study on the ophthalmic viscosurgical devices market.
-
Bausch + Lomb
-
Carl Zeiss Meditec AG
-
Johnson & Johnson Services, Inc.
-
Alcon
-
Rayner Group
-
Bohus BioTech AB
-
BVI
-
Nordic Pharma, Inc.
-
Truviz Ophthalmic
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Alcon, Johnson & Johnson Services, Inc., Bausch + Lomb, Carl Zeiss Meditec AG, Rayner Group, BVI)
- Established companies focus on offering comprehensive ophthalmic surgical portfolios comprising ophthalmic viscosurgical devices, intraocular lenses, phacoemulsification systems, ophthalmic surgical instruments, and cataract surgery consumables. They emphasize global manufacturing capabilities, surgeon education, strategic hospital partnerships, continuous product innovation, and expansion of premium viscoelastic formulations to maintain market leadership.
- Extensive global distribution networks, well-established relationships with ophthalmic surgeons and hospitals, broad ophthalmology product portfolios, strong regulatory expertise, and significant investments in research and development. Their ability to bundle OVDs with cataract surgery solutions and premium intraocular lenses strengthens customer retention and recurring revenue generation.
- Dependence on mature ophthalmic surgery markets and premium pricing strategies may limit penetration in cost-sensitive regions. Pricing pressure from generic viscoelastic products, reimbursement constraints, and increasing competition from regional manufacturers may impact profit margins.
Emerging Players (Bohus BioTech AB, Nordic Pharma, Inc., Truviz Ophthalmic, Ophtechnics Unlimited)
- Emerging companies prioritize specialized viscoelastic formulations, competitive pricing, regional market expansion, and innovation in rheological properties to address evolving surgical requirements. Many focus on niche ophthalmology markets, private-label manufacturing, and differentiated product offerings targeting cataract and specialty ophthalmic procedures.
- Agile product development, specialty-focused portfolios, competitive pricing strategies, and flexibility in addressing surgeon preferences enable these companies to compete effectively in regional markets. Strategic collaborations and niche product innovation support gradual market expansion.
- Limited global distribution infrastructure, lower brand recognition, smaller manufacturing scale, and dependence on distributor partnerships may restrict international market penetration. Limited R&D resources compared with multinational competitors may slow new product development and regulatory expansion.
Recent Developments
-
In April 2024, Carl Zeiss Meditec AG announced the acquisition of the Dutch Ophthalmic Research Center (D.O.R.C.). This strategic move aims to consolidate the companies' strengths and drive innovation in ophthalmic medical devices and surgery.
-
In June 2024, Alcon received FDA clearance for its UNITY Vitreoretinal Cataract System (VCS) and UNITY Cataract System (CS). These are the first products from Alcon's new Unity portfolio. This clearance marks a significant milestone for Alcon, as it expands its offerings in the eye care market. The UNITY systems are expected to provide innovative solutions for cataract surgery.
Ophthalmic Viscosurgical Devices Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 479.8 million
Estimated market size in 2026
USD 521.1 million
Projected market size by 2033
USD 738.0 million
Growth rate
CAGR of 5.1% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, material, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; South Korea; Thailand; Australia; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Bausch + Lomb; Carl Zeiss Meditec AG; Johnson & Johnson Services; Inc.; Alcon; Rayner Group; Bohus BioTech AB; BVI; Nordic Pharma, Inc.; Truviz Ophthalmic; Ophtechnics Unlimited
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Ophthalmic Viscosurgical Devices Market Report Segmentation
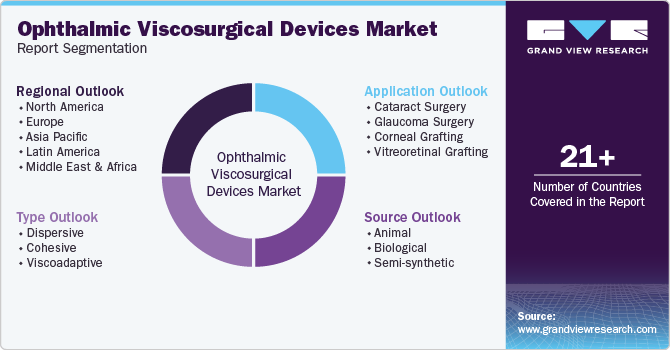
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global ophthalmic viscosurgical devices market report based on type, source, application, and region.
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Dispersive
-
Cohesive
-
Viscoadaptive
-
-
Source Outlook (Revenue, USD Million, 2021 - 2033)
-
Animal
-
Biological
-
Semi-synthetic
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Cataract Surgery
-
Glaucoma Surgery
-
Corneal Grafting
-
Vitreoretinal Grafting
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Mexico
-
Canada
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
South Korea
-
Thailand
-
Australia
-
-
Latin America
-
Brazil
-
Argentina
-
-
MEA
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The ophthalmic viscosurgical devices market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each ophthalmic viscosurgical devices segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
Dispersive
Revenue is generated through dispersive ophthalmic viscosurgical devices formulated to provide prolonged coating and protection of corneal endothelial cells during ophthalmic surgery. Manufacturers capture recurring revenue through widespread utilization in cataract, glaucoma, and complex anterior segment procedures requiring enhanced tissue protection.
Cohesive
Revenue is derived from cohesive viscoelastic formulations utilized to maintain anterior chamber depth, facilitate intraocular lens implantation, and enable easy removal following surgery. Market participants benefit from routine use across standard cataract procedures and other anterior segment surgeries.
Viscoadaptive
Revenue is generated through advanced viscoadaptive formulations that combine the protective characteristics of dispersive OVDs with the chamber-maintaining properties of cohesive agents. Manufacturers benefit from premium pricing and increasing adoption in complex ophthalmic procedures requiring superior surgical control and versatility.
Segment - Source
Revenue capture definition
Animal
Revenue is generated through ophthalmic viscosurgical devices manufactured using animal-derived hyaluronic acid and related biological materials. Manufacturers capture value through established clinical acceptance and utilization across routine ophthalmic surgeries.
Biological
Revenue is derived from naturally sourced biological viscoelastic materials produced through microbial fermentation or other biological production technologies. The segment benefits from increasing preference for highly purified, biocompatible formulations with consistent product quality.
Semi-synthetic
Revenue is generated through semi-synthetic viscoelastic formulations developed using modified biopolymers or chemically enhanced materials designed to optimize viscosity, elasticity, and surgical performance. Manufacturers benefit from continuous innovation and increasing demand for next-generation ophthalmic surgical products.
Segment - Application
Revenue capture definition
Cataract surgery
Revenue is generated through utilization of ophthalmic viscosurgical devices during cataract extraction and intraocular lens implantation procedures. This represents the largest revenue-generating segment owing to the high global volume of cataract surgeries and routine use of OVDs in every procedure.
Glaucoma surgery
Revenue is derived from OVD utilization during trabeculectomy, minimally invasive glaucoma surgery (MIGS), glaucoma drainage device implantation, and other pressure-lowering surgical procedures requiring maintenance of anterior chamber stability and tissue protection.
Corneal grafting
Revenue is generated through utilization of viscoelastic agents during penetrating keratoplasty, endothelial keratoplasty, and other corneal transplantation procedures requiring protection of donor and recipient corneal tissues.
Vitreoretinal grafting
Revenue is captured through utilization of ophthalmic viscosurgical devices during vitreoretinal surgeries involving retinal repair, membrane peeling, macular procedures, and complex posterior segment interventions requiring intraocular tissue stabilization and protection.
Estimation Model
Step / Key Question
Process Steps
Data Sources
Scope Definition
What is being sized?
1. Define Ophthalmic Viscosurgical Devices Product Scope.
2. Scope Type, Source, Application Segments.
3. Establish Geographic Coverage (Global/Regional).
4. Align on base year & forecast horizon (2026-2033).
FDA, PMDA, Aao, ESCRS
Build the Procedure Volume
How large is total addressable market?
1. Estimate Annual Ophthalmic Surgical Procedures by Country.
2. Assess Cataract, Glaucoma, Corneal, and Vitreoretinal Surgery Volumes.
3. Evaluate OVD Utilization per Procedure.
4. Forecast Procedure Growth Across Clinical Applications.
WHO, National Ophthalmology Registries, Hospital Statistics
Estimate Product Utilization
What portion of procedures use disposable devices?
1. Estimate Product Utilization by Procedure Type.
2. Evaluate Preference for Dispersive, Cohesive, and Viscoadaptive OVDs.
3. Analyze Purchasing Patterns Across Healthcare Facilities.
4. Validate Through Industry Interviews.
Primary interviews, clinical surveys, industry experts
Revenue Conversion
How does volume become revenue?
1. Determine ASPs by Product Type and Region.
2. Estimate Revenue from Device Sales.
3. Apply Regional Pricing Variations.
4. Cross-validate with Company Revenues and Public Findings.
Company Annual Reports, Distributor pricing sheets, procurement data, expert interviews
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Competitive Landscape Analysis
Conducted a comprehensive competitive assessment of the global ophthalmic viscosurgical devices market, evaluating leading manufacturers across viscoelastic formulations, ophthalmic surgical consumables, and cataract surgery portfolios. The study assessed product portfolios, viscoelastic technologies, rheological properties, manufacturing capabilities, pricing strategies, regulatory approvals, surgeon adoption trends, geographic expansion initiatives, and ongoing innovations in ophthalmic surgery.
Enables stakeholders to understand technology leadership, competitive positioning, pricing dynamics, procurement strategies, and commercialization approaches shaping the global ophthalmic viscosurgical devices market. Supports supplier benchmarking, partnership evaluation, product differentiation, and strategic investment decisions.
Segment by Application Analysis
Conducted a detailed assessment across Cataract Surgery, Glaucoma Surgery, Corneal Grafting, and Vitreoretinal Surgery, evaluating procedure volumes, product utilization, surgeon preferences, formulation selection, purchasing patterns, and forecast demand by application and product type.
Enables stakeholders to identify high-growth surgical applications, optimize product portfolios, prioritize commercialization efforts, forecast procedure-driven demand, and align product development strategies with evolving ophthalmic surgical trends.
Macroeconomic Analysis
Conducted an in-depth assessment of aging demographics, cataract prevalence, ophthalmic surgery volumes, healthcare expenditure, reimbursement policies, ophthalmology infrastructure development, surgeon availability, regulatory trends, and healthcare investments influencing global demand for ophthalmic viscosurgical devices.
Enables stakeholders to understand the macroeconomic, demographic, regulatory, and healthcare system factors influencing demand within the global ophthalmic viscosurgical devices market. The study supports long-term forecasting, pricing strategy development, regional expansion planning, manufacturing capacity decisions, and investment prioritization amid increasing demand for advanced ophthalmic surgical care.
Frequently Asked Questions About This Report
The global ophthalmic viscosurgical devices market size was valued at USD 479.8 million in 2025 and is estimated at USD 521.1 million for 2026.
The global ophthalmic viscosurgical devices market is expected to grow at a CAGR of 5.1% from 2026 to 2033, reaching USD 738.0 million by 2033.
Key factors that are driving the market growth include rapidly increasing geriatric population, increasing prevalence of diabetes, increasing number of cataract and glaucoma surgeries, improving access to ophthalmic care facilities, and presence of several national and regional eye policies.
Dispersive segment led the market with the largest revenue share of 37.2% in 2025.
Biological segment led the market with the largest revenue share of 39.8% in 2025.
Cataract surgery segment led the market with the largest revenue share of 50.9% in 2025.
North America dominated the market, accounting for a revenue share of 37.7% in 2025.
Some key players operating in the ophthalmic viscosurgical devices market include include Bausch + Lomb; Carl Zeiss Meditec AG; Johnson & Johnson Services; Inc.; Alcon; Rayner Group; Bohus BioTech AB; BVI; Nordic Pharma, Inc.; Truviz Ophthalmic; Ophtechnics Unlimited
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


