
- Home
- »
- Pharmaceuticals
- »
-
Oral Clinical Nutrition Market Size & Share Report 2026-2033GVR Report cover

Oral Clinical Nutrition Market (2026 - 2033)
Size, Share & Trends Analysis Report By Stage (Adults, Pediatrics), By Indication (Dysphagia, Alzheimer’s, Diabetes), By Sales Channel (Online Sales, Retail Sales), By Region, And Segment Forecasts
Market Size, 2025
$18.4BMarket Estimate, 2026
$19.4BMarket Forecast, 2033
$27.2BCAGR, 2026–2033
5.0%Oral Clinical Nutrition Market Summary
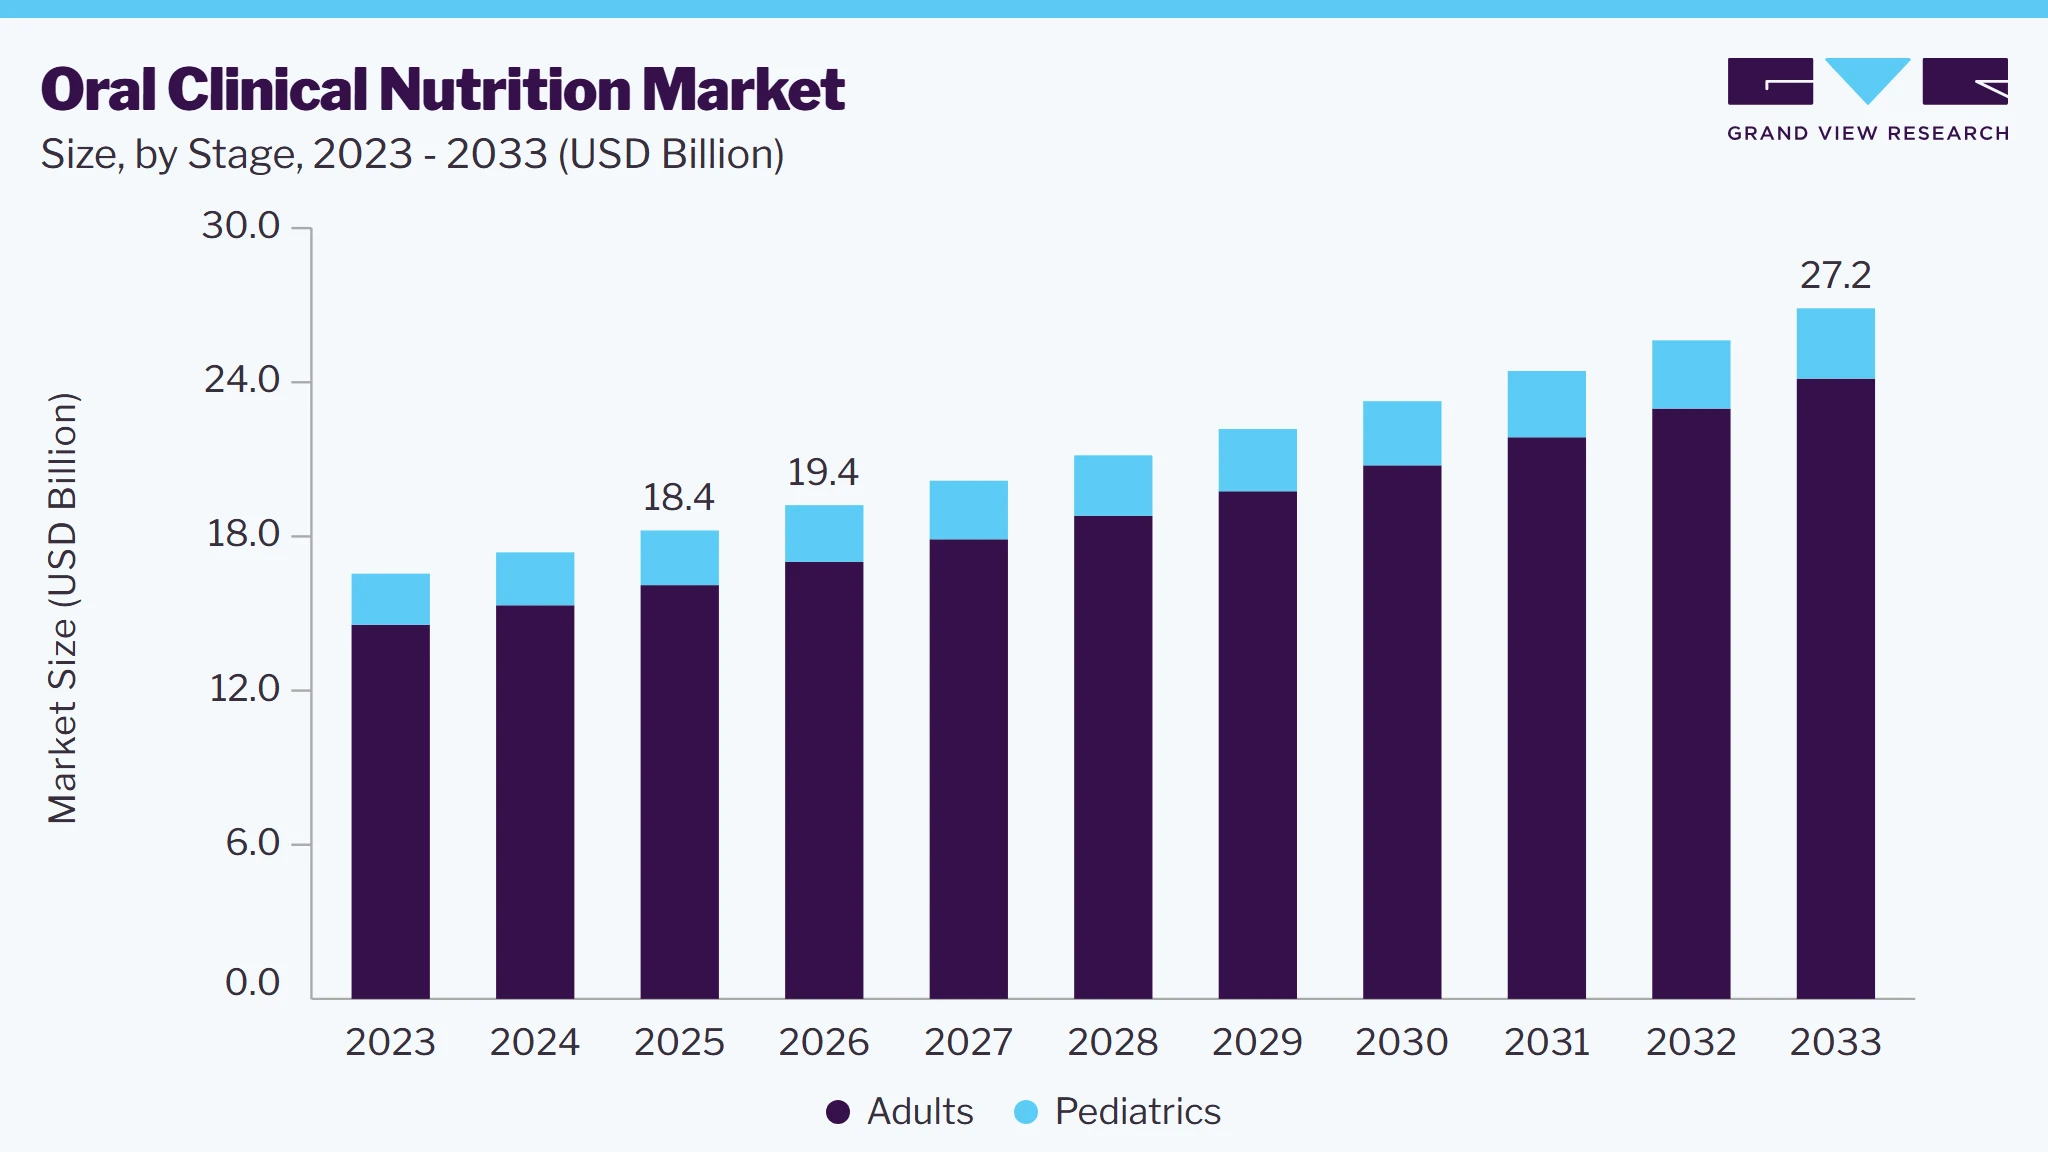
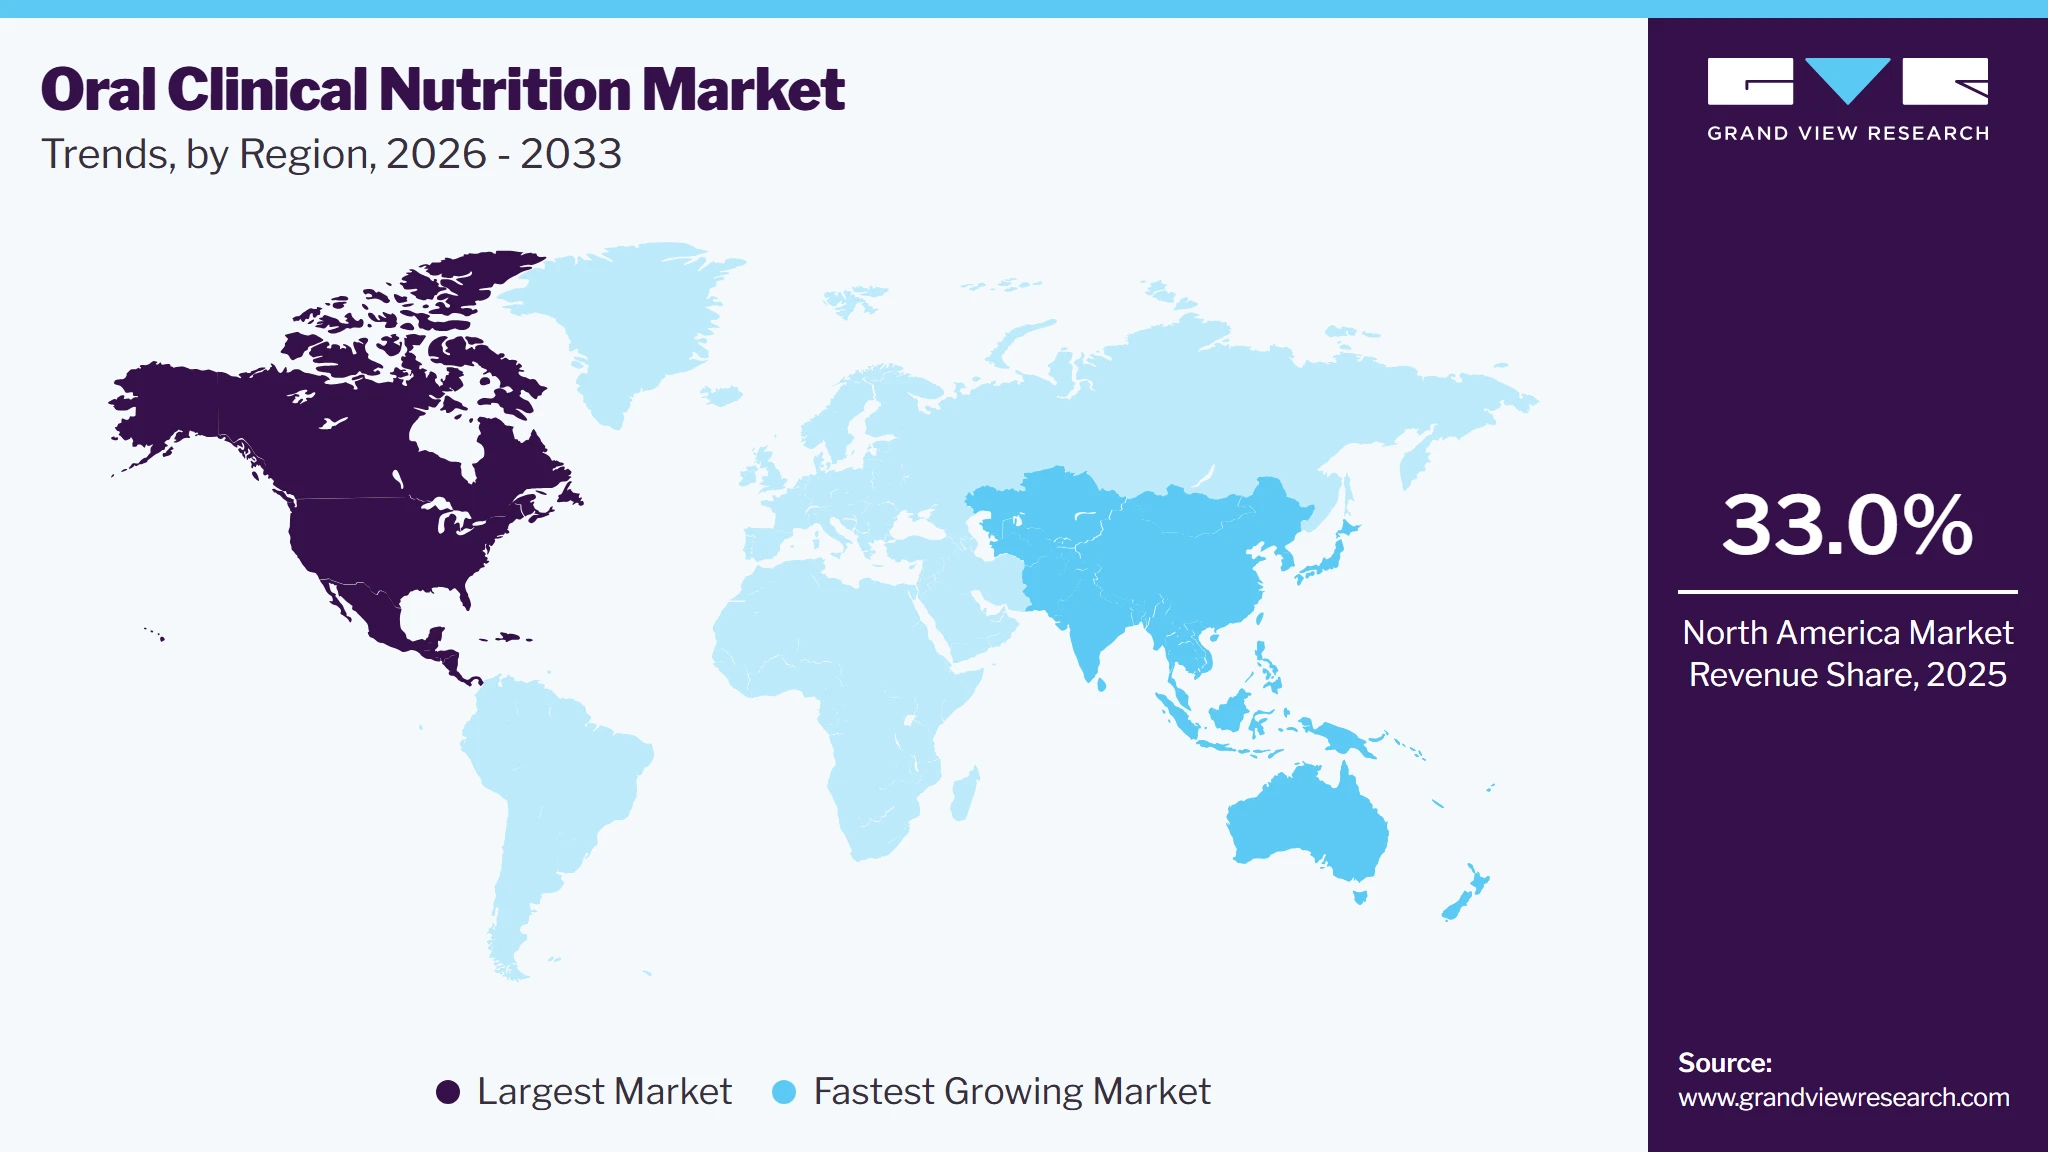
The global oral clinical nutrition market size was valued at USD 18.4 billion in 2025 and is projected to grow from USD 19.4 billion in 2026 to USD 27.2 billion by 2033, at a CAGR of 5.0% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 33.0% in 2025. The growing rates of malnutrition in adults, along with increasing cases of obesity and chronic conditions such as cancer and diabetes, are key drivers of market growth.
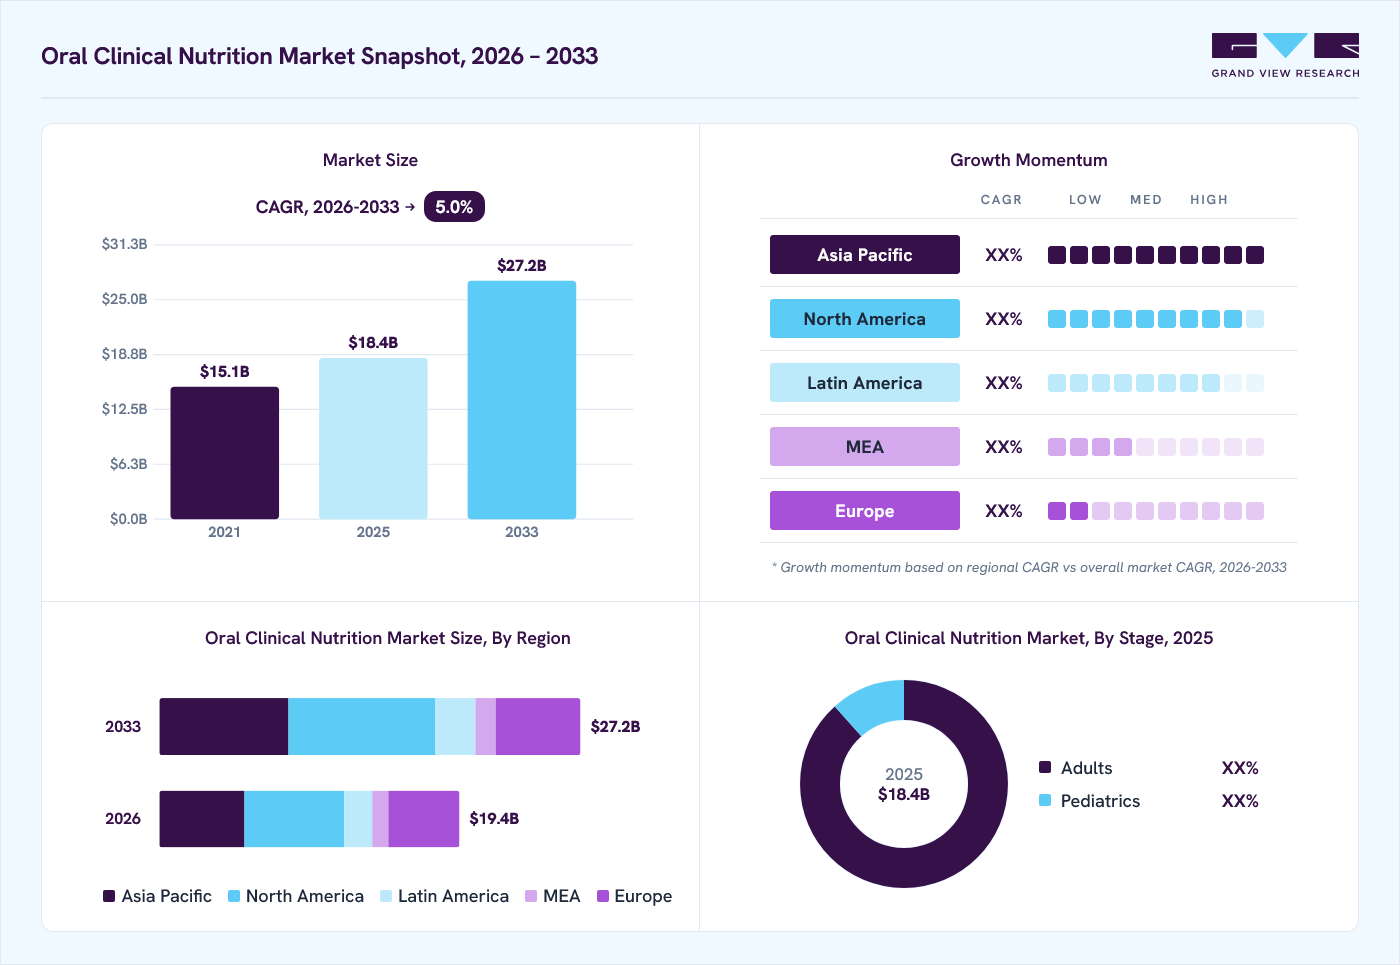 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Adult segment dominated the market, with a revenue share of 88.3% in 2025.
- By indication: Cancer care segment held the largest market share in 2025.
- By sales channel: Institutional sales segment held the largest revenue share of 41.4% in 2025.
Regional Highlights
- Largest regional market: North America (33.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 18.4 Billion
- Estimated market size in 2026: USD 19.4 Billion
- Projected market size by 2033: USD 27.2 Billion
- CAGR (2026-2033): 5.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Oral clinical nutrition products in powder, liquid, and semi-solid forms deliver essential nutrients such as vitamins, proteins, and carbohydrates. Manufacturers are introducing new flavors to improve taste and attract more consumers, increasing sales and market demand. For instance, in May 2023, Otsuka Pharmaceutical Factory released an updated ENORAS Liquid, now available in coffee and tea flavors. This specialized liquid is designed for both feeding tube and oral administration, offering more palatable options for patients.
 To learn more about this report, Download Free Sample Report
According to WHO, the global population aged 60 & above significantly increased from around 1 billion in 2020 to about 1.4 billion in 2033 and is expected to almost double by 2050 to reach around 2.1 billion. The number of elderly patients with critical illnesses has significantly increased in the past few years. The risk of malnutrition and frailty among the geriatric population with comorbidities, such as stroke, depression, and dementia, is much higher, mainly owing to various age-related changes in body composition and muscle mass. This results in a reduced ability to perform Activities of Daily Living (ADLs), thereby increasing the risk of falls or injuries. Therefore, it is important to analyze the pathophysiology behind the condition (nutritional deficiency).
Major companies and innovators are introducing new products to boost efficiency, shelf life, quality, and nutritional content. In addition to enhancing nutritional value, manufacturers also focus on improving taste by adding various flavors. These efforts contribute to increased demand for oral clinical nutrition products, fueling growth in the global market. For instance, in March 2021, Kate Farms launched two products covering Medi-Cal insurance for children and adults. The products, Kate Farms Standard 1.4 Vanilla and Plain, and Kate Farms Pediatric Peptide Vanilla Flavor 1.0, are indicated to treat nutrient deficiency in patients with chronic diseases such as allergies, malnutrition in adults, cancer, and gastrointestinal disorders. Such novel product inventions are expected to drive industry growth.
The outbreak of COVID-19 had a significant impact on the oral clinical nutrition industry. The viral infection led to a decrease in the immunity in patient. Moreover, conditions such as hypertension, obesity, and diabetes were also some of the major risk factors resulting in poor clinical outcomes for hospitalized patients due to SARS-CoV-2 infection. As per the clinical studies, the population over 50-65 was more prone to lower immunity, poor nutrition, and conditions such as sarcopenia. There is a rise in demand for oral clinical nutrition supplements to enhance the body's immunity, driving the overall market.
Market Dynamics
Companies operating in the oral clinical nutrition market are increasingly focusing on strategic initiatives such as product launches, acquisitions, partnerships, and geographic expansion to strengthen their market position and address the growing demand for disease-specific and specialized nutritional products. For instance, in July 2025, Danone announced the completion of its acquisition of a majority stake in Kate Farms, strengthening its U.S. specialized nutrition and medical nutrition portfolio. The acquisition expands Danone's offerings in plant-based oral and tube-feeding nutritional solutions for both pediatric and adult patients
We are thrilled to welcome Brett Matthews and the Kate Farms team to the Danone family. This partnership is a significant step forward in our Specialized Nutrition journey and enhances our collective ability to serve patients and consumers with innovative solutions. Together, our combined organizations will accelerate growth, better serve communities and patients in the U.S. and continue to support healthier lives through nutrition that truly makes a difference."
-Antoine de Saint-Affrique, Danone SA Chief Executive Officer
The general lack of awareness and understanding regarding clinical nutrition in the medical community is projected to limit its adoption. It requires prescription and supervision by medical professionals. Although these products are gaining acceptance, they remain poorly understood by patients, physicians, and pharmacists.
Dieticians are generally aware of these products; however, most doctors and specialists lack awareness regarding the same. This factor prevents doctors from adopting or prescribing enteral nutrition, which may restrain market growth. Furthermore, not all medical experts are convinced that enteral formula would be successful in the treatment of chronic conditions and their symptoms, which may negatively impact the adoption of enteral feeding products along with treatment.
The increasing demand for personalized and disease-specific clinical nutrition is creating significant opportunities for the oral clinical nutrition market. Healthcare providers are increasingly recommending specialized nutritional formulations tailored to patients with conditions such as cancer, diabetes, chronic kidney disease, neurological disorders, and gastrointestinal diseases to improve clinical outcomes and support recovery. For instance, Abbott Nutrition developed Ketocal, a specialized ketogenic medical food for patients with drug-resistant epilepsy. Similarly, the availability of medical nutrition products for conditions such as phenylketonuria (PKU) and Crohn's disease is expanding, reflecting the growing focus on targeted nutritional management. This trend is encouraging manufacturers to invest in innovative, clinically validated formulations and expand their disease-specific nutrition portfolios to meet evolving patient needs.
Market Concentration & Characteristics
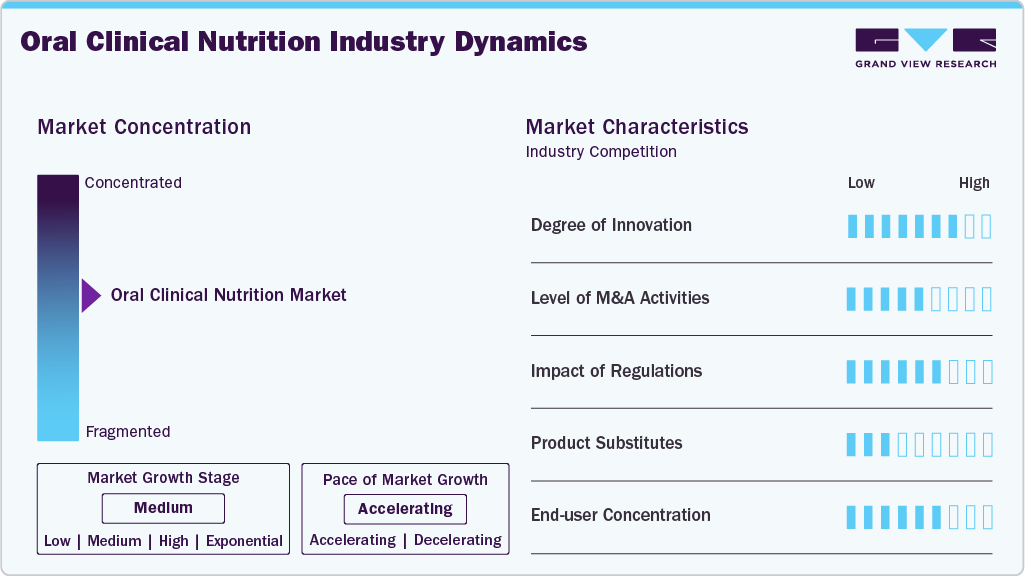
The oral clinical nutrition industry is experiencing moderate growth with an accelerating trajectory. Key factors shaping the market include a rising elderly population, a growing burden of chronic diseases, technological advancements, a shift toward personalized nutrition, and evolving regulatory frameworks.
The oral clinical nutrition industry is evolving rapidly, driven by medical research and technological advancements. Trends such as personalized nutrition, innovative formulations, and bioactive ingredients are gaining momentum. Manufacturers heavily invest in R&D to develop products that go beyond basic nutrition and offer added health benefits. This innovation push intensifies competition and expands offerings tailored to diverse patient needs.
 To learn more about this report, Download Free Sample Report
Key players are implementing strategic initiatives such as M&A, collaborations, and partnerships to strengthen their market presence. For instance, in February 2023, Nestlé and EraCal Therapeutics formed a research partnership to explore new nutraceuticals to regulate food intake. This partnership focuses on developing innovative nutraceutical compounds to manage metabolic diseases such as obesity through appetite control, which aligns with preventive and supportive nutritional approaches.
Regulations are essential in shaping the oral clinical nutrition industry. Producers of medical foods are required to adhere to all relevant FDA food regulations, which include the following compliance standards:
-
Current good manufacturing practice (21 CFR part 110)
-
Registration of food facilities (21 CFR part 1 subpart H)
-
Thermally processed low-acid foods packaged in hermetically sealed containers (21 CFR part 113)
-
Acidified foods (21 CFR part 114)
-
Emergency permit control (21 CFR part 108).
The product substitutes are expected to be low for clinical nutrition products as they are specifically formulated to meet the unique nutritional needs of patients with specific medical conditions, providing a level of efficacy and precision that may not be available in substitutes.
Key industry players are prioritizing geographic expansion to access untapped markets. This is typically achieved by establishing manufacturing facilities in new regions or forming strategic partnerships with local companies in target areas. For instance, in September 2023, Nutrisens Group reinforced its role as a leading independent clinical nutrition provider in Europe by acquiring Vitasyn Medical GmbH, a German company specializing in nephrology and oncology. This move supports Nutrisens' ongoing European growth strategy, which was marked by establishing a German subsidiary, adding to its existing presence in France, Spain, Italy, and Portugal.
Analyst Perspective
The oral clinical nutrition market is expected to witness steady growth over the forecast period, driven by the rising prevalence of chronic diseases, increasing incidence of disease-related malnutrition, and a growing aging population requiring specialized nutritional support. The market is evolving from standardized nutritional products toward disease-specific and personalized formulations, supported by continuous product innovation and expanding clinical evidence. Furthermore, increasing adoption of oral nutritional supplements across hospitals, long-term care facilities, and homecare settings, coupled with strategic investments by leading manufacturers to strengthen their specialized nutrition portfolios and expand into emerging markets, is expected to sustain long-term market growth.
Stage Insights
The adult segment led the market with the largest revenue share of 88.3% in 2025 and is anticipated to grow at the fastest CAGR over the forecast period. This is attributed to the increasing prevalence of nutritional deficiency and malnutrition among adults. The adult age group is prone to reduced muscle strength, vitamins and calcium deficiency among women above 30 years, apathy, lower immunity, hypertension, and fatigue. This results in nutritional deficiency among the adult population. The rise in awareness among people and healthcare professionals about treating such deficiencies has increased the demand for oral clinical nutrition products.
The pediatric segment is expected to grow at a significant CAGR over the forecast period. This growth is driven by increasing awareness of pediatric nutrition, rising incidences of malnutrition among children, and the prevalence of gastrointestinal disorders and allergies. In October 2023, Nutricia, a division of the global food and beverage leader Danone, introduced its first medical nutrition beverage containing a balanced blend of real fruit and vegetable ingredients. This product is designed to support the dietary needs of pediatric patients with disease-related malnutrition and growth challenges.
Indication Insights
The cancer care segment accounted for the largest market revenue share in 2025. This can be attributed to the unhealthy lifestyle, bad eating habits, inherited traits, and poor immunity have increased the occurrence of genetic disorders. The prevalence of cancer is rising globally. According to the National Cancer Institute, cancer remains one of the top causes of death globally. In 2022, nearly 20 million new cases were diagnosed, and approximately 9.7 million people died from cancer-related causes worldwide. In the surge for early diagnosis and treatment of cancer symptoms, advanced treatments such as chemotherapy and radiation therapy are implemented. The side effects of these treatments result in poor food intake, decreased body nutrition, and malnutrition among the patients.
The Malabsorption/GI Disorder/Diarrhea segment is anticipated to witness at the fastest CAGR during the forecast period. This is attributed to the rising prevalence of these diseases among infants and children. Malabsorption and GI disorders are most commonly seen among infants. Thus, oral nutrition products are available in the market to treat these indications. The industry players are increasing their production to cater to the growing market demand. For instance, Nutricia has taken proactive measures to address the unprecedented demand for its Neocate products, particularly Neocate DHA/ARA Infant formula and Neocate Junior Unflavored. In March 2022, Nutricia announced that it prioritized the U.S. market to increase supply and specifically ramp up production of these key products. In addition, the company began expediting deliveries via air shipments from its manufacturing sites to ensure timely availability in the market.
Sales Channel Insights
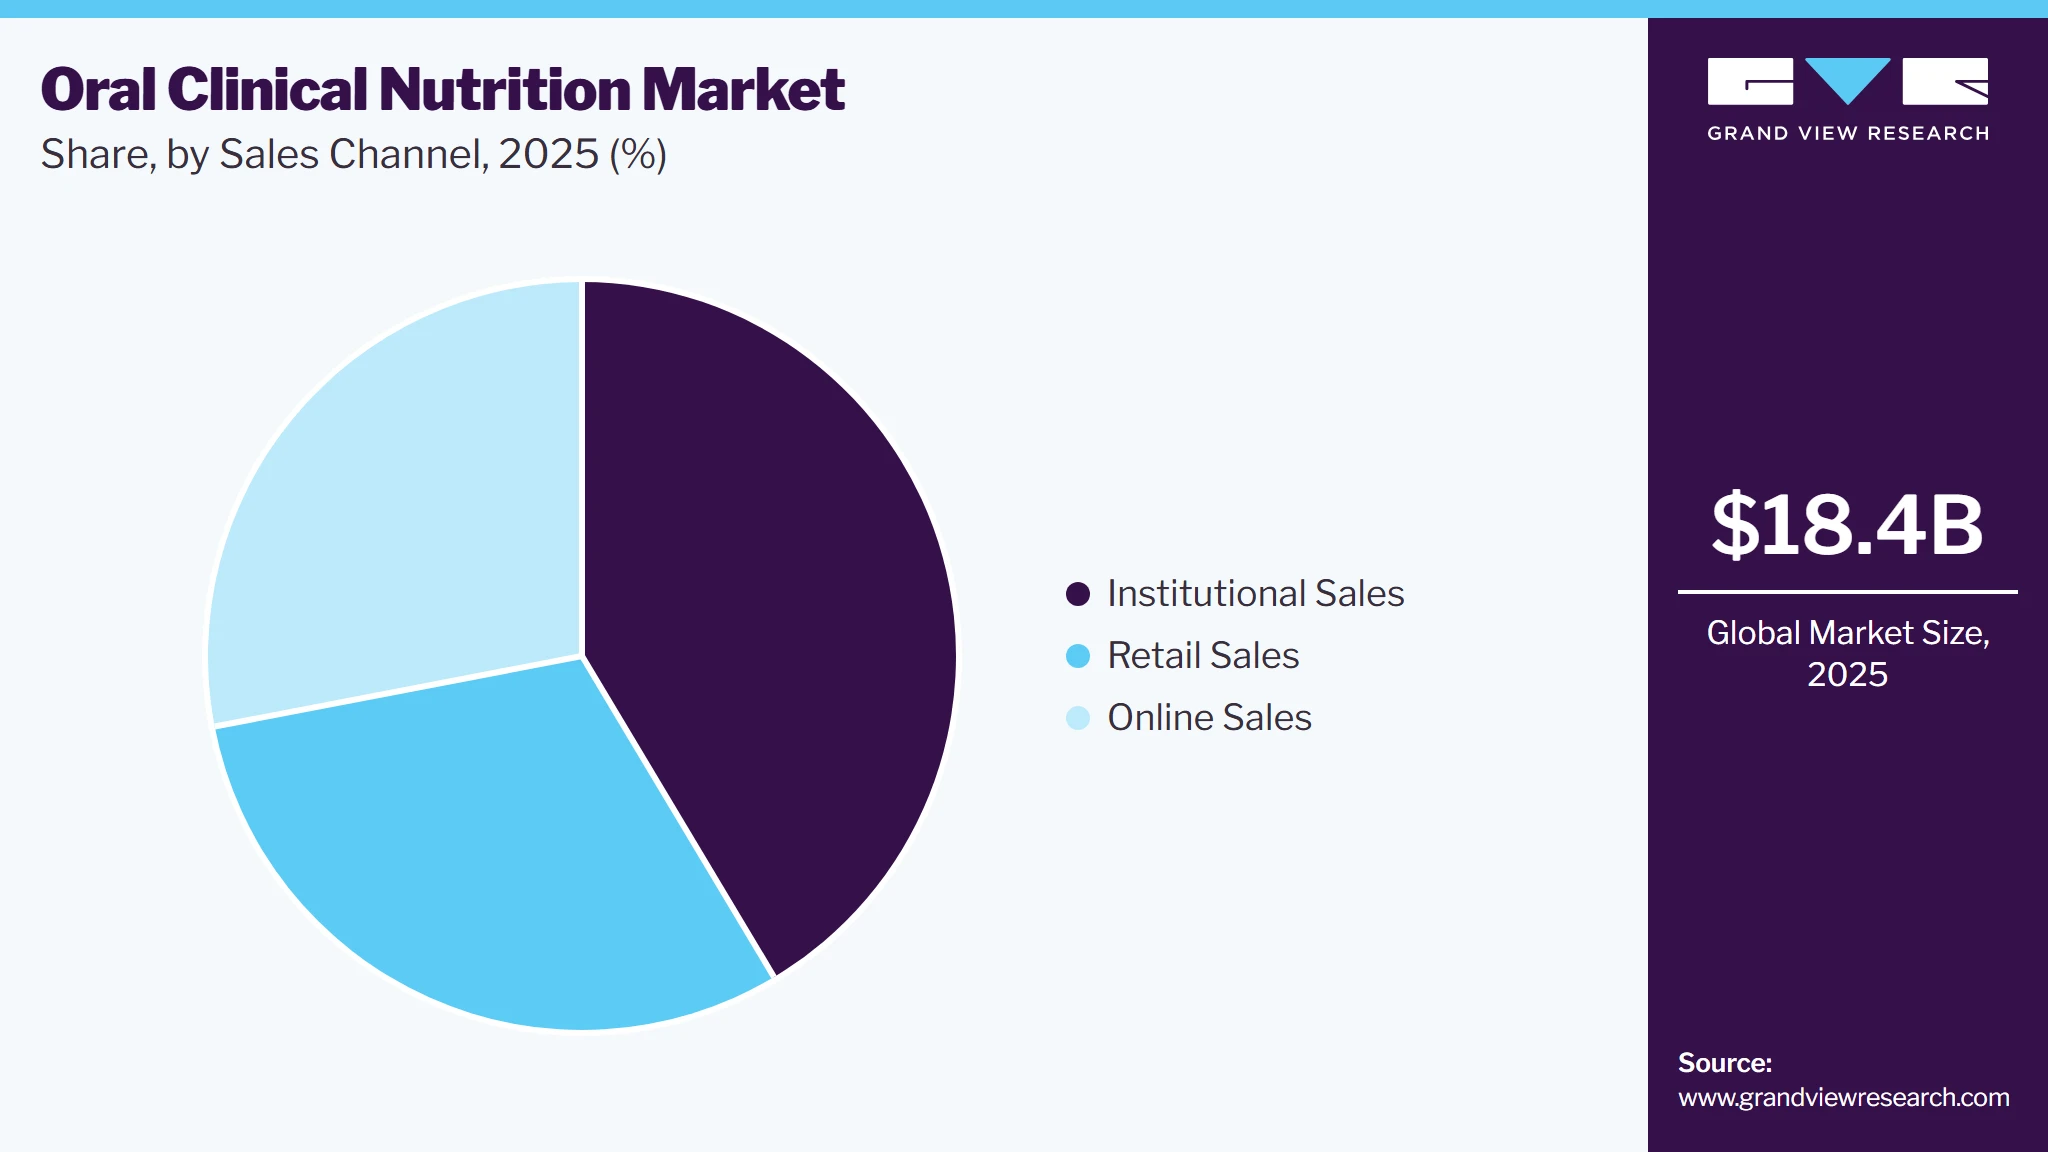
The institutional sales segment accounted for the largest revenue share of 41.4% in 2025, due to high demand from hospitals, long-term care centers, and nursing homes for managing malnutrition and chronic illnesses. These settings often treat elderly and critically ill patients who require nutritional support, driving consistent product usage. Government and private healthcare institutions prioritize therapeutic nutrition to improve recovery outcomes, especially in post-operative care and oncology.
 To learn more about this report, Download Free Sample Report
The online sales channel segment is anticipated to witness at the fastest CAGR during the forecast period. There is a shift in the trend of direct selling to customers via e-commerce platforms. The preference for online purchase of enteral feeding formula is rising owing to the convenience offered by this sales channel. In addition, online platforms provide consumers easy access to product information, reviews, and home delivery services, enhancing the shopping experience. This trend reflects a broader shift towards digital health solutions and direct-to-consumer sales models in the healthcare industry.
Regional Insights
North America dominated the oral clinical nutrition market with the largest revenue share of 33.0% in 2025. The increasing number of patients with non-communicable diseases, such as diabetes and hypertension, cancer, and CKDs, is expected to promote the demand for oral clinical nutritional products in this region. Moreover, there is a rising awareness amongst the companies to launch novel oral clinical nutrition products which are safe, regulatory approved, and have enhanced nutritional value. This spurs the growth of the global oral clinical nutrition industry.
 To learn more about this report, Download Free Sample Report
U.S. Oral Clinical Nutrition Market Trends
The oral clinical nutrition market in the U.S. held the largest share in the North America region in 2025, primarily due to the rising prevalence of cancer across the country. For instance, according to the American Cancer Society, an estimated 54,540 new cases and 11,580 deaths from oral cavity and oropharyngeal cancer were reported in 2023. In addition, the increasing burden of chronic conditions such as neurological disorders is expected to drive the uptake of clinical nutrition during the forecast period. As per the Alzheimer’s Association 2022 Report, approximately 6.5 million individuals in the U.S. were living with Alzheimer’s disease in 2022. Similarly, the Parkinson’s Foundation estimates that around 60,000 new cases of Parkinson’s disease are diagnosed each year, with over 930,000 individuals affected as of 2020.
Asia Pacific Oral Clinical Nutrition Market Trends
The oral clinical nutrition market in Asia Pacific is anticipated to grow at the fastest CAGR from 2026 to 2033, driven by factors such as government initiatives, localized product development, and increasing healthcare access. Companies focus on tailoring products to regional dietary preferences and health conditions. For instance, in August 2024, Danone India partnered with Apollo 24/7 to launch the Super 6 Diabetes Program, targeting India’s growing diabetes epidemic. The program features Protinex Diabetes Care, formulated as a food for special dietary use to support diabetes management. In addition, the rise of e-commerce platforms facilitates broader distribution and accessibility of clinical nutrition products across the region.
The Japan oral clinical nutrition market is expected to grow at a significant CAGR during the forecast period, due to the country's increasing aging population. As per the data published by the Ministry of Internal Affairs and Communications in October 2023, the number of people aged 65 and above as of September 15, 2023, stood at 36.2 million. In addition, supportive legislative changes in the country are expected to impact the market positively. The Ministry of Health, Labour, and Welfare in Japan has established exclusive clinical guidelines for clinical nutrition for enteral and parenteral nutrition. This is expected to drive the market over the forecast period.
Europe Oral Clinical Nutrition Market Trends
The oral clinical nutrition market in Europe is growing owing to the strong regulatory framework, an aging population, and a growing preference for plant-based and allergen-free supplements characterize Europe's market. Countries such as Germany, the UK, and France are witnessing increased adoption of oral clinical nutrition supplements, especially among the elderly and patients with chronic illnesses. European consumers are inclined toward plant-based and allergen-free supplements, reflecting broader dietary trends. For instance, a 2023 survey by the European Consumer Organization revealed that 47% of consumers in Germany prefer plant-based nutrition supplements. The region's robust regulatory framework ensures product quality and safety, fostering consumer trust.
The oral clinical nutrition market in the UK is driven by an increasing prevalence of malnutrition, particularly among older people. According to the Malnutrition Task Force, 1.3 million people over 65 suffer from malnutrition in the UK, with the vast majority living in the community. Innovation is evident in product offerings, with manufacturers introducing new flavors to enhance taste and improve patient compliance. The regulatory framework is strong, with oversight from the Medicines and Healthcare Products Regulatory Agency (MHRA) and the Food Standards Agency (FSA).
Latin America Oral Clinical Nutrition Market Trends
The oral clinical nutrition market in Latin America is expanding due to improving healthcare infrastructure, increased healthcare expenditures, and rising awareness of clinical nutrition's importance. In addition, M&A plays a key role in shaping the market, with companies seeking to strengthen their regional footprint and enhance product offerings. For instance, in March 2025, Nutrisens Group expanded its presence in Latin America by acquiring a majority stake in Prodiet, a Brazilian company specializing in clinical nutrition for medical use. This acquisition marks Nutrisens' entry into Latin America's significant clinical nutrition market and establishes a strong local platform for broader regional expansion.
Middle East & Africa Oral Clinical Nutrition Market Trends
The oral clinical nutrition market in the Middle East & Africa (MEA) is evolving with improving healthcare facilities, rising awareness about nutritional therapies, and economic development. Countries in the MEA region are witnessing growth in the demand for clinical nutrition products, driven by increasing healthcare investments and awareness. Economic development and healthcare reforms contribute to market expansion despite access and affordability challenges. The focus is on expanding access to clinical nutrition products across diverse demographics.
Key Oral Clinical Nutrition Company Insights
Key participants in the industry are focusing on developing innovative growth strategies in the form of product portfolio expansions, partnerships & collaborations, mergers & acquisitions, and business footprint expansions. For instance, in October 2023, Nutricia, a division of global food and beverage leader Danone, introduced its first medical nutrition drink made with a balanced blend of real fruit and vegetable ingredients. Specially designed for the dietary management of disease-related malnutrition and faltering growth in pediatric patients, the drink is ready-to-consume, nutritionally complete, and sourced from natural ingredients. It delivers one-third of the recommended daily intake of fruits and vegetables in each serving.
“We know the role that food plays, not only in terms of health, but also socially and emotionally. And this is no exception for younger patients with specific medical nutritional needs. When nutritional intervention is needed, the lack of naturalness can be frustrating for both younger patients and their parents. We are pleased to pioneer our first medical nutrition drink with a balance of real fruit and vegetable ingredients, empowering patients’ needs, Healthcare Professionals' recommendations, and parental wishes.”
-Brands and Innovation Specialized Nutrition at Danone
Key Oral Clinical Nutrition Companies
The following key companies have been profiled for this study on the oral clinical nutrition market.
-
Fresenius Kabi AG
-
Abbott Laboratories
-
Pfizer Inc.
-
Bayer AG
-
Nestle S.A.
-
GlaxoSmithKline plc
-
Baxter International Inc.
-
Otsuka Holdings Co., Ltd.
-
Mead Johnson & Company, LLC
-
Danone (Nutricia)
-
B. Braun Melsungen AG.
-
Kate Farms, Inc.
-
Medline Industries, LP
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Fresenius Kabi AG, Abbott Laboratories)
etc.)
Focus on product innovation, disease-specific nutrition, strategic acquisitions, global expansion, clinical research, and partnerships with hospitals and healthcare providers.
Strong global distribution networks, extensive brand recognition, broad product portfolios, robust R&D capabilities, established regulatory compliance, and strong relationships with healthcare professionals.
High operational and R&D costs, slower product development cycles due to complex regulatory requirements, and intense competition among leading multinational companies.
Emerging Players (Ausnutria Dairy Corporation Ltd., Maifu Nutrition Technology. etc.)
Focus on niche therapeutic nutrition, regional market expansion, cost-competitive offerings, digital sales channels, and targeted product launches.
Greater flexibility, faster innovation cycles, ability to address underserved markets, and competitive pricing strategies.
Limited global presence, smaller product portfolios, lower brand recognition, constrained R&D budgets, and comparatively weaker distribution and commercialization capabilities.
Recent Developments
-
In May 2024, Danone acquired Functional Formularies, a provider of whole food tube feeding solutions in the U.S., from Swander Pace Capital. This acquisition is a strategic component of Danone's Renew Strategy, enhancing the company's Medical Nutrition offerings in the U.S. market by broadening its portfolio of enteral tube feeding products.
“As a global leader in Medical Nutrition, we are delighted to welcome Functional Formularies to Danone. We are confident that with the addition of the greatly differentiated product portfolio of Functional Formularies, which complements our existing Real Food Blends branded range, we are even better positioned to support the nutritional needs of tube-fed families and patients.”
- Juergen Esser, Deputy CEO and CFO
-
In January 2024, Danone partnered with Resilience, a digital oncology firm, to enhance nutritional care for cancer patients. The partnership integrates Danone's expertise in nutrition's impact on health & illness with Resilience's capacity to revolutionize patient care and lead the digital healthcare transformation.
“We are pleased to partner with Danone to combine our expertise in remote patient care with their knowledge of cancer and nutrition. We intend to improve cancer-related malnutrition care by supporting healthcare professionals in the early detection of nutrition issues and in empowering patients to achieve better outcomes. In patient care, this is the first time we address patients’ vulnerabilities early on with the aim of increasing treatment adherence. This project is completely in line with the holistic approach of Resilience and our aim to redefine patient care and to personalize the care pathway.”
- Dr Charles Ferté, Chief Medical and Patient Officer of Resilience
-
In January 2023, Nutricia introduced Fortimel PlantBased Energy, its inaugural plant-based, ready-to-consume oral nutritional supplement, designed to meet the dietary needs of individuals suffering from or vulnerable to illness-related malnutrition.
“Nutrition is not just about the nutrients. It also has many connotations in life, about the lives we lead, the interaction with other people, and respecting values and preferences. This is equally true in medical nutrition, where the importance of individualized nutritional care that is in line with people’s lifestyle preferences is very important. To provide this kind of individualized nutritional care, plant-based options are a welcome evolution of medical nutrition.”
- Dr. Anne Holdoway, a registered dietitian from the UK
Oral Clinical Nutrition Market Report Scope
Report Attribute
Details
Market size in 2025
USD 18.4 billion
Estimated market size in 2026
USD 19.4 billion
Projected market size by 2033
USD 27.2 billion
Growth rate
CAGR of 5.0% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Stage, indication, sales channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S., Canada, Mexico, UK, Germany, France, Italy, Spain, Norway, Denmark, Sweden, Japan, China, India, Australia, Thailand, South Korea, Brazil, Argentina, Saudi Arabia, South Africa, UAE, and Kuwait
Key companies profiled
Fresenius Kabi AG, Abbott Laboratories, Nestlé S.A., Mead Johnson & Company, LLC, Danone (Nutricia), B. Braun Melsungen AG, Ausnutria Dairy Corporation Ltd., Maifu Nutrition Technology, Megalabs, Alfasigma USA, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Oral Clinical Nutrition Market Report Segmentation
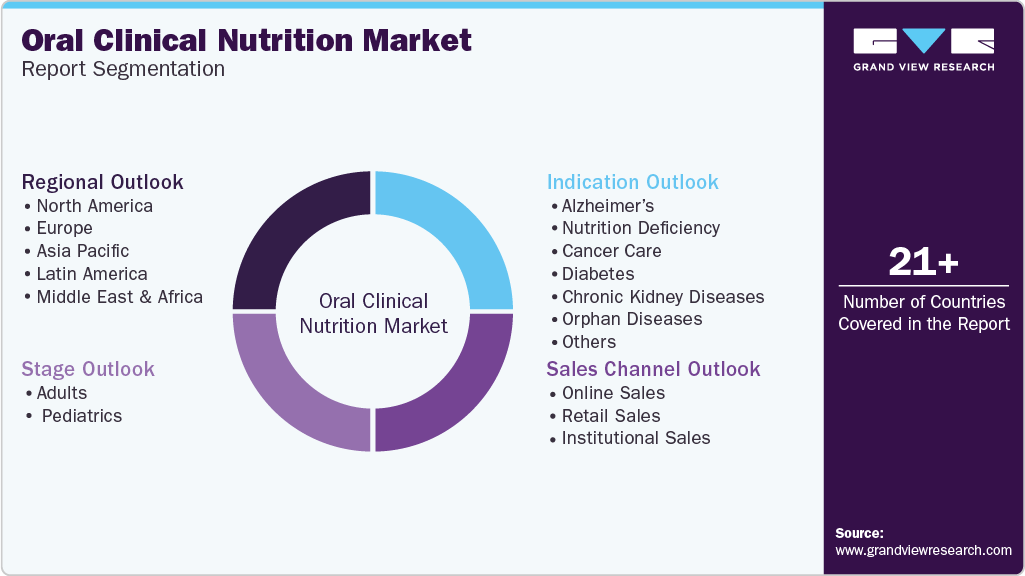
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global oral clinical nutrition market report based on stage, indication, sales channel, and region:
 To learn more about this report, Download Free Sample Report
-
Stage Outlook (Revenue, USD Million, 2021 - 2033)
-
Adults
-
Pediatrics
-
-
Indication Outlook (Revenue, USD Million, 2021 - 2033)
-
Alzheimer’s
-
Nutrition Deficiency
-
Cancer Care
-
Diabetes
-
Chronic Kidney Diseases
-
Orphan Diseases
-
Dysphagia
-
Pain Management
-
Malabsorption/GI Disorder/Diarrhea
-
Others
-
-
Sales Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Online Sales
-
Retail Sales
-
Institutional Sales
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Sweden
-
Denmark
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
Saudi Arabia
-
South Africa
-
UAE
-
Kuwait
-
-
Research Methodology
The oral clinical nutrition market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each oral clinical nutrition segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment- Stage
Revenue Capture Definition
Adults
Includes revenue generated from oral clinical nutrition products formulated for the nutritional management of adult patients, including those with chronic diseases, malnutrition, post-surgical recovery, cancer, metabolic disorders, and age-related conditions.
Pediatrics
Comprises revenue derived from oral clinical nutrition products designed for infants, children, and adolescents to support growth, disease-specific nutritional requirements, recovery, and the management of pediatric medical conditions.
Segment- Indication
Revenue Capture Definition
Alzheimer’s
Includes revenue generated from oral clinical nutrition products formulated to support the nutritional needs and cognitive health of patients with Alzheimer's disease and other neurodegenerative disorders.
Nutrition Deficiency
Comprises revenue derived from products used to manage protein-energy malnutrition, micronutrient deficiencies, and general nutritional inadequacies resulting from illness, aging, or poor dietary intake.
Cancer Care
Covers revenue associated with oral nutritional supplements formulated for oncology patients to address cancer-related malnutrition, cachexia, treatment-induced side effects, and recovery during chemotherapy or radiotherapy.
Diabetes
Includes revenue generated from diabetes-specific oral nutritional products formulated to support glycemic control while meeting the nutritional requirements of diabetic patients.
Chronic Kidney Diseases
Represents revenue earned from renal-specific oral nutrition products designed to manage the dietary requirements of patients with chronic kidney disease, including those undergoing dialysis.
Orphan Diseases
Comprises revenue derived from specialized oral clinical nutrition products developed for the dietary management of rare metabolic, genetic, and inherited disorders requiring disease-specific nutritional interventions.
Dysphagia
Includes revenue generated from texture-modified oral nutritional products and thickened nutritional supplements designed for patients with swallowing disorders.
Pain Management
Covers revenue associated with oral nutritional products formulated to support patients experiencing chronic pain, post-operative recovery, trauma, or inflammatory conditions where nutritional support contributes to recovery and overall health.
Malabsorption/GI Disorder/Diarrhea
Represents revenue generated from oral clinical nutrition products formulated for patients with gastrointestinal disorders, malabsorption syndromes, inflammatory bowel disease, short bowel syndrome, diarrhea, and related digestive conditions.
Others
Includes revenue derived from oral clinical nutrition products indicated for additional medical conditions such as respiratory disorders, liver diseases, immune support, wound healing, critical care, and other disease-specific nutritional requirements.
Segment- Sales Channel
Revenue Capture Definition
Online Sales
Includes revenue generated through e-commerce platforms, company-owned websites, online pharmacies, and digital healthcare marketplaces offering oral clinical nutrition products.
Retail Sales
Comprises revenue derived from pharmacies, drug stores, supermarkets, hypermarkets, specialty nutrition stores, and other retail outlets selling oral clinical nutrition products.
Institutional Sales
Represents revenue earned through direct sales to hospitals, clinics, long-term care facilities, nursing homes, rehabilitation centers, government healthcare institutions, and other healthcare organizations procuring oral clinical nutrition products.
Estimation Model
Methodology / Analysis
Description
Commodity Flow Analysis
The oral clinical nutrition market was estimated using a top-down approach by analyzing the revenues, product portfolios, and regional presence of leading manufacturers. Revenue contributions from adult and pediatric oral clinical nutrition products across key indications, including nutrition deficiency, cancer, cachexia, chronic kidney disease, Alzheimer’s disease, dysphagia, orphan diseases, pain management, and gastrointestinal disorders, were assessed to estimate the overall market size.
Parent Market & Penetration-Based Analysis
The oral clinical nutrition market was evaluated within the broader clinical nutrition market. Penetration of oral clinical nutrition products across therapeutic indications, patient populations, and healthcare settings was analyzed to estimate the addressable market and identify growth opportunities.
Country-Level Segment Share Modeling
The market was segmented by stage, indication, sales channel, and geography. Country-level shares were estimated based on disease prevalence, clinical nutrition adoption, healthcare expenditure, reimbursement landscape, and distribution channel penetration across key regions.
Data Triangulation & Validation Model
Market estimates and segment shares were validated through primary interviews with manufacturers, healthcare professionals, dietitians, distributors, and industry experts. Secondary findings were cross-verified using company reports, regulatory publications, clinical guidelines, and industry databases to ensure accuracy.
Forecasting & CAGR Modeling
Market forecasts were developed by evaluating trends in disease-specific nutrition, rising prevalence of chronic diseases and malnutrition, aging population, expanding home healthcare, and increasing awareness of medical nutrition therapy. The analysis also considered product innovation, healthcare spending, and distribution channel expansion.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Market share analysis at global and regional level
Detailed market share of notable 10 players at global and regional level including revenue contribution and analyst key takeaways
Enables identification of dominant and emerging regional markets, supporting regional expansion and investment strategies
Average selling price (ASP) analysis at the country level
Provided average selling price at 23 notable country, considering product type, distribution channel, and pricing variations
Provides insights into pricing dynamics, competitive positioning, reimbursement impact, and revenue optimization opportunities
Regulatory and product approval landscape
List and analysis of FDA-approved oral clinical nutrition products and key permitted ingredients used in medical foods and oral nutritional supplements
Provides regulatory clarity, supports product development strategies, ensures compliance understanding, and helps identify approved formulation opportunities
Frequently Asked Questions About This Report
Some key players operating in the oral clinical nutrition market include Fresenius Kabi AG, Abbott Laboratories, Pfizer Inc., Bayer AG, Nestle S.A., GlaxoSmithKline plc, Baxter International Inc., Otsuka Holdings Co., Ltd., Mead Johnson & Company, LLC, Danone (Nutricia), B. Braun Melsungen AG., Kate Farms, Inc., Medline Industries, LP
Key factors that are driving the market growth include growing rates of malnutrition in adults, along with increasing cases of obesity and chronic conditions such as cancer and diabetes, are key drivers of market growth. Oral clinical nutrition products in powder, liquid, and semi-solid forms deliver essential nutrients such as vitamins, proteins, and carbohydrates.
North America dominated the oral clinical nutrition market with a share of 30.0% in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
The adult segment led the market with the largest revenue share of 88.3% in 2025 and is anticipated to grow at the fastest CAGR over the forecast period. This is attributed to the increasing prevalence of nutritional deficiency and malnutrition among adults.
The cancer care segment accounted for the largest market revenue share in 2025 while malabsorption/GI Disorder/Diarrhea segment is second fastest growing market
The institutional sales segment accounted for the largest revenue share of 41.4% in 2025 while online sales channel segment is expected to be the fastest-growing market.
The global oral clinical nutrition market size was valued at USD 18.4 billion in 2025 and is estimated at USD 19.4 billion in 2026.
The global oral clinical nutrition market is expected to grow at a compound annual growth rate of 5.0% from 2026 to 2033, reaching USD 27.2 billion by 2033
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


