
- Home
- »
- Medical Devices
- »
-
Orthopedic Braces And Supports Market Size Report, 2033GVR Report cover

Orthopedic Braces And Supports Market (2026 - 2033)
Size, Share & Trends Analysis Report By Products (Braces & Supports Type, Pain Management Products), By End Use (OTC, Hospitals, Orthopedic Clinics, DME Dealers), By Region, And Segment Forecasts
Market Size, 2025
$4.9BMarket Estimate, 2026
$5.2BMarket Forecast, 2033
$8.1BCAGR, 2026–2033
6.5%Orthopedic Braces And Supports Market Summary
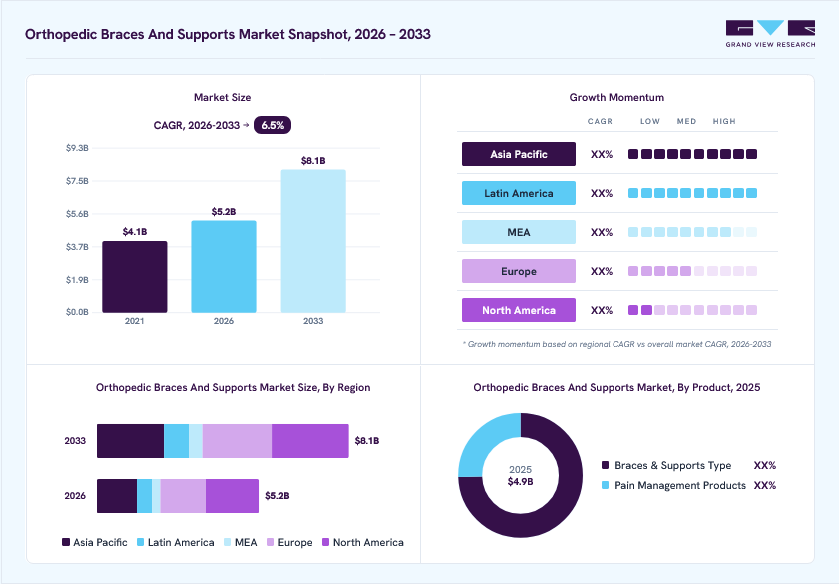
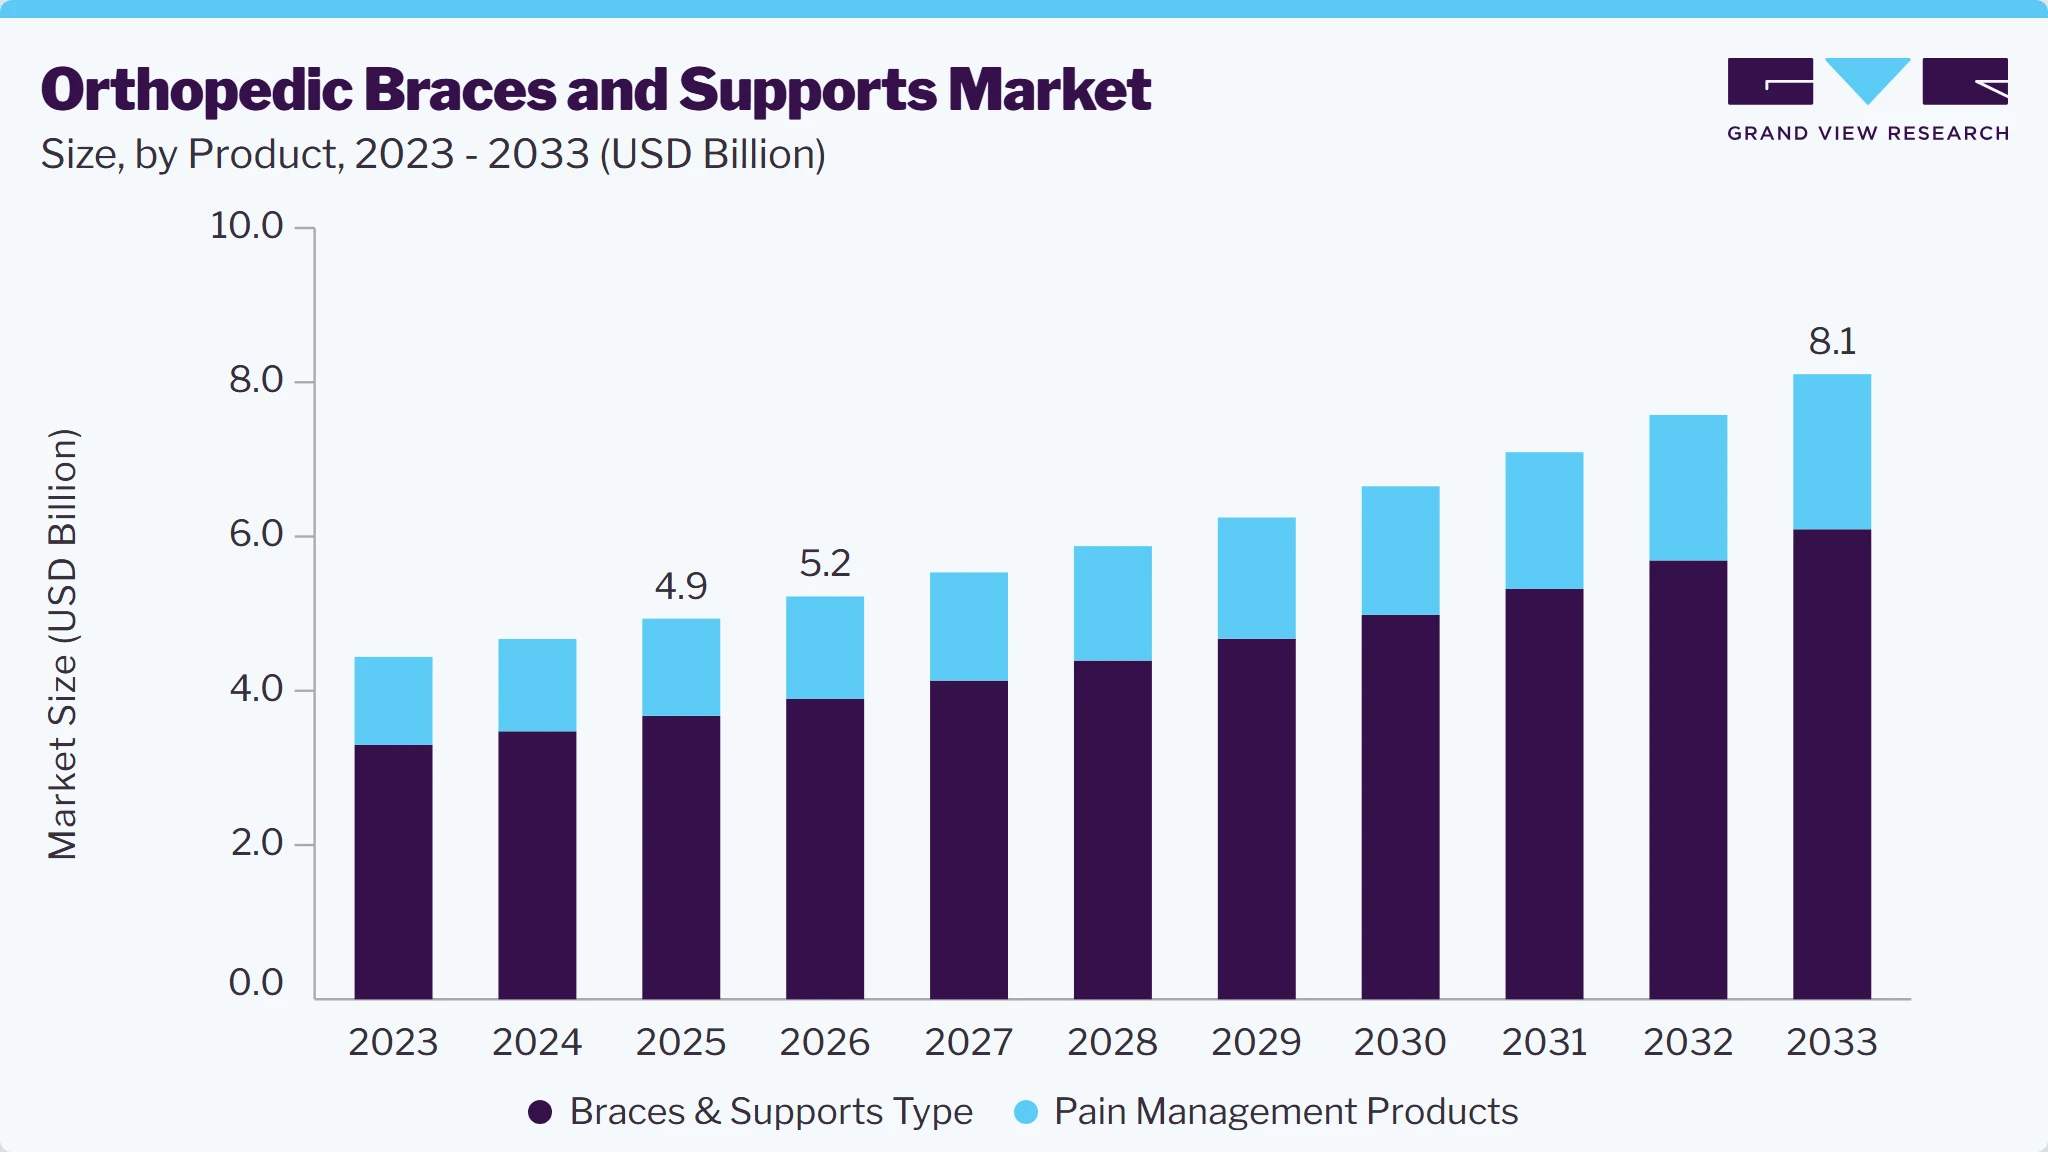
The global orthopedic braces and supports market size was valued at USD 4.9 billion in 2025 and is projected to grow from USD 5.2 billion in 2026 to USD 8.1 billion by 2033, at a CAGR of 6.5% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 33.4% in 2025. Increasing technological advancements, rising number of sports and accident-related injuries, increasing geriatric population, and growing public awareness of preventive care are key drivers in the orthopedic braces and support market.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Races & supports type segment dominated the market, with a revenue share of 74.5% in 2025.
- By end use: Orthopedic clinics segment accounted for the largest revenue share of 30.0% in 2025.
Regional Highlights
- Largest regional market: North America (33.4% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 4.9 Billion
- Estimated market size in 2026: USD 5.2 Billion
- Projected market size by 2033: USD 8.1 Billion
- CAGR (2026-2033): 6.5%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
These factors contribute to developing innovative products and solutions and distribution platforms for better patient outcomes. For instance, in February 2025, Canadian Orthopedic Supply, a Medical equipment supplier, launched its new website. The company has expanded from a small home office in Georgetown, Ontario, into a nationwide provider of orthopedic bracing solutions. Its product portfolio includes brands such as Push Sport, Push, M-Brace, and Solidea. In addition, the rising prevalence of chronic and acute conditions, such as arthritis and sports injuries, further boosts the demand for orthopedic braces and supports.Major companies in the market are actively involved in initiatives to improve product offerings and expand their market presence, which is expected to contribute to the overall market growth. For instance, in February 2021, BREG, Inc., a provider of billing services and orthopedic bracing, introduced two new product lines called Pinnacle and Ascend. These product lines consist of 15 orthopedic braces specifically designed for patients with spinal injuries. The launch of these new product lines signifies the company's expansion of its product portfolio, allowing them to offer a wider range of solutions to meet the needs of patients with spinal injuries.
 To learn more about this report, Download Free Sample Report
The demand for market products, including postoperative bracing solutions and unloader OA (Osteoarthritis) bracing products, is expected to be driven by factors such as the growing popularity of amateur sports and increased activity levels, contributing to the need for orthopedic braces and supports. The aging population in key markets worldwide creates a higher demand for these products as older individuals are more prone to musculoskeletal issues. Moreover, the rising number of orthopedic surgeries further fuels the demand for postoperative bracing solutions.
Furthermore, the increasing incidence of osteoarthritis, the most commonly occurring form of arthritis affecting individuals of all age groups, significantly drives the demand for orthopedic braces and supports. For instance, according to Arthritis & Osteoporosis Tasmania, in Australia, 3.9 million individuals have arthritis, which is projected to increase to 5.4 million by 2030. This increases the risk of muscle injuries, particularly in the shoulders and knees of older people. Stiffening of the joints is a common issue among older people, emphasizing the need for braces and supports to improve mobility.
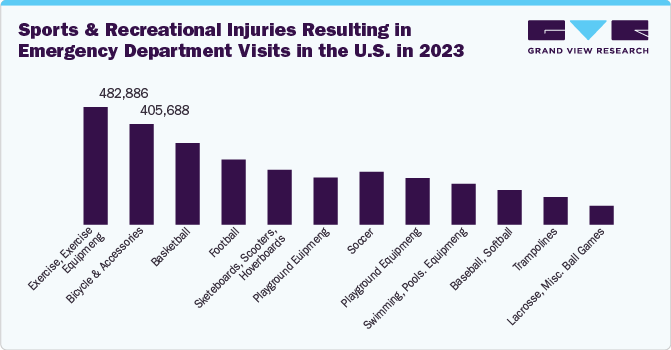
Injuries associated with sports are rising due to the increasing number of sports activities. Athletes involved in fitness-related pursuits, including cycling, running, and others, are particularly susceptible to physical injuries, including ligament injuries. Indoor athletes, in particular, face a high threat of ankle ligament tears, leading to a significant demand for ankle braces. For instance, according to the National Safety Council, in the U.S., 445,642 and 409,224 exercise and exercise equipment injuries were reported in 2022 and 2021, respectively. In addition, ankle braces are commonly recommended for recovery from acute ankle sprains. Athletes utilize orthopedic braces to safeguard themselves from injuries during sports activities. These braces aid in restricting unwanted movements during matches, allowing athletes to play with greater ease and convenience.
 To learn more about this report, Download Free Sample Report
Market Dynamics
The orthopedic braces and supports market is experiencing significant growth, driven by the increasing adoption of non-invasive treatment approaches, growing demand for post-operative rehabilitation and injury recovery solutions, rising awareness of preventive orthopedic care, and expanding participation in sports and fitness activities. The growing elderly population and advancements in lightweight, ergonomic, and patient-specific brace designs continue to support market expansion. Orthopedic braces and supports are widely used to provide stability, pain relief, injury prevention, and post-operative rehabilitation for various anatomical regions, including the knee, ankle, spine, shoulder, wrist, and elbow. Increasing participation in sports and physical activities, a growing geriatric population susceptible to osteoarthritis and mobility impairments, and rising awareness regarding non-invasive treatment options are contributing to market expansion.
The increasing volume of orthopedic surgeries, including joint replacements, ligament reconstructions, fracture repairs, and spinal procedures, is significantly driving demand for orthopedic braces and supports. These devices play a critical role in post-operative rehabilitation by providing joint stabilization, limiting unwanted movement, reducing pain, and promoting proper healing during recovery. Healthcare providers are increasingly recommending functional knee braces, ankle supports, spinal orthoses, and shoulder immobilizers to improve patient outcomes and accelerate rehabilitation timelines. Furthermore, the growing emphasis on outpatient and ambulatory surgical procedures has increased the need for effective home-based recovery solutions, further driving the adoption of orthopedic braces and supports. Advances in brace design, including lightweight materials, adjustable fit systems, and enhanced patient comfort features, have also improved compliance rates, making these products an integral component of modern orthopedic rehabilitation protocols.
This demand is further supported by the rising procedural burden in joint replacement surgeries. For instance, the American Joint Replacement Registry (AJRR) reported that over 4 million hip and knee arthroplasty procedures were recorded in its database as of March 2024. The report also indicated an 18% year-over-year increase in procedures, reflecting a steadily expanding surgical volume base that continues to drive demand for post-operative orthopedic braces and supports.
The orthopedic braces and supports market faces a significant restraint from limited and inconsistent reimbursement coverage across key healthcare systems. In several regions, orthopedic braces are categorized as durable medical equipment (DME) or semi-essential assistive devices, resulting in partial or no reimbursement, particularly for advanced or customized products. This shifts a higher out-of-pocket cost burden onto patients, which can restrict adoption, especially in price-sensitive and emerging markets.
In addition, increasing cost containment pressures from payers and healthcare systems are driving procurement toward low-cost alternatives and generic brace designs, limiting the uptake of premium, technologically advanced products. Competitive pricing intensity among manufacturers further compresses margins, discouraging investment in innovation and premium product differentiation. Collectively, reimbursement variability and pricing pressures remain key constraints on broader market penetration and value expansion.
The growing adoption of personalized orthopedic braces enabled by advanced technologies such as 3D scanning, 3D printing, intelligent software design, and novel biomaterials presents a significant opportunity for market growth. Customized braces offer improved fit, comfort, patient compliance, and treatment outcomes compared to traditional casts and support devices. In April 2025, Dimension Ortho partnered with Rothman Orthopaedics to deploy its personalized bracing and fracture care platform across Rothman's clinical network. The solution combines advanced 3D printing, digital scanning, intelligent software design, and innovative biomaterials to provide patients with customized alternatives to conventional casts and braces. The partnership highlights the growing industry focusing on personalized orthopedic care and demonstrates the commercial potential of next-generation orthopedic bracing technologies.
Analyst Perspective
The orthopedic braces and supports market is benefiting from the rising prevalence of musculoskeletal disorders, increasing sports-related injuries, and growing demand for non-invasive treatment and rehabilitation solutions. The key competitive advantage will lie with manufacturers that offer comprehensive orthopedic solutions tailored to different patient needs, ranging from injury prevention and post-operative recovery to chronic condition management. By integrating product innovation with digital monitoring capabilities, clinician engagement, and patient-centric support programs, companies can improve treatment adherence, strengthen relationships with healthcare providers, and establish a stronger position in the evolving orthopedic care landscape.
Market Concentration & Characteristics
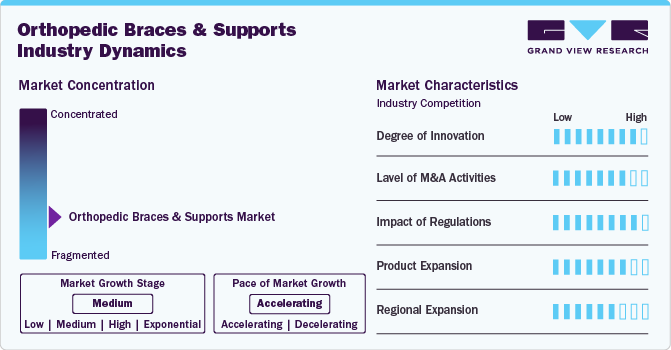
The global market is characterized by a high degree of innovation, technological advancements, and increased funding for product development. For instance, in December 2023, OrthoPediatrics Corp., a Warsaw-based company, introduced the OrthoPediatrics Specialty Bracing division, focusing on pediatric braces. Moreover, in June 2021, TayCo Brace , a medical device company and manufacturer of ankle braces, raised USD 1.2 million in a seed round financing for the development of orthotic devices.
Several market players engage in acquisition strategies to strengthen their market position. This strategy enables companies to expand their product portfolios, increase their capabilities, and improve competency. For instance, in January 2024, OrthoPediatrics Corp. acquired Boston Orthotics & Prosthetics, a pediatric orthotic management company. This acquisition expands the company's OrthoPediatrics Specialty Bracing division.
 To learn more about this report, Download Free Sample Report
Strict regulatory guidelines issued by different regulatory bodies may hinder market growth. For instance, the European Union Commission has implemented a new regulation for medical devices sold within the European Union. Braces fall under this new medical device regulation. The European market needs to undergo a significant regulatory process to enhance patient safety, followed by strict post-market surveillance.
Several orthopedic braces and supports companies are embracing this strategy to stay competitive and ahead in the dynamically evolving market landscape. For instance, in January 2024, Enovis Corporation introduced the DonJoy ROAM OA knee brace, which is designed for individuals experiencing knee pain, instability, and osteoarthritis. This brace alleviates pressure on the affected knee compartment and redistributes weight away from it, providing dynamic pain relief, enhancing stability, and aiding in mobility improvement.
Market players are adopting a diverse range of strategies, including partnerships, collaborations, mergers, and acquisitions, to expand their footprints in global markets. For instance, in May 2022, Ultra Ankle and Tandem Sport entered into a partnership agreement to accelerate growth for both companies within the rapidly expanding North American volleyball market. The new agreement will incorporate Ultra Ankle’s well-known line of ankle braces into Tandem Sport’s extensive selection of volleyball products.
Product Insights
Based on product, the races & supports type segment led the market with the largest revenue share of 74.5% in 2025, owing to an increase in orthopedic disorders and injuries, such as arthritis. This segment is subdivided into the back, ankle, knee, upper extremity braces and supports, and walking boots. The rising occurrence of ankle, knee, and upper extremity-related injuries and issues among individuals has significantly increased demand for braces and support products. These injuries can stem from various factors such as sports activities, physical exertion, accidents, or underlying medical conditions. Ankle sprains, knee ligament tears, and upper extremity conditions like wrist fractures or shoulder instability are common examples of such injuries. For instance, according to Datalys Center and Hospital for Special Surgery (HSS), anterior cruciate ligament (ACL) tears increased by 12% between 2007-08 and 2021-22.
In addition, the braces & supports segment is expected to witness the fastest CAGR growth over the forecast period, owing to the growing number of individuals suffering from knee joint-related disorders. Moreover, with a growing awareness of the importance of early intervention and proper support in the healing and management of these injuries, individuals seek reliable and effective braces and support. These products provide stability, compression, and targeted support to the affected area, aiding pain relief, reducing inflammation, promoting healing, and preventing further damage.
In 2024, pain management products held a significant market share due to the rising prevalence of pain-related issues and demand for treating chronic joint and back pain. This segment is bifurcated into Deep Vein Thrombosis (DVT) and cold therapy products. For instance, according to data published by the University of Sydney in May 2023, it is estimated that more than 800 individuals globally will suffer from back pain by 2050. Moreover, strategic alliances among various companies are rising to increase their market reach, further boosting the segment growth. For instance, in January 2025, Aspen Medical Products (Aspen), the provider of pain and mobility management products, acquired Advanced Orthopaedics, a manufacturer of orthopedic bracing solutions. This strategic acquisition broadens Aspen's expertise beyond spinal care, expanding its global presence with a comprehensive portfolio and a focus on customer-driven solutions.
End Use Insights
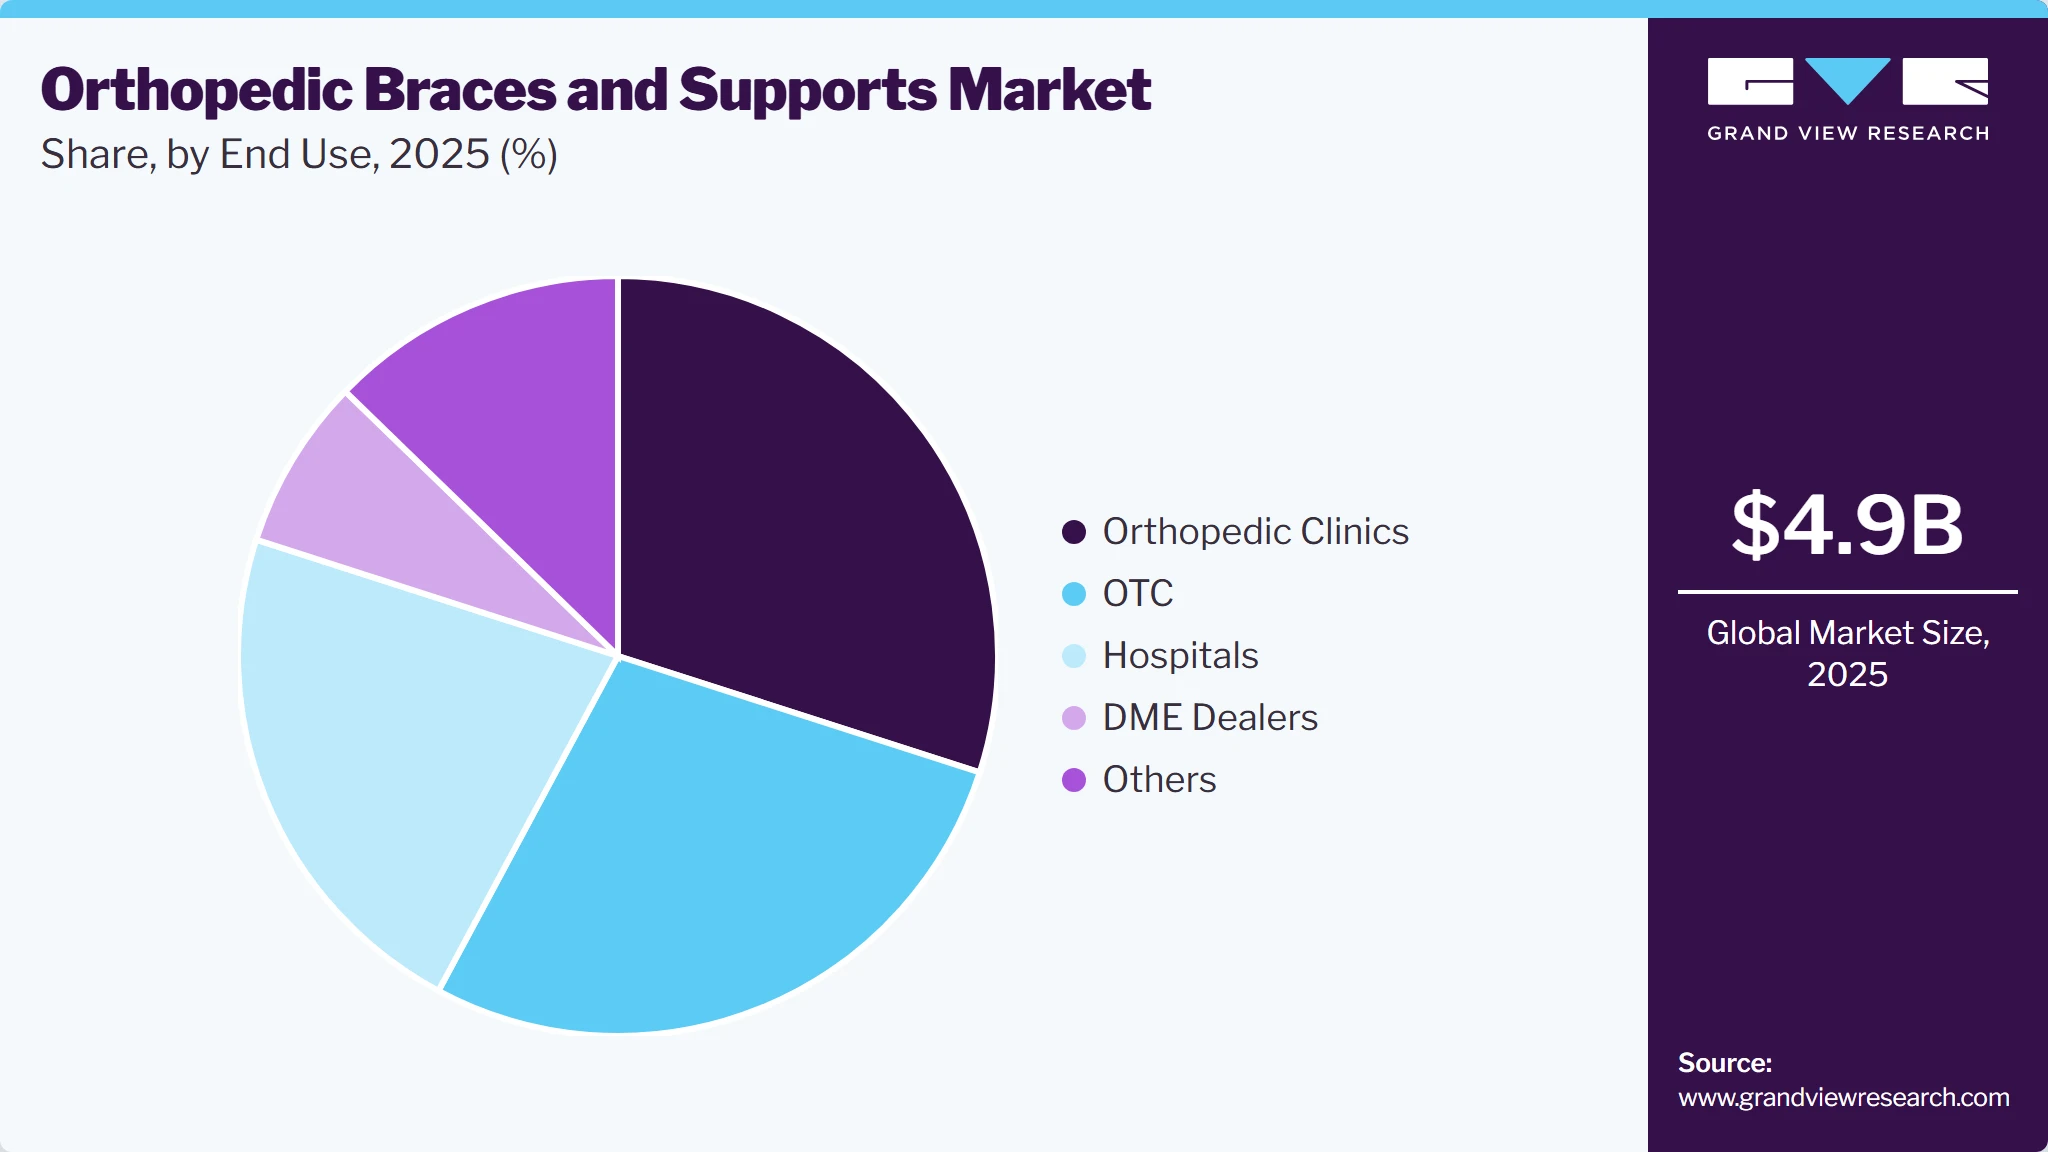
Based on end use, the orthopedic clinics segment led the market with the largest revenue share of 30.0% in 2025. This demand can be attributed to the rise in orthopedic surgeons and that orthopedic clinics are primary healthcare providers for patients experiencing musculoskeletal pain. For instance, according to an article published by Definitive Healthcare, LLC. in October 2023, there were more than 27,000 active orthopedic surgeons in the U.S.
 To learn more about this report, Download Free Sample Report
OTC is anticipated to experience the fastest growth over the forecast period. The segment's growth is attributed to the easy availability of OTC-related orthopedic braces in retail pharmacies. Patients suffering from acute muscle pain often prefer OTC products, which aid in reducing recovery time and providing quick relief to injured joints and muscles. The market growth is anticipated to be propelled by the several initiatives undertaken by key companies operating in the market. For instance, in February 2021, Breg, Inc., a billing services provider and orthopedic bracing, collaborated with distributor Club Warehouse based in Australia to expand high-value, premium orthopedic products in the Australian market.
Regional Insights
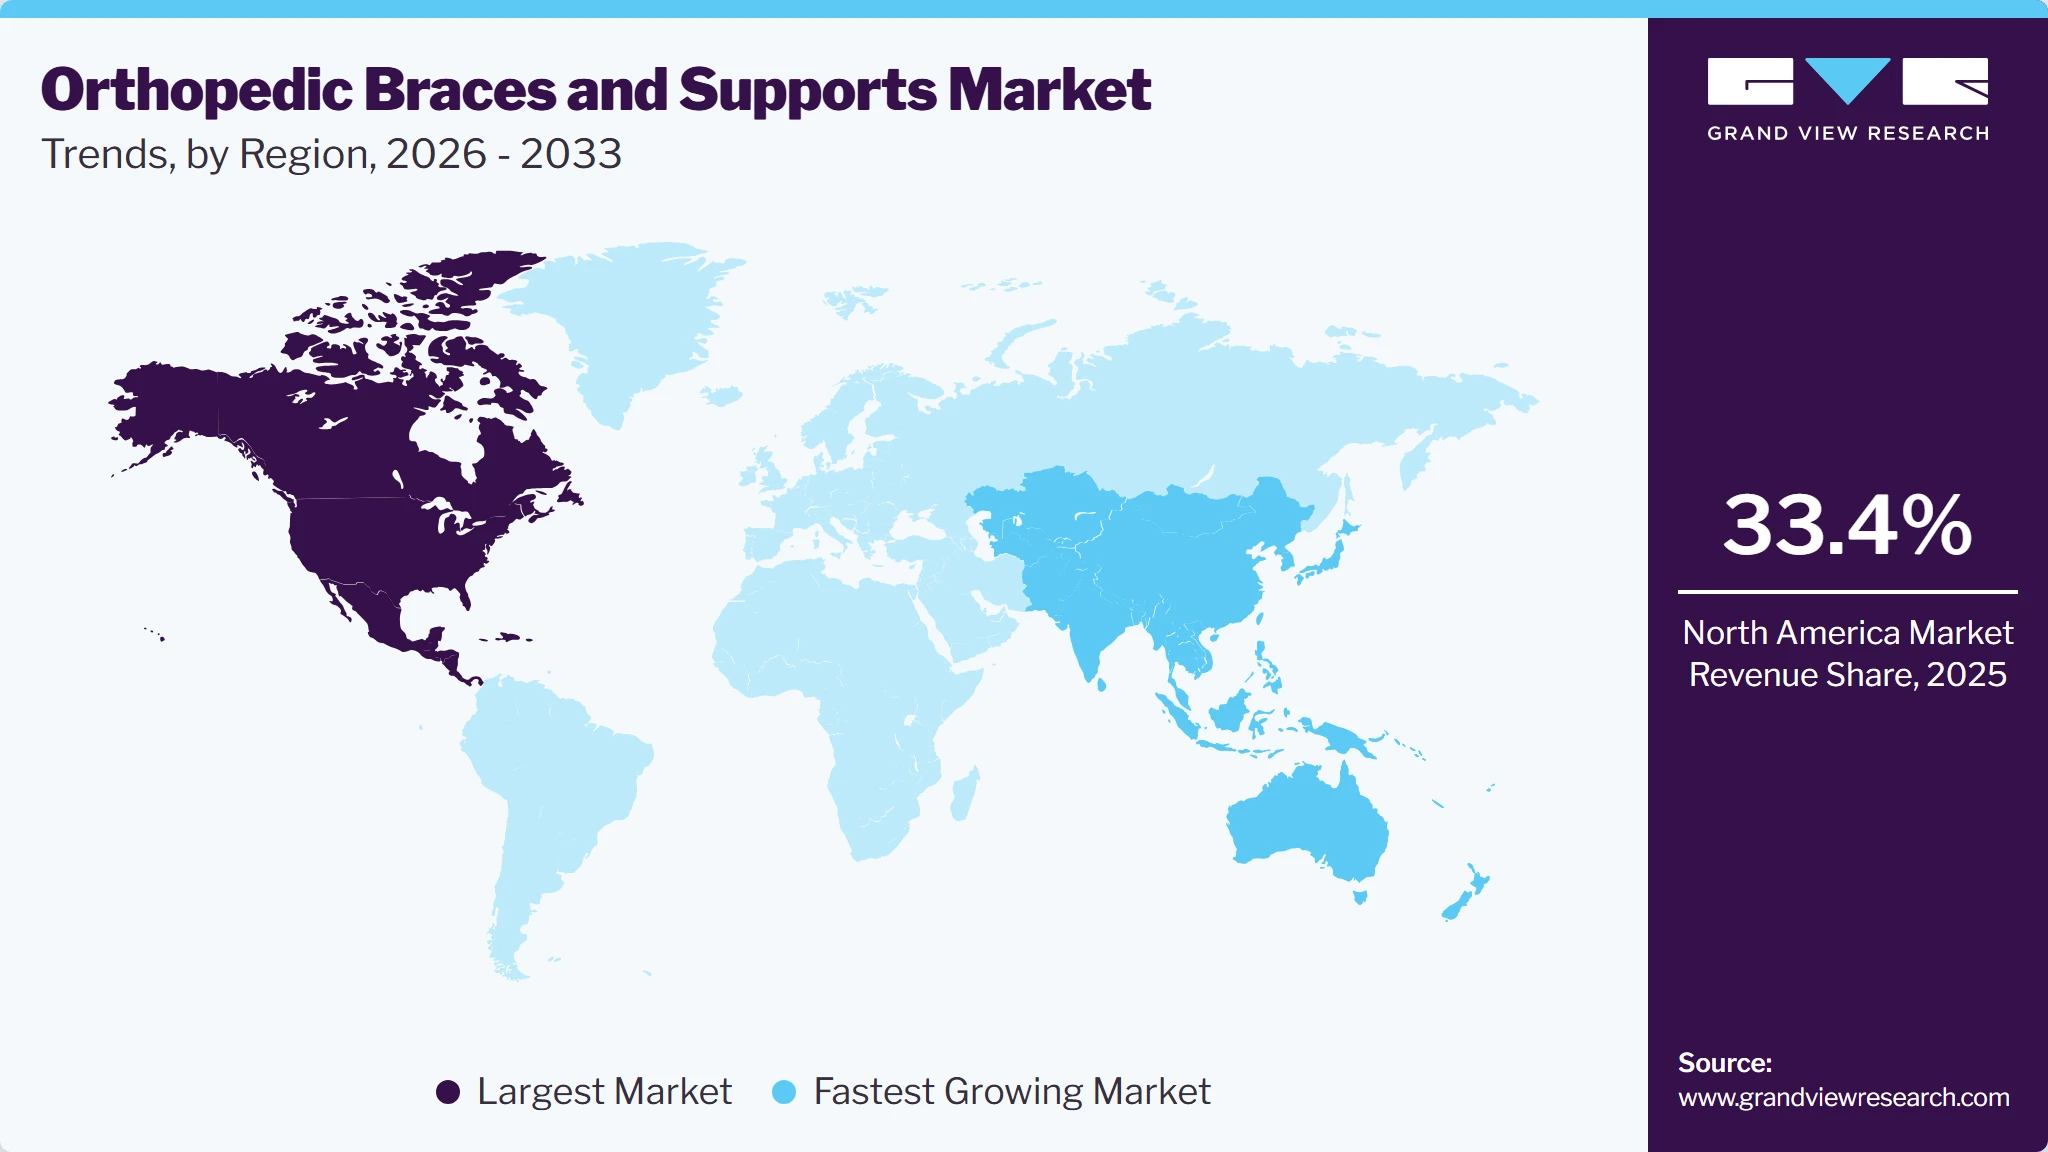
North America dominated the orthopedic braces and supports market with the largest revenue share of 33.4% in 2025, with a revenue share of 35.83%. The dominance of the North American region is attributed to the presence of technologically equipped hospitals in Canada and the U.S. In addition, the region experiences a growing prevalence of chronic conditions, resulting in an increased number of orthopedic surgeries. The expanding geriatric population further fuels this trend as older individuals are more susceptible to orthopedic issues. Furthermore, an article published in March 2022 by Becker's Orthopedic Review highlighted that in 2021 alone, approximately 1 million hip and knee arthroplasties were conducted in the U.S. This statistic underscores the significant volume of orthopedic surgical procedures in the region. Thus, an increased number of surgeries fuels market growth.
 To learn more about this report, Download Free Sample Report
U.S. Orthopedic Braces And Supports Market Trends
The market in the U.S. held the largest share in the North America region in 2025. Growing government initiatives to accelerate arthritis research and the rise in sports-related injuries are boosting market growth. For instance, according to The Johns Hopkins University in the U.S., approximately 30 million children and teens take part in organized sports each year, resulting in over 3.5 million injuries annually. Nearly one-third of all childhood injuries are related to sports activities.
Europe Orthopedic Braces And Supports Market Trends
The orthopedic braces and supports market in Europe is expected to grow significantly over the forecast period. The region’s strong emphasis on research and development drives ongoing innovation in orthopedic braces, improving product effectiveness and patient outcomes. In addition, supportive healthcare policies and well-established regulatory standards help ensure the safety and quality of these products, contributing to their growing demand among the population.
France orthopedic braces and supports industry is expected to grow significantly during orthopedic braces and supports the forecast period. The government of France introduced the Innovative Medical Devices plan in March 2022 to support the medical device sector as part of the France 2030 project. This strategic plan involves a government investment of USD 450 million in the MedTech industry. French companies and an expanding foreign sales division of global corporations service the market. These companies are often small- or medium-sized enterprises. The rapid import growth further expanded the country's orthopedic braces and support market.
Asia Pacific Orthopedic Braces And Supports Market Trends
The orthopedic braces and supports market in Asia Pacific is expected to grow at the fastest CAGR over the forecast period. This growth is attributed to the growing investments and funding by key companies in the market to develop healthcare infrastructure and expand their geographical presence. For instance, in December 2023, Tynor Orthotics , a leading brand in orthotic appliances, invested Rs 800 crore into an orthopaedic manufacturing facility in Punjab. Moreover, the demand for orthopedic braces and support in the APAC region is propelled by the increasing prevalence of obesity, the growing geriatric population, and increasing healthcare expenditure in APAC countries such as India, China, and Japan.
Japan orthopedic braces and supports market is anticipated to register considerable growth during the forecast period. The increase in the frequency of musculoskeletal problems, the rising geriatric population, and the increase in demand for joint replacement are all factors driving the market's growth in the country. Japan has a highly developed medical device industry with advanced manufacturing facilities and technologies. The availability of resources that enable the development of advanced technologies at cheaper costs is boosting the number of local manufacturing facilities.
Latin America Orthopedic Braces And Supports Market Trends
The orthopedic braces and supports industry in Latin America is anticipated to grow considerably over the forecast period. The rapidly developing healthcare infrastructure in major countries such as Brazil, Argentina, and Chile propels the region's demand for orthopedic braces and supports. Moreover, the number of fractures and joint replacement cases is anticipated to increase due to growth in sports accidents, further fueling the market.
Brazil orthopedic braces and supports market is anticipated to register the fastest CAGR during the forecast period. The country's growing focus on sports and physical activity and rising road accidents boost the market growth. According to the World Resources Institute, Brazil ranks fifth in the world for traffic deaths, with cyclists, motorcyclists, and pedestrians comprising the greatest number of fatalities.
Middle East & Africa Orthopedic Braces And Supports Market Trends
The orthopedic braces and supports market in the Middle East and Africa is witnessing steady growth driven by rising musculoskeletal disorders, increasing road accidents, and expanding orthopedic surgical volumes. The region saw an increased adoption of imported, technologically advanced braces in urban centers, supported by private healthcare investments and growing awareness of post-surgical rehabilitation. The inconsistent reimbursement policies and limited local manufacturing capacity remain challenges.
South Africa orthopedic braces and supports market is expanding due to a high burden of sports injuries, an aging population, and the prevalence of arthritis. Public-private initiatives support growth to improve access to orthopedic care and physiotherapy services. The regulatory framework is evolving under the South African Health Products Regulatory Authority (SAHPRA), leading to delays in product approvals, and limited local R&D continues to slow innovation compared to global peers.
Key Orthopedic Braces And Supports Company Insights
Key players operating in the market include BREG, Inc., Össur, DeRoyal Industries, Inc., and DJO, LLC (Enovis). Frank Stubbs Company Inc., Weber Orthopedic LP, and Ottobock are some of the emerging market players in the orthopedic braces and supports market.
-
BREG, Inc. manufactures and markets sports medicine products. The company sells its products through more than 100 distributors in 36 countries. The company offers hip, knee, spine, elbow, ankle, and foot braces. The company utilizes its well-established distribution network to expand its business geographies and cater to emerging economies.
-
Frank Stubbs Company Inc. is an emerging player that designs and manufactures orthopedic supports, binders, and compression garments for the plastic surgery market.
Key Orthopedic Braces And Supports Companies:
The following are the leading companies in the orthopedic braces and supports market. These companies collectively hold the largest market share and dictate industry trends.
- BREG, Inc.
- Frank Stubbs Company Inc.
- DeRoyal Industries, Inc.
- Össur
- Fillauer LLC
- Ottobock
- McDavid
- Bauerfeind
- Weber Orthopedic LP
- DJO, LLC (Enovis)
- 3M
- Zimmer Biomet
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., Ottobock, DJO, LLC)
Expand product portfolios through continuous innovation in orthopedic braces, supports, and rehabilitation solutions. Invest in lightweight materials, smart bracing technologies, and strategic partnerships with hospitals, clinics, and sports organizations. Strengthening global distribution networks and pursue acquisitions to expand market reach.
Strong brand reputation, extensive distribution channels, broad product offerings, and significant R&D capabilities. Established relationships with healthcare providers and reimbursement networks support large-scale market penetration.
High manufacturing and operational costs, complex regulatory requirements, and longer product development cycles. Large organizations may face challenges rapidly responding to niche customer demands and emerging market trends.
Emerging Players (e.g., Fillauer LLC)
Focus on specialized orthopedic bracing solutions for sports injuries, rehabilitation, and chronic musculoskeletal conditions. Leverage direct-to-consumer channels, digital marketing, clinician engagement programs, and product customization to build market presence.
Greater flexibility in product development, faster adoption of new materials and technologies, and ability to address niche clinical and patient requirements. Strong focus on personalized solutions and customer service.
Limited global presence, lower brand recognition, and fewer financial resources for large-scale expansion and R&D investments. Dependence on regional markets and distributor networks can constrain growth.
Recent Developments
-
In October 2024, Dr. Brace, a manufacturer of sports orthopedic braces, launched the Dr. Brace Knee Compression Sleeve. It includes 360-degree compression to evenly distribute support across the knee joint, alongside side stabilizers that enhance joint alignment and minimize strain during movement.
-
In January 2024, Enovis Corporation acquired LimaCorporate S.p.A., an orthopedic implant solutions company. Lima strengthens Enovis’ position in the global orthopedic reconstruction market by offering various orthopedic medical devices, including braces.
-
In October 2023, OrthoPediatrics Corp. launched the DF2 Brace to treat kids suffering from musculoskeletal injuries. It is intended for femur fracture fixation in pediatric patients aged six months to 5 years.
Orthopedic Braces And Supports Market Report Scope
Report Attribute
Details
Market size in 2025
USD 4.9 billion
Estimated market size in 2026
USD 5.2 billion
Projected market size by 2033
USD 8.1 billion
Growth rate
CAGR of 6.5% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait
Key companies profiled
BREG, Inc.; Frank Stubbs Company Inc.; DeRoyal Industries, Inc.; Össur; Fillauer LLC; Ottobock; McDavid; Bauerfeind; Weber Orthopedic LP; DJO, LLC (Enovis); 3M; Zimmer Biomet
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchasse. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Orthopedic Braces And Supports Market Report Segmentation
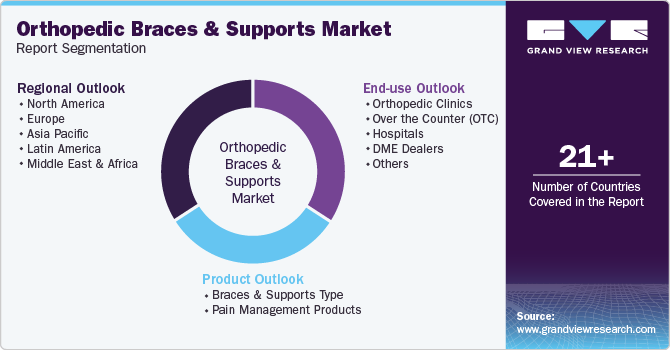
This report forecasts revenue growth at the regional & country level and provides an analysis of the latest trends and opportunities in each of the sub-segments from 2021 to 2033. For this report, Grand View Research has segmented the global orthopedic braces and supports market based on product, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Braces & Supports Type
-
Knee Braces & Supports
-
Knee Braces for Osteoarthritis and Ligament Injuries
-
Post-operational Knee Braces
-
-
Back Braces & Supports
-
Upper Spine Orthoses
-
TLSOs
-
LSOs
-
Others
-
-
Ankle Braces & Supports
-
Soft Braces
-
Hinged Braces
-
-
Walking Boots
-
Pneumatic
-
Non-pneumatic
-
-
Upper Extremity Braces & Supports
-
Elbow Braces & Supports
-
Wrist Braces & Supports
-
Others
-
-
Hip Braces & Supports
-
Others
-
-
Pain Management Products
-
Cold Therapy Products
-
DVT Products
-
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Orthopedic Clinics
-
Over the Counter (OTC)
-
Hospitals
-
DME Dealers
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Norway
-
Denmark
-
Sweden
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
MEA
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The orthopedic braces and supports market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each orthopedic braces and supports segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Braces & Supports Type
This segment includes orthopedic devices designed to provide stability, compression, and support to joints, muscles, and ligaments affected by injury, strain, or chronic musculoskeletal conditions. It encompasses products such as knee braces, ankle supports, wrist splints, back supports, and other supportive devices intended to enhance mobility, aid recovery, and prevent further injury.
Pain Management Products
This segment includes products designed to alleviate acute and chronic pain associated with musculoskeletal disorders, injuries, and post-surgical recovery. It encompasses topical analgesics, hot and cold therapy products, transcutaneous electrical nerve stimulation (TENS) devices, pain relief patches, and other non-invasive solutions aimed at reducing discomfort and improving patient quality of life.
Segment - End Use
Revenue capture definition
Orthopedic Clinics
Specialized healthcare facilities that diagnose, treat, and rehabilitate musculoskeletal injuries and disorders.
Over the Counter (OTC)
Retail channels that sell orthopedic and pain management products directly to consumers without a prescription.
Hospitals
Healthcare institutions that utilize orthopedic products for patient treatment, surgery, and rehabilitation.
DME Dealers
Suppliers and distributors of durable medical equipment, including braces, supports, and mobility aids.
Others
Includes rehabilitation centers, physiotherapy clinics, sports medicine facilities, and home healthcare providers.
Estimation Model
Research Model
The orthopedic braces and supports market was analyzed using a combination of extensive secondary research and targeted primary research. Market estimates and forecasts were developed by assessing key market parameters, including:
-
Prevalence of orthopedic disorders and musculoskeletal injuries
-
Incidence of sports-related injuries and trauma cases
-
Aging population and arthritis burden
-
Adoption trends of preventive and rehabilitative orthopedic care
-
Technological advancements in orthopedic bracing solutions
-
Healthcare expenditure and reimbursement landscape
-
Market drivers, restraints, and emerging industry trends
A weighted-average analytical framework was applied to quantify the impact of these factors and derive market growth forecasts. All estimates and assumptions were validated through primary interviews with key industry participants, including:
-
Leading orthopedic brace and support manufacturers
-
Orthopedic surgeons and sports medicine specialists
-
Rehabilitation and physiotherapy professionals
-
Distributors and industry experts
-
The primary research process was conducted to:
-
Validate market size estimates and assumptions
-
Assess current demand and future growth prospects
-
Understand product adoption trends and competitive dynamics
Region-Wise Market Calculation
Regional Market Estimation
Approach 1: Bottom-Up Market Assessment
Objective: To estimate regional and global market size by analyzing country-level demand for orthopedic braces and support market.
Key Variables Evaluated:
-
Unit sales volume of orthopedic braces and supports
-
Average selling prices (ASPs) by product category
-
Regional disease and injury prevalence
-
Product penetration rates
-
Healthcare expenditure levels
-
Distribution network strength
-
Technological adoption trends
-
Demographic and target population growth
Conclusion: Country-level market values were aggregated to derive regional estimates, which were subsequently consolidated to calculate the global market size using a bottom-up methodology.
Approach 2: Volume-Price Analysis
Objective: To estimate market value through analysis of product utilization rates and average product pricing.
Key Inputs:
-
Number of patients requiring orthopedic support devices
-
Procedure and rehabilitation volumes
-
Product adoption rates across healthcare settings
-
Average selling prices by product segment
Conclusion: This approach provided insights into demand patterns, utilization trends, and regional adoption rates.
Approach 3: Competitive Share Analysis
Objective: To validate market estimates through company-level revenue and market share assessment.
Key Inputs:
-
Annual reports and financial disclosures
-
Product portfolio analysis
-
Geographic presence of manufacturers
-
Distributor network assessment
-
Expert interviews
Conclusion: Company revenue mapping and competitive positioning analysis were used to validate overall market size and regional estimates.
Global Market Forecasting
Market growth forecasts were derived based on:
-
Growth in orthopedic brace and support revenues
-
Growth of the broader orthopedic and rehabilitation markets
-
Increasing orthopedic procedure volumes
-
Rising incidence of sports injuries and musculoskeletal disorders
-
Expansion of the elderly and arthritis patient population
-
Technological innovation and product adoption trends
Segment Share Calculation
Market segmentation analysis was conducted by evaluating utilization patterns, clinical applications, product availability, and regional adoption rates.
Segment shares were determined using a weighted variable analysis model incorporating:
Adoption rates
-
Clinical effectiveness
-
Patient and physician awareness
-
Cost efficiency
-
Product accessibility and availability
-
Reimbursement support
-
Regional penetration rates
The resulting segment allocations were validated through primary interviews, company disclosures, and secondary industry research.
Research Scope and Assumptions
-
The report provides market revenue estimates (USD Million) and forecasts for the orthopedic braces and supports market.
-
Market sizing was conducted using a bottom-up methodology, with country-level estimates aggregated to regional and global levels.
-
Key market dynamics, competitive landscape, regulatory environment, technological advancements, and end-user trends were analyzed to assess future demand.
-
Forecasts were developed using a combination of historical trend analysis, correlation analysis, and expert validation.
-
All estimates and forecasts were verified through primary interviews with industry stakeholders.
-
Inflationary impacts have not been incorporated into market forecasts unless otherwise specified.
-
Numbers may not add up precisely due to rounding.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Volume Analysis by Product Type
Developed a comprehensive volume assessment of orthopedic braces and supports segmented by knee braces, ankle braces, spinal orthoses, upper extremity supports, and soft supports. The study evaluates annual unit volumes, prescription versus OTC utilization, patient demographics, injury prevalence, and regional demand patterns.
Enables stakeholders to identify high-volume product categories, optimize manufacturing and inventory planning, allocate resources effectively, and prioritize investments in rapidly growing product segments.
Patient Journey & Product Adoption Analysis
Developed a patient-centric assessment tracking diagnosis, treatment recommendation, brace selection, rehabilitation, and long-term usage across orthopedic conditions. The study incorporates patient preferences, physician prescribing patterns, treatment adherence, purchasing channels, and product replacement cycles.
Provides actionable insights for improving patient engagement, product adoption, treatment compliance, channel strategies, and customer retention initiatives.
Advanced Orthopedic Technology Assessment
Conducted an in-depth evaluation of emerging orthopedic technologies, including smart braces, sensor-enabled monitoring systems, lightweight composite materials, and customized 3D printed supports. The study benchmarks technology adoption, clinical effectiveness, patient outcomes, and competitive positioning.
Helps stakeholders identify innovation opportunities, enhance product performance, improve patient outcomes, and strengthen long-term competitive differentiation through technology investments.
Frequently Asked Questions About This Report
The global orthopedic braces and supports market size was valued at USD 4.9 billion in 2025 and is estimated at USD 5.2 billion in 2026.
Some key players operating in the orthopedic braces and supports market include Össur, BREG, Inc., DeRoyal Industries, Inc., Bauerfeind, • DJO Global, Inc., Ottobock, Fillauer LLC, Frank Stubbs Company Inc., and McDavid, Hely & Weber.
Key factors that are driving the orthopedic braces and supports market growth include rising incidence of osteoarthritis, increasing cases of sports-related injuries, and growing geriatric population bases.
Asia Pacific is the fastest-growing region over the forecast period.
Orthopedic clinics held the largest revenue share of 30.0% in 2025, while OTC is the fastest-growing segment.
The global orthopedic braces and supports market is expected to grow at a compound annual growth rate of 6.5% from 2026 to 2033 to reach USD 8.1 billion by 2033.
The braces & supports type segment led with the largest revenue share over 74.5% in 2025.
North America dominated the orthopedic braces and supports market with a share of over 33.4% in 2025.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


