
- Home
- »
- Medical Devices
- »
-
Palliative Care Market Size, Share & Growth Report, 2026-2033GVR Report cover

Palliative Care Market (2026 - 2033)
Size, Share & Trends Analysis Report by Condition (Cancer, HIV), By Age Group (Geriatric, Adult), By Provider (Home-based, Hospitals & Clinics), By Diagnostic Group, By Region, And Segment Forecasts
Market Size, 2025
$151.9BMarket Estimate, 2026
$167.0BMarket Forecast, 2033
$352.7BCAGR, 2026–2033
11.3%Palliative Care Market Summary
The global palliative care market size was valued at USD 151.9 billion in 2025 and is projected to grow from USD 167.0 billion in 2026 to USD 352.7 billion in 2033, at a CAGR of 11.3% from 2026 to 2033. Europe dominated the market, accounting for a revenue share of 35.0% in 2025. Palliative care involves comprehensive services for patients with conditions that do not respond to curative treatments.
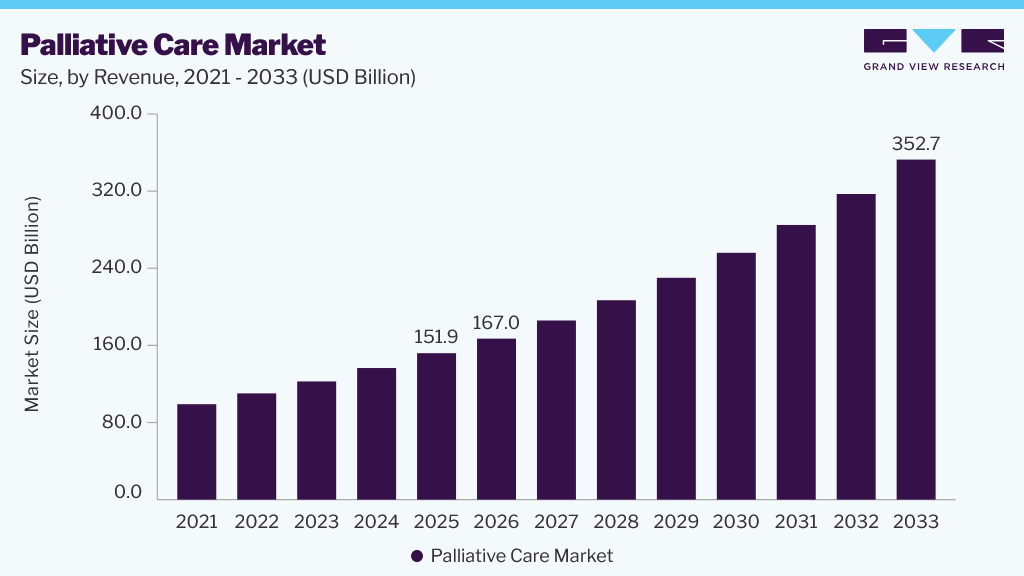 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By provider: The home-based providers segment held the largest market share, at around 45.0% in 2025.
- By condition: The cancer segment accounted for the largest revenue share of over 35.0% in 2025.
- By diagnostic group: The non-communicable diseases (NCD) segment accounted for the largest revenue share of over 65.0% in 2025.
- By age group: The adult segment accounted for the largest revenue share of around 50.0% in 2025.
Regional Highlights
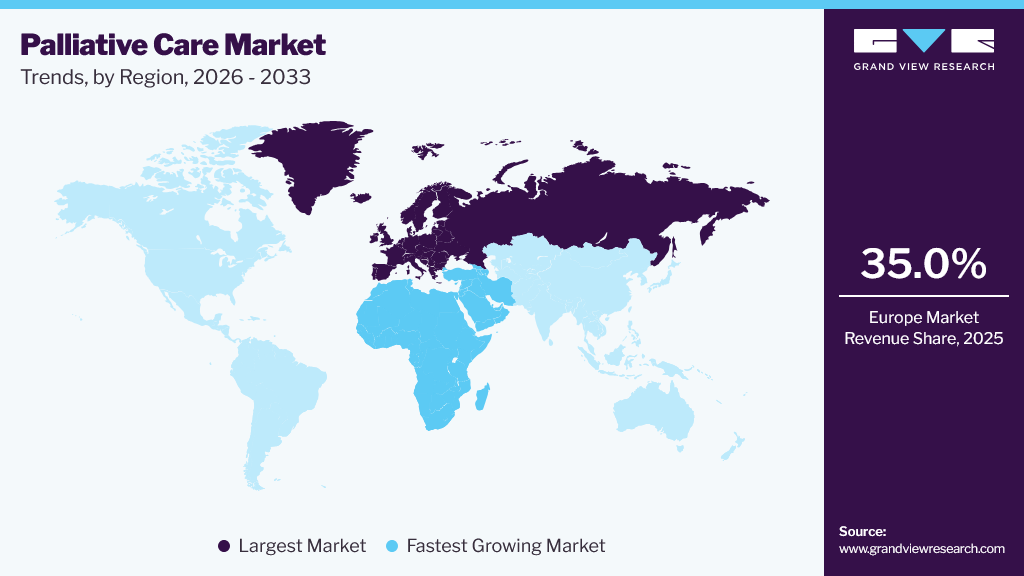
- Largest regional market: Europe (35.0% revenue share, 2025)
- Fastest-growing regional market: Middle East & Africa (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 151.9 Billion
- Estimated market size in 2026: USD 167.0 Billion
- Projected market size by 2033: USD 352.7 Billion
- CAGR (2026-2033): 11.3 %
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The major factors driving market growth include the increasing prevalence of life-threatening disorders, supportive government policies and initiatives that promote these services as an integral part of healthcare, and a rising number of service providers worldwide. In addition, the growing presence of private and public providers in developing countries is expected to further contribute to market expansion.
Increasing awareness of palliative care services is also anticipated to boost service utilization. According to the Australian Institute of Health and Welfare (AIHW), in 2024, 202 services participating in the Australian Palliative Care Outcomes Collaboration (PCOC) program provided palliative care to approximately 72,400 patients across Australia. Supportive government initiatives, such as funding, policy development, and awareness promotion, are expected to facilitate market growth.
Many countries allocate special funding to enhance the quality and accessibility of these services. For instance, in May 2023, the Albanese government in Australia allocated USD 53 million for 14 national palliative care projects aimed at improving care for Australians. In addition, USD 15.9 million was allocated to the national End of Life Directions for Aged Care (ELDAC) service to provide training and support to service providers and general practitioners in advanced care planning and skills development.
Analyst Perspective
Palliative care has become a strategic component of modern healthcare systems due to rising chronic disease prevalence and aging populations. Healthcare providers increasingly integrate palliative services to improve patient outcomes and optimize resource utilization. Growing awareness of patient-centered care continues to support long-term demand across hospitals, home healthcare, and specialized care settings. Market expansion faces challenges due to workforce shortages, uneven access to specialized services, and limited reimbursement frameworks across several regions. Variations in healthcare infrastructure also restrict consistent service delivery across urban and rural populations. Regulatory differences and inadequate training programs further constrain the broader adoption of comprehensive palliative care models.
Provider Insights
The home-based providers segment accounted for the largest revenue share, at around 45.0%, in 2025 and is projected to grow at the fastest rate from 2026 to 2033, owing to elderly patients' strong preference for home-based care. Moreover, many providers are launching home-based centers offering services to patients with special needs. Healthcare organizations continue to expand home-based palliative care programs to improve patient access and continuity of care. For instance, in July 2025, the Rajasthan Health Department launched a statewide home-based palliative care program, deploying multidisciplinary mobile teams to deliver palliative services directly to patients' homes.
The new program provides patients with at-home services for serious conditions. The hospitals & clinics segment is expected to grow significantly over the forecast period. This is due to the well-established infrastructure and high capacity of hospitals & clinics to cater to complex health conditions. Hospitals & clinics are expanding service offerings, and payers are expanding reimbursement for these services, contributing to the segment’s growth. According to Yale University, more than 1,700 hospitals with more than 50 beds offer palliative care programs in the U.S.
Condition Insights
The cancer segment accounted for the highest revenue share of over 35.0% in 2025. This is attributed to the rising prevalence of cancer globally and increasing focus on palliative care services in improving the quality of life for cancer patients and their families. Healthcare providers continue to strengthen specialized oncology care to address the growing burden on cancer patients. For instance, in March 2025, Moffitt Cancer Center partnered with Empath Health to launch inpatient hospice services for eligible cancer patients.
The respiratory disease segment is expected to witness the fastest growth from 2026 to 2033, owing to the rising prevalence of respiratory diseases, such as chronic obstructive pulmonary disease & asthma, and rising demand for coordinated respiratory and palliative care services. Healthcare systems are strengthening integrated respiratory and palliative care models to address the rising burden of chronic respiratory disease. For instance, in 2025, the EU PAL-COPD project launched a multinational clinical program integrating palliative care into advanced COPD management across 18 hospitals in six European countries.
Diagnostic Group Insights
The non-communicable diseases (NCD) segment accounted for the largest revenue share, exceeding 65.0% in 2025. This can be attributed to the growing prevalence of NCDs, mainly due to changing and sedentary lifestyles. These conditions include cancer, cardiovascular diseases, diabetes, chronic respiratory diseases, and neurodegenerative diseases. According to the World Health Organization (WHO), 41 million people die yearly due to NCDs, accounting for 74% of the global mortality rate. Many companies are launching specialized centers offering services to patients with special needs, such as cancer patients.
Age Group Insights
The adult segment dominated the market, with a share of over 50.0% in 2025. The prevalence of chronic and life-threatening illnesses, such as cancer, cardiovascular diseases, and neurodegenerative conditions, is rising in adults. These diseases require palliative care to manage symptoms, provide comfort, and improve quality of life; thus, contributing to the high demand for these services among adults. The pediatric segment is expected to register the fastest CAGR from 2026 to 2033.
There is a growing incidence of chronic and life-threatening diseases among children, including congenital disorders, cancer, and neurological conditions. These diseases require specialized palliative care to enhance the quality of life and offer physical & emotional support. Hence, providers are expanding their business to offer specialized services to patients. Healthcare providers are expanding specialized pediatric palliative care services to address growing demand from children with complex conditions. For instance, in November 2025, KK Women's and Children's Hospital, SingHealth Community Hospitals, and Lien Foundation launched the Cocoon program, establishing Singapore's only pediatric community facility for palliative and complex care.
Regional Insights
The Europe dominated the market, accounting for a revenue share of 35.0% of revenue in 2025. Europe is one of the regions with the highest geriatric population, leading to an increased market demand. This, in turn, creates the need for specialized services to address the unique needs of older people, including end-of-life care. Many European countries, such as Germany, Italy, and the UK, have integrated palliative care into their healthcare systems, recognizing it as an essential component of healthcare delivery. This integration ensures that services are accessible to patients as part of their medical care. According to the World Health Organization, 26% of Central and Eastern European countries and 63% of Western European countries have a standalone national palliative care plan.
 To learn more about this report, Download Free Sample Report
Middle East & Africa Palliative Care Market Trends
The palliative care market in MEA is expected to witness the fastest CAGR from 2026 to 2033 due to an increasing prevalence of chronic and non-communicable diseases, such as cancer, cardiovascular diseases, and diabetes. Some countries, such as the UAE, Jordan, and Egypt, have been investing in improving their healthcare infrastructure and services, which is also expected to contribute to the region’s growth. Healthcare authorities in some MEA countries have taken steps to integrate palliative care into their healthcare systems, emphasizing its role in providing services to patients with life-threatening illnesses. Regional healthcare investments are accelerating the integration of palliative care into healthcare systems across the Middle East and Africa. For instance, in April 2025, the Department of Health – Abu Dhabi launched the Palliative and End-of-Life Care Strategy, establishing a comprehensive framework to integrate palliative care services across the emirate's healthcare system.
Key Palliative Care Company Insights
The market is highly fragmented, with many local private, public, and community-based providers. The services in many countries are not defined and are provided by family members. Hence, the market is not in the mature phase. However, many private players are entering the market to meet growing demand for care services. These players are adopting several strategies, including partnerships & collaborations, to meet rising demand. For instance, in February 2023, Pallium India and Athulya Senior Care collaborated and launched palliative care services in South India.
Key Palliative Care Companies
The following key companies have been profiled for this study on the palliative care market:
-
Adventist Health
-
Baptist Health
-
Teresa Dellar Palliative Care Residence
-
Fonthill Care
-
Banksia Palliative Care Service Inc.
-
HammondCare
-
Alpha Palliative Care
-
Drakenstein Palliative Hospice
-
VITAS Healthcare
-
Amedisys
-
Gentiva Health Services (Kindred at Home)
-
Genesis HealthCare System
Recent Developments
-
In March 2025, the Singapore International Foundation (SIF) and Pallium India launched the Singapore-India: Palliative Care Accessibility Core Training (PACT) project to strengthen palliative care capabilities across 14 Indian states. The initiative brings together multidisciplinary healthcare professionals to improve clinical practice, education, and service delivery, to benefit nearly 35,000 patients and caregivers.
-
In March 2025, Kerala's Department of Health & Family Welfare, in collaboration with Kerala Digital University, officially launched the Kerala Care Palliative Care Grid. The digital platform integrates government and voluntary-sector palliative care units to streamline patient registration, referrals, and follow-up services across the state. By strengthening coordination and expanding community-based care, the initiative improves service accessibility and establishes a scalable digital model that supports broader adoption of integrated palliative care systems.
Palliative Care Market Report Scope
Report Attribute
Details
Market size in 2025
USD 151.9 billion
Estimated market size in 2026
USD 167.0 billion
Projected market size by 2033
USD 352.7 billion
Growth rate
CAGR of 11.3 % from 2026 to 2033
Base year for estimation
2025
Historical data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Condition, diagnostic group, age group, provider, region
Regional Scope
North America; Europe; Asia Pacific; Latin America; MEA
Country Scope
U.S.; Canada; UK; Germany; France; Italy; Spain; Norway; Denmark; Sweden; Japan; China; India; Australia; South Korea; Thailand; Mexico; Brazil; Argentina; South Africa; Saudi Arabia; Jordan; Kuwait
Key companies profiled
Adventist Health; Baptist Health; Teresa Dellar Palliative Care Residence; Fonthill Care; Banksia Palliative Care Service Inc.; HammondCare; Alpha Palliative Care; Drakenstein Palliative Hospice; VITAS Healthcare; Amedisys; Gentiva Health Services (Kindred at Home); Genesis HealthCare System
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Palliative Care Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global palliative care market report based on condition, diagnostic group, age group, provider, and region:
-
Condition Outlook (Revenue, USD Million, 2021 - 2033)
-
Cancer
-
Dementia
-
HIV
-
Cerebrovascular Disease
-
Respiratory Disease
-
Others
-
-
Diagnostic Group Outlook (Revenue, USD Million, 2021 - 2033)
-
Communicable diseases
-
Non-communicable diseases
-
Injury, poisoning, external causes
-
Maternal, perinatal, and nutritional conditions
-
-
Age Group Outlook (Revenue, USD Million, 2021 - 2033)
-
Pediatric
-
Adult
-
Geriatric
-
-
Provider Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals and Clinics
-
Home-based
-
Community Settings
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Norway
-
Denmark
-
Sweden
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Mexico
-
Brazil
-
Argentina
-
-
Middle East & Africa (MEA)
-
South Africa
-
Saudi Arabia
-
Jordan
-
Kuwait
-
-
Frequently Asked Questions About This Report
Europe dominated with a 35.0% revenue share in 2025.
The cancer segment accounted for the largest revenue share of over 35.0% in 2025
The global palliative care market size was valued at USD 151.9 billion in 2025 and is estimated at USD 167.0 billion for 2026.
The global palliative care market is expected to grow at a CAGR of 11.3 % from 2026 to 2033, reaching USD 352.7 billion
Key players in the market include Adventist Health, Baptist Health, Teresa Dellar Palliative Care Residence, Fonthill Care, Banksia Palliative Care Service Inc., HammondCare, Alpha Palliative Care, Drakenstein Palliative Hospice, VITAS Healthcare, Amedisys, Gentiva Health Services (Kindred at Home), Genesis HealthCare System, and others.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


