
- Home
- »
- Pharmaceuticals
- »
-
Pancreatic Cancer Treatment Market Size Report, 2026-2033GVR Report cover

Pancreatic Cancer Treatment Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Exocrine, Endocrine), By Treatment (Chemotherapy, Radiation Therapy), By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2025
$3.3BMarket Estimate, 2026
$3.7BMarket Forecast, 2033
$8.3BCAGR, 2026–2033
12.4%Pancreatic Cancer Treatment Market Summary
The global pancreatic cancer treatment market size was valued at USD 3.3 billion in 2025 and is projected to grow from USD 3.7 billion in 2026 to USD 8.3 billion by 2033, at a CAGR of 12.4% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 39.2% in 2025. Demand is linked to disease incidence, access to diagnostic services, treatment eligibility, and the availability of specialist oncology care across healthcare systems.
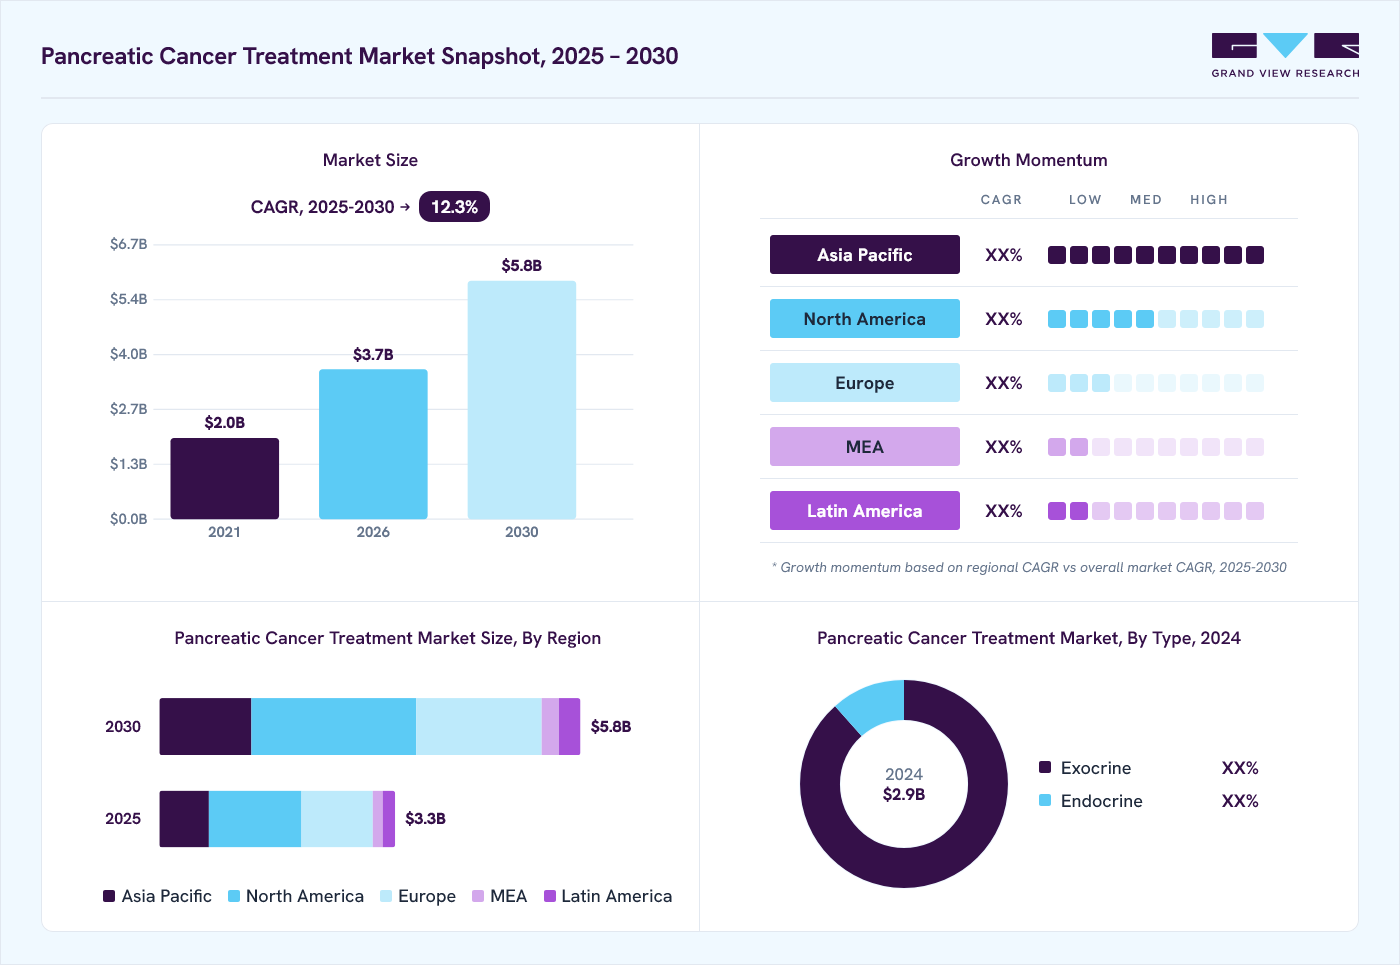 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Exocrine segment held the largest market share of 88.3% in 2025.
- By treatment: Chemotherapy segment held the largest market share of 43.1% in 2025.
- By distribution channel: Hospital pharmacies segment held the largest market share in 2025.
Regional Highlights
- Largest regional market: North America (39.2% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market Size in 2025: USD 3.3 Billion
- Estimated market size in 2026: USD 3.7 billion
- Projected Market Size by 2033: USD 8.3 Billion
- CAGR (2026-2033): 12.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The pancreatic cancer treatment market comprises medicines and therapeutic procedures used to manage cancers originating in the pancreas. Pancreatic ductal adenocarcinoma accounts for most cases, while pancreatic neuroendocrine tumors form a smaller disease group. Treatment selection depends on tumor type, disease stage, resectability, molecular characteristics, and the patient's general health. Surgery remains the main treatment option with curative intent for eligible patients, often combined with chemotherapy before or after the operation. For locally advanced or metastatic disease, systemic chemotherapy is a key treatment, while radiation therapy and supportive care are used in selected cases. Targeted medicines are prescribed to patients whose tumors carry specific molecular alterations. The market includes chemotherapy, targeted therapy, and other emerging treatments.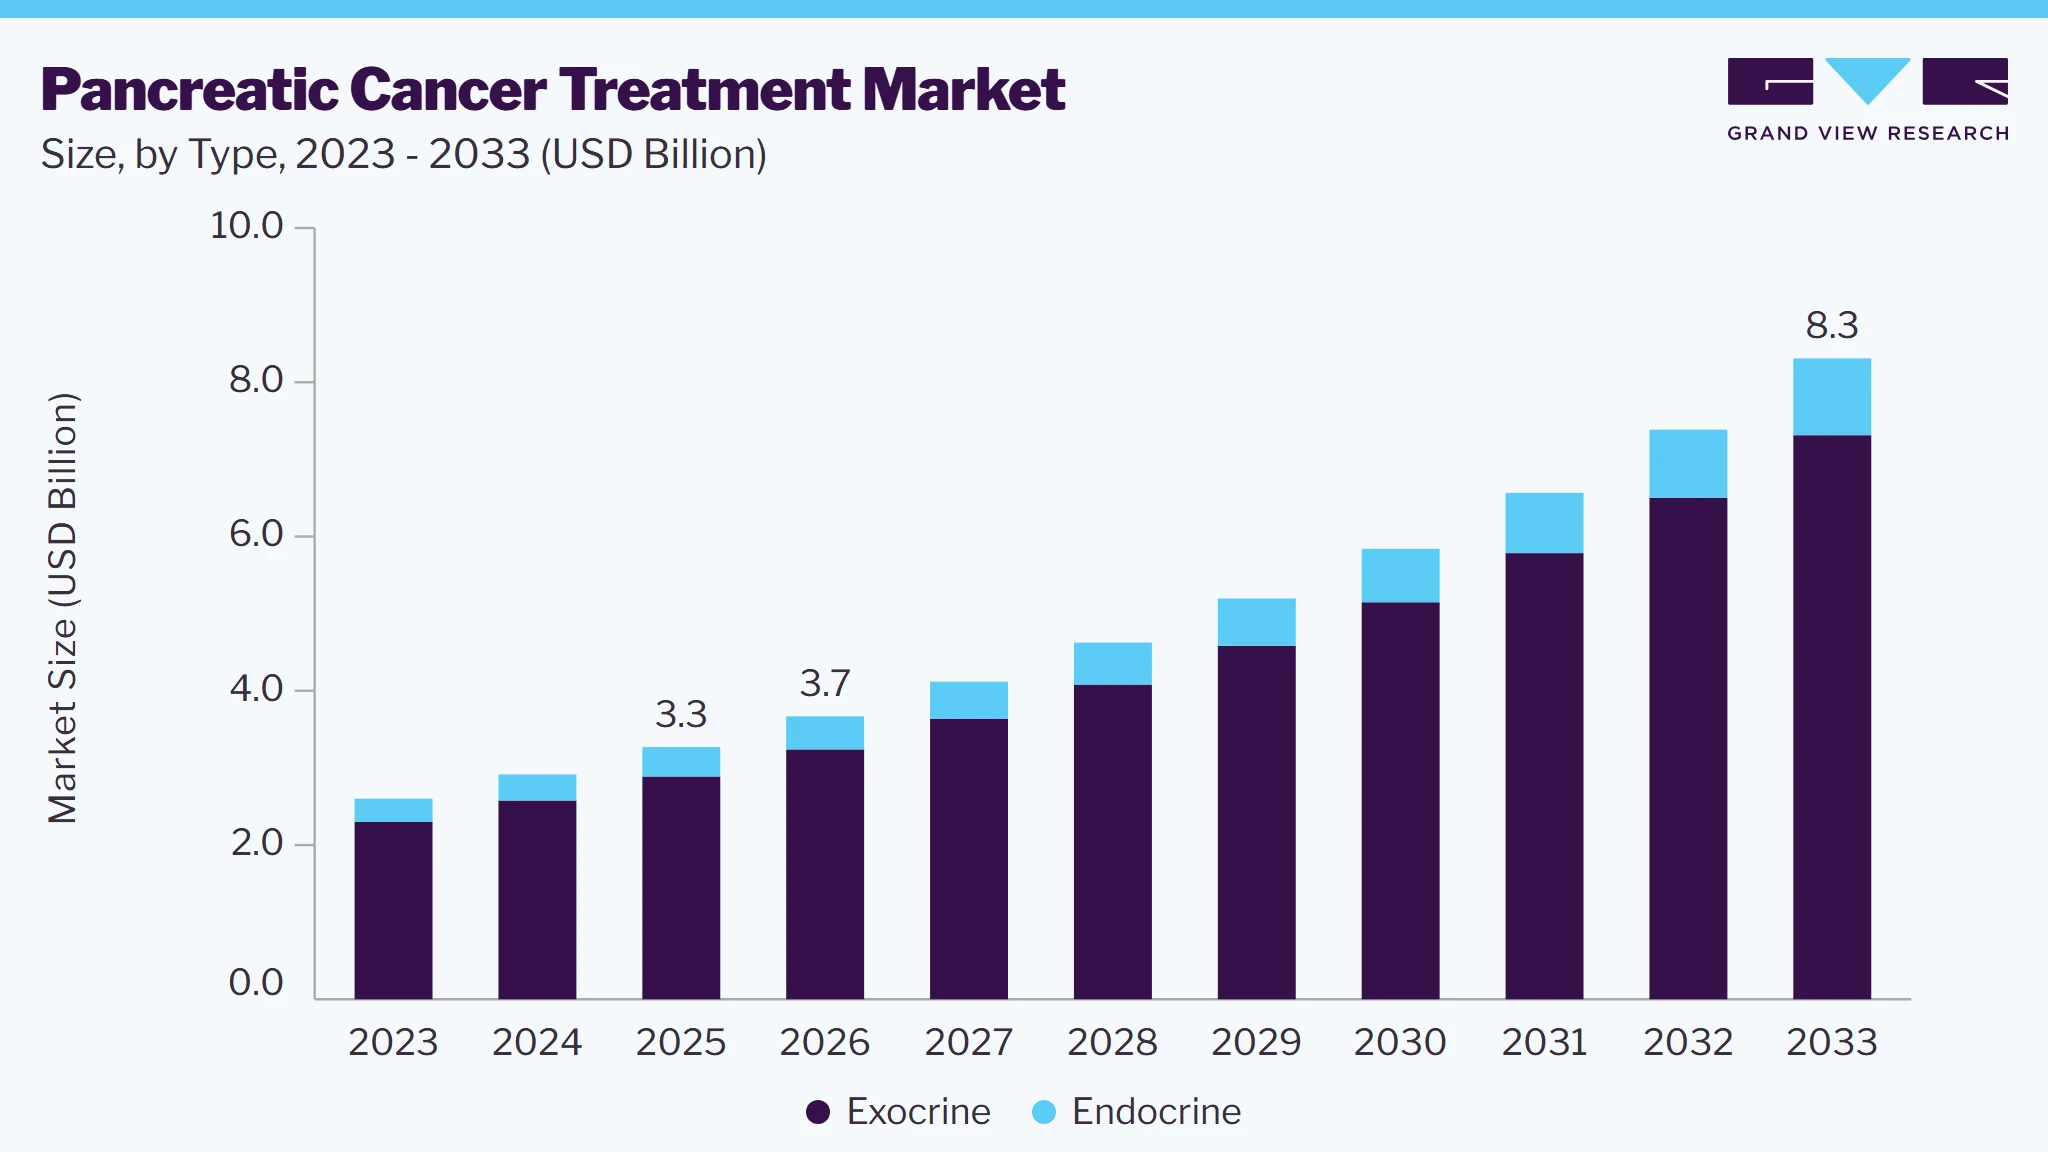 To learn more about this report, Download Free Sample Report
The disease burden is associated with late diagnosis, limited surgical eligibility, and a high risk of disease progression. Early symptoms, including abdominal discomfort, weight loss, jaundice, and changes in appetite, can be difficult to distinguish from other conditions. As a result, some patients are diagnosed after the cancer has spread beyond the pancreas. Smoking, obesity, chronic pancreatitis, family history, and inherited genetic changes are among the factors associated with disease risk. These clinical characteristics influence treatment selection and the duration of care. Patients with localized tumors may undergo surgery followed by chemotherapy, whereas those with advanced disease generally require systemic treatment. Access to specialist oncology services, diagnostic imaging, pathology, and molecular testing also affects the treatment process. Differences in healthcare infrastructure and reimbursement policies influence the availability of approved medicines across countries and support variation in treatment demand between regions.
Research and development activities focus on improving treatment response, extending disease control, and addressing resistance to existing medicines. Chemotherapy remains a key treatment for pancreatic adenocarcinoma, while targeted therapies are used for selected patients based on specific molecular alterations. Clinical research also covers immunotherapies, therapeutic vaccines, and new drug combinations. However, the dense tissue surrounding pancreatic tumors and the immunosuppressive tumor environment create challenges for treatment development, particularly for immune-based medicines. Pharmaceutical companies are studying combinations that can improve treatment response and expand options for patients with advanced disease. Molecular profiling also supports the identification of patients who may benefit from targeted treatment. Market development depends on clinical trial outcomes, regulatory approvals, reimbursement decisions, and access to specialist care. Improvements in early diagnosis and patient selection remain important for increasing treatment opportunities. Demand will also depend on disease burden, treatment duration, and the availability of new therapies for different patient groups.
Market Dynamics
The increasing need for systemic treatment supports growth in the pancreatic cancer treatment market, particularly among patients with locally advanced or metastatic disease. Chemotherapy remains a key treatment because many patients are diagnosed after the cancer has progressed beyond the pancreas. Medicines such as gemcitabine, nab-paclitaxel, and FOLFIRINOX-based regimens are used according to disease stage, patient health, and treatment eligibility. For patients with resectable tumors, chemotherapy is also used before or after surgery to manage the risk of recurrence. However, treatment response varies across patients, and disease progression can reduce the benefits of existing regimens. This supports continued use of established medicines and research into combination treatments that improve disease control. In addition, improvements in diagnostic imaging and molecular testing help physicians assess tumor characteristics and select appropriate treatments. Demand for systemic treatment is therefore linked to the number of diagnosed patients, disease stage at diagnosis, treatment duration, and the availability of approved medicines. Continued clinical research and access to specialist oncology services will remain important factors supporting treatment demand.
Late diagnosis remains a major restraint in the pancreatic cancer treatment market because symptoms often become noticeable after the disease has progressed. Abdominal pain, weight loss, jaundice, and digestive changes can overlap with symptoms of other conditions, which can delay diagnosis. Many patients are identified when the tumor has spread locally or to distant organs, reducing eligibility for surgical removal. Surgery remains the main treatment with curative intent for eligible patients, and limited surgical eligibility increases reliance on chemotherapy and supportive care. Although systemic treatment can control disease progression, long-term outcomes remain poor for many patients with advanced cancer. Treatment selection is also affected by the patient's general health, nutritional status, tumor characteristics, and response to prior medications. Patients with advanced disease may experience pain, weight loss, and declining physical condition, which can limit their ability to tolerate intensive treatment. These clinical and healthcare barriers restrict access to suitable therapies and can delay treatment initiation.
The development of targeted therapies for RAS-mutated pancreatic cancer presents an opportunity for the pancreatic cancer treatment market. RAS alterations, particularly KRAS mutations, are common in pancreatic ductal adenocarcinoma and have been an important focus of drug development. Research into these molecular targets is expanding treatment development beyond established chemotherapy regimens. Molecular testing helps identify patients with specific alterations and supports the selection of therapies targeting cancer-related mechanisms. This is particularly relevant for patients with advanced disease whose tumors progress despite initial treatment. Researchers are also evaluating combination regimens that pair targeted medicines with chemotherapy or other agents to improve treatment response and address resistance. Progress in this area can expand treatment options for patients with defined molecular profiles. However, the benefits of targeted treatment depend on the specific mutation, clinical evidence, patient eligibility, and regulatory approval. Access to molecular testing and reimbursement also affects the use of these medicines. Continued clinical development of RAS-targeted treatments offers pharmaceutical companies opportunities to address unmet treatment needs and expand options for patients with advanced pancreatic cancer.
Market Concentration & Characteristics
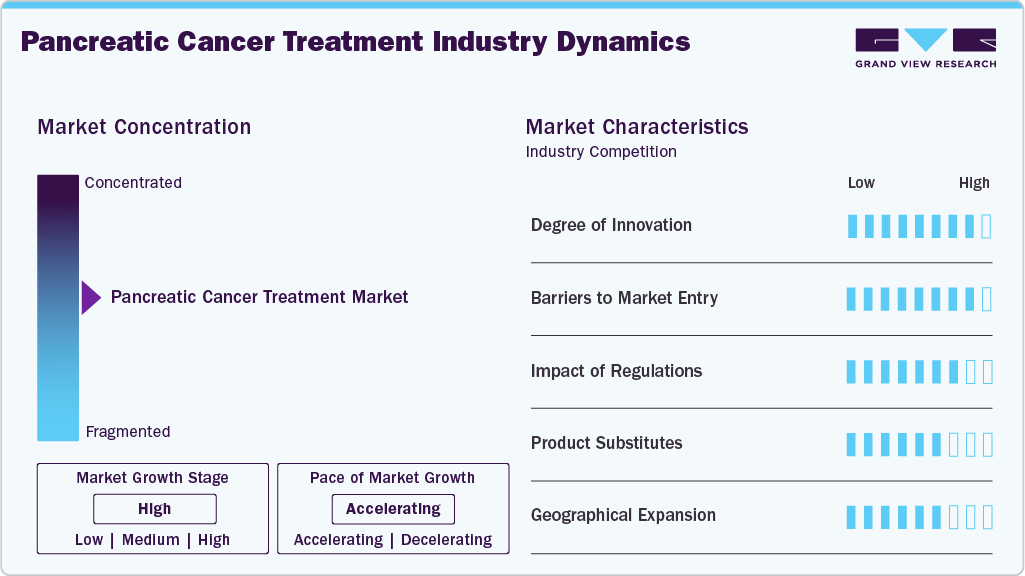
Innovation in the pancreatic cancer treatment market is high, driven by research into targeted therapies, molecular testing, and combination treatments. Chemotherapy remains a key treatment, but its benefits are limited for many patients with advanced disease. This has encouraged pharmaceutical and biotechnology companies to investigate treatments targeting cancer-related mechanisms, including KRAS mutations. However, treatment development remains challenging because pancreatic tumors can develop resistance and have an immunosuppressive environment. Continued innovation is important for expanding treatment options, improving disease control, and addressing unmet clinical needs across different stages of pancreatic cancer.
Barriers to entry in the industry are high, due to substantial research investment, clinical trial requirements, and regulatory approval procedures. Pharmaceutical companies must demonstrate treatment safety and efficacy before receiving authorization from regulatory agencies. Pancreatic cancer presents additional development challenges because many patients are diagnosed with advanced disease, and treatment response varies across patient groups. Developers of targeted therapies must establish relevant molecular targets and identify patients likely to benefit. Clinical trial recruitment can also be difficult because of disease progression and patients' health conditions. Companies require manufacturing capabilities, regulatory expertise, and access to specialist oncology centers. Established pharmaceutical companies benefit from existing research infrastructure and commercial networks. These requirements can limit entry for smaller developers and increase the time needed to bring new treatments to patients.
 To learn more about this report, Download Free Sample Report
The impact of regulations on the pancreatic cancer treatment industry is high because medicines must meet strict requirements for safety, efficacy, manufacturing quality, and clinical evidence. Regulatory agencies, including the U.S. Food and Drug Administration and the European Medicines Agency, review clinical trial data before granting marketing authorization. Requirements differ by product type, indication, and jurisdiction. Developers must also comply with pharmacovigilance obligations and report safety concerns after approval. For targeted therapies, regulatory review considers the supporting clinical evidence and the patient population for which treatment is indicated. Diagnostic tests used to identify eligible patients can also affect treatment access. Reimbursement assessments and national healthcare policies influence medicine availability. These requirements increase development costs and affect the time needed to introduce new treatments. Regulatory decisions therefore influence product availability, patient access, and competition among pharmaceutical companies.
The availability of product substitutes is moderate, because treatment alternatives vary by disease stage, tumor characteristics, and patient eligibility, limiting the options available for specific patient groups. Radiation therapy has a role in selected cases, particularly for local disease control, while targeted medicines provide options for patients with specific molecular alterations. Immunotherapy is also used for selected patients based on tumor biomarkers. Supportive care helps manage symptoms and treatment-related complications but does not replace anticancer treatment. These treatment options serve different clinical purposes, and their use depends on disease progression and the patient's health. The availability of alternative regimens within chemotherapy and other drug classes provides some flexibility in treatment selection. However, limited options for patients with advanced disease or specific tumor characteristics restrict substitution between therapies.
Geographical expansion in the market is moderate, because access to approved medicines depends on healthcare infrastructure, reimbursement policies, and diagnostic capacity. Pharmaceutical companies can increase access by obtaining regulatory approval in additional countries and establishing distribution agreements with local healthcare providers. Molecular testing is particularly relevant for targeted therapies because patients must be identified according to specific tumor alterations. Countries with limited access to pathology services and specialist cancer centers may face challenges in adopting these treatments. Differences in national treatment guidelines and public or private insurance coverage also affect medicine use. Expansion depends on regulatory submissions, pricing decisions, local partnerships, and the availability of trained healthcare professionals. Improvements in diagnostic services and reimbursement coverage can support broader access to pancreatic cancer treatments across regional markets.
Analyst Perspective
The pancreatic cancer treatment market is shaped by chemotherapy use, advances in targeted therapies, and research into new treatment combinations. Late diagnosis and limited treatment response continue to affect patient outcomes. Development of RAS-targeted medicines and new drug combinations supports treatment innovation. Future market growth will be shaped by the introduction of new therapies, changes in treatment practices, and patient access to approved medicines. Companies addressing unmet treatment needs will support further market development.
Type Insights
The exocrine segment dominated the market with a share of 88.3% in 2025. Its dominance is supported by the high prevalence of pancreatic ductal adenocarcinoma, which accounts for most pancreatic cancer cases. The segment has gained prominence due to the use of chemotherapy in locally advanced and metastatic disease, including gemcitabine-based regimens. Late diagnosis increases the need for systemic treatment, while disease progression supports continued demand for additional treatment lines. Research into targeted therapies for KRAS mutations is also expanding treatment options for selected patients. In addition, improvements in molecular testing and oncology services support treatment selection. These factors maintain the exocrine segment's leading position in the market.
The endocrine segment is projected to register the fastest CAGR of 12.8% during the forecast period, supported by advances in research and rising demand for treatments for pancreatic neuroendocrine tumors. Growth is driven by wider use of somatostatin analogs to manage hormone-related symptoms and control tumor growth. Targeted medicines, including everolimus and sunitinib, provide treatment options for patients with advanced disease. Peptide receptor radionuclide therapy also supports segment growth among eligible patients with somatostatin receptor-positive tumors. Improvements in diagnostic imaging and biomarker testing help identify pancreatic neuroendocrine tumors and guide treatment selection. In addition, clinical research into radioligand therapies and new drug combinations is expanding treatment options. Greater awareness of these tumors among healthcare professionals and improved access to specialist oncology services also support growth in the endocrine segment over the forecast period.
Treatment Insights
The chemotherapy segment dominated with a market share of 43.1% in 2025, supported by its central role in pancreatic cancer treatment. Its use across locally advanced and metastatic disease supports demand, while administration before or after surgery provides additional treatment options for eligible patients. Combination regimens address different disease stages and patient requirements. Established clinical guidelines and physician familiarity also support chemotherapy use across oncology centers. Although treatment resistance and adverse effects remain challenges, chemotherapy continues to form the basis of care for many patients. Its established clinical role and use across disease stages support its leading revenue position in the market.
The radiation therapy segment is growing significantly with a CAGR of 13.2% during the forecast period, supported by research into improved local disease control and treatment combinations. Radiation therapy is used in selected patients with locally advanced pancreatic cancer to target tumors and manage local progression. Advances in treatment planning and image-guided delivery support more precise targeting while limiting exposure to surrounding organs. Its use alongside chemotherapy is also being studied to improve disease control in patients who are not eligible for surgery. In addition, research into stereotactic body radiation therapy (SBRT) is expanding treatment options for selected patients with localized disease. Greater use of multidisciplinary treatment planning supports the selection of radiation therapy for suitable patients. Adoption is also supported by improvements in radiotherapy equipment and access to specialist cancer centers.
Distribution Channel Insights
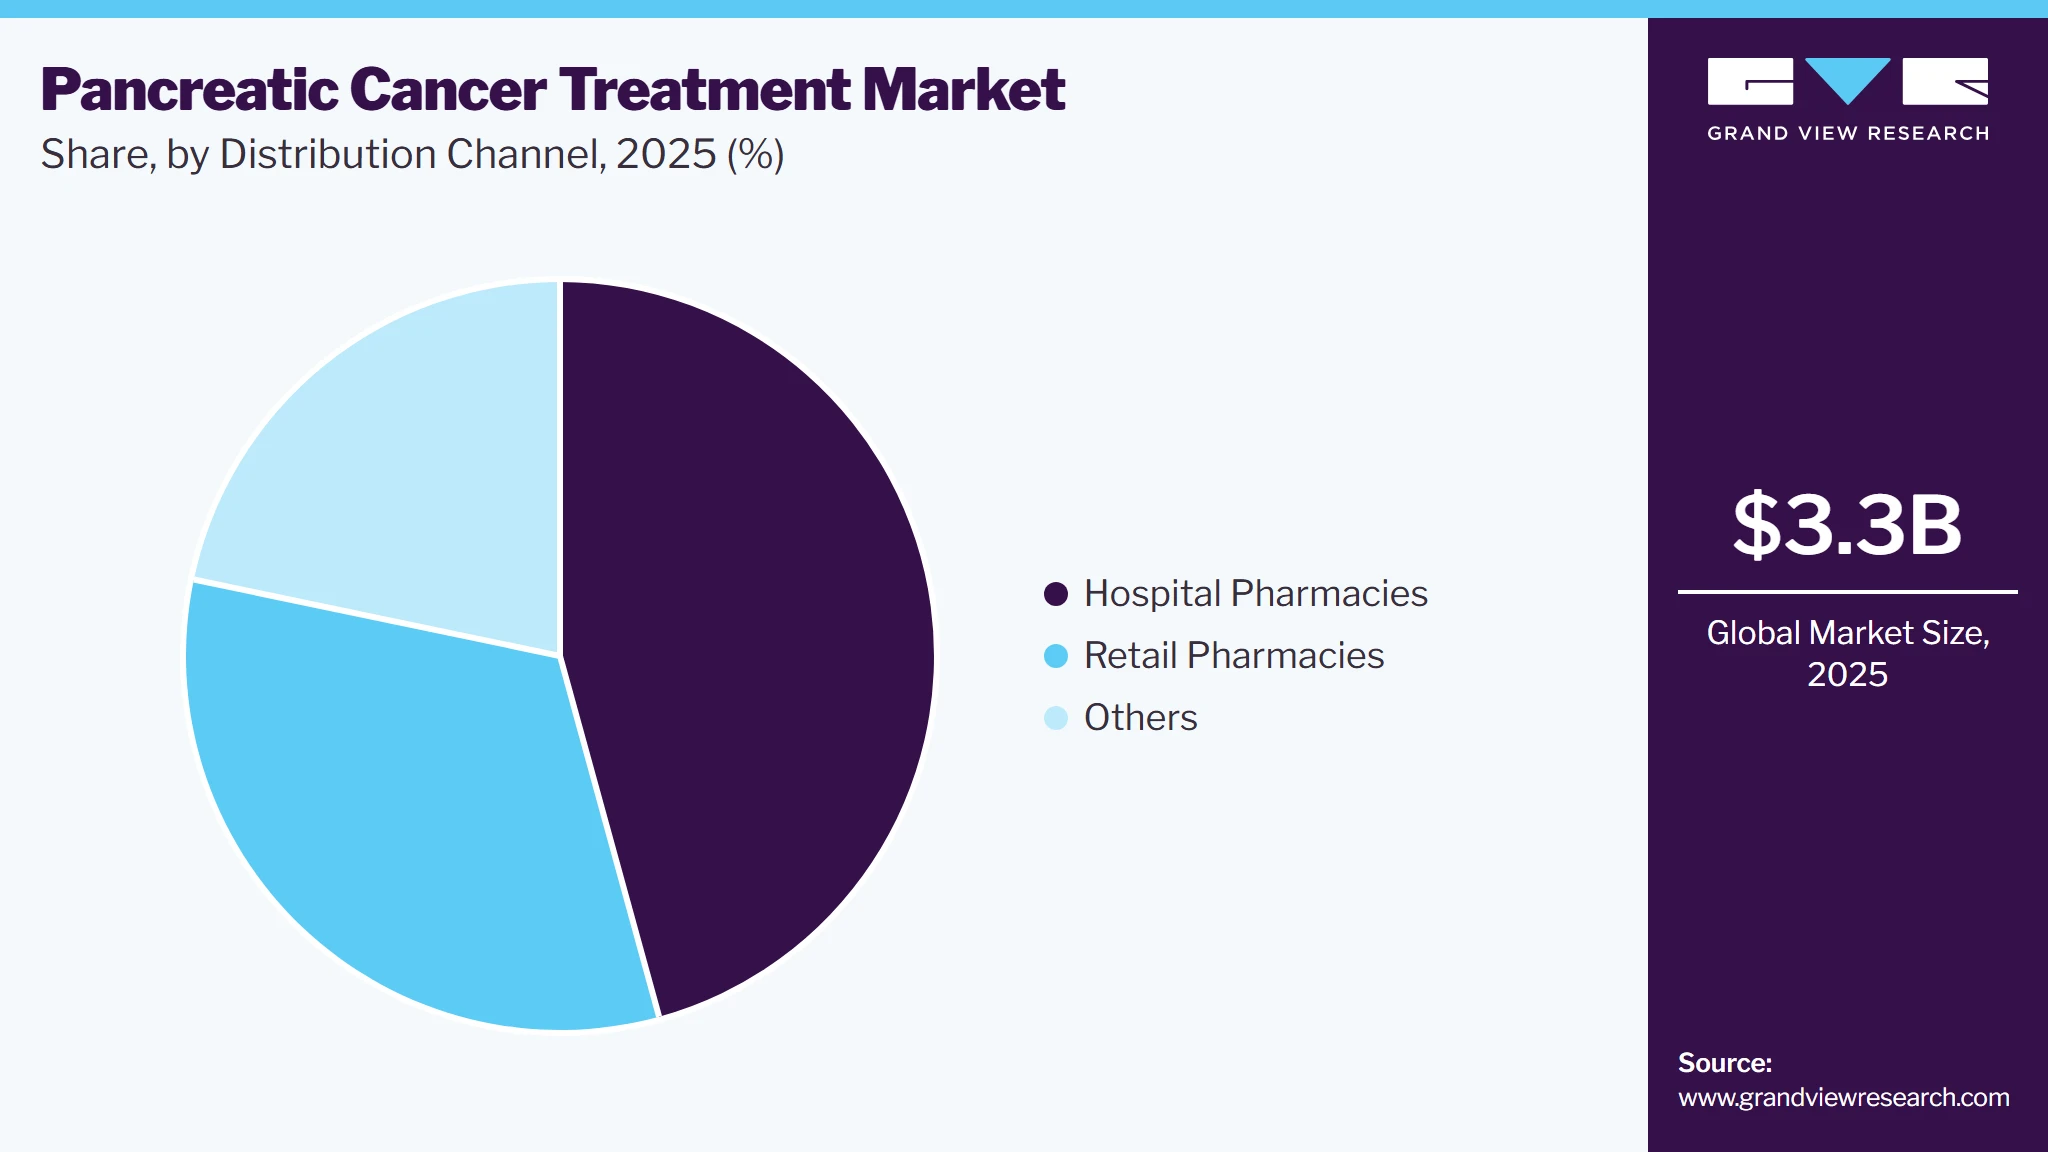
The hospital pharmacies segment dominated with a market share of 45.7% in 2025, supported by the need for supervised cancer treatment and medicine dispensing within healthcare facilities. Hospital pharmacies supply chemotherapy medicines used in inpatient and outpatient oncology services. Their role in handling medicines with specific storage and preparation requirements supports their importance in cancer care. Access to oncologists and clinical pharmacists also helps coordinate prescriptions, dose adjustments, and treatment-related supportive medicines. Hospitals manage complex treatment regimens that require monitoring for adverse effects and changes in patient health. In addition, hospital-based infusion services support the administration of intravenous chemotherapy. Integrated oncology departments and established medicine procurement systems further support this channel. These factors maintain hospital pharmacies as the leading distribution channel for pancreatic cancer treatments, particularly for patients receiving supervised systemic therapy.
 To learn more about this report, Download Free Sample Report
The retail pharmacies segment is growing significantly with a CAGR of 12.1% during the forecast period, supported by the growing need for convenient access to oral cancer medicines and supportive care products. Selected patients receive oral targeted therapies that can be dispensed through eligible retail or specialty pharmacy channels. Wider access to community pharmacies also helps patients obtain medicines for pain, nausea, and other treatment-related symptoms. Expansion of pharmacy networks and prescription fulfillment services can improve medicine access outside hospital visits. In addition, outpatient care and home-based symptom management support demand for retail pharmacy services. Specialty pharmacy services can assist with prescription coordination, patient counseling, and medicine supply for eligible treatments. However, dispensing depends on the medicine, prescription requirements, and payer policies. These factors support the role of retail pharmacies in the distribution of selected pancreatic cancer treatments.
Regional Insights
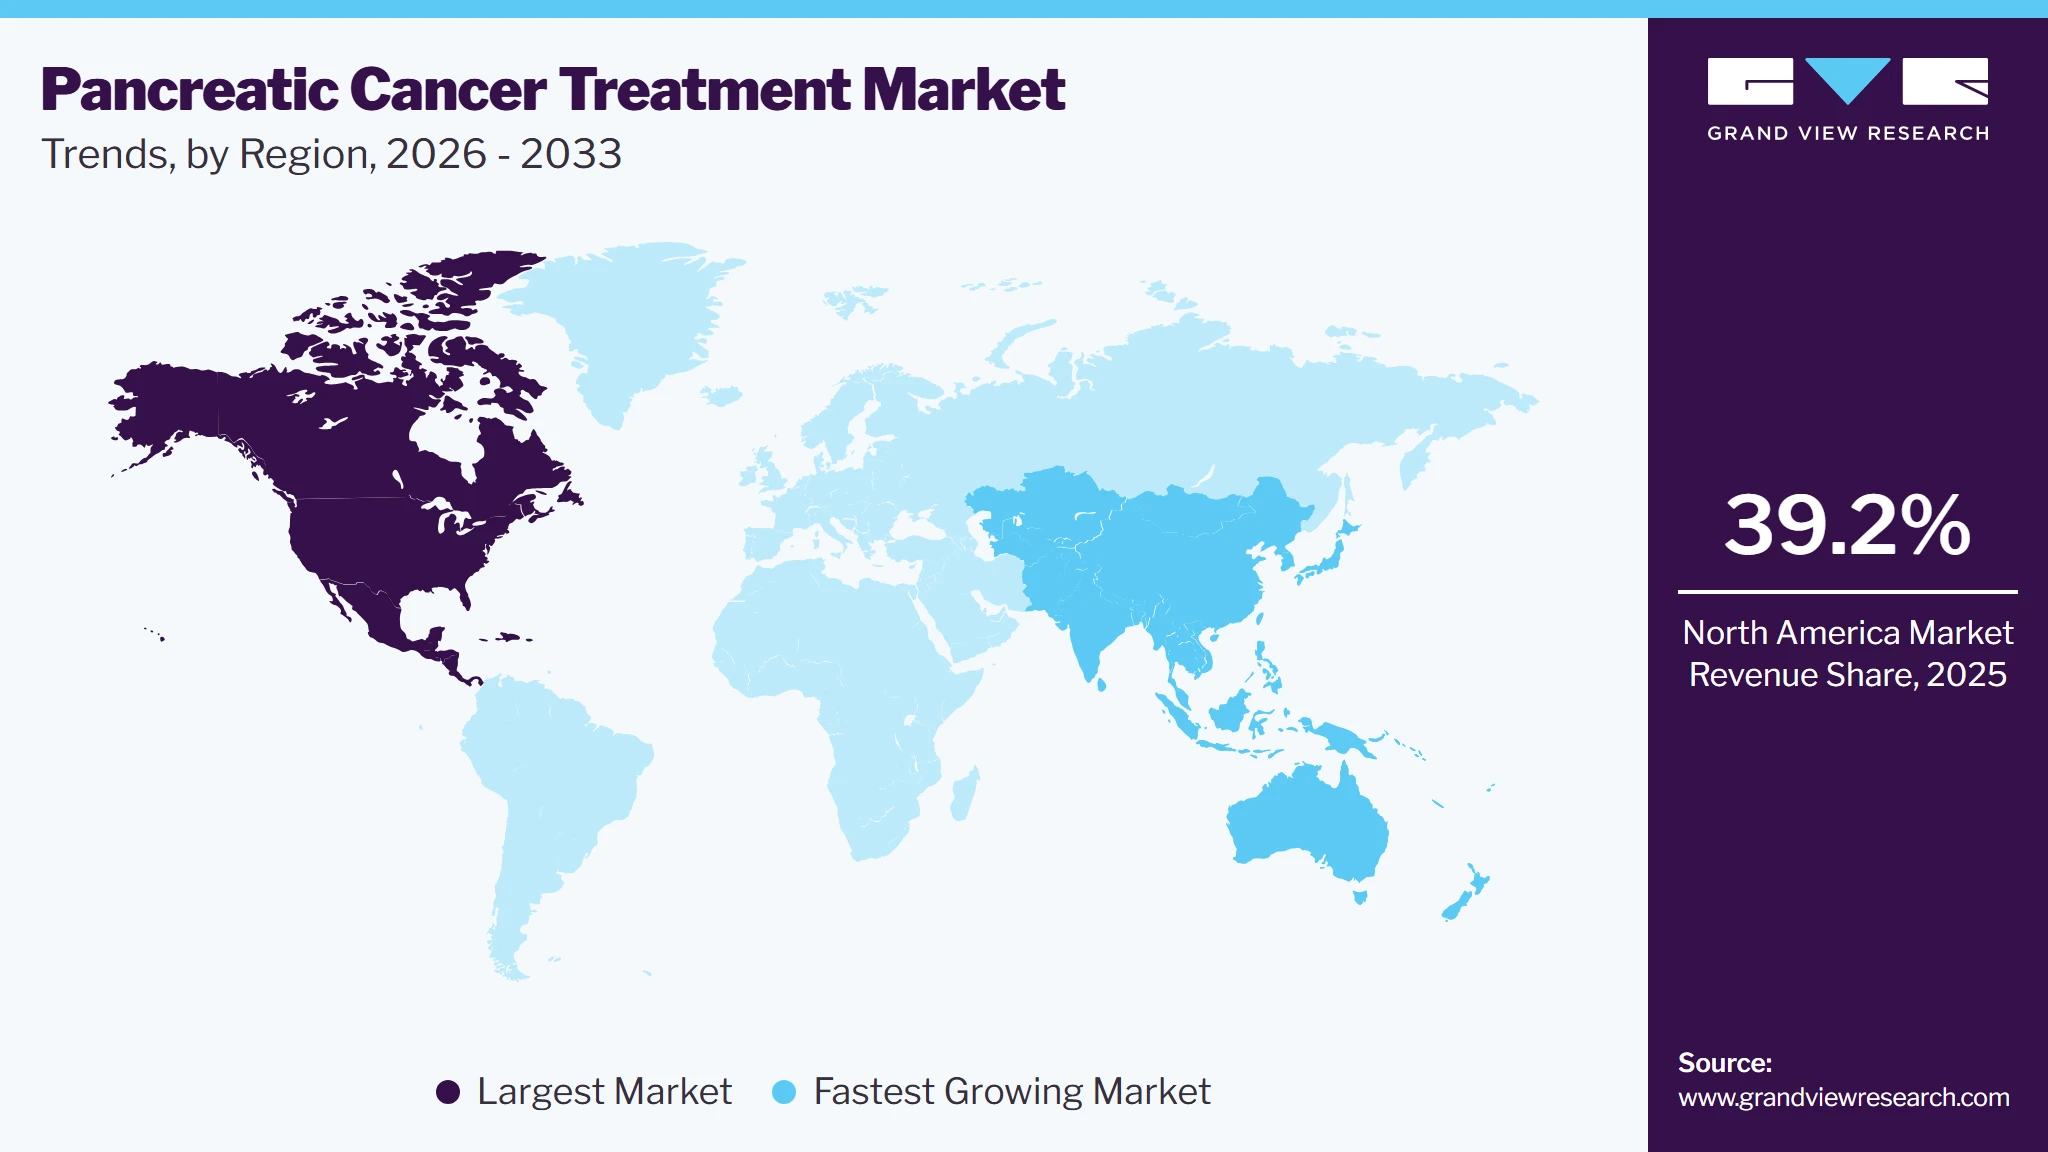
North America dominated the pancreatic cancer treatment market with a share of 39.2% in 2025, due to established oncology infrastructure and access to approved cancer medicines. The region benefits from the presence of pharmaceutical companies engaged in pancreatic cancer drug development. High use of chemotherapy and access to molecular testing support treatment selection. Access to specialist cancer centers and advanced diagnostic services supports treatment across different disease stages. Established distribution networks further support the availability of cancer medicines.
 To learn more about this report, Download Free Sample Report
U.S. Pancreatic Cancer Treatment Market Trends
The pancreatic cancer treatment market in the U.S. leads the North American industry through its established oncology network and access to a wide range of cancer therapies. The presence of pharmaceutical and biotechnology companies supports research into chemotherapy combinations and targeted medicines. Broad access to molecular profiling helps identify patients eligible for specific treatments. Clinical trials also support the development of new therapies for advanced pancreatic cancer. Specialist cancer centers provide surgical, medical oncology, and radiation therapy services. These factors support demand for established and emerging treatment options.
Europe Pancreatic Cancer Treatment Market Trends
The pancreatic cancer treatment market in Europe holds a significant position due to the region’s established cancer care services and access to approved medicines. Demand is supported by the use of chemotherapy across localized, locally advanced, and metastatic disease. Specialist oncology centers provide multidisciplinary care and support treatment selection. Clinical research across the region contributes to the development of targeted medicines and combination regimens. Access to diagnostic imaging and pathology services supports disease identification and monitoring. Differences in reimbursement and medicine access across countries influence regional treatment patterns.
The UK pancreatic cancer treatment market is supported by specialist cancer centers, established oncology services, and the use of evidence-based treatment protocols. Chemotherapy remains important for patients with advanced disease and for eligible patients receiving treatment around surgery. Improvements in diagnostic imaging and pathology support disease assessment and treatment planning. Access to multidisciplinary teams helps coordinate surgery, medical oncology, and supportive care. Medicine availability and treatment access depend on clinical eligibility and reimbursement decisions.
The pancreatic cancer treatment market in Germany benefits from established hospital infrastructure, specialist oncology services, and access to systemic cancer medicines. Chemotherapy is widely used for patients with locally advanced and metastatic disease, while surgery remains an option for eligible patients with localized tumors. Hospital-based oncology departments also support treatment monitoring and management of adverse effects. Research activity contributes to clinical studies of new medicines and combination regimens.
The France pancreatic cancer treatment market is supported by specialist oncology services, hospital-based treatment, and access to established chemotherapy regimens. Multidisciplinary care helps determine treatment plans based on tumor location, disease stage, and patient health. Access to medicines and treatment services is shaped by clinical guidelines, reimbursement policies, and the availability of specialist care.
Asia-Pacific Pancreatic Cancer Treatment Market Trends
The pancreatic cancer treatment market in the Asia Pacific is projected to register the fastest CAGR of 13.2% over the forecast period, supported by a large patient population and expanding access to cancer care. Improvements in diagnostic imaging and pathology services are helping identify more patients who require treatment. Growth in specialist oncology facilities supports the use of chemotherapy and other treatment options. Rising access to molecular testing is also supporting the use of targeted medicines in eligible patient groups. Clinical research and pharmaceutical manufacturing activity contribute to treatment development across the region. Differences in healthcare access, medicine affordability, and reimbursement continue to influence adoption across individual countries.
The Japan pancreatic cancer treatment market is supported by established oncology services, access to diagnostic imaging, and the use of chemotherapy in clinical practice. Specialist hospitals provide treatment planning for patients with localized and advanced disease. Molecular testing helps identify selected patients who may benefit from targeted medicines. An established pharmaceutical sector contributes to research into cancer therapies and treatment combinations. Clinical studies support the evaluation of new treatment options for patients with pancreatic cancer. Demand is also influenced by the need for symptom management and supportive care during prolonged treatment.
The pancreatic cancer treatment market in China is supported by a large patient population, expanding oncology infrastructure, and wider access to cancer diagnostic services. Improvements in hospital capacity and diagnostic imaging support disease detection and treatment planning. Chemotherapy remains a key option for patients with advanced pancreatic cancer. Domestic pharmaceutical companies are also engaged in oncology drug development, including research into targeted treatments.
Latin America Pancreatic Cancer Treatment Market Trends
The pancreatic cancer treatment market in Latin America is supported by expanding oncology services and demand for medicines used to manage advanced disease. Hospital-based chemotherapy has gained traction among patients who are not eligible for surgery. The availability of specialist oncology facilities influences access to surgery, radiation therapy, and systemic treatment. Pharmaceutical distribution networks help supply established cancer medicines across the region.
The Brazil pancreatic cancer treatment market is supported by its network of oncology hospitals and demand for chemotherapy and supportive care. Major urban centers provide specialist services for diagnosis, surgery, and treatment of advanced pancreatic cancer. Diagnostic imaging and pathology help determine disease stage and guide treatment selection. The use of systemic medicines supports care for patients with locally advanced and metastatic disease. Differences in healthcare access and affordability influence the use of newer cancer medicines across public and private care.
Middle East & Africa Pancreatic Cancer Treatment Market Trends
The pancreatic cancer treatment market in the Middle East and Africa is supported by the development of specialist oncology services and increasing access to cancer diagnostic facilities in selected countries. Hospital-based chemotherapy remains an important treatment option for patients with advanced disease. Access to surgical oncology and radiation therapy facilities influences the range of available treatment options. However, differences in specialist workforce availability, medicine affordability, and healthcare infrastructure affect treatment access across the region.
The Saudi Arabia pancreatic cancer treatment market is supported by the development of specialist cancer centers, access to diagnostic imaging, and demand for systemic cancer medicines. Hospital oncology departments provide chemotherapy and supportive care for patients with advanced disease. Improvements in pathology and molecular testing support treatment selection for eligible patients. The availability of approved medicines supports treatment across different disease stages. Differences in patient referral patterns, access to specialized diagnostics, and treatment availability influence the use of newer therapies.
Key Pancreatic Cancer Treatment Company Insights
The pancreatic cancer treatment market is witnessing competition across drug therapies and radiation treatment technologies, supported by research into targeted medicines and treatment options for advanced disease. AstraZeneca, Novartis AG, Pfizer Inc., and Ipsen Pharma participate in oncology through established drug portfolios, while Revolution Medicines, Inc., Exelixis, Inc., and Merus N.V. contribute through targeted therapy development and clinical research. Revolution Medicines is advancing RAS-targeted treatments for pancreatic cancer, while other pharmaceutical companies support treatment development through research programs and oncology portfolios. In parallel, Accuray Incorporated, Siemens Healthineers AG through Varian Medical Systems, and Elekta AB supply radiation therapy systems used in cancer care. Competition varies across treatment categories, approved indications, clinical research programs, and the availability of treatment technologies for patients with pancreatic cancer.
Key Pancreatic Cancer Treatment Companies
The following key companies have been profiled for this study on the pancreatic cancer treatment market:
-
AstraZeneca
-
Novartis AG
-
Pfizer Inc.
-
Ipsen Pharma
-
Revolution Medicines, Inc.
-
Exelixis, Inc.
-
Merus N.V.
-
Accuray Incorporated
-
Siemens Healthineers AG (Varian Medical Systems)
-
Elekta AB
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
- Mature Players: AstraZeneca
- Expand oncology portfolios through targeted medicines, chemotherapy combinations, and clinical research to address different pancreatic cancer treatment needs.
- Invest in clinical trials and research collaborations to develop new therapies, evaluate treatment combinations, and expand approved indications.
- Strengthen commercial operations and improve radiation therapy technologies through established distribution networks, hospital partnerships, and treatment planning systems.
- Established oncology portfolios and clinical research capabilities support participation in cancer treatment and drug development.
- Existing manufacturing infrastructure, distribution networks, and relationships with hospitals and oncology specialists support product access.
- Experience in regulatory submissions, clinical development, and cancer treatment technologies supports operations across multiple markets.
- High research and development costs and lengthy clinical trials increase investment requirements and development risks.
- Competition from established medicines, new targeted therapies, and alternative treatment technologies affects product adoption.
- Patent expiry, pricing pressure, reimbursement requirements, and hospital budget constraints can affect product sales and technology demand.
- Emerging Players: Merus N.V.
- Focus on targeted medicines designed to address specific molecular alterations and treatment needs in advanced pancreatic cancer.
- Conduct clinical trials to evaluate new therapies and combinations that aim to improve treatment response.
- Establish research collaborations and licensing agreements to support drug development, manufacturing, and commercial expansion.
- Focused research programs allow companies to concentrate resources on specific cancer-related targets.
- Specialized drug development capabilities support research into new treatment options for patients with advanced disease.
- Clinical progress can create opportunities for partnerships with established pharmaceutical companies and expansion into additional markets.
- Dependence on clinical trial results creates uncertainty regarding product safety, efficacy, and regulatory approval.
- Continued research and development requires substantial funding before products generate commercial returns.
- Limited commercial infrastructure and competition from established pharmaceutical companies can restrict market access and product adoption.
Recent Developments:
-
In September 2026, Elekta AB reported clinical study findings presented at ASTRO 2026 on MR-guided adaptive radiotherapy for localized pancreatic cancer in patients who were not eligible for surgery. The study evaluated treatment outcomes among 123 patients treated using the Elekta Unity system.
-
In June 2025, Revolution Medicines, Inc. received U.S. FDA Breakthrough Therapy Designation for daraxonrasib for previously treated metastatic pancreatic ductal adenocarcinoma in patients with KRAS G12 mutations.
-
In May 2025, Ipsen Pharma presented results from a post-hoc analysis of the Phase III NAPOLI 3 trial at the American Society of Clinical Oncology (ASCO) Annual Meeting. The analysis evaluated long-term survival outcomes among patients with metastatic pancreatic adenocarcinoma receiving a first-line regimen of liposomal irinotecan, oxaliplatin, fluorouracil, and leucovorin. Among 15 long-term survivors in the analysis, median overall survival was 19.5 months.
Pancreatic Cancer Treatment Market Report Scope
Report Attribute
Details
Market size in 2025
USD 3.3 billion
Estimated market size in 2026
USD 3.7 billion
Projected market size by 2033:
USD 8.3 billion
Growth rate
CAGR of 12.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, trends
Segments covered
Type, treatment, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; Australia; South Korea; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key company profiled
AstraZeneca; Novartis AG; Pfizer Inc.; Ipsen Pharma; Revolution Medicines, Inc.; Exelixis, Inc.; Merus N.V.; Accuray Incorporated; Siemens Healthineers AG (Varian Medical Systems); Elekta AB
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Pancreatic Cancer Treatment Market Report Segmentation
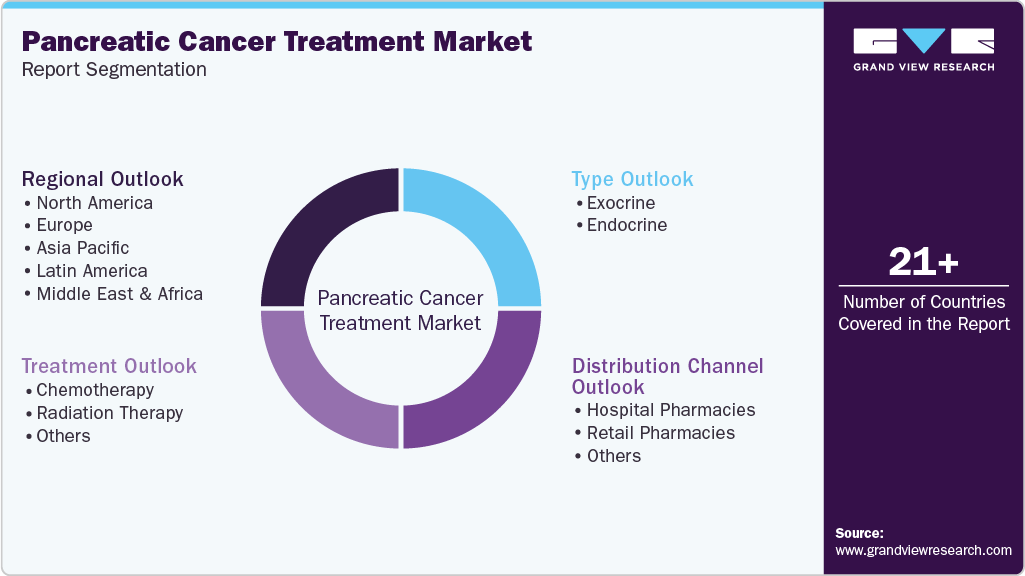
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global pancreatic cancer treatment market report based on type, treatment, distribution channel, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Billion, 2021 – 2033)
-
Exocrine
-
Endocrine
-
-
Treatment Outlook (Revenue, USD Billion, 2021 – 2033)
-
Chemotherapy
-
Radiation Therapy
-
Others
-
-
Distribution Channel Outlook (Revenue, USD Billion, 2021 – 2033)
-
Hospital Pharmacies
-
Retail Pharmacies
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
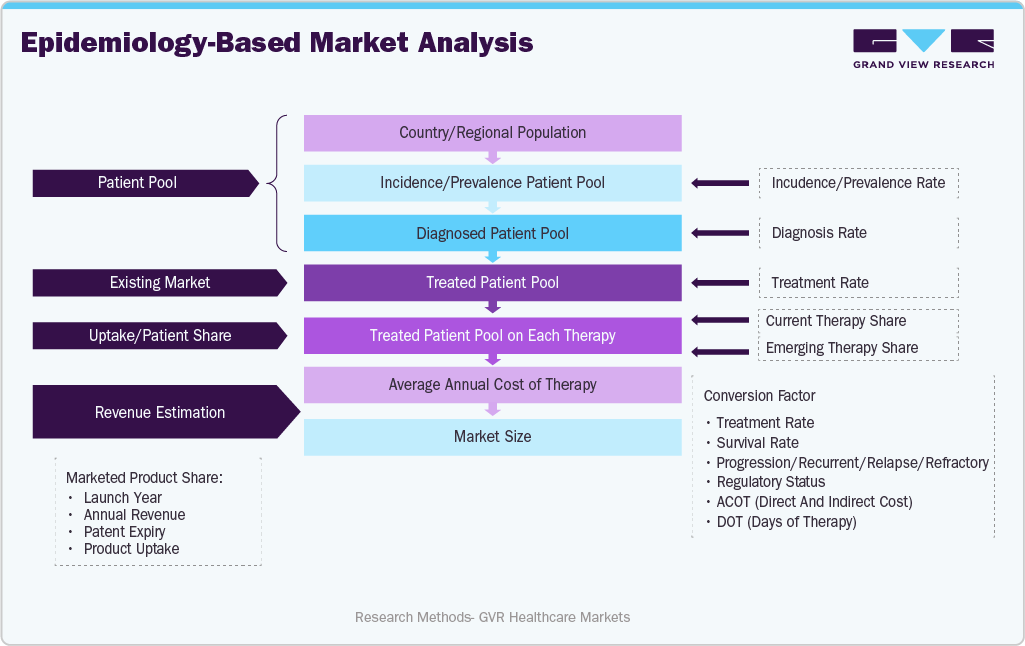
The pancreatic cancer treatment market is estimated using the epidemiology-based approach, which assesses the patient population eligible for treatment and the associated cost of therapy. The analysis begins with identifying country-level data on pancreatic cancer incidence, prevalence, disease stage, and treatment eligibility. Patient populations are segmented based on disease stage and treatment type, including chemotherapy, targeted therapy, and other relevant drug classes. The number of patients receiving each treatment is estimated using treatment patterns, therapy adoption rates, and available clinical data. Annual treatment costs are calculated using drug prices, dosage requirements, treatment duration, and the number of treatment cycles. For medicines used across multiple cancer indications, the share attributable to pancreatic cancer is estimated based on eligible patient numbers and treatment patterns. Country-level market values are calculated by multiplying the estimated treated patient population by the corresponding annual treatment cost and are aggregated to derive the global pancreatic cancer treatment market size.
Segment Definition
Type
Revenue capture definition
Exocrine
Includes treatments for cancers arising from the exocrine cells of the pancreas, which produce digestive enzymes. This segment primarily covers pancreatic ductal adenocarcinoma and other exocrine pancreatic malignancies, with revenue assigned according to the cancer type being treated.
Endocrine
Includes treatments for pancreatic neuroendocrine tumors arising from hormone-producing cells of the pancreas. This segment covers medicines and procedures used to manage these tumors, including chemotherapy, targeted therapy, somatostatin analogues, and peptide receptor radionuclide therapy, where indicated.
Treatment
Revenue capture definition
Chemotherapy
Includes cytotoxic medicines used to destroy or inhibit the growth of cancer cells in patients with pancreatic cancer. This segment covers single-agent and combination chemotherapy regimens administered before surgery, after surgery, or for locally advanced and metastatic disease.
Radiation Therapy
Includes procedures that use ionizing radiation to damage cancer cells and control tumor growth. This segment covers external beam radiation therapy, stereotactic body radiation therapy, and other radiation techniques used to treat pancreatic cancer.
Others
Includes pancreatic cancer treatments not classified under chemotherapy or radiation therapy, such as targeted therapy, immunotherapy, and other systemic medicines, along with radiopharmaceutical treatments where applicable. Each product is assigned to one treatment category based on its primary therapeutic modality
Distribution Channel
Revenue capture definition
Hospital Pharmacies
Includes pancreatic cancer medicines dispensed through hospital-operated pharmacy services for inpatient and outpatient treatment. Revenue is assigned to this segment when the hospital pharmacy supplies the medicine, including medicines used in hospital-based oncology departments.
Retail Pharmacies
Includes pancreatic cancer medicines dispensed through independent and chain community pharmacies outside hospital-operated pharmacy services. This segment covers eligible prescription medicines supplied directly to patients through physical retail pharmacy outlets.
Others
Includes pancreatic cancer medicines dispensed through specialty pharmacies, mail-order pharmacies, online pharmacies, and other distribution channels not classified under hospital or retail pharmacies.
Estimation Model
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Pancreatic Cancer Treatment Market Assessment
Conducted a detailed assessment of the pancreatic cancer treatment market, covering disease burden, diagnosis patterns, treatment practices, clinical developments, and patient care requirements. The study evaluated patient demographics, diagnosis rates, treatment eligibility, medicine utilization, pricing factors, and access to cancer care to assess market demand.
Helped the client understand key demand drivers, treatment gaps, and factors affecting market growth. The analysis supported strategic planning by identifying unmet treatment needs, assessing changes in clinical practice, and evaluating factors affecting patient access to cancer therapies.
Pancreatic Cancer Treatment Pipeline and Competitive Assessment
Delivered a structured assessment of the treatment development landscape, covering approved medicines, investigational therapies, clinical trial progress, research collaborations, and product development activities. The study examined clinical evidence, regulatory progress, treatment innovation, and the development of new options for patients with pancreatic cancer.
Supported the identification of treatment development opportunities, assessment of clinical research priorities, and evaluation of emerging therapies. The analysis also helped assess competitive positioning, research partnerships, and unmet treatment needs in pancreatic cancer care.
Pancreatic Cancer Market Sizing and Forecast Assessment
Conducted a market sizing and forecasting assessment using patient-based and revenue-based analysis. The study evaluated the diagnosed and treated patient population, treatment patterns, medicine utilization, pricing, and product sales to estimate market size and forecast demand.
Supported market entry assessment, resource allocation, and business planning by identifying factors affecting treatment demand and future market development. The study also provided a basis for evaluating treatment adoption, pricing patterns, and changes in demand over the forecast period.
Frequently Asked Questions About This Report
The global pancreatic cancer treatment market market size was valued at USD 2.9 billion in 2024 and is estimated at USD 3.7 billion for 2026.
The global pancreatic cancer treatment market market is expected to grow at a CAGR of 12.3% from 2025 to 2030, reaching USD 5.8 billion by 2030.
Based on treatment, the chemotherapy segment captured the largest revenue share at 43.83% in 2024. Drugs such as Abraxane (axel), Xeloda (capecitabine), cisplatin, Taxol (paclitaxel), Taxotere (docetaxel), and Onivyde (irinotecan liposome) are key contributors to the chemotherapy segment.
Key players operating in the market are Accuray Incorporated, AstraZeneca, Novartis AG, Pfizer Inc., Genentech, Inc. (F. Hoffmann-La Roche Ltd), Bristol-Myers Squibb Company, Ipsen Pharma, Eli Lilly and Company, Siemens Healthineers AG (Varian Medical Systems, Inc., part of the company), and Elekta AB.
The growth can be attributed to factors such as unhealthy lifestyles, alcohol consumption, and obesity have been the primary cause of pancreatic cancer in patients. The growing aging population and associated rise in lifestyle-related diseases are contributing to an increasing demand for specialized treatments.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


