
- Home
- »
- Healthcare IT
- »
-
Patient Safety And Risk Management Software Market Report, 2033GVR Report cover

Patient Safety And Risk Management Software Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type, By Deployment Type (Cloud, On-premise), By End-use (Hospitals, Ambulatory Care Centers, Long-term Care Centers), By Region, And Segment Forecasts
Market Size, 2025
$2.5BMarket Estimate, 2026
$2.7BMarket Forecast, 2033
$6.4BCAGR, 2026–2033
13.0%Patient Safety And Risk Management Software Market Summary
The global patient safety and risk management software market size was valued at USD 2.5 billion in 2025 and is projected to grow from USD 2.7 billion in 2026 to USD 6.4 billion by 2033, at a CAGR of 13.0% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 49.2% in 2025. The growing number of medical errors and the need for patient safety and care are the factors driving the market growth. Moreover, government initiatives to promote the healthcare software sector and the increased adoption of digitization are further accelerating market growth.
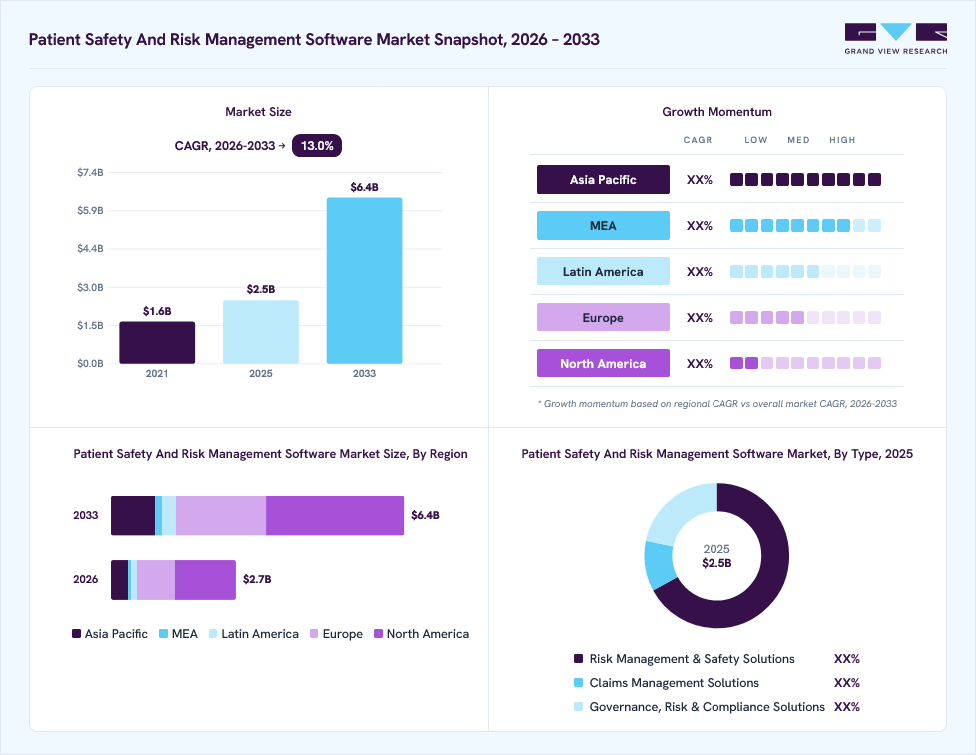 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Risk management & safety solutions segment led the market with the largest revenue share of 67.0% in 2025.
- By deployment type: Cloud segment led the market with the largest revenue share of 58.5% in 2025.
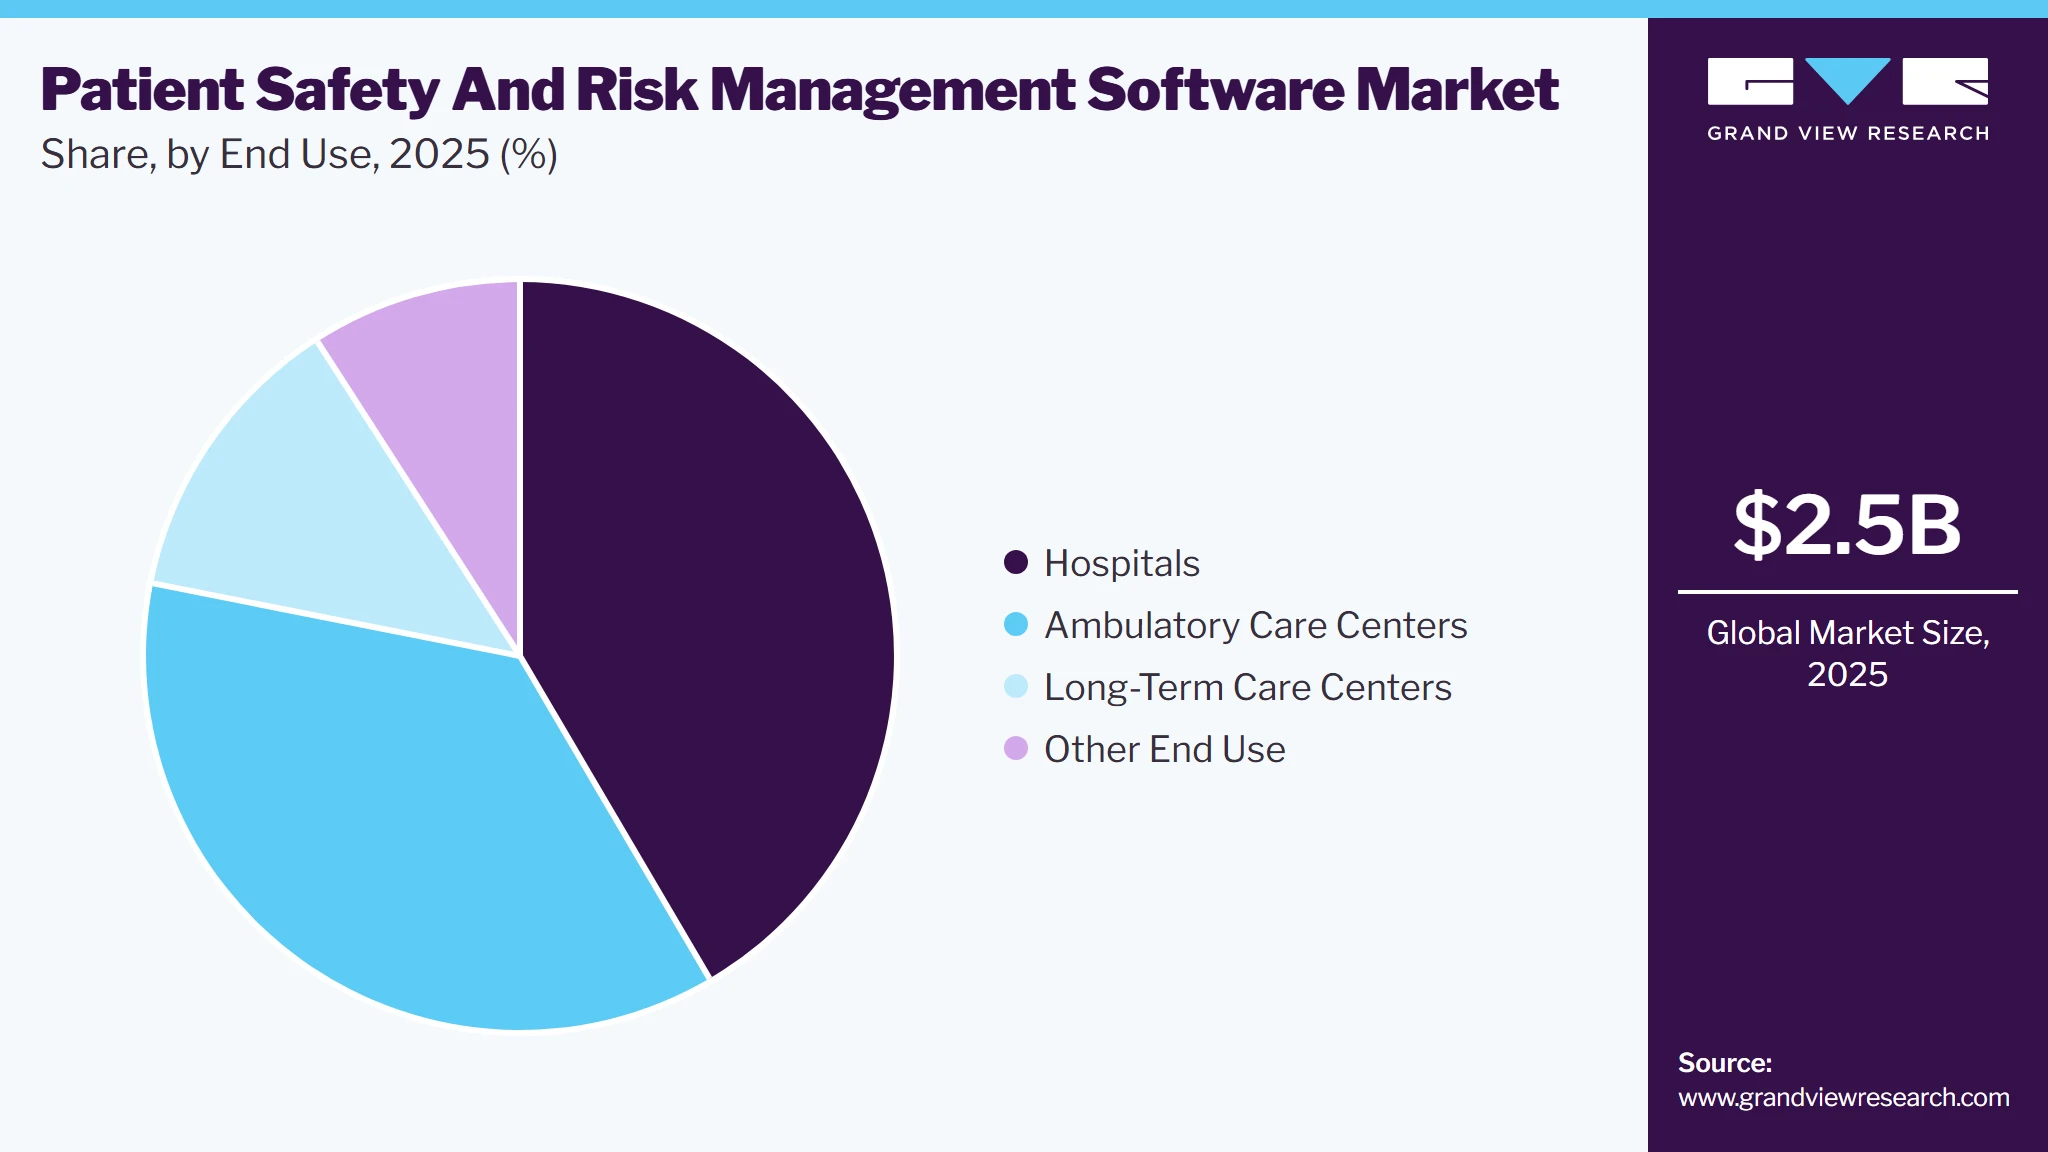
- By end use: Hospital segment led the market with the largest revenue share of 41.5%.
Regional Highlights
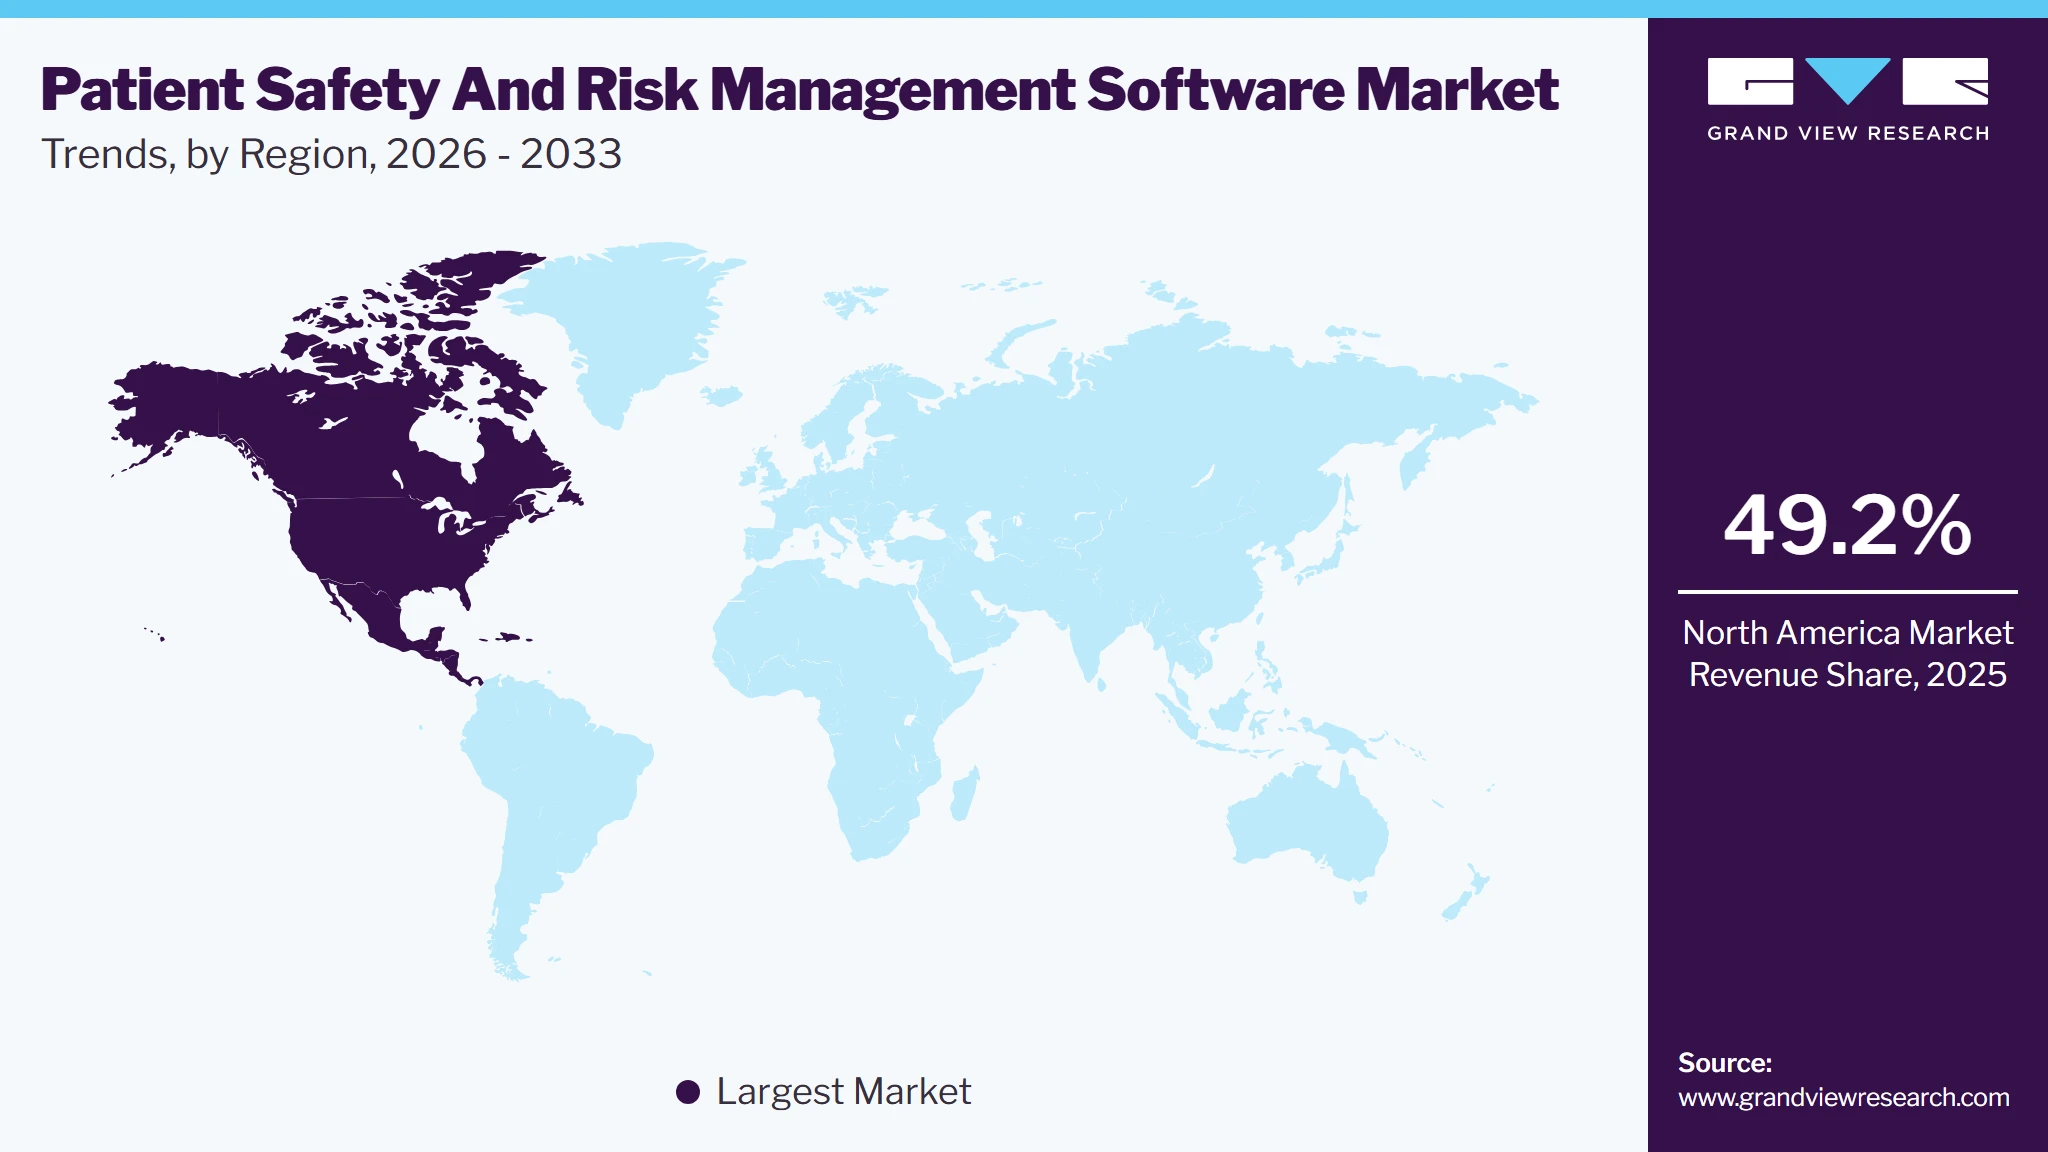
- Largest regional market: North America (49.2% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 2.5 Billion
- Estimated market size in 2026: USD 2.7 Billion
- Projected market size by 2033: USD 6.4 Billion
- CAGR (2026-2033): 13.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Moreover, government initiatives to promote the healthcare software sector and the increased adoption of digitization are further accelerating market growth. The WHO organized a World Patient Safety Day 2023 campaign with the slogan “Elevate the voice of patients!” to assure that all stakeholders are involved in policy formulation, designing safety strategies, and being active partners. Such activities contribute to the development of a platform that is patient-centered.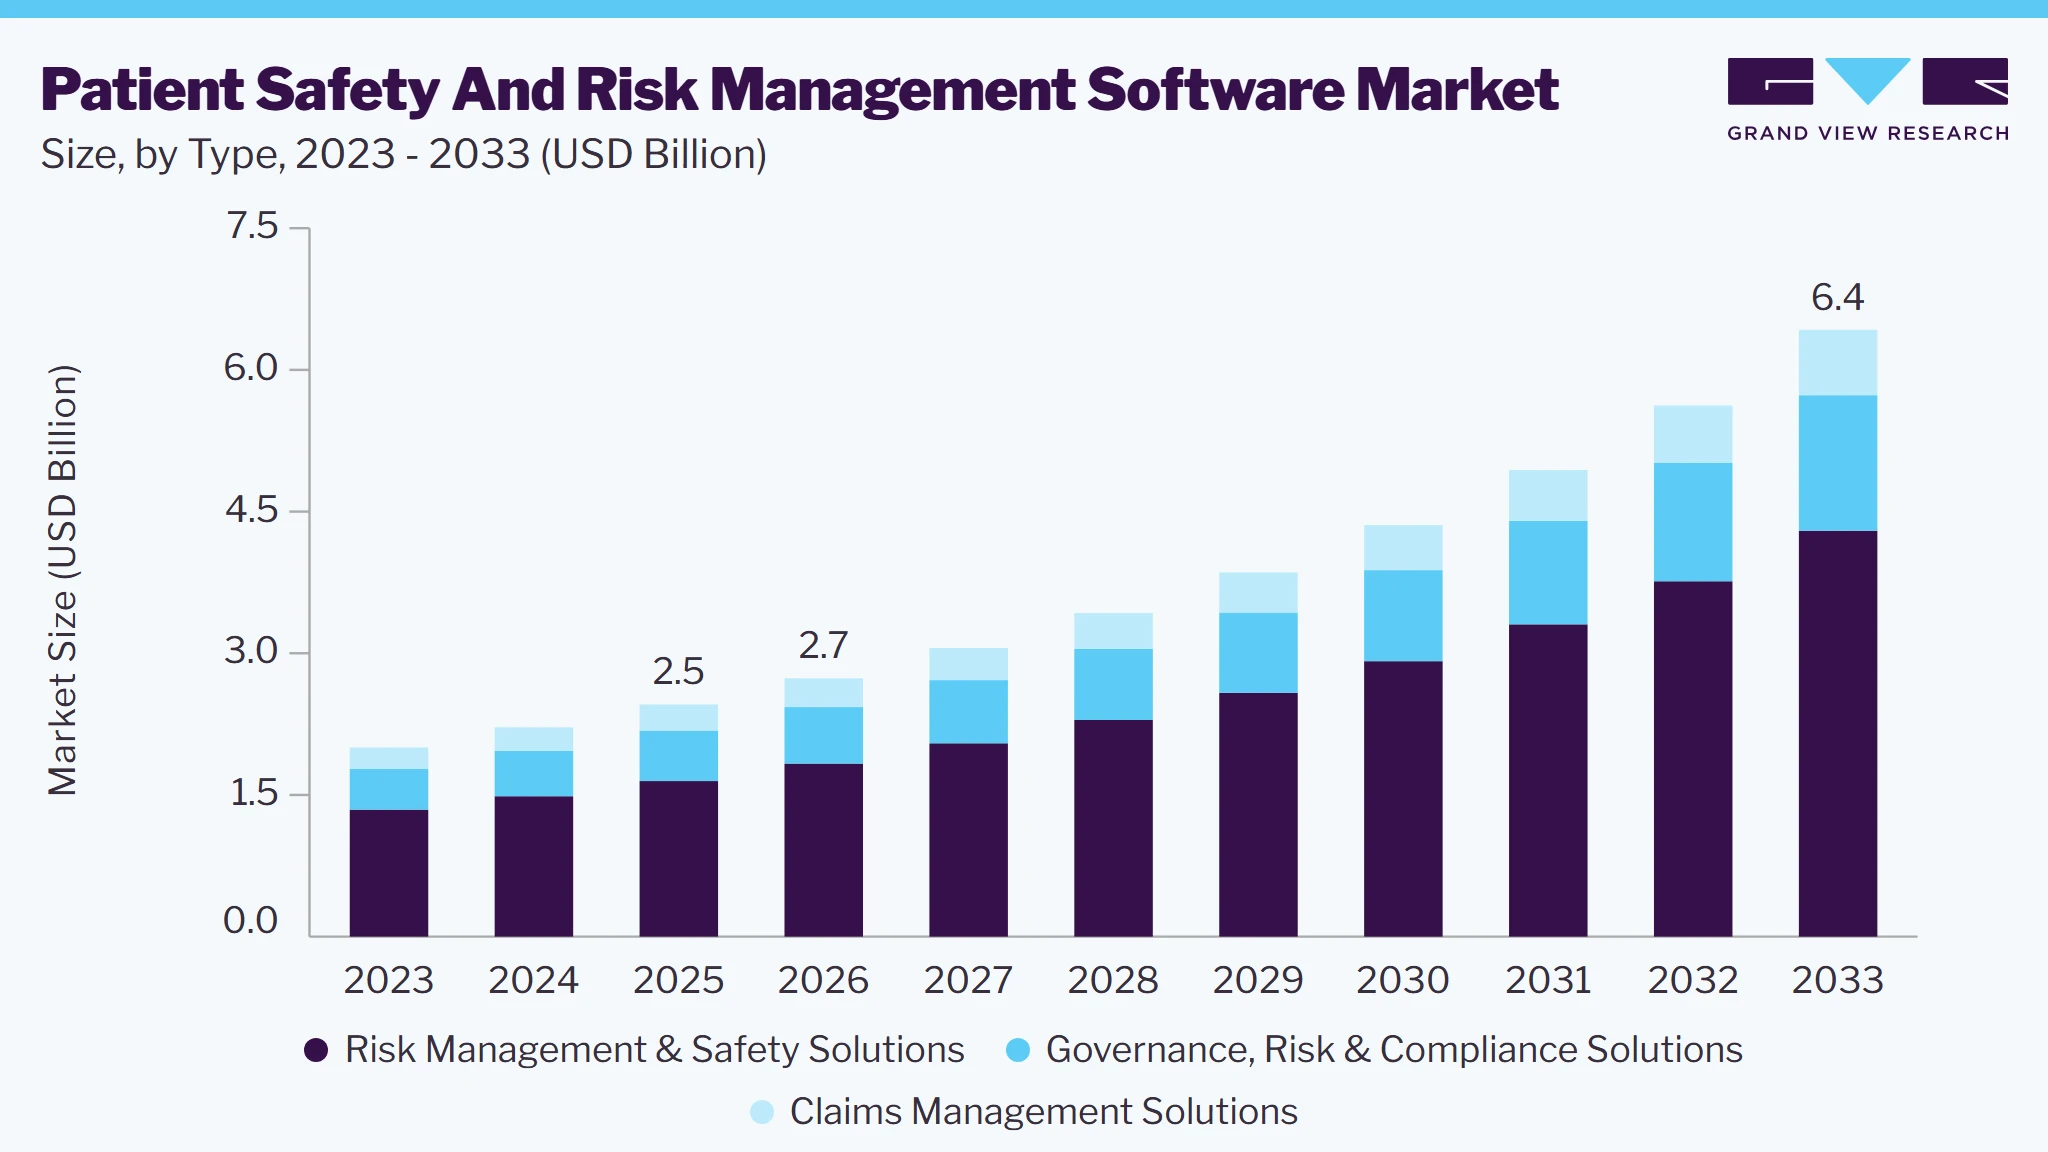 To learn more about this report, Download Free Sample Report
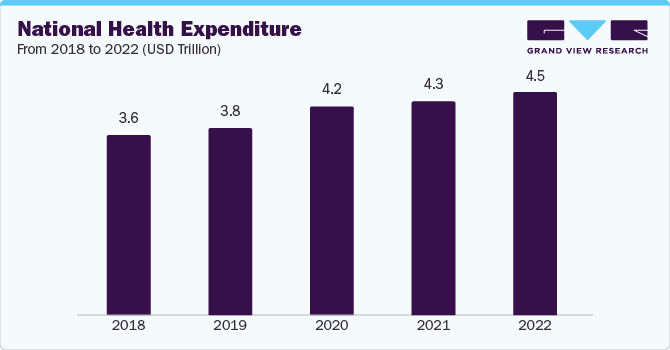
Rising healthcare expenditure in both developed and developing regions is driving the adoption of patient safety and risk management software in the healthcare industry. The sector is shifting from a fee-for-service framework to a value-based approach, where reimbursements are aligned with treatment outcomes. This shift is driving the demand for patient safety and risk management solutions. For instance, data published by the U.S. Centers for Medicare & Medicaid Services in December 2023 showcased that National Health Expenditure (NHE) was USD 13,493 per capita in 2022. The below-mentioned bar chart showcases the growth in NHE from 2018 to 2022.
Furthermore, increasing government initiatives for better patient safety and outcomes drive the adoption of patient safety and risk management software in the healthcare industry. For instance, the WHO has formulated a Global Patient Safety Action Plan 2021-2030. The action plan aims to offer a strategic framework for stakeholders to eliminate avoidable harm in healthcare and enhance patient safety across various practice areas. This is achieved through policy actions focused on the safety & quality of health services and implementing recommendations at the point of care. Furthermore, the plan guides countries to formulate national patient safety action plans and aligns with existing strategies to improve patient safety in clinical & health-related programs.
 To learn more about this report, Download Free Sample Report
Patient safety has become a top priority for healthcare organizations and regulatory bodies worldwide. The importance of preventing adverse events, medical errors, and enhancing patient outcomes is growing. This focus on patient safety is fueling the demand for software solutions capable of rapidly identifying and addressing hazards. According to The Joint Commission (TJC), a nonprofit organization accrediting numerous healthcare organizations and programs in the U.S., there has been a concerning rise in adverse patient safety events. Its 2023 annual report revealed a significant increase in sentinel events, which are significant breaches in patient safety that can lead to serious harm or fatalities.
From 2020 to 2021, these events surged by 78.1%, and from 2021 to 2022, they rose by 19.3%. Furthermore, as per the findings published in the Journal of Patient Safety, approximately 210,000 lives are lost annually due to preventable medical errors. However, when considering errors of omission and diagnostic inaccuracies, this figure escalates to 440,000 lives lost each year. Moreover, medical errors cost USD 1 trillion each year. This has raised the adoption of various software to reduce medical errors and adverse events in healthcare settings, thereby driving the market.
Market Dynamics
Healthcare organizations are increasingly investing in digital solutions to identify, monitor, and mitigate clinical risks, reduce medical errors, and prevent adverse events that can negatively impact patient outcomes. Rising patient volumes, increasing complexity of care delivery, and increasing awareness of healthcare-associated risks have strengthened the need for comprehensive safety management systems. These platforms help streamline incident reporting, root-cause analysis, safety monitoring, and corrective actions. In addition, the shift toward value-based care encouraging providers to adopt advanced risk management software to improve patient outcomes and operational efficiency. For instance, in June 2026, Sentact unified Hardenbergh Group, Preverity, and National Credentialing Solutions under a single brand expanding its capabilities in patient safety, clinical quality, and risk management. Such developments underscore the growing demand for integrated healthcare safety solutions.
“By bringing these organizations together and expanding our capabilities, we are empowering healthcare organizations nationwide with the tools, insights, and expertise needed to deliver exceptional, safe care reliably and consistently.”
- Daniel Hart, CEO of Sentact
Data privacy and security concerns remain a key restraint for the patient safety and risk management software market, as these platforms handle sensitive patient and clinical data. Healthcare organizations face increasing risks from cyberattacks, ransomware, unauthorized access, and data breaches, which can lead to financial losses, reputational damage, and regulatory penalties. The growing adoption of cloud-based solutions further heightens security concerns. In addition, compliance with stringent data protection regulations requires ongoing investments in cybersecurity infrastructure and compliance management. These challenges can increase implementation costs and complexity, particularly for smaller healthcare providers, limiting software adoption.
The increasing adoption of artificial intelligence (AI) and predictive analytics in healthcare presents a significant growth opportunity for the patient safety and risk management software market. Healthcare organizations are increasingly adopting advanced solutions that enable proactive risk identification, early intervention, and data-driven decision-making. AI-powered platforms can analyze large volumes of clinical and patient data to predict adverse events, identify high-risk patients, and detect safety vulnerabilities before harm occurs. These capabilities help reduce medical errors, improve the quality of care, optimize resources, and enhance patient outcomes.
Moreover, the growing availability of electronic health records (EHRs), real-time monitoring systems, and healthcare big data is accelerating the adoption of AI-driven safety solutions. For instance, in November 2025, Max India launched an AI-enabled patient management system in India to enhance patient monitoring, safety, and recovery outcomes. As healthcare providers increasingly prioritize preventive risk management and value-based care, demand for intelligent patient safety solutions is expected to rise significantly.
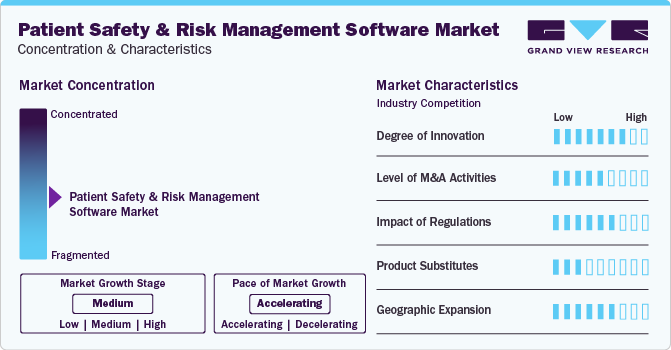
Market Concentration & Characteristics
Technological advancements in patient safety and risk management software are revolutionizing healthcare. These advancements include AI and machine learning for predictive analytics, real-time monitoring through IoT devices, cloud computing for scalability and data security, advanced data analytics for insights, mobile apps for communication, blockchain for data integrity, and predictive analytics for risk prevention. For instance, in June 2023, Pharmapod deployed OMNI Care Homes (OMNI) to enhance medication management and facilitate the provision of superior resident care. This platform efficiently integrates data from residential facilities and pharmacies, enabling OMNI to conduct thorough analyses and identify and mitigate risks effectively.
 To learn more about this report, Download Free Sample Report
The activities, such as mergers, acquisitions, and partnerships, enable companies to expand geographically, financially, and technologically. For instance, in July 2022, RLDatix announced the acquisition of Galen Healthcare Solutions. This strategic acquisition enabled organizations to satisfy regulatory conditions for data retention while ensuring patient care continuity throughout their healthcare journey.
The regulation sets standards for software development, marketing, and use. Software used for patient safety and risk management must comply with these regulations' safety, performance, and data protection requirements. Regulatory bodies like the European Medicines Agency and national competent authorities oversee the approval and monitoring of such software to ensure patient safety and effectiveness. Moreover, compliance with HIPAA and the Health Information Technology for Economic and Clinical Health (HITECH) Act is essential in the North American healthcare sector. These standards focus on safeguarding patient health information and ensuring secure electronic data transfer. Healthcare providers must adhere to these regulations to protect patient privacy and avoid penalties.
Companies in the patient safety and risk management software industry adopt geographic expansion strategies to maintain their position in emerging markets and customer base from these regions. For instance, in October 2020, Health Catalyst marked its entry into the Middle East healthcare market by partnering with the Middle East Healthcare Company to offer its services to six Saudi Arabian hospitals. These hospitals would implement Health Catalyst’s DOS technology platform.
Analyst Perspective
The patient safety and risk management software market is evolving from a compliance-focused segment into a strategic component of healthcare quality management. Healthcare providers are increasingly recognizing that adverse events, medication errors, hospital-acquired infections, and clinical workflow inefficiencies not only impact patient outcomes but also create substantial financial and reputational risks. As a result, hospitals are moving beyond basic incident reporting systems toward integrated platforms that provide real-time visibility into safety events, root-cause analysis, risk mitigation, and performance benchmarking.
Type Insights
Based on type, the risk management & safety solutions segment led the market with the largest revenue share of 67.0% in 2025. This large share is attributed to the development of patient safety software, which allows healthcare managers to access patient data from a single system, resulting in easy accessibility and data protection. These solutions provide effective and high-quality care for patients. In May 2023, DOSIsoft announced the launch of ThinkQA Secondary Dose Check, a new software application that calculates and verifies patients' secondary doses. It is designed to help Radiation Therapy (RT) departments with patient-specific safety and quality assurance (QA) procedures and meet the QA standards of the most recent adaptive radiotherapy tools and procedures.
The governance, risk & compliance solutions segment is expected to grow at the fastest CAGR from 2025 to 2030. The growth is attributed to the rising number of adverse health-related events worldwide. According to a report by the Institute of Medicine (IOM), around 98,000 people die annually due to medical errors when they are admitted to the hospital. Hence, the WHO and several governments are directing several patient safety programs to raise awareness in this area. Moreover, some key players are adopting various strategies, such as mergers & acquisitions, to strengthen their market presence and cater to the growing demand.
For instance, in July 2022, RLDatix, specializing in healthcare Governance, Risk, & Compliance (GRC) solutions, acquired Galen Healthcare Solutions (Galen), specializing in optimization, data migration, implementation, & archival solutions for HIT systems. This acquisition facilitated organizations in complying with regulatory mandates related to data retention while assuring patient continuity care throughout their healthcare trajectory. By leveraging RLDatix’s premier GRC solutions, organizations can be prepared to archive, administer, and preserve legacy data essential for safer healthcare services.
Deployment Type Insights
Based on deployment type, the cloud segment led the market with the largest revenue share of 58.5% in 2025. Cloud-based patient safety & risk management software is a digital platform that runs on cloud servers and can be accessed through web browsers. It is specifically created to assist healthcare providers & organizations to manage and enhance patient safety while minimizing risks. This software utilizes advanced cloud computing and/or web technologies to deliver a secure, scalable, & adaptable framework for storing, analyzing, & addressing patient safety data, incidents, and risk evaluations.
The on-premise segment is expected to grow at a significant CAGR from 2025 to 2030. On-premise patient safety & risk management software gives healthcare organizations greater control over data security and compliance. It offers customization & integration options, reliable performance in areas with limited internet access, and adherence to regulatory requirements. In addition, the software enables offline access, strong data backup, potential cost savings, and local maintenance support. These advantages make it a preferred choice for many healthcare institutions seeking secure and efficient patient safety & risk management systems.
End-use Insights
Based on end use, the hospital segment led the market with the largest revenue share of 41.5%. Growth in the segment can be attributed to the growing need to reduce medical errors. The adoption of IT in healthcare is increasing due to its numerous advantages, such as a simplified & consistent data collection process and single point of data entry, which reduces the risk of errors.
Market players are undertaking several strategic initiatives to promote patient safety software in hospitals. For instance, in December 2023, ObservSMART collaborated with Mount Sinai Medical Center to enhance behavioral health patients’ safety across its three emergency centers in Miami-Dade County. The innovative portable rounding technology developed by ObservSMART, which employs Bluetooth proximity and patient wearable devices, facilitates the monitoring of patients with higher acuity levels.
 To learn more about this report, Download Free Sample Report
The ambulatory care centers segment is expected to grow at the fastest CAGR from 2025 to 2030. Ambulatory care encompasses medical services provided on an outpatient basis without needing admission to a hospital or similar facility. It comprises services offered by physicians' offices and other healthcare professionals, hospital outpatient departments, specialty clinics or centers for dialysis or infusion, urgent care clinics, and ambulatory surgical centers (ASCs), among others. Hence, market players are introducing several offerings to cater to this segment. For instance, in March 2024, Surglogs announced that it was chosen as the compliance management software provider by one of the largest ASC companies in the U.S. This collaboration sets Surglogs to enhance and streamline regulatory compliance operations throughout over 300 ASCs within its portfolio.
Regional Insights
North America dominated the patient safety and risk management software market with the largest revenue share of 49.2% in 2025. The growth is attributed to the high adoption of healthcare IT services to organize & streamline workflows at healthcare institutions in the U.S. and Canada. Moreover, the presence of technologically advanced healthcare infrastructure and the shift from on-premise solutions to cloud-based solutions are driving the market growth. In addition, the rise in the usage of data analytics to enhance patient safety and the presence of numerous key market participants in the U.S. are some of the key factors boosting market growth in this region.
 To learn more about this report, Download Free Sample Report
U.S. Patient Safety And Risk Management Software Market Trends
The patient safety and risk management software market in the U.S. held the largest share in the North America region in 2025 due to government initiatives that support improvements in treatment, diagnosis, and patient care. During a hospital stay, approximately 25% of Medicare patients experience adverse events, with over 40% of these incidents being preventable errors. There is a continuous effort within hospitals and health systems to improve patient safety standards. In 2023, the American Hospital Association (AHA) initiated a new Patient Safety Initiative to promote ongoing efforts in this country. This initiative aims at reinforcing and advancing patient safety measures across hospitals & health systems.
Europe Patient Safety And Risk Management Software Market Trends
Europe followed North America in terms of revenue share in 2024 and is expected to maintain its position from 2025 to 2030. The healthcare industry in Europe is focused on developing solutions capable of mitigating the rising costs, increasing prevalence of chronic conditions, rising frequency of medical errors, rapidly aging population, growing demand for treatments, and declining healthcare workforce. A shift toward value-based healthcare is expected to strengthen the demand for better patient outcomes at a reasonable cost.
The Germany patient safety and risk management software market dominated in the European region in 2024. Increasing adoption of innovative healthcare IT solutions due to the need for efficient utilization of resources and increased patient-centric approach significantly contributes to the adoption of patient safety & risk management software solutions in healthcare systems.
The patient safety and risk management software market in the UK is expected to grow significantly from 2025 to 2030. The market growth in the country is attributed to the increasing incidence of medical errors and hospital-acquired infections. Medical errors present a challenge in healthcare, often leading to preventable patient harm, extended hospital stays, and elevated costs. According to a study by the Policy Research Unit in Economic Evaluation of Health and Care Interventions, about 237 million medication errors occurrence estimated annually in England, with approximately 66 million potentially having clinical significance.
Asia Pacific Patient Safety And Risk Management Software Market Trends
Asia Pacific is anticipated to register the fastest CAGR from 2025 to 2030. An increase in the patient pool, a rise in investments to improve healthcare infrastructure and advancements related to AI/ML are factors propelling the demand for patient safety & risk management software. Furthermore, the growing need for managing efficient workflows and increasing demand for personalized and customized information in emerging economies like India and China are driving the market growth in the region.
The China patient safety and risk management software market held a significant market share in 2024. An increase in medical errors resulting in high demand for patient safety and care is driving the market growth in the country. Moreover, growing concerns regarding hospital-acquired infections and high healthcare costs are further propelling the growth of the market. For instance, according to a study published by NCBI in January 2023, the median total medical costs and length of hospital stay for in-patients with Hospital-Acquired Infections (HAI) in China exceed those without HAI by approximately USD 4000 and 13.89 days, respectively.
The patient safety and risk management software market in India is expected to grow significantly from 2025 to 2030. Digitalization in the healthcare sector in India is being rapidly adopted. Tech giants have started focusing on implementing healthcare IT solutions in the country. These solutions help overcome barriers by solving the problem through early detection, diagnostics, decision-making, & treatment, supporting the shortage of personnel and catering to the country's large population. This, in turn, is driving the adoption of patient safety and risk management software to promote care, reduce risks associated with hospital-acquired infections, and maintain compliance with industry standards & regulations.
Key Patient Safety And Risk Management Software Company Insights
The market is fairly competitive, and some notable participants in the market are symplr; BD; Origami Risk LLC; and Riskonnect, Inc. These players are involved in new product launches, partnerships, and acquisitions to gain a competitive edge over each other.
Key Patient Safety And Risk Management Software Companies:
The following key companies have been profiled for this study on the patient safety and risk management software market.
- Riskonnect, Inc.
- Origami Risk LLC
- RLDatix
- Health Catalyst
- Conduent, Inc.
- symplr
- Clarity Group, Inc.
- Becton, Dickinson and Company (BD)
- RiskQual Technologies, Inc.
- Prista Corporation
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Riskonnect, Inc., Origami Risk LLC, RLDatix,etc)
- Expand integrated risk management, patient safety, compliance, and quality management platforms through product enhancements and strategic acquisitions.
- Strong healthcare customer base, comprehensive software suites, and deep expertise in clinical risk and safety management workflows.
- Complex implementation processes and high dependence on healthcare IT budgets and digital transformation initiatives.
Emerging Players (InPhase Health, Clarity Group, Inc., RiskQual Technologies, Inc., etc)
- Focus on specialized patient safety, incident reporting, and quality improvement solutions tailored to healthcare providers.
- Niche expertise, flexible deployment models, and customized solutions for specific healthcare risk management requirements.
- Limited global market penetration and fewer resources for large-scale platform expansion compared with established vendors.
Recent Development
- In October 2025, Basil Systems launched its AI-powered Safety Signaling solution, strengthening the Patient Safety and Risk Management Software market by enabling proactive risk detection, advanced post-market surveillance, faster corrective actions, and improved patient safety management for medical device manufacturers.
“Medical device companies are drowning in post-market data but starving for predictive analytics and intelligence. Our AI-powered Safety Signaling delivers those insights. We directly address the challenges of early risk detection and root cause analysis by using verifiable data to ignite actionable insights. This isn’t about finding more data; it’s about finding the critical connections in the data that already exist. We help our customers predict and prevent issues, improve product design, and solidify market leadership, while championing patient safety.”
- Anthony Cirurgiao, CEO & Founder, Basil Systems
Patient Safety And Risk Management Software Market Report Scope
Report Attribute
Details
Market size in 2025
USD 2.5 billion
Estimated market size in 2026
USD 2.7 billion
Projected market size by 2033
USD 6.4 billion
Growth rate
CAGR of 13.0% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, deployment type, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; UK; Germany; France; Spain; Italy; Sweden; Norway; Denmark; Russia; Japan; China; India; South Korea; Australia; Thailand; Brazil; Mexico; Argentina; South Africa; UAE; Saudi Arabia; Kuwait
Key companies profiled
Riskonnect, Inc.; Origami Risk LLC; RLDatix; Health Catalyst; InPhase Health; symplr; Clarity Group, Inc.; Becton, Dickinson and Company (BD); RiskQual Technologies, Inc.; Prista Corporation
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Patient Safety And Risk Management Software Market Report Segmentation
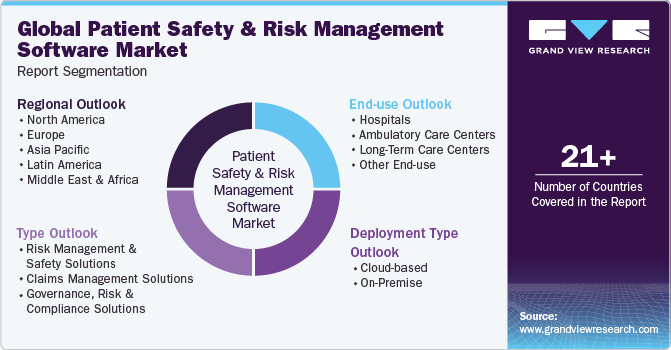
This report forecasts revenue growth and provides at global, regional, and country levels an analysis of the latest trends in each of the sub-segments from 2021 to 2033. For this report, Grand View Research has segmented the global patient safety and risk management software market report based on type, deployment type, end-use, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Risk Management & Safety Solutions
-
Claims Management Solutions
-
Governance, Risk & Compliance Solutions
-
-
Deployment Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Cloud-based
-
On-Premise
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Ambulatory Care Centers
-
Long-Term Care Centers
-
Other End-use
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Mexico
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
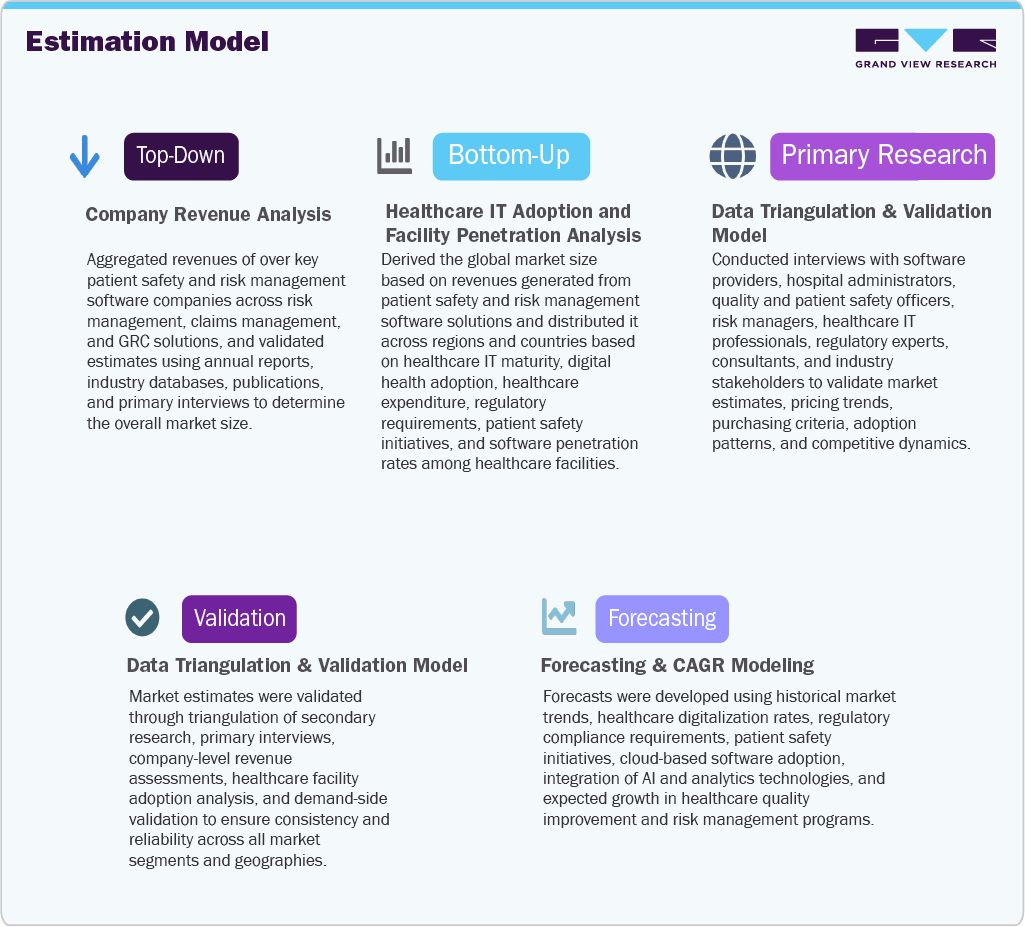
The patient safety and risk management software market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each patient safety and risk management software quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
Risk Management & Safety Solutions
Revenue is generated from software platforms that support incident reporting, adverse event tracking, patient safety monitoring, root cause analysis, risk assessment, and safety improvement initiatives, enabling healthcare organizations to identify, manage, and mitigate clinical and operational risks.
Claims Management Solutions
Revenue is generated from software solutions designed to manage malpractice claims, liability cases, patient complaints, litigation processes, and insurance-related workflows, helping healthcare providers streamline claims handling and reduce financial and legal risks.
Governance, Risk & Compliance
(GRC) Solutions
Revenue is generated from software platforms that facilitate regulatory compliance, policy management, audit management, accreditation tracking, enterprise risk management, and governance oversight, ensuring adherence to healthcare regulations and organizational standards.
Segment - Deployment Type
Revenue capture definition
Cloud-based
Revenue is generated from subscription- or license-based patient safety and risk management software hosted on cloud infrastructure, providing remote accessibility, scalability, automatic updates, and reduced IT maintenance requirements for healthcare organizations.
On-Premise
Revenue is generated from patient safety and risk management software installed and operated within a healthcare organization's own IT infrastructure, offering greater control over data security, customization, and system management.
Segment - End Use
Revenue capture definition
Hospitals
Revenue is generated from patient safety and risk management software specifically formulated to meet the nutritional requirements of adult and geriatric patient populations requiring nutritional support.
Ambulatory Care Centers
Revenue is generated from pediatric enteral nutrition products tailored to support growth, development, and disease management in infants, children, and adolescents.
Long-Term Care Centers
Revenue is generated from patient safety and risk management software deployed in nursing homes, rehabilitation facilities, assisted living centers, and other long-term care settings to monitor resident safety, manage incidents, ensure regulatory compliance, and improve care quality.
Other End-use
Revenue is generated from software adoption by healthcare organizations such as specialty clinics, diagnostic centers, home healthcare providers, behavioral health facilities, and other care settings that require patient safety monitoring, risk management, and compliance oversight capabilities.
Estimation Model
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Cross-Solution Adoption Analysis Across Healthcare Settings
Detailed cross-segmentation analysis of Risk Management & Safety Solutions, Claims Management Solutions, and Governance, Risk & Compliance (GRC) Solutions across hospitals, ambulatory care centers, long-term care facilities, payer organizations, and life sciences companies. Includes adoption rates by facility size, deployment model, healthcare maturity, and patient volume.
Identifies the fastest-growing solution categories across different healthcare settings. Highlights unmet adoption areas, end-user investment priorities, and cross-selling opportunities. Supports go-to-market strategies by aligning solution offerings with customer-specific needs.
Competitive Intelligence & Vendor Positioning Analysis
Comprehensive benchmarking of leading vendors based on product capabilities, AI-enabled risk analytics, interoperability, regulatory compliance, customer base, deployment models, pricing strategies, geographic footprint, strategic partnerships, acquisitions, and innovation pipeline. Includes comparative feature matrix and vendor positioning by enterprise scale.
Helps clients benchmark competitors, identify product differentiation opportunities, evaluate partnership and acquisition targets, and understand competitive intensity across regional markets. Supports strategic product development and market expansion decisions.
Software Pricing & Procurement Analysis
Pricing analysis includes subscription models, implementation costs, professional services, maintenance fees, enterprise licensing, SaaS pricing, and pricing variations by end use.
Enables competitive pricing strategy development, improves commercial positioning, and supports revenue forecasting. Helps vendors optimize pricing models, understand procurement dynamics, and identify opportunities for premium AI-enabled and cloud-based solutions.
Frequently Asked Questions About This Report
Some key players operating in the patient safety and risk management software market include Riskonnect Inc.; Health Catalyst (U.S.), LLC; Conduent Inc.; Origami Risk; Symplr.; RLDatix; Clarity Group Inc; Verge Health; RiskQual Technologies; Quantros Inc.; and The Patient Safety Company.
Key factors driving patient safety & risk management software market growth include an increase in the number of medical errors coupled with an increased necessity to provide patient safety and care.
Based on deployment type, the cloud segment led the market with the largest revenue share of 58.5% in 2025.
Based on end use, the hospital segment led the market with the largest revenue share of 41.5%.
North America dominated with a 49.2% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
The global patient safety and risk management software market size was valued at USD 2.5 billion in 2025 and is expected to reach USD 2.7 billion in 2026.
The global patient safety and risk management software market is expected to grow at a compound annual growth rate of 13.0% from 2026 to 2033 to reach USD 6.4 billion by 2033.
Risk management and safety solutions dominated the patient safety & risk management software market with a share of 67.0% in 2025. This is attributable to the development of patient safety software devices, which provides an advantage to the healthcare managers to access patient data from a single system, resulting in easy accessibility and protection of data.
About the Author(s)
Healthcare IT Research Team
Healthcare · Healthcare ITThis report was authored by the healthcare it research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the healthcare it segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


