
- Home
- »
- Medical Devices
- »
-
Pediatric Orthopedic Devices Market Size Report, 2026-2033GVR Report cover

Pediatric Orthopedic Devices Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Trauma, Sports Medicine, Spine), By End Use (Hospitals, Outpatient Facilities), By Region (North America, Europe, Asia Pacific;,Latin America, MEA), And Segment Forecasts
Market Size, 2025
$4.5BMarket Estimate, 2026
$5.0BMarket Forecast, 2033
$11.5BCAGR, 2026–2033
12.7%Pediatric Orthopedic Devices Market Summary
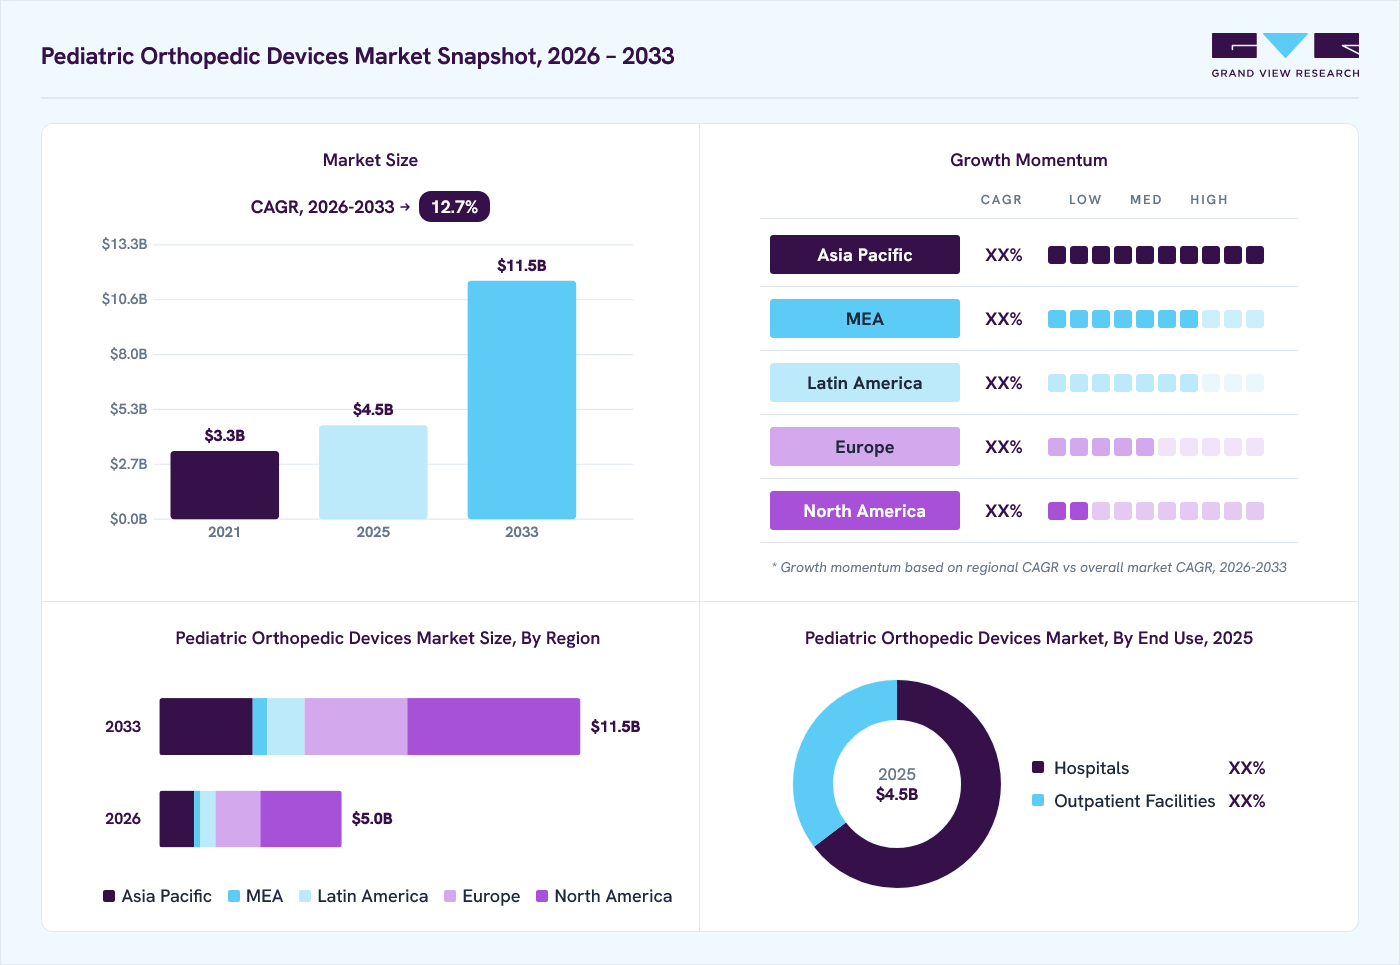
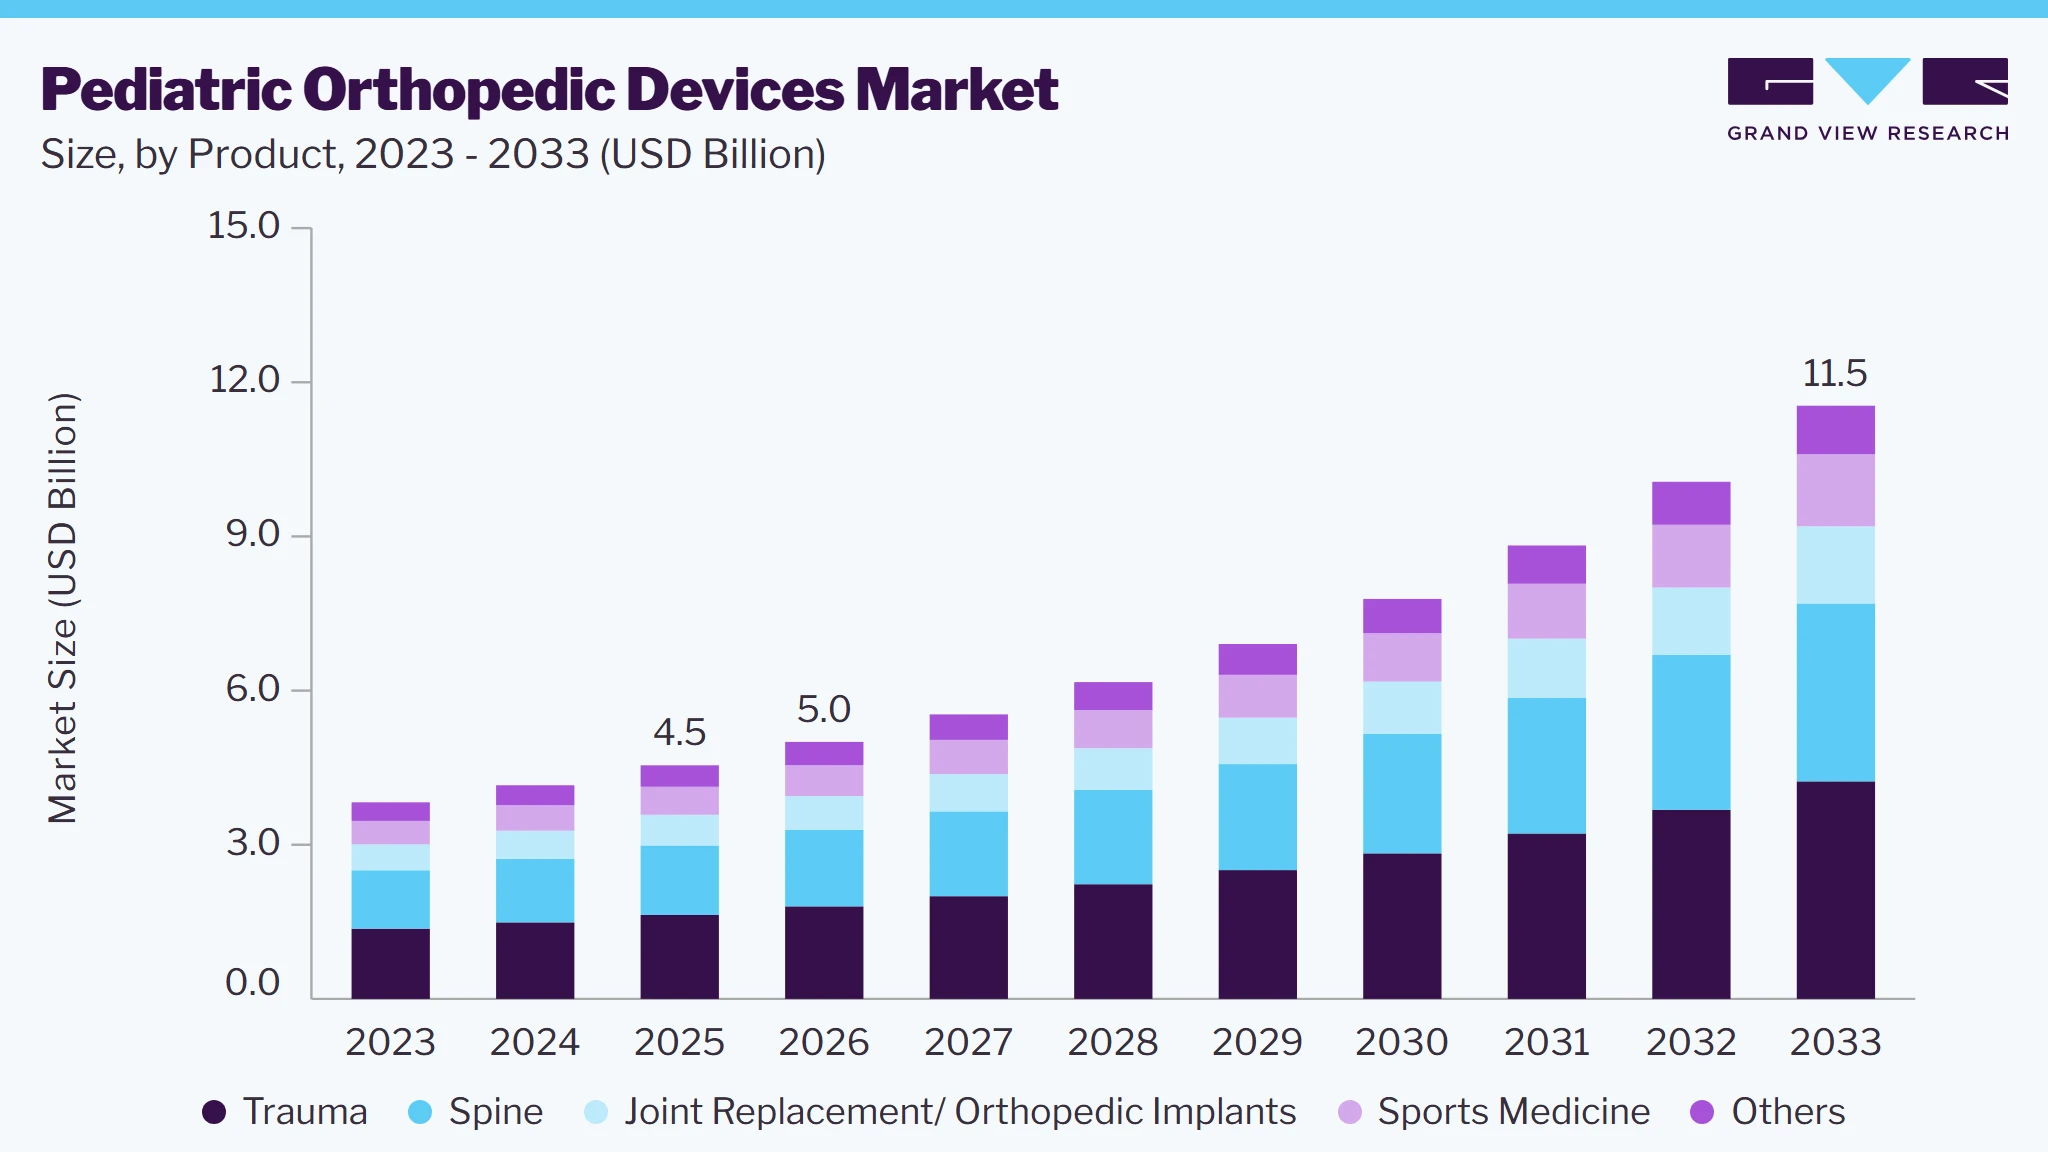
The global pediatric orthopedic devices market size was valued at USD 4.5 billion in 2025 and is projected to grow from USD 5.0 billion in 2026 to USD 11.5 billion by 2033, at a CAGR of 12.7%from 2026 to 2033. North America dominated the market, accounting for a revenue share of 45.2% in 2025. Factors such as growing awareness of orthopedic conditions in children and the rise in congenital & developmental disorders, coupled with advancements in design & materials to provide effectiveness & comfort, are driving demand.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Trauma segment dominated the market, with a revenue share of 35.9% in 2025.
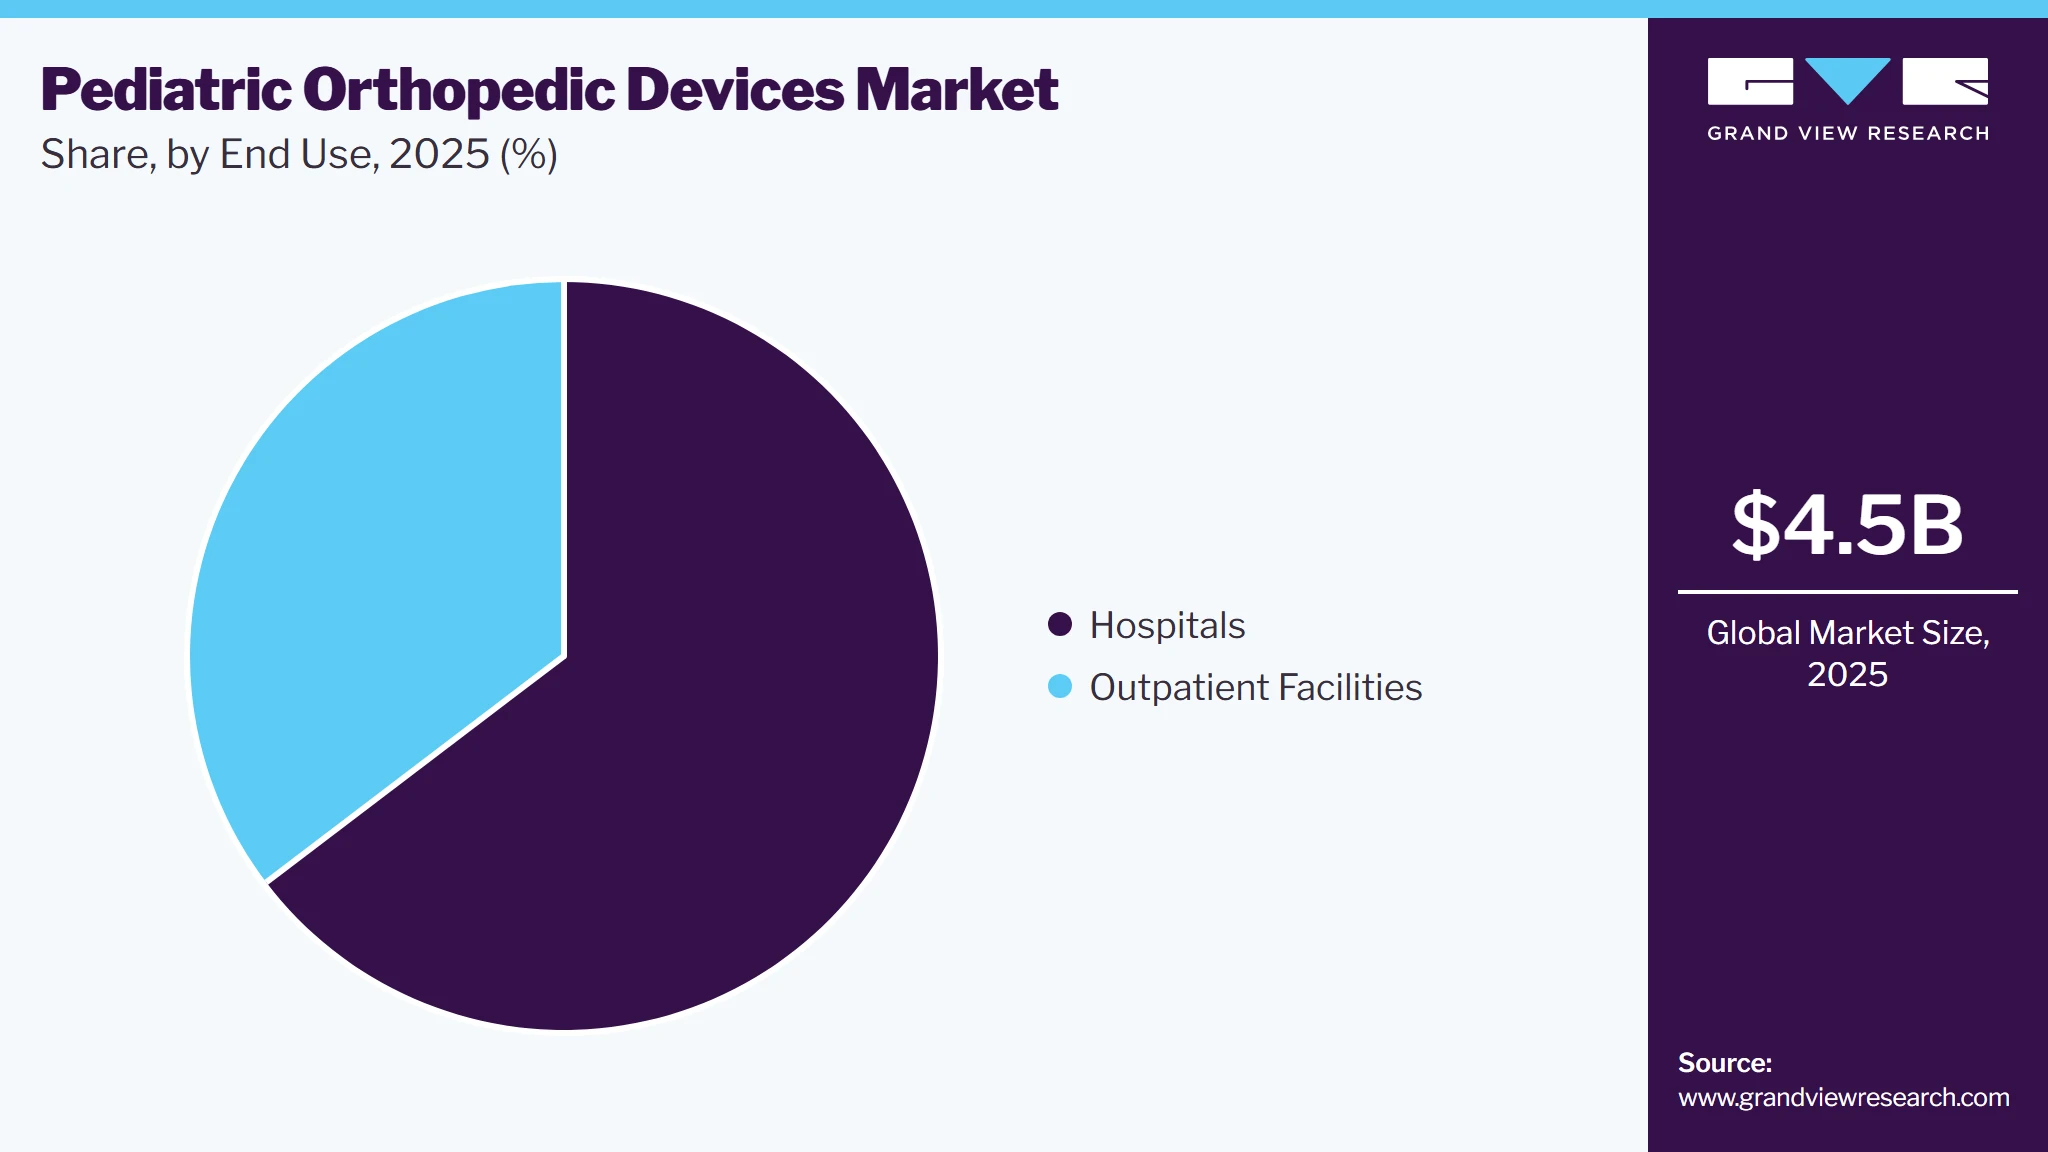
- By end use: Hospitals segment held the largest market share of 64.7% in 2025.
Regional Highlights
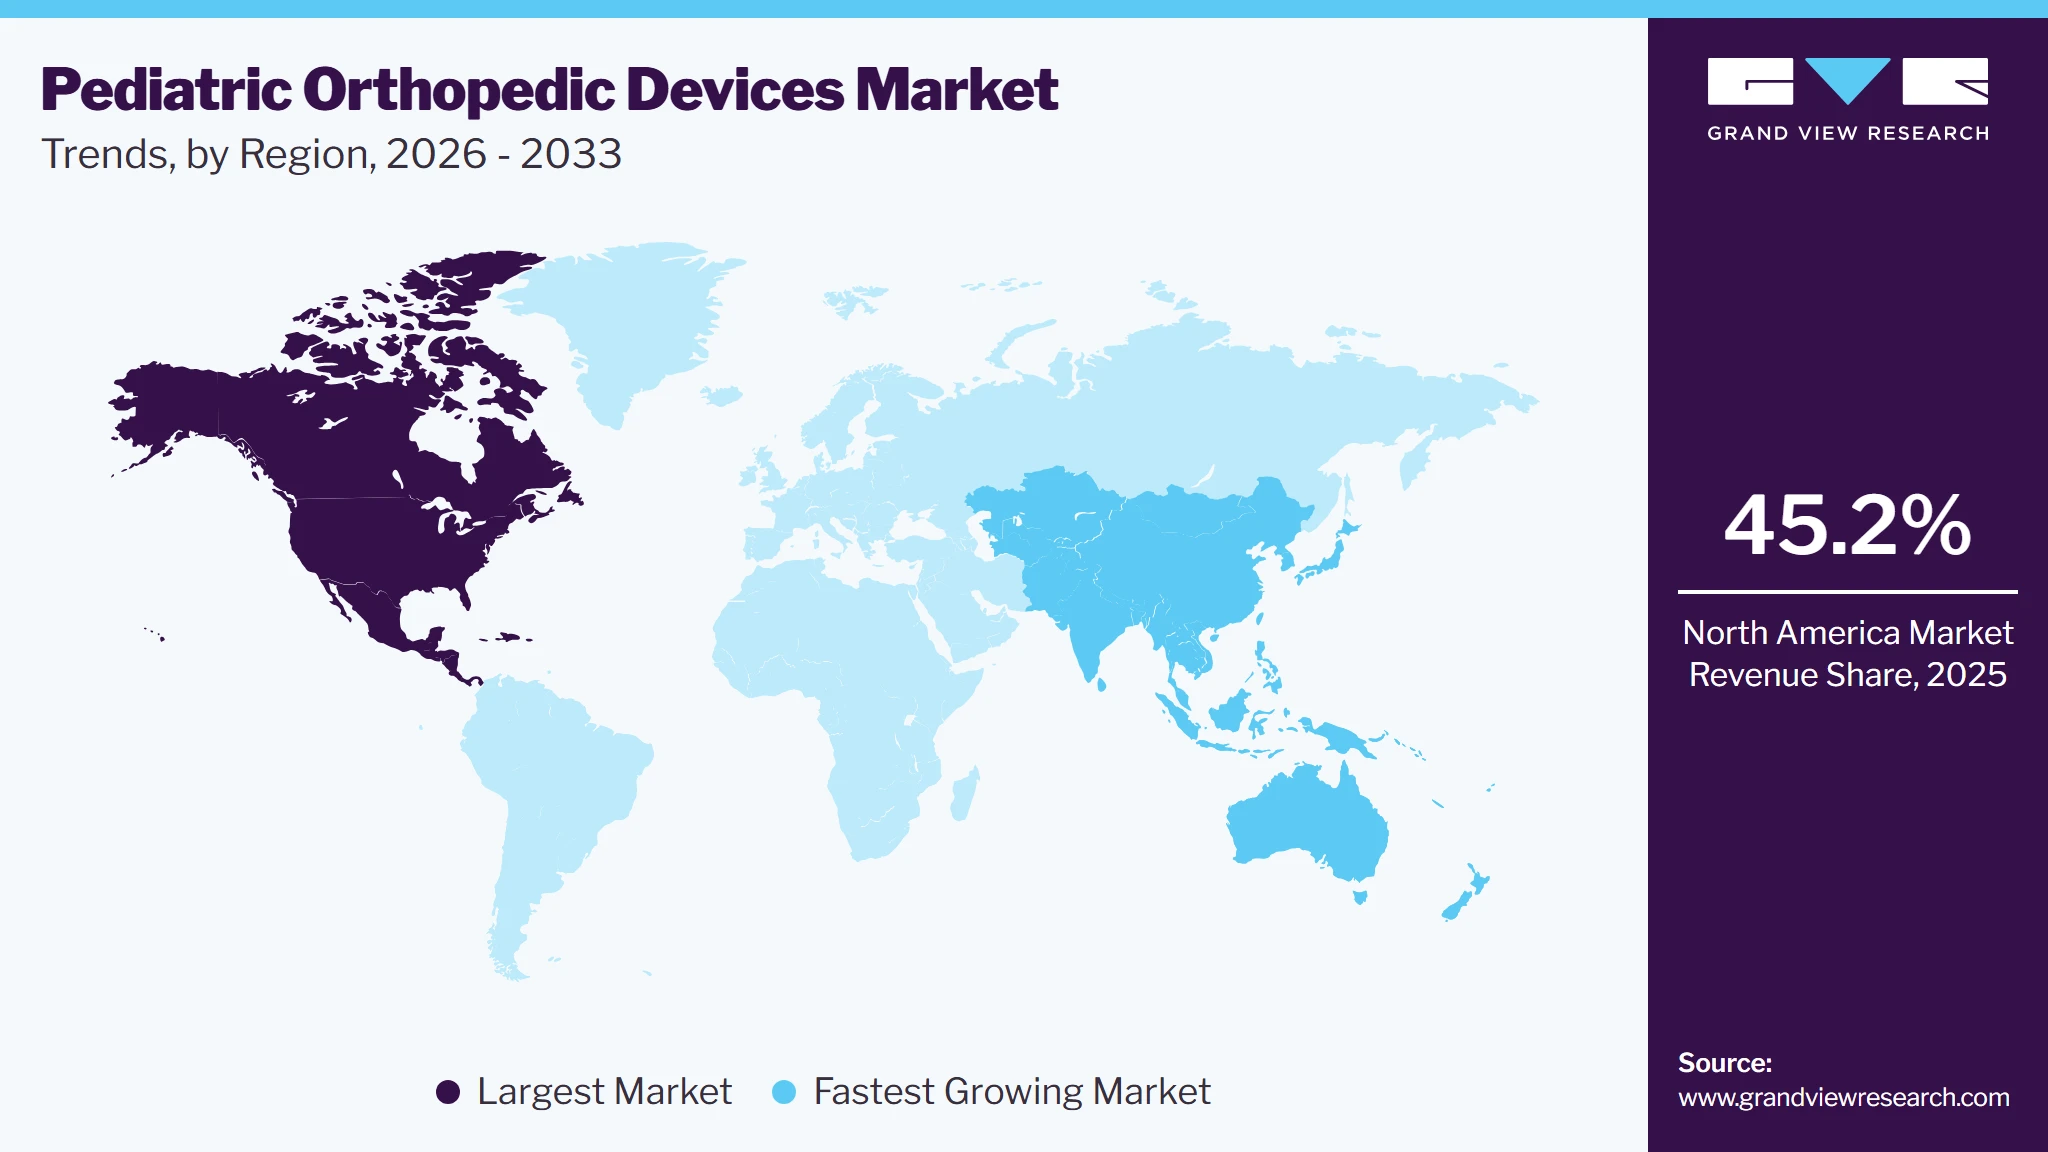
- Largest regional market: North America (45.2% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 4.5 Billion
- Estimated market size in 2026: USD 5.0 Billion
- Projected market size by 2033: USD 11.5 Billion
- CAGR (2026-2033): 12.7%
Prism AI by Grand View Research Free to tryAsk a question about the pediatric orthopedic devices marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →Furthermore, innovations such as adjustable & customizable devices and improved materials for better functionality & safety are fueling the market. For example, OrthoPediatrics Corp. offers Hinge Pediatric Plating System, an articulated plate and screw system to address knee deformities in children by modulating their growth.
Rising technological advancements in the orthopedic devices sector, including pediatric orthopedic devices, are expected to accelerate the market growth. For instance, in March 2022, Explorer Surgical, a GHX company, in collaboration with Pega Medical, a Pediatric orthopedic medical device innovator, extended its presence in the pediatric orthopedic medical device to enhance surgical procedures and support remote case management. Moreover, advanced biomaterials with better durability and biocompatibility have improved the quality of orthopedic implants, leading to a growth in their demand. These biomaterials, which include various alloys and ceramics, are designed to replicate the function of natural bones and joints, further propelling the market growth.
 To learn more about this report, Download Free Sample Report
Moreover, rapid development in healthcare infrastructure and the availability of technologically advanced orthopedic devices globally are anticipated to drive market growth over the forecast period. In addition, rising awareness, the availability of minimally invasive surgical techniques, and the rise in U.S. Food and Drug Administration (FDA) clearances boost the market growth. For instance, in December 2023, OSSIO, Inc., an orthopedic fixation technology company, received U.S. FDA clearance for its OSSIOfiber bio-integrative fixation technology to use in orthopedic surgical procedures such as bone fracture repairs, osteotomies, or fusions for children and adolescents.
The growing focus on early diagnosing bone deformities and preventive care in pediatrics propels market growth. As parents and healthcare practitioners seek solutions to treat and manage pediatric musculoskeletal conditions, this is expected to fuel market growth. According to data published by the Australian Institute of Health and Welfare, in Australia, around 34,200 disability-adjusted life years (DALYs) were recorded in 2023 for individuals aged 0 to 24 in Australia suffering from musculoskeletal conditions. In addition, approximately USD 696.5 million was invested within the Australian healthcare system to address musculoskeletal conditions for people aged 0 to 24 in 2020-2021.
Moreover, the rapid rise in sports participation among children led to increased sports injuries, which increased the demand for pediatric orthopedic devices. For instance, according to the National Survey of Children's Health, in the U.S., 36.3 million children aged 6 to 17 participated in sports activities or took lessons in 20 22. Moreover, according to Stanford Medicine Children's Health, in the U.S., over 775,000 children participating in sport-related activities are injured annually, and one in four injuries is supposed to be serious.
In addition, increasing government initiatives, reform policies, and funding raised by public and private companies boost market growth. For instance, in August 2021, WishBone Medical, Inc., a pediatric orthopedic medical devices company, received USD 10 million from LKCM Headwater Investments to expand its manufacturing facilities, support other operational initiatives, and accelerate product development to meet growing demands.
Market Dynamics
The pediatric orthopedic devices market is expected to grow due to increasing diagnosis of orthopedic disorders, rising demand for customized solutions, technological advancements, and greater emphasis on early intervention. Manufacturers are increasingly moving beyond traditional braces toward connected, adjustable, and digitally optimized devices that improve comfort, compliance, and long-term clinical outcomes. Integration of sensors, wearable technology, and digital monitoring platforms is emerging as a significant trend in pediatric orthopedic devices. Smart orthoses allow clinicians to monitor brace usage, assess movement patterns, and improve patient adherence through real-time data collection.
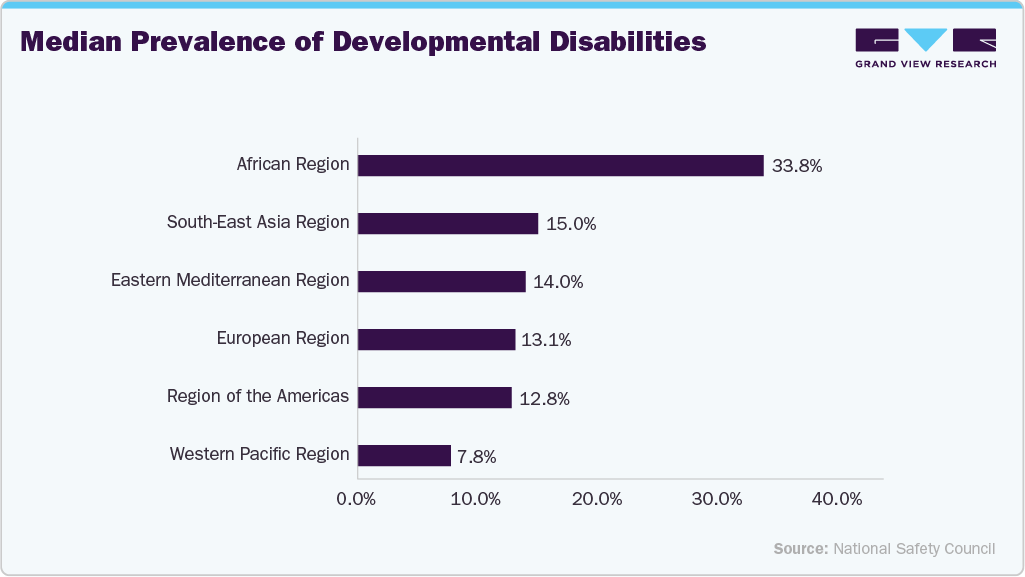
The increasing prevalence of pediatric neuromuscular and musculoskeletal disorders, including cerebral palsy, spina bifida, developmental gait abnormalities, clubfoot, and scoliosis, is a major growth driver for the pediatric orthopedic devices market. These conditions often result in impaired mobility, muscle imbalance, joint instability, and progressive deformities, creating a sustained demand for ankle-foot orthoses (AFOs), spinal braces, lower-limb orthoses, and customized mobility-support solutions. According to the UNICEF report 2023, the median prevalence of developmental disabilities among children and adolescents varies significantly across regions, ranging from 7.8% in the Western Pacific Region to 33.8% in the African Region. The high prevalence of developmental and motor impairments is increasing the need for supportive interventions such as ankle-foot orthoses (AFOs), spinal braces, and customized lower-limb orthopedic solutions to improve mobility, posture, and functional outcomes in pediatric patients.
 To learn more about this report, Download Free Sample Report
Rising technological advancements in the orthopedic devices sector, including pediatric orthopedic devices, drive the market growth. For instance, an article published in January 2026 in Orthopedic Clinics showcased how a Yale School of Medicine team created a precise virtual replica of a child’s bone, mapped out the surgery virtually, and used custom-printed tools to execute the plan with unprecedented precision using advances in 3D planning and patient-specific instrumentation.
"Digital modeling allows us to see the hidden complexities of a child's anatomy, we can then determine the best way to perform surgery on a computer multiple times before the patient even enters the operating room. This enables orthopedic surgeons to find the best angle in an osteotomy, for example, a procedure where a bone is cut and reshaped to correct a deformity”.
- David Frumberg, MD, associate professor of orthopaedics and rehabilitation at Yale School of Medicine and the study's principal investigator
The high cost associated with customized pediatric orthopedic devices is a significant challenge limiting market adoption, particularly in price-sensitive regions. Standard orthopedic supports, pediatric orthoses often require specialized clinical assessment, digital scanning, customized fabrication, and frequent modifications due to children’s continuous growth. These factors increase manufacturing and treatment costs, creating a financial burden for families and healthcare systems. For instance, custom ankle-foot orthoses (AFOs) can cost up to USD 1,990, while custom thoracolumbosacral orthoses (TLSOs) used for scoliosis management can exceed USD 2,400, excluding clinical evaluation, fitting, and follow-up appointments. These costs increase further because pediatric patients require frequent replacements as they grow, creating a substantial financial burden for families.
The increasing adoption of digital technologies, including 3D scanning, computer-aided design (CAD), additive manufacturing (3D printing), artificial intelligence (AI), and gait analysis systems, presents a significant growth opportunity for the pediatric orthopedic devices market. The conventional orthoses digitally designed, and patient-specific devices provide improved anatomical fit, enhanced comfort, reduced weight, and greater adaptability to children's changing physical requirements. These advancements also enable faster production, reduced manufacturing waste, and improved clinical outcomes, encouraging healthcare providers to transition from traditional fabrication methods to digitally enabled orthopedic solutions. In February 2026, OrthoPediatrics Corp. announced the expansion of its Enabling Technology platform through its ongoing partnership with iotaMotion, following the FDA 510(k) clearance for the iotaSOFT Insertion System to be used in children aged four and older.
Case Study: Advancements in Digital Technologies and Personalized Pediatric Orthopedic Care
Overview:
A 2025 review published in Cureus highlighted advancements in pediatric orthopedic diagnosis and management, including AI-assisted imaging, 3D assessment, and personalized treatment approaches. These innovations are improving early detection and management of conditions such as scoliosis, congenital deformities, and neuromuscular disorders, increasing the need for customized pediatric orthopedic devices.
Implementation:
Advanced imaging and digital design technologies are enabling clinicians to develop patient-specific orthopedic solutions based on children’s anatomical requirements and growth patterns. The use of 3D scanning, CAD-based design, and customized manufacturing has improved the fit, comfort, and adaptability of devices such as ankle-foot orthoses (AFOs), spinal braces, and lower-limb orthoses.
Outcomes:
- Early Intervention: Improved diagnosis enables timely orthopedic management and reduces progression of pediatric orthopedic deformities.
- Improved Mobility: Customized orthoses support better gait, posture, and functional outcomes in children with mobility impairments.
- Higher Compliance: Better fitting and lightweight designs improve comfort and long-term device acceptance.
- Personalized Care: Growth-adjustable solutions allow continuous adaptation as children develop.
Conclusion:
The integration of digital technologies and personalized orthopedic solutions is transforming pediatric orthopedic care by improving treatment accuracy, patient comfort, and rehabilitation outcomes, thereby creating growth opportunities for the pediatric orthopedic devices market.
Market Concentration & Characteristics
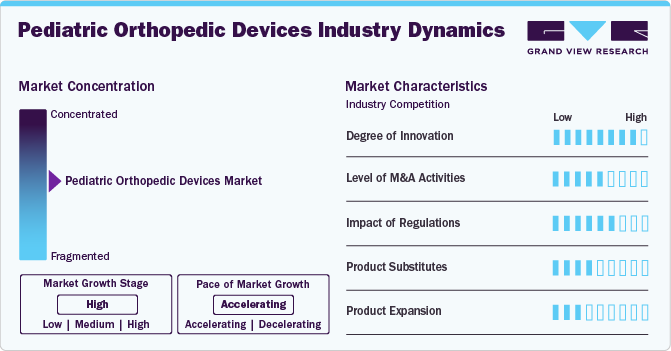
The market is characterized by a high degree of innovation, driven by technological advancements in biomechanics, materials science, and surgical techniques. For instance, the Nemours Pediatric Engineering Research Lab (PERL), based in the U.S., works with devices that rehabilitate and assist children with neuromuscular disabilities and orthopedic disorders such as spinal muscular atrophy, muscular dystrophy (MD), arthrogryposis, scoliosis, limb length discrepancies, and spinal cord injury.
The market is characterized by a medium level of merger and acquisition (M&A) activity, owing to a desire to extend the business to cater to the growing demand and maintain a competitive edge. For instance, in May 2023, OrthoPediatrics Corp. acquired Medtech Concepts , an enabling technology platform, for USD 15.2 million to offer intraoperative resources for surgeons that enhance decision-making, drive operating room efficiency, and ultimately improve healthcare for children.
 To learn more about this report, Download Free Sample Report
Regulations play an important role in shaping the market, ensuring the efficacy, safety, and quality of orthopedic devices available for pediatric patients. Regulatory requirements govern various aspects of orthopedic device manufacturing, development, and distribution and impose design, materials, sterilization, and labeling standards. In the UK, pediatric orthopedic devices are governed by The Medicines and Healthcare Products Regulatory Agency (MHRA) to ensure the quality and safety of the products.
Rehabilitation and physical therapy equipment serve as alternatives to orthopedic devices. Such equipment includes balance boards, therapy balls designed to enhance strength and flexibility, and exercise bands. Technological advancements led to the development of mobile applications and wearable devices that assist individuals through customized rehabilitation programs, offering convenience and accessibility.
Several market players are expanding their business by launching new products to strengthen their market position. For instance, in May 2023, Stryker introduced the Ortho Q Guidance system. The system integrates advanced optical tracking features through a redesigned, modern camera with sophisticated algorithms of the newly introduced Ortho Guidance software to enhance surgical planning and guidance capabilities.
Analyst Perspective
The pediatric orthopedic devices market is driven by the increasing prevalence of congenital and acquired musculoskeletal disorders, including scoliosis, cerebral palsy, clubfoot, limb deformities, and pediatric fractures. Rising awareness of early diagnosis and intervention, together with growing demand for specialized pediatric orthopedic care, is accelerating the adoption of implants, fixation systems, spinal correction devices, and orthotic solutions. Technological advancements in patient-specific implants, 3D printing, minimally invasive surgical techniques, and growth-preserving orthopedic devices are further supporting market expansion.
Product Insights
Based on product, the trauma segment led the market with the largest revenue share of 35.9% in 2025. Accidents, sports-related injuries, falls (including falling from heights), burns, assaults, and drownings are the most reported causes of traumatic mortality among children. For instance, according to an article published by NCBI in May 2023, trauma accounts for over 15,000 fatalities, and 50% of all reported deaths are children every year. The rising trend of urbanization and the increase in outdoor activities among children are expected to increase the incidence of trauma significantly. Thus, such factors boost the segment growth.
The sports medicine segment held a significant market share in 2024. The demand for sports medicine is growing due to the increasing prevalence of sports injuries and growing participation in sports & fitness-related activities. Growing career opportunities and a rising inclination toward fitness due to increasing health awareness have improved the number of people choosing sports as a hobby or a career. This, in turn, is expected to increase their chances of incurring injuries, which further drives the market growth.
End Use Insights
Based on end use, the hospitals segment led the market with the largest revenue share of 64.7% in 2025. Hospitals are primary centers for orthopedic surgeries, where patients receive comprehensive care from diagnosis to post-operative rehabilitation. Moreover, advancements in minimally invasive surgeries have made orthopedic procedures more feasible, further driving demand for these facilities. The presence of skilled healthcare professionals specializing in orthopedics and the availability of modern medical equipment fuel the segment's growth. For instance, according to Stanford Medicine Children's Health, in the U.S., 110,000 children ages 5 to 14 were treated in hospital emergency rooms due to baseball-related injuries.
 To learn more about this report, Download Free Sample Report
The outpatient facilities segment is expected to grow significantly over the forecast period. As the trend towards ambulatory care continues to grow, outpatient facilities are becoming increasingly popular for patients seeking quicker recovery times and reduced healthcare costs associated with inpatient hospital stays. For instance, according to the Ambulatory Surgery Center Association, as of 2023, there are more than 6,200 Medicare-certified Ambulatory surgery centers in the U.S.
Regional Insights
North America dominated the pediatric orthopedic devices market with the largest revenue share of 45.2% in 2025. owing to a rise in musculoskeletal disorders, such as juvenile idiopathic arthritis. In addition, the presence of well-established healthcare infrastructure and reimbursement policies further stimulates market growth. Furthermore, the growing focus on minimally invasive surgeries and the rise in trauma and fracture cases in the region is anticipated to boost the market growth.
 To learn more about this report, Download Free Sample Report
U.S. Pediatric Orthopedic Devices Market Trends
The market in the U.S. held the largest share in the North America region in 2025. Favorable government initiatives and investment in arthritis are boosting market growth. For instance, in July 2022, the Arthritis Foundation collaborated with the Childhood Arthritis and Rheumatology Research Alliance (CARRA) and invested USD 1.12 million to research childhood rheumatic diseases, especially juvenile idiopathic arthritis.
Europe Pediatric Orthopedic Devices Market Trends
The pediatric orthopedic devices market in Europe is anticipated to grow considerably during the forecast period. The region's strong focus on R&D fosters continuous innovation in orthopedic implant technologies, enhancing product effectiveness and patient outcomes. Furthermore, robust regulatory frameworks and favorable healthcare policies ensure the quality and safety of pediatric orthopedic devices, thus increasing their demands among the patient population.
France pediatric orthopedic devices market is anticipated to register a significant growth rate during the forecast period. The market for orthopedic implants in France is expected to witness growth driven by new government initiatives. In March 2022, the government of France introduced the Innovative Medical Devices plan to support the medical device sector as part of the France 2030 project. This strategic plan involves a government investment of USD 450 million in the MedTech industry.
The pediatric orthopedic devices market in the UK is anticipated to grow considerably during the forecast period. The UK's National Health Service (NHS) provides universal healthcare coverage to all its residents, ensuring access to orthopedic treatments and stimulating market growth. Moreover, ongoing research activities on childhood arthritis boost market growth. For example, in February 2021, the UK's charity institute Versus Arthritis was awarded the UK's Experimental Arthritis Treatment Centre for Children (EATC4Children).
Asia Pacific Orthopedic Devices Market Trends
The pediatric orthopedic devices market in Asia Pacific is expected to grow at the fastest CAGR over the forecast period. Technological advancements in healthcare infrastructure and increasing healthcare expenditures in countries such as India, Japan, and China stimulate the growth of pediatric orthopedic devices. In addition, a rise in sports-related injuries is driving the demand for orthopedic surgeries, including orthopedic implants, in the region.
India pediatric orthopedic devices market is anticipated to register a significant growth rate during the forecast period. Factors such as recent implementations of state and federal government insurance programs and an annual expansion of insurance coverage are expected to boost the country's market growth.
The pediatric orthopedic devices market in Japan is anticipated to register a considerable growth rate during the forecast period. Japan has a highly developed medical device industry with advanced manufacturing facilities and technologies. The availability of resources that enable the development of advanced technologies at cheaper costs is boosting the number of local manufacturing facilities for pediatric orthopedic devices.
Latin America Orthopedic Devices Market Trends
The pediatric orthopedic devices market in Latin America is witnessing considerable growth due to the growing awareness among healthcare professionals and patients of the benefits and availability of pediatric orthopedic solutions.
Brazil pediatric orthopedic devices market is anticipated to register a significant growth rate during the forecast period. Growing sport-related injuries and accidents in the country fuel the market growth. For instance, according to a study published by Elsevier in October 2022, 40% and 25% of children aged between 1 to 14 die due to accidents and drownings, respectively.
Middle East and Africa Pediatric Devices Market Trends
The pediatric orthopedic devices market in the Middle East and Africa is experiencing lucrative growth. Growing awareness of orthopedic implant surgeries among patients and healthcare professionals, rising product launches, and favorable reimbursement policies for orthopedic procedures boost the market growth.
The UAE pediatric orthopedic devices market is anticipated to grow fastest during the forecast period. The country's improving healthcare system and increasing investments in medical technology will supplement market growth by enabling better access to orthopedic treatments.
Key Pediatric Orthopedic Devices Company Insights
 To learn more about this report, Download Free Sample Report
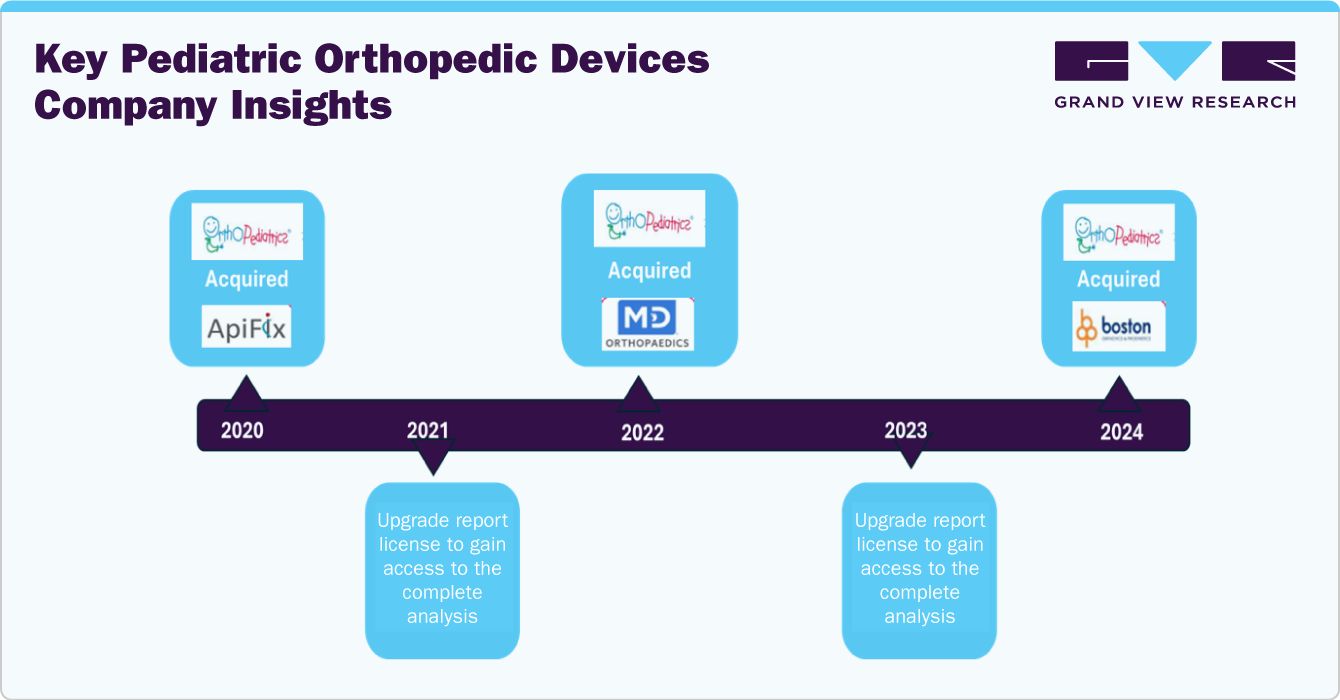
Key participants in the market focus on devising innovative business growth strategies in product portfolio expansions, partnerships & collaborations, mergers & acquisitions, and business footprint expansions.
Key Pediatric Orthopedic Devices Companies:
The following key companies have been profiled for this study on the pediatric orthopedic devices market.
-
Orthofix Medical Inc.
-
OrthoPediatrics Corporation
-
WishBone Medical
-
Pega Medical Inc.
-
Arthrex Inc.
-
Johnson & Johnson Services, Inc. (DePuy Synthes)
-
NuVasive Inc.
-
Smith+Nephew
-
Stryker
-
Zimmer Biomet
-
Medtronic
-
Auxein Medical
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., Medtronic, Johnson & Johnson Services, Inc. (DePuy Synthes), Smith+Nephew, Stryker, Zimmer Biomet, Arthrex Inc., NuVasive Inc., Orthofix Medical Inc.)
- Invest in pediatric-specific orthopedic implants, spinal deformity correction systems, trauma fixation devices, biologics, navigation technologies, and minimally invasive surgical solutions. Strengthening market presence through product innovation, strategic acquisitions, surgeon education programs, and collaborations with pediatric hospitals and healthcare institutions while expanding their global distribution networks.
- Strong global presence, diversified orthopedic product portfolios, advanced R&D capabilities, extensive regulatory expertise, well-established surgeon relationships, robust manufacturing infrastructure, and strong financial resources to support innovation and international expansion.
- High product development and regulatory compliance costs, premium pricing of advanced orthopedic devices, dependence on hospital capital expenditure and reimbursement policies, lengthy product approval timelines, and increasing competition from specialized pediatric orthopedic manufacturers.
Emerging & Specialized Players (e.g., OrthoPediatrics Corporation, WishBone Medical, Pega Medical Inc., Auxein Medical)
- Focus on developing pediatric-specific implants, growth-preserving orthopedic systems, trauma fixation devices, and deformity correction solutions tailored to children's anatomy. Expand through targeted product launches, partnerships with pediatric orthopedic surgeons, geographic expansion, and adoption of advanced manufacturing technologies.
- Specialized expertise in pediatric orthopedics, highly customized product portfolios, faster product innovation, strong relationships with pediatric orthopedic specialists, and the ability to address unmet clinical needs in niche pediatric indications.
- Limited global footprint, smaller distribution networks, lower brand recognition compared to multinational companies, limited financial resources, dependence on strategic partnerships, and challenges in scaling manufacturing and commercialization globally.
Recent Developments
-
In December 2023, OrthoPediatrics Corp. launched the OrthoPediatrics Specialty Bracing Division (OPSB), a non-surgical intervention for pediatric orthopedics.
-
In June 2023, OrthoPediatrics Corp. (KIDS) introduced the GIRO Growth Modulation System for pediatric trauma and deformity correction.
Pediatric Orthopedic Devices Market Report Scope
Report Attribute
Details
Market size in 2025
USD 4.5 billion
Estimated market size in 2026
USD 5.0 billion
Projected market size by 2033
USD 11.5 billion
Growth rate
CAGR of 12.7% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Application, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait
Key companies profiled
Orthofix Medical Inc.,Medtronic; OrthoPediatrics Corporation, WishBone Medical, Pega Medical Inc., Arthrex Inc., Johnson & Johnson Services, Inc. (DePuy Synthes), NuVasive Inc., Smith+Nephew, Stryker, Zimmer Biomet, Medtronic, Auxein Medical
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchasse. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Pediatric Orthopedic Devices Market Report Segmentation
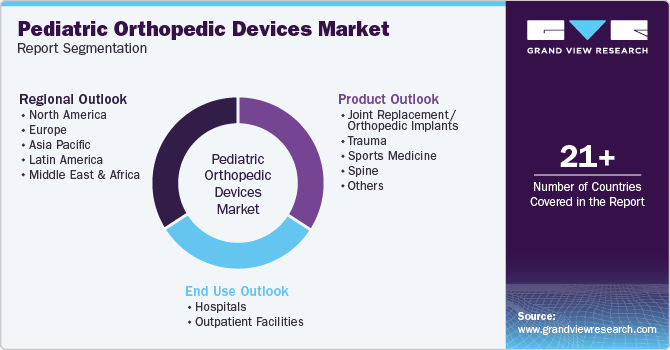
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research, Inc. has segmented the global pediatric orthopedic devices market report based on product, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue USD Million, 2021 - 2033)
-
Joint Replacement/ Orthopedic Implants
-
Lower Extremity Implants
-
Knee Implants
-
Hip Implants
-
Foot & Ankle Implants
-
-
Dental
-
Dental Implants
-
Craniomaxillofacial Implants
-
-
Upper Extremity Implants
-
Elbow Implants
-
Hand & Wrist Implants
-
Shoulder Implants
-
-
-
Trauma
-
Implants
-
Accessories (Plates, Screws, Nails, Pins, Wires)
-
Instruments
-
-
Sports Medicine
-
Body Reconstruction & Repair
-
Accessories
-
Body Monitoring & Evaluation
-
Body Support & Recovery
-
-
Spine
-
Others (Orthobiologics, Enabling Technology, Miscellaneous Items)
-
-
End Use Outlook (Revenue USD Million, 2021 - 2033)
-
Hospitals
-
Outpatient Facilities
-
-
Regional Outlook Revenue USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
Spain
-
Italy
-
France
-
Denmark
-
Norway
-
Sweden
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
MEA
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The pediatric orthopedic devices market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each pediatric orthopedic devices segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Joint Replacement/Orthopedic Implants
Implantable devices are used to restore, stabilize, or replace damaged bones and joints in pediatric patients with congenital disorders, trauma, tumors, or deformities.
Trauma
Devices used for the fixation and stabilization of pediatric fractures and traumatic musculoskeletal injuries.
Sports Medicine
Devices used to repair, reconstruct, and rehabilitate musculoskeletal injuries related to sports and physical activities in pediatric and adolescent patients.
Spine
Implants and fixation systems are used to correct spinal deformities and stabilize the spine in conditions such as scoliosis, kyphosis, and congenital spinal disorders.
Others
Includes external fixation systems, bone graft substitutes, growth modulation devices, and other specialized pediatric orthopedic products.
Segment - Joint Replacement/ Orthopedic Implants
Revenue capture definition
Joint Replacement/Orthopedic Implants
Implantable devices designed to replace or reconstruct damaged joints and bones while restoring function and mobility in pediatric patients.
Lower Extremity Implants
Implants used to treat disorders and injuries affecting the hip, knee, foot, ankle, and other lower-limb structures.
Dental
Implantable devices used for pediatric oral and craniofacial reconstruction procedures.
Upper Extremity Implants
Implants used for the treatment and reconstruction of the shoulder, elbow, wrist, and hand.
Segment - Lower Extremity Implants
Revenue capture definition
Lower Extremity Implants
Orthopedic implants used to stabilize, reconstruct, or replace bones and joints of the lower limbs.
Knee Implants
Devices used for pediatric knee reconstruction, deformity correction, and fracture management.
Hip Implants
Implants designed to restore hip function in children with congenital abnormalities, fractures, or developmental disorders.
Foot & Ankle Implants
Implants used for correcting congenital deformities, fractures, and instability affecting the foot and ankle.
Segment - Upper Extremity Implants
Revenue capture definition
Upper Extremity Implants
Orthopedic implants used to repair and reconstruct bones and joints of the upper limbs.
Elbow Implants
Devices used to restore elbow stability and function following trauma or congenital abnormalities.
Hand & Wrist Implants
Implants used for fracture fixation, deformity correction, and reconstruction of the hand and wrist.
Shoulder Implants
Implants designed for stabilization or reconstruction of the shoulder joint in pediatric patients.
Segment - Dental
Revenue capture definition
Dental
Implantable products used for oral rehabilitation and craniofacial reconstruction in pediatric patients.
Dental Implants
Biocompatible implants placed within the jawbone to support prosthetic teeth in selected pediatric cases.
Craniomaxillofacial Implants
Plates, screws, meshes, and fixation systems used to reconstruct the skull, facial bones, and jaw following trauma, congenital defects, or tumor surgery.
Segment - Trauma
Revenue capture definition
Trauma
Devices used for the surgical management of pediatric fractures and traumatic bone injuries.
Implants
Internal fixation devices such as plates, rods, screws, and nails used to stabilize fractured bones.
Accessories (Plates, Screws, Nails, Pins, Wires)
Fixation components that provide stability and support during bone healing.
Instruments
Surgical tools used for implant placement, fixation, alignment, and removal during orthopedic procedures.
Segment - Sports Medicine
Revenue capture definition
Sports Medicine
Devices used to diagnose, repair, reconstruct, and rehabilitate pediatric sports-related musculoskeletal injuries.
Body Reconstruction & Repair
Implants and fixation devices used to repair ligaments, tendons, cartilage, and soft tissues.
Accessories
Surgical consumables and fixation components used during sports medicine procedures.
Body Monitoring & Evaluation
Diagnostic devices and systems used to assess musculoskeletal function, injury severity, and recovery progress.
Body Support & Recovery
Braces, supports, rehabilitation devices, and recovery aids that assist healing and restore mobility after injury or surgery.
Segment - End Use
Revenue capture definition
Hospitals
Healthcare institutions that provide comprehensive pediatric orthopedic diagnosis, surgical treatment, and rehabilitation services.
Outpatient Facilities
Ambulatory surgical centers and specialty orthopedic clinics that perform pediatric orthopedic procedures and follow-up care without requiring overnight hospitalization.
Estimation Model
The pediatric orthopedic devices market is estimated using a triangulated analytical framework that integrates bottom-up, demand-side, and supply-side approaches. Market size and segment-wise revenue are validated through primary interviews, secondary research, industry benchmarks, company revenues, and epidemiological data.
Model 1: Patient Population-Based Demand Model
Approach: Bottom-up demand estimation
Key Inputs:
-
Prevalence of pediatric musculoskeletal and neuromuscular disorders (e.g., cerebral palsy, scoliosis, clubfoot)
-
Pediatric patient population requiring orthopedic intervention
-
Orthotic prescription and adoption rates
-
Average selling price (ASP) of pediatric orthopedic devices
Method:
Market revenue is estimated by calculating the number of pediatric patients requiring orthopedic devices and multiplying it by the average selling price across product categories.
Model 2: Manufacturer Revenue Model
Approach: Supply-side revenue estimation
Key Inputs:
-
Revenue of leading pediatric orthopedic device manufacturers
-
Product portfolio and regional sales
-
Distribution channel analysis
-
Market share of key players
Method:
Market size is derived by aggregating revenues generated from pediatric orthopedic device sales and validating them through company financial reports and industry benchmarks.
Model 3: Procedure and Healthcare Utilization Model
Approach: Healthcare utilization-based estimation
Key Inputs:
-
Pediatric orthopedic clinic visits
-
Orthotic prescriptions and rehabilitation service utilization
-
Hospital and specialty clinic adoption
-
Average orthopedic device utilization per patient
Method:
Revenue is estimated by assessing orthopedic device utilization across hospitals, rehabilitation centers, and orthopedic clinics and applying average device pricing.
Data Inputs
-
Epidemiological data on pediatric orthopedic disorders
-
Statistics for hospital and rehabilitation center
-
Company annual reports and product portfolios
-
Government healthcare databases
-
Industry publications and primary interviews
Key Assumptions
-
Rising prevalence of pediatric orthopedic and neuromuscular disorders
-
Increasing adoption of customized and 3D-printed orthopedic devices
-
Continued growth in pediatric rehabilitation services
-
Stable pricing trends with regional reimbursement variations
Validation Approach
-
Market estimates are validated through:
-
Cross-verification of demand- and supply-side models
-
Benchmarking against company revenues and historical market trends
-
Sensitivity analysis of disease prevalence, device adoption, and pricing
-
Regional consistency checks based on healthcare expenditure and pediatric population.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Market Revenue Assessment
Developed a comprehensive assessment of the pediatric orthopedic devices market across implants, fixation devices, spinal systems, trauma devices, and orthotic solutions. The analysis evaluates revenue by product type, application, end user, and region, while examining pricing trends, procedure volumes, reimbursement landscape, and market demand drivers.
Supports strategic planning by identifying high-growth revenue segments, optimizing product portfolios, prioritizing regional expansion, and enabling informed investment decisions.
Unit Volume & Revenue Opportunity Assessment
Developed a bottom-up model estimating annual unit demand for pediatric orthopedic implants across trauma, deformity correction, scoliosis, limb reconstruction, and sports injuries. The analysis incorporates procedure incidence, implant utilization per surgery, replacement rates, and ASPs to derive market value by product category.
Enables accurate demand forecasting, production planning, pricing optimization, and revenue opportunity assessment across product segments and geographies.
Clinical Trial & Product Pipeline Assessment
Evaluated ongoing clinical trials, regulatory approvals, and product pipelines for pediatric orthopedic implants, including growth-friendly implants, magnetically controlled growing rods, bioresorbable fixation systems, expandable nails, and patient-specific implants. The study benchmarks innovation maturity, expected launch timelines, and future technology adoption.
Helps manufacturers monitor innovation trends, identify licensing or acquisition opportunities, anticipate competitive launches, and prioritize R&D investments in high-growth product categories.
Frequently Asked Questions About This Report
The global pediatric orthopedic devices market size was valued at USD 4.5 billion in 2025 and is estimated at USD 5.0 billion in 2026.
The global pediatric orthopedic devices market is expected to grow at a compound annual growth rate of 12.7% from 2026 to 2033, reaching USD11.5 billion by 2033.
Some key players operating in the market include Orthofix Medical Inc., OrthoPediatrics Corporation, WishBone Medical, Pega Medical Inc., Arthrex Inc., Johnson & Johnson Services, Inc. (DePuy Synthes), NuVasive Inc., Smith+Nephew, Stryker, Zimmer Biomet, Medtronic, Auxein Medical
Factors such as growing awareness of orthopedic conditions in children and the rise in congenital & developmental disorders, coupled with advancements in design & materials to provide effectiveness & comfort, are driving demand.
The trauma segment accounted for the largest revenue share of 35.9% in 2025, driven by the rising incidence of pediatric fractures, increasing sports injuries, growing use of pediatric trauma implants, and advancements in minimally invasive orthopedic procedures.
Hospitals segment held the largest market share of 64.7% in 2025 while outpatient facilities segment is second fastest growing market
Asia Pacific is expected to register the fastest growth over the forecast period.
North America dominated the pediatric orthopedic devices market with a revenue share of 45.2% in 2025.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


