
- Home
- »
- Consumer F&B
- »
-
Pet Food Market Size, Share And Trends Report, 2026-2033GVR Report cover

Pet Food Market (2026 - 2033)
Size, Share & Trend Analysis Report By Product (Wet Pet Food, Dry Pet Food), By Pet Type (Cats, Dogs), By Category (Traditional Pet Food, Specialist Veterinary Nutrition), By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2025
$128.7BMarket Estimate, 2026
$135.0BMarket Forecast, 2033
$191.2BCAGR, 2026–2033
5.1%Pet Food Market Summary
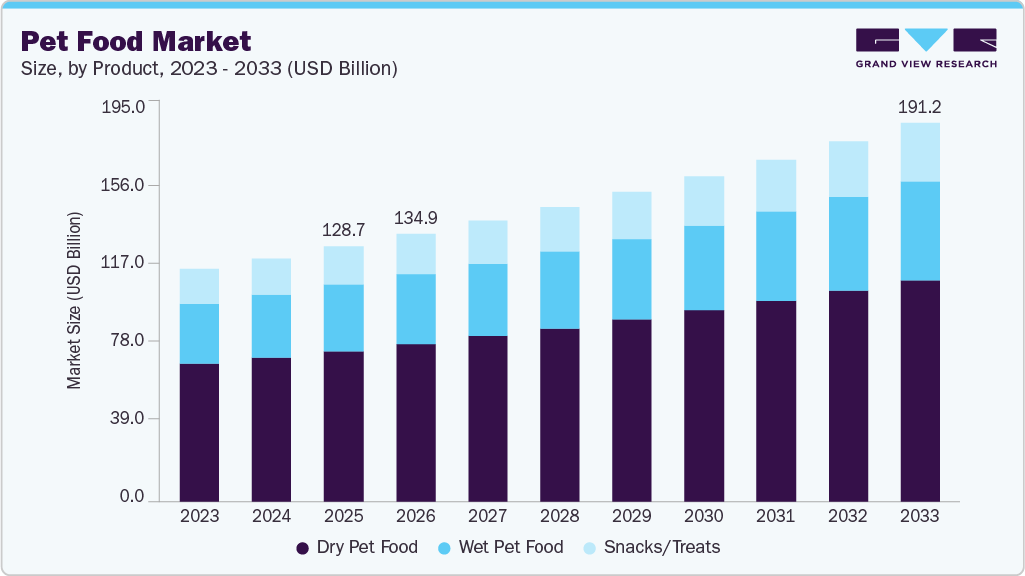
The global pet food market size was valued at USD 128.7 billion in 2025 and is projected to grow from USD 135 billion in 2026 to USD 191.2 billion by 2033, at a CAGR of 5.1% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 41.4% in 2025. The demand for pet food products is anticipated to be driven by growing consumer inclination toward the adoption of pets, along with rising concerns regarding pet health and wellness.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- Based on product: Dry pet food segment dominated the market with a revenue share of over 59.1% in 2025.
- Based on pet type: Dogs segment held the largest revenue market share of 60.8% in 2025.
- Based on category: Traditional pet food segment held the largest revenue market share of 86.2% in 2025.
- By distribution channel: E-commerce segment is expected to exhibit a CAGR of 6.6% over the forecast period.
Regional Highlights
- Largest regional market: North America (41.4% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market Size in 2025: USD 128.7 Billion
- Estimated market size in 2026: USD 135 Billion
- Projected Market Size by 2033: USD 191.2 Billion
- CAGR (2026-2033): 5.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Improvement in overall digestion and performance of pet animals owing to the consumption of nutritious food is also likely to boost the pet food and care products market growth. The pet food products available in the global market rarely vary, prompting manufacturers to include multifunctional and innovative ingredients in their offerings to curb such similarity bias. Convenience is likely to play a vital role in driving this industry, given the increased popularity of prepared pet food and the supporting role of the pet food packaging market.According to the American Pet Products Association (APPA), 90.5 million U.S. households owned a pet in 2024, representing a 7.0% increase from 84.6 million households in 2019 and exceeding the 52.8 million households with children. The trend indicates a substantial consumer base for pet food products.
 To learn more about this report, Download Free Sample Report
Increasing pet humanization and growing awareness of pet health and nutrition are encouraging owners to seek higher-quality, premium, and functional food products for their pets. The availability of organic pet foods in diverse flavors and formulations, along with products containing functional ingredients such as probiotics, prebiotics, antioxidants, and vitamins, is supporting demand for nutritionally enhanced diets. Rising concerns regarding obesity, joint health, digestive health, and overall pet wellness are further encouraging owners to adopt products formulated to address specific nutritional and health needs. This shift toward preventive and wellness-focused pet care is contributing to greater demand for premium and specialized pet food products globally.
Pets also suffer from high blood pressure and diabetes. Pet owners are increasingly adopting nutritious foods manufactured by various companies, owing to rising awareness of the importance of maintaining their pets' health. This shift in consumer preferences is expected to positively impact the pet food additive market over the forecast period.
Diseases, such as osteoarthritis, among dogs and cats have considerably increased, with over 50% of cats and dogs reportedly suffering from it globally. The demand for pet food has grown significantly over the past few years. Large companies manufacture high-quality products, while others are attempting to market less expensive imitations. This is expected to act as a restraining factor for the growth of the frozen pet food market.
Market Dynamics
Growing pet ownership is a major factor supporting demand for pet food products. In the U.S., 71% of households owned a pet in 2025, creating a broad consumer base for commercial pet food. Dogs were present in 51% of households, while cats were present in 37%, supporting sustained demand across major pet categories. Pet owners are also paying greater attention to complete and balanced nutrition, ingredient quality, digestive health, weight management, and overall animal wellness. This shift encourages manufacturers to introduce products tailored to specific breeds, ages, sizes, and nutritional requirements.
The expansion of specialized pet diets is further supporting market consumption. Manufacturers are developing formulations focused on digestive health, skin and coat care, joint support, weight management, and other wellness needs. Growing awareness of preventive pet healthcare is encouraging owners to treat nutrition as an important component of long-term animal care, supporting recurring purchases of commercial pet food products.
Rising pet food costs and increasing price sensitivity among consumers are creating challenges for market participants. In July 2025, 42% of pet owners reported high pet food prices as a significant challenge, while the proportion increased to 45%-46% among lower-income households, according to data reported by Petfood Industry. Persistent cost pressures may encourage consumers to compare prices, purchase value-oriented products, or shift toward lower-priced brands, placing pressure on premium pet food manufacturers.
Demand for products tailored to specific health requirements, breeds, species, and life stages is creating opportunities for more targeted pet food formulations. ADM reported that 95% of functional animal-health supplement purchases are influenced by the product's attribute and primary health-benefit claim, highlighting the importance of targeted functionality. Manufacturers can capitalize by developing formulations for puppies and kittens, senior pets, digestive health, mobility, oral health, and other specific needs.
Analyst Perspective
The pet food market is evolving as pet owners increasingly view nutrition as an important component of preventive health and overall animal well-being. Demand is shifting beyond basic feeding toward functional, life-stage, specialized, and health-oriented formulations, creating opportunities across dry food, wet food, and snacks/treats. Established manufacturers benefit from broad product portfolios, strong distribution networks, and high brand recognition, while smaller and specialized players can compete through differentiated formulations, targeted nutrition, and regional market positioning. Rising ingredient costs and consumer price sensitivity remain key challenges; however, continued interest in pet health, premium nutrition, digestive wellness, healthy aging, and customized diets is expected to support product innovation and category expansion.
Consumer Insights for Pet Food Market
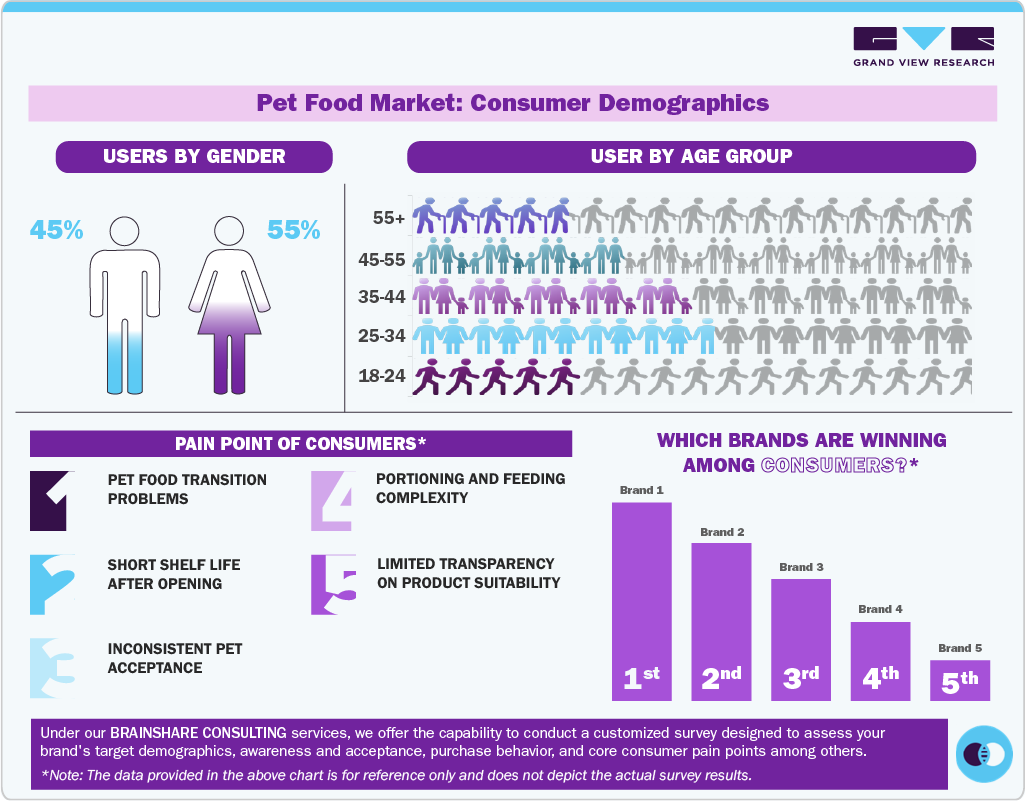
Consumers are increasingly treating pets as family members, which is influencing purchasing decisions toward products that support everyday nutrition, healthy weight, digestion, and overall well-being. Pet owners are also paying greater attention to ingredient lists, protein sources, functional ingredients, and nutritional adequacy when selecting food. Preferences are becoming more individualized, with choices varying according to pet age, breed, size, activity level, and dietary sensitivity.
 To learn more about this report, Download Free Sample Report
Convenience is also shaping purchasing behavior across the pet food category. Consumers are seeking formats that simplify feeding routines, including portion-controlled products, single-serve options, dry food, wet food, and subscription-based purchases. Online shopping provides access to a wider selection of specialized formulations, while established retail channels remain important for routine purchases. Sustainability, ingredient sourcing, and packaging considerations are also becoming relevant factors as consumers evaluate products beyond basic nutritional requirements.
Product Insights
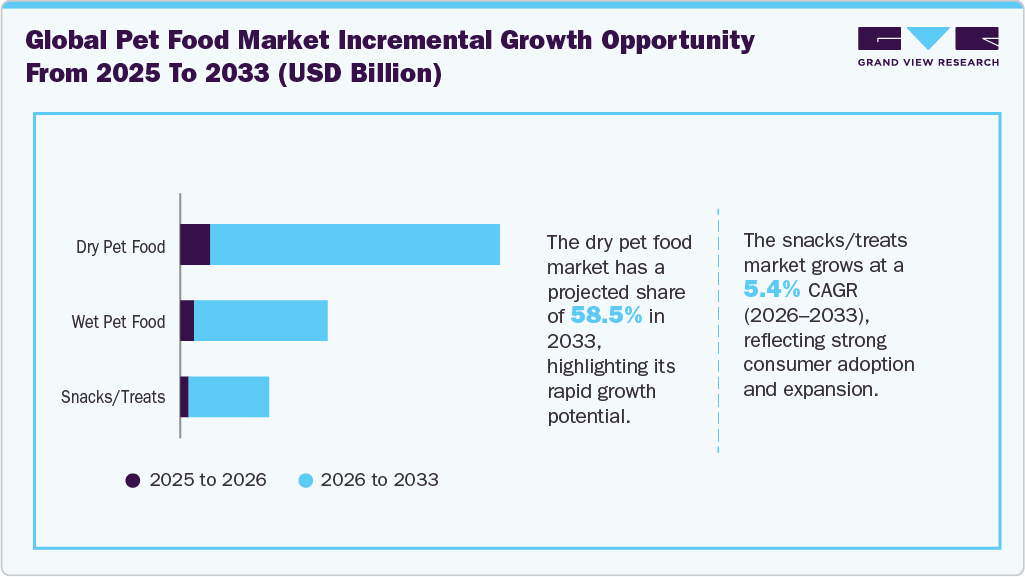
The dry pet food segment dominated the pet food market with a revenue share of 59.1% in 2025, driven by its superior shelf stability, ease of handling, and economic pricing compared to wet and fresh alternatives. High nutrient density and standardized formulations have supported consistent daily feeding practices, particularly among multi-pet households. Additionally, the widespread availability of dry pet food across supermarkets, specialty pet stores, and e-commerce platforms has reinforced its position as the primary feeding option for cost- and convenience-driven consumers, driving growth in the dry pet food market.
 To learn more about this report, Download Free Sample Report
The snacks/treats segment is expected to grow at the fastest CAGR of 5.4% during the forecast period. Growth in the snacks and treats segment has been driven by increasing pet humanization and the use of treats as tools for training, behavioral reinforcement, and emotional bonding. Functional treats that offer dental care, joint support, and digestive benefits have gained traction, supported by a rising willingness among pet owners to spend on non-essential but value-added products. Frequent product launches, flavor innovation, and premium positioning have further accelerated demand within this segment.
Pet Type Insights
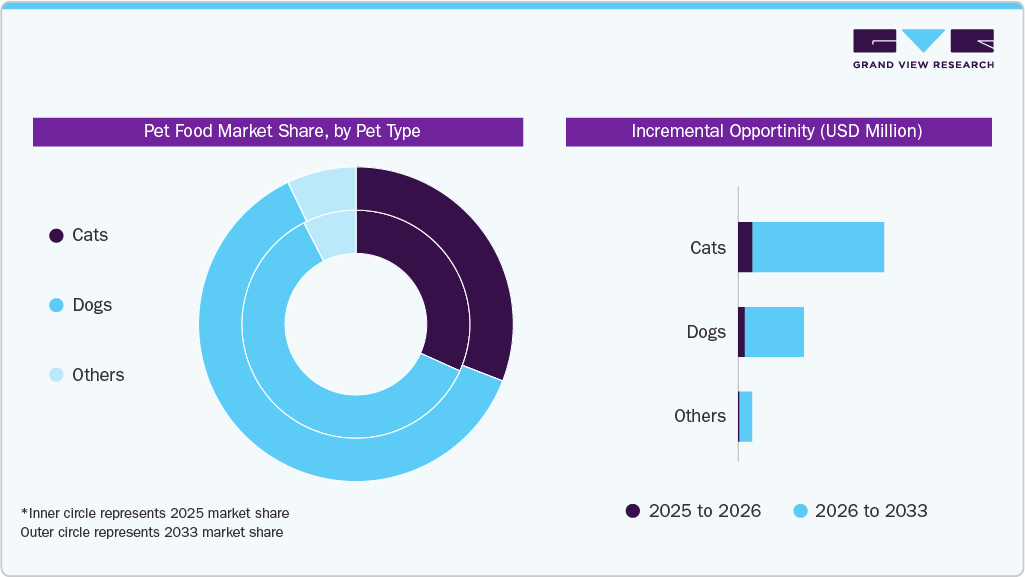
The dogs segment accounted for the largest revenue share, at 60.8%, in 2025, driven by the widespread adoption of dogs as household companions and the growing focus on their nutrition and overall well-being. As dog ownership expands, pet owners are increasingly seeking convenient, balanced, and nutritionally complete food options that fit into daily feeding routines. The rising preference for premium and functional diets, including products formulated with targeted nutritional benefits, is further supporting global demand for dog food.
 To learn more about this report, Download Free Sample Report
The cats segment is projected to expand at a CAGR of 4.7% from 2026 to 2033, supported by the increasing adoption of cats as household pets. Rising cat ownership is contributing to greater demand for convenient, nutritious, and balanced food products tailored to feline dietary needs. Growing awareness of pet nutrition and wellness is also encouraging owners to explore premium and specialized cat food formulations, supporting continued segment growth.
Category Insights
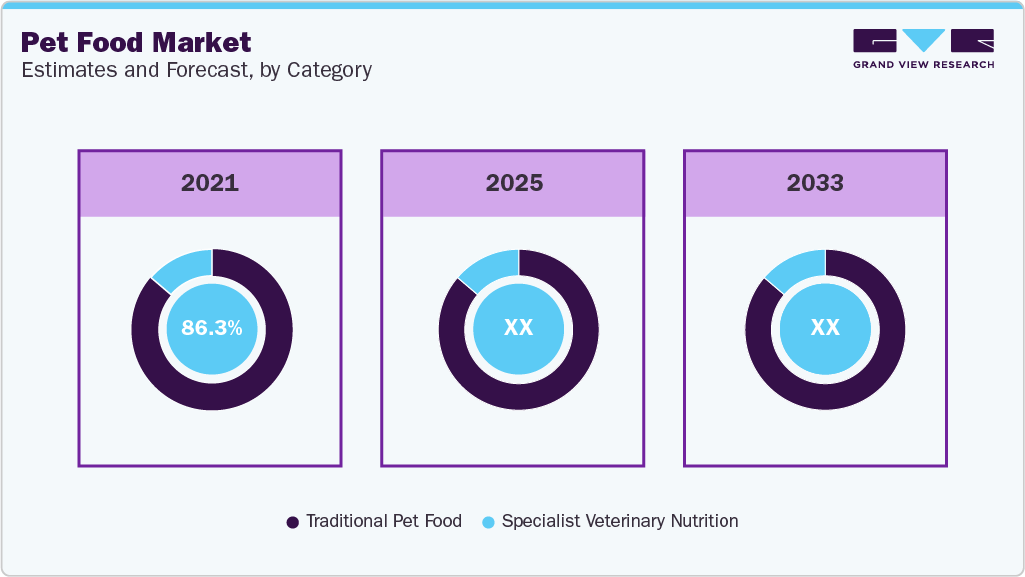
The traditional pet food segment held the largest revenue market share of 86.2% in 2025. The traditional pet food segment has continued to dominate due to established consumer familiarity, affordability, and broad acceptance across diverse income groups. These products benefit from long-standing brand trust, standardized nutritional profiles, and extensive distribution through mass retail channels. Routine feeding habits and limited switching behavior among price-sensitive consumers have further sustained high volume consumption of traditional pet food offerings.
 To learn more about this report, Download Free Sample Report
The specialist veterinary nutrition segment is expected to grow at a significant CAGR of 5.2% over the forecast period, driven by rising awareness of pet health management and increased diagnosis of chronic conditions such as obesity, renal disorders, food sensitivities, and gastrointestinal issues. Veterinarian recommendations and prescription-based feeding have strengthened consumer confidence in clinically formulated diets. Growing emphasis on preventive care and longevity in companion animals has further encouraged the adoption of targeted veterinary nutrition products.
Distribution Channel Insights
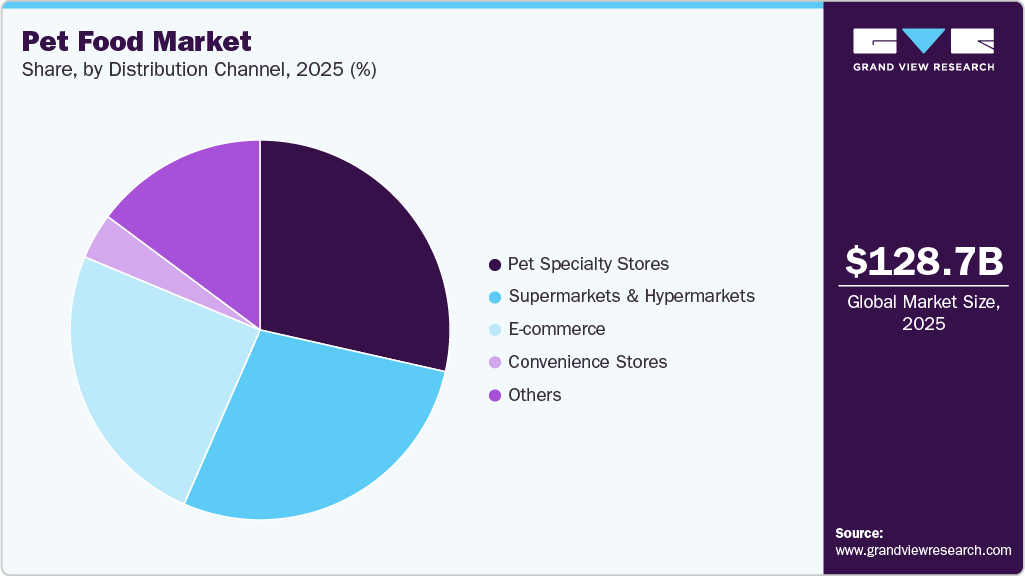
The pet specialty stores segment held the largest revenue market share of 28.5% in 2025. Pet specialty stores are staffed with knowledgeable personnel who offer expert advice on pet nutrition, health, and wellness. This personalized service attracts pet owners who prefer tailored recommendations for their pets, particularly for wet food products that cater to specific dietary needs. In-store experts provide advice on choosing the right food for pets with special dietary requirements, such as grain-free, hypoallergenic, or senior pet formulas. This personalized service enhances customer trust and drives repeat sales.
 To learn more about this report, Download Free Sample Report
The e-commerce segment is expected to grow at the fastest CAGR of 6.6% over the forecast period. The increasing shift towards online shopping is a significant driver for pet food sales. E-commerce offers unparalleled convenience, allowing customers to order products from home and have them delivered to their doorstep, often with subscription options for recurring purchases. Online pet retailers like Zooplus and Bitiba have established a strong presence across Europe, offering a wide range of pet wet food products. These platforms offer free shipping on bulk orders, subscription models for regular deliveries, and competitive pricing, making them a go-to option for pet owners seeking convenience and savings.
Regional Insights
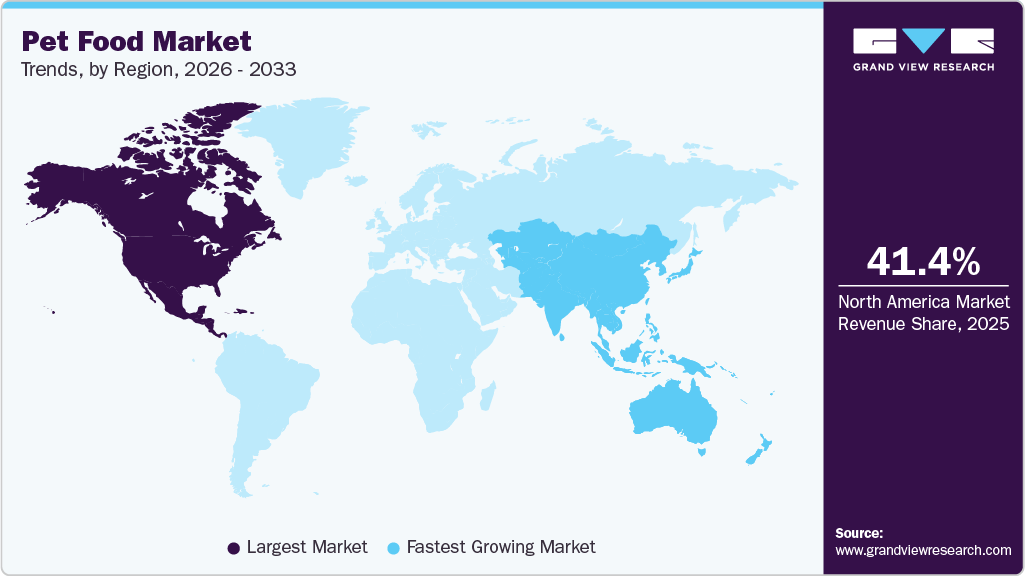
The pet food market in North America accounted for the largest revenue share of 41.4% in 2025. North America’s strong share has been driven by high pet ownership rates, robust consumer spending on premium pet nutrition, and well-established distribution channels spanning specialty retailers, supermarkets, and online platforms. Advanced e-commerce penetration, widespread adoption of value-added and functional pet food formulations, and greater awareness of pet health and wellness have collectively elevated market demand. Additionally, frequent product innovations and strong brand loyalty among U.S. and Canadian consumers have reinforced North America’s pet food market leadership.
 To learn more about this report, Download Free Sample Report
U.S. Pet Food Market Trends
The pet food market in the U.S. led the North American industry in 2025, holding the largest market share with 85.0% of the region’s total revenue. The U.S. industry has been propelled by an increasing trend toward pet humanization, with owners prioritizing nutrition, safety, and premium quality in their purchasing decisions. Rising disposable incomes, growth in single-person and dual-income households, and heightened focus on pet health conditions such as weight management and digestive wellness have driven demand for specialized and premium formulations. The proliferation of online retail and subscription services has further enhanced accessibility and frequency of purchases.
Europe Pet Food Market Trends
The pet food market in Europe accounted for the revenue share of 29.4% in 2025. The industry is growing due to a combination of trends such as humanization, health-consciousness, convenience, and sustainability. These drivers have led to the rise of premium, specialized, and eco-friendly options in the wet pet food category, making it a dynamic and competitive market. Many consumers are willing to spend more on wet pet food that promises superior quality, natural ingredients, and health benefits. Pet food brands are focusing on transparency in ingredients, free from artificial additives or preservatives. Brands such as Lily’s Kitchen have gained popularity in Europe by offering wet pet food made from human-grade ingredients with clear, simple labeling. The trend mirrors the clean eating trend seen in human food markets.
The UK pet food market accounted for the largest share of 25.6% of the European market in 2025. High demand for vegan and plant-based products with customized meal preferences by owners is estimated to fuel the demand for natural and organic pet food products. As per the UK Pet Food Report 2024, the UK has a total population of 13.5 million and 12.5 million dogs and cats, respectively, and is one of the prominent markets for pet food in Europe in 2024. According to the UK Pet Food Manufacturers Association (PFMA), 82 members of the trade body account for more than 90% of the market share. The pet food market in the UK complies with stringent standards and over 50 different legislations to manufacture wet pet food products of the highest quality and safety.
Asia Pacific Pet Food Market Trends
The pet food market in the Asia Pacific is expected to grow at the fastest CAGR of 6.8% over the forecast period. The growth has been supported by expanding pet ownership, particularly in urban and affluent households, along with rising awareness of pet nutrition and welfare. Increased adoption of Western feeding practices and growing middle-class spending on premium and customized pet food products have amplified market expansion. E-commerce growth and the rising availability of international brands have also contributed to accelerated regional CAGR.
The China pet food market led the Asia Pacific industry in 2025, holding the largest market share with 34.3% of the region’s total revenue. China has emerged as a key contributor to the Asia Pacific region’s growth, driven by booming pet ownership, especially among younger urban consumers. A shift toward premium, imported, and functional pet foods, supported by expanding retail and online channels, has strengthened market presence. Rising consumer awareness of pet dietary health and increased expenditure on nutrition, grooming, and healthcare have also enhanced China’s influence within the APAC pet food landscape.
Central & South America Pet Food Market Trends
The pet food market in Central & South America is expected to grow at a CAGR of 6.3% over the forecast period. The region is witnessing rising pet ownership, greater attention to animal health, and growing awareness of balanced pet nutrition. Consumers are showing stronger interest in products formulated with quality ingredients, functional benefits, and specific nutritional profiles for different life stages. Urbanization and changing household structures are also encouraging demand for convenient packaged pet food products. In addition, the expansion of modern retail and e-commerce channels is improving product availability across the region. Manufacturers are responding by introducing varied formulations, premium product options, and specialized diets to address evolving preferences among pet owners.
Middle East & Africa Pet Food Market Trends
The pet food market in the Middle East & Africa is projected to grow at a CAGR of 5.6% over the forecast period. The growth is supported by rising pet ownership, increasing awareness of pet health, and growing interest in nutritionally balanced food products. Pet owners are paying greater attention to ingredient quality, dietary needs, and products designed for specific life stages and health requirements. Similar to the Central & South American market, the MEA is witnessing the urbanization and changing lifestyles, boosting the demand for convenient packaged pet food. In addition, the expansion of supermarkets, specialty pet stores, and online platforms is improving access to a wider range of products. Manufacturers are responding with diverse formulations, functional nutrition, and specialized offerings to meet evolving preferences across the region.
Key Pet Food Company Insights
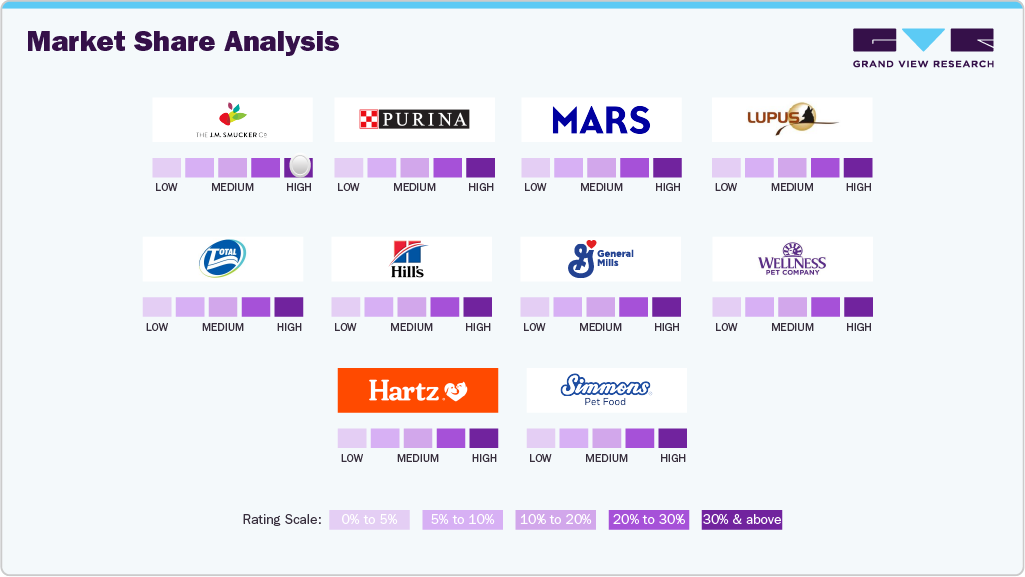
The competitive landscape of this market is moderately consolidated with the presence of multinationals striving to fulfill high demand from large customers and an end-user base. Key industry participants are inclined to adopt new marketing strategies and use advanced technologies to strengthen their customer base and increase revenue in the near future. In addition, companies are undertaking expansion, mergers, and acquisitions as part of their strategic initiatives.
Industry participants are inclined to invest heavily in research and technology to advance processes and create new recipes, which are manufactured using varied and specialized ingredients. Key manufacturers are also focused on developing innovative formulas to provide diverse, high-quality food for pets and farm animals. Industry players also utilize raw materials, applying criteria to meet demand and regulations, in both domestic and international markets.
 To learn more about this report, Download Free Sample Report
Key Pet Food Companies
The following key companies have been profiled for this study on the pet food market.
-
The J.M. Smucker Company
-
Nestle Purina
-
Mars, Incorporated
-
LUPUS Alimentos
-
Total Alimentos
-
Hill’s Pet Nutrition, Inc.
-
General Mills Inc.
-
WellPet LLC
-
The Hartz Mountain Corporation
-
Simmons Foods Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (The J.M. Smucker Company, Nestlé Purina, Mars, Incorporated, Hill’s Pet Nutrition, Inc., General Mills Inc.)
- Expand pet food portfolios across dry food, wet food, snacks, treats, and specialized nutrition; invest in functional formulations, product innovation, brand development, and broad retail and e-commerce distribution. Strengthen portfolios through premium, life-stage, and health-focused products.
- Strong brand recognition, extensive product portfolios, large-scale manufacturing capabilities, broad distribution networks, established customer relationships, and significant resources for product development and marketing.
- High operating and marketing costs, complex global supply chains, exposure to fluctuations in ingredient and packaging costs, and pricing pressure from private-label and specialized pet food brands.
Emerging Players (LUPUS Alimentos, Total Alimentos, WellPet LLC, The Hartz Mountain Corporation, Simmons Foods Inc.)
- Focus on specialized and value-oriented pet food products, regional market expansion, private-label manufacturing, differentiated formulations, and targeted nutrition. Strengthen manufacturing capabilities and distribution partnerships to increase market reach.
- Greater flexibility in product development, specialized manufacturing capabilities, competitive pricing, regional market knowledge, and the ability to respond quickly to changing consumer and retailer requirements.
- Smaller global distribution footprint, lower brand recognition in some international markets, comparatively limited financial resources, and greater dependence on regional markets and selected product categories.
Recent Developments
-
In June 2025, General Mills expanded its Blue Buffalo brand with a fresh, minimally processed pet food line aimed at the rapidly growing fresh pet food category valued at billions and designed to appeal to owners treating pets like family.
-
In 2024, Nestlé Purina PetCare commissioned a 1.3-million-sq-ft advanced manufacturing plant in North Carolina to boost production efficiency, sustainability goals, and capacity for its pet food portfolio.
Pet Food Market Report Scope
Report Attribute
Details
Market size in 2025
USD 128.7 billion
Estimated market size in 2026
USD 135 billion
Projected market size by 2033
USD 191.2 billion
Growth rate (revenue)
CAGR of 5.1%
Actuals
2021 - 2025
Forecast period
2026 - 2033
Quantitative (Revenue & Volume) units
Revenue in USD billion, Volume in Kilo tons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, volume forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, pet type, category, distribution channel, region
Regional scope
North America; Europe; Asia-Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; Japan; Australia & New Zealand; India; South Korea; Brazil; Saudi Arabia
Key companies profiled
The J.M. Smucker Company; Nestle Purina; Mars, Incorporated; LUPUS Alimentos; Total Alimentos; Hill’s Pet Nutrition, Inc.; General Mills Inc.; WellPet LLC; The Hartz Mountain Corporation; Simmons Foods Inc.
Customization scope
Free report customization (equivalent up to 8 analysts’ working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Pet Food Market Report Segmentation
This report forecasts revenue growth at the global, regional and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global pet food market report on the basis of product, pet type, category, distribution channel, and region.
-
Product Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
Wet Pet Food
-
Dry Pet Food
-
Snacks/Treats
-
-
Pet Type Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
Cats
-
Dogs
-
Others (birds, rodents, rabbits, turtles, and fish)
-
-
Category Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
Traditional Pet Food
-
Specialist Veterinary Nutrition
-
-
Distribution Channel Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
Supermarkets & Hypermarkets
-
Convenience Stores
-
E-commerce
-
Pet Specialty Stores
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
Japan
-
India
-
China
-
Australia & New Zealand
-
South Korea
-
-
Central & South America
-
Brazil
-
-
Middle East & Africa
-
Saudi Arabia
-
-
Research Methodology
The pet food market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each pet food segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Product
Revenue capture definition
Wet Pet Food
This segment includes the sales of vitamin B3 derived from naturally occurring raw materials for use in dietary supplements, functional foods, and premium nutritional formulations. It is preferred in clean-label and naturally positioned products.
Dry Pet Food
This segment includes the sales of chemically manufactured vitamin B3 used in pharmaceuticals, food fortification, dietary supplements, and animal feed. It is widely adopted due to its cost efficiency, consistent quality, and large-scale production availability.
Snacks/Treats
This segment includes the sales of pet food products offered as treats, rewards, or supplementary feeding items between regular meals. It includes biscuits, chews, dental treats, training treats, and other snack products for companion animals.
Pet Type
Revenue capture definition
Cats
This segment includes the sales of pet food products formulated specifically for cats based on their nutritional and dietary requirements. It includes wet food, dry food, snacks, treats, and specialized cat food formulations.
Dogs
This segment includes the sales of pet food products formulated specifically for dogs based on their nutritional and dietary requirements. It includes wet food, dry food, snacks, treats, and specialized dog food formulations.
Others
This segment includes the sales of pet food products formulated for companion animals other than cats and dogs. It includes food products for birds, fish, rabbits, and other household pets.
Estimation Model
Title
Guiding Question
Description
Raw Material Layer Where is pet food production initiated?
Evaluates the availability of key inputs such as animal proteins, grains, fats, oils, vitamins, minerals, functional ingredients, and other materials required for pet food manufacturing, establishing the industry’s production base.
Production Layer How much pet food enters commercial supply?
Applies manufacturing capacity, processing efficiency, product yields, quality standards, and regional production output to estimate commercially available pet food supply.
Behavioural Layer Which pet categories and product formats utilize pet food?
Applies product- and pet-type-specific consumption shares across dogs, cats, and other companion animals, covering wet food, dry food, and snacks/treats to determine end-use demand.
Monetisation Layer How much revenue is generated?
Multiplies consumption volumes by regional average selling prices while incorporating product format, pet type, quality tier, distribution channel, and regional market dynamics to estimate market value.
Customization Table
Client Request
Customization Delivered
Value Adds
Pet Food Consumption & Category Assessment
Assessed demand across dogs, cats, and other companion animals, examining consumption by dry food, wet food, and snacks/treats and evaluating differences in feeding preferences and product usage.
Helps identify the most attractive consumption categories and areas with greater potential for product development and market expansion.
Pet Nutrition & Product Innovation Analysis
Evaluated developments in functional nutrition, specialized diets, healthy aging, digestive support, immunity, joint health, natural ingredients, and tailored feeding solutions.
Provides visibility into changing nutritional priorities and supports identification of emerging product concepts and formulation opportunities.
Supply, Manufacturing & Competitive Assessment
Examined ingredient sourcing, processing capabilities, production structures, distribution networks, pricing considerations, and competitive positioning across major regional markets.
Helps businesses evaluate supply-side constraints, identify operational opportunities, and strengthen strategic positioning within the pet food industry.
Frequently Asked Questions About This Report
North America dominated with a 41.4% revenue share in 2025.
Traditional pet food segment held the largest revenue market share of 86.2% in 2025.The traditional pet food segment has continued to dominate due to established consumer familiarity, affordability, and broad acceptance across diverse income groups.
The pet specialty stores segment held the largest revenue market share of 28.5% in 2025 while e-commerce segment is expected to be the fastest-growing market.
Asia Pacific is the fastest-growing region over the forecast period.
The dry pet food segment led with a 59.1% revenue share in 2025, while snacks/treats is the fastest-growing segment.
The global pet food market is expected to grow at 5.1% from 2026 to 2033, reaching USD 191.2 billion by 2033.
Key players include The J.M. Smucker Company; Nestle Purina; Mars, Incorporated; LUPUS Alimentos; Total Alimentos; Hill’s Pet Nutrition, Inc.; General Mills Inc.; WellPet LLC; The Hartz Mountain Corporation; Simmons Foods Inc.
Key factors include growing consumer inclination toward the adoption of pets, along with rising concerns regarding pet health and wellness.
The global pet food market size was valued at USD 128.7 billion in 2025 and is estimated at USD 135.0 billion in 2026.
About the Author(s)
Consumer F&B Research Team
Consumer Goods · Consumer F&BThis report was authored by the consumer f&b research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the consumer f&b segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


