
- Home
- »
- Medical Devices
- »
-
Pharmaceutical Contract Sales Organizations Market Report 2033GVR Report cover

Pharmaceutical Contract Sales Organizations Market (2026 - 2033)
Size, Share & Trends Analysis Report By Service (Personal, Non-personal Promotion), By Therapeutic Area, By End Use (Pharma, Biopharma Companies), By Region, And Segment Forecasts
Market Size, 2025
$11.9BMarket Estimate, 2026
$12.9BMarket Forecast, 2033
$23.8BCAGR, 2026–2033
9.1%Pharmaceutical Contract Sales Organizations Market Summary
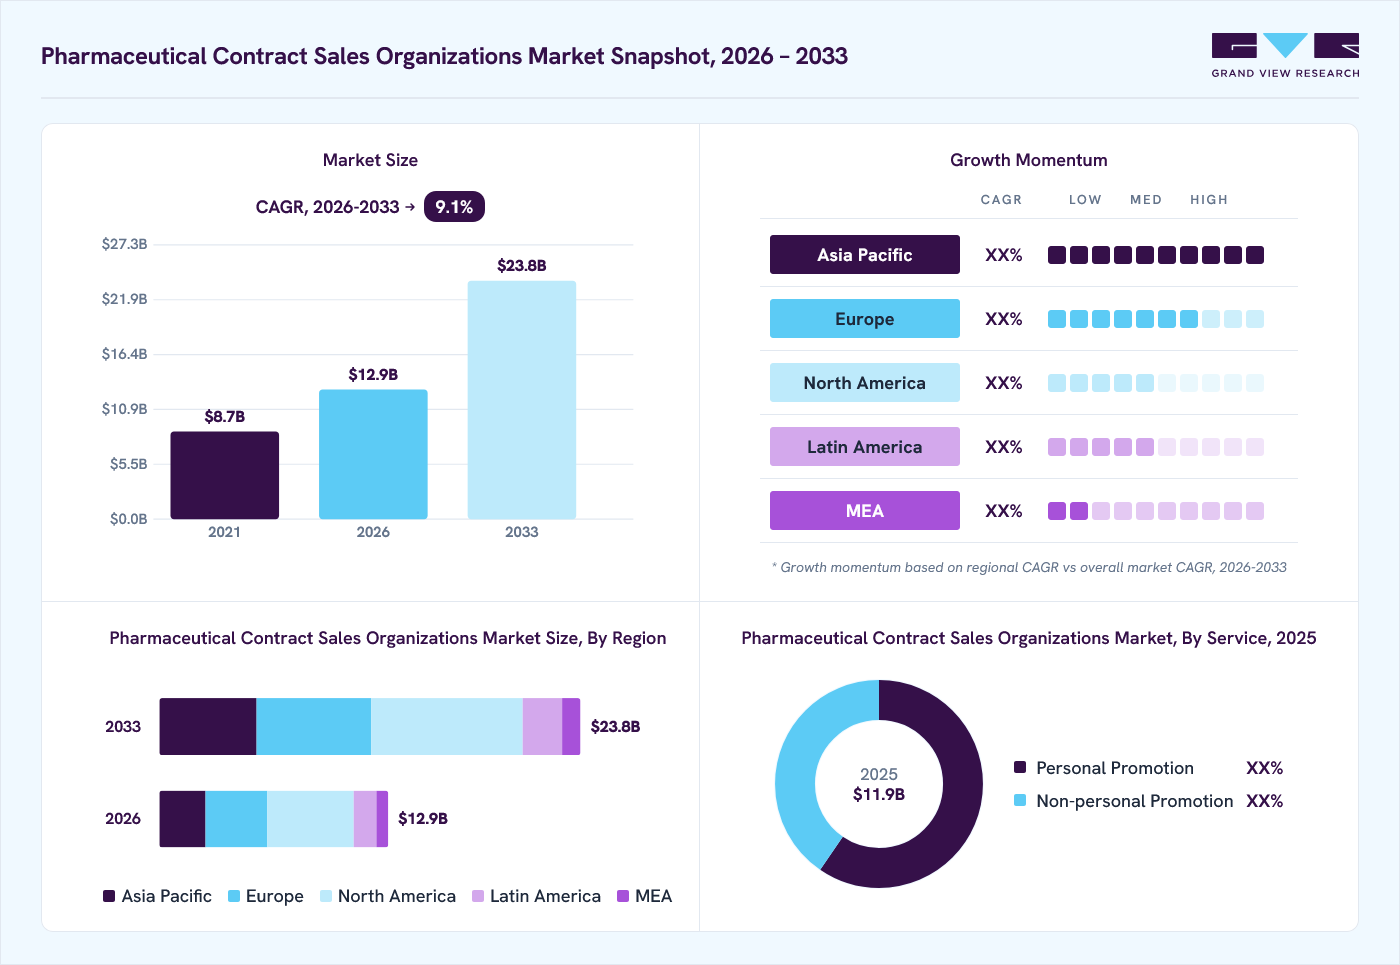
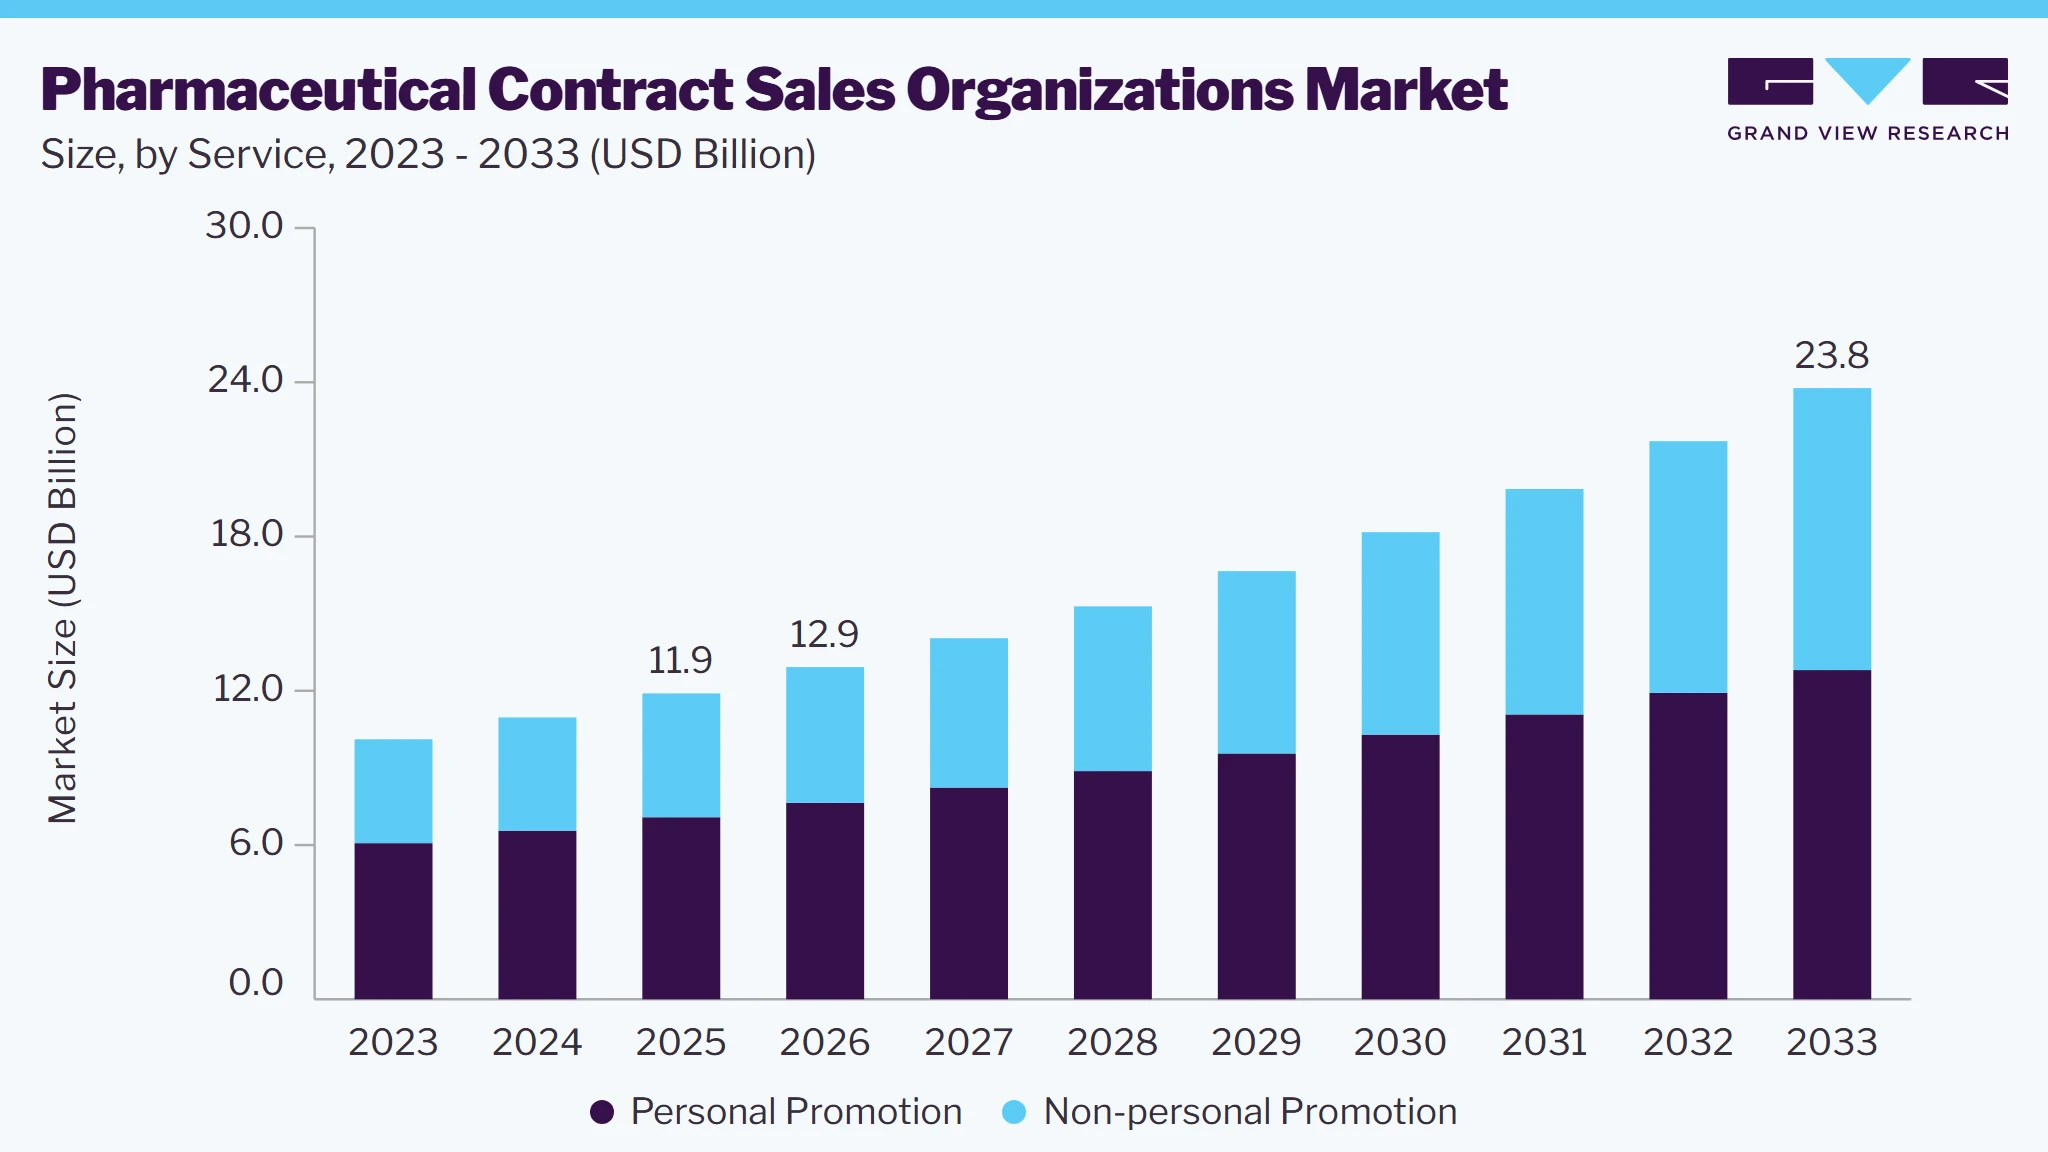
The global pharmaceutical contract sales organizations market size was valued at USD 11.9 billion in 2025 and is projected to grow from USD 12.9 billion in 2026 to USD 23.8 billion by 2033, at a CAGR of 9.1% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 37.9% in 2025. The market growth is driven by the increasing number of new drug launches, a rise in pharmaceutical R&D activities, growing demand to reduce costs associated with in-house sales, rising complexity of drug commercialization, increasing regulatory oversight, and the ongoing need for cost optimization.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By service: Personal promotion segment held the largest market share of 59.5% in 2025.
- By therapeutic area: Oncology segment held the largest market share of 32.8% in 2025.
- By end use: Pharmaceutical companies segment held the largest market share of 53.1% in 2025.
Regional Highlights
- Largest regional market: North America (37.9% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. dominated North America with the largest revenue share in 2025.
Market Size & Forecast
- Market size in 2025: USD 11.9 Billion
- Estimated market size in 2026: USD 12.9 Billion
- Projected market size by 2033: USD 23.8 Billion
- CAGR (2026-2033): 9.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
 To learn more about this report, Download Free Sample Report
Market Dynamics
The pharmaceutical contract sales organizations industry is experiencing steady growth, driven by the increasing number of new drug launches and the expansion of pharmaceutical research and development activities worldwide. The pharmaceutical and biopharmaceutical companies introduce more specialty therapies, biologics, and rare disease treatments, and also rely on contract sales organizations to accelerate commercialization and optimize physician engagement. Similarly, companies are seeking to reduce the high fixed costs associated with maintaining large in-house sales forces, making outsourced commercial services a cost-effective alternative.
The rising complexity of drug commercialization, including specialized therapeutic expertise, omnichannel engagement, and evolving market access requirements, is boosting demand for experienced CSOs. In addition, increasing regulatory oversight requires highly trained sales professionals capable of ensuring compliant promotional practices and scientific communication. These factors, coupled with the industry's continued focus on operational efficiency, commercial flexibility, and faster market penetration, are encouraging greater adoption of outsourced sales, key account management, medical affairs, and digital engagement services across global pharmaceutical markets.
The rapid adoption of artificial intelligence (AI) across pharmaceutical commercialization is emerging as a major driver for the pharmaceutical contract sales organizations industry. AI-powered customer relationship management (CRM) platforms, predictive analytics, and machine learning algorithms enable CSOs to optimize territory planning, identify high-value healthcare professionals, personalize physician engagement, and improve sales force productivity. In addition, generative AI and intelligent virtual assistants also support sales representatives by delivering real-time scientific information, automated content generation, and next-best-action recommendations during customer interactions. For instance, in June 2026, Vanigent BioPharm launched Vanitrack, an AI-powered compliance platform that automates expense management, compliance reporting, and sales documentation, improving pharmaceutical sales productivity.
AI-driven omnichannel engagement enhances communication through email, virtual detailing, chatbots, and remote interactions, improving the customer experience while ensuring regulatory compliance. In addition, AI automates sales reporting, compliance documentation, expense management, and performance analytics, reducing administrative workloads and enabling representatives to focus on high-value commercial activities. As pharmaceutical companies increasingly prioritize data-driven commercialization strategies and operational efficiency, demand for technologically advanced contract sales organizations equipped with AI-enabled capabilities continues to accelerate globally.
Stringent regulatory requirements governing pharmaceutical promotion and interactions with healthcare professionals present a significant restraint on the pharmaceutical contract sales organizations industry. The CSOs must comply with evolving regulations related to promotional practices, transparency reporting, data privacy, anti-bribery laws, and scientific communication across multiple jurisdictions. In addition, frequent regulatory updates require continuous training, compliance monitoring, and investment in digital governance systems, increasing operational costs. Any non-compliance can result in financial penalties, reputational damage, and contract losses for both CSOs and their pharmaceutical clients. Moreover, varying country-specific promotional regulations limit standardized commercial strategies, making multinational sales operations more complex and resource-intensive, thereby slowing market expansion and reducing operational efficiency.
Emerging pharmaceutical markets present a significant growth opportunity for the pharmaceutical contract sales organizations industry. Rapid healthcare infrastructure development, increasing pharmaceutical consumption, expanding health insurance coverage, and rising investments by multinational pharmaceutical companies are accelerating demand for outsourced commercial services across Asia-Pacific, Latin America, the Middle East, and Africa. Thus, entering these markets requires strong local regulatory knowledge, established relationships with healthcare providers, and region-specific commercial strategies.
In addition, CSOs address these challenges by providing experienced local sales teams, multilingual field representatives, market access expertise, and country-specific commercialization support, enabling pharmaceutical companies to expand efficiently without building extensive in-house sales organizations. Their understanding of local prescribing practices, reimbursement environments, and distribution networks reduces market entry risks while accelerating product adoption. As pharmaceutical companies seek geographic diversification and access to high-growth patient populations, demand for CSOs with strong regional expertise and scalable commercial capabilities is expected to grow substantially, creating long-term expansion opportunities for the market.
Market Characteristics & Concentration
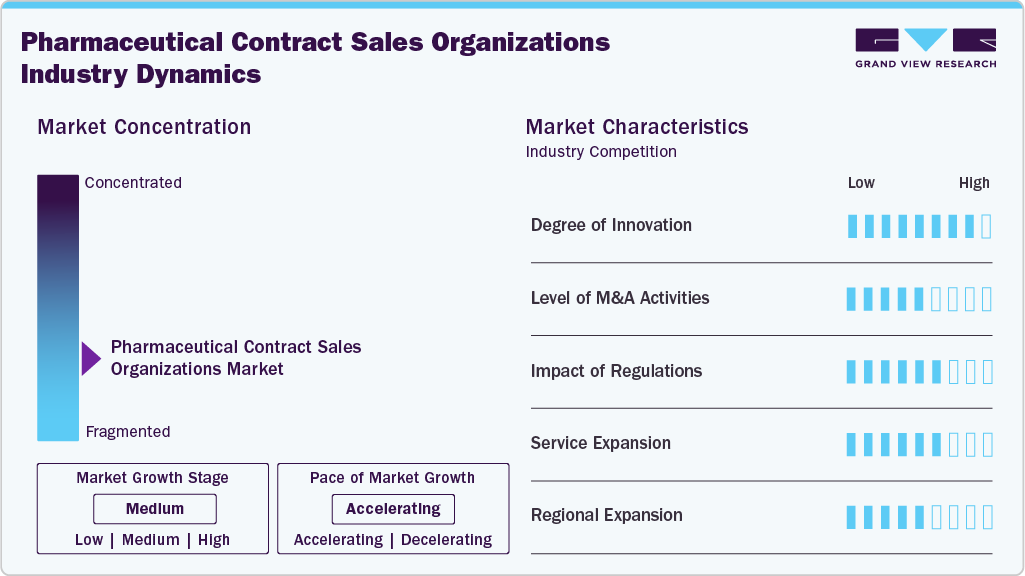
The market is characterized by increasing outsourcing of commercial operations, growing adoption of AI-enabled omnichannel engagement, demand for flexible sales force models, stringent regulatory compliance, expansion of medical affairs services, and rising specialization in high-value therapeutic areas. Long-term partnerships and performance-based commercial models are becoming key competitive differentiators.
The market is rapidly evolving with the adoption of AI-driven analytics, omnichannel engagement, and automation. Companies like IQVIA, EPS Corp., and Peak Pharma Solutions are integrating machine learning and real-time data insights to enhance sales efficiency and optimize engagement with healthcare professionals (HCPs). In addition, the market is advancing through innovations in AI-powered sales analytics, omnichannel engagement platforms, predictive customer targeting, digital compliance tools, and virtual Medical Science Liaison (MSL) services.
 To learn more about this report, Download Free Sample Report
The market is witnessing high M&A activity, as leading CSOs seek to expand their service portfolios and technological capabilities. Companies are acquiring specialized sales organizations, medical affairs providers, and technology firms to strengthen integrated commercialization services. In addition, strategic partnerships and acquisitions enable broader client portfolios, improved operational scale, enhanced market competitiveness, and comprehensive end-to-end commercial support for pharmaceutical manufacturers.
Regulatory requirements significantly influence CSO operations by governing promotional practices, interactions with healthcare professionals, transparency reporting, pharmacovigilance, and data privacy. Compliance with FDA, EMA, Sunshine Act, GDPR, and country-specific regulations requires continuous employee training, digital compliance systems, and standardized operating procedures, increasing operational complexity while ensuring ethical, compliant, and scientifically accurate pharmaceutical commercialization.
CSOs are expanding into medical affairs, market access, omnichannel marketing, remote Medical Science Liaison services, patient support programs, digital engagement, commercial analytics, and key account management. This broader service portfolio enables clients to outsource comprehensive commercialization activities, improve operational efficiency, accelerate product launches, and enhance customer engagement throughout the product lifecycle.
The key CSO players are expanding aggressively into Asia-Pacific, Latin America, and the Middle East, where the pharmaceutical market is experiencing rapid growth. CMIC Holdings Co., Ltd. has strengthened its presence in Japan and China, while IQVIA and Syneos Health continue to expand across Latin America.
Analyst Perspective
The pharmaceutical contract sales organizations market is expanding as pharma companies increasingly outsource sales functions to reduce operational costs and enhance market reach and flexibility. In addition, a rising number of product launches, patent expirations, and growing focus on specialty and niche therapeutics are driving demand for skilled, scalable sales forces. Furthermore, CSOs offer faster market penetration, reduced fixed costs, and access to specialized therapeutic expertise, particularly benefiting small and mid-sized biopharma companies. Thus, increasing adoption of hybrid engagement models and data-driven sales strategies is further strengthening market growth across developed and emerging pharmaceutical markets.
Impact of U.S. Tariffs on Pharmaceutical Contract Sales Organizations Market
U.S. tariffs on imported pharmaceutical products, active pharmaceutical ingredients (APIs), and healthcare-related components are transforming commercialization strategies across the pharmaceutical industry and indirectly influencing the pharmaceutical contract sales organization (CSO) market. The rising import costs are encouraging pharmaceutical companies to localize manufacturing, diversify supply chains, and accelerate the commercialization of domestically produced products. This transition increases demand for outsourced sales organizations to support new product launches, physician engagement, market access, and regional expansion within the U.S.
Similarly, companies facing higher production costs are under pressure to optimize operating expenses, driving greater adoption of flexible, outsourced commercial models instead of maintaining large in-house sales teams. However, tariffs may delay product launches and reduce promotional budgets for companies facing higher manufacturing costs, particularly those that rely on imported raw materials. Thus, tariffs create short-term commercial uncertainty and are expected to strengthen long-term demand for cost-efficient, scalable, and locally focused contract sales organization services.
Technological Advancements
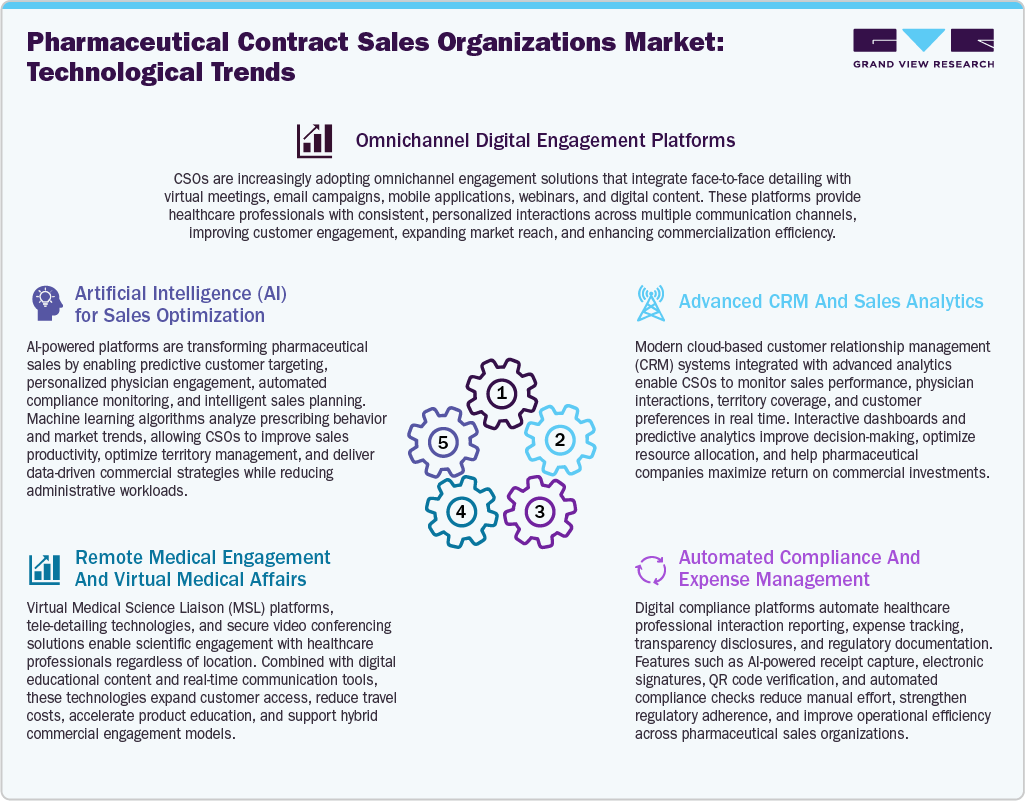
The market is witnessing technological advancements that are transforming the market by enhancing commercial efficiency, customer engagement, and regulatory compliance. One of the advancements is artificial intelligence (AI) and machine learning, which enable predictive sales analytics, physician segmentation, personalized engagement strategies, and optimized territory management, improving sales productivity and commercial outcomes. In addition, cloud-based customer relationship management (CRM) platforms, integrated with real-time analytics, provide actionable insights into healthcare professionals' interactions, enabling data-driven decision-making and performance optimization.
 To learn more about this report, Download Free Sample Report
In addition, omnichannel engagement technologies combine face-to-face detailing with virtual meetings, email campaigns, mobile applications, and digital content to deliver consistent customer experiences across multiple communication channels. Furthermore, automated compliance platforms that incorporate AI, electronic signatures, QR code verification, and digital expense management simplify transparency reporting and reduce administrative burdens while ensuring regulatory compliance. In addition, remote Medical Science Liaison (MSL) platforms, tele-detailing solutions, and virtual scientific engagement tools expand healthcare professionals' access, reduce operational costs, and support hybrid commercialization models, driving greater adoption of outsourcing across the pharmaceutical industry.
Pricing Model Analysis
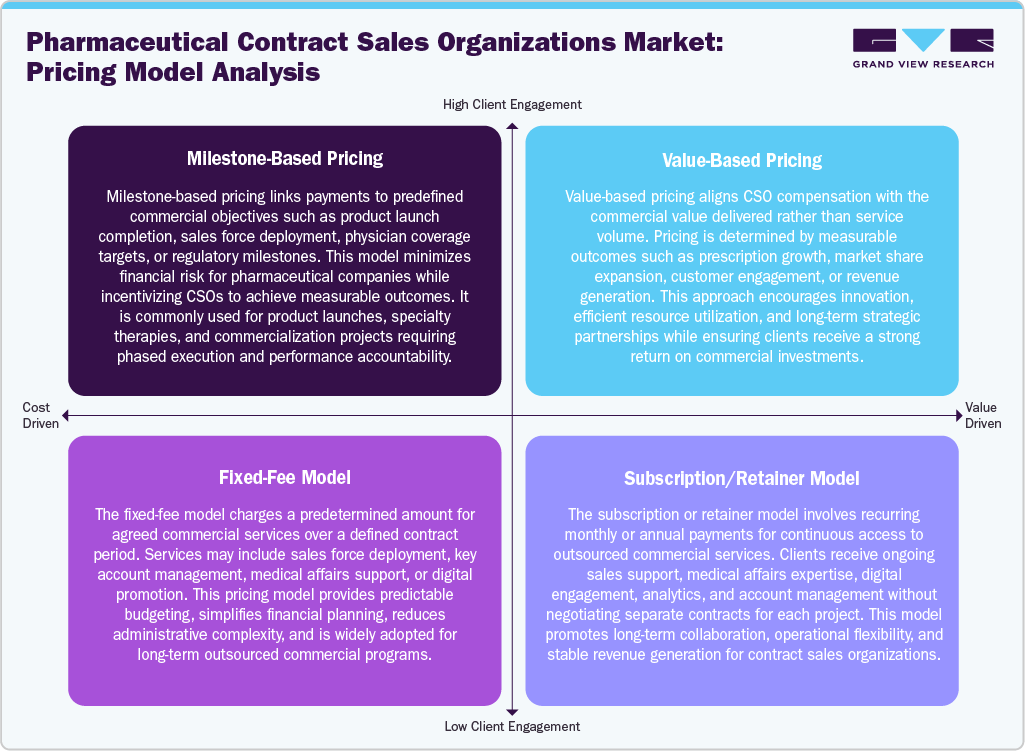
The market employs multiple pricing models to align commercial services with client objectives and project complexity. In milestone-based pricing, payments are made for predefined achievements, such as product launches, sales force deployment, or physician coverage targets, ensuring accountability and reducing financial risk. Whereas value-based pricing ties compensation to measurable outcomes, such as prescription growth, market penetration, or revenue generation, thereby encouraging high-performance commercial execution. The fixed-fee model provides a predetermined contract value for defined services such as sales force management, key account support, and medical affairs, enabling predictable budgeting and long-term planning.
 To learn more about this report, Download Free Sample Report
Meanwhile, the subscription or retainer model offers continuous access to commercial services through recurring monthly or annual payments, supporting ongoing physician engagement, omnichannel promotion, analytics, and account management. These flexible pricing approaches allow pharmaceutical and biopharmaceutical companies to optimize commercialization costs, improve operational efficiency, and select engagement models that best match their product lifecycle, commercialization strategy, and business objectives.
Service Insights
The personal promotion segment led the market with the largest revenue share of 59.5% in 2025. The growth is driven by increasing investment by pharmaceutical companies in R&D, making commercial marketing crucial to overall revenue growth. Companies are prioritizing new product launches to strengthen their market presence,with an increasing focus on year-on-year revenue expansion. In addition, personal promotion, which includes face-to-face interactions, sales representatives, and customized marketing strategies, remains the preferred approach for building strong relationships with healthcare professionals (HCPs) and driving prescription growth
The non-personal promotion segment is projected to grow at the fastest CAGR during the forecast period, driven by the increasing adoption of digital marketing strategies, AI-driven sales automation, and omnichannel engagement. Pharmaceutical companies are shifting towards remote detailing, virtual interactions, email marketing, and AI-powered content personalization to reach healthcare professionals (HCPs) more efficiently. The rising preference for cost-effective and scalable marketing solutions, coupled with the growing influence of data-driven insights and targeted advertising, is accelerating the expansion of this segment.
Therapeutic Area Insights
The oncology segment led the market with the largest revenue share of 32.8% in 2025. According to January 2026 estimates, the U.S. is expected to record approximately 2,114,850 new cancer diagnoses and 626,140 cancer deaths. Thus, the rising cancer burden in the U.S. continues to accelerate demand for specialized pharmaceutical commercialization services, strengthening growth opportunities for pharmaceutical contract sales organizations. The segment’s growth is also driven by the rising prevalence of cancer, ongoing advances in targeted therapies, and a surge in drug approvals. In addition, pharmaceutical companies are investing heavily in oncology R&D, leading to a higher demand for specialized sales representatives and tailored marketing strategies. The complexity of oncology treatments, including immunotherapies, biologics, and precision medicine, makes highly trained sales teams essential for effective communication with healthcare professionals (HCPs).
The neurology segment is growing at a considerable CAGR during the forecast period, driven by the rising prevalence of neurological disorders such as Alzheimer's, Parkinson's, epilepsy, and multiple sclerosis. The increasing pipeline activity in CNS therapeutics, the growing complexity of neurology drug launches, and the need for specialized sales expertise to engage neurologists effectively are boosting demand for contract sales organizations. In addition, rising investments in rare neurological disease treatments and orphan drugs, coupled with pharmaceutical companies' focus on cost-efficient commercialization strategies, are further accelerating outsourced sales support within this specialized therapeutic segment.
End Use Insights
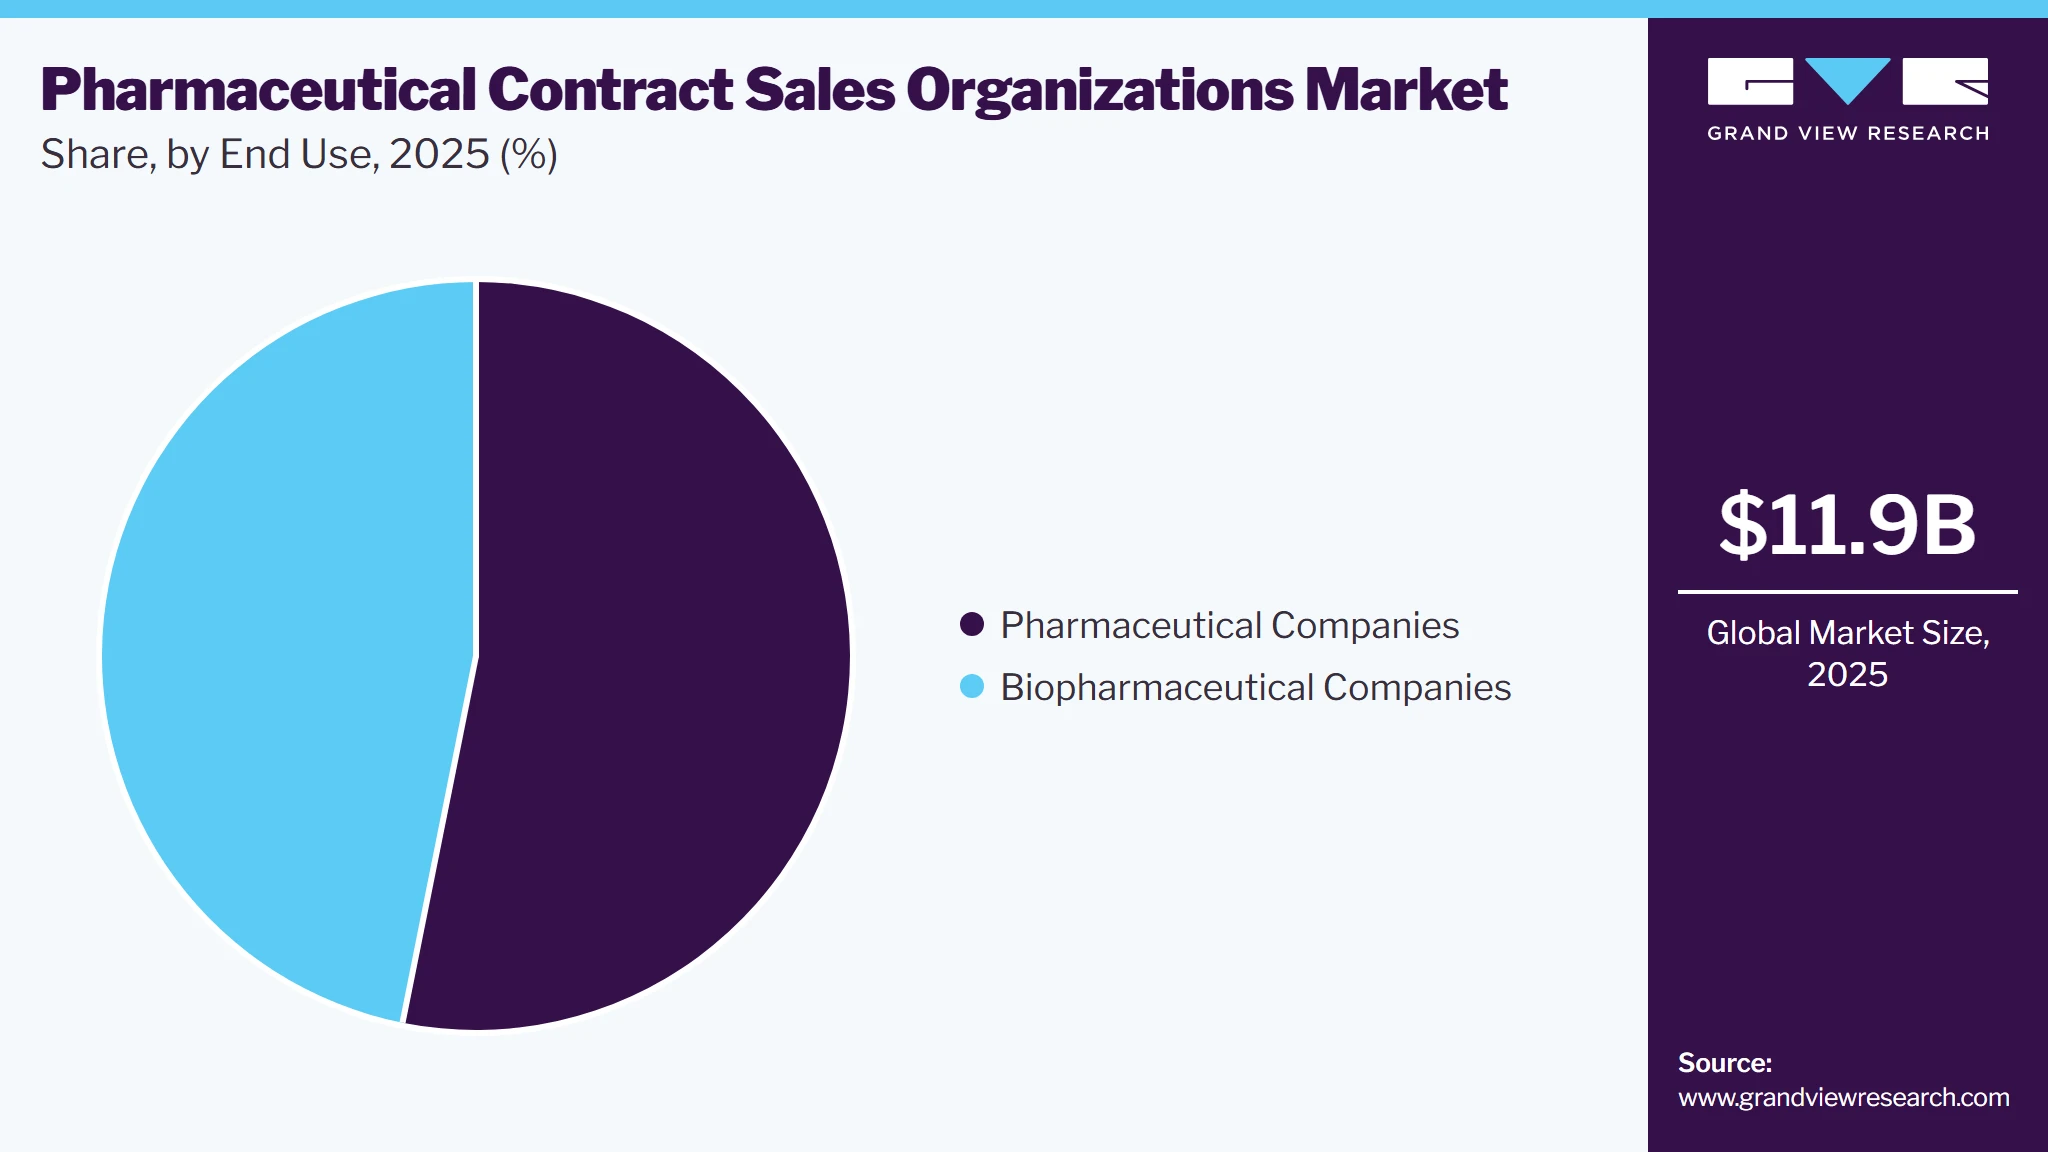
The pharmaceutical companies segment led the market with the largest revenue share of 53.1% in 2025. The market growth is driven by increasing demand for cost-effective sales solutions, expanding drug pipelines, and rising commercialization efforts. As pharmaceutical firms focus on maximizing market reach and optimizing sales strategies, the reliance on contract sales organizations has grown with an increasing trend. The high costs associated with in-house sales teams, coupled with the demand for specialized sales expertise in complex therapeutic areas, have further strengthened this segment’s dominance.
 To learn more about this report, Download Free Sample Report
The biopharmaceutical companies segment is anticipated to grow at the fastest CAGR during the forecast period, due to their increasing reliance on outsourced commercialization expertise. Many emerging and mid-sized biopharma companies lack an extensive in-house sales infrastructure, making CSOs a cost-effective solution for product launches, physician engagement, market access, and medical affairs support. The rapid growth of biologics, biosimilars, cell and gene therapies, and orphan drugs further increases demand for specialized sales teams with therapeutic expertise, omnichannel engagement capabilities, and flexible commercialization models across global markets.
Regional Insights
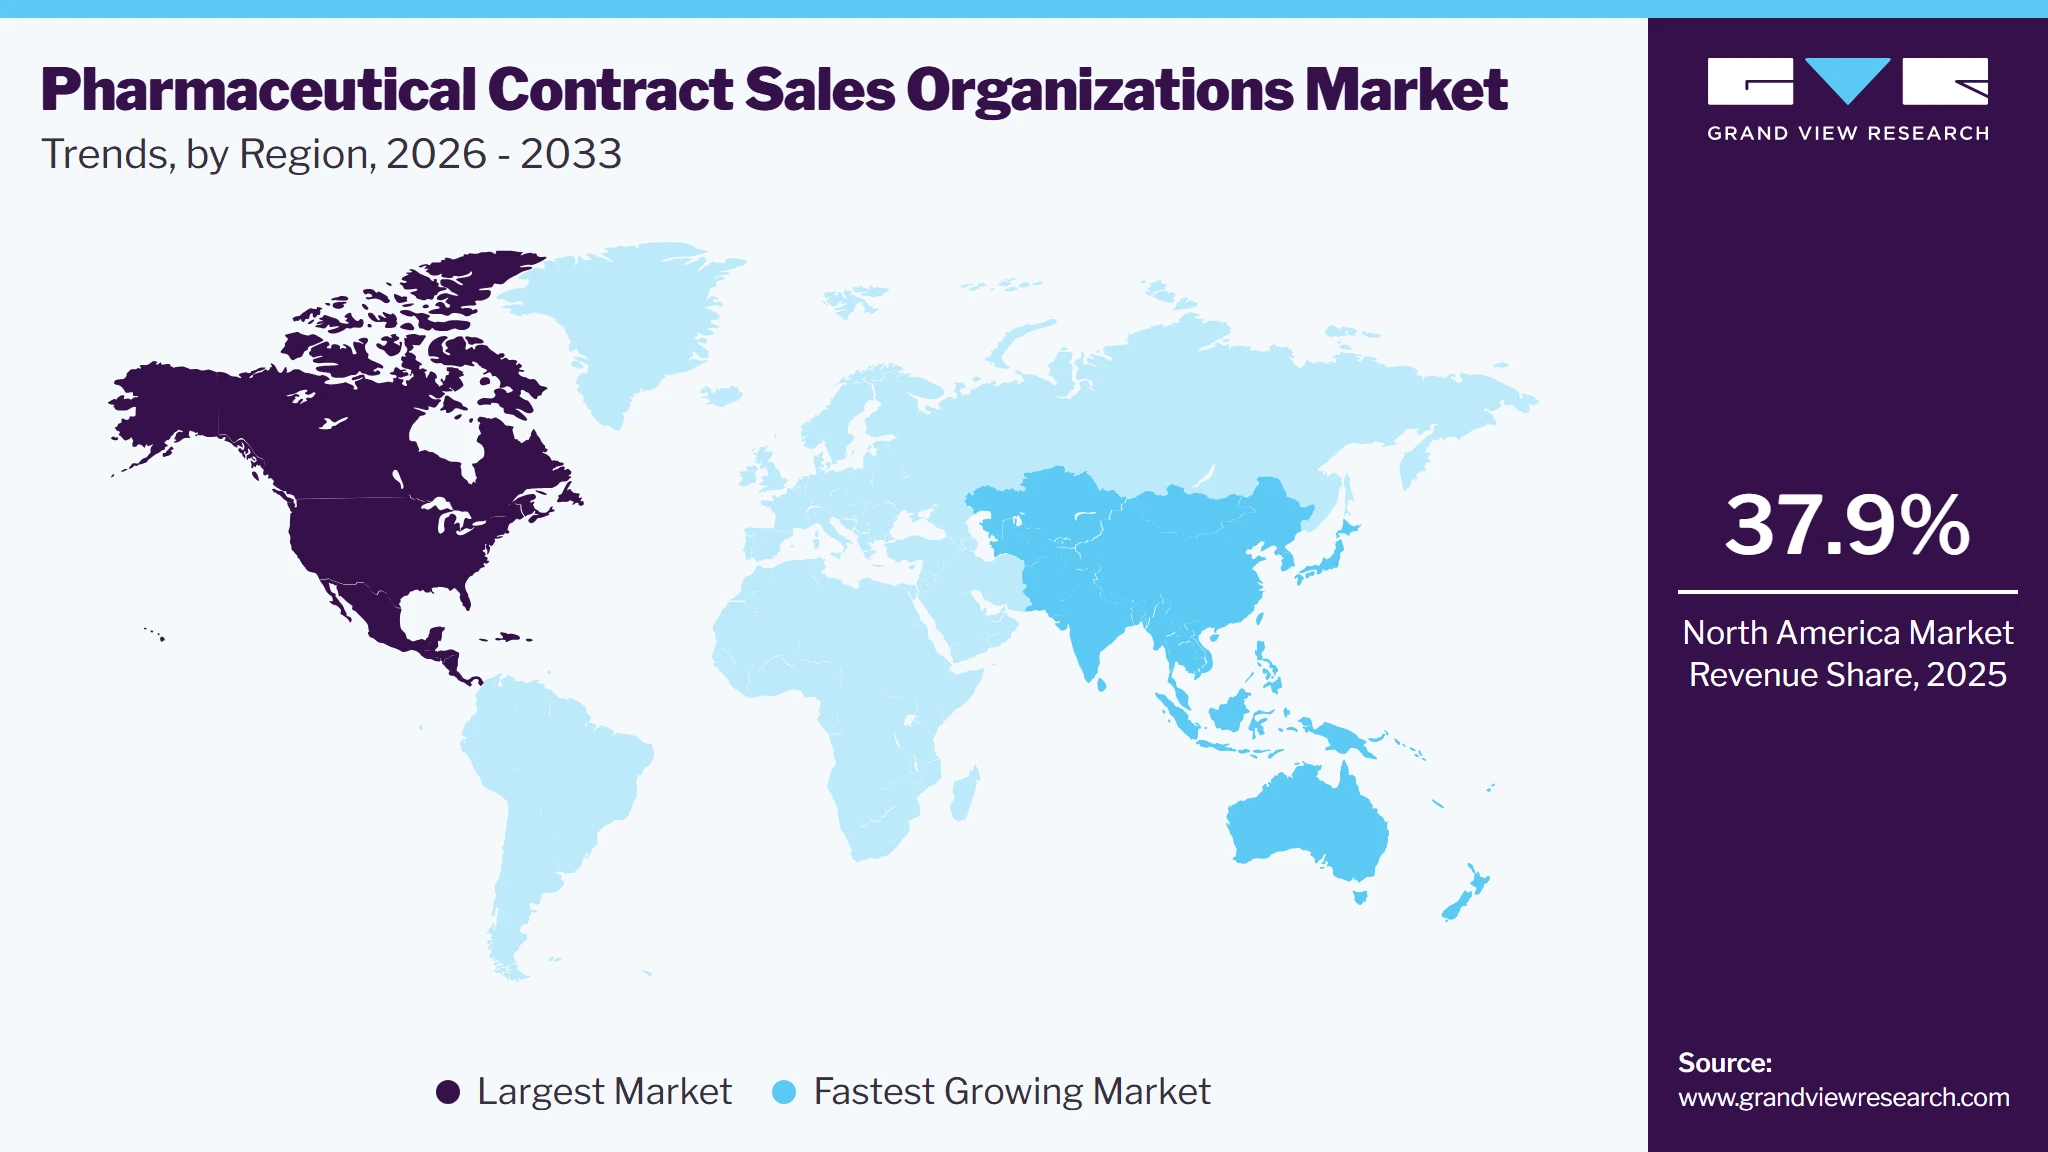
North America dominated the global pharmaceutical contract sales organizations market with the largest revenue share of 37.9% in 2025. This can be attributed to the strong presence of major pharmaceutical and biopharmaceutical companies, high healthcare expenditures, and advanced commercialization strategies. The region's well-established regulatory framework and increasing adoption of digital sales and omnichannel engagement have further strengthened its dominance.
 To learn more about this report, Download Free Sample Report
U.S. Pharmaceutical Contract Sales Organizations Market Trends
The pharmaceutical contract sales organizations market in the U.S. accounted for the largest revenue share in North America in 2025, owing to the strong presence of pharmaceutical and biopharmaceutical companies, rising drug approvals, and growing demand for cost-effective sales solutions. The growing trend of outsourcing among pharma firms to optimize commercial operations and reduce overhead costs has further fueled market expansion. In addition, strategic initiatives are boosting market growth. For instance, in February 2026, Vanigent BioPharm launched Vanitrack, an AI-powered compliance and expense management platform for pharmaceutical sales teams. The solution automates reporting, compliance checks, and expense management, improving sales force productivity and accelerating digital transformation across the market.
The Canada pharmaceutical contract sales organizations market is driven by a growing biopharmaceutical sector, increasing commercialization of specialty and rare disease therapies, and rising outsourcing by mid-sized pharmaceutical companies seeking flexible sales models. In addition, strong regulatory standards, expanding adoption of digital and omnichannel engagement, and increasing demand for bilingual sales support enhance CSO opportunities. Furthermore, Canada's universal healthcare system and expanding clinical research ecosystem encourage sustained demand for specialized contract sales and medical affairs services.
Europe Pharmaceutical Contract Sales Organizations Market Trends
The pharmaceutical contract sales organizations market in Europe is experiencing growth due to the increasing adoption of outsourcing strategies, the expanding biopharmaceutical sector, and rising demand for specialized sales expertise. Pharmaceutical companies are focusing on cost reduction and operational efficiency, leading to a greater reliance on CSOs for commercialization, market access, and digital sales engagement.
The UK pharmaceutical contract sales organizations marketheld a significant share in Europe in 2025. The country’s market growth is due to its expanding pharmaceutical and biopharmaceutical sectors, increasing adoption of digital sales strategies, and rising demand for cost-effective commercialization solutions. With a strong focus on outsourcing sales operations, pharmaceutical companies in the UK are leveraging contract sales organizations to enhance market reach, optimize engagement with healthcare professionals (HCPs), and improve sales efficiency.
The pharmaceutical contract sales organizations market in Germany is anticipated to grow significantly over the forecast period. The country’s growth is due to the strong focus on cost efficiency, regulatory compliance, and digital transformation is driving pharmaceutical companies to collaborate with CSOs for market access, sales optimization, and omnichannel engagement.
Asia PacificPharmaceutical Contract Sales Organizations Market Trends
The pharmaceutical contract sales organizations market in the Asia Pacific is projected to grow at the fastest CAGR over the forecast period. The market growth is driven by the rapid expansion of the pharmaceutical and biotechnology industries, increased drug commercialization, and rising demand for cost-effective sales solutions. Growing healthcare investments, a large patient population, and a surge in clinical trials are further accelerating market growth.
The China pharmaceutical contract sales organizations market is expected to grow at a significant CAGR over the forecast period. The growth of the market is due to rising investments in biopharmaceutical research, growing demand for specialized sales expertise, and government initiatives supporting healthcare innovation, which are further driving market growth.
The pharmaceutical contract sales organizations market in Japan is witnessing significant growth over the forecast period. The growth of the market is driven by the expansion of the pharmaceutical and biopharmaceutical industries, an increase in drug launches, and rising demand for specialized sales expertise. A rapidly aging population, along with a growing prevalence of chronic diseases, is fueling the need for effective commercialization and market access strategies.
The India Pharmaceutical contract sales organizations marketis witnessing considerable growth due to the rapid expansion of domestic pharmaceutical manufacturing, increasing commercialization of specialty therapies, and growing outsourcing of sales and medical affairs functions. In addition, favorable government initiatives and expanding global partnerships further strengthen demand for outsourced commercial services. For instance, in June 2026, the Union Commerce and Industry Minister announced that global pharmaceutical companies would expand partnerships and strengthen their commercial presence in India. Such an initiative is expected to accelerate demand for contract sales organizations supporting product launches, physician engagement, and market expansion.
Latin America Pharmaceutical Contract Sales Organizations Market
The pharmaceutical contract sales organizations market in Latin America is projected to grow at a substantial CAGR over the forecast period. The growth in the region is due to the expanding pharmaceutical industry, increasing drug commercialization efforts, and rising demand for cost-effective sales solutions. A growing population, improving healthcare infrastructure, and higher investments in pharmaceutical R&D are further driving market growth.
The Brazil pharmaceutical contract sales organizations market is expanding rapidly. The growth is driven by the expansion of the pharmaceutical and biopharmaceutical industries, increased drug commercialization, and rising demand for outsourced sales solutions. A large patient population, improving healthcare access, and growing government support for the pharmaceutical sector are driving market growth.
Middle East And AfricaPharmaceutical Contract Sales Organizations Market Trends
The pharmaceutical contract sales organizations market in the Middle East & Africa accounted for a significant revenue share in 2025. The growth in the region is driven by expanding pharmaceutical investments, increasing demand for specialty medicines, healthcare modernization, and growing outsourcing of commercial operations by multinational companies. The competition remains moderate, with global CSOs partnering with regional distributors and local commercial service providers to strengthen market access. In addition, digital physician engagement, regulatory expertise, and therapeutic specialization are becoming key differentiators as pharmaceutical commercialization accelerates across the region.
The South Africa pharmaceutical contract sales organizations market is witnessing growth due to well-developed private healthcare networks and increasing penetration of multinational pharmaceutical companies. In addition, growing demand for market access expertise, hospital-focused sales teams, and regulatory navigation services is expanding outsourcing opportunities. Furthermore, competition centers on firms that offer localized commercial intelligence, multilingual field-force capabilities, and strong relationships with private hospital groups, distributors, and specialist physicians to improve market penetration and product adoption.
Thepharmaceutical contract sales organizations market in Saudi Arabia is driven by the expansion of healthcare transformation under Vision 2030, increasing localization of pharmaceutical manufacturing, and rising market entry by multinational drug companies. In addition, the demand is growing for outsourced launch excellence, hospital account management, and market access support as specialty medicines expand.
Key Pharmaceutical Contract Sales Organizations Company Insights
The pharmaceutical contract sales organizations (CSO) Market is moderately consolidated, with leading players competing through specialized therapeutic expertise, flexible field force models, digital engagement capabilities, and global commercial networks. Companies strengthen market positions through strategic partnerships, acquisitions, AI-enabled sales solutions, and expansion into emerging markets. Long-term contracts, regulatory compliance, and value-added commercial services remain key differentiators influencing market share and competitive advantage. For instance,
Key Pharmaceutical Contract Sales Organizations Companies
The following key companies have been profiled for this study on the global pharmaceutical contract sales organizations market:
-
CMIC Holdings Co., Ltd.
-
Axxelus
-
EPS Corp.
-
QFR Solutions
-
MaBico
-
Mednext Pharma Pvt. Ltd.
-
Peak Pharma Solutions Inc.
-
IQVIA, Inc.
-
Promoveo Health
-
Syneous Health
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: IQVIA Inc.
- Mature players strengthen market leadership by expanding therapeutic-specialized sales teams, integrating AI-driven customer engagement platforms, and offering omnichannel commercialization services.
- Long-term outsourcing agreements, strategic partnerships with pharmaceutical and biopharmaceutical companies, expansion, continuous sales force training, and data-driven performance analytics to improve customer retention, operational efficiency, and scalable commercial execution.
- Established players possess extensive global sales networks, experienced therapeutic specialists, strong regulatory knowledge, and proven commercialization expertise.
- Their ability to rapidly deploy dedicated sales teams, provide integrated medical affairs and digital engagement solutions, and maintain long-standing relationships with major pharmaceutical companies enables higher customer retention, stronger contract wins, and sustainable competitive differentiation.
- Mature organizations often face high operational costs, dependence on large pharmaceutical clients, and challenges in rapidly adapting to evolving digital commercialization models.
Emerging Players: Promoveo Health
- Emerging players focus on niche therapeutic expertise, flexible sales force deployment, and cost-effective commercial solutions tailored to small and mid-sized pharmaceutical and biotechnology companies.
- Digital engagement platforms, remote detailing, AI-enabled sales analytics, and strategic partnerships to expand market presence. Emphasizing agility, personalized services, and rapid scalability enables them to compete with established contract sales organizations.
- Emerging players gain a competitive advantage through specialized therapeutic knowledge, flexible engagement models, competitive pricing, and faster decision-making.
- Their ability to deliver customized commercial solutions, adopt digital-first sales strategies, and rapidly deploy dedicated or shared sales teams makes them attractive partners for biotech firms launching innovative therapies with limited in-house commercial infrastructure.
- Emerging players often face limited geographic reach, smaller sales force capacity, and lower brand recognition compared with established CSOs. Restricted financial resources can constrain investments in digital platforms, advanced analytics, and large-scale commercial infrastructure.
Recent Developments
-
In April 2026, Catalent expanded its commercial licensing agreement with Cartherics to support cGMP iPSC-derived CAR-NK cell therapy manufacturing. The partnership strengthens advanced biologics manufacturing capabilities, accelerates commercialization of cell therapies, and reinforces CDMO demand for integrated GMP manufacturing platforms in the biologics market.
-
In April 2026, Thermo Fisher Scientific agreed to sell its microbiology business to Astorg for USD 1.075 billion. The divestiture enables Thermo Fisher to optimize its portfolio, strengthen strategic investments in high-growth biopharma services, and intensify competition by increasing its focus on contract development and manufacturing capabilities.
Pharmaceutical Contract Sales Organizations Market Report Scope
Report Attribute
Details
Market size in 2025
USD 11.9 billion
Estimated market size in 2026
USD 12.9 billion
Projected market size by 2033
USD 23.8 billion
Growth rate
CAGR of 9.1% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Service, therapeutic area, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait; Oman; Qatar.
Key companies profiled
CMIC Holdings Co., Ltd.; Axxelus; EPS Corp.; QFR Solutions; MaBico; Mednext Pharma Pvt. Ltd.; Peak Pharma Solutions Inc.; IQVIA, Inc.; Promoveo Health; Syneous Health
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Pharmaceutical Contract Sales Organizations Market Report Segmentation
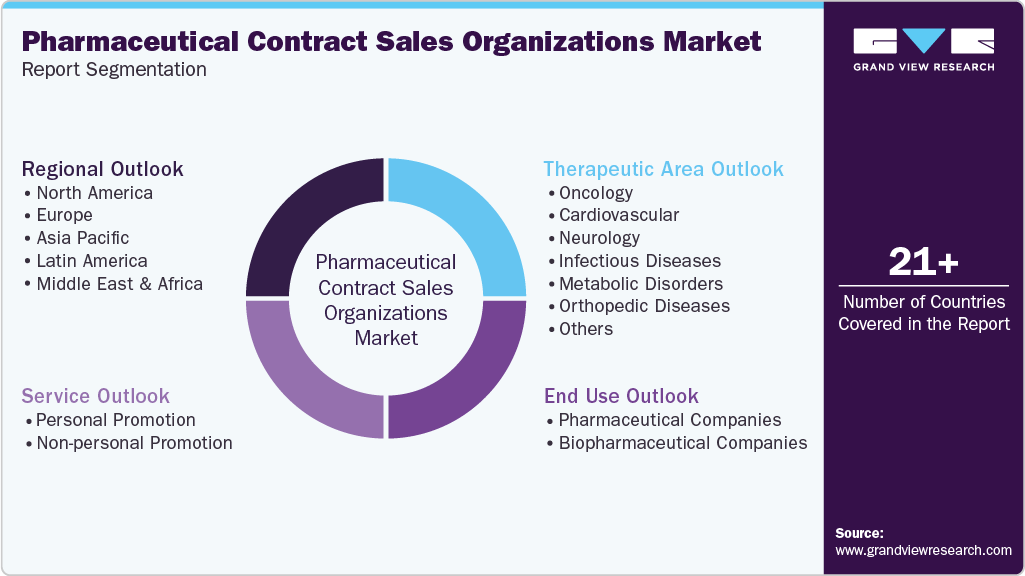
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global pharmaceutical contract sales organizations market report based on service, therapeutic area, end use, and region.
 To learn more about this report, Download Free Sample Report
-
Service Outlook (Revenue, USD Billion, 2021 - 2033)
-
Personal Promotion
-
Promotional sales team
-
Key account management
-
Vacancy Management
-
-
Non-personal promotion
-
Medical affairs solutions
-
Remote medical science liaisons
-
Nurse educators
-
Others
-
-
-
Therapeutic Area Outlook (Revenue, USD Billion, 2021 - 2033)
-
Oncology
-
Cardiovascular
-
Neurology
-
Infectious Diseases
-
Metabolic Disorders
-
Orthopedic Diseases
-
Others
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Pharmaceutical Companies
-
Biopharmaceutical Companies
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
Oman
-
Qatar
-
-
Research Methodology
The pharmaceutical contract sales organizations market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with eachpharmaceutical contract sales organizations segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Service
Revenue capture definition
Personal Promotion
The revenue captured includes outsourced face-to-face sales detailing, physician engagement, territory management, product promotion, sales force deployment, and relationship-building services provided by contract sales representatives.
Promotional Sales Team
The revenue captured includes dedicated and shared sales representatives, product launch teams, promotional campaigns, physician detailing, sales execution, and field force management for pharmaceutical products.
Key Account Management
The revenue captured includes strategic account management, hospital engagement, institutional sales, payer interactions, customer relationship management, and commercial support for high-value healthcare accounts and networks.
Vacancy Management
The revenue captured includes temporary sales force deployment, territory coverage, replacement representatives, interim commercial support, and workforce continuity services during sales team vacancies or organizational transitions.
Non-personal Promotion
The revenue captured includes digital promotion, remote detailing, virtual engagement, omnichannel communication, telesales, email campaigns, and technology-enabled commercial services supporting pharmaceutical product promotion.
Medical Affairs Solutions
The revenue captured includes outsourced medical affairs support, scientific communications, medical information services, evidence dissemination, healthcare professional education, and compliant scientific engagement for pharmaceutical companies.
Remote Medical Science Liaisons
The revenue captured includes virtual scientific engagement, medical education, clinical evidence communication, key opinion leader interactions, and remote medical liaison services supporting pharmaceutical commercialization strategies.
Nurse Educators
The revenue captured includes patient education, therapy administration training, adherence support, disease awareness programs, healthcare professional education, and clinical assistance services delivered by specialized nurse educators.
Others
The revenue captured includes sales analytics, commercial consulting, market access support, customer service, training programs, CRM management, and additional outsourced pharmaceutical commercial services.
Segment - Therapeutic Area
Revenue capture definition
Oncology
The revenue captured includes outsourced sales and commercialization services supporting oncology therapies through physician engagement, hospital promotion, scientific communication, and specialized commercial activities for cancer treatment products.
Cardiovascular
The revenue captured includes contract sales services promoting cardiovascular medicines through physician detailing, hospital engagement, healthcare provider education, and commercial support across cardiovascular therapeutic markets.
Neurology
The revenue captured includes outsourced commercial services supporting neurological therapies through specialized sales representatives, physician engagement, product promotion, and healthcare professional education across neurology markets.
Infectious Diseases
The revenue captured includes contract sales services promoting anti-infectives, vaccines, and related therapies through healthcare provider engagement, educational initiatives, and commercial execution across infectious disease markets.
Metabolic Disorders
The revenue captured includes outsourced sales services supporting diabetes, obesity, endocrine, and metabolic therapies through physician detailing, commercial promotion, and healthcare provider relationship management activities.
Orthopedic Diseases
The revenue captured includes commercial services promoting orthopedic pharmaceuticals through healthcare provider engagement, hospital sales support, product detailing, and specialized sales force deployment across orthopedic care settings.
Others (Therapeutic Area)
The revenue captured includes outsourced sales services supporting respiratory, dermatology, gastroenterology, ophthalmology, immunology, rare diseases, and other specialty therapeutic areas requiring dedicated commercial expertise.
Segment - End Use
Revenue capture definition
Pharmaceutical Companies
The revenue captured includes outsourced sales force deployment, commercial promotion, key account management, medical affairs support, and omnichannel engagement services provided to pharmaceutical manufacturers for product commercialization.
Biopharmaceutical Companies
The revenue captured includes contract sales, launch excellence, scientific engagement, medical affairs, and commercialization support services provided to biopharmaceutical companies developing innovative biologics and specialty therapies.
Estimation Model
Model Type
Description
Key Highlights
Bottom-Up Model Estimation
Estimates the market by calculating the number of outsourced pharmaceutical sales representatives deployed globally across therapeutic areas and multiplying them by the average annual contract value per representative. Adjustments are made for dedicated/shared teams, key account managers, medical liaisons, nurse educators, and regional pricing differences. Company revenues are validated through annual reports and industry databases before aggregation into regional and global market estimates.
Provides granular insights into representative deployment, contract value variations, and regional pricing dynamics for accurate bottom-up market sizing.
Top-Down Model Estimation
Estimates the percentage of pharmaceutical commercialization expenditure allocated toward contract sales organizations (CSOs). Total spending is analyzed by region, and the proportion outsourced to CSOs is determined using company disclosures, industry benchmarks, and expert interviews. Revenue estimates are segmented by service type, therapeutic area, and end user, cross-validated against reported revenues of major CSO providers.
Enables macro-level validation of outsourcing trends, regional expenditure patterns, and service-type segmentation for top-down market estimation.
Product Launch-Based Demand Estimation Model
Estimates market size by assessing annual pharmaceutical and biopharmaceutical product launch requirements for outsourced commercial support. Each launch is assigned an average contract value based on duration, sales force size, therapeutic specialization, and geographic coverage. Additional revenues from training, vacancy management, and medical affairs services are incorporated. Reflects increasing outsourcing trends among biotech and specialty pharma companies.
Captures demand fluctuations linked to new product launches, commercialization cycles, and specialized outsourcing needs in emerging biotech segments.
Company Revenue Benchmarking Model
Derives market size by consolidating revenues generated by leading pharmaceutical contract sales organizations from annual reports, investor presentations, and financial disclosures. Revenues attributable to outsourced sales, commercial operations, and medical affairs services are extracted and adjusted for private company estimates. Market share analysis, regional expansion, acquisition activity, and service portfolio coverage are used to estimate the combined contribution of smaller providers and calculate total global market size.
Provides comprehensive benchmarking of leading CSOs, highlighting market share distribution, acquisition trends, and service diversification across global regions.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Market Forecasting & Revenue Opportunity Assessment
Customized market forecasts by service, therapeutic area, geography, and end user using bottom-up and top-down estimation models, supported by scenario analysis, pricing trends, outsourcing penetration, and commercial adoption rates.
This provides reliable revenue projections, supports strategic planning, minimizes forecasting uncertainty, identifies future growth pockets, and enables clients to make data-driven investment, expansion, and resource allocation decisions.
Competitive Benchmarking & Company Profiling
Detailed benchmarking of leading CSOs based on service portfolio, therapeutic expertise, geographic presence, client base, strategic partnerships, acquisitions, digital capabilities, financial performance, and commercialization strengths, supported by pestle analysis and market share evaluation.
This helps clients benchmark competitors, identify strategic gaps, evaluate partnership or acquisition opportunities, improve service differentiation, strengthen competitive positioning, and support informed business development and investment decisions.
Regional Market Assessment
Comprehensive analysis of the Pharmaceutical Contract Sales Organizations market across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa, including country-level market sizing, outsourcing trends, therapeutic demand, reimbursement environment, regulatory landscape, competitive intensity, and growth opportunities.
This enables clients to identify high-growth geographies, optimize regional commercial strategies, prioritize investments, understand competitive positioning, and develop effective market entry and expansion plans based on regional demand patterns and outsourcing maturity.
Frequently Asked Questions About This Report
The global pharmaceutical contract sales organizations market size was valued at USD 11.9 billion in 2025 and is estimated at USD 12.9 billion for 2026.
The global pharmaceutical contract sales organizations market is expected to grow at a CAGR of 9.1% from 2026 to 2033, reaching USD 23.8 billion.
Key factors include high adoption of new technologies for contract sales by pharmaceutical contract sales organizations, an increase in the interest among end users to increase the sales of biopharmaceutical and small molecule drugs, and the surge in demand for reducing the cost associated with in-house sales are some of the key factors supporting the growth of the Pharmaceutical Contract Sales Organization market.
North America dominated with a 37.9% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
The personal promotion segment led with a 59.5% revenue share in 2025, while the non-personal promotion is the fastest-growing segment.
The oncology segment led the market with the largest revenue share of 32.8% in 2025.
Pharmaceutical companies held the largest share of 53.1% in 2025, while biopharmaceutical companies are the fastest-growing segment.
Key players include CMIC Holdings Co., Ltd., Axxelus, EPS Corp., QFR Solutions, MaBico, Mednext Pharma Pvt. Ltd., Peak Pharma Solutions Inc., IQVIA, Inc., Promoveo Health, and Syneos Health among others.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


