
- Home
- »
- Medical Devices
- »
-
Point-of-Care Medical Imaging Market Report, 2026-2033GVR Report cover

Point-of-Care Medical Imaging Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (X-ray, Ultrasound, CT), By Application (General, Cardiovascular, Musculoskeletal), By End Use (Hospitals, ASCs), By Region, And Segment Forecasts
Market Size, 2025
$1.3BMarket Estimate, 2026
$1.4BMarket Forecast, 2033
$1.9BCAGR, 2026–2033
4.3%Point-of-Care Medical Imaging Market Summary
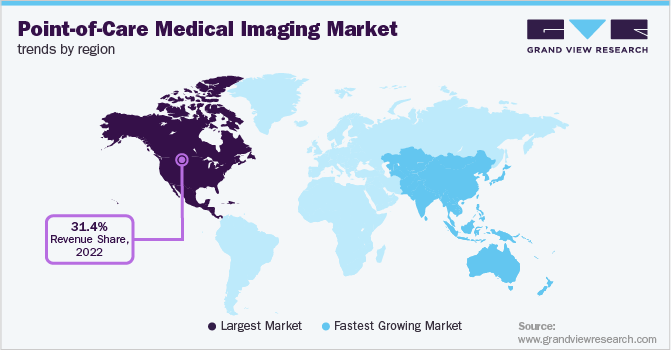
The global point-of-care medical imaging market size was valued at USD 1.3 billion in 2025 and is projected to grow from USD 1.4 billion in 2026 to USD 1.9 billion by 2033, at a CAGR of 4.3% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 30.0% in 2025. The growing adoption of point-of-care (POC) medical imaging devices and ongoing technological advancements are driving industry growth in the coming years.
Key Market Trends & Insights
- By product: The ultrasound segment held the largest market share of around 55.0% in 2025.
- By application: The general imaging application segment held the largest market share of over 30.0% in 2025.
- By end use: The hospital segment held the largest market share of more than 40.0% in 2025.
Regional Highlights
- Largest regional market: North America (30.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 1.3 Billion
- Estimated market size in 2026: USD 1.4 Billion
- Projected market size by 2033: USD 1.9 Billion
- CAGR (2026-2033): 4.3%
GVR research-powered AIAsk Prism AI about the Point-of-Care medical imaging marketGet cited answers from GVR research on market growth, segments, regulations and forecasts.Start with✓ Source-linked answers ✓ Market-specific context ✓ Traceable figuresExplore Prism AI ↗
For instance, in June 2025, Philips launched the Flash Ultrasound System 5100 POC, a portable point-of-care ultrasound system for critical care, emergency medicine, anesthesia, and musculoskeletal imaging. The system offers advanced imaging, smart automation, and real-time collaboration features, enabling faster diagnosis and improved clinical decision-making, thereby supporting the growth of the point-of-care medical imaging industry.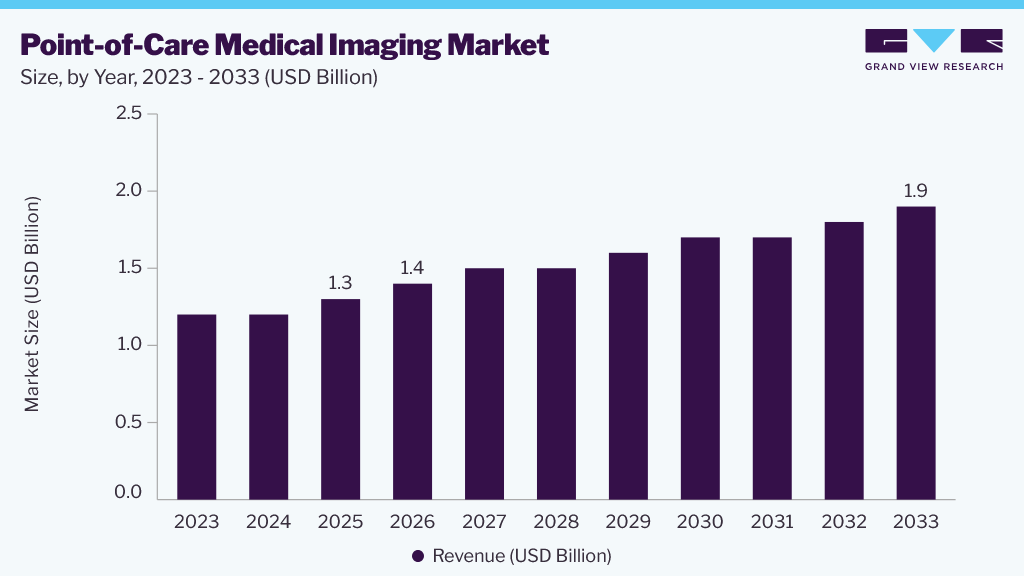 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
The primary factor influencing the use of POC imaging systems in healthcare facilities is their contribution to enhanced patient care, infection control, and rapid diagnosis. Transferring seriously ill patients to the radiology department may result in complications. As per the International Journal of Critical Illness & Injury Science, a few instances of transport-related consequences include dangers to the respiratory system, traumatic damage, acid-base homeostasis, glucose regulation, the risk for infection, and even fatality. Thus, by bringing diagnostic imaging equipment directly to the patient’s bedside, the risk of patient transport can be eliminated.
Radiologists and other diagnostic professionals focus on image quality, speed, flexibility of application, and ease of use. As POC imaging systems continue to advance, they can offer all of these characteristics by leveraging cutting-edge technology and design. This is expected to drive the adoption of POC medical imaging systems. Furthermore, constant technological advancements are supporting the industry's growth.
Major industry players are adopting various strategic initiatives, such as product development and government approvals, to gain greater market share. For instance, in January 2026, ASUS received U.S. FDA clearance for its Handheld Ultrasound LU800, a wireless point-of-care ultrasound device offering multiple imaging modes, cross-platform compatibility, and high-quality diagnostic imaging capabilities. Such developments are supporting rapid assessments in emergency, ambulance, and remote care settings. This development is expected to drive the adoption of portable medical imaging.
Analyst Perspective
The global point-of-care medical imaging industry is witnessing strong momentum as healthcare providers prioritize rapid diagnosis, bedside imaging, and improved patient management in emergency, critical care, and outpatient settings. Ultrasound remains the leading product segment due to its portability, broad clinical applicability, and growing adoption of advanced POCUS systems, while mobile CT solutions are gaining traction for critical care imaging. Ongoing technological advancements, such as AI-enabled workflow automation and improved image quality, are increasing diagnostic efficiency and supporting wider use of portable imaging devices. Rising healthcare investments and the growing prevalence of chronic and cardiovascular diseases are expected to drive significant growth, especially in emerging Asia-Pacific markets.
Product Insights
The ultrasound segment led the market with the largest revenue share of more than 55.0% in 2025. The segment is projected to expand further at a steady CAGR, maintaining its dominant position in the industry throughout the forecast period. The growth can be attributed to the introduction of technologically advanced POC Ultrasound Systems (POCUS) and to an increase in patients visiting emergency departments with a variety of health issues, including acute abdominal pain, urological difficulties, and chest discomfort. Moreover, the demand for POCUS is anticipated to increase due to its multiple therapeutic and diagnostic applications.
The CT product segment is expected to register at the fastest CAGR during the forecast period. Point-of-care/mobile CT scanners yield highly beneficial results compared to stationary CT scanners, as they reduce the time patients spend undergoing diagnostic imaging, improve patient recovery, increase the accuracy of patient care, and shorten hospital stays. The ability of mobile CT to conduct imaging tests on a patient without requiring repositioning and restricting the patient’s movement makes CT scans possible even for the most unstable and severely ill patients.
For instance, in August 2025, Samsung India and NeuroLogica launched their next-generation mobile CT imaging portfolio in India, including the OmniTom Elite mobile point-of-care CT scanner. Designed for critical care environments such as intensive care units, operating rooms, and emergency departments, the system enables bedside CT imaging, reducing patient transport requirements, improving workflow efficiency, and supporting growth in this segment.
Application Insights
The general imaging segment led the market with the largest revenue share of more than 30.0% in 2025. General imaging is less expensive than other applications and includes a wide range of scans that clinicians need for diagnosis and direct treatment, such as the abdomen, musculoskeletal system, small parts, urology, liver, thyroid, scrotum, bladder, pancreas, kidneys, spleen, and gallbladder. Furthermore, the growing awareness of general radiology with POC devices is expected to drive growth in the segment over the coming years.
The cardiovascular segment is expected to grow at the fastest CAGR during the forecast period. The growing demand for cardiac imaging poses a major challenge for cardiologists, driven by the increasing prevalence of cardiovascular disorders worldwide. According to the data published by the World Health Organization (WHO) in 2025, cardiovascular diseases (CVDs) remain the leading cause of death globally, accounting for an estimated 19.8 million deaths in 2022. The increasing prevalence of cardiovascular disorders has put significant pressure on the healthcare systems, where physicians have to address a large number of patients in a short time.
In addition, companies are investing in technological advancements to improve the accuracy and efficiency of imaging devices used for cardiovascular treatment. For instance, in June 2025, Samsung Medison showcased its premium ultrasound system, the V8, at WHX Miami, featuring advanced AI-powered cardiac imaging and automation capabilities. The system is designed to improve the accuracy of cardiovascular assessments and streamline workflow efficiency. Such developments contributed to the growing demand for POC imaging systems in cardiac care, thereby supporting growth in the segment.
End Use Insights
The hospitals segment led the market with the largest revenue share of more than 40.0% in 2025. Hospitals are replacing stationary modalities with portable technology to improve patient care, reduce the costs of in-hospital patient transportation, and lower the processing time and storage required by traditional systems. For instance, in October 2025, GE HealthCare launched the latest generation of its Venue Family point-of-care ultrasound systems, featuring AI-enabled workflow enhancements and enhanced portability. The systems support faster bedside diagnosis across emergency and critical care settings, encouraging greater adoption of portable imaging technologies in hospitals' end-use segment.
The ambulatory surgical centers (ASCs) segment is anticipated to grow at the fastest CAGR during the forecast period. The growing number of patients visiting ASCs for surgical care is expected to contribute to the segment's growth. There is a need for POC imaging systems for ambulatory surgery that can access patients from any direction and at any height and produce high-quality three-dimensional images. Moreover, efficient cost coverage policies for point-of-care systems in these centers are expected to boost segment growth.
Regional Insights
North America dominated the global point-of-care medical imaging market with the largest revenue share of more than 30.0% in 2025. Some of the major factors contributing to the region’s growth include a greater preference for technologically advanced medical systems and greater accessibility to advanced healthcare facilities. Furthermore, the increased government spending on healthcare in the region is expected to drive growth. For instance, according to the Centers for Medicare & Medicaid Services (CMS), U.S. healthcare spending increased by 7.2% to USD 5.3 trillion in 2024, accounting for 18.0% of the nation's gross domestic product (GDP). The growth was driven by increased utilization of healthcare services across hospitals, physician services, and prescription drugs. The region is further anticipated to grow due to the presence of prominent players such as GE Healthcare and FUJIFILM SonoSite.
 To learn more about this report, Download Free Sample Report
Asia Pacific Point-of-Care Medical Imaging Market Trends
The point-of-care medical imaging market in the Asia Pacific region is anticipated to grow at the fastest CAGR over the forecast period, owing to supportive government initiatives to improve healthcare infrastructure in the region. Moreover, economic development in countries such as India and China is expected to facilitate market growth. The growing target population, along with low per capita income in the region, has also led to a high demand for affordable treatment options. The regional market is further driven by a large geriatric population and growing demand for decentralized diagnostics.
Key Point-of-Care Medical Imaging Company Insights
Key players are focusing on various growth strategies, including new product launches, expansions, collaborations, partnerships, and acquisitions. For instance, in September 2025, Canon Medical launched the Alphenix 4D CT integrated with the Aquilion ONE/INSIGHT Edition in Europe. The Angio-CT solution combines advanced CT imaging with interventional capabilities, enabling faster and more precise image-guided procedures.
Key Point-of-Care Medical Imaging Companies
The following key companies have been profiled for this study on the global point-of-care medical imaging market:
-
GE HealthCare Technologies Inc.
-
Siemens Healthineers AG
-
Koninklijke Philips N.V.
-
Canon Medical Systems Corporation
-
Shenzhen Mindray Bio-Medical Electronics Co., Ltd.
-
FUJIFILM SonoSite, Inc.
-
Esaote SPA
-
Neurologica Corp
-
Samsung Medison Co.
-
Xoran Technologies, LLC
Recent Developments
- In November 2025, Micro-X unveiled an updated version of its Rover Mobile DR X-ray system ahead of RSNA 2025. The upgraded platform features a high-resolution glass-free detector, in-bin charging, a larger touchscreen interface, and improved mobility, strengthening its capabilities for bedside and point-of-care X-ray imaging.
- In July 2025, FUJIFILM Healthcare Americas launched the FDR Go iQ, a portable digital radiography system for bedside imaging. The solution delivers high-quality X-ray imaging and advanced workflow features, supporting greater adoption of point-of-care medical imaging devices.
- In March 2025, GE HealthCare and NVIDIA partnered to develop AI-powered autonomous X-ray and ultrasound technologies. The collaboration aims to automate imaging workflows, improve efficiency, and support broader adoption of advanced point-of-care imaging solutions.
- In March 2025, GE HealthCare launched the Revolution Vibe CT system, featuring advanced cardiac imaging and AI-powered workflow capabilities that enable faster, high-quality cardiac assessments and improved operational efficiency, thereby supporting the adoption of advanced diagnostic imaging technologies.
Point-of-Care Medical Imaging Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.3 billion
Estimated market size in 2026
USD 1.4 billion
Projected market size by 2033
USD 1.9 billion
Growth rate
CAGR of 4.3% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; UK; Germany; France; Italy; Spain; Japan; China; India; Australia; South Korea; Brazil; Mexico; Columbia; Argentina; South Africa; Saudi Arabia; UAE
Key companies profiled
GE HealthCare Technologies Inc.; Siemens Healthineers AG; Koninklijke Philips N.V. s; Canon Medical Systems Corporation; Shenzhen Mindray Bio-Medical Electronics Co., Ltd.; FUJIFILM SonoSite, Inc.; Esaote SPA; Neurologica; Samsung Medison Co.; Xoran Technologies, LLC
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Point-of-Care Medical Imaging Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends and opportunities across each sub-segment from 2021 to 2033. For this study, Grand View Research has segmented the global point-of-care medical imaging market report based on product, application, end-use, and region:
- Product Outlook (Revenue, USD Billion, 2021 - 2033)
- X-ray
- CT
- Ultrasound
- Application Outlook (Revenue, USD Billion, 2021 - 2033)
- General Imaging
- Cardiovascular
- Musculoskeletal
- Others
- End-use Outlook (Revenue, USD Billion, 2021 - 2033)
- Hospitals
- Clinics
- Ambulatory Surgical Centers
- Regional Outlook (Revenue, USD Billion, 2021 - 2033)
- North America
- U.S.
- Canada
- Europe
- UK
- Germany
- France
- Spain
- Italy
- Asia Pacific
- Japan
- China
- India
- Australia
- South Korea
- Latin America
- Brazil
- Mexico
- Argentina
- Colombia
- Middle East & Africa
- South Africa
- Saudi Arabia
- UAE
- North America
Frequently Asked Questions About This Report
The global point-of-care medical imaging market size was valued at USD 1.3 billion in 2025 and is estimated at USD 1.4 billion for 2026.
The global point-of-care medical imaging market is expected to grow at a CAGR of 4.3% from 2026 to 2033, reaching USD 1.9 billion.
North America dominated with a 30.0% revenue share in 2025.
Ultrasound dominated the point-of-care medical imaging market with a share of around 55.0% in 2025.
Key players in the market include GE HealthCare Technologies Inc., Siemens Healthineers AG, Koninklijke Philips N.V., Canon Medical Systems Corporation, Shenzhen Mindray Bio-Medical Electronics Co., Ltd., FUJIFILM SonoSite, Inc., Esaote SPA, Neurologica Corp, Samsung Medison Co., Xoran Technologies, LLC, and others.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


