
- Home
- »
- Plastics, Polymers & Resins
- »
-
Polyethylene Terephthalate Films Market Report, 2026-2033GVR Report cover

Polyethylene Terephthalate Films Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Conventional PET Films, Isotropic PET Films), By End Use (Food & Beverage, Electrical & Electronics), By Region (Asia Pacific, North America, Europe), And Segment Forecasts
Market Size, 2025
$40.1BMarket Estimate, 2026
$43.9BMarket Forecast, 2033
$64.9BCAGR, 2026–2033
5.7%Polyethylene Terephthalate Films Market Summary
The global polyethylene terephthalate films market size was valued at USD 40.1 billion in 2025 and is projected to grow from USD 43.9 billion in 2026 to USD 64.9 billion by 2033, at a CAGR of 5.7% from 2026 to 2033. The market in Asia Pacific dominated with a revenue share of 36.4% in 2025. Rising demand from the electrical and electronics sector is driving PET film consumption, as it offers strong dielectric strength and thermal stability.
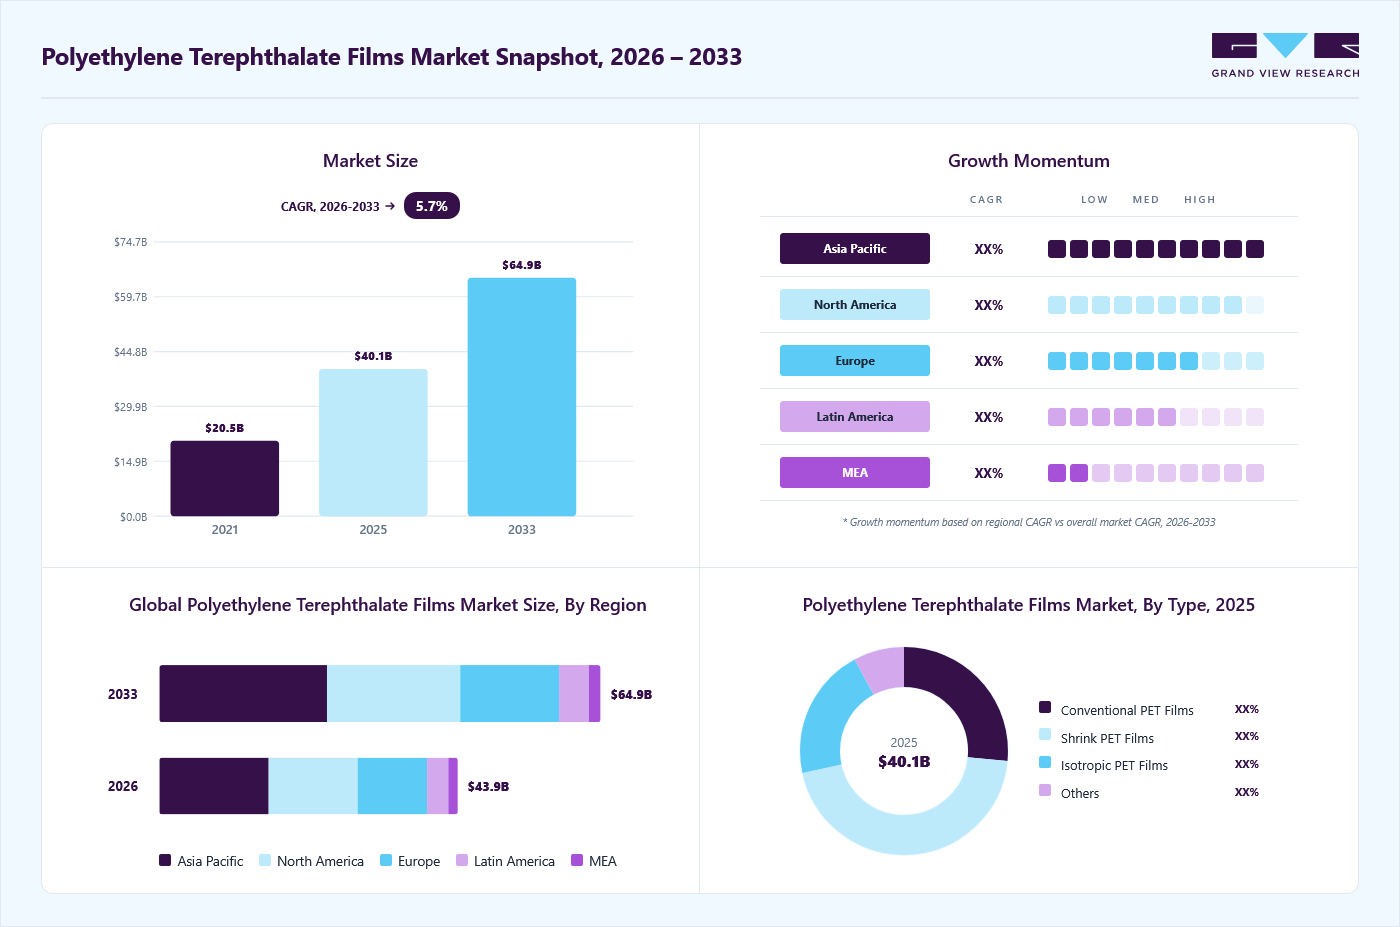 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Shrink PET films segment held the largest market share of 45.0% in 2025.
- By end use: Food & beverage segment held the largest market share of 37.8% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (36.4% revenue share, 2025)
- By country: China held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 40.1 Billion
- Estimated market size in 2026: USD 43.9 Billion
- Projected market size by 2033: USD 64.9 Billion
- CAGR (2026-2033): 5.7%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
According to industry association publications, PET film is widely used in capacitors, insulation, and flexible circuits, which supports steady demand growth alongside expanding electronics manufacturing.
 To learn more about this report, Download Free Sample Report
The PET film market is shifting toward recyclable mono-material and recycled-content structures. Producers are introducing high-barrier PET films and functional coatings that protect food while supporting circularity. Design guidance from the flexible packaging value chain favors monomaterial structures where feasible, and food-contact rules now permit recycled PET under defined safety conditions. This is pushing converters toward simpler, regulation-ready film formats across packaging lines, especially where shelf-life extension and recyclability must work together.
Drivers, Opportunities & Restraints
Food and beverage packaging remains the primary demand driver for PET film, as the material offers clarity, stiffness, and barrier performance. Industry sources highlight its role in extending shelf life for dry foods and other packaged goods, while food-contact regulations continue to recognize PET as a compliant packaging material. As brands seek lighter packs with better product protection, PET film is gaining share in flexible packaging specifications that need both visual appeal and functional performance.
Food-grade recycled PET film and closed-loop recovery systems are opening premium growth avenues. Recycled PET can now be used for food-contact applications under defined guidelines, improving downstream acceptance of recycled-content packaging. At the same time, manufacturers are scaling PCR-based PET films and single-pellet solutions to help converters meet recycled-content targets. Beyond packaging, higher-value applications in electronics and electric mobility are also expanding, including capacitor films and release films that support miniaturization and thermal resistance.
Volatility in petrochemical feedstocks and the complexity of multilayer laminate recycling remain structural restraints. Polyester film producers continue to report sensitivity to changes in raw material and fuel prices, especially when price pass-through lags. At the same time, multi-material flexible structures complicate separation and can reduce the quality of recyclable output. That keeps cost discipline and design simplification central to competitiveness, particularly in commodity film grades where margins are more exposed.
Market Concentration & Characteristics
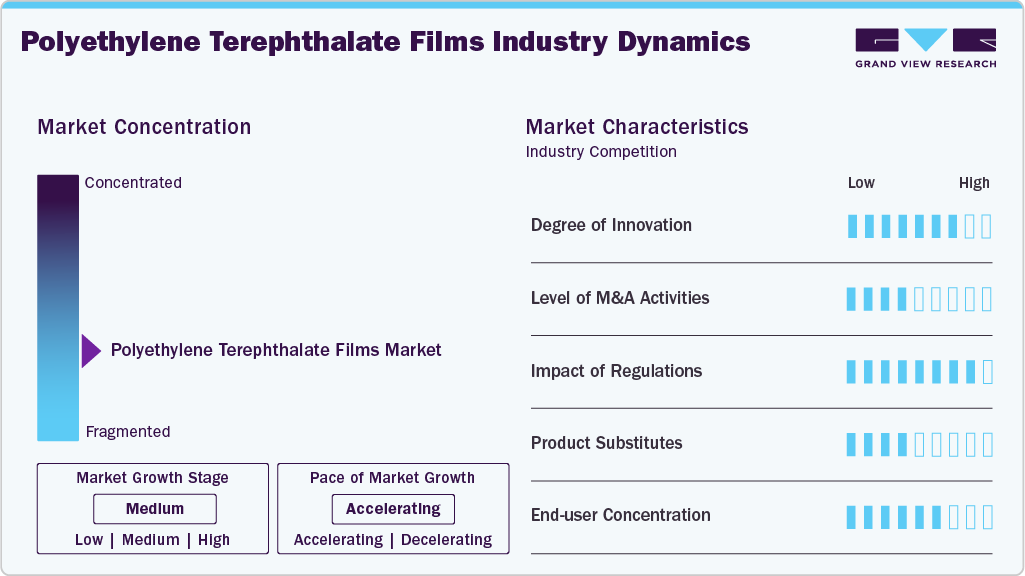
The market growth stage is medium, and growth is accelerating. The market exhibits fragmentation, with key players dominating the industry landscape. Major companies such as Bleher Folientechnik GmbH, Shenzhen KHJ Technology Co., Ltd., Jiangsu Yuxing Film Technology Company, Nuroll SpA., Qingdao Kingchuan Packaging, Mitsubishi Chemical Group, and others play a significant role in shaping the market dynamics. These leading players often drive innovation in the market by introducing new products, technologies, and materials to meet the industry's evolving demands.
The degree of innovation in PET film is high and increasingly tied to circularity and performance upgrading. Producers are commercializing recycled PET film, closed-loop recovery schemes, and high-barrier coated grades that preserve clarity while improving moisture and oxygen protection. The product set is moving beyond standard base film into specialty formats for demanding packaging and industrial uses. This shows a market that is no longer driven only by volume, but by functional differentiation and recycled-content compliance.
 To learn more about this report, Download Free Sample Report
Substitution pressure is strongest in flexible packaging, where mono-PE and mono-PP structures are increasingly preferred because they are easier to sort and recycle at scale. Paper-based, aluminum foil-based, biodegradable, and compostable structures also compete in selected applications, but they remain smaller in the recyclable stream and often face technical or end-of-life trade-offs. In practice, PET film is displaced mainly when recyclability targets outweigh transparency, stiffness, or barrier needs. That limits broad substitution and keeps PET relevant in higher-performance packs.
Type Insights
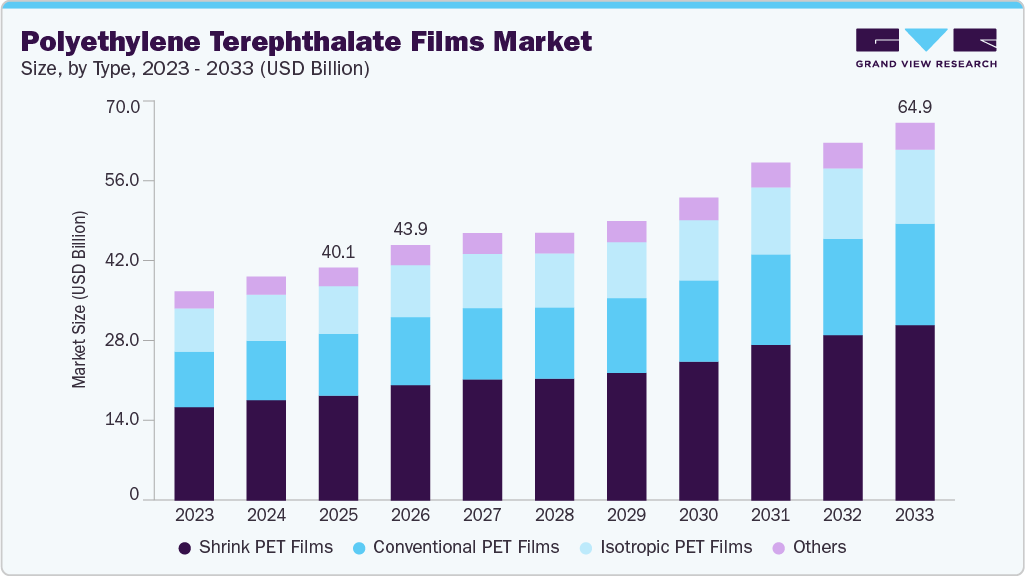
The shrink PET films segment dominated the market across type segmentation in terms of revenue, accounting for 45.0% market share in 2025, and is forecast to grow at a 6.1% CAGR from 2026 to 2033. The main driver is premium sleeve decoration on complex container shapes, especially in beverages and personal care. A 2025 product overview shows shrink PET sleeves are engineered for high shrink rates on highly contoured bottles, while recyclable sleeve grades now meet APR critical guidance for clear PET articles. This gives brand owners a way to lift shelf impact, add tamper evidence, and preserve recyclability targets at the same time.
The conventional PET films segment is expected to expand at a 5.9% CAGR in the polyethylene terephthalate films market over the forecast period. Conventional PET films are supported by their role as the standard workhorse in high-volume laminates and flexible packaging. Current manufacturer disclosures indicate that BOPET is available in plain, surface-treated, coated, matte, heat-sealable, metallisable, clear, and extra-clear grades, making it suitable for a wide range of converters. Sustainability is also improving through the reuse of recycled PET film and lower-gauge formats, which keep this segment relevant in cost-sensitive applications.
End Use Insights
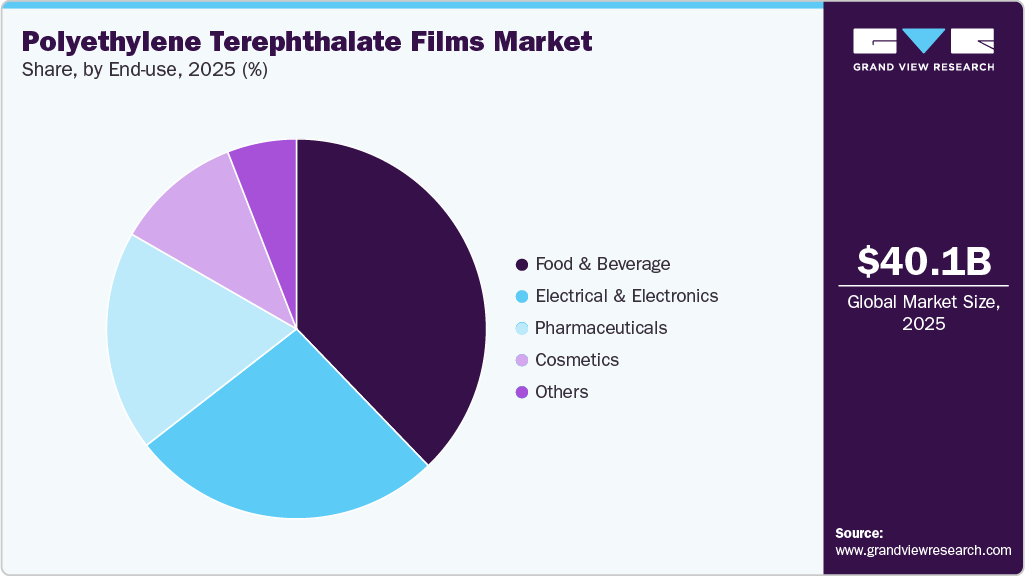
The food & beverage segment dominated the market across end-use segmentation in terms of revenue, accounting for 37.8% market share in 2025, and is forecast to grow at a 6.1% CAGR from 2026 to 2033. Demand for food and beverages is being driven by shelf-life protection, food-contact compliance, and the shift toward recyclable packaging structures. FSSAI’s 2025 guidance allows recycled PET for food-contact use under defined testing requirements, which strengthens acceptance of PET-based films in packaging systems. At the same time, film manufacturers are reducing plastic use and moving to monomer-based structures to improve recyclability while maintaining barrier performance for packaged foods.
 To learn more about this report, Download Free Sample Report
The electrical & electronics segment is expected to expand at a 5.9% CAGR in the polyethylene terephthalate films market over the forecast period. The key driver is the need for thin films that combine insulation, thermal stability, and long service life in compact devices. Official product pages show polyester films are widely used in electrical insulation, motors, flexible printed circuitry, capacitors, lighting, and related electronics. Demand is further supported by the expansion of EVs, batteries, and flexible electronics, where films must withstand higher temperatures while keeping dimensional stability and processing reliability.
Regional Insights
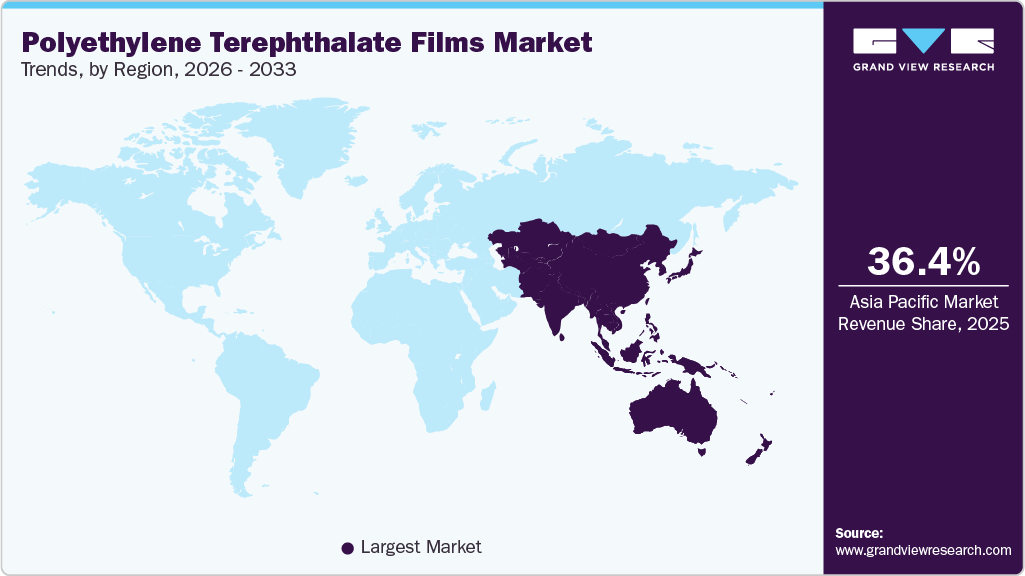
The Asia Pacific polyethylene terephthalate films industry held the largest revenue share of 36.4% in 2025. Asia Pacific demand is being strengthened by the region’s electronics and EV manufacturing base. Industry disclosures show PET films are essential in MLCC and semiconductor-related applications, with production sites in Japan, South Korea, and Malaysia positioned for further demand growth. IEA data also show electric car sales in Southeast Asia rising nearly 50% in 2024. This mix of electronics, mobility, and packaging activity supports steady consumption of high-performance PET film grades.
 To learn more about this report, Download Free Sample Report
China Polyethylene Terephthalate Films Market Trends
China’s PET film demand is driven by scale in logistics, manufacturing, and clean mobility. The postal sector handled 174.5 billion parcels in 2024, and new regulations from June 2025 encourage greener, reduced, and reusable express packaging. At the same time, China remains the world’s electric vehicle manufacturing hub, which sustains film demand in batteries, insulation, and electronic components. Together, these trends support higher consumption of functional PET film in both packaging and industrial uses.
North America Polyethylene Terephthalate Films Market Trends
North America is benefiting from the depth of PET collection and reprocessing capacity across the U.S. and Canada. Industry data show reclaimers could process nearly 2 billion more pounds of plastic annually, with excess capacity across PET and film. That gives converters more room to secure locally sourced PCR, which supports PET film use in packaging and other applications. The market is also gaining from better alignment between recyclability targets and manufacturing demand.
The U.S. polyethylene terephthalate market is witnessing a rise in demand, which is being pulled by state-level packaging rules and FDA pathways for recycled plastics in food-contact uses. Five states have already enacted PCR content laws, while California requires packaging to be recyclable or compostable and to reach a 65 percent recycling rate by 2032. These measures push brand owners toward PET film formats that can support recycled content, clear labeling, and compliant food packaging systems.
Europe Polyethylene Terephthalate Films Market Trends
Europe is being shaped by policy-led circularity rather than pure volume growth. The Packaging and Packaging Waste Regulation entered into force in February 2025 and targets lower primary raw material use, economically viable recycling by 2030, and safer incorporation of recycled plastic. The Circular Plastics Alliance is also working to expand the use of recycled plastics to 10 million tons and improve recyclability across packaging. This keeps PET film relevant in compliant, recyclable packaging structures.
Key Polyethylene Terephthalate Films Company Insights
The polyethylene terephthalate films industry is highly competitive, with several key players dominating the landscape. Major companies include Bleher Folientechnik GmbH, Shenzhen KHJ Technology Co., Ltd, Jiangsu Yuxing Film Technology Company, Nuroll SpA., Qingdao Kingchuan Packaging, and Mitsubishi Chemical Group. The polyethylene terephthalate films industry is characterized by a competitive landscape with several key players driving innovation and market growth. Major companies in this sector are investing heavily in research and development to enhance the performance, cost-effectiveness, and sustainability of their products.
Key Polyethylene Terephthalate Films Companies:
The following key companies have been profiled for this study on the polyethylene terephthalate films market.
- Bleher Folientechnik GmbH
- Shenzhen KHJ Technology Co., Ltd
- Jiangsu Yuxing Film Technology Company
- Nuroll SpA.
- Qingdao Kingchuan Packaging
- Mitsubishi Chemical Group
- GLS Group
- Polyplex
- TORAY INDUSTRIES, INC.
- COVINIL S.A.
Recent Developments
-
In February 2026, UFlex introduced F-HSS, a mono-material PET film at PLASTINDIA 2026. The film supports recyclable PET-to-PET structures, offers high seal strength and clarity, and targets food, beverage, and FMCG packaging where converters are replacing mixed-material laminates with easier-to-recycle formats.
-
In July 2025, Cosmo Plastech launched an ESD PET sheet for electronic component packaging in India. The new grade is designed to address electrostatic protection needs in a fast-growing electronics manufacturing base, which broadens PET film use beyond packaging into higher-value technical applications.
Polyethylene Terephthalate Films Market Report Scope
Report Attribute
Details
Market size in 2025
USD 40.1 billion
Estimated Market size in 2026
USD 43.9 billion
Projected Market size by 2033
USD 64.9 billion
Growth rate
CAGR of 5.7% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, volume in Kilotons, and CAGR from 2026 to 2033
Report coverage
Revenue & volume forecast, competitive landscape, growth factors, and trends
Segments covered
Film type, end use, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country Scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; China; India; Japan; Australia; South Korea; Brazil; Argentina; South Africa; Saudi Arabia; UAE
Key companies profiled
Bleher Folientechnik GmbH; Shenzhen KHJ Technology Co., Ltd.; Jiangsu Yuxing Film Technology Company; Nuroll SpA.; Qingdao Kingchuan Packaging; Mitsubishi Chemical Group; GLS Group; Polyplex; TORAY INDUSTRIES, INC.; COVINIL S.A.
Customization scope
Free report customization (equivalent to up to 8 analyst working days) with purchase. Addition or alteration to country, regional & segment scope
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Polyethylene Terephthalate Films Market Report Segmentation
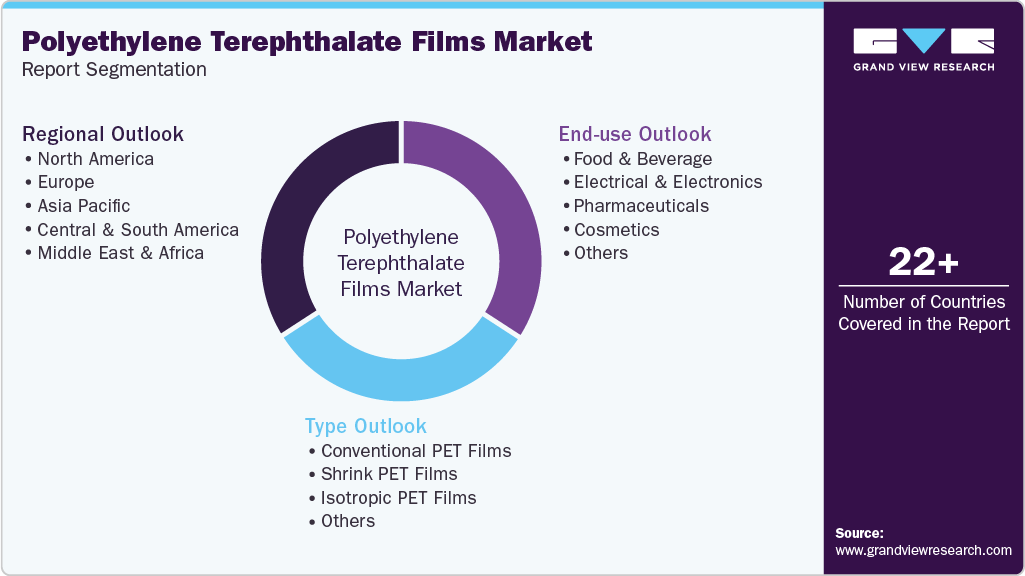
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends across sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global polyethylene terephthalate films market report based on type, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Volume, Kilotons; Revenue, USD Million; 2021 - 2033)
-
Conventional PET Films
-
Shrink PET Films
-
Isotropic PET Films
-
Others
-
-
End Use Outlook (Volume, Kilotons; Revenue, USD Million; 2021 - 2033)
-
Food & Beverage
-
Electrical & Electronics
-
Pharmaceuticals
-
Cosmetics
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million; 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
UAE
-
-
Frequently Asked Questions About This Report
The food & beverage segment led with a 37.8% revenue share in 2025, while the electrical & electronics segment is expected to expand at a 5.9% CAGR.
The global polyethylene terephthalate films market size was estimated at USD 40.1 billion in 2025 and is expected to reach USD 43.9 billion in 2026.
The global PET films market is expected to grow at a compound annual growth rate of 5.7% from 2026 to 2033 to reach USD 64.9 billion by 2033.
The shrink PET films segment led with a 45.0% revenue share in 2025, while the conventional PET films segment is expected to expand at a 5.9% CAGR.
Some key players operating in the PET films market include Bleher Folientechnik GmbH , Shenzhen KHJ Technology Co., Ltd ., Jiangsu Yuxing Film Technology Company, Nuroll SpA., Qingdao Kingchuan Packaging, and Mitsubishi Chemical Group.
Rising demand from the electrical and electronics sector is driving PET film consumption due to its strong dielectric strength and thermal stability. According to industry association publications, PET film is widely used in capacitors, insulation, and flexible circuits, which supports steady demand growth alongside expanding electronics manufacturing.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


