
- Home
- »
- Plastics, Polymers & Resins
- »
-
Polyphthalamide Market Size, Share & Trends Report, 2033GVR Report cover

Polyphthalamide Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Glass Fiber Filled, Carbon Fiber Filled), By Application (Automotive, Electronics & Electrical, Industrial Equipment & Apparatus), By Region, And Segment Forecasts
Market Size, 2025
$3.2BMarket Estimate, 2026
$3.4BMarket Forecast, 2033
$5.6BCAGR, 2026–2033
7.4%Polyphthalamide Market Summary
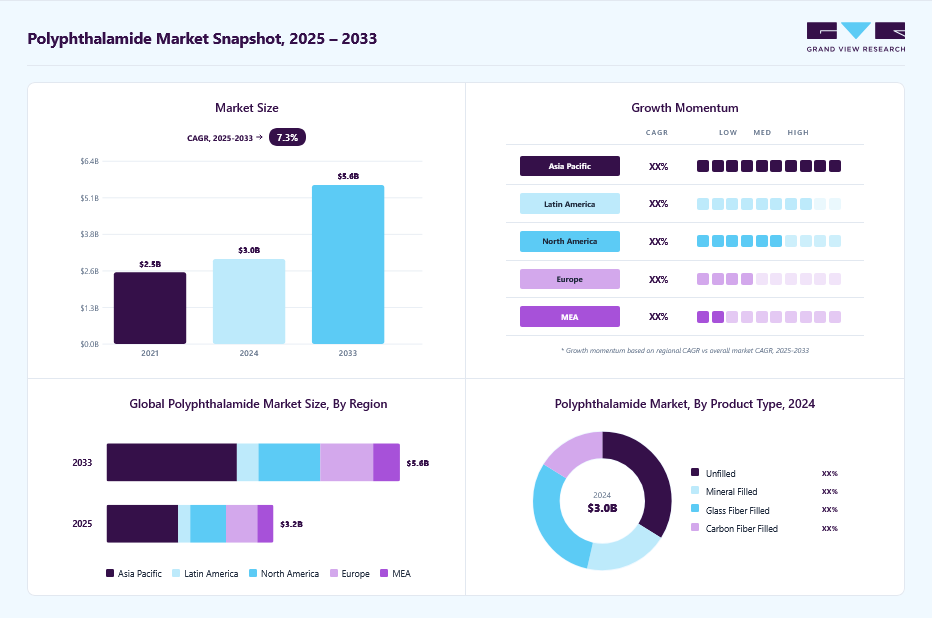
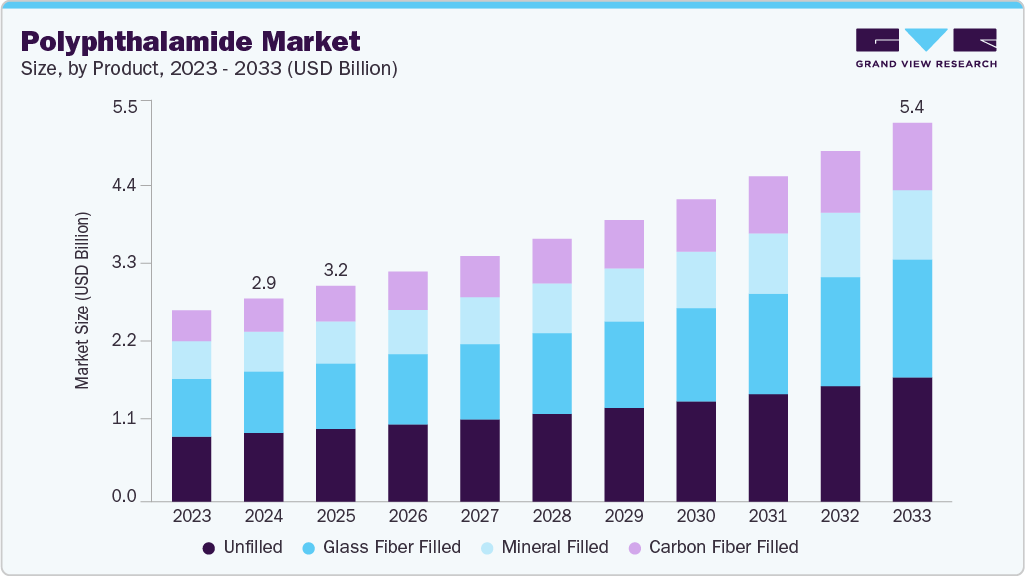
The global polyphthalamide market size was valued at USD 3.2 billion in 2025 and is projected to grow from USD 3.4 billion in 2026 to USD 5.6 billion by 2033, at a CAGR of 7.4% from 2026 to 2033. Asia Pacific dominated the market, accounting for the largest revenue share of 43.0% in 2025. Growing demand from the electronics, electrical, automotive, industrial equipment, and consumer electronics sectors, coupled with increasing substitution of metals and conventional polyamides, is driving the polyphthalamide (PPA) market.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product type: Unfilled polyphthalamide segment led the market with the largest revenue share of 33.7% in 2025.
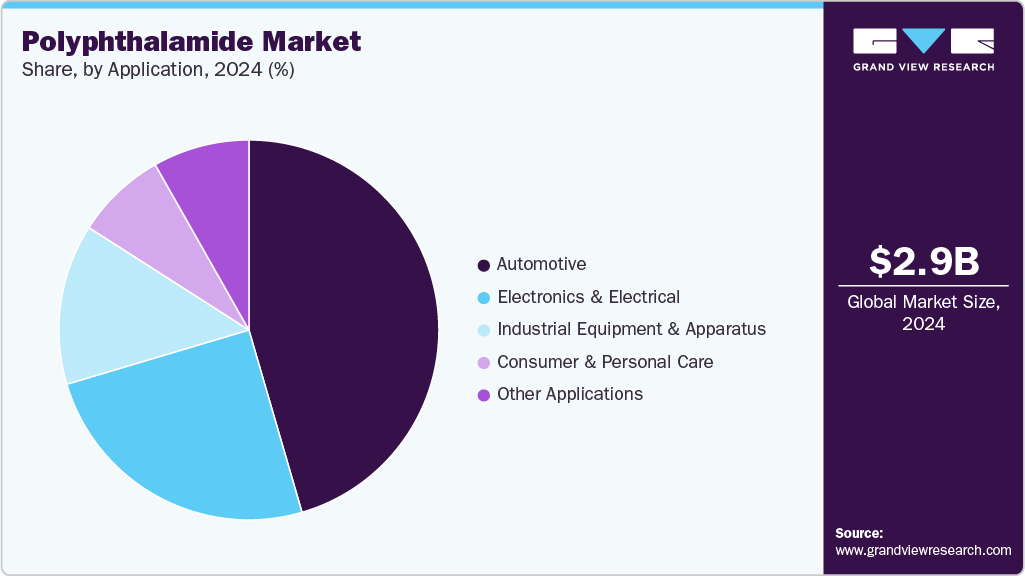
- By application: Automotive segment led the market with the largest revenue share of 45.7% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (43.0% revenue share, 2025)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 3.2 Billion
- Estimated market size in 2026: USD 3.4 Billion
- Projected market size by 2033: USD 5.6 Billion
- CAGR (2026-2033): 7.4%
Prism AI by Grand View Research Free to tryAsk a question about the polyphthalamide marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →Advances in glass and carbon fiber reinforced formulations, improved thermal and dimensional performance, and rising electrification and miniaturization trends are accelerating PPA adoption across high-performance engineering applications. The industry is driven by the rising demand from the electronics and electrical sector, where polyphthalamide (PPA) is used to produce compact, heat-resistant connectors and components for high-performance devices. Its excellent dimensional stability and dielectric strength make it ideal for miniaturized and high-voltage applications. The industry is maturing from a niche high-performance polymer into a mainstream engineering material driven by the substitution of metals and standard polyamides in under-the-hood automotive parts and compact electrical connectors. Manufacturers are moving toward glass and carbon fiber reinforced grades and formulation tuning to meet tighter dimensional and thermal cycling requirements associated with electrification and miniaturization.
 To learn more about this report, Download Free Sample Report
This shift is accompanied by broader uptake across industrial equipment and consumer electronics, where long-term thermal stability and low moisture uptake are mission-critical.
Market Dynamics
Polyphthalamide demand is concentrated in high-spec applications where heat resistance, low moisture absorption, and dimensional stability justify premium pricing. Revenue is led by electronics and electrical parts, followed by automotive and industrial hardware, because these uses require compact, durable components that can replace metal or standard polyamides. Growth is strongest in Asia Pacific, where electronics manufacturing and vehicle electrification are dense, while North America and Europe support higher-value specialty grades. The commercial structure remains qualification-led, with long OEM approval cycles, tight supplier relationships, and a clear split between volume compounds and engineered, application-specific formulations.
Demand for PPA is being pulled by electrified vehicles and high-density electrical systems, where heat buildup, dielectric performance, and dimensional stability are critical. The material is increasingly specified in high-voltage connectors, inverter housings, relay components, and under-hood parts because it supports tighter packaging and lower electrochemical risk than standard nylons. As OEMs reduce part count and shift to lighter assemblies, PPA gains content per unit even when total resin volumes remain selective.
The driver is reinforced by the move toward glass and carbon fiber reinforced grades. Suppliers are tuning flow, stiffness, and thermal cycling performance for miniaturized connectors and compact power devices, which raises material value and supports repeat qualification wins. Asia Pacific electronics scale and India’s expected growth reinforce this pull, making application engineering more important than commodity supply and allowing producers with compounding depth and technical service strength to capture premium margins.
PPA adoption is restrained by its cost structure and the technical burden of processing and qualification. The resin requires higher molding temperatures, careful drying, and formulation control, which increases conversion cost and limits use in lower-margin parts. In addition, premium grades depend on extended OEM validation, so design wins can take time and shift with platform cycles. Feedstock-linked price volatility and the availability of lower-cost substitutes, such as stabilized PA66 blends, also pressure adoption in price-sensitive applications where performance gains do not clearly offset the cost premium.
A clear opportunity lies in application-specific high-value grades for EV power electronics, compact connectors, and lightweight structural parts. Carbon fiber filled PPA and low-carbon formulations can win content where designers need stiffness, thermal endurance, and sustainability credentials together. Producers that combine reinforcement design, fast qualification, and regional technical support can convert these niches into recurring platform wins.
Market Concentration & Characteristics
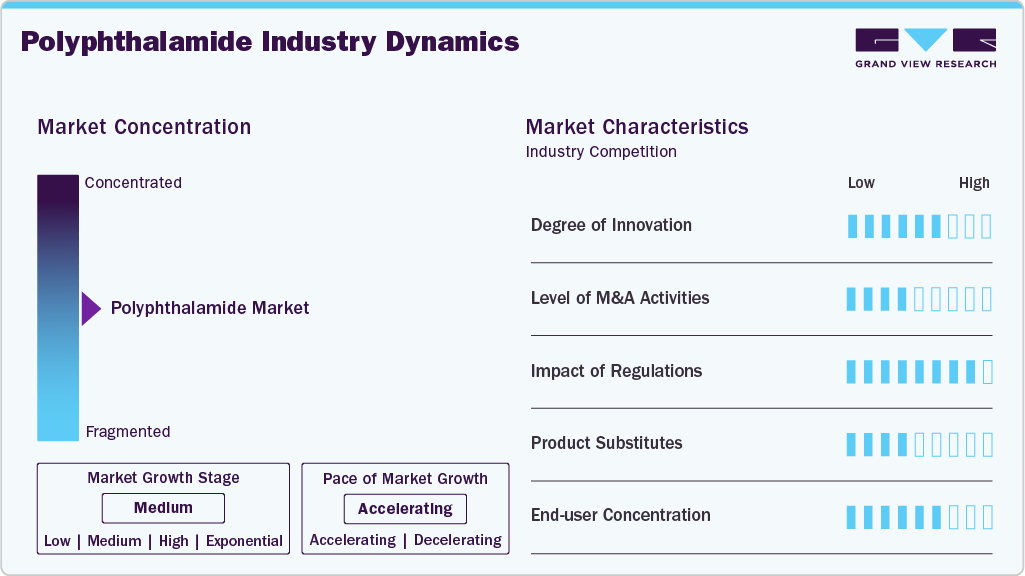
The growth stage of the industry is medium, and the pace is accelerating. The industry exhibits slight fragmentation, with key players dominating the industry landscape. Major companies like BASF SE, Arkema, Celanese Corporation, Akro-Plastic, Evonik Industries AG, Syensqo, SABIC, KURARAY CO., LTD., Ems-Chemie, RTP Company Inc., Xiamen Keyuan Plastic Co., Ltd., Teknor Apex, and others play a significant role in shaping the market dynamics. These leading players often drive innovation within the market, introducing new products, technologies, and applications to meet evolving industry demands.
Innovation in the PPA space is increasingly pragmatic and application-led: suppliers are tuning chemistry and compounding to deliver flame-retardant, high-flow, and fiber-reinforced grades specifically tailored for electric vehicle power electronics and high-density connectors, rather than pursuing one-size-fits-all resins. Parallel R&D trajectories focus on bio-derived monomers and lower-carbon production routes to meet OEM sustainability mandates, and on engineered blends that marry PPA performance with improved processability and cost parity versus PA66.
 To learn more about this report, Download Free Sample Report
Substitution dynamics vary by performance tier: in mid-performance applications, engineered PA66 or PA6/PA66 blends with improved stabilization compete on price and established supply chains, while premium niches requiring extreme thermal or chemical resistance still default to polymers such as PEEK, PPS, or polyimides, or to metal alloys when structural rigidity and fatigue resistance are paramount.
Analyst Perspective
The PPA market is moving from a niche high-performance polymer position toward a more mainstream, value-led engineering material platform. Over the next 5 to 10 years, demand will be shaped by electrified mobility, compact power electronics, and higher-density electrical assemblies, with Asia Pacific remaining the center of gravity and India adding stronger growth momentum. Leaders will be the suppliers that combine reinforced grade development, fast application qualification, regional technical support, and credible sustainability progress through lower-carbon chemistries and material efficiency. The market will reward companies that can replace metal, stabilize performance in thermal cycling, and tailor grades to specific connectors, housings, and structural parts. Profitability will remain exposed to raw material volatility, high processing costs, and substitution from lower-cost engineering nylons, so differentiation will depend on formulation depth, OEM relationships, and application-specific innovation rather than volume alone.
Product Insights
Based on product, the unfilled polyphthalamide segment led the market with the largest revenue share of 33.7% in 2025. For unfilled PPA grades, the key commercial driver is process economics allied with formulation flexibility. Unfilled PPA offers easier flow and colorability versus fiber-filled grades, enabling efficient injection molding of thin-walled consumer and general industrial parts where extreme stiffness is not required but thermal resistance and chemical robustness still matter. This combination lowers conversion cost and shortens cycle time for mid-volume runs, which makes unfilled PPA the logical choice for appliance housings, fluid-handling components, and other price-sensitive applications that need dependable long-term performance.
The carbon fiber filled segment is anticipated to grow at a substantial CAGR of 8.4% over the forecast period. The defining driver for carbon fiber filled PPA is performance-driven lightweighting for precision structural components. Carbon fiber reinforcement delivers a step-change in stiffness, dimensional stability, and thermal conductivity, allowing designers to replace metal subassemblies in premium automotive and aerospace applications while meeting tight tolerances under thermal cycling. As design engineers push for lower mass without sacrificing heat management or creep resistance, demand for CF-PPA in niche, high-value parts is accelerating, supported by suppliers developing optimized CF coupling and processing packages.
Application Insights
Based on application, the automotive segment led the market with the largest revenue share of 45.7% in 2025. Automotive adoption is being pulled by the shift to electrified powertrains and the need to consolidate parts in thermally demanding environments. PPA is increasingly specified for high-voltage connectors, inverter housings, and under-hood plumbing because it withstands continuous elevated temperatures, resists automotive fluids, and reduces electrochemical corrosion risk compared with aliphatic nylons. OEMs and tier suppliers are therefore prioritizing PPA where durability and safety at elevated voltages are prerequisites, which raises content per vehicle even as overall weight and part count fall.
 To learn more about this report, Download Free Sample Report
The electronics & electrical segment is expected to expand at a substantial CAGR of 7.5% through the forecast period. Miniaturization and higher power densities in electronics are creating a clear technical demand for PPA in E&E components. High flow, heat-stable PPA grades permit production of compact, high-voltage connectors, IGBT, and power module housings that require excellent dielectric strength and low moisture uptake to preserve signal integrity and long-term insulation. The need to manage localized heat in denser assemblies while maintaining tight dimensional tolerances means PPA innovations focused on flowability and flame retardance are rapidly gaining traction with connector and power electronics makers.
Regional Insights & Trends
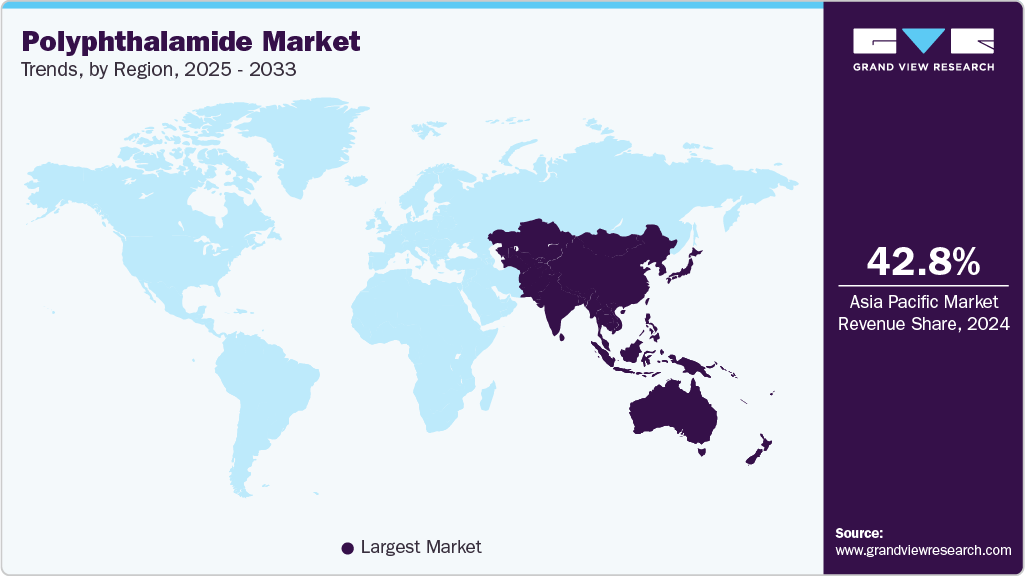
Asia Pacific dominated the polyphthalamide market with the largest revenue share of 43.0% in 2025. Rapid electrification and continued electronics manufacturing scale-up are the twin demand engines in the Asia Pacific. Growing EV volumes across India, Southeast Asia, and Japan, together with massive electronics and connector production in the region, are increasing technical specifications for materials that withstand continuous high temperatures and aggressive chemistries. Local compounders who offer tailored, high-flow, and flame-retardant PPA grades alongside supply-chain agility are therefore capturing share as OEMs compress development cycles and prioritize regional sourcing.
 To learn more about this report, Download Free Sample Report
The polyphthalamide market in China accounted for the largest market revenue share in the Asia Pacific in 2025. China’s polyphthalamide market’s driver is market scale plus industrial policy: very high EV penetration and government nudges to expand domestic content across automotive electronics and semiconductors amplify demand for high-performance polymers in powertrain and power-electronics assemblies. As carmakers and suppliers accelerate verticalization and local procurement, materials that enable lightweighting and thermal management at volume, such as reinforced and flame-retardant PPA grades, are being prioritized for local design wins and large-scale production.
North America Polyphthalamide Market Trends
The polyphthalamide market in North America is influenced by policy-led onshoring and electrification that is reshaping automotive and component supply chains. Incentives and tax credits tied to domestic sourcing have pushed OEMs and tier suppliers to localize battery, power electronics, and connector production, which increases demand for high-performance engineering polymers like PPA that meet thermal and chemical requirements while being manufacturable at scale. Converters and compounders are therefore investing in U.S.-based capacity and technical support to win design-ins with vehicle and industrial OEMs.
U.S. Polyphthalamide Market Trends
In the U.S. polyphthalamide market, the dominant commercial lever is legislative stimulus for clean-technology manufacturing that raises the content-per-vehicle for specialty polymers. Programs created under the recent industrial policy have accelerated investment in battery and power-electronics assembly, creating near-term procurement preferences for locally supplied, high-temperature plastics; this favors PPA for high-voltage connectors, inverter housings, and thermal-management components. Suppliers that can provide validated processing guidance and local inventory are winning priority from OEMs and tiers.
Europe Polyphthalamide Market Trends
The polyphthalamide market in Europe is driven by regulatory pressure toward sustainability and sovereign industrial capability, which is prompting automakers and system suppliers to demand materials that support lighter, longer-life components and easier recycling-ready design. Proposed European measures to boost EV demand and local battery content, alongside stricter circular-economy rules for vehicle design, are pushing OEMs to specify polymers that enable part consolidation and extended service life; PPA’s thermal endurance and chemical resistance fit this brief, particularly where flame retardance and long-term dimensional stability are required.
Key Polyphthalamide Companies Insights
Key players operating in the polyphthalamide market are undertaking various initiatives to strengthen their presence and increase the reach of their products and services. Strategies such as expansion activities and partnerships are key in propelling the market growth.
Key Polyphthalamide Companies:
The following key companies have been profiled for this study on the polyphthalamide market.
-
BASF SE
-
Arkema
-
Celanese Corporation
-
Akro-Plastic
-
Evonik Industries AG
-
Syensqo
-
SABIC
-
KURARAY CO., LTD.
-
Ems-Chemie
-
RTP Company Inc.
-
Xiamen Keyuan Plastic Co., Ltd
-
Teknor Apex
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (BASF SE, Arkema, Celanese Corporation, Evonik Industries AG, Syensqo, SABIC, KURARAY CO., LTD., Ems-Chemie, RTP Company Inc., Teknor Apex)
- Expand reinforced and heat-stabilized PPA portfolios for EV, connector, and compact electrical assemblies.
- Use global application labs and long OEM qualification cycles to secure design-in positions.
- Bundle PPA with broader engineering polymer and compounding portfolios to defend key accounts.
- Strong scale and technical service depth across automotive and electronics channels.
- Established qualification history with multinational OEMs and tier suppliers.
- Broader formulation capability for filled, flame-retardant, and custom compounds.
- Slower response to niche design changes than smaller compounders.
- Higher cost structure and longer approval cycles in new accounts.
- Greater exposure to pricing pressure in mature application segments.
Emerging Players (Akro-Plastic, Xiamen Keyuan Plastic Co., Ltd.)
- Focus on targeted compounding, regional customer support, and fast formulation changes.
- Compete in niche grades where tailored performance matters more than scale.
- Use price agility and shorter development cycles to win local programs.
- Faster customization for application-specific grades.
- Closer alignment with regional buyers and shorter lead times.
- Leaner operating structure that supports quicker commercial decisions.
- Limited global brand recognition and fewer long-cycle OEM approvals.
- Smaller technical service footprint across major end-use regions.
- Narrower product breadth and weaker protection against large-scale price competition.
Recent Developments
-
In September 2025, Syensqo launched a new medical-grade Amodel polyphthalamide (PPA) designed for advanced single-use medical devices. The glass-filled polymer offered high heat resistance with a melting point over 300 °C and maintained strength at temperatures up to 280 °C, making it ideal for manufacturing processes like surface-mount technology assembly and infrared reflow.
-
In July 2025, SIBUR, Russia's largest polymer producer, began manufacturing a high-performance plastic, polyphthalamide (PPA), using its proprietary technology. This plastic is strong, stable, and resistant to harsh environments, making it suitable for food and pharmaceutical packaging films, automotive engine parts, electrical components, and industrial equipment like pumps and compressors.
Polyphthalamide Market Report Scope
Report Attribute
Details
Market size in 2025
USD 3.2 billion
Estimated market size in 2026
USD 3.4 billion
Projected market size by 2033
USD 5.6 billion
Growth rate
CAGR of 7.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, volume in kilotons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product type, application, region
RegioFinal scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; France; UK; Spain; Italy; China; Japan; India; South Korea; Brazil; Argentina; Saudi Arabia; South Africa; UAE
Key companies profiled
BASF SE; Arkema; Celanese Corporation; Akro-Plastic; Evonik Industries AG; Syensqo; SABIC; KURARAY CO., LTD.; Ems-Chemie; RTP Company Inc.; Xiamen Keyuan Plastic Co., Ltd.; Teknor Apex
Customization scope
Free report customization (equivalent to up to 8 analysts' working days) with purchase addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Polyphthalamide Market Report Segmentation
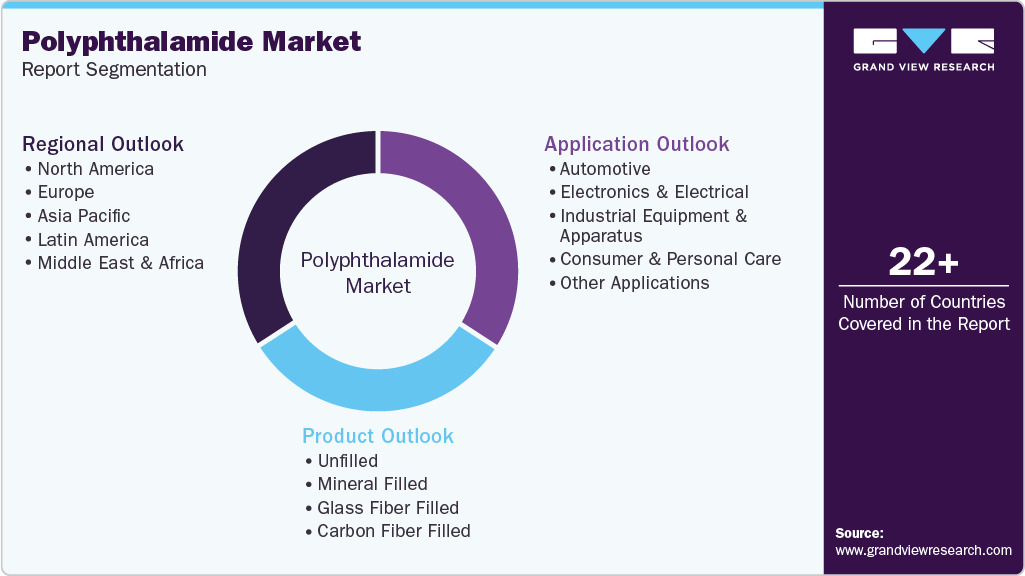
This report forecasts volume & revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global polyphthalamide market report on the basis of product, application, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Unfilled
-
Mineral Filled
-
Glass Fiber Filled
-
Carbon Fiber Filled
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Automotive
-
Electronics & Electrical
-
Industrial Equipment & Apparatus
-
Consumer & Personal Care
-
Other Applications
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
UAE
-
-
Research Methodology
The polyphthalamide market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each polyphthalamide segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product Type
Revenue capture definition
Unfilled
Revenue is captured through standard PPA resin sales for thin-wall molded parts where flow, colorability, and process economics matter more than reinforcement.
Mineral Filled
Revenue is generated from compounds using mineral fillers to improve dimensional stability, warp control, stiffness, and cost-performance balance in mid-load parts.
Glass Fiber Filled
Revenue comes from reinforced grades sold into high-stiffness structural applications that require heat resistance, chemical durability, and stable molding performance.
Carbon Fiber Filled
Revenue is captured through premium reinforcement grades for lightweight, precision parts that need higher stiffness, thermal conductivity, and tighter tolerance retention.
Segment - Application
Revenue capture definition
Automotive
Revenue is generated from PPA sold into connectors, housings, fluid handling parts, and electrified powertrain components supplied to OEMs and Tier suppliers.
Electronics & Electrical
Revenue is captured through high-voltage connectors, sockets, switch components, and compact device parts where dielectric strength and thermal stability drive qualification.
Industrial Equipment & Apparatus
Revenue is generated from pumps, valves, compressor parts, and mechanical housings that need chemical resistance, durability, and stable long-life performance.
Consumer & Personal Care
Revenue comes from appliance housings, compact consumer devices, and care equipment components where aesthetics, heat stability, and moldability support adoption.
Other Applications
Revenue is captured from niche uses in aerospace, medical, telecom, and energy equipment where low-volume, high-value compounds are sold against specifications.
Estimation Model
Layer Name
Key Question
Description
Demand Mapping Layer
Why assess demand first?
It fixes the base PPA volume pool from automotive, electronics, and industrial demand before mix adjustments.
Product Value Layer
Why evaluate product mix?
Filled grades command different pricing and margin structures, so product mix drives revenue more than tonnage.
Application Validation Layer
Why validate end-use demand?
End-use qualification, part geometry, and temperature exposure determine which segments actually convert into realized sales.
Regional Calibration Layer
Why calibrate regional trends?
Asia Pacific-led electronics and automotive concentration skew pricing, qualification speed, and supplier access across the forecast.
Delivered Customizations
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
Regional coverage
Added regional commentary for Asia Pacific, North America, and Europe, with demand concentration tied to electronics manufacturing, automotive electrification, and premium engineering polymer adoption.
Improves geographic relevance for buyers tracking region-specific qualification and demand build-out.
Product mix detail
Broke out unfilled, mineral filled, glass fiber filled, and carbon fiber filled grades with commercial revenue logic tied to pricing, reinforcement, and end-use intensity.
Helps distinguish volume-led grades from high-margin specialty compounds.
Company benchmarking
Classified major producers into mature and emerging players with operating strategies, competitive edge, and weaknesses for a clearer competitive landscape view.
Supports supplier positioning, white-space identification, and account strategy.
Frequently Asked Questions About This Report
The unfilled polyphthalamide industry led the polyphthalamide product type market in 2025 with a 33.7% share. Growing demand from automotive, electronics, electrical, industrial equipment, and consumer product industries, coupled with advances in polymer synthesis, precision injection molding, and resin formulation technologies, is accelerating the adoption of unfilled polyphthalamide (PPA) for lightweight, dimensionally stable, electrically insulating, and high-temperature engineering components requiring superior surface finish and processing efficiency.
Some key players operating in the polyphthalamide market include Celanese Corporation, Evonik Industries AG, Arkema, Solvay, BASF SE, SABIC, EMS-CHEMIE HOLDING AG, RTP Company, Syensqo, DuPont, Xiamen Keyuan Plastic Co.,Ltd, and Teknor Apex.
The polyphthalamide market was estimated at around USD 3.2 billion in the year 2025 and is expected to reach around USD 3.4 billion in 2026.
The polyphthalamide market is expected to grow at a compound annual growth rate of 7.4% from 2026 to 2033 to reach around USD 5.6 billion by 2033.
The Asia Pacific polyphthalamide market accounted for the largest share of 43.0% market size in 2025.
Key factors that are driving the market growth include rising demand from the automotive industry around the world, where PPA is valued for its superior thermal stability, mechanical strength, and chemical resistance.
Based on application, the automotive segment accounted for the largest share of 45.7% market size in 2025. Growing vehicle production, increasing electric vehicle adoption, and rising automotive lightweighting initiatives, together with advances in glass fiber reinforced formulations and high-temperature polymer technologies, are accelerating polyphthalamide (PPA) adoption for under-the-hood components, electrical connectors, fluid management systems, structural assemblies, and lightweight automotive applications.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


