
- Home
- »
- Clinical Diagnostics
- »
-
Population Screening Market Size, Share Report, 2026-2033GVR Report cover

Population Screening Market (2026 - 2033)
Size, Share & Trends Analysis Report By Geography, By Business (Hospitals, Diagnostic Labs), By Product (Hardware Equipment, Testing / Lab, Analytics / Interpretation), By Gender, By Type, By Age, By Region, And Segment Forecasts
Market Size, 2025
$38.5BMarket Estimate, 2026
$41.1BMarket Forecast, 2033
$66.1BCAGR, 2026–2033
7.0%Population Screening Market Summary
The global population screening market size was valued at USD 38.5 billion in 2025 and is projected to grow from USD 41.1 billion in 2026 to USD 66.1 billion in 2033, at a CAGR of 7.0% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 42.5% in 2025. The market is witnessing growth due to factors such as the increasing prevalence of chronic and non-communicable diseases among physicians & patients, which is propelling demand for screening products.
Key Market Trends & Insights
- By geography: The nation segment dominated the market in 2025.
- By product: The hardware equipment segment held the largest revenue share of over 62.5% in 2025.
- By business: The hospital segment accounted for the largest revenue of over 52.0% in 2025.
- By gender: The male segment held the largest revenue share of over 50.5% in 2025.
- By type: The mass segment accounted for the largest share of over 73.5% in 2025.
- By age: The 15-65 years’ segment dominated the market and held the largest revenue share of over 60.5% in 2025.
Regional Highlights
- Largest regional market: North America (42.5% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 38.5 Billion
- Estimated market size in 2026: USD 41.1 Billion
- Projected market size by 2033: USD 66.1 Billion
- CAGR (2026-2033): 7.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
A direct answer, usually in 1 working day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Population screening is being adopted as a major strategy owing to benefits such as early patient identification, which can help reduce the burden of higher treatment costs for diseases at later stages. The rising prevalence of cancer is a key driver of market growth over the forecast period. This rise in the number of cancer cases is expected to compel governments to initiate new programs for cancer screening of the population. Early detection through population-based screening has been shown to significantly improve survival and reduce downstream treatment costs, as cancers identified at an early, localized stage are generally far more treatable than those diagnosed after symptoms have developed. As a result, health systems across both developed and emerging economies are increasingly incorporating advanced screening modalities, including imaging-based, molecular, and genomic tests, into routine public health programs rather than relying solely on traditional methods.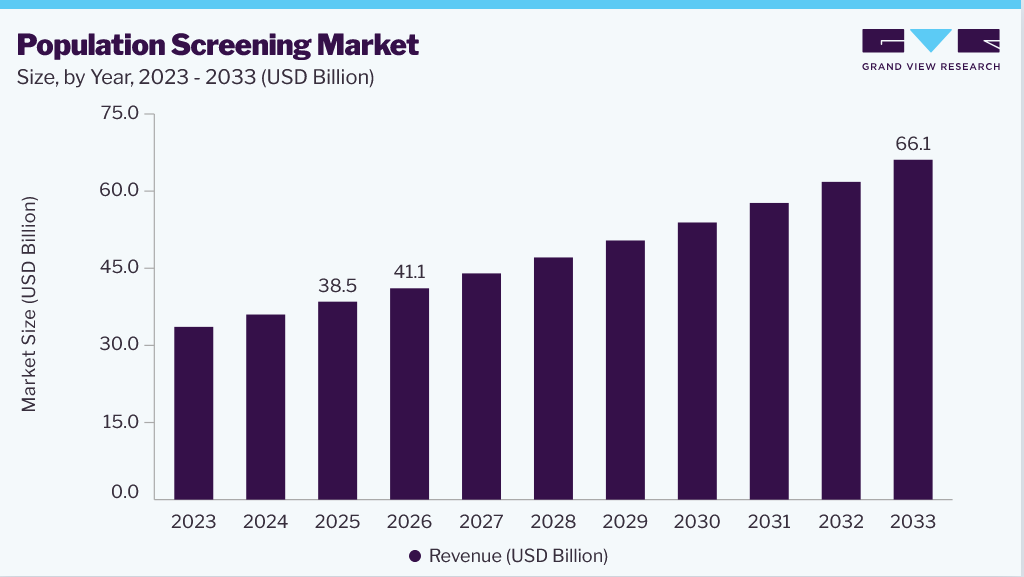 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Furthermore, increasing investment in population screening programs is projected to drive market growth. For instance, in October 2025, GeneDx joined the BEACONS (Building Evidence and Collaboration for Genomics in Nationwide Newborn Screening) initiative, launched with a USD 14.4 million award from the U.S. National Institutes of Health (NIH). The multi-state program aims to evaluate the integration of whole-genome sequencing into newborn screening systems, highlighting growing investments in large-scale genomic screening and early disease detection programs.
Analyst Perspective
The market is experiencing steady growth, driven by the rising prevalence of chronic and genetic diseases, increased government investment in early detection programs, and growing awareness of preventive healthcare. Advances in genomic technologies, digital health infrastructure, and large-scale screening initiatives are improving diagnostic accuracy and expanding access to screening services. While challenges related to high implementation costs, data management, and healthcare infrastructure persist, continued public health funding and the increasing emphasis on early diagnosis are expected to support sustained market growth over the forecast period.
Geography Insights
The nation segment dominated the market in 2025 by geography, and it is expected to be the fastest-growing segment over the forecast period. This can be attributed to the wide availability of population screening programs for various diseases at the national level. In the U.S., the U.S. Preventive Services Task Force (USPSTF) is the primary governing body that works with the CDC to recommend programs for the population. Furthermore, governments are also extending population screening infrastructure to cover other preventable chronic conditions. For instance, in April 2025, the United Kingdom strengthened its NHS Health Check program, enhancing nationwide preventive screening coverage for adults aged 40-74 years to improve early detection of risk factors for cardiovascular disease, diabetes, and stroke.
The states segment is expected to show lucrative growth during the forecast period. The rules and regulations for population screening vary by nation and state. In the U.S., every state regulates and manages its screening programs. For instance, in October 2024, the Karnataka state government in India took a leading role in expanding doorstep population health screening. The state launched the 'Gruha Arogya Yojane' (Home Health Scheme), piloting door-to-door screening for non-communicable diseases, including diabetes, hypertension, and oral, breast, and cervical cancers, for residents aged 30 and above. Following its success, the Karnataka government announced the statewide expansion of the program in June 2025, extending coverage to rural areas across all districts.
Product Insights
The hardware equipment (instruments, kits, chips) segment held the largest revenue share of over 62.5% in 2025. This can be attributed to the approval of novel test kits and equipment for the population screening of more diseases. The increasing implementation of national and regional screening programs for cancer, genetic disorders, infectious diseases, and metabolic conditions is further driving demand for advanced screening instruments and consumables. In addition, continuous technological advancements in molecular diagnostics, next-generation sequencing, microarray technologies, and point-of-care testing platforms are enhancing screening accuracy and efficiency. The recurring demand for test kits, reagents, and disposable screening components across healthcare facilities and diagnostic laboratories is also contributing significantly to segment growth.
The testing/lab segment is expected to show the fastest growth over the forecast period. The most common tests performed globally for various diseases include cholesterol measurement, fecal occult blood test, Pap test, prostate-specific antigen, mammography, colonoscopy, and diabetes screening. High cholesterol level is associated with a high risk of stroke & cardiovascular disorders and is a major cause of death. The CDC recommends cholesterol screening for people aged 20 years or older. Thus, the importance of population screening for diseases has increased in recent years and is expected to continue to increase over the forecast period.
Business Insights
The hospital segment accounted for the largest revenue share of over 52.0% in 2025. Hospitals have experts who can assist patients in selecting appropriate population screening tests. Factors contributing to market growth include the increasing prevalence of chronic diseases, the availability of multiple testing options, and the launch of new tests for improved and more effective patient screening. For instance, in December 2025, Ram Sagar Mishra Joint Hospital in Lucknow significantly expanded its diagnostic and cancer screening capabilities by introducing multiple pathology and tumor marker tests, including CA125, CA19.9, PSA, and Pap smear tests under government-supported facilities, enabling early detection of cancer and improving access to population-based screening in rural and semi-urban regions.
The research Institutes segment is expected to show the fastest growth during the forecast period. The segment's growth is associated with increased research activities to identify candidates and establish patient diagnoses for research participation, which is anticipated to drive market growth. For instance, in February 2024, the U.S. National Cancer Institute (NCI), under the National Institutes of Health (NIH), launched the Cancer Screening Research Network (CSRN) and initiated the Vanguard Study to evaluate emerging multi-cancer early detection (MCED) technologies. The program aims to assess blood-based screening tools across diverse populations to determine their effectiveness in early cancer detection and potential integration into future population screening guidelines.
Gender Insights
The male segment dominated the market, accounting for over 50.5% of revenue in 2025. The most commonly recommended health screening tests for men are abdominal aortic aneurysm, blood cholesterol, blood cancer, colon cancer, depression, diabetes, hepatitis C virus, HIV, obesity, and prostate cancer. The increasing prevalence of prostate cancer is anticipated to boost the demand for population screening products. For instance, in July 2025, Harvard Health Publishing highlighted ongoing clinical consensus that PSA-based prostate cancer screening remains a shared decision-making approach for men, particularly those aged 50-69 years, as evolving evidence continues to refine risk-benefit evaluation for early detection and overdiagnosis in population screening programs.
The female segment accounted for a significant share of revenue in 2025. The most commonly used tests for females are Pap smear, pelvic examination, mammogram, thyroid function test, lipid panel, and blood pressure test. The Pap smear test is mainly recommended for women screening for cervical cancer. For instance, in January 2026, the American Cancer Society (ACS) updated its cervical cancer screening guidelines, expanding the use of primary HPV testing and endorsing self-collected vaginal samples for screening among women aged 25-65 years. The updated recommendations aim to improve screening accessibility and early detection of cervical cancer, which is primarily caused by human papillomavirus (HPV), thereby strengthening participation in population-based female screening programs.
Type Insights
The mass segment accounted for the largest revenue share of over 73.5% in 2025. Mass screening programs are increasingly being implemented to identify undiagnosed diseases at an early stage, enabling timely treatment and improving patient outcomes. Aside from Tuberculosis (TB), routine premarital testing services for infectious and genetic diseases, as well as population-wide screening programs for the early detection of cancers, are contributing to segment growth. The increasing focus of governments and public health organizations on preventive healthcare, disease surveillance, and reducing long-term healthcare costs is further supporting the adoption of large-scale screening initiatives. In addition, advancements in diagnostic technologies and the expansion of national screening programs for conditions such as cardiovascular diseases, diabetes, and hereditary disorders are enhancing the reach and effectiveness of mass screening efforts. Growing public awareness regarding the benefits of early diagnosis and regular health assessments is also driving participation in these programs.
The premium segment is expected to show the fastest growth during the forecast period. The premium market is driven by the private programs launched by key players. For instance, in November 2025, Hims & Hers Health partnered with Quest Diagnostics to expand access to preventive lab-based population screening, enabling customers to undergo biomarker testing across more than 1,000 Quest service centers in the United States. The program integrates digital health platforms with large-scale diagnostic infrastructure, allowing users to receive screening results and personalized health insights for conditions such as cardiovascular risk, metabolic disorders, and hormonal imbalances. This reflects the growing shift toward subscription-based, private, and technology-enabled premium screening models.
Age Insights
The 15-65 years segment dominated the market and held the largest revenue share of over 60.5% in 2025. The segment's dominance is attributed to the growing population in the 15-65 age group. Individuals between the ages of 15 and 65 years are at a higher risk of developing non-communicable diseases (NCDs) and various cancers, including breast, cervical, prostate, lung, leukemia, and colorectal cancer. As a result, healthcare providers and public health agencies are increasingly focusing on regular screening and early detection programs targeting this population. Furthermore, growing awareness regarding preventive healthcare, rising participation in workplace wellness initiatives, and expanding government-sponsored screening programs are supporting segment growth. The increasing adoption of genetic testing, cancer screening, and routine health assessments among working-age adults is also driving strong demand for population screening services in this age group.
The 65+ segment is expected to show the fastest growth over the forecast period. The segment's growth is attributed to the growing dominance of the geriatric population. The age group is at a high risk of developing NCDs such as Cardiovascular Disorders (CVD), diabetes, cancers, and metabolic disorders due to weak immune systems and high comorbid conditions. According to the WHO, life expectancy is likely to exceed 80 years in most developed economies by 2050. Aging is influenced by the interaction of several environmental & genetic factors and is characterized as the single most substantial risk factor for cancer development.
Regional Insights
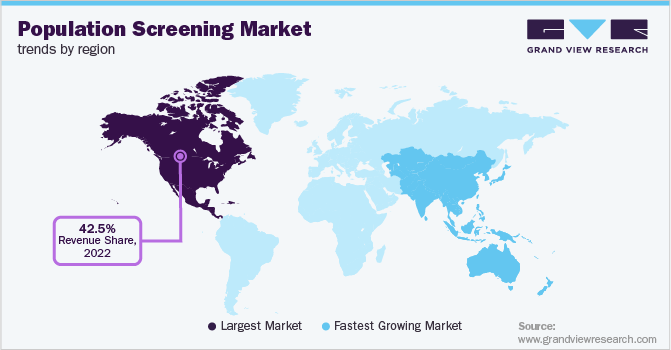
North America dominated the market, accounting for over 42.5% of revenue in 2025. This growth is attributed to preventive measures undertaken by governments to stop the progression of diseases. In North America, the U.S. and Canada are two major markets for population screening due to high patient and physician awareness of its benefits. For instance, in April 2025, according to the U.S. Centers for Disease Control and Prevention (CDC), tuberculosis (TB) testing in healthcare settings is focused on targeted screening of individuals at increased risk, including those with known exposure, symptoms of TB disease, or occupational risk, such as healthcare personnel. The CDC emphasizes that TB testing should be accompanied by proper clinical evaluation and follow-up to ensure early detection and treatment of latent TB infection, thereby supporting TB elimination efforts through preventive population screening strategies in the United States.
 To learn more about this report, Download Free Sample Report
Asia Pacific Population Screening Market Trends
The population screening market in the Asia Pacific is expected to be the fastest-growing region over the forecast period. Japan is expected to be the major market in the Asia-Pacific region due to increasing investment in screening and supportive reimbursement policies. For instance, in April 2026, the World Economic Forum highlighted Japan’s national focus on strengthening cancer care through innovation and early detection strategies, with the government prioritizing improved screening participation, advanced diagnostic technologies, and coordinated public-private efforts to enhance early diagnosis and patient outcomes. This reflects Japan’s broader shift toward preventive healthcare models aimed at improving cancer survival rates through structured population screening programs.
Key Population Screening Company Insights
The key players operating in the market are focusing on partnerships, geographical expansion, and strategic collaborations in emerging and economically favorable regions.
Key Population Screening Companies
The following key companies have been profiled for this study on the population screening market.
-
Agilent Technologies, Inc.
-
Thermo Fisher Scientific, Inc.
-
QIAGEN
-
F. Hoffmann-La Roche Ltd.
-
Quest Diagnostics
-
Illumina, Inc.
-
ARUP Laboratories
-
Novogene Co., Ltd.
-
LGC Limited
-
Gene by Gene, Ltd.
Recent Developments
-
In March 2026, Agilent Technologies agreed to acquire Biocare Medical for USD 950 million, expanding its pathology and oncology diagnostics portfolio to strengthen its cancer diagnostic capabilities for screening-adjacent laboratory workflows.
-
In May 2025, QIAGEN acquired Genoox for USD 70 million, adding the Franklin AI-powered genomic interpretation platform to strengthen clinical genomics workflows for genetic disease diagnosis and screening.
-
In July 2024, Thermo Fisher Scientific completed its acquisition of Olink Holding, adding next-generation proteomics technology to support biomarker discovery that will underpin future screening and diagnostic applications.
Population Screening Market Report Scope
Report Attribute
Details
Market size in 2025
USD 38.5 billion
Estimated market size in 2026
USD 41.1 billion
Projected market size by 2033
USD 66.1 billion
Growth rate
CAGR of 7.0% from 2026 to 2033
Base year for estimation
2025
Actual data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Geography, product, business, gender, type, age, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Germany; UK; France; Italy; Spain; Denmark, Sweden, Norway, China; Japan; India; Australia; Thailand, South Korea; Brazil; Mexico; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Agilent Technologies, Inc., Thermo Fisher Scientific, Inc., QIAGEN, F. Hoffmann-La Roche Ltd., Quest Diagnostics, Illumina, Inc., ARUP Laboratories, Novogene Co., Ltd., LGC Limited, Gene by Gene, Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Population Screening Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global population screening market report based on geography, product, business, gender, type, age, and region:
-
Geography Outlook (Revenue, USD Million, 2021 - 2033)
-
Nation
-
State
-
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Hardware Equipment (Instrument, Kits, Chips)
-
Testing / Lab (Services)
-
Analytics / Interpretation (Personalization And Interpretation)
-
-
Business Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Research Institutes
-
Diagnostic Labs
-
-
Gender Outlook (Revenue, USD Million, 2021 - 2033)
-
Male
-
Female
-
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Mass
-
Premium
-
-
Age Outlook (Revenue, USD Million, 2021 - 2033)
-
Ages <15
-
15-65
-
Ages 65+
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Mexico
-
Argentina
-
-
Middle East and Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Frequently Asked Questions About This Report
The global population screening market size was valued at USD 38.5 billion in 2025 and is estimated at USD 41.1 billion for 2026.
The global population screening market is expected to grow at a CAGR of 7.0% from 2026 to 2033, reaching USD 66.1 billion by 2033.
North America dominated with a 42.5% revenue share in 2025.
Some key players operating in the population screening market include Agilent Technologies, Inc., Thermo Fisher Scientific, Inc., QIAGEN, F. Hoffmann-La Roche Ltd., Quest Diagnostics, Illumina, Inc., ARUP Laboratories, Novogene Co., Ltd., LGC Limited, and Gene by Gene, Ltd.
Hardware equipment dominated the hardware equipment market with a share of 62.5% in 2025, while testing/lab is the fastest-growing segment.
About the Author(s)
Clinical Diagnostics Research Team
Industry · Clinical DiagnosticsThis report was authored by the clinical diagnostics research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the clinical diagnostics segment of the industry industry. All findings are based on proprietary industry databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


