
- Home
- »
- Agrochemicals & Fertilizers
- »
-
Post-Harvest Treatment Market Size Report, 2026-2033GVR Report cover

Post-Harvest Treatment Market (2026 - 2033)
Size, Share & Trends Analysis Report By Origin (Natural, Synthetic), By Product (Coatings, Cleaners, Fungicides, Insecticides), By Application (Cereals & Grains, Oilseeds & Pulses), By Region, And Segment Forecasts
Market Size, 2025
$11.8BMarket Estimate, 2026
$12.8BMarket Forecast, 2033
$23.6BCAGR, 2026–2033
9.2%Post-Harvest Treatment Market Summary
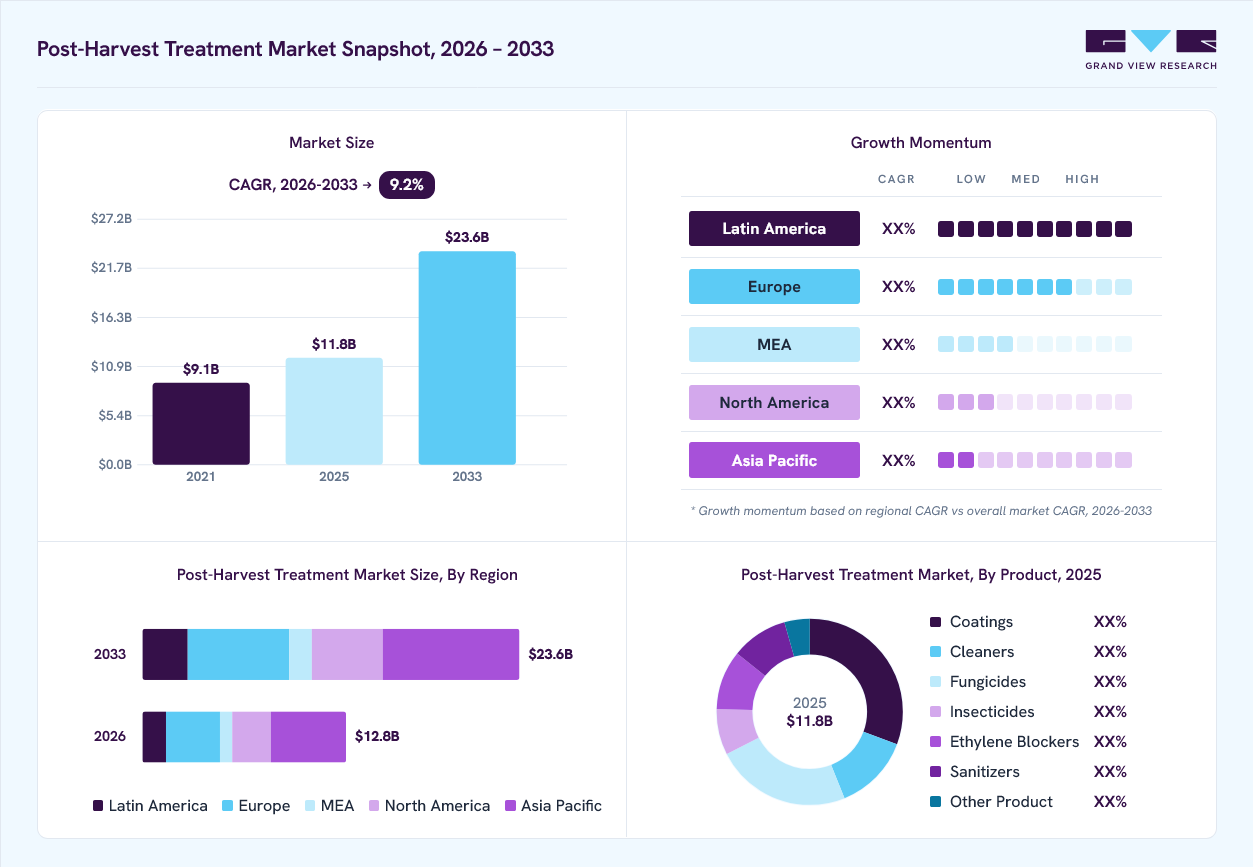
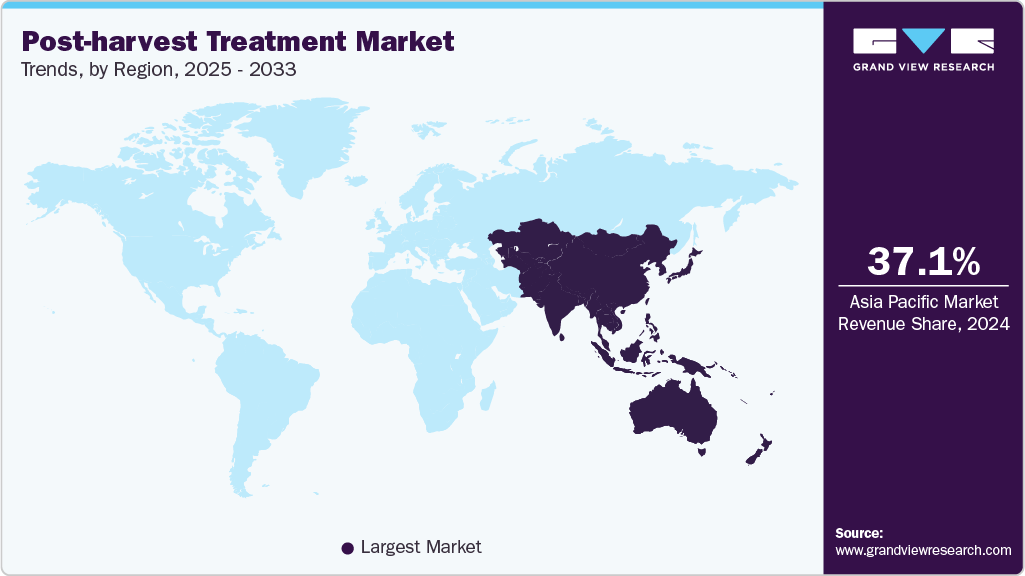
The global post-harvest treatment market size was valued at USD 11.8 billion in 2025 and is projected to grow from USD 12.8 billion in 2026 to USD 23.6 billion by 2033, at a CAGR of 9.2% from 2026 to 2033. The market in Asia Pacific dominated with a revenue share of 37.0% in 2025. The market is primarily driven by the increasing demand for fresh and high-quality produce, rising concerns over food loss and waste, and the expansion of global trade in perishable agricultural commodities.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By origin: Synthetic segment held the largest market share of 62.3% in 2025.
- By product: Ethylene blockers segment held the largest market share of 31.4% in 2025.
- By application: Fruits & vegetables segment held the largest market share of 46.8% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (37.0% revenue share, 2025)
- By country: China held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 11.8 Billion
- Estimated market size in 2026: USD 12.8 Billion
- Projected market size by 2033: USD 23.6 Billion
- CAGR (2026-2033): 9.2%
Prism AI by Grand View Research Free to tryAsk a question about the Post-Harvest treatment marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
In addition, growing consumer preference for residue-free and organic fruits and vegetables, coupled with stringent food safety regulations, is accelerating the adoption of both natural and synthetic post-harvest solutions. Advancements in post-harvest technologies and cold chain infrastructure are further supporting market growth across developed and emerging economies.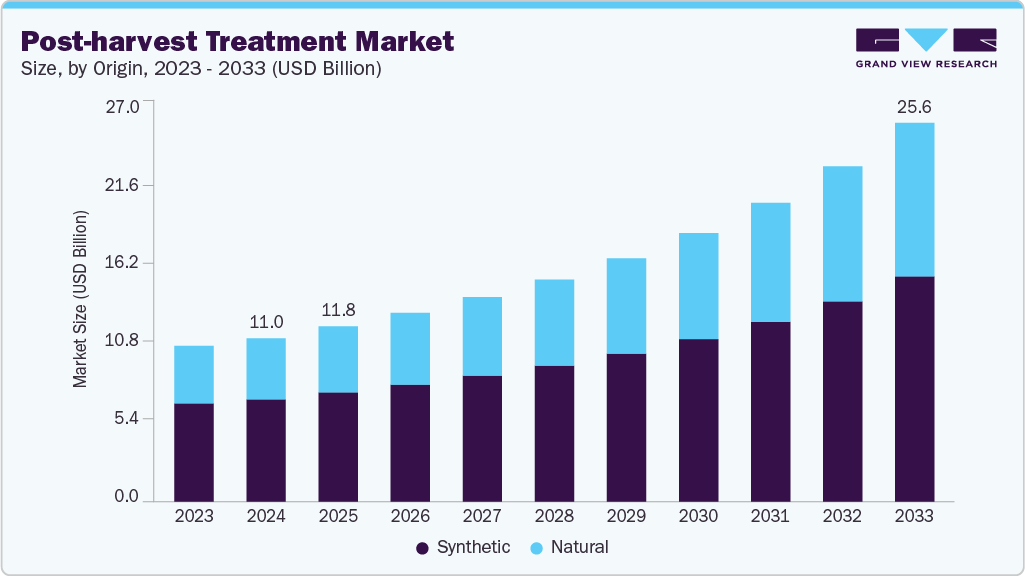 To learn more about this report, Download Free Sample Report
The market presents significant growth opportunities driven by increasing global demand for fresh produce, expanding international trade of perishables, and heightened focus on reducing food loss across the value chain. Emerging markets in Asia Pacific, Latin America, and Africa offer strong potential due to the modernization of agricultural practices, rising investments in cold chain infrastructure, and favorable government initiatives to minimize post-harvest wastage. The growing shift toward sustainable agriculture and organic produce is creating demand for bio-based and residue-free treatment solutions, opening doors for innovation and product differentiation.
Despite its growth potential, the market faces several challenges, including stringent regulatory frameworks surrounding the use of chemical-based treatments and growing scrutiny over pesticide residues and food safety. High dependency on synthetic products in cost-sensitive markets poses a barrier to the adoption of natural alternatives, which are often more expensive. The lack of awareness and inadequate infrastructure in developing regions limit the implementation of effective post-harvest solutions. The variability in climatic and logistical conditions complicates uniform application across diverse geographies and crop types.
Market Dynamics
The global post-harvest treatment market is experiencing steady growth, driven by increasing concerns over food loss and waste, rising global production of fruits and vegetables, and growing demand for high-quality fresh produce with extended shelf life. Post-harvest treatment solutions, including coatings, fungicides, insecticides, sanitizers, cleaners, and ethylene blockers, help preserve product quality, reduce microbial spoilage, and minimize losses during storage, transportation, and distribution. Increasing international trade in perishable agricultural commodities, stringent food safety regulations, and advancements in post-harvest technologies are further supporting market expansion. Additionally, the growing adoption of sustainable and residue-free treatment solutions, coupled with rising investments in cold chain infrastructure and modern agricultural practices, is expected to drive long-term demand for post-harvest treatment products across both developed and emerging markets
Shelf life of horticultural produce refers to the duration from harvest to consumption during which the product remains safe to eat and retains its desired quality attributes. It is a critical factor in ensuring food quality, which includes characteristics like appearance, texture, taste, aroma, and nutritional value, elements that determine consumer satisfaction. However, this shelf life is significantly influenced by various natural and environmental factors, necessitating effective post-harvest treatments to delay deterioration and maintain marketability.
One of the primary factors affecting shelf life is the respiration rate. Even after harvest, fruits and vegetables remain metabolically active, breaking down carbohydrates and releasing energy. This respiration process accelerates senescence and quality degradation. Since the rate of deterioration is directly proportional to respiration, controlling it primarily through reduced oxygen availability or atmospheric modification is essential. Post-harvest technologies like controlled atmosphere storage and ethylene inhibitors are often applied to slow this process.
One key challenge lies in the disconnect between upstream pre-harvest and downstream retail and consumption influences, which results in inconsistent product performance and unpredictable shelf-life outcomes. For example, variations in crop maturity, nutrient management, and harvesting techniques can greatly alter the efficacy of fungicides or coatings applied postharvest. Companies like JBT, Citrosol, and Lytone Enterprise Inc., which offer sanitizers, coatings, and ethylene blockers, must increasingly customize formulations based on these crop-specific variables, demanding deeper integration with growers and packers.
The divergent performance and perception for selecting natural over synthetic treatments. Natural-origin solutions such as those from Hazel Technologies, Futureco Bioscience, or Janssen PNP are gaining popularity due to environmental and regulatory pressures, especially in markets like the EU. However, these solutions often face limitations in broad-spectrum protection, consistency across climates, and cost-efficiency. Conversely, synthetic products from BASF SE, Bayer AG, Syngenta, and Nufarm are more established in terms of efficacy, shelf-life extension, and scalability, but face residue regulations, resistance development, and growing consumer rejection.
The post-harvest treatment market is witnessing strong opportunities in enzymatic browning, and quality retention. Fruits and vegetables, due to their high moisture content and biological makeup, are highly susceptible to microbial spoilage, bacteria in vegetables (e.g., Erwinia), and fungal pathogens in fruits (e.g., Botrytis, Penicillium). This has increased demand for fungicides, sanitizers, and antimicrobial coatings. Synthetic fungicides such as thiabendazole remain widely adopted and supported by companies like Syngenta, Bayer, and BASF, which continue to innovate broad-spectrum and low-residue solutions that comply with regulatory and retail standards.
Sanitizers such as chlorine dioxide, peracetic acid, and hydrogen peroxide dips are also widely used, especially for leafy greens and root crops, with companies like JBT and Citrosol offering integrated cleaning systems. Natural-origin antimicrobial coatings, such as chitosan-based films, are gaining ground as sustainable alternatives, with Futureco Chemicals and Janssen PNP leading innovation in biodegradable and organic-compliant solutions. While fruits and vegetables account for the highest demand, flowers, ornamentals, herbs, and spices also represent niche but lucrative applications where microbial contamination impacts export quality and shelf life.
Market Concentration & Characteristics
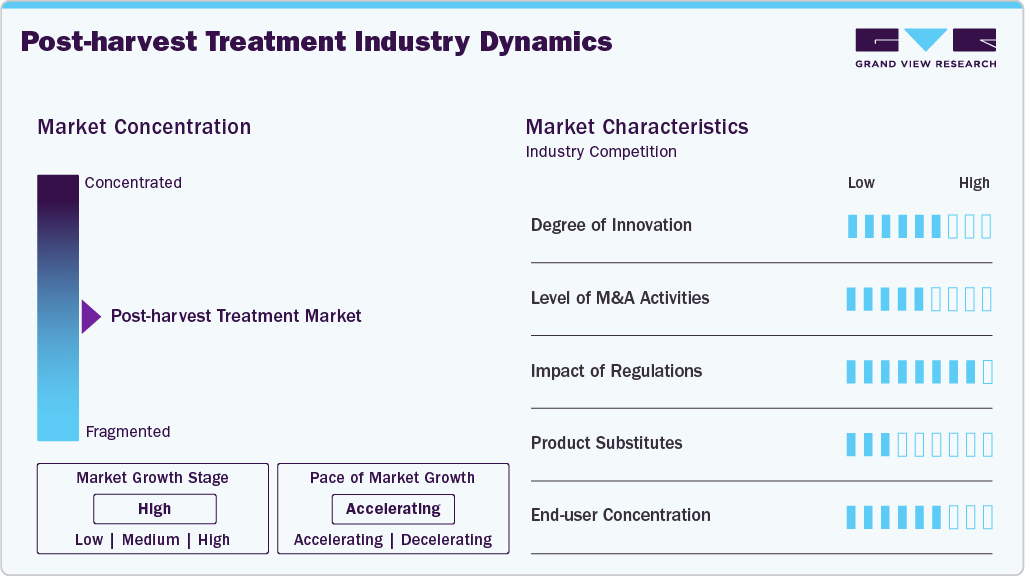
The market is moderately fragmented, with a few global players, such as JBT, Syngenta Crop Protection, and Nufarm, dominating the competitive landscape. These companies benefit from their scale of operations, competitive pricing, and diversified product offerings. They are actively investing in research and development, expanding production capacities, and focusing on sustainable practices to strengthen their positions in the competitive market.
 To learn more about this report, Download Free Sample Report
Leading players in the industry are actively pursuing a combination of strategies to strengthen their market position, including product innovation, strategic acquisitions, and geographic expansion. Companies are increasingly investing in the development of sustainable and bio-based treatment solutions to meet evolving regulatory standards and consumer demand for residue-free produce. Strategic partnerships with growers, exporters, and cold chain logistics providers are also being leveraged to enhance value delivery and end-to-end service offerings. These players are expanding their footprint in emerging markets through localized production facilities and tailored product portfolios to capture untapped growth potential and build long-term customer loyalty.
Analyst Perspective
The global post-harvest treatment market is expected to witness steady growth over the forecast period, supported by increasing efforts to reduce post-harvest losses, improve food security, and extend the shelf life of fresh produce. Rising international trade in fruits, vegetables, flowers, and grains, coupled with stringent food safety regulations, is driving demand for advanced post-harvest solutions such as coatings, fungicides, sanitizers, insecticides, and ethylene blockers. The market is also benefiting from the growing adoption of bio-based and residue-free treatment technologies as producers seek sustainable alternatives to conventional chemical products. While regulatory approvals for crop protection chemicals and concerns regarding chemical residues remain key challenges, companies investing in biological formulations, integrated post-harvest management solutions, and innovative shelf-life extension technologies are expected to strengthen their competitive position and capitalize on the increasing global demand for high-quality agricultural produce.
Origin Insights
Based on origin, the synthetic post-harvest treatment segment accounted for the highest market share, representing 62.3% of total revenue in 2025, owing to their broad-spectrum efficacy, cost-effectiveness, and widespread availability. These treatments, including chemical fungicides, insecticides, and sanitizers, remain the preferred choice across large-scale commercial operations and export-driven supply chains. Their proven ability to minimize post-harvest losses and maintain produce quality during extended storage and transit has reinforced their dominance in both developed and emerging markets. However, tightening global regulations on pesticide residues and growing consumer demand for sustainable practices are compelling manufacturers to reformulate their offerings with lower toxicity and improved environmental profiles.
Natural post-harvest treatments, derived from plant extracts, microbial agents, essential oils, and biopolymers, are gaining traction due to rising consumer preference for organic and residue-free produce. These treatments offer an environmentally sustainable alternative to conventional synthetic chemicals, aligning well with global trends toward clean-label and eco-friendly food production. Governments and regulatory bodies across North America and Europe are promoting the adoption of bio-based inputs through favorable policies and funding for sustainable agriculture initiatives. Although currently holding a smaller market share, the natural segment is projected to witness robust growth over the forecast period, supported by increasing R&D investments and the introduction of innovative biological formulations that ensure efficacy and regulatory compliance.
Application Insights
By application, fruits & vegetables held a dominant position, contributing 46.8% of total revenue in 2025, owing to the highly perishable nature of these crops and the growing global demand for fresh, high-quality produce. Treatments such as coatings, fungicides, ethylene blockers, and sanitizers are widely used to preserve freshness, reduce spoilage, and meet stringent export standards. The expansion of cold chain infrastructure and the surge in cross-border trade of produce, especially from Latin America, Asia Pacific, and Africa to Europe and North America, are further propelling demand in this segment. In addition, rising health consciousness and the shift toward plant-based diets are encouraging investment in advanced post-harvest solutions to enhance shelf-life and visual appeal.
 To learn more about this report, Download Free Sample Report
The cereals & grains and oilseeds & pulses segments are also witnessing growing adoption of post-harvest treatments, particularly insecticides, fungicides, and sprout inhibitors to minimize storage losses and preserve grain quality. Increased grain storage capacities and food security concerns in developing economies are driving treatment uptake. The flowers & ornamentals segment continues to benefit from treatments such as ethylene blockers, hydration solutions, and anti-wilt agents, driven by the expanding global floriculture trade. The others category, which includes tubers, herbs, and spices, relies on niche treatments tailored to specific storage and quality preservation needs. As global food demand rises and supply chains become more integrated, post-harvest application strategies are becoming more crop-specific, sophisticated, and regionally targeted.
Product Insights
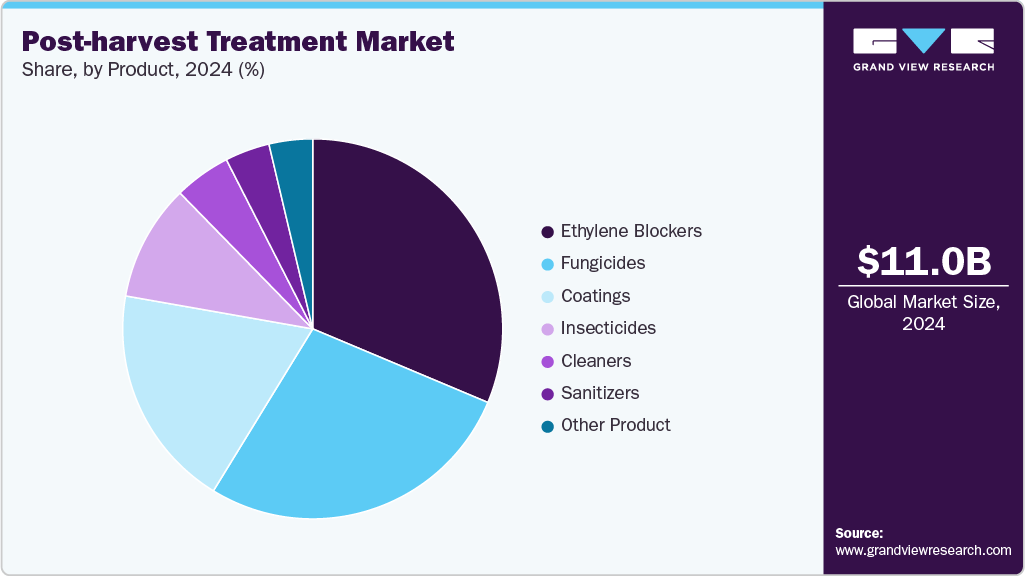
Based on product, the ethylene blockers post-harvest treatment segment accounted for the highest market share, representing 31.4% of total revenue in 2025, driven by its widespread use in extending the shelf life of climacteric fruits such as bananas, avocados, and mangoes, as well as in flowers and ornamentals. With growing global fruit trade and the need for quality retention during long-distance shipping, technologies like 1-Methylcyclopropene (1-MCP) have gained significant traction, particularly in export-heavy regions such as North America, Latin America, and Southeast Asia. Meanwhile, coatings, including edible films and wax emulsions, are increasingly adopted to reduce respiration rates and microbial spoilage in fresh produce. Demand for biodegradable and plant-based coatings is rising, fueled by the clean-label movement and sustainability goals.
Fungicides and insecticides remain vital in preventing fungal decay and insect infestation during storage and transit, especially in fruits, vegetables, and grains. While synthetic variants continue to dominate, the shift toward bio-based formulations is accelerating in response to regulatory scrutiny. Sanitizers are gaining importance with heightened emphasis on food safety and hygiene across processing and packaging stages, particularly in high-volume retail and export chains. Cleaners, used to remove dirt, pesticide residues, and microbial contaminants, are witnessing steady adoption in pre-packaging treatment lines. Other products, such as sprout inhibitors, desiccants, and anti-browning agents, cater to specialized applications across tubers, leafy greens, and ornamentals, offering targeted solutions for post-harvest quality preservation. Together, these diverse product categories reflect a dynamic market adapting to evolving consumer expectations, trade requirements, and sustainability imperatives.
Regional Insights
Asia Pacific Post-Harvest Treatment Market Trends
Asia Pacific dominated the post-harvest treatment market with the highest revenue share of 37.0% in 2025, driven by the region’s vast agricultural output, growing exports of fresh produce, and increasing focus on reducing post-harvest losses. Rapid urbanization, rising demand for high-quality fruits and vegetables, and expanding cold chain infrastructure across countries like India, Vietnam, Thailand, and Indonesia are fueling market growth. Government support for post-harvest management practices and the emergence of domestic solution providers are further contributing to market expansion.
 To learn more about this report, Download Free Sample Report
China Post-Harvest Treatment Market Trends
China dominated the Asia Pacific post-harvest treatment market in 2025, supported by its massive fruit and vegetable production base and growing export potential. The government’s push for modern agricultural practices and reduction of food wastage has led to increased adoption of advanced post-harvest technologies. Chinese players are also investing heavily in research and partnerships to develop bio-based treatments aligned with rising consumer demand for safe and sustainable food products.
North America Post-Harvest Treatment Market Trends
North America post-harvest treatment industry accounted for a global share of 19.0% in 2025, driven by high-value crop production, technological advancements in agricultural practices, and strong regulatory oversight. The region’s emphasis on food quality, supply chain efficiency, and sustainability is leading to widespread adoption of both synthetic and natural post-harvest treatments. The presence of key global players and a well-developed distribution network also supports continued market growth.
The U.S. post-harvest treatment industry dominated the North American regional market because of its large-scale commercial agriculture sector, robust export activities, and early adoption of innovative preservation technologies. Demand for residue-free, organic produce is prompting a shift toward biocontrol agents and bio-based coatings. The country also serves as a major hub for R&D and commercialization of advanced post-harvest solutions.
Europe Post-Harvest Treatment Market Trends
The post-harvest treatment industry in Europe held a 26.4% global market share in 2025, due to stringent food safety regulations, a well-established cold chain ecosystem, and high consumer demand for organic and minimally processed food products. Countries across Western and Northern Europe are leading adopters of bio-based coatings, ethylene blockers, and sanitizers to maintain produce quality and meet strict compliance standards. Sustainability and traceability are key focus areas, driving innovation in natural post-harvest treatment solutions.
Germany Post-Harvest Treatment Market Trends
Germany post-harvest treatment industry remained a prominent market in Europe, backed by its advanced food processing industry, strong export orientation, and high standards for food quality and hygiene. The country is witnessing growing demand for clean-label and organic post-harvest solutions, prompting both local and global companies to expand their product portfolios. Investments in R&D and sustainable agriculture are further shaping the German post-harvest treatment landscape.
Latin America Post-Harvest Treatment Market Trends
Latin America post-harvest treatment industry emerged as a high-potential market, driven by increasing exports of fruits, vegetables, and flowers, particularly from countries such as Brazil, Mexico, Chile, and Peru. Rising investments in cold storage and packaging technologies, along with growing awareness about post-harvest losses, are driving market growth. The region is also witnessing a shift toward natural and eco-friendly solutions to align with global export standards.
Middle East & Africa Post-Harvest Treatment Market Trends
The Middle East & Africa post-harvest treatment industry is experiencing gradual growth, supported by government efforts to enhance food security, reduce post-harvest waste, and strengthen supply chain infrastructure. Increasing imports and intra-regional trade of perishable produce are boosting demand for sanitizers, coatings, and temperature-sensitive packaging. While the market is still developing, rising agricultural investments in countries like South Africa, Kenya, and the UAE are expected to open new opportunities for post-harvest solution providers.
Key Post-Harvest Treatment Company Insights
Key players, such as JBT, Syngenta Crop Protection, Nufarm, and Bayer AG, are dominating the market.
JBT
-
JBT is a leading global provider of technology solutions for the food and beverage industry, including comprehensive post-harvest treatment systems. The company offers a wide range of equipment and solutions aimed at improving food quality, extending shelf life, and reducing waste across the supply chain. JBT's post-harvest portfolio includes fruit and vegetable coatings, cleaning and waxing systems, and produce handling automation, catering primarily to the citrus, apple, avocado, and tropical fruit segments. Leveraging its global footprint, strong R&D capabilities, and focus on sustainability, JBT continues to expand its market presence through strategic acquisitions and innovations in natural, biodegradable treatment solutions that align with evolving regulatory standards and consumer preferences.
Key Post-Harvest Treatment Companies:
The following are the leading companies in the post-harvest treatment market.
-
JBT
-
Syngenta Crop Protection
-
Nufarm
-
Bayer AG
-
BASF SE
-
Citrosol
-
Hazel Technologies Inc.
-
Lytone Enterprise Inc.
-
Janssen PNP
-
Futureco Chemicals Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (BASF SE, Taiwan Semiconductor Manufacturing Company, Eastman Chemical Company, Honeywell International , SK Inc)
- Market players are adopting strategies such as innovations, focusing on sustainability, or streamlining operations.
- The market players in the semiconductor chemicals market benefit from established brand recognition and customer loyalty, which enhance their market presence. Their extensive distribution networks allow for reliable product availability, while established relationships with key clients can lead to long-term contracts.
- These players are facing challenges related to rising production costs or increasing transportation costs.
- Some establishments may struggle to adapt to the changing market conditions or customer preference
Emerging Players (FUJIFILM Corporation, Linde PLC, Solvay, VWR International, LLC. Entegris)
- Emerging players focus on innovation to differentiate themselves from established competitors.
- They identify needs emerging trends and needs and tailor product according to market needs.
- Emerging players can gain a competitive edge through agility and flexibility in adapting to market trends and consumer preferences. They often focus on niche segments or specialized products that meet specific customer needs, allowing them to differentiate from established brands. Furthermore, leveraging technology for direct-to-consumer sales and targeted marketing strategies can enhance visibility and attract a younger demographic.
- Emerging players may face challenges such as limited recognition, scalability issues, and intense competition from established companies.
- Securing the supply chain and adapting to market fluctuations can pose challenges for newcomers.
Recent Developments
-
In May 2023, KitoZyme and Janssen PMP, signed an Exclusive Collaboration Agreement to evaluate and develop KitoZyme technologies for post-harvest use on fresh produce.
-
In January 2022, Syngenta AG launched a new fungicide named Archive to control the diseases occurring during the post-harvest.
Post-Harvest Treatment Market Report Scope
Report Attribute
Details
Market size in 2025
USD 11.8 billion
Estimated market size in 2026
USD 12.8 billion
Projected market size by 2033
USD 23.6 billion
Growth rate
CAGR of 9.2% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/million, Volume in Kilotons and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Origin, product, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; and Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; Italy; France; Spain; China; India; Japan; South Korea; Brazil; Argentina; Saudi Arabia; South Africa
Key companies profiled
JBT; Syngenta Crop Protection; Nufarm; Bayer AG; BASF SE; Citrosol; Hazel Technologies Inc.; Lytone Enterprise Inc.; Janssen PNP; Futureco Chemicals Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Post-Harvest Treatment Market Report Segmentation
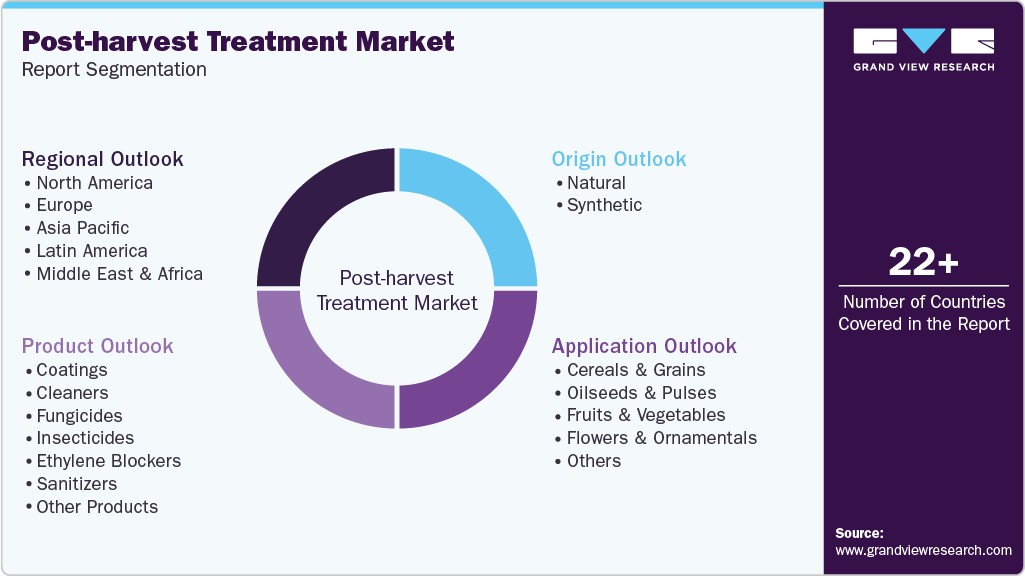
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global post-harvest treatment market report based on origin, product, application, and region.
 To learn more about this report, Download Free Sample Report
-
Origin Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Natural
-
Synthetic
-
-
Product Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Coatings
-
Cleaners
-
Fungicides
-
Insecticides
-
Ethylene Blockers
-
Sanitizers
-
Other Products
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Cereals & Grains
-
Oilseeds & Pulses
-
Fruits & Vegetables
-
Flowers & Ornamentals
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
-
Latin America
-
Brazil
-
Argentina
-
-
Research Methodology
The post-harvest treatment market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each post-harvest treatment segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Origin
Revenue capture definition
Natural
Revenue is generated through the commercialization of naturally derived post-harvest treatment products, including plant extracts, essential oils, biological fungicides, edible coatings, and bio-based sanitizers. Growing demand for residue-free produce, organic farming, and sustainable crop protection solutions continues to drive adoption across global agricultural markets
Synthetic
Sales are driven by synthetic post-harvest treatment products such as chemical fungicides, insecticides, sanitizers, ethylene blockers, and cleaning agents that provide effective disease control, shelf-life extension, and quality preservation. Their proven efficacy, cost-effectiveness, and widespread use in commercial fruit and vegetable production support consistent market demand.
Segment - Product
Revenue capture definition
Coatings
Revenue is generated through the supply of edible and protective coatings that reduce moisture loss, delay ripening, preserve freshness, and improve the appearance of fruits and vegetables during storage and transportation. Increasing demand for shelf-life extension and export-quality produce continues to support market growth.
Cleaners
Business income is derived from specialized cleaning solutions used to remove soil, pesticide residues, microorganisms, and contaminants from harvested produce before storage and packaging. Growing emphasis on food safety and hygiene standards is driving demand for post-harvest cleaning products
Fungicides
Revenue is supported by fungicide formulations that prevent fungal infections and decay during storage, transportation, and retail distribution. Increasing post-harvest disease incidence and the need to reduce crop losses continue to strengthen demand across commercial horticulture.
Insecticides
Sales are generated through insecticide products designed to control storage insects and quarantine pests, protecting produce quality during post-harvest handling and export. Expanding international trade and stringent phytosanitary regulations continue to support market adoption.
Ethylene Blockers
Revenue is generated through ethylene management products that delay fruit ripening, reduce physiological deterioration, and extend storage life by inhibiting ethylene activity. Growing demand for long-distance transportation and controlled atmosphere storage is increasing product utilization.
Sanitizers
Business value is created through sanitizing agents used to eliminate bacteria, fungi, and other microbial contaminants from harvested crops, packaging equipment, and processing facilities. Increasing regulatory focus on food safety and microbial control continues to drive demand globally
Other Products
Revenue is generated from specialty post-harvest solutions including growth regulators, anti-sprouting agents, waxes, preservatives, and integrated treatment formulations that improve produce quality, minimize spoilage, and enhance storage performance across multiple crop types
Segment - Application
Revenue capture definition
Cereals & Grains
Revenue is generated through post-harvest treatments that protect stored grains from insects, fungi, moisture damage, and quality deterioration during storage and transportation. Growing investments in grain storage infrastructure continue to support product demand.
Oilseeds & Pulses
Business income is derived from treatment solutions that preserve seed quality, reduce microbial contamination, and prevent storage losses in oilseeds and pulses. Rising global trade and increasing demand for high-quality agricultural commodities contribute to sustained market growth.
Fruits & Vegetables
Revenue is supported by coatings, fungicides, sanitizers, cleaners, and ethylene blockers that extend shelf life, maintain freshness, and reduce post-harvest losses in fresh produce. Increasing exports of perishable fruits and vegetables and rising consumer demand for premium-quality produce make this the largest application segment
Flowers & Ornamentals
Sales are generated through post-harvest treatment products that preserve color, freshness, and vase life while minimizing microbial spoilage during storage and transportation. Growing international floriculture trade continues to support demand for specialized treatment solutions
Other Applications
Business value is created through the use of post-harvest treatment products across spices, plantation crops, nuts, medicinal plants, and other specialty agricultural products requiring quality preservation, pest control, and extended storage life
Estimation Model
Layer Name
Key Question
Description
Raw Material & Production Layer
What forms the supply base?
Assess the global production of post-harvest treatment products derived from natural extracts, edible waxes, polymers, fungicides, insecticides, sanitizers, ethylene inhibitors, and other specialty agricultural chemicals. The analysis evaluates raw material availability, chemical and biological manufacturing technologies, production capacities, supplier networks, and major manufacturing hubs supporting the global supply of post-harvest treatment solutions
Application Adoption Layer
Where are post-harvest treatment utilized?
Evaluate the adoption of post-harvest treatment products across major agricultural applications including cereals & grains, oilseeds & pulses, fruits & vegetables, flowers & ornamentals, and other horticultural crops. Adoption is driven by increasing demand for shelf-life extension, food safety, export-quality produce, reduction in post-harvest losses, and compliance with international phytosanitary regulations.
Consumption Intensity Layer
How much post-harvest treatment are utilized?
Quantify product consumption across key crop categories by analyzing treatment application rates, harvested crop volumes, storage duration, export volumes, disease incidence, and processing requirements. The assessment measures annual consumption intensity of coatings, fungicides, insecticides, sanitizers, cleaners, ethylene blockers, and other post-harvest products across major agricultural commodities and regional markets.
Revenue Layer
How is market revenue generated?
Market revenue is generated through the manufacturing and commercialization of post-harvest treatment products supplied to growers, exporters, packhouses, storage facilities, food processors, and agricultural distributors worldwide. Commercial performance is influenced by crop production, treatment efficacy, regulatory approvals, raw material pricing, technological innovation, international trade, and increasing demand for high-quality produce with extended shelf life.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
The study provides comprehensive country-level analysis across key post-harvest treatment markets. The assessment covers agricultural production, crop cultivation patterns, post-harvest infrastructure, cold chain development, consumption trends, import-export dynamics, regulatory frameworks, and demand across cereals & grains, oilseeds & pulses, fruits & vegetables, flowers & ornamentals, and other agricultural applications
Enables stakeholders to identify high-growth regional markets, evaluate agricultural production ecosystems, understand crop-specific demand patterns, benchmark competitive positioning, and formulate expansion strategies aligned with regional cultivation practices, trade flows, and regulatory requirements.
Trade Assessment
The report provides a detailed analysis of historical and current trade flows for post-harvest treatment products, including imports, exports, major producing and consuming countries, raw material procurement patterns, pricing trends, distribution networks, and global supply chain dynamics. The assessment further evaluates regional manufacturing concentration, trade dependencies, and cross-border movement of post-harvest chemicals and biological treatment solutions influencing market availability.
Supports procurement and sourcing decisions by identifying reliable supply regions, evaluating trade-related risks, strengthening supplier diversification, assessing export opportunities, and improving strategic planning through enhanced visibility into global trade patterns and supply chain dynamics.
Opportunity Assessment
The study presents a comprehensive evaluation of growth opportunities across key product categories including coatings, cleaners, fungicides, insecticides, ethylene blockers, sanitizers, and other post-harvest treatment products. It also assesses emerging opportunities driven by biological crop protection solutions, residue-free treatments, edible coatings, precision agriculture, cold chain expansion, increasing fresh produce exports, and advancements in post-harvest preservation technologies
Assists organizations in identifying high-growth product segments and crop applications, prioritizing investment opportunities, aligning product development with evolving food safety and sustainability requirements, strengthening innovation strategies, and capturing long-term value through advanced post-harvest management solutions.
Frequently Asked Questions About This Report
The synthetic segment held the largest revenue share in 2025 due to its proven efficacy, cost-effectiveness, and widespread availability across large-scale commercial operations. Its reliability in minimizing post-harvest losses and preserving crop quality during extended storage and transit continues to drive strong demand globally.
Some of the key players operating in the post-harvest treatment market include JBT, Syngenta Crop Protection, Nufarm, Bayer AG, BASF SE, Citrosol, Hazel Technologies Inc. and Lytone Enterprise Inc.
The post-harvest treatment market is driven by rising global demand for fresh and high-quality produce, along with increasing efforts to reduce food loss across the supply chain. Stringent food safety regulations and the expansion of cold chain logistics are accelerating the adoption of advanced post-harvest solutions.
Ethylene blocker dominated the product segment in the post-harvest treatment market with a revenue share of 31.4% in 2025.
Natural segment is expected to grow the fastest with a compound annual growth (CAGR) rate of 10.2% from 2026 to 2033.
Fruits & vegetable application segment dominated the market with a revenue share of 46.8% in 2025.
Flowers and Ornamentals application segment is expected to grow the fastest with a CAGR of 9.7% from 2026 to 2033
The global post-harvest treatment market size was valued at USD 11.8 billion in 2025 and is estimated at USD 12.8 billion for 2026.
The global post-harvest treatment market is expected to grow at a CAGR of 9.2% from 2026 to 2033, reaching USD 23.6 billion by 2033.
About the Author(s)
Agrochemicals & Fertilizers Research Team
Bulk Chemicals · Agrochemicals & FertilizersThis report was authored by the agrochemicals & fertilizers research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the agrochemicals & fertilizers segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


