
- Home
- »
- Advanced Interior Materials
- »
-
PVC And CPVC Pipe Fittings Market Size Report, 2025-2033GVR Report cover

PVC And CPVC Pipe Fittings Market (2025 - 2033)
Size, Share & Trends Analysis Report By Product (Polyvinyl Chloride (PVC), Chlorinated Polyvinyl Chloride (CPVC)), By End Use (Residential, Commercial), By Region, And Segment Forecasts
Market Size, 2024
$25.0BMarket Estimate, 2026
$27.5BMarket Forecast, 2033
$40.8BCAGR, 2025–2033
5.7%PVC And CPVC Pipe Fittings Market Summary
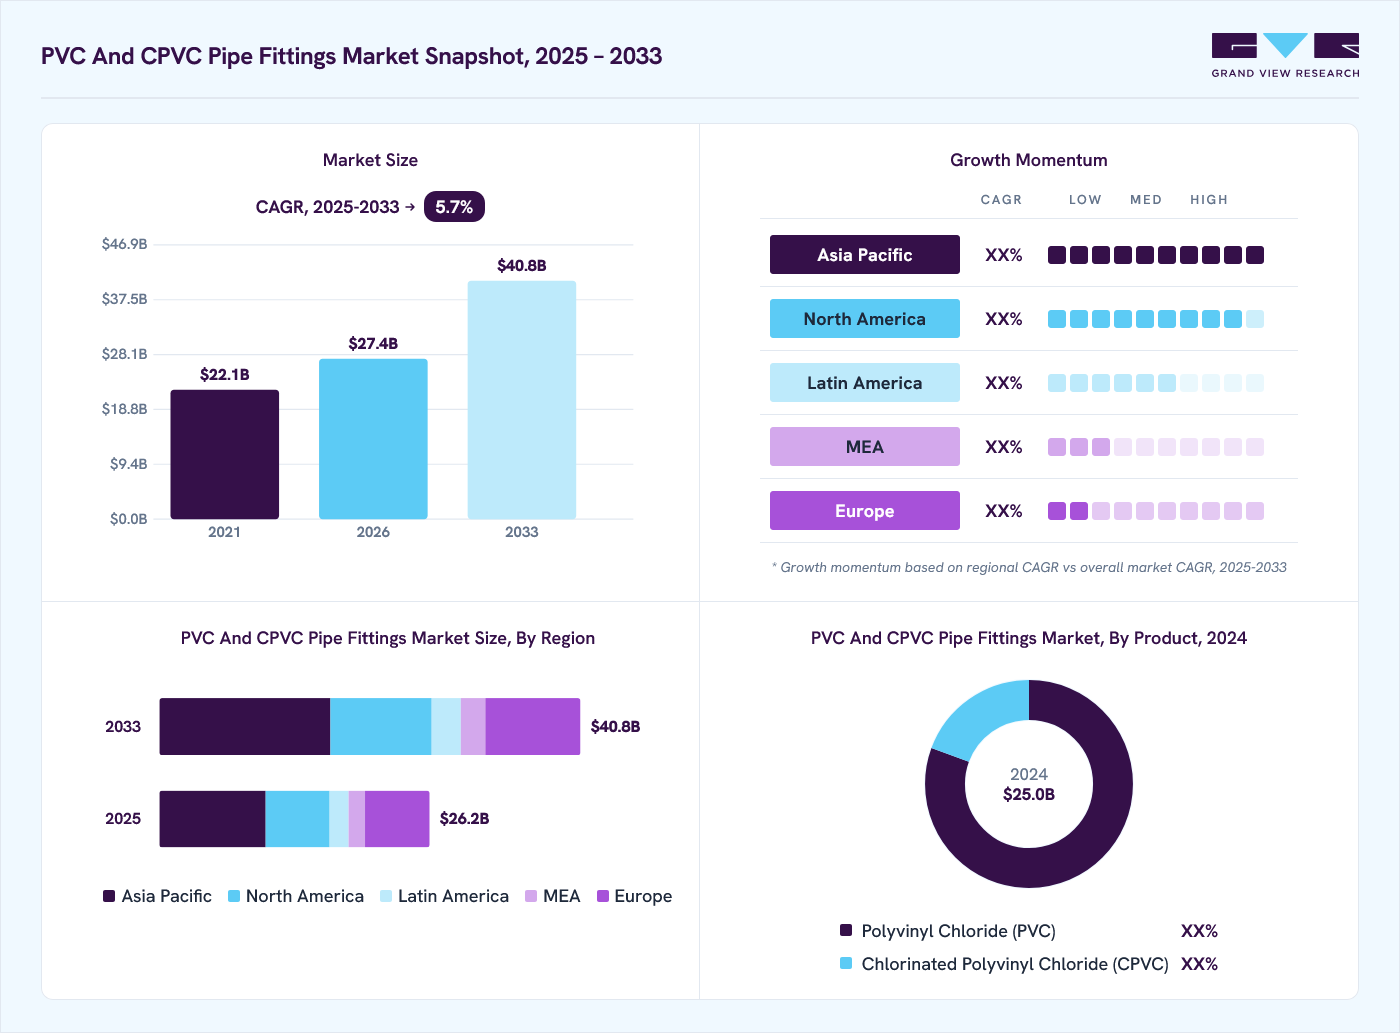
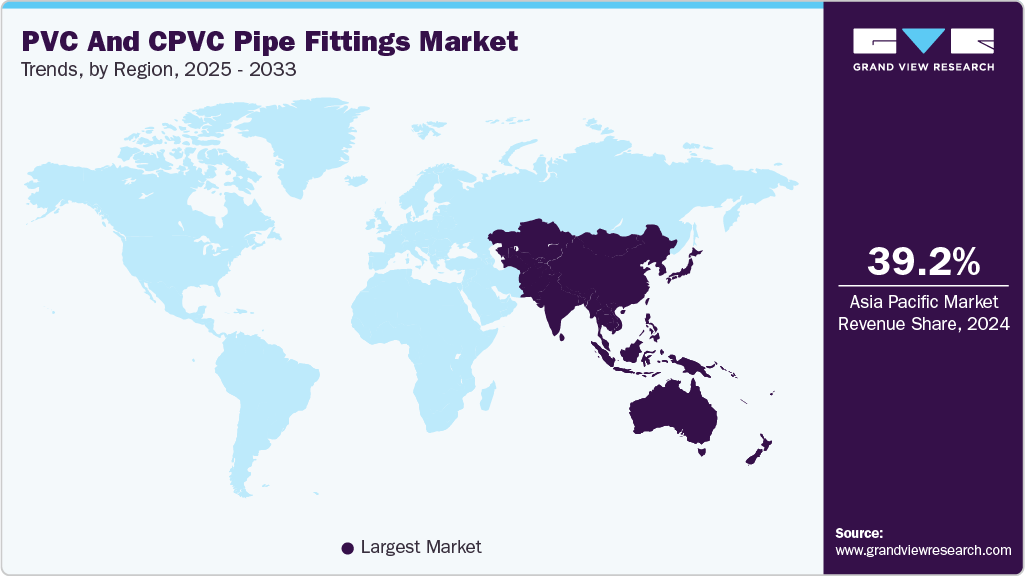
The global PVC and CPVC pipe fittings market size was valued at USD 25.0 billion in 2024 and is projected to grow from USD 27.5 billion in 2026 to USD 40.8 billion by 2033, at a CAGR of 5.7% from 2025 to 2033, driven by the increasing demand for reliable and cost-effective piping systems in water supply and sanitation infrastructure. Asia Pacific dominated the market, accounting for a revenue share of 39.2% in 2024.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product, chlorinated polyvinyl chloride (CPVC) segment is expected to grow at fastest CAGR of 6.5% over the forecast period.
- By end use, residential segment is expected to grow at fastest CAGR of 5.9% over the forecast period.
Market Size & Forecast
- 2024 Market Size: USD 25.0 Billion
- 2033 Projected Market Size: USD 40.8 Billion
- CAGR (2025-2033): 5.7%
- Asia Pacific: Largest market in 2024
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2025–2033 annual, 2024 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
With growing concerns around water scarcity, aging pipelines, and the need for efficient water management, municipal authorities and urban developers are increasingly investing in durable and corrosion-resistant pipe fittings. PVC and CPVC materials offer advantages such as chemical resistance, lightweight handling, and low maintenance, making them ideal for potable water systems, wastewater treatment, and irrigation networks across developed and developing economies. Technological advancements in material formulation and jointing techniques, such as solvent welding and push-fit connections, further enhance the ease of installation and reliability of PVC and CPVC fittings. Manufacturers are introducing innovations to improve pressure ratings, thermal performance, and product lifecycle, making these fittings increasingly suitable for diverse End Uses. These factors collectively contribute to steady market growth, as stakeholders prioritize efficiency, safety, and cost-effectiveness in pipeline infrastructure.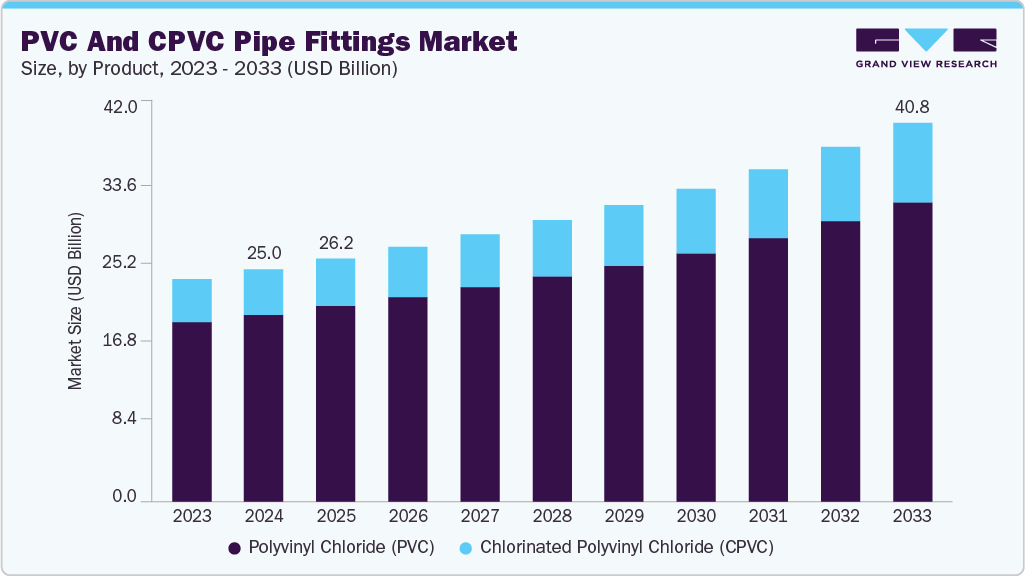 To learn more about this report, Download Free Sample Report
In addition, the growth of industrial end uses, including chemical processing, oil & gas, and manufacturing, propels the adoption of PVC and CPVC fittings. These industries require pipe systems that can withstand corrosive fluids and extreme temperatures. CPVC materials offer an effective alternative to metal pipes at a lower cost and with reduced installation time. The rise of green building standards and sustainable construction practices also encourages using CPVC and PVC, as they are recyclable and have a lower carbon footprint than traditional materials like steel or copper.
Market Concentration & Characteristics
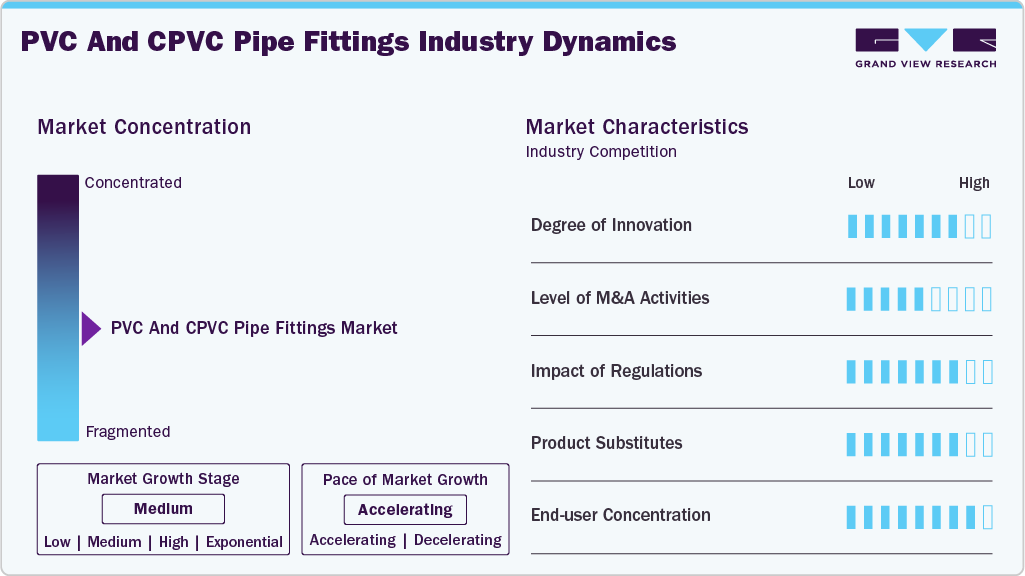
The global PVC and CPVC pipe fittings industry exhibits a moderately fragmented structure, with a mix of global manufacturers, regional players, and specialized suppliers catering to diverse end uses. The degree of innovation in the market is moderate, largely focused on enhancing material performance, developing heat- and chemical-resistant grades, and improving jointing technologies like solvent welding, mechanical joints, and push-fit systems. Many manufacturers also invest in sustainable production practices, including lead-free formulations and recyclable materials, in response to rising environmental concerns and consumer preference for eco-friendly solutions.
 To learn more about this report, Download Free Sample Report
The level of mergers and acquisitions in the market remains moderate, with strategic collaborations occurring mainly among regional players seeking to expand distribution networks or diversify product portfolios. Regulations play a critical role in shaping the market, particularly in sectors like drinking water, fire safety, and industrial piping, where product certification and compliance with standards (e.g., ASTM, NSF, ISO) are essential. Although product substitutes such as metal (copper, steel) and PEX piping exist, PVC and CPVC fittings remain preferred for their lower cost, corrosion resistance, and ease of installation. The end-use concentration is high in residential, municipal, and industrial sectors, which account for the majority of demand due to extensive use in water supply systems, plumbing, HVAC, and chemical processing.
Product Insights
Polyvinyl chloride (PVC) held the highest revenue share of 80.57% in 2024, driven by the material’s affordability, ease of installation, and wide applicability in low-pressure and non-corrosive environments. Its extensive use in water supply, sewage, agricultural irrigation, and drainage systems is supported by its lightweight, corrosion-resistant, and low-maintenance properties. In developing regions, particularly in Asia and Latin America, growing infrastructure development and government investments in sanitation and water distribution projects are accelerating the adoption of PVC pipe fittings for residential and utility-scale applications.
Chlorinated polyvinyl chloride (CPVC) is expected to grow at the fastest CAGR of 6.5% over the forecast period, driven by its superior thermal and chemical resistance, making it suitable for hot and cold water plumbing, fire sprinkler systems, and industrial piping applications. As building codes in many countries increasingly mandate fire-resistant high-pressure-capable piping systems, CPVC fittings are gaining preference over metal and other plastic alternatives. The material's non-corrosive nature and compatibility with potable water standards further fuel its growth in residential and commercial sectors, especially in developed markets like North America and Europe.
End Use Insights
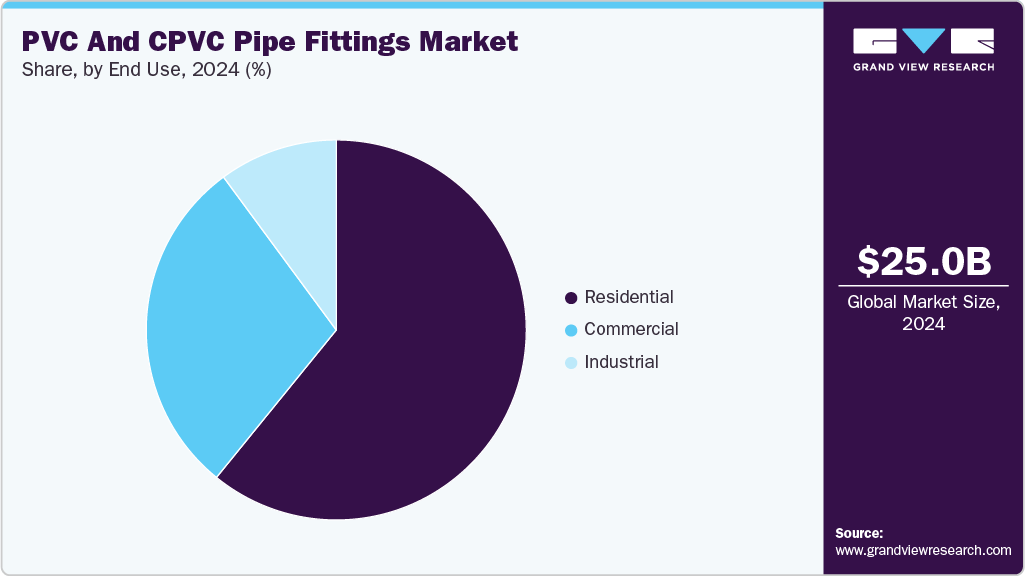
Residential held the highest revenue share of 60.84% in 2024, driven by the rising demand for safe, cost-effective, and durable modern plumbing systems. Rapid urbanization, housing development schemes, and increased awareness of water conservation are prompting builders and homeowners to adopt PVC and CPVC piping for potable water supply, waste drainage, and rainwater harvesting. Furthermore, CPVC’s ability to withstand higher temperatures makes it ideal for domestic hot water applications, which is increasingly important in multistory housing and premium residential projects.
 To learn more about this report, Download Free Sample Report
The commercial segment is expected to grow significantly at a CAGR of 5.6% over the forecast period, driven by the need for robust and code-compliant piping systems in large-scale developments such as offices, malls, hospitals, hotels, and educational institutions. PVC and CPVC pipe fittings offer ease of installation, chemical resistance, and long service life, which help reduce maintenance costs and downtime. CPVC, in particular, is widely used in HVAC systems and fire protection piping in commercial buildings due to its flame-retardant properties and compliance with international safety standards. The growth of commercial real estate, coupled with stringent regulatory requirements, continues to propel the demand for advanced piping systems in this segment.
Regional Insights
Asia Pacific dominated the PVC and CPVC pipe fittings market in 2024 with a revenue share of 39.17% and is further expected to grow significantly over the forecast period. The region's rapid urbanization, infrastructure development, and rising demand for affordable and durable piping solutions in residential and commercial construction drive market growth. Government-backed sanitation programs, smart city initiatives, and large-scale water management projects in India, Indonesia, and Vietnam fuel demand for corrosion-resistant and cost-effective piping systems. Moreover, the region’s growing industrial base, especially in chemical processing and manufacturing, contributes to the increasing adoption of CPVC pipe fittings.
 To learn more about this report, Download Free Sample Report
China PVC And CPVC Pipe Fittings Market Trends
The PVC and CPVC pipe fittings market in China is primarily driven by stringent government regulations to improve water quality and environmental sustainability. Nationwide upgrades to aging municipal water infrastructure and the adoption of green building standards have accelerated the shift from traditional metal pipes to PVC and CPVC alternatives. In addition, the expanding construction sector, rising disposable incomes, and increased investment in high-rise residential buildings and fire protection systems are further boosting the demand for CPVC fittings due to their thermal resistance and long service life.
North America PVC And CPVC Pipe Fittings Market Trends
The PVC and CPVC pipe fittings market in North America is driven by the increasing need for pipe replacement in aging water distribution systems and the adoption of energy-efficient and environmentally sustainable building materials. Regulatory support for lead-free and recyclable piping solutions and strong demand for CPVC in fire sprinkler and hot water end uses are propelling the market. In both new construction and retrofitting projects, the advantages of CPVC-such as ease of installation and low maintenance-encourage its widespread use.
The U.S. PVC and CPVC pipe fittings market is strongly driven by code-compliant plumbing systems in residential and commercial construction and growing adoption in fire safety and HVAC End Uses. The presence of well-established manufacturers and distributors and a high rate of single-family home developments and apartment complexes support the demand for PVC and CPVC fittings. Moreover, enforcing stringent plumbing standards and building codes has increased preference for certified CPVC systems in potable and hot water installations.
Europe PVC And CPVC Pipe Fittings Market Trends
The PVC and CPVC pipe fittings market in Europe is fueled by growing awareness of sustainable construction practices and the enforcement of stringent environmental and quality standards. The shift towards non-metallic piping in water supply, wastewater treatment, and heating systems is gaining momentum due to PVC and CPVC’s corrosion resistance and cost-efficiency. Increased investments in infrastructure modernization, especially in Eastern Europe, and the demand for low-maintenance plumbing in commercial buildings further contribute to market expansion.
Germany PVC and CPVC pipe fittings marketis driven by its advanced engineering standards and focus on energy-efficient building systems. The use of CPVC in heating, ventilation, and hot water end uses is growing due to its thermal and pressure resistance. In addition, Germany’s strong industrial base and demand for high-performance piping systems in chemical processing, pharmaceuticals, and manufacturing sectors are stimulating the uptake of CPVC over metal alternatives.
Latin America PVC And CPVC Pipe Fittings Market Trends
The PVC and CPVC pipe fittings market in Latin America is largely driven by urban housing demand, sanitation infrastructure development, and the need for affordable piping solutions in rural and semi-urban regions. Countries like Brazil, Mexico, and Colombia are investing in potable water and sewerage systems, where PVC’s durability, ease of installation, and cost-effectiveness make it the preferred material. Governmental initiatives focused on improving public health and water access are further catalyzing growth in the region.
Middle East & Africa PVC And CPVC Pipe Fittings Market Trends
The PVC and CPVC pipe fittings market in the Middle East and Africa is driven by large-scale infrastructure and construction projects, particularly in Gulf countries. Demand is especially strong in commercial real estate, industrial zones, and water-intensive sectors such as oil and gas and desalination plants. CPVC offers excellent resistance to heat and chemicals. In Africa, the need for durable and low-cost water distribution systems in urban and rural areas is prompting increased use of PVC pipe fittings in public infrastructure projects supported by international development funds.
Key PVC And CPVC Pipe Fittings Company Insights
Some key players operating in the market are Ashirvad Pipes and Finolex Industries.
-
Ashirvad Pipes, a subsidiary of Aliaxis Group, is a leading manufacturer of PVC and CPVC piping systems in India. The company is widely recognized for its CPVC piping systems for hot and cold water plumbing applications. Its product portfolio includes FlowGuard Plus CPVC pipes and fittings, SWR drainage systems, Agri pipes, and uPVC column pipes for borewells.
-
Finolex Industries is one of India’s largest PVC-U pipe manufacturers, catering primarily to the agriculture and infrastructure sectors. Its offerings include a wide range of PVC pipes, fittings, and solvent cements. The company supplies pressure pipes, casing pipes, non-pressure sewage pipes, and CPVC plumbing systems suitable for residential and commercial water supply.
Astral Limited and Prince Pipes and Fittings Ltd are some of the emerging participants in the market.
-
Astral Limited is a leading manufacturer of CPVC, PVC, and other polymer-based piping solutions in India. Known for its innovation and quality, Astral offers CPVC piping systems for hot and cold water plumbing, industrial piping, and fire sprinkler systems. Its product line includes SWR drainage systems, underground pipes, electrical conduit systems, and lead-free uPVC pipes.
-
Prince Pipes is a prominent player in the Indian plastic piping industry, offering end-to-end piping solutions across diverse sectors. The company manufactures CPVC, uPVC, HDPE, and PPR pipes and fittings. Its CPVC Pro and Aquaflow series are widely used in plumbing and water distribution, while its Rainfit and Underground Drainage systems cater to infrastructure and agriculture.
Key PVC And CPVC Pipe Fittings Companies:
The following are the leading companies in the PVC and CPVC pipe fittings market. These companies collectively hold the largest market share and dictate industry trends.
- Finolex Industries
- Astral Limited
- Prince Pipes and Fittings Ltd
- Supreme Industries
- Lubrizol Corporation
- Georg Fischer
- NIBCO Inc.
- IPEX Inc.
- Formosa Plastics Corporation
Recent Developments
-
In March 2025, Prince Pipes & Fittings Limited expanded its manufacturing footprint by launching its eighth production facility in Begusarai, Bihar. The plant commenced operations with an initial capacity of around 24,000 metric tonnes per annum, with plans to scale up to 60,000 metric tonnes within the next 6 to 9 months. This strategic move strengthens the company’s presence in the eastern region of India, catering to growing demand while optimizing logistics and reducing freight costs. The facility focuses on producing PVC and CPVC pipes and fittings, reinforcing Prince Pipes’ commitment to expanding its pan-India network and enhancing supply chain efficiency.
PVC And CPVC Pipe Fittings Market Report Scope
Report Attribute
Details
Market size in 2024
USD 25.0 billion
Estimated market size in 2026
USD 27.5 billion
Projected market size by 2033
USD 40.8 billion
Growth rate
CAGR of 5.7% from 2025 to 2033
Base year for estimation
2024
Historical data
2021 - 2024
Forecast period
2025 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2025 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, end use, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; China; India; Japan; South Korea
Key companies profiled
Finolex Industries; Astral Limited; Prince Pipes and Fittings Ltd; Supreme Industries; Lubrizol Corporation; Georg Fischer; NIBCO Inc.; IPEX Inc.; Formosa Plastics Corporation
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global PVC And CPVC Pipe Fittings Market Report Segmentation
This report forecasts revenue growth at the regional & country levels and provides an analysis of the industry trends in each of the segments from 2021 to 2033. For this study, Grand View Research has segmented the PVC and CPVC pipe fittings market based on product, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Billion, 2021 - 2033)
-
Polyvinyl Chloride (PVC)
-
Chlorinated Polyvinyl Chloride (CPVC)
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Residential
-
Commercial
-
Industrial
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
-
Central & South America
-
Middle East & Africa
-
Frequently Asked Questions About This Report
Residential segment held the highest revenue share of 60.84% in 2024, driven by the rising demand for modern plumbing systems that are safe, cost-effective, and durable.
Some key players operating in the PVC and CPVC pipe fittings market include Finolex Industries, Astral Limited, Prince Pipes and Fittings Ltd, Supreme Industries, Lubrizol Corporation, Georg Fischer, NIBCO Inc., IPEX Inc., and Formosa Plastics Corporation.
The key factors that are driving the PVC and CPVC pipe fittings market growth include increasing demand for durable and cost-effective piping solutions across residential, commercial, and industrial applications, along with rising urbanization and supportive government infrastructure initiatives.
The global PVC and CPVC pipe fittings market size was valued at USD 25.0 billion in 2024 and is estimated at USD 27.5 billion for 2026.
The global PVC and CPVC pipe fittings market is expected to grow at a CAGR of 5.7% from 2025 to 2030, reaching USD 40.8 billion by 2033.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


