
- Home
- »
- Medical Devices
- »
-
Sclerotherapy Market Size & Share Report, 2026-2033GVR Report cover

Sclerotherapy Market (2026 - 2033)
Size, Share & Trends Analysis Report By Agents (Detergents, Chemical Irritants, Osmotic Agents), By Type (Ultrasound Sclerotherapy), By Application, By Region, And Segment Forecasts
Market Size, 2025
$1.2BMarket Estimate, 2026
$1.3BMarket Forecast, 2033
$1.7BCAGR, 2026–2033
4.1%Sclerotherapy Market Size & Trends
The global sclerotherapy market size was valued at USD 1.2 billion in 2025 and is projected to grow from USD 1.3 billion in 2026 to USD 1.7 billion by 2033, at a CAGR of 4.1% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 44.2% in 2025. The increasing prevalence of venous diseases, such as varicose veins and chronic venous insufficiency, which affect a significant portion of the population, drive the market. Patients seek effective and minimally invasive treatment options that address medical symptoms and enhance cosmetic appearance.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By agents: Detergents segment led the market with the largest revenue share of 43.8% in 2025.
- By type: Foam sclerotherapy segment led the market with the largest revenue share of 38.3% in 2025.
- By application: Hemorrhoids segment led the market with the largest revenue share of 31.3% in 2025.
Regional Highlights
- Largest regional market: North America (44.2% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 1.2 Billion
- Estimated market size in 2026: USD 1.3 Billion
- Projected market size by 2033: USD 1.7 Billion
- CAGR (2026-2033): 4.1%
Prism AI by Grand View Research Free to tryAsk a question about the sclerotherapy marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Advancements in techniques and sclerosants further fuel the demand for sclerotherapy, improving treatment efficacy and safety. As healthcare systems evolve, the accessibility of these treatments is expected to rise, contributing to the sclerotherapy industry expansion. Hence, these factors further stimulating growth in the sclerotherapy market. Advancements in sclerotherapy techniques and technologies are enhancing treatment efficacy and safety. Innovations such as foam sclerotherapy and ultrasound-guided procedures have improved the precision of injections and patient outcomes. These technological developments make the procedure safer and expand its applicability to a wider range of venous disorders. As healthcare providers adopt these advanced techniques, the overall acceptance and utilization of sclerotherapy are expected to rise, contributing to the sclerotherapy industry growth.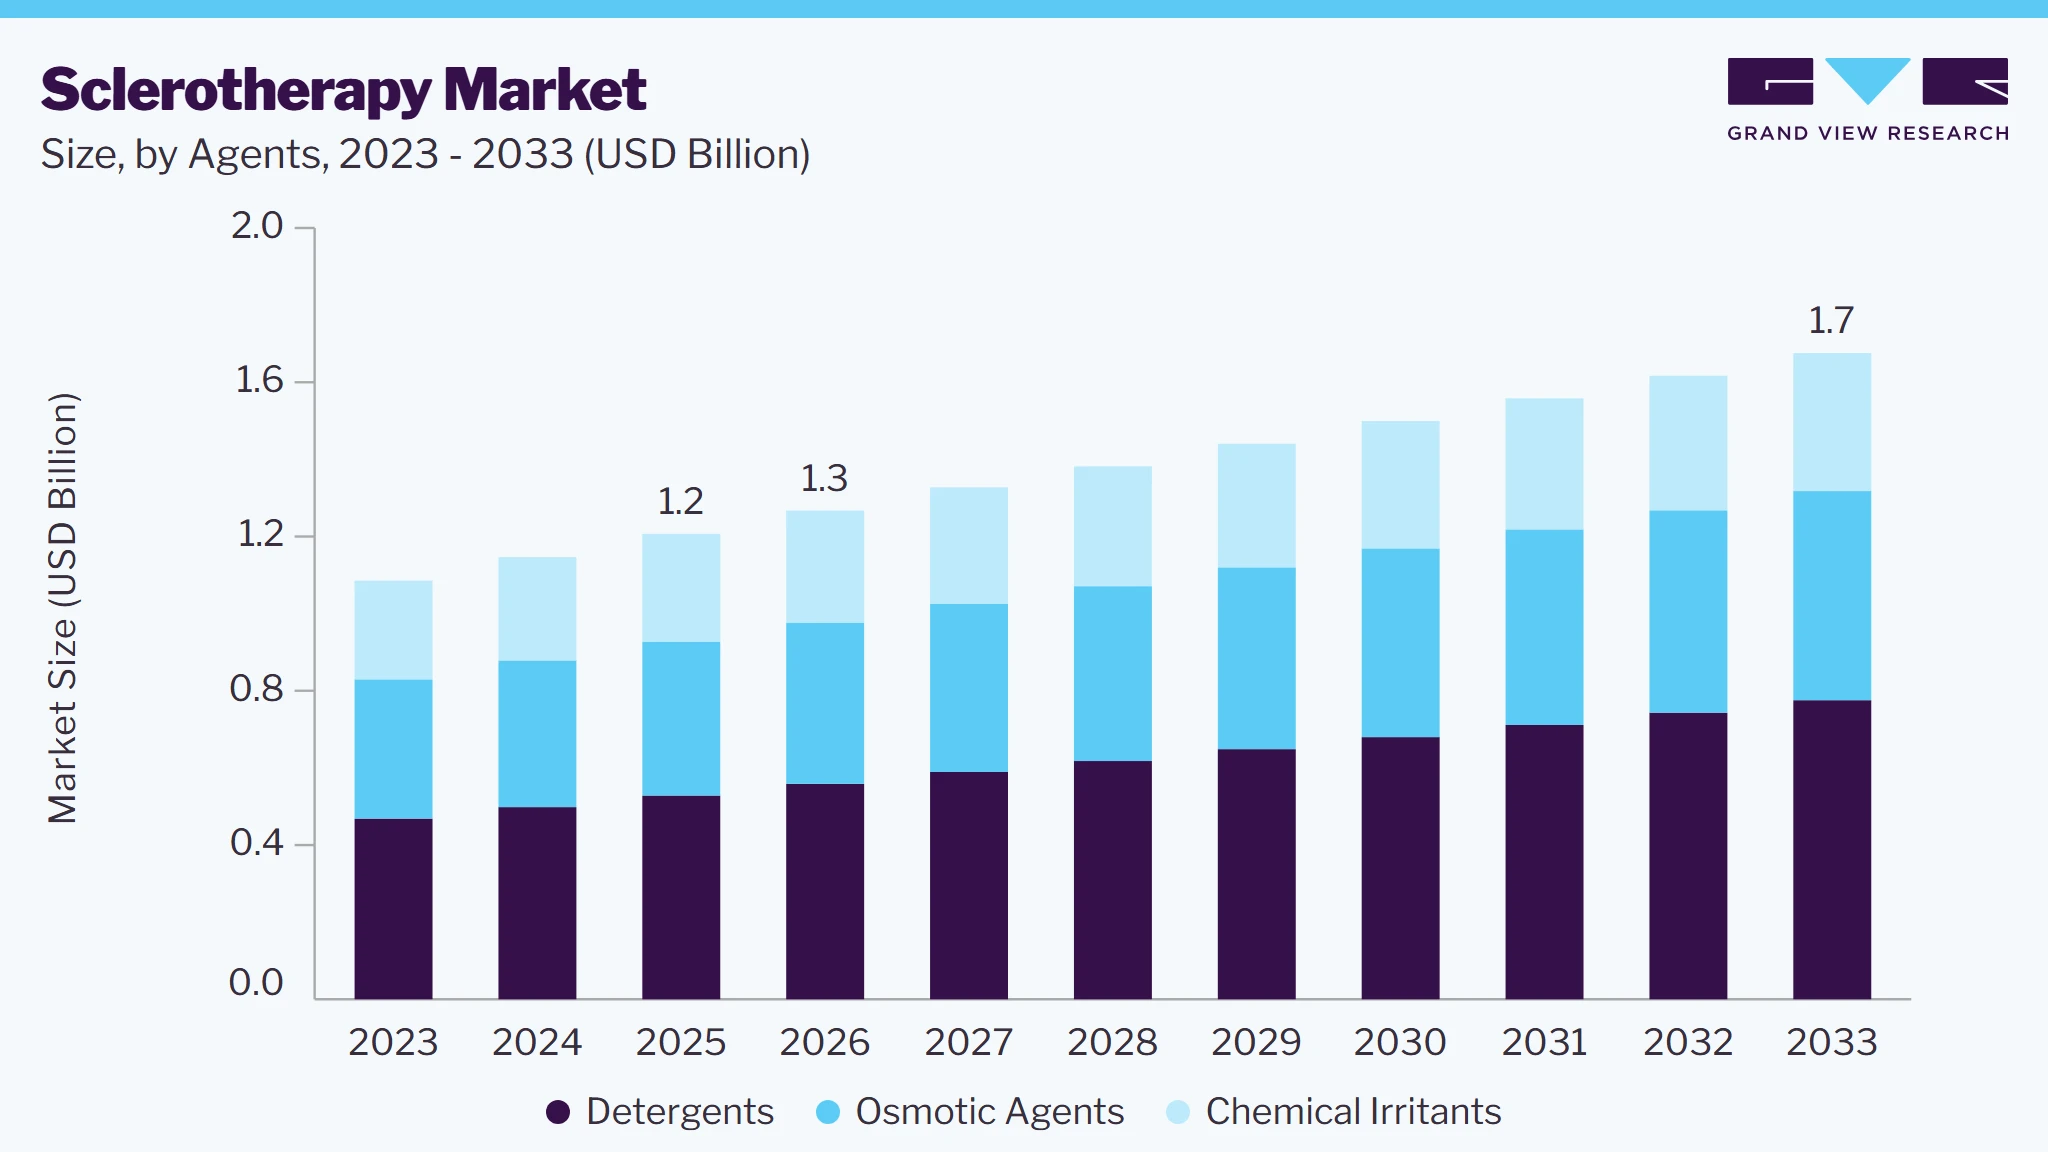 To learn more about this report, Download Free Sample Report
The increasing preference for minimally invasive procedures among patients is reshaping the landscape of the sclerotherapy industry. With benefits such as reduced recovery times, lower risks of complications, and minimal scarring compared to traditional surgical methods, more patients are opting for sclerotherapy as their choice of treatment. This trend is further supported by growing awareness and education about the procedure advantages, leading to higher patient compliance and demand. As healthcare infrastructure improves globally, access to these innovative treatments is expected to expand, driving further growth in the sclerotherapy market.
Market Dynamics
The sclerotherapy market is witnessing robust growth due to the increasing prevalence of chronic venous disorders and the growing adoption of minimally invasive procedures for the treatment of varicose veins, spider veins, hemorrhoids, vascular malformations, and lymphatic abnormalities. Sclerotherapy is a widely established treatment technique that involves the injection of sclerosing agents into diseased veins, causing endothelial damage, vessel collapse, fibrosis, and eventual resorption of the treated vessel. The market comprises a range of sclerosants, including detergent-based, osmotic, and chemical agents, as well as foam and liquid formulations used across hospitals, vascular surgery centers, dermatology clinics, ambulatory surgical centers, and aesthetic medicine practices. The rising incidence of chronic venous insufficiency, obesity, sedentary lifestyles, pregnancy-related venous disorders, and an aging population is driving demand for sclerotherapy procedures globally. In addition, advancements in ultrasound-guided sclerotherapy, foam sclerotherapy techniques, catheter-based delivery systems, and image-guided vascular interventions are improving treatment precision, procedural safety, and long-term clinical outcomes, thereby supporting market growth.
The increasing prevalence of chronic venous disorders and the growing preference for minimally invasive treatment options are major factors driving the global sclerotherapy market. The rising incidence of varicose veins, spider veins, chronic venous insufficiency, hemorrhoids, vascular malformations, and other venous disorders is significantly increasing demand for effective, outpatient treatment procedures. Factors such as aging populations, obesity, prolonged standing occupations, pregnancy, and sedentary lifestyles continue to contribute to the expanding patient pool worldwide. Sclerotherapy has become one of the preferred treatment options due to its minimally invasive nature, high success rates, minimal downtime, excellent cosmetic outcomes, and lower treatment costs compared with surgical vein stripping. Growing patient awareness regarding early treatment of venous disease, expanding availability of ultrasound-guided foam sclerotherapy, and increasing adoption across vascular surgery, dermatology, and aesthetic medicine practices are further accelerating market growth. Continuous innovations in sclerosant formulations, imaging technologies, and injection techniques are improving procedural efficacy, reducing recurrence rates, and supporting broader clinical adoption.
Despite continuous technological advancements, the sclerotherapy market remains constrained by the potential for treatment recurrence and the requirement for highly skilled healthcare professionals to achieve optimal clinical outcomes. The success of sclerotherapy depends on accurate patient selection, proper sclerosant concentration, injection technique, ultrasound guidance, and post-treatment compression therapy. Inadequate treatment planning or improper administration may lead to incomplete vein closure, recurrence, hyperpigmentation, allergic reactions, thrombophlebitis, or other treatment-related complications. Furthermore, patients with advanced venous disease may require multiple treatment sessions or combination therapies, increasing overall treatment costs. Limited reimbursement for cosmetic vein treatments in several healthcare systems and shortages of trained vascular specialists in developing regions may further restrict market adoption. These challenges, together with varying treatment outcomes depending on disease severity and practitioner experience, may limit the widespread adoption of sclerotherapy in certain healthcare markets.
Analyst Perspective
The sclerotherapy market is positioned at the intersection of several transformative healthcare trends, including the rising prevalence of chronic venous disorders, increasing demand for minimally invasive vascular treatments, expanding aesthetic medicine, and continuous advancements in image-guided intervention techniques. Healthcare providers are increasingly adopting advanced sclerotherapy procedures that offer effective vein closure, improved cosmetic outcomes, shorter recovery times, and reduced procedural risks compared with conventional surgery.
Technological innovations in foam sclerosants, ultrasound-guided injection techniques, catheter-based delivery systems, and optimized sclerosants formulations are reshaping the competitive landscape. The growing incidence of varicose veins, spider veins, hemorrhoids, and lymphatic malformations, coupled with increasing awareness of early venous disease management, is creating significant growth opportunities for manufacturers. As healthcare systems continue to prioritize outpatient care, patient convenience, and cost-effective minimally invasive therapies, demand for advanced sclerotherapy products and procedures is expected to increase steadily across hospitals, vascular surgery centers, dermatology clinics, and ambulatory surgical centers worldwide.
Agents Insights
Based on agents, the detergents segment led the market with the largest revenue share of 43.8% in 2025, driven by their proven efficacy and safety profile as sclerosing agents. Detergents are widely recognized for irritating the vein wall effectively, leading to the successful closure of varicose veins and other venous conditions. The FDA approval further enhances their credibility among healthcare providers, encouraging widespread adoption in clinical practice. In addition, the low risk of side effects associated with detergent sclerotherapy makes it a preferred choice for both patients and practitioners. The increasing incidence of venous diseases globally has also contributed to the rising demand for effective treatment options, solidifying the detergents segment leading position in the market.
The osmotic agents segment is expected to grow at a significant CAGR over the forecast period, fueled by their innovative approach to treating venous diseases. These agents leverage osmotic pressure to induce vein closure, offering a targeted and effective treatment option that minimizes damage to surrounding tissues. As healthcare professionals become more aware of the advantages of osmotic agents, including reduced side effects and improved patient outcomes, their utilization is likely to increase. Furthermore, ongoing research into new formulations and delivery systems is expected to enhance the effectiveness and safety of osmotic agents, driving their growth in the sclerotherapy industry.
Type Insights
Based on type, the foam sclerotherapy segment led the market with the largest revenue share of 38.3% in 2025, attributed to its ability to treat larger veins effectively. Foam formulations provide better visibility and contact with the vein wall than traditional liquid sclerosants, improving treatment outcomes. The growing preference among patients for minimally invasive procedures has further boosted the adoption of foam sclerotherapy. Moreover, clinical studies continue demonstrating its efficacy in treating various venous conditions, reinforcing its position as a leading treatment option in the sclerotherapy industry.
The ultrasound sclerotherapy segment is projected to grow at a significant CAGR over the forecast period due to advancements in imaging technology that enhance treatment precision. Real-time ultrasound guidance allows practitioners to accurately target affected veins, improving injection accuracy and overall treatment success rates. As awareness of these benefits increases among healthcare professionals, the adoption of ultrasound-guided sclerotherapy is expected to rise significantly. This trend is further supported by ongoing training and education initiatives aimed at enhancing practitioners skills in utilizing ultrasound technology for sclerotherapy.
Application Insights
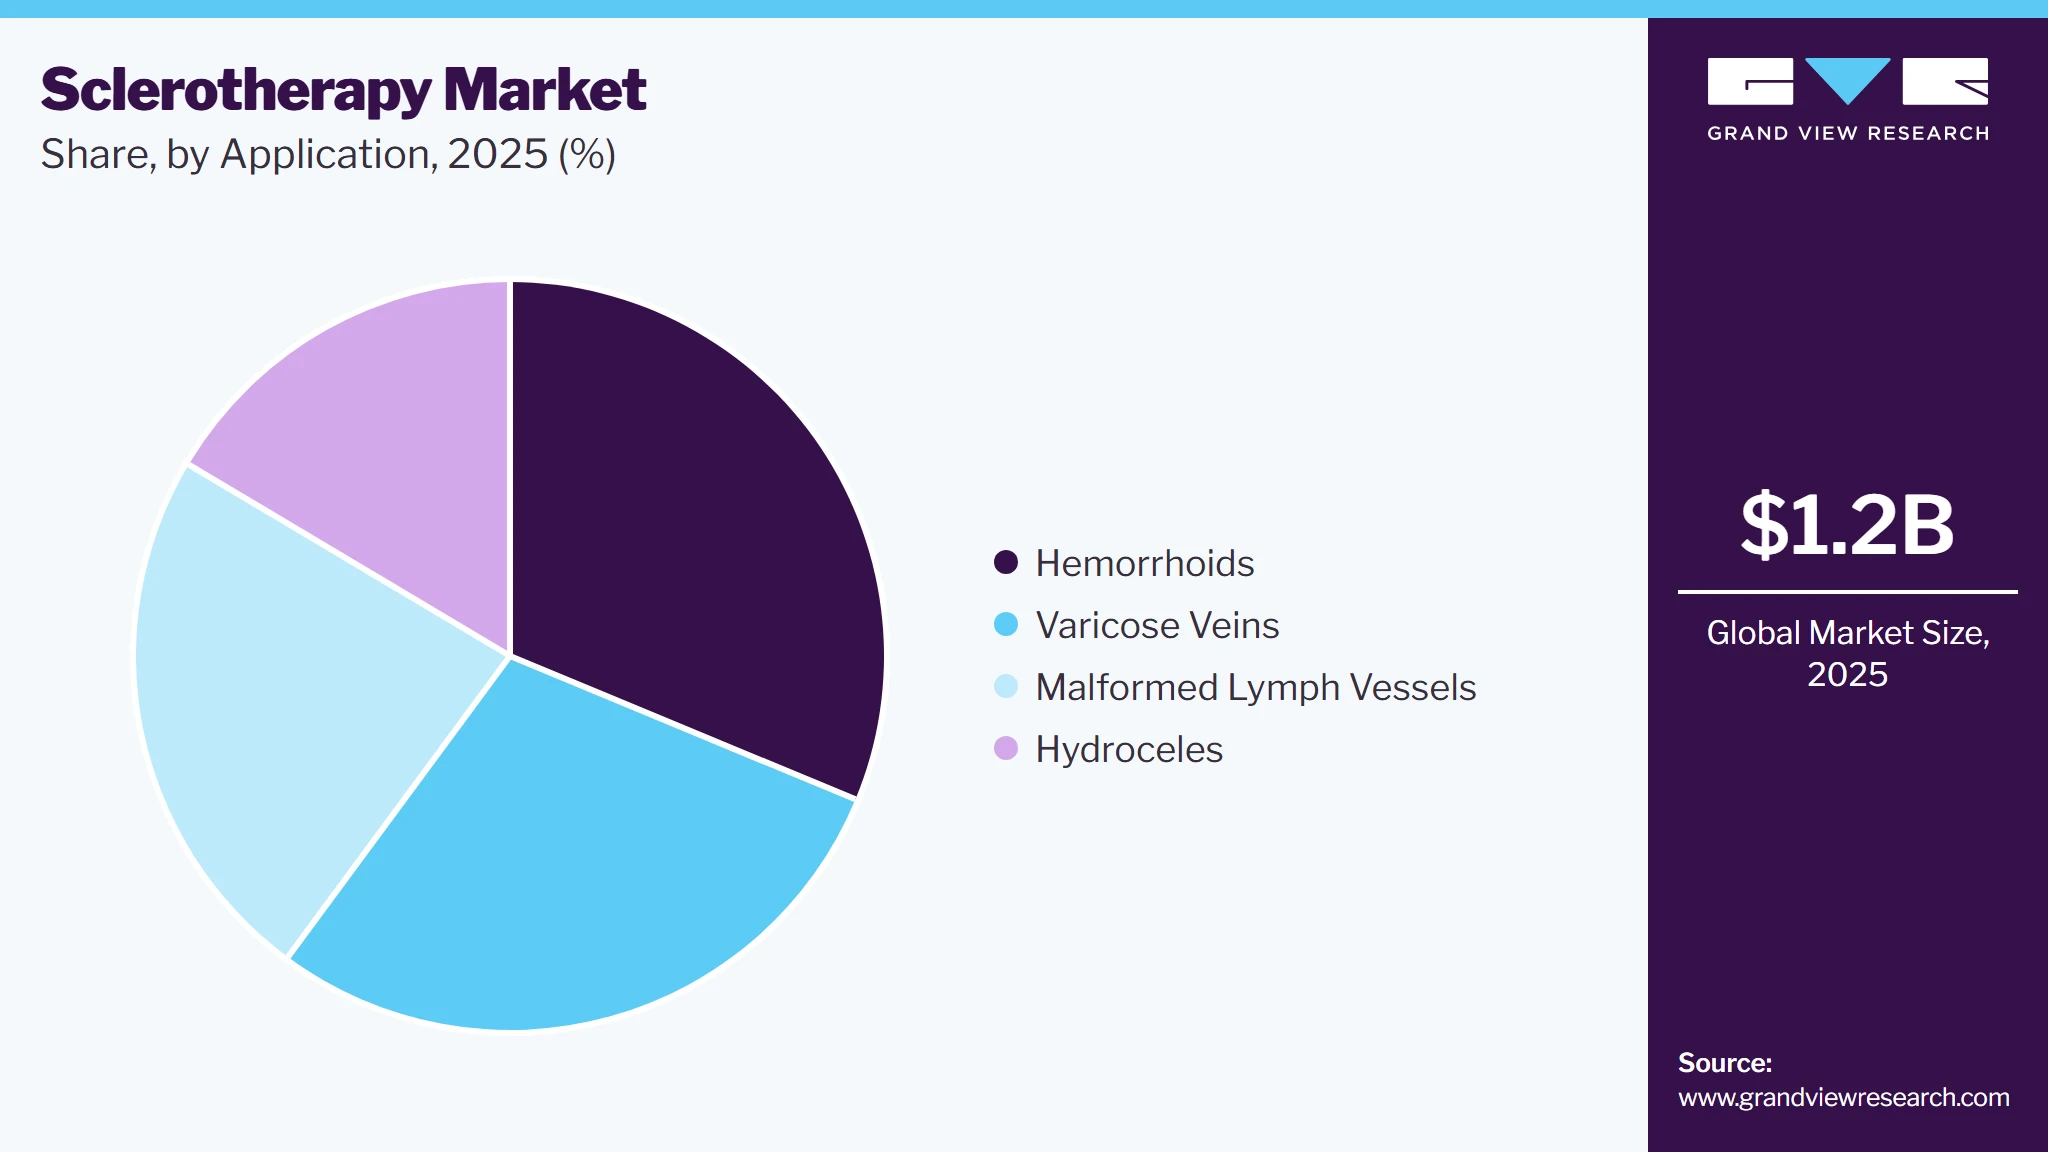
Based on application, the hemorrhoids segment led the market with the largest revenue share of 31.3% in 2025, driven by the high prevalence of hemorrhoids among adults. Hemorrhoids are a common ailment that often requires effective management options, and sclerotherapy offers a minimally invasive solution that appeals to patients seeking relief from discomfort. The increasing awareness about treatment options for hemorrhoids and the growing preference for non-surgical interventions further support this segment dominance in the market. In addition, healthcare providers are increasingly recommending sclerotherapy as a first-line treatment option for hemorrhoids due to its effectiveness and lower risk profile.
 To learn more about this report, Download Free Sample Report
The varicose veins segment is expected to grow at a significant CAGR over the forecast period, which can be attributed to the rising incidence of varicose veins among aging populations. As more individuals seek effective treatments for this common condition, demand for sclerotherapy options is likely to increase. Furthermore, growing awareness regarding cosmetic concerns associated with varicose veins drives more patients toward considering sclerotherapy as a viable treatment option. The increasing availability of specialized clinics offering sclerotherapy treatments also contributes positively to this segment growth.
Regional Insights
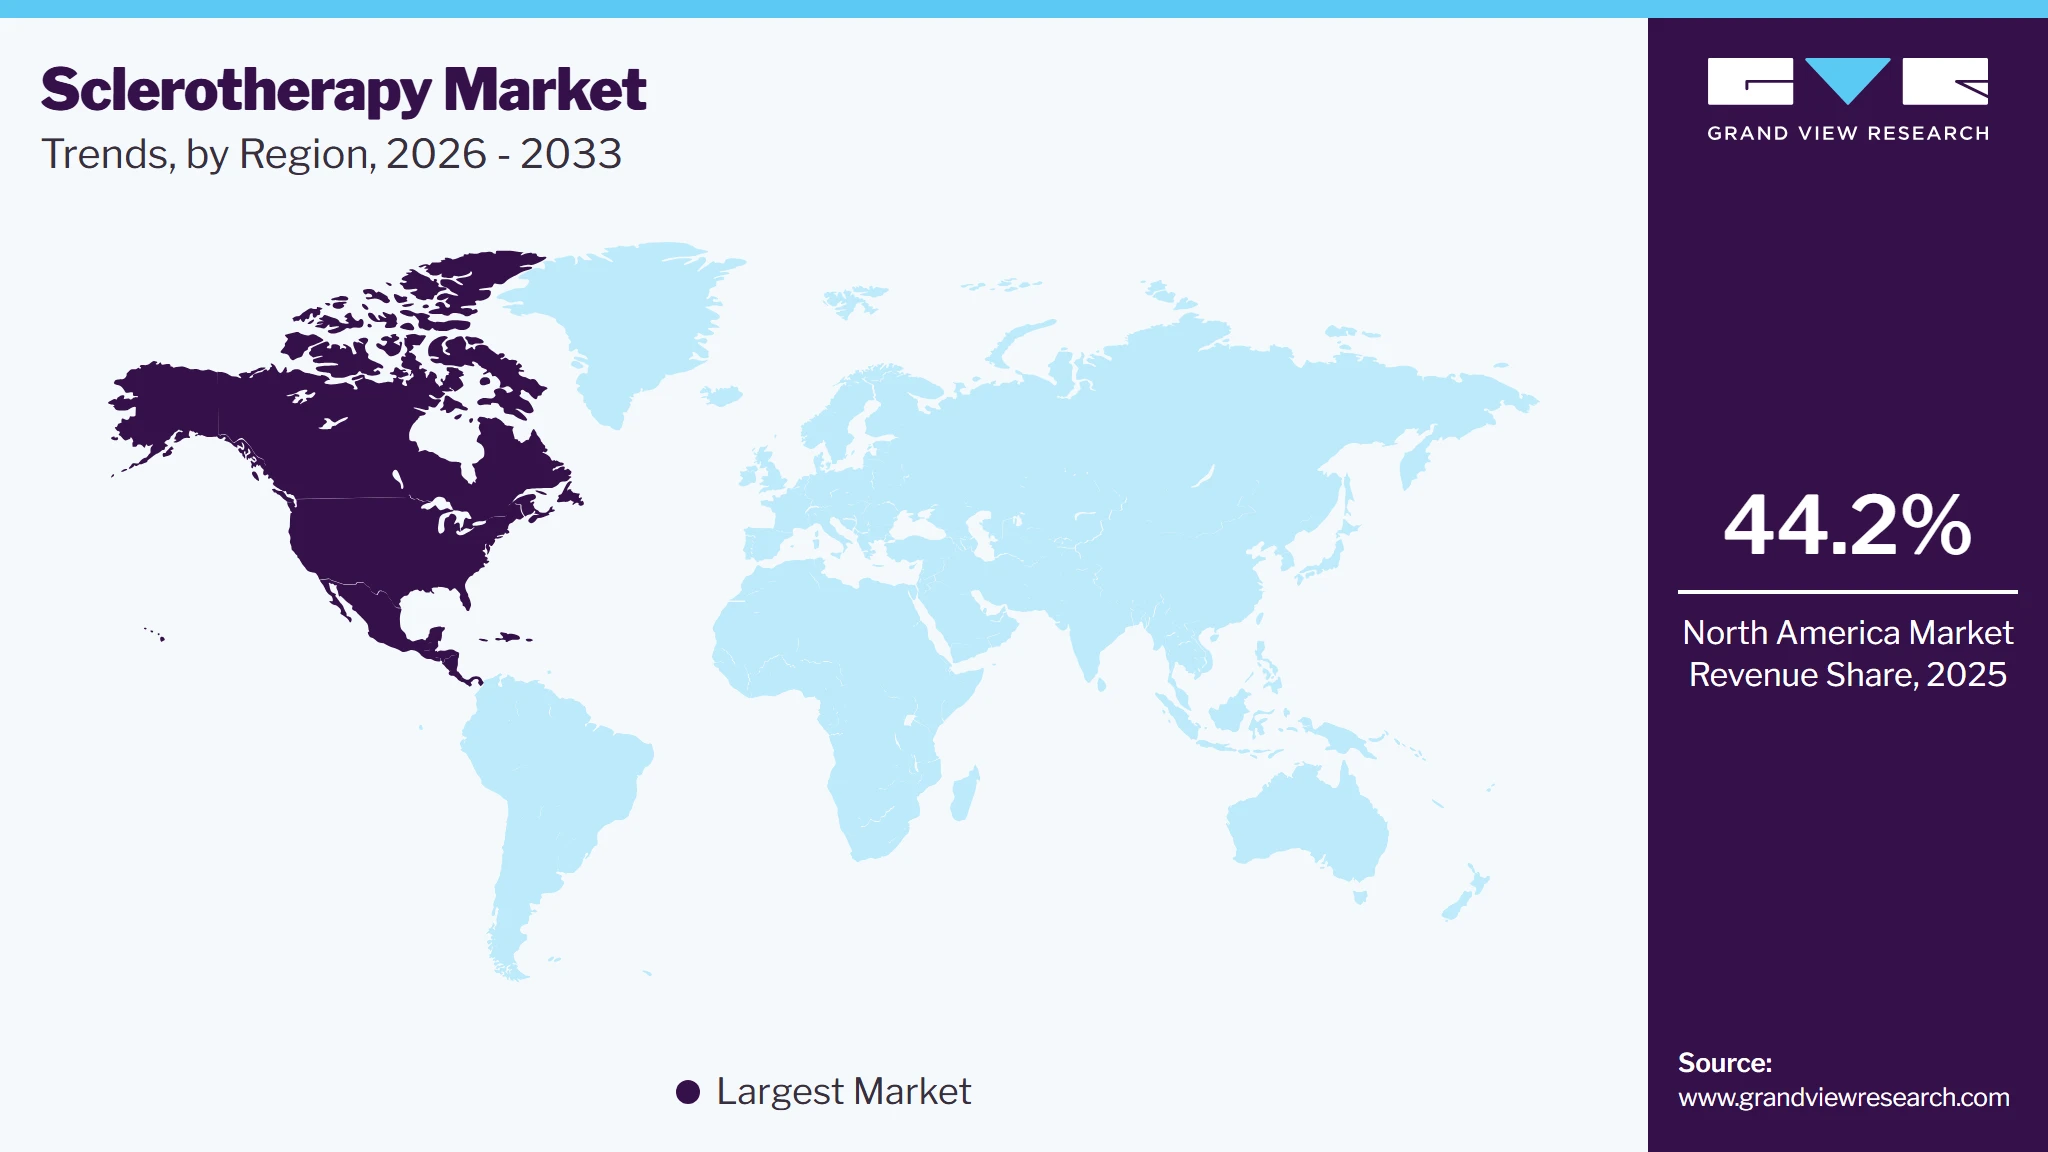
North America dominated the sclerotherapy market with the largest revenue share of 44.2% in 2025 due to advanced healthcare infrastructure and high patient awareness regarding venous treatments. The region benefits from well-established medical facilities and a strong presence of skilled practitioners specializing in minimally invasive procedures. In addition, favorable reimbursement policies enhance patient access to sclerotherapy treatments, further solidifying North America leading position in the market. The growing elderly population in North America also contributes significantly to the demand for effective venous disease treatments.
 To learn more about this report, Download Free Sample Report
U.S. Sclerotherapy Market Trends
The sclerotherapy market in the U.S. held the largest share in the North America region in 2025, fueled by a robust healthcare system and high demand for effective venous disease treatments. The availability of advanced medical technologies and a large population suffering from conditions such as varicose veins contribute significantly to market growth. Moreover, increasing investments in research and development drive innovative treatment modalities within the U.S., enhancing overall market dynamics. The presence of numerous specialized clinics dedicated to treating venous diseases further supports this trend.
Europe Sclerotherapy Market Trends
Europe sclerotherapy market held a substantial market share in 2024, driven by increasing investments in healthcare infrastructure and rising awareness about venous diseases. The region aging population contributes significantly to demand for effective treatment options such as sclerotherapy. Furthermore, ongoing research initiatives to improve treatment efficacy are expected to boost market growth across various European countries. Regulatory support for minimally invasive procedures also plays a crucial role in promoting sclerotherapy as an effective treatment option within Europe.
Asia Pacific Sclerotherapy Market Trends
Asia Pacific sclerotherapy market is expected to register the highest CAGR of 5.7% over the forecast period, which can be attributed to rapid urbanization and increasing healthcare access in emerging economies. The growing prevalence of venous diseases among urban populations drives demand for sclerotherapy. In addition, rising disposable incomes enable more individuals to seek medical interventions for aesthetic concerns related to venous conditions. The expansion of specialized clinics offering sclerotherapy services is also anticipated to contribute positively to market growth in this region.
The China sclerotherapy market dominates the Asia Pacific with a significant revenue share in 2024 due to its large population base and increasing awareness about venous health issues. The rapid development of healthcare facilities and investment in medical technologies enhance treatment accessibility across the country. Furthermore, government initiatives aimed at improving healthcare services contribute positively to market growth in China as more patients seek effective solutions for venous diseases. The rising prevalence of lifestyle-related factors contributing to venous disorders also plays a pivotal role in driving demand for sclerotherapy treatments within China.
Key Sclerotherapy Company Insights
Some key companies operating in the market include LGM Pharma; Troikaa; Viatris Inc.; Omega Pharmaceuticals Pvt. Ltd.; and Merz Pharma. Companies are undertaking strategic initiatives such as mergers, acquisitions, and product launches, to expand their market presence and address the evolving healthcare demands through sclerotherapy market.
-
LGM Pharma offers a range of products, including various sclerosing agents such as detergents, osmotic agents, and chemical irritants used in liquid and foam sclerotherapy procedures. The company also provides comprehensive contract development and manufacturing organization (CDMO) services, facilitating clients transition from concept to commercialization and ensuring timely market entry of their sclerotherapy-related products.
-
Troikaa Pharmaceuticals offers a range of products and solutions tailored for the sclerotherapy market. Its products include Dynapar AQ, a high-concentration diclofenac injection that utilizes aquatic technology for effective pain management, which is beneficial in sclerotherapy procedures. The company also provides Dynapar QPS, Xykaa Extend, and Troypofol. Dynapar QPS is the world’s first transdermal preparation of diclofenac, enhancing skin penetration for rapid pain relief, thus supporting patients undergoing sclerotherapy treatments.
Key Sclerotherapy Companies
The following key companies have been profiled for this study on the sclerotherapy market.
-
LGM Pharma
-
Troikaa
-
Viatris Inc.
-
Omega Pharmaceuticals Pvt. Ltd.
-
Merz Pharma
-
ENDO-FLEX GmbH.
-
Perrigo Company plc
-
Medi-Globe GmbH.
-
Medtronic
-
AngioDynamics
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Merz Pharma; Perrigo Company plc, Medtronic; AngioDynamics, Viatris Inc.)
- Established companies focus on expanding comprehensive sclerotherapy portfolios comprising liquid and foam sclerosants, catheter-based delivery systems, ultrasound-guided treatment solutions, and vascular intervention products for varicose veins, spider veins, hemorrhoids, hydroceles, and other venous disorders. They emphasize continuous innovation in sclerosant formulations, physician training programs, clinical validation, strategic collaborations with vascular clinics and hospitals, and global distribution expansion to strengthen market leadership.
- Strong global distribution networks, established relationships with vascular surgeons, interventional radiologists, dermatologists, hospitals, and ambulatory surgical centers support sustained market leadership. Broad product portfolios, proven clinical efficacy, advanced manufacturing capabilities, regulatory expertise, and significant R&D investments enable continuous innovation and widespread adoption across vascular and aesthetic medicine applications.
- Dependence on premium product portfolios may create pricing challenges in cost-sensitive healthcare markets. Strict regulatory requirements, extensive clinical validation, and lengthy approval processes can increase commercialization timelines and operational costs. Large organizational structures may also reduce agility in responding rapidly to evolving treatment technologies and emerging clinical needs.
Emerging Players (LGM Pharma, Troikaa, Omega Pharmaceuticals Pvt. Ltd., ENDO-FLEX GmbH, Medi-Globe GmbH)
- Emerging companies prioritize the development of cost-effective sclerosants, innovative foam formulations, advanced injection and catheter-based delivery technologies, and specialty products for minimally invasive venous interventions. They focus on expanding regional distribution, strengthening collaborations with vascular specialists and vein treatment centers, improving product performance, and addressing unmet clinical needs through differentiated sclerotherapy solutions.
- Agile product development, competitive pricing strategies, and the ability to rapidly introduce innovative sclerosant formulations and minimally invasive treatment technologies enable emerging companies to strengthen their market presence. Their specialization in vascular intervention products, flexible manufacturing capabilities, and focus on underserved regional markets provide opportunities to gain market share and respond quickly to evolving physician requirements.
- Limited global brand recognition and comparatively smaller distribution infrastructures may restrict international expansion. Lower financial resources can constrain large-scale clinical validation, regulatory approvals, manufacturing scale-up, and commercialization activities. Dependence on distributor partnerships and strong competition from established pharmaceutical and medical device companies may challenge long-term market penetration and revenue growth.
Recent Developments
-
In July 2024, Swizton Medcare announced a partnership with Medtronic to launch India’s first specialized clinic dedicated to the treatment of varicose veins. This initiative aims to enhance patient care by providing advanced diagnostic and therapeutic options for individuals suffering from venous diseases.
-
In August 2023, Viatris Inc. and Mapi Pharma Ltd. announced that the U.S. Food and Drug Administration (FDA) had accepted a New Drug Application (NDA) for GA Depot, a long-acting glatiramer acetate formulation intended for the treatment of Relapsing Multiple Sclerosis (MS).
Sclerotherapy Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.2 billion
Estimated market size in 2026
USD 1.3 billion
Projected market size by 2033
USD 1.7 billion
Growth rate
CAGR of 4.1% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Agent, type, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; South Korea; Thailand; Australia; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
LGM Pharma; Troikaa; Viatris Inc.; Omega Pharmaceuticals Pvt. Ltd.; Merz Pharma; ENDO-FLEX GmbH.; Perrigo Company plc; Medi-Globe GmbH.; Medtronic; AngioDynamics.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Sclerotherapy Market Report Segmentation
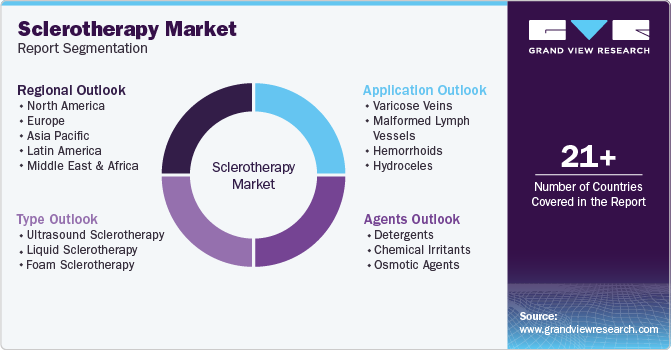
This report forecasts global, regional, and country revenue growth and analyzes the latest industry trends in each sub-segment from 2021 to 2033. For this study, Grand View Research has segmented the global sclerotherapy market report based on agents, type, application, and region:
 To learn more about this report, Download Free Sample Report
-
Agents Outlook (Revenue, USD Billion, 2021 - 2033)
-
Detergents
-
Chemical Irritants
-
Osmotic Agents
-
-
Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Ultrasound Sclerotherapy
-
Liquid Sclerotherapy
-
Foam Sclerotherapy
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Varicose Veins
-
Malformed Lymph Vessels
-
Hemorrhoids
-
Hydroceles
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Norway
-
Denmark
-
Sweden
-
-
Asia Pacific
-
Japan
-
China
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Mexico
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Segment Definition
Segment – Agent
Revenue capture definition
Detergents
Revenue is captured from detergent-based sclerosants such as polidocanol and sodium tetradecyl sulfate (STS), which damage the endothelial lining of veins through surfactant action. These agents are widely used in liquid and foam sclerotherapy due to their high efficacy, predictable safety profile, and broad application in treating varicose and spider veins.
Chemical Irritants
Revenue is generated from chemical irritant sclerosants, including agents such as chromated glycerin, which induce endothelial damage through direct chemical irritation. These products are primarily utilized for the treatment of smaller superficial veins and selected vascular lesions where controlled vessel sclerosis is required.
Osmotic Agents
Revenue is captured from osmotic sclerosants such as hypertonic saline and hypertonic saline with dextrose. These agents dehydrate endothelial cells, leading to vessel fibrosis and closure, and are commonly used for treating spider veins and small varicosities, particularly in patients requiring non-detergent formulations.
Segment – Type
Revenue capture definition
Ultrasound Sclerotherapy
Revenue is generated from ultrasound-guided sclerotherapy procedures that utilize duplex ultrasound imaging to accurately visualize and inject sclerosants into deeper or incompetent veins. This technique improves treatment precision, enhances procedural safety, and expands the management of chronic venous insufficiency.
Liquid Sclerotherapy
Revenue is captured from conventional liquid sclerosant procedures used primarily for treating spider veins and small varicose veins. The segment includes revenue from liquid sclerosant formulations administered through direct injection in outpatient vascular and dermatology clinics.
Foam Sclerotherapy
Revenue is generated from foam sclerotherapy procedures, where sclerosants are converted into foam before injection to improve vessel wall contact and treatment efficacy. Foam sclerotherapy is widely adopted for larger varicose veins and chronic venous insufficiency due to its superior clinical effectiveness and reduced sclerosant volume requirements.
Segment – Application
Revenue capture definition
Varicose Veins
Revenue is captured from sclerotherapy procedures performed for the treatment of symptomatic and cosmetic varicose veins. This represents the largest application segment, driven by the increasing prevalence of chronic venous disease, aging populations, obesity, pregnancy-related venous disorders, and growing demand for minimally invasive vein treatments.
Malformed Lymph Vessels
Revenue is generated from sclerotherapy procedures used to treat lymphatic malformations and abnormal lymphatic vessels. Sclerosing agents are injected into the malformed vessels to induce fibrosis and reduce lesion size, providing a minimally invasive alternative to surgical intervention.
Hemorrhoids
Revenue is captured from injection sclerotherapy performed for the management of internal hemorrhoids, particularly early-stage disease. Sclerosants promote fibrosis and shrinkage of hemorrhoidal tissue, reducing bleeding and prolapse while offering an effective outpatient treatment option.
Hydroceles
Revenue is generated from sclerotherapy procedures used for recurrent or non-communicating hydroceles, particularly in patients who are poor surgical candidates. The procedure involves aspiration followed by sclerosant injection to prevent fluid reaccumulation, offering a minimally invasive alternative to hydrocelectomy.
Estimation Model
01 – Scope Definition
02 – Build the Install Base
03 – Estimate Utilization & Procedure
04 – Revenue Conversion
What is being sized?
How large is the addressable sclerotherapy patient population?
What proportion undergoes sclerotherapy treatment?
How are treatment volumes converted into market revenue?
Process Steps
Process Steps
Process Steps
Process Steps
1. Define the market scope covering detergent, osmotic, and chemical sclerosants, including liquid, foam, and ultrasound-guided sclerotherapy
1. Estimate annual sclerotherapy procedures performed for varicose veins, spider veins, hemorrhoids, hydroceles, lymphatic malformations, and other vascular disorders
1. Assess utilization rates of different sclerosant types and treatment techniques
1. Determine average selling prices (ASP) of sclerosants, treatment kits, and procedure-related consumables by product type and regional market
2. Identify end users
2. Analyze disease prevalence, aging population trends
2. Evaluate physician adoption of foam sclerotherapy, ultrasound-guided procedures, and advanced injection techniques
2. Calculate market revenues by sclerosant type, treatment technique, application, end user, and region
3. Establish Geographic Coverage (Global/Regional)
3. Incorporate healthcare infrastructure, vascular specialist availability, outpatient treatment trends
3. Validate penetration assumptions through physician interviews, hospital procurement data, distributor insights, published clinical studies, and company reports
3. Validate revenue estimates using company financial reports
4. Align on base year & forecast horizon (2026–2033)
4. Forecast procedure growth based on demographic trends
4. Cross-verify adoption estimates using historical treatment data, clinical publications, expert interviews, market intelligence, and healthcare utilization trends
4. Cross-check final market estimates through triangulation using company revenues
Data Sources: FDA, EMA, PMDA, NMPA, Hospital Imaging Database
Data Sources: Company Annual Reports, Hospital Procurement Databases, Distributor Sales Data
Data Sources: Primary interviews, OECD Database, clinical surveys, industry experts
Data Sources: Company Annual Reports, Distributor pricing sheets, procurement data, expert interviews
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Product Technology and Treatment Assessment
Conducted a comprehensive assessment of sclerotherapy technologies, including detergent, osmotic, and chemical sclerosants, as well as liquid, foam, and ultrasound-guided sclerotherapy techniques. The study evaluated treatment efficacy, safety profiles, recurrence rates, injection protocols, foam preparation methods, imaging guidance technologies, and innovations in minimally invasive venous interventions across multiple clinical indications.
Enables stakeholders to identify emerging treatment technologies, evaluate product performance, and benchmark innovative sclerosant formulations and delivery techniques. Supports product development, clinical strategy, and long-term portfolio expansion decisions.
Competitive Landscape and Strategic Benchmarking
Performed a detailed competitive analysis of leading sclerotherapy product manufacturers based on product portfolios, sclerosant formulations, regulatory approvals, manufacturing capabilities, pricing strategies, geographic footprint, distribution networks, strategic collaborations, acquisitions, and recent product launches across global vascular and aesthetic medicine markets.
Provides actionable competitive intelligence by identifying market leaders, benchmarking commercialization strategies, evaluating competitive differentiation, and highlighting partnership and expansion opportunities. Supports strategic planning and investment decisions.
Regional Market and Clinical Adoption Analysis
Conducted a comprehensive regional assessment across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa by evaluating chronic venous disease prevalence, treatment procedure volumes, healthcare infrastructure, reimbursement policies, physician adoption, regulatory frameworks, and availability of minimally invasive vascular care.
Supports regional expansion strategies by identifying high-growth markets, evolving treatment adoption trends, unmet clinical needs, and healthcare investment opportunities. Enables optimized market entry, distribution planning, and resource allocation across developed and emerging markets.
Frequently Asked Questions About This Report
Key factors that are driving the sclerotherapy market growth include a rising global geriatric population with an increased incidence of varicose veins, high technological advancements for the treatment of venous diseases, and high demand for less invasive procedures.
Based on agents, the detergents segment led the market with the largest revenue share of 43.8% in 2025.
Based on type, the foam sclerotherapy segment led the market with the largest revenue share of 38.3% in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
Based on agents, the detergents segment led the market with the largest revenue share of 43.8% in 2025.
Based on type, the foam sclerotherapy segment led the market with the largest revenue share of 38.3% in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
North America dominated the sclerotherapy market with a share of 44.2% in 2025. This is attributable to rising geriatric population with varicose veins, high technological advancements pertaining to venous diseases, and high acceptance of minimally invasive procedures.
Some key players operating in the sclerotherapy market include LGM Pharma; Troikaa; Viatris Inc.; Omega Pharmaceuticals Pvt. Ltd.; Merz Pharma; ENDO-FLEX GmbH.; Perrigo Company plc; Medi-Globe GmbH.; Medtronic; AngioDynamics.
The global sclerotherapy market size was valued at USD 1.2 billion in 2025 and is estimated at USD 1.3 billion for 2026.
The global sclerotherapy market is expected to grow at a CAGR of 4.1% from 2026 to 2033, reaching USD 1.7 billion by 2033.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


