
- Home
- »
- Automotive & Transportation
- »
-
Semi-trailer Market Size, Share & Growth Report, 2026-2033GVR Report cover

Semi-trailer Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Flat Bed Trailer, Dry Vans, Refrigerated Trailers, Lowboy Trailers, Tankers), By Region (North America, Europe, Asia Pacific, Latin America, MEA), And Segment Forecasts
Market Size, 2025
$24.2BMarket Estimate, 2026
$25.7BMarket Forecast, 2033
$42.3BCAGR, 2026–2033
7.3%Semi-trailer Market Summary
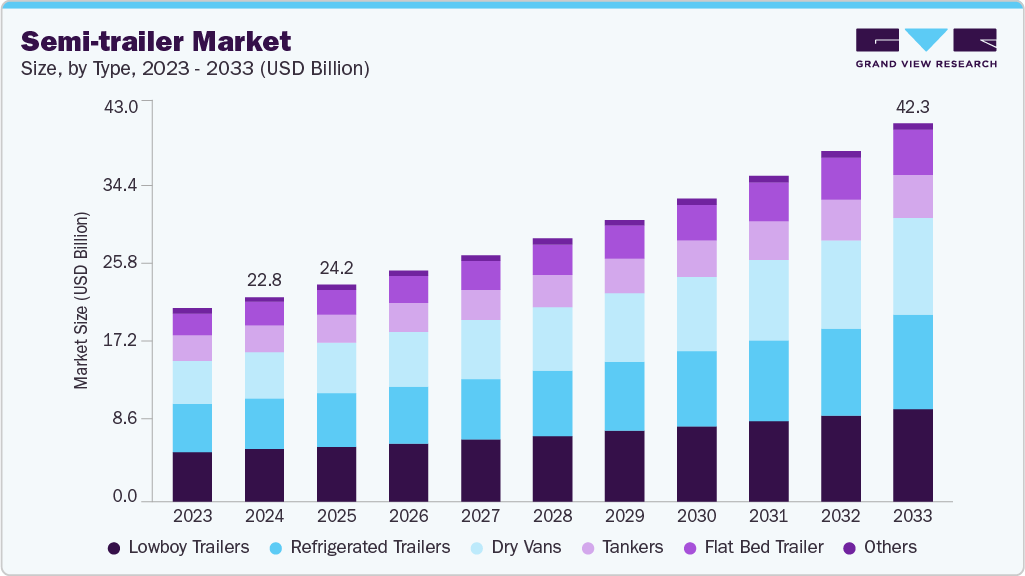
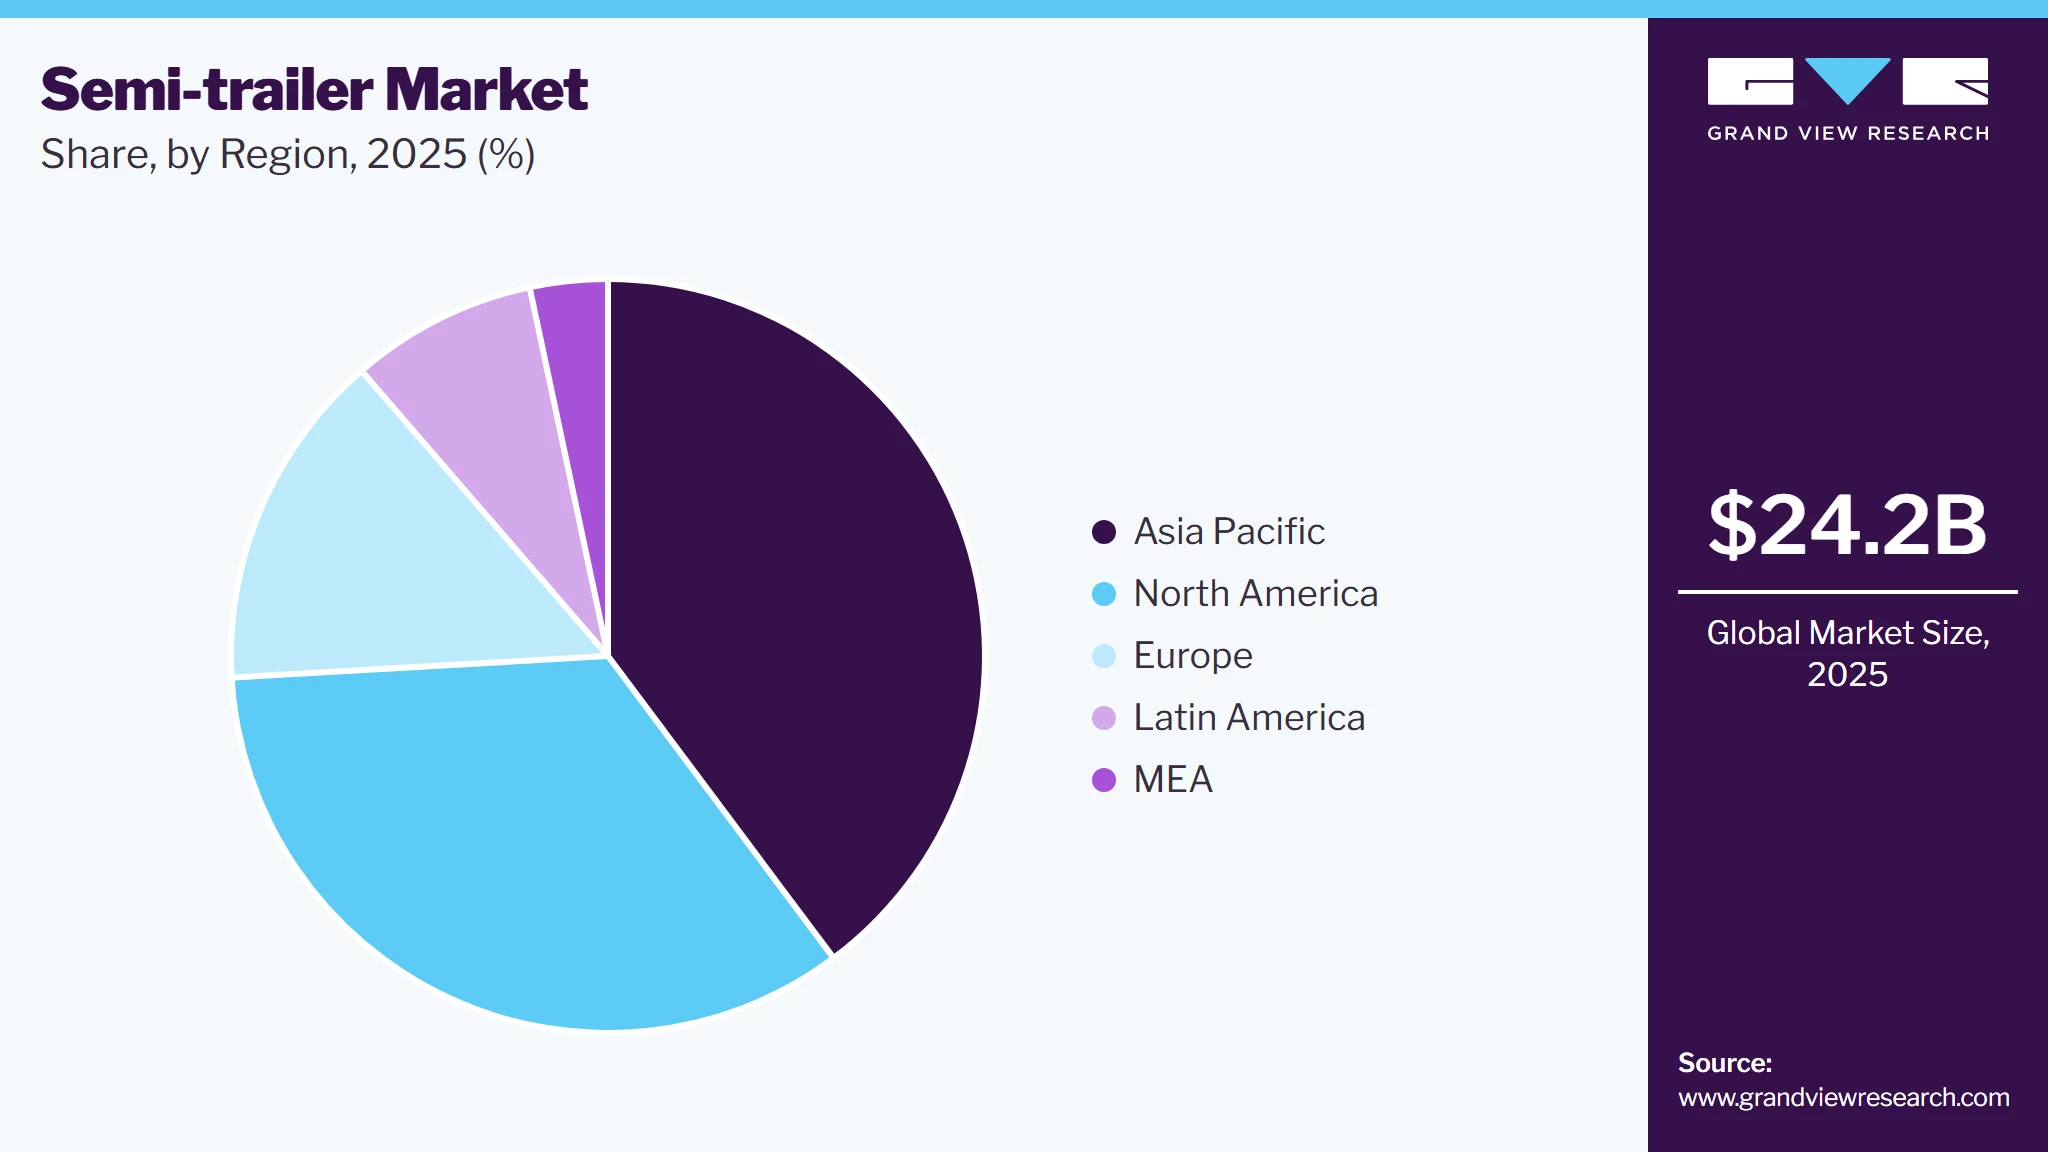
The global semi-trailer market size was valued at USD 24.2 billion in 2025 and is projected to grow from USD 25.7 billion in 2026 to USD 42.3 billion by 2033, at a CAGR of 7.3% from 2026 to 2033. Asia Pacific dominated the global market, accounting for a revenue share of 39.8% in 2025. Rising urbanization, increasing manufacturing output, and the growing need for efficient freight transportation are expected to be key factors driving the demand for semi-trailers.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Lowboy Trailers segment dominated the market, with a revenue share of 25.6% in 2025
- The dry vans segment is expected to expand at the fastest CAGR of 8.6% over the forecast period.
Regional Highlights
- Largest regional market: Asia Pacific (39.8% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 24.2 Billion
- Estimated market size in 2026: USD 25.7 Billion
- Projected market size by 2033: USD 42.3 Billion
- CAGR (2026-2033): 7.3%
Prism AI by Grand View Research Free to tryAsk a question about the semi-trailer marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
The expansion of end-use industries such as logistics, retail, and construction is further contributing to the market growth. In particular, the rapid development of the cold chain industry is fueling the demand for refrigerated trailers to ensure temperature-sensitive cargo remains intact throughout transit. Moreover, fleet operators are increasingly adopting custom-built and application-specific semi-trailers, creating new avenues for manufacturers to offer tailored solutions.This shift toward customization enhances operational efficiency and meets niche transportation requirements across different sectors. Also, the integration of telematics and smart tracking technologies into semi-trailers is emerging as a lucrative opportunity, enabling real-time fleet management, predictive maintenance, and improved asset utilization.
 To learn more about this report, Download Free Sample Report
Logistics is one of the primary end use sectors for semi-trailers, with road transportation offering a cost-effective and flexible mode of freight movement. Improved road infrastructure, especially in emerging economies, is accelerating the use of trailers and trucks to meet the rising demand for goods delivery across the FMCG, e-commerce, and retail sectors. The shift toward fast and doorstep deliveries, driven by urbanization and changing lifestyles, is further boosting demand for road freight solutions. The growing demand for temperature-sensitive products such as pharmaceuticals, poultry, dairy, and fresh produce is fueling the need for refrigerated semi-trailers. Rising middle-class incomes, along with increasing awareness of health and nutrition, are encouraging consumers to opt for fresh, organic, and premium-quality products. This shift has supported the growth of QSR chains and fresh food delivery services, thereby expanding the global cold chain logistics network.
The FMCG industry, which depends on the rapid distribution of low-cost, high-demand perishable goods, continues to be a major driver of transportation needs. Factors such as increasing consumer spending, heightened brand awareness, growing digital retail adoption, and population growth are accelerating the demand for fast and reliable logistics. Since many FMCG items have limited shelf lives, efficient and timely transport using semi-trailers is essential for maintaining product quality and availability.
The shift from internal combustion engines to electric propulsion in commercial transportation is opening up a significant opportunity for manufacturers. Electrification addresses the dual goals of sustainability and cost efficiency, especially in regions enforcing strict emission norms. With ongoing R&D and investment in EV infrastructure, electric semi-trailers are poised to become a mainstream segment over the next decade. The explosion of e-commerce, along with omnichannel retail strategies, is driving the need for efficient regional and last-mile delivery networks. Semi-trailers that support intermodal logistics and quick loading/unloading cycles are gaining prominence. This trend is particularly visible in densely populated urban areas and fast-growing tier-2 and tier-3 cities.
Although semi-trailers are cost-effective over the long term, the high upfront investment can be a barrier for small and mid-sized fleet operators. The lack of widespread awareness about long-term TCO benefits and operational efficiency gains can slow down the market adoption in cost-sensitive regions.
Market Dynamics
The semi-trailer market is experiencing steady growth, driven by expanding freight transportation activity, rising e-commerce volumes, increasing cross-border trade, and the need for efficient logistics infrastructure. Technological advancements such as lightweight trailer materials, telematics integration, aerodynamic designs, refrigerated systems, and connected fleet management solutions are reshaping trailer operations. Growing emphasis on fuel efficiency, payload optimization, and regulatory compliance is encouraging fleet operators to invest in advanced semi-trailer solutions. The market is also evolving toward smart and sustainable transportation solutions, with manufacturers focusing on digital connectivity, electrification readiness, and improved lifecycle performance.
The growth of global trade, urbanization, and e-commerce activities has significantly increased the demand for reliable freight transportation solutions. Logistics operators are under pressure to improve delivery efficiency, increase payload capacity, and reduce operational costs while managing growing shipment volumes. Road freight remains a critical mode of transportation across regions due to its flexibility and ability to support last-mile and long-distance distribution networks. These factors are increasing demand for semi-trailers that can support diverse cargo requirements across industries such as retail, automotive, food & beverage, pharmaceuticals, and manufacturing.
Semi-trailers enable logistics companies to optimize transportation operations through higher cargo capacity, flexible configurations, and compatibility with different truck models. Manufacturers are introducing lightweight structures, improved suspension systems, aerodynamic designs, and specialized trailer solutions to enhance fuel efficiency and reduce operating expenses. The adoption of dry vans, refrigerated trailers, tankers, and flatbed trailers is expanding as companies seek application-specific transportation solutions. These advancements are supporting fleet modernization and accelerating the global demand for semi-trailers.
The high acquisition cost associated with advanced semi-trailers remains a key challenge for small and medium-sized fleet operators. Modern semi-trailers equipped with lightweight materials, refrigeration systems, telematics, and advanced safety technologies require significant upfront investment compared with conventional trailer models. In addition, maintenance expenses related to specialized components, refrigeration units, electronic systems, and structural repairs can increase the total cost of ownership. This cost pressure limits adoption among price-sensitive operators, particularly in developing markets.
The impact of high investment requirements is more pronounced in emerging economies, where transportation companies often operate with limited capital. Small fleet owners may continue to use older trailers due to replacement-cost concerns, thereby slowing fleet modernization rates. The restraint hinders the adoption of premium, technologically advanced semi-trailer solutions, especially refrigerated and smart-connected trailers. However, leasing models, fleet financing programs, and increasing demand for operational efficiency are gradually reducing this barrier.
The integration of digital technologies into transportation operations is creating new opportunities for semi-trailer manufacturers. Fleet operators are increasingly adopting telematics, GPS tracking, remote monitoring, predictive maintenance systems, and IoT-enabled solutions to improve asset utilization and reduce downtime. Connected semi-trailers provide real-time visibility into trailer location, cargo conditions, maintenance requirements, and operational performance. The growing focus on supply chain transparency and fleet optimization is encouraging investments in intelligent trailer solutions.
Manufacturers offering connected, lightweight, and energy-efficient semi-trailers are positioned to capture emerging opportunities in the market. Refrigerated trailer providers can benefit from increasing demand for temperature-controlled logistics, while smart trailer solution providers can gain traction among large logistics companies and fleet operators. Companies integrating digital platforms, advanced materials, and sustainable technologies are expected to strengthen their competitive positioning as transportation networks become increasingly automated and data driven.
Analyst Perspective
The semi-trailer market is positioned for steady expansion as rising freight transportation demand, logistics modernization, and fleet replacement drive growth. Technology adoption, including telematics, lightweight materials, aerodynamic improvements, and smart monitoring systems, is transforming conventional trailers into connected transportation assets. Manufacturers are increasingly focusing on sustainable designs, operational efficiency, and application-specific solutions to meet evolving customer requirements. The market is expected to witness continued investments in advanced trailer technologies, with prominent players strengthening their positions through innovation, strategic partnerships, and expansion into high-growth logistics segments.
Type Insights
Based on type, the lowboy trailers segment led the market with the largest revenue share of 25.6% in 2025. The demand for heavy equipment transportation, infrastructure development, and e-commerce drive the need for lowboy trailers. Additionally, new technologies are making lowboy trailers more efficient and cost-effective.
The dry vans segment is expected to expand at the fastest CAGR of 8.6% over the forecast period. Dry vans generally transport freight that requires nominal protection against road and climate conditions. Full truckload (FTL) and less-than-truckload (LTL) fleet operators rely on these trailers for their operations due to their cost-effectiveness and flexibility.
The flatbed trailer held a significant market share in 2025. The growth in the construction industry across developed and emerging economies is anticipated to fuel the segment growth. Flatbed trailers are generally used to transport heavy cargo, such as machinery, construction materials, and equipment. Besides, the adoption of refrigerated trailers is expected to increase significantly due to the flourishing cold chain industry. The increasing number of QSRs, the general push for healthier, fresh products, and higher disposable income positively impact every aspect of the cold chain industry.
Regional Insights
Asia Pacific dominated the global semi-trailer market with the largest revenue share of 39.8% in 2025.The regional market is mainly driven 4, driven by rapid economic expansion in India and China, the rise of e-commerce logistics, growing demand for sustainable freight solutions, and increasing public-private investments in road freight infrastructure. The region’s growing emphasis on domestic manufacturing partnerships and technological integration is shaping a more self-reliant and efficient trailer supply chain. For instance, in April 2023, MaxiTRANS, a major Australian heavy-duty trailer supplier, partnered with Schmitz Cargobull to strengthen its market footprint and technological capability. This strategic alliance enabled the localization of premium trailer manufacturing, enhancing supply efficiency within Australia and nearby Asian markets.
 To learn more about this report, Download Free Sample Report
Asia Pacific is also becoming a key launchpad for next-generation, clean-energy freight vehicles amid tightening emissions standards. In December 2024, Propel Industries introduced the 470 eTR electric tractor-trailer at bauma CONEXPO India, featuring a 55-ton GCW, up to 550 kWh battery options, and a 350 km range. Designed for long-haul logistics, it integrates advanced telematics and supports zero-emission operations, underscoring the region’s shift toward decarbonized freight transport. This reinforces the region’s strategic pivot toward sustainable freight mobility, where regulatory support, innovation, and commercial demand are converging to accelerate the deployment of electric and environmentally responsible semi-trailer solutions.
The semi-trailer market in the China held the largest share in the Asia Pacific region in 2025.. The Semi-trailer market in China is experiencing rapid growth, driven by the rapid expansion of domestic logistics networks, the rising demand for cold chain infrastructure, increased government investment in freight corridor development, and the ongoing shift toward high-capacity and fuel-efficient transport vehicles. China's booming e-commerce and retail sectors have intensified the need for scalable, last-mile and intercity freight capabilities, while stricter emissions regulations are pushing the adoption of more advanced and compliant semi-trailer systems.As a result, China continues to emerge as one of the most dynamic and strategically important markets for semi-trailer manufacturers and fleet operators worldwide.
The semi-trailer market in Japan held a significant share in 2025. Japan's mature logistics ecosystem relies heavily on precision, timeliness, and advanced vehicle technologies to support its dense urban networks and export-heavy economy. With space constraints and a shrinking workforce, the country is gradually shifting toward higher-capacity and technologically integrated trailer solutions. In Japan, the semi-trailer market is influenced by the steady demand for efficient freight transportation, rising focus on low-emission logistics, aging driver demographics prompting automation, and robust aftermarket trailer maintenance services.
Europe Semi-trailer Market Trends
The European semi-trailer industry was identified as a lucrative region in 2025. The European semi-trailer market is witnessing significant transformation, driven by rising demand for smart trailer technologies, stringent CO₂ emission norms, the growth of cross-border e-commerce, and increased investments in digital freight platforms. The region’s strong regulatory framework and emphasis on sustainability have encouraged manufacturers to integrate telematics, automation, and energy-efficient designs into their trailer offerings. For instance, in April 2023, Schmitz Cargobull partnered with Trimble to enhance data-driven freight forwarding. This collaboration allows freight forwarders to leverage real-time trailer data for better operational planning, efficiency, and visibility. This reflects Europe’s strategic push toward intelligent transport systems, making the region a leading hub for connected and eco-conscious semi-trailer innovations.
Germany Semi-trailer market is witnessing growth due tobGermany’s position as a logistics hub within Europe, coupled with its ambitious decarbonization goals, is pushing fleets to adopt technologically advanced and fuel-efficient trailer solutions. The German semi-trailer market is being shaped by increasing emphasis on green logistics, strong demand from the automotive and industrial sectors, integration of advanced telematics in fleet operations, and ongoing investment in cold chain transport infrastructure. Germany’s central location and highly developed autobahn network make it a natural distribution gateway for intra-European trade, boosting demand for high-performance trailers, particularly refrigerated and curtain-side variants.
Furthermore, EU regulations promoting CO₂ reduction in freight transportation are accelerating the shift toward lightweight materials, electric axles, and digital trailer monitoring systems.
The semi-trailer market in UK is driven by post Brexit supply chain adjustments, growth in online retail logistics, rising focus on fleet automation, and investments in last-mile cold chain delivery. As logistics companies adapt to new customs and cross-border regulations, there is a growing preference for semi-trailers that offer flexibility, modularity, and data integration to ensure delivery continuity. The surge in e-commerce, particularly in food, pharmaceuticals, and same-day delivery segments, has prompted investment in temperature-controlled trailers and smaller-format urban delivery units. In addition, government incentives around decarbonizing transport are promoting the adoption of smart trailers equipped with fuel-saving features and load-tracking sensors.North America Semi-trailer Market Trends
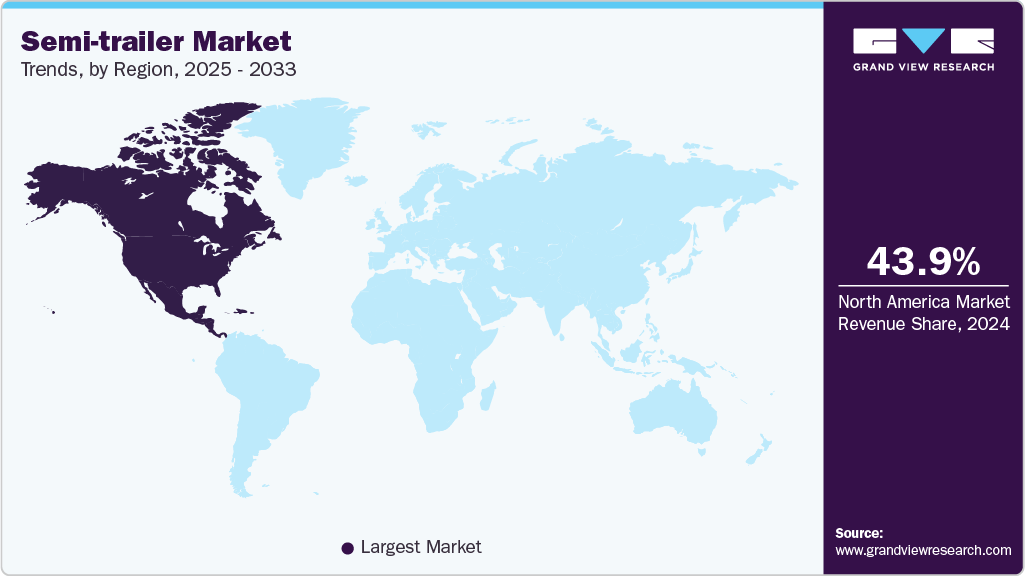
The semi-trailer industry in North America was identified as a lucrative region in 2025. The market is currently in the replacement phase with an aging fleet that needs to be replaced with technologically advanced semi-trailers. Moreover, the busy road infrastructure network and the growing transportation and logistics industry in the U.S. and Canada are expected to boost the regional market growth. Furthermore, relaxation in government regulations regarding weight carrying capacity and dimensions of the semi-trailer is anticipated to fuel the demand for lightweight transport vehicles, thereby driving the market demand. In addition, the California Air Resources Board (CARB) mandated the installation of “SmartWay,” a verified aerodynamic technology, to improve fuel efficiency in tractors and semi-trailers.
 To learn more about this report, Download Free Sample Report
In Canada, the semi-trailer market is driven by the expansion of cross-border trade with the U.S., increasing infrastructure investments, rising demand for temperature-controlled logistics, and adoption of smart trailer technologies. Mexico’s growing role as a North American manufacturing base has intensified demand for flatbed, lowboy, and tank trailers to support sectors including automotive, electronics, and petrochemical. In Mexico, the semi-trailer market is experiencing strong growth, fueled by nearshoring trends, the expansion of industrial manufacturing hubs, rising exports to the U.S., and government-backed investments in logistics infrastructure.
U.S. Semi-trailer Market Trends
The U.S. semi-trailer industry held a dominant position in 2025. The semi-trailer market in the U.S. is witnessing significant transformation, driven by rising demand for sustainable freight solutions, rapid expansion of cold chain logistics, integration of advanced telematics and automation, and federal investments in transportation infrastructure. The country’s vast domestic freight movement, growing e-commerce volumes, and focus on emission reduction targets are prompting fleet operators to modernize their trailer fleets with energy-efficient, smart, and compliant technologies. Increased regulatory pressure and customer expectations for transparency and traceability in logistics are also accelerating the adoption of connected and low-emission trailer systems. For instance, in September 2024, Carrier Transicold launched the Vector HE 19 refrigeration unit for semi-trailers at IAA Transportation in Germany. Featuring a low-GWP refrigerant and B100 biofuel compatibility, the unit offers up to 84% annual CO₂ emission reduction, supporting the shift toward sustainable cold chain logistics solutions.
Key Semi-trailer Company Insights
Some of the key players operating in the market include Qingdao CIMC Special Vehicles Co., Ltd, Fontaine Trailer, Kögel, and Great Dane A Division of Great Dane LLC.
-
Founded in 2004 and headquartered in Qingdao, China, Qingdao CIMC Special Vehicles Co., Ltd. is a subsidiary of China International Marine Containers (CIMC). The company specializes in the manufacturing of a wide range of semi-trailers, including flatbeds, container chassis, low-bed trailers, dump trailers, cement tankers, fuel tankers, and other specialized transport equipment. It serves markets across Africa, Southeast Asia, the Americas, Australia, and South Korea. The company operates a large-scale manufacturing facility near Qingdao Port and Airport, integrating advanced production lines, automation technologies, and high-quality branded components.
-
Founded in 1940 and headquartered in Haleyville, Alabama, Fontaine Trailer Company is a division of Marmon Holdings, a Berkshire Hathaway company. It is the largest platform trailer manufacturer in North America, specializing in the production of flatbeds, drop decks, extendables, lowbeds, and hydraulic tail trailers. The company operates advanced manufacturing facilities in Haleyville and Springville, Alabama. Fontaine Trailer is known for its commitment to quality and innovation, offering durable trailer solutions under product lines such as Velocity and TraverseHT. Its trailers are widely used across the heavy-haul, construction, industrial, and intermodal sectors, supported by IATF 16949-certified processes and a focus on continuous improvement.
Key Semi-trailer Companies:
The following are the leading companies in the semi-trailer market.
- Qingdao CIMC Special Vehicles Co., Ltd
- Fontaine Trailer
- Great Dane A Division of Great Dane LLC.
- Kögel
- KRONE Trailer
- LAMBERET SAS
- Polar Tank Trailer.
- Schmitz Cargobull.
- Utility Trailer Manufacturing Company
- Wabash National Corporation.
- HYUNDAI TRANSLEAD
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Schmitz Cargobull, Wabash National Corporation, Utility Trailer Manufacturing Company, KRONE Trailer)
- These players are focused on wide product portfolios, large-scale manufacturing, strong distribution networks, and continuous product innovation.
- These players have strong brand presence, broad customer base, and advanced manufacturing capabilities.
- Higher operating costs and slower adaptation to emerging technologies.
Emerging Players (Qingdao CIMC Special Vehicles Co., Ltd, Fontaine Trailer, LAMBERET SAS)
- These players are focused on specialized trailer solutions, regional expansion, and application-specific product development.
- Competitive pricing, niche expertise, and growing presence in targeted segments.
- Limited global reach and lower brand recognition compared with established players.
Recent Developments
-
In April 2025, Disfrimur launched Spain’s largest refrigerated semi-trailer combination, a 32-meter, 70-ton truck set using two SOR trailers and a dolly. Developed with MAN and SOR Ibérica, the project aims to optimize cold chain logistics by doubling cargo capacity while reducing emissions and operational costs.
-
In February 2025, Volvo Trucks launched India’s first Road Train solution in partnership with Delhivery Ltd. The configuration includes a 44-ft semi-trailer and offers 50% more cargo volume than standard setups, marking a major advancement in high-capacity road transport under India’s Gati Shakti infrastructure initiative.
-
In January 2025, EKA Mobility unveiled its 55-ton electric tractor-trailer at Auto Expo 2025. Featuring a 322 kW battery, dual charging options, and a 42-ton payload capacity, the vehicle represents a significant step toward electrifying heavy-duty semi-trailer transport in India’s evolving logistics landscape.
-
In November 2024, Mack Trucks announced plans to launch a new flagship Class 8 semi-tractor in 2025. Touted as a market disruptor, the vehicle is designed to significantly expand Mack’s competitive footprint across long-haul freight, with expectations to boost its share in the semi-trailer-driven logistics segment.
-
In February 2023, The Great Dane, a Division of Great Dane LLC., a trailer manufacturer, announced upgrades to its FleetPulse smart trailer system and an electrification option from SAF-Holland for its trailers. ABS fault code notifications and hub rotation miles added to the FleetPulse system, which assists fleets in enhancing safety and efficiency.
-
In February 2023, Kögel opened a workshop at its headquarters in Burtenbach, Germany. The workshop offers a wide range of services for semi-trailers and trailers of all brands. With this workshop, customers gained access to repairs, maintenance, upgrades, and customizations.
-
In January 2023, a container logistics company, KBC, expanded its fleet of Krone trailers with 51 new Box Liner FS10 skeletal trailers. The new trailers help KBC to support its rapid growth in the container logistics market.
-
In January 2023, J.B. Hunt and Wabash National Corporation signed a multi-year trailer supply agreement. The agreement between Wabash Trailers and J.B. Hunt included a supply of over 15,000 trailers.
Semi-trailer Market Report Scope
Report Attribute
Details
Market size in 2025
USD 24.2 billion
Estimated Market size in 2026
USD 25.7 billion
Projected Market size by 2033
USD 42.3 billion
Growth rate
CAGR of 7.3% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company market share, competitive landscape, growth factors, and trends
Segments covered
Type, region
Regional scope
North America; Europe; North America; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; U.K.; France; China; Japan; India; South Korea; Australia; Brazil; Saudi Arabia; UAE; and South Africa
Key companies profiled
Qingdao CIMC Special Vehicles Co., Ltd; Fontaine Trailer; Great Dane A Division of Great Dane LLC.; Kögel; KRONE Trailer; LAMBERET SAS; Polar Tank Trailer.; Schmitz Cargobull.; Utility Trailer Manufacturing Company; Wabash National Corporation.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Semi-trailer Market Report Segmentation
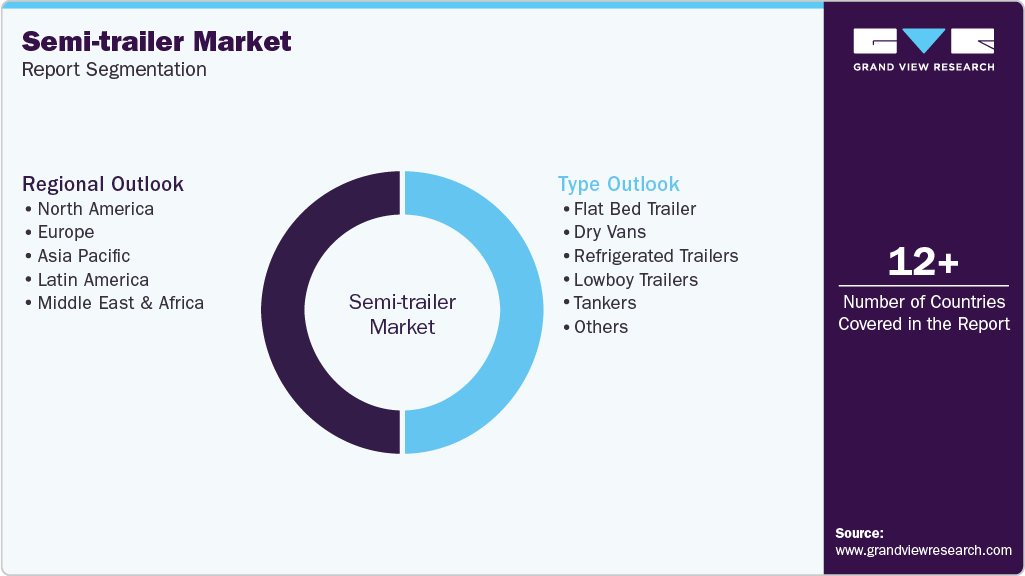
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global semi-trailer market report based on type and region.
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Million; Volume Units, 2021 - 2033)
-
Flat Bed Trailer
-
Dry Vans
-
Refrigerated Trailers
-
Lowboy Trailers
-
Tankers
-
Others
-
-
Regional Outlook (Revenue, USD Million; Volume, Units, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
-
Middle East & Africa (MEA)
-
UAE
-
Kingdom of Saudi Arabia (KSA)
-
South Africa
-
-
Research Methodology
The semi-trailer market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each semi-trailer segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Vehicle Type
Revenue capture definition
Flat Bed Trailer
Revenue generated from the sale and customization of open-platform semi-trailers designed for transporting oversized, heavy, or irregularly shaped cargo such as construction materials, machinery, steel products, and industrial equipment.
Dry Vans
Revenue from enclosed semi-trailer sales is used to transport general freight, packaged goods, consumer products, electronics, automotive components, and non-temperature-sensitive cargo.
Refrigerated Trailers
Revenue is generated from the manufacturing and sales of temperature-controlled semi-trailers equipped with refrigeration systems for transporting food products, pharmaceuticals, beverages, and other perishable goods.
Lowboy Trailers
Revenue generated from specialized semi-trailers designed for heavy-haul transportation of construction equipment, mining machinery, agricultural equipment, and oversized loads requiring low deck height.
Tankers
Revenue generated from semi-trailer units designed for liquid and bulk transportation applications, including petroleum products, chemicals, food-grade liquids, gases, and industrial materials.
Others
Revenue is generated from specialized semi-trailer categories, including dump trailers, container chassis, livestock trailers, logging trailers, utility trailers, and other customized transportation solutions.
Estimation Model
Layer Name
Key Question
Description
Industry Demand Assessment
What factors determine overall semi-trailer demand?
This layer evaluates macroeconomic factors influencing the semi-trailer market, including freight transportation growth, logistics activity, e-commerce expansion, industrial production, and trade flows. It analyzes demand patterns across major end-use industries such as retail, manufacturing, agriculture, construction, and pharmaceuticals. Regional transportation infrastructure development and fleet expansion trends are also considered.
Trailer Production and Supply Analysis
How much semi-trailer capacity is available in the market?
This layer assesses semi-trailer manufacturing volumes, production capabilities, supplier networks, and capacity expansion strategies of manufacturers. It evaluates the availability of different trailer types, including dry vans, refrigerated trailers, tankers, and flatbed trailers. Manufacturer investments in automation, lightweight materials, and smart technologies are considered to estimate supply-side growth.
Segment and Application Analysis
Which trailer types and applications generate market revenue?
This layer analyzes revenue contribution from different semi-trailer categories based on application requirements and customer demand. It evaluates adoption trends across freight transportation, cold chain logistics, industrial transportation, and specialized cargo movement. Pricing trends, customization requirements, and technology integration levels are considered for segment-level estimation.
Competitive Landscape and Future Outlook
How will market participants influence future growth?
This layer evaluates competitive positioning, product portfolios, strategic partnerships, technology investments, and regional expansion strategies of semi-trailer manufacturers. It considers how established and emerging players are adopting lightweight designs, connected technologies, and sustainable solutions. Future market growth is estimated based on innovation trends, replacement demand, and evolving logistics requirements.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Semi-trailer Market Opportunity Assessment
Country/region-wise market sizing and forecasts
Analysis of demand, adoption trends, and regulatory landscape
Identification of high-growth regions and investment hotspots
Identified region-specific growth opportunities
Supported expansion and go-to-market strategy
Enabled informed regional investment decisions
Cross-Segmentation Analysis for the Semi-trailer Market
Criss-cross market analysis by type
Demand and adoption assessment across key segments
Segment attractiveness and growth potential benchmarking
Identified high-potential market segments
Supported targeted product positioning and marketing strategy
Improved customer and segment prioritization
Competitive Benchmarking and Strategic Positioning in the Semi-trailer Market
Benchmarking of key competitors across products, pricing, partnerships, and innovation
Comparative assessment of market share, capabilities, and strategies
Analysis of competitive strengths, gaps, and differentiation areas
Identified competitive white spaces and growth gaps
Supported strategic positioning and differentiation
Enabled data-driven competitive strategy development
Frequently Asked Questions About This Report
The global semi-trailer market size was estimated at USD 24.2 billion in 2025 and is expected to reach USD 25.7 billion in 2026.
The global semi-trailer market is expected to grow at a compound annual growth rate of 7.3% from 2026 to 2033, reaching USD 42.3 billion by 2033.
Lowboy Trailers segment dominated the market, with a revenue share of 25.6% in 2025. The demand for heavy equipment transportation, infrastructure development, and e-commerce drive the need for lowboy trailers.
Dry vans are the fastest-growing segment over the forecast period.
The China held the largest market share in 2025.
India is the fastest-growing country over the forecast period.
Asia Pacific dominated the global market with the largest revenue share of 39.8% in 2025, driven by rapid economic expansion in India and China, the rise of e-commerce logistics, growing demand for sustainable freight solutions, and increasing public-private investments in road freight infrastructure.
Rising urbanization, increasing manufacturing output, and the growing need for efficient freight transportation are expected to be key factors driving the demand for semi-trailers.
Some key players operating in the semi-trailer market include Qingdao CIMC Special Vehicles Co., Ltd; Fontaine Trailer; Great Dane A Division of Great Dane LLC.; Kögel; KRONE Trailer; LAMBERET SAS; Polar Tank Trailer.; Schmitz Cargobull.; Utility Trailer Manufacturing Company; Wabash National Corporation.
About the Author(s)
Automotive & Transportation Research Team
Technology · Automotive & TransportationThis report was authored by the automotive & transportation research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the automotive & transportation segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


