
- Home
- »
- Plastics, Polymers & Resins
- »
-
Smart Card Materials Market Size, Share Report, 2026-2033GVR Report cover

Smart Card Materials Market (2026 - 2033)
Size, Share & Trends Analysis Report By Material (PVC, Polycarbonate, Others), By Type (Contact, Contactless, Multi-component), By End Use (BFSI, Government, Others), By Region, And Segment Forecasts
Market Size, 2025
$1.8BMarket Estimate, 2026
$1.9BMarket Forecast, 2033
$2.8BCAGR, 2026–2033
5.2%Smart Card Materials Market Summary
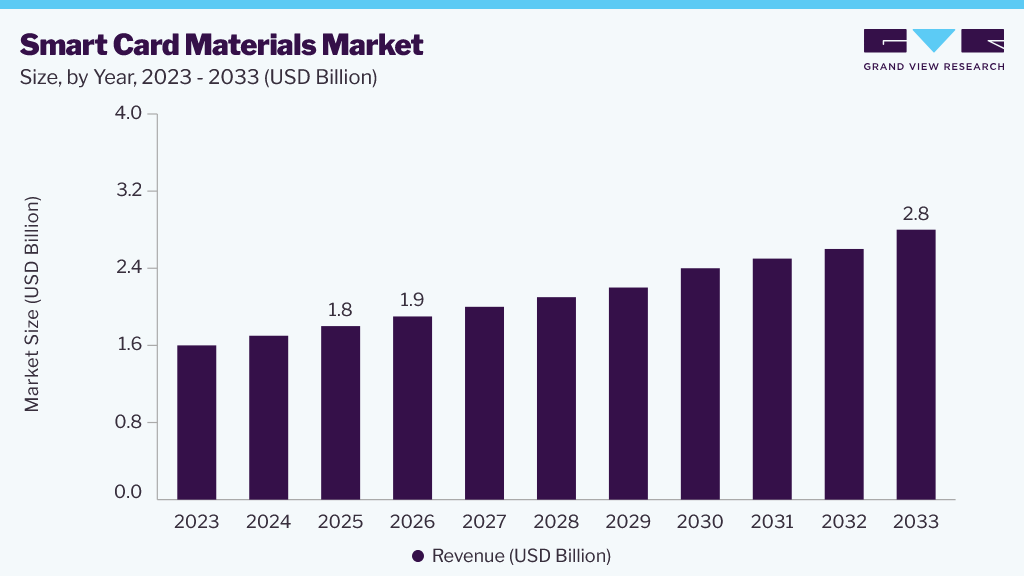
The global smart card materials market size was estimated at USD 1.8 billion in 2025 and is projected to grow from USD 1.9 billion in 2026 to USD 2.8 billion by 2033, growing at a CAGR of 5.2% from 2026 to 2033. The Asia Pacific market dominated, accounting for a revenue share of approximately 43.0% in 2025. The burgeoning demand for reliable, secure payment transactions and the increasing inclination towards cashless payments are expected to be the primary drivers of market growth.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By material: Polyvinyl Chloride (PVC) dominated the market and accounted for the largest revenue share of over 45.0% in 2025.
- By type: Contact cards led the market and accounted for the largest revenue share of over 60.0% of the market share in 2025.
- By end use: Telecommunication dominated the market with over 45.0% share in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (43.0% revenue share, 2025)
- Fastest-growing regional market: Europe (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 1.8 Billion
- Estimated market size in 2026: USD 1.9 Billion
- Projected market size by 2033: USD 2.8 Billion
- CAGR (2026-2033): 5.2%
Prism AI by Grand View Research Free to tryAsk a question about the smart card materials marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →This trend is particularly evident in the banking, financial services, and insurance (BFSI) sector, where smart cards are used for credit and debit cards, and secure access to banking services. In addition, these materials are widely used to produce universal integrated circuit cards (UICC) in mobile phones and subscriber identity modules (SIM) in the telecommunication industry.
Manufacturers have increasingly sought materials, including polyvinyl chloride (PVC), polycarbonate (PC), and acrylonitrile butadiene styrene (ABS), to enhance the durability and functionality of smart cards. These materials are essential for producing cards that withstand physical wear and tear while maintaining high security. Furthermore, integrating smart card technology into mobile devices, smartphones, and wearables has expanded the applications, making them more versatile and user-friendly.
Moreover, the increasing need for secure identification and authentication solutions has driven the market. Governments and organizations worldwide have adopted smart cards for identity verification, access control, and secure data storage. For instance, e-passports, national ID cards, and driver’s licenses are increasingly embedded with smart card technology to enhance security and prevent fraud. This trend is particularly prominent in regions with stringent security regulations and a high emphasis on data protection.
Despite the widespread usage of smart card materials, the market has faced significant challenges. Uncertainty in ethylene prices has increased the cost of production and distribution, which in turn has affected the prices of vinyl chloride monomers (VCM). VCM is the immediate raw material used to produce PVC. Fluctuating VCM prices have negatively influenced the final cost of PVC. Such volatility in ethylene prices might consequently affect the profit margins of market participants.
Analyst Perspective
The smart card materials market is experiencing steady growth, driven by the expanding adoption of secure payment systems and digital identity verification across banking, telecommunications, transit, and government sectors. To meet demands for higher security and durability, manufacturers are utilizing advanced polymers, specialty adhesives, conductive inks, and protective laminates. Although the market faces challenges like volatile raw material costs, cybersecurity threats, and the rise of mobile alternatives, technological advancements in contactless systems and sustainable materials offer significant new opportunities. Moving forward, businesses focusing on eco-friendly, highly durable, and secure card materials will be best positioned to capture long-term market growth.
Material Insights
Polyvinyl Chloride (PVC) dominated the market, accounting for the largest revenue share of over 45.0% in 2025, owing to its excellent chemical, mechanical, tensile strength, and thermal properties. This thermoplastic polymer offers a unique combination of durability, flexibility, and cost-effectiveness, making it ideal for smart card production. In addition, PVC can be easily molded and shaped into various forms, allowing for the efficient production of smart cards with different designs and functionalities. This flexibility in manufacturing is essential to meeting the diverse needs of industries such as banking, telecommunications, healthcare, and transportation, where smart cards are used for applications including payment, identification, and access control.
Polycarbonate (PC) is expected to register the fastest growth during the forecast period owing to its exceptional properties, such as durability, high-impact resistance, and tamper-evident characteristics. These features make it suitable for high-security applications such as ID proofs and passports that require long-term use and reliability. Furthermore, PC enables the incorporation of advanced security elements such as holograms, microtext, and embedded chips, which are crucial for preventing fraud and ensuring data protection.
Type Insights
Contact cards led the market and accounted for the largest revenue share in 2025, owing to their widespread adoption in the banking and financial services industry. These cards are extensively used for credit and debit cards, providing secure and reliable payment solutions. The need for enhanced security features, such as EMV (Europay, MasterCard, and Visa) chips, has increased the demand for contact cards in this sector. With their reliability, enhanced security, compatibility with other systems, and cost-effectiveness, contact cards are popular among users. Furthermore, the location of readers and terminals for contact cards across financial institutions and POS systems has strengthened the market position of contact cards.
Multi-component cards are expected to emerge as the fastest-growing segment during the forecast period, owing to the increasing demand for secure and multifunctional solutions in the BFSI sector. These cards integrate multiple technologies, such as magnetic stripes, EMV chips, and contactless capabilities, offering enhanced security and transaction convenience. This makes them highly desirable for credit and debit cards, where robust security measures, including biometric features, are essential to prevent fraud and ensure secure payments.
End Use Insights
The telecommunication segment dominated the market with a XX% share in 2025. The increased adoption of SIM cards in mobile devices has fueled the market growth. The global scale of telecommunications and the necessity of SIM cards for mobile connectivity have contributed to the large volume of smart cards produced. The evolution of SIM technology, including the development of embedded SIMs (eSIMs) and reprogrammable SIMs, has continued to drive innovation in smart card materials.
The BFSI segment is projected to grow substantially during the forecast period owing to the increasing demand for secure payment solutions. With the rise of digital banking and e-commerce, there is a heightened need for smart cards that offer robust security features to protect against fraud and cyber threats. Smart cards equipped with EMV (Europay, MasterCard, and Visa) chips provide enhanced security for credit and debit transactions, making them indispensable in the BFSI sector. Furthermore, integrating contactless payment capabilities and multi-application functionality into banking cards has driven the need for sophisticated smart card materials.
Regional Insights
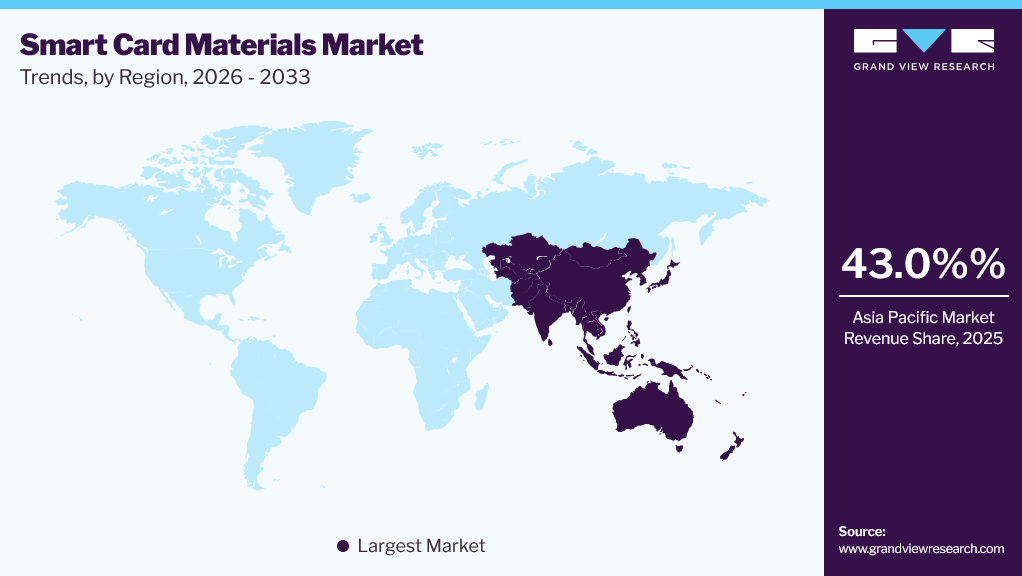
Asia Pacific dominated the global smart card materials market, accounting for the largest revenue share of approximately 43.0% in 2025 due to the rapid adoption of contactless payment systems. This trend has continued, with contactless smart cards becoming the norm for everyday transactions, including public transportation, retail, and healthcare services. In addition, technological advancements with growing digital infrastructure and increasing demand for better financial transactions have boosted the market demand. Furthermore, the region’s large population and rising disposable income have driven the demand for convenient payment solutions.
China dominated the Asia Pacific market and held the largest revenue share, over 45.0%, in 2025. The country’s rapid urbanization and strong economic growth have fueled the market demand. In addition, government agencies and private enterprises have increasingly implemented smart card-based systems to enhance security and streamline operations.
 To learn more about this report, Download Free Sample Report
North America Smart Card Materials Market Trends
The demand for smart card materials in North America is driven by the region's strong emphasis on secure payment infrastructure and cybersecurity. The increasing adoption of EMV payment cards, digital identity solutions, and advanced authentication technologies has fueled the need for high-performance smart card materials. In addition, the continued expansion of digital wallets, contactless payments, and mobile payment platforms is further supporting market growth across the region.
U.S. Smart Card Materials Market Trends
The smart card material market in the U.S. is expected to register strong growth over the forecast period, owing to the increasing preference for contactless payments and the need for advanced fraud prevention. The proliferation of smart cards in the telecommunications sector has also been a key driver. As the country continues to expand its mobile network infrastructure, the need for secure and reliable SIM cards has grown.
Europe Smart Card Materials Market Trends
The Europe smart card material market is expected to be driven by the growing demand for secure payment transactions and the increasing adoption of contactless payments. Europe has seen a surge in digital services and connectivity, particularly in the telecommunications sector, which is a major consumer of smart card materials. The BFSI industry's expansion and the rising popularity of debit/credit cards are also contributing to market growth. Furthermore, the region's focus on developing eco-friendly, sustainable materials is creating opportunities for smart card manufacturers to meet the demands of environmentally conscious consumers.
The growth of the smart card materials market in the UK is driven by the increasing adoption of smart cards for secure payment transactions and identification. In addition, the demand for contactless payments has surged, enhancing the need for efficient and set solutions. Furthermore, government initiatives to implement smart cards for various applications, such as e-passports and national IDs, are further propelling market growth. The focus on sustainability and eco-friendly materials is also positively influencing the market landscape.
Key Smart Card Materials Company Insights
The global smart card materials market features key players such as Thales, IDEMIA, and Infineon Technologies AG. To maintain their dominant footprint, these organizations have primarily focused on R&D activities, strategic partnerships, and mergers & acquisitions.
- Giesecke+Devrient GmbH offers secure solutions for the smart card industry. The company is known for its expertise in digital security and advanced materials. It produces high-quality smart card materials, including secure chips, card bodies, and personalization services. The company's portfolio encompasses financial, government, and mobile application products, such as EMV cards, contactless payment cards, and ID cards.
- IDEMIA is a global identity and security solutions provider focused on smart card technologies. It offers a comprehensive range of products and services related to smart card materials, including secure chip solutions, card bodies, and personalization services. Their portfolio serves sectors such as banking, telecommunications, and government, featuring EMV payment cards, biometric identification cards, and contactless smart cards.
Key Smart Card Materials Companies
The following key companies have been profiled for this study on the smart card materials market:
-
Thales
-
Giesecke+Devrient GmbH
-
IDEMIA
-
Infineon Technologies AG
-
NXP Semiconductors
-
Samsung Electronics Co., Ltd.
-
Texas Instruments Incorporated
-
CPI Card Group Inc.
-
HID Global Corporation
-
Watchdata Technologies Ltd.
-
CardLogix Corporation
-
Eastcompeace Technology Co., Ltd.
-
Wuhan Tianyu Information Industry Co., Ltd.
Recent Developments
-
In June 2026, IDEMIA Secure Transactions introduced the industry's first black contact plate for payment cards, enabling premium card designs while maintaining compatibility with existing smart card manufacturing processes. The innovation highlights the growing demand for advanced materials and differentiated components in next-generation smart payment cards.
-
In May 2026, IDEMIA Secure Transactions launched a new Metal Card Innovation and Design Lab to accelerate the development of premium metal payment cards. The facility is dedicated to advancing new materials, finishes, and manufacturing technologies that improve the durability, aesthetics, and performance of smart payment cards.
-
In July 2025, Thales highlighted the growing adoption of its Gemalto PVC-Free Card, manufactured using 100% recycled PETG instead of conventional PVC. The solution enables financial institutions to reduce the environmental footprint of payment cards while maintaining the durability, security, and performance required for smart card applications, reflecting the industry's increasing shift toward sustainable materials in next-generation smart card manufacturing.
Smart Card Materials Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.8 billion
Estimated market size in 2026
USD 1.9 billion
Projected market size by 2033
USD 2.8 billion
Growth rate
CAGR of 5.2% from 2026 to 2033
Base year for estimation
2025
Actual data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Volume in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Material, type, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Russia; Denmark; Sweden; Norway; China; Japan; India; South Korea; Australia; Indonesia; Vietnam; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait
Key companies profiled
Thales; Giesecke+Devrient GmbH; IDEMIA; Infineon Technologies AG; NXP Semiconductors; Samsung Electronics Co., Ltd.; Texas Instruments Incorporated; CPI Card Group Inc.; HID Global Corporation; Watchdata Technologies Ltd.; CardLogix Corporation; Eastcompeace Technology Co., Ltd.; Wuhan Tianyu Information Industry Co., Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Smart Card Materials Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global smart card materials market report on the basis of material, type, end-use, and region:
-
Material Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Polyvinyl Chloride (PVC)
-
Polycarbonate (PC)
-
Acrylonitrile Butadiene Styrene (ABS)
-
Polyethylene Terephthalate-Glycol (PETG)
-
Others
-
-
Type Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Contact Cards
-
Contactless Cards
-
Multi-Component Cards
-
-
End Use Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
BFSI
-
Government
-
Telecommunication
-
Retail
-
Healthcare
-
Hospitality
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Spain
-
Italy
-
Russia
-
Sweden
-
Denmark
-
Norway
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
Indonesia
-
Vietnam
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
UAE
-
South Africa
-
Saudi Arabia
-
Kuwait
-
-
Frequently Asked Questions About This Report
Some key players operating in the smart card materials market include Eastman Chemical Company, SK Chemicals, PetroChina Company Limited, Solvay S.A., Axiall Corporation, KEM One, SABIC Innovative Plastics, 3A Composites GmbH, Teijin Ltd., LG Chemicals, Formosa Plastics Group, and BASF SE.
The global smart card materials market size was valued at USD 1.8 billion in 2025 and is estimated at USD 1.9 billion for 2026.
Polyvinyl Chloride (PVC) dominated the market, accounting for over 45.0% of revenue in 2025.
The global smart card materials market is expected to grow at a CAGR of 5.2% from 2026 to 2033, reaching USD 2.8 billion by 2033.
Asia Pacific dominated with a 43.0% revenue share in 2025.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


