
- Home
- »
- Sensors & Controls
- »
-
Soil Moisture Sensor Market Size, Share Report, 2026-2033GVR Report cover

Soil Moisture Sensor Market (2026 - 2033)
Size, Share & Trends Analysis Report By Sensor Type (Capacitance Sensors, Probes), By Connectivity (Wired, Wireless), By Application (Agriculture, Construction & Mining), By Region, And Segment Forecasts
Market Size, 2025
$473.7MMarket Estimate, 2026
$543.3MMarket Forecast, 2033
$1,419.1MCAGR, 2026–2033
14.7%Soil Moisture Sensor Market Summary
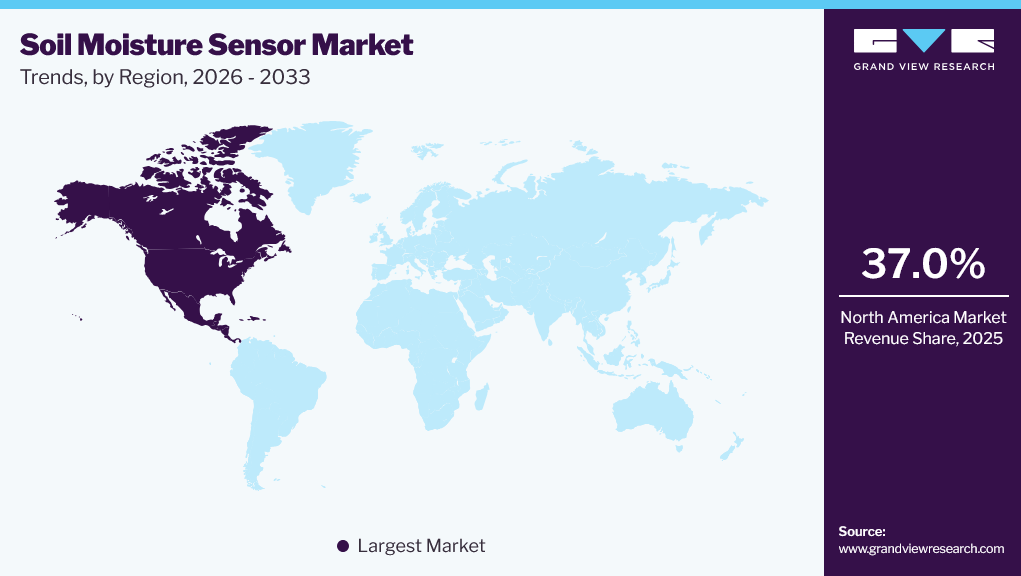
The global soil moisture sensor market size was valued at USD 473.7 million in 2025 and is projected to grow from USD 543.3 million in 2026 to USD 1,419.1 million by 2033, at a CAGR of 14.7% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 37.0%% in 2025. The increasing adoption of these sensors in the agricultural sector to enhance farm productivity and reduce water consumption is expected to drive market growth over the forecast period.
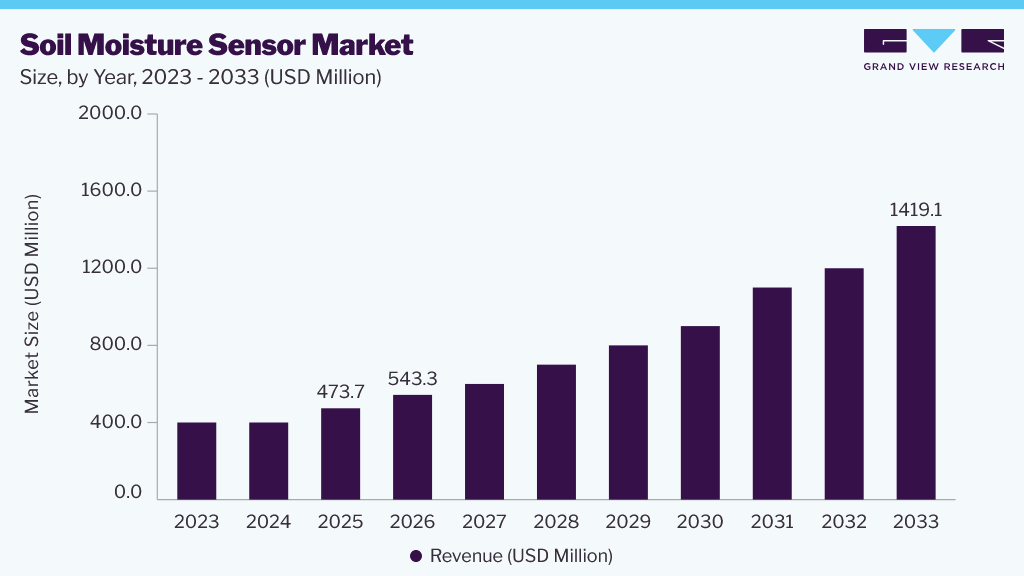 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By sensor type: The tensiometers segment held the largest market share of around 28.0 % in 2025.
- By connectivity: The wired soil moisture sensors segment held the largest market share of around 54.0 % in 2025.
- By application: The agriculture segment held the largest market share of around 48.0% in 2025.
Regional Highlights
- Largest regional market: North America (37.0 % revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 473.7 Million
- Estimated market size in 2026: USD 543.3 Million
- Projected market size by 2033: USD 1,419.1 Million
- CAGR (2026-2033): 14.7%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Moreover, this product helps prevent irrigation issues through constant monitoring, which, in turn, is spurring market growth. The introduction of new technologies that help residential owners monitor soil moisture in potted plants, vegetable gardens, and lawns is also expected to drive market demand.
The demand for low-cost sensors, such as tensiometers and granular matrix sensors, especially in the residential sector for lawn maintenance, is driving market growth. These products play a crucial role in maintaining lush green lawns, which, in turn, is driving their adoption in the residential segment. The use of soil moisture sensors by weather forecasters to offer accurate weather readings and forecasts is another prominent factor driving market demand. The segment is estimated to register considerable growth during the forecast period. For instance, in March 2025, the U.S. Environmental Protection Agency (EPA) states that Soil Moisture-Based Irrigation Controllers help homeowners and businesses reduce outdoor water waste by detecting soil moisture levels and scheduling irrigation when plants do not need water, helping keep landscapes healthy.
The increasing demand for soil moisture sensors in the building and construction sectors is also estimated to drive market growth in the coming years. This product is widely preferred before initiating a wetland detection project. The imminent need to measure water content at construction sites is driving market growth. On the flip side, the lack of awareness among farmers about the benefits of sensors, the limited availability of skilled labor, and a preference for traditional farming practices, especially in emerging economies, are hampering the market's overall growth.
North America held the largest market share in 2025, owing to greater adoption of mechanized farming practices and numerous research & development efforts in wireless sensor technology. In addition, farmers in the region are more aware of the benefits of using moisture sensors. In addition, farmers have been receiving sample support to adopt mechanized farming practices from organizations such as the U.S. Department of Agriculture (USDA) Natural Resources Conservation Service (NRCS), and The Nature Conservancy (TNC) continue to support precision irrigation and soil moisture monitoring initiatives that encourage the adoption of advanced irrigation technologies.
Analyst Perspective
The soil moisture sensor industry is moving beyond conventional irrigation monitoring toward integrated precision agriculture solutions. Increasing pressure on water resources, changing weather patterns, and the need to improve farm productivity are encouraging growers to adopt data-driven irrigation practices. Demand is also benefiting from the growing use of connected farming technologies, where soil moisture data is integrated with IoT platforms, weather information, and automated irrigation systems to support timely field decisions. While agriculture remains the primary application, adoption is gradually expanding into landscaping, turf management, research, and smart greenhouse operations. Continuous improvements in sensor accuracy, wireless connectivity, battery life, and affordability are making these solutions more practical for farms of different sizes. As governments and agricultural organizations continue to promote efficient water management and precision agriculture, advancements in sensor technology are expected to support broader commercial adoption across agriculture and non-agricultural applications.
Application Insights
The agriculture segment led the market with the largest revenue share of around 48.0% in 2025. Soil moisture sensors find applications across an array of industries and verticals, including agriculture, construction and mining, residential, forestry, landscaping and ground care, research studies, sports, and weather forecasting. Soil moisture sensors are integral to precision agriculture practices, enabling farmers to make data-driven decisions regarding irrigation scheduling and water conservation. With growing awareness of the importance of water efficiency in agriculture, demand for soil moisture sensors continues to rise in this segment.
Increasing the use of sensors in agricultural lands has enabled farmers to reduce water consumption and increase overall food production. These benefits are expected to drive demand in the segment. Furthermore, government initiatives promoting precision irrigation, water-use efficiency, and sustainable agriculture are accelerating the adoption of soil moisture monitoring technologies across agricultural operations. For instance, in March 2025, the state of Missouri partnered with the U.S. Department of Agriculture (USDA), the University of Missouri, the Missouri Mesonet, and the National Integrated Drought Information System (NIDIS) to expand soil moisture monitoring across the state. The initiative aims to strengthen irrigation management, improve water conservation, and provide farmers with better data to support agricultural decision-making.
The sports segment is expected to grow at the fastest CAGR during the forecast period, owing to the increasing use of soil moisture sensors for professional turf management and irrigation optimization. Sports fields, golf courses, and recreational facilities rely on these sensors to maintain optimal soil moisture, improve turf quality, and provide consistent playing conditions while preventing excessive or insufficient irrigation.
The integration of sensor data with automated irrigation systems and weather information further enhances water-use efficiency and reduces maintenance costs. Growing emphasis on sustainable landscape management, coupled with advancements in wireless and IoT-enabled sensor technologies, is expected to support further the adoption of soil moisture sensors across sports facilities.
Sensor Type Insights
The tensiometers segment led the market with the largest revenue share of around 28.0% in 2025, driven by their reliability and accuracy in measuring soil water potential for effective irrigation management. They are widely used in agriculture because they provide real-time soil moisture data, enabling farmers to optimize irrigation practices, conserve water, and improve crop yields. Tensiometers are also relatively affordable, easy to install, and suitable for a wide range of soil types and climatic conditions, making them accessible to both large commercial farms and small-scale growers. Their proven performance, cost-effectiveness, and long-standing market presence continue to support their widespread adoption.
The capacitance sensors segment is expected to grow at the fastest CAGR during the forecast period, due to their advanced technology and versatility. These sensors offer high accuracy and rapid response times, which are crucial for real-time soil moisture monitoring and efficient water management. Their ability to provide continuous, automated measurements without significant maintenance has made them increasingly popular among modern agricultural practices and precision farming. In addition, integrating IoT and wireless connectivity into capacitance sensors enables seamless data collection and remote monitoring, appealing to tech-savvy farmers and large agribusinesses. The growing emphasis on sustainable agriculture and water conservation has also driven the adoption of these sensors, as they help optimize irrigation and reduce water waste. Thus, technological advancements, ease of integration, and alignment with modern agricultural needs have contributed to the rapid growth of capacitance sensors in the target market. For instance, inMay 2025, Phoenix Contact introduced the PMD EM wireless soil moisture sensor for demand-oriented irrigation. The sensor delivers volumetric soil moisture data, supports LoRaWAN connectivity for remote monitoring, is maintenance-free, and can be adapted to different soil types, helping users improve irrigation efficiency and water management.
Connectivity Insights
The wired soil moisture sensors segment led the market with the largest revenue share of around 54.0% in 2025. Wired soil moisture sensors continue to be widely adopted due to their high reliability, measurement accuracy, and stable data transmission. Their long operational life, minimal maintenance requirements, and compatibility with existing irrigation infrastructure make them a preferred choice across agricultural applications. In addition, their cost-effectiveness and straightforward installation process make them suitable for both commercial farming operations and smaller agricultural users, supporting continued market dominance.
The wireless soil moisture sensors segment is anticipated to grow at the fastest CAGR during the forecast period, primarily due to their convenience and flexibility. Wireless sensors offer easy deployment, allowing users to place them in various locations without the constraints of wiring infrastructure. This flexibility enables more comprehensive monitoring of soil moisture levels across large or difficult-to-access areas, optimizing irrigation strategies. Furthermore, advances in wireless technology have enhanced data transmission rates and reliability, ensuring real-time monitoring and timely decision-making. The scalability of wireless systems also appeals to users looking to expand their monitoring networks without significant additional infrastructure costs. In addition, the growing adoption of IoT and cloud-based solutions has boosted demand for wireless sensors, enabling remote access to data and insights from anywhere, at any time. Moreover, the growing focus on precision agriculture and sustainable farming practices has driven the uptake of wireless soil moisture sensors, as they enable more efficient water usage and resource management.
Regional Insights
North America dominated the global soil moisture sensor market with the largest revenue share of approximately 37.0% in 2025. The region's growth is driven by widespread adoption of precision agriculture, increasing concerns over water scarcity, and the need to improve irrigation efficiency. Continuous investments in agricultural technology, sensor innovation, and smart irrigation systems have strengthened the adoption of soil moisture monitoring solutions across the region. In addition, supportive government initiatives promoting sustainable farming and efficient water management continue to encourage the deployment of advanced soil moisture sensors. For instance, in February 2025, GroundWorx partnered with Ewing Outdoor Supply to expand the availability of its autonomous soil-monitoring sensors across the United States. The partnership brings real-time soil moisture, temperature, and salinity monitoring technology to customers nationwide, helping improve irrigation management, resource efficiency, and sustainable landscape and agricultural practices.
 To learn more about this report, Download Free Sample Report
U.S. Soil Moisture Sensor Market Trends
The soil moisture sensor market in the U.S. accounted for the largest market revenue share in North America in 2025, driven by the nation's highly developed agricultural sector, which strongly emphasizes technology adoption, including precision farming practices. The country also faces diverse climatic conditions and water management challenges across its regions, driving the demand for advanced soil moisture monitoring solutions. Furthermore, the presence of major sensor manufacturers, research institutions, and government support for agricultural innovation further boosts the market growth in the U.S.
Asia Pacific Soil Moisture Sensor Market Trends
The soil moisture sensor market in the Asia Pacificis expected to grow at the fastest CAGR during the forecast period. The governments in the region are promoting sustainable agricultural practices, prompting farmers to invest in advanced water-management technologies, such as irrigation modernization and precision farming initiatives, including soil moisture monitoring systems. In 2025, the Government of India approved the scheme under the Pradhan Mantri Krishi Sinchayee Yojana (PMKSY), Modernization of Command Area Development and Water Management (M-CADWM). The initiative promotes the use of Internet of Things (IoT) technology for water accounting and water management, helping improve water-use efficiency and encouraging the adoption of modern irrigation technologies across the agricultural sector.
The China soil moisture sensor market held the significant market share in the Asia Pacific in 2025. China's extensive agricultural sector, coupled with government initiatives promoting precision agriculture and water efficiency, drives significant demand for soil moisture sensors. In addition, China's robust manufacturing capabilities and numerous sensor technology companies further bolster its market leadership. Furthermore, the country's growing focus on environmental sustainability and resource management is driving demand for soil moisture sensors.
Europe Soil Moisture Sensor Market Trends
The soil moisture sensor market in Europe occupies the second-largest share of the market due to several contributing factors. The region's extensive agricultural sector, characterized by diverse climates and soil types, requires precise water management solutions, thereby driving demand for soil moisture sensors. In addition, stringent environmental regulations and sustainability initiatives across European countries encourage the adoption of technologies that enable efficient resource use, such as soil moisture sensors. Moreover, Europe's emphasis on research and innovation fosters the development of advanced sensor technologies, further propelling market growth. Furthermore, increasing awareness among farmers about the benefits of precision agriculture and the role of soil moisture sensors in optimizing crop yields also contributes to Europe's significant market share.
The UK soil moisture sensor market is growing due to the country's advanced agricultural sector and increasing focus on sustainable farming and efficient water management. Government initiatives, including the UK's Countryside Stewardship scheme, encourage farmers to adopt technologies that improve irrigation efficiency and conserve water resources. In addition, the country's strong emphasis on environmental sustainability, compliance with water conservation regulations, and ongoing investments in precision agriculture continue to support the adoption of soil moisture sensors across agricultural and landscaping applications.
Key Soil Moisture Sensor Company Insights
Leading companies operating in the soil moisture sensor industry are focusing on product innovation, IoT-enabled monitoring solutions, wireless sensing technologies, strategic partnerships, and portfolio expansion to strengthen their market position. Companies are also investing in precision agriculture solutions and smart irrigation technologies to improve water-use efficiency and meet the growing demand for sustainable farming practices.
Key Soil Moisture Sensor Companies
The following key companies have been profiled for this study on the global soil moisture sensor market:
-
The Toro Company
-
METER Group, Inc. USA
-
Campbell Scientific, Inc.
-
Stevens Water Monitoring Systems Inc.
-
IMKO Micromodultechnik GmbH
-
Irrometer Company, Inc.
-
Delta-T Devices Ltd
-
GroPoint
-
Sentek
-
Spectrum Technologies, Inc.
-
Acclima, Inc.
-
Smartrek Technologies Inc.
-
Caipos GmbH
-
Spiio
-
Plaid Systems LLC
Recent Developments
-
In March 2026, THIRDREALITY launched the Smart Soil Moisture Sensor Gen2, featuring enhanced consistency, durability, and connection stability to support reliable soil moisture monitoring for smart gardening applications.
-
In April 2026, LI-COR launched the LI-300 and LI-350 Soil Moisture Sensors, expanding its environmental research instrumentation portfolio with easy-to-deploy sensors designed to deliver clear, consistent soil-water insights for research and commercial applications.
-
In February 2025, the U.S. Golf Association (USGA) launched the USGA Moisture Meter, providing golf course superintendents with precise soil moisture, salinity, and temperature data that automatically uploads to the DEACON platform for improved water management.
Soil Moisture Sensor Market Report Scope
Report Attribute
Details
Market size in 2025
USD 473.7 million
Estimated market size in 2026
USD 543.3 million
Projected market size by 2033
USD 1,419.1 million
Growth rate
CAGR of 14.7% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Sensor type, connectivity, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; China; Japan; India; South Korea; Australia; Brazil; KSA; UAE; South Africa
Key companies profiled
The Toro Company; METER Group, Inc. USA; Campbell Scientific, Inc.; Stevens Water Monitoring Systems Inc.; IMKO Micromodultechnik GmbH; Irrometer Company, Inc.; Delta-T Devices Ltd.; GroPoint; Sentek; Spectrum Technologies, Inc.; Acclima, Inc.; Smartrek Technologies Inc.; Caipos GmbH; Spiio; Plaid Systems LLC.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Soil Moisture Sensor Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global soil moisture sensor market report based on sensor type, connectivity, application, and region.
-
Sensor Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Capacitance sensors
-
Probes
-
Time Domain Transmissometry (TDT) Sensors
-
Gypsum blocks
-
Tensiometers
-
Granular matrix sensors
-
-
Connectivity Outlook (Revenue, USD Million, 2021 - 2033)
-
Wired
-
Wireless
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Agriculture
-
Construction and Mining
-
Residential
-
Forestry
-
Landscaping and Ground Care
-
Research Studies
-
Sports
-
Weather Forecasting
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East and Africa (MEA)
-
KSA
-
UAE
-
South Africa
-
-
Frequently Asked Questions About This Report
The agriculture soil moisture sensor segment accounted for the largest revenue share of around 48.0% in 2025.
North America dominated with a 37.0% revenue share in 2025.
Some key players operating in the soil moisture sensor market include The Toro Company; METER Group, Inc. USA; Campbell Scientific, Inc.; Stevens Water Monitoring Systems Inc.; IMKO Micromodultechnik GmbH; Irrometer Company; Inc.; Delta-T Devices Ltd.; GroPoint; Sentek; Spectrum Technologies, Inc.; Acclima, Inc.; Smartrek Technologies Inc.; Caipos GmbH; Spiio; Plaid Systems LLC., and others.
The global soil moisture sensor market size was valued at USD 473.7 million in 2025 and is estimated at USD 543.3 million for 2026.
The global soil moisture sensor market is expected to grow at a CAGR of 14.7% from 2026 to 2033, reaching USD 1,419.1 million by 2033.
About the Author(s)
Sensors & Controls Research Team
Semiconductors & Electronics · Sensors & ControlsThis report was authored by the sensors & controls research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the sensors & controls segment of the semiconductors & electronics industry. All findings are based on proprietary semiconductors & electronics databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


