
- Home
- »
- Consumer F&B
- »
-
Sports Supplements Market Size & Share Report, 2026-2033GVR Report cover

Sports Supplements Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Capsules/Tablets, Powder, Liquid, Bars), By Source (Animal-based, Plant-based), By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2025
$97.4BMarket Estimate, 2026
$105.3BMarket Forecast, 2033
$189.4BCAGR, 2026–2033
8.7%Sports Supplements Market Summary
The global sports supplements market size was valued at USD 97.4 billion in 2025 and is projected to grow from USD 105.3 billion in 2026 to USD 189.4 billion by 2033, at a CAGR of 8.7% from 2026 to 2033. North America dominated the sports supplements market, accounting for the largest revenue share of 54.1% in 2025. The market has experienced significant growth over the past decade, driven by the rising adoption of fitness regimes and increasing awareness of the importance of nutrition in maintaining an active lifestyle.
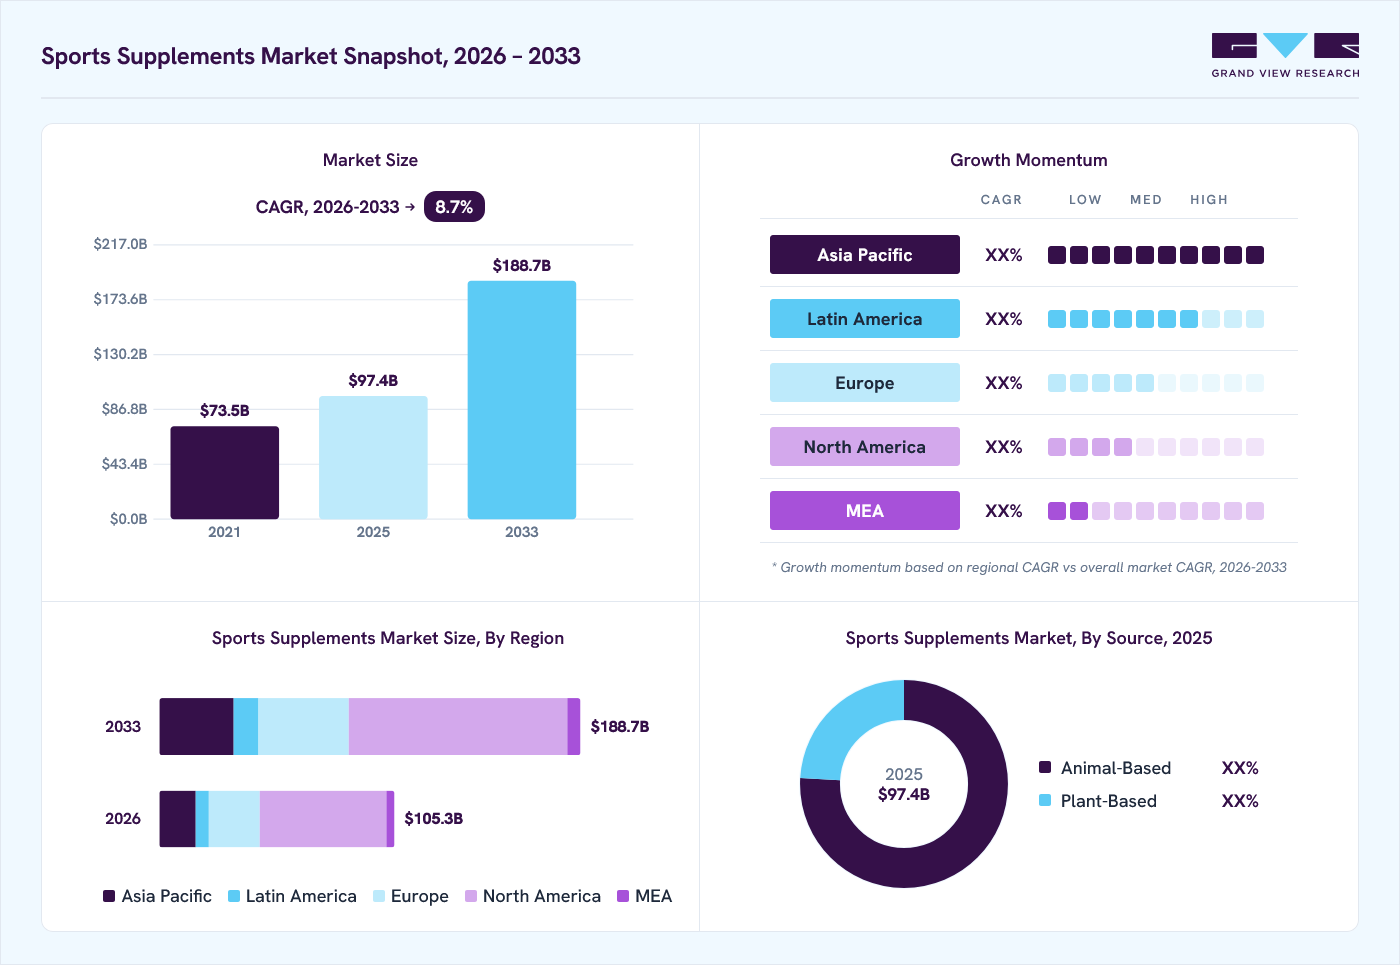 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Liquid segment held the largest market share of 56.7% in 2025.
- By source: Animal-based segment held the largest market share of 75.8% in 2025.
- By distribution channel: Supermarkets and hypermarkets segment held the largest market share of 33.9% in 2025.
Regional Highlights
- Largest regional market: North America (54.1% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 97.4 Billion
- Estimated market size in 2026: USD 105.3 Billion
- Projected market size by 2033: USD 189.4 Billion
- CAGR (2026-2033): 8.7%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The market encompasses a broad range of products, including protein powders, energy bars, dietary supplements, and ready-to-drink (RTD) beverages, designed to enhance athletic performance, support recovery, and improve overall health, driving the overall market during the forecast period.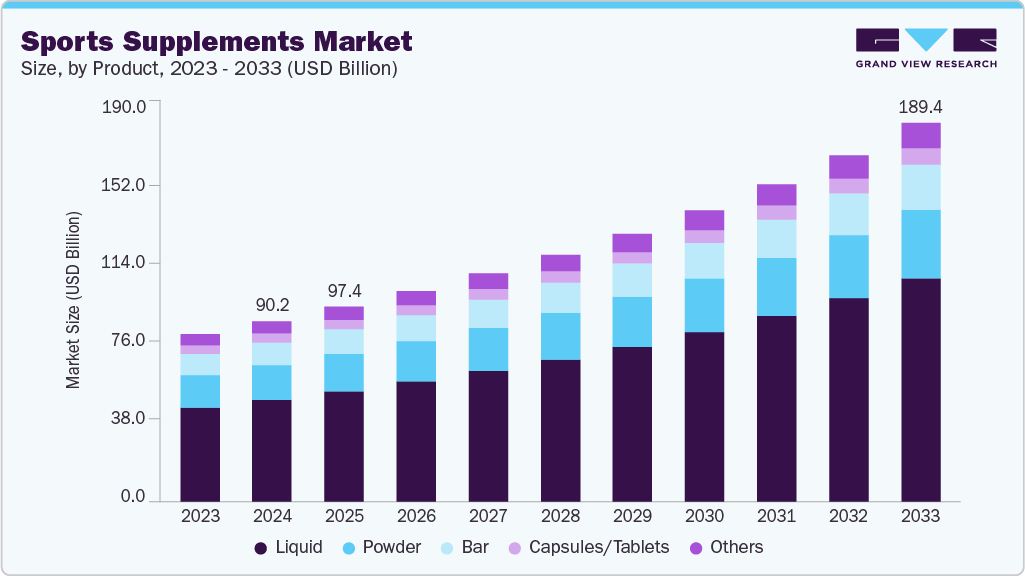 To learn more about this report, Download Free Sample Report
Rising health and fitness awareness is expanding the sports supplement consumer base, particularly among Millennials and Gen Z, as more consumers adopt active lifestyles, join gyms, and participate in sports and recreational fitness activities. Social media and fitness influencers are further increasing product awareness and encouraging consumers to incorporate supplements into their wellness routines.
Growing focus on performance optimization and recovery is driving demand for targeted products such as protein supplements, pre-workouts, hydration products, energy bars, and recovery formulations. Consumers increasingly seek products designed around specific fitness objectives, creating opportunities for specialized and multifunctional sports nutrition solutions.
Product innovation and technological advancements are further supporting market development through plant-based proteins, improved formulations, and convenient delivery formats. At the same time, the expansion of e-commerce and digital retail platforms is improving product accessibility, enabling consumers to compare ingredients, reviews, prices, and product benefits before purchasing.
Market Dynamics
The sports supplements market is experiencing steady growth due to increasing consumer focus on fitness, athletic performance, muscle recovery, and overall health management. Sports supplements, including protein powders, amino acids, creatine, pre-workout formulations, energy boosters, and recovery products, are widely used by professional athletes, fitness enthusiasts, and recreational consumers. Growing participation in sports activities, rising gym memberships, and increasing awareness regarding nutrition and performance enhancement are supporting market expansion. Furthermore, the growing influence of social media fitness trends and the adoption of active lifestyles are expected to continue driving demand for sports supplements globally.
The increasing adoption of resistance training, bodybuilding, and high-intensity fitness programs is significantly boosting demand for sports supplements. Consumers are prioritizing higher protein intake to support muscle synthesis, recovery, and performance optimization, leading to strong demand for whey protein, creatine, branched-chain amino acids (BCAAs), and recovery formulations. Additionally, the expansion of sports nutrition beyond professional athletes to recreational exercisers, women, and aging populations seeking muscle preservation is broadening the consumer base. The growing popularity of sports nutrition products in emerging economies, supported by expanding gym infrastructure and sports participation rates, continues to strengthen market growth.
The sports supplements market faces challenges from the widespread availability of counterfeit, mislabeled, and low-quality products across online and unregulated distribution channels. Variations in ingredient purity, inaccurate protein content claims, and contamination with prohibited substances have raised concerns among consumers and sporting organizations. Furthermore, inconsistent regulatory frameworks across countries create difficulties in maintaining uniform quality standards, while product recalls and negative publicity surrounding adulterated supplements can adversely impact consumer trust and purchasing decisions.
Growing demand for sustainable and specialized nutrition is creating significant opportunities within the sports supplements market. Manufacturers are increasingly developing plant-based protein formulations derived from pea, soy, rice, and other alternative sources to cater to vegan, vegetarian, and lactose-intolerant consumers. At the same time, demand is rising for multifunctional products that combine performance benefits with immune support, gut health, hydration, cognitive performance, and recovery enhancement. Innovations in personalized nutrition, clean-label formulations, and scientifically backed functional ingredients are expected to create new revenue streams and support long-term market expansion.
Analyst Perspective
The sports supplements market is evolving from a performance-focused industry into a broader nutrition category driven by changing consumer behavior and increasing demand for targeted health outcomes. Future market leadership is expected to shift toward companies that combine clinically supported ingredients, personalized nutrition solutions, and transparent product formulations rather than competing solely on brand recognition or product variety. As consumers become more selective regarding efficacy, ingredient sourcing, and product credibility, manufacturers capable of demonstrating measurable benefits while maintaining strong distribution reach and innovation pipelines will be best positioned to capture premium-value segments and sustain long-term growth.
Consumer Insights
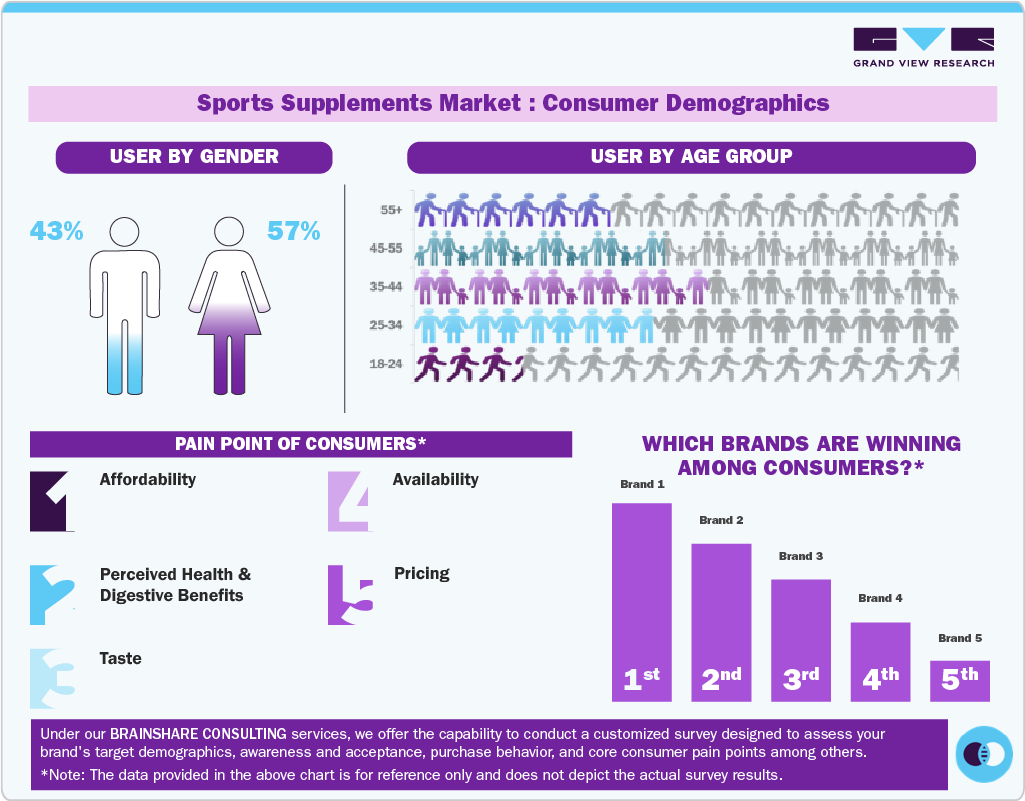
Consumers increasingly perceive sports supplements as everyday performance and wellness products, rather than offerings limited to professional athletes. They seek products that support energy, muscle recovery, hydration, and overall fitness, creating opportunities for multifunctional formulations. For instance, in April 2025, GNC India launched Creatine + Electrolytes, combining creatine with an electrolyte complex to address performance, hydration, and recovery needs among active consumers.
Consumers are also showing greater interest in plant-based and clean-label sports nutrition, particularly products that align with vegan lifestyles and ingredient-conscious purchasing. Convenience is another important consumer consideration, with users increasingly favoring portable, ready-to-consume formats that fit active, busy lifestyles. For instance, in March 2025, Per4m launched Hydrate Shots, a 100-ml, zero-sugar electrolyte product designed for convenient hydration before, during, or after physical activity.
 To learn more about this report, Download Free Sample Report
Product Insights
Based on product, the liquid segment led the market with the largest revenue share of 56.7% in 2025 and is expected to grow at the fastest CAGR over the forecast period. The market is seeing greater interest in capsule and tablet formats that combine convenience, plant-based materials, and targeted ingredient delivery. Manufacturers are responding with HPMC and pullulan capsules, liquid-filled formats, and designed-release technologies that can improve ingredient protection and formulation flexibility. For instance, in May 2025, Parkacre launched Vangard Performance, a sports nutrition range that included creatine monohydrate capsules and pre-workout capsules, demonstrating the growing use of capsule formats for performance-focused supplementatio
The bars segment is projected to grow at a significant CAGR of 8.2% from 2026 to 2033. Growing demand for convenient, multifunctional sports nutrition is encouraging brands to integrate multiple performance ingredients into ready-to-eat bar formats. For instance, in October 2025, JiMMYBAR launched its Creatine Protein Bar, combining 20 g of protein and 5 g of creatine in a ready-to-eat format, offering consumers a portable alternative to conventional protein powders and creatine supplements.
Source Insights
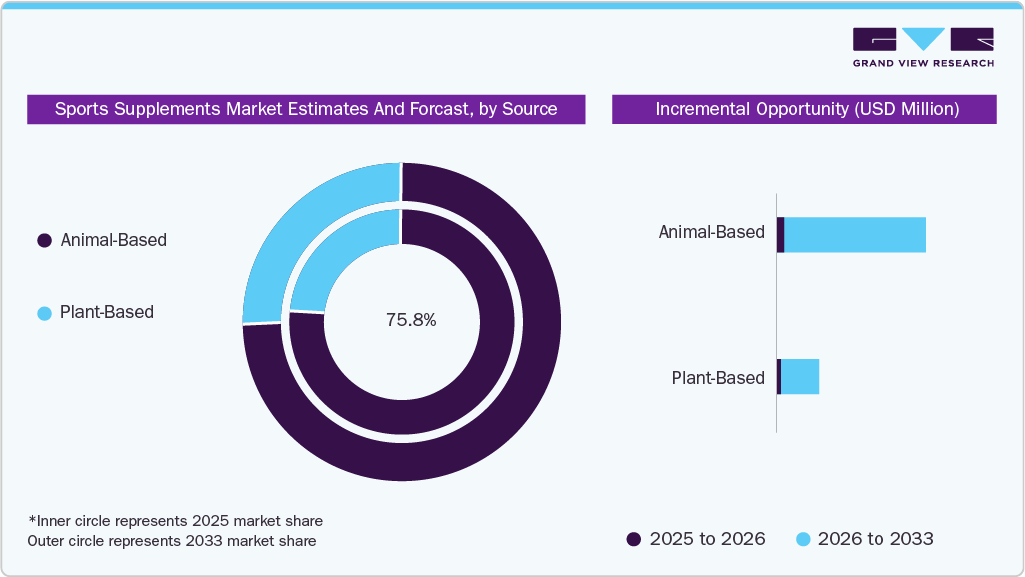
Based on the source, the animal-based segment led the market with the largest revenue share of 75.8% in 2025. Animal-based proteins, particularly whey, remain important in sports nutrition because consumers associate them with high protein quality, rapid absorption, muscle development, and post-workout recovery. This supports continued demand for whey-based powders and other dairy-derived protein supplements among performance-focused consumers.
 To learn more about this report, Download Free Sample Report
The plant-based segment is projected to grow at the fastest CAGR of 10.1% from 2026 to 2033. Plant-based proteins are gaining traction in sports nutrition as consumers increasingly seek vegan, dairy-free, and sustainable alternatives that still deliver meaningful protein and performance benefits. Product innovation is moving beyond basic plant protein toward multifunctional formulations that combine protein with performance-enhancing ingredients and convenient formats.
Distribution Channel Insights
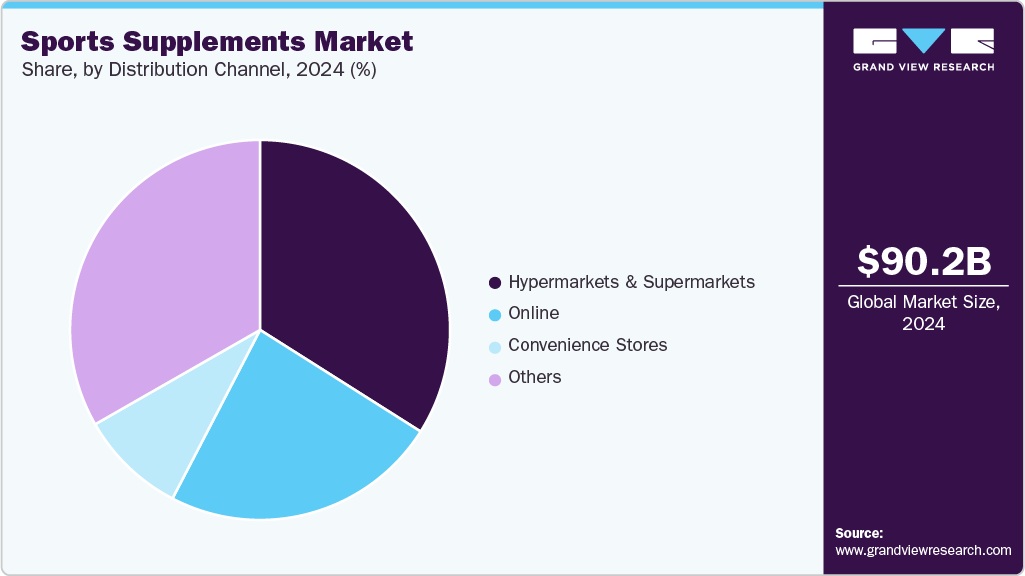
The supermarkets and hypermarkets segment led the market with the largest revenue share of 33.9% in 2025. Supermarkets and hypermarkets have become major players in the distribution of dietary supplements, highlighting their significant role in making sports nutrition and wellness products widely accessible to the general public. Their extensive reach, ample shelf space, and ability to stock a wide range of brands allow consumers to find both mainstream and niche supplements in one location, enhancing visibility and boosting impulse purchases.
In addition to accessibility, consumer behavior strongly favors the convenience of purchasing supplements alongside everyday groceries. Shoppers appreciate the convenience of picking up their protein powders, vitamins, or pre-workout drinks during regular grocery shopping, rather than visiting specialized stores. This one-stop shopping experience saves time and encourages consumers to try new products, as the diverse assortment in hypermarkets and supermarkets allows them to explore different brands and formulations in a familiar environment.
The online segment is projected to grow at the fastest CAGR of 10.2% from 2026 to 2033. Consumers today are increasingly turning to other stores for sports supplements due to the convenience they offer. Shopping from home eliminates the need to visit physical stores, allowing buyers to browse a wide range of products at any time, fitting easily into their busy lifestyles. Another reason is the access to a wider variety of products and detailed information.
Other platforms often stock both mainstream and niche brands that may not be available locally, while providing comprehensive product descriptions, nutritional facts, and customer reviews. This helps consumers make informed choices and select supplements that meet their fitness goals. Price and personalization also play a key role. E-commerce sites make it easy to compare prices, find discounts, and even subscribe to regular deliveries, offering convenience and value. In addition, personalized recommendations based on previous purchases or fitness preferences enhance the shopping experience, making other stores a preferred option for many fitness enthusiasts.
Regional Insights
North America dominated the sports supplements market with the largest revenue share of 54.1% in 2025. In North America, growing health and wellness awareness is driving the consumption of sports supplements. Consumers are increasingly focused on preventive health and functional nutrition, seeking ways to support overall well-being beyond regular meals. Supplements are viewed as a convenient solution to fill nutrient gaps, enhance immune function, and maintain energy levels, helping individuals stay active and healthy in their daily lives.
 To learn more about this report, Download Free Sample Report
U.S. Sports Supplements Market Trends
The sports supplements market in the U.S. held the largest share in the North America region in 2025. The U.S. market is supported by increasing focus on performance nutrition and demand for convenient, multifunctional products. Consumers are increasingly shifting toward portable formats that integrate supplementation into daily fitness routines. For instance, in April 2025, Thorne launched its Sports Performance line with Daily Electrolytes, its first on-the-go electrolyte product, offering NSF Certified for Sport supplementation for athletes across preparation, performance, and recovery.
Europe Sports Supplements Market Trends
The sports supplements market in the U.K. held the largest share in the Europe region in 2025. In Europe, growing participation in gyms, recreational sports, and endurance activities is expanding demand for sports supplements among younger and increasingly mainstream consumers. Products are increasingly viewed as convenient tools for performance, recovery, energy, and daily protein intake, rather than being limited to professional athletes. For instance, in July 2025, Team Picnic PostNL and DSM-Firmenich launched the up4 Sports Nutrition range to the public in the Netherlands, offering products developed and used by professional cycling athletes for training and competition. This highlights the region’s shift toward performance-oriented and convenient sports nutrition.
The UK sports supplement market is increasingly shaped by mainstream protein consumption, product premiumization, and the integration of sports nutrition into everyday diets. Consumers are showing greater interest in products that offer clear nutritional value while fitting easily into daily routines, creating demand for protein powders, bars, shakes, and specialized performance products across both specialist and mainstream retail channels. For instance, in October 2025, Glanbia introduced Isopure in the UK through retailers including Holland & Barrett, Boots, Sainsbury’s, Amazon, and Ocado, expanding access to whey-isolate-based sports nutrition beyond traditional specialist channels.
Asia Pacific Sports Supplements Market Trends
The sports supplements market in the Asia Pacific is projected to grow at the fastest CAGR of 10.7% from 2026 to 2033. The Asia Pacific market is entering a broader consumer adoption phase, supported by expanding fitness communities and increasing emphasis on protein intake and active living. Demand is shifting toward easy-to-consume, performance-oriented products such as protein beverages, powders, bars, and recovery formulations, particularly among urban consumers seeking nutrition solutions that complement work, exercise, and busy daily schedules.
Central & South America Sports Supplements Market Trends
The sports supplements market in Central & South America is projected to grow at a substantial CAGR of 9.5% from 2026 to 2033. The market is supported by rising health awareness, urbanization, and expanding digital commerce, increasing demand for protein powders, pre-workouts, energy products, and convenient sports nutrition formats.
Middle East & Africa Sports Supplements Market Trends
The sports supplements market in the Middle East & Africa is supported by encouraging demand for protein powders, sports drinks, energy bars, and weight-management supplements. The region's growing focus on fitness and preventive health is further expanding the consumer base beyond professional athletes.
Key Sports Supplements Company Insights
The sports supplement industry is experiencing increasing competition as established companies and emerging brands expand their product portfolios. Market participants are focusing on product differentiation through new formulations, flavors, packaging formats, and targeted offerings. Strategic partnerships, distribution expansion, and brand development are also shaping competitive positioning. The market remains fragmented across product categories, with opportunities for companies to strengthen their share through innovation and geographic expansion.
Key Sports Supplements Companies
The following key companies have been profiled for this study on the sports supplements market
-
Herbalife
-
Glanbia PLC
-
Abbott
-
GNC Holdings, LLC
-
The Simply Good Foods Company
-
THG PLC
-
NOW Foods
-
SciTec, Inc.
-
Universal Nutrition
-
Maxinutrition
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Glanbia plc, Abbott Laboratories, PepsiCo, GNC Holdings, Herbalife Ltd.)
- Expand product portfolios through innovation in protein, performance, and recovery nutrition products. Strengthen omnichannel distribution through retail, e-commerce, fitness centers, and strategic partnerships with athletes and sports organizations.
- Strong brand recognition, extensive distribution networks, and significant R&D capabilities. Established consumer trust and the ability to leverage economies of scale for global market penetration.
- Higher operating costs and complex supply chain management. Slower response to emerging consumer preferences and niche nutrition trends compared to smaller competitors.
Emerging Players (MaxiNutrition Ltd., Scitec Nutrition, NOW Foods, The Simply Good Foods Company, THG plc/Myprotein)
- Focus on specialized segments such as plant-based proteins, clean-label formulations, personalized nutrition, and direct-to-consumer sales.
- Utilize digital marketing, influencer partnerships, and e-commerce platforms to build brand awareness.
- Greater agility in product innovation and the ability to rapidly address evolving consumer demands.
- Strong engagement with fitness communities and targeted customer segments.
- Limited financial resources and lower global brand visibility. Dependence on online channels and challenges in achieving large-scale distribution and customer acquisition profitability.
Recent Developments
-
In August 2025, Silver Star Nutrition launched ELITE Whey Protein Isolate, a milk-derived whey protein supplement providing 20 g of protein per serving, demonstrating continued product innovation in the animal-based protein segment.
-
In April 2025, Nutrex launched its IsoFit Protein Bar at the Arnold Sports Festival South America in São Paulo, offering 13 g of protein per bar and expanding its sports nutrition portfolio into a convenient, ready-to-eat format.
-
In February 2025, VEGA introduced its rebranded performance nutrition line, including Protein + Creatine with 30 g of plant-based protein and 3 g of creatine per serving, alongside a ready-to-drink plant-based protein shake. The launch demonstrates how brands are integrating plant-based protein, performance functionality, and convenience to address the evolving requirements of active consumers.
Sports Supplements Market Report Scope
Report Attribute
Details
Market size in 2025
USD 97.4 billion
Estimated market size in 2026
USD 105.3 billion
Projected market size by 2033
USD 189.4 billion
Growth rate
CAGR of 8.7% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, source, distribution channel, and region
Regional scope
North America; Europe; Asia Pacific; Central & South America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; Russia; Iceland; Finland; China; Japan; India; South Korea; Australia; Thailand; Singapore; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait; Israel
Key companies profiled
The Simply Good Foods Company; Maxinutrition; Universal Nutrition; GNC Holdings, LLC; Glanbia PLC; NOW Foods; SciTec, Inc.; THG PLC; PepsiCo; Abott; Herbalife
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Sports Supplements Market Report Segmentation
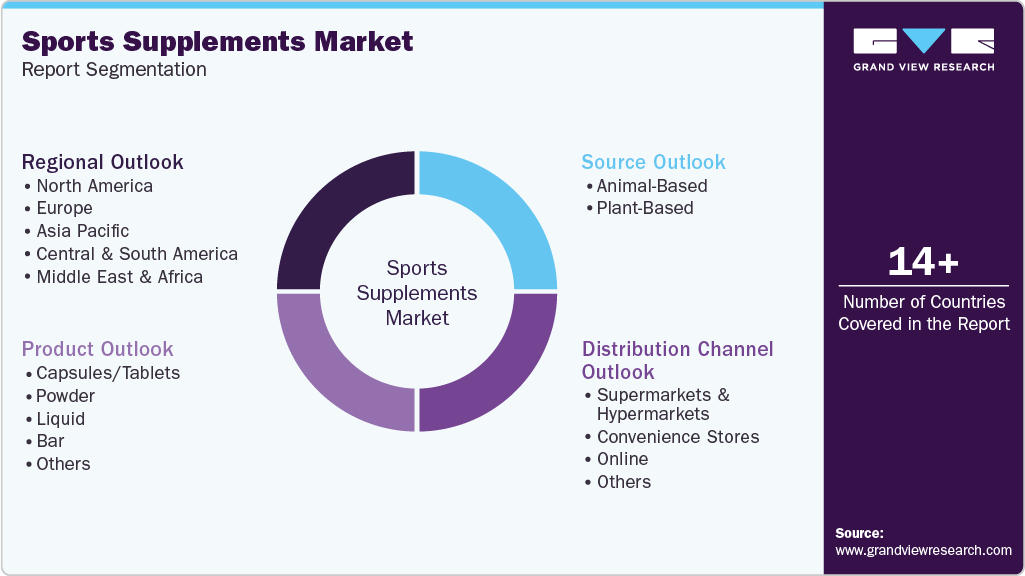
This report forecasts revenue growth at the regional and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global sports supplements market report based on the product, source, distribution channel, and region.
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Billion, 2021 - 2033)
-
Capsules/Tablets
-
Powder
-
Liquid
-
Bars
-
Others
-
-
Source Outlook (Revenue, USD Billion, 2021 - 2033)
-
Animal-Based
-
Plant-Based
-
-
Distribution Channel Outlook (Revenue, USD Billion, 2021 - 2033)
-
Supermarkets & Hypermarkets
-
Convenience Stores
-
Online
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia & New Zealand
-
-
Central & South America
-
Brazil
-
-
Middle East & Africa
-
South Africa
-
-
Research Methodology
The sports supplements market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing, reconciling supply-side and demand-side estimates, and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each sports supplements segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Capsules/Tablets
This segment includes the sales of sports supplements formulated in capsule, softgel, and tablet forms containing vitamins, minerals, amino acids, creatine, electrolytes, and performance-support ingredients. These products are preferred for their portability, precise dosing, and ease of consumption.
Powder
This segment includes the sales of powdered sports nutrition products such as protein powders, meal replacement formulas, pre-workout blends, post-workout recovery supplements, and amino acid mixes. Powdered formats are widely used due to their flexibility in dosage and ability to deliver higher concentrations of active ingredients.
Liquid
This segment includes the sales of ready-to-drink protein beverages, energy drinks, recovery drinks, hydration solutions, and concentrated supplement shots. Liquid formulations are commonly consumed for rapid absorption and convenience before, during, or after physical activity.
Bar
This segment includes the sales of protein bars, energy bars, meal replacement bars, and functional nutrition bars designed to support muscle recovery, endurance, satiety, and performance goals. These products are often used as convenient on-the-go nutrition options.
Others
This segment includes the sales of sports supplements offered in formats such as gummies, gels, chews, powders in sachets, and functional snacks. It also covers emerging delivery formats developed to improve convenience, taste, and consumer engagement.
Segment - Source
Revenue capture definition
Animal-Based
This segment includes the sales of sports supplements derived from animal sources such as whey protein, casein protein, collagen peptides, egg protein, and fish-based ingredients. These products are widely utilized for their complete amino acid profiles and high protein bioavailability.
Plant-Based
This segment includes the sales of sports supplements formulated from plant-derived ingredients such as pea protein, soy protein, rice protein, hemp protein, and blended botanical formulations. Demand for these products is supported by vegan lifestyles, sustainability preferences, and dairy-free nutritional requirements.
Segment - Distribution Channel
Revenue capture definition
Hypermarkets & Supermarkets
This segment includes the sales of sports supplements through large retail chains, supermarkets, warehouse clubs, & mass merchandisers. These outlets provide consumers with access to a broad range of products from multiple brands under one location.
Convenience Stores
This segment includes the sales of sports nutrition products through convenience stores, forecourt retailers, and small-format retail outlets. Purchases in this channel are largely driven by immediate consumption needs, particularly for energy drinks, protein bars, and ready-to-drink products.
Online
This segment includes the sales of sports supplements through e-commerce platforms, brand-owned websites, online pharmacies, fitness marketplaces, and digital subscription services. The channel benefits from wider product availability, direct-to-consumer offerings, and access to detailed product information.
Others
This segment includes the sales of sports supplements through specialty nutrition stores, fitness centers, health clubs, pharmacies, healthcare facilities, and direct selling networks. These channels often provide product guidance, expert recommendations, and specialized sports nutrition offerings.
Estimation Model
Sports Participation Layer
Product Accessibility Layer
Consumption Layer
Revenue Layer
Key Question: Who uses sports nutrition products?
Key Question: Who can purchase sports supplements?
Key Question: Who actively consumes sports supplements?
Key Question: How much revenue is generated?
Identify the global population engaged in fitness activities, strength training, endurance sports, and professional athletics to establish the core consumer base.
Apply retail availability, e-commerce penetration, and consumer awareness levels to determine the addressable market.
Apply supplement adoption and repeat-purchase rates among fitness enthusiasts and athletes to estimate the active user base.
Multiply active consumers by average annual spending on sports supplements and incorporate institutional and fitness channel sales to estimate market revenue.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Sports Nutrition Product Segmentation & Consumer Demand Analysis
Conducted a focused assessment of sports supplements across protein powders, amino acids, creatine, pre-workout, recovery, hydration, and weight management products, evaluating demand patterns among athletes, bodybuilders, and fitness enthusiasts.
Helps stakeholders identify high-growth product segments, understand consumer purchasing behavior, and prioritize investments in the most attractive revenue-generating categories.
Distribution Channel & End-User Assessment
Evaluated sales performance across e-commerce platforms, specialty nutrition stores, pharmacies, supermarkets, fitness centers, and direct-to-consumer channels, alongside demand analysis by recreational and professional users.
Provides insights into channel effectiveness, customer acquisition opportunities, and market penetration strategies to optimize commercial performance.
Product Innovation & Competitive Landscape Assessment
Assessed developments in clean-label formulations, plant-based proteins, personalized sports nutrition, functional ingredients, and emerging performance-enhancing products, while benchmarking key market participants and innovation pipelines.
Supports strategic planning by identifying emerging opportunities, competitive differentiation factors, and long-term growth areas within the sports supplements industry.
Frequently Asked Questions About This Report
North America dominated with a 54.1% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
Animal-based held the largest revenue share in 2025, while plant-based is the fastest-growing area.
The supermarkets and hypermarkets segment led with a 33.9% revenue share in 2025.
Key players include Herbalife, Glanbia PLC, Abbott, GNC Holdings, LLC, The Simply Good Foods Company, THG PLC, NOW Foods, SciTec, Inc., Universal Nutrition, and Maxinutrition.
Key factors include accelerating demand for science-backed performance nutrition, increasing consumption of protein-enriched formulations for strength development and recovery optimization, and expanding product portfolios targeting endurance, functional fitness, and competitive sports segments.
The global sports supplements market size was valued at USD 97.4 billion in 2025 and is estimated at USD 105.3 billion for 2026.
The global sports supplements market is expected to grow at a CAGR of 8.7% from 2026 to 2033, reaching USD 189.4 billion by 2033.
Liquid segment led with a revenue share of 56.7% in 2025.
About the Author(s)
Consumer F&B Research Team
Consumer Goods · Consumer F&BThis report was authored by the consumer f&b research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the consumer f&b segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


