
- Home
- »
- Advanced Interior Materials
- »
-
Steel Rebar Market Size, Share & Trends Report, 2026-2033GVR Report cover

Steel Rebar Market (2026 - 2033)
Size, Share & Trends Analysis Report By Application (Infrastructure, Construction, Industrial), By Region (North America, Europe, Asia Pacific, Latin America, Middle East & Africa), And Segment Forecasts
Market Size, 2025
$246.1BMarket Estimate, 2026
$250.9BMarket Forecast, 2033
$377.6BCAGR, 2026–2033
6.0%Steel Rebar Market Summary
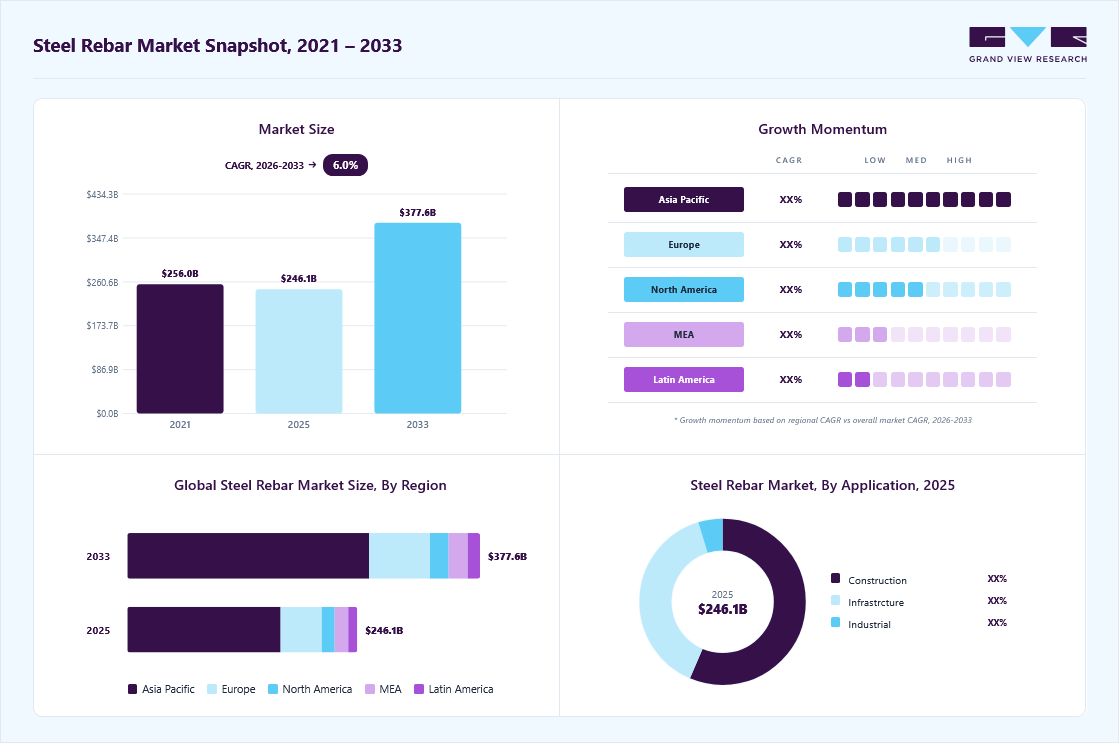
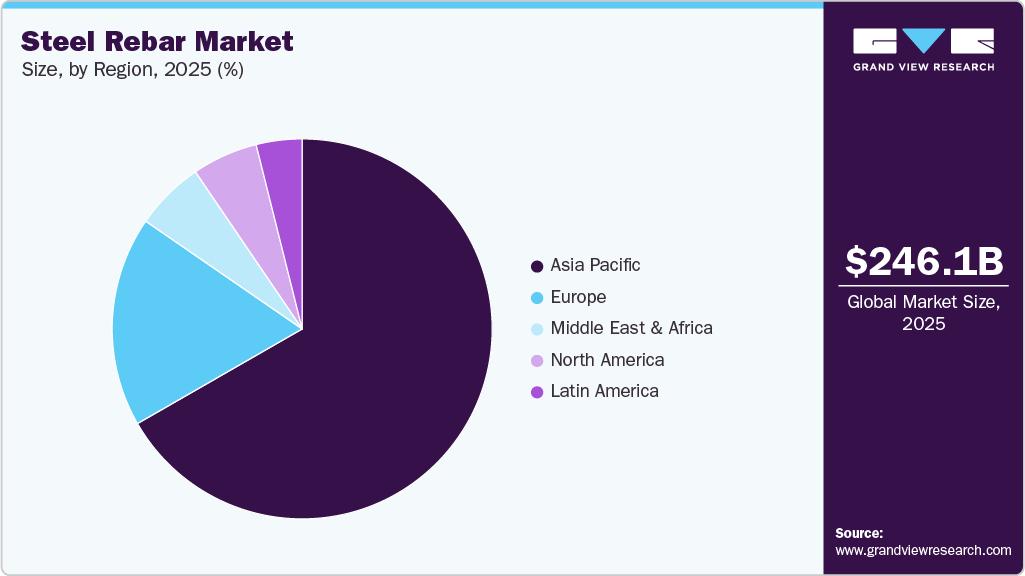
The global steel rebar market size was valued at USD 246.1 billion in 2025 and is projected to grow from USD 250.9 billion in 2026 to USD 377.6 billion by 2033, at a CAGR of 6.0% from 2026 to 2033. Asia Pacific dominated the market, accounting for the largest revenue share of 66.7% in 2025. The steel rebar market is witnessing steady growth driven by rising investments in infrastructure development, rapid urbanization, and expanding construction activities.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By Application: The construction segment held the largest market share of 56.3% in 2025.
- Growing demand, majorly from emerging economies, is expected to drive growth.
Regional Highlights
- Largest regional market: Asia Pacific (66.7% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR of 6.4%, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 246.1 Billion
- Estimated market size in 2026: USD 250.9 Billion
- Projected market size by 2033: USD 377.6 Billion
- CAGR (2026-2033): 6.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
A considerable increase in demand for durable and high-strength reinforcement materials across residential, commercial, and industrial projects is favoring market growth. Steel rebar is a reinforcing steel bar used in concrete structures to enhance tensile strength, structural integrity, and durability across infrastructure, residential, and commercial construction applications. The development of transportation networks, bridges, high-rise buildings, and large-scale infrastructure projects is significantly contributing to demand for steel rebar worldwide. Ongoing innovations in high-strength, corrosion-resistant rebar grades are expanding their application potential in large-scale infrastructure and seismic-resistant construction projects.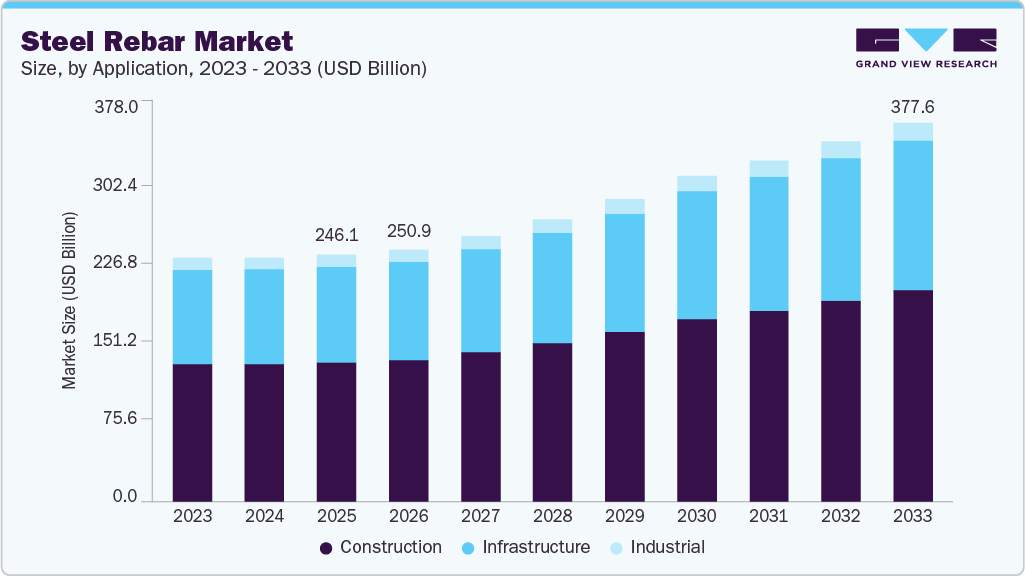 To learn more about this report, Download Free Sample Report
The increased focus on upgrading infrastructure and building resilient structures is driving demand for steel rebar in both developed and developing countries. Governments and private developers are increasing investments in roads, airports, commercial complexes, residential buildings, and renewable energy infrastructure, creating sustained opportunities for reinforcement steel. Furthermore, more stringent construction regulations, coupled with the imperative to enhance the structural integrity and durability of concrete constructions, are driving the adoption of high-strength and corrosion-resistant reinforcing bar products.
Technological advancements in steel production and growing sustainability initiatives are influencing the evolution of the steel rebar market. Manufacturers are increasingly adopting energy-efficient production processes, electric arc furnace technology, recycled steel inputs, and advanced rebar grades to lower the environmental impact while meeting performance requirements. The increasing adoption of prefabricated and modular construction, coupled with the expansion of urban infrastructure and industrial facilities, is expected to create additional demand for steel rebar during the forecast period. Moreover, the use of Industry 4.0 tools such as IoT, AI-driven predictive maintenance, and automation in steel plants is also helping manufacturers reduce downtime and optimize output.
Steel rebar prices recorded upward momentum in 2026, supported by geopolitical tensions involving Iran, Israel, and the U.S., which disrupted trade flows and increased energy and transportation costs. Concerns over shipping through the Strait of Hormuz contributed to higher freight rates, insurance premiums, and fuel costs, while elevated oil and gas prices increased production expenses for energy-intensive steelmakers. These cost pressures prompted producers to raise rebar prices to protect margins, supporting higher price levels across key markets.
Market Dynamics
The global steel rebar market is shaped by rising infrastructure investment and increasing construction activities, particularly across emerging economies. Capacity expansions, value-added rebar development, and emerging applications such as data centers, renewable energy, and industrial infrastructure are expected to present new growth opportunities for market participants, thereby impacting the global market scenario.
The global steel rebar market is expected to benefit from continued infrastructure spending, rapid urbanization, and expanding construction activity across emerging economies. Large-scale investments in roads, bridges, railways, housing, and industrial facilities are supporting demand for high-strength reinforcement materials. As per the World Steel Association, India is emerging as a particularly strong growth market, with steel demand projected to increase by 7.4% in 2026, supported by infrastructure-led construction and rail network expansion. According to India’s Ministry of Steel, crude steel production increased 10.7% year-on-year to 168.4 million tonnes in FY 2025-26, while finished steel consumption rose 7.6% to 163.7 million tonnes. This expansion is supporting demand for long steel products, including rebar, across transportation, housing, and industrial projects. Moreover, government-led investments in road and rail networks, urban infrastructure, and industrial corridors are providing sustained demand visibility, particularly across developing markets.
Given the energy-intensive characteristics of steel production, escalating energy prices pose a significant challenge to steel rebar manufacturers, thereby affecting their production margins. Volatility in natural gas and electricity prices can increase operating costs, particularly for European manufacturers, while investments required to transition toward lower-carbon production routes add further financial pressure. In April 2026, ArcelorMittal reported that European steel demand remained below previous peak levels, with 2026 growth forecasts revised to around 1.3% due to high energy costs, subdued construction activity, and macroeconomic uncertainty. The situation emphasizes the continued lack of growth in demand in developed economies, where construction timelines are extended and are more susceptible to shifts in interest rates.
A key opportunity for the market lies in expanding capacity and producing value-added long steel aligned with long-term construction growth. The global steel rebar market presents significant opportunities through the development of high-strength, corrosion-resistant, and low-carbon rebar products that address evolving construction standards and sustainability requirements. In January 2026, JSW Steel announced a strategic expansion plan to reach approximately 56 MTPA of steel capacity by FY2031, supported by investments exceeding USD 24 billion. A significant portion of this expansion is focused on downstream and construction-grade steel products, including rebar and wire rods, which are critical for infrastructure development. This reflects a broader industry trend where steel producers are shifting toward high-volume, infrastructure-linked products while simultaneously improving product quality and efficiency. In parallel, rising demand from data center construction, renewable energy installations, and industrial logistics infrastructure is presenting non-traditional end-use segments for rebar consumption, particularly in developed markets like North America.
Analyst Perspective
The global steel rebar market is expected to witness sustained growth, supported by infrastructure expansion, urbanization, and rising construction activity, particularly across developing economies such as India and other emerging Asian markets. Demand is also likely to benefit from investments in transportation infrastructure and resilient construction. Product quality, high-strength and corrosion-resistant rebar offerings, production efficiency, pricing competitiveness, supply-chain capabilities, and progress toward low-carbon steel production are among the key factors that will help the market players stay abreast of the competition. Sustainability and the ability to provide customized solutions for evolving construction requirements are also expected to play a key role.
Application Insights
The construction segment held the largest market share of 56.3% in 2025, supported by the extensive use of steel rebar across residential, commercial, and industrial building projects. Rapid urbanization, population growth, and rising housing requirements, particularly in emerging economies, are supporting demand for reinforcement materials used in foundations, columns, slabs, beams, and other load-bearing structures. The growing adoption of high-strength and corrosion-resistant rebar in high-rise buildings and resilient structures is also creating opportunities for value-added products. Additionally, ongoing real estate development and renovation activities in developed markets continue to reinforce steady demand, making construction the dominant application segment in the global steel rebar market.
The infrastructure segment is expected to record the fastest CAGR of 6.3% over the forecast period, driven by large-scale public investments in transportation networks, energy systems, and urban connectivity projects. Governments in both emerging and developed nations are placing a high emphasis on infrastructure projects such as highways, bridges, ports, and intelligent urban development, all of which necessitate significant quantities of reinforced concrete. Continued capital expenditure in infrastructure modernization programs across Asia and North America is further accelerating demand for high-strength and corrosion-resistant rebar, making this segment the fastest-growing application area.
Regional Insights
The North American steel rebar market is projected to register a CAGR of 5.2% from 2026 to 2033, supported by government-backed infrastructure programs and investment in highways, bridges, public utilities, and other critical infrastructure. The market growth in North America is driven by ongoing infrastructure renewal, transportation modernization, and resilient non-residential construction activities. Infrastructure modernization initiatives are sustaining demand for reinforcing steel, while investments in manufacturing facilities, data centers, and energy infrastructure are creating additional consumption opportunities. Furthermore, the region’s high adoption of electric arc furnace (EAF)-based steelmaking supports flexible, localized production and helps strengthen domestic rebar supply chains. The increasing focus on supply-chain resilience and domestically produced steel is further supporting regional manufacturers and reducing dependence on imported reinforcement products.
U.S. Steel Rebar Market Trends
The U.S. dominated the North American regional market, accounting for a share of over 80.0% of the regional market in 2025, supported by sustained federal infrastructure spending and robust private-sector construction activity, particularly across industrial facilities, data centers, and commercial projects. Increasing investments in logistics hubs, semiconductor manufacturing facilities, energy infrastructure, and transportation networks are further expected to strengthen demand for long steel products. Domestic steel producers, particularly electric arc furnace (EAF)-based mini-mill operators, are expanding and modernizing their production capacities to meet growing regional demand and strengthen supply-chain resilience. The increasing preference for domestically produced steel is also supporting local manufacturers amid trade and import-related uncertainties. Furthermore, ongoing investments in advanced manufacturing and large-scale infrastructure projects are expected to sustain rebar demand over the forecast period.
Asia Pacific Steel Rebar Market Trends
The Asia Pacific steel rebar market held the largest share of 66.7% of the global market in 2025 and is projected to record the fastest CAGR of 6.4% over the forecast period. The region’s strong market position is supported by rapid urbanization, population growth, industrialization, and extensive infrastructure development. India, Indonesia, and Vietnam are currently witnessing a surge in construction projects, including residential housing, infrastructure development, commercial establishments, and industrial zones. In addition, rising government capital expenditure on urban infrastructure is strengthening long-term demand for reinforcing steel. The growth in manufacturing capacity and the allocation of capital to industrial and logistics infrastructure are also expected to create additional opportunities for regional steel rebar producers.
 To learn more about this report, Download Free Sample Report
China Steel Rebar Market Trends
China accounted for approximately 55.0% of the global steel rebar market in 2025. It is the world’s largest producer and consumer of steel rebar, supported by its extensive infrastructure network, large construction sector, and significant industrial base. During early 2026, rebar prices showed moderate strengthening despite subdued real estate activity, supported by production controls, reduced inventories, and improved supply-demand balance. China’s steel rebar market is transitioning from a phase of rapid capacity and construction expansion toward more measured growth, with increasing emphasis on urban redevelopment, high-quality infrastructure, energy efficiency, and environmental compliance. Production rationalization and capacity-control measures are also reshaping long steel supply dynamics and encouraging producers to prioritize efficiency and product quality.
Europe Steel Rebar Market Trends
The Europe steel rebar market accounted for a 17.9% share of the global market in 2025. Influenced by infrastructure modernization, sustainable construction, and stringent decarbonization requirements, the region is projected to witness growth in demand supported by investments in transportation infrastructure, building renovation, and energy-related projects. The EU’s climate policies are encouraging steelmakers to adopt lower-carbon production technologies and increase the use of recycled steel. Trade protection measures and efforts to strengthen regional steel supply chains are also influencing domestic market dynamics and reducing competitive pressure from imports. However, elevated energy and production costs continue to challenge European producers and contribute to higher rebar prices.
Latin America Steel Rebar Market Trends
The Latin American steel rebar market is expected to record a CAGR of 4.6% from 2026 to 2033, supported by infrastructure modernization, urban housing development, and expanding industrial activity, particularly in Brazil and Mexico. Sustained demand for reinforcing steel is being driven by governmental investments in transportation networks, energy infrastructure, and urban development initiatives. Increased investment in the logistics sector, production sites, and housing projects is projected to foster additional avenues for regional rebar suppliers. However, economic uncertainty, currency fluctuations, and variations in construction activity across countries can result in uneven demand and pricing patterns throughout the region.
Middle East Steel Rebar Market Trends
The Middle East & Africa steel rebar market is expected to grow with a CAGR of 4.8% over the forecast period, driven by increasing demand from large-scale infrastructure projects, urban development, and tourism-related construction, particularly in Saudi Arabia and the UAE. The Investments in smart cities, commercial developments, transportation networks, and major tourism projects are strengthening rebar consumption. Saudi Arabia’s Vision 2030 initiatives and the UAE’s continued infrastructure and urban development programs are expected to provide sustained demand opportunities. In Africa, rapid urbanization, population growth, and significant infrastructure deficits offer substantial long-term growth potential. However, limited financing availability, policy uncertainty, and uneven economic development across countries continue to constrain market expansion.
Key Steel Rebar Company Insights
Key players in the steel rebar market are focusing on capacity expansion, product innovation, and strategic partnerships to strengthen their market position. Companies are also investing in advanced manufacturing technologies, sustainable production practices, and regional expansion to meet growing demand in the construction and infrastructure sector. Some of the key players operating in the market include ArcelorMittal, Nucor, Tata Steel, and others.
-
ArcelorMittal is a global steel and mining company engaged in the production of both flat and long steel products. The company manufactures a wide range of products, including rebar, wire rod, structural steel, hot-rolled and cold-rolled coils, coated steel, and specialty steels for construction, automotive, and industrial applications. Its integrated mining operations further support raw material security and supply chain efficiency.
-
Nucor is one of the largest steel producers in the U.S. It primarily uses electric arc furnace (EAF) technology and offers a broad portfolio of long and flat steel products, including reinforcing bars (rebar), structural steel, beams, sheet, and plate steel, as well as downstream fabricated construction products, serving infrastructure, commercial, and industrial applications.
-
Tata Steel is an integrated steel producer with operations across India and international markets. The company manufactures a diversified range of products, including TMT bars and rebars, wire rods, structural sections, hot-rolled and cold-rolled steel, coated products, and specialty steels, catering to construction, automotive, engineering, and infrastructure applications.
Key Steel Rebar Companies
The following key companies have been profiled for this study on the steel rebar market.
-
Jiangsu Shagang Group
-
JSW Steel
-
POSCO Holdings Inc.
-
Steel Authority of India Limited (SAIL)
Recent Developments
-
In March 2026, Tata Steel inaugurated its 0.75 MTPA scrap-based electric arc furnace (EAF) at Ludhiana, Punjab, following an investment of approximately USD 342 million. The facility will use 100% steel scrap and is designed to operate with nearly 50% renewable energy, with planned emissions of less than 0.3 tonnes of CO₂ per tonneof steel. Theplant is designedto produceconstruction-grade TMT rebar under the Tata Tiscon brand, strengthening Tata Steel’s presence in India’s construction segment.
-
In February 2024, Nucor approved an investment of approximately USD 860 million to construct a 650,000-ton-per-year rebar micro mill in the Pacific Northwest. The facility is planned to produce a full range of rebar sizes, including spooled products, and represents Nucor’s fourth and largest rebar micro mill. The investment is aimed at strengthening the company’s regional rebar supply capabilities and capitalizing on sustained demand associated with U.S. infrastructure investment.
Steel Rebar Market Report Scope
Report Attribute
Details
Market size in 2025
USD 246.1 billion
Estimated market size in 2026
USD 250.9 billion
Projected market size by 2033
USD 377.6 billion
Growth Rate
CAGR of 6.0% from 2026 to 2033
Base year for estimation
2025
Actual data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Volume in Kilotons, Revenue in USD million, and CAGR from 2026 to 2033
Report coverage
Volume forecast, revenue forecast, competitive landscape, growth factors, and trends
Segments covered
Application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; France; Italy; Russia; UK; China; India; Japan; Indonesia; Brazil; UAE; Saudi Arabia
Key companies profiled
ArcelorMittal; Jiangsu Shagang Group; JSW Steel; Nippon Steel Corporation; NLMK; Nucor; POSCO Holdings Inc.; Steel Authority of India Limited (SAIL); Steel Dynamics, Inc.; Tata Steel
Customization scope
Free report customization (equivalent to 8 analyst working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Steel Rebar Market Report Segmentation
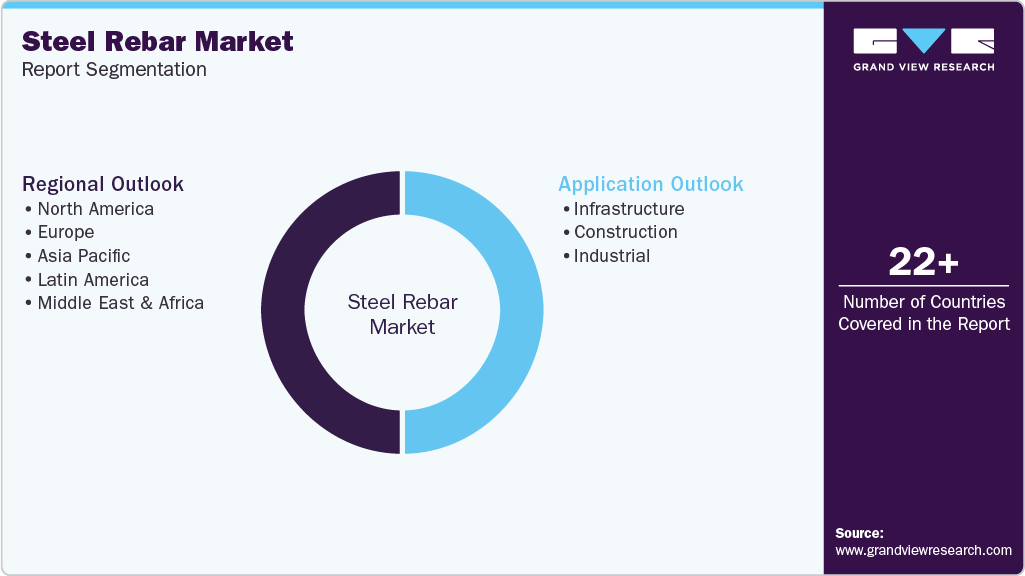
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends and opportunities across each sub-segment from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global steel rebar market report based on application and region:
 To learn more about this report, Download Free Sample Report
-
Application Outlook (Volume, Kilotons; Revenue, USD Million; 2021 - 2033)
-
Infrastructure
-
Construction
-
Industrial
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million; 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
Italy
-
Russia
-
UK
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Indonesia
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
UAE
-
Saudi Arabia
-
-
Frequently Asked Questions About This Report
Key factors include rising infrastructure and construction activities across emerging economies, and increased government spending on transportation, housing, and energy projects.
Asia Pacific dominated with a revenue share of 66.7% in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
The Construction segment held the market with the largest revenue share of 56.3% in 2025, while Infrastructure is the fastest-growing segment.
Key players are ArcelorMittal, Jiangsu Shagang Group, JSW Steel, Nippon Steel Corporation, NLMK, Nucor, POSCO Holdings Inc., Steel Authority of India Limited (SAIL), Steel Dynamics, Inc., Tata Steel.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


