
- Home
- »
- Next Generation Technologies
- »
-
STEM Education in K-12 Market Size, Share Report, 2033GVR Report cover

STEM Education In K-12 Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Self-paced, Instructor-led), By Application (Elementary School (K-5), Middle School (6-8), High School (9-12)), By Region And Segment Forecasts
Market Size, 2025
$69.5BMarket Estimate, 2026
$80.0BMarket Forecast, 2033
$182.4BCAGR, 2026–2033
12.5%Stem Education In K-12 Market Summary
The global STEM education in K-12 market size was valued at USD 69.5 billion in 2025 and is projected to grow from USD 80.0 billion in 2026 to USD 182.4 billion by 2033, at a CAGR of 12.5% from 2026 to 2033. North America dominated the global market with the largest revenue share of 43.9% in 2025. The adoption of AI-enabled STEM learning platforms and immersive technologies such as virtual labs and educational robotics is reshaping K-12 education by making STEM instruction more interactive and personalized.
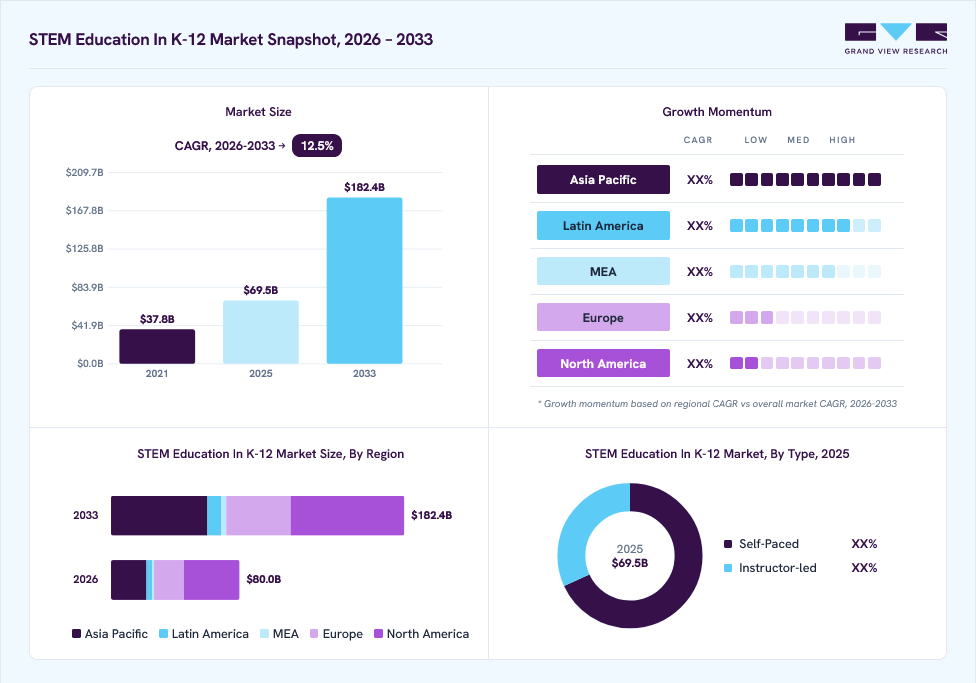 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Self-paced segment dominated the market, with a revenue share of 68.0% in 2025.
- By application: High school (9-12) segment held the largest market share of 46.5% in 2025.
Regional Highlights
- Largest regional market: North America (43.9% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 69.5 Billion
- Estimated market size in 2026: USD 80.0 Billion
- Projected market size by 2033: USD 182.4 Billion
- CAGR (2026-2033): 12.5%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Advanced technologies, such as artificial intelligence (AI) and quantum computing, could reinforce the STEM education system to propel innovation-based competitiveness. STEM, the foundation for technological advancements and discovery, could bolster creativity and ingenuity. STEM learning during the K 12 years is expected to expedite experimentation, build resilience, boost science literacy, foster teamwork, and drive tech use, helping produce the next generation of innovators.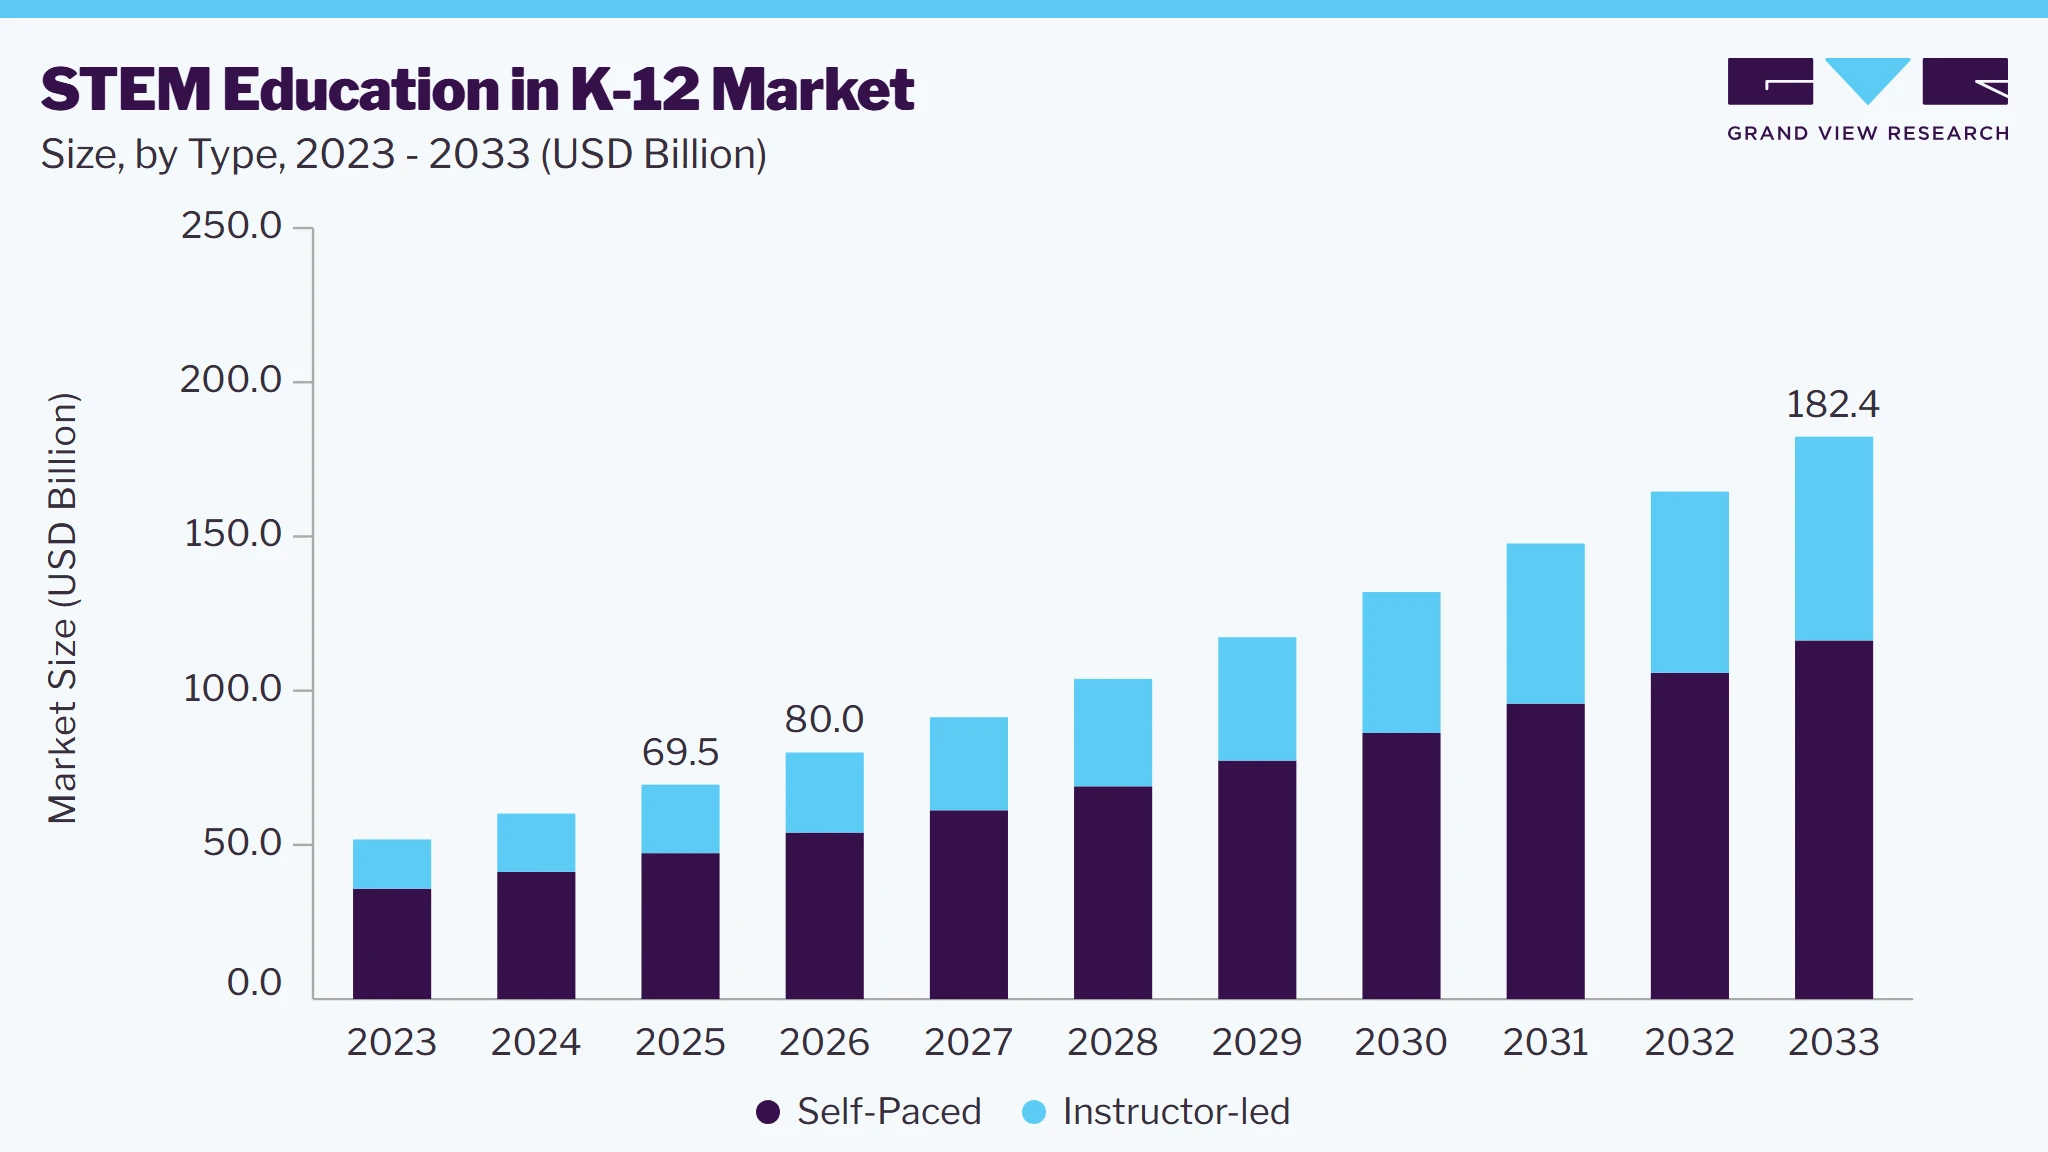 To learn more about this report, Download Free Sample Report
STEM education in K-12 industry focuses on programs to help learners gain skills and knowledge to excel in the job market. It inspires and motivates students to generate new ideas and promotes problem-solving and project-based learning. Education leaders are expected to expose children at preschool and kindergarten to subjects once perceived as higher level, including science, programming, math, engineering, and languages. Integrating STEM concepts through a K-12 education could have an invaluable influence on the talent pool, requiring advanced knowledge and skills to stay competitive in the digitally disruptive world. STEM education in K-12 industry is poised to hold prominence in helping students explore machine learning, AI, and IoT. STEM pedagogy at the K-12 level will remain instrumental in creating a solid foundation for academic growth, fostering positive attitudes, and preparing children for jobs.
The emergence of advanced educational technologies (EdTech) is making STEM education more engaging and accessible for students. These technologies include online learning platforms, simulations, virtual reality experiences, and robotics. EdTech can personalize learning experiences and cater to various learning styles, making STEM education more inclusive. Various governments in developing countries recognize the importance of STEM education and are increasing their investment in STEM programs. This funding is used to develop new curriculum materials, train teachers, and provide professional development opportunities.
Market Dynamics
The increasing focus on preparing students for technology-driven careers is accelerating investment in STEM education across K-12 schools worldwide. Governments, educational institutions, and private organizations are expanding funding for coding, robotics, engineering, and hands-on science programs to address future workforce requirements. The growing integration of AI-powered learning platforms, virtual laboratories, and interactive digital content is improving student engagement while enabling personalized learning experiences. In addition, rising collaboration between schools and technology companies to modernize curricula and strengthen practical skill development is further supporting market expansion.
The integration of AI, robotics, and digital learning technologies is transforming K-12 STEM education by making lessons more interactive, personalized, and application-oriented. AI-powered platforms enable adaptive learning based on individual student performance, while robotics kits, coding tools, and virtual laboratories strengthen practical understanding of STEM concepts. Schools are increasingly adopting these technologies to improve student engagement, encourage critical thinking, and build problem-solving capabilities aligned with evolving industry needs.
Moreover, technology companies and education providers are collaborating with schools to introduce advanced STEM curricula supported by cloud-based learning platforms and immersive educational tools. The growing availability of connected classroom infrastructure and digital devices is making advanced STEM resources more accessible across both developed and emerging economies, supporting sustained growth in the K-12 STEM education market.
The shortage of qualified STEM teachers remains a significant challenge for the K-12 STEM education market, as many schools struggle to recruit and retain educators with expertise in science, technology, engineering, and mathematics. Rapid advancements in fields such as artificial intelligence, robotics, and coding further widen the skills gap, making it difficult for teachers to keep pace with evolving curriculum requirements. Limited access to continuous professional development and specialized training programs also affects the effective delivery of practical and technology-driven STEM education. As a result, many schools face difficulties in providing high-quality, hands-on STEM learning experiences, particularly in underserved and rural regions. This imbalance in teaching capabilities can slow the adoption of advanced STEM programs and reduce student participation, ultimately restraining the overall growth of the STEM education in K-12 market.
The rapid advancement of AI is creating significant opportunities for K-12 STEM education providers to deliver highly personalized learning experiences focused to each student's pace, strengths, and learning needs. AI-powered platforms can analyze student performance in real time, recommend customized learning pathways, and provide instant feedback, helping improve academic outcomes while reducing learning gaps. As schools increasingly adopt digital education technologies, demand for intelligent STEM learning solutions is expected to grow across both developed and emerging markets.
In addition, AI-enabled virtual tutors, adaptive assessments, and interactive STEM simulations are making science, technology, engineering, and mathematics education more engaging and accessible. Education technology companies are partnering with schools and governments to integrate AI-driven platforms into classrooms, creating new revenue opportunities through software subscriptions, cloud-based services, and digital curriculum solutions.
Market Concentration & Characteristics
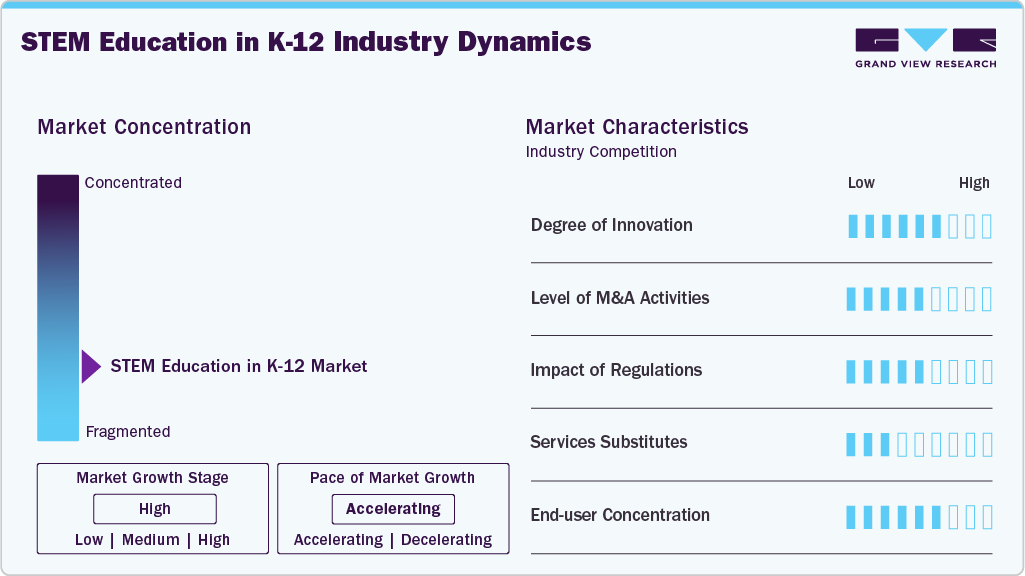
The market demonstrates a high degree of innovation, driven by continuous advancements in artificial intelligence, adaptive learning, educational robotics, virtual laboratories, augmented reality, and gamified STEM education. Companies are consistently introducing new digital learning tools that improve student engagement and personalize instruction. Growing investments in intelligent learning platforms and immersive educational technologies are expected to sustain innovation throughout the forecast period.
 To learn more about this report, Download Free Sample Report
The impact of regulations is moderately high, as government education policies, curriculum standards, student data privacy requirements, and digital learning regulations significantly influence product development and market adoption. Vendors must align their STEM solutions with national education frameworks, accessibility standards, and cybersecurity requirements to gain acceptance in schools. Public funding initiatives and curriculum reforms also play an important role in shaping demand across different regions.
Analyst Perspective
The STEM education in K-12 market is gaining momentum as governments, schools, and technology providers prioritize future-ready skills such as coding, robotics, AI, and engineering within mainstream education. The market is transitioning from conventional classroom instruction toward integrated digital learning environments supported by AI-powered platforms, virtual laboratories, and hands-on STEM resources that improve student engagement and learning outcomes. The competitive landscape increasingly favors providers offering comprehensive ecosystems that combine curriculum content, assessments, teacher training, and interactive learning tools under a single platform. Long-term growth is supported by rising public and private investments in STEM education infrastructure, curriculum modernization, and digital transformation initiatives across K-12 institutions.
Type Insights
Based on type, the self-paced segment led the market with the largest revenue share of 68.0% in 2025 and is expected to grow at the significant CAGR over the forecast period. The high share can be attributed to individualized learning, which has received impetus as it allows students to learn at their pace, controlling how and when they know. Prominently, built-in assessment and engagement tools have witnessed tremendous traction among K-12 students as the former provides real-time assessments. At the same time, the latter keeps learners interested through videos, photos, and interactive lessons.
The instructor-led segment is predicted to foresee significant growth in the forecast years. Instructor-led learning defines the instruction provided by one or more instructors in the form of lectures, presentations, demonstrations, and conversations. Although one-on-one instruction is less common and generally more expensive, the instructor typically addresses groups. During the instructor-led training, a large group is addressed at once, and various tactics are used, including games, exercises, and role-playing, to enhance the digital learning experience.
Application Insights
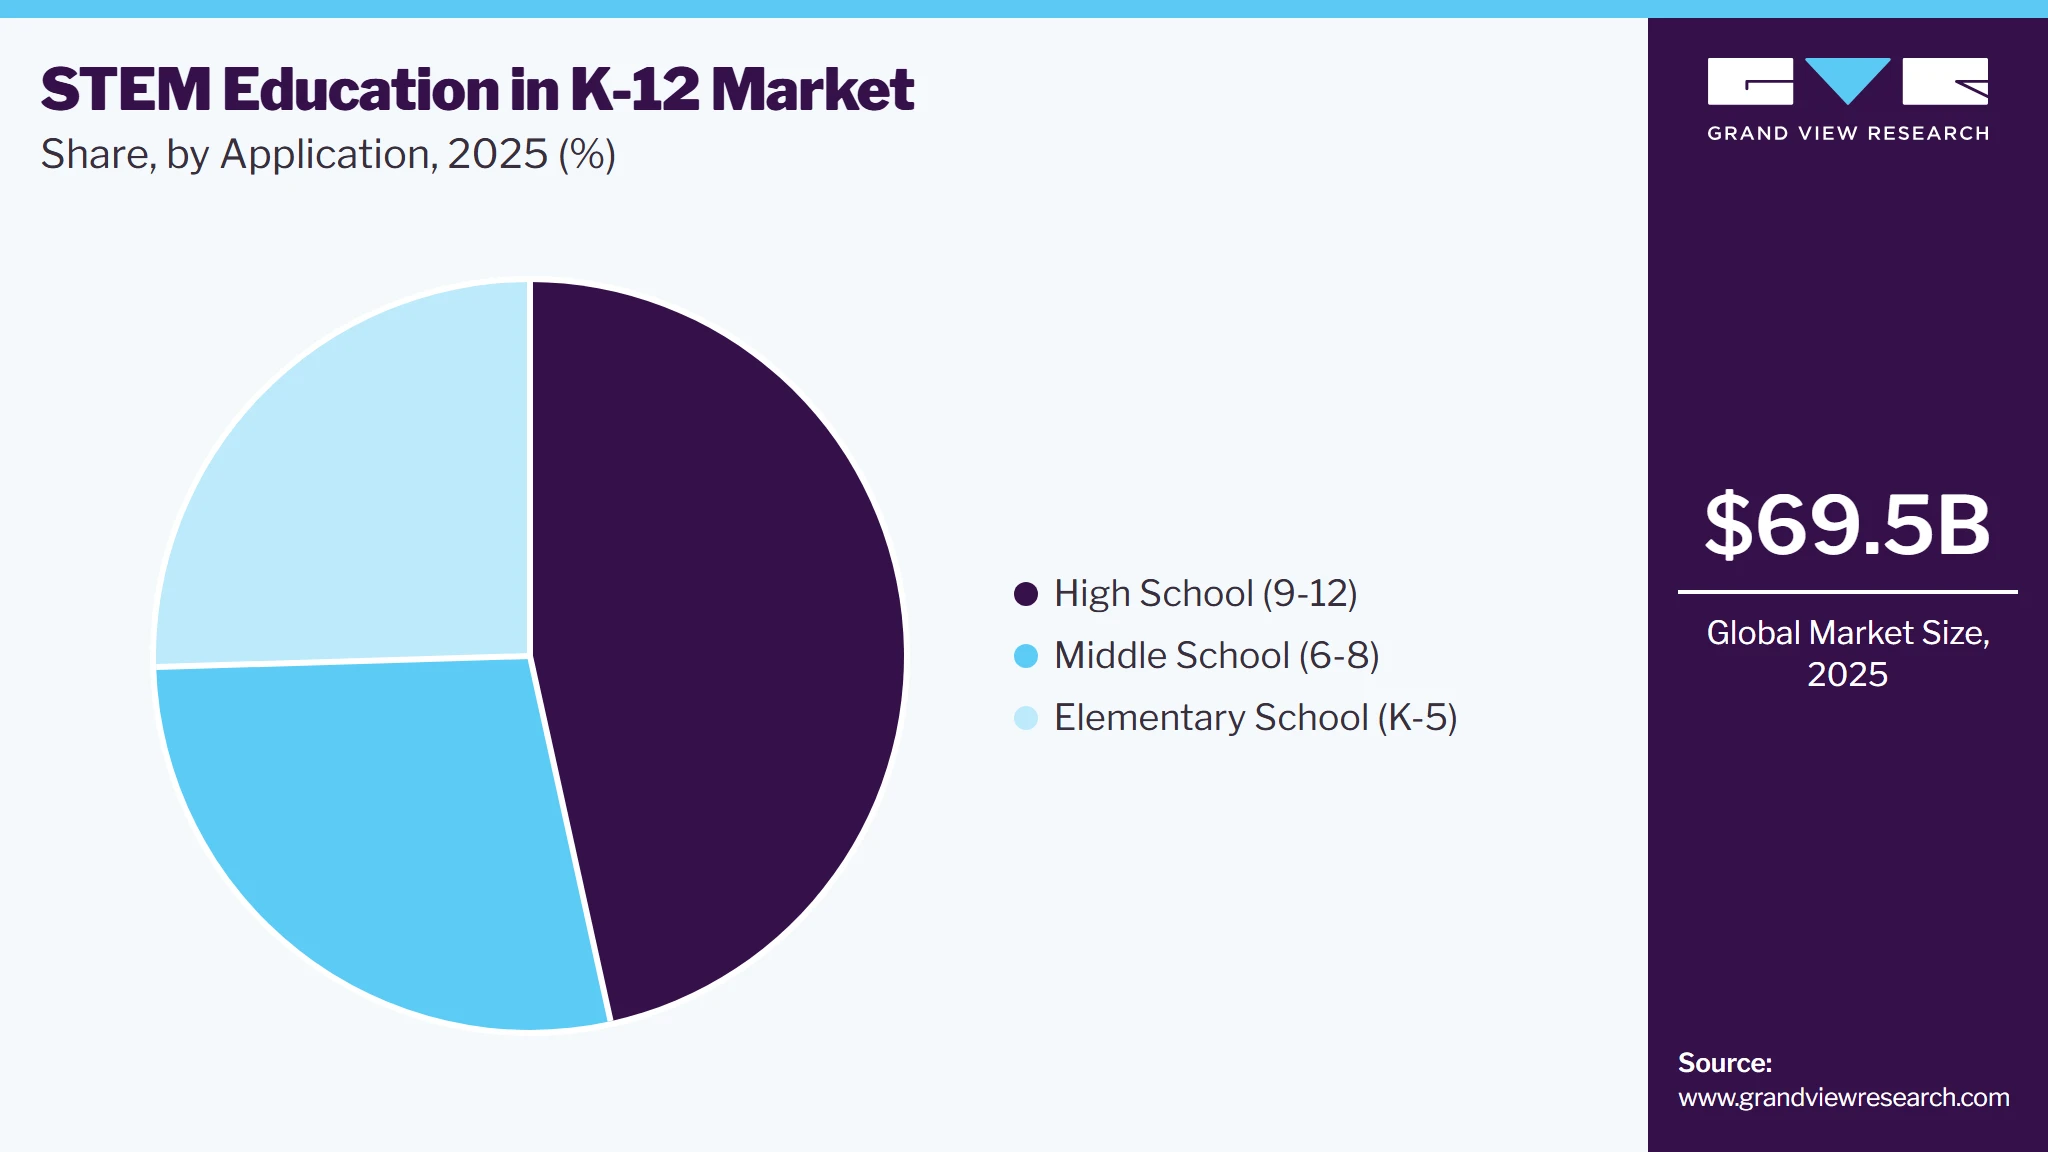
Based on application, the high school (9-12) segment led the market with the largest revenue share of 46.5% in 2025 and is expected to grow at the significant CAGR over the forecast period. Educators and other stakeholders are investing in STEM education for high school students. High school allows students to delve deeper into specific STEM fields, such as engineering, computer science, or biotechnology. Project-based learning allows them to apply their knowledge to real-world problems, fostering critical thinking, collaboration, and innovation skills. For instance, in May 2024, the Indian Institute of Technology Delhi launched its STEM mentorship program for high school girls in Classes 9 and 11. The initiative includes expert lectures, lab demonstrations, hands-on problem-solving, and a Maker Space workshop for DIY projects, aiming to immerse participants in STEM fields.
 To learn more about this report, Download Free Sample Report
The middle school (6-8) segment is expected to showcase significant growth over the forecast period. Middle school provides an opportunity to identify students with a talent for STEM and provide them with early intervention and enrichment programs. This can help close achievement gaps and ensure all students thrive in STEM fields. Middle school students are naturally curious and eager to explore new things. Engaging in STEM programs incorporating hands-on activities, experiments, and project-based learning can enhance their interest in science, technology, engineering, and mathematics. For instance, in November 2024, Virginia Commonwealth University received USD 1.7 million for a four-year research project, "Hybrid2: Creating Equitable Spaces for Science Discourse in Blended Learning Environments. Funded by the National Center for Education Research, the project aims to enhance science learning for marginalized middle school students by integrating scientific discourse with everyday experiences and leveraging technology for inclusivity.
Regional Insights
North America dominated the STEM education in K-12 market with the largest revenue share of 43.9% in 2025. North American economies are heavily reliant on innovation and technological advancement. This creates a strong demand for professionals with strong STEM skills across various industries. North America is a hub for educational technology (EdTech) innovation. These technologies are transforming STEM education by making it more engaging, interactive, and accessible for students.
 To learn more about this report, Download Free Sample Report
U.S. STEM Education In K-12 Market Trends
The STEM education in K-12 market in the U.S. held the largest share in the North America region in 2025. The U.S. has the presence of leading universities and research institutions, fostering innovation and research in STEM education. Moreover, the growing EdTech industry provides a variety of tools and resources to enhance STEM learning experiences.
Europe STEM Education In K-12 Market Trends
The STEM education in the K-12 market in Europe is gaining traction. The European Union (EU) plays a crucial role in supporting STEM education through various initiatives and funding programs. These programs promote collaboration between member states, encourage curriculum development, and support teacher training in STEM subjects.
Asia Pacific STEM Education In K-12 Market Trends
The STEM education in K-12 market in Asia Pacific is positioned for significant growth. Rapid economic growth across the region necessitates a workforce equipped with strong STEM skills. STEM education programs prepare students for future careers in these high-demand fields.
Key STEM Education In K-12 Company Insights
Some key players in the STEM education in K-12 market, such as Chegg Inc.; Qkids Teacher; Varsity Tutors; and Vedantu are actively working to expand their customer base and gain a competitive advantage. To achieve this, they are pursuing various strategic initiatives, including partnerships, mergers and acquisitions, collaborations, and the development of new products. This proactive approach allows them to enhance their market presence and innovate in response to evolving needs.
-
McGraw-Hill Education specializes in learning science, offering customized learning experiences that aid students, parents, educators, and professionals. The company provides its offerings across 125 countries globally. In the U.S., the company’s products are used by over 5,000 higher education institutions and 13,000 K-12 school districts across all 50 states. The company’s product offerings are broadly classified into four types, namely PreK-12, Higher Ed, Professional, and International. The company provides various applications in its PreK-12 category, such as McGraw Hill AR, ALEKS Adventure, ALEKS Online Learning, and Everyday Mathematics Game Kits.
-
Activate Learning is a U.S.-based educational company dedicated to transforming K-12 STEM education through innovative curriculum and hands-on learning solutions. The company provides comprehensive teaching resources, including inquiry-based STEM programs, digital tools, and professional development for educators. Its flagship programs, such as "IQWST" (Investigating and Questioning our World through Science and Technology), are designed to align with Next Generation Science Standards (NGSS).
Key STEM Education In K-12 Companies:
The following key companies have been profiled for this study on the STEM education in K-12 market.
-
Activate Learning
-
Amplify Education, Inc.
-
Bedford, Freeman & Worth Publishing Group, LLC
-
Carolina Biological Supply Company
-
Cengage Learning
-
Discovery Education
-
EduCo International
-
Houghton Mifflin Harcourt
-
Kendall Hunt Publishing Company
-
Lab-Aids
-
McGraw Hill
-
OpenSciEd
-
PASCO Scientific
-
Savvas Learning
-
School Specialty, LLC
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Amplify Education, Inc.; Bedford, Freeman & Worth Publishing Group, LLC; Discovery Education; Lab-Aids; Activate Learning; Savvas Learning)
- Focus on expanding comprehensive STEM curriculum portfolios through digital learning platforms, assessments, and classroom resources.
- Strengthen market presence through long-term school district partnerships, curriculum alignment, and continuous product enhancements.
- An extensive customer base established brand recognition and broad distribution networks across K-12 institutions.
- Ability to provide integrated STEM solutions combining curriculum, professional development, laboratory resources, and digital content.
- Longer product development and curriculum update cycles due to large-scale operations and compliance requirements.
- Higher implementation costs and complex procurement processes may limit adoption among smaller educational institutions.
Emerging Players (EduCo International; OpenSciEd)
- Focus on specialized STEM content, open educational resources, and innovative instructional approaches targeting specific learning needs.
- Expand adoption through collaborative partnerships, flexible delivery models, and curriculum innovation.
- Greater flexibility in introducing modern STEM teaching methodologies and rapidly incorporating new educational technologies.
- Strong focus on niche subject areas and cost-effective solutions that address evolving classroom requirements.
- Limited geographic presence and smaller customer base compared with established education publishers.
- Lower financial resources and brand recognition may reduce competitiveness in large institutional procurement opportunities.
Recent Developments
-
In October 2024, Siemens Stiftung partnered with Siemens to introduce its digital Open Education Resource (OER) platform, Experimento, to Indian schools under Project Jigyaasa, a curiosity-based STEM learning initiative. The program, implemented by the Pratham Foundation, provides multimedia educational resources, including video activities, lesson plans, quizzes, and student worksheets, to enhance STEM education and accessibility for school students.
-
In October 2024, Shell International B.V. launched new EdTech initiatives to strengthen STEM education for the next generation in India. Using AI, data analytics, and advanced digital tools, the programs offer personalized learning interventions. Developed with partners such as Pratham InfoTech Foundation, Educational Initiatives, and Khan Academy, they build on the success of Shell International B.V.'s NXplorers program, which has already impacted over 3 lakh Indian students.
-
In March 2024, Bayer India, a pharmaceutical and biotechnology company, partnered with BharatCares, a non-profit social impact organization, to launch the Better School Program for Adpodra Group Government Primary School in Himatnagar, Gujarat, India. Designed to improve educational infrastructure and offer hands-on learning experiences for students in Himatnagar, the 'Better School Program' targets giving economically challenged students a major educational boost. It will assist over 850 students from 1st to 8th grade, spread across four schools.
STEM Education In K-12 Market Report Scope
Report Attribute
Details
Market size in 2025
USD 69.5 billion
Estimated market size in 2026
USD 80.0 billion
Projected market size by 2033
USD 182.4 billion
Growth rate
CAGR of 12.5% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, application, region
Regional scope
Asia Pacific; Europe; North America; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; China; Japan; India; South Korea; Australia; Brazil; Saudi Arabia; South Africa; UAE
Key companies profiled
Activate Learning; Amplify Education, Inc.; Bedford, Freeman & Worth Publishing Group, LLC; Carolina Biological Supply Company; Cengage Learning; Discovery Education; EduCo International; Houghton Mifflin Harcourt; Kendall Hunt Publishing Company; Lab-Aids; McGraw Hill; OpenSciEd; PASCO Scientific; Savvas Learning; School Specialty, LLC
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global STEM Education In K-12 Market Segmentation
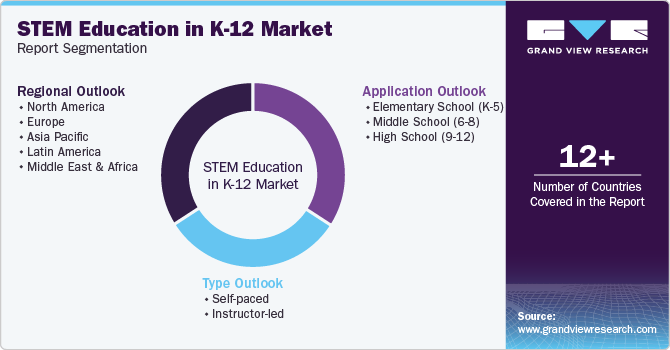
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global STEM education in K-12 market report based on type, application, and region.
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Self-paced
-
Instructor-led
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Elementary School (K-5)
-
Middle School (6-8)
-
High School (9-12)
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
-
MEA
-
UAE
-
South Africa
-
KSA
-
-
Research Methodology
The STEM education in k-12 market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each STEM education in k-12 segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
Self-Paced
Revenue in this segment is generated from subscription-based digital platforms that allow students to learn independently using recorded lessons, interactive modules, coding exercises, and virtual STEM activities. Growth is supported by flexible access, personalized learning paths, and increasing adoption of online STEM resources in schools and at home.
Instructor-led
This segment captures revenue from live classroom instruction, virtual teacher-led sessions, workshops, and structured STEM training programs delivered by certified educators. Demand is supported by the need for guided learning, practical demonstrations, collaborative projects, and curriculum-aligned instruction across K-12 institutions.
Segment - Application
Revenue capture definition
Elementary School (K-5)
Revenue in this segment is generated from foundational STEM learning programs that introduce basic concepts in science, mathematics, coding, and problem-solving through interactive classroom activities. Demand is supported by digital learning platforms, educational kits, robotics, and teacher-assisted instructional resources designed for early learners.
Middle School (6-8)
This segment captures revenue from STEM solutions focused on developing analytical thinking, computational skills, and practical experimentation through structured coursework. Schools invest in coding platforms, laboratory tools, engineering kits, and project-based learning resources to expand student engagement.
High School (9-12)
Revenue is derived from advanced STEM education programs that prepare students for higher education and technical career pathways through specialized coursework and practical applications. Adoption of AI-enabled learning platforms, virtual laboratories, engineering modules, and career-focused certifications contributes significantly to this segment.
Estimation Model
Layer Name
Key Questions
Description
Student Population Layer
Who can access STEM education?
Estimate the total K-12 student population across public, private, and alternative schools to determine the addressable learner base for STEM education programs and solutions.
STEM Adoption Layer
How many students participate in STEM programs?
Apply STEM curriculum adoption rates, school participation, and enrollment in STEM-focused programs to estimate the active student base using STEM education resources.
Delivery Channel Layer
How is STEM education delivered?
Measure the distribution of STEM learning through classroom instruction, digital learning platforms, virtual laboratories, robotics kits, after-school programs, and blended learning environments to determine channel penetration.
Monetization Layer
How much revenue is generated?
Apply the average annual spending per student and institutional expenditure on STEM software, hardware, curriculum content, teacher training, and laboratory equipment to estimate total market revenue.
Delivered Customizations
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
Market Entry & Expansion Assessment
Regional demand sizing and forecasting
Customer segmentation and buying behavior analysis
Competitive landscape benchmarking
Regulatory and distribution channel assessment
Identified high-growth market opportunities
Supported go-to-market strategy development
Highlighted investment priorities and risks
Enabled data-driven expansion planning
Technology & Innovation Assessment
Emerging technology trend analysis
Innovation pipeline
Technology adoption readiness assessment
Ecosystem and partnership mapping
Identified future growth areas
Supported innovation roadmap planning
Evaluated commercialization potential
Strengthened strategic partnership decisions
Customer & End-User Insights Study
Consumer awareness and adoption analysis
Purchase decision journey mapping
Satisfaction and loyalty assessment
Usage pattern and pain-point evaluation
Revealed key adoption drivers and barriers
Supported customer-centric product development
Improved targeting and engagement strategy
Identified opportunities for retention and upselling
Frequently Asked Questions About This Report
The global STEM education in K-12 market size was estimated at USD 69.5 billion in 2025 and is projected to grow from USD 80.0 billion in 2026
The global STEM education in K-12 market is expected to grow at a compound annual growth rate of 12.5% from 2026 to 2033 to reach USD 182.4 billion by 2033
Asia Pacific is the fastest-growing region over the forecast period.
North America dominated the STEM education in K-12 market with a share of 43.9% in 2025. This is attributable to the plenty of investments from venture capitalists and private-equity investors in STEM education in the U.S.
Some key players operating in the STEM education in K-12 market include Activate Learning; Amplify Education, Inc.; Bedford, Freeman & Worth Publishing Group, LLC; Carolina Biological Supply Company; Cengage Learning; Discovery Education; EduCo International; Houghton Mifflin Harcourt; Kendall Hunt Publishing Company; Lab-Aids; McGraw Hill; OpenSciEd; PASCO Scientific; Savvas Learning; School Specialty, LLC
The adoption of AI-enabled STEM learning platforms and immersive technologies such as virtual labs and educational robotics is reshaping K-12 education by making STEM instruction more interactive and personalized.
Self-paced segment dominated the market, with a revenue share of 68.0% in 2025.
High school (9-12) segment held the largest market share of 46.5% in 2025.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


