
- Home
- »
- Renewable Energy
- »
-
Sustainable Aviation Fuel Market Size Report, 2026-2033GVR Report cover

Sustainable Aviation Fuel Market (2026 - 2033)
Size, Share & Trends Analysis Report By Production Pathway (HEFA, Alcohol-to-Jet), By Feedstock, By Application (Commercial Aviation, Military Aviation, Business & General Aviation), By Region, And Segment Forecasts
Market Size, 2025
$3.1BMarket Estimate, 2026
$3.3BMarket Forecast, 2033
$15.3BCAGR, 2026–2033
24.6%Sustainable Aviation Fuel Market Summary
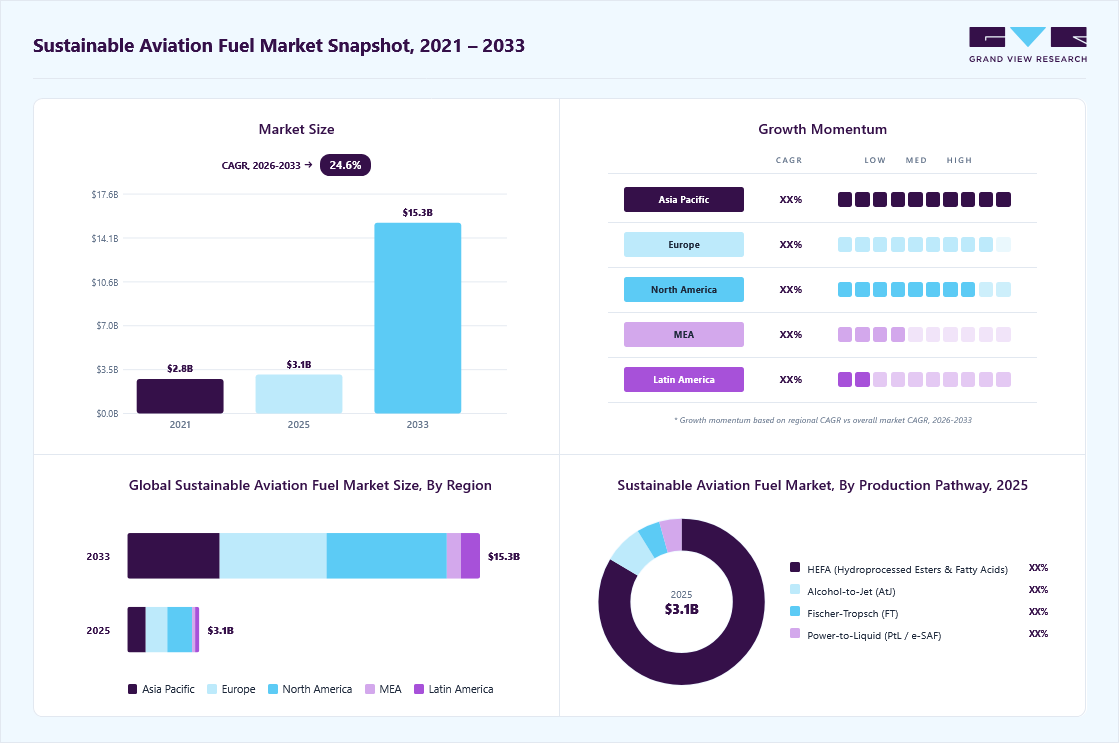
The global sustainable aviation fuel market size was valued at USD 3.1 billion in 2025 and is projected to grow from USD 3.3 billion in 2026 to USD 15.3 billion by 2033, at a CAGR of 24.6% from 2026 to 2033. North America held the largest share of 34.3% of the global market in 2025. Growth is driven by stringent aviation emissions-reduction targets, government mandates, and initiatives such as CORSIA, which are pushing airlines to adopt low-carbon fuel alternatives.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
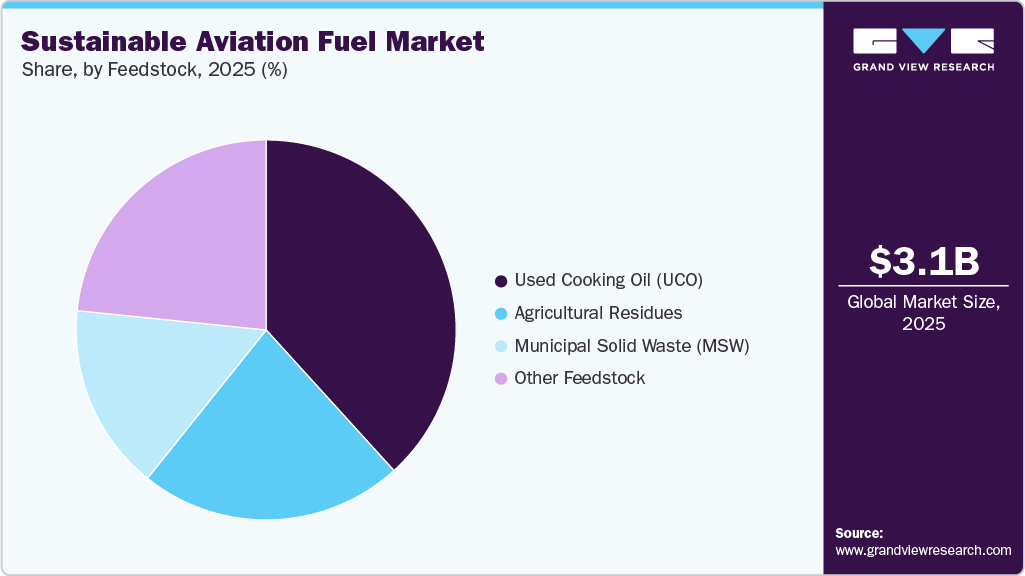
- By feedstock: Used cooking oil (UCO) led the global sustainable aviation fuel industry and accounted for a share of 38.3% in 2025.
- By production pathway: HEFA (Hydroprocessed Esters & Fatty Acids) segment led the market and accounted for a share of 83.4% in 2025.
- By application: Commercial aviation segment led the market and accounted for a share of 84.9% in 2025.
Regional Highlights
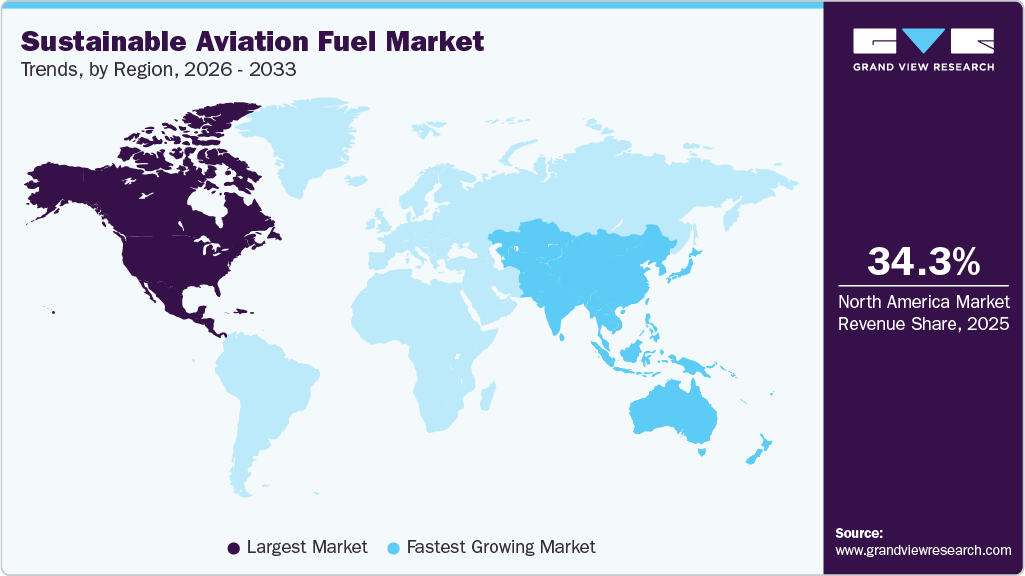
- Largest regional market: North America (34.3% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest revenue share in 2025.
Market Size & Forecast
- Market size in 2025: USD 3.1 Billion
- Estimated market size in 2026: USD 3.3 Billion
- Projected market size by 2033: USD 15.3 Billion
- CAGR (2026-2033): 24.6%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
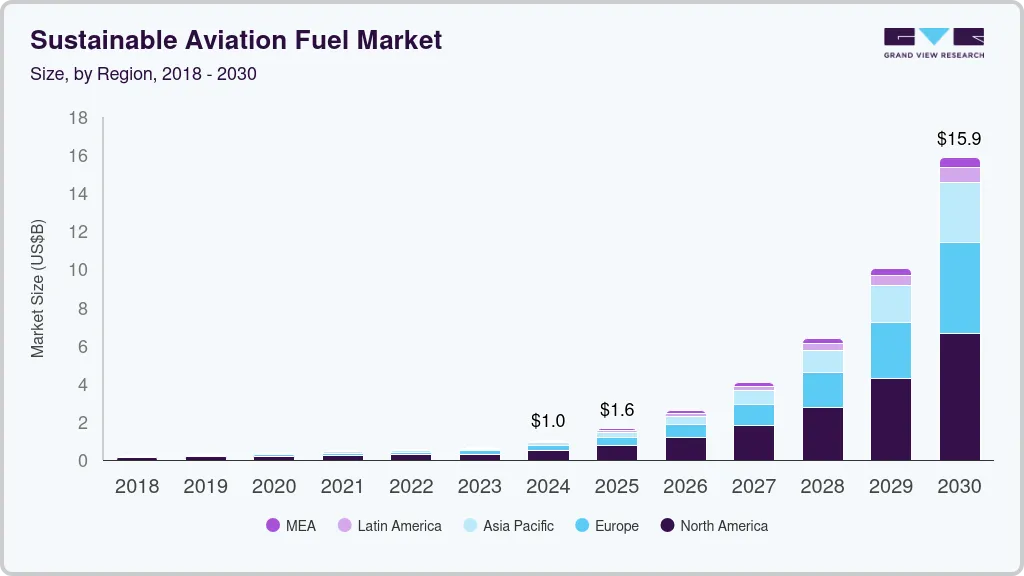
Increasing investments in SAF production facilities, advancements in conversion technologies, and expanding availability of renewable feedstock are further accelerating market expansion, supported by collaborations among airlines, fuel producers, and policymakers to scale commercialization.The market is experiencing a strong growth, driven by the surge in global air travel demand, which is increasing pressure on the aviation sector to adopt low-carbon alternatives without compromising operational efficiency. Airlines are entering long-term offtake agreements with SAF producers to secure future supply, while corporate customers are increasingly opting for low-emission travel options as part of their sustainability commitments, further supporting demand growth.
 To learn more about this report, Download Free Sample Report
The market is benefiting from rising investments in refining capacity and supply chain infrastructure, enabling large-scale production and distribution of SAF. Strategic collaborations between fuel producers, airlines, and technology providers, along with continuous improvements in conversion processes and feedstock diversification, are enhancing production efficiency and making SAF more commercially viable over time.
Drivers, Opportunities & Restraints
The sustainable aviation fuel industry is primarily driven by stringent government mandates and policy support, including blending targets and financial incentives that encourage adoption. Regulatory frameworks such as ReFuelEU and global mechanisms like CORSIA are compelling airlines to reduce lifecycle emissions. Airlines are also setting aggressive net-zero and carbon-neutral targets, increasing demand for SAF as a key decarbonization solution. Growing pressure from investors and corporate travelers for sustainable operations is further accelerating uptake. Long-term offtake agreements between airlines and fuel producers are helping in scaling production and securing supply.
A key market opportunity in the sector lies in feedstock aggregation and pre-processing, as the growing demand for waste-based inputs such as used cooking oil, animal fats, and agricultural residues is creating supply chain gaps. Businesses that can efficiently collect, standardize, and pre-treat these feedstocks are well-positioned to support large-scale SAF production, while improving cost efficiency and ensuring consistent quality for conversion processes. Expanding logistics networks, traceability systems, and partnerships with food processing, agriculture, and waste management industries is further enhancing the viability of this segment.
However, the sustainable aviation fuel industry faces challenges related to high production costs, as SAF can cost significantly more than conventional jet fuel due to expensive feedstock, complex conversion technologies, and limited economies of scale. This cost disparity places financial pressure on airlines, especially in price-sensitive markets. Fluctuating feedstock availability and logistics costs further impact overall pricing. The lack of cost parity with fossil fuels continues to hinder widespread commercial adoption.
Lack of dedicated infrastructure is restraining the sustainable aviation fuel industry, including limited blending facilities, storage capacity, and distribution networks required for seamless integration into existing aviation fuel systems. Many airports are not yet equipped to handle SAF at scale, leading to supply bottlenecks. Inconsistent infrastructure development across regions further restricts uniform adoption. These gaps increase operational complexities and delay the expansion of SAF supply chains.
Production Pathway Insights
The HEFA (Hydroprocessed Esters & Fatty Acids) segment led the market with the largest revenue share of 83.4% in 2025, due to its strong commercial maturity and scalability. It is currently the most widely deployed production route at a large commercial scale, unlike emerging pathways that are still in early stages. HEFA benefits from lower production costs and established infrastructure, leveraging existing hydroprocessing technologies similar to those used in renewable diesel production. This reduces capital investment requirements and enables faster integration into current refining systems, supporting its dominant market position.
The Power-to-Liquid (PtL / e-SAF) segment is anticipated to grow at the fastest CAGR of 33.3% over the forecast period, driven by its long-term scalability and superior sustainability profile. Unlike bio-based pathways, PtL is not constrained by the availability of agricultural land or waste feedstock, as it utilizes renewable electricity and captured carbon dioxide to produce synthetic fuels. This makes it a highly attractive solution for achieving deep decarbonization in aviation. Increasing investments in green hydrogen and carbon capture technologies, along with supportive policy frameworks, also support the growth of this segment.
Feedstock Insights
The used cooking oil (UCO) segment led the market with the largest revenue share of 38.3% in 2025. This growth is supported by its strong sustainability credentials as a waste-based feedstock, offering significantly lower carbon intensity and lifecycle greenhouse gas (GHG) emissions reductions of up to 80%. UCO does not compete with food crops, making it a preferred choice under regulatory frameworks promoting waste-to-fuel solutions. Its high compatibility with established pathways such as HEFA and relatively streamlined collection and processing infrastructure further reinforce its dominant position in the SAF market.
 To learn more about this report, Download Free Sample Report
The agricultural residues segment is projected to register at the fastest CAGR of 25.0% over the forecast period, driven by its abundant, underutilized supply potential. Feedstock such as straw, husks, and corn stover are widely available across global agricultural systems and is often treated as waste. Unlike first-generation feedstock, they do not interfere with food production. Their scalability and increasing suitability for advanced conversion pathways are further driving rapid adoption in SAF production.
Application Insights
The commercial aviation segment led the market with the largest revenue share of 84.9% in 2025, driven by stringent emission reduction targets and growing regulatory pressure on airlines to decarbonize operations. The sector faces intense scrutiny to meet net-zero 2050 commitments, accelerating the adoption of sustainable aviation fuel as a key solution. SAF enables significant lifecycle (carbon dioxide) emission reductions of up to 80%, making it highly attractive for large-scale commercial use. Increasing passenger volumes and rising demand for sustainable air travel are further reinforcing SAF uptake within this segment.
The military aviation segment is expected to grow at the fastest CAGR of 25.1% over the forecast period, supported by increasing government mandates and rising defense budgets focused on sustainable modernization. Armed forces are actively incorporating SAF into training and operational missions to meet sustainability targets. Strong policy support and procurement commitments from defense agencies are accelerating adoption. The need to enhance energy security and reduce dependence on conventional fossil fuels is further supporting the growth of SAF in military aviation.
Regional Insights
North America dominated the global sustainable aviation fuel market with the largest revenue share of 34.3% in 2025, driven by strong policy incentives such as tax credits under the Inflation Reduction Act and supportive programs from agencies like the U.S. Department of Energy. The region benefits from the presence of leading SAF producers and partnerships with major airlines, supported by well-established refining and distribution infrastructure. Early adoption of commercial-scale production pathways, particularly HEFA, along with a robust pipeline of announced projects and long-term offtake agreements, is further strengthening market growth.
 To learn more about this report, Download Free Sample Report
U.S. Sustainable Aviation Fuel Market Trends
The sustainable aviation fuel market in the U.S. accounted for the largest market revenue share in North America in 2025, driven by strong federal support through initiatives such as the SAF Grand Challenge, which aims to significantly scale domestic SAF production by the end of the decade. This is supported by policy incentives, including tax credits and funding programs that encourage investment in production facilities and feedstock supply chains. Collaborations between government agencies, fuel producers, and airlines are accelerating commercialization and capacity expansion. The presence of advanced refining infrastructure and early adoption by major carriers further strengthens market growth.
Asia Pacific Sustainable Aviation Fuel Market Trends
The sustainable aviation fuel market in the Asia Pacific is anticipated to grow at the fastest CAGR of 25.0% from 2026 to 2033, driven by abundant and diverse feedstock availability across the region, including agricultural residues, used cooking oil, and other waste-based resources. Countries such as Indonesia are leveraging these resources to scale domestic SAF production, with ambitious targets to significantly increase output in the coming years. The region’s strong agricultural base and expanding waste collection networks support a reliable feedstock supply chain. Growing air traffic and increasing focus on aviation decarbonization are further accelerating SAF adoption across Asia Pacific.
The China sustainable aviation fuel market is significantly influenced by strong policy support and national sustainability goals, particularly under Beijing’s “1+N” policy framework aimed at achieving carbon neutrality. The government is promoting SAF adoption through blending initiatives and regulatory measures to reduce aviation emissions. These policies are positioning SAF as a key component of the country’s broader decarbonization strategy. Increasing investments in domestic production capacity and advancements in fuel conversion technologies are further supporting market growth.
Europe Sustainable Aviation Fuel Market Trends
The sustainable aviation fuel market is supported by stringent decarbonization targets across the aviation sector, compelling airlines to accelerate the adoption of low-carbon fuels. SAF is widely regarded as the most practical solution for reducing emissions in long-haul flights, where alternatives remain limited. Strong regulatory frameworks, including regional mandates and sustainability initiatives, are further reinforcing demand, alongside growing investments in production capacity and supply chain development across Europe.
Latin America Sustainable Aviation Fuel Market Trends
The sustainable aviation fuel market in Latin America is driven by strong policy alignment with international aviation decarbonization commitments, as the region integrates global climate goals into its aviation strategies. Increasing recognition of SAF as a key solution for reducing greenhouse gas emissions in aviation is encouraging governments and stakeholders to support its adoption. Abundant regional feedstock availability, including agricultural residues and waste-based resources, is creating a strong foundation for local SAF production. Growing collaboration between airlines, energy companies, and policymakers is further supporting market development across the region.
Middle East & Africa Sustainable Aviation Fuel Market Trends
The sustainable aviation fuel market in the Middle East and Africa is driven by strategic government initiatives aimed at positioning the region as a future hub for clean aviation fuels. Countries are increasingly investing in large-scale infrastructure development, with a strong focus on green hydrogen production and Power-to-Liquid (PtL) technologies, to support long-term SAF manufacturing capabilities. The region’s access to low-cost renewable energy, particularly solar, is further enabling cost-competitive hydrogen production.
Key Sustainable Aviation Fuel Company Insights
Some of the key participants in the global sustainable aviation fuel industry include Neste, World Energy LLC, Alder Energy LLC, SkyNRG, Shell plc, BP p.l.c., Repsol, Honeywell International Inc., Eni, and LanzaJet. These companies collectively hold a significant share of the SAF market and play a key role in shaping industry development and competitive dynamics. They are focused on expanding SAF production capacity, developing advanced conversion technologies, and securing long-term offtake agreements with airlines to support large-scale commercialization.
Their operations span multiple production pathways, including HEFA, Alcohol-to-Jet, Fischer-Tropsch, and emerging Power-to-Liquid technologies, enabling diversification of supply sources. They are also investing in feedstock sourcing networks, including used cooking oil, agricultural residues, and waste-based inputs, to ensure stable, scalable production.
As SAF adoption accelerates, companies are strengthening partnerships with aviation stakeholders, energy firms, and governments to expand infrastructure and reduce production costs. Increasing regulatory pressure, airline decarbonization commitments, and global net-zero targets are driving continuous innovation, capacity expansion, and geographic diversification across the SAF value chain.
Key Sustainable Aviation Fuel Companies:
The following key companies have been profiled for this study on the sustainable aviation fuel market.
- Alder Energy, LLC
- BP p.l.c.
- Eni
- Honeywell International Inc.
- LanzaJet
- Neste
- Repsol
- Shell plc
- SkyNRG
- World Energy, LLC
Recent Developments
-
In February 2026, CAPHENIA advanced its plasma-based Sustainable Aviation Fuel (SAF) technology from pilot to commercial transition, with support from Siemens. The technology converts biomethane into synthesis gas for jet fuel production, representing a next-generation SAF pathway to reduce lifecycle emissions and improve production efficiency. This development supports the broader industry push toward scalable, standardized SAF production facilities and strengthens efforts to accelerate global SAF adoption through innovative conversion technologies.
Sustainable Aviation Fuel Market Report Scope
Report Attribute
Details
Market Definition
The Sustainable Aviation Fuel (SAF) market refers to the global revenue generated from the sale of low-carbon aviation fuels derived from renewable and waste-based feedstock.
Market size in 2025
USD 3.1 billion
Estimated Market size in 2026
USD 3.3 billion
Projected Market size by 2033
USD 15.3 billion
Growth rate
CAGR of 24.6% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative Units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, competitive landscape, growth factors, and trends
Segments covered
Production pathway, feedstock, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; India; Australia;Japan; South Korea; Brazil; Argentina; UAE; Saudi Arabia; South Africa
Key companies profiled
Alder Energy, LLC; BP p.l.c.; Eni; Honeywell International Inc.; LanzaJet; Neste; Repsol; Shell plc; SkyNRG; World Energy, LLC
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Sustainable Aviation Fuel Market Report Segmentation
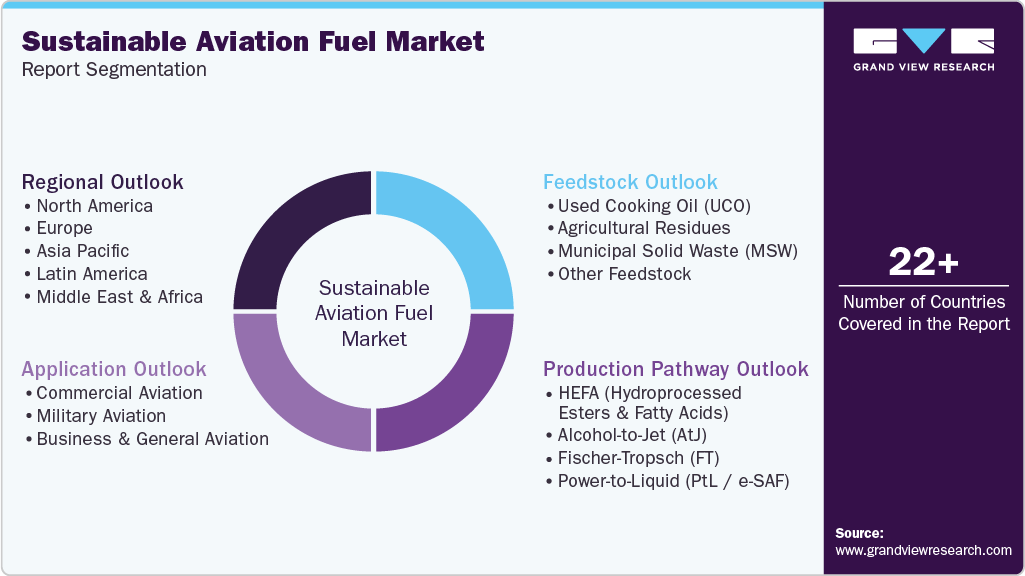
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global sustainable aviation fuel market report based on the production pathway, feedstock, application, and region:
 To learn more about this report, Download Free Sample Report
-
Production Pathway Outlook (Volume, Million Liters; Revenue, USD Million, 2021 - 2033)
-
HEFA (Hydroprocessed Esters & Fatty Acids)
-
Alcohol-to-Jet (AtJ)
-
Fischer-Tropsch (FT)
-
Power-to-Liquid (PtL / e-SAF)
-
-
Feedstock Outlook (Volume, Million Liters; Revenue, USD Million, 2021 - 2033)
-
Used Cooking Oil (UCO)
-
Agricultural Residues
-
Municipal Solid Waste (MSW)
-
Other Feedstock
-
-
Application Outlook (Volume, Million Liters; Revenue, USD Million, 2021 - 2033)
-
Commercial Aviation
-
Military Aviation
-
Business & General Aviation
-
-
Regional Outlook (Volume, Million Liters; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Australia
-
Japan
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
UAE
-
South Africa
-
-
Frequently Asked Questions About This Report
North America dominated with a 34.3% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
The global sustainable aviation fuel market was valued at USD 3.1 billion in 2025 and is expected to reach USD 3.3 billion in 2026.
The global sustainable aviation fuel market is expected to grow at a compound annual growth rate of 24.6% from 2026 to 2033 to reach USD 15.3 billion by 2033.
Based on the production pathway segment, the HEFA (Hydroprocessed Esters & Fatty Acids) segment held the largest revenue share of 83.4% in 2025.
Key players include Neste; World Energy, LLC; Alder Energy, LLC; SkyNRG; Shell plc; BP p.l.c.; Repsol; Honeywell International Inc.; Eni; LanzaJet; among others.
Key factors include stringent government regulations and blending mandates, along with airline commitments to reduce carbon emissions and achieve net-zero targets.
The used cooking oil (UCO) segment led with a 38.3% revenue share in 2025, while agricultural residues is the fastest-growing segment.
The HEFA (Hydroprocessed Esters & Fatty Acids) segment held the highest market share of 83.4% in 2025, while Power-to-Liquid (PtL / e-SAF) is the fastest-growing segment.
The commercial aviation segment held the highest market share of 84.9% in 2025, while military aviation is the fastest-growing segment.
About the Author(s)
Renewable Energy Research Team
Energy & Power · Renewable EnergyThis report was authored by the renewable energy research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the renewable energy segment of the energy & power industry. All findings are based on proprietary energy & power databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


